B
ERKSHIRE
H
ATHAWAY
INC.
2025
ANNUAL
REPORT
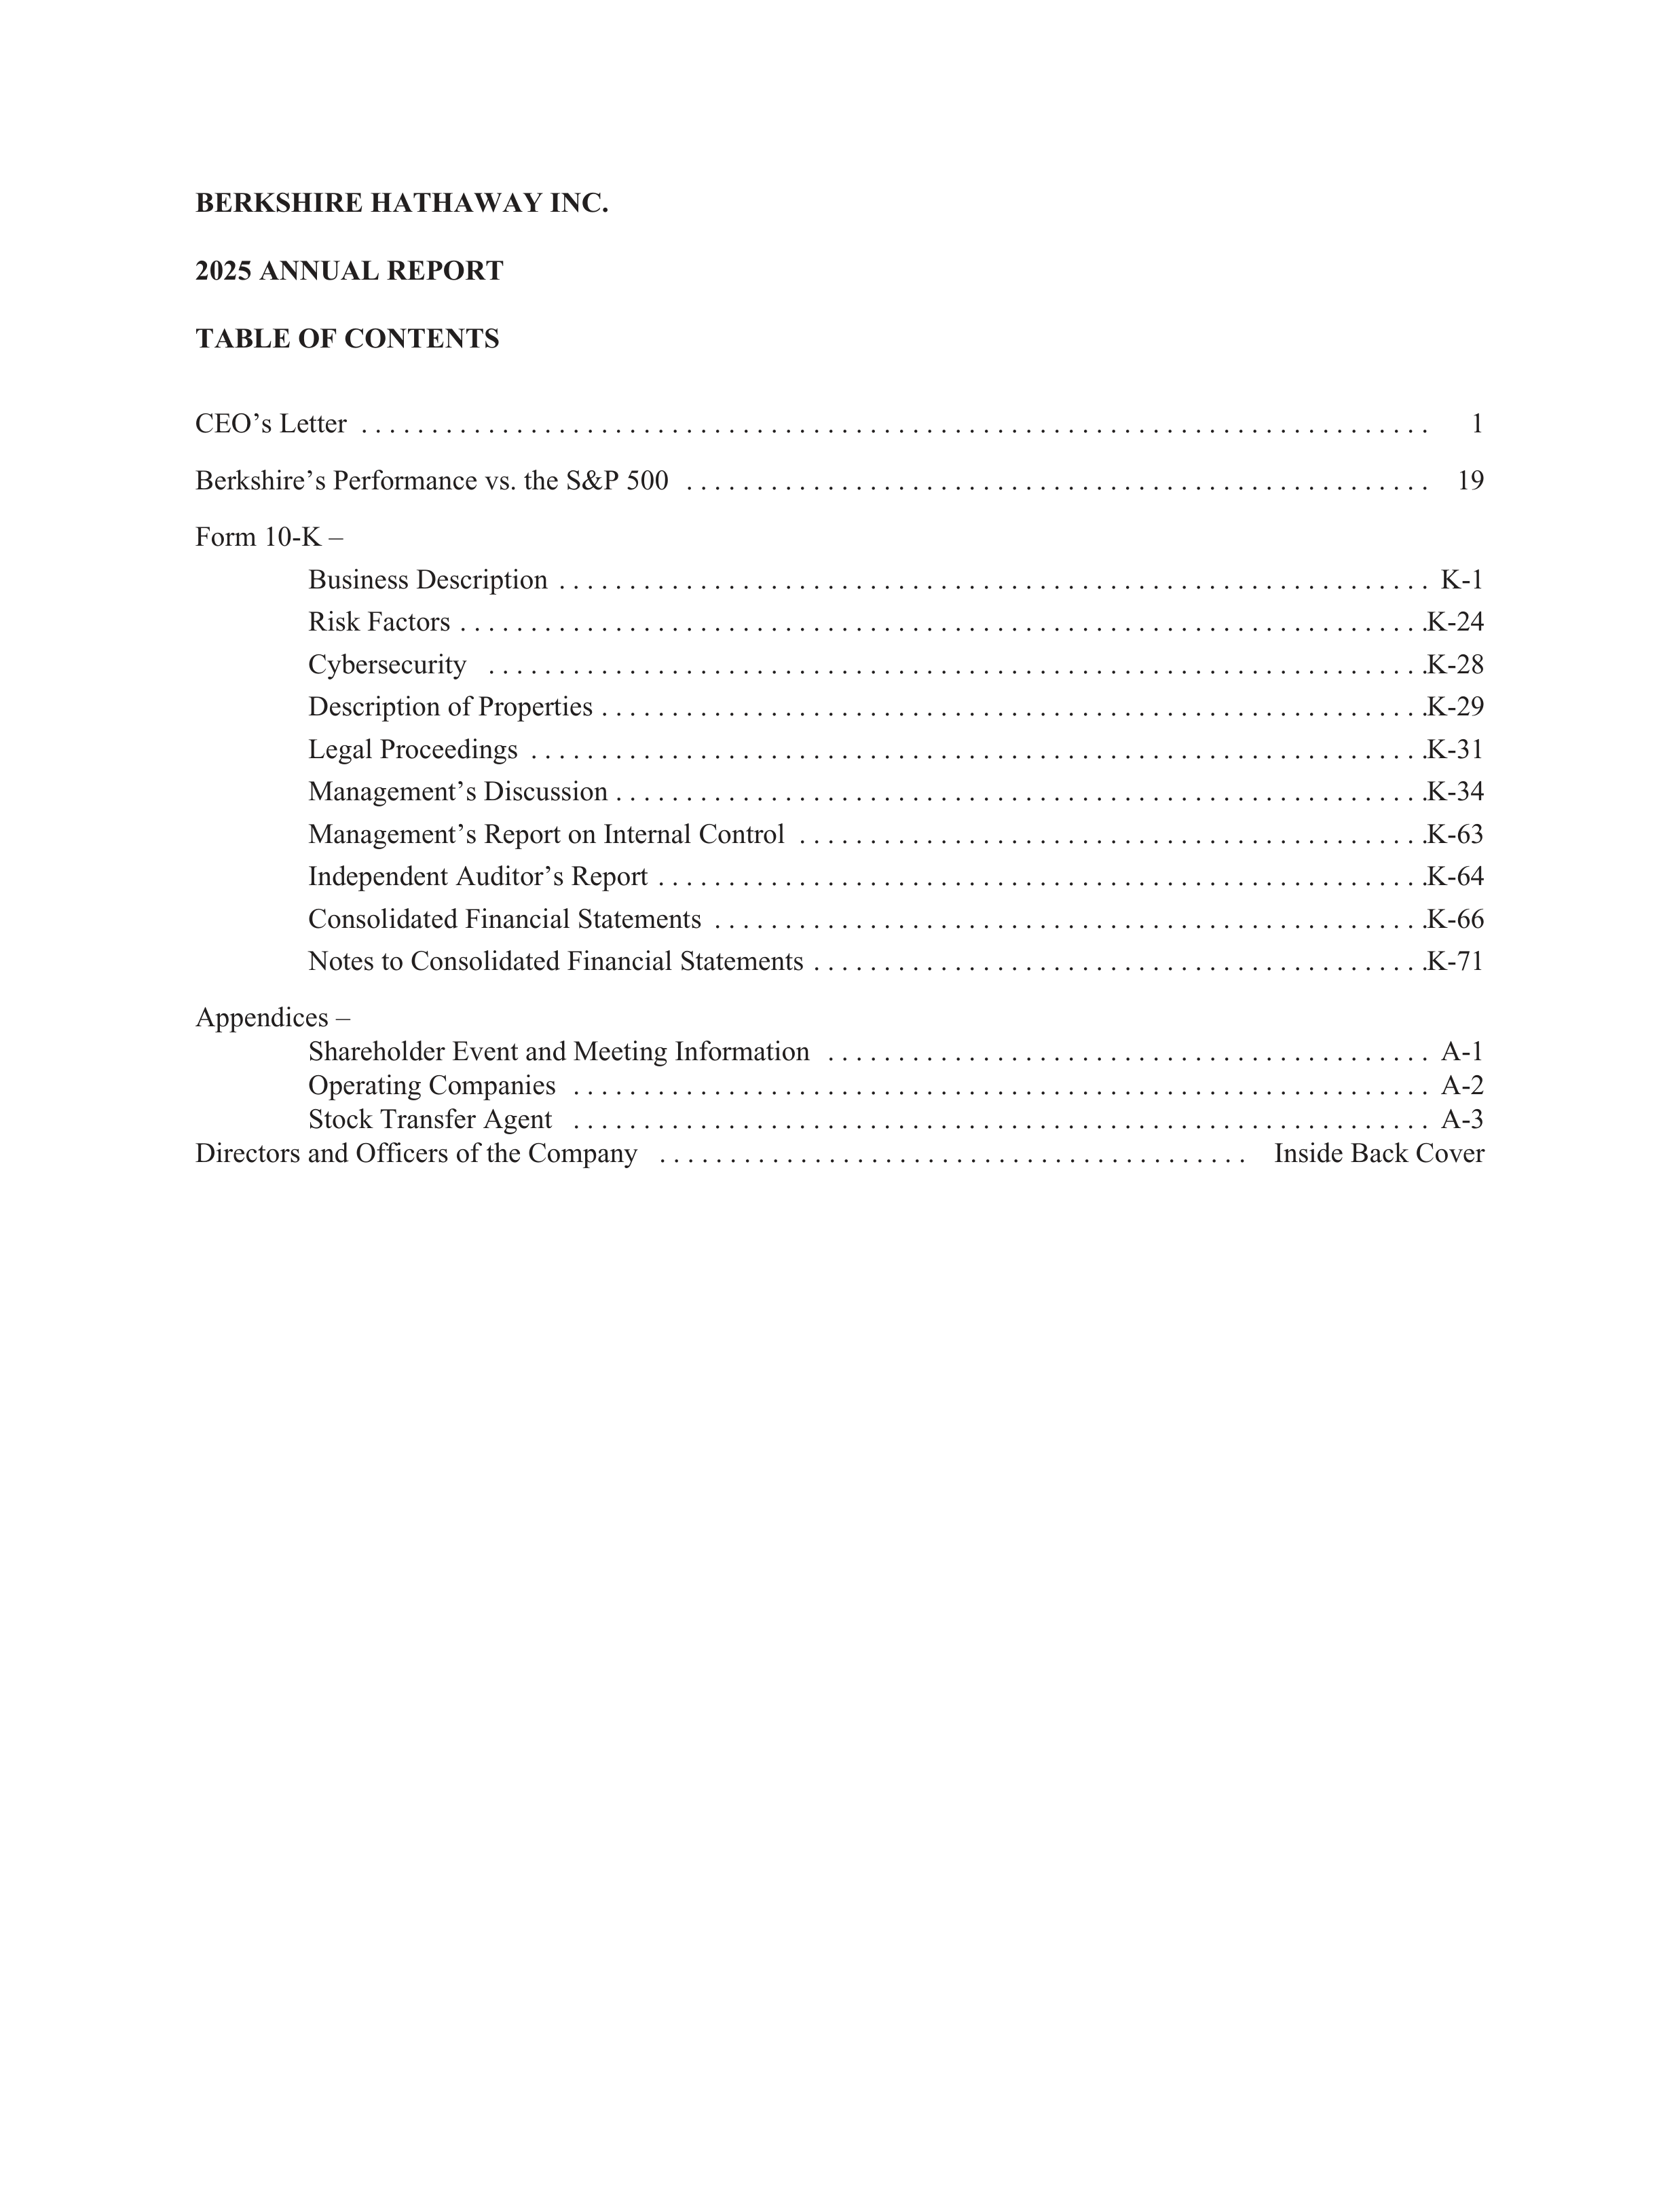
BERKSHIRE HATHAWAY INC.
2025 ANNUAL REPORT
TABLE OF CONTENTS
CEO’s Letter . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
1
Berkshire’s Performance vs. the S&P 500 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
19
Form 10-K –
Business Description . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
K-1
Risk Factors . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-24
Cybersecurity . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-28
Description of Properties . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-29
Legal Proceedings . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-31
Management’s Discussion . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-34
Management’s Report on Internal Control . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-63
Independent Auditor’s Report . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-64
Consolidated Financial Statements . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-66
Notes to Consolidated Financial Statements . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .K-71
Appendices –
Shareholder Event and Meeting Information . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
A-1
Operating Companies . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
A-2
Stock Transfer Agent . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
A-3
Directors and Officers of the Company . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Inside Back Cover
Berkshire Hathaway Inc.
To My Fellow Berkshire Shareholders,
Warren Buffett is arguably the greatest investor of all time, with generations benefiting from his
investment acumen. He has also been a remarkable CEO, executing his vision of building a great
insurance business since the acquisition of National Indemnity in 1967, and deploying the float to
make successful investments across major sectors of the economy, concentrating in the U.S. (To
Warren’s great frustration, this letter begins with these observations – yet we all know they are
true.)
In the past, Warren has spoken about how he draws inspiration from Ted Williams – the baseball
Hall of Fame hitter who divided the strike zone into 77 segments and tried to swing only at pitches
in a much smaller “happy zone,” resulting in a .344 career batting average and a historic .406
season in 1941. Similar discipline, patience, and judgment define Warren’s investing: determining
preferred pitches, waiting for them, then swinging decisively. But he is more than an investing
guru. Warren built Berkshire into an enduring enterprise with his business partner Charlie Munger.
They combined world-class capital allocation with the vision and leadership to create a business
fully equipped to transition from founder-led to one well-positioned for the next 60 years and
beyond.
More than these achievements, what endures is how Berkshire treated its shareholders as true
partners for 60 years. Warren has frequently expressed his respect and appreciation for Berkshire’s
long-term shareholders, who represent one of the most remarkable owner bases of any publicly
owned business. He invested alongside us, wrote with candor about both mistakes and successes,
and welcomed us to Omaha each year for open, unfiltered discussion. His annual shareholder
letters and direct interactions at Berkshire’s annual shareholder meetings are the clearest
expression of Warren’s – and Berkshire’s – commitment to partnership with our shareholders.
We are fortunate to have Warren as Berkshire’s Chairman, in the office five days a week, and
available to us as we underwrite insurance, operate our non-insurance businesses, and deploy
capital including equity investments. Warren also continues as an owner of Berkshire (although his
shares will all go to philanthropy over the 10 years or so following his passing).
To invest in Berkshire has long been a vote of trust in our founder – a trust that now rests with
Berkshire. Your capital is commingled with ours, but it does not belong to us. Our role is
stewardship. That stewardship has shaped a culture and reinforced a set of values that are not the
result of our success, but the reason for it.
* * * * * * * * * * * *
I am honored by our Board’s decision to appoint me CEO of Berkshire and humbled to succeed
Warren as I write my first annual letter to you. Warren is obviously a very hard act to follow.
1
Stepping into any leadership role begins with understanding the organization – why it exists, how
its culture shapes its people, and what values guide its decisions. While you will see similarities
and differences between Warren, Charlie, and me, we share the view that Berkshire is shareholder-
oriented to an unusual degree.
My understanding of Berkshire in this way began in 1992, when I moved to Omaha to join
CalEnergy, then unaffiliated with Berkshire. CalEnergy was partly owned by Peter Kiewit Sons’,
and chaired by Walter Scott, Jr., who was also a Berkshire director. Walter had succeeded Peter
Kiewit as the firm’s CEO and set a standard for leadership that mattered greatly to me.
My specific roles at CalEnergy matter little today. What matters is that it was an extraordinary
period of personal development. I felt fortunate to live in Omaha, a city that represented a form of
capitalism grounded in fundamentals and advanced by values, anchored in businesses built to last,
across industries such as insurance, construction, railroads, manufacturing, and – soon – energy.
I met Warren and Charlie after CalEnergy became MidAmerican Energy Holdings and was
acquired by Berkshire. I admired how they worked together to build an enterprise that reflected
their beliefs about business and life. Those beliefs fostered Berkshire’s culture and values that
continue to guide the company today, enabling it to endure through market cycles, disruptions, and
change. Our durability comes from knowing who we are and how we operate.
That deep understanding of the role our culture and values play in our success is shared by our
unique shareholders – our partners in this enterprise. Through my engagement with you at annual
meetings, I recognize how you want us to succeed together, and to do so in the right way.
Berkshire’s culture and values form the basis of our operating framework, which shapes the
strategy we pursue and the choices we make as we build Berkshire. As CEO, the framework
governs how I lead every day.
Our owners’ time horizon extends beyond the tenure of any individual CEO. I will not be your
CEO for the next 60 years as simple arithmetic makes that – shall we say – an ambitious plan.
However, 20 years from now, when I will have just a fraction of the tenure that Warren had, my
intention is that you – or your descendants – will be proud that your company is even stronger.
Culture and Foundational Values
Berkshire’s success depends on our nearly 400,000 employees. Their commitment to applying our
culture and values across Berkshire’s operating businesses – from See’s Candies to GEICO and
everything in between – and in every circumstance is central to our progress. Our success also
benefits from our Board’s leadership and ongoing alignment with our focus.
2
Last month, I sent a letter to our employees to emphasize that Berkshire’s culture and values remain
unchanged and will continue into perpetuity. It is important to share with you the full articulation
of this statement that was provided to them, with additional observations (shown in regular type)
about what they mean to me personally, based on my experience at Berkshire. While these values
are listed individually, they are mutually reinforcing and inseparable.
Berkshire
Berkshire is a unique conglomerate, intentionally designed to allocate capital rationally and
efficiently. Insurance is our core, and we also hold substantial investments in businesses across
many other sectors. Our approach underpins our goal to be exceptional stewards of our
shareholders’ capital, maximizing the growth in Berkshire’s intrinsic value per share over the long
term.
We are committed to strengthening the great legacy built by Warren Buffett and his business
partner Charlie Munger, ensuring it endures through our commitment to excellence.
Our Culture
Our culture begins with a partnership attitude. Our shareholders are our partners whose trust we
have earned and must work to keep. Their interests are at the center of our decision-making.
This attitude goes well beyond Berkshire’s corporate office in Omaha. It extends across our
operating businesses, where employees embrace an ownership mindset, managing our
shareholders’ assets as if they were their own. We think in decades, act with discipline, and uphold
our commitments. Stewardship is embedded in how we operate, reinforcing that our culture is a
system for generating long-term performance, not just a set of beliefs.
Charlie’s comment on May 1, 2021, that “Greg will keep the culture” will forever resonate with
me. It was a reminder that our culture is our most treasured asset, a call to maintain what defines
Berkshire, and a challenge to ensure our culture continues.
When I led Berkshire Hathaway Energy (BHE), Berkshire’s culture influenced how we operated.
When capital was allocated or underlying risks were assessed, Warren’s questions consistently cut
to the heart of the issue. Beyond that, we were entrusted with real autonomy to run the business,
always focusing on our customers, and taking a long-term view. That owner’s mindset is expected
from every Berkshire leader.
Our Foundational Values
The foundational values that follow are statements of principle that we embrace fully and strive
every day to achieve.
3
Decentralized Model
We seek the best managers to run our operating businesses, who in turn lead talented teams. We
operate a decentralized model with autonomy grounded in deserved trust. We minimize
bureaucracy to provide our managers the independence to focus relentlessly on their business. In
return, we expect accountability and integrity in performance. This autonomy attracts exceptional
people to Berkshire.
As I transitioned to Vice Chairman – Non-Insurance Operations in 2018, the leaders of those
operating businesses shared a similar question: will the decentralized model and their
responsibilities change? I assured them I had lived the culture of autonomy paired with
accountability and seen the results. Decisions are made faster, with better knowledge and greater
conviction, when they are made by those who are closest to the business and have accountability
for its outcomes. This will not change. Our CEOs will never have to navigate layers of bureaucracy
or have short-term earnings expectations dictated to them, leading to long-term value destruction.
Our decentralized approach is a competitive advantage, attracting managers who thrive on
autonomy and deliver on accountability. Berkshire must have leaders that reflect its principles, and
not principles that fit individuals.
Integrity
We uphold Berkshire’s reputation for integrity, as demonstrated by alignment between how we
think, what we say, and what we do. We make decisions that uphold our culture, communicate with
candor and transparency, and deliver on our commitments. The result is a reputation that is
earned, not claimed, through cumulative principled conduct. Every action reflects a deliberate
effort to deepen the trust placed in Berkshire.
For over 25 years, at each shareholder meeting we played a clip from Warren’s 1991 Salomon
Brothers Congressional testimony: “Lose money for the firm, and I will be understanding; lose a
shred of reputation for the firm, and I will be ruthless.” Our commitment to integrity has always
been steadfast and uncompromising. We know integrity is not a quality you admire on a shelf; it
is an active quality that must be earned, re-earned, and maintained daily.
We will encounter business successes and setbacks. When we fail, we will say so. Doing the right
thing also means rectifying our errors. A great example of both is BNSF’s resolution in 2025 of a
longstanding dispute with the Swinomish Indian Tribal Community over crude oil shipments
across Tribal lands. The BNSF decisions that sparked the dispute were made long ago, but the
current BNSF leadership built a partnership rooted in communication, understanding, and respect.
BNSF acknowledged its past mistakes and apologized, paving the way for mutually beneficial
agreements that allow it to meet customer needs while operating safely on Tribal lands.
4
Across our operating businesses, we make choices every day about how we conduct ourselves. We
have hundreds of thousands of employees who are good people and act with integrity and do the
right thing. But in any large organization a small minority will fail to meet our standards. We will
not tolerate such behavior. When it occurs, we will act decisively and ruthlessly to address it.
Protecting our integrity and reputation is a never-ending journey. You can rest assured that we will
remain relentless in this effort.
Financial Strength
We maintain a fortress-like balance sheet, ensuring Berkshire’s foundation is never compromised.
We preserve this financial strength by using debt sparingly and prudently. Our substantial liquidity
enables us to meet our obligations even under the most adverse conditions and to respond swiftly
when opportunities arise.
We are committed to maintaining exceptional financial strength. Our balance sheet is a strategic
asset to be deployed at the right time. It allows us to act decisively, invest when others are tentative
or fearful, and stand firm when financial storms roll through.
We uphold Berkshire’s financial resilience and independence by holding limited levels of debt. We
will remain an asset, not a risk, to America and the global financial system. Our cash and U.S.
Treasury holdings now exceed $370 billion. While some of this capital is required to support our
insurance operations and protect Berkshire against extreme scenarios, it also constitutes our dry
powder.
There will undoubtedly be incremental opportunities to deploy our owners’ capital without
compromising Berkshire’s resilience. My role is to ensure our liquidity levels and capital
deployment remain intentional and deliberate. We will always aim for ownership of productive
businesses over U.S. Treasuries.
Capital Discipline
We deploy our shareholders’ capital to opportunities that generate rewards commensurate with
their risk. When we expand existing operations, acquire new operating businesses, invest in equity
securities, and repurchase Berkshire stock, we evaluate each opportunity based on its potential to
grow Berkshire’s intrinsic value per share over a time horizon measured in perpetuity.
Berkshire’s capital allocation principles and strategy guide us in identifying opportunities:
•
Invest in businesses that we thoroughly understand, with durable advantages and long-term
economic prospects;
•
Partner with high integrity leaders who understand their customers and act like owners;
5
•
Avoid businesses that undermine the fabric of society or could jeopardize Berkshire’s
reputation;
•
Act quickly and concentrate our capital in a few high conviction ideas; and
•
Maintain discipline and let compounding unfold.
These criteria enable us to effectively and efficiently evaluate opportunities that come our way.
Despite our substantial size, we take pride in a nimble culture where big investment opportunities
can be confidentially shared with us, with a prompt response assured (and if we like it, no financing
contingency attached). We quickly say “no” to those that do not align with our principles, and
pursue those that do, knowing there will be many more of the former than the latter.
Many times in Berkshire’s history, some observers have suggested that our substantial cash
position signals a retreat from investing. It does not. We continue to evaluate many opportunities
and will remain patient and disciplined in pursuing the right ones for the benefit of our owners.
In 2025, our approach resulted in Berkshire announcing the acquisition of two very different
businesses: OxyChem and Bell Laboratories.
OxyChem is a well-run industrial chemicals business we first encountered through our investment
in Occidental. The chlorine and caustic soda it produces serve essential markets, led by
construction and core industrial uses. Management prioritizes efficient execution over volume,
supported by an integrated asset base and access to low-cost raw materials. For Berkshire, this
translates into cash flows from a compelling addition to our operating businesses.
Last year, Warren received a letter from Steve Levy, Bell Laboratories’ CEO, asking that we look
at the family-owned business he manages for the daughters of founder Malcolm Stack. Steve’s
letter was perfect. Bell Laboratories meets a persistent need: rodent control. In Steve’s words, it
possesses “high operating margins, very good historical growth and future growth potential, easy
to understand and always needed, and a strong management team.” In our words: a business with
durable advantages and long-term economic prospects run by excellent managers. We only wish it
had been ten times bigger.
These investments now join Berkshire’s strong set of operating businesses. Some of them require
little incremental investment and return excess cash to Berkshire; others present compelling
investment opportunities that will compound over time.
Share repurchases are another important capital allocation option. We will buy back Berkshire
shares when they trade below our estimate of intrinsic value, conservatively determined, ensuring
that repurchases enhance per-share value for continuing owners. We may also purchase large
blocks of shares directly from major holders when the opportunity presents itself. These purchases
allow shareholders to own an incrementally larger piece of Berkshire’s businesses, without
deploying any additional capital of their own.
6
Our approach to cash dividends continues to be that Berkshire will not pay dividends so long as
more than one dollar of market value for shareholders is reasonably likely to be created by each
dollar of retained earnings. On an annual basis, the Board reviews our policy.
Our capital discipline guides us, whether we seek to purchase an entire business, a portion of equity
in a publicly traded company, or our own shares. We maintain this approach regardless of the size
of our cash and U.S. Treasury holdings. We will assess value carefully, act patiently, and hold for
the long term – preferably forever.
Risk Management
We identify risks and strive to manage the level of risk across our organization. Our approach is
decentralized, suited to each operating business’s scale and complexity. We focus on risks that
could threaten Berkshire’s reputation, financial strength, or ability to realize opportunities for the
long term.
Risk management is central to Berkshire. The CEO is responsible for serving as Chief Risk Officer
– there is no more important duty.
An important part of fulfilling that responsibility is having the best on our team. When it comes to
risk, Ajit wrote the playbook. His rigor in managing and pricing risk sets the standard in insurance.
Any contract can be subject to legal challenge, and new coverages are particularly dangerous. We
often set a price today for a cost that may not be known for many years. Pricing insurance risk
correctly is essential, and we will walk away when the price is wrong. This approach is core to our
insurance business, and Ajit is simply peerless at doing it.
As a result, our insurance operations are a global powerhouse, able to accept risks others cannot,
and pay claims without hesitation. Our unmatched financial strength allows us to retain
underwriting risk and preserve the full economics for our owners, rather than dilute it through the
purchase of reinsurance.
Of course, understanding and managing risk is also essential for our non-insurance businesses.
Each must thoroughly assess its specific risks and plan for new risks before pursuing new or
incremental opportunities.
Across all our businesses, our responsibility is to understand the risks and actively manage them.
7
Operational Excellence
We pursue operational excellence across our operating businesses. Our employees continuously
strive to exceed customer expectations, improve efficiency to better compete and prepare for
challenges to our operating models, and reinvest prudently in their operations. We recognize that
performance fluctuates year to year, so we assess a business’s success not by short-term results
but by its ability over the long term to maintain and strengthen its competitive position and improve
its economic prospects.
Operational excellence at Berkshire is not a program. It is the result of disciplined decision making
across our businesses. That work starts with safety and carries through to how we serve customers,
make products, and compete – every day.
In February 2025, Precision Castparts’ response to a major fire at its Jenkintown, Pennsylvania
facility showed Berkshire at its best. All employees on site were evacuated safely. The team then
worked closely with first responders, providing site layouts and identifying potential hazards. In the
aftermath, Precision Castparts supported the local volunteer fire department, assisted the city, and
conducted extensive environmental testing that confirmed the area was safe.
At the same time, the fire created a significant operational challenge. The facility produced more
than 700 parts that were sole-sourced and critical to major aerospace customers. Mark Donegan,
Precision Castparts’ CEO, and his team quickly redistributed production across U.S. and
international sites, doing so without compromising safety, quality, or delivery standards. No
customer experienced a production line stoppage. The episode reflected our model at work:
decentralized leadership, clear accountability, and exceptional execution under pressure.
The daily pursuit of excellence must be never-ending. By focusing on customers, efficiency, and
continuous improvement, we create value over the long term.
Taken together, the foundational values listed above built Berkshire, and equip us to succeed in the
decades ahead. While we have set them out explicitly this year, we will publish them as an
attachment to future letters, with each letter discussing how we practiced those values across
Berkshire.
Their impact is also very evident in the operating performance of our businesses today.
* * * * * * * * * * *
Berkshire’s Performance
Berkshire delivered operating earnings of $44.5 billion in 2025, below $47.4 billion in 2024 and
above the $37.5 billion we have averaged over the past five years, a result that underscored the
durability of our operating businesses, while also reflecting the fact that we have opportunities for
further improvement.
8
Before diving into details, it is worth reiterating a Berkshire belief: our GAAP net earnings – with
its sometimes-large annual swings from realized and unrealized investment gains and losses – must
be assessed with caution. These gains and losses matter over the long run, but when evaluating
Berkshire’s annual business performance, we believe operating earnings remains the best measure.
Equally important is the cash our businesses generate. In 2025, Berkshire produced $46 billion of
net cash flows from operating activities, compared to a five-year average of more than $40 billion,
underscoring our ability to invest in opportunities across our businesses.
Insurance Operations
In 2025, Berkshire’s insurance operations accomplished their fundamental goals: grow
underwriting profits and float in a disciplined manner.
We own an extraordinary group of insurance businesses, each managed with a long-term
orientation. Their performance reflected both their inherent strengths and an industry that, after
several years of needed adjustments to pricing and policy terms, in 2025 began to experience a
deceleration or reversal of these trends, particularly in the latter half of the year. This likely means
we will write less property and casualty business for a period of time.
Although the year began with significant wildfire-related losses in Los Angeles, the Atlantic
hurricane season was unusually benign. For the first time in a decade, no hurricane made landfall in
the U.S., our largest region of global exposure for our primary insurance and reinsurance
businesses – a reminder that nature controls the winds, not Warren and certainly not me.
We produced a combined ratio of 87.1% across our property and casualty businesses in 2025,
comparing favorably with our five-year average of 90.7%, ten-year average of 93.0% and twenty-
year average of 92.2%, an exceptional underwriting result for an insurer of our scale. (Our
retroactive reinsurance business, which does not receive regular premiums, is excluded from these
figures.)
No discussion of our insurance businesses would be complete without again acknowledging and
appreciating Ajit. For nearly four decades, his judgment and discipline have shaped our ability to
underwrite large and complex risks with care and precision. The organization and team he built
understand both the limits and the opportunities inherent in very large risks, and his example
continues to guide our teams. Their steadiness benefits us all.
9
GEICO
GEICO has been a significant contributor to the group’s lower combined ratio. Over the past few
years, GEICO has improved its cost structure, strengthened its underwriting discipline, and
enhanced its ability to segment customers and the related pricing of risk. Industrywide rate
increases from the end of 2022 through 2024 continued to positively impact performance in 2025.
While these increases varied by product and jurisdiction, the pricing environment remained firm,
and GEICO benefited accordingly.
GEICO’s broad rate increases in recent years have restored margins but come at the cost of lower
retention. Competitors’ rate reductions may extend that pressure into 2026. The GEICO team
remains focused on pricing risks correctly for both existing and new customers. Restoring retention
while maintaining underwriting discipline will take time.
Alongside retaining its customer base with a more nuanced pricing strategy, GEICO is investing
in technology to improve efficiency and service, while preserving its position as the industry’s
low-cost provider.
Primary Group
Across our other primary property and casualty businesses, demand entering 2025 was solid, and
pricing in most commercial insurance business segments was adequate or improving. As the year
progressed, additional capital entered the market, resulting in lower pricing or decelerating rate
increases in several important lines. We have always prioritized underwriting discipline over
volume, and as pricing became less attractive, our premium growth plateaued. We expect these
primary insurance businesses to face continued headwinds in 2026, and potentially beyond.
Reinsurance Group
Our reinsurance operations face similar dynamics. The reinsurance sector has attracted significant
increases in available capital from both the traditional and alternative markets, which together with
a more benign reinsured catastrophe loss burden in 2025 in most major regions has led to
significant price declines in property reinsurance. In most casualty reinsurance segments, claims
inflation continued to outpace pricing. As long as these phases of the cycle endure, we expect to
write less reinsurance premium.
Our insurance team will remain patient because of Berkshire’s structural strengths:
1.
We have significant capital, enabling us to underwrite large and unusual risks.
2.
We give our insurance managers autonomy to run their businesses, without quarterly
earnings targets or growth mandates that might otherwise distort their underwriting
judgment.
10
3.
We insist on underwriting discipline as the most important ingredient in insurance success.
4.
We focus on the long term, resisting temporary industry enthusiasms and exuberances.
The environment ahead will reward insurers whose focus remains on growing underwriting profit
sustainably, not volume; customer trust and loyalty, not temporary spikes in market share; and
long-term resilience, not short-lived opportunism.
At year-end, our insurance float – the capital we hold to pay future losses and, in the meantime,
invest for Berkshire’s benefit – stood at $176 billion. That amount increased from $171 billion at
the end of 2024 and from $88 billion at the end of 2015.
Our insurance businesses’ ability to declare ordinary dividends to Berkshire is restricted by
insurance statutes and regulations, permitting up to $31 billion during 2025 without prior
regulatory approval. The insurance businesses ultimately returned $29 billion to Berkshire in the
year, underscoring the continued strength of their capital base.
Non-Insurance Operations
Our non-insurance group is composed of strong businesses operating within the railroad, utilities
and energy, manufacturing, service and retailing industries. It also includes Pilot and McLane.
Berkshire’s approach with its 51 non-insurance operating businesses is markedly different from
most conglomerates. There are no layers of management and no allocated goals or targets set by
Berkshire. Each business is accountable to its CEO, who is expected to pursue operational
excellence relentlessly and close performance gaps. Capital allocation decisions for these
businesses ultimately reside with me as Berkshire’s CEO and are based on each business’s
opportunities and related risks. Most operate with no debt, and will remain that way.
Across these businesses, we have made progress in the fundamentals that drive long-term value
but also have a clear understanding of where we need to improve performance. Regardless of
industry, our expectations are the same: managers who think like owners and rigorous execution –
measured by results, not intentions.
We are fortunate to have Adam Johnson now serving as president of our consumer products,
service, and retailing businesses. Adam, who has lived the Berkshire culture for nearly 30 years
(10 as CEO of NetJets), is now responsible for a group consisting of 32 companies. Adam and his
team at NetJets think like owners and earned their reputation for operational excellence over the
past decade. Their work transformed NetJets from a challenged business model into a successful
enterprise that delivers value for Berkshire shareholders. That same approach – accountability and
a focus on avoiding complacency – will guide how he works with the CEOs across his portfolio.
11
BNSF
As one of the six major freight railroads in North America, BNSF is a key part of the transportation
backbone of the U.S. economy. Berkshire acquired this iconic business in 2010 with an equity
value of $34.5 billion. In 2025, BNSF produced $8.1 billion in net operating cash flows and
returned $4.4 billion of that cash to Berkshire through dividends. For context, its average annual
dividend over the past five years was $4.1 billion.
Safe operations, reliable service, and a competitive cost structure ultimately determine a railroad’s
success – and accordingly how we assess management’s performance. BNSF has focused on
improving each of these. Safety remains the top priority, and BNSF has been the industry leader
for the past decade. In 2025, shipments spent less time idling at terminals and moved through the
network faster than in nearly any year in the company’s history.
These gains matter, but they are not enough; more progress is needed to translate operational
improvements into stronger financial results. We view operating margin (the inverse of the
industry’s operating ratio) as the best measure of performance. In 2025, BNSF’s operating margin
improved to 34.5% from 32.0% in 2024. It remained only modestly above its five-year average.
The gap to the industry’s best remains too wide and closing it will require continued improvements
in efficiency and service. Each one-percentage-point improvement in operating margin generates
approximately $230 million of incremental operating cash flow for our owners. The team
recognizes the significance of this opportunity, and we will be disappointed if we do not deliver a
substantial improvement over the next few years.
Alongside BNSF’s own improvements, there is also potential consolidation in the rail industry
with the proposed Union Pacific–Norfolk Southern merger. Berkshire has been clear that it is not
interested in acquiring one of the other Class I railroads, since the current economics would not
work in our shareholders’ favor. BNSF’s focus on the proposed merger has been to ensure BNSF
can continue to offer customers a compelling value proposition, including full and competitive
access to Eastern rail markets.
BHE
BHE’s objective is straightforward: to deliver affordable and reliable energy service for its
customers. That responsibility has grown as the industry enters a significant investment cycle,
driven by rising electricity demand from artificial intelligence computing and by increasing
wildfire risk, particularly in the Western U.S. Growth is welcome, but it will not come at the
expense of affordability or reliability for households, small businesses, and industrial users.
12
BHE is proud that it continues to offer meaningful value to customers in the markets it serves –
averaging 24% below the national retail electric rate level, with all its markets priced at least in
the double-digit range beneath that benchmark. Infrastructure built for hyperscalers and data
centers must be paid for by those customers and reflect the risks tied to step-changes in long-term
demand. BHE will pursue this incremental growth and invest our shareholders’ capital only when
those risks and rewards are appropriately balanced.
On wildfire risk, BHE has taken a leadership role, working with regulators, public officials, and
the communities it serves. Its mitigation programs are among the most comprehensive in the
industry. When a BHE utility is responsible for a wildfire, it has acknowledged that responsibility,
including PacifiCorp’s settlements related primarily to the 2020 Labor Day fires. At the same time,
PacifiCorp is not an insurer of last resort and should not be treated as a deep pocket. Where
responsibility does not exist, it will continue to seek judicial relief. Accountability, paired with
principled opposition to unwarranted liability, is essential to preserving the regulatory compact
that governs utilities.
BHE is rebalancing as the team positions it to move forward. In 2025, BHE produced $8.4 billion
in net cash flows from operating activities, consistent with its five-year average, even as it absorbed
these challenges. Our willingness to invest capital depends on the continued functioning of the
regulatory compact through which utilities earn a reasonable return on invested capital. Near-term
opportunities are significant, and BHE will pursue them selectively.
Manufacturing – Industrial Products
The macro environment in 2025 for our industrial products businesses was challenging, yet the
businesses delivered earnings results that demonstrated underlying resilience. Operational
execution was strong across the group, and specifically at Precision Castparts, Marmon, IMC, and
Lubrizol, which positions all of them well to pursue incremental opportunities.
The Lubrizol team, led by Rebecca Liebert, was integral to the acquisition of OxyChem and its
planned integration as a standalone operating business within Berkshire. Rebecca has assumed
responsibility for OxyChem in addition to her role as CEO of Lubrizol, working in partnership
with OxyChem CEO Wade Alleman and his leadership team.
Our largest industrial manufacturing business, Precision Castparts, spent much of the past decade
navigating a difficult period for the aerospace industry. Aircraft production slowed materially,
volumes declined, and a series of disruptions – most notably the pandemic, when air travel
effectively stopped – put sustained pressure on earnings.
13
The Precision Castparts team has now worked through the most challenging part of that period.
Air travel has recovered, aircraft orders have resumed, and demand for the company’s components
has normalized and is growing. The business has remained disciplined throughout, with
management focused on translating a healthier industry backdrop into margins that better reflect
its long-term potential. In 2025, Precision Castparts generated $2.4 billion of net cash flows from
operating activities, compared to an average of $0.9 billion in 2021 and 2022 and $1.7 billion in
2015, the last full fiscal year before our acquisition.
Manufacturing – Building Products
Our building products businesses span the U.S. housing and commercial building landscape, from
the homes Clayton builds to the materials and finishes our other companies supply. As in any
market, end-consumer preferences can evolve, and our businesses must adapt accordingly to meet
those changing demands.
Shaw has navigated a challenging period as consumers moved away from soft-surface flooring
(carpets), and some of its difficulties were self-inflicted. As it expanded hard-surface production,
execution slipped, affecting quality and service. Shaw is now rebuilding its manufacturing
organization and restoring the operational discipline needed to regain customer confidence.
Clayton leads the group in size. Its business model – centered on efficient manufacturing and
construction of well-built homes, supported by integrated financing – has proven resilient through
short-term shifts in the broader housing market. This approach enables Clayton to meet the
ongoing need for quality, affordable housing nationwide.
While activity in this building-products sector varies from year to year with broader construction
trends, the long-term needs for housing and commercial buildings remain strong, positioning the
group, which also includes Johns Manville and MiTek, well for the future. This durable demand
underpins these operations, which are distinguished by disciplined and knowledgeable
management, a strong focus on customers, and well-established operating models.
Manufacturing – Consumer Products; and Service and Retailing
As highlighted earlier in the letter, Adam is president of Berkshire’s consumer products, service,
and retailing businesses. These businesses performed well overall in 2025, recognizing certain
consumer segments faced a very challenging environment.
NetJets is the largest business in our service group. NetJets maintains a relentless focus on safety
and exceptional service to reinforce its position as a premium offering. That foundation has enabled
NetJets to attract many customers, and today it operates nearly 1,100 aircraft in over 150 countries
around the world. It is a prized asset in a very tough industry.
14
Pilot
Pilot continues to strengthen its operations. As the largest operator of travel centers in North
America, it competes on location, service, and reliability. Management has focused on execution
at the store level – improving customer experience for both professional drivers and everyday
travelers, investing in store upgrades, food offerings, and customer loyalty. Since 2023, Pilot has
increased capital spending to modernize facilities and expand its electric vehicle charging network.
These efforts are reflected in Pilot’s Pro Preference score – a third-party study of how often
professional drivers choose Pilot over travel center competitors – which rose from 27% in 2022 to
35% in 2025, placing the business second in the industry. We should be #1 and we will not be
pleased until that standard is achieved. We first invested in Pilot in 2017; however, our ability to
manage it was contractually delayed until 2023. That mistake will not happen again.
The underlying economics of the business are reflected in its cash generation. In 2025, Pilot
delivered $1.7 billion of net cash flow from operating activities, an improvement from 2024. As
operations continue to strengthen and capital needs normalize, we expect more cash to be returned
to Berkshire.
Equity Investments
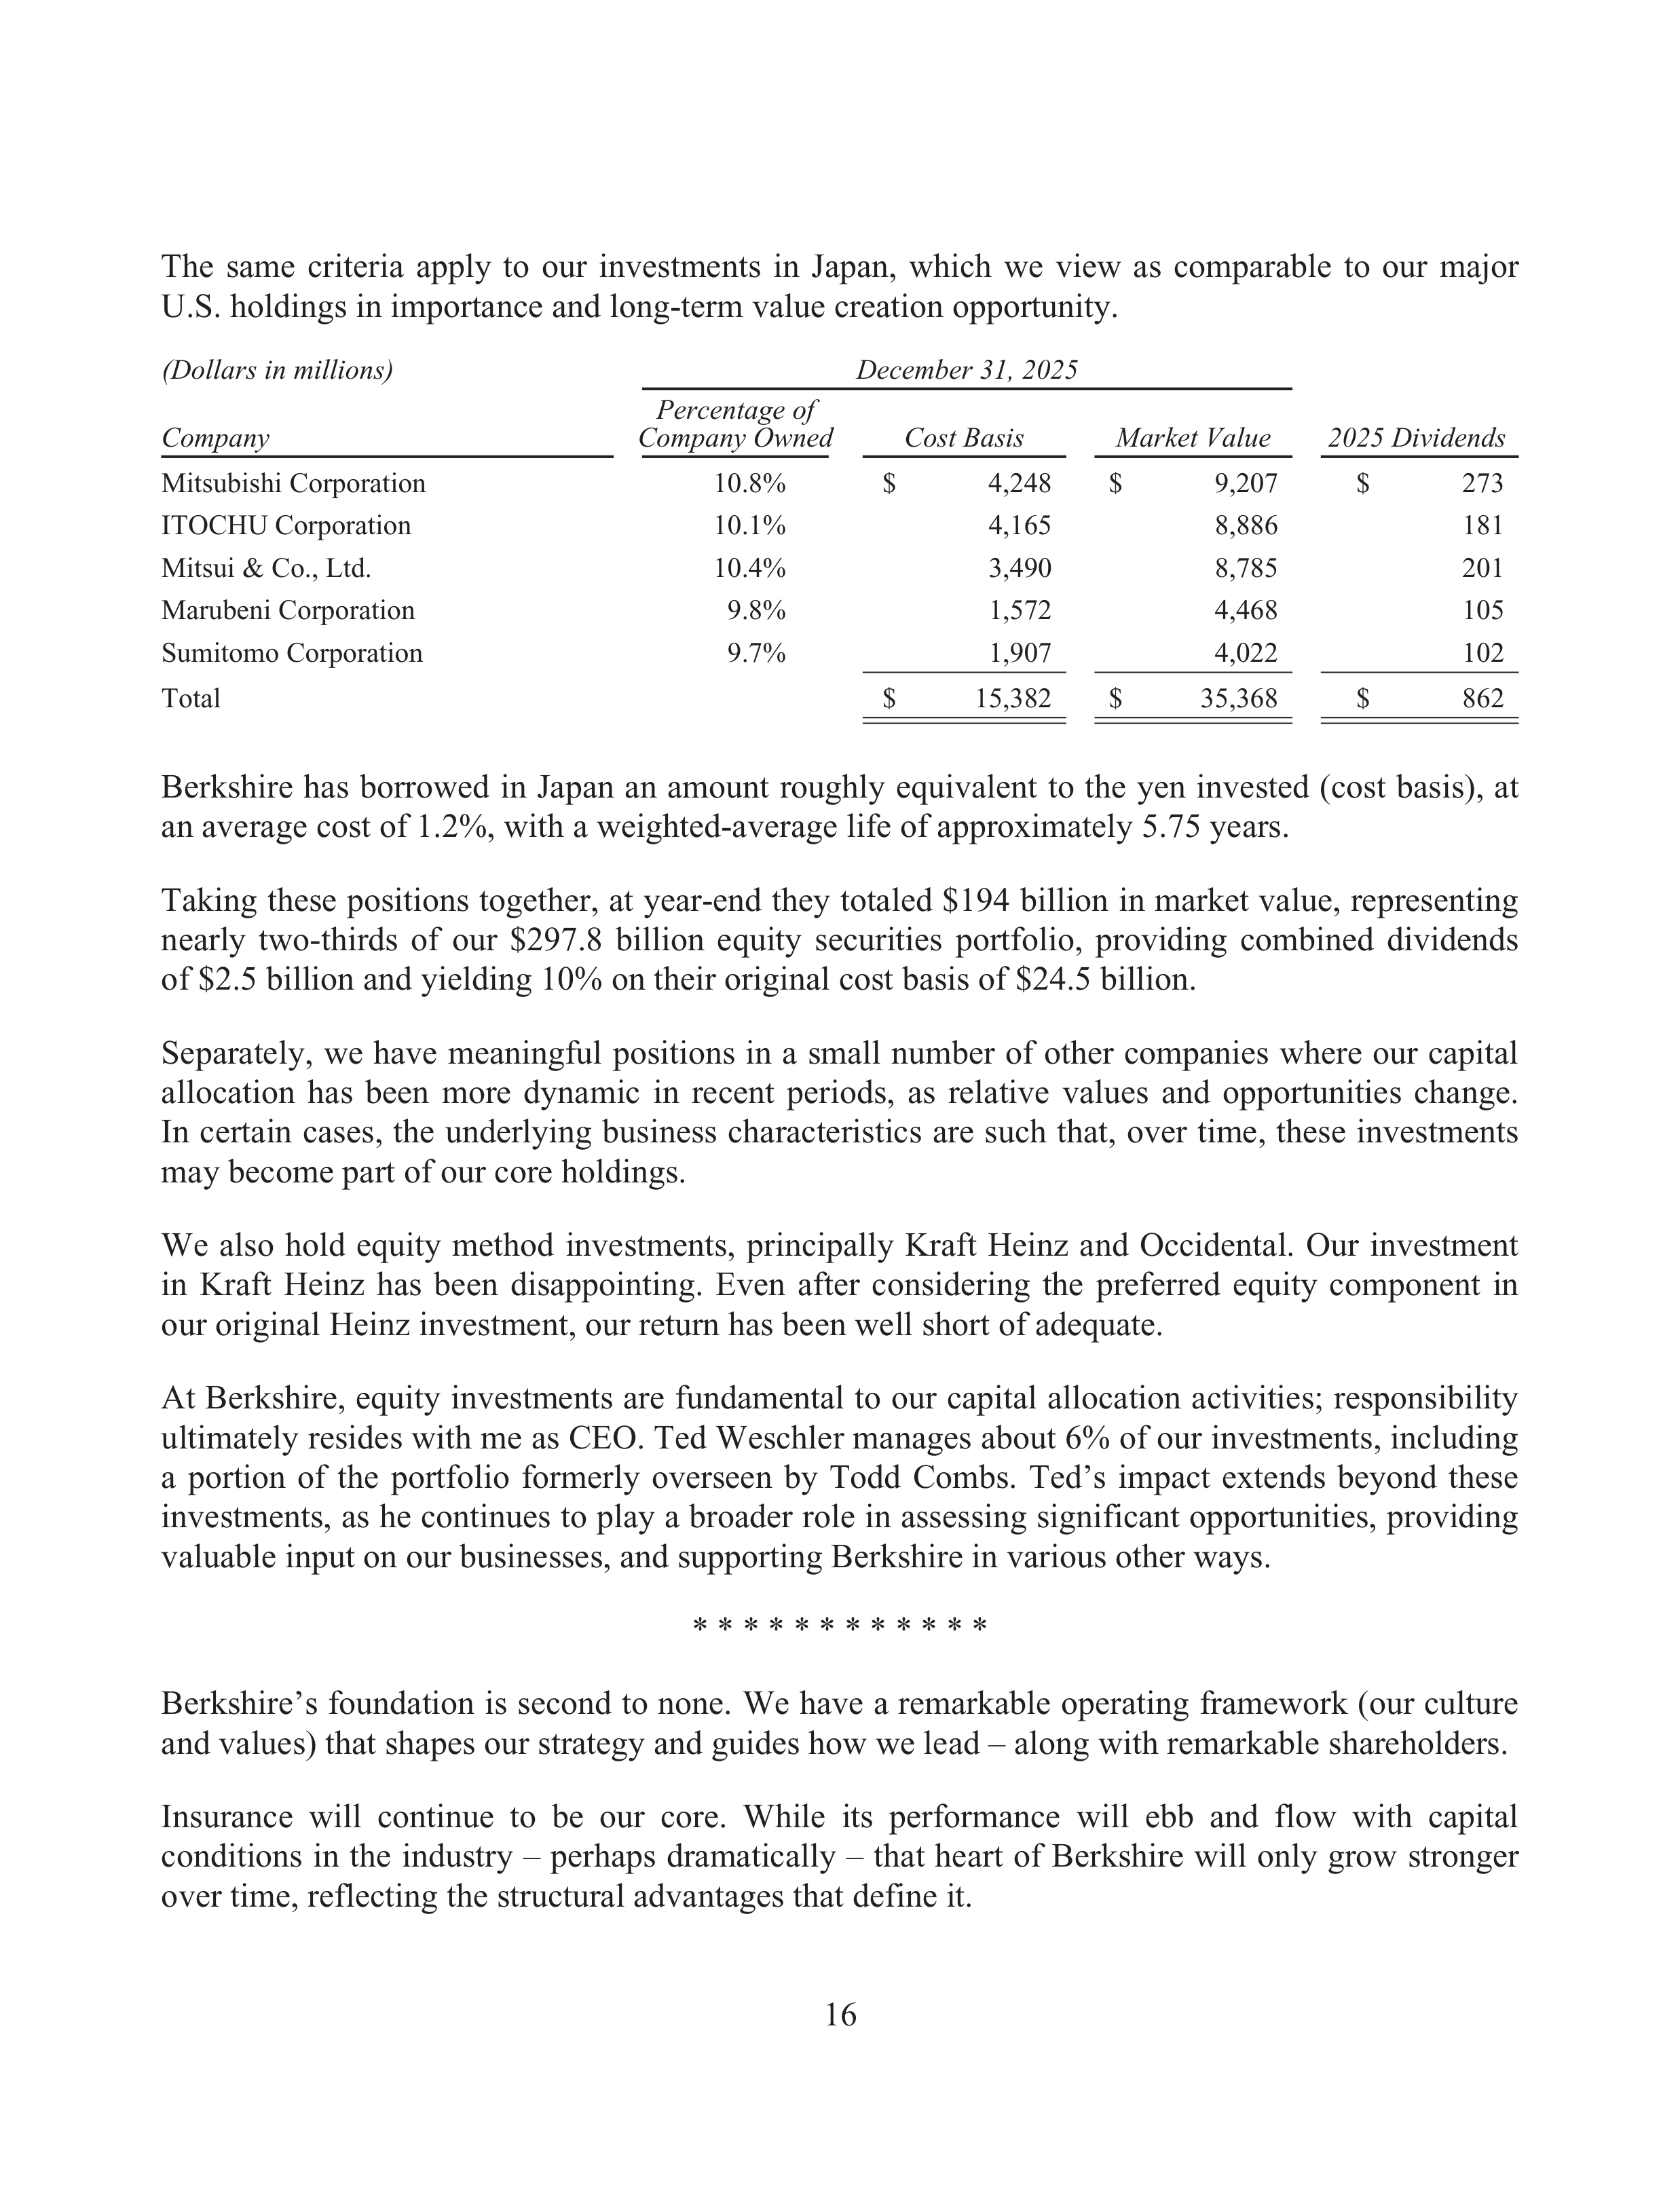
We apply the same fundamental value of capital discipline to Berkshire’s portfolio of equity
securities as we do to our operating businesses. A large portion of our portfolio is concentrated in
a small number of American companies such as Apple, American Express, Coca-Cola, and
Moody’s – businesses we understand well, have a high regard for their leaders, and expect will
compound over decades. This concentrated approach will continue, with limited activity in these
holdings, though we may significantly adjust a holding if we see fundamental changes in its long-
term economic prospects.
(Dollars in millions)
December 31, 2025
Company
Percentage of
Company Owned
Cost Basis
Market Value
2025 Dividends
Apple Inc.
1.6%
$
6,255
$
61,962
$
280
American Express Company
22.1%
1,287
56,088
479
The Coca-Cola Company
9.3%
1,299
27,964
816
Moody’s Corporation
13.9%
248
12,603
93
Total
$
9,089
$
158,617
$
1,668
15
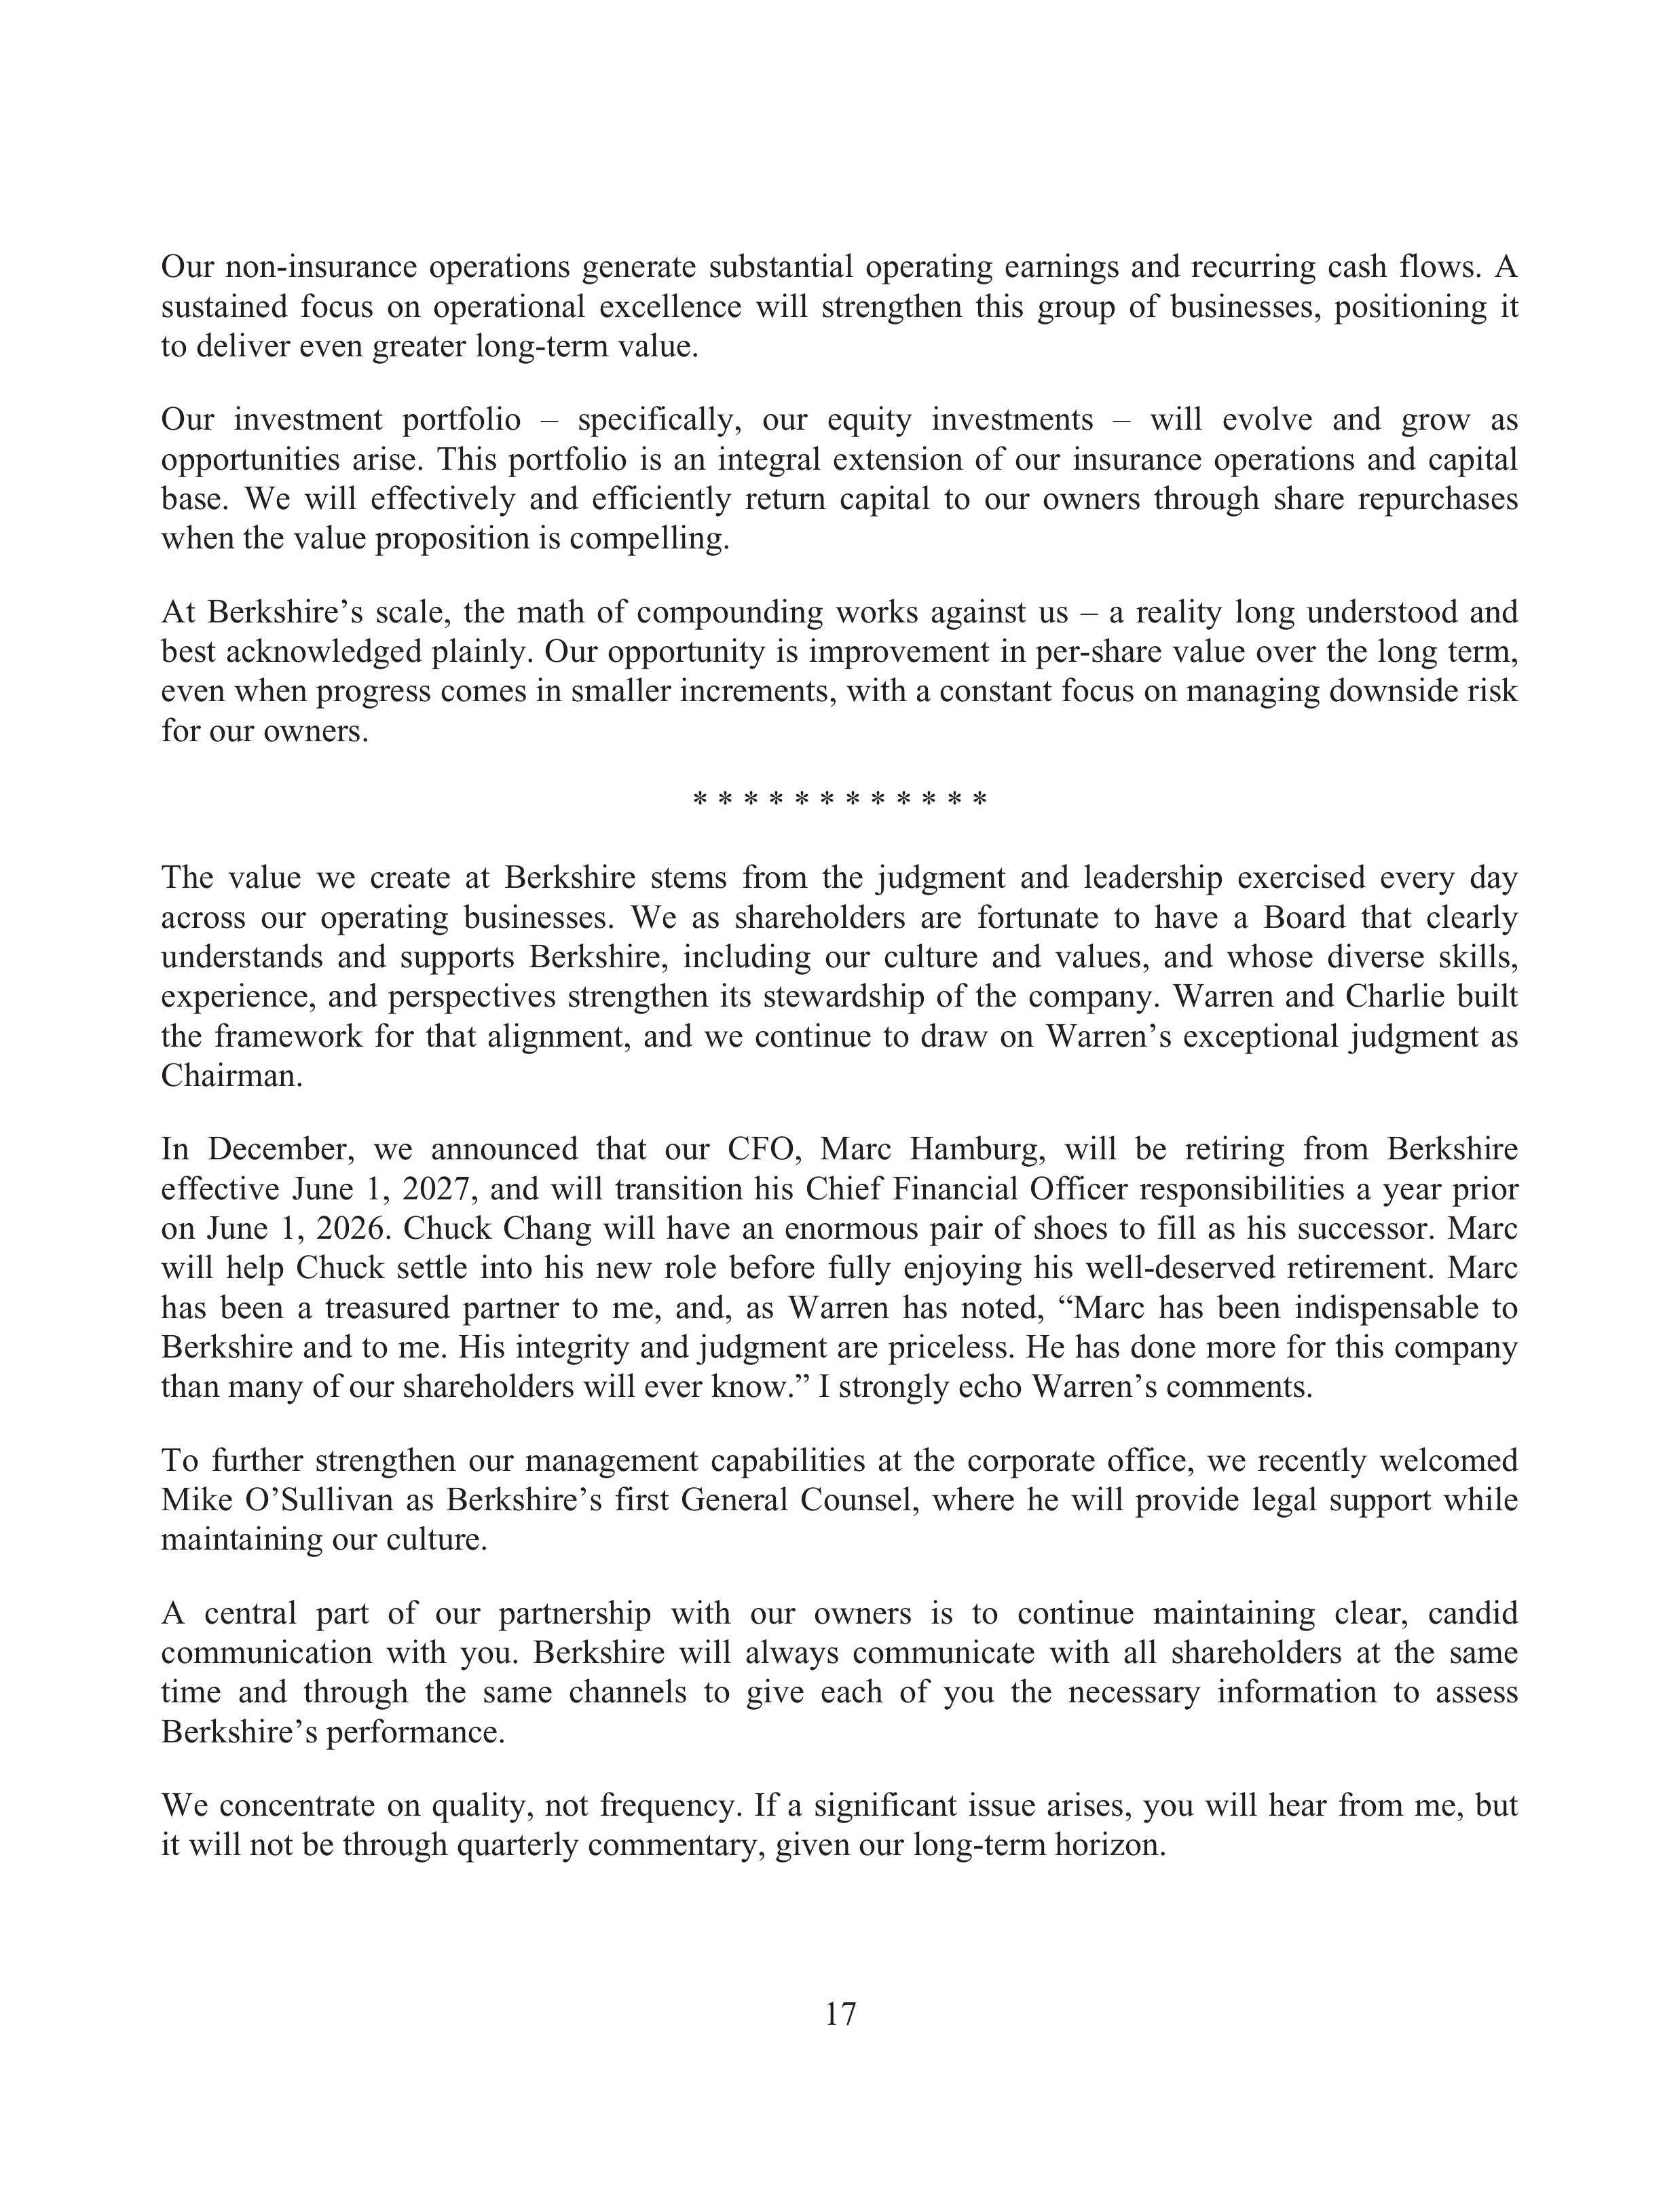
The same criteria apply to our investments in Japan, which we view as comparable to our major
U.S. holdings in importance and long-term value creation opportunity.
(Dollars in millions)
December 31, 2025
Company
Percentage of
Company Owned
Cost Basis
Market Value
2025 Dividends
Mitsubishi Corporation
10.8%
$
4,248
$
9,207
$
273
ITOCHU Corporation
10.1%
4,165
8,886
181
Mitsui & Co., Ltd.
10.4%
3,490
8,785
201
Marubeni Corporation
9.8%
1,572
4,468
105
Sumitomo Corporation
9.7%
1,907
4,022
102
Total
$
15,382
$
35,368
$
862
Berkshire has borrowed in Japan an amount roughly equivalent to the yen invested (cost basis), at
an average cost of 1.2%, with a weighted-average life of approximately 5.75 years.
Taking these positions together, at year-end they totaled $194 billion in market value, representing
nearly two-thirds of our $297.8 billion equity securities portfolio, providing combined dividends
of $2.5 billion and yielding 10% on their original cost basis of $24.5 billion.
Separately, we have meaningful positions in a small number of other companies where our capital
allocation has been more dynamic in recent periods, as relative values and opportunities change.
In certain cases, the underlying business characteristics are such that, over time, these investments
may become part of our core holdings.
We also hold equity method investments, principally Kraft Heinz and Occidental. Our investment
in Kraft Heinz has been disappointing. Even after considering the preferred equity component in
our original Heinz investment, our return has been well short of adequate.
At Berkshire, equity investments are fundamental to our capital allocation activities; responsibility
ultimately resides with me as CEO. Ted Weschler manages about 6% of our investments, including
a portion of the portfolio formerly overseen by Todd Combs. Ted’s impact extends beyond these
investments, as he continues to play a broader role in assessing significant opportunities, providing
valuable input on our businesses, and supporting Berkshire in various other ways.
* * * * * * * * * * * *
Berkshire’s foundation is second to none. We have a remarkable operating framework (our culture
and values) that shapes our strategy and guides how we lead – along with remarkable shareholders.
Insurance will continue to be our core. While its performance will ebb and flow with capital
conditions in the industry – perhaps dramatically – that heart of Berkshire will only grow stronger
over time, reflecting the structural advantages that define it.
16
Our non-insurance operations generate substantial operating earnings and recurring cash flows. A
sustained focus on operational excellence will strengthen this group of businesses, positioning it
to deliver even greater long-term value.
Our investment portfolio – specifically, our equity investments – will evolve and grow as
opportunities arise. This portfolio is an integral extension of our insurance operations and capital
base. We will effectively and efficiently return capital to our owners through share repurchases
when the value proposition is compelling.
At Berkshire’s scale, the math of compounding works against us – a reality long understood and
best acknowledged plainly. Our opportunity is improvement in per-share value over the long term,
even when progress comes in smaller increments, with a constant focus on managing downside risk
for our owners.
* * * * * * * * * * * *
The value we create at Berkshire stems from the judgment and leadership exercised every day
across our operating businesses. We as shareholders are fortunate to have a Board that clearly
understands and supports Berkshire, including our culture and values, and whose diverse skills,
experience, and perspectives strengthen its stewardship of the company. Warren and Charlie built
the framework for that alignment, and we continue to draw on Warren’s exceptional judgment as
Chairman.
In December, we announced that our CFO, Marc Hamburg, will be retiring from Berkshire
effective June 1, 2027, and will transition his Chief Financial Officer responsibilities a year prior
on June 1, 2026. Chuck Chang will have an enormous pair of shoes to fill as his successor. Marc
will help Chuck settle into his new role before fully enjoying his well-deserved retirement. Marc
has been a treasured partner to me, and, as Warren has noted, “Marc has been indispensable to
Berkshire and to me. His integrity and judgment are priceless. He has done more for this company
than many of our shareholders will ever know.” I strongly echo Warren’s comments.
To further strengthen our management capabilities at the corporate office, we recently welcomed
Mike O’Sullivan as Berkshire’s first General Counsel, where he will provide legal support while
maintaining our culture.
A central part of our partnership with our owners is to continue maintaining clear, candid
communication with you. Berkshire will always communicate with all shareholders at the same
time and through the same channels to give each of you the necessary information to assess
Berkshire’s performance.
We concentrate on quality, not frequency. If a significant issue arises, you will hear from me, but
it will not be through quarterly commentary, given our long-term horizon.
17
The next time we gather as owners will be in Omaha on May 2, 2026, for the annual meeting (our
owners’ day, or what other companies might call an “investor day”). The format you know well
will guide the day, centered on open communication and direct engagement, with your questions
answered in the same unscripted manner during sessions moderated by Becky Quick. We also look
forward to owners getting to know, over time, more of the Berkshire team.
This year’s program will include a CEO’s update on Berkshire, and two Q&A sessions – one with
Ajit and me, and a second featuring Katie Farmer (BNSF), Adam Johnson (NetJets and president
of consumer products, service, and retailing), and me, where Katie and Adam will discuss the
challenges and opportunities they see in their respective businesses. In that way, we will be able
to cover Berkshire’s insurance and non-insurance operations. While each session has a natural
focus based on who is on stage with me, shareholders may ask me any question at any time. Further
details are included in this Annual Report.
Our Board, the CEOs and managers at Berkshire, and I look forward to welcoming you to Omaha
and to our continued partnership. Central to Berkshire’s extraordinary success is the relationship
we maintain with you, our owners. I am honored by the responsibility of continuing to build our
company and our partnership in the years ahead. We move forward with great intent and purpose.
Gregory E. Abel
Chief Executive Officer
February 28, 2026
18
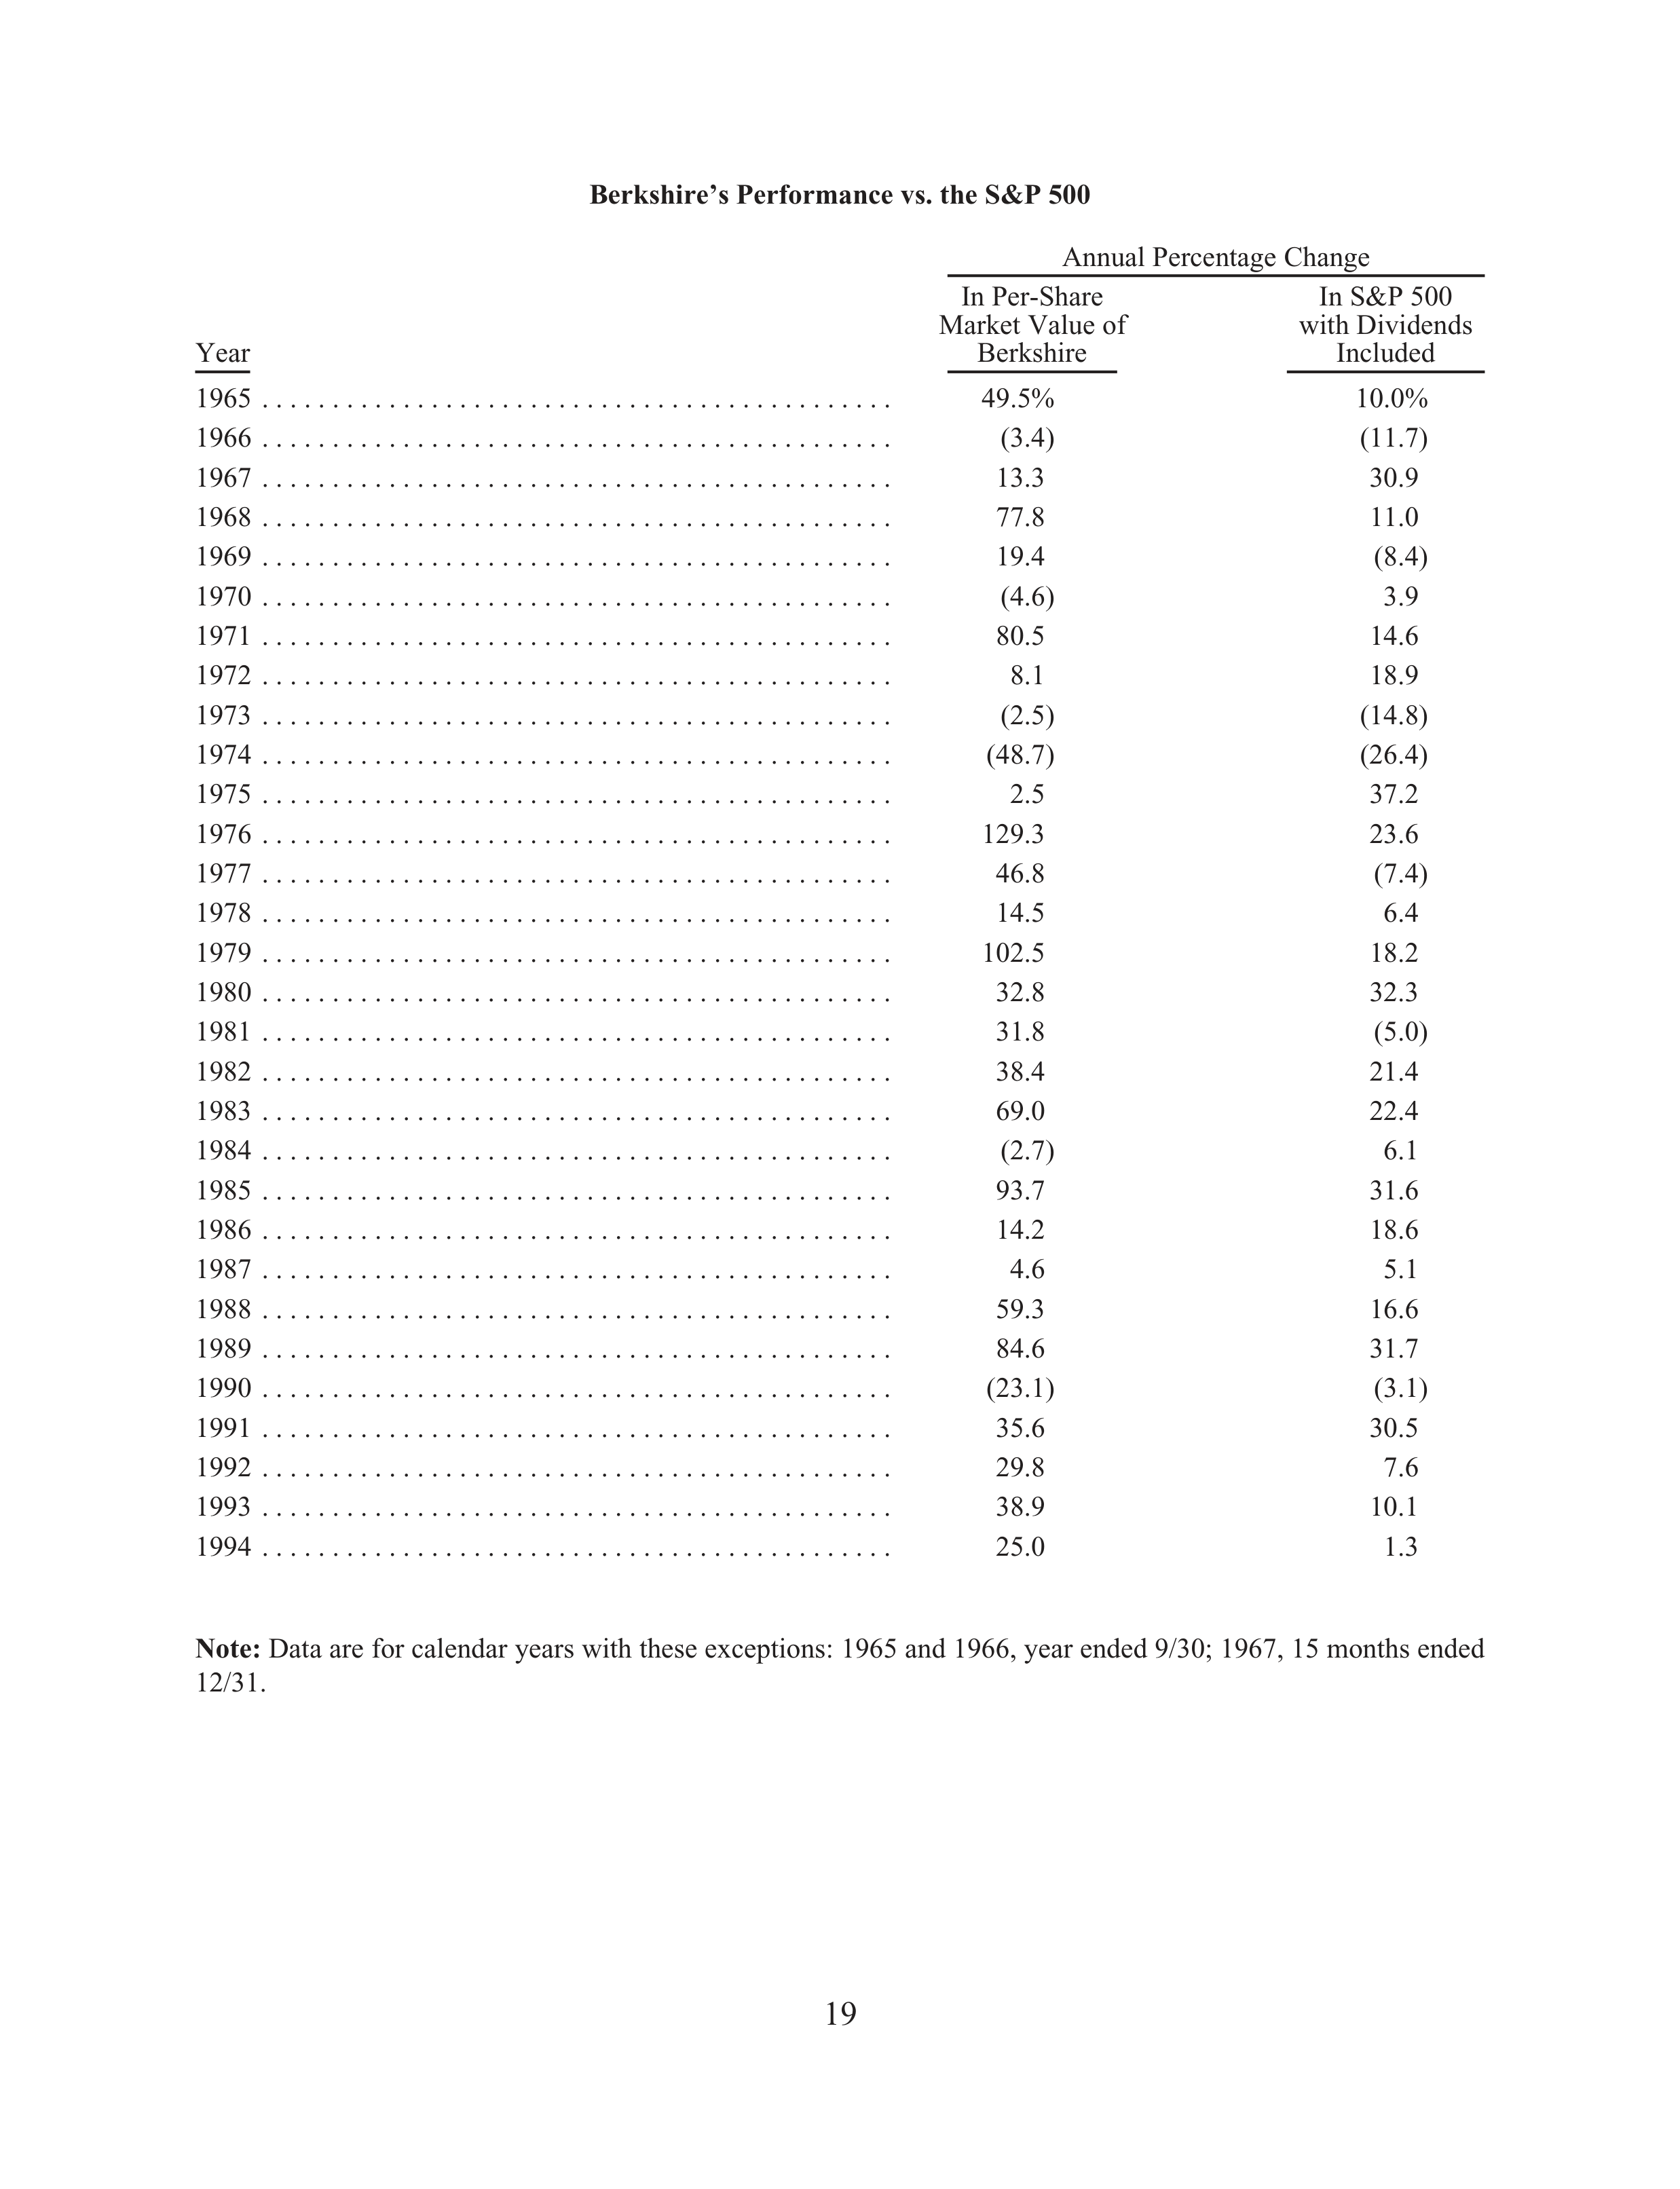
Berkshire’s Performance vs. the S&P 500
Annual Percentage Change
Year
In Per-Share
Market Value of
Berkshire
In S&P 500
with Dividends
Included
1965 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
49.5%
10.0%
1966 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3.4)
(11.7)
1967 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
13.3
30.9
1968 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
77.8
11.0
1969 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
19.4
(8.4)
1970 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4.6)
3.9
1971 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
80.5
14.6
1972 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
8.1
18.9
1973 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2.5)
(14.8)
1974 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(48.7)
(26.4)
1975 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
2.5
37.2
1976 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
129.3
23.6
1977 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
46.8
(7.4)
1978 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
14.5
6.4
1979 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
102.5
18.2
1980 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
32.8
32.3
1981 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
31.8
(5.0)
1982 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
38.4
21.4
1983 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
69.0
22.4
1984 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2.7)
6.1
1985 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
93.7
31.6
1986 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
14.2
18.6
1987 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
4.6
5.1
1988 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
59.3
16.6
1989 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
84.6
31.7
1990 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(23.1)
(3.1)
1991 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
35.6
30.5
1992 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
29.8
7.6
1993 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
38.9
10.1
1994 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
25.0
1.3
Note:
Data are for calendar years with these exceptions: 1965 and 1966, year ended 9/30; 1967, 15 months ended
12/31.
19
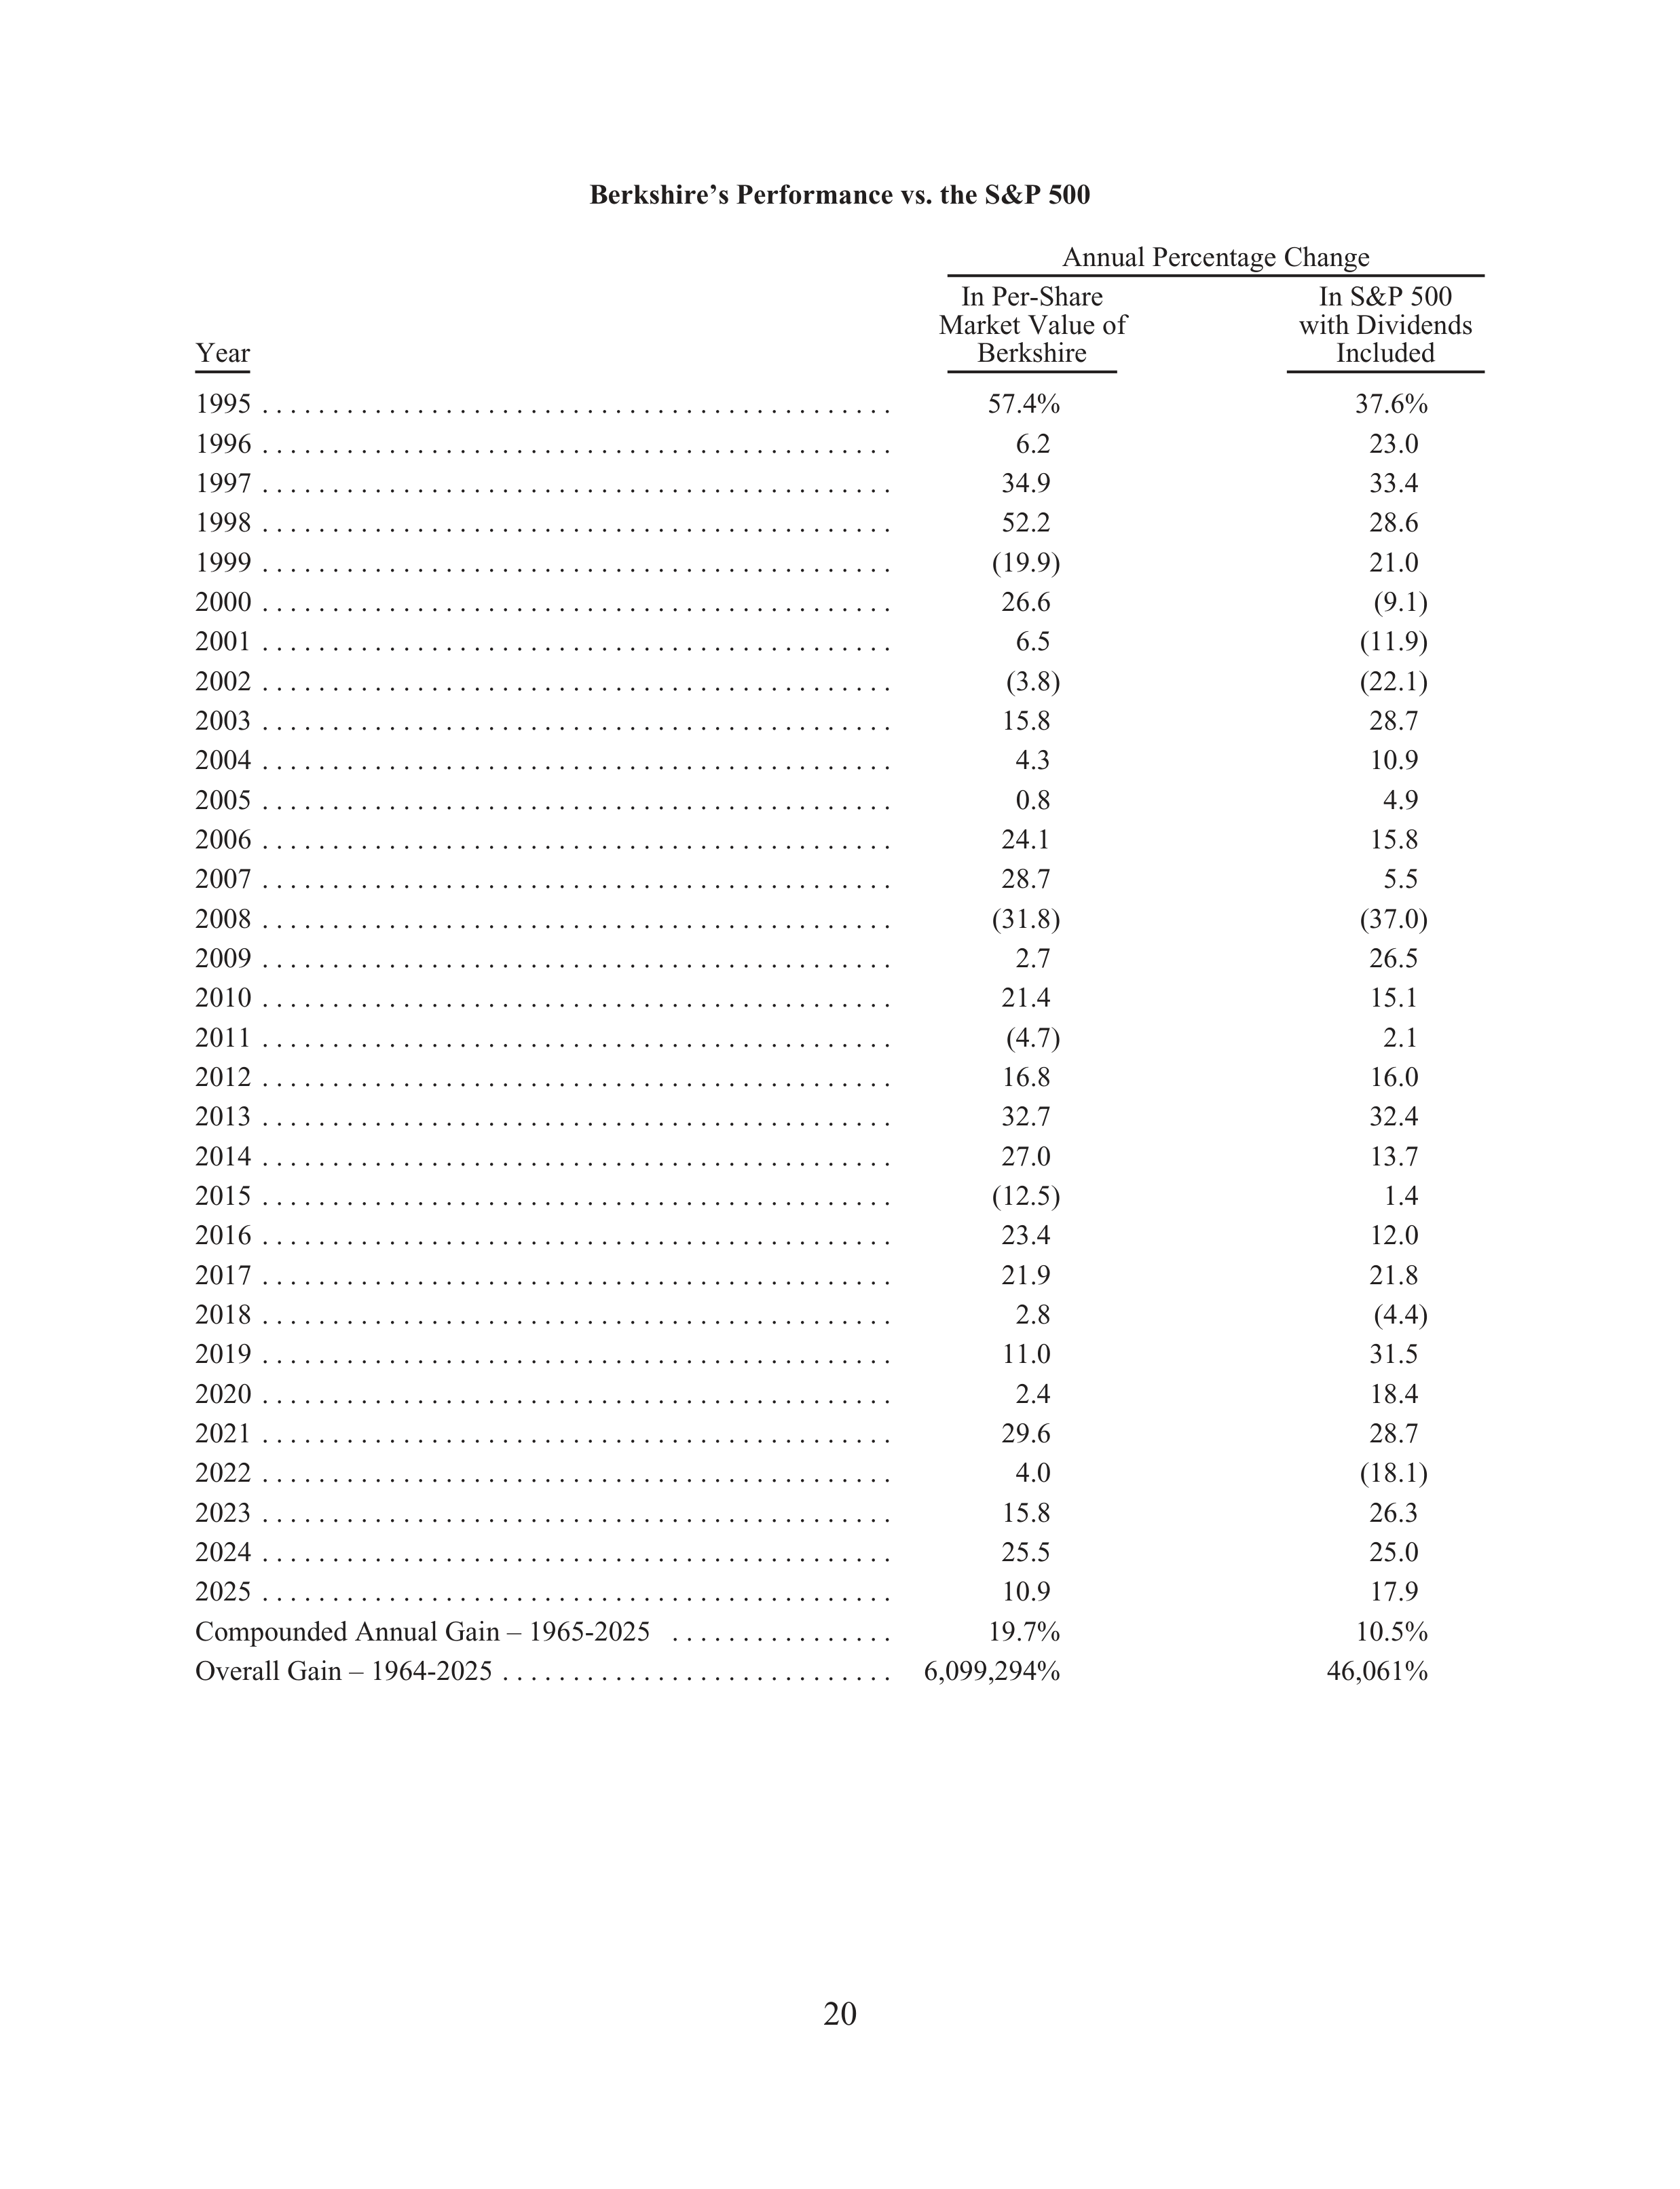
Berkshire’s Performance vs. the S&P 500
Annual Percentage Change
Year
In Per-Share
Market Value of
Berkshire
In S&P 500
with Dividends
Included
1995 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
57.4%
37.6%
1996 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
6.2
23.0
1997 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
34.9
33.4
1998 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
52.2
28.6
1999 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(19.9)
21.0
2000 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
26.6
(9.1)
2001 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
6.5
(11.9)
2002 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3.8)
(22.1)
2003 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
15.8
28.7
2004 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
4.3
10.9
2005 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
0.8
4.9
2006 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
24.1
15.8
2007 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
28.7
5.5
2008 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(31.8)
(37.0)
2009 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
2.7
26.5
2010 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
21.4
15.1
2011 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4.7)
2.1
2012 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
16.8
16.0
2013 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
32.7
32.4
2014 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
27.0
13.7
2015 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(12.5)
1.4
2016 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
23.4
12.0
2017 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
21.9
21.8
2018 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
2.8
(4.4)
2019 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
11.0
31.5
2020 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
2.4
18.4
2021 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
29.6
28.7
2022 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
4.0
(18.1)
2023 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
15.8
26.3
2024 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
25.5
25.0
2025 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
10.9
17.9
Compounded Annual Gain – 1965-2025 . . . . . . . . . . . . . . . .
19.7%
10.5%
Overall Gain – 1964-2025 . . . . . . . . . . . . . . . . . . . . . . . . . . . .
6,099,294%
46,061%
20
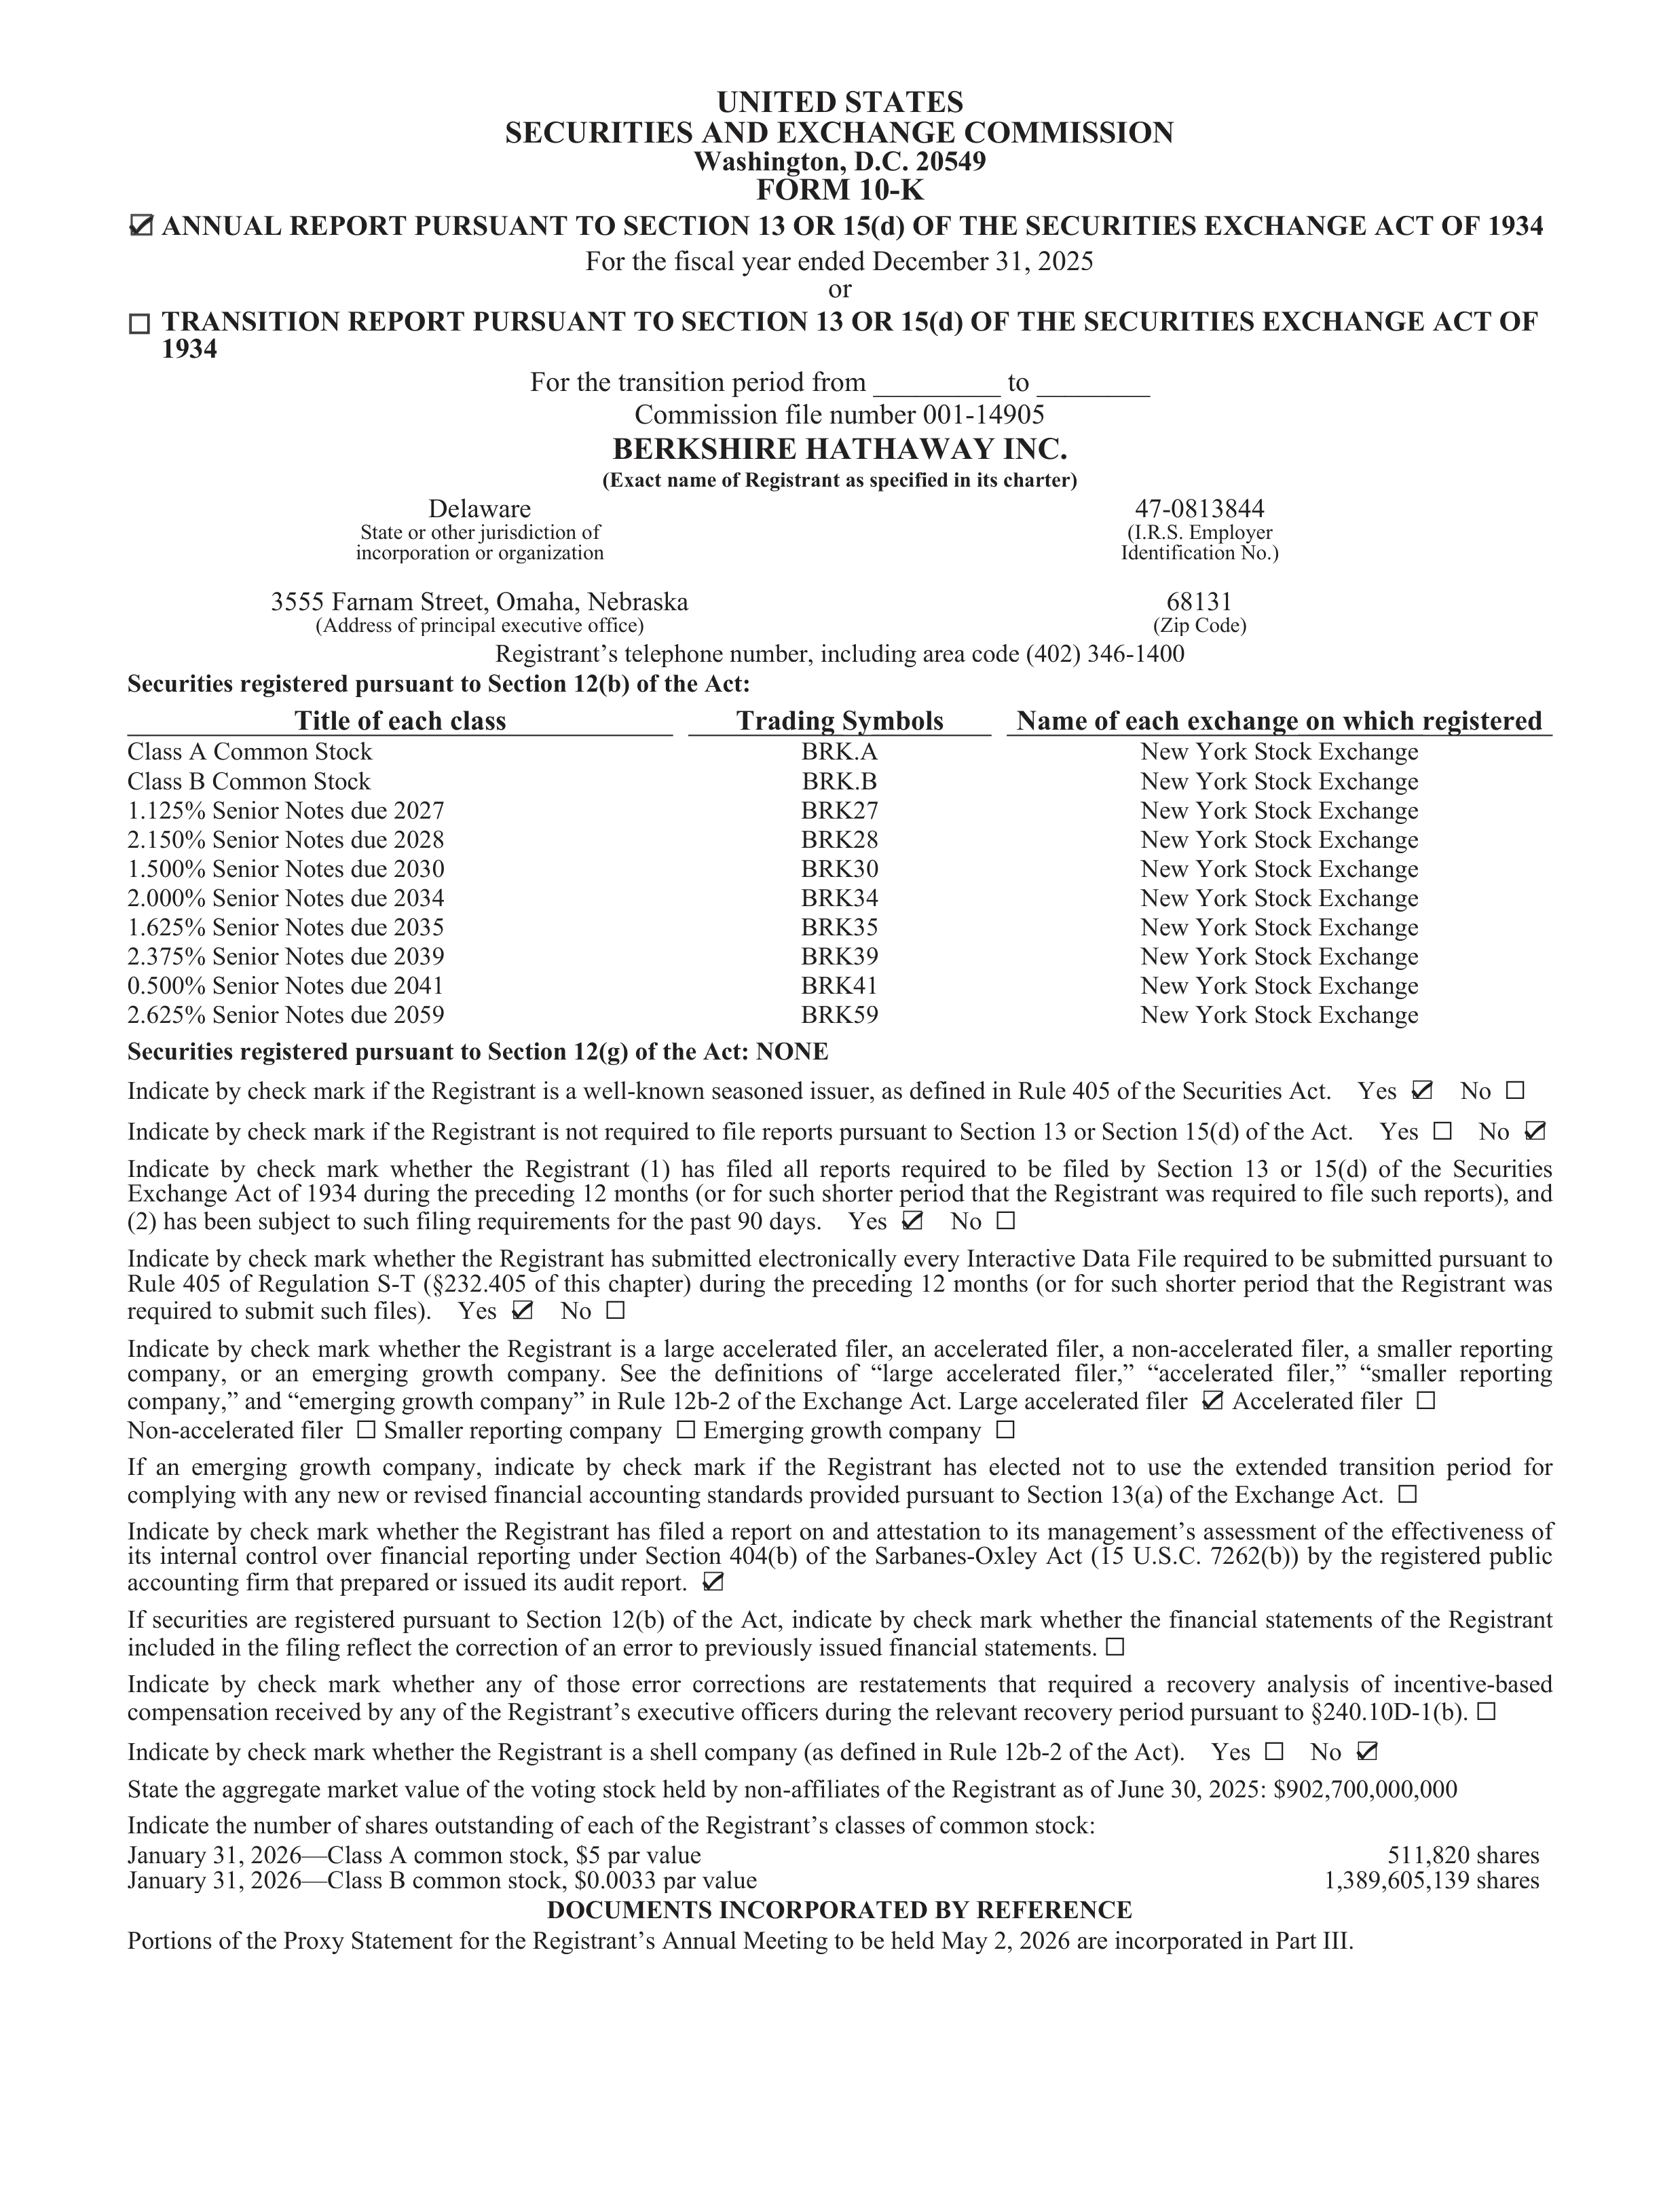
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
☑
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2025
or
☐
TRANS
R
ITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF
1934
For the transition period from _________ to ________
Commission file number 001-14905
BERKSHIRE HATHAWAY INC.
(Exact name of Registrant as specified in its charter)
Delaware
47-0813844
State or other jurisdiction of
incorporation or organization
(I.R.S. Employer
Identific
f
ation No.)
3555 Farnam Street, Omaha, Nebraska
68131
(Address of principal executive offi
f
ce)
(Zip Code)
Registrant’s telephone number, including area code (402) 346-1400
Securities registered pursuant to Section 12(b) of the Act:
Title of each class
Trading Symbols
Name of each exchange on which registered
Class A Common Stock
Class B Common Stock
1.125% Senior Notes due 2027
2.150% Senior Notes due 2028
1.500% Senior Notes due 2030
2.000% Senior Notes due 2034
1.625% Senior Notes due 2035
2.375% Senior Notes due 2039
0.500% Senior Notes due 2041
2.625% Senior Notes due 2059
BRK.A
BRK.B
BRK27
BRK28
BRK30
BRK34
BRK35
BRK39
BRK41
BRK59
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
New York Stock Exchange
Securities registered pursuant to Section 12(g) of the Act: NONE
Indicate by check mark if the Registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
Yes
☑
No
☐
Indicate by check mark if the Registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act.
Yes
☐
No
☑
Indicate
by
check
mark
whether
the
Registrant
(1)
has
filed
all
reports
required
to
be
filed
by
Section
13
or
15(d)
of
the
Securities
Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the Registrant was required to file such reports), and
(2) has been subj
u
ect to such filing requirements for the past 90 days.
Yes
☑
No
☐
Indicate by check mark whether the Registrant has subm
u
itted electronically every
r
Interactive Data File required to be subm
u
itted pursuant to
Rule
405
of
Regulation
S-T
(§232.405
of
this
chapter)
during
the
preceding
12
months
(or
for
such
shorter
period
that
the
Registrant
was
required to subm
u
it such files).
Yes
☑
No
☐
Indicate
by
check
mark
whether
the
Registrant
is
a
large
accelerated
filer,
an
accelerated
filer,
a
non-accelerated
filer,
a
smaller
reporting
company,
or
an
emerging
growth
company.
See
the
definitions
of
“large
accelerated
filer,”
“accelerated
filer,”
“smaller
reporting
company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. Large accelerated filer
☑
Accelerated filer
☐
Non-accelerated filer
☐
Smaller reporting company
☐
Emerging growth company
☐
If
an
emerging
growth
company,
indicate
by
check
mark
if
the
Registrant
has
elected
not
to
use
the
extended
transition
period
for
complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
☐
Indicate by check mark whether the Registrant has filed a report on and attestation to its management’s assessment of the effe
f
ctiveness of
its
internal
control
over
financial
reporting
under
Section
404(b)
of
the
Sarbanes-Oxley
Act
(15
U.S.C.
7262(b))
by
the
registered
public
accounting firm that prepared or issued its audit report.
☑
If
securities
are
registered
pursuant
to
Section
12(b)
of
the
Act,
indicate
by
check
mark
whether
the
financial
statements
of
the
Registrant
included in the filing reflect the correction of an error to previously issued financial statements.
☐
Indicate
by
check
mark
whether
any
of
those
error
corrections
are
restatements
that
required
a
recovery
analysis
of
incentive-based
compensation received by any of the Registrant’s executive offi
f
cers during the relevant recovery period pursuant to §240.10D-1(b).
☐
Indicate by check mark whether the Registrant is a shell company (as defined in Rule 12b-2 of the Act).
Yes
☐
No
☑
State the aggregate market value of the voting stock held by non-affi
f
liates of the Registrant as of June 30, 2025: $902,700,000,000
Indicate the number of shares outstanding of each of the Registrant’s classes of common stock:
January 31, 2026—Class A common stock, $5 par value
511,820 shares
January 31, 2026—Class B common stock, $0.0033 par value
1,389,605,139 shares
DOCUMENTS INCORPORAT
R
ED BY REFERENCE
Portions of the Proxy Statement for the Registrant’s Annual Meeting to be held May 2, 2026 are incorporated in Part III.
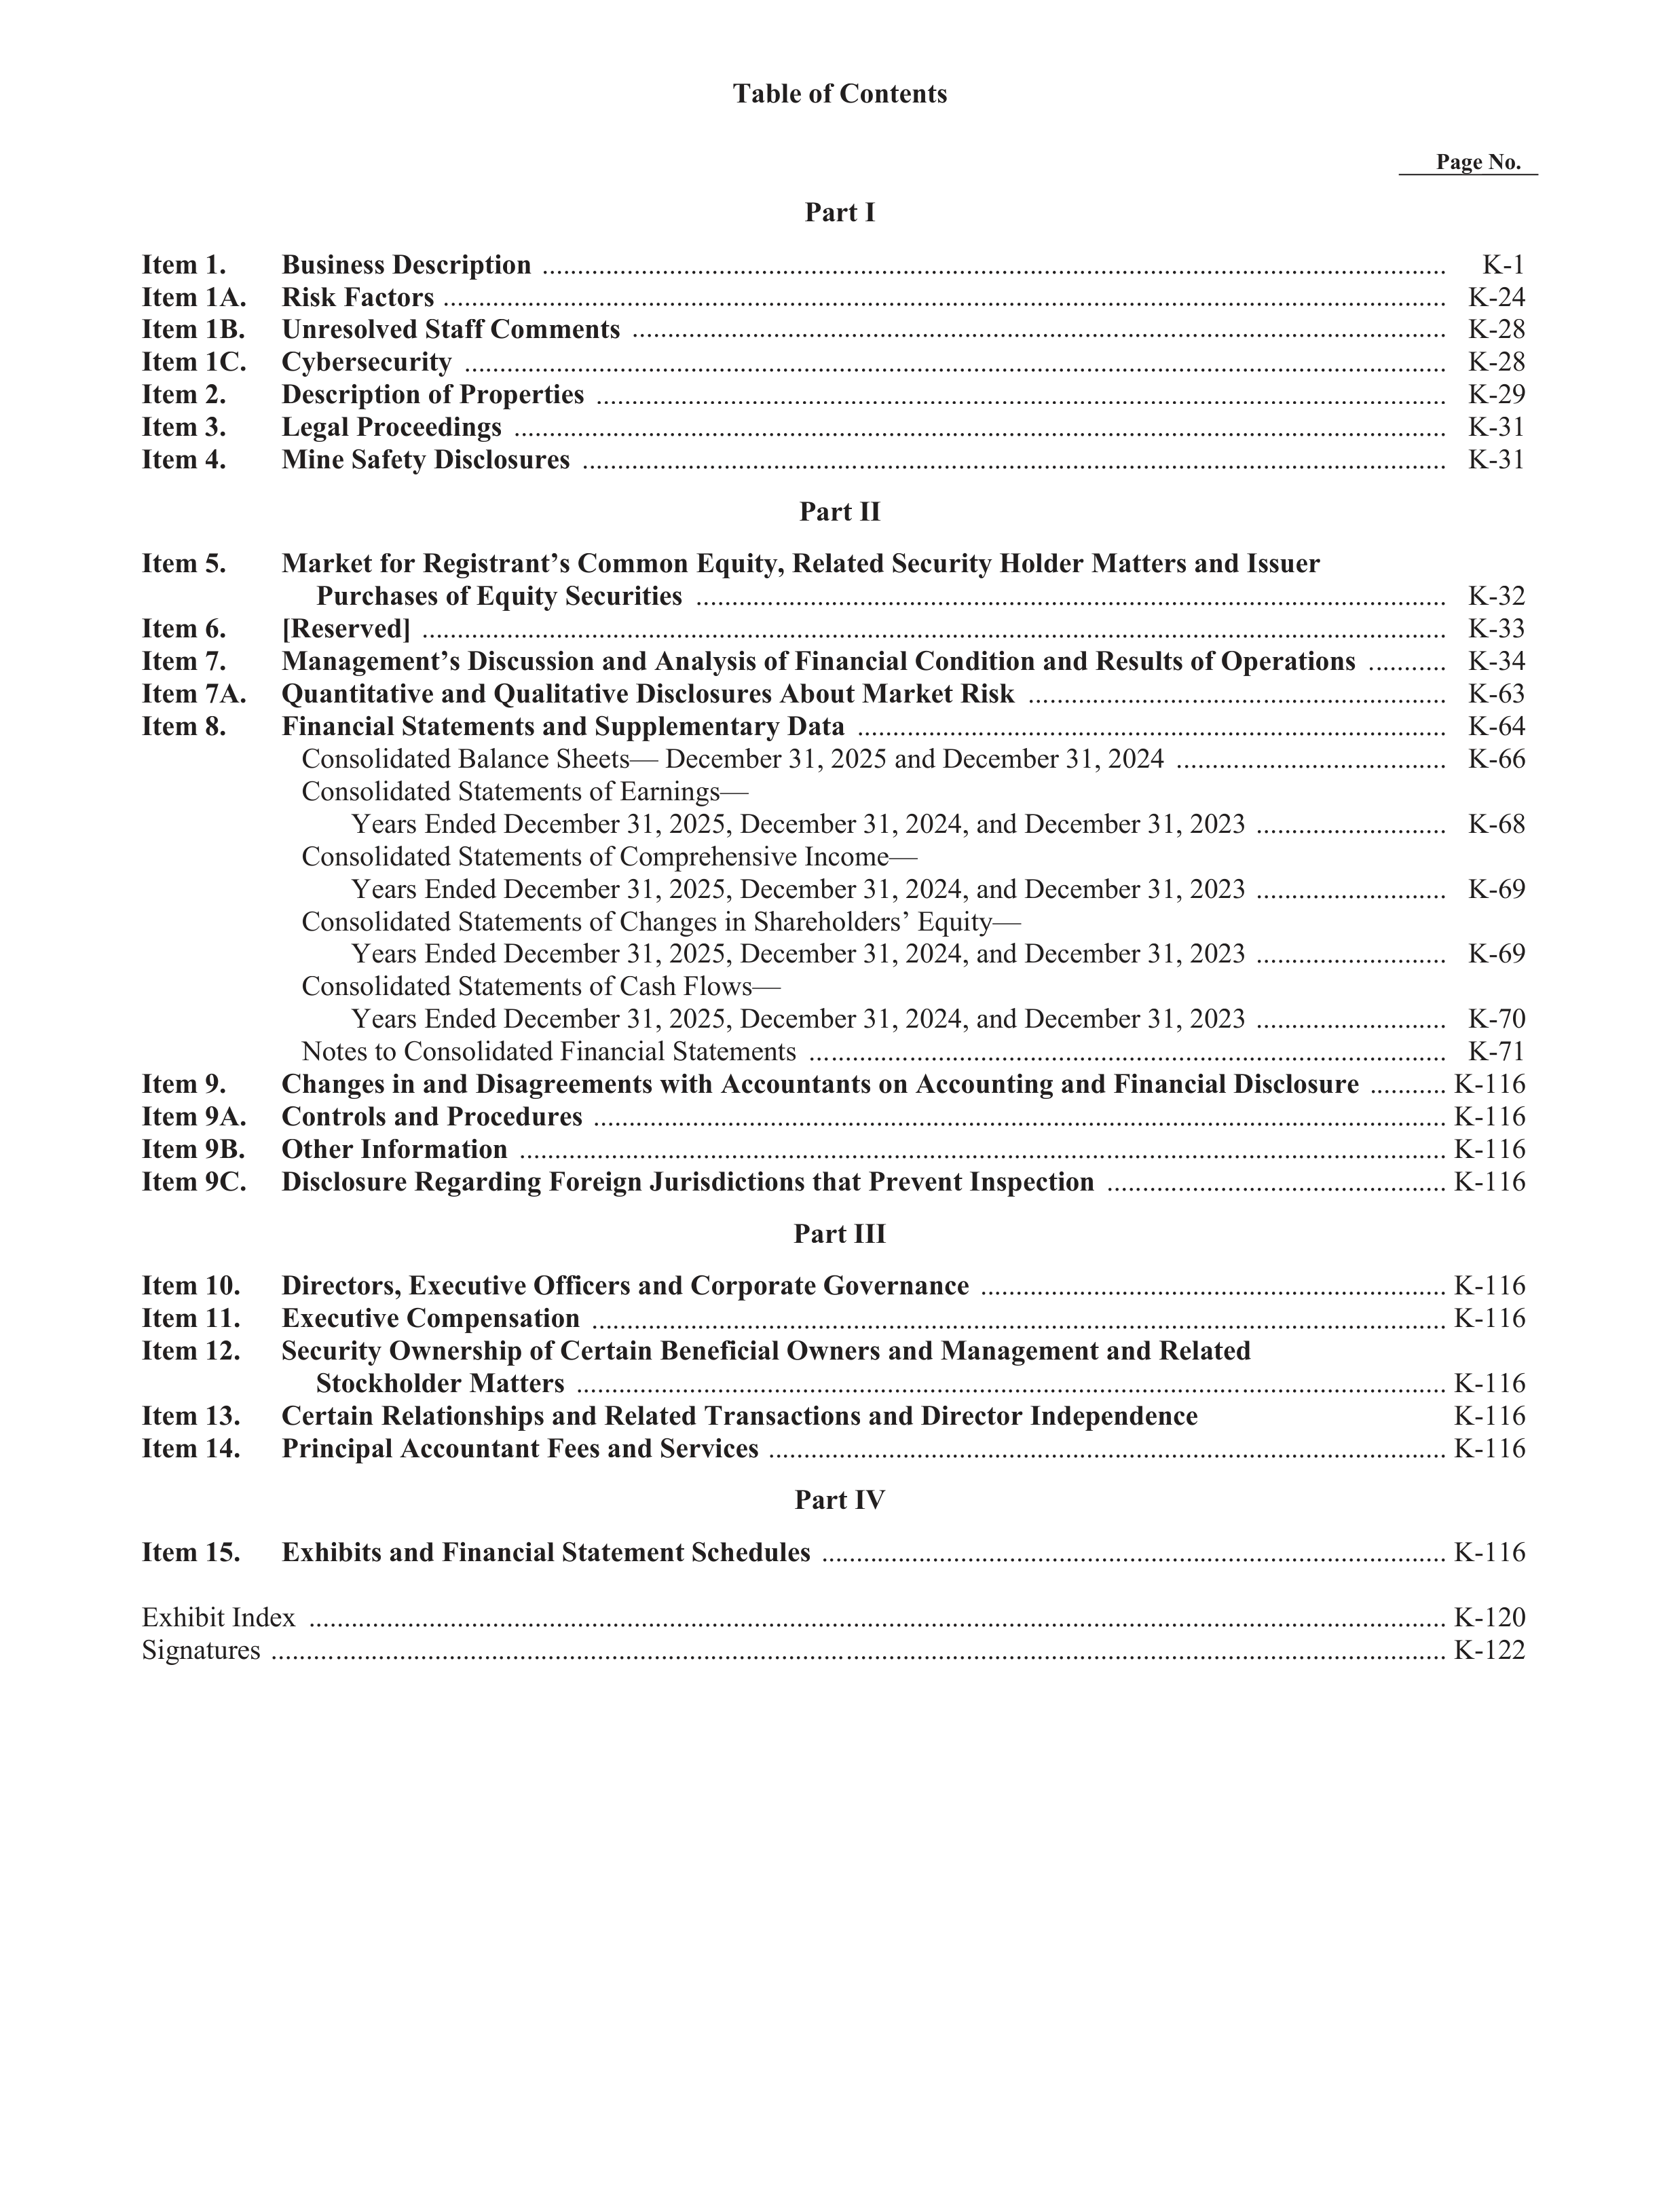
Table of Contents
Page No.
K-1
K-24
K-28
K-28
K-29
K-31
K-31
K-32
K-33
K-34
K-63
K-64
K-66
K-68
K-69
K-69
K-70
K-71
K-116
K-116
K-116
K-116
K-116
K-116
K-116
K-116
K-116
K-116
K-120
K-122
Part I
Item 1.
Business Description
Item 1A.
Risk Factors
Item 1B.
Unresolved Stafff
Comments
Item 1C.
Cybersecurity
Item 2.
Description of Properties
Item 3.
Legal Proceedings
Item 4.
Mine Safef
ty Disclosures
Part II
Item 5.
Market fo
f
r Registrant’s Common Equity, Related Security Holder Matters and Issuer
Purchases of Equity Securities
Item 6.
Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Item 7A.
Quantitative and Qualitative Disclosures About Market Risk
Item 8.
Financial Statements and Supplementary Data
Consolidated Balance Sheets— December 31, 2025 and December 31, 2024
Consolidated Statements of Earnings—
Years Ended December 31, 2025, December 31, 2024, and December 31, 2023
Consolidated Statements of Comprehensive Income—
Years Ended December 31, 2025, December 31, 2024, and December 31, 2023
Consolidated Statements of Changes in Shareholders’ Equity—
y
Years Ended December 31, 2025, December 31, 2024, and December 31, 2023
Consolidated Statements of Cash Flows—
Years Ended December 31, 2025, December 31, 2024, and December 31, 2023
Notes to Consolidated Financial Statements
Item 9.
Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
Item 9A.
Controls and Procedures
Item 9B.
Other Info
f
rmation
Item 9C.
Disclosure Regarding Foreign Jurisdictions that Prevent Inspection
Part III
Item 10.
Directors, Executive Offf
if cers and Corporate Governance
Item 11.
Executive Compensation
Item 12.
Security Ownership of Certain Benefif cial Owners and Management and Related
Stockholder Matters
Item 13.
Certain Relationships and Related Transactions and Director Independence
Item 14.
Principal Accountant Fees and Services
Part IV
Item 15.
Exhibits and Financial Statement Schedules
Exhibit Index
.................................................................................................................................................................
Signatut
res
......................................................................................................................................................................
[Reserved]
K-1
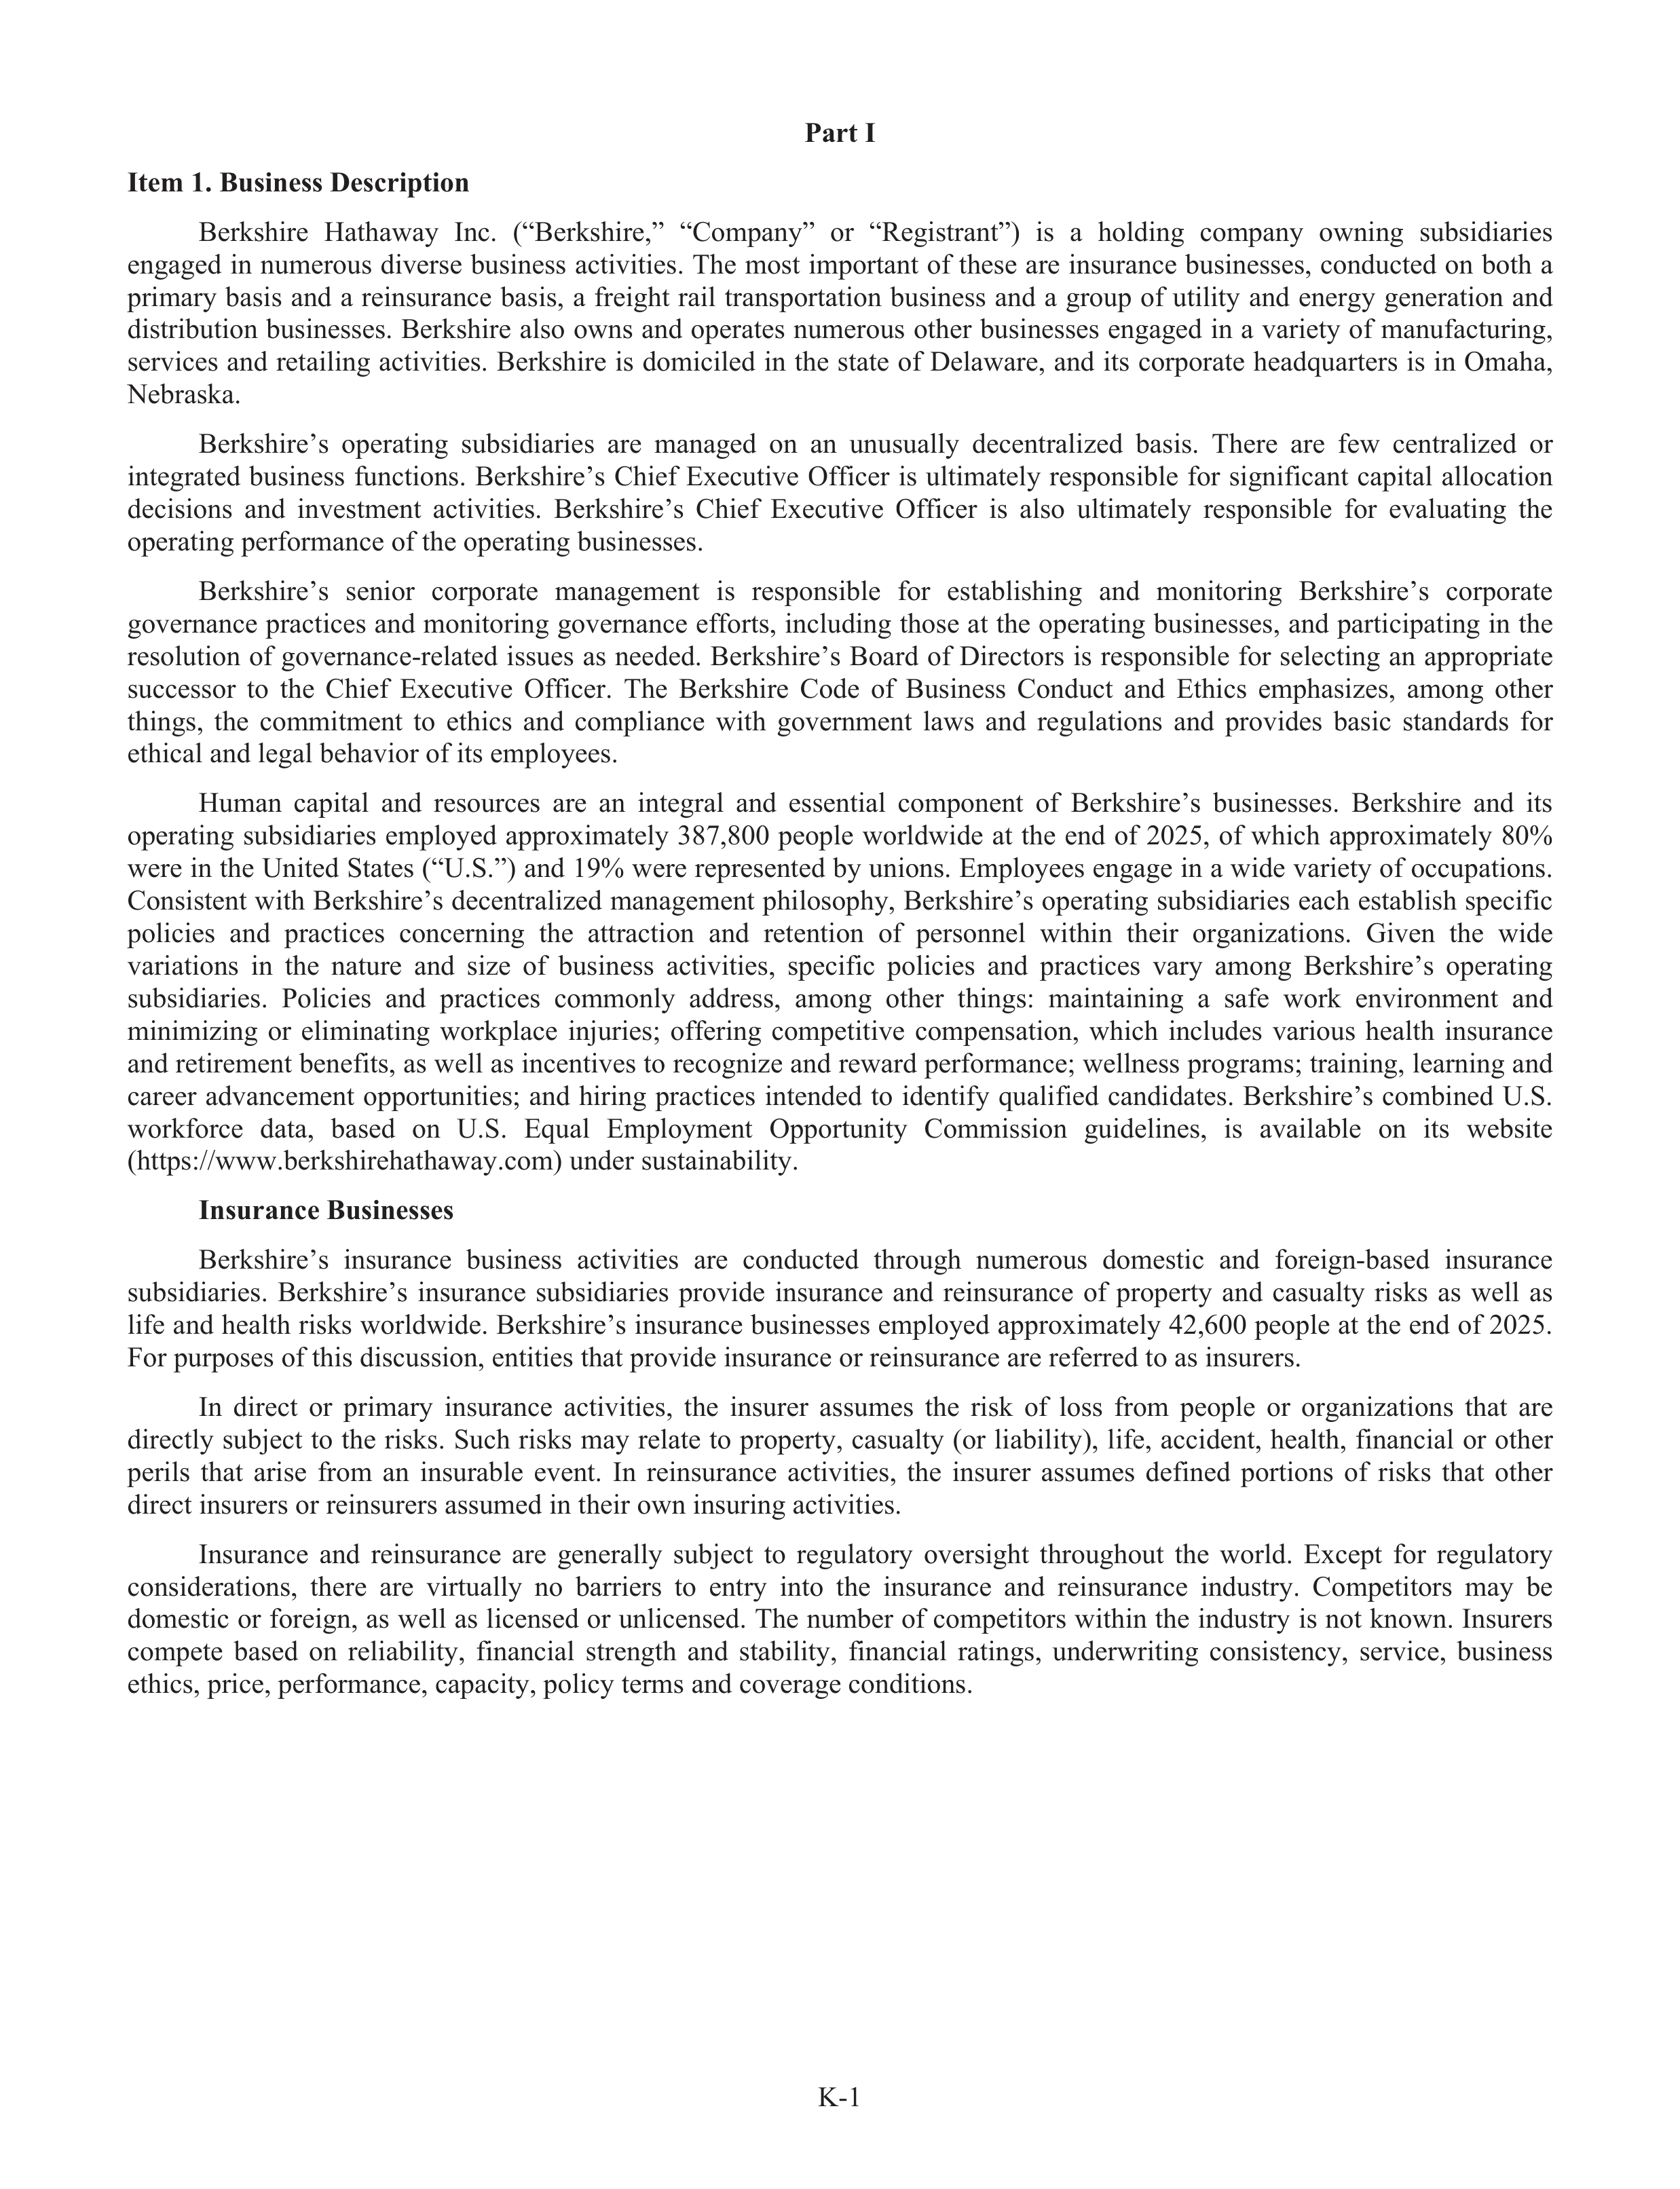
Part I
Item 1. Business Description
Berkshire
Hathaway
Inc.
(“Berkshire,”
“Company”
or
“Registrant”)
is
a
holding
company
owning
subs
u
idiaries
engaged in numerous diverse business activities. The most important of these are insurance businesses, conducted on both a
primary
basis
and
a
reinsurance
basis,
a
freight
rail
transportation
business
and
a
group
of
utility
and
energy
generation
and
distribution businesses. Berkshire also owns and operates numerous other businesses engaged in a variety of manufact
f
ur
t
ing,
services and retailing activities. Berkshire is domiciled in the state of Delaware, and its corporate headquarters is in Omaha,
Nebraska.
Berkshire’s
operating
subs
u
idiaries
are
managed
on
an
unusually
decentralized
basis.
There
are
few
centralized
or
integrated
business
functions.
Berkshire’s
Chief
Executive
Offi
f
cer
is
ultimately
responsible
for
significant
capital
allocation
decisions
and
investment
activities.
Berkshire’s
Chief
Executive
Offi
f
cer
is
also
ultimately
responsible
for
evaluating
the
operating performance of the operating businesses.
Berkshire’s
senior
corporate
management
is
responsible
for
establ
a
ishing
and
monitoring
Berkshire’s
corpor
r
ate
governance practices and monitoring governance effo
f
rts, including those at the operating businesses, and participating in the
resolution
of
governance-related
issues
as
needed.
Berkshire’s
Board
of
Directors
is
responsible
for
selecting
an
appropriate
successor
to
the
Chief
Executive
Offi
f
cer.
The
Berkshire
Code
of
Business
Conduct
and
Ethics
emphasizes,
among
other
things,
the
commitment
to
ethics
and
compliance
with
government
laws
and
regulations
and
provides
basic
standards
for
ethical and legal behavior of its employees.
Human
capital
and
resources
are
an
integral
and
essential
component
of
Berkshire’s
businesses.
Berkshire
and
its
operating
subs
u
idiaries
employed
approximately
387,800
people
worldwide
at
the
end
of
2025,
of
which
approximately
80%
were in the United States (“U.S.”) and 19% were represented by unions. Employees engage in a wide variety of occupa
u
tions.
Consistent with Berkshire’s decentralized management philosophy, Berkshire’s operating subs
u
idiaries each establ
a
ish specific
policies
and
practices
concerning
the
attraction
and
retention
of
personnel
within
their
organizations.
Given
the
wide
variations
in
the
nature
and
size
of
business
activities,
specific
policies
and
practices
vary
among
Berkshire’s
operating
subs
u
idiaries.
Policies
and
practices
commonly
address,
among
other
things:
maintaining
a
safe
work
environment
and
minimizing
or
eliminating
workpl
k
ace
inju
n
ries;
offe
f
ring
competitive
compensation,
which
includes
various
health
insurance
and retirement benefits, as well as incentives to recognize and reward performance; wellness programs; training, learning and
career
advancement
opportunities;
and
hiring
practices
intended
to
identify
f
qualifie
f
d
candidates.
Berkshire’s
combined
U.S.
workforce
data,
based
on
U.S.
Equal
Employment
Opportunity
Commission
guidelines,
is
availabl
a
e
on
its
website
(https://www.berkshirehathaway.com) under sustainabi
a
lity.
Insurance Businesses
Berkshire’s
insurance
business
activities
are
conducted
through
numerous
domestic
and
foreign-based
insurance
subs
u
idiaries.
Berkshire’s
insurance
subs
u
idiaries
provide
insurance
and
reinsurance
of
property
and
casualty
risks
as
well
as
lifef
and health risks worldwide. Berkshire’s insurance businesses employed approximately 42,600 people at the end of 2025.
For purpos
r
es of this discussion, entities that provide insurance or reinsurance are referred to as insurers.
In
direct
or
primary
insurance
activities,
the
insurer
assumes
the
risk
of
loss
from
people
or
organizations
that
are
directly
subj
u
ect
to
the
risks.
Such
risks
may
relate
to
property,
casualty
(or
liabi
a
lity),
life,
f
accident,
health,
financial
or
other
perils
that
arise
from
an
insurabl
a
e
event.
In
reinsurance
activities,
the
insurer
assumes
defined
portions
of
risks
that
other
direct insurers or reinsurers assumed in their own insuring activities.
Insurance
and
reinsurance
are
generally
subj
u
ect
to
regulatory
r
oversight
throughout
the
world.
Except
for
regulatory
r
considerations,
there
are
virtua
t
lly
no
barriers
to
entry
r
into
the
insurance
and
reinsurance
industry.
r
Competitors
may
be
domestic or foreign, as well as licensed or unlicensed. The number of competitors within the industry
r
is not known. Insurers
compete
based
on
reliabi
a
lity,
financial
strength
and
stability,
financial
ratings,
underwriting
consistency,
service,
business
ethics, price, performance, capacity, policy terms and coverage conditions.
K-2
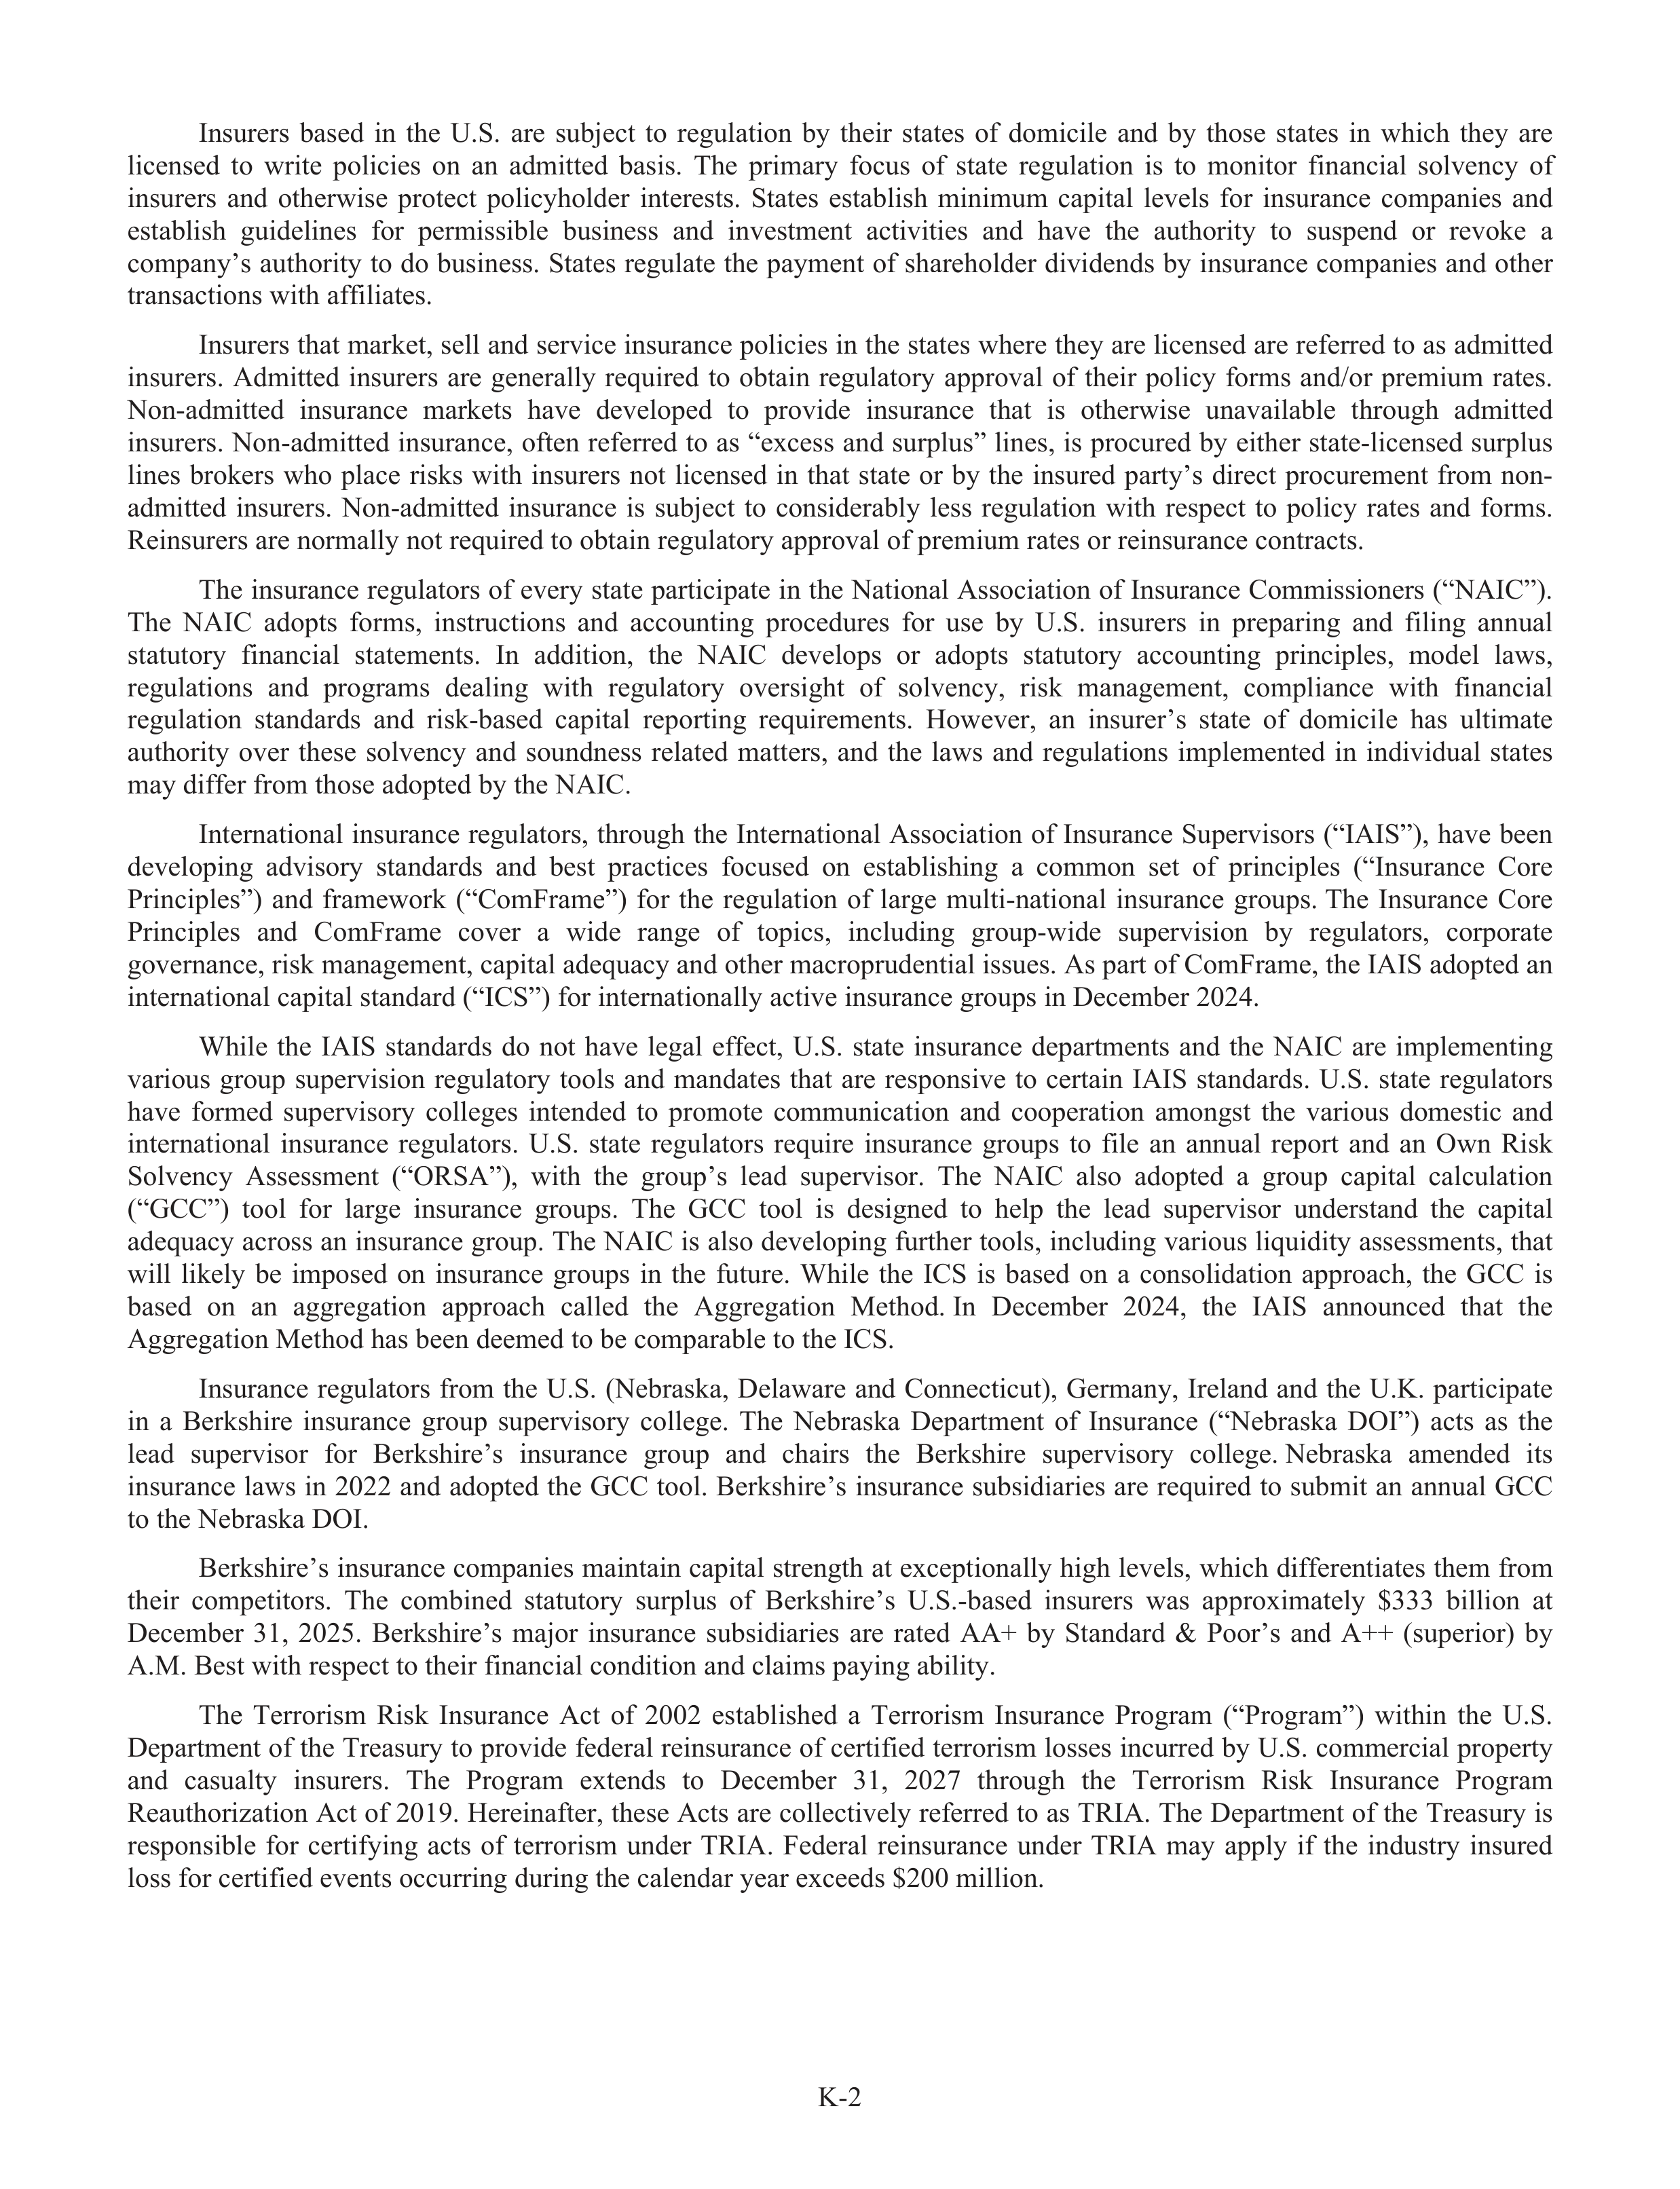
Insurers
based
in
the
U.S.
are
subj
u
ect
to
regulation
by
their
states
of
domicile
and
by
those
states
in
which
they
are
licensed
to
write
policies
on
an
admitted
basis.
The
primary
r
focus
of
state
regulation
is
to
monitor
financial
solvency
of
insurers
and
otherwise
protect
policyholder
interests.
States
establ
a
ish
minimum
capital
levels
for
insurance
companies
and
establ
a
ish
guidelines
for
permissible
business
and
investment
activities
and
have
the
authority
to
suspend
or
revoke
a
company’s authority to do business. States regulate the payment of shareholder dividends by insurance companies and other
transactions with affi
f
liates.
Insurers that market, sell and service insurance policies in the states where they are licensed are referred to as admitted
insurers.
Admitted
insurers
are
generally
required
to
obtain
regulatory
r
approval
of
their
policy
forms
and/or
premium
rates.
Non-admitted
insurance
markets
have
developed
to
provide
insurance
that
is
otherwise
unavailabl
a
e
through
admitted
insurers. Non-admitted insurance, ofte
f
n referred to as “excess and surplus” lines, is procured by either state-licensed surplus
lines
brokers
who
place
risks
with
insurers
not
licensed
in
that
state
or
by
the
insured
party’s
direct
procurement
from
non-
admitted
insurers.
Non-admitted
insurance
is
subj
u
ect
to
considerably
less
regulation
with
respect
to
policy
rates
and
forms.
Reinsurers are normally not required to obtain regulatory approval of premium rates or reinsurance contracts.
The insurance regulators of every
r
state participate in the National Association of Insurance Commissioners (“NAIC”).
The
NAIC
adopts
forms,
instructions
and
accounting
procedur
d
es
for
use
by
U.S.
insurers
in
preparing
and
filing
annual
statut
t
ory
r
financial
statements.
In
addition,
the
NAIC
develops
or
adopts
statut
t
ory
r
accounting
principles,
model
laws,
regulations
and
programs
dealing
with
regulatory
oversight
of
solvency,
risk
management,
compliance
with
financial
regulation
standards
and
risk-based
capital
reporting
requirements.
However,
an
insurer’s
state
of
domicile
has
ultimate
authority
over
these
solvency
and
soundness
related
matters,
and
the
laws
and
regulations
implemented
in
individual
states
may differ from those adopted by the NAIC.
International insurance regulators, through the International Association of Insurance Supe
u
rvisors (“IAIS”), have been
developing
advisory
standards
and
best
practices
focused
on
establ
a
ishing
a
common
set
of
principles
(“Insurance
Core
Principles”)
and
framework
(“ComFrame”)
for
the
regulation
of
large
multi-national
insurance
groups. The
Insurance
Core
Principles
and
ComFrame
cover
a
wide
range
of
topics,
including
group-wide
supe
u
rvision
by
regulators,
corporate
governance, risk management, capital adequacy and other macroprude
r
ntial issues. As part of ComFrame, the IAIS adopted an
international capital standard (“ICS”) for
f
internationally active insurance groups in December 2024.
While
the
IAIS
standards
do
not
have
legal
effe
f
ct,
U.S.
state
insurance
departments
and
the
NAIC
are
implementing
various
group
supe
u
rvision
regulatory
r
tools
and
mandates
that
are
responsive
to
certain
IAIS
standards.
U.S.
state
regulators
have
formed
supe
u
rvisory
r
colleges
intended
to
promote
communication
and
cooperation
amongst
the
various
domestic
and
international
insurance
regulators.
U.S.
state
regulators
require
insurance
groups
to
file
an
annual
report
and
an
Own
Risk
Solvency
Assessment
(“ORSA”),
with
the
group’s
lead
supe
u
rvisor.
The
NAIC
also
adopted
a
group
capital
calculation
(“GCC”)
tool
for
large
insurance
groups.
The
GCC
tool
is
designed
to
help
the
lead
supe
u
rvisor
understand
the
capital
adequacy across an insurance group. The NAIC is also developing further tools, including various liquidity assessments, that
will
likely
be
imposed
on
insurance
groups
in
the
future.
While
the
ICS
is
based
on
a
consolidation
approach,
the
GCC
is
based
on
an
aggregation
approach
called
the
Aggregation
Method. In
December
2024,
the
IAIS
announced
that
the
Aggregation Method has been deemed to be comparable to the ICS.
Insurance
regulators
from
the
U.S.
(Nebraska,
Delaware
and
Connecticut),
Germany,
Ireland
and
the
U.K.
participate
in
a
Berkshire
insurance
group
supe
u
rvisory
r
college.
The
Nebraska
Department
of
Insurance
(“Nebraska
DOI”)
acts
as
the
lead
supe
u
rvisor
for
Berkshire’s
insurance
group
and
chairs
the
Berkshire
supe
u
rvisory
r
college. Nebraska
amended
its
insurance laws in 2022 and adopted the GCC tool. Berkshire’s insurance subs
u
idiaries are required to subm
u
it an annual GCC
to the Nebraska DOI.
Berkshire’s insurance companies maintain capital strength at exceptionally high levels, which differentiates them from
their
competitors.
The
combined
statut
t
ory
r
surplus
of
Berkshire’s
U.S.-based
insurers
was
approximately
$333
billion
at
December
31,
2025.
Berkshire’s
major
insurance
subs
u
idiaries
are
rated
AA+
by
Standard
&
Poor’s
and
A++
(superior)
by
A.M. Best with respect to their financial condition and claims paying ability.
The
Terrorism
Risk
Insurance
Act
of
2002
establ
a
ished
a
Terrorism
Insurance
Program
(“Program”)
within
the
U.S.
Department of the Treasury
r
to provide federal reinsurance of certifie
f
d terrorism losses incurred by U.S. commercial property
and
casualty
insurers.
The
Program
extends
to
December
31,
2027
through
the
Terrorism
Risk
Insurance
Program
Reauthorization Act of 2019. Hereinafte
f
r, these Acts are collectively referred to as TRIA. The Department of the Treasury
r
is
responsible
for
certifyi
f
ng
acts
of
terrorism
under
TRIA.
Federal
reinsurance
under
TRIA
may
apply
if
the
industry
r
insured
loss for certifie
f
d events occurring during the calendar year exceeds $200 million.
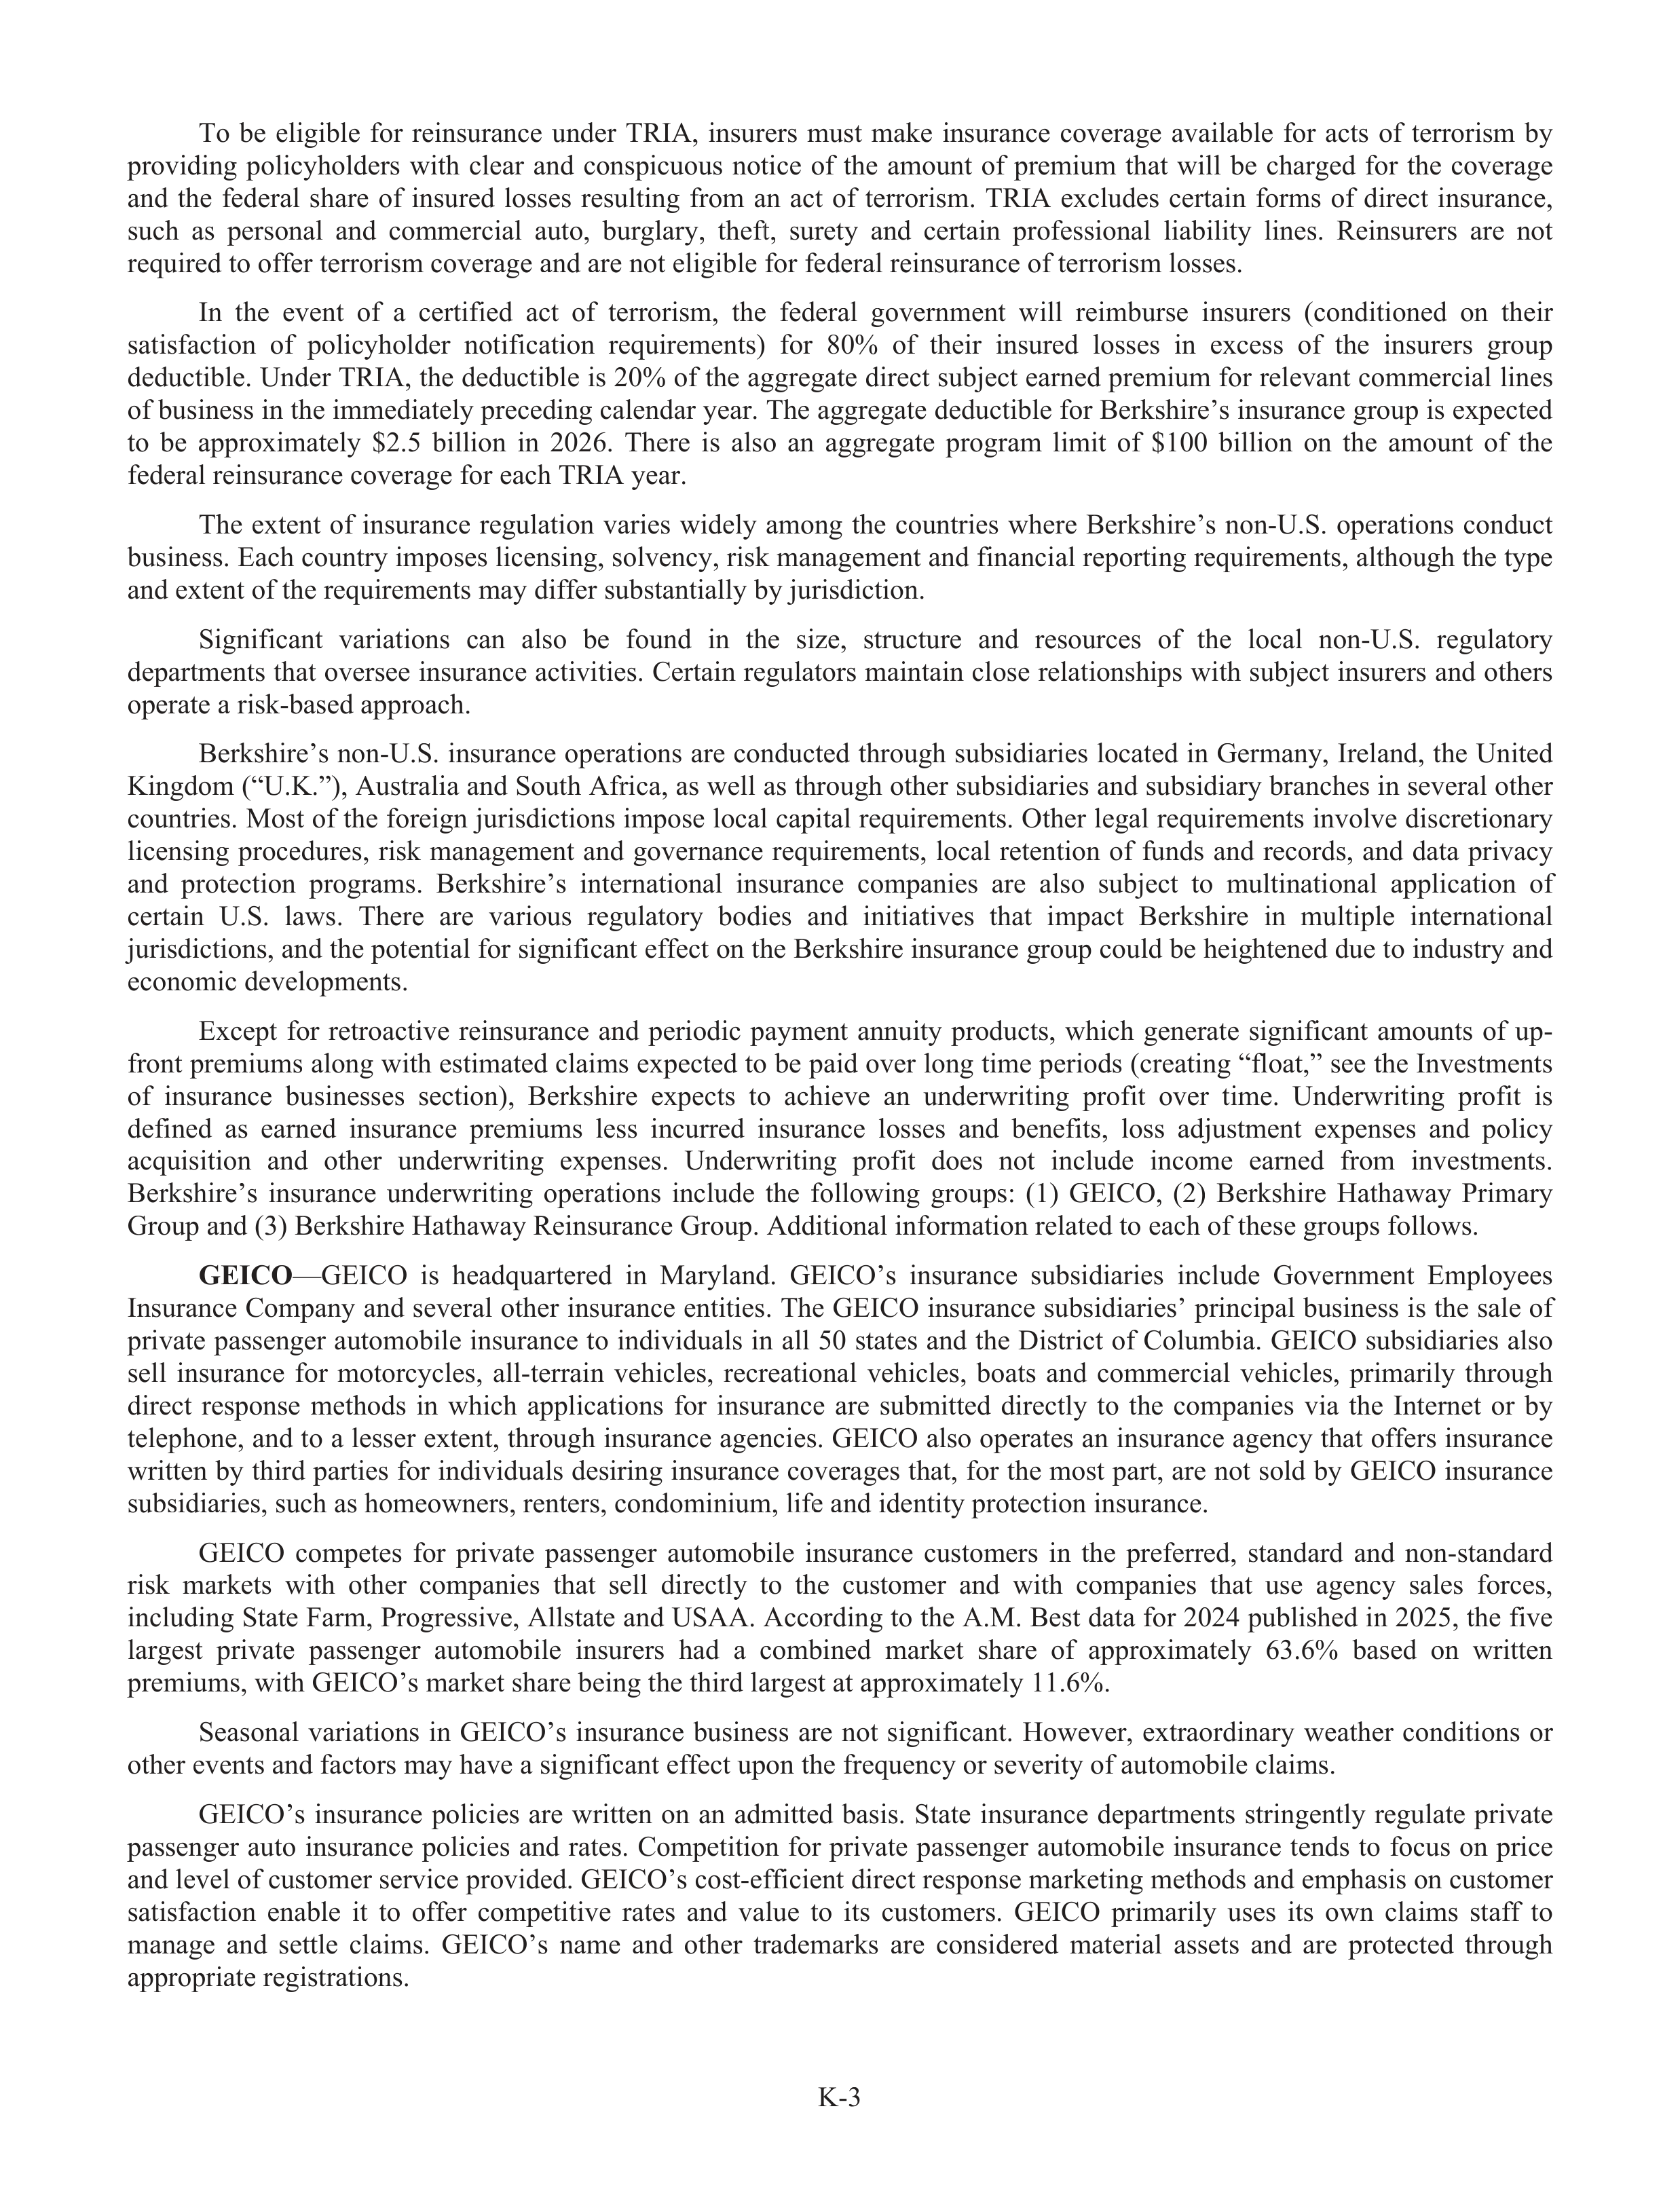
K-3
To
be
eligible
for
reinsurance
under
TRIA,
insurers
must
make
insurance
coverage
availabl
a
e
for
acts
of
terrorism
by
providing
policyholders
with
clear
and
conspicuous
notice
of
the
amount
of
premium
that
will
be
charged
for
the
coverage
and
the
federal
share
of
insured
losses
resulting
from
an
act
of
terrorism.
TRIA
excludes
certain
forms
of
direct
insurance,
such
as
personal
and
commercial
auto,
burglary,
r
theft,
f
surety
and
certain
profes
f
sional
liabi
a
lity
lines.
Reinsurers
are
not
required to offe
f
r terrorism coverage and are not eligible for federal reinsurance of terrorism losses.
In
the
event
of
a
certifie
f
d
act
of
terrorism,
the
federal
government
will
reimburse
insurers
(conditioned
on
their
satisfaction
of
policyholder
notific
f
ation
requirements)
for
80%
of
their
insured
losses
in
excess
of
the
insurers
group
deductible. Under TRIA, the deductible is 20% of the aggregate direct subj
u
ect earned premium for relevant commercial lines
of business in the immediately preceding calendar year. The aggregate deductible for Berkshire’s insurance group is expected
to
be
approximately
$2.5
billion
in
2026.
There
is
also
an
aggregate
program
limit
of
$100
billion
on
the
amount
of
the
federal reinsurance coverage for each TRIA year.
The
extent
of
insurance
regulation
varies
widely
among
the
countries
where
Berkshire’s
non-U.S.
operations
conduct
business. Each country imposes licensing, solvency, risk management and financial reporting requirements, although the type
and extent of the requirements may differ subs
u
tantially by jurisdiction.
Significant
variations
can
also
be
found
in
the
size,
structur
t
e
and
resources
of
the
local
non-U.S.
regulatory
r
departments that oversee insurance activities. Certain regulators maintain close relationships with subj
u
ect insurers and others
operate a risk-based approach.
Berkshire’s non-U.S. insurance operations are conducted through subs
u
idiaries located in Germany, Ireland, the United
Kingdom (“U.K.”), Australia and South Afri
f
ca, as well as through other subs
u
idiaries and subs
u
idiary branches in several other
countries. Most of the foreign jurisdictions impose local capi
a
tal requirements. Other legal requirements involve discretionary
licensing
procedur
d
es,
risk
management
and
governance
requirements,
local
retention
of
funds
and
records,
and
data
privacy
and
protection
programs.
Berkshire’s
international
insurance
companies
are
also
subj
u
ect
to
multinational
application
of
certain
U.S.
laws.
There
are
various
regulatory
r
bodies
and
initiatives
that
impact
Berkshire
in
multiple
international
jurisdictions, and the potential for significant effe
f
ct on the Berkshire insurance group could be heightened due to indus
d
try
r
and
economic developments.
Except
for
retroactive
reinsurance
and
periodic
payment
annuity
products,
which
generate
significant
amounts
of
up-
front premiums along with estimated claims expected to be paid over long time periods (creating “float,” see the Investments
of
insurance
businesses
section),
Berkshire
expects
to
achieve
an
underwriting
profit
f
over
time.
Underwriting
profit
f
is
defined
as
earned
insurance
premiums
less
incurred
insurance
losses
and
benefits,
loss
adju
d
stment
expenses
and
policy
acquisition
and
other
underwriting
expenses.
Underwriting
profit
f
does
not
include
income
earned
from
investments.
Berkshire’s
insurance
underwriting
operations
include
the
following
groups:
(1)
GEICO,
(2)
Berkshire
Hathaway
Primary
Group and (3) Berkshire Hathaway Reinsurance Group. Additional information related to each of these groups follows.
GEICO
—GEICO
is
headquartered
in
Maryland.
GEICO’s
insurance
subs
u
idiaries
include
Government
Employees
Insurance Company and several other insurance entities. The GEICO insurance subsidiaries’ principal business is the sale of
private passenger automobile insurance to individuals in all 50 states and the District of Columbia. GEICO subs
u
idiaries also
sell
insurance
for
motorcycles,
all-terrain
vehicles,
recreational
vehicles,
boats
and
commercial
vehicles,
primarily
through
direct
response
methods
in
which
applications
for
insurance
are
subm
u
itted
directly
to
the
companies
via
the
Internet
or
by
telephone, and to a lesser extent, through insurance agencies. GEICO also operates an insurance agency that offe
f
rs insurance
written by third parties for individuals desiring insurance coverages that, for the most part, are not sold by GEICO insurance
subs
u
idiaries, such as homeowners, renters, condominium, lifef
and identity protection insurance.
GEICO
competes
for
private
passenger
automobile
insurance
customers
in
the
prefer
f
red,
standard
and
non-standard
risk
markets
with
other
companies
that
sell
directly
to
the
customer
and
with
companies
that
use
agency
sales
forces,
including State Farm, Progressive, Allstate and USAA. According to the A.M. Best data for 2024 published in 2025, the five
largest
private
passenger
automobile
insurers
had
a
combined
market
share
of
approximately
63.6%
based
on
written
premiums, with GEICO’s market share being the third largest at approximately 11.6%.
Seasonal
variations
in
GEICO’s
insurance
business
are
not
significant.
However,
extraordinary
r
weather
conditions
or
other events and factors may have a significant effe
f
ct upon the frequency or severity of automobile claims.
GEICO’s
insurance
policies
are
written
on
an
admitted
basis.
State
insurance
departments
stringently
regulate
private
passenger
auto
insurance
policies
and
rates.
Competition
for
private
passenger
automobile
insurance
tends
to
focus
on
price
and level of customer service provided. GEICO’s cost-effi
f
cient direct response marketing methods and emphasis on customer
satisfaction
enable
it
to
offe
f
r
competitive
rates
and
value
to
its
customers.
GEICO
primarily
uses
its
own
claims
stafff
to
manage
and
settle
claims.
GEICO’s
name
and
other
trademarks
are
considered
material
assets
and
are
protected
through
appropriate registrations.
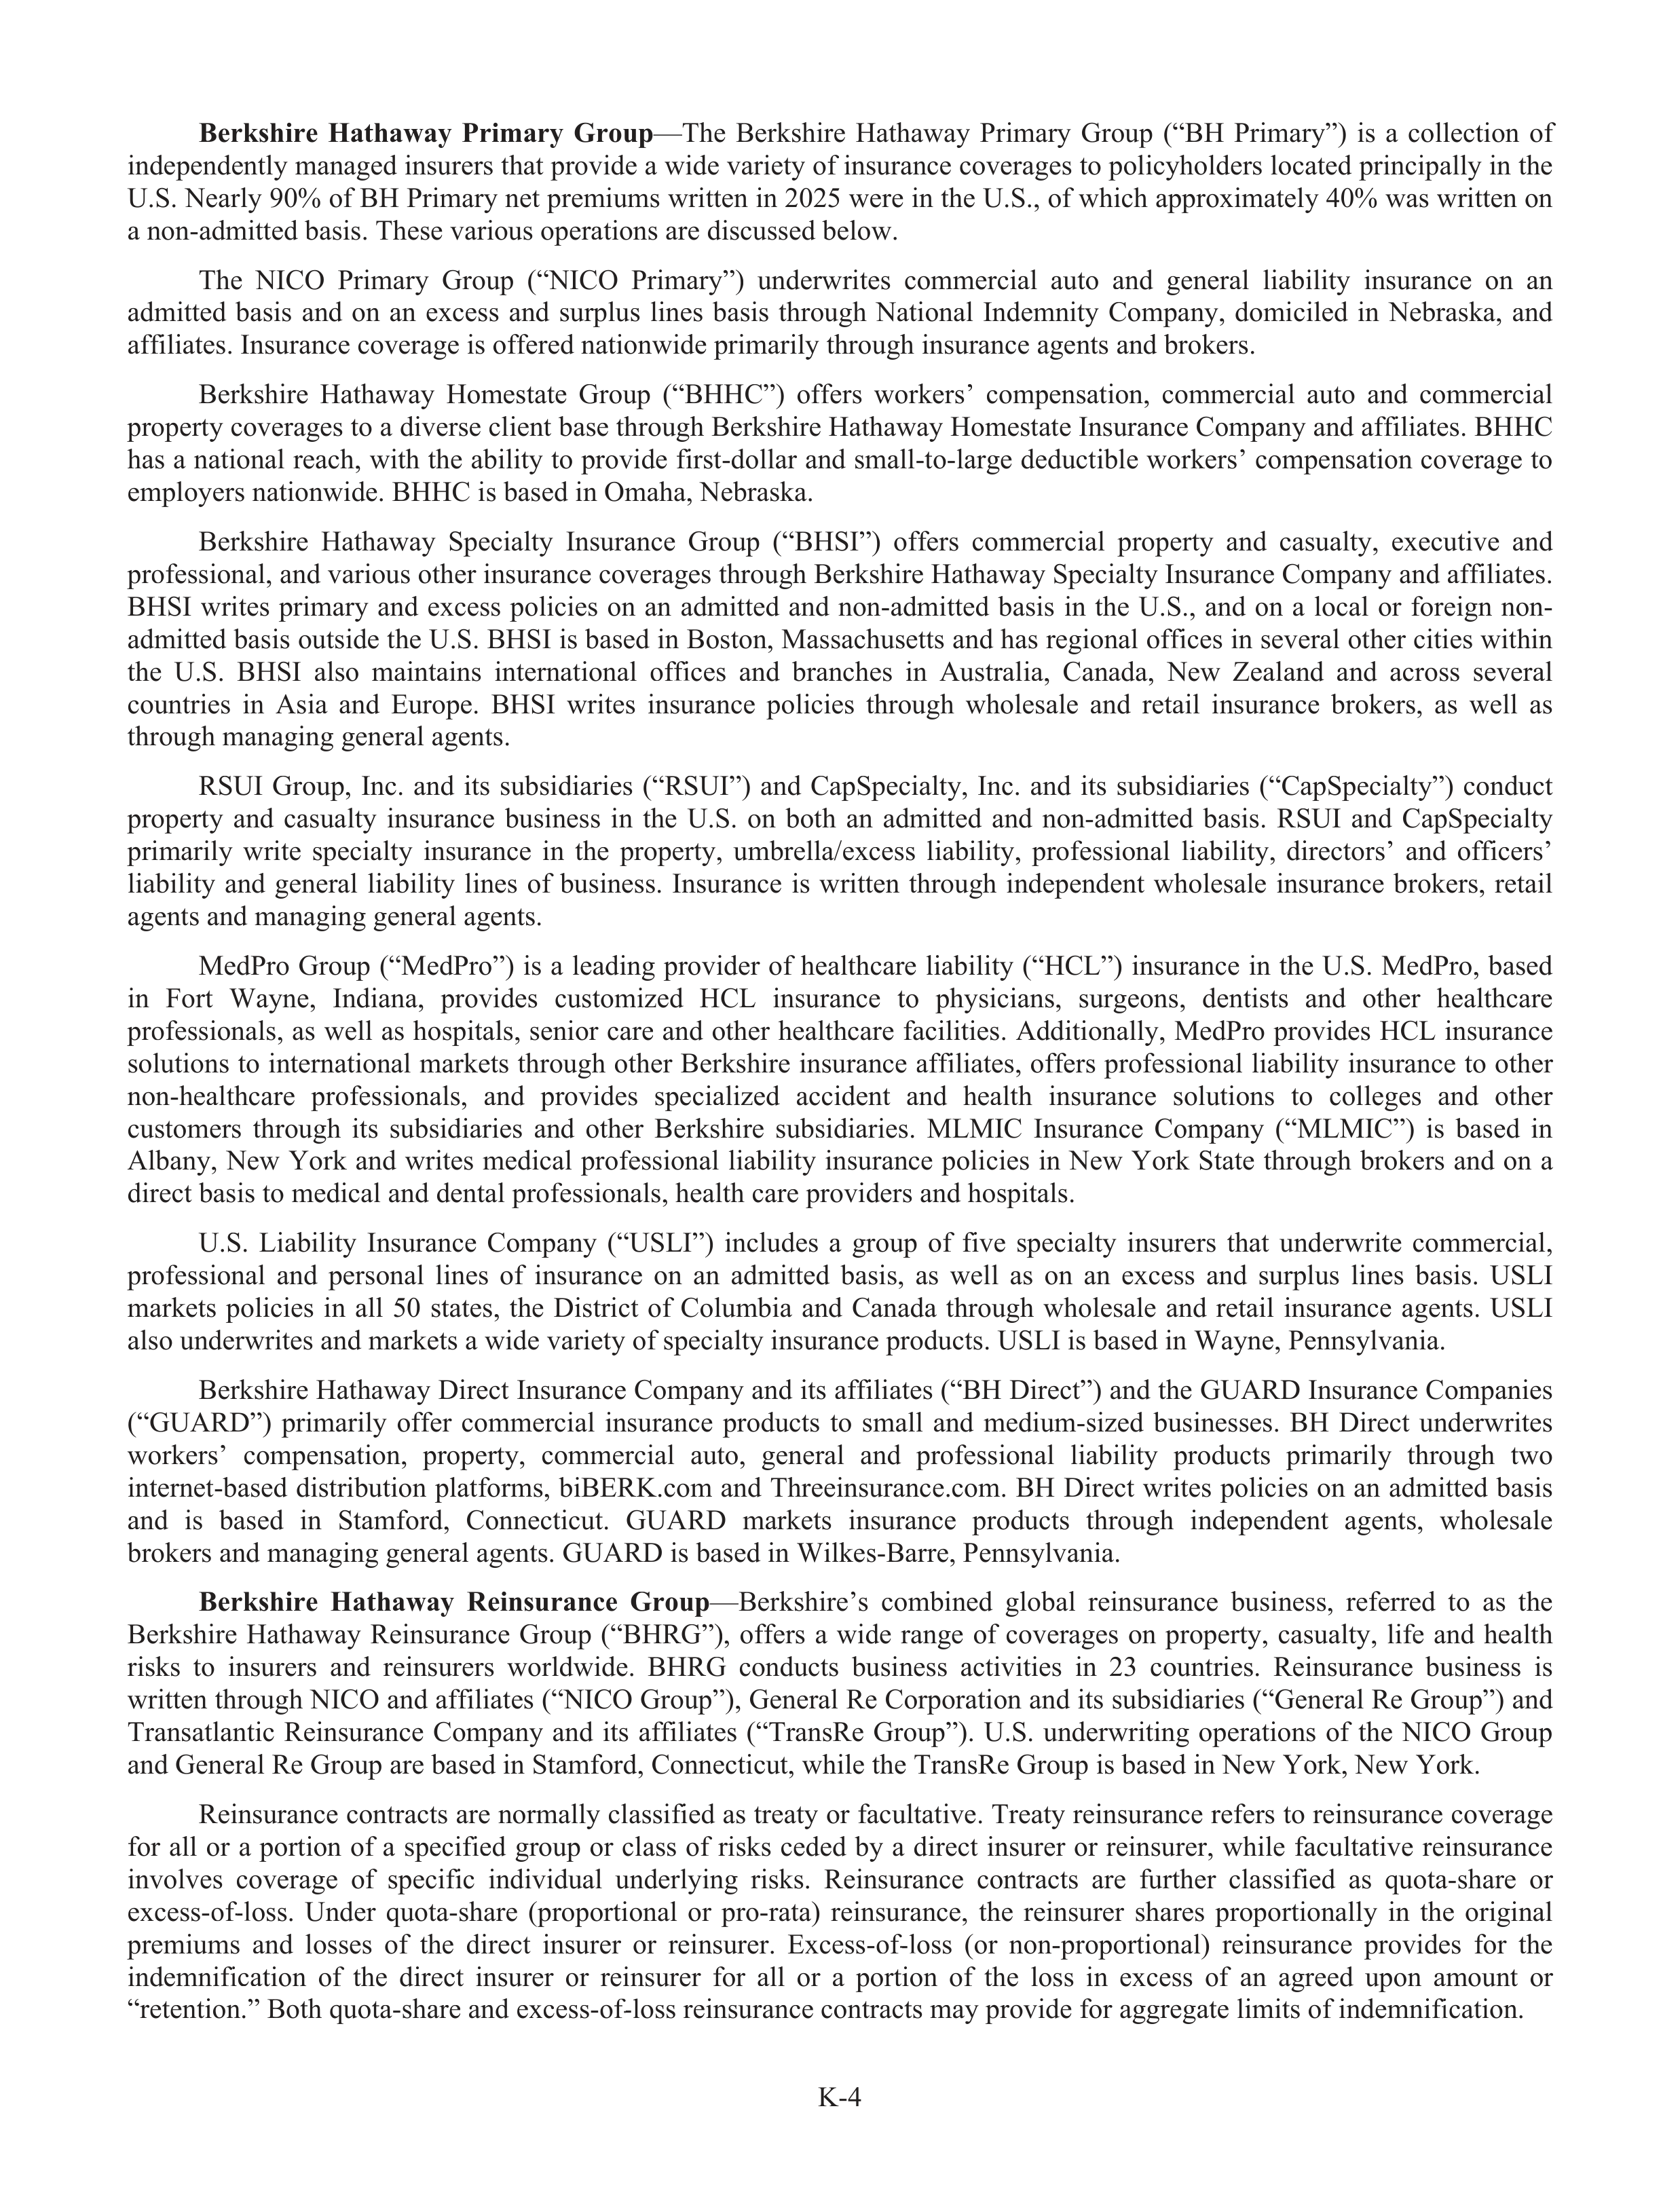
K-4
Berkshire
Hathaway
Primary
Group
—The
Berkshire
Hathaway
Primary
Group
(
u
“BH
Primary”)
is
a
collection
of
independently managed insurers that provide a wide variety of insurance coverages to policyholders located principally in the
U.S. Nearly 90% of BH Primary net premiums written in 2025 were in the U.S., of which approximately 40% was written on
a non-admitted basis. These various operations are discussed below.
The
NICO
Primary
Group
(“NICO
Primary”)
underwrites
commercial
auto
and
general
liabi
a
lity
insurance
on
an
admitted
basis
and
on
an
excess
and
surplus
lines
basis
through
National
Indemnity
Company,
domiciled
in
Nebraska,
and
affi
f
liates. Insurance coverage is offe
f
red nationwide primarily through insurance agents and brokers.
Berkshire
Hathaway
Homestate
Group
(“BHHC”)
offe
f
rs
workers’
compensation,
commercial
auto
and
commercial
property coverages to a diverse client base through Berkshire Hathaway Homestate Insurance Company and affi
f
liates. BHHC
has a national reach, with the ability to provide first-dollar and small-to-large deductible workers’ compensation coverage to
employers nationwide. BHHC is based in Omaha, Nebraska.
Berkshire
Hathaway
Specialty
Insurance
Group
(“BHSI”)
offe
f
rs
commercial
property
and
casualty,
executive
and
profes
f
sional, and various other insurance coverages through Berkshire Hathaway Specialty Insurance Company and affi
f
liates.
BHSI
writes
primary
and
excess
policies
on
an
admitted
and
non-admitted
basis
in
the
U.S.,
and
on
a
local
or
foreign
non-
admitted basis outside the U.S. BHSI is based in Boston, Massachusetts and has regional offi
f
ces in several other cities within
the
U.S.
BHSI
also
maintains
international
offi
f
ces
and
branches
in
Australia,
Canada,
New
Zealand
and
across
several
countries
in
Asia
and
Europe.
BHSI
writes
insurance
policies
through
wholesale
and
retail
insurance
brokers,
as
well
as
through managing general agents.
RSUI
Group,
Inc.
and
its
subs
u
idiaries
(“RSUI”)
and
CapS
a
pecialty,
Inc.
and
its
subs
u
idiaries
(“CapS
a
pecialty”)
conduct
property
and
casualty
insurance
business
in
the
U.S.
on
both
an
admitted
and
non-admitted
basis.
RSUI
and
CapS
a
pecialty
primarily
write
specialty
insurance
in
the
property,
umbrella/excess
liabi
a
lity,
profes
f
sional
liabi
a
lity,
directors’
and
officers’
liabi
a
lity
and
general
liabi
a
lity
lines
of
business.
Insurance
is
written
through
independent
wholesale
insurance
brokers,
retail
agents and managing general agents.
MedPro
Group
(“MedPro”)
is
a
leading
provider
of
healthcare
liabi
a
lity
(“HCL”)
insurance
in
the
U.S.
MedPro,
based
in
Fort
Wayne,
Indiana,
provides
customized
HCL
insurance
to
physicians,
surgeons,
dentists
and
other
healthcare
profes
f
sionals, as well as hospitals, senior care and other healthcare facilities. Additionally, MedPro provides HCL insurance
solutions to international markets through other Berkshire insurance affi
f
liates, offe
f
rs profes
f
sional liabi
a
lity insurance to other
non-healthcare
profes
f
sionals,
and
provides
specialized
accident
and
health
insurance
solutions
to
colleges
and
other
customers
through
its
subs
u
idiaries
and
other
Berkshire
subs
u
idiaries.
MLMIC
Insurance
Company
(“MLMIC”)
is
based
in
Albany,
New
York
and
writes
medical
profes
f
sional
liabi
a
lity
insurance
policies
in
New
York
State
through
brokers
and
on
a
direct basis to medical and dental profes
f
sionals, health care providers and hospitals.
U.S.
Liability
Insurance
Company
(“USLI”)
includes
a
group
of
five
specialty
insurers
that
underwrite
commercial,
profes
f
sional
and
personal
lines
of
insurance
on
an
admitted
basis,
as
well
as
on
an
excess
and
surplus
lines
basis.
USLI
markets
policies
in
all
50
states,
the
District
of
Columbia
and
Canada
through
wholesale
and
retail
insurance
agents.
USLI
also underwrites and markets a wide variety of specialty insurance products. USLI is based in Wayne, Pennsylvania.
Berkshire Hathaway Direct Insurance Company and its affi
f
liates (“BH Direct”) and the GUARD Insurance Companies
(“GUARD”)
primarily
offe
f
r
commercial
insurance
products
to
small
and
medium-sized
businesses.
BH
Direct
underwrites
workers’
compensation,
property,
commercial
auto,
general
and
profes
f
sional
liabi
a
lity
products
primarily
through
two
internet-based
distribution
platforms,
biBERK.com
and
Threeinsurance.com.
BH
Direct
writes
policies
on
an
admitted
basis
and
is
based
in
Stamford,
Connecticut.
GUARD
markets
insurance
products
through
independent
agents,
wholesale
brokers and managing general agents. GUARD is based in Wilkes-Barre, Pennsylvania.
Berkshire
Hathaway
Reinsurance
Group
—Berkshire’s
combined
global
reinsurance
business,
referred
to
as
the
Berkshire
Hathaway
Reinsurance
Group
(“BHRG”),
offers
a
wide
range
of
coverages
on
property,
casualty,
lifef
and
health
risks
to
insurers
and
reinsurers
worldwide.
BHRG
conducts
business
activities
in
23
countries.
Reinsurance
business
is
written through NICO and affi
f
liates (“NICO Group”), General Re Corporation and its subs
u
idiaries (“General Re Group”) and
Transatlantic
Reinsurance
Company
and
its
affi
f
liates
(“TransRe
Group”).
U.S.
underwriting
operations
of
the
NICO
Group
and General Re Group are based in Stamford, Connecticut, while the TransRe Group is based in New York, New York.
Reinsurance contracts are normally classified as treaty or facultative. Treaty reinsurance refers to reinsurance coverage
for
all
or
a
portion
of
a
specifie
f
d
group
or
class
of
risks
ceded
by
a
direct
insurer
or
reinsurer,
while
facultative
reinsurance
involves
coverage
of
specific
individual
underlying
risks.
Reinsurance
contracts
are
further
classified
as
quota-share
or
excess-of-l
f
oss.
Under
quota-share
(proportional
or
pro-rata)
reinsurance,
the
reinsurer
shares
proportionally
in
the
original
premiums
and
losses
of
the
direct
insurer
or
reinsurer.
Excess-of-l
f
oss
(or
non-proportional)
reinsurance
provides
for
the
indemnific
f
ation
of
the
direct
insurer
or
reinsurer
for
all
or
a
portion
of
the
loss
in
excess
of
an
agreed
upon
amount
or
“retention.” Both quota-share and excess-of-l
f
oss reinsurance contracts may provide for aggregate limits of indemnific
f
ation.
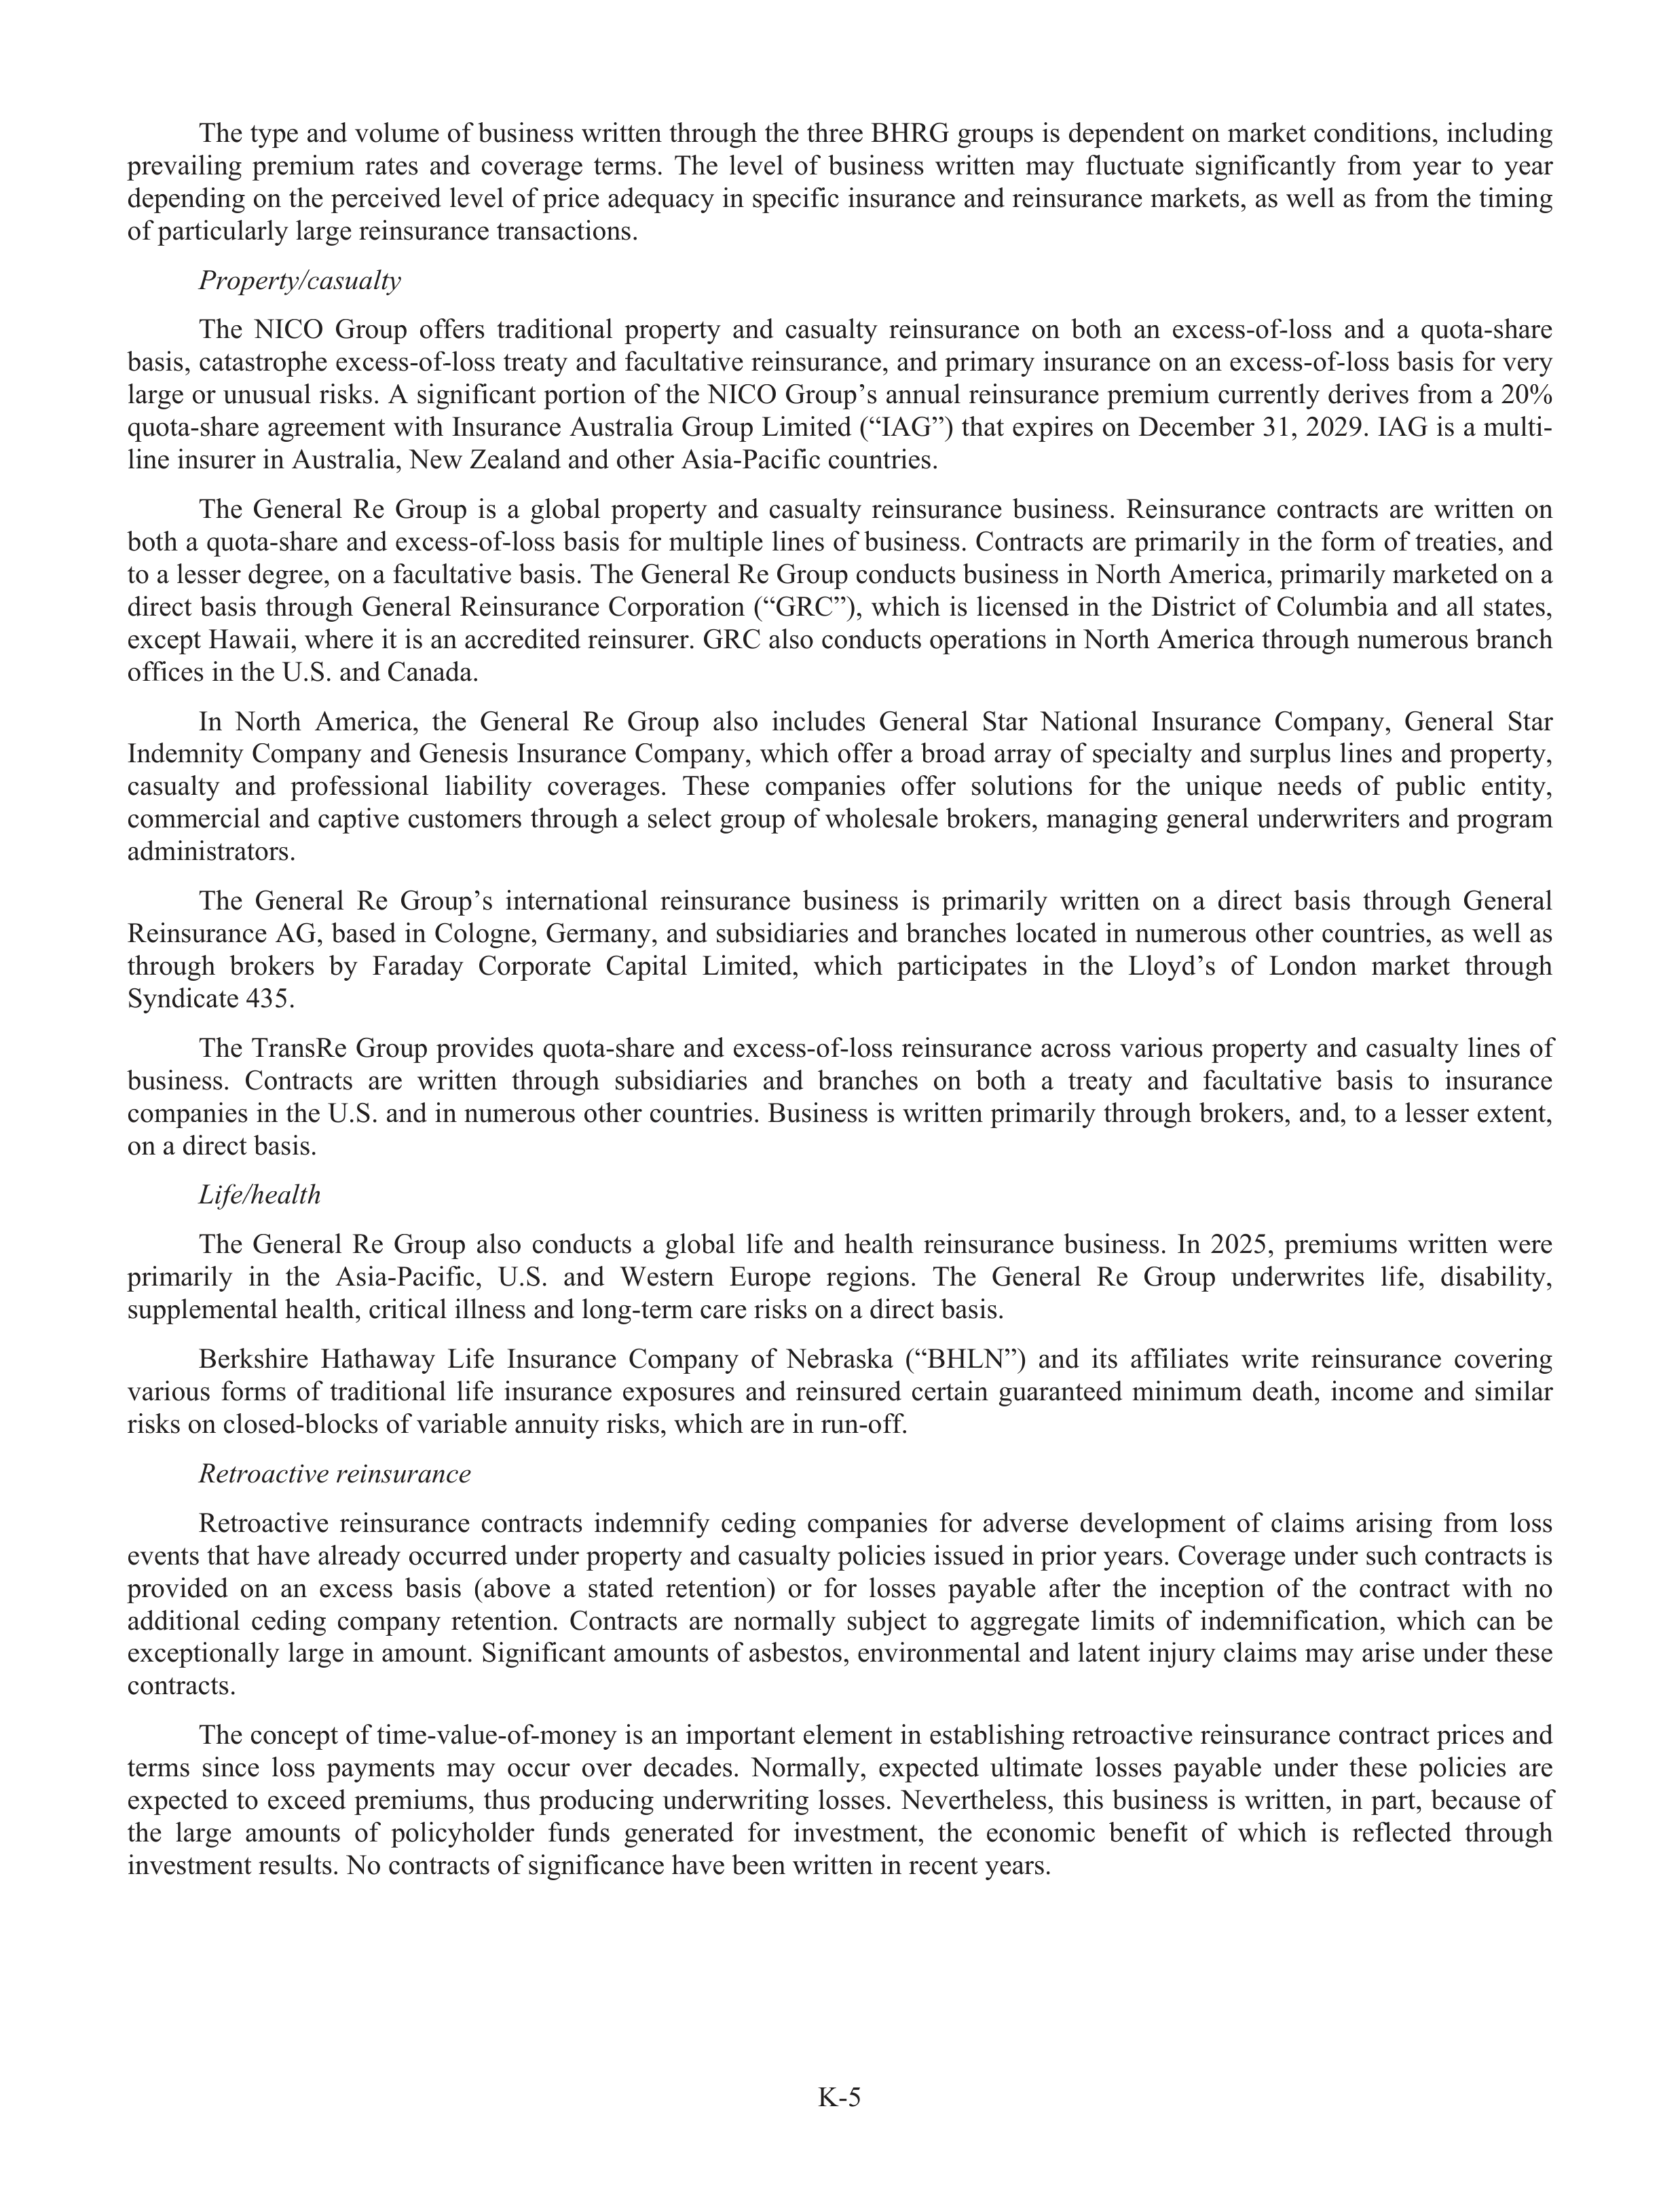
K-5
The type and volume of business written through the three BHRG groups is dependent on market conditions, including
prevailing
premium
rates
and
coverage
terms.
The
level
of
business
written
may
fluctuate
significantly
from
year
to
year
depending on the perceived level of price adequacy in specific insurance and reinsurance markets, as well as from the timing
of particularly large reinsurance transactions.
Property/
t
ca
/
sualty
The
NICO
Group
offe
f
rs
traditional
property
and
casualty
reinsurance
on
both
an
excess-of-l
f
oss
and
a
quota-share
basis, catastrophe excess-of-l
f
oss treaty and facultative reinsurance, and primary insurance on an excess-of-l
f
oss basis for very
large or unusual risks. A significant portion of the NICO Group’s annual reinsurance premium currently derives from a 20%
quota-share agreement with Insurance Australia Group Limited (“IAG”) that expires on December 31, 2029. IAG is a multi-
line insurer in Australia, New Zealand and other Asia-Pacific countries.
The
General
Re
Group
is
a
global
property
and
casualty
reinsurance
business.
Reinsurance
contracts
are
written
on
both a quota-share and excess-of-l
f
oss basis for multiple lines of business. Contracts are primarily in the form of treaties, and
to a lesser degree, on a facultative basis. The General Re Group conducts business in North America, primarily marketed on a
direct
basis
through
General
Reinsurance
Corporation (“GRC”),
which
is
licensed
in
the
District
of
Columbia
and
all
states,
except Hawaii, where it is an accredited reinsurer. GRC also conducts operations in North America through numerous branch
offi
f
ces in the U.S. and Canada.
In
North
America,
the
General
Re
Group
also
includes
General
Star
National
Insurance
Company,
General
Star
Indemnity Company and Genesis Insurance Company, which offe
f
r a broad array of specialty and surplus lines and property,
casualty
and
profes
f
sional
liabi
a
lity
coverages.
These
companies
offe
f
r
solutions
for
the
unique
needs
of
public
entity,
commercial and captive customers through a select group
u
of wholesale brokers, managing general underwriters and program
administrators.
The
General
Re
Group’s
international
reinsurance
business
is
primarily
written
on
a
direct
basis
through
General
Reinsurance AG, based in Cologne, Germany, and subs
u
idiaries and branches located in numerous other countries, as well as
through
brokers
by
Faraday
Corporate
Capi
a
tal
Limited,
which
participates
in
the
Lloyd’s
of
London
market
through
Syndicate 435.
The
TransRe
Group
provides
quota-share
and
excess-of-l
f
oss
reinsurance
across
various
property
and
casualty
lines
of
business.
Contracts
are
written
through
subs
u
idiaries
and
branches
on
both
a
treaty
and
facultative
basis
to
insurance
companies in the U.S. and in numerous other countries. Business is written primarily through brokers, and, to a lesser extent,
on a direct basis.
Life
i
/h
e
ealth
The
General
Re
Group
also
conducts
a
global
lifef
and
health
reinsurance
business.
In
2025,
premiums
written
were
primarily
in
the
Asia-Pacific,
U.S.
and
Western
Europe
regions.
The
General
Re
Group
underwrites
life,
f
disabi
a
lity,
suppl
u
emental health, critical illness and long-term care risks on a direct basis.
Berkshire
Hathaway
Life
Insurance
Company
of
Nebraska
(“BHLN”)
and
its
affi
f
liates
write
reinsurance
covering
various
forms
of
traditional
lifef
insurance
exposures
and
reinsured
certain
guaranteed
minimum
death,
income
and
similar
risks on closed-blocks of variable annuity risks, which are in run-off.
f
Retroactive reinsurance
Retroactive
reinsurance
contracts
indemnify
f
ceding
companies
for
adverse
development
of
claims
arising
from
loss
events that have already occurred under property and casualty policies issued in prior years. Coverage under such contracts is
provided
on
an
excess
basis
(above
a
a
stated
retention)
or
for
losses
payabl
a
e
afte
f
r
the
inception
of
the
contract
with
no
additional
ceding
company
retention.
Contracts
are
normally
subj
u
ect
to
aggregate
limits
of
indemnific
f
ation,
which
can
be
exceptionally large in amount. Significant amounts of asbestos, environmental and latent inju
n
ry claims may arise under these
contracts.
The concept of time-value-of-money is an important element in establ
a
ishing retroactive reinsurance contract prices and
terms
since
loss
payments
may
occur
over
decades.
Normally,
expected
ultimate
losses
payabl
a
e
under
these
policies
are
expected
to
exceed
premiums,
thus
producing
underwriting
losses.
Nevertheless,
this
business
is
written,
in
part,
because
of
the
large
amounts
of
policyholder
funds
generated
for
investment,
the
economic
benefit
of
which
is
reflected
through
investment results. No contracts of significance have been written in recent years.
K-6
Periodic payment annuity
BHLN writes periodic payment annuity insurance policies and reinsures annuity-like obligations. Under these policies,
BHLN
receives
upfro
f
nt
consideration
and
agrees
in
the
future
to
make
periodic
payments
that
ofte
f
n
extend
for
decades.
These
policies
generally
relate
to
the
settlement
of
underlying
personal
inju
n
ry
or
workers’
compensation
claims
of
other
insurers,
known
as
structur
t
ed
settlements.
Consistent
with
retroactive
reinsurance
contracts,
time-value-of-money
is
an
important
factor
in
establ
a
ishing
annuity
premiums
and
ultimate
payments
are
expected
to
exceed
premiums
received,
producing underwriting losses. BHLN has not written any new policies since 2022.
Investments
of
insurance
businesses
—Berkshire’s
insurance
subs
u
idiaries
hold
significant
levels
of
invested
assets.
Investments include a very large portfol
f
io of publicly traded equity securities, which are unusually concentrated in relatively
few
companies,
as
well
as
in
short-term
investments
and
fixed
maturity
securities.
Generally,
there
are
no
target
allocations
by
investment
type
or
attempts
to
match
investment
asset
and
insurance
liabi
a
lity
durations.
However,
investment
portfol
f
ios
have historically included a much greater proportion of equity securities than is customary
r
in the insurance industry.
r
Invested
assets
derive
from
shareholder
capital
as
well
as
funds
provided
from
policyholders
through
insurance
and
reinsurance
businesses
(“flo
f
at”).
Float
represents
the
approximate
net
policyholder
funds
generated
through
underwriting
activities
that
are
held
for
investment.
The
majo
a
r
components
of
float
are
unpaid
losses
and
loss
adju
d
stment
expenses,
life,
f
annuity
and
health
benefit
insurance
liabi
a
lities
(excluding
the
effe
f
cts
of
discount
rate
changes
that
are
recorded
in
accumulated
other
comprehensive
income),
unearned
insurance
premiums
and
other
insurance
policyholder
liabi
a
lities
less
premium
and
reinsurance
receivabl
a
es,
deferred
policy
acquisition
costs
and
deferred
charges
on
assumed
retroactive
reinsurance
contracts.
On
a
consolidated
basis,
float
has
increased
from
approximately
$138
billion
at
the
end
of
2020
to
approximately $176 billion at the end of 2025. The cost of float can be measured as the net pre-tax underwriting earnings (or
loss) as a percentage of the average float balance.
Burlington Northern Santa Fe
Burlington
Northern
Santa
Fe,
LLC
(“BNSF”)
is
based
in
Fort
Worth,
Texas,
and
through
BNSF
Railway
Company
(“BNSF
Railway”)
operates
one
of
the
largest
freight
rail
transportation
systems
in
North
America.
BNSF
Railway
had
approximately 35,000 employees at the end of 2025, of whom approximately 30,000 were members of a labor
a
union.
In
serving
the
Midwest,
Pacific
Northwest,
Western,
Southwestern
and
Southeastern
regions
and
certain
ports
of
the
U.S.,
BNSF
Railway
transports
a
range
of
products
and
commodities
derived
from
manufact
f
ur
t
ing,
agricultural
and
natural
resource
industries.
Freight
revenues
are
covered
by
contractua
t
l
agreements
of
varying
durations
or
common
carrier
published
prices
or
company
quotations.
BNSF’s
fin
f
ancial
performance
is
influenced
by,
among
other
things,
general
and
industry
r
economic conditions at the international, national and regional levels.
BNSF
Railway’s
primary
routes,
including
trackage
rights,
allow
it
to
access
majo
a
r
cities
and
certain
ports
in
the
western
and
southern
U.S.,
as
well
as
parts
of
Canada
and
Mexico.
In
addition
to
majo
a
r
cities
and
ports,
BNSF
Railway
effi
f
ciently
serves
many
smaller
markets
by
working
closely
with
approximately
200
shortline
railroads.
BNSF
Railway
has
also
entered
into
marketing
agreements
with
other
rail
carriers,
expanding
the
marketing
reach
for
each
railroad
and
its
customers.
Freight
revenues
are
classified
into
the
following
categories:
consumer
products,
industrial
products,
agricultural
and energy products and coal. The volumes shipped and rates charged are affe
f
cted by competition from other freight carriers
within the transportation industry,
r
and changes in the underlying suppl
u
y and demand for such products.
Regul
e
atory
r
matters
BNSF
is
subj
u
ect
to
federal,
state
and
local
laws
and
regulations
generally
applicable
to
its
businesses.
Rail
operations
are subj
u
ect to the regulatory
r
jurisdiction of the Surface Transportation Board (“STB”), the Federal Railroad Administration of
the
U.S.
Department
of
Transportation
(“DOT”),
the
Occupa
u
tional
Safety
and
Health
Administration
(“OSHA”),
the
Environmental
Protection
Agency
(“EPA”),
as
well
as
other
federal
and
state
regulatory
r
agencies
and
Canadian
regulatory
r
agencies for operations in Canada. The STB has jurisdiction over disputes and complaints involving certain rates, routes and
services,
the
sale
or
abandonment
of
rail
lines,
applications
for
line
extensions
and
construc
r
tion,
and
the
merger
with
or
acquisition
of
control
of
rail
common
carriers.
The
outcome
of
STB
proceedings
can
affe
f
ct
the
profita
f
bi
a
lity
of
BNSF
Railway’s business.
The
DOT,
OSHA
and
EPA
have
jurisdiction
under
several
federal
statut
t
es
over
a
number
of
safety,
health
and
environmental
aspects
of
rail
operations,
including
the
transportation
of
hazardous
materials.
BNSF
Railway
is
required
to
transport
these
materials
to
the
extent
of
its
common
carrier
obligation.
State
agencies
regulate
some
health,
safety
and
environmental aspects of rail operations in areas not otherwise preempted by federal law.
K-7
Environmental matters
BNSF’s
rail
operations,
as
well
as
those
of
its
competitors,
are
also
subj
u
ect
to
extensive
federal,
state
and
local
environmental
regulations
covering
discharges
to
the
ground
or
waters,
air
emissions,
toxic
subs
u
tances
and
the
generation,
handling,
storage,
transportation
and
disposal
of
waste
and
hazardous
materials.
Such
regulations
effe
f
ctively
increase
the
costs and liabi
a
lities associated with rail operations. Environmental risks are also inherent in rail operations, which frequently
involve transporting chemicals and other hazardous materials.
Many
of
BNSF’s
land
holdings
are
or
have
been
used
for
industrial
or
transportation-related
purpos
r
es
or
leased
to
commercial
or
industrial
companies
whose
activities
may
have
resulted
in
discharges
onto
the
property.
Under
federal
statut
t
es
(in
particular,
the
Comprehensive
Environmental
Response,
Compensation
and
Liability
Act)
and
state
statut
t
es,
BNSF
may
be
held
jointly
and
severally
liabl
a
e
for
cleanup
and
enforcement
costs
associated
with
a
particular
site
without
regard
to
fault
or
the
legality
of
the
original
conduct.
BNSF
may
also
be
subj
u
ect
to
claims
by
third
parties
for
investigation,
cleanup, restoration or other environmental costs under environmental statut
t
es or common law with respect to properties they
own that have been impacted by BNSF operations.
Consumption
of
diesel
fuel
by
locomotives
accounted
for
approximately
80%
of
BNSF
Railway’s
greenhouse
gas
(“GHG”) emissions in its baseline year of 2018. BNSF management has committed to a broad sustainabi
a
lity model, applying
science-based approaches, that is anticipated to result in a 30% reduction in BNSF Railway’s GHG emissions by 2030 from
its
baseline
year
of
2018.
BNSF
Railway
intends
to
continue
improvements
in
fuel
effi
f
ciency
and
increased
utilization
of
renewabl
a
e
diesel
fuel.
Long-term
solutions,
such
as
battery-electric
and
hydrogen
locomotives,
are
also
being
evaluated
and
field-tested.
Competition
The
business
environment
in
which
BNSF
Railway
operates
is
highly
competitive.
Depending
on
the
specific
market,
deregulated
motor
carriers
and
other
railroads,
as
well
as
river
barges,
ships
and
pipelines,
may
exert
pressure
on
price
and
service
levels.
The
presence
of
advanced,
high
service
truc
r
k
lines
with
expedited
delivery,
r
subs
u
idized
infrastructure
and
minimal empty mileage continues to affe
f
ct the market for non-bulk, time-sensitive freight. The potential expansion of longer
combination
vehicles
could
further
encroach
upon
markets
traditionally
served
by
railroads.
To
remain
competitive,
BNSF
Railway and other railroads seek to develop and implement operating effi
f
ciencies to improve productivity.
As railroads streamline, rationalize and otherwise enhance their franchises, competition among rail carriers intensifie
f
s.
BNSF Railway’s primary rail competitor in the Western region of the U.S. is Union Pacific Railroad Company. Other Class I
railroads
and
numerous
regional
railroads
and
motor
carriers
also
operate
in
parts
of
the
same
territories
served
by
BNSF
Railway.
Berkshire Hathaway Energy
Berkshire
Hathaway
Energy
Company
(“BHE”)
is
a
holding
company
headquartered
in
Iowa
with
investments
in
a
diversifie
f
d
portfol
f
io
of
locally
managed
and
operated
businesses,
principally
within
the
energy
industry.
r
BHE’s
domestic
regulated
energy
interests
are
comprised
of
four
regulated
U.S.
utility
companies
(collectively,
“U.S.
utilities”)
serving
approximately 5.4 million retail customers and five U.S. interstate natural gas pipeline companies with approximately 20,900
miles
of
operated
pipeline
having
a
design
capacity
of
approximately
21.6
billion
cubi
u
c
feet
of
natural
gas
per
day.
Other
energy
businesses
include
electric
transmission
and
distribution
operations
in
Great
Britain
and
Canada,
a
diversifie
f
d
portfol
f
io
of
mostly
renewabl
a
e
independent
power
projects
and
investments,
and
a
75%
interest
in
a
liquefied
natural
gas
export, import and storage facility. BHE also has an investment in a residential real estate brokerage firm in the U.S. and is a
franchisor
to
a
large
network
of
residential
real
estate
brokerages
in
the
U.S.
BHE
employs
approximately
24,000
people
in
connection with its various operations.
Energy
r
businesses
BHE’s
U.S.
utilities
include
PacifiCorp,
MidAmerican
Energy
Company
(“MEC”)
and
NV
Energy,
Inc.’s
(“NV
Energy”)
two
regulated
utility
subs
u
idiaries,
Nevada
Power
Company
(“Nevada
Power”)
and
Sierra
Pacific
Power
Company
(“Sierra Pacific”).
K-8
PacifiCorp
is
a
regulated
electric
utility
company
headquartered
in
Oregon,
serving
electric
customers
in
portions
of
Utah,
Oregon,
Wyoming,
Washington,
Idaho
and
Califor
f
nia.
The
combined
service
territory’s
diverse
regional
economy
ranges from rural, agricultural and mining areas to urba
r
n, manufact
f
ur
t
ing and government service centers. No single segment
of
the
economy
dominates
the
combined
service
territory,
which
helps
mitigate
PacifiCorp’s
exposure
to
economic
fluctuations. In addition to retail sales, PacifiCorp buys and sells electricity on a wholesale basis.
MEC
is
a
regulated
electric
and
natural
gas
utility
company
headquartered
in
Iowa,
serving
electric
and
natural
gas
customers primarily in Iowa and also in portions of Illinois, South Dakota and Nebraska. MEC’s diverse retail customer base
operates
in
the
electronic
data
storage,
agricultural,
manufact
f
ur
t
ing
and
government
service
centers
industries.
In
addition
to
retail sales and natural gas transportation, MEC sells electricity and natural gas on a wholesale basis.
Nevada
Power
serves
retail
electric
customers
in
southern
Nevada
and
Sierra
Pacific
serves
retail
electric
and
natural
gas
customers
in
northern
Nevada.
The
combined
Nevada
Power/Sierra
Pacific
service
territory
economy
includes
retail
customers
in
the
gaming,
mining,
recreation,
warehousing,
manufact
f
ur
t
ing
and
governmental
service
centers
sectors.
These
utilities also buy and sell electricity on a wholesale basis.
As
vertically
integrated
utilities,
BHE’s
U.S.
utilities
collectively
own
approximately
32,400
net
megawatts
of
generation
capacity
in
operation
and
under
construc
r
tion.
The
U.S.
utilities’
business
is
subj
u
ect
to
seasonal
variations
principally
related
to
the
use
of
electricity
for
air
conditioning
and
natural
gas
for
heating.
Typically,
regulated
electric
revenues are higher in the summer months, while regulated natural gas revenues are higher in the winter months.
The
natural
gas
pipelines
consist
of
BHE
GT&S,
LLC
(“BHE
GT&S”),
Northern
Natural
Gas
Company
(“Northern
Natural”) and Kern River Gas Transmission Company (“Kern River”).
BHE
GT&S,
based
in
Virginia,
operates
three
interstate
natural
gas
pipeline
systems
that
consist
of
approximately
5,400
miles
of
natural
gas
transmission,
gathering
and
storage
pipelines
and
operates
seventeen
underground
natural
gas
storage
fields
in
the
eastern
region
of
the
U.S.
BHE
GT&S’s
large
underground
natural
gas
storage
assets
and
pipeline
systems are part of an interconnected gas transmission network that provides transportation services to utilities and numerous
other
customers.
BHE
GT&S
is
also
an
industry
r
leader
in
liquefied
natural
gas
solutions
through
its
investments
in
and
ownership of several liquefied natural gas facilities located throughout the eastern region of the U.S.
Northern Natural, based in Nebraska, operates the largest interstate natural gas pipeline system in the U.S., as measured
by
pipeline
miles,
reaching
from
west
Texas
to
Michigan’s
Upper
Peninsula.
Northern
Natural’s
pipeline
system
consists
of
approximately
14,100
miles
of
natural
gas
pipelines.
Northern
Natural’s
extensive
pipeline
system,
which
is
interconnected
with
many
interstate
and
intrastate
pipelines
in
the
national
grid
system,
has
access
to
suppl
u
ies
from
multiple
majo
a
r
suppl
u
y
basins
and
provides
transportation
services
to
utilities
and
numerous
other
customers.
Northern
Natural
also
operates
three
underground
natural
gas
storage
facilities
and
two
liquefied
natural
gas
storage
peaking
units.
Northern
Natural’s
pipeline
system
experiences
significant
seasonal
swings
in
demand
and
revenue,
with
the
highest
demand
typically
occurring
during
the months of November through March.
Kern River, based in Utah, operates an interstate natural gas pipeline system that consists of approximately 1,400 miles
and
extends
from
suppl
u
y
areas
in
the
Rocky
k
Mountains
to
consuming
markets
in
Utah,
Nevada
and
Califor
f
nia.
Kern
River
transports
natural
gas
for
electric
and
natural
gas
distribution
utilities,
majo
a
r
oil
and
natural
gas
companies
or
affi
f
liates
of
such companies, electric generating companies, energy marketing and trading companies, and financial institutions.
Other
energy
businesses
include
Northern
Powergrid
(Northeast)
plc
and
Northern
Powergrid
(Yorkshire)
plc,
which
own
a
subs
u
tantial
electricity
distribution
network
that
delivers
electricity
to
end-users
in
northeast
England
in
an
area
covering
approximately
10,000
square
miles.
These
distribution
companies
primarily
charge
suppl
u
y
companies
regulated
tariffs for the use of their distribution systems and serve about 4.0 million electricity end-users. AltaLink L.P. (“AltaLink”) is
a
regulated
electric
transmission-only
utility
company
headquartered
in
Calgary,
r
Alberta.
AltaLink’s
high
voltage
transmission
lines
and
related
facilities
transmit
electricity
from
generating
facilities
to
majo
a
r
load
centers,
cities
and
large
industrial
plants
throughout
its
87,000
square
mile
service
territory.
AltaLink
serves
approximately
85%
of
Alberta’s
population.
BHE
and
its
subs
u
idiaries,
also
own
interests
in
independent
power
projects
having
approximately
6,400
net
megawatts of generation capacity that are in service and under construc
r
tion in Califor
f
nia, Texas, Illinois, Nebraska, Montana,
New
York,
Arizona,
West
Virginia,
Minnesota,
Kansas,
Iowa,
Hawaii,
Australia
and
Canada.
These
independent
power
projects
sell
power
generated
primarily
from
wind,
solar,
geothermal
and
hydro
sources
under
long-term
contracts.
Additionally,
BHE
subs
u
idiaries
have
invested
approximately
$7.1
billion
in
wind
projects
sponsored
by
third
parties,
commonly referred to as tax equity investments.
K-9
Regul
e
atory
r
matters
The
U.S.
utilities
are
subj
u
ect
to
comprehensive
regulation
by
various
federal,
state
and
local
agencies.
The
Federal
Energy
Regulatory
r
Commission
(“FERC”)
is
an
independent
agency
with
broad
authority
to
implement
provisions
of
the
Federal Power Act, the Energy Policy Act of 2005 and other federal statut
t
es. The FERC regulates rates for wholesale sales of
electricity;
transmission
of
electricity,
including
pricing
and
regional
planning
for
the
expansion
of
transmission
systems;
electric system reliabi
a
lity; utility holding companies; accounting and records retention; securities issuances; construc
r
tion and
operation of hydroelectric facilities; and other matters. The FERC also has the enforcement authority to assess civil penalties
for
violation
of
rules,
regulations
and
orders
issued
under
the
Federal
Power
Act.
MEC
is
also
subj
u
ect
to
regulation
by
the
Nuclear Regulatory
r
Commission pursuant to the Atomic Energy Act of 1954, as amended, with respect to its 25% ownership
of the Quad Cities Nuclear Station.
With certain limited exceptions, the U.S. utilities have an exclusive right to serve retail customers within their service
territories
and,
in
turn,
have
an
obligation
to
provide
service
to
those
customers.
In
some
jurisdictions,
certain
classes
of
customers
may
choose
to
purchase
all
or
a
portion
of
their
energy
from
alternative
energy
suppl
u
iers,
and
in
some
jurisdictions,
retail
customers
can
generate
all
or
a
portion
of
their
own
energy.
Historically,
state
regulatory
r
commissions
have
establ
a
ished
retail
electric
and
natural
gas
rates
on
a
cost-of-service
basis,
which
are
designed
to
allow
a
utility
the
opportunity to recover what each state regulatory commission deems to be the utility’s reasonabl
a
e costs of providing services,
including
the
opportunity
to
earn
a
fair
and
reasonabl
a
e
return
on
its
investments
based
on
its
cost
of
debt
and
equity.
The
retail
electric
rates
of
U.S.
utilities
are
generally
based
on
the
cost
of
providing
traditional
bundled
services,
including
generation,
transmission
and
distribution
services;
however,
rates
are
availabl
a
e
for
transmission-only
and
distribution-only
services.
Northern
Powergrid
(Northeast)
plc
and
Northern
Powergrid
(Yorkshire)
plc
each
charge
fees
for
the
use
of
their
distribution
systems
that
are
controlled
by
a
formula
prescribed
by
the
Gas
and
Electricity
Markets
Authority,
the
British
electricity regulatory
r
body. The current electricity distribution price control runs from April 1, 2023 through March 31, 2028.
AltaLink is regulated by the Alberta Utilities Commission (“AUC”), pursuant to the Electric Utilities Act (Alberta), the
Publ
u
ic
Utilities
Act
(Alberta),
the
Alberta
Utilities
Commission
Act
(Alberta)
and
the
Hydro
and
Electric
Energy
Act
(Alberta). The AUC is an independent quasi-judicial agency, which regulates and oversees Alberta’s electricity transmission
sector with broad authority that may impact many of AltaLink’s activities, including its tariffs, rates, construc
r
tion, operations
and financing. Under the Electric Utilities Act, AltaLink prepares and files applications with the AUC for approval of tariffsf
to
be
paid
by
the
Alberta
Electric
System
Operator
(“AESO”)
for
the
use
of
its
transmission
facilities,
and
the
terms
and
conditions
governing
the
use
of
those
facilities.
The
AESO
is
an
independent
system
operator
in
Alberta,
Canada
that
oversees
Alberta’s
integrated
electrical
system
(“AIES”)
and
wholesale
electricity
market.
The
AESO
is
responsible
for
directing the safe, reliable and economic operation of the AIES, including long-term transmission system planning.
The
natural
gas
pipelines
are
subj
u
ect
to
regulation
by
various
federal
and
state
agencies.
The
natural
gas
pipeline
and
storage operations of BHE GT&S, Northern Natural and Kern River are regulated by the FERC pursuant to the Natural Gas
Act and the Natural Gas Policy Act of 1978. Under this authority, the FERC regulates, among other items, (a) rates, charges,
terms
and
conditions
of
service;
(b)
the
construc
r
tion
and
operation
of
interstate
pipelines,
storage
and
related
facilities,
including
the
extension,
expansion
or
abandonment
of
such
facilities;
and
(c)
the
construc
r
tion
and
operation
of
liquefied
natural
gas
export/import
facilities.
Interstate
natural
gas
pipeline
companies
are
also
subj
u
ect
to
regulations
administered
by
the
Offi
f
ce
of
Pipeline
Safety
within
the
Pipeline
and
Hazardous
Materials
Safety
Administration,
an
agency
of
the
DOT.
Federal
pipeline
safety
regulations
are
issued
pursuant
to
the
Natural
Gas
Pipeline
Safety
Act
of
1968,
as
amended,
which
establ
a
ishes
safety
requirements
in
the
design,
construc
r
tion,
operation
and
maintenance
of
interstate
natural
gas
pipeline
facilities.
Environmental matters
BHE and its energy businesses are subj
u
ect to federal, state, local and foreign laws and regulations regarding air quality,
climate change, emissions performance standards, water quality, coal ash disposal and other environmental matters that have
the
potential
to
impact
current
and
future
operations.
In
addition
to
imposing
continuing
compliance
obligations,
these
laws
and
regulations,
such
as
the
Federal
Clean
Air
Act,
provide
regulators
with
the
authority
to
levy
subs
u
tantial
penalties
for
noncompliance, including fines, inju
n
nctive relief and other sanctions.
The
Federal
Clean
Air
Act,
as
well
as
state
laws
and
regulations
impacting
air
emissions,
provides
a
framework
for
protecting
and
improving
air
quality
and
controlling
sources
of
air
emissions.
The
implementation
of
these
laws
and
regulations
may
impact
the
operation
of
BHE’s
generating
facilities,
including
requiring
reductions
in
emissions
at
those
facilities to comply with the requirements. In addition, the potential adoption of state or federal clean energy standards, which
include
low-carbon,
r
non-carbon
r
and
renewabl
a
e
electricity
generating
resources,
may
also
impact
electricity
generators
and
natural gas providers.
K-10
In
December
2015,
an
international
agreement
was
negotiated
by
195
nations
to
create
a
universal
framework
for
coordinated
action
on
climate
change
in
what
is
referred
to
as
the
Paris
Agreement.
The
Paris
Agreement
reaffi
f
rms
the
goal
of limiting global temperatur
t
e increase well below 2 degrees Celsius, while urging effo
f
rts to limit the increase to 1.5 degrees
Celsius
and
reaching
a
global
peak
of
GHG
emissions
as
soon
as
possible
to
achieve
climate
neutrality
by
mid-century;
establ
a
ishes
commitments
by
all
parties
to
make
nationally
determined
contributions
and
pursue
domestic
measures
aimed
at
achieving
the
commitments;
commits
all
countries
to
subm
u
it
emissions
inventories
and
report
regularly
on
their
emissions
and
progress
made
in
implementing
and
achieving
their
nationally
determined
commitments;
and
commits
all
countries
to
subm
u
it
new
commitments
every
r
five
years,
with
the
expectation
that
the
commitments
will
be
more
aggressive
in
reducing
GHG
emissions.
The
Paris
Agreement
formally
became
effe
f
ctive
on
November
4,
2016;
however,
the
U.S.
completed
its
withdrawal from the Paris Agreement in November 2020. The U.S. accepted the terms of the Paris Agreement following the
inauguration
of
President
Biden
on
January
20,
2021,
and
completed
its
reentry
r
on
Februa
r
ry
19,
2021.
Following
President
Trum
r
p’s
inauguration
on
January
20,
2025,
the
U.S.
announced
its
second
departur
t
e
from
the
Paris
Agreement,
which
was
finalized in January 2026.
In July 2025, the EPA proposed a rule that would repeal the EPA’s 2009 Endangerment Finding, a determination that
greenhouse
gas
emissions
qualify
f
as
air
pollution
that
endangers
human
health
or
the
environment.
The
EPA
finalized
the
Endangerment
Finding
Rescission
on
Februa
r
ry
11,
2026.
The
EPA
said
that
Section
202(a)
of
the
Clean
Air
Act
does
not
allow the agency to enact emissions regulations for vehicles in a way that addresses climate change, so there is no legal basis
to
issue
the
endangerment
finding
and
any
resulting
regulations.
The
EPA
further
argues
that
the
Clean
Air
Act
was
never
intended
to
allow
for
regulation
of
greenhouse
gases
because
climate
change
is
a
global
phenomenon.
The
final
rule
is
expected
to
be
challenged
in
the
U.S.
Court
of
Appeals
for
the
District
of
Columbia
Circuit
and
ultimately
appealed
to
the
U.S.
Supr
u
eme
Court
for
final
adju
d
dication.
The
legal
process
could
take
several
years.
The
EPA
has
indicated
it
intends
to
address greenhouse gas rules for individual industry
r
sectors in separate and subs
u
equent actions.
In
April
2024,
the
EPA
finalized
new
rules
addressing
GHG
emissions
for
the
power
sector.
The
requirements
are
scheduled
to
take
effe
f
ct
January
1,
2030.
New
natural
gas-fueled
combustion
turbines
are
expected
to
utilize
lower-emitting
fuels
and
operate
as
highly
effi
f
cient
generation.
Additionally,
new
baseload
combustion
turbines
exceeding
a
40%
annual
capacity factor must meet an emission limit equivalent to operating with carbon
r
capture and sequestration beginning January
1,
2032.
The
EPA
also
identifie
f
d
carbon
r
capture
and
sequestration
as
the
technology
basis
for
the
emissions
standards
for
coal
units.
Coal-fueled
units
that
will
operate
afte
f
r
December
31,
2038,
must
meet
emission
limits
equivalent
to
operating
with
carbon
r
capture
and
sequestration
beginning
January
1,
2032.
Other
units
are
anticipated
to
co-fire
with
natural
gas
and
retire
prior
to
January
r
1,
2039,
or
convert
to
natural
gas
operations
and
meet
emission
limits
corresponding
to
capacity
factors.
The
EPA
deferred
action
on
standards
for
existing
natural
gas-fueled
combustion
turbines.
In
June
2025,
the
EPA
proposed to rescind the 2024 rules, reflecting a change in federal policy. The proposed rescission is expected to be finalized
in the spring of 2026, at which time BHE and its energy subs
u
idiaries will be able to ascertain remaining requirements.
In November 2021, the EPA proposed rules that would reduce methane emissions from both new and existing sources
in
the
oil
and
natural
gas
industry.
r
The
proposals
would
expand
and
strengthen
emission
reduction
requirements
for
new,
modified
and
reconstruc
r
ted
oil
and
natural
gas
sources
and
would
require
states
to
reduce
methane
emissions
from
existing
sources nationwide. The EPA issued a suppl
u
emental proposal in November 2022 to further strengthen emission requirements.
The
rule
was
finalized
in
December
2023.
Affe
f
cted
sources
may
have
up
to
five
years
from
the
rul
r
e’s
effective
date
to
comply with requirements identifie
f
d in state implementation plans. The rule has been challenged in the D.C. Circuit Court of
Appeals.
In
July
2025,
the
EPA
extended
several
compliance
deadlines
in
the
methane
rule
while
it
reconsiders
the
subs
u
tantive requirements of the rule.
BHE
and
its
energy
subs
u
idiaries
continue
to
focus
on
delivering
reliabl
a
e,
affo
f
rdable,
safe
and
clean
energy
to
its
customers
and
on
actions
to
mitigate
its
GHG
emissions.
BHE’s
primary
source
of
GHG
emissions
is
the
generation
of
electricity
from
its
power
plants
that
are
fueled
by
coal
or
natural
gas.
In
managing
its
electricity
generation,
BHE’s
subs
u
idiaries
work
with
their
regulators
to
protect
the
energy
and
economic
needs
of
customers
by
considering
costs,
reliabi
a
lity
and
sources
of
electric
generation.
Over
the
years,
BHE
has
invested
heavily
in
owned
renewabl
a
e
generation
and
storage,
with
cumulative
investments
of
$38.0
billion
through
December
31,
2025.
Additionally,
BHE
has
ceased
coal
operations at 22 generation units. As a result, as of December 31, 2025, BHE has reduced its annual GHG emissions by 30%
as compared to 2005 levels. To the extent it is beneficial for customers and consistent with regulatory
r
provisions, BHE plans
to continue investing in renewabl
a
e and other low-carbon
r
generation and storage in the future
and to cease coal operations at
additional coal generation units in a reliable and cost-effec
f
tive manner.
K-11
Non-Energy
r
businesses
HomeServices
of
America,
Inc.
(“HomeServices”)
is
a
residential
real
estate
brokerage
firm
in
the
U.S.
In
addition
to
providing
traditional
residential
real
estate
brokerage
services,
HomeServices
offe
f
rs
other
integrated
real
estate
services,
including
mortgage
originations
and
mortgage
banking,
title
and
closing
services,
insurance,
home
warranties,
relocation
services and other home-related services. It operates under 46 brand names with nearly 35,000 real estate agents in over 770
brokerage offi
f
ces in 35 states and the District of Columbia.
HomeServices’
fra
f
nchise
network
includes
over
250
franchisees
and
nearly
1,400
brokerage
offi
f
ces
with
approximately
39,700
third-party
real
estate
agents
under
two
brand
names.
In
exchange
for
franchise
fees,
HomeServices
provides the right to use the Berkshire Hathaway HomeServices or Real Living brand names and other related service marks,
as well as providing orientation programs, training and consultation services, advertising programs and other services.
HomeServices’
principal
sources
of
revenue
are
dependent
on
residential
real
estate
transaction
volumes,
which
are
normally higher in the second and third quarters of each year. This business is highly competitive and subj
u
ect to general real
estate market conditions.
Manufac
f
turing Businesses
Berkshire’s numerous and diverse manufact
f
ur
t
ing subs
u
idiaries are groupe
u
d into three categories: (1) industrial products,
(2)
building
products
and
(3)
consumer
products.
Berkshire’s
industrial
products
businesses
manufact
f
ur
t
e
and
distribute
components
for
aerospace
and
power
generation
applications,
specialty
chemicals,
metal
cutting
tools
and
a
variety
of
other
products
primarily
for
industrial
use.
The
building
products
group
u
produces
prefab
f
ricated
and
site-built
residential
homes,
flooring
products,
insulation,
roofin
f
g
and
engineered
produc
d
ts,
building
and
engineered
components,
paint
and
coatings
and
bricks
and
masonry
r
products.
The
consumer
products
group
u
manufact
f
ur
t
es
and/or
distributes
recreational
vehicles,
batteries,
apparel,
footwear
and
other
products.
Information
concerning
the
majo
a
r
activities
of
these
three
groups
follows.
Berkshire’s
manufact
f
ur
t
ing businesses employed approximately 175,600 people at the end of 2025.
Industrial products
Precision Castpa
t
rts
Precision
Castpa
t
rts
Corp.
(“PCC”),
based
in
Lake
Oswego,
Oregon,
manufact
f
ur
t
es
complex
metal
components
and
products
and
provides
high-quality
investment
castings,
forgings,
fasteners/fastener
systems
and
aerostruc
r
tures
for
critical
aerospace
and
power
and
energy
applications.
PCC
also
manufact
f
ur
t
es
(1)
investment
castings
and
forgings
for
general
industrial,
armament,
medical
and
other
applications;
(2)
nickel,
titanium
and
cobalt
alloys
in
all
standard
mill
forms,
including
specialty
alloys
used
to
produce
investment
castings
and
forgings
for
the
aerospace,
chemical
processing,
oil
and
gas,
pollution
control
and
other
industries;
(3)
fasteners
and
engineered
products
for
automotive
and
general
industrial
markets; and (4) other products and services for various markets and applications.
Investment
casting
technology
involves
a
multi-step
process
that
uses
ceramic
molds
in
the
manufact
f
ur
t
e
of
metal
components
with
more
complex
shapes,
closer
tolerances
and
finer
surface
finishes
than
parts
manufact
f
ur
t
ed
using
other
methods.
PCC
uses
this
process
to
manufact
f
ur
t
e
products
for
aircraft
engines,
industrial
gas
turbine
and
other
aeroderivative
engines,
airframes,
medical
implants,
armament,
unmanned
aerial
vehicles
and
other
industrial
applications.
PCC
also
manufact
f
ur
t
es
high
temperatur
t
e
carbon
r
and
ceramic
composite
components,
including
ceramic
matrix
composites,
for
use
in
next-generation aerospace engines.
PCC
uses
forging
processes
to
manufactur
t
e
components
for
the
aerospace
and
power
generation
markets.
PCC
manufact
f
ur
t
es
high-performance,
nickel-based
alloys,
as
well
as
titanium
alloys
and
products.
PCC’s
nickel-based
alloys
are
used to produce forged components and investment castings for aerospace and non-aerospace applications in such markets as
oil and gas, chemical processing and pollution control. PCC’s titanium produc
d
ts are used to manufact
f
ur
t
e components for the
commercial and military aerospace, power generation, energy, medical and industrial end markets.
PCC is also a leading developer and manufact
f
ur
t
er of highly engineered fasteners, fastener systems, aerostruc
r
tures and
precision components, primarily for critical aerospace applications. These products are produced for the aerospace and power
and
energy
markets,
as
well
as
for
construc
r
tion,
automotive,
heavy
truc
r
k,
farm
machinery,
r
mining
and
construc
r
tion
equipment, shipbuilding, machine tools, appliances and recreation markets.
PCC
has
several
significant
customers,
including
aerospace
original
equipment
manufact
f
ur
t
ers
(“OEMs”)
(Boeing
and
Airbus)
and
aircraft
engine
manufact
f
ur
t
er
suppl
u
iers
(GE
Aerospace,
Rolls
Royce
and
Pratt
&
Whitney).
The
majo
a
rity
of
PCC’s
sales
are
from
customer
orders
or
demand
schedules
pursuant
to
long-term
agreements.
Contractua
t
l
terms
may
provide
for
termination
by
the
customer,
subj
u
ect
to
payment
for
work
performed.
PCC
typically
does
not
experience
significant order cancellations, although periodically it receives requests for delays in delivery
r
schedules.
p
K-12
Long-term
industry
r
forecasts
continue
to
show
growth
and
strong
demand
for
air
travel
and
aerospace
products.
Continued
growth
in
revenues
and
earnings
will
be
predicated
on PCC’s
and
the
aerospace
industry’
r
s
abi
a
lity
to
successful
f
ly
increase production levels to match the demand in aerospace products.
PCC is subj
u
ect to subs
u
tantial competition in each of its markets. Components and similar products may be produced by
competitors, who use either the same types of manufact
f
ur
t
ing processes as PCC or other processes. Although PCC believes its
manufact
f
ur
t
ing processes, technology and experience provide its customers with advantages, such as high quality, competitive
prices
and
physical
properties
that
ofte
f
n
meet
more
stringent
demands,
alternative
forms
of
manufact
f
ur
t
ing
can
be
used
to
produce many of the same components and products. Nevertheless, PCC is a leading suppl
u
ier in most of its principal markets.
Several
factors,
including
long-standing
customer
relationships,
technical
expertise,
state-of-t
f
he-art
facilities
and
dedicated
employees, aid PCC in maintaining competitive advantages.
Several
raw
materials
used
in
PCC
products,
including
certain
metals
such
as
nickel,
titanium,
cobalt,
tantalum,
hafnium, vanadium, rhenium and molybdenum, are found in only a few parts of the world. These metals are required for the
alloys
used
in
manufact
f
ur
t
ed
products.
The
availabi
a
lity
and
costs
of
these
metals
may
be
influenced
by
private
or
governmental
cartels,
changes
in
world
politics,
labor
a
relations
between
the
metal
producers
and
their
workforces
and
inflation. Future shortages or price fluctuations in raw materials could have a material adverse effe
f
ct on results.
PCC
is
subj
u
ect
to
various
federal,
state
and
foreign
environmental
laws
concerning,
among
other
things,
water
discharges,
air
emissions,
waste
management,
toxic
materials
use
reduction
and
environmental
cleanup.
Environmental
laws
and
regulations
continue
to
evolve,
particularly
related
to
air
and
water
quality
and
climate
change,
including
reporting
of
GHG emissions. As a result, it is also reasonabl
a
y likely that PCC will be regularly required to make additional expenditures,
including capital expenditures, which could be significant, relating to environmental matters.
Lubr
u
izol
The
Lubr
u
izol
Corporation
(“Lubrizol”),
headquartered
in
Wickliffe
f
,
Ohio,
is
a
specialty
chemical
and
performance
materials
company
that
manufactur
t
es
products
and
suppl
u
ies
technologies
for
the
global
transportation,
industrial
and
consumer markets. Lubr
u
izol operates two business segments: Lubr
u
izol Additives, which produces engine lubr
u
icant additives,
driveline lubr
u
icant additives and industrial specialties products; and Lubr
u
izol Advanced Materials, which includes engineered
materials
(engineered
polymers
and
performance
coatings)
and
lifef
sciences
(beauty,
personal
care,
health
and
home
care
solutions).
Lubr
u
izol
Additives’
products
are
used
in
a
broad
range
of
applications
including
engine
oils,
transmission
fluids,
gear
oils,
specialty
driveline
lubr
u
icants,
fuels,
metalworking
fluids
and
compressor
lubr
u
icants
for
transportation
and
industrial
applications.
Lubr
u
izol
Advanced
Materials’
products
are
used
in
many
different
types
of
applications
including
beauty,
personal
care,
home
care,
over-the-counter
pharmaceuticals,
medical
devices,
performance
coatings,
sporting
goods,
plumbing
and
fire
sprinkler
systems.
Lubr
u
izol
is
an
industry
r
leader
in
many
of
the
markets
in
which
it
competes.
Lubr
u
izol
Additives’
principal
competitors
are
Infineum
International
Ltd.,
Chevron
Oronite
Company
and
Afto
f
n
Chemical
Corporation.
Lubr
u
izol
Advanced
Materials’
businesses
compete
in
many
markets
with
a
variety
of
competitors
in
each
product line.
Lubr
u
izol
uses
its
technological
leadership
position
and
applies
its
scientific
f
capabilities,
formulation
know-how
and
market expertise in product development to improve the demand, quality and value of its products. Lubr
u
izol also leverages its
scientific
f
and
applications
knowledge
to
meet
and
exceed
customer
performance
and
sustainabi
a
lity
requirements.
While
Lubr
u
izol
typically
has
patents
that
expire
each
year,
it
invests
resources
to
protect
its
intellectua
t
l
property
and
to
develop
or
acquire innovative products for the markets it serves. Lubr
u
izol uses many specialty and commodity chemical raw materials in
its
manufact
f
ur
t
ing
processes.
Raw
materials
are
primarily
feedstocks
derived
from
petroleum
and
petrochemicals
and,
generally, are obtainabl
a
e from several sources. The materials that Lubr
u
izol chooses to purchase from a single source typically
are subj
u
ect to long-term suppl
u
y contracts to ensure reliabi
a
lity.
Lubr
u
izol
operates
its
business
on
a
global
basis
through
more
than
100
offi
f
ces,
labor
a
atories,
production
facilities
and
warehouses
on
six
continents,
the
most
significant
of
which
are
North
America,
Europe,
Asia
and
South
America.
Lubr
u
izol
markets its produ
d
cts worldwide through direct sales, sales agents and distributors. Lubr
u
izol’s customers principally consist of
majo
a
r
global
and
regional
oil
companies
and
industrial
and
consumer
products
companies.
Some
of
Lubr
u
izol’s
largest
customers
also
may
be
suppl
u
iers,
although
no
single
customer
represented
more
than
10%
of
Lubr
u
izol’s
consolidated
revenues
in
2025.
In
recent
years,
suppl
u
y
chain
disrupt
r
ions
arising
from
various
sources
and
severe
weather
affe
f
cted
the
availabi
a
lity of raw materials and fulfillme
f
nt of customer orders and otherwise disrupt
r
ed Lubr
u
izol’s operations.
Lubr
u
izol
expends
significant
capi
a
tal
to
ensure
the
safety
of
its
employees
and
the
communities
where
it
operates,
as
well
as
delivering
on
its
commitments
to
operational
excellence
and
cybersecurity.
Lubr
u
izol
also
makes
significant
capital
investments
to
ensure
reliabl
a
e
suppl
u
y
and
compliance
with
regulations
governing
its
operations,
while
reducing
its
environmental footpr
t
int.
K-13
Lubr
u
izol
is
subj
u
ect
to
foreign,
federal,
state
and
local
laws
to
protect
the
environment,
limit
manufact
f
ur
t
ing
waste
and
emissions,
ensure
product
and
employee
safety
and
regulate
trade.
While
Lubr
u
izol’s
policies,
practices
and
procedur
d
es
are
designed
to
limit
the
associated
risks
and
consequent
financial
liabi
a
lity,
the
operation
of
chemical
manufact
f
ur
t
ing
plants
entails
inherent
environmental,
safety
and
other
risks,
and
significant
capital
expenditures,
costs
or
liabi
a
lities
could
be
incurred in the future.
IMC International Metalworking Companies
IMC
International
Metalworking
Companies
and
its
subs
u
idiaries
(“IMC”)
is
one
of
the
three
largest
multinational
manufact
f
ur
t
ers of consumable precision carbi
r
de metal cutting tools for applications in a broad range of industrial end markets.
IMC’s
primary
brand
names
include
ISCAR®,
TaeguTec®,
Ingersoll®,
Tungaloy®
and
NTK®.
Other
IMC
brand
names
include,
among
others,
Unitac®,
UOP,
It.te.di,
Qutiltec,
Tool—Flo®,
PCT®,
IMCO®,
BSW®,
RKS®,
Supermill®
and
Neoboss.
IMC’s
primary
manufact
f
ur
t
ing
facilities
are
in
Israel,
the
U.S.,
South
Korea,
Japa
a
n,
Germany,
Italy,
Switzerland,
India, China, Mexico and Hungary.
IMC
has
six
primary
product
lines:
milling
tools,
parting
and
grooving
tools,
turning/thread
tools,
hole
making
tools,
round
tools
and
tooling.
These
main
product
lines
are
split
between
consumable
cemented
tungsten
carbi
r
de
inserts
and
steel
tool
holders.
Inserts
comprise
a
majo
a
r
portion
of
IMC’s
sales
and
earnings.
Metal
cutting
inserts
are
used
by
industrial
manufact
f
ur
t
ers to cut metals and are consumed during their use in cutting applications. Steel tool holders are used to hold the
insert
against
the
cutting
piece.
IMC
manufact
f
ur
t
es
hundreds
of
types
of
highly
engineered
inserts
within
each
produc
d
t
line
that
are
tailored
to
maximize
productivity
and
meet
the
technical
requirements
of
customers.
IMC’s
staff
of
scientists
and
engineers continuously develop and innovate products that address end-user needs and requirements.
IMC’s
global
sales
and
marketing
network
operates
in
nearly
every
r
majo
a
r
manufact
f
ur
t
ing
center
around
the
world,
staffe
f
d
with
highly
skilled
engineers
and
technical
personnel.
IMC’s
customer
base
is
very
diverse,
with
its
primary
customers
being
large,
multinational
businesses
in
the
automotive,
aerospace,
engineering
and
machinery
r
industries.
IMC
operates
a
regional
central
warehouse
system
with
locations
in
Israel,
the
U.S.,
Belgium,
South
Korea,
Japa
a
n
and
China.
Additional
small
quantities
of
products
are
maintained
at
local
IMC
sales
offi
f
ces
to
provide
on-time
customer
suppor
u
t
and
inventory
r
management.
IMC
competes
in
the
metal
cutting
tools
segment
of
the
global
metalworking
tools
market.
The
segment
includes
hundreds
of
participants
who
range
from
small,
private
manufact
f
ur
t
ers
of
specialized
products
for
niche
applications
and
markets to larger, global multinational businesses (such as Sandvik and Kennametal, Inc.) with a wide assortment of products
and
extensive
distribution
networks.
Other
manufact
f
ur
t
ing
companies
such
as
Kyocera,
Mitsubishi,
Sumitomo,
Ceratizit,
OSG, Guhring, Mapa
a
l and YG-1 also play a significant role in the cutting tool market.
Cemented tungsten carbi
r
de powder is the main raw material used in manufact
f
ur
t
ing cutting tools. Most of IMC’s insert
products
are
made
from
tungsten.
While
suppl
u
ies,
including
alternative
sources,
are
currently
adequate,
significant
disrupt
r
ions
or
constraints
in
production
processing
facilities,
or
other
global
suppl
u
y
chain
restrictions,
could
cause
reduced
availabi
a
lity and increased prices.
IMC
is
committed
to
following
and
complying
with
all
government
and
environmental
rules,
regulations
and
requirements and applicable laws. IMC considers environmental preservation and pollution prevention as important factors in
all
operations
and
activities.
IMC
production
facilities
are
built
with
the
highest
standards
and
follow
all
applicable
regulations.
Marmon
Marmon Holdings, Inc. (“Marmon”), headquartered in Chicago, Illinois, is a global industrial organization comprising
eleven
diverse
business
groups
and
more
than
120
autonomous
manufact
f
ur
t
ing
and
service
businesses.
Marmon’s
manufact
f
ur
t
ing
and
service
operations
are
conducted
at
approximately
630
manufact
f
ur
t
ing,
distribution
and
service
facilities
located primarily in the U.S., as well as 19 other countries worldwide. Marmon’s business groups are as follows.
The
Foodservice
Technologies
group
manufact
f
ur
t
es
beverage
dispensing
and
cooling
equipment,
hot
and
cold
food
preparation and holding equipment and related products for restaurants, global brand owners and other foodservice providers.
Operations
are
based
in
the
U.S.
with
manufactur
t
ing
facilities
in
the
U.S.,
Mexico,
China,
the
Czech
Republic
and
Italy.
Products are sold primarily throughout the U.S., Europe and Asia.
The
Water
Technologies
group
manufact
f
ur
t
es
water
treatment
equipment
for
residential,
commercial
and
industrial
applications
worldwide.
Operations
are
based
primarily
in
the
U.S.,
Canada,
China,
Singapor
a
e,
India
and
Poland
with
business centers located in Belgium, France, Germany and Italy.
g
p
K-14
The
Transportation
Products
group
serves
the
automotive
and
heavy-duty
highway
transportation
industries
with
precision-molded
plastic
components;
aluminum
tubi
u
ng
and
extrus
r
ions;
replacement
parts
and
solutions
for
the
automotive
afte
f
rmarket;
dry
r
van,
flatbe
t
d,
lowbed
and
specialty
trailers;
and
truc
r
k
and
trailer
components.
Operations
are
conducted
primarily in the U.S., Mexico, Canada, Europe and China.
The
Retail
Solutions
group
provides
retailer
design
services;
in-store
digital
merchandising,
dispensing
and
display
fixtur
t
es;
and
shopping,
material
handling
and
security
carts.
Operations
are
conducted
in
the
U.S.,
the
U.K.
and
the
Czech
Republic.
The Metal Services group provides specialty metal pipe, tubi
u
ng, tooling and related value-added distribution services to
customers across a broad range of industries including aerospace, construc
r
tion and agricultural. Operations are conducted in
the U.S., India, Poland, Singapor
a
e, Spain, the U.K., the Netherlands, Canada and Mexico.
The
Electrical
group
produces
electrical
wire
for
use
in
residential
and
commercial
buildings,
and
specialty
wire
and
cable
for
use
in
energy,
transit,
aerospace,
defense,
communication
and
other
industrial
applications.
Operations
are
conducted in the U.S., Canada, India and England.
The
Plumbing
&
Refrigeration
group
manufact
f
ur
t
es
copper
tubi
u
ng
and
copper,
brass,
aluminum
and
stainless-steel
fittings and components for the plumbing, heating, ventilation, air conditioning and refrigeration (HVAC-R) market; custom
heat
exchange,
ducting,
air
handling
units
and
energy
recovery
solutions
for
the
HVAC-R
market;
HVAC
systems
and
structur
t
es
for
data
centers,
pharmaceutical
and
industrial
sites;
and
aluminum
and
brass
forgings
for
many
commercial
and
industrial
applications.
Key
raw
materials,
including
aluminum,
copper
and
stainless
steel
are
widely
availabl
a
e.
Operations
are conducted primarily in the U.S., Canada and the U.K.
The
Industrial
Products
group
suppl
u
ies
construc
r
tion
fasteners;
masonry
r
and
stone
anchoring
systems
used
in
commercial construc
r
tion; two component polymer produc
d
ts for anchoring, bonding and repair applications, gloves and other
protective wear; gear drives, gearboxe
r
s, fan and pump drives for various markets; wind machines for agricultural use; wheels,
axles
and
gears
for
rail,
mining
and
other
applications;
lighting
products
for
industrial
and
mining;
equipment
for
the
manufact
f
ur
t
e and assembly of lead acid batteries; the manufact
f
ur
t
ing and installation of afte
f
r lifef
service products; assembly of
air
compressor
systems
used
within
the
medical
and
industrial
markets;
manufact
f
ur
t
ing
and
assembly
of
various
awning
solutions
for
use
in
residential
and
motor
homes;
development
and
licensing
of
educ
d
ational
software
and
literature;
and
financial service offe
f
rings across multiple verticals. Operations are primarily based in the U.S., the U.K., Canada and China.
The Rail & Leasing group manufact
f
ur
t
es, leases and maintains railcars; leases intermodal tank containers; manufact
f
ur
t
es
mobile
railcar
movers;
provides
in-plant
rail
switching
and
loading
services;
and
performs
track
construc
r
tion
and
maintenance.
Union Tank Car Company (“UTLX”) is the largest component of the Rail & Leasing group and is a leading designer,
builder and full-service lessor of railroad tank cars and other specialized railcars. Together, with its Canadian affi
f
liate Procor,
UTLX
owns
a
fleet
of
approximately
118,000
railcars
for
lease
to
customers
in
chemical,
petrochemical,
energy
and
agricultural/food
f
industries. UTLX manufact
f
ur
t
es tank cars in the U.S. and performs railcar maintenance services at more than
100 locations across North America.
UTLX
has
a
diversifie
f
d
customer
base,
both
geographically
and
across
industries.
UTLX,
while
subj
u
ect
to
cyclicality
and significant competition in most of its markets, competes by offe
f
ring a broad range of high-quality products and services
targeted
at
its
niche
markets.
Railcars
are
typically
leased
for
multiple-year
terms
and
most
of
the
leases
are
renewed
upon
expiration.
Due
to
selective
ongoing
capital
investment,
utilization
rates
(the
number
of
railcars
on
lease
as
a
percentage
of
the total fleet) are generally high.
Intermodal tank containers are leased through EXSIF Worldwide (“EXSIF”). EXSIF is a leading international lessor of
intermodal
tank
containers
with
a
fleet
of
approximately
76,000
units,
primarily
serving
chemical
producers
and
logistics
operators.
The
Crane
Services
group
is
a
provider
of
mobile
cranes
and
operators
in
North
America
and
Australia
with
a
combined
fleet
of
approximately
1,000
cranes,
primarily
serving
the
energy,
mining,
petrochemical
and
infrastructure
markets.
Cranes
are
leased
on
a
fully
operated
and
maintained
service
basis
or
on
an
equipment-only
basis.
The
Crane
Services group is subj
u
ect to customer seasonality, with concentration of volume typically in the warmer months.
The
Medical
group
develops,
manufact
f
ur
t
es
and
sells
a
wide
range
of
innovative
medical
devices
in
the
extremities
fixation,
craniomaxillofacial
surgery,
r
neurosurgery,
aesthetics
and
cardiac
rehabi
a
litation
markets.
The
group’s
leading-edge
medical
technology
and
products
are
used
globally
to
help
improve
patient
care
and
outcomes.
Operations
are
based
in
the
U.S.,
Europe,
Australia
and
China
and
business
is
conducted
primarily
in
North
and
South
America,
Europe,
Asia
and
Australia.
K-15
Certain
Marmon
businesses,
including
the
Rail
&
Leasing
and
Medical
groups,
are
subj
u
ect
to
government
regulation
and
oversight.
Marmon
has
numerous
known
environmental
matters
which
are
subj
u
ect
to
on-going
monitoring
and/or
remediation effo
f
rts. Marmon follows all federal, state and local environmental regulations.
Other industrial products
CTB
International
Corp.
(“CTB”),
headquartered
in
Milfor
f
d,
Indiana,
is
a
leading
global
designer,
manufactur
t
er
and
marketer of a wide range of agricultural systems and solutions for preserving grain, producing poultry,
r
pigs and eggs, and for
processing
poultry,
r
fish,
vegetabl
a
es
and
other
foods.
CTB
operates
from
facilities
located
around
the
globe
and
suppor
u
ts
customers through a worldwide network of independent distributors and dealers.
CTB
competes
with
a
variety
of
manufact
f
ur
t
ers
and
suppl
u
iers,
including
many
that
offe
f
r
only
a
limited
number
of
the
products offe
f
red by CTB, as well as a few that offe
f
r products across several of CTB’s product lines. Competition is based on
the
price,
value,
reputation,
quality
and
design
of
the
products
offe
f
red
and
the
customer
service
provided
by
distributors,
dealers
and
manufact
f
ur
t
ers
of
the
products.
CTB’s
leading
brand
names,
distribution
network,
diversifie
f
d
product
line,
product
suppor
u
t
and
high-quality
products
enable
it
to
compete
effe
f
ctively.
CTB
manufact
f
ur
t
es
its
products
primarily
from
galvanized steel, steel wire, stainless steel and polymer materials. The availabi
a
lity of these materials in recent years has been
adequate.
LiquidPower
Specialty
Products
Inc.
(“LSPI”),
headquartered
in
Houston,
Texas,
is
a
global
leader
in
the
science
of
drag
reduction
application
(“DRA”)
technology
by
maximizing
the
flow
potential
of
pipelines,
increasing
operational
flexibility
and
throughput
capa
a
city,
and
effi
f
ciencies
for
customers.
LSPI
develops
innovative
flow
improver
solutions
with
customers
in
27
countries
on
five
continents,
treating
over
50
million
barrels
of
hydrocarbon
r
liquids
per
day.
LSPI’s
DRA
R
offe
f
ring
is
part
of
a
comprehensive,
full-service
solution
that
encompasses
industry-
r
leading
technology,
quality
manufact
f
ur
t
ing,
technical
suppor
u
t
and
consulting,
a
reliabl
a
e
suppl
u
y
chain,
inje
n
ction
equipment
and
field
service.
LSPI
is
subj
u
ect to foreign, federal, state and local laws to protect the environment and limit manufact
f
ur
t
ing waste and emissions.
W&W|AFCO
Steel
(“W&W|AFCO”)
is
a
leading
structur
t
al
steel
fabr
a
icator
and
steel
construc
r
tion
business
in
North
America.
W&W|AFCO
operates
19
steel
fabr
a
ication
plants
located
across
the
U.S.
W&W|AFCO’s projects
include
semiconductor plants, stadiums, high-rise buildings, bridges, mining facilities, aircraft hangars, military projects, automotive
assembly
plants,
as
well
as
international
projects.
W&W|AFCO’s
multiyear
backlog
of
projects
at
the
end
of
2025
was
subs
u
tantial.
W&W|AFCO
was
acquired
in
connection
with
the
Alleghany
acquisition
in
October
2022,
and
its
headquarters
are in Oklahoma City, Oklahoma.
Berkshire
acquired
Bell
Labor
a
atories,
LLC
(“Bell
Laboratories”)
on
July
31,
2025.
Bell
Labor
a
atories
produces
high
quality rodenticides and other rodent control products for commercial, agricultural and retail markets and is headquartered in
Windsor, Wisconsin.
OxyChem
Berkshire
completed
the
acquisition
of
Occidental
Petroleum
Corporation’s
chemicals
business
(“OxyChem”)
on
January
2,
2026,
pursuant
to
a
definitive
agreement
as
of
October
1,
2025.
Pursuant
to
the
agreement,
Occidental
retained
OxyChem’s legacy environmental liabi
a
lities. See Note 2 to the accompanying Consolidated Financial Statements. OxyChem
is
a
leading
producer
of
basic
chemicals
that
suppor
u
t
critical
applications
in
water
treatment,
pharmaceuticals,
healthcare,
manufact
f
ur
t
ing,
automotive,
personal
hygiene
and
construc
r
tion
and
other
industries.
OxyChem
is
headquartered
in
Dallas,
Texas
and
operates
21
manufact
f
ur
t
ing
plants
in
the
U.S.
in
ten
states
and
two
international
sites
in
Canada
and
Chile.
OxyChem has approximately 4,000 employees and contractors.
OxyChem
is
a
top
three
North
American
manufact
f
ur
t
er
of
polyvinyl
chloride
(PVC),
chlor-alkali
products
and
chlorinated organic chemicals. OxyChem concentrates on the chlorovinyl chain, beginning with the co-production of caustic
soda
and
chlorine,
which
are
marketed
to
external
customers.
In
addition,
chlorine,
together
with
ethylene,
is
converted
through
a
series
of
intermediate
products
into
PVC.
OxyChem
is
subj
u
ect
to
federal,
state,
local
and
foreign
government
regulations,
including
environmental
and
worker
safety
regulations,
and
invests
significant
resources
to
ensure
the
safety
of
employees
and
the
communities
in
which
it
operates
and
to
maintain
full
compliance
with
environmental
and
governmental
regulations.
OxyChem’s primary feedstocks are ethylene, ethane, natural gas and salt, which are generally obtainabl
a
e from several
sources
and
suppl
u
iers.
Materials
that
OxyChem
chooses
to
purchase
from
a
single
source
are
typically
subj
u
ect
to
long-term
suppl
u
y contracts to ensure reliabi
a
lity.
OxyChem
operates
through
five
international
sales
offi
f
ces
and
markets
its
products
worldwide
through
direct
sales,
sales agents and distributors. OxyChem’s primary customers consist of leading chemical manufact
f
ur
t
ers, several of which are
connected to OxyChem manufact
f
ur
t
ing sites via pipelines.
p
y
K-16
Building products
Clayton
Clayton Homes, Inc. (“Clayton”), headquartered near Knoxville, Tennessee, is a vertically integrated housing company
offe
f
ring off-s
f
ite (factory)
r
and site-built homes, including modular, manufact
f
ur
t
ed, CrossMod™, town homes and tiny homes.
In
2025,
Clayton
shipped
approximately
49,400
off-s
f
ite
built
homes,
over
83%
of
which
were
built
to
the
Department
of
Energy’s
Zero
Energy
Ready
Home
program
requirements,
as
well
as
approximately
10,000
site-built
homes.
Clayton
also
offe
f
rs home financing and other financial services and competes on price, service, location and delivery
r
capabilities.
All
Clayton
Built®
off-s
f
ite
built
homes
are
designed,
engineered
and
assembled
in
the
U.S.
At
the
end
of
December
2025, off-s
f
ite backlog was approximately $285 million. Clayton construc
r
ts its off-s
f
ite homes with components like windows,
interior
doors
and
cabinets
manufact
f
ur
t
ed
by
its
suppl
u
y
division.
Clayton
sells
off-s
f
ite
built
homes
through
independent
and
company-owned
home
centers,
realtors
and
subdi
u
vision
channels.
Clayton
considers
its
ability
to
offe
f
r
financing
to
retail
purchasers
a
factor
affe
f
cting
the
marketpl
t
ace
acceptance
of
its
off-s
f
ite
built
homes.
Clayton’s
fin
f
ancing
programs
utilize
proprietary loan underwriting guidelines to evaluate loan applicants.
Clayton’s
site-built
division,
Clayton
Properties
Group
(“CPG”),
includes
nine
builders
across
17
states
with
approximately
300
subdi
u
visions,
suppl
u
ementing
the
portfol
f
io
of
housing
products
offe
f
red
to
customers.
CPG
owned
and
controlled approximately 67,300 homesites, with a home order backlog of approximately $1.2 billion at the end of December
2025.
Access to key housing inputs, including lumber, oriented strand board, steel and resin products, was adequate in 2025.
Historically,
the
availabi
a
lity
and
pricing
of
these
and
other
inputs
has
been
volatile.
Clayton’s
home
building
business
is
impacted by changes in U.S. home mortgage interest rates and the suppl
u
y of pre-existing homes for sale, which affe
f
ct home
affo
f
rdability.
Clayton’s
home
building
business
regularly
makes
capital
and
non-capital
expenditures
with
respect
to
compliance
with
federal,
state
and
local
environmental
regulations,
primarily
related
to
erosion
control,
permitting
and
stormwater
protection for site-built home subdi
u
visions. The financing business originates and services loans which are federally regulated
by
the
Consumer
Financial
Protection
Bureau,
various
state
regulatory
r
agencies
and
reviewed
by
the
U.S.
Department
of
Housing and Urba
r
n Development, the Government National Mortgage Association and government-sponsored enterprises.
Shaw
Shaw
Industries
Group,
Inc.
(“Shaw”),
headquartered
in
Dalton,
Georgia,
is
a
leading
manufact
f
ur
t
er
and
distributor
of
carpe
r
t, carpe
r
t tile and hard surface flooring products. Shaw designs and manufact
f
ur
t
es over 3,800 styles of tufted carpe
r
t, wood
and
resilient
flooring
for
residential
and
commercial
use
under
numerous
brand
and
trade
names
and
under
certain
private
labe
a
ls.
Soft
and
hard
surface
products
are
availabl
a
e
in
a
broad
range
of
patterns,
colors
and
textur
t
es.
Shaw’s
carpe
r
t
manufact
f
ur
t
ing
operations
are
fully
integrated
from
the
processing
of
raw
materials
used
to
make
fiber
through
the
carpe
r
t
finishing.
Shaw’s
flooring
business
is
primarily
in
the
U.S.
Shaw
also
manufact
f
ur
t
es
carpe
r
t
tile
in
China
and
the
U.K.
and
distributes
carpe
r
t
tile
throughout
Europe
and
Southeast
Asia.
It
manufact
f
ur
t
es
or
distributes
a
variety
of
hardwood,
wood
plastic
composite,
stone
plastic
composite,
vinyl
and
laminate
floor
products
(collectively,
“hard
surfaces”).
Shaw’s
Integrated Solutions business also provides project management and installation services.
Shaw
also
operates
Shaw
Sports
Turf,
Shawgrass
and
Southwest
Greens
International,
LLC,
which
provide
synthetic
sports
turf,
golf
greens
and
landscape
turf
products.
Shaw’s
Watershed
Geosynthetics
subs
u
idiary
sells
innovative
and
patented environmental solutions for utility, waste management, erosion control and mining industries and provides patented
renewabl
a
e energy solutions.
Shaw
products
are
sold
wholesale
to
over
42,000
retailers,
distributors
and
commercial
users
throughout
the
world.
Shaw’s
wholesale
products
are
marketed
domestically
by
over
1,700
salaried
and
commissioned
sales
personnel
directly
to
retailers
and
distributors
and
to
large
national
accounts.
Shaw’s
distribution
facilities,
including
seven
carpe
r
t,
nine
hard
surfaces, one sample full-service and three sample satellite facilities and 29 redistribution centers, enable it to provide prompt
and effi
f
cient delivery
r
of its products to both its retail customers and wholesale distributors.
Subs
u
tantially all carpe
r
t manufact
f
ur
t
ed by Shaw is tufted carpe
r
t made from nylon, polypropylene and polyester, as well
as
recycled
materials.
During
2025,
Shaw
processed
approximately
92%
of
its
requirements
for
carpe
r
t
yarn
in
its
own
yarn
processing
facilities.
The
availabi
a
lity
of
raw
materials
is
adequate,
but
costs
are
impacted
by
petro-chemical
and
natural
gas
price
changes.
A
significant
portion
of
Shaw’s
soft-flooring
raw
materials
derive
from
recycled
sources.
Raw
material
cost
changes are periodically factored into selling prices to customers.
y
K-17
The soft floor covering industry
r
is highly competitive with only a handful
f
of majo
a
r competitors domestically. There are
numerous manufact
f
ur
t
ers, domestically and internationally, that are engaged in the hard surfaces flooring sector. According to
industry
r
estimates published in 2025 for 2024, carpe
r
t and rugs account for approximately 44% of the total U.S. consumption
of
all
flooring
types.
The
principal
competitive
measures
within
the
floor
covering
industry
r
are
quality,
style,
price
and
service.
Johns Manville
Johns
Manville
Corporation
(“JM”),
based
in
Denver,
Colorado,
is
a
leading
manufact
f
ur
t
er
and
marketer
of
premium-
quality products for building insulation, mechanical and industrial insulation, commercial roofin
f
g and roof insulation, as well
as reinforcement fiberglass and technical nonwovens. JM serves markets that include residential and nonresidential buildings,
automotive
and
transportation,
air
handling,
appliance,
HVAC,
pipe
and
equipment,
air
and
liquid
filtration,
waterproofing,
flooring,
interiors,
aerospace
and
wind
energy.
Fiberglass
is
the
basic
material
in
many
of
JM’s
products,
although
JM
also
manufact
f
ur
t
es a significant portion of its products with other materials to satisfy the broader needs of its customers.
JM
regards
its
patents
and
licenses
as
valuable;
however,
it
does
not
consider
any
of
its
businesses
to
be
materially
dependent
on
any
single
patent
or
license.
JM
operates
over
40
manufact
f
ur
t
ing
facilities
in
North
America
and
Europe
and
conducts research and development at its technical center in Littleton, Colorado and at other facilities in the U.S. and Europe.
Fiberglass
is
made
from
earthen
raw
materials
and
recycled
glass.
JM’s
products
also
contain
materials
other
than
fiberglass,
including
chemical
agents
to
bind
many
of
its
glass
fibers
and
various
chemical-based
and
petrochemical-based
materials used in roofin
f
g and other specialized products. JM uses recycled material when availabl
a
e and suitabl
a
e to satisfy
f
the
broader needs of its customers. The raw materials used in these various products are generally readily availabl
a
e in suffic
f
ient
quantities
from
various
sources
to
maintain
and
expand
current
production
levels,
although
the
availabi
a
lity
of
recycled
glass
can fluctuate.
JM’s
operations
are
subj
u
ect
to
a
variety
of
federal,
state
and
local
environmental
laws
and
regulations,
which
regulate
or
impose
liabi
a
lity
for
the
discharge
of
materials
into
the
air,
land
and
water
and
govern
the
use
and
disposal
of
hazardous
subs
u
tances
and
use
of
chemical
subs
u
tances.
The
most
relevant
of
the
federal
laws
are
the
Federal
Clean
Air
Act,
the
Clean
Water
Act,
the
Toxic
Subs
u
tances
Control
Act,
the
Resource
Conservation
and
Recovery
Act
and
the
Comprehensive
Environmental
Response,
Compensation
and
Liability
Act,
which
are
administered
by
the
EPA.
Canadian
and
European
regulatory
r
authorities
have
also
adopted
their
own
environmental
laws
and
regulations.
JM
continually
monitors
new
and
pending regulations and assesses their potential impact on the business. JM’s capital projects regularly address environmental
compliance,
although
capital
expenditures
for
environmental
compliance
are
generally
in
conjunction
with
other
capital
project expenditures.
JM sells its products through a wide variety of channels including contractors, distributors, retailers, manufact
f
ur
t
ers and
fabr
a
icators.
JM
operates
in
highly
competitive
markets.
Competitors
are
primarily
large
U.S.
and
internationally-based
manufact
f
ur
t
ers,
as
well
as
smaller
regional
manufact
f
ur
t
ers.
JM
holds
leadership
positions
in
the
key
markets
that
it
serves.
JM’s
products
compete
primarily
on
value,
differentiation
and
customization,
breadth
of
product
line,
quality
and
service.
Sales of JM’s products are moderately seasonal due to increases in construc
r
tion activity that typically occur in the second and
third quarters of the calendar year.
MiTek
MiTek
Industries,
Inc.
(“MiTek”),
based
in
Chesterfield,
Missouri,
operates
in
two
separate
building
markets:
residential
and
commercial.
MiTek
operates
worldwide
with
sales
in
over
60
countries
and
with
manufact
f
ur
t
ing
facilities
and/or sales/engineering offi
f
ces located in 15 countries.
In
the
residential
building
market,
MiTek
is
a
leading
suppl
u
ier
of
engineered
connector
products,
construc
r
tion
hardware,
engineering
software
and
services,
and
computer-driven
manufact
f
ur
t
ing
machinery
r
to
the
trus
r
s
component
market
of
the
building
components
industry.
r
MiTek’s
primary
customers
are
component
manufact
f
ur
t
ers,
who
manufact
f
ur
t
e
prefab
f
ricated
roof
and
floor
trus
r
ses
and
wall
panels
for
the
residential
building
market.
MiTek
also
sells
construc
r
tion
hardware to commercial distributors and retail stores for do-it-yourself customers.
A significant raw material used by MiTek is hot dipped galvanized sheet steel. While suppl
u
ies are adequate, variations
in suppl
u
y can produce significant variations in cost and availabi
a
lity.
Benjamin Moore
Benjamin
Moore
&
Co.
(“Benja
n
min
Moore”),
headquartered
in
Montvale,
New
Jersey,
is
one
of
North
America’s
leading
manufact
f
ur
t
ers
of
premium
quality
residential,
commercial
and
industrial
maintenance
coatings.
Benjamin
Moore
is
committed
to
innovation
and
sustainabl
a
e
manufact
f
ur
t
ing
practices.
The
Benjamin
Moore
premium
portfol
f
io
includes Aura®,
Regal® Select, Ben®, Advance®, Element Guard®, Woodluxe®, Ultra Spec® and others. The Benjamin Moore diversifie
f
d
brands include specialty and architectur
t
al paints from Coronado® and Insl-x®.
j
K-18
Benjamin
Moore
coatings
are
availabl
a
e
through
more
than
8,000
independently
owned
and
operated
paint,
decorating
and hardware retailers, including approximately 4,000 Ace Hardware (“Ace”) stores, throughout the U.S. and Canada, as well
as 66 other countries. Benjamin Moore is the prefer
f
red paint suppl
u
ier for Ace stores through an agreement which permits Ace
stores
to
carry
specified
Benjamin
Moore
products.
Additionally,
Benjamin
Moore
manufact
f
ur
t
es
Clark+Kensington®
and
Royal® brands, as well as the balance of Ace’s private labe
a
l paint brands.
Benjamin
Moore
also
allows
customers
to
directly
order
coatings
or
color
samples
online
or
via
its
customer
information center for national accounts. Orders may be delivered to the customer or a retailer near the customer.
Benjamin
Moore
competes
with
numerous
manufact
f
ur
t
ers,
distributors
and
paint,
coatings
and
related
products
retailers.
Product
quality,
product
innovation,
breadth
of
product
line,
technical
expertise,
service
and
price
determine
the
competitive
advantage.
Competitors
include
other
premium
paint
and
decorating
stores,
mass
merchandisers,
home
centers,
independent hardware stores, hardware chains and manufact
f
ur
t
er-operated direct outlets, such as Sherwin-Williams Company,
The Pittsburgh Paints Company, The Home Depot, Inc., Lowe’s Companies, Inc and Farrow & Ball.
The most significant raw materials in Benjamin Moore products are titanium dioxide, monomers, polymers, packaging
materials and pigments. Historically, the purchased raw materials have been generally availabl
a
e, with pricing and availabi
a
lity
subj
u
ect to fluctuation.
Benjamin
Moore
complies
with
applicable
regulations
relating
to
protection
of
the
environment
and
workers’
safet
f
y
and
Benjamin
Moore
products
are
compliant
with
environmental
standards.
Benjamin
Moore
has
certain
known
past
environmental matters, which are subj
u
ect to on-going monitoring and/or remediation effo
f
rts.
Acme
Acme Brick Company (“Acme”), headquartered in Fort Worth, Texas, manufact
f
ur
t
es and distributes clay bricks (Acme
Brick®)
and
concrete
block
(Featherlite).
In
addition,
Acme
distributes
numerous
other
building
products
of
other
manufact
f
ur
t
ers, including cladding, floor and wall tile, wood flooring and other masonry
r
products. Products are sold primarily
in
the
South
Central
and
Southeastern
U.S.
through
company-operated
sales
offi
f
ces.
Acme
distributes
products
primarily
to
homebuilders and masonry
r
and general contractors.
Acme operates 12 clay brick manufactur
t
ing sites located in four states and three concrete block facilities in Texas. The
demand
for
Acme’s
products
is
seasonal,
with
higher
sales
in
the
warmer
weather
months,
and
is
subj
u
ect
to
the
level
of
construc
r
tion
activity,
which
is
cyclical.
Acme
also
owns
and
leases
properties
and
mineral
rights
that
suppl
u
y
raw
materials
used in many of its manufactur
t
ed products. Acme’s raw materials suppl
u
y is currently adequate.
The brick industry
r
is subj
u
ect to the EPA Maximum Achievable Control Technology Standards (“MACT”). As required
under
the
1990
Clean
Air
Act,
the
EPA
developed
a
list
of
source
categories
that
require
the
development
of
National
Emission Standards for Hazardous Air Pollutants, which are also referred to as MACT Standards (“Rul
R
e”). Key elements of
the MACT Rule include emission limits establ
a
ished for certain hazardous air pollutants and acidic gases. Acme’s brick plants
comply with the current Rule.
Consumer products
Recreational vehicles
Forest
River,
Inc.
(“Forest
River”),
headquartered
in
Elkhart,
Indiana,
manufact
f
ur
t
es
recreational
vehicles
(“RV”),
utility
cargo
trailers,
commercial
truc
r
ks,
buses
and
pontoon
boats,
which
are
sold
in
the
U.S.
and
Canada
through
an
independent
dealer
network.
Forest
River
has
numerous
manufactur
t
ing
facilities
located
in
seven
states
and
is
a
leading
manufact
f
ur
t
er
of
RVs
with
numerous
brand
names,
including
Forest
River,
Coachmen
RV,
Cherokee,
Rockwood,
Salem,
Wildwood,
Surveyor,
Sunseeker,
Entrada,
Forester
and
Georgetown.
Utility
cargo
trailers
are
sold
under
a
variety
of
brand
names.
Commercial
truc
r
ks
are
sold
under
the
Rockpor
k
t
brand
name.
Buses
are
sold
under
several
brand
names,
including
Starcraftf
Bus. Pontoon boats are sold under the Berkshire, South Bay, Trifect
f
a and Dockside brand names.
The
RV
industry
r
is
highly
competitive.
Competition
is
based
primarily
on
price,
design,
quality
and
service.
The
industry
r
has
consolidated
over
the
past
several
years
and
is
concentrated
in
a
few
companies,
the
largest
of
which
had
a
market
share
of
approximately
39%
based
on
industry
r
data
as
of
December
2025.
Forest
River
held
a
market
share
of
approximately 36% at that time. Forest River is subj
u
ect to regulations of the National Traffi
f
c and Motor Vehicle Safety Act,
the
safety
standards
for
recreational
vehicles
establ
a
ished
by
the
U.S.
Department
of
Transportation
and
similar
laws
and
regulations issued by the Canadian government. Forest River is a member of the Recreational Vehicle Industry
r
Association, a
voluntary
r
association
of
RV
manufact
f
ur
t
ers
which
promotes
safety
standards
for
RVs.
Forest
River
believes
its
products
comply in all material respects with the standards that govern their products.
K-19
Apparel and footwear
Frui
r
t
of
the
Loom,
Inc.
(“FOL”),
headquartered
in
Bowling
Green,
Kentuc
t
ky,
manufact
f
ur
t
es
and
distributes
basic
apparel,
underwear,
outerwear,
athletic
apparel
and
sports
equipment.
Products
under
the
Frui
r
t
of
the
Loom®
and
JERZEES®
labels
are
primarily
sold
in
the
mass
merchandise,
mid-tier
chains
and
wholesale
markets.
In
the
Vanity
Fair
Brands product line, Vassarette®, Curvation® and Radiant by Vanity Fair® are sold in the mass merchandise market, while
other
Vanity
Fair®
products
are
sold
to
mid-tier
chains
and
department
stores.
FOL
also
markets
and
sells
athletic
apparel
and sports equipment to team dealers and to sporting goods retailers under the Russell Athletic® and Spalding® brands.
FOL
generally
perfor
f
ms
its
own
knitting,
cloth
finishing,
cutting,
sewing
and
packaging
for
apparel.
For
the
North
American market, which is FOL’s predominant sales region, cloth manufact
f
ur
t
ing is primarily performed in Honduras. Labor
a
-
intensive
cutting,
sewing
and
packaging
operations
are
in
Central
America
and
Asia.
For
the
European
market,
products
are
either
sourced
from
third-party
contractors
in
Europe
or
Asia
or
sewn
in
Morocco
from
textiles
internally
produced
in
Morocco.
Athletic
equipment,
sporting
goods
and
other
athletic
apparel
lines
are
generally
sourced
from
third-party
contractors located primarily in Asia.
U.S.-grown
cotton
fiber
and
manufact
f
ur
t
ed
polyester
fiber
are
the
main
raw
materials
used
in
manufact
f
ur
t
ing
FOL’s
products.
Currently,
suppl
u
ies
are
adequate.
If
relationships
with
suppl
u
iers
cannot
be
maintained
or
delays
occur
in
obtaining
alternative
sources
of
suppl
u
y,
production
can
be
adversely
affe
f
cted,
which
can
result
in
a
corresponding
adverse
effe
f
ct
on
results
of
operations.
FOL’s
markets
are
highly
competitive,
consisting
of
many
domestic
and
foreign
manufact
f
ur
t
ers
and
distributors. Competition is generally based upon product featur
t
es, quality, customer service and price.
Garan Incorporated (“Garan”), headquartered in New York, New York, designs, manufact
f
ur
t
es, imports and distributes
children’s
apparel,
including
products
for
boys,
girls,
toddlers
and
infants.
Garan
markets
its
products
under
its
own
trademarks,
including
GARANI
R
MALS®,
365
Kids
from
Garanimals®
and
easy-peasy®,
as
well
as
customer
private-labe
a
l
brands and licensed trademarks, and sells to a diversifie
f
d group of retailers as well as through its direct-to-consumer channel.
Garan operates through subs
u
idiaries located in the U.S., Central America and Asia, with subs
u
tantially all products distributed
through
its
U.S.-based
distribution
centers.
Fechheimer
Brothers
Company
(“Fechheimers”)
manufact
f
ur
t
es
and
distributes
uniforms,
principally
for
the
publ
u
ic
service
and
safety
markets,
including
police,
fire,
postal
and
military
markets.
Fechheimers is based in Cincinnati, Ohio.
Through
its
subs
u
idiaries,
BH
Shoe
Holdings,
Inc.
manufact
f
ur
t
es,
imports
and
distributes
work,
rugged
outdoor
and
casual
shoes
and
western-style
footwear
under
several
brand
names,
including
Justin®,
BØRN®,
Carolina®,
Söfft
f
®
and
Double-H
Boots®,
as
well
as
under
several
other
brand
names.
Brooks
Sports,
Inc.,
headquartered
in
Seattle,
Washington,
markets and sells high-performance running footwear and apparel to specialty and national retailers and directly to consumers
under
the
Brooks®
brand.
A
significant
volume
of
the
shoes
sold
by
Berkshire’s
shoe
businesses
are
manufact
f
ur
t
ed
or
purchased
from
sources
located
outside
the
U.S.
Products
are
sold
worldwide
through
a
variety
of
channels
including
department
stores,
footwear
chains,
specialty
stores,
catalogs
and
e-commerce,
as
well
as
through
company-owned
retail
stores.
Other consumer products
The Duracell Company (“Duracell”), headquartered in Chicago, Illinois, is a leading manufact
f
ur
t
er of high-performance
alkaline and lithium coin batteries. Duracell manufact
f
ur
t
es batteries primarily in the U.S., as well as in Europe and China and
provides a network of worldwide sales and distribution centers. Duracell sells its products to a diverse group of retailers and
distributors across the globe. There are several competitors in the battery manufact
f
ur
t
ing market. Duracell estimates that it had
a 32% market share of the global alkaline battery market in 2025. The availabi
a
lity of raw materials, which are primarily steel,
zinc, manganese and nickel-based chemistries, is currently suffic
f
ient.
The consumer products group also includes Jazwares, LLC, (“Jazwares”), acquired in October 2022 in connection with
Alleghany. Jazwares, headquartered in Plantation, Florida, is a leading global toy and consumer products manufact
f
ur
t
er with a
robust portfol
f
io of owned and licensed brands, such as Squishmallows™, BLDR™, Pokémon™, Hello Kitty™, Star Wars™,
Disney™,
BumBumz™Stranger
Things™and
Five
Nights
at
Freddy’s™.
In
addition
to
toys
and
plush,
offe
f
rings
also
include virtua
t
l games, costum
t
es, pet products and housewares. Jazwares sells its products in more than 100 countries.
Richline Group, Inc., headquartered in New York, New York, operates four strategic business units: Richline Jewelry,
r
LeachGarner,
Rio
Grande
and
Inverness.
Each
business
unit
is
a
manufact
f
ur
t
er
and/or
distributor
of
precious
metal,
non-
precious
metal,
diamond
and
gem
products
to
specific
target
markets,
including
large
jewelry
r
chains,
department
stores,
shopping
networks,
mass
merchandisers,
e-commerce
retailers
and
artisans
as
well
as
certain
global
manufact
f
ur
t
ers
and
wholesalers
in
the
medical,
electronics
and
aerospace
industries.
Albecca
Inc.,
headquartered
in
Suwanee,
Georgia,
operates
in the U.S., Canada and several other countries, primarily under the Larson-Juhl® name (“Larson-Juhl”). Larson-Juhl designs
and
distributes
a
complete
line
of
high
quality,
branded
custom
framing
products,
including
wood
and
metal
moulding,
matboard, foamboard, glass and framing suppl
u
ies. Complementary
r
to its framing products, Larson Juhl offe
f
rs art printing and
fulfillme
f
nt services.
pp
p
K-20
Service and Retailing Businesses
Service businesses
Berkshire’s service businesses provide shared aircraft ownership programs and profes
f
sional aviation training programs
(“aviation
services”),
and
distribution
of
electronic
components.
Additionally,
service
businesses
include
franchising
and
servicing of quick service restaurants, media businesses (television and information distribution), as well as logistics services
businesses.
Berkshire’s
service
businesses,
excluding
McLane,
employed
approximately
31,200
people
at
the
end
of
2025.
Information regarding each of these operations follows.
NetJets
NetJets
is
the
leader
in
private
aviation
services
and
operates
a
large,
diverse
private
aircraft
fleet
and
offe
f
rs
a
full
range
of
personalized
private
aviation
solutions
to
meet
and
exceed
the
high
standards
of
its
customers.
NetJets’
global
headquarters
are
in
Columbus,
Ohio
and
its
European
operations
are
based
in
Lisbon,
Portuga
t
l.
The
shared
ownership
concept
is
designed
to
meet
the
travel
needs
of
customers
who
require
the
scale,
flexibility
and
access
of
a
large
fleet
of
aircraft
as
opposed
to
reliance
on
whole
aircraft
ownership.
In
addition,
shared
ownership
programs
are
availabl
a
e
for
corporate flight departments seeking to outsource their general aviation needs or add capacity for peak periods and for others
that previously chartered aircraft.
NetJets’
programs
are
focused
on
safety
and
service
and
are
designed
to
offe
f
r
customers
guaranteed
availabi
a
lity
of
aircraft, predictabl
a
e operating costs and increased liquidity. NetJets’ shared aircraft ownership programs permit customers to
acquire
a
specific
percentage
of
a
certain
aircraft
type
and
allow
customers
to
utilize
the
aircraft
for
a
specified
number
of
flight
hours
annually.
In
addition,
NetJets
offe
f
rs
prepaid
flight
cards
and
other
aviation
solutions
and
services
for
aircraft
management, customized aircraft sales and acquisition, ground suppor
u
t and flight operation services under several programs,
including NetJets Shares™, NetJets Leases™and the NetJets Card Program™.
NetJets
is
subj
u
ect
to
the
rules
and
regulations
of
the
U.S.
Federal
Aviation
Administration
(“FAA”),
the
Portugue
t
se
Civil
Aviation
Authority
and
the
European
Union
Aviation
Safety
Agency.
Regulations
address
aircraft
registration,
maintenance
requirements,
pilot
qualific
f
ations
and
airport
operations,
including
flight
planning
and
scheduling,
as
well
as
security
issues
and
other
matters.
NetJets
maintains
comprehensive
training
and
development
programs
in
compliance
with
regulatory
r
requirements
for
pilots,
flight
attendants,
maintenance
mechanics
and
other
flight
operations
specialists,
many
of
whom are represented by unions.
FlightSafety
FlightSafety
is
an
industry
r
leading
provider
of
profes
f
sional
aviation
training
services
and
flight
simulation
products.
FlightSafety
and
FlightSafety
Textron
Aviation
Training,
a
joint
ventur
t
e
with
Textron,
provide
high
technology
training
to
pilots, aircraft maintenance technicians, flight attendants and dispatchers who operate and suppor
u
t a wide variety of business,
commercial
and
military
aircraft.
The
training
is
provided
using
a
large
fleet
of
advanced
full
flight
simulators
at
learning
centers and training locations in the U.S., Australia, Brazil, Canada, France, Japa
a
n, Norway, Singapor
a
e, South Afri
f
ca and the
U.K.
Compliance
with
applicable
environmental
regulations
is
an
inherent
requirement
to
operate
the
facilities.
The
vast
majo
a
rity
of
the
instructors,
training
programs
and
flight
simulators
are
qualifie
f
d
by
the
FAA
and
other
aviation
regulatory
r
agencies around the world.
FlightSafety, based in Columbus, Ohio, is also a leader in the design and manufact
f
ur
t
ing of full flight simulators, visual
systems,
displays
and
other
advanced
technology
training
devices.
This
equipment
is
used
to
suppor
u
t
FlightSafety
training
programs and is offe
f
red for sale to airlines and governments around the world. Manufact
f
ur
t
ing facilities are in Oklahoma and
Illinois.
FlightSafety
strives
to
maintain
and
manufact
f
ur
t
e
simulators
and
develop
courseware
using
state-of-t
f
he-art
technology, incorporating critical safety standards and procedur
d
es. FlightSafety invests in research and development, further
advancing the delivery
r
of new equipment and training programs.
TTI
TTI,
Inc.
(“TTI”),
headquartered
in
Fort
Worth,
Texas,
is
a
global
specialty
distributor
of
passive,
interconnect,
electromechanical,
discrete
and
semiconductor
components
used
by
customers
in
the
manufact
f
ur
t
ing
and
assembling
of
electronic
products.
TTI’s
customer
base
includes
OEMs,
electronic
manufact
f
ur
t
ing
services,
original
design
manufact
f
ur
t
ers
and
military
and
commercial
customers,
as
well
as
design
and
system
engineers.
TTI’s
distribution
agreements
with
the
industry’
r
s
leading
suppl
u
iers
allow
it
to
uniquely
leverage
its
produc
d
t
cost
and
to
expand
its
business
by
providing
new
lines
and
products
to
its
customers.
TTI
operates
sales
offi
f
ces
and
distribution
centers
from
more
than
180
locations
throughout
North America, South America, Europe and Asia.
g
y
K-21
TTI
services
a
variety
of
industries
including
telecommunications,
medical
devices,
computers
and
offi
f
ce
equipment,
military/aerospace,
automotive
and
industrial
electronics.
TTI’s
core
businesses
serve
customers
in
the
design
through
production
stages
in
the
electronic
component
suppl
u
y
chain,
which
suppor
u
ts
high-volume
customers.
Its
Mouser
subs
u
idiary
suppor
u
ts
a
broader
base
of
customers
with
lower
volume
purchases
through
internet-based
marketing,
and
its
XTG
division
services customers with specialty semiconductors and design services.
McLane
McLane Company, Inc. (“McLane”) provides wholesale distribution services in all 50 states to customers that include
convenience
stores,
discount
retailers,
wholesale
clubs,
drug
r
stores,
military
bases,
quick
service
restaurants
and
casual
dining
restaurants.
McLane’s
majo
a
r
customers
during
2025
included
Walmart
(appr
a
oximately
17.2%
of
revenues);
7-Eleven
(appr
a
oximately
13.3%
of
revenues);
and
Yum!
Brands
(appr
a
oximately
13.3%
of
revenues).
McLane’s
business
model
is
based
on
a
high
volume
of
sales,
rapi
a
d
inventory
r
turnover
and
stringent
expense
controls.
Operations
are
divided
into
three
business units: retail distribution, restaurant distribution and beverage distribution.
McLane’s
retail
distribution
unit,
based
in
Temple,
Texas,
is
a
leader
within
the
convenience
store
market,
serving
many
national
convenience
store
chains
and
majo
a
r
oil
company
retail
outlets.
Retail
operations
provide
products
to
approximately
43,100
retail
locations
nationwide.
McLane’s
retail
distribution
unit
operates
27
distribution
facilities
in
20
states.
McLane’s
restaurant
distribution
unit,
based
in
Carrollton,
Texas,
focuses
on
serving
the
quick
service
and
casual
dining
restaurant
industry
r
with
high
quality,
timely-delivered
products.
Operations
are
conducted
through
46
facilities
in
22
states. The restaurant distribution unit services approximately 35,300 restaurants nationwide.
Through its subs
u
idiaries, McLane also operates wholesale distributors of distilled spirits, wine and beer. The beverage
unit
operates
as
Empire
Distributors,
with
operations
conducted
through
14
distribution
centers
in
Georgia,
North
Carolina,
Tennessee
and
Colorado.
Empire
Distributors
services
approximately
30,800
retail
locations
in
the
Southeastern
U.S.
and
Colorado. McLane had approximately 24,900 employees at the end of 2025.
Other
XTRA
Corporation
(“XTRA”
R
),
headquartered
in
St.
Louis,
Missouri,
is
a
leading
transportation
equipment
lessor
operating under the XTRA Lease® brand name. XTRA manages a diverse fleet of approximately 90,000 units located at 47
facilities
throughout
the
U.S.
The
fleet
includes
over-the-road
and
storage
trailers,
chassis,
temperatur
t
e-controlled
vans
and
flatbe
t
d
trailers.
XTRA
is
one
of
the
largest
lessors
(in
terms
of
units
availabl
a
e)
of
over-the-road
trailers
in
North
America.
Transportation equipment customers lease equipment to cover cyclical, seasonal and geographic needs and as a subs
u
titute for
purchasing
equipment.
By
maintaining
a
large
fleet,
XTRA
provides
customers
with
a
broad
selection
of
equipment
and
quick response times.
IPS-Integrated Project Services, LLC (“IPS”) was acquired in connection with the Alleghany acquisition in 2022. IPS
operates
globally
and
provides
a
range
of
profes
f
sional
design,
qualific
f
ation/validation,
construc
r
tion
and
construc
r
tion/pr
/
oject
management
consulting
services
for
manufact
f
ur
t
ing,
research
labor
a
atory
r
and
suppor
u
t
facilities
within
the
pharmaceutical,
biotech
and
lifef
sciences,
technology,
data
center,
industrial,
commercial
and
retail
industries
sectors.
Most
of
IPS
services
are subj
u
ect to strict regulatory
r
compliance requirements that adds to the complexity of its services.
International
Dairy
r
Queen
Inc.
develops
and
services
a
worldwide
system
of
approximately
7,800
franchised
restaurants
operating
primarily
under
the
names
DQ
Grill
and
Chill®,
Dairy
Queen®,
DQ®
and
Orange
Julius®
that
offe
f
r
various
dairy
r
desserts,
beverages,
prepared
foods
and
blended
fruit
drinks.
Business
Wire
Inc.
(“Business
Wire”)
transmits
full-text
news
releases,
regulatory
r
filings,
photos
and
other
multimedia
content
primarily
to
journalists,
financial
profes
f
sionals, investor services and regulatory
r
authorities. Releases are distributed globally via Business Wire’s patented NX
network.
CORT
Business
Services
Corporation
(“CORT”)
is
a
leading
national
provider
of
rental
furniture
and
related
services
in
the
“rent-to-rent”
segment
of
the
furniture
rental
industry.
r
CORT
primarily
rents
furniture
to
individua
d
ls,
businesses,
government
agencies
and
the
trade
show
and
events
industry.
r
CORT
also
sells
new
and
used
furniture.
WPLG,
Inc.
is
an
independent
television
broadcasting
station
serving
the
Miami/Ft.
Lauderdale
market
and
operates
WPLG-TV,
local10.com,
MeTV
South
Florida
and
Heroes
&
Icons
Network
in
South
Florida.
Charter
Brokerage
Holdings
Corp.
is
a
leading non-asset based third party logistics provider to various industries.
Retailing businesses
Berkshire’s
retailing
businesses
include
automotive,
home
furnishings
and
several
other
operations
that
sell
various
consumer products and services. Berkshire’s retailing businesses, excluding Pilot, employed approximately 25,400 people at
the end of 2025. Information regarding each of these operations follows.
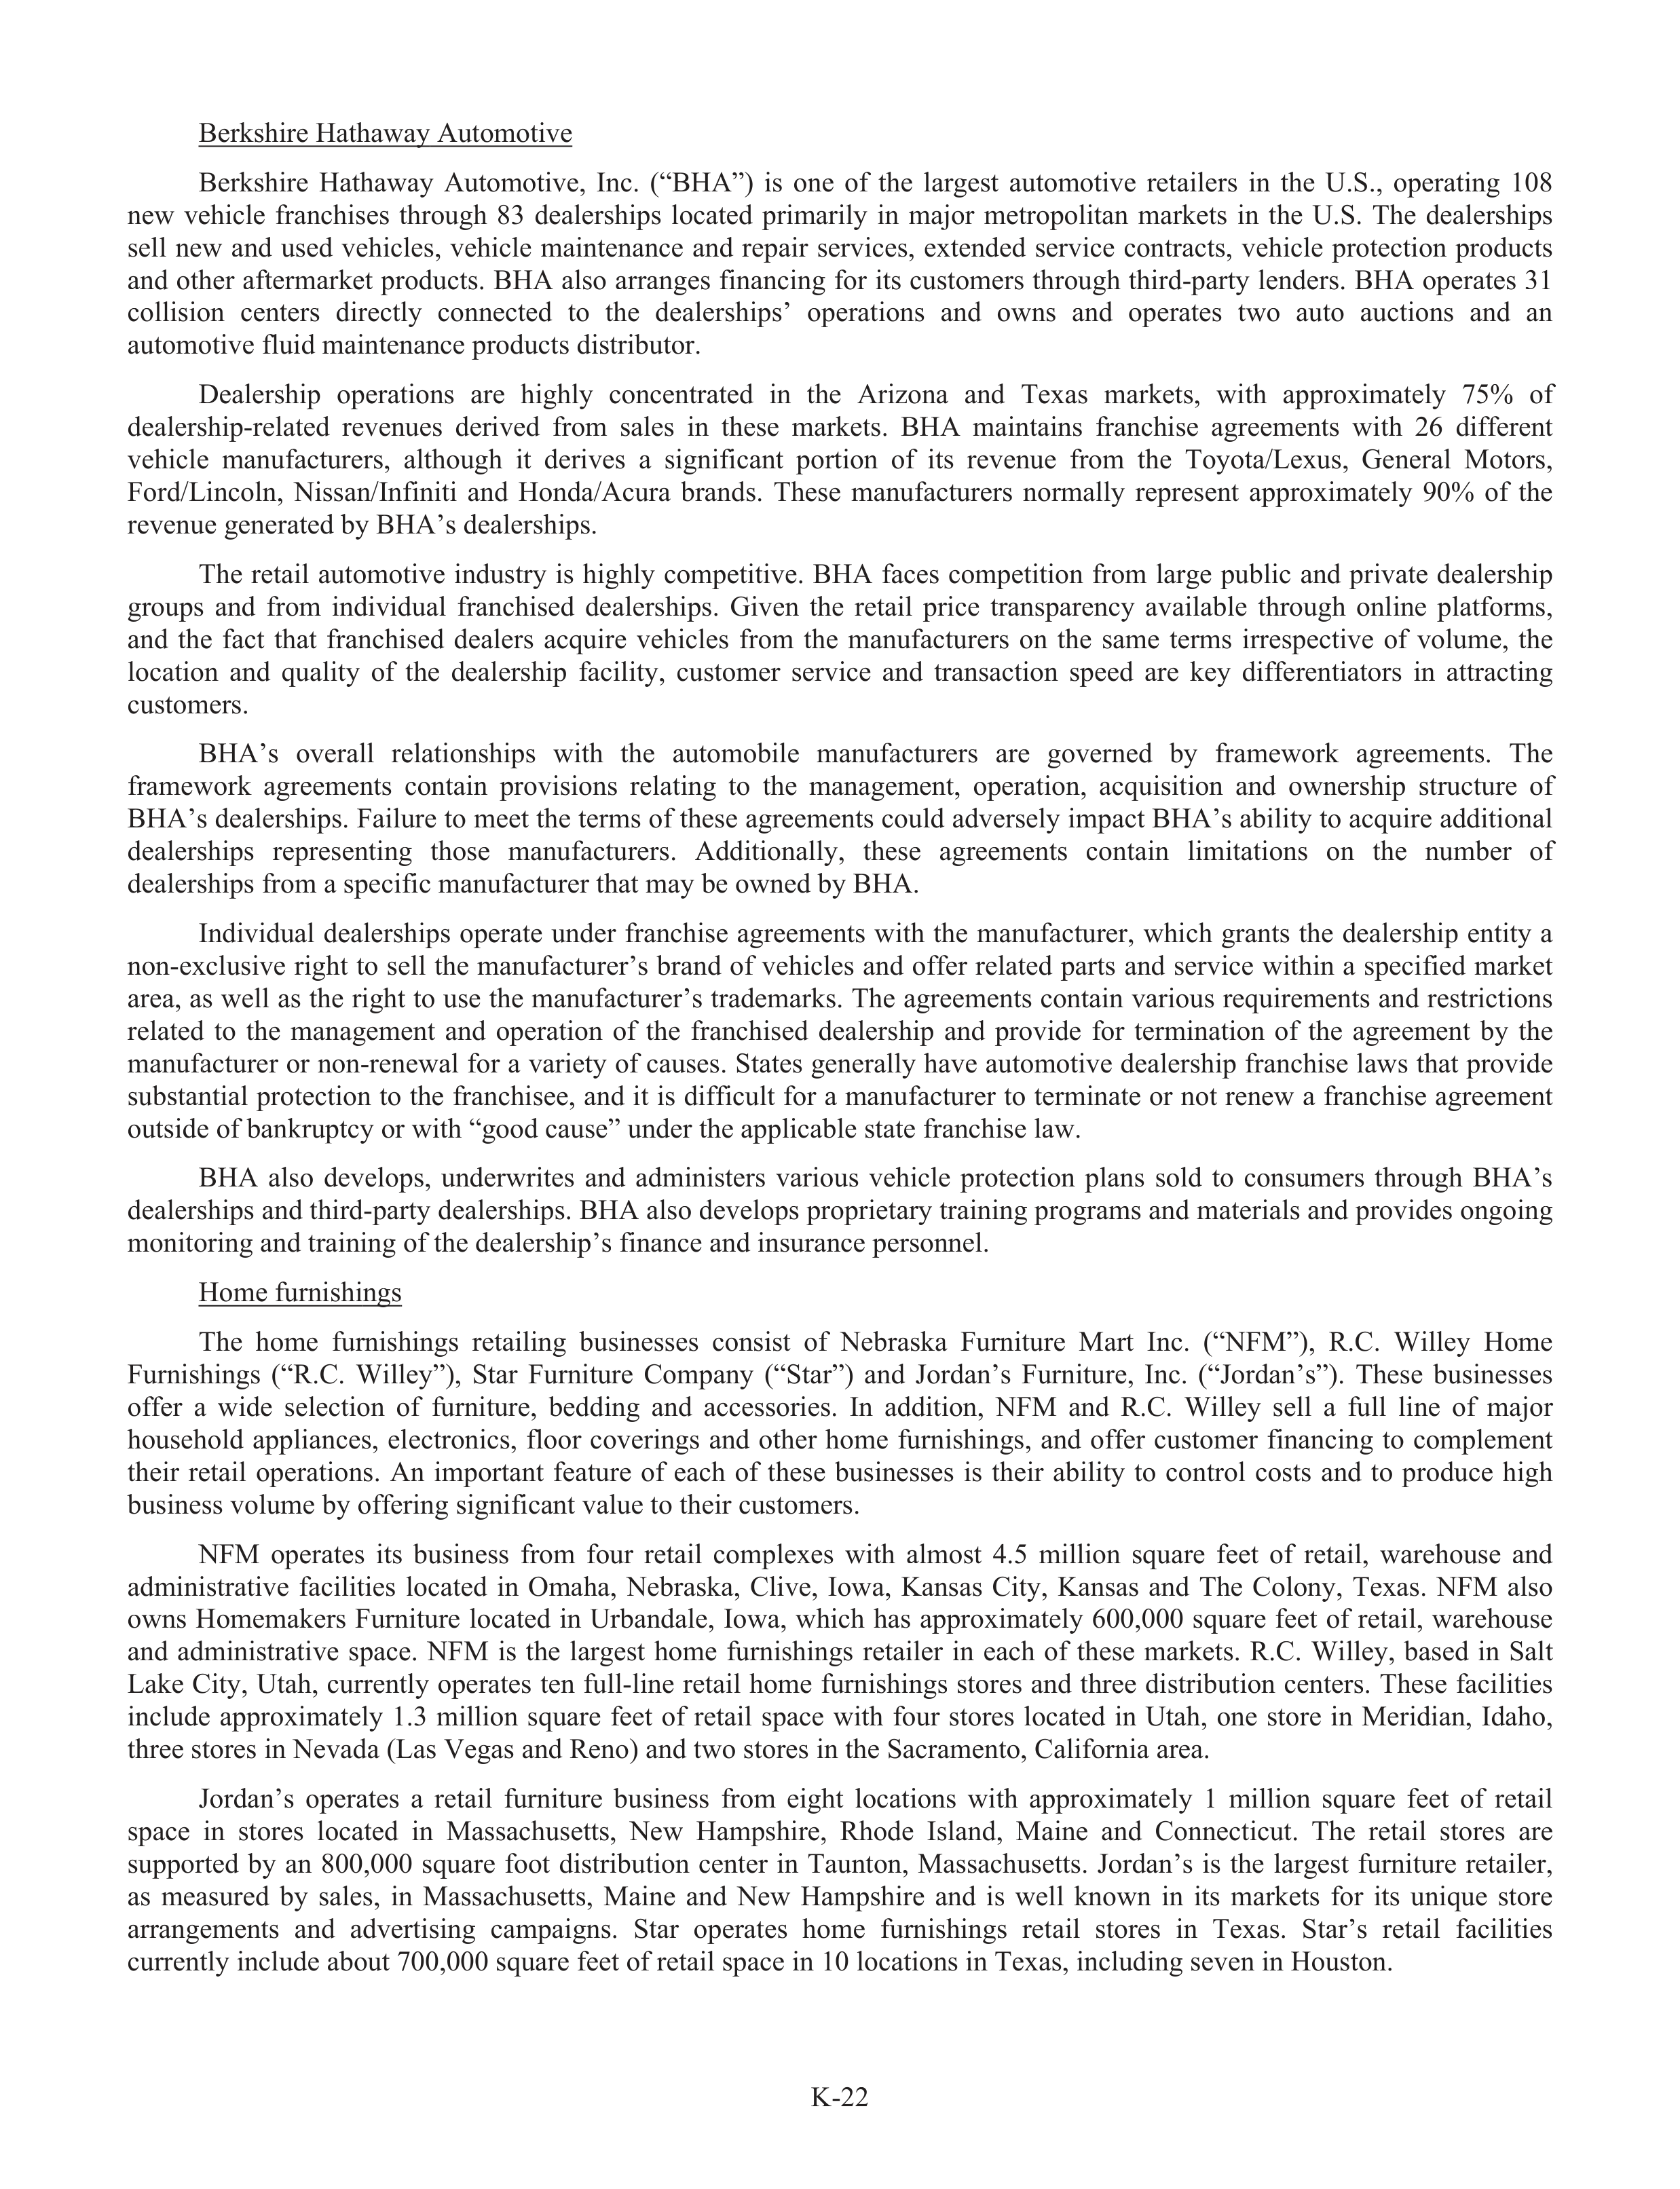
K-22
Berkshire Hathaway Automotive
Berkshire
Hathaway
Automotive,
Inc.
(“BHA”)
is
one
of
the
largest
automotive
retailers
in
the
U.S.,
operating
108
new
vehicle
franchises
through
83
dealerships
located
primarily
in
majo
a
r
metropolitan
markets
in
the
U.S.
The
dealerships
sell
new
and
used
vehicles,
vehicle
maintenance
and
repair
services,
extended
service
contracts,
vehicle
protection
products
and other afte
f
rmarket products. BHA also arranges financing for its customers through third-party lenders. BHA operates 31
collision
centers
directly
connected
to
the
dealerships’
operations
and
owns
and
operates
two
auto
auctions
and
an
automotive fluid maintenance products distributor.
Dealership
operations
are
highly
concentrated
in
the
Arizona
and
Texas
markets,
with
approximately
75%
of
dealership-related
revenues
derived
from
sales
in
these
markets.
BHA
maintains
franchise
agreements
with
26
different
vehicle
manufact
f
ur
t
ers,
although
it
derives
a
significant
portion
of
its
revenue
from
the
Toyota/Lexus,
General
Motors,
Ford/L
d
incoln,
Nissan/Infiniti
and
Honda/Acura
brands.
These
manufact
f
ur
t
ers
normally
represent
approximately
90%
of
the
revenue generated by BHA’s dealerships.
The
retail
automotive
industry
r
is
highly
competitive.
BHA
faces
competition
from
large
public
and
private
dealership
groups
and
from
individual
franchised
dealerships.
Given
the
retail
price
transparency
availabl
a
e
through
online
platforms,
and
the
fact
that
franchised
dealers
acquire
vehicles
from
the
manufact
f
ur
t
ers
on
the
same
terms
irrespective
of
volume,
the
location
and
quality
of
the
dealership
facility,
customer
service
and
transaction
speed
are
key
differentiators
in
attracting
customers.
BHA’s
overall
relationships
with
the
automobile
manufact
f
ur
t
ers
are
governed
by
framework
agreements.
The
framework
agreements
contain
provisions
relating
to
the
management,
operation,
acquisition
and
ownership
structure
of
BHA’s dealerships. Failure to meet the terms of these agreements could adversely impact BHA’s abi
a
lity to acquire additional
dealerships
representing
those
manufact
f
ur
t
ers.
Additionally,
these
agreements
contain
limitations
on
the
number
of
dealerships from a specific manufactur
t
er that may be owned by BHA.
Individual
dealerships
operate
under
franchise
agreements
with
the
manufact
f
ur
t
er,
which
grants
the
dealership
entity
a
non-exclusive right to sell the manufact
f
ur
t
er’s brand of vehicles and offe
f
r related parts and service within a specified market
area, as well as the right to use the manufact
f
ur
t
er’s trademarks. The agreements contain various requirements and restrictions
related
to
the
management
and
operation
of
the
franchised
dealership
and
provide
for
termination
of
the
agreement
by
the
manufact
f
ur
t
er or non-renewal for a variety of causes. States generally have automotive dealership franchise laws that provide
subs
u
tantial protection to the franchisee, and it is difficult for a manufact
f
ur
t
er to terminate or not renew a franchise agreement
outside of bankrupt
r
cy or with “good cause” under the applicable state franchise law.
BHA
also
develops,
underwrites
and
administers
various
vehicle
protection
plans
sold
to
consumers
through
BHA’s
dealerships and third-party dealerships. BHA also develops proprietary training programs and materials and provides ongoing
monitoring and training of the dealership’s finance and insurance personnel.
Home furnishings
The
home
furnishings
retailing
businesses
consist
of
Nebraska
Furniture
Mart
Inc.
(“NFM”),
R.C.
Willey
Home
Furnishings
(“R.C.
Willey”),
Star
Furniture
Company
(“Star”)
and
Jordan’s
Furniture,
Inc.
(“Jordan’s”).
These
businesses
offe
f
r
a
wide
selection
of
furnitur
t
e,
bedding
and
accessories.
In
addition,
NFM
and
R.C.
Willey
sell
a
full
line
of
majo
a
r
household
appliances,
electronics,
floor
coverings
and
other
home
furnishings,
and
offe
f
r
customer
financing
to
complement
their
retail
operations.
An
important
featur
t
e
of
each
of
these
businesses
is
their
ability
to
control
costs
and
to
produc
d
e
high
business volume by offe
f
ring significant value to their customers.
NFM
operates
its
business
from
four
retail
complexes
with
almost
4.5
million
square
feet
of
retail,
warehouse
and
administrative
facilities
located
in
Omaha,
Nebraska,
Clive,
Iowa,
Kansas
City,
Kansas
and
The
Colony,
Texas.
NFM
also
owns
Homemakers
Furniture
located
in
Urba
r
ndale,
Iowa,
which
has
approximately
600,000
square
feet
of
retail,
warehouse
and
administrative
space.
NFM
is
the
largest
home
furnishings
retailer
in
each
of
these
markets.
R.C.
Willey,
based
in
Salt
Lake City, Utah, currently operates ten full-line retail home furnishings stores and three distribution centers. These facilities
include
approximately
1.3
million
square
feet
of
retail
space
with
four
stores
located
in
Utah,
one
store
in
Meridian,
Idaho,
three stores in Nevada (Las Vegas and Reno) and two stores in the Sacramento, Califor
f
nia area.
Jordan’s
operates
a
retail
furniture
business
from
eight
locations
with
approximately
1
million
square
feet
of
retail
space
in
stores
located
in
Massachusetts,
New
Hampshire,
Rhode
Island,
Maine
and
Connecticut.
The
retail
stores
are
suppor
u
ted
by
an
800,000
square
foot
distribution
center
in
Taunton,
Massachusetts.
Jordan’s
is
the
largest
furniture
retailer,
as
measured
by
sales,
in
Massachusetts,
Maine
and
New
Hampshire
and
is
well
known
in
its
markets
for
its
unique
store
arrangements
and
advertising
campaigns.
Star
operates
home
furnishings
retail
stores
in
Texas.
Star’s
retail
facilities
currently include about 700,000 square feet of retail space in 10 locations in Texas, including seven in Houston.
y
g
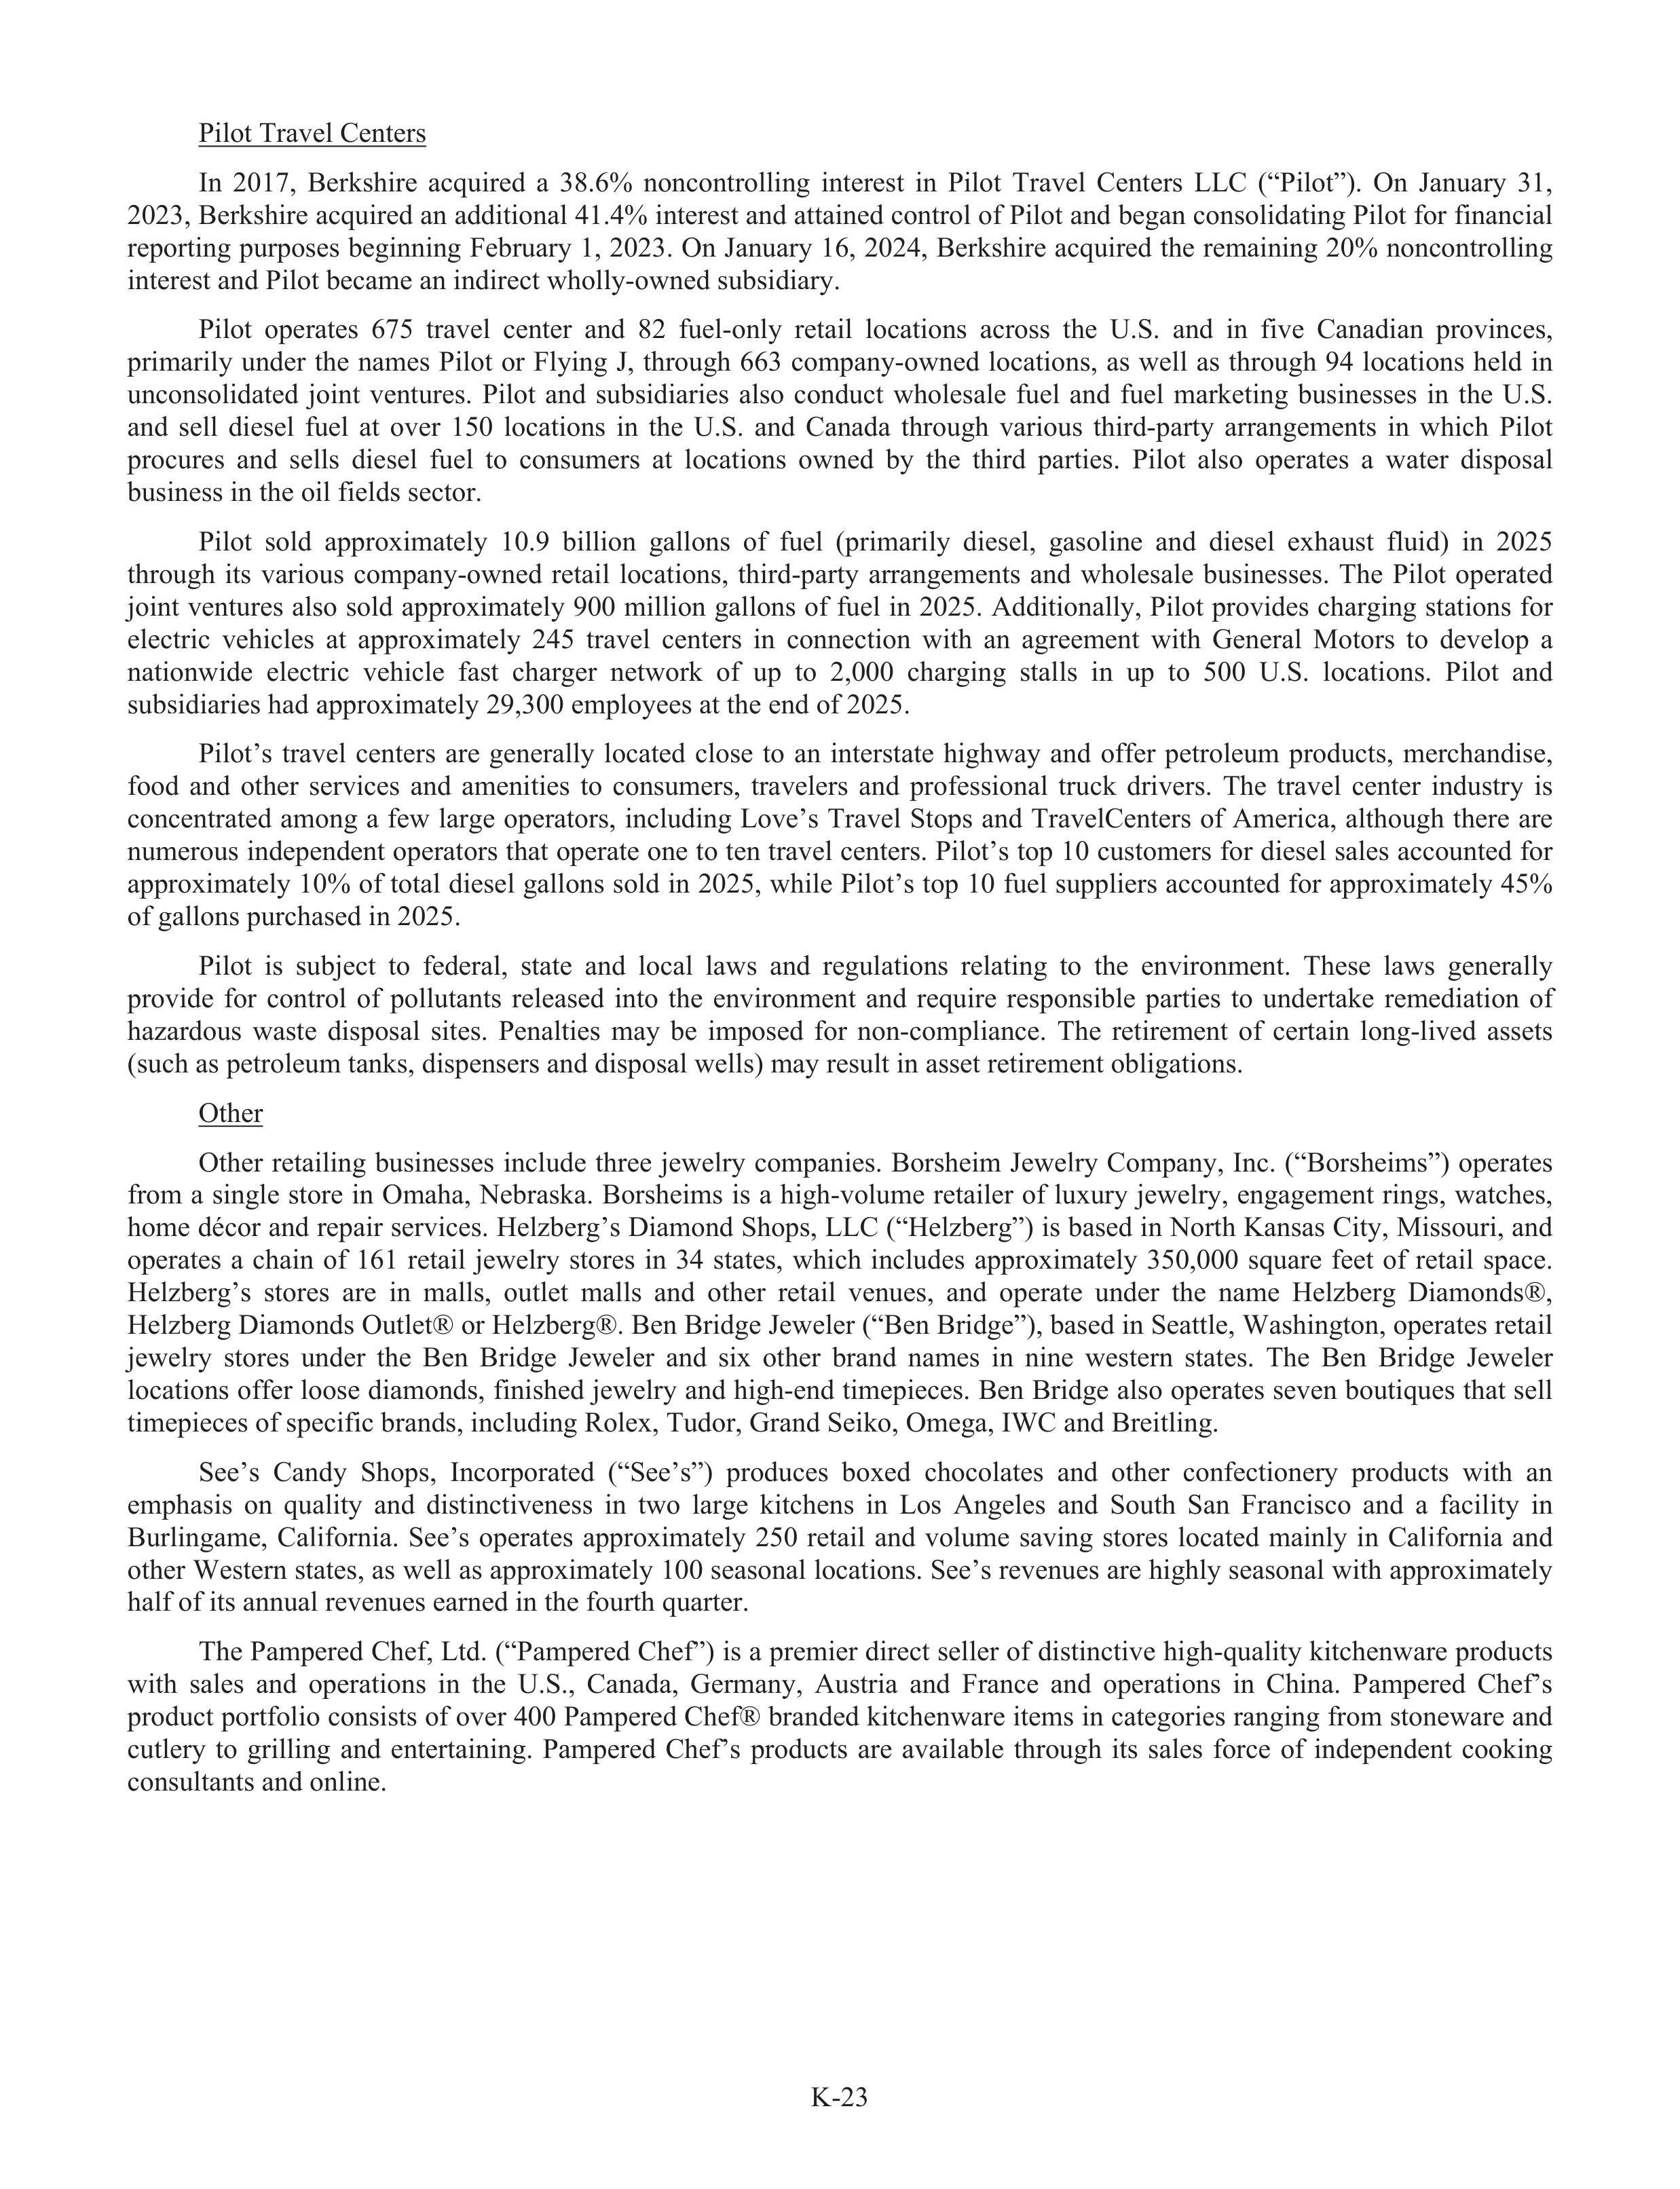
K-23
Pilot Travel Centers
In
2017,
Berkshire
acquired
a
38.6%
noncontrolling
interest
in
Pilot
Travel
Centers
LLC
(“Pilot”).
On
January
31,
2023, Berkshire acquired an additional 41.4% interest and attained control of Pilot and began consolidating Pilot for financial
reporting purpos
r
es beginning Februa
r
ry 1, 2023. On January 16, 2024, Berkshire acquired the remaining 20% noncontrolling
interest and Pilot became an indirect wholly-owned subs
u
idiary.
Pilot
operates
675
travel
center
and
82
fuel-only
retail
locations
across
the
U.S.
and
in
five
Canadian
provinces,
primarily
under
the
names
Pilot
or
Flying
J,
through
663
company-owned
locations,
as
well
as
through
94
locations
held
in
unconsolidated
joint
ventur
t
es.
Pilot
and
subs
u
idiaries
also
conduct
wholesale
fuel
and
fuel
marketing
businesses
in
the
U.S.
and
sell
diesel
fuel
at
over
150
locations
in
the
U.S.
and
Canada
through
various
third-party
arrangements
in
which
Pilot
procures
and
sells
diesel
fuel
to
consumers
at
locations
owned
by
the
third
parties.
Pilot
also
operates
a
water
disposal
business in the oil fields sector.
Pilot
sold
approximately
10.9
billion
gallons
of
fuel
(primarily
diesel,
gasoline
and
diesel
exhaust
fluid)
in
2025
through
its
various
company-owned
retail
locations,
third-party
arrangements
and
wholesale
businesses.
The
Pilot
operated
joint ventur
t
es also sold approximately 900 million gallons of fuel in 2025. Additionally, Pilot provides charging stations for
electric
vehicles
at
approximately
245
travel
centers
in
connection
with
an
agreement
with
General
Motors
to
develop
a
nationwide
electric
vehicle
fast
charger
network
of
up
to
2,000
charging
stalls
in
up
to
500
U.S.
locations.
Pilot
and
subs
u
idiaries had approximately 29,300 employees at the end of 2025.
Pilot’s
travel
centers
are
generally
located
close
to
an
interstate
highway
and
offe
f
r
petroleum
products,
merchandise,
food
and
other
services
and
amenities
to
consumers,
travelers
and
profes
f
sional
truc
r
k
drivers.
The
travel
center
industry
r
is
concentrated
among
a
few
large
operators,
including
Love’s
Travel
Stops
and
TravelCenters
of
America,
although
there
are
numerous independent operators that operate one to ten travel centers. Pilot’s top 10 customers for diesel sales accounted for
approximately 10% of total diesel gallons sold in 2025, while Pilot’s top 10 fuel suppl
u
iers accounted for approximately 45%
of gallons purchased in 2025.
Pilot
is
subj
u
ect
to
federal,
state
and
local
laws
and
regulations
relating
to
the
environment.
These
laws
generally
provide
for
control
of
pollutants
released
into
the
environment
and
require
responsible
parties
to
undertake
remediation
of
hazardous
waste
disposal
sites.
Penalties
may
be
imposed
for
non-compliance.
The
retirement
of
certain
long-lived
assets
(such as petroleum tanks, dispensers and disposal wells) may result in asset retirement obligations.
Other
Other
retailing
businesses
include
three
jewelry
r
companies.
Borsheim
Jewelry
r
Company,
Inc.
(“Borsheims”)
operates
from
a
single
store
in
Omaha,
Nebraska.
Borsheims
is
a
high-volume
retailer
of
luxury
r
jewelry,
r
engagement
rings,
watches,
home décor and repair services. Helzberg’s Diamond Shops, LLC (“Helzberg”) is based in North Kansas City, Missouri, and
operates
a
chain
of
161
retail
jewelry
r
stores
in
34
states,
which
includes
approximately
350,000
square
feet
of
retail
space.
Helzberg’s
stores
are
in
malls,
outlet
malls
and
other
retail
venues,
and
operate
under
the
name
Helzberg
Diamonds®,
Helzberg Diamonds Outlet® or Helzberg®. Ben Bridge Jeweler (“Ben Bridge”), based in Seattle, Washington, operates retail
jewelry
r
stores
under
the
Ben
Bridge
Jeweler
and
six
other
brand
names
in
nine
western
states.
The
Ben
Bridge
Jeweler
locations offe
f
r loose diamonds, finished jewelry
r
and high-end timepieces. Ben Bridge also operates seven boutiques that sell
timepieces of specific
f
brands, including Rolex, Tudor, Grand Seiko, Omega, IWC and Breitling.
See’s
Candy
Shops,
Incorporated
(“See’s”)
produces
boxed
chocolates
and
other
confect
f
ionery
products
with
an
emphasis
on
quality
and
distinctiveness
in
two
large
kitchens
in
Los
Angeles
and
South
San
Francisco
and
a
facility
in
Burlingame,
Califor
f
nia.
See’s
operates
approximately
250
retail
and
volume
saving
stores
located
mainly
in
Califor
f
nia
and
other Western states, as well as appr
a
oximately 100 seasonal locations. See’s revenues are highly seasonal with approximately
half of its annual revenues earned in the fourth quarter.
The Pampered Chef,f
Ltd. (“Pampered Chef”)
f
is a premier direct seller of distinctive high-quality kitchenware products
with
sales
and
operations
in
the
U.S.,
Canada,
Germany,
Austria
and
France
and
operations
in
China.
Pampered
Chef’s
f
product portfol
f
io consists of over 400 Pampered Chef® b
f
randed kitchenware items in categories ranging from stoneware and
cutlery
to
grilling
and
entertaining.
Pampered
Chef’s
f
products
are
availabl
a
e
through
its
sales
force
of
independent
cooking
consultants and online.
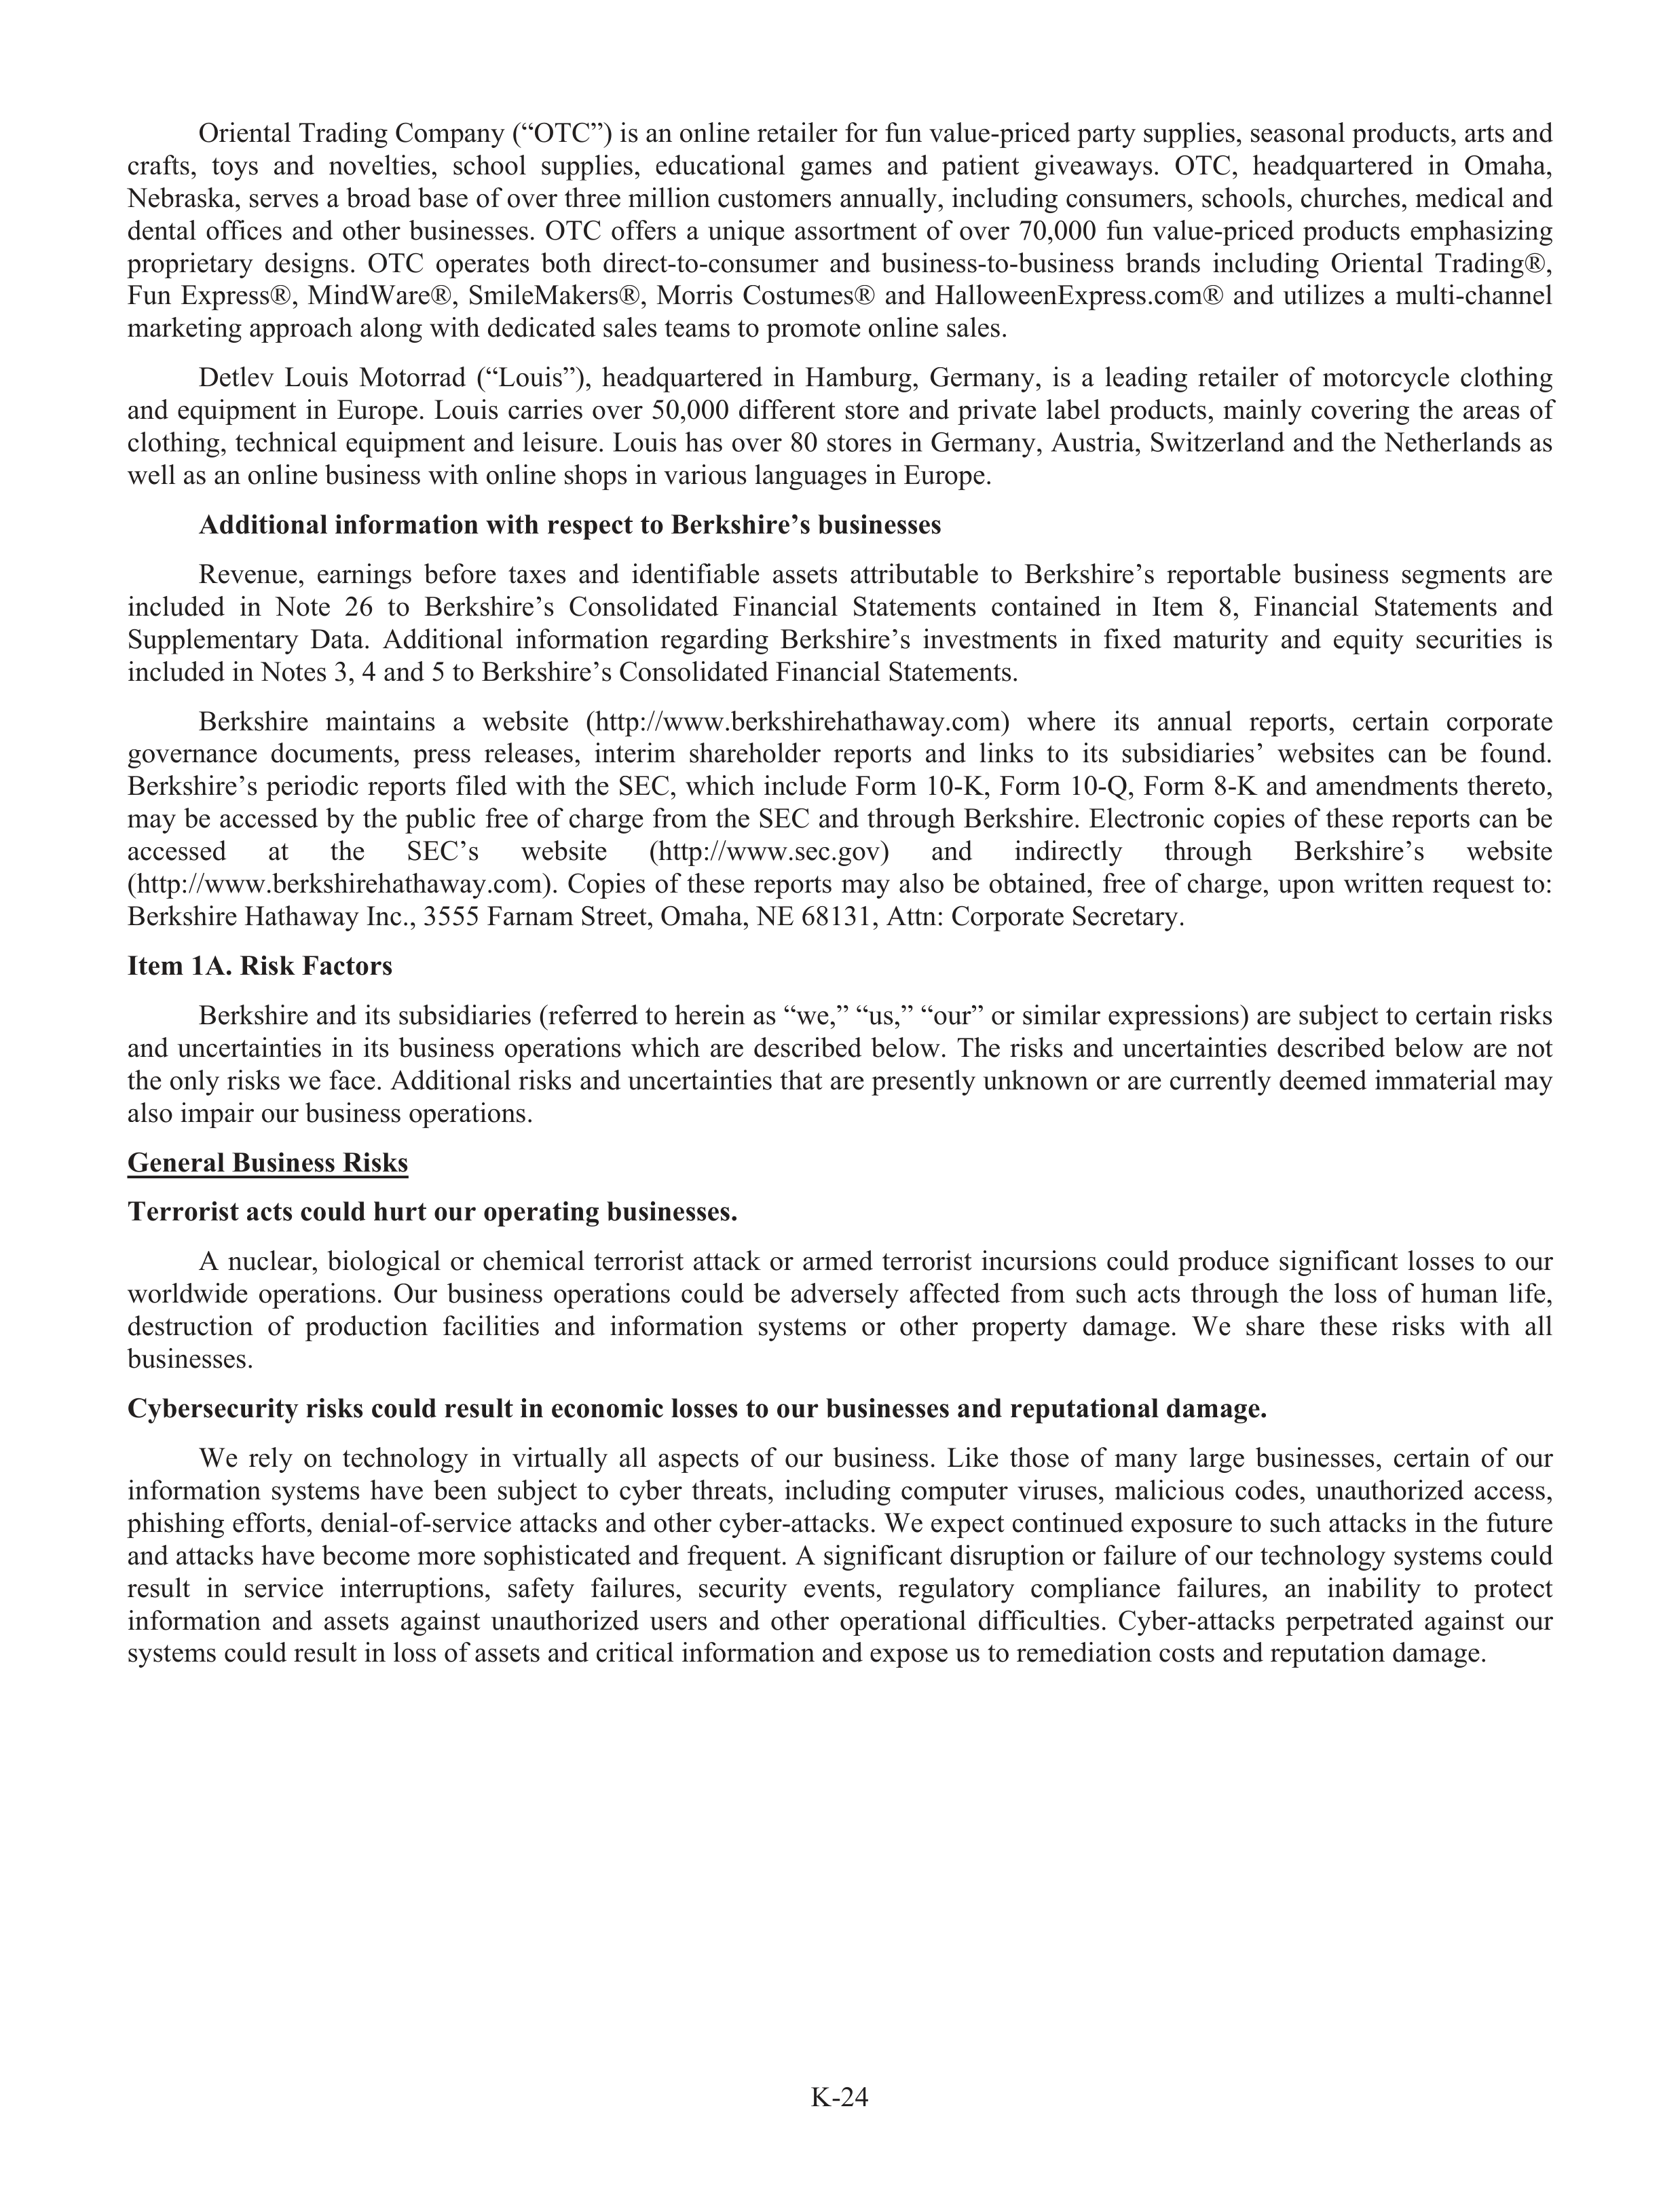
K-24
Oriental Trading Company (“OTC”) is an online retailer for fun value-priced party suppl
u
ies, seasonal products, arts and
crafts
f
,
toys
and
novelties,
school
suppl
u
ies,
educ
d
ational
games
and
patient
giveaways.
OTC,
headquartered
in
Omaha,
Nebraska, serves a broad base of over three million customers annually, including consumers, schools, churches, medical and
dental
offi
f
ces
and
other
businesses.
OTC
offe
f
rs
a
unique
assortment
of
over
70,000
fun
value-priced
products
emphasizing
proprietary
designs.
OTC
operates
both
direct-to-consumer
and
business-to-business
brands
including
Oriental
Trading®,
Fun
Express®,
MindWare®,
SmileMakers®,
Morris
Costumes®
and
HalloweenExpress.com®
and
utilizes
a
multi-channel
marketing approach along with dedicated sales teams to promote online sales.
Detlev
Louis
Motorrad
(“Louis”),
headquartered
in
Hamburg,
Germany,
is
a
leading
retailer
of
motorcycle
clothing
and
equipment
in
Europe.
Louis
carries
over
50,000
different
store
and
private
labe
a
l
products,
mainly
covering
the
areas
of
clothing, technical equipment and leisure. Louis has over 80 stores in Germany, Austria, Switzerland and the Netherlands as
well as an online business with online shops in various languages in Europe.
Additional information with respect to Berkshire’s businesses
Revenue,
earnings
before
taxes
and
identifia
f
bl
a
e
assets
attributable
to
Berkshire’s
reportabl
a
e
business
segments
are
included
in
Note
26
to
Berkshire’s
Consolidated
Financial
Statements
contained
in
Item
8,
Financial
Statements
and
Suppl
u
ementary
Data.
Additional
information
regarding
Berkshire’s
investments
in
fixed
maturity
and
equity
securities
is
included in Notes 3, 4 and 5 to Berkshire’s Consolidated Financial Statements.
Berkshire
maintains
a
website
(http://www.berkshirehathaway.com)
where
its
annual
reports,
certain
corporate
governance
documents,
press
releases,
interim
shareholder
reports
and
links
to
its
subs
u
idiaries’
websites
can
be
found.
Berkshire’s
periodic
reports
filed
with
the
SEC,
which
include
Form
10-K,
Form
10-Q,
Form
8-K
and
amendments
thereto,
may be accessed by the public free of charge from the SEC and through Berkshire. Electronic copies of these reports can be
accessed
at
the
SEC’s
website
(http:
t
//www.sec.gov)
and
indirectly
through
Berkshire’s
website
(http://www.berkshirehathaway.com).
Copies
of
these
reports
may
also
be
obtained,
free
of
charge,
upon
written
request
to:
Berkshire Hathaway Inc., 3555 Farnam Street, Omaha, NE 68131, Attn: Corporate Secretary.
r
Item 1A. Risk Factors
Berkshire and its subs
u
idiaries (referred to herein as “we,” “us,” “our” or similar expressions) are subj
u
ect to certain risks
and
uncertainties
in
its
business
operations
which
are
described
below.
The
risks
and
uncertainties
described
below
are
not
the only risks we face. Additional risks and uncertainties that are presently unknown or are currently deemed immaterial may
also impair our business operations.
General Business Risks
Terrorist acts could hurt our operating businesses.
A
nuclear,
biological
or
chemical
terrorist
attack
or
armed
terrorist
incursions
could
produce
significant
losses
to
our
worldwide
operations.
Our
business
operations
could
be
adversely
affe
f
cted
from
such
acts
through
the
loss
of
human
life,
f
destruction
of
production
facilities
and
information
systems
or
other
property
damage.
We
share
these
risks
with
all
businesses.
Cybersecurity risks could result in economic losses to our businesses and reputational damage.
We
rely
on
technology
in
virtua
t
lly
all
aspects
of
our
business.
Like
those
of
many
large
businesses,
certain
of
our
information
systems
have
been
subj
u
ect
to
cyber
threats,
including
computer
viruses,
malicious
codes,
unauthorized
access,
phishing effo
f
rts, denial-of-service attacks and other cyber-attacks. We expect continued exposure to such attacks in the future
and attacks have become more sophisticated and frequent. A significant disrupt
r
ion or failure of our technology systems could
result
in
service
interrupt
u
ions,
safety
failures,
security
events,
regulatory
r
compliance
failures,
an
inability
to
protect
information
and
assets
against
unauthorized
users
and
other
operational
difficulties.
Cyber-attacks
perpetrated
against
our
systems could result in loss of assets and critical information and expose us to remediation costs and reputation damage.
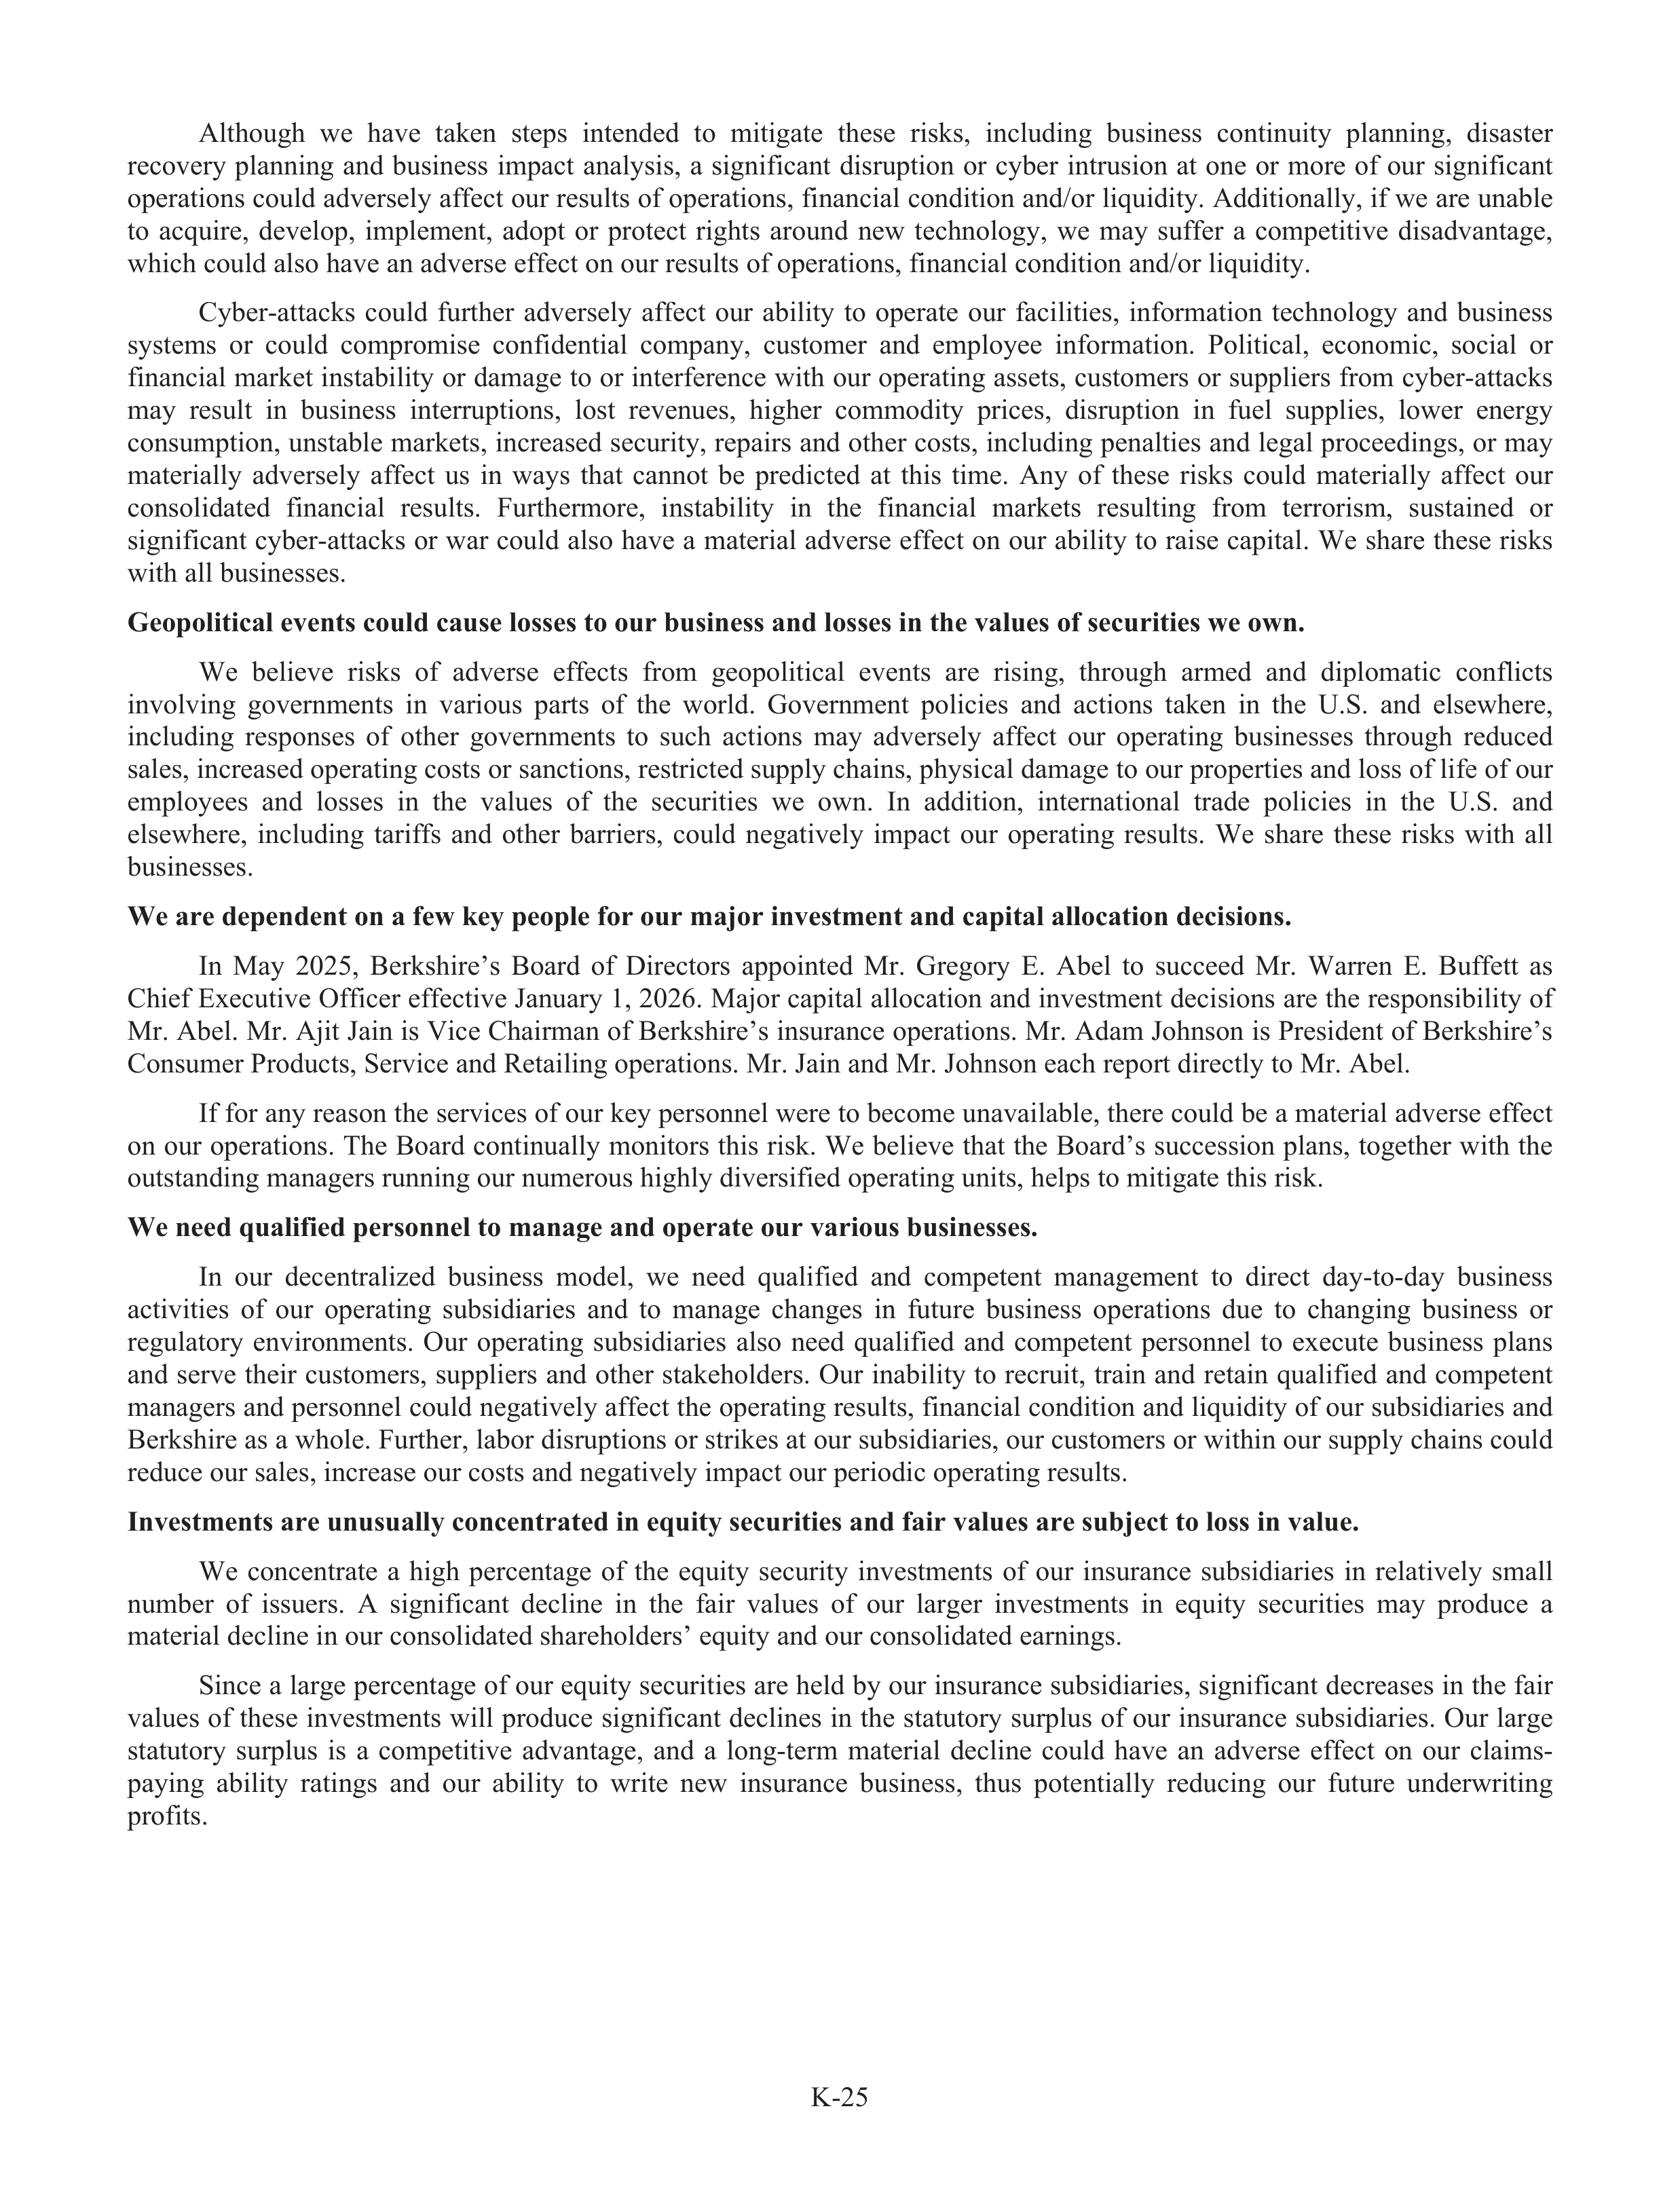
K-25
Although
we
have
taken
steps
intended
to
mitigate
these
risks,
including
business
continuity
planning,
disaster
recovery
planning
and
business
impact
analysis,
a
significant
disrupt
r
ion
or
cyber
intrus
r
ion
at
one
or
more
of
our
significant
operations could adversely affe
f
ct our results of operations, financial condition and/or liquidity. Additionally, if we are unabl
a
e
to
acquire,
develop,
implement,
adopt
or
protect
rights
around
new
technology,
we
may
suffer
a
competitive
disadvantage,
which could also have an adverse effe
f
ct on our results of operations, financial condition and/or liquidity.
Cyber-attacks
could
further
adversely
affe
f
ct
our
ability
to
operate
our
facilities,
information
technology
and
business
systems
or
could
compromise
confid
f
ential
company,
customer
and
employee
information.
Political,
economic,
social
or
financial market instability or damage to or interfer
f
ence with our operating assets, customers or suppl
u
iers from cyber-attacks
may
result
in
business
interrupt
u
ions,
lost
revenues,
higher
commodity
prices,
disrupt
r
ion
in
fuel
suppl
u
ies,
lower
energy
consumption, unstabl
a
e markets, increased security, repairs and other costs, including penalties and legal proceedings, or may
materially
adversely
affe
f
ct
us
in
ways
that
cannot
be
predicted
at
this
time.
Any
of
these
risks
could
materially
affe
f
ct
our
consolidated
financial
results.
Furthermore,
instability
in
the
financial
markets
resulting
from
terrorism,
sustained
or
significant cyber-attacks or war could also have a material adverse effe
f
ct on our ability to raise capital. We share these risks
with all businesses.
Geopolitical events could cause losses to our business and losses in the values of securities we own.
We
believe
risks
of
adverse
effe
f
cts
from
geopolitical
events
are
rising,
through
armed
and
diplomatic
conflic
f
ts
involving
governments
in
various
parts
of
the
world.
Government
policies
and
actions
taken
in
the
U.S.
and
elsewhere,
including
responses
of
other
governments
to
such
actions
may
adversely
affe
f
ct
our
operating
businesses
through
reduced
sales, increased operating costs or sanctions, restricted suppl
u
y chains, physical damage to our properties and loss of lifef
of our
employees
and
losses
in
the
values
of
the
securities
we
own.
In
addition,
international
trade
policies
in
the
U.S.
and
elsewhere,
including
tariffs
and
other
barriers,
could
negatively
impact
our
operating
results.
We
share
these
risks
with
all
businesses.
We are dependent on a few key people for our majo
a
r investment and capital allocation decisions.
In
May
2025,
Berkshire’s
Board
of
Directors
appointed
Mr.
Gregory
r
E.
Abel
to
succeed
Mr.
Warren
E.
Buffet
f
t
as
Chief Executive Offi
f
cer effe
f
ctive January 1, 2026. Majo
a
r capital allocation and investment decisions are the responsibility of
Mr. Abel. Mr. Ajit Jain is Vice Chairman of Berkshire’s insurance operations. Mr. Adam Johnson is President of Berkshire’s
Consumer Products, Service and Retailing operations. Mr. Jain and Mr. Johnson each report directly to Mr. Abel.
If for any reason the services of our key personnel were to become unavailabl
a
e, there could be a material adverse effe
f
ct
on our operations. The Board continually monitors this risk. We believe that the Board’s succession plans, together with the
outstanding managers running our numerous highly diversifie
f
d operating units, helps to mitigate this risk.
We need qualifie
f
d personnel to manage and operate our various businesses.
In
our
decentralized
business
model,
we
need
qualifie
f
d
and
competent
management
to
direct
day-to-day
business
activities
of
our
operating
subs
u
idiaries
and
to
manage
changes
in
future
business
operations
due
to
changing
business
or
regulatory
r
environments.
Our
operating
subs
u
idiaries
also
need
qualifie
f
d
and
competent
personnel
to
execute
business
plans
and
serve
their
customers,
suppl
u
iers
and
other
stakeholders.
Our
inability
to
recrui
r
t,
train
and
retain
qualifie
f
d
and
competent
managers and personnel could negatively affe
f
ct the operating results, financial condition and liquidity of our subs
u
idiaries and
Berkshire as a whole. Further, labor
a
disrupt
r
ions or strikes at our subs
u
idiaries, our customers or within our suppl
u
y chains could
reduce our sales, increase our costs and negatively impact our periodic operating results.
Investments are unusually concentrated in equity securities and fair values are subject to loss in value.
We
concentrate
a
high
percentage
of
the
equity
security
investments
of
our
insurance
subs
u
idiaries
in
relatively
small
number
of
issuers.
A
significant
decline
in
the
fair
values
of
our
larger
investments
in
equity
securities
may
produce
a
material decline in our consolidated shareholders’ equity and our consolidated earnings.
Since a large percentage of our equity securities are held by our insurance subs
u
idiaries, significant decreases in the fair
values of these investments will produce significant declines in the statut
t
ory
r
surplus of our insurance subs
u
idiaries. Our large
statut
t
ory
r
surplus
is
a
competitive
advantage,
and
a
long-term
material
decline
could
have
an
adverse
effe
f
ct
on
our
claims-
paying
ability
ratings
and
our
ability
to
write
new
insurance
business,
thus
potentially
reducing
our
future
underwriting
profits
f
.
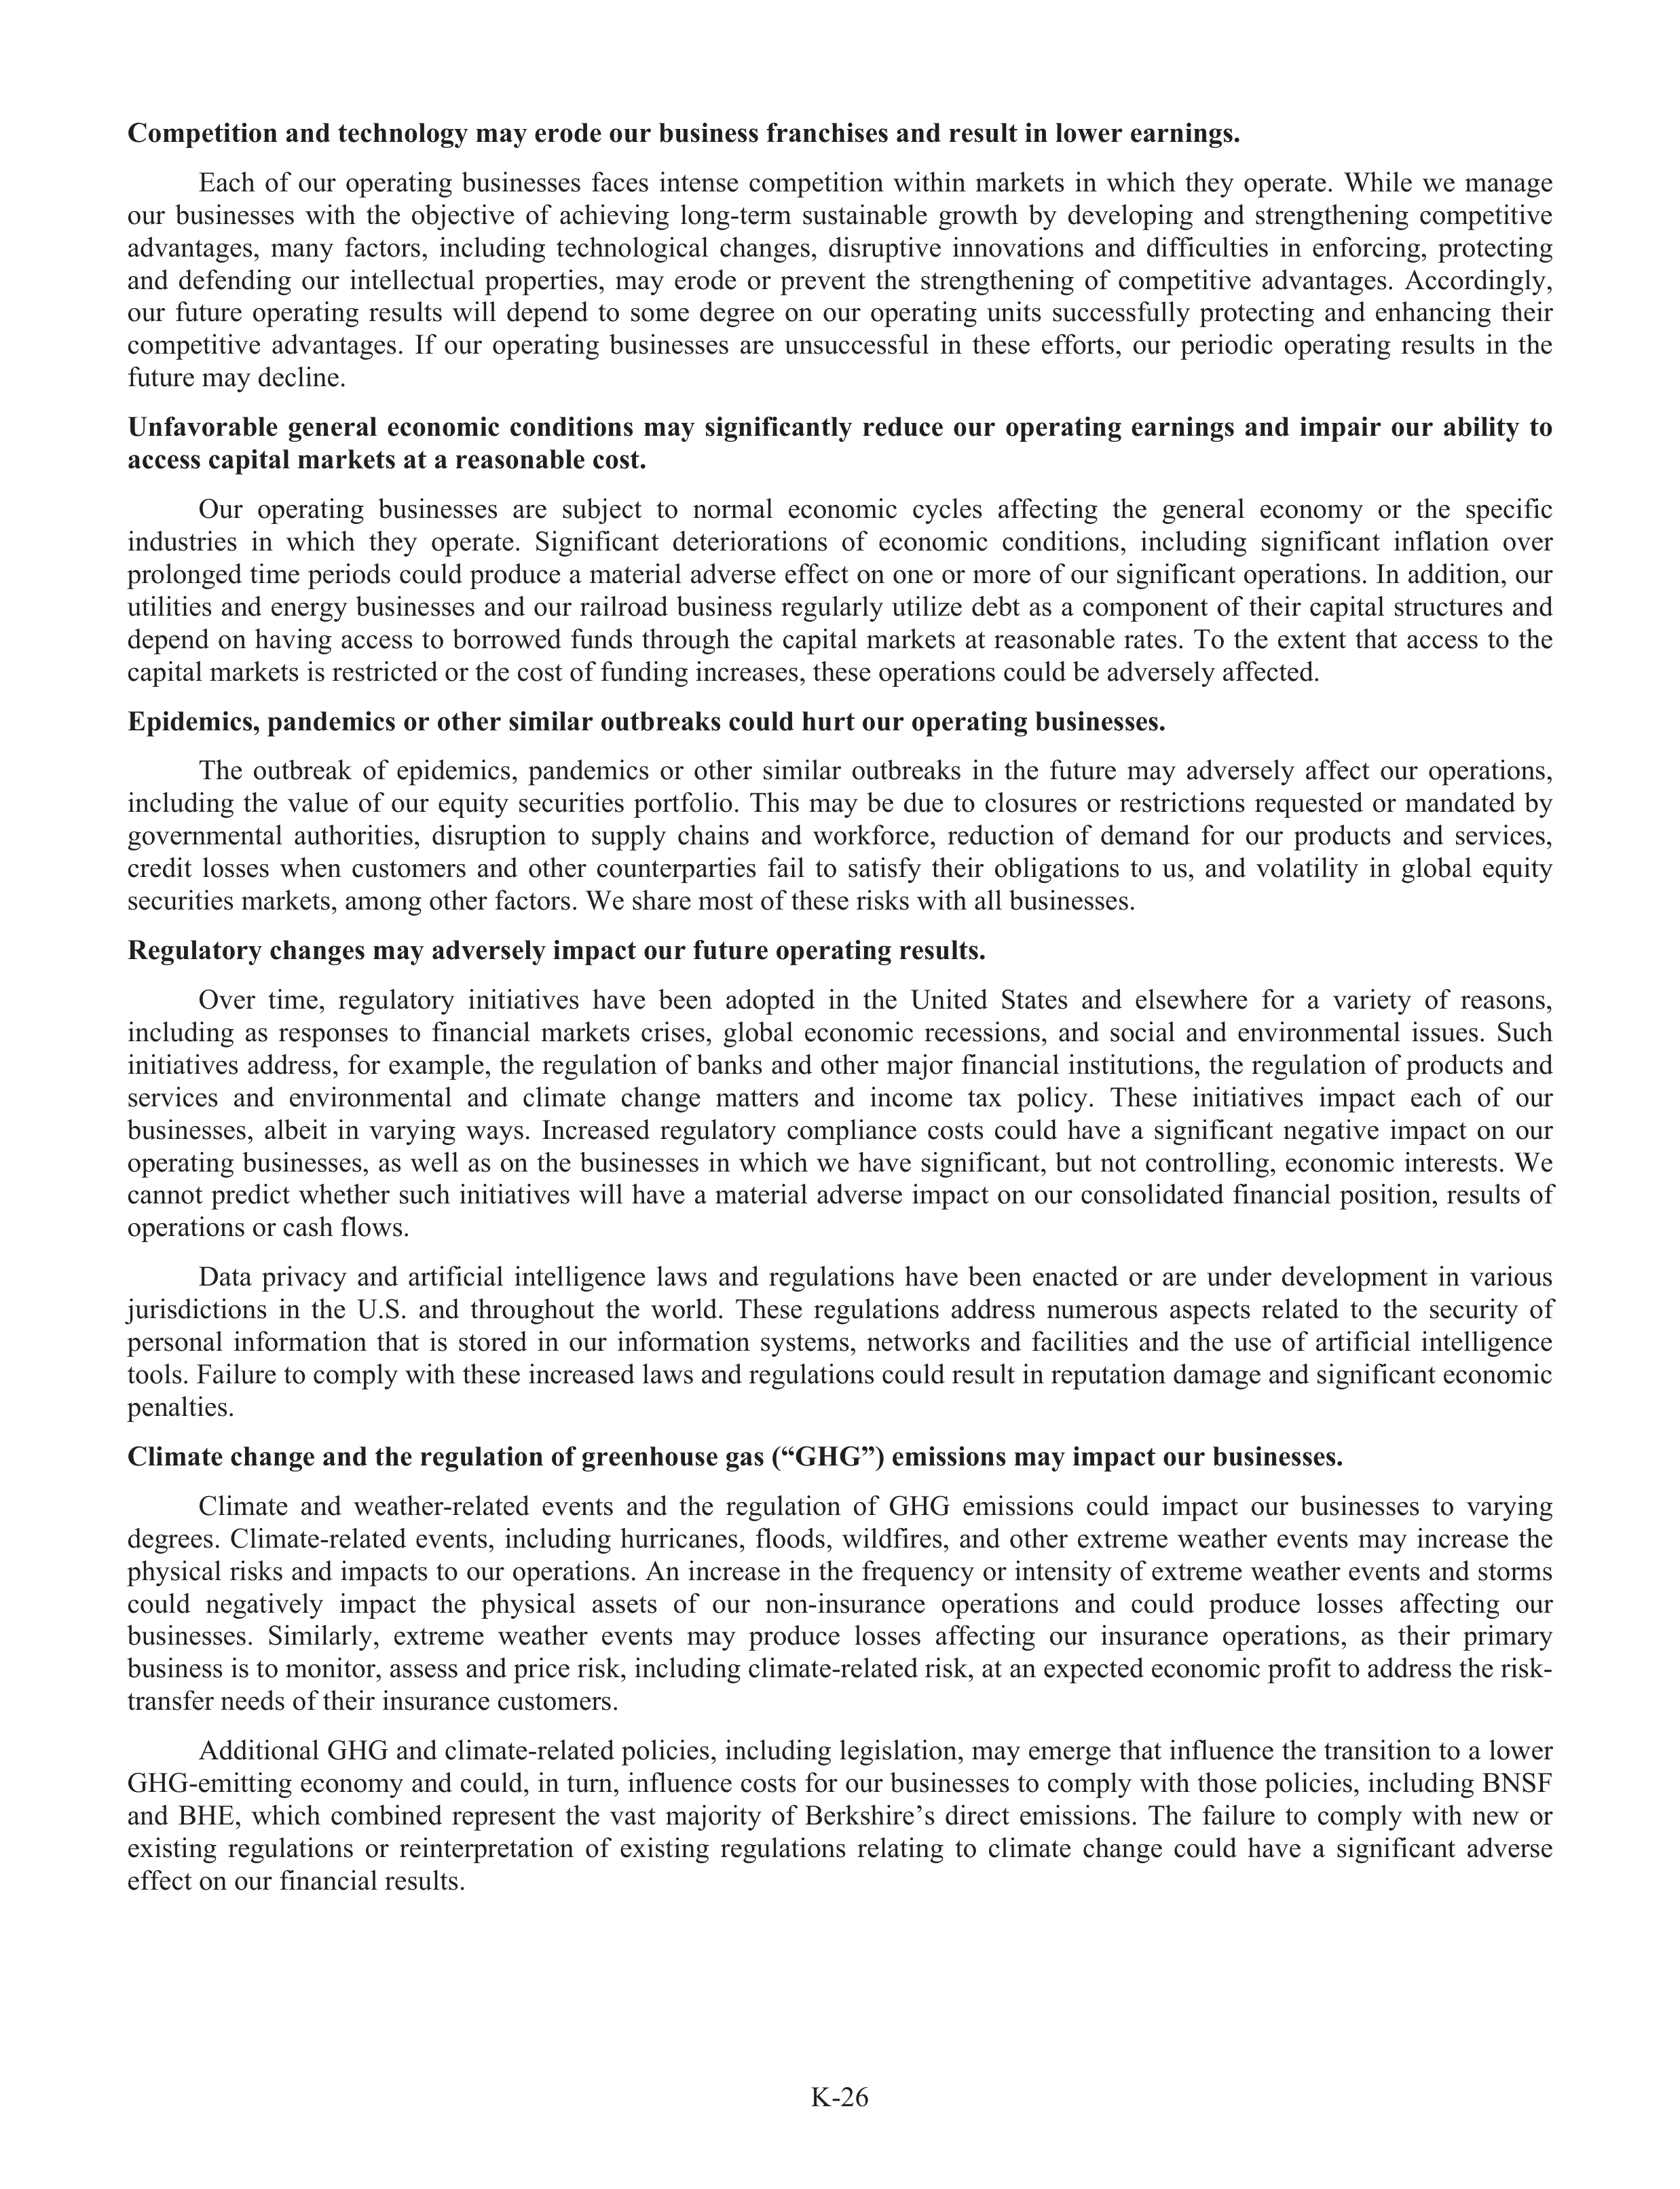
K-26
Competition and technology may erode our business franchises and result in lower earnings.
Each
of
our
operating
businesses
faces
intense
competition
within
markets
in
which
they
operate.
While
we
manage
our
businesses
with
the
objective
of
achieving
long-term
sustainabl
a
e
growth
by
developing
and
strengthening
competitive
advantages,
many
factors,
including
technological
changes,
disrupt
r
ive
innovations
and
difficulties
in
enforcing,
protecting
and
defending
our
intellectual
properties,
may
erode
or
prevent
the
strengthening
of
competitive
advantages.
Accordingly,
our
future
operating
results
will
depend
to
some
degree
on
our
operating
units
successful
f
ly
protecting
and
enhancing
their
competitive
advantages.
If
our
operating
businesses
are
unsuccessful
f
in
these
effo
f
rts,
our
periodic
operating
results
in
the
future may decline.
Unfavorable
general
economic
conditions
may
signific
f
antly
reduce
our
operating
earnings
and
impair
our
ability
to
access capital markets at a reasonable cost.
Our
operating
businesses
are
subj
u
ect
to
normal
economic
cycles
affe
f
cting
the
general
economy
or
the
specific
industries
in
which
they
operate.
Significant
deteriorations
of
economic
conditions,
including
significant
inflation
over
prolonged time periods could produce a material adverse effe
f
ct on one or more of our significant operations. In addition, our
utilities
and
energy
businesses
and
our
railroad
business
regularly
utilize
debt
as
a
component
of
their
capital
structures
and
depend
on
having
access
to
borrowed
funds
through
the
capital
markets
at
reasonabl
a
e
rates.
To
the
extent
that
access
to
the
capital markets is restricted or the cost of funding increases, these operations could be adversely affe
f
cted.
Epidemics, pandemics or other similar outbreaks could hurt our operating businesses.
The
outbr
t
eak
of
epidemics,
pandemics
or
other
similar
outbr
t
eaks
in
the
future
may
adversely
affe
f
ct
our
operations,
including
the
value
of
our
equity
securities
portfol
f
io.
This
may
be
due
to
closures
or
restrictions
requested
or
mandated
by
governmental
authorities,
disrupt
r
ion
to
suppl
u
y
chains
and
workforce,
reduction
of
demand
for
our
products
and
services,
credit
losses
when
customers
and
other
counterpa
r
rties
fail
to
satisfy
their
obligations
to
us,
and
volatility
in
global
equity
securities markets, among other factors. We share most of these risks with all businesses.
Regulatory changes may adversely impact our future operating results.
Over
time,
regulatory
r
initiatives
have
been
adopted
in
the
United
States
and
elsewhere
for
a
variety
of
reasons,
including
as
responses
to
financial
markets
crises,
global
economic
recessions,
and
social
and
environmental
issues.
Such
initiatives address, for example, the regulation of banks and other majo
a
r financial institutions, the regulation of produc
d
ts and
services
and
environmental
and
climate
change
matters
and
income
tax
policy.
These
initiatives
impact
each
of
our
businesses,
albeit
in
varying
ways.
Increased
regulatory
r
compliance
costs
could
have
a
significant
negative
impact
on
our
operating
businesses,
as
well
as
on
the
businesses
in
which
we
have
significant,
but
not
controlling,
economic
interests.
We
cannot
predict
whether
such
initiatives
will
have
a
material
adverse
impact
on
our
consolidated
financial
position,
results
of
operations or cash flows.
Data
privacy
and
artific
f
ial
intelligence
laws
and
regulations
have
been
enacted
or
are
under
development
in
various
jurisdictions
in
the
U.S.
and
throughout
the
world.
These
regulations
address
numerous
aspects
related
to
the
security
of
personal
information
that
is
stored
in
our
information
systems,
networks
and
facilities
and
the
use
of
artific
f
ial
intelligence
tools. Failure to comply with these increased laws and regulations could result in reputation damage and significant economic
penalties.
Climate change and the regulation of greenhouse gas (“GHG”) emissions may impact our businesses.
Climate
and
weather-related
events
and
the
regulation
of
GHG
emissions
could
impact
our
businesses
to
varying
degrees.
Climate-related
events,
including
hurricanes,
floods,
wildfires,
and
other
extreme
weather
events
may
increase
the
physical risks and impacts to our operations. An increase in the frequency or intensity of extreme weather events and storms
could
negatively
impact
the
physical
assets
of
our
non-insurance
operations
and
could
produce
losses
affe
f
cting
our
businesses.
Similarly,
extreme
weather
events
may
produc
d
e
losses
affe
f
cting
our
insurance
operations,
as
their
primary
business is to monitor, assess and price risk, including climate-related risk, at an expected economic profit
f
to address the risk-
transfer
f
needs of their insurance customers.
Additional GHG and climate-related policies, including legislation, may emerge that influence the transition to a lower
GHG-emitting economy and could, in turn, influence costs for our businesses to comply with those policies, including BNSF
and
BHE,
which
combined
represent
the
vast
majo
a
rity
of
Berkshire’s
direct
emissions.
The
failure
to
comply
with
new
or
existing
regulations
or
reinterpretation
of
existing
regulations
relating
to
climate
change
could
have
a
significant
adverse
effe
f
ct on our financial results.
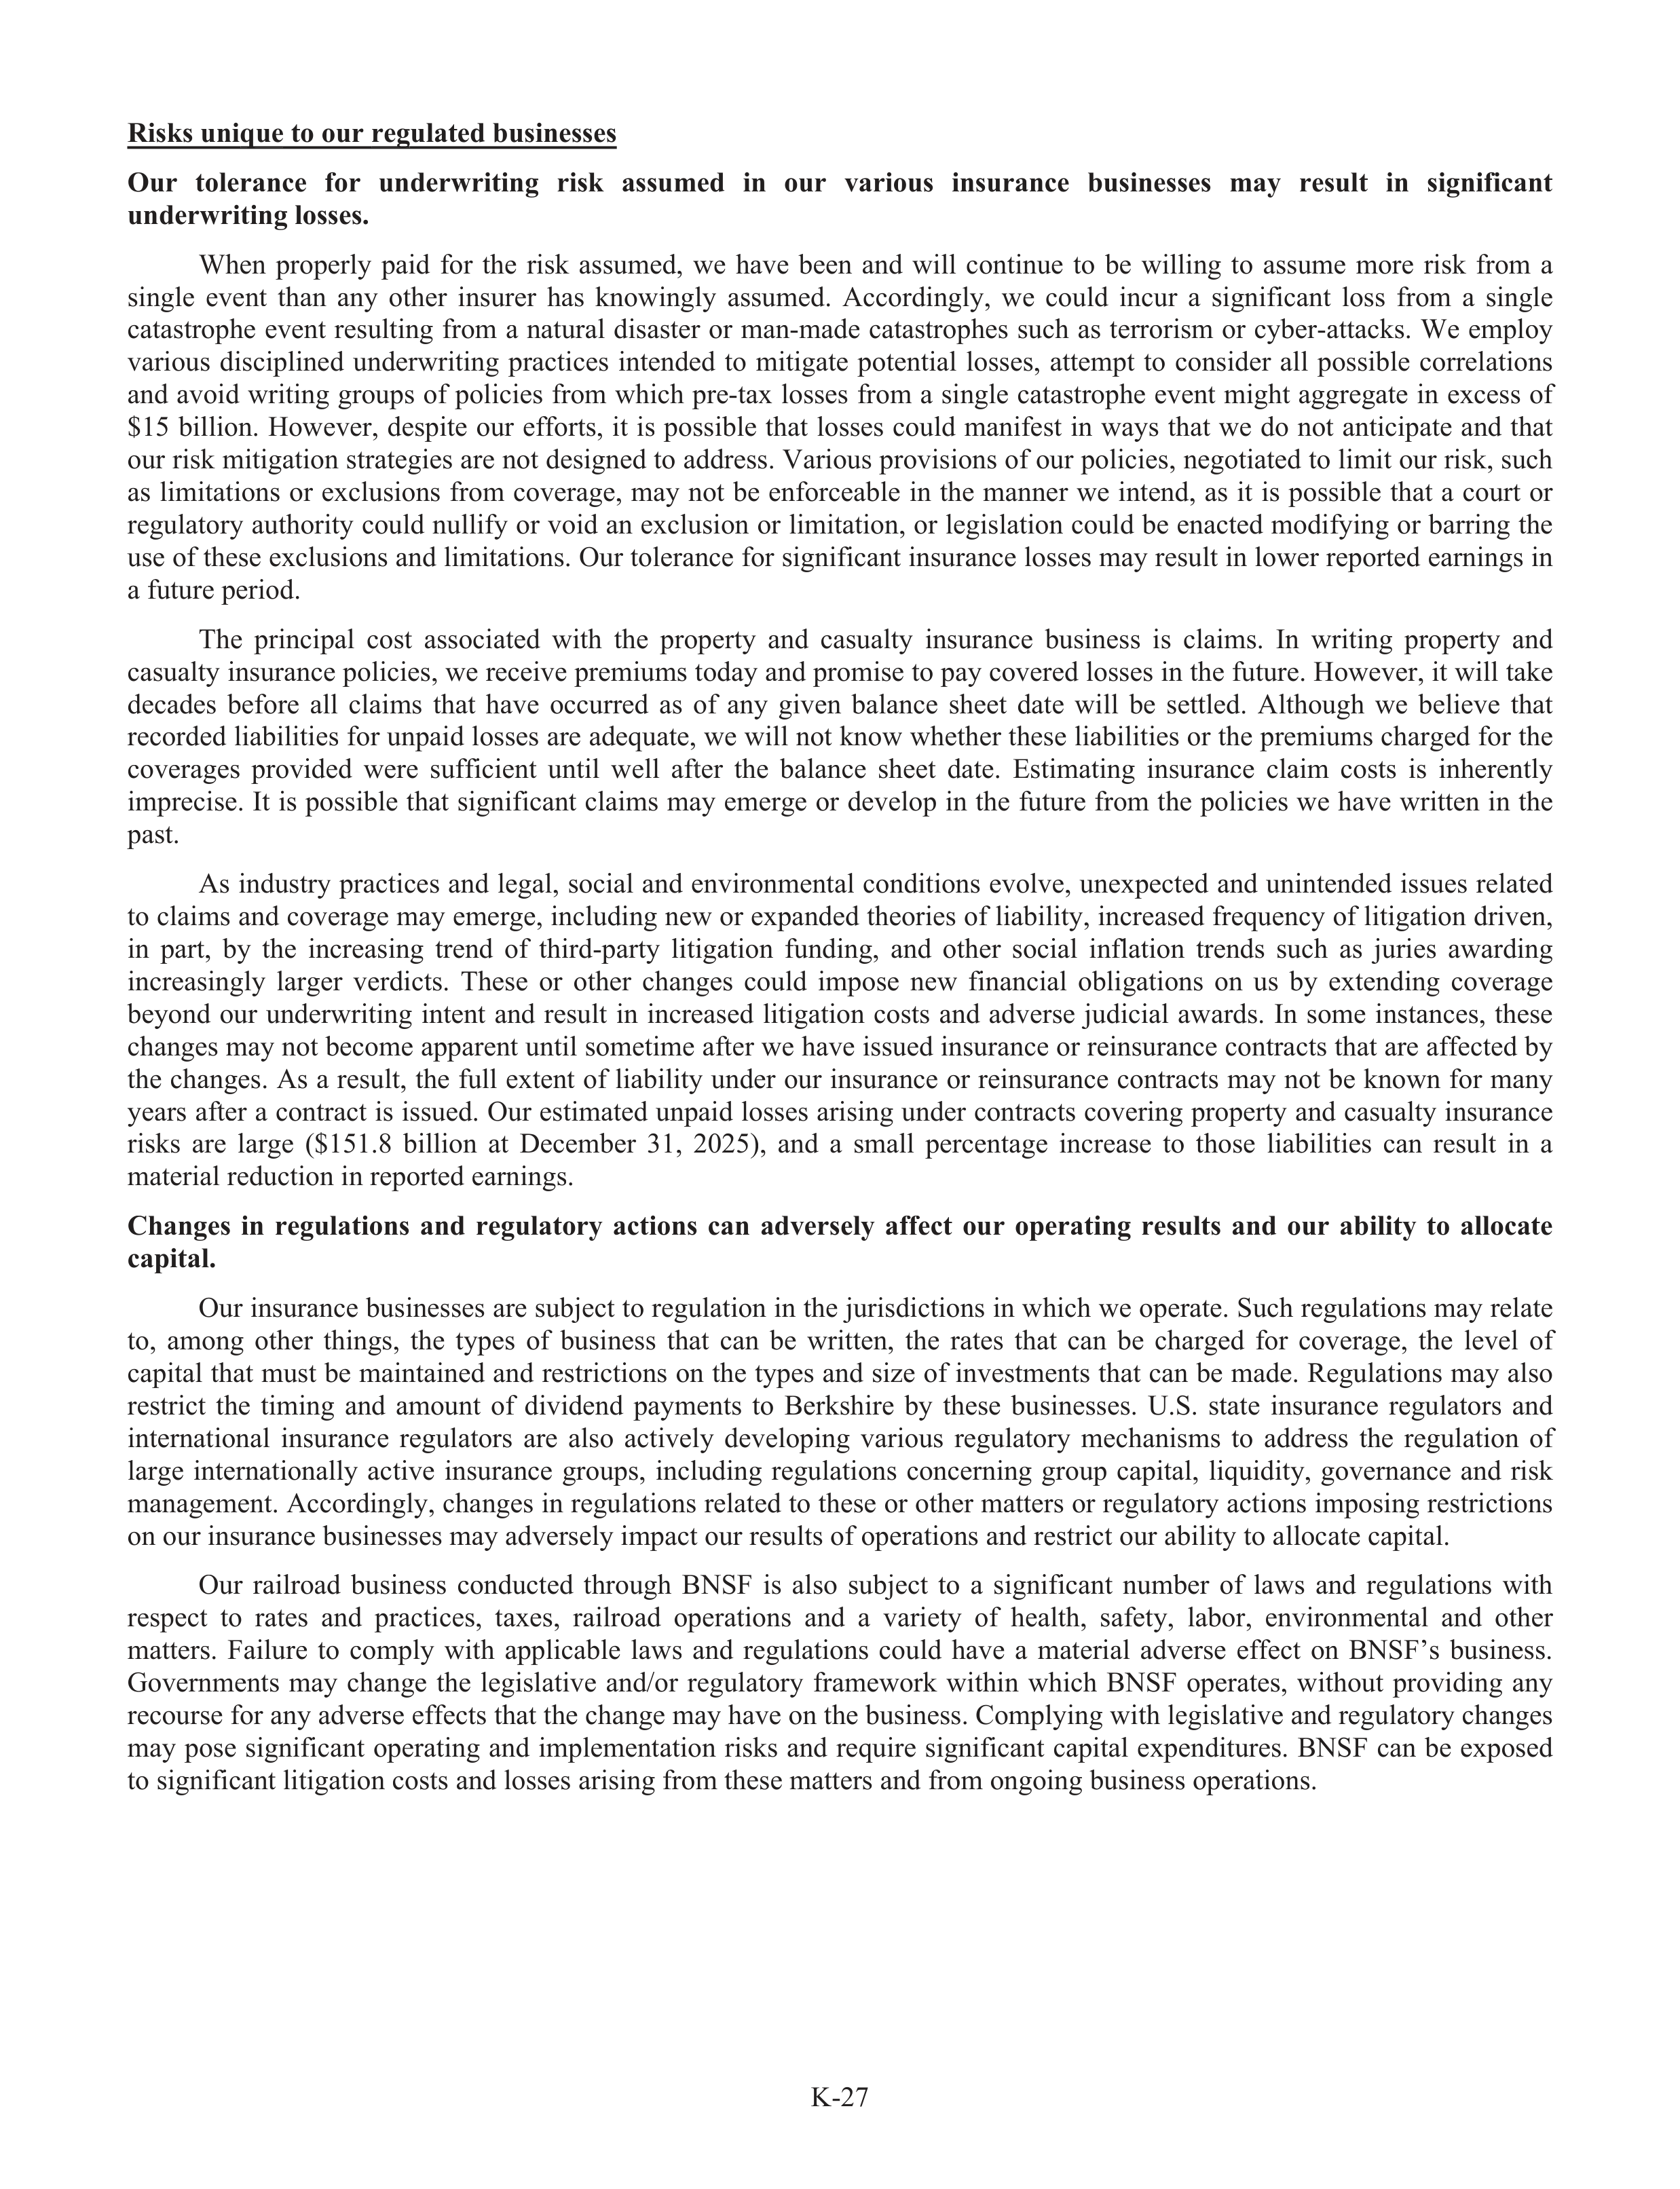
K-27
Risks unique to our regulated businesses
Our
tolerance
for
underwriting
risk
assumed
in
our
various
insurance
businesses
may
result
in
signific
f
ant
underwriting losses.
When
properly
paid
for
the
risk
assumed,
we
have
been
and
will
continue
to
be
willing
to
assume
more
risk
from
a
single
event
than
any
other
insurer
has
knowingly
assumed.
Accordingly,
we
could
incur
a
significant
loss
from
a
single
catastrophe
event
resulting
from
a
natural
disaster
or
man-made
catastrophes
such
as
terrorism
or
cyber-attacks.
We
employ
various
disciplined
underwriting
practices
intended
to
mitigate
potential
losses,
attempt
to
consider
all
possible
correlations
and avoid writing groups of policies from which pre-tax losses from a single catastrophe event might aggregate in excess of
$15
billion.
However,
despite
our
effo
f
rts,
it
is
possible
that
losses
could
manifest
in
ways
that
we
do
not
anticipate
and
that
our risk mitigation strategies are not designed to address. Various provisions of our policies, negotiated to limit our risk, such
as
limitations
or
exclusions
from
coverage,
may
not
be
enforceable
in
the
manner
we
intend,
as
it
is
possible
that
a
court
or
regulatory
r
authority could nullify
f
or void an exclusion or limitation, or legislation could be enacted modifying or barring the
use of these exclusions and limitations. Our tolerance for significant insurance losses may result in lower reported earnings in
a future period.
The
principal
cost
associated
with
the
property
and
casualty
insurance
business
is
claims.
In
writing
property
and
casualty insurance policies, we receive premiums today and promise to pay covered losses in the future. However, it will take
decades
before
all
claims
that
have
occurred
as
of
any
given
balance
sheet
date
will
be
settled.
Although
we
believe
that
recorded liabi
a
lities for unpaid losses are adequate, we will not know whether these liabi
a
lities or the premiums charged for the
coverages
provided
were
sufficient
until
well
afte
f
r
the
balance
sheet
date.
Estimating
insurance
claim
costs
is
inherently
imprecise. It is possible that signific
f
ant claims may emerge or develop in the future from the policies we have written in the
past.
As industry
r
practices and legal, social and environmental conditions evolve, unexpected and unintended issues related
to claims and coverage may emerge, including new or expanded theories of liabi
a
lity, increased frequency of litigation driven,
in
part,
by
the
increasing
trend
of
third-party
litigation
funding,
and
other
social
inflation
trends
such
as
juries
awarding
increasingly
larger
verdicts.
These
or
other
changes
could
impose
new
financial
obligations
on
us
by
extending
coverage
beyond
our
underwriting
intent
and
result
in
increased
litigation
costs
and
adverse
judicial
awards.
In
some
instances,
these
changes may not become apparent until sometime afte
f
r we have issued insurance or reinsurance contracts that are affe
f
cted by
the changes. As a result, the full extent of liabi
a
lity under our insurance or reinsurance contracts may not be known for many
years afte
f
r a contract is issued. Our estimated unpaid losses arising under contracts covering property and casualty insurance
risks
are
large
($151.8
billion
at
December
31,
2025),
and
a
small
percentage
increase
to
those
liabi
a
lities
can
result
in
a
material reduction in reported earnings.
Changes
in
regulations
and
regulatory
actions
can
adversely
affe
f
ct
our
operating
results
and
our
ability
to
allocate
capital.
Our insurance businesses are subj
u
ect to regulation in the jurisdictions in which we operate. Such regulations may relate
to,
among
other
things,
the
types
of
business
that
can
be
written,
the
rates
that
can
be
charged
for
coverage,
the
level
of
capital that must be maintained and restrictions on the types and size of investments that can be made. Regulations may also
restrict
the
timing
and
amount
of
dividend
payments
to
Berkshire
by
these
businesses.
U.S.
state
insurance
regulators
and
international
insurance
regulators
are
also
actively
developing
various
regulatory
r
mechanisms
to
address
the
regulation
of
large
internationally
active
insurance
groups,
including
regulations
concerning
group
capital,
liquidity,
governance
and
risk
management. Accordingly, changes in regulations related to these or other matters or regulatory
r
actions imposing restrictions
on our insurance businesses may adversely impact our results of operations and restrict our ability to allocate capital.
Our
railroad
business
conducted
through
BNSF
is
also
subj
u
ect
to
a
significant
number
of
laws
and
regulations
with
respect
to
rates
and
practices,
taxes,
railroad
operations
and
a
variety
of
health,
safety,
labor
a
,
environmental
and
other
matters.
Failure
to
comply
with
applicable
laws
and
regulations
could
have
a
material
adverse
effe
f
ct
on
BNSF’s
business.
Governments
may
change
the
legislative
and/or
regulatory
r
framework
within
which
BNSF
operates,
without
providing
any
recourse for any adverse effe
f
cts that the change may have on the business. Complying with legislative and regulatory
r
changes
may
pose
significant
operating
and
implementation
risks
and
require
significant
capital
expenditures.
BNSF
can
be
exposed
to significant litigation costs and losses arising from these matters and from ongoing business operations.
q
g
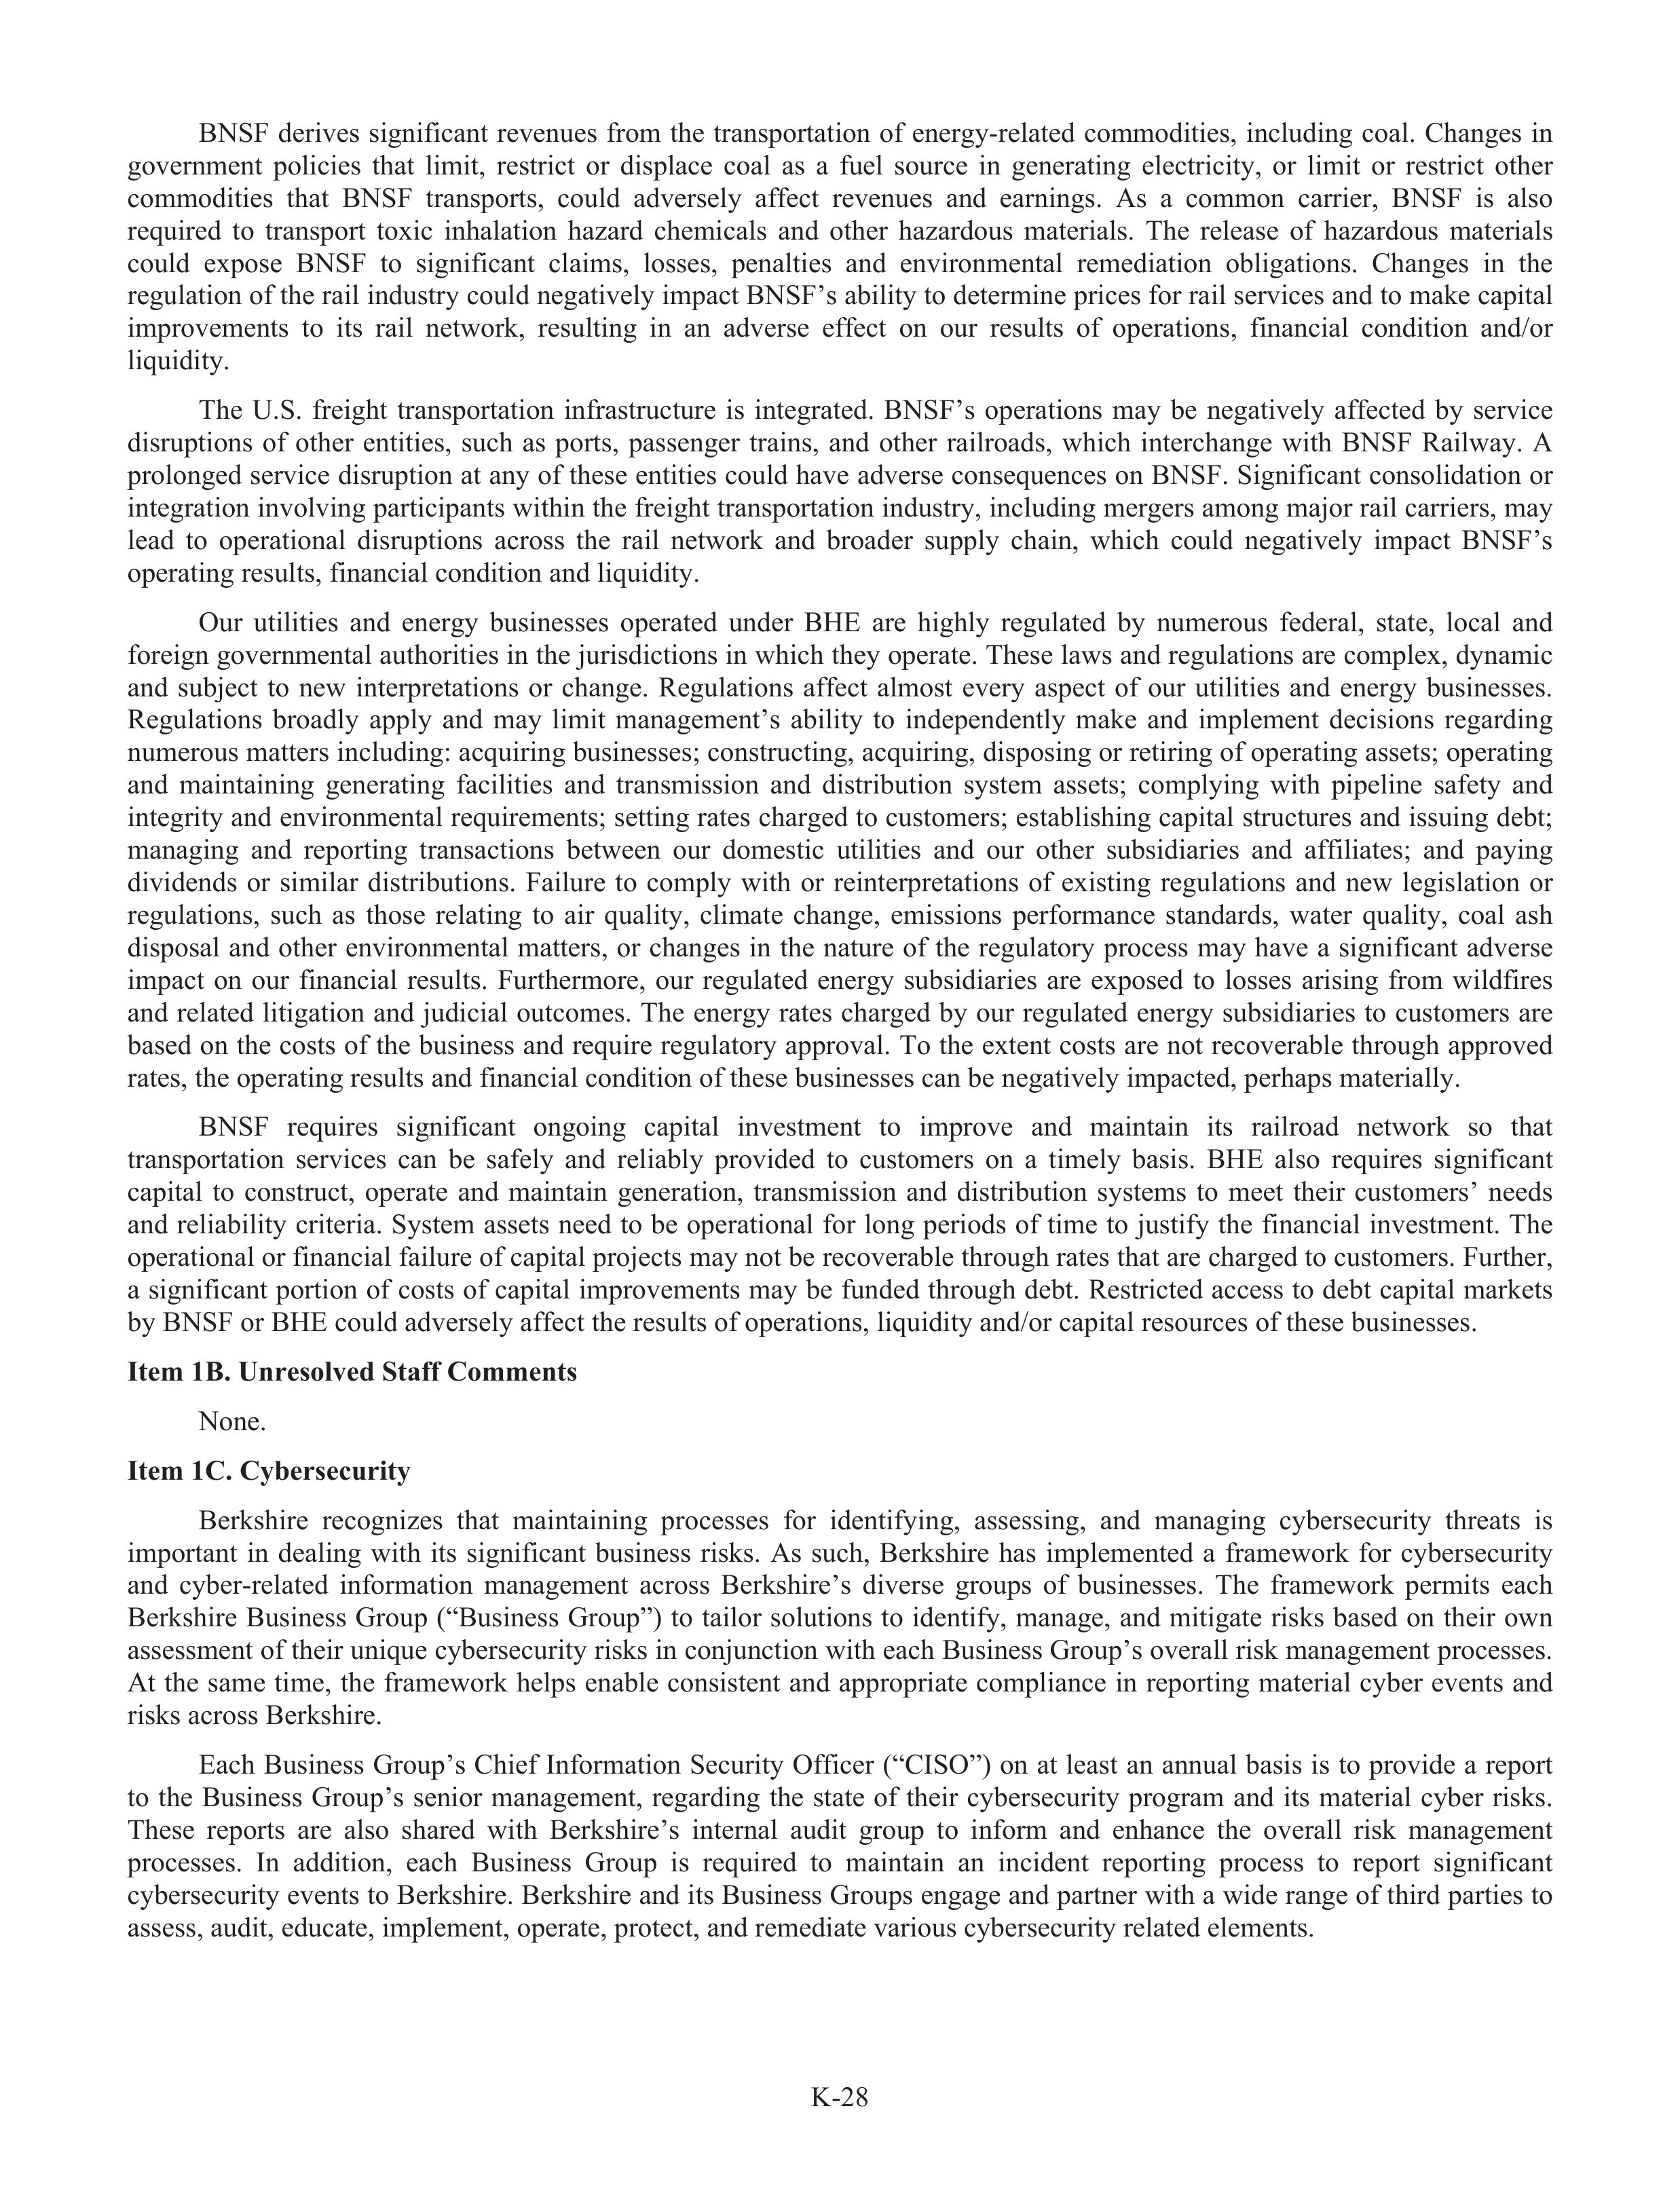
K-28
BNSF
derives
significant
revenues
from
the
transportation
of
energy-related
commodities,
including
coal.
Changes
in
government
policies
that
limit,
restrict
or
displace
coal
as
a
fuel
source
in
generating
electricity,
or
limit
or
restrict
other
commodities
that
BNSF
transports,
could
adversely
affe
f
ct
revenues
and
earnings.
As
a
common
carrier,
BNSF
is
also
required
to
transport
toxic
inhalation
hazard
chemicals
and
other
hazardous
materials.
The
release
of
hazardous
materials
could
expose
BNSF
to
significant
claims,
losses,
penalties
and
environmental
remediation
obligations.
Changes
in
the
regulation of the rail industry
r
could negatively impact BNSF’s abi
a
lity to determine prices for rail services and to make capital
improvements
to
its
rail
network,
resulting
in
an
adverse
effe
f
ct
on
our
results
of
operations,
financial
condition
and/or
liquidity.
The
U.S.
freight
transportation
infrastructur
t
e
is
integrated.
BNSF’s
operations
may
be
negatively
affe
f
cted
by
service
disrupt
r
ions
of
other
entities,
such
as
ports,
passenger
trains,
and
other
railroads,
which
interchange
with
BNSF
Railway.
A
prolonged service disrupt
r
ion at any of these entities could have adverse consequences on BNSF. Significant consolidation or
integration involving participants within the freight transportation industry,
r
including mergers among majo
a
r rail carriers, may
lead
to
operational
disrupt
r
ions
across
the
rail
network
and
broader
suppl
u
y
chain,
which
could
negatively
impact
BNSF’s
operating results, financial condition and liquidity.
Our
utilities
and
energy
businesses
operated
under
BHE
are
highly
regulated
by
numerous
federal,
state,
local
and
foreign governmental authorities in the jurisdictions in which they operate. These laws and regulations are complex, dynamic
and
subj
u
ect
to
new
interpretations
or
change.
Regulations
affe
f
ct
almost
every
r
aspect
of
our
utilities
and
energy
businesses.
Regulations
broadly
apply
and
may
limit
management’s
ability
to
independently
make
and
implement
decisions
regarding
numerous matters including: acquiring businesses; construc
r
ting, acquiring, disposing or retiring of operating assets; operating
and
maintaining
generating
facilities
and
transmission
and
distribution
system
assets;
complying
with
pipeline
safety
and
integrity and environmental requirements; setting rates charged to customers; establ
a
ishing capital structur
t
es and issuing debt;
managing
and
reporting
transactions
between
our
domestic
utilities
and
our
other
subs
u
idiaries
and
affi
f
liates;
and
paying
dividends
or
similar
distributions.
Failure
to
comply
with
or
reinterpretations
of
existing
regulations
and
new
legislation
or
regulations,
such
as
those
relating
to
air
quality,
climate
change,
emissions
performance
standards,
water
quality,
coal
ash
disposal
and
other
environmental
matters,
or
changes
in
the
nature
of
the
regulatory
r
process
may
have
a
significant
adverse
impact
on
our
financial
results.
Furthermore,
our
regulated
energy
subs
u
idiaries
are
exposed
to
losses
arising
from
wildfires
and
related
litigation
and
judicial
outcomes.
The
energy
rates
charged
by
our
regulated
energy
subs
u
idiaries
to
customers
are
based on the costs of the business and require regulatory approval. To the extent costs are not recoverabl
a
e through approved
rates, the operating results and financial condition of these businesses can be negatively impacted, perhaps materially.
BNSF
requires
significant
ongoing
capital
investment
to
improve
and
maintain
its
railroad
network
so
that
transportation
services
can
be
safely
and
reliabl
a
y
provided
to
customers
on
a
timely
basis.
BHE
also
requires
significant
capital
to
construc
r
t,
operate
and
maintain
generation,
transmission
and
distribution
systems
to
meet
their
customers’
needs
and
reliabi
a
lity
criteria.
System
assets
need
to
be
operational
for
long
periods
of
time
to
justify
f
the
financial
investment.
The
operational or financial failure of capital projects may not be recoverabl
a
e through rates that are charged to customers. Further,
a significant portion of costs of capital improvements may be funded through debt. Restricted access to debt capital markets
by BNSF or BHE could adversely affe
f
ct the results of operations, liquidity and/or capital resources of these businesses.
Item 1B. Unresolved Stafff
Comments
None.
Item 1C. Cybersecurity
Berkshire
recognizes
that
maintaining
processes
for
identifyi
f
ng,
assessing,
and
managing
cybersecurity
threats
is
important
in
dealing
with
its
significant
business
risks.
As
such,
Berkshire
has
implemented
a
framework
for
cybersecurity
and
cyber-related
information
management
across
Berkshire’s
diverse
groups
of
businesses.
The
framework
permits
each
Berkshire
Business
Group
(“Business
Group”)
to
tailor
solutions
to
identify,
f
manage,
and
mitigate
risks
based
on
their
own
assessment of their unique cybersecurity risks in conjunction with each Business Group’s overall risk management processes.
At
the
same
time,
the
framework
helps
enable
consistent
and
appropriate
compliance
in
reporting
material
cyber
events
and
risks across Berkshire.
Each
Business
Group’s
Chief
Information
Security
Offi
f
cer
(“CISO”)
on
at
least
an
annual
basis
is
to
provide
a
report
to
the
Business
Group’s
senior
management,
regarding
the
state
of
their
cybersecurity
program
and
its
material
cyber
risks.
These
reports
are
also
shared
with
Berkshire’s
internal
audit
group
to
inform
and
enhance
the
overall
risk
management
processes.
In
addition,
each
Business
Group
is
required
to
maintain
an
incident
reporting
process
to
report
significant
cybersecurity events to Berkshire. Berkshire and its Business Groups engage and partner with a wide range of third parties to
assess, audit, educ
d
ate, implement, operate, protect, and remediate various cybersecurity related elements.
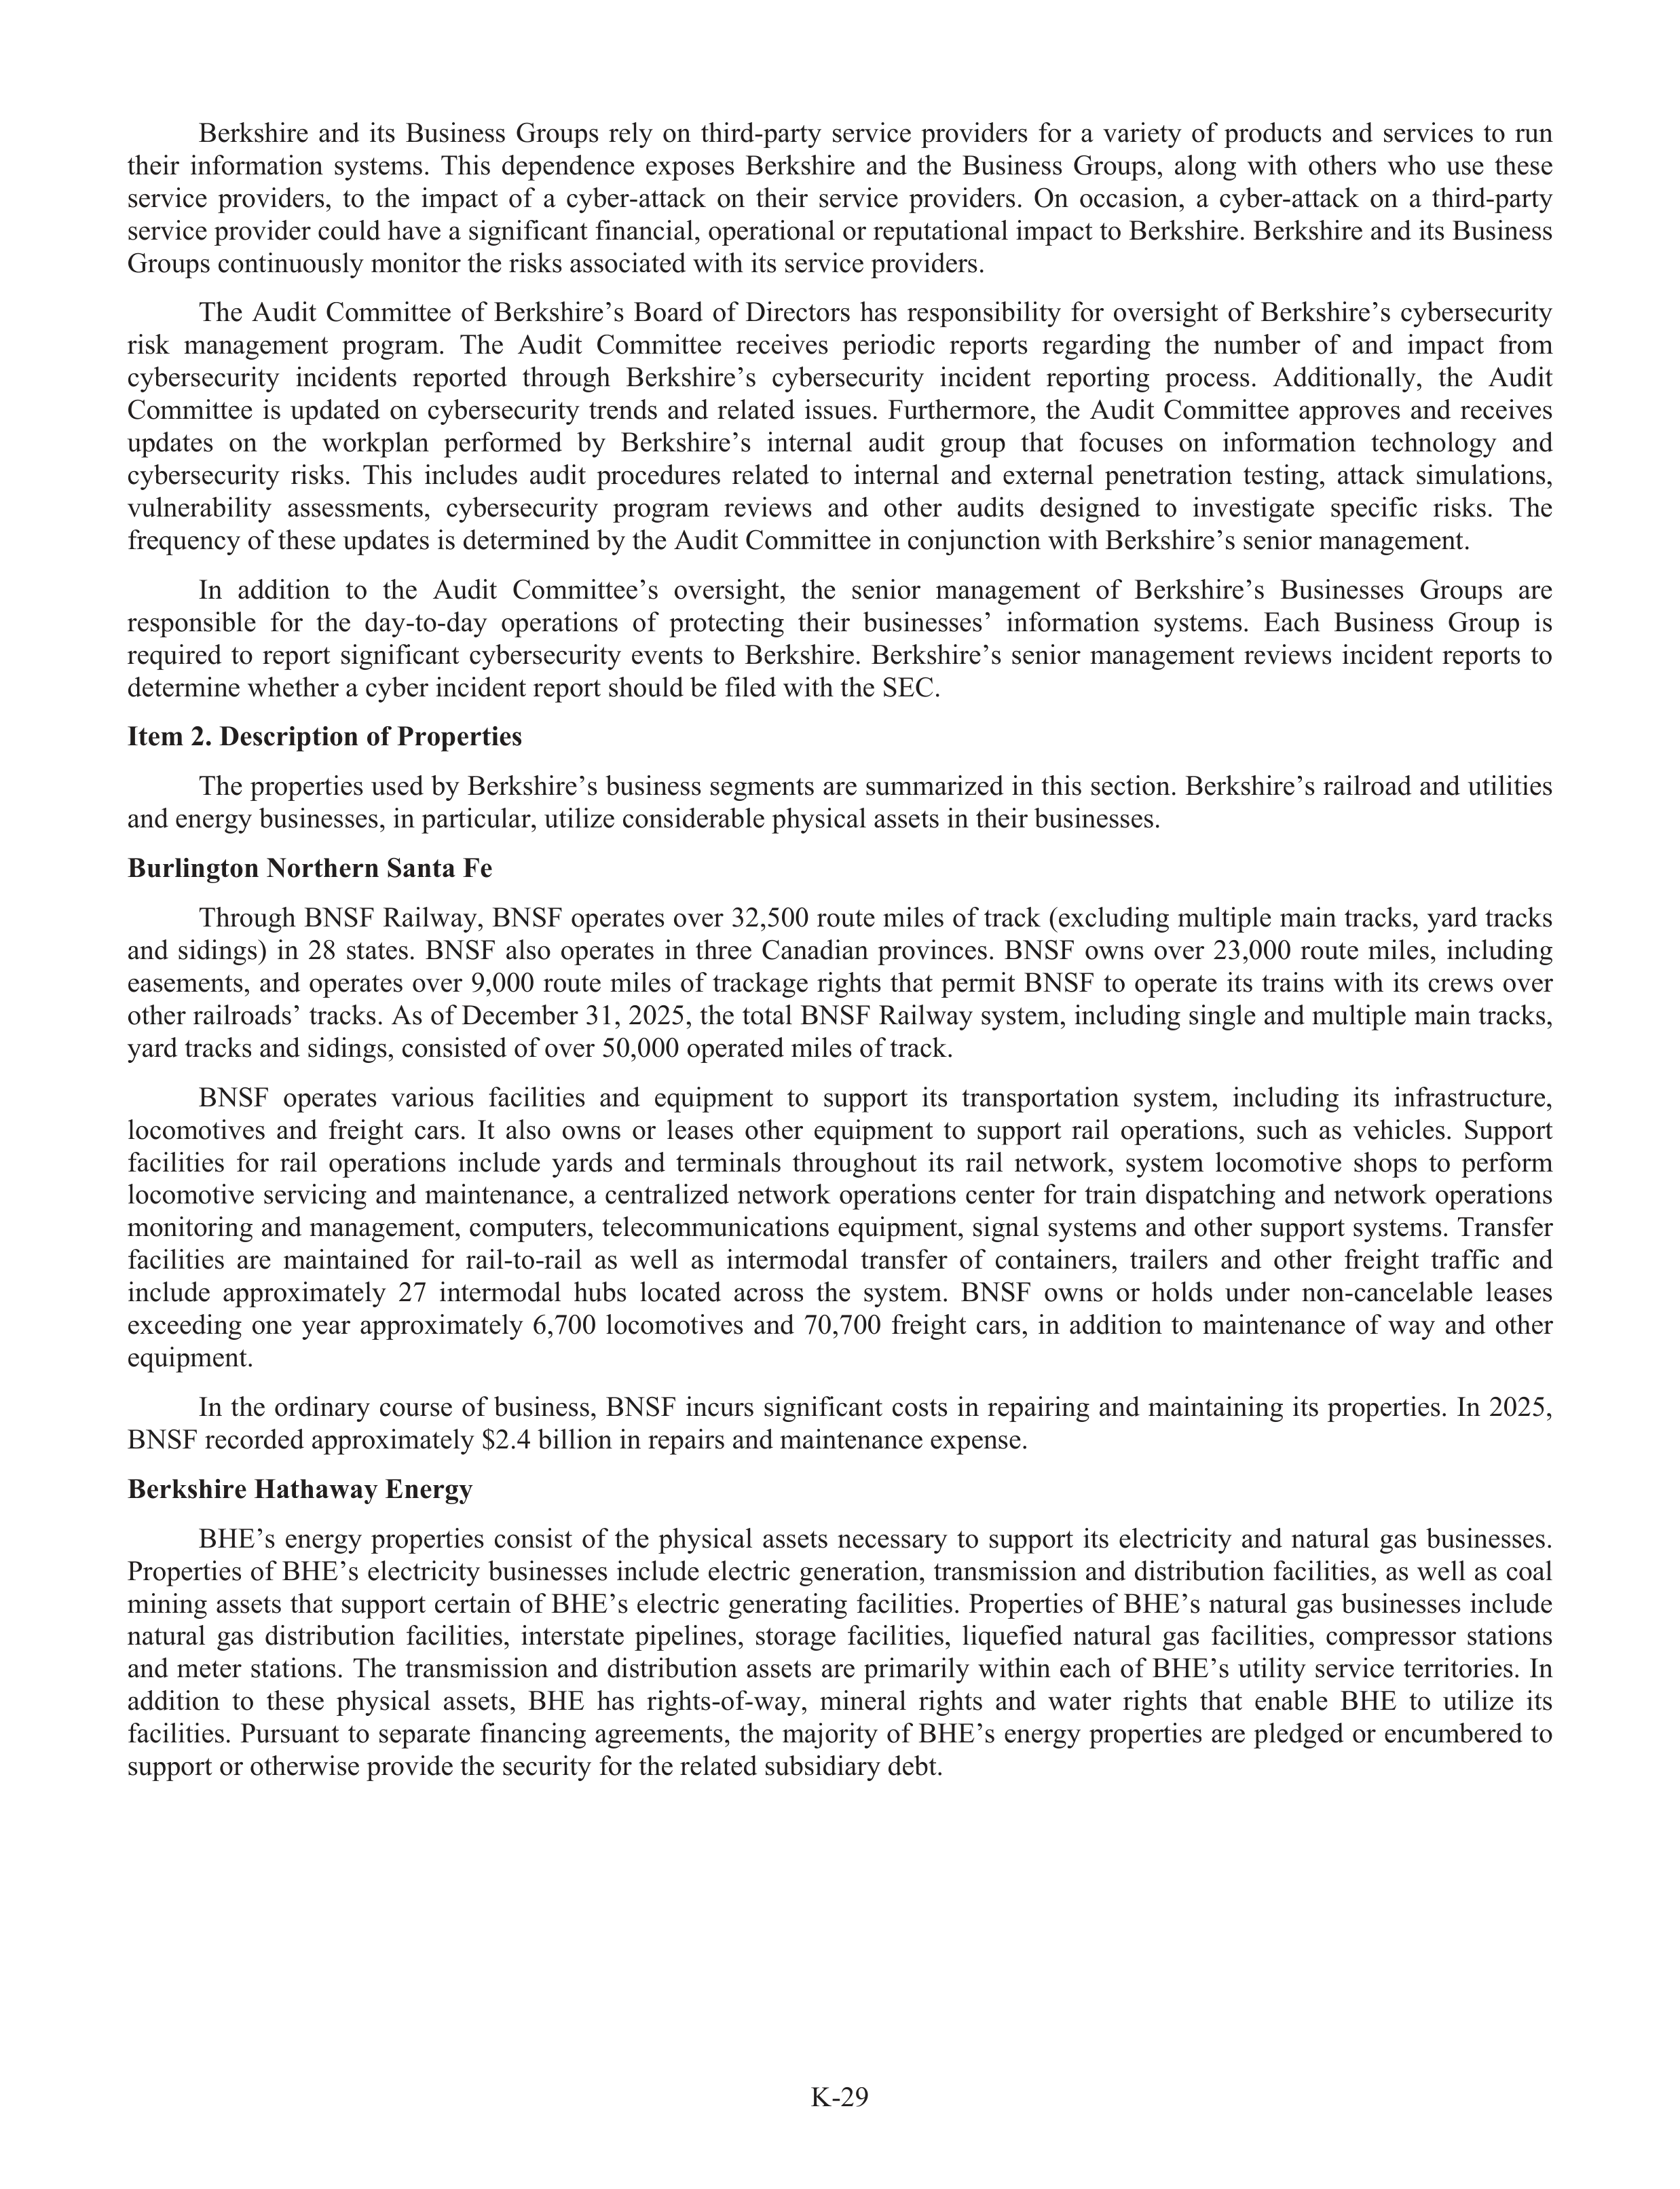
K-29
Berkshire
and
its
Business
Groups
rely
on
third-party
service
providers
for
a
variety
of
products
and
services
to
run
their
information
systems.
This
dependence
exposes
Berkshire
and
the
Business
Groups,
along
with
others
who
use
these
service
providers,
to
the
impact
of
a
cyber-attack
on
their
service
providers.
On
occasion,
a
cyber-attack
on
a
third-party
service provider could have a significant financial, operational or reputational impact to Berkshire. Berkshire and its Business
Groups continuously monitor the risks associated with its service providers.
The
Audit
Committee
of
Berkshire’s
Board
of
Directors
has
responsibility
for
oversight
of
Berkshire’s
cybersecurity
risk
management
program.
The
Audit
Committee
receives
periodic
reports
regarding
the
number
of
and
impact
from
cybersecurity
incidents
reported
through
Berkshire’s
cybersecurity
incident
reporting
process.
Additionally,
the
Audit
Committee
is
updated
on
cybersecurity
trends
and
related
issues.
Furthermore,
the
Audit
Committee
approves
and
receives
updates
on
the
workpl
k
an
performed
by
Berkshire’s
internal
audit
group
that
focuses
on
information
technology
and
cybersecurity
risks.
This
includes
audit
procedur
d
es
related
to
internal
and
external
penetration
testing,
attack
simulations,
vulnerabi
a
lity
assessments,
cybersecurity
program
reviews
and
other
audits
designed
to
investigate
specific
risks.
The
frequency of these updates is determined by the Audit Committee in conjunction with Berkshire’s senior management.
In
addition
to
the
Audit
Committee’s
oversight,
the
senior
management
of
Berkshire’s
Businesses
Groups
are
responsible
for
the
day-to-day
operations
of
protecting
their
businesses’
information
systems.
Each
Business
Group
is
required
to
report
significant
cybersecurity
events
to
Berkshire.
Berkshire’s
senior
management