
Annual Report 2025
Life, Liberty
and
the Pursuit of
Happiness
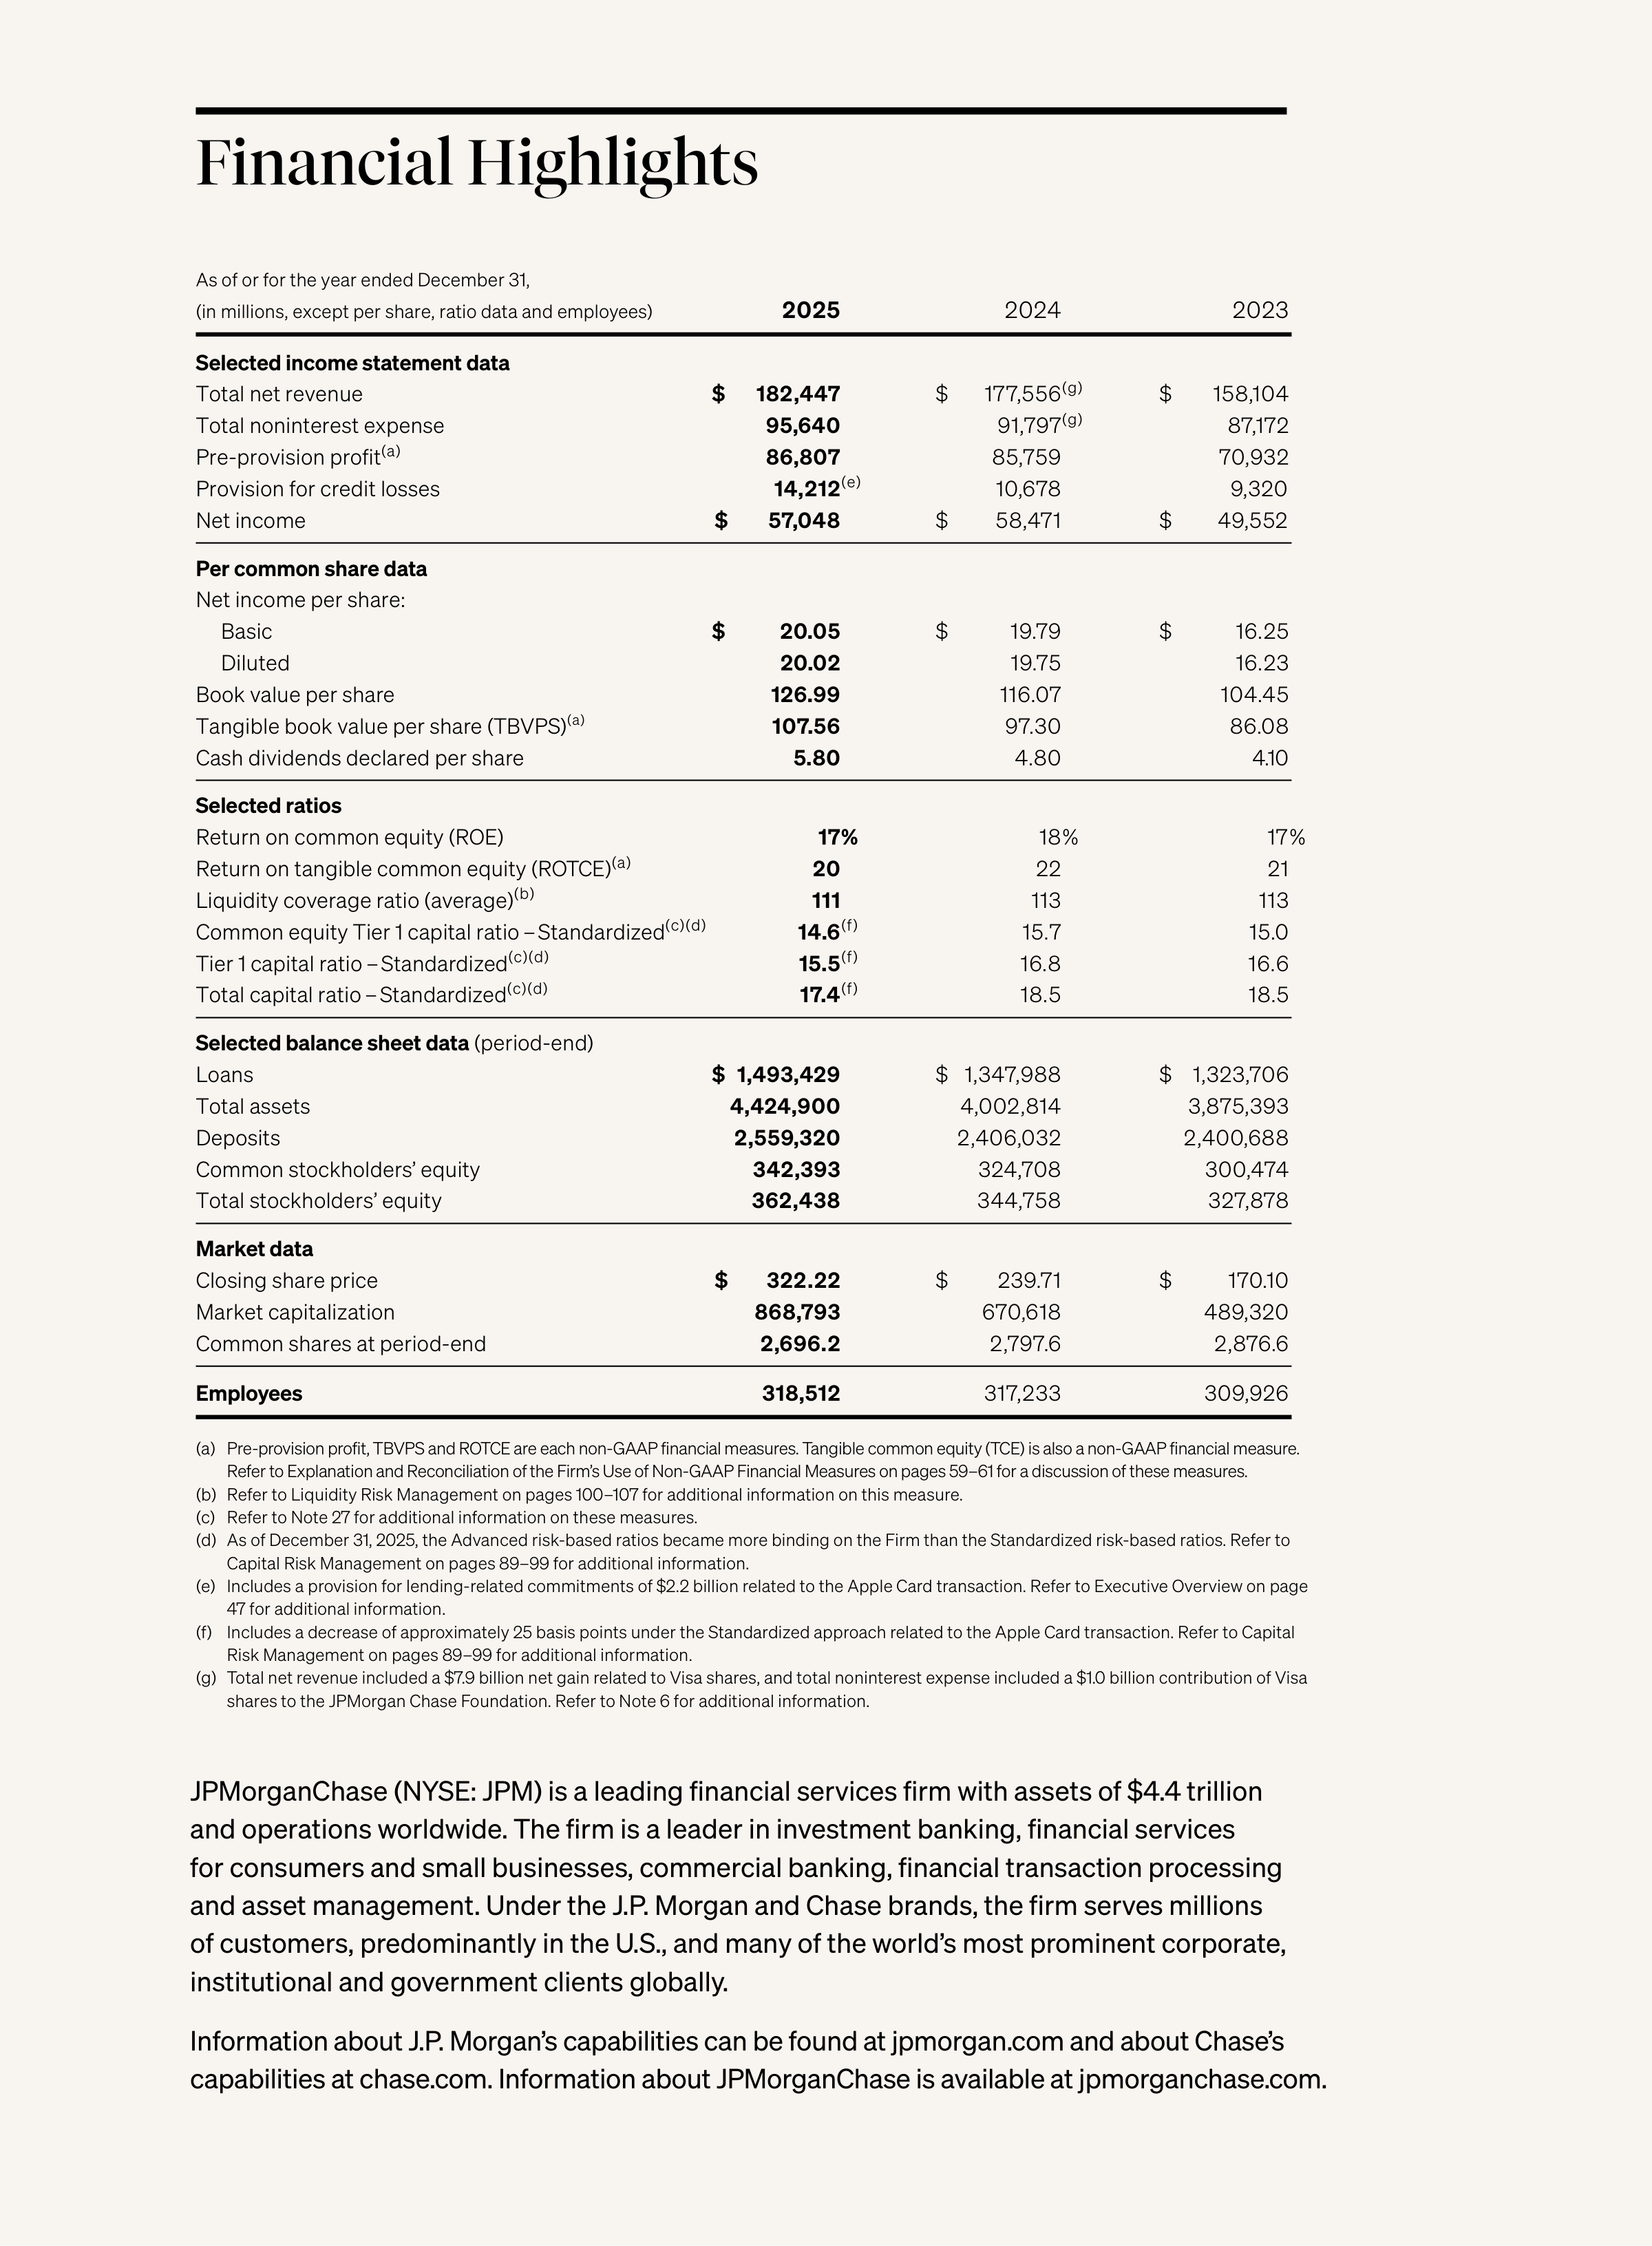
Financial Highlights
As of or for the year ended December 31,
(in millions, except per share, ratio data and employees)
2025
2024
2023
Selected income statement data
Total net revenue
$
182,447
$
177,556
(g)
$
158,104
Total noninterest expense
95,640
91,797
(g)
87,172
Pre-provision profit
(a)
86,807
85,759
70,932
Provision for credit losses
14,212
(e)
10,678
9,320
Net income
$
57,048
$
58,471
$
49,552
Per common share data
Net income per share:
Basic
$
20.05
$
19.79
$
16.25
Diluted
20.02
19.75
16.23
Book value per share
126.99
116.07
104.45
Tangible book value per share (TBVPS)
(a)
107.56
97.30
86.08
Cash dividends declared per share
5.80
4.80
4.10
Selected ratios
Return on common equity (ROE)
17 %
18 %
17 %
Return on tangible common equity (ROTCE)
(a)
20
22
21
Liquidity coverage ratio (average)
(b)
111
113
113
Common equity Tier 1 capital ratio – Standardized
(c)(d)
14.6
(f)
15.7
15.0
Tier 1 capital ratio – Standardized
(c)(d)
15.5
(f)
16.8
16.6
Total capital ratio – Standardized
(c)(d)
17.4
(f)
18.5
18.5
Selected balance sheet data
(period-end)
Loans
$
1,493,429
$
1,347,988
$
1,323,706
Total assets
4,424,900
4,002,814
3,875,393
Deposits
2,559,320
2,406,032
2,400,688
Common stockholders’ equity
342,393
324,708
300,474
Total stockholders’ equity
362,438
344,758
327,878
Market data
Closing share price
$
322.22
$
239.71
$
170.10
Market capitalization
868,793
670,618
489,320
Common shares at period-end
2,696.2
2,797.6
2,876.6
Employees
318,512
317,233
309,926
(a) Pre-provision profit, TBVPS and ROTCE are each non-GAAP financial measures. Tangible common equity (TCE) is also a non-GAAP financial measure.
Refer to Explanation and Reconciliation of the Firm’s Use of Non-GAAP Financial Measures on pages 59–61 for a discussion of these measures.
(b) Refer to Liquidity Risk Management on pages 100–107 for additional information on this measure.
(c) Refer to Note 27 for additional information on these measures.
(d) As of December 31, 2025, the Advanced risk-based ratios became more binding on the Firm than the Standardized risk-based ratios. Refer to
Capital Risk Management on pages 89–99 for additional information.
(e) Includes a provision for lending-related commitments of $2.2 billion related to the Apple Card transaction. Refer to Executive Overview on page
47 for additional information.
(f)
Includes a decrease of approximately 25 basis points under the Standardized approach related to the Apple Card transaction. Refer to Capital
Risk Management on pages 89–99 for additional information.
(g) Total net revenue included a $7.9 billion net gain related to Visa shares, and total noninterest expense included a $1.0 billion contribution of Visa
shares to the JPMorgan Chase Foundation. Refer to Note 6 for additional information.
JPMorganChase (NYSE: JPM) is a leading financial services firm with assets of $4.4 trillion
and operations worldwide. The firm is a leader in investment banking, financial services
for consumers and small businesses, commercial banking, financial transaction processing
and asset management. Under the J.P. Morgan and Chase brands, the firm serves millions
of customers, predominantly in the U.S., and many of the world’s most prominent corporate,
institutional and government clients globally.
Information about J.P. Morgan’s capabilities can be found at jpmorgan.com and about Chase’s
capabilities at chase.com. Information about JPMorganChase is available at jpmorganchase.com.
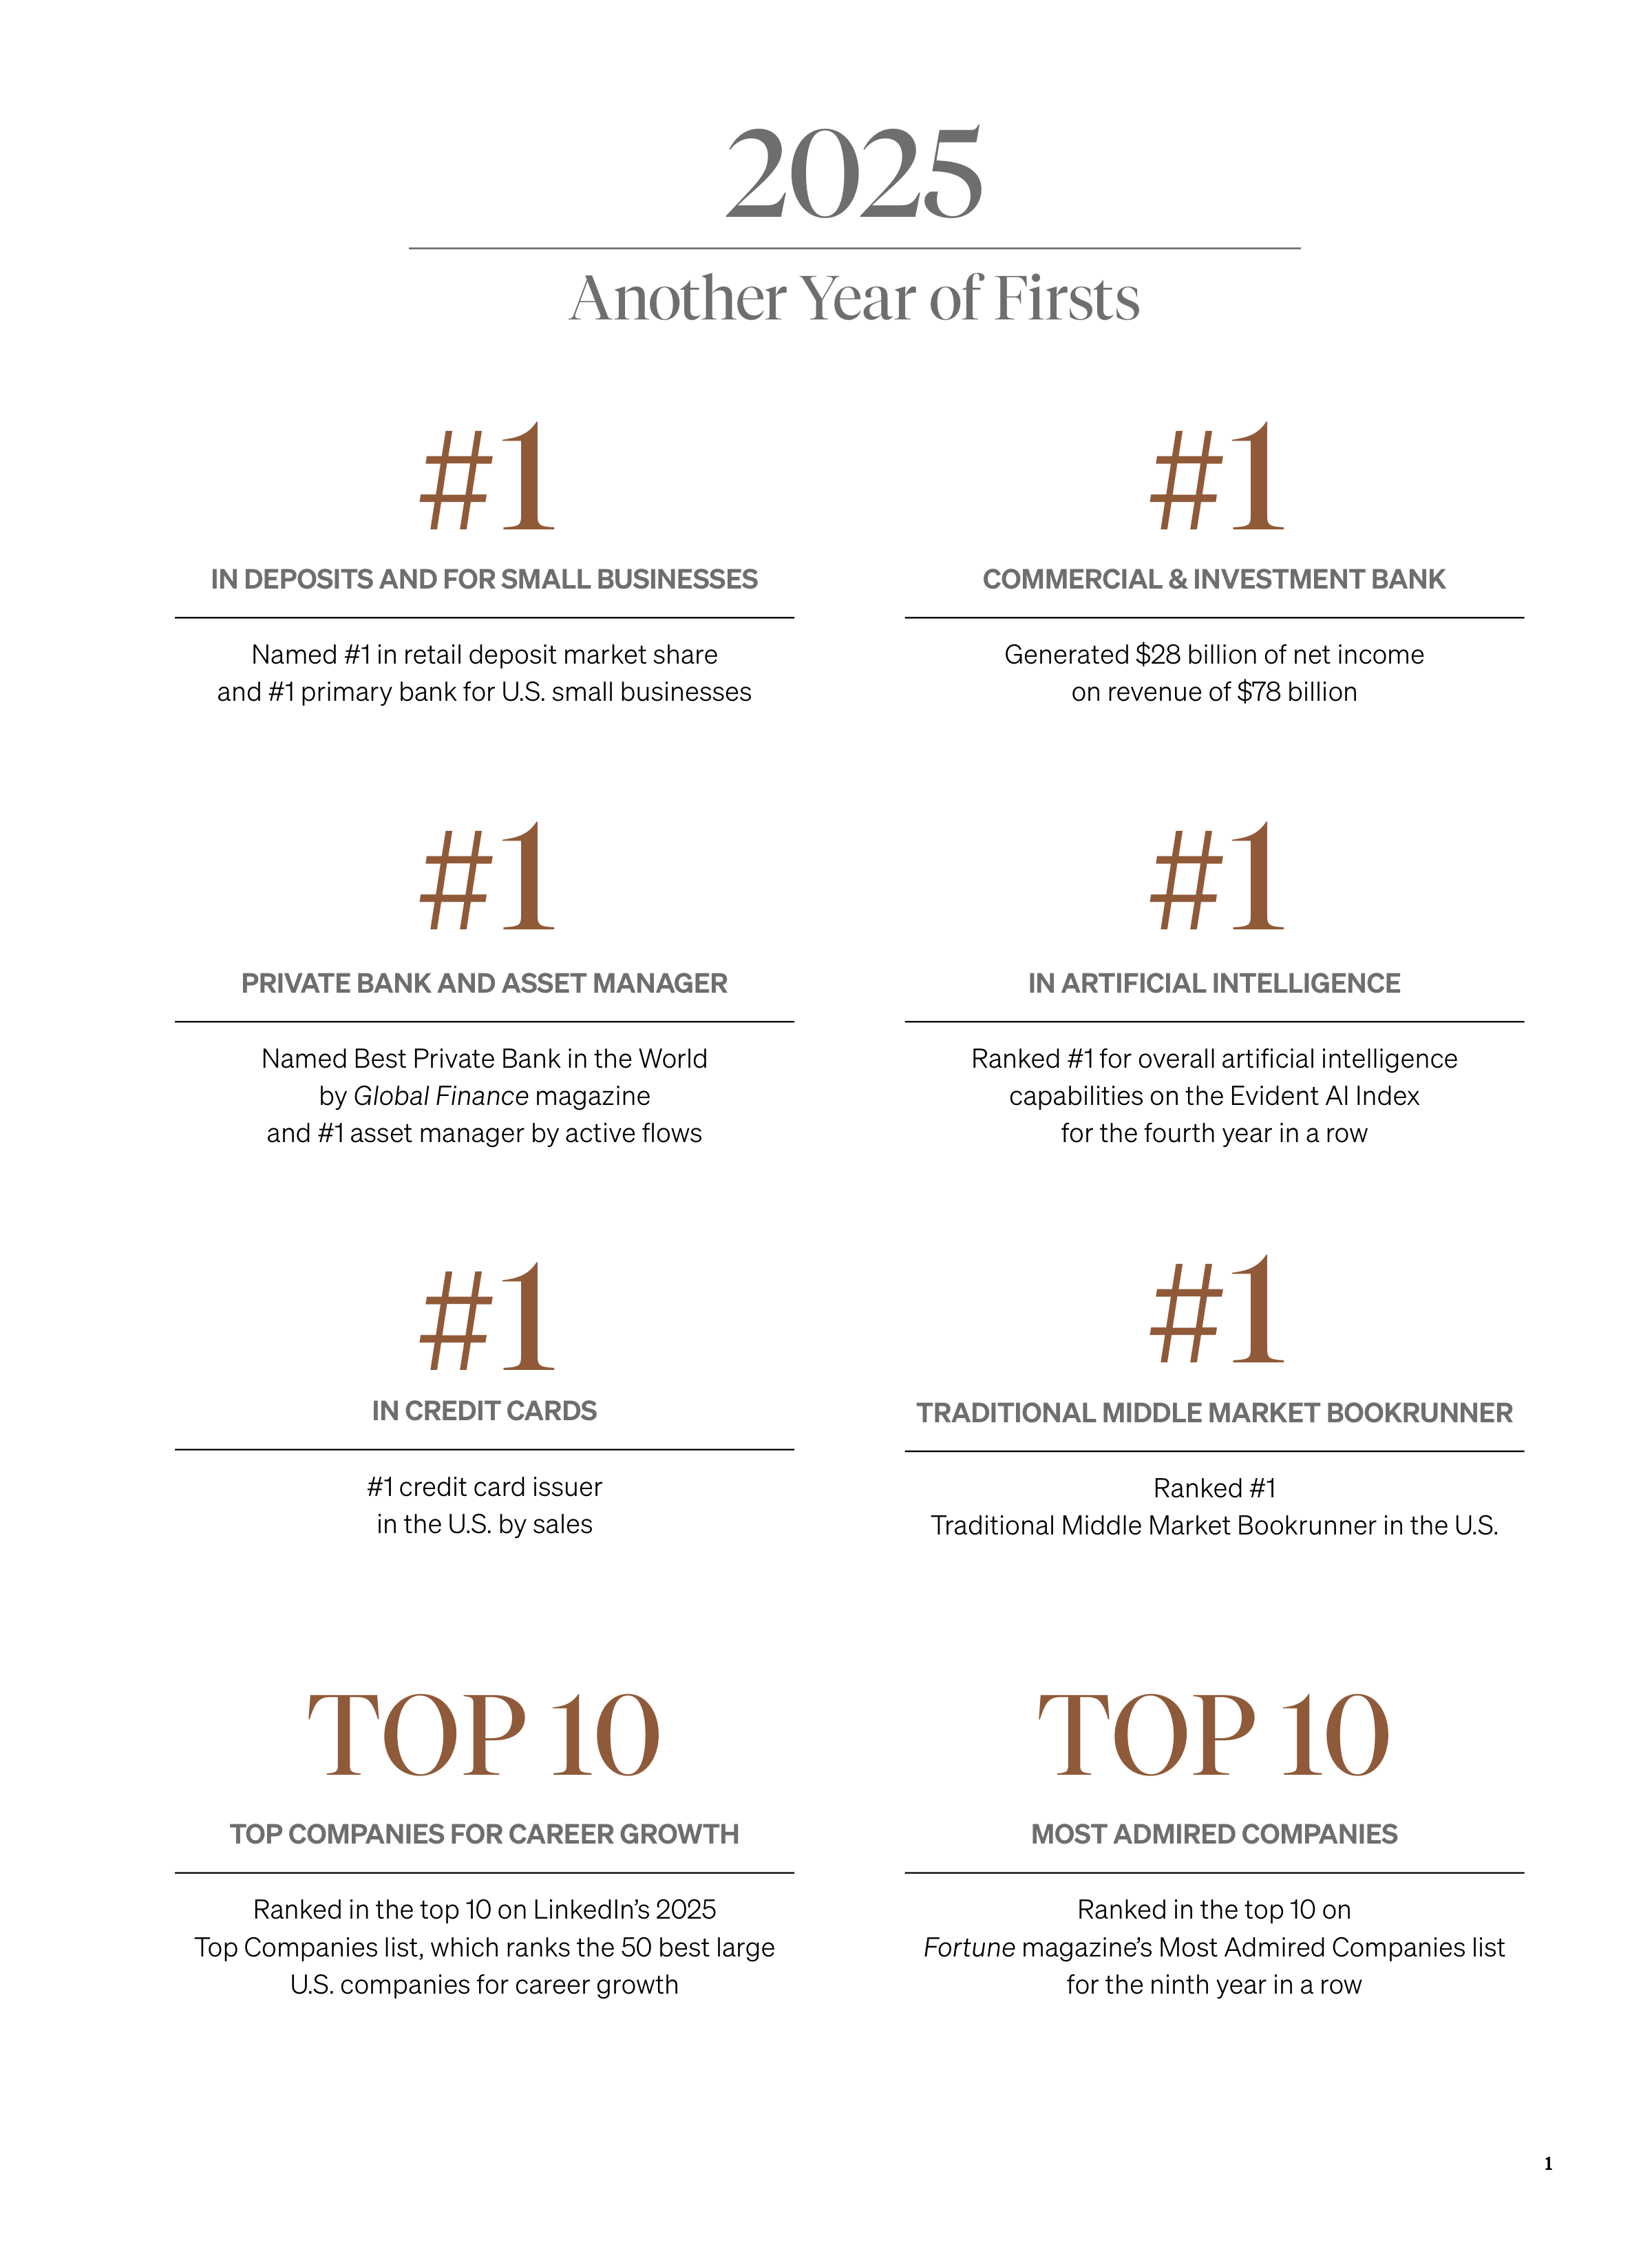
2025
Another Year of Firsts
COMMERCIAL & INVESTMENT BANK
Generated $28 billion of net income
on revenue of $78 billion
#
1
#
1
IN DEPOSITS AND FOR SMALL BUSINESSES
Named #1 in retail deposit market share
and #1 primary bank for U.S. small businesses
TRADITIONAL MIDDLE MARKET BOOKRUNNER
Ranked #1
Traditional Middle Market Bookrunner in the U.S.
#
1
IN ARTIFICIAL INTELLIGENCE
Ranked #1 for overall artificial intelligence
capabilities on the Evident AI Index
for the fourth year in a row
#
1
IN CREDIT CARDS
#1 credit card issuer
in the U.S. by sales
#
1
MOST ADMIRED COMPANIES
Ranked in the top 10 on
Fortune
magazine’s Most Admired Companies list
for the ninth year in a row
TOP 10
TOP COMPANIES FOR CAREER GROWTH
Ranked in the top 10 on LinkedIn’s 2025
Top Companies list, which ranks the 50 best large
U.S. companies for career growth
TOP 10
PRIVATE BANK AND ASSET MANAGER
Named Best Private Bank in the World
by
Global Finance
magazine
and #1 asset manager by active flows
#
1
1
In 2026, America is celebrating its 250
th
anniversary. Also this year, we are
celebrating the 227
th
anniversary of JPMorganChase, which was founded in April
1799. This is the perfect time to rededicate ourselves to the values that made this
great nation of ours — freedom, liberty and opportunity — and to recognize that
we all stand on our country’s shoulders.
The challenges we all face are significant. The list is long but at the top are the
terrible ongoing war and violence in Ukraine, the current war in Iran and the
broader hostilities in the Middle East, terrorist activity and growing geopolitical
tensions, importantly with China. Our hearts go out to those whose lives are
profoundly affected by these crises. We sincerely hope these global conflicts are
properly resolved and that one day all of Europe and the Middle East will attain
long-term stability and prosperity. Even in troubled times, we have confidence
that America will do what it has always done — look to the values that have
defined our singular nation and sustained our leadership of the free world.
Despite the unsettling landscape, the U.S. economy continues to be resilient, with
consumers still earning and spending (though with some recent weakening) and
businesses still healthy. It is important to note that our economy has been fueled
Dear Fellow Shareholders,
2
INTRODUCTION
Jamie Dimon,
Chairman and
Chief Executive Officer
by large amounts of government deficit spending and past stimulus and that
increased expenditure on infrastructure remains a growing need. Now, because
of the war in Iran, we additionally face the potential for significant ongoing oil and
commodity price shocks, along with the reshaping of global supply chains, which
may lead to stickier inflation and ultimately higher interest rates than markets
currently expect. Continual trade negotiations exacerbate the tense geopolitical
issues. And high asset prices, which certainly feel good in the short run, create
additional risk if anything goes wrong. In Section III of this letter, I describe in
greater detail how we are dealing with these risks.
JPMorganChase, a company that historically has worked across borders and
boundaries, will do its part to ensure that the global economy is safe and secure,
but we cannot confidently predict the outcome of current events, and our
company is not immune to their ultimate effects. As we have for more than two
centuries, we will continue to work through all of the complexities that confront us
and continue to help our clients, including governments, always defending our
values, even when challenged.
Remember the poem “If—” by Rudyard Kipling that begins “If you can keep your
head when all about you are losing theirs”? We will stay true to this. We must deal
with the world we have — and strive for the one we want.
Two things are absolutely foundational to our long-term success: The first is
that we run a great company, and the second, which is maybe more important,
is that the vitality of America domestically and the future of the free and
democratic world are strong. In the first part of this letter, I talk about issues
unique to JPMorganChase and how we are addressing them, including constantly
surmounting complexity, bureaucracy and complacency. And in the last two
sections, I focus on the perils before us, both nationally and internationally, that
require urgent, effective solutions.
Throughout 2025, JPMorganChase demonstrated the power of its investment
philosophy and guiding principles, as well as the value of being there for clients —
as we always are — in both good times and bad times. The result was continued
broad healthy growth across all our franchises, with the firm generating record
revenue for the eighth consecutive year and setting numerous records in each of
our lines of business. We earned revenue in 2025 of $185.6 billion
1
and net income
of $57.0 billion, with return on tangible common equity (ROTCE) of 20%, reflecting
a strong underlying performance across all of our businesses.
We also increased our quarterly common dividend from $1.25 per share to
$1.40 per share in the first quarter of 2025 — and again to $1.50 per share in the
third quarter of 2025 — while continuing to reinforce our fortress balance sheet.
We grew market share in several of our businesses and continued to make
1
Represents managed
revenue.
3
INTRODUCTION
significant investments in products, people and technologies while exercising
strict risk disciplines. We have achieved our decades-long consistency by
adhering to our key principles and strategies (see the sidebar on our steadfast
principles on page 5), which allow us to drive good organic growth and promote
proper management of our capital (including dividends and stock buybacks).
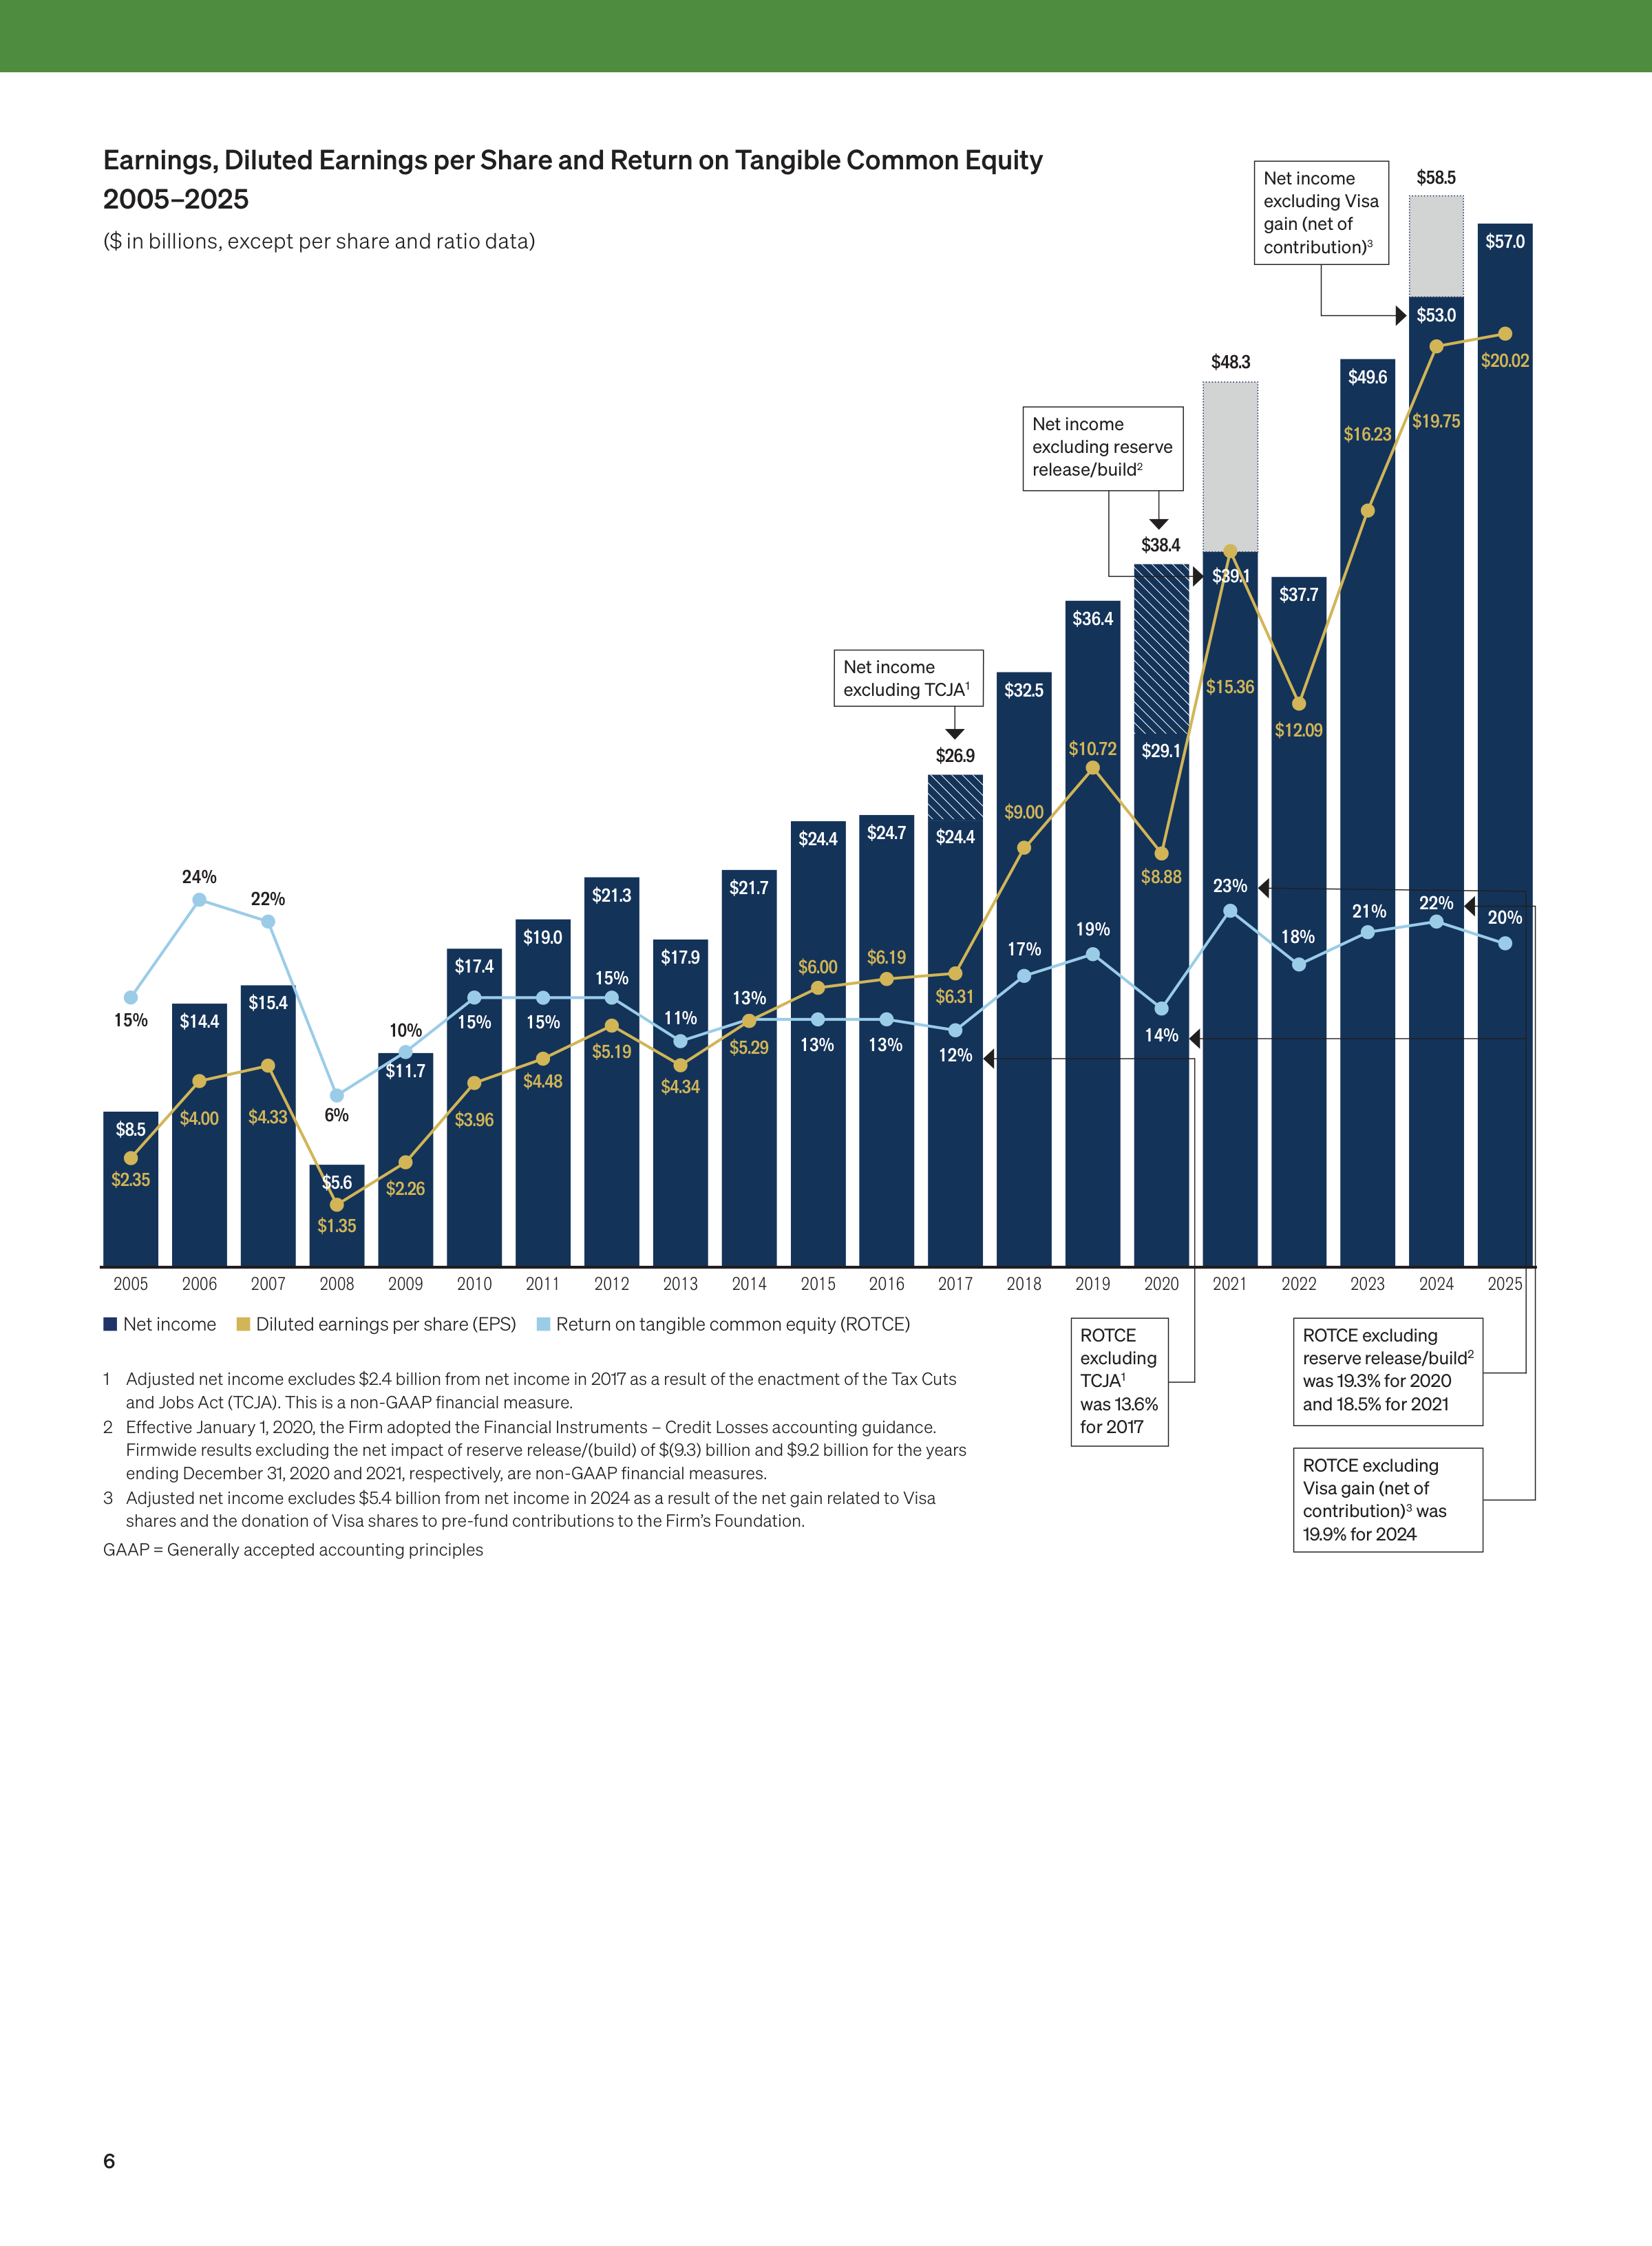
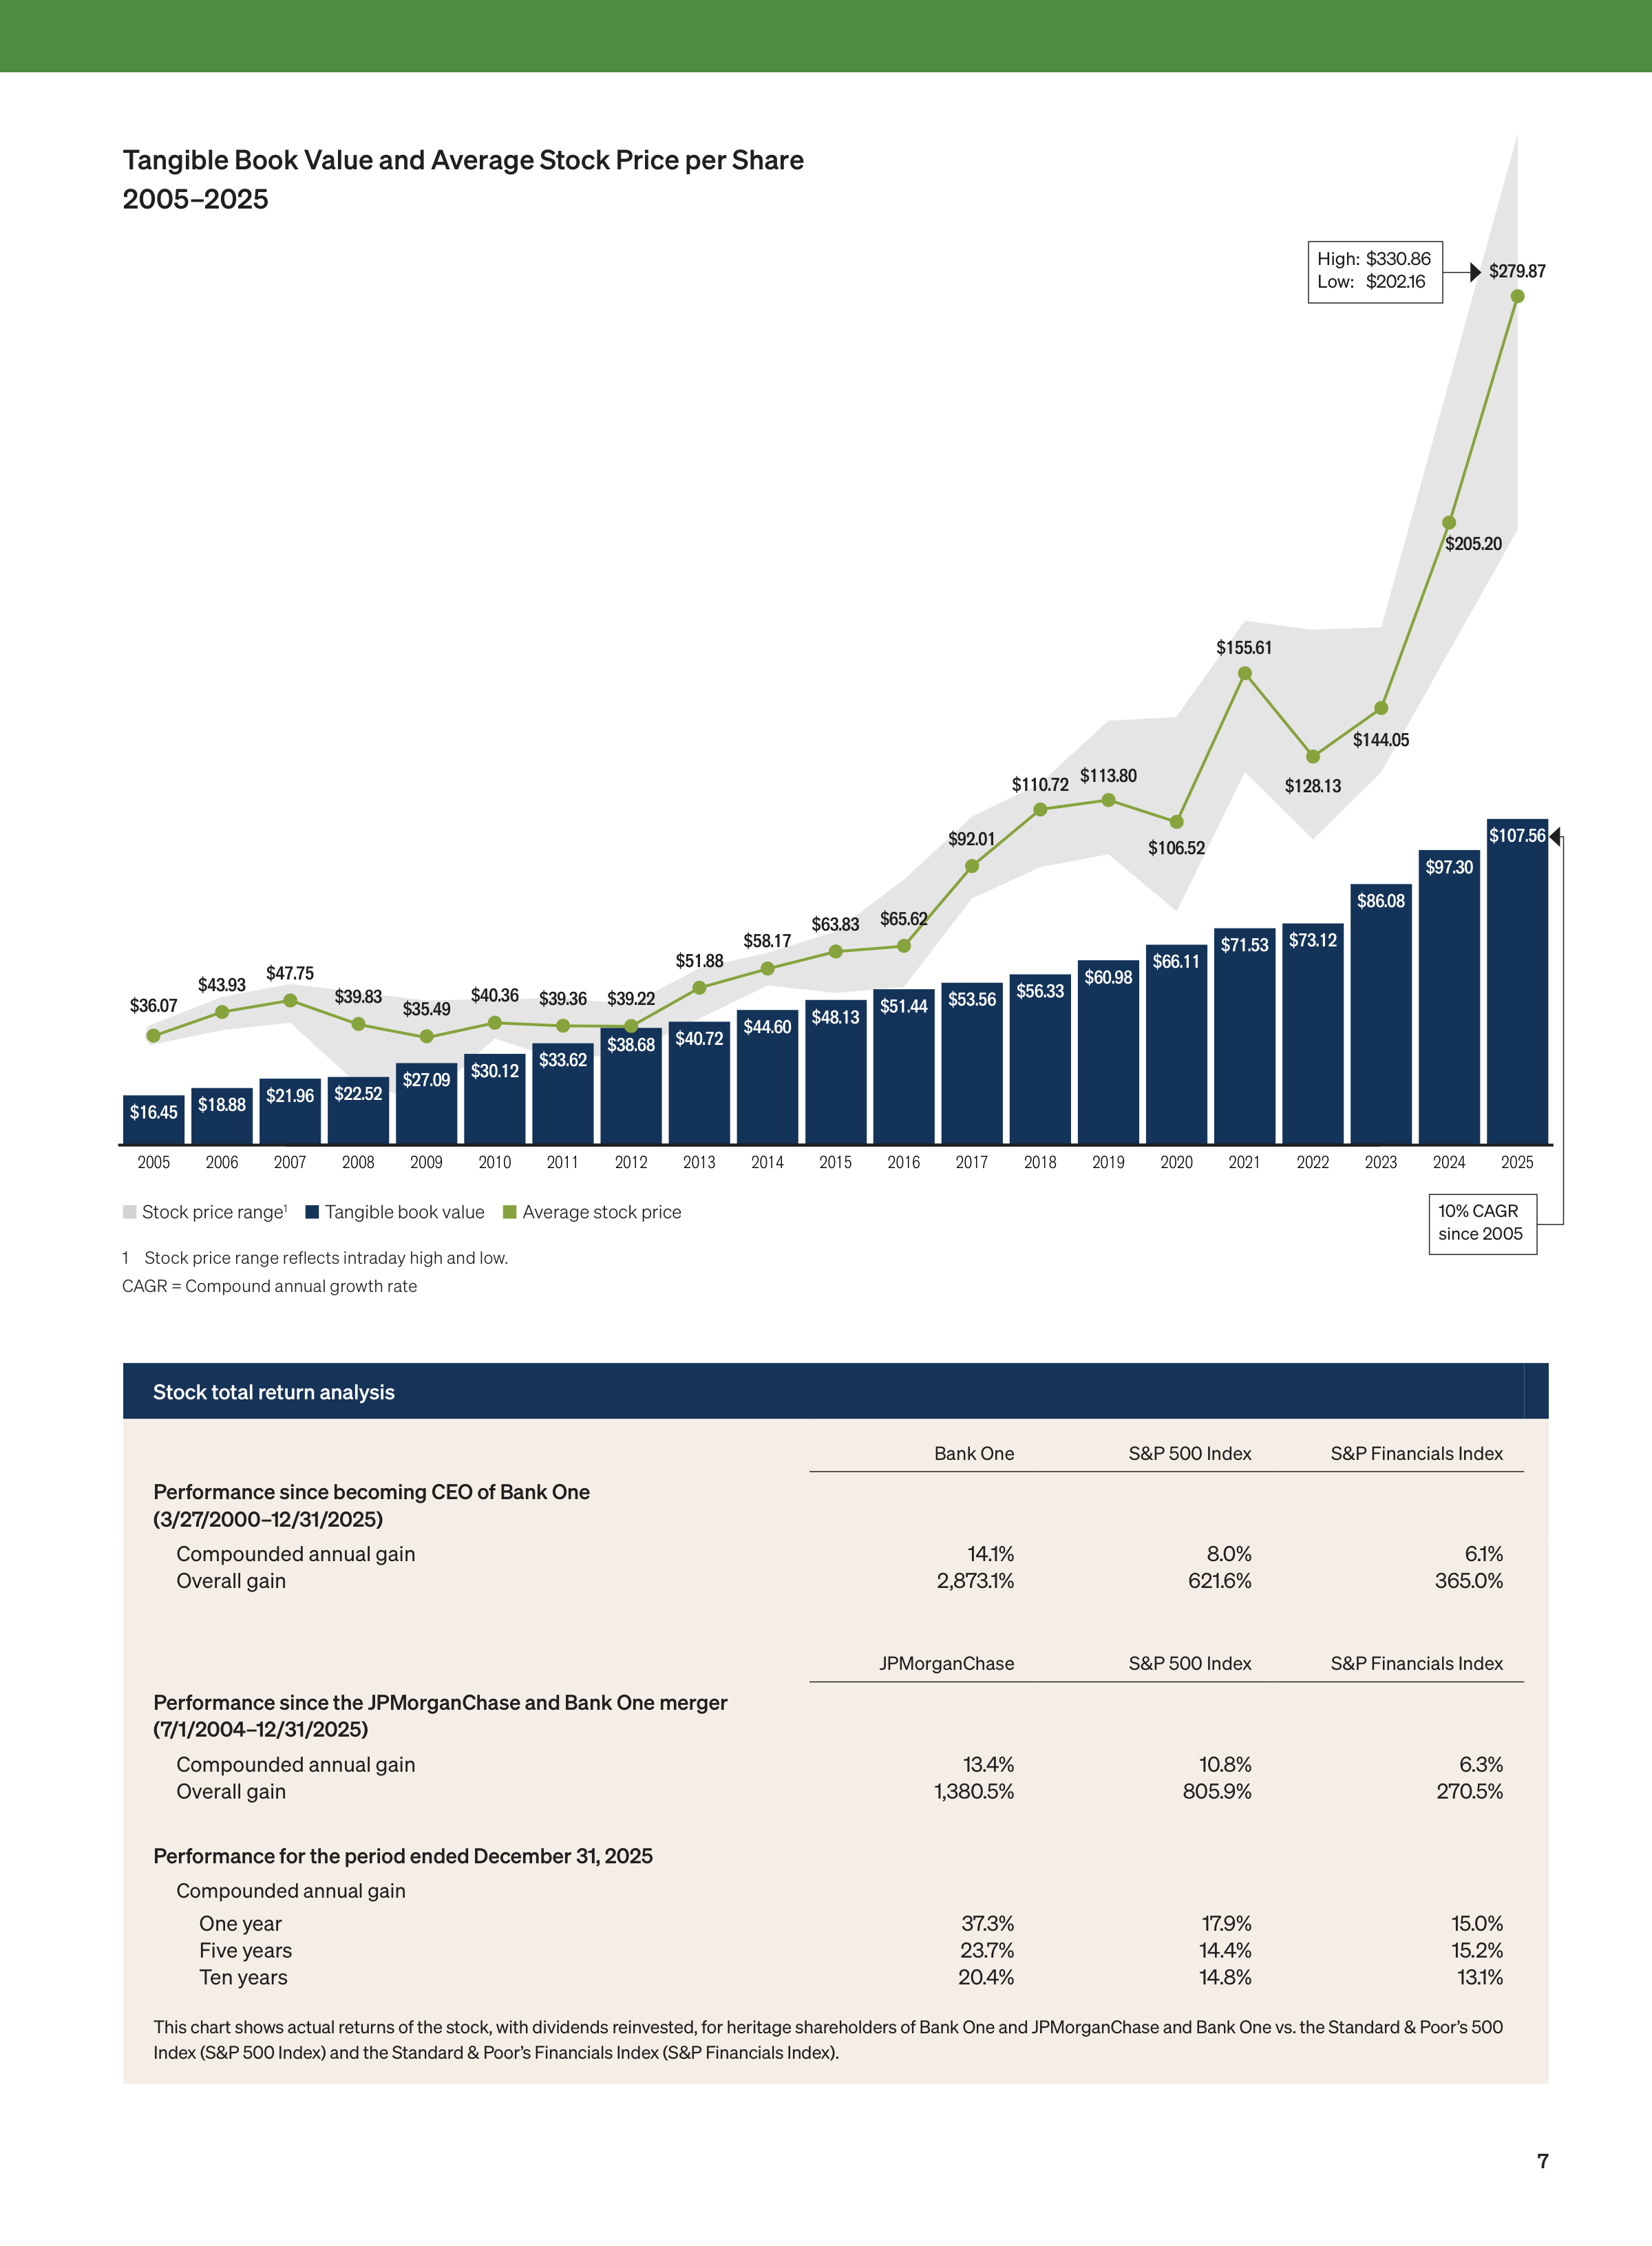
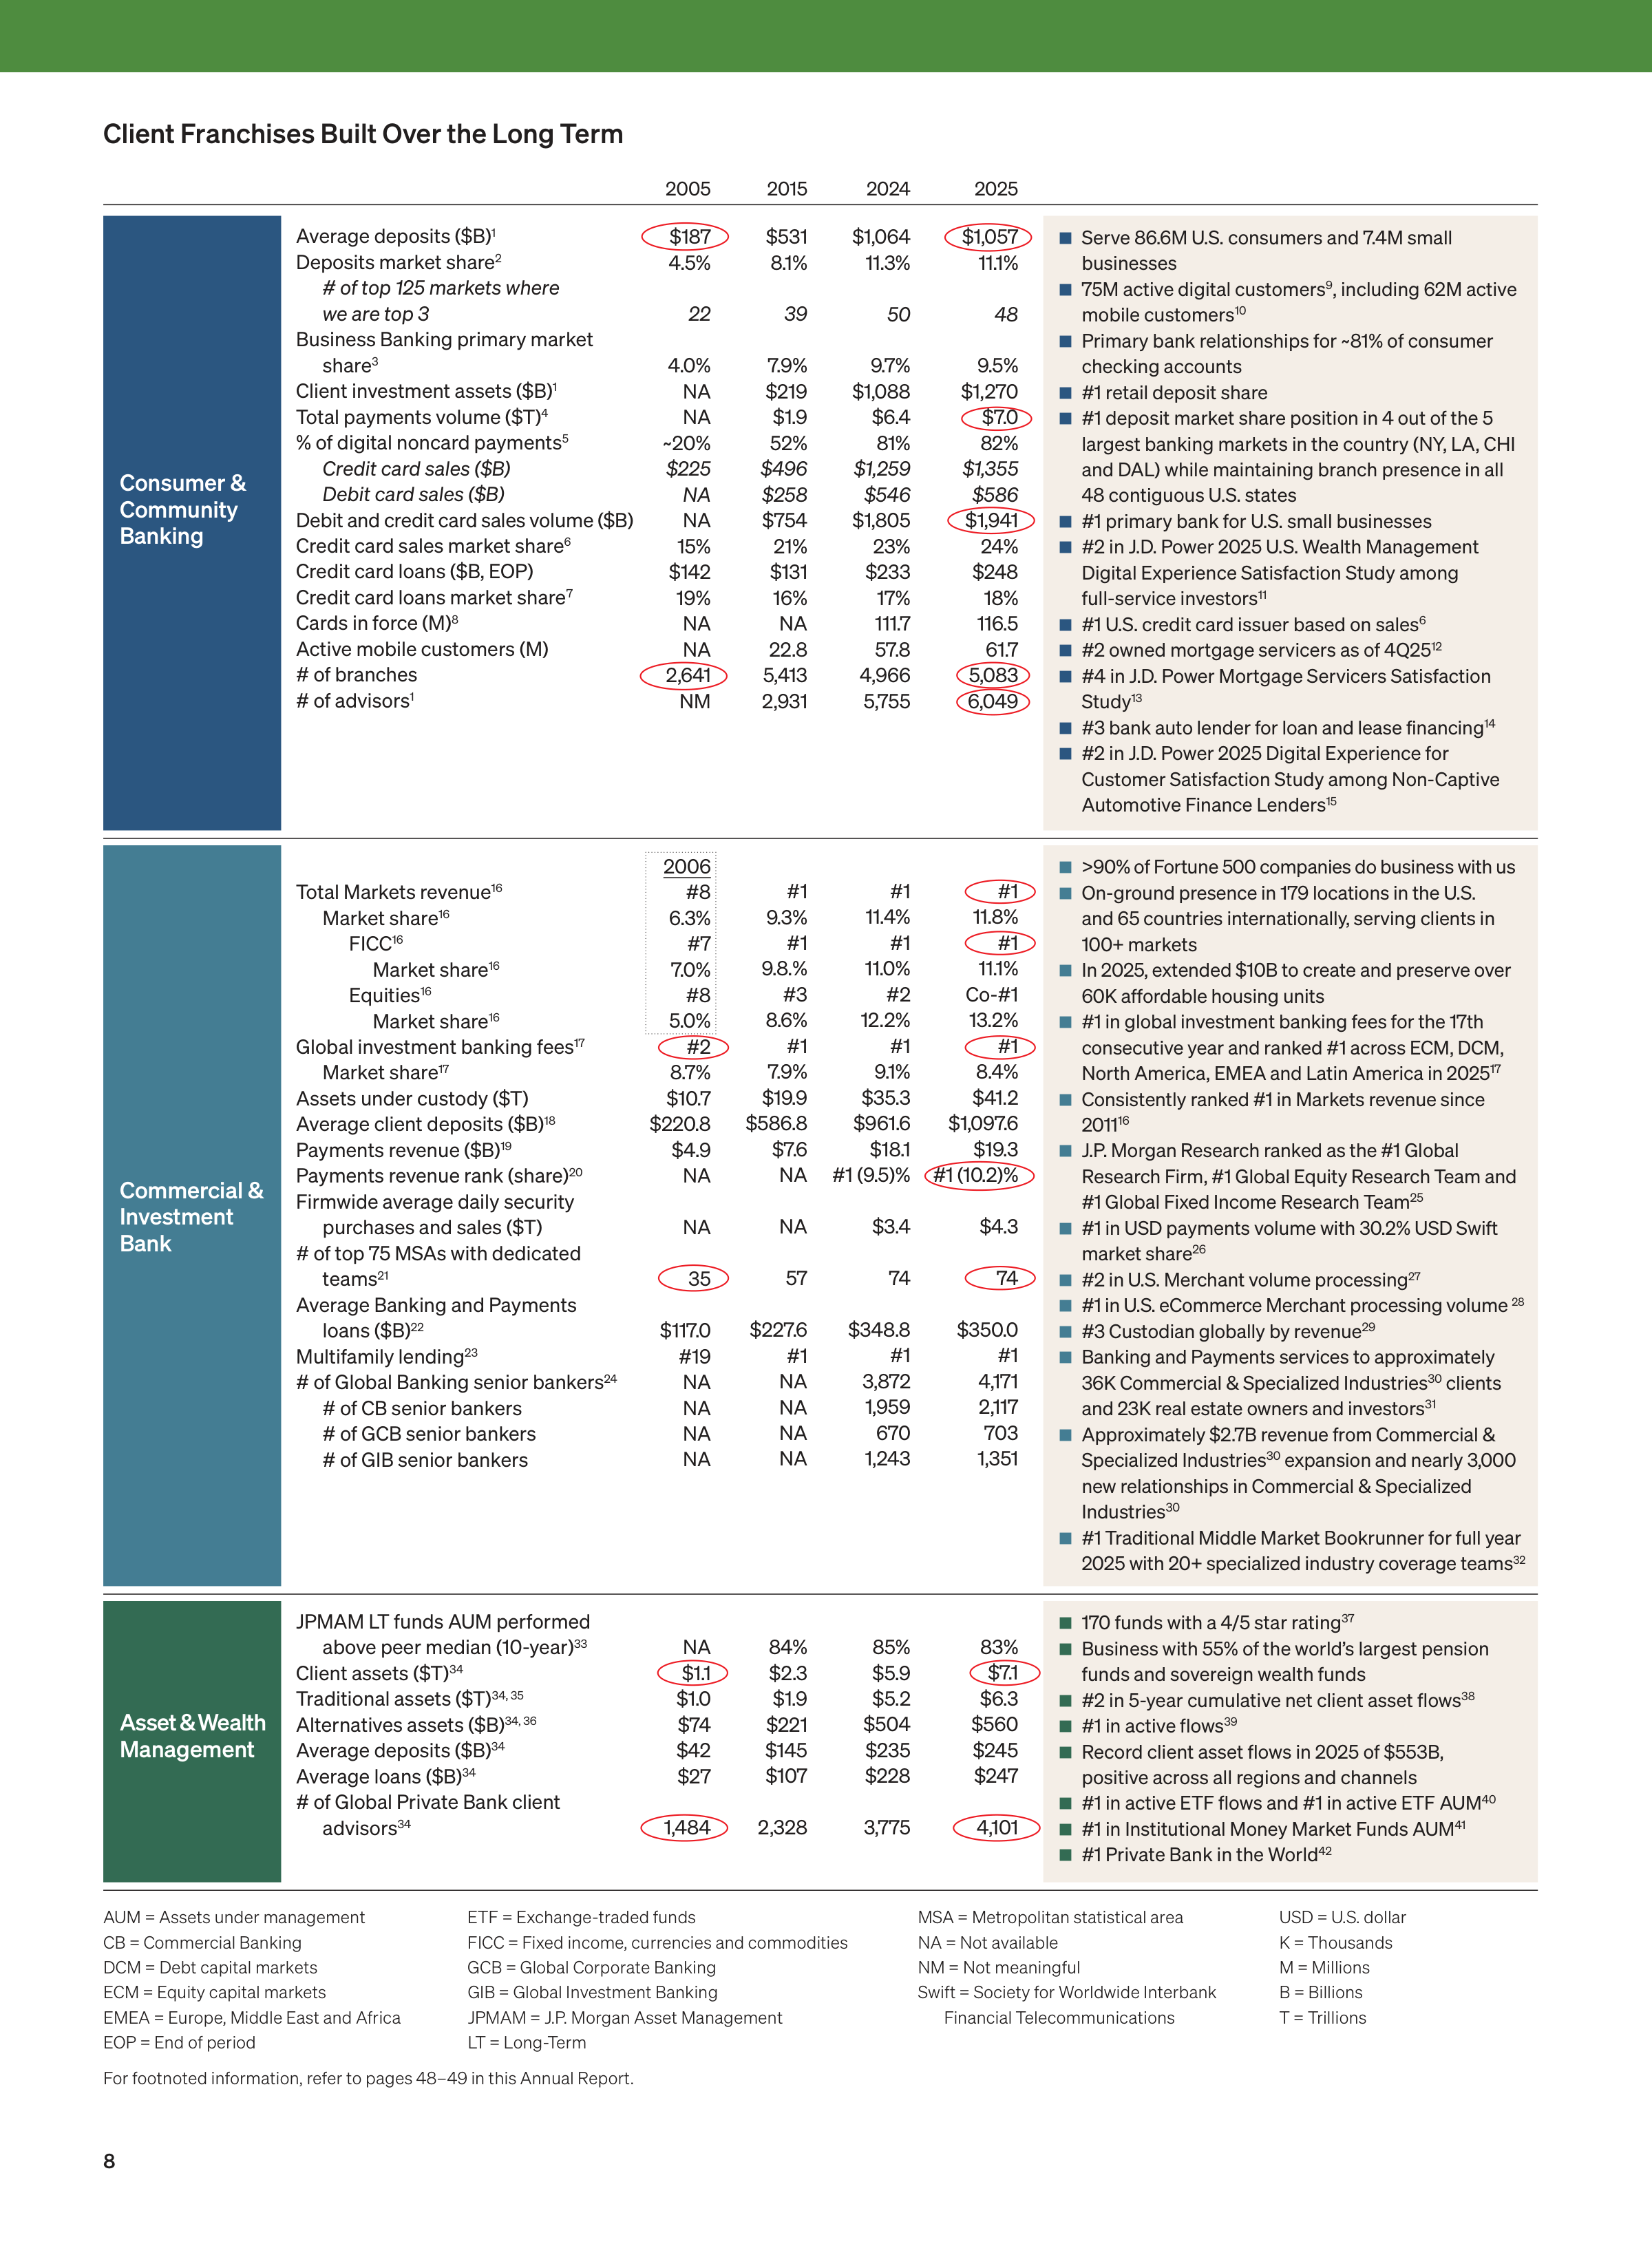
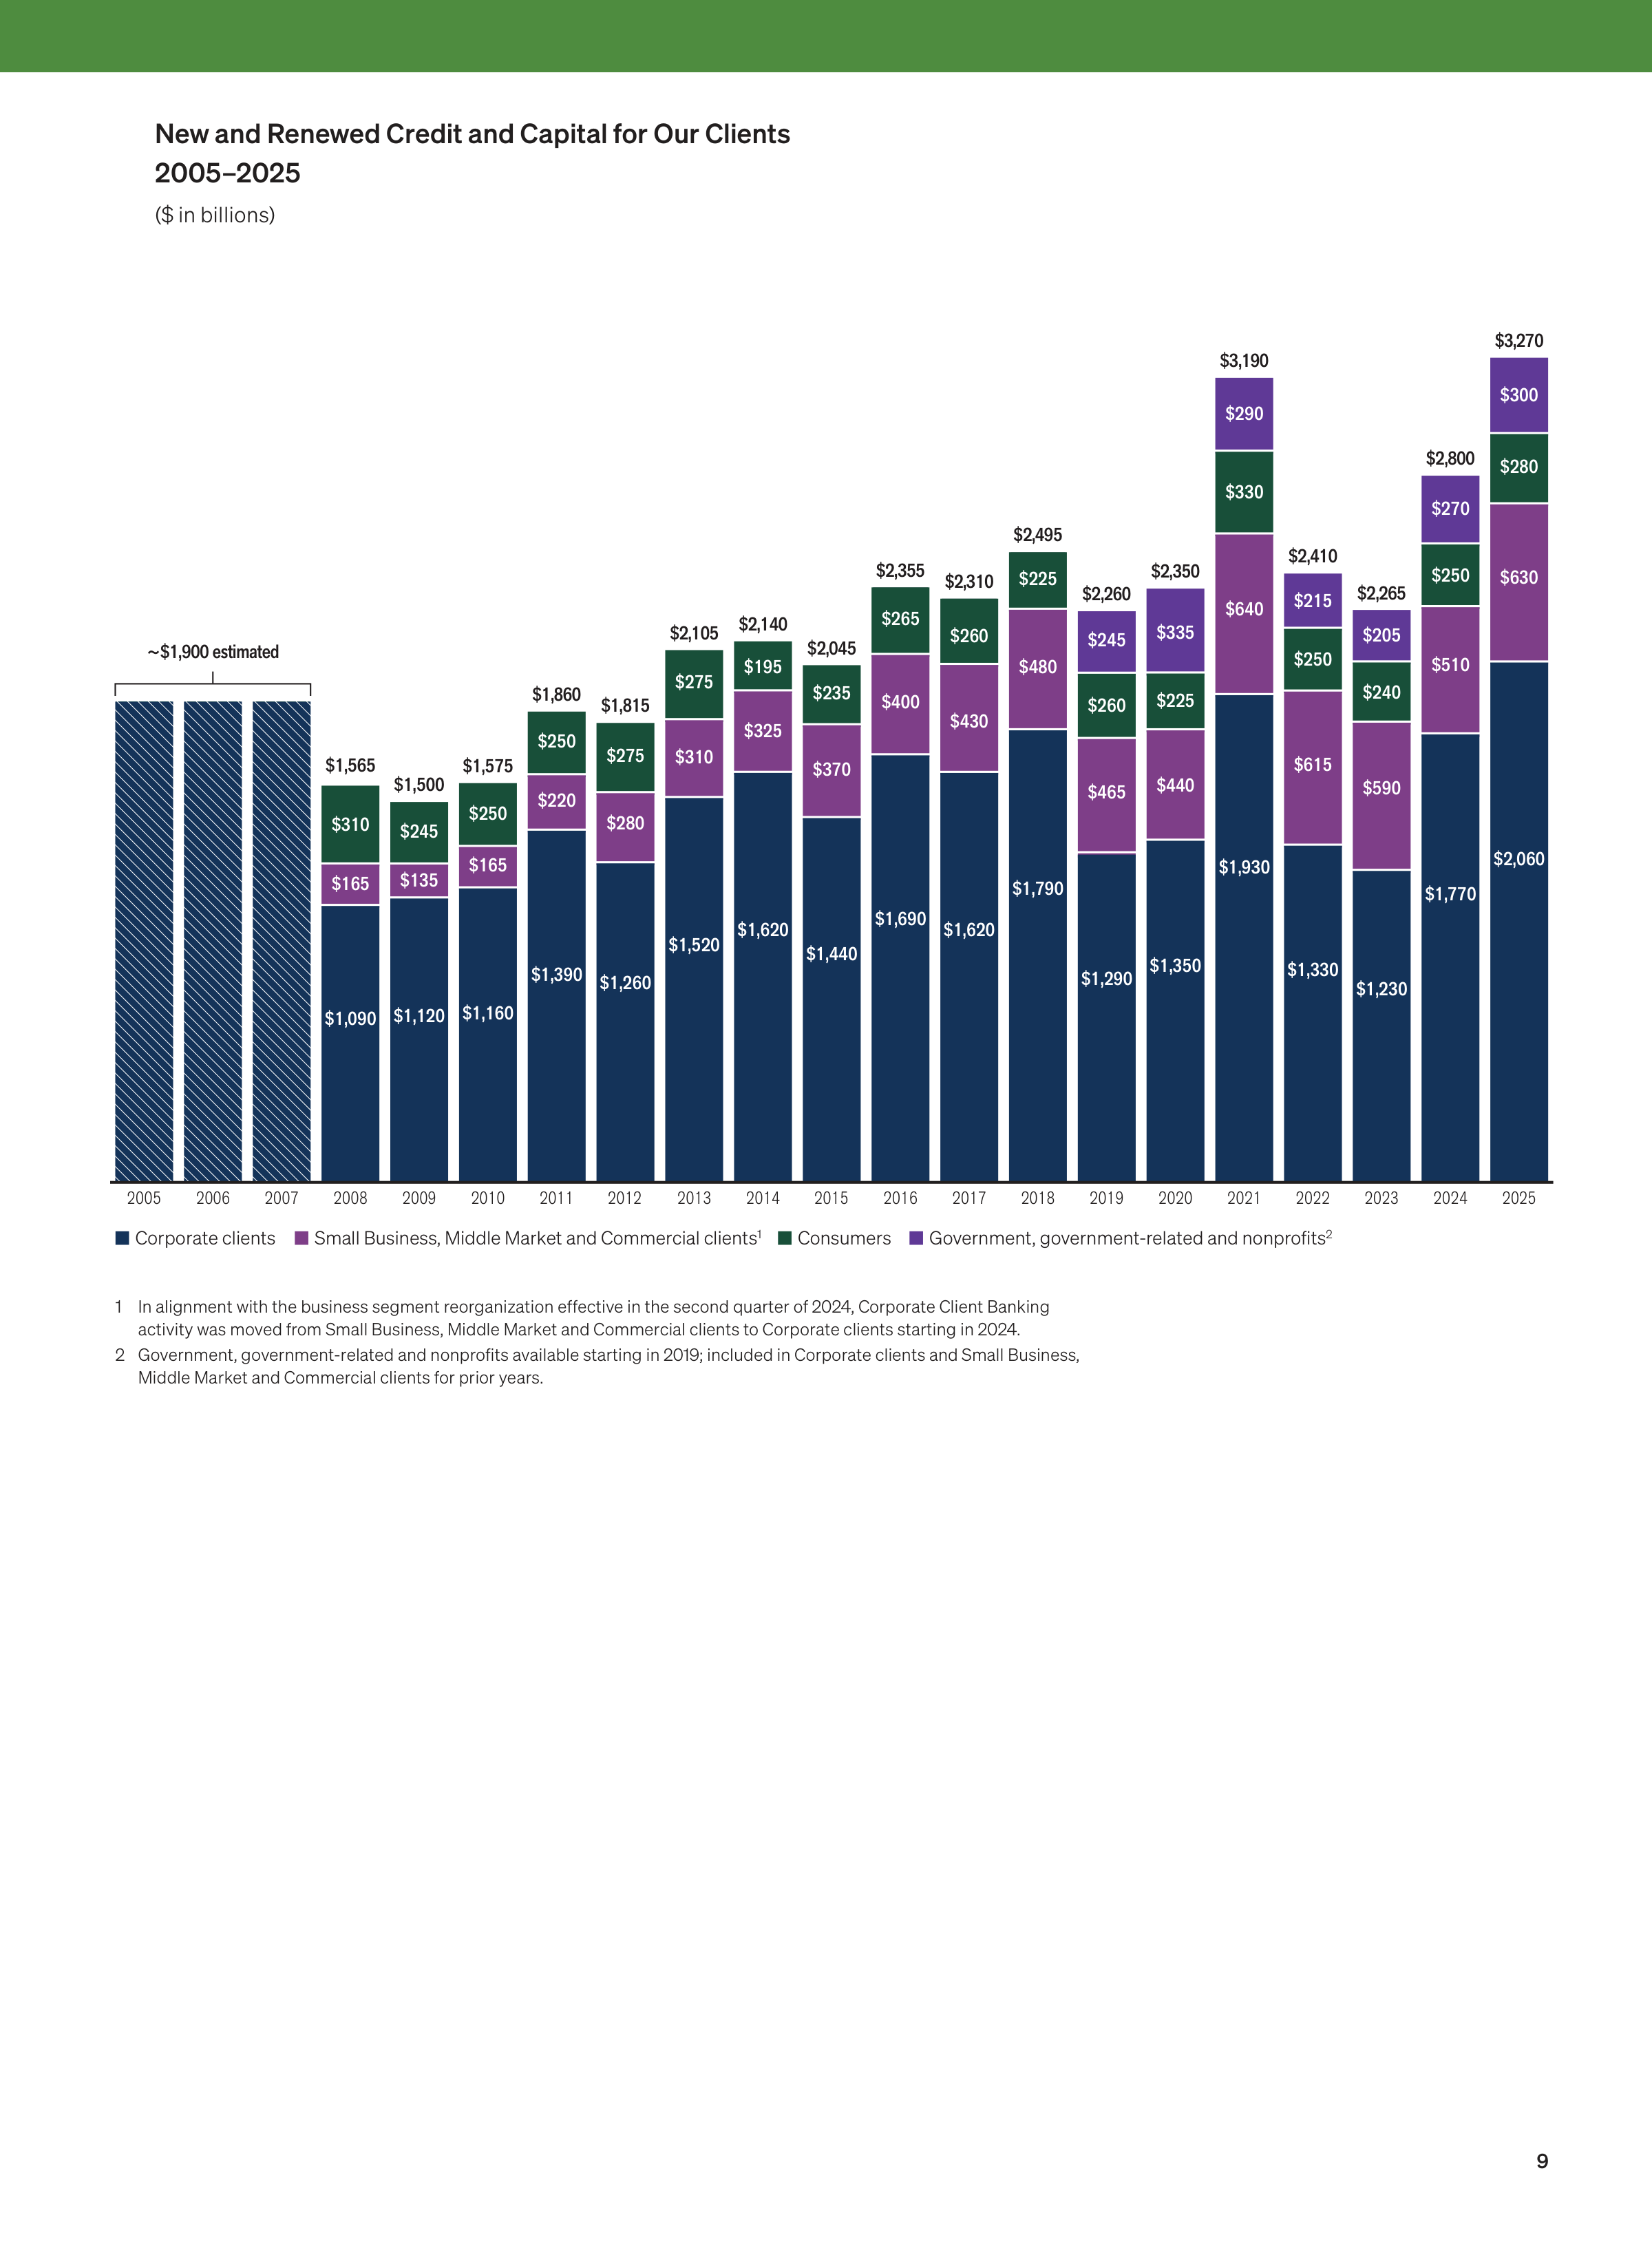
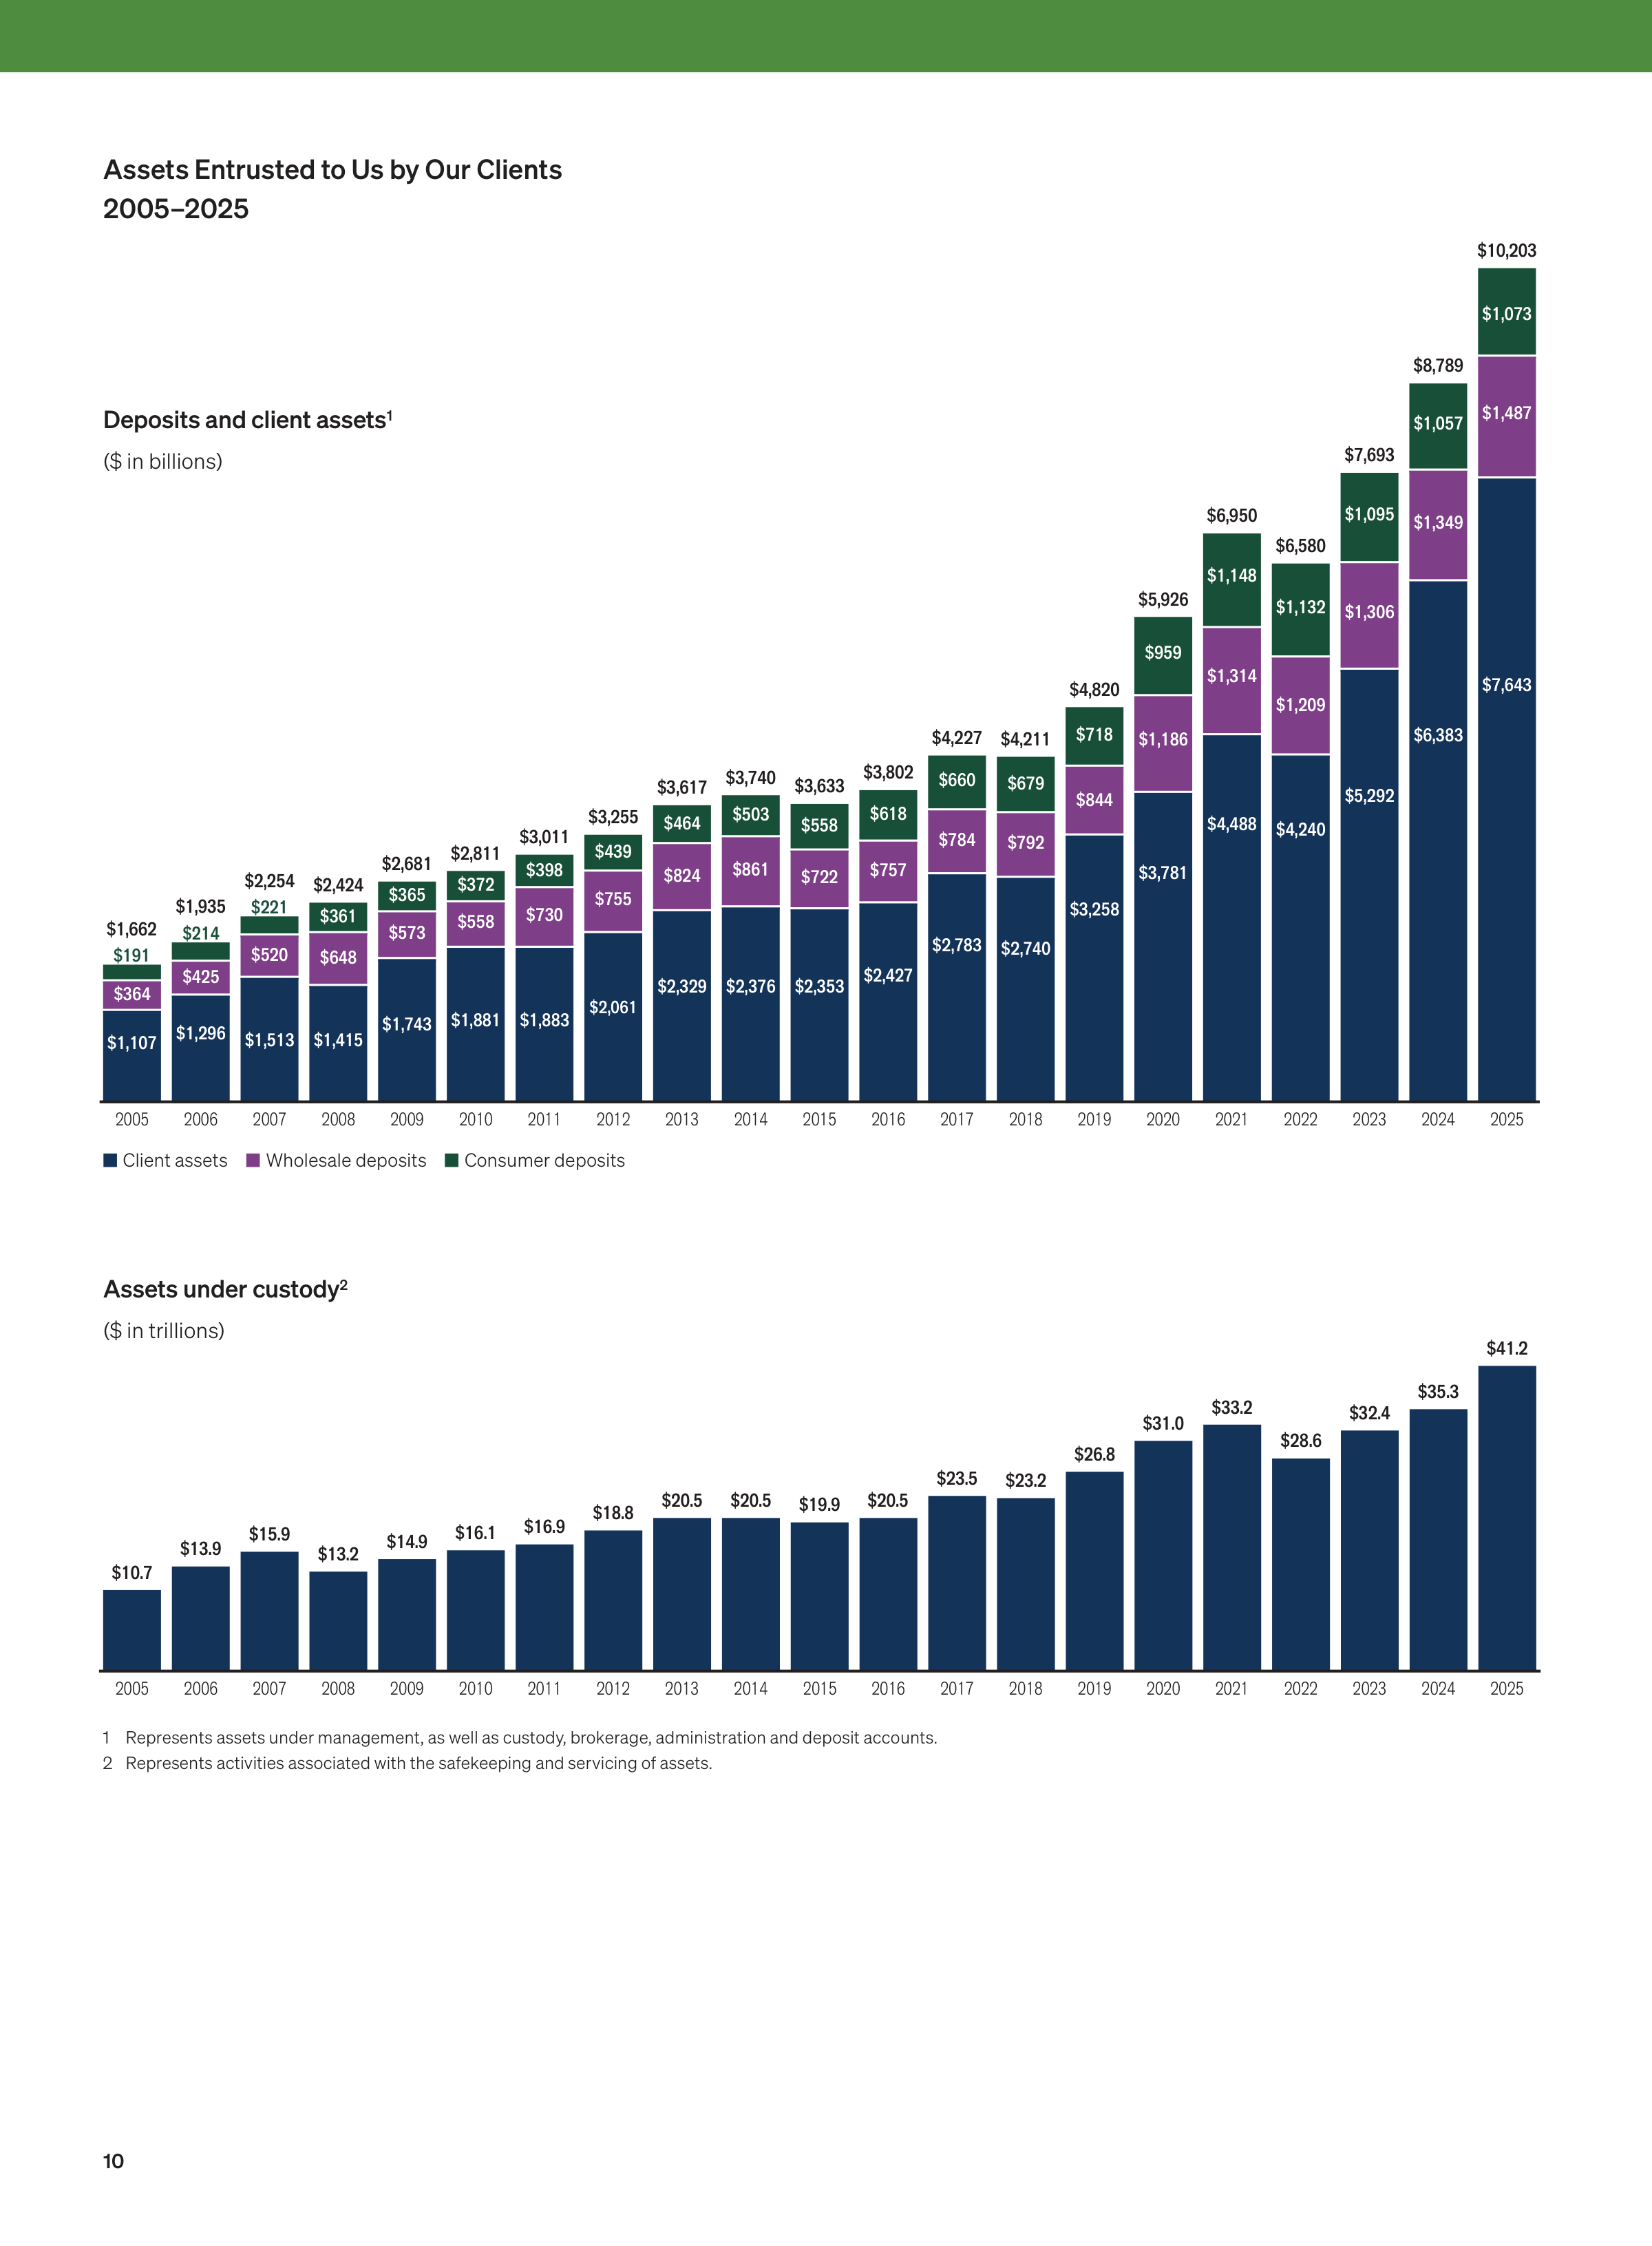
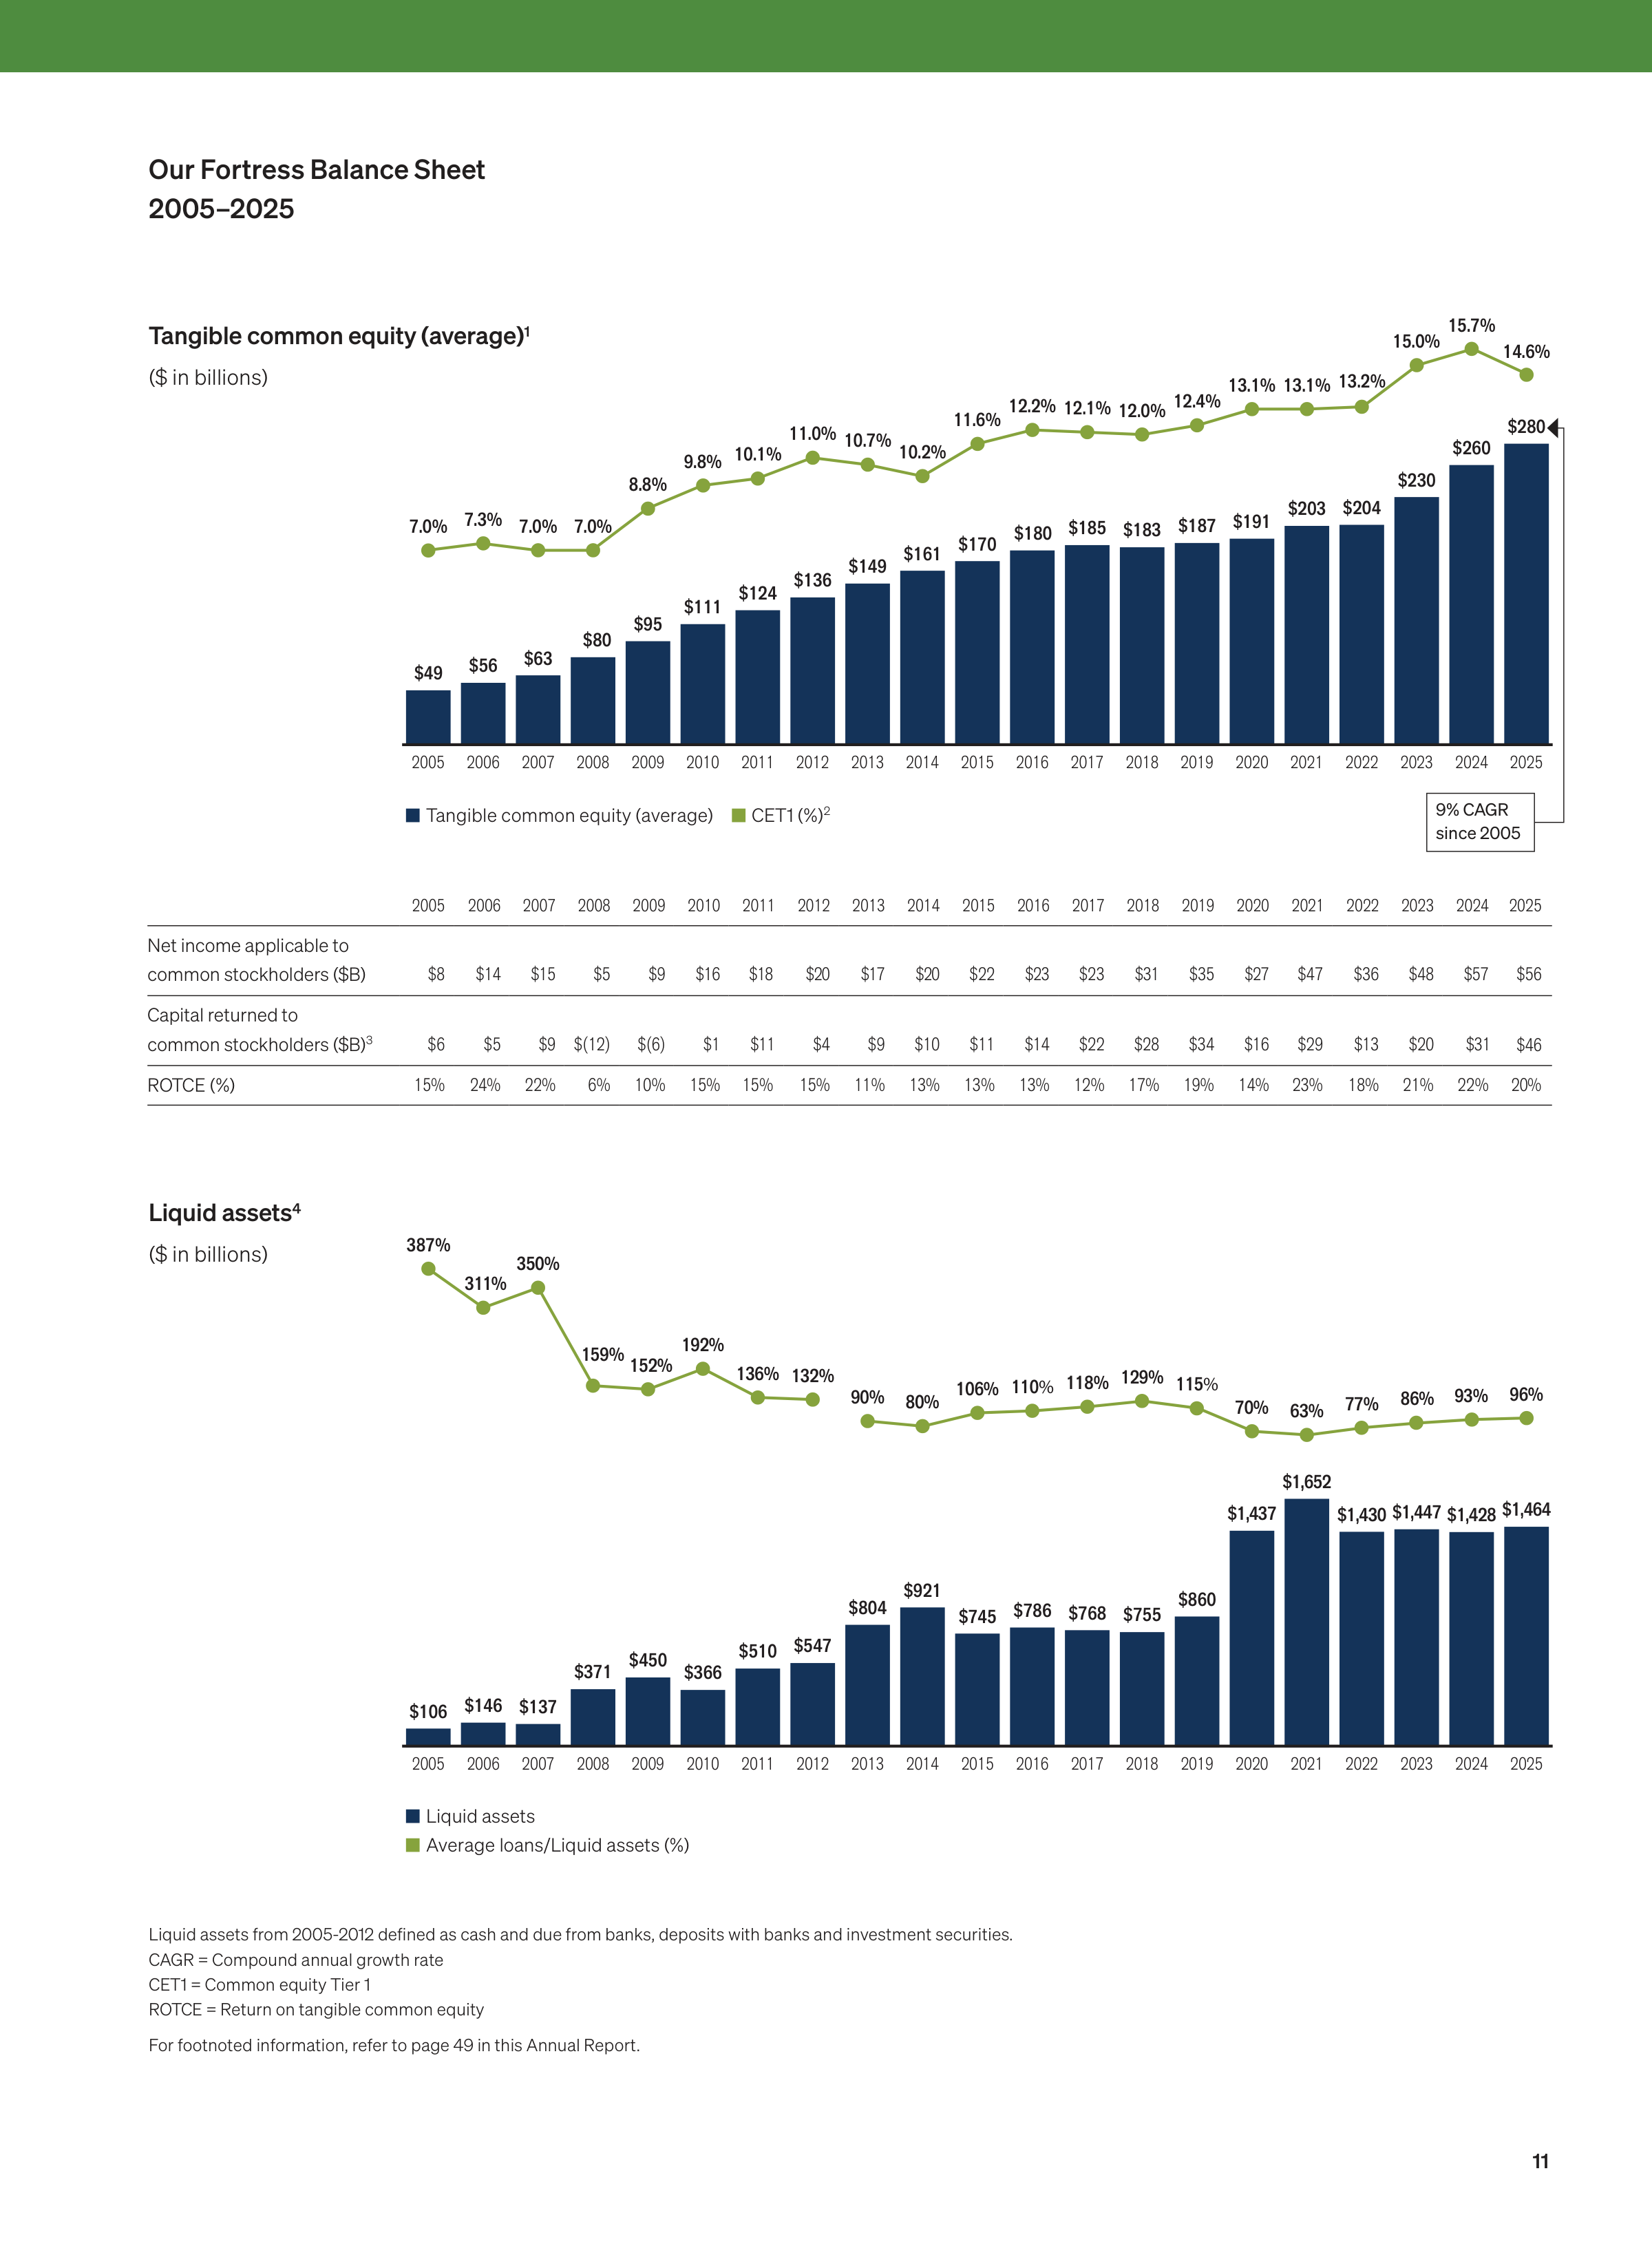
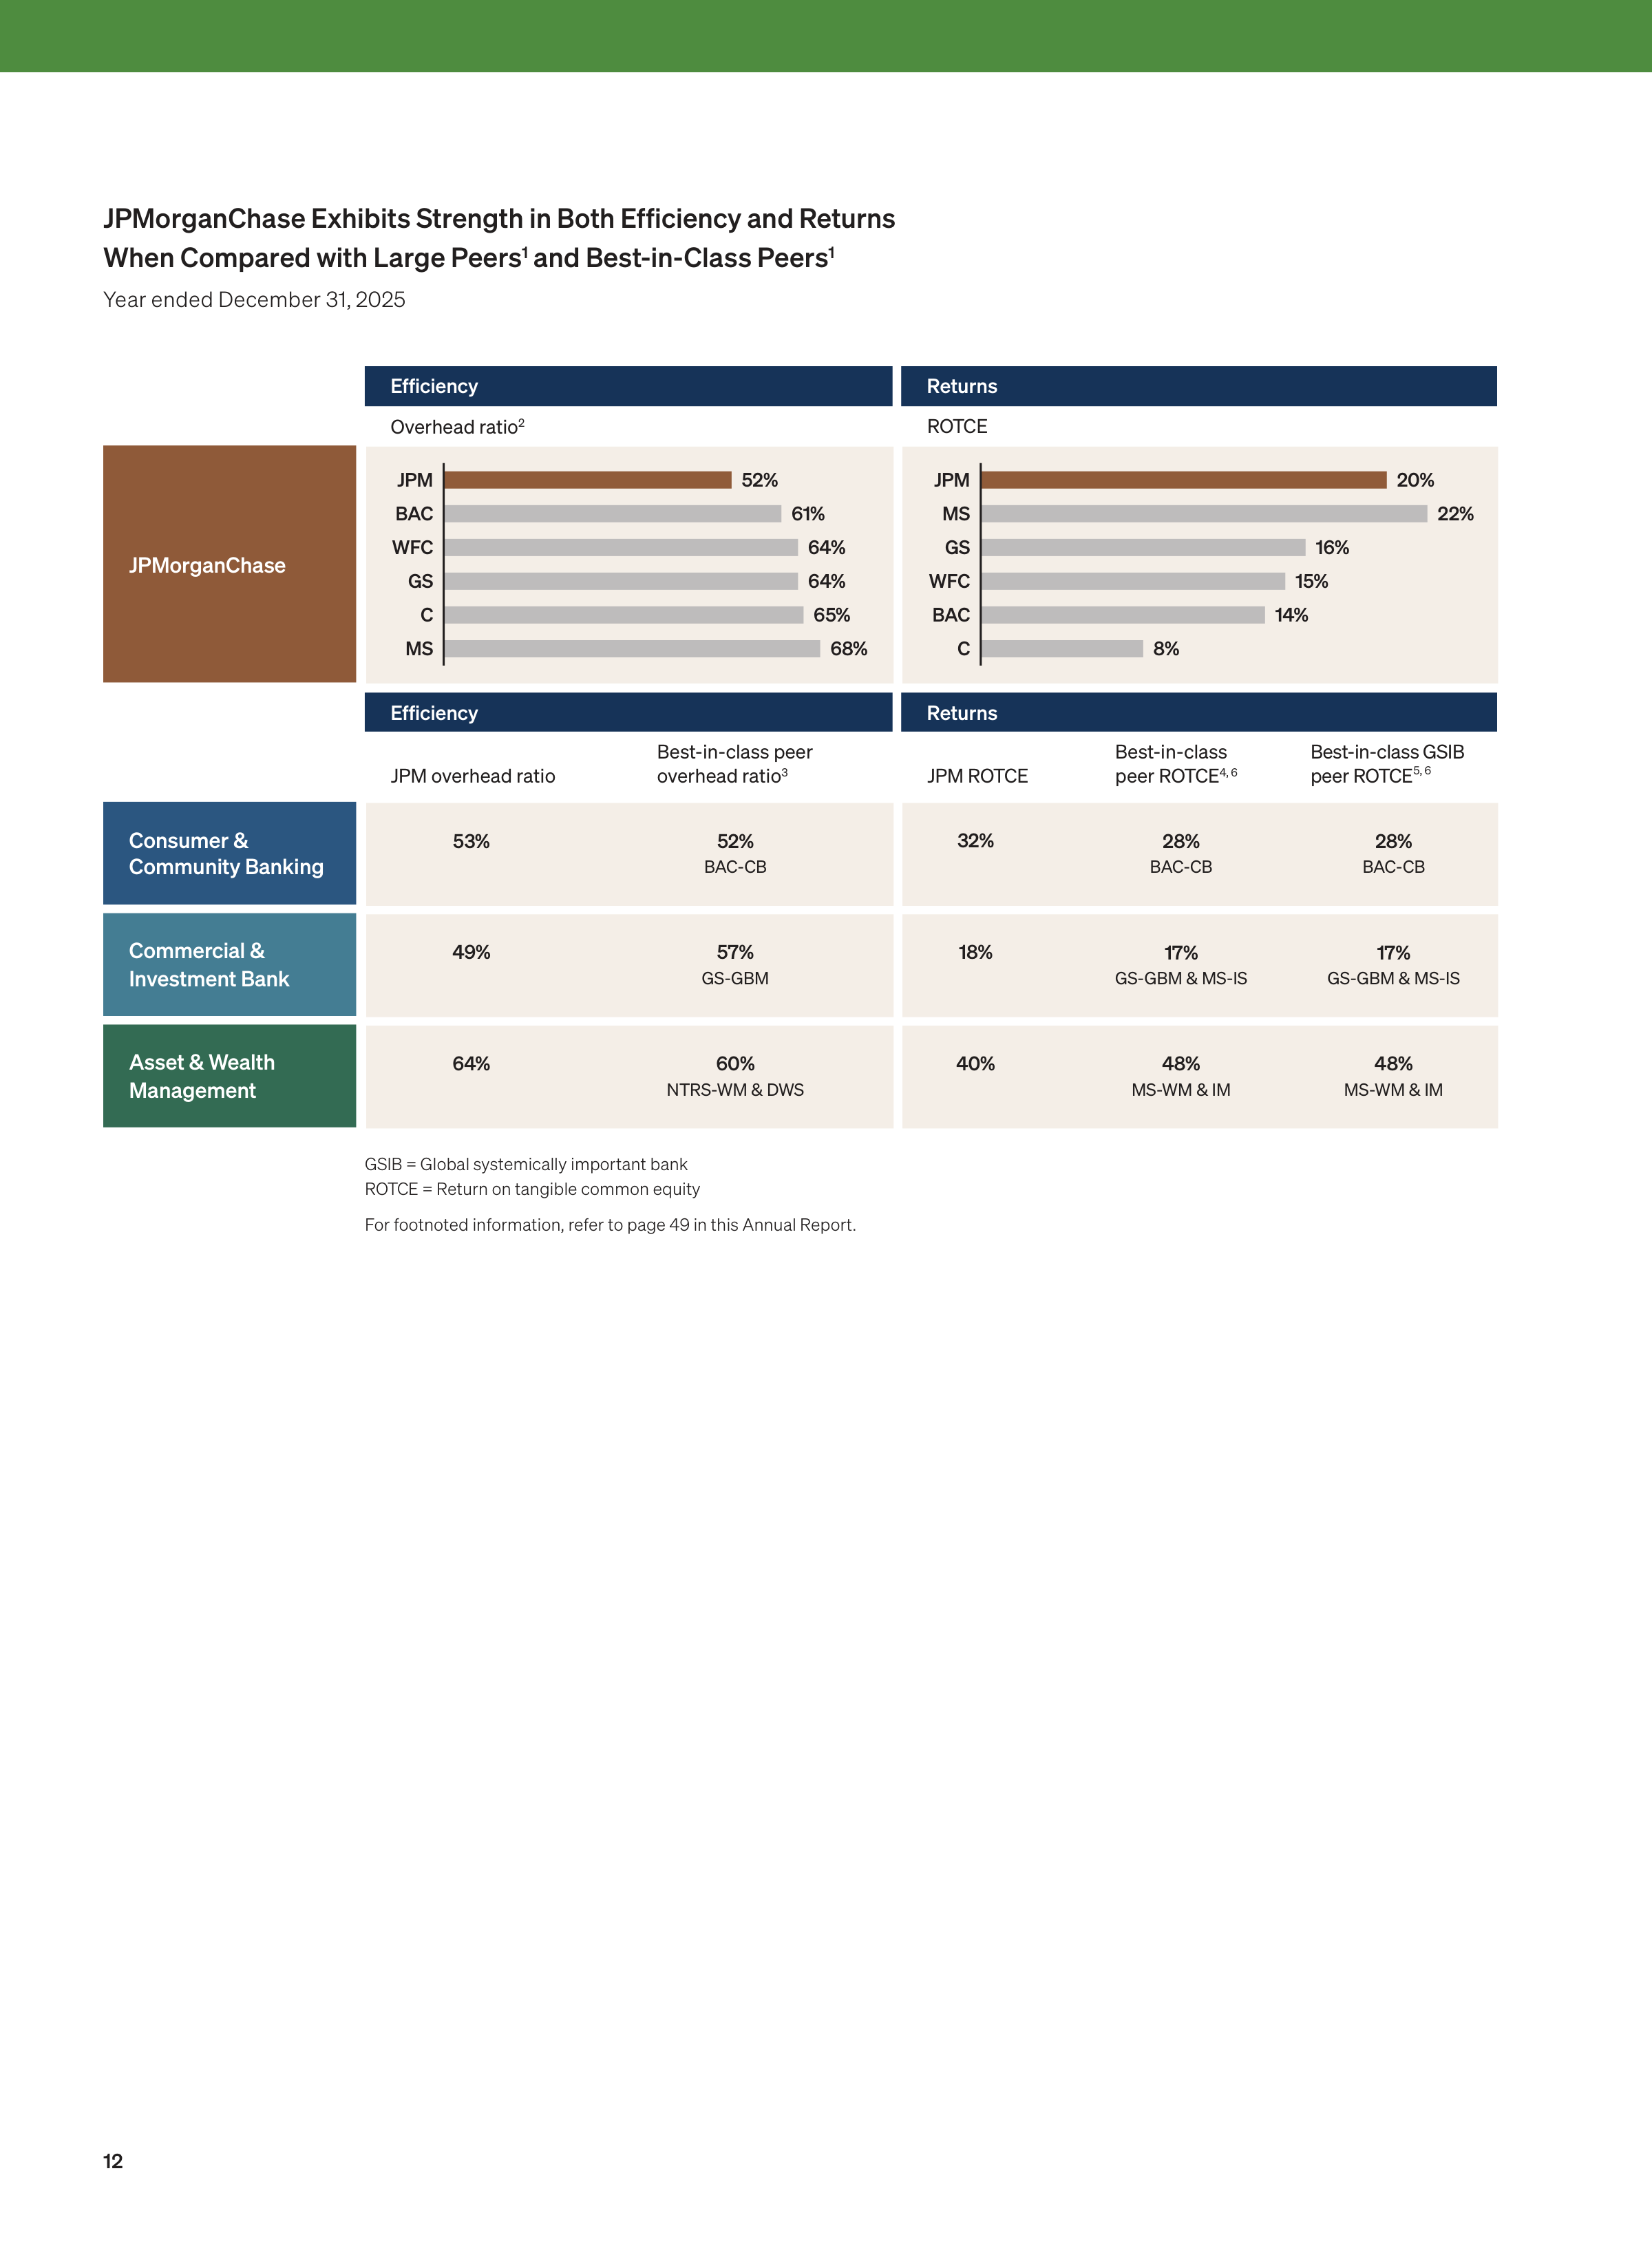
The charts on pages 6–12 show our performance results and illustrate how we
have grown our franchises, how we compare with our competitors and how we
look at our fortress balance sheet. Please peruse them and the CEO and COO
letters in this Annual Report, all of which provide specific details about our
businesses and our plans for the future.
In 2025, we continued to play a forceful and essential role in advancing economic
growth. In total, we extended credit and raised capital amounting to $3.3 trillion
for our consumer and institutional clients around the world. On a daily basis, we
move nearly $12 trillion in 120+ currencies and more than 160 countries, as well
as safeguard over $41 trillion in assets. Bank deregulation will make it easier for
financial institutions to support our growing economy, and, I believe, if properly
done, it can actually make the banking system safer. More on this in Section I.
Amidst the extreme challenges of the last two decades, we have never stopped
doing all the things we should be doing to serve our clients and our communities.
As you know, we are champions of banking’s essential role in a community — its
potential for bringing people together, for enabling companies and individuals to
attain their goals, and for being a source of strength in difficult times. We remain
as committed as ever to reaching out to all communities in an effort to create a
stronger, more inclusive economy.
We recently launched two ambitious initiatives, the Security and Resiliency
Initiative (described in detail in Sections I and IV) and the American Dream
Initiative (highlighted in Section I), both inspired by our resolve to offer our
expertise to help address the needs of our country and what’s best for all
Americans. We hope these commitments also demonstrate how business and
government leaders can work together to solve seemingly intractable problems.
These efforts are also commercial in nature — and they are no different from
what most businesses large and small are trying to do in towns across America.
I often remind our employees that the work we do matters and has impact. United
by our principles and purpose, we help people and institutions finance and
achieve their aspirations, lifting up individuals, homeowners, small businesses,
larger corporations, schools, hospitals, cities and countries in all regions of the
world. I remain proud of our company’s resiliency and of what our hundreds of
thousands of employees around the world have achieved, collectively and
individually. We owe them a great debt of gratitude.
4
INTRODUCTION
Steadfast principles worth repeating
Looking back on the past two+ decades
— starting from my time as Chairman
and CEO of Bank One in 2000 — there is
one common theme: our unwavering
dedication to help clients, communities
and countries throughout the world.
Clearly our financial discipline, constant
investment in innovation and ongoing
development of our people have
enabled us to achieve this consistency
and commitment. In addition, across the
firm, we uphold certain steadfast tenets
that are worth repeating.
First, our work has very real human
impact. While JPMorganChase stock is
owned by large institutions, pension
plans, mutual funds and directly by sin
gle investors, the ultimate beneficiaries,
in almost all cases, are individuals in our
communities. More than 100 million
people in the United States own stocks;
many, in one way or another, own
JPMorganChase stock. Frequently,
these shareholders are veterans, teach
ers, police officers, firefighters, health
care workers, retirees, or those saving
for a home, education or retirement.
Often our employees also bank these
shareholders, as well as their families
and their companies. Our management
team goes to work every day recogniz
ing the enormous responsibility that we
have to all of our shareholders.
Second, shareholder value can be built
only
if you maintain a healthy and
vibrant company, which means doing a
good job of taking care of your custom
ers, employees and communities.
Conversely, how can you have a healthy
company if you neglect any of these
stakeholders? As we have learned over
the past few years, there are myriad
ways an institution can demonstrate
compassion for its employees and its
communities while still strengthening
shareholder value.
Third, while we don’t run the company
worrying about the stock price in the
short run, in the
long run
we consider
our stock price a measure of our prog
ress over time. This progress is a func
tion of continual investments in our
people, systems and products, in good
and bad times, to build our capabilities.
These important investments also
drive our company’s future prospects
and position it to grow and prosper for
decades. Measured by stock perfor
mance, our progress is exceptional.
For example, whether looking back 10
years or even further to 2004, when the
JPMorganChase/Bank One merger
took place, we have outperformed the
Standard & Poor’s 500 Index and the
Standard & Poor’s Financials Index.
Fourth, we are united behind basic
principles and strategies (you can see
the principles for How We Do Business
on our website and our Purpose state
ment in
my letter from 2022
) that have
helped build this company and made
it thrive. These allow us to maintain a
fortress balance sheet, constantly
invest and nurture talent, fully satisfy
regulators, continually improve risk,
governance and controls, and serve
customers and clients while lifting up
communities worldwide. This philoso
phy is embedded in our company cul
ture and influences nearly every role in
the firm.
Fifth, we strive to build enduring busi
nesses, which rely on and benefit from
one another, but we are not a conglom
erate. This structure helps generate
our superior returns. Nonetheless,
despite our best efforts, the walls that
protect this company are not particu
larly high — and we face extraordinary
competition. I have written about this
reality extensively in the past and cover
it again in this letter. We recognize our
strengths and vulnerabilities, and we
play our hand as best we can.
Sixth, we must be a source of strength,
particularly in tough times, for our
clients and the countries in which we
operate. We must take seriously our
role as one of the guardians of the
world’s financial systems.
Seventh, we operate with a very
important silent partner — the U.S. gov
ernment — noting, as my friend Warren
Buffett points out, that his company’s
success is predicated upon the extraor
dinary conditions our country creates.
He is right to have said to his sharehold
ers that when they see the American
flag, they all should say thank you. We
should, too. JPMorganChase is a healthy
and thriving company, and we always
want to give back and pay our fair share.
We do pay our fair share — and we want
it to be spent well and have the greatest
impact.
To give you an idea of where our
taxes and fees go: In the last 10 years,
we paid more than $44 billion in federal,
state and local taxes in the United
States and over $30 billion in taxes out
side of the United States. Additionally,
we paid the Federal Deposit Insurance
Corporation (FDIC) over $13 billion so
that it has the resources to cover fail
ures in the American banking sector.
Our partner — the federal government
— also imposes significant regulations
upon us, and it is imperative that we
meet all legal and regulatory require
ments imposed on our company.
Eighth and finally, we know the founda
tion of our success rests with our
people. They are the front line, both
individually and as teams, serving our
customers and communities, building
the technology, making the strategic
decisions, managing the risks, deter
mining our investments and driving
innovation. However you view the world
— its complexity, risks and opportuni
ties — a company’s prosperity requires
a great team of people with guts,
brains, integrity, enormous capabilities
and high standards of professional
excellence to ensure its ongoing
success.
5
INTRODUCTION
6
Net income
Diluted earnings per share (EPS)
Return on tangible common equity (ROTCE)
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
$8.5
$15.4
$17.4
$19.0
$21.3
$17.9
$24.4
$21.7
$24.7
$14.4
$24.4
$32.5
$26.9
$38.4
$49.6
$53.0
$57.0
$48.3
$58.5
$36.4
15%
24%
22%
6%
10%
15%
15%
15%
11%
13%
13%
13%
17%
19%
14%
23%
18%
21%
22%
20%
12%
$4.00
$4.33
$1.35
$2.26
$3.96
$4.48
$5.19
$4.34
$5.29
$6.00
$6.31
$10.72
$15.36
$12.09
$16.23
$20.02
$19.75
$8.88
$9.00
$6.19
$2.35
$5.6
$11.7
$37.7
$39.1
$29.1
Net income
excluding TCJA
1
Net income
excluding reserve
release/build
2
ROTCE
excluding
TCJA
1
was 13.6%
for 2017
ROTCE excluding
reserve release/build
2
was 19.3% for 2020
and 18.5% for 2021
ROTCE excluding
Visa gain (net of
contribution)
3
was
19.9% for 2024
Net income
excluding Visa
gain (net of
contribution)
3
1
Adjusted net income excludes $2.4 billion from net income in 2017 as a result of the enactment of the Tax Cuts
and Jobs Act (TCJA). This is a non-GAAP financial measure.
2
Effective January 1, 2020, the Firm adopted the Financial Instruments – Credit Losses accounting guidance.
Firmwide results excluding the net impact of reserve release/(build) of $(9.3) billion and $9.2 billion for the years
ending December 31, 2020 and 2021, respectively, are non-GAAP financial measures.
3
Adjusted net income excludes $5.4 billion from net income in 2024 as a result of the net gain related to Visa
shares and the donation of Visa shares to pre-fund contributions to the Firm’s Foundation.
GAAP = Generally accepted accounting principles
Earnings, Diluted Earnings per Share and Return on Tangible Common Equity
2005–2025
($ in billions, except per share and ratio data)
7
Stock price range
1
Tangible book value
Average stock price
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
$60.98
$66.11
$71.53
$73.12
$86.08
$97.30
$107.56
$56.33
$16.45
$18.88
$21.96
$22.52
$27.09
$30.12
$33.62
$38.68
$40.72
$44.60
$48.13
$51.44
$53.56
$36.07
$43.93
$47.75
$39.83
$35.49
$40.36 $39.36
$39.22
$51.88
$58.17
$63.83
$65.62
$106.52
$155.61
$128.13
$144.05
$279.87
$110.72
$92.01
$113.80
$205.20
1 Stock price range reflects intraday high and low.
CAGR = Compound annual growth rate
10% CAGR
since 2005
High: $330.86
Low: $202.16
Stock total return analysis
Bank One
S&P 500 Index
S&P Financials Index
Performance since becoming CEO of Bank One
(3/27/2000–12/31/2025)
Compounded annual gain
14.1%
8.0%
6.1%
Overall gain
2,873.1%
621.6%
365.0%
JPMorganChase
S&P 500 Index
S&P Financials Index
Performance since the JPMorganChase and Bank One merger
(7/1/2004–12/31/2025)
Compounded annual gain
13.4%
10.8%
6.3%
Overall gain
1,380.5%
805.9%
270.5%
Performance for the period ended December 31, 2025
Compounded annual gain
One year
37.3%
17.9%
15.0%
Five years
23.7%
14.4%
15.2%
Ten years
20.4%
14.8%
13.1%
This chart shows actual returns of the stock, with dividends reinvested, for heritage shareholders of Bank One and JPMorganChase and Bank One vs. the Standard & Poor’s 500
Index (S&P 500 Index) and the Standard & Poor’s Financials Index (S&P Financials Index).
Tangible Book Value and Average Stock Price per Share
2005–2025
8
AUM = Assets under management
ETF = Exchange-traded funds
MSA = Metropolitan statistical area
USD = U.S. dollar
CB = Commercial Banking
FICC = Fixed income, currencies and commodities
NA = Not available
K = Thousands
DCM = Debt capital markets
GCB = Global Corporate Banking
NM = Not meaningful
M = Millions
ECM = Equity capital markets
GIB = Global Investment Banking
Swift = Society for Worldwide Interbank
B = Billions
EMEA = Europe, Middle East and Africa
JPMAM = J.P. Morgan Asset Management
Financial Telecommunications
T = Trillions
EOP = End of period
LT = Long-Term
For footnoted information, refer to pages 48–49 in this Annual Report.
2005
2015
2024
2025
Consumer &
Community
Banking
Average deposits ($B)
1
Deposits market share
2
# of top 125 markets where
we are top 3
Business Banking primary market
share
3
Client investment assets ($B)
1
Total payments volume ($T)
4
% of digital noncard payments
5
Credit card sales ($B)
Debit card sales ($B)
Debit and credit card sales volume ($B)
Credit card sales market share
6
Credit card loans ($B, EOP)
Credit card loans market share
7
Cards in force (M)
8
Active mobile customers (M)
# of branches
# of advisors
1
$187
4.5%
22
4.0%
NA
NA
~20%
$225
NA
NA
15%
$142
19%
NA
NA
2,641
NM
$531
8.1%
39
7.9%
$219
$1.9
52%
$496
$258
$754
21%
$131
16%
NA
22.8
5,413
2,931
$1,064
11.3%
50
9.7%
$1,088
$6.4
81%
$1,259
$546
$1,805
23%
$233
17%
111.7
57.8
4,966
5,755
$1,057
11.1%
48
9.5%
$1,270
$7.0
82%
$1,355
$586
$1,941
24%
$248
18%
116.5
61.7
5,083
6,049
Serve 86.6M U.S. consumers and 7.4M small
businesses
75M active digital customers
9
, including 62M active
mobile customers
10
Primary bank relationships for ~81% of consumer
checking accounts
#1 retail deposit share
#1 deposit market share position in 4 out of the 5
largest banking markets in the country (NY, LA, CHI
and DAL) while maintaining branch presence in all
48 contiguous U.S. states
#1 primary bank for U.S. small businesses
#2 in J.D. Power 2025 U.S. Wealth Management
Digital Experience Satisfaction Study among
full-service investors
11
#1 U.S. credit card issuer based on sales
6
#2 owned mortgage servicers as of 4Q25
12
#4 in J.D. Power Mortgage Servicers Satisfaction
Study
13
#3 bank auto lender for loan and lease financing
14
#2 in J.D. Power 2025 Digital Experience for
Customer Satisfaction Study among Non-Captive
Automotive Finance Lenders
15
Commercial &
Investment
Bank
Total Markets revenue
16
Market share
16
FICC
16
Market share
16
Equities
16
Market share
16
Global investment banking fees
17
Market share
17
Assets under custody ($T)
Average client deposits ($B)
18
Payments revenue ($B)
19
Payments revenue rank (share)
20
Firmwide average daily security
purchases and sales ($T)
# of top 75 MSAs with dedicated
teams
21
Average Banking and Payments
loans ($B)
22
Multifamily lending
23
# of Global Banking senior bankers
24
# of CB senior bankers
# of GCB senior bankers
# of GIB senior bankers
2006
#8
6.3%
#7
7.0%
#8
5.0%
#2
8.7%
$10.7
$220.8
$4.9
NA
NA
35
$117.0
#19
NA
NA
NA
NA
#1
9.3%
#1
9.8.%
#3
8.6%
#1
7.9%
$19.9
$586.8
$7.6
NA
NA
57
$227.6
#1
NA
NA
NA
NA
#1
11.4%
#1
11.0%
#2
12.2%
#1
9.1%
$35.3
$961.6
$18.1
#1 (9.5)%
$3.4
74
$348.8
#1
3,872
1,959
670
1,243
#1
11.8%
#1
11.1%
Co-#1
13.2%
#1
8.4%
$41.2
$1,097.6
$19.3
#1 (10.2)%
$4.3
74
$350.0
#1
4,171
2,117
703
1,351
>90% of Fortune 500 companies do business with us
On-ground presence in 179 locations in the U.S.
and 65 countries internationally, serving clients in
100+ markets
In 2025, extended $10B to create and preserve over
60K affordable housing units
#1 in global investment banking fees for the 17th
consecutive year and ranked #1 across ECM, DCM,
North America, EMEA and Latin America in 2025
17
Consistently ranked #1 in Markets revenue since
2011
16
J.P. Morgan Research ranked as the #1 Global
Research Firm, #1 Global Equity Research Team and
#1 Global Fixed Income Research Team
25
#1 in USD payments volume with 30.2% USD Swift
market share
26
#2 in U.S. Merchant volume processing
27
#1 in U.S. eCommerce Merchant processing volume
28
#3 Custodian globally by revenue
29
Banking and Payments services to approximately
36K Commercial & Specialized Industries
30
clients
and 23K real estate owners and investors
31
Approximately $2.7B revenue from Commercial &
Specialized Industries
30
expansion and nearly 3,000
new relationships in Commercial & Specialized
Industries
30
#1 Traditional Middle Market Bookrunner for full year
2025 with 20+ specialized industry coverage teams
32
Asset & Wealth
Management
JPMAM LT funds AUM performed
above peer median (10-year)
33
Client assets ($T)
34
Traditional assets ($T)
34, 35
Alternatives assets ($B)
34, 36
Average deposits ($B)
34
Average loans ($B)
34
# of Global Private Bank client
advisors
34
NA
$1.1
$1.0
$74
$42
$27
1,484
84%
$2.3
$1.9
$221
$145
$107
2,328
85%
$5.9
$5.2
$504
$235
$228
3,775
83%
$7.1
$6.3
$560
$245
$247
4,101
170 funds with a 4/5 star rating
37
Business with 55% of the world’s largest pension
funds and sovereign wealth funds
#2 in 5-year cumulative net client asset flows
38
#1 in active flows
39
Record client asset flows in 2025 of $553B,
positive across all regions and channels
#1 in active ETF flows and #1 in active ETF AUM
40
#1 in Institutional Money Market Funds AUM
41
#1 Private Bank in the World
42
Client Franchises Built Over the Long Term
9
1 In alignment with the business segment reorganization effective in the second quarter of 2024, Corporate Client Banking
activity was moved from Small Business, Middle Market and Commercial clients to Corporate clients starting in 2024.
2 Government, government-related and nonprofits available starting in 2019; included in Corporate clients and Small Business,
Middle Market and Commercial clients for prior years.
Corporate clients
Small Business, Middle Market and Commercial clients
1
Consumers
Government, government-related and nonprofits
2
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
$1,090
$165
$310
$1,120
$135
$245
$1,160
$165
$250
$1,390
$220
$250
$1,260
$1,520
$280
$310
$275
$275
$1,690
$400
$265
$1,620
$430
$260
$1,790
$480
$225
$1,350
$440
$225
$335
$290
$215
$250
$615
$590
$1,290
$465
$245
$260
$640
$1,930
$1,330
$205
$240
$270
$250
$510
$1,230
$1,770
$330
$1,440
$370
$235
$1,620
$325
$195
$1,500
$1,575
$1,860
$1,815
$2,105
$2,355
$2,310
$2,495
$2,350
$3,190
$2,410
$2,265
$2,800
$300
$280
$630
$2,060
$3,270
$2,260
$2,045
$2,140
$1,565
~$1,900 estimated
New and Renewed Credit and Capital for Our Clients
2005–2025
($ in billions)
10
1 Represents assets under management, as well as custody, brokerage, administration and deposit accounts.
2 Represents activities associated with the safekeeping and servicing of assets.
Client assets
Wholesale deposits
Consumer deposits
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
$1,883
$730
$398
$2,061
$755
$439
$2,329
$824
$464
$2,376
$861
$503
$2,353
$2,427
$722
$757
$558
$618
$3,255
$3,617
$3,740 $3,633
$3,802
$3,781
$4,240
$1,186
$1,209
$959
$1,132
$5,926
$6,580
$7,643
$1,487
$1,073
$10,203
$6,383
$1,349
$1,057
$8,789
$5,292
$1,306
$1,095
$7,693
$4,488
$1,314
$1,148
$6,950
$3,258
$844
$718
$4,820
$2,740
$792
$679
$4,211
$2,783
$784
$660
$4,227
$3,011
$1,881
$558
$372
$2,811
$1,743
$573
$365
$2,681
$1,415
$648
$361
$2,424
$1,513
$520
$221
$2,254
$1,296
$425
$214
$1,935
$1,107
$364
$191
$1,662
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
$16.9
$18.8
$20.5
$13.2
$10.7
$13.9
$15.9
$14.9
$16.1
$20.5
$19.9
$20.5
$23.5
$23.2
$26.8
$33.2
$32.4
$41.2
$35.3
$31.0
$28.6
Assets Entrusted to Us by Our Clients
2005–2025
Deposits and client assets
1
($ in billions)
Assets under custody
2
($ in trillions)
11
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
$124
$136
$149
$80
$56
$49
$63
$95
$111
$161
$170
$180
$185
$183
$187
$203
$230
$260
$280
$191
$204
10.1%
11.0%
10.7%
7.3%
7.0%
7.0%
7.0%
8.8%
9.8%
10.2%
11.6%
12.2%
12.1%
12.0%
12.4%
15.0%
15.7%
14.6%
13.1%
13.1%
13.2%
Tangible common equity (average)
CET1 (%)
2
Liquid assets
Average loans/Liquid assets (%)
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
2010
2009
2008
2007
2006
2005
90%
132%
136%
192%
152%
159%
350%
387%
80%
106%
129%
86%
93%
96%
70%
63%
77%
311%
110
%
118%
115
%
$804
$547
$510
$366
$450
$371
$137
$146
$106
$921
$745
$786
$768
$755
$860
$1,652
$1,447 $1,428
$1,464
$1,437
$1,430
9% CAGR
since 2005
2005
2006
2007
2008
2009
2010
2011
2012
2013
2014
2015
2016
2017
2018
2019
2020
2021
2022
2023
2024
2025
Net income applicable to
common stockholders ($B)
$8
$14
$15
$5
$9
$16
$18
$20
$17
$20
$22
$23
$23
$31
$35
$27
$47
$36
$48
$57
$56
Capital returned to
common stockholders ($B)
3
$6
$5
$9
$(12)
$(6)
$1
$11
$4
$9
$10
$11
$14
$22
$28
$34
$16
$29
$13
$20
$31
$46
ROTCE (%)
15%
24%
22%
6%
10%
15%
15%
15%
11%
13%
13%
13%
12%
17%
19%
14%
23%
18%
21%
22%
20%
Liquid assets from 2005-2012 defined as cash and due from banks, deposits with banks and investment securities.
CAGR = Compound annual growth rate
CET1 = Common equity Tier 1
ROTCE = Return on tangible common equity
For footnoted information, refer to page 49 in this Annual Report.
Our Fortress Balance Sheet
2005–2025
Tangible common equity (average)
1
($ in billions)
Liquid assets
4
($ in billions)
12
Efficiency
Returns
Overhead ratio
2
ROTCE
JPMorganChase
Efficiency
Returns
JPM overhead ratio
Best-in-class peer
overhead ratio
3
JPM ROTCE
Best-in-class
peer ROTCE
4, 6
Best-in-class GSIB
peer ROTCE
5, 6
Consumer &
Community Banking
53%
52%
BAC-CB
32%
28%
BAC-CB
28%
BAC-CB
Commercial &
Investment Bank
49%
57%
GS-GBM
18%
17%
GS-GBM & MS-IS
17%
GS-GBM & MS-IS
Asset & Wealth
Management
64%
60%
NTRS-WM & DWS
40%
48%
MS-WM & IM
48%
MS-WM & IM
GSIB = Global systemically important bank
ROTCE = Return on tangible common equity
For footnoted information, refer to page 49 in this Annual Report.
68%
65%
64%
64%
61%
52%
MS
C
GS
WFC
BAC
JPM
8%
14%
15%
16%
22%
20%
C
BAC
WFC
GS
MS
JPM
JPMorganChase Exhibits Strength in Both Efficiency and Returns
When Compared with Large Peers
1
and Best-in-Class Peers
1
Year ended December 31, 2025
Page 2
Page 5
Page 14
Page 14
Page 14
Page 15
Page 17
Page 19
Page 20
Page 23
Page 24
Page 25
Page 25
Page 25
Page 25
Page 27
Page 28
Page 28
Page 28
Page 31
Page 31
Page 34
Page 34
Page 34
Page 36
Page 39
Page 41
Page 45
Page 47
Introduction
. . .
. .
.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
— Steadfast principles worth repeating . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
I.
Specific Issues Facing Our Company
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
We are confronted with extraordinary global competition from both traditional and new challengers.
•
We’re addressing those challengers as part of our expansion plans.
. .
. . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
We continue to roll out exciting new initiatives.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
—
Investing in Alabama
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
We believe we can deploy our excess capital over time at good returns.
. . . . . . . . . . . . . . . . . . . . . . . . . . .
•
Well-designed bank regulations can make the system safer, simpler and more customer-friendly
as they help free up capital and liquidity for productive use.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
AI, data and technology are key to the future, as is solving for how to implement AI properly and fast.
•
Cities — like individuals, companies and countries — need to compete.
. . . . . . . . . . . . . . . . . . . . . . . . . .
II.
Management Learnings
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
It’s essential to organize in small teams for super speed.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
Teams require great platforms across the company.
•
Building a lasting, deeply rooted and common culture is critical — and it takes an extraordinary
amount of effort.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
JPMorganChase is a powerful neural network.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
III.
Managing in a Time of Increasing and Complex Risks
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
We manage “through the cycle.”
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
Many factors are dramatically different in the global economic and financial system than in 2010 —
many better but some possibly worse.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
There are lots of tailwinds helping us in 2026.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
There are large risks still in front of us that are multi-year and unresolved.
. . . . . . . . . . . . . . . . . . . . . . . . .
IV.
Critical Issues Facing America and the World
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
JPMorganChase and companies across the public and private sectors have an important and
unique role in addressing global challenges.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
We need the world’s strongest military — what we can do to help: our new Security and
Resiliency Initiative.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
The foundation of America’s strength is predicated on remaining the preeminent economy in the
world — what we can do to help: promote growth policies.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
Reigniting the American Dream is essential to strengthening our country: taking three specific
steps can help.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
Good U.S. foreign economic policy ensures that America is first (though not alone) — it strengthens
the U.S. economy and that of our critical allies.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
•
We need to strengthen our commitment to the values and virtues that created America and to the
Constitution, which embeds these values in law.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
In Closing
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Within this letter, I discuss the following:
13
serving people and businesses needing to hold
money, move money, invest money, raise money
and manage their investments — new competi
tors and new technologies may change the
fundamental nature of
how
all this is done.
We’re addressing those challengers as
part of our expansion plans.
While the competition is fierce, we do believe
in most cases we will be able to sustain our
top-ranking performance. In the section on
management learnings, I discuss what we need
to do as a management team to ensure our
ongoing success.
We continue to see growth opportunities in
almost all our businesses.
Some of our growth opportunities are basic
and exist in every detailed segment level. In
Consumer & Community Banking (CCB), we
continue to add, train and enable bankers and
advisors to serve more clients. We’re expanding
our branch network to capture share in under
penetrated markets, including more
rural
markets
across the country. And we’re investing
in marketing and product refreshes to drive card
account growth, as well as scaling natural adja
cencies in wealth management and commerce
to address more of our customers’ needs. In the
Commercial & Investment Bank (CIB), we’re
expanding to more countries and regions, secur
ing growth in private markets and building upon
our capabilities in global payments and digital
assets. And in Asset & Wealth Management
(AWM), we are continuing to invest in our active
management capabilities, enhancing our alter
natives and exchange-traded fund platforms,
expanding our international footprint and adding
Global Private Bank advisors.
You can read about these plans more specifi
cally in the CEO letters.
14
14
SPECIFIC ISSUES FACING OUR COMPANY
I. Specific Issues Facing Our
Company
The last five years have been a period of signifi
cant growth for us — as evidence, we added
more than 60,000 people to our workforce, we
opened over 900 branches across the United
States, and we launched multiple new products
and services. In the following section and in the
letter by our Chief Operating Officer, we share
various ways we seek to keep our company
healthy, including specific efforts designed to
maintain our grit, our leading position and our
efficiency. We are keenly aware that our compe
tition around the world is always gaining.
We are confronted with extraordinary
global competition from both
traditional and new challengers.
Our shareholders should recognize, as we do,
that our company faces strengthened tradi
tional competitors, including large banks in the
United States, regional banks, strong interna
tional banks, large and successful money man
agers, and strong investment banks.
As I’ve detailed in previous letters, our rivals
increasingly include a large and growing set of
nontraditional and fintech competitors globally
in areas such as payments, digital banking and
investing, and global market making. I’m not
going to mention all their names, but you can
imagine that we study and track over a hundred
of them.
While we have been able to grow, many but not
all of the new players have been quite success
ful and continue to raise both money and their
ambitions. In addition, a whole new set of
competitors is emerging based on blockchain,
which includes stablecoins, smart contracts
and other forms of tokenization.
Our ongoing success will be based on our
ability to wisely invest and move very quickly
and nimbly, especially around product design
and rollout, including incorporating artificial
intelligence (AI) in everything we do. While
much of what we do will remain the same —
Our ongoing success will require us to up
our game — and in multiple ways.
We need to do a better job of utilizing our data
to help the customer. We must develop prod
ucts quicker and always look at the adjacencies
that can make a customer’s life easier. We need
to roll out our own blockchain technology and
continually focus on what our customers want in
a very detailed way.
We need to maximize the benefits of our
scale and scope, which are necessary to our
largest institutional and government clients,
while minimizing their considerable
negatives.
Size can often be a tremendous business disad
vantage because it frequently comes with the
baggage of complexity, bureaucracy and com
placency. It can slow down decision making,
generate arrogance and cloud the essential
focus on seeing the world through the custom
er’s eyes. Being a company of sizable magni
tude makes it easier to ignore new competitors
since they often start small in one product but
move rapidly to expand. The most successful
examples of these are Block, Citadel Securities,
Revolut and Stripe.
However, scale, capital and capabilities are
going to matter
more
with the enormous invest
ments that need to be made in global infra
structure — technology, new supply chains,
AI and enhancements that meet government
needs. In some of these cases, our size, capital
and capabilities can be a relatively good com
petitive advantage.
We continue to roll out exciting new
initiatives.
They are outlined as follows:
Our Security and Resiliency Initiative is
critical to national and global security.
Our Security and Resiliency Initiative (SRI) is
already well underway and, in fact, will help us
grow. It is explained in greater detail in the last
section of this letter but, broadly speaking,
describes our deployment of capital and exper
tise to support industries critical to the military
and economic security of the United States and
its partners. We have a lot to catch up on and
not much time
.
Reigniting the American Dream is also
essential — and it drives growth as well.
I continue to believe the American Dream is
alive, but it’s slipping out of reach for too many
people — and it’s now affecting generations of
families. This slows economic growth, hurts
communities and prevents many people from
getting ahead. Further, it deeply damages
Americans’ faith and confidence in their country.
That is why JPMorganChase recently
announced the American Dream Initiative (ADI)
— a firmwide multi-year effort to expand
opportunity to millions of Americans through
targeted investments in local communities
across the United States. It builds on our firm’s
years of experience of investing in local solu
tions that work.
We will focus on six areas where we have deep
expertise that helps drive meaningful impact:
Business growth and entrepreneurship:
Increase access to capital, advice, training
or tools for 10 million small businesses.
Housing access and affordability:
Improve
affordability for hundreds of thousands of
renters and buyers through increased hous
ing supply and homeownership opportunities.
15
15
SPECIFIC ISSUES FACING OUR COMPANY
Financial health and wealth creation:
Expand
access to financial education, banking prod
ucts, services and digital financial health
tools — scaling financial education efforts to
reach approximately 5 million cumulative
customers, students and small businesses,
up from 1 million served over the past five
years.
Careers and skills:
Broaden access to skills-
based training through policy and hiring
opportunities, including for JPMorganChase
employees.
Healthcare:
Support efforts that offer better
access to healthcare, as well as promote
better health outcomes, affordability and
transparency for all Americans.
Local institutions:
Provide more financing
and support for thousands of schools, hospi
tals, nonprofits and local governments
critical to community success across the
United States.
We are starting by supporting 10 million small
businesses — up from 7 million served today —
over the next several years. As the nation’s
leading small business bank, we intend to scale
support for small businesses by deploying
increased capital and providing more financial
coaching, advice, training and tools.
We’re also taking the American Dream to the
local level — and our presence in Detroit proves
that point. When we went there in 2014, we
looked at what the city needed and how invest
ments from our firm could make a meaningful
difference, targeting areas where we could
make the greatest impact. We must continue
these efforts, learning from successes like
Detroit. That city spawned many initiatives
at our company (think our Service Corps and
Advancing
Cities), but most important, it
showed how proper
collaboration
between
business and government can help to tackle
some of our biggest problems.
Now we want to replicate and scale what works.
ADI will be nationwide with a particular focus on
amplifying impactful work already happening
in certain markets, such as Alabama, Atlanta,
Los Angeles, Philadelphia and San Francisco.
Please read the sidebar, which shows how we’re
going deep and local in Alabama.
We need to support policies that create jobs,
foster upward mobility and ensure everyone
has a fair shot. This could go a long way to solv
ing affordability challenges, too. Jobs create
dignity and self-worth — and attaining that first
rung almost always leads to the second, which,
in turn, fosters many positive social outcomes.
The dream of enjoying freedom, taking care
of your family, experiencing good health and
making the most of opportunity is not just an
American aspiration, it’s a global one.
16
16
SPECIFIC ISSUES FACING OUR COMPANY
For over 50 years, JPMorganChase has helped drive
economic and job growth, support businesses of all
sizes and put the American Dream within reach for
more Alabamians. It’s clear that Alabama’s future is
bright, and we are excited for what’s next.
We’ve been working hand in hand with local govern
ments, businesses and community partners to under
stand how we can best use JPMorganChase’s full range
of resources to complement their efforts. I was hon
ored to meet with many of these leaders during our bus
tour through Alabama last summer. The state’s expan
sive economic growth has opened up immense oppor
tunity for the residents and businesses of Alabama.
We proudly serve more than 590,000 Consumer
Banking customers, helping them buy homes and save
for the future. We bank over 29,000 small businesses
statewide, as well as key institutions like Auburn
University, the University of Alabama, Children’s Hospi
tal of Alabama and Infirmary Health System, among
others. We also finance critical infrastructure, including
a recent $730 million Alabama Highway Authority bond
for the West Alabama Corridor project.
This year we are deepening our efforts in Alabama as
part of our recently announced American Dream Initia
tive. This includes new programs and ideas that you’ll
hear more about in the coming weeks and months,
such as:
Strengthening small businesses by expanding
access to capital and providing expert advice,
helping them compete for supply chain contracts
and other opportunities.
Equipping individuals to secure in-demand jobs in
Alabama’s growing sectors, working with employers,
colleges and other local partners to accomplish this.
Helping families achieve their financial goals with
new digital tools and education programs.
Many of these efforts align with our Security and
Resiliency Initiative, a $1.5 trillion, 10-year plan to
facilitate, finance and invest in industries critical to
national economic security and resiliency. We expect
this to benefit companies, workers and communities
in Alabama, a leader in advanced manufacturing,
aerospace and defense.
Supporting local businesses
Small and midsized businesses are the backbone of the
state’s economy — the former alone employ nearly half
of Alabama’s private sector workers. JPMorganChase
will continue to help local entrepreneurs and busi
nesses, like Astrion, headquartered in Huntsville, at
every stage of their growth secure access to capital,
supply chain opportunities and other essential
resources to thrive.
This includes a recent $2 million philanthropic invest
ment to launch the Alabama Capital Access Collabora
tive aimed to help small businesses gain improved
access to capital and achieve greater efficiencies, as
well as assist local community development finance
institutions and other community lenders in improving
their lending, investing and operational capacity.
Moving forward, we’re helping local small businesses
overcome barriers to serving as suppliers in Alabama’s
growing aerospace, defense and government indus
tries by providing mentorship, capital and upskilling to
compete for supply chain contracts. It can be costly
and difficult for smaller companies to meet the require
ments, including cyber readiness.
Additionally, we’re expanding our team of senior busi
ness consultants in branches across Alabama and pro
viding more coaching and expert guidance on business
planning, financial management and marketing.
Connecting Alabama workers to high-growth
industries
A prosperous job market is the foundation of a strong
economy — and in Alabama, demand is high for skilled
workers, especially those who can perform technical
work in the industries that are vital for America’s secu
rity and local economic growth.
With our support, the nonprofit Alabama Possible is
working with community colleges to expand eight
career advancement programs for adult learners in
aviation, steel and aerospace. They’re also partnering
with Alabama Power to support two accelerated
training programs for HVAC technicians and utility
line workers.
Investing in Alabama
17
17
SPECIFIC ISSUES FACING OUR COMPANY
As we do more in Alabama, we intend to partner with
additional community colleges and universities, busi
ness leaders, and groups that serve communities large
and small to better connect local workers and employ
ers. This includes expanding access to skills and job
opportunities for veterans and strengthening appren
ticeship pathways.
Expanding access to banking services
We’re working to help more Alabamians save money,
build credit and achieve their financial dreams.
We are opening new branches in Decatur, Foley and
Trussville this year as part of our plan to triple the num
ber of Chase branches to 35 by 2030. We will also open
our first Community Center in the state, which is
designed with extra space for community events,
financial health workshops, skills training and small
business pop-ups.
This effort will create more than
170 new jobs and help over 50% of the state’s citizens
reside within an accessible drive of a Chase branch.
Through Chase Money Skills, Chase Secure Banking
SM
and Chase First Banking
SM
, we’re also helping people
access digital financial tools and affordable banking
products. Through our Birmingham-based Community
Manager, we’re offering additional financial education
and expanding our partnerships with community orga
nizations and colleges. These collective efforts help
with ways to boost credit scores and put residents on
a pathway to homeownership.
By doing more in Alabama, we’re not just investing in
the state’s economic future — we’re helping to secure
America’s long-term economic resilience and security,
with Alabama’s people and industries leading the way.
Serving Alabama since 1973
Our footprint includes:
Serving our clients and customers
~280 medium and large clients
$15+ billion in credit and capital provided to medium
and large clients since 2021
590,000+ customers supported with mortgages,
auto loans, and savings, checking and credit card
accounts
29,000+ small business customers
14 branches across the state, growing to 35 by 2030
Serving local institutions
17 government, higher education, healthcare and
nonprofit clients throughout the state
$5.1 billion in credit and capital provided to govern
ment, higher education, healthcare and nonprofit
clients throughout the state since 2021
30+ regional, midsized and community banks
provided services, helping them serve local
communities
$155 million in credit and capital extended to finan
cial institutions, such as local and regional banks,
since 2021
$55+ million in financing for affordable housing con
struction and preservation in Alabama since 2020
$730 million Alabama Highway Authority bond
to advance the West Alabama Corridor project,
widening the highway to four lanes and creating
better access to services like healthcare, education
and jobs
Serving the local economy and communities
150 company employees throughout the state, pro
viding full-time employees with a minimum annual
pay of $41,600 (plus an average annual benefits
package worth over $21,000), compared with the
statewide per capita income of nearly $36,100
$9.5+ million contributed to the Alabama economy
through goods and services purchased by the firm
in 2025
$6.5 million in philanthropic support provided since
2019
18
18
SPECIFIC ISSUES FACING OUR COMPANY
We will be building new products to make
us an even greater trusted partner.
We are an extremely trusted partner in a world
of growing distrust, particularly in the spheres
of social media, commerce and use of data and
where these intersect. There are a lot of risks
associated with the misuse of customer data
and commerce, which is likely to get far worse
with AI and agentic commerce. We think there
are large opportunities for us to act on behalf of
our customers and in the way they want — as a
truly trusted partner. We are continually improv
ing our already strong capabilities to combat
scams and fraud. We expect to roll out some
products over the next two years that will build
on what we already offer, particularly around
control of personal data, safe commerce and
customer-friendly algorithms. We also believe
that some of our identity and fraud prevention
capabilities can be extended to more third
parties.
We continue to bring all our clients,
regardless of size, best-in-class money
management tools.
We have continued to grow our Wealth Manage
ment business through our branch bank model,
J.P. Morgan advisors and Self-Directed Investing.
In total, client investment assets in this area
rose 17% in 2025 to $1.3 trillion. In 2026, we
intend to make it much easier for clients to
automatically
move money from their regular
checking account to higher-yielding brokerage
products and vice versa so they can maximize
yield while managing day-to-day cash flow. It
won’t require multiple steps to trade, clear and
transfer cash between accounts — our Smart
Cash capability will do it for them. Eventually,
AI will allow clients to predict cash flow needs
and anticipate upcoming bills, doing their
budgeting for them.
In 2026, we have also rolled out what we
believe is
best-in-class retail trade execution
— basically giving consumers access to the
same execution capability that the largest,
most sophisticated investors in the world
enjoy, which saves them money. We believe
this is better than the execution provided
when a broker is paid for order flow.
We now offer Special Advisory Services
to our key clients.
With clients facing unprecedented change,
uncertainty and opportunity, we recognize that
the traditional role of a banker is changing. In
navigating complex challenges, clients are often
seeking guidance far beyond typical financial
advice. We’re commonly asked, “How does
JPMorganChase approach this? How are you
preparing for that? How do you protect the firm?
How do you ensure operational resiliency?”
Special Advisory Services allows us to formally
connect clients with our in-house experts leading
critical areas such as AI, cybersecurity, digital
assets, geopolitics, government affairs, real
estate, risk strategy, supply chain and talent man
agement. This means our clients can draw on the
same expertise and insights that guide our own
firm through today’s most complex challenges.
Whether a client is preparing for a major IPO,
planning a transformational deal or looking to
grow their business with us as their primary
bank, our commitment is to be there every step
of the way. Sharing insights and best practices
with them across so many aspects of their com
pany can help them run a better business. It’s
also one more way we can demonstrate our
dedication to the client, understanding their
challenges and strengthening our value as their
partner for years to come.
We used to offer these services on an ad hoc
basis, often by request. Now we intend to
extend these extraordinary services further to
companies that have a long-term relationship
with us; i.e., we are one of their lead banks and
have trusted relationships with their C-suite and
board members.
We believe we can deploy our excess
capital over time at good returns.
Our excess capital, making many assumptions
around regulatory reform, is approximately $40
billion. This $40 billion is effectively earning a
4% after-tax return. We now believe that over
time we can deploy it at excellent returns. We
will do this with our normal careful building of
important customer relationships, which also
means that it may take several years or so to
deploy this capital.
19
19
SPECIFIC ISSUES FACING OUR COMPANY
In the meantime, we continue to pay healthy and
increasing dividends. And we also continue to
buy back enough stock so as not to increase
total excess capital, though we have a number
of options on how to deploy our capital and are
clear-eyed that many asset prices, including
bank stocks, are fully valued. We always prefer
to deploy capital, if possible, and when we do
that through share repurchases, we want it at
prices that enhance the value for our ongoing
shareholders.
Some of our excess capital is effectively
deployed when we build new branches or hire
new bankers, even though it is treated as an
expense. We believe that the initiatives listed
above and outlined in the CEO letters are
effective uses of our deployable capital.
Well-designed bank regulations
can make the system safer, simpler
and more customer-friendly as they
help free up capital and liquidity for
productive use.
A properly regulated banking system helps
reduce risk to the financial system, protect
customers, and maximize productive use of
capital and lending. The Dodd-Frank Wall Street
Reform and Consumer Protection Act and some
of the rules that followed that legislation accom
plished some good things. At the same time,
they also created a fragmented, slow-moving
system with expensive, overlapping and exces
sive rules and regulations — some of which
made the financial system weaker and reduced
productive lending. Those regulations also
created many rules and requirements that had
nothing to do with safety and soundness, and in
fact often took the regulators’ eyes off the real
risk. The real risks almost always end up being
credit, liquidity, interest rate or operational risk.
Many of the financial rules that were put in place
did not originate from a clear idea about what
they should be or what they should accomplish,
which led to unintended consequences. Addi
tionally, rules were often inconsistent from reg
ulating body to regulating body — and many
regulators were independently involved in so
many regulations that they lacked an ability to
make rapid or coordinated changes as needed.
Of course, this was also very difficult for them.
I am going to talk further about some of the
negative consequences of bad bank regula
tions, but I also hope to provide some real
solutions.
One other flaw of the banking regulations is that
they were legislated in a way that made them
open to completely different interpretations
depending on your political point of view. As
agency leadership changes, this has the effect
of creating ping-pong regulations. It would be
very helpful if legislators wrote more clearly
crafted regulations across the board that mini
mized the risk of dramatically different political
interpretations.
Here are some of the negative consequences
partially due to poor bank regulations.
Because capital requirements on banks are
much higher than the market gives to private
entities, insurance companies or even foreign
banks, huge arbitrage is created. This is
often a sign of potential risk.
Regulators wrongly incorporated an
accounting concept called “held to maturity”
(HTM) into the capital rules, thereby giving
Treasury and mortgage securities better
capital treatment because the holder has
promised not to sell them. This had many
negative consequences — it allowed banks
to not recognize mark-to-market losses on
those securities in their regulatory capital,
and in some cases, it falsely increased
returns on those securities (because the
amount of regulatory capital needed to be
held against them was significantly smaller).
This inadvertently encouraged banks to take
on more interest rate risk, which was the ulti
mate trigger for the failure of Silicon Valley
Bank (SVB) and First Republic Bank (FRB).
The Fed’s Comprehensive Capital Analysis
and Review (CCAR) stress test, as currently
constructed, produces results that are far
worse, in our strongly held opinion, than what
our actual results would be under those
severely adverse conditions. The process
is flawed, including reliance on inaccurate
models and assumptions and the fact that it
tests only one type of crisis, so other scenar
ios are overlooked (e.g., rapid rises in interest
rates, as in the case of SVB and FRB). Testing
20
20
SPECIFIC ISSUES FACING OUR COMPANY
should use accurate numbers and assump
tions — then the results are what they are —
rather than being driven by predetermined
“what-ifs.” More transparency and sound
methodology would lead to continuous
improvement, not gaming the system. Essen
tially, we do not use CCAR to manage risk —
we look at far more scenarios and need to be
prepared for all of them. We also look at these
risks every week, not just once a year.
The calculation for a global systemically
important bank (GSIB) remains one of the
most convoluted and distorted calculations
I have ever seen (it was a typical over-
architected academic modeling exercise
that has very little to do with real risk) —
and it should be gotten rid of and replaced
with something reasonable. I understand
the concept that the failure of a large bank
would be more damaging in general than the
failure of a smaller bank. This is the same
concept as loss given default, however the
probability of default may be considerably
less. At the very least, the methodology
should be simplified and made to focus on
risk more than it does today.
Operational risk capital calculations are also
intensely inaccurate and should
actually
measure
risk in a way that helps banks man
age operational risk. The framework does
not offer credit for anything that was done to
dramatically reduce such risk. And it does
not measure factors that cause
actual
opera
tional risk, such as excessive margining,
low-quality collateral, actual operational fail
ures, lower-quality lending and others. In an
ironic twist, most of the operational risk capi
tal borne by banks is related to litigation plus
fines and fees charged by regulators, which
were excessive and punitive (and impossible
to dispute).
The Federal Reserve never fully disclosed
what they believed the changes in capital
rules and liquidity requirements would do to
bank lending and market liquidity. Nor has
the Fed ever accurately provided an analysis
of the effects that result from the intercon
nectivity between liquidity requirements and
quantitative easing (QE).
Liquidity requirement regulations perma
nently locked up (in a very rigid way) an
extraordinary amount of liquidity in the bank
ing system, which could have gone to more
productive use. JPMorganChase alone will
have over $1 trillion in usable liquidity but will
be unable to deploy it because of the inflexi
bility of the calculations. More to come on
this point.
All these financial rules dramatically reduced
lending by banks and contributed to lend
ing’s shift into the nonbank sector, which is
often more expensive and less reliable.
The FDIC process was badly handled. Its
mismanagement of SVB, Signature Bank and
FRB probably cost the FDIC many billions
more than it should have. And since the FDIC
is effectively a mutual insurance company,
these losses are always charged back to the
banks —
the taxpayer has never paid
.
Not all bank regulations are all good or all bad
— we should just try to get it right. I have a few
suggestions.
Here are some examples of smart, rigorous
regulations and new ideas that could make
the system safer and better.
One of the huge risks for a bank has always
been a “run on the bank,” which occurs when
people think that their uninsured deposits are
at risk. The FDIC only covers insured deposits,
and the run risk is driven by uninsured depos
its, particularly nonoperating uninsured depos
its. In recent bank failures, regulators have had
to invoke the systemic risk exception (SRE) to
protect uninsured deposits at the point of fail
ure. That is a problem — no one should want
this as an emergency mechanism. It creates
moral hazard, and the process to invoke the
SRE is chaotic and involves multiple agencies,
including approval by the Treasury Secretary in
consultation with the President. Bank runs can
happen quickly, and relying on that type of
action to avoid contagion is simply not a good
idea. Here are some ideas that I believe would
not only significantly reduce the chances
that the SRE would need to be invoked but
would also make the system safer and avoid
moral hazard.
21
21
SPECIFIC ISSUES FACING OUR COMPANY
I would limit the amount of HTM securities
in a way that links to the total long-term debt
that the bank must have available to absorb
losses upon its failure. And while this is a
judgment call, banks need to realize that
when available-for-sale and HTM security
losses start to exceed 50% of tangible equity,
investors will get worried.
Through some simple tests, I would limit the
extent of interest rate exposure that banks
can take.
Capital has not been an issue for banks.
However, I would establish clear capital
thresholds. If banks go below a certain
amount, they cannot raise their dividend or
buy back stock. At a level below that, they
would have to cut their dividend. And at a
level below that, they would be forced to
raise capital. This would impose real disci
pline. Although current Fed rules already
achieve some of that, I think the rules could
be tougher, clearer and simpler.
The liquidity component of loans and securi
ties should be equal to what the Fed discount
window would lend against those securities.
We should eliminate duplicative or unneces
sary liquidity buffers. These actions would
create an enormous amount of lendable
liquidity and also allow banks to use their
capital far more flexibly in a crisis. They
would also reduce the need for the Fed to
step in every time there is a kerfuffle in the
market. Credit for the Fed discount window
alone would increase JPMorganChase’s
lendable liquidity by almost $500 billion.
Prior to failure — between the Fed window
and the rather quick sale or financing of
securities or other assets — banks should be
in a position where they have enough liquid
ity to
pay off more than 50% of uninsured,
nonoperating deposits. Regulators floated
a similar idea in 2024, and I agree with them.
This plan, plus the fact that equity and
long-term debt will absorb losses before
uninsured deposits are at risk, would give
customers far greater peace of mind.
We should also consider simply setting,
upfront, a statutory cap on the percentage
loss on uninsured deposits in the event of
failure — say, at 5%. This would reduce moral
hazard and create an additional buffer for the
FDIC to achieve a smooth resolution without
using the SRE. With this plan, a small portion
of the uninsured deposits would be immedi
ately available to cover losses and communi
cated to depositors in “peacetime” while
the bulk of uninsured deposits would be pro
tected in a resolution. Although some might
argue that a mechanism like this might
increase the risk of a bank run, I think if the
percentage is well-chosen, it might actually
be stabilizing by eliminating the uninsured
depositor’s nightmare scenario of losing all
their money. In the end, all debates about
the best way to proceed revolve around how
much shareholders, creditors and uninsured
depositors of the failing bank should pay and
how much healthy banks should pay. As I
already said, it has never been the taxpayer.
And perhaps capping the maximum loss on
uninsured deposits upfront would put an end
to ad hoc involvement by the government
once and for all.
On highly leveraged repo or derivative-type
positions, there should be standard conser
vative margin requirements, as appropriate,
for each type of collateral and maturity.
Banks should be allowed to require less mar
gin, which often happens because of com
petitive markets; but if banks take this step,
they should report that action to the Fed. The
Fed ought to reserve the right to charge cap
ital if it thinks margin requirements are too
low or the aggregate size of these positions
is causing risk to the system. This would give
the Fed a very powerful tool to deleverage
and derisk the system.
Our initial reactions to the revised Basel 3
Endgame and GSIB proposals are mixed.
While it was good to see that the recent propos
als for the Basel 3 Endgame (B3E) and GSIB
attempted to reduce the increase in required
capital from the 2023 proposals, there are still
some aspects that are frankly nonsensical.
22
22
SPECIFIC ISSUES FACING OUR COMPANY
The GSIB surcharge is still broken. The original
Basel rule, known as Method 1, was a grab bag of
overlapping metrics — many of which had noth
ing to do with risk or resolvability — that solved
for a number that international regulators thought
was right. Then the United States decided that
wasn’t high enough and created Method 2, which
basically was double Method 1. In the meantime,
banks, including JPMorganChase, have made
enormous progress addressing resolvability con
cerns while remaining profitable and becoming
more resilient. Due to its methodological flaws,
the bulk of the increase of our Method 2 sur
charge has been driven by growth in the overall
economy. Under the GSIB re-proposal, our sur
charge would only decrease very modestly, to
about 5.0%. This is absurd when we compare it
with our 2015 Method 2 surcharge of 3.5%, and
even more absurd when compared with our
Method 1 surcharge of 2.5%, which has been flat
versus inception.
A properly designed framework should reward
the resilience and strength of our diverse
income streams and strong risk management.
With a surcharge of approximately 5.0%,
JPMorganChase will have to hold as much as
50% more capital across the vast majority of
loans to U.S. consumers and businesses when
compared with a large non-GSIB bank for the
same set of loans. While we can accept that
some level of surcharge is appropriate, given
our position in the market, the proposed
level just seems to punish our success, our
strength, our consistency and our balanced
business model. Frankly, it’s not right, and it’s
un-American.
As I mentioned earlier, there are numerous
flaws in the operational risk framework. Since
the current proposal still retains this operational
risk and hasn’t addressed all the duplication
and flaws, we could show you some additional
capital metrics that are a fairer representation
of the strength of our balance sheet.
We support a timely finalization of the B3E and
GSIB re-proposals: Everyone wants to move on,
and there are new important areas that require
focus, like liquidity regulation. But, unfortu
nately, the latest proposals are still very flawed
in a few specific areas, so we will be pointing
that out in our comment letters.
AI, data and technology are key to
the future, as is solving for how to
implement AI properly and fast.
The importance of AI is real — and while I hesi
tate to use the word transformational — it is.
The pace of adoption will likely be far faster
than prior technological transformations, like
electricity or the internet. Those took decades
to roll out, but this implementation looks likely
to accelerate over the next few years. Our Chief
Operating Officer describes our efforts in more
detail, but I want to make some key points here.
We will not put our heads in the sand. We
will deploy AI, as we deploy all technology,
to do a better job for our customers (and
employees).
AI will affect virtually every function, applica
tion and process in the company. And in the
long run, it will have a huge positive impact
on productivity. I do not think it is an exag
geration to say that AI will cure some can
cers, create new composites and reduce
accidental deaths, among other positive
outcomes. It will eventually reduce the work
week in the developed world. And people
will live longer and safer.
We do not yet know exactly how AI will
unfold. The landscape will change rapidly,
with shifting assumptions about power con
sumption, costs, chip technologies and the
speed at which data centers are deployed.
There will be a wide variety of AI models —
open and closed, large and small — and no
single tool will dominate. Overall, the invest
ment in AI is not a speculative bubble; rather,
it will deliver significant benefits. However,
at this time, we cannot predict the ultimate
winners and losers in AI-related industries.
AI is a genuine technological shift that will
impact many sectors, including physical
industries and scientific research. AI is only
beginning to be applied broadly in science,
and its influence will continue to expand.
23
23
SPECIFIC ISSUES FACING OUR COMPANY
AI will also introduce serious new risks —
from deepfakes and misinformation to
cybersecurity vulnerabilities. These risks are
real, but they are manageable if companies,
regulators and governments prepare. The
worst mistakes we can make are predictable:
overreact at the first serious incident and
regulate out important innovation or under
react and fail to learn from what went wrong.
The right approach requires rigorous prepa
ration in advance, an honest assessment
when things go wrong — and they will —
and discipline to fix what’s broken without
destroying what works.
AI will definitely eliminate some jobs, while it
enhances others. Our firm will have definitive
plans on how we can support and redeploy
our affected workforce.
AI will create many jobs — some we can see
today in cybersecurity and AI itself, and
some we can’t see. But we do know that there
is a huge workforce shortage for many
well-paying white- and blue-collar jobs.
There is a possibility that AI deployment will
move faster than workforce adaptation to
new job creation. In prior technological trans
formations, labor had time to adjust and
retrain. We do believe that business and
government can do many things to properly
incent retraining, income assistance, reskill
ing, early retirement and relocation for those
whose job might be adversely impacted by AI
(I talk about some of these ideas in Section IV
around work skills training and the Earned
Income Tax Credit).
One last but important point: We have focused
on some of the “known and predictable” and
some of the “known unknown” events. But huge
technological shifts like AI always have second-
and third-order effects as well that can deeply
impact society. Some of these are, for example,
cars bringing about the development of sub
urbs and shopping malls; agriculture enabling
cities; and the original internet (invented back in
1969) leading to mobile phones, apps and social
media. We should be monitoring for this kind of
transformation, too.
Cities — like individuals, companies
and countries — need to compete.
No matter who you are, you need to deal with
reality and the truth. The truth is that while New
York City has much going for it, particularly for
financial companies (because of extraordinary
local talent), it also has the highest city and
state corporate taxes and the highest individual
income and state taxes. People often make this
a moral or loyalty issue, but it is not. Companies
need to remain competitive in this very tough,
fast-moving world. And higher taxes mean
lower returns on capital and less competitive
ness by their nature.
Additionally, individuals vote with their feet —
you can already see a fairly large exodus of peo
ple and jobs out of some states with high taxes
and high expenses (often due to high taxes and
regulatory burdens). Sometimes you see com
panies leaving states, but migration also shows
up in shifts of employees out of certain states.
For example, while New York City is still our
company’s global headquarters, we have shrunk
our headcount in the city, from 30,000 a decade
ago to 24,000 today, and increased our head
count in Texas, from 26,000 in 2015 to 32,000
today. This trend will likely continue.
Sometimes this can be a disaster for a city. I am
reminded that in the 1970s, nearly half of the 125
Fortune 500 companies based in New York City
left. While mergers accounted for some depar
tures, the price of doing business in New York
City accounted for most: cost of taxes, office
rents, labor and so on. No city — or company or
country — has a divine right to success.
24
24
SPECIFIC ISSUES FACING OUR COMPANY
We need to keep everything in motion, break
down bureaucracy, and leverage our trusted
brand and technological edge to win in every
market where opportunity exists. I do believe
that we have everything in motion for continu
ous progress.
Teams require great platforms across
the company.
While there is an unbelievable need for speed,
these teams can’t all build their own systems.
They need to rely on a common language,
common tools and interoperability. Therefore,
certain platforms (e.g., for data, AI, coding,
financial and CRM systems) need to be compa
nywide and easily deployed, which may mean
they are necessarily large. Before they are
deployed, it may require consensus that they
are the best platform to use. This makes them
reusable and highly efficient. The trick is to have
great platforms without creating bureaucracy
and to build great teams for speed.
Building a lasting, deeply rooted and
common culture is critical — and it
takes an extraordinary amount of effort.
It has been an immense pleasure and honor
running this company. It has also been an
extraordinary amount of hard work, long days
and lots of travel. And I have often wondered
if all of that effort was worthwhile. I have seen
management teams that don’t work as hard or
travel as much and still run a successful com
pany. And I have seen companies that have
multiple cultures and still seem to get by — at
least in the short run. But I do not believe this
company, with its complexity and extraordinary
risk and global reach, could have survived or
thrived that way. When I look back, I do believe
the exceptional effort that we all made really
made a huge difference.
We always enjoy every year musing about man
agement lessons learned — and sometimes
relearned. Sometimes we also discover that we
need to change how we function because the
world (technology, competitors, products,
among other factors) has changed.
It’s essential to organize in small teams
for super speed.
The real competitive battles are fought at the
detailed segment level: It’s not just investment
banking or the investment banking healthcare
sector; it’s having the right team to win in
healthcare pharma or medical devices. It’s not
just credit card or even affluent brands; it’s the
Chase Sapphire® card. It’s not small business
clients in branches; it’s restaurateurs or law
firms. It’s not digital payments; it’s 24/7 digital
payments with automatic currency conversions.
It’s hundreds of small teams (including technol
ogy, AI, marketing, subject matter experts and
others) attacking specific problems. The teams
needed to tackle these challenges should be
small and authorized with the decision-making
ability to move and act like Navy SEALs or the
Army’s Delta Force. Finally, they need to be
dedicated to the task at hand. Very often when
a management team wants to accomplish
something new, like create a digital account
opening process that cuts across virtually every
area, everyone on the team says, “We’ll get it
done,” meaning they will add it to the long list of
tasks already on their plate. But when efforts
are 1% of a lot of people’s jobs, it will never get
done. You need a team 100% dedicated to the
mission — and everyone else supports them.
Success requires speed, agility and relentless
execution. This is trench warfare; it’s about fight
ing for every inch, moving quickly and getting
things done. Growth comes from out-working
and out-innovating the competition, deploying
our resources strategically and fine-tuning our
initiatives to maximize impact.
II. Management Learnings
MANAGEMENT LEARNINGS
25
Given the breadth of our company, these efforts
take many forms. In addition to constant busi
ness reviews, management meetings, workout
sessions, deep dives, client and employee
lunches, and leadership offsites, our commit
ments are considerable, a sampling of which
may help our shareholders better understand
how we maintain our culture. Here are a few
examples from the
past 10 years
:
The letter to shareholders
, published each
year in the Annual Report, is very clarifying
not just to shareholders but to me, the man
agement team, our employees and the
communities in which we operate. While the
annual letter is a lot of work — both for me
and for many people in the company — it
makes us analyze and answer complex ques
tions, and articulate clearly and concisely
what we are trying to accomplish.
Attending leadership training sessions, of
which we do hundreds, and employee town
halls, of which I
personally hosted more than
60 last year
, has been a significant commit
ment over the last 10 years.
In my travels, I’ve made a total of over
230
international visits
to
46 countries
.
Meetings that our leadership has held with
management, employees, clients, regulators
and government leaders have involved
6,887
flights, 9 million miles
and
372 cities
, again
with extensive meetings in each place.
Wherever I go, I also meet with community
leaders and partners, traveling on average
145 days
a year.
Over the course of each year, JPMorganChase
hosts more than
2,900 global client events
for over
440,000 attendees
. Of those, I
typically host approximately
250
of these
large events around the world. And I always
try to stand out front shaking the hands of
clients as they enter.
This year we will host our
16
th
bus tour, where
we travel off the beaten path to visit branches
and operations centers to see our employees
in action and to meet with clients in their local
communities. Over our first 15 bus tours span
ning 14 years, we have stopped in
39 states
,
with California, Illinois, Minnesota and Wash
ington hosting three tours each. North Dakota
was a first. Last year we hit Mississippi,
Alabama and the Carolinas, the backyard of
some of our biggest competitors. And the bus
has made stops in approximately
75 cities
in the United States. Approximately
24,000
clients
and
30,000 employees
have attended
a bus tour event. Approximately
100 branches
have been visited by bus over the 15 tours.
Each year, one of my other favorite things to
do is travel to our annual
National Achievers
event
—
1,400 strong
— where we recognize
and thank our top branch tellers and personal
bankers for the great job they are doing in
serving our customers. We present awards to
the winners that takes hours — and we all find
it inspiring. It always motivates me to do a
better job for all of them.
Importantly, our travels have included
396
trips to Washington, D.C.,
over the last
decade, visiting regulators, administration
officials and members of Congress approxi
mately 300 times — providing insights,
research, data and, where necessary, a coun
tervailing view, testifying and receiving input,
handling customer complaints and helping
to resolve issues (including big ones like the
failure of First Republic). Not every conversa
tion resulted in agreement or alignment, but
we are committed to being part of the solu
tion. During this time, JPMorganChase has
played a central role, across party lines and
administrations, to support American resil
ience and global safety in moments of stress.
Every year,
350 of our senior leaders
from
around the world gather together to educate
and network with one another, hear from
expert external speakers and internal
colleagues about business segments and
innovations, and prepare with a common
purpose for the year ahead.
MANAGEMENT LEARNINGS
26
This hard work is also fun as we celebrate our
successes, and it is extremely informative as
we learn from employees and customers about
what we could do better. These extensive efforts
and travel drive continuous improvement and
inform how we educate our people to treat one
another and our clients and deal with problems.
One last note: Wherever I go, I get to observe
our employees around the world getting to know
our people in other parts of the firm and seam
lessly collaborate with one another for the ben
efit of JPMorganChase and our clients. It’s
gratifying to see this exceptional company in
action.
One of the most rewarding parts of the bus trip
for us is riding alongside some of our front-line
employees — our bankers and advisors. Their
perspective and advice on how we can do a
better job are invaluable. And, boy, do we get a
lot of advice — over the years, there have been
hundreds of specific recommendations, which
we implement as appropriate.
We want to make this drive toward continuous
improvement a part of the fiber of every person
at our firm.
JPMorganChase is a powerful neural
network.
Recently, I was blown away by the presentations
of several of our executives (at a senior leaders’
meeting) and by the level of collaboration across
every segment — consumer, private bank,
investment bank, commercial bank and others.
There’s a sense of momentum: I feel like we’ve
got everything in motion and that we’re attack
ing our problems in multiple ways. If the senior
leaders ever feel we’re too bureaucratic or slow,
they speak up. Our challenge to them is: “Don’t
wait. Get stuff done; get it fixed.” We need to
make it an “always-on” process of streamlining
and bureaucracy-busting.
In effect, with all of this “culture building,”
JPMorganChase is its own strong “neural
network”— powerful and healthy connections
between
our people. People usually look at
investment as capital expenditures, but in many
ways, our investment is in the intelligence of our
people and their healthy connections. They
need to perform like a well-functioning sports
team. This network and the knowledge, talents
and brainpower of our people, dedicated to the
purpose of serving clients, create the capabili
ties that we have today, which would be very
difficult to replicate.
A good culture is hard to create and easy to
lose so you have to fight for it every day — with
a little bit of grit, courage and an open mind.
MANAGEMENT LEARNINGS
27
We must remain clear-eyed: As good — or bad
— as things feel now, we must necessarily
always be prepared for all possibilities, including
the possibility of some really tough times ahead.
We do this so that our company is prepared to
serve all of our clients, including governments
around the world, regardless of the turn of
events.
To do this, we look at many increasingly large
and complex factors — such as geopolitics and
wars, energy prices, trade and economic rela
tions, political polarization, large global deficits
and high asset prices, among others. We look
at both short-term factors that will likely affect
us in the ensuing 12 months and the complex
factors that may affect us in the current year
and in
future
years.
We manage “through the cycle.”
On Investor Day, our Chief Financial Officer
showed what our returns would look like under
various scenarios. Some of these examples
reflect historical economic events. For instance,
the worst-case scenario (a very bad recession)
assumes front-end rates cutting to floor levels,
the stock market dropping 40%, credit losses
doubling and volumes dropping significantly.
Even then, our return on tangible common
equity would still be approximately 10%. It’s also
worth remembering that the firm didn’t lose
money in any single quarter during the great
financial crisis — a period whose stresses are
similar to those modeled for the Fed’s annual
CCAR test. We are very disciplined in using both
actual historical scenarios and very detailed
economic models, but we know they do not
and cannot accurately predict the future.
We often talk about our “through-the-cycle”
target returns of 17% return on tangible common
equity. By through the cycle, we mean that there
will be times when returns will be better than
that, and there will be times when they will be
worse. We are often asked why we don’t raise
that target since we have exceeded it for
numerous years. It’s good to put this number
in context. Compared with the returns of our
10 major competitors, this return has been
exceeded only 9% of the time over the last
10 years.
Many factors are dramatically different
in the global economic and financial
system than in 2010 — many better but
some possibly worse.
Before I talk about risks specifically, it’s helpful
to recognize that the world’s economy is far
larger and more diversified and far less reliant
on energy as an input versus 20 years ago.
Global energy consumption to the global gross
domestic product (GDP) is only about 40% of
what it was around 45 years ago, say in the early
1980s, and the United States, instead of being
a major importer on a net basis, is now a major
exporter. All of this may very well mean that the
economy is more resilient and less vulnerable
to some of the factors I am going to discuss. It
is also good to remember that the United States
remains the world’s best investment destina
tion, particularly when things are going badly.
If you look at the table on the next page, there
are a few items that are truly different now from
what they were in 2010, and these may well lead
to different and unexpected outcomes. To name
a few: The global debt and equity markets are
far bigger than before (as are global deficits).
Many nonbank financial institutions and inves
tors are dramatically bigger than they were
in the past (think hedge funds, private equity
funds, sovereign wealth funds, among others).
Global foreign portfolio investments are far
bigger than before, and a large stock of U.S.
Treasuries owned by foreigners is not held by
III. Managing in a Time of
Increasing and Complex Risks
MANAGING IN A TIME OF INCREASING AND COMPLEX RISKS
28
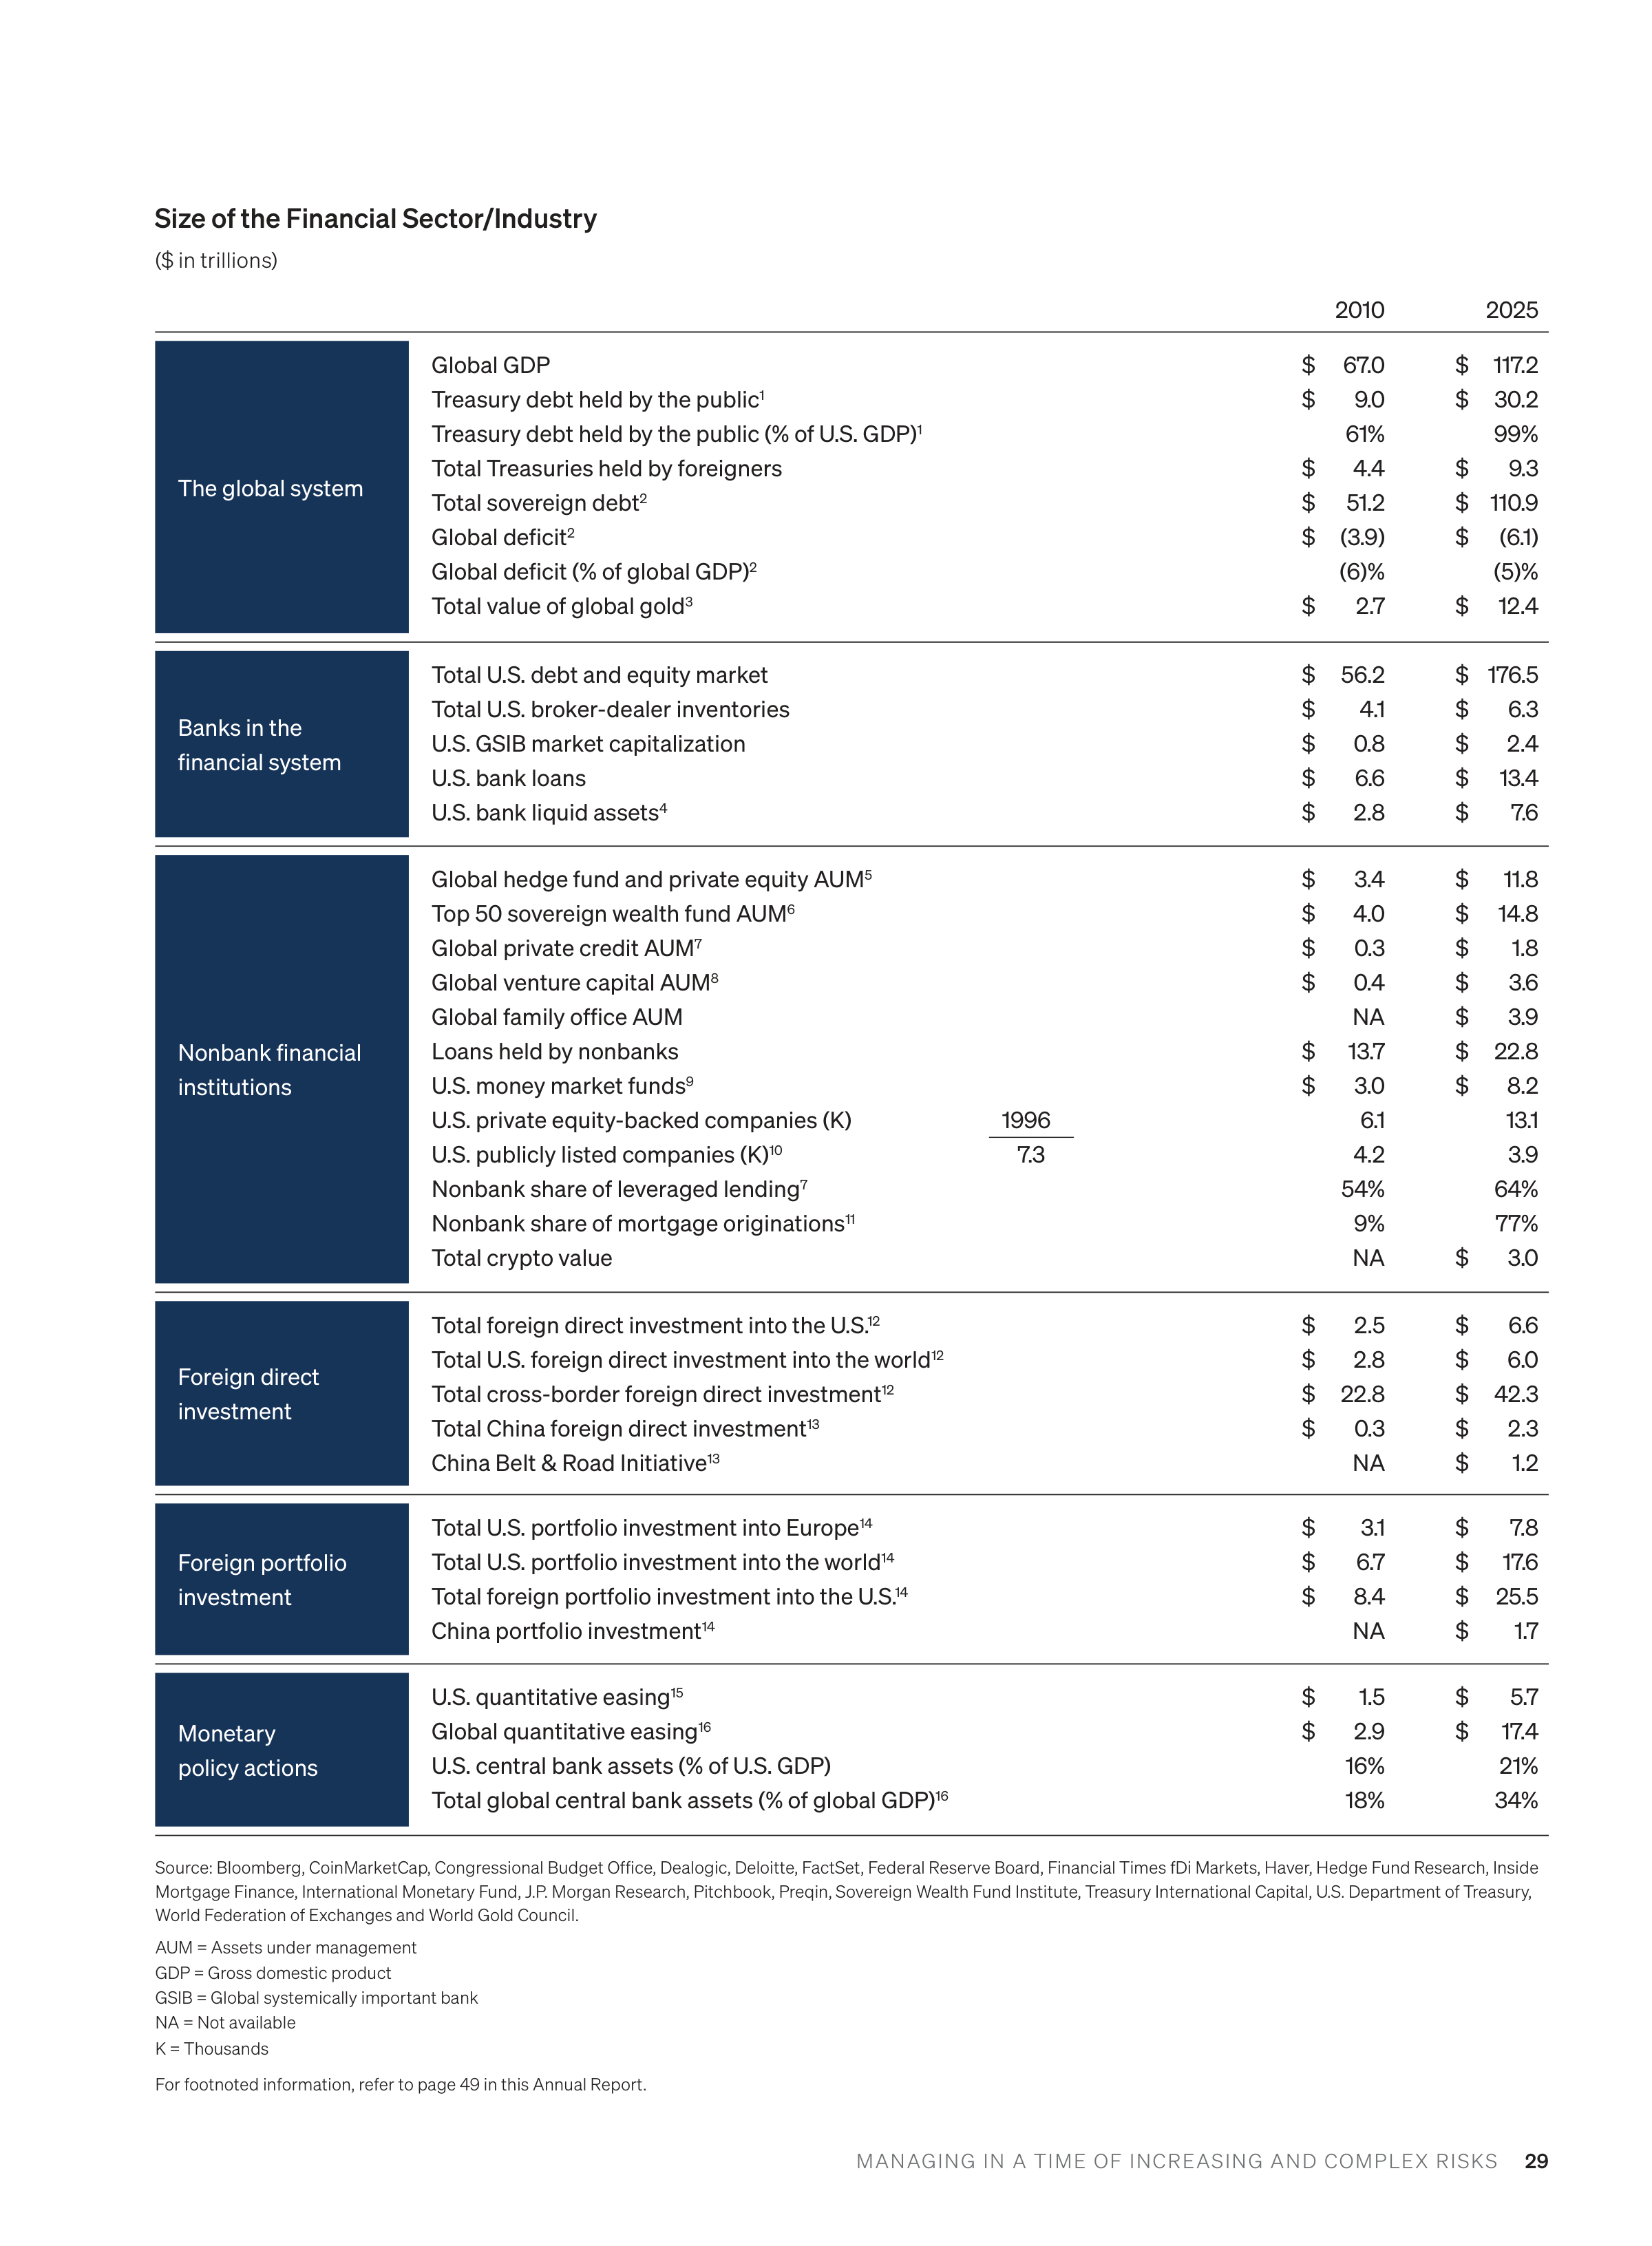
MANAGING IN A TIME OF INCREASING AND COMPLEX RISKS
29
2010
2025
The global system
Global GDP
Treasury debt held by the public
1
Treasury debt held by the public (% of U.S. GDP)
1
Total Treasuries held by foreigners
Total sovereign debt
2
Global deficit
2
Global deficit (% of global GDP)
2
Total value of global gold
3
$
67.0
$
9.0
61%
$
4.4
$
51.2
$
(3.9)
(6)%
$
2.7
$
117.2
$
30.2
99%
$
9.3
$ 110.9
$
(6.1)
(5)%
$
12.4
Banks in the
financial system
Total U.S. debt and equity market
Total U.S. broker-dealer inventories
U.S. GSIB market capitalization
U.S. bank loans
U.S. bank liquid assets
4
$
56.2
$
4.1
$
0.8
$
6.6
$
2.8
$ 176.5
$
6.3
$
2.4
$
13.4
$
7.6
Nonbank financial
institutions
Global hedge fund and private equity AUM
5
Top 50 sovereign wealth fund AUM
6
Global private credit AUM
7
Global venture capital AUM
8
Global family office AUM
Loans held by nonbanks
U.S. money market funds
9
U.S. private equity-backed companies (K)
U.S. publicly listed companies (K)
10
Nonbank share of leveraged lending
7
Nonbank share of mortgage originations
11
Total crypto value
1996
7.3
$
3.4
$
4.0
$
0.3
$
0.4
NA
$
13.7
$
3.0
6.1
4.2
54%
9%
NA
$
11.8
$
14.8
$
1.8
$
3.6
$
3.9
$
22.8
$
8.2
13.1
3.9
64%
77%
$
3.0
Foreign direct
investment
Total foreign direct investment into the U.S.
12
Total U.S. foreign direct investment into the world
12
Total cross-border foreign direct investment
12
Total China foreign direct investment
13
China Belt & Road Initiative
13
$
2.5
$
2.8
$
22.8
$
0.3
NA
$
6.6
$
6.0
$
42.3
$
2.3
$
1.2
Foreign portfolio
investment
Total U.S. portfolio investment into Europe
14
Total U.S. portfolio investment into the world
14
Total foreign portfolio investment into the U.S.
14
China portfolio investment
14
$
3.1
$
6.7
$
8.4
NA
$
7.8
$
17.6
$
25.5
$
1.7
Monetary
policy actions
U.S. quantitative easing
15
Global quantitative easing
16
U.S. central bank assets (% of U.S. GDP)
Total global central bank assets (% of global GDP)
16
$
1.5
$
2.9
16%
18%
$
5.7
$
17.4
21%
34%
Source: Bloomberg, CoinMarketCap, Congressional Budget Office, Dealogic, Deloitte, FactSet, Federal Reserve Board, Financial Times fDi Markets, Haver, Hedge Fund Research, Inside
Mortgage Finance, International Monetary Fund, J.P. Morgan Research, Pitchbook, Preqin, Sovereign Wealth Fund Institute, Treasury International Capital, U.S. Department of Treasury,
World Federation of Exchanges and World Gold Council.
AUM = Assets under management
GDP = Gross domestic product
GSIB = Global systemically important bank
NA = Not available
K = Thousands
For footnoted information, refer to page 49 in this Annual Report.
Size of the Financial Sector/Industry
($ in trillions)
central banks (central banks are less likely to
make dramatic changes in their holdings of U.S.
Treasuries). In addition, global QE is far bigger
than it ever was before. A change in sentiment
could easily affect the global flow of investments
into securities, including U.S. Treasuries. You
can also see that brokerage inventories are far
smaller as a percentage of investments than
ever before and, as a result, market makers are
less able to intermediate in extremely volatile
markets.
More broadly, as we think about how these new
conditions relate to one another, it’s good to
keep three things in mind: 1) It seems to me
that while people frequently overreact to often-
inaccurate short-term weekly and monthly data,
their forecasts are generally small modifications
versus current conditions, 2) while the economy
may be less fragile than in the past, this alone
does not mean there is no “tipping point” — it
just may mean it could take more straws on the
camel’s back to get there and 3) often it is an
unexpected confluence of events that causes
a “tipping point.” The convergence of rapidly
increasing oil prices and inflation is frequently
viewed as among the main causes of the very
large 1974 and 1982 recessions. Also, human
nature has
not
changed — sentiment and
confidence can change rapidly and drive
the markets.
Liquidity itself is a complex concept and can
also change with sentiment. Often when people
talk about liquidity, they are talking about the
ability to readily buy or sell in the marketplace,
e.g., when spreads are high and volumes are
low, this would be considered low liquidity.
Sometimes people are referring to the money
supply. Money can be created by the central
bank when it buys securities or by banks when
they expand their balance sheets. In both cases,
they create deposits (more liquid assets) in the
short run. But all investors, from individuals to
companies to major asset managers and banks,
have their own liquidity needs and require
ments, usually driven by their policy or regula
tory policy, working capital requirements, col
lateral needs and sentiment (for example, the
desire to be more conservative). When asset
prices drop and all of these other factors
change, the “need for liquidity” can change
dramatically, too. When people get scared, they
generally sell risky assets to buy safe ones,
e.g., essentially T-bills or deposits at safe banks.
And when they sell risky assets, they usually
start with their most liquid positions.
While the most important outcome we should
all hope for now is proper resolution of the cur
rent wars and, ultimately, peace on Earth, we
do need to understand and track the economic
effects of all the risks we mentioned. A bad
confluence of events generally causes various
degrees of a recession, which is accompanied
by high credit losses and volatile markets, lower
asset prices and higher unemployment rates,
though recession would happen in different
ways in different places. What might vary is
inflation. There are some scenarios that would
result in a recession, which generally reduces
inflation, and other scenarios that would lead to
a recession with inflation (stagflation — where
inflationary forces overcome deflationary ones).
The skunk at the party — and it could happen in
2026 — would be inflation slowly going up, as
opposed to slowly going down. This alone could
cause interest rates to rise and asset prices to
drop. Interest rates are like gravity to almost all
asset prices. And falling asset prices at one
point can change sentiment rapidly and cause
a flight to cash.
MANAGING IN A TIME OF INCREASING AND COMPLEX RISKS
30
There are lots of tailwinds helping us
in 2026.
While there are many larger risks, as discussed
in the next section, that may or may not impact
the economy in 2026, we do know several
things that will have a positive impact on the
economy in the remainder of this year. They are:
Increasing fiscal stimulus from the One Big
Beautiful Bill. Our economists believe this will
inject another $300 billion (effectively 1% of
GDP) into the economy. This has to be very
modestly inflationary this year.
Benefits from the Fed’s purchase of $40
billion of additional securities each month,
which is supposed to be reduced to $20
billion–$25 billion this April. At a minimum,
this supports asset prices and helps ensure
there is no liquidity squeeze in the financial
system.
Positive effects of comprehensive deregula
tory policies. This was badly needed and
long overdue. Change is clearly evident in
bank regulations that will free up capital and
liquidity, which can be lent out (and we
already see this happening), and in deregula
tion across many other industries, from
energy to home building. It is fair to say that
actions taken have clearly increased confi
dence and animal spirits. This should add to
productivity and be modestly deflationary
this year.
Huge increase in AI-driven capital spending
and construction by the five hyperscalers.
In 2025, this number was $450 billion, and in
2026, it will be approximately $725 billion.
While AI will clearly drive productivity, which
is generally good for inflation in the long run,
all of this spending is probably inflationary in
the short run.
Some of the items above have mild inflationary
effects, while others probably have some defla
tionary effects.
There are large risks still in front of us
that are multi-year and unresolved.
I think some of the larger risks are much like
tectonic plates, always moving and periodically
causing earthquakes and volcanoes when they
crash into each other. Some of the larger risks
we should keep our eyes on are:
First and foremost, geopolitics.
Russia’s
war in Ukraine and its ongoing sabotage in
Europe and now the war in Iran and its poten
tial effects on energy prices can cause
events that are unpredictable. We all hope
these wars get properly resolved. But war is
the realm of uncertainty, as each side in a war
determines what it wants to do (as is often
said, “the enemy gets a vote”), and these
conflicts involve many countries. Not only do
they have a major impact on the nations at
war, but they also have an impact on coun
tries and economies across the globe that
are not directly involved in war. Nations that
are heavily dependent upon imported energy
are already seeing the effects. And it’s not
just energy, it’s commodity products that are
byproducts of oil and gas, like fertilizer and
helium. And given our complex global supply
chains, countries are experiencing disrup
tions in shipbuilding, food and farming,
among others. The outcome of current geo
political events may very well be the defining
factor in how the future global economic
order unfolds — then again, it may not.
High global sovereign deficits and debt.
Global deficits are significantly elevated,
particularly during what has been a relatively
healthy global economy and, until recently,
a time of peace — the deficit globally is at an
extremely high 5%, while global sovereign
debt is at all-time highs. The current forecast
from the Congressional Budget Office has
our debt-to-GDP ratio going from 100% today
to 120% in 2036. High government debt is
somewhat offset by low consumer debt,
which was nearly 100% of GDP in 2007 and is
now below 70%. Similarly, corporate debt is
at a fairly normal healthy level of 45%. High
and increasing government debt will eventu
ally have to be dealt with — the right way
would be to deal with it now before it
becomes a problem; the wrong way would
MANAGING IN A TIME OF INCREASING AND COMPLEX RISKS
31
be to let it become a crisis, which, in my
opinion, is probably the likely outcome.
Importantly, almost 60% of government
spending is for entitlements and is not
discretionary. This makes the job that much
harder. A crucial note on the
importance of
growth
: If interest rates went down 100 basis
points and GDP grew at 3%, the debt-to-GDP
ratio could actually start to go down instead
of going up.
High asset prices and very low credit
spreads.
In and of itself, this is not a bad
thing. Household net worth as a percentage
of GDP is now 560%. The high during the
housing peak in 2006 was 460%. But this
also means that anything less than positive
outcomes could have a dramatic impact on
global markets. Rapidly decreasing asset
prices can sometimes create a self-reinforc
ing loop. It’s always good to remember that
prices are set by the
marginal
buyers and
sellers — which, on the average day, is only
a small fraction of asset owners. And it’s also
good to remember that foreigners own
almost $30 trillion of U.S. equities and bonds.
While U.S. investments and the U.S. dollar
are generally havens of security in a troubled
world, that didn’t stop recessions and bad
markets in prior times.
Trade 2.0.
The U.S. tariffs themselves had
only minor effects on inflation or growth, and
were only one straw on the camel’s back. But
the trade battles are clearly not over, and it
should be expected that many nations are
analyzing how and with whom they should
create trade arrangements. This is causing
a realignment of economic relations in the
world. While some of this is necessary for
national security and resiliency, which are
paramount, it is hard to figure out what the
long-term effects will be.
U.S. and China relations.
This relationship
is critical to the whole world and is also
impacted by the events mentioned above.
The United States and China clearly have dif
ferent systems, values, goals and objectives,
and while both sides are currently engaging,
we have to expect that there will be some
bumps in the road — maybe even some large
ones. We should all hope that ongoing proper
engagement continues to lead to what may
be a competitive but peaceful future.
Private credit and credit in general.
The lever
aged private credit market totals $1.8 trillion.
As a comparison, the U.S. high yield bond
market totals $1.5 trillion, and the bank syndi
cated leveraged loan market totals $1.7 trillion.
Taking a wider view, the total market size of
investment grade bonds is $13 trillion. And the
total market value of all residential mortgage
securities and loans is also $13 trillion. In the
great scheme of things, private credit proba
bly does not present a systemic risk.
I do believe that when we have a credit cycle,
which will happen one day, losses on all lev
eraged lending in general will be higher than
expected, relative to the environment. This
is because credit standards have been mod
estly weakening pretty much across the
board; i.e., more aggressive and positive
assumptions about future performance
(called add-backs), weaker covenants, more
use of PIK (payment-in-kind; not paying inter
est in cash but accruing it), more aggressive
private ratings (particularly in insurance
companies) and more arbitrage (not always a
great sign). Also, by and large, private credit
does not tend to have great transparency or
rigorous valuation “marks” of their loans —
this increases the chance that people will sell
if they think the environment will get worse
— even if actual realized losses barely
change.
MANAGING IN A TIME OF INCREASING AND COMPLEX RISKS
32
Additionally, actual losses right now are
already a little higher than they should be,
relative to the environment. Finally, if rates or
credit spreads ever go up, the companies
that borrowed will have to borrow at even
higher rates, putting them under even
greater stress. However this plays out, it
should be expected that at some point insur
ance regulators will insist on more rigorous
ratings or markdowns, which will likely lead
to demands for more capital.
It has always been true that not everyone
providing credit is necessarily good at it.
There are many players who are late to this
game, and it should be expected that some
credit providers will do a far worse job than
others. We have not had a credit recession in
a long time, and it seems that some people
assume it will never happen.
Additionally, anything that gets sold to retail
investors as opposed to institutional inves
tors requires greater transparency, higher
standards and fewer potential conflicts.
If anything ever goes wrong, you should
assume that retail investors, even though
they were told about some of the risks, will
seek remedy in the courts. Also, some of
these loans go into various funds run by the
asset management company. Generally,
each of these funds has its own objectives
and its own fiduciary responsibility to make
sure that the loans are suitable for that spe
cific fund. Those who do not do this properly
are likely to get into trouble.
Private markets.
With stock markets at all-
time highs in recent months, it is a little sur
prising that private equity firms, which own
close to 13,000 companies, have not taken
greater advantage of healthy markets to take
their companies public. Private equity invest
ments are now held for an average of seven
years — this is virtually double what it used
to be. And some are sold, not to another
company or taken public, and put in a new
fund called a continuation fund. We have
generally had nothing but a bull market since
the great financial crisis — it’s hard to imagine
what will happen if and when we have an
extended bear market.
Cyber risk.
I have to mention this because it
remains one of our biggest risks, and this is
probably true for many other major indus
tries and corporations. AI will almost surely
make this risk worse. We invest significantly
to protect ourselves and stay vigilant.
All in all, there are lots of moving parts and
potential straws that might be added to the
poor camel’s back. We are watching closely and
hoping for the best. We always try to be pre
pared and vigilant and also recognize that
tough times can create good opportunities.
MANAGING IN A TIME OF INCREASING AND COMPLEX RISKS
33
leaders, community stakeholders and govern
ment officials worked together to successfully
address the city’s economic decline. We see
this same need for collaboration to help address
challenges related to our national education
system, job creation, skills development and
virtually anything related to realizing the
American Dream. America will be far stronger
if more Americans prosper.
The scale, brain
power and resources that institutions like
ours can bring to bear on these challenges
can be extraordinary.
We at JPMorganChase feel an enormous
responsibility to our nation and many others —
and we remind ourselves that many companies
will only thrive if their countries thrive. With the
right policies and committed actions, the United
States will maintain the strongest military and
strongest economy, and will remain the bastion
of freedom and the arsenal of democracy. (An
important side note: This is also essential to
maintaining the U.S. dollar as the world’s
reserve currency.) In spite of all our extraordi
nary blessings, the United States needs to get
stronger and tougher to make this true — no
country has a divine right to success.
We have met big challenges before. At one
point in 1940, only one nation, the United King
dom, stood against the Nazi war machine, which
had already conquered most of Western
Europe. The United States was unprepared for
what was going to happen but rose to the chal
lenge. You may find it uplifting to read the book
Freedom’s Forge
, which shows how the United
States came together to build the arsenal
of freedom and to keep the world safe for
democracy.
We need the world’s strongest military
— what we can do to help: our new
Security and Resiliency Initiative.
The ongoing war in Ukraine, the conflict
between Iran and both the United States and
Israel, and other major hostilities across the
globe should permanently dispel the illusion
There are three critical issues that will ultimately
determine the health and safety of the United
States and possibly determine the future direc
tion and strength of the free and democratic
world. JPMorganChase and its employees —
like all other businesses and individuals — will
be deeply affected over time by how the United
States succeeds in these areas:
1.
The United States must maintain the premier
military force in the world.
2. The United States must maintain its preemi
nent economic position in the world, which
also requires reigniting the American Dream.
3. The United States must manage its foreign
economic affairs to strengthen the U.S. econ
omy and that of our critical allies
so that the
first two points remain true.
Foundational to accomplishing the three goals
above is that the core strength of the United
States — its deeply held values and principles,
including our commitment to the Constitution
— is constantly nourished and strengthened.
In this section, we also ask and answer the
question: What can we as a company offer in
order to do our part?
JPMorganChase and companies
across the public and private sectors
have an important and unique role in
addressing global challenges.
Many public and private companies and insti
tutions play a vital role in addressing various
critical policy issues. The world is increasingly
complex and polarized, and we need to remain
completely clear-headed. It has become obvi
ous, for example, that many of our largest pol
icy issues cannot be solved by government or
business alone. Our national security clearly
depends not only on the U.S. military but also
on the civilians and companies responsible for
developing equipment and tools critical to our
country’s defense, from ships and planes to
chips and AI. JPMorganChase saw the benefit
of collaboration in Detroit, where business
IV. Critical Issues Facing America
and the World
CRITICAL ISSUES FACING AMERICA AND THE WORLD
34
that the world is safe. Having the world’s best
military is expensive, but it will always be a huge
deterrent to war. Fighting wars is even more
expensive. And losing wars even more so.
I firmly hope that the United States provides
sufficient military and economic support to
help Ukraine prevail in what has become an
extended and bloody war for democracy and
against autocracy. Time will tell whether the
current war in Iran achieves our short-term and
long-term objectives in the region and at what
cost. We should not turn a blind eye to the role
the current regime in Iran has played in foster
ing terrorism and killing thousands of people,
including Americans and many of its own citi
zens, over many years. And that threat must be
addressed in an appropriate manner (by those
who have more intel and knowledge than I do)
— and urgently if Iran ever acquires a nuclear
ballistic missile. Nuclear proliferation remains
the gravest threat to the future of mankind.
The U.S. military umbrella has not only provided
security for our allies and partner countries
since World War II, but it has also provided
safety and stability for non-allied states, includ
ing major countries like India.
We have much to do to ensure we remain the
world’s best military.
While we have the world’s best military and while
congressional oversight is a constitutional
responsibility, the military is often stretched and
hampered by congressional rules, interference,
legislation and short-term budgeting, as well as
by over-consolidation and under-investment in
our defense industrial base. We need to spend
more (and we hope smarter and more efficiently)
on our military and give it the ability to move
faster, unimpeded by politics and bureaucracy.
The United States has also allowed itself to
become too dependent on unreliable sources for
items that are essential to our national security,
such as critical minerals, semiconductors and
advanced manufacturing output, among others.
We have maintained insufficient productive
capabilities to be ready to quickly increase pro
duction if necessary. And our military needs to
be able to rapidly develop new and often cheaper
weapons, like drones. The Pentagon, and in fact
the whole government, is now actively address
ing this problem, but it needs lots of private
sector help.
JPMorganChase is well-positioned to do its part.
That’s why JPMorganChase has launched
the Security and Resiliency Initiative.
This initiative is a $1.5 trillion, 10-year plan to
facilitate, finance and invest in industries critical
to national economic security and resiliency.
As part of this endeavor, we will make direct
equity and venture capital investments, with an
initial amount of $10 billion, to help companies
enhance their growth, spur innovation and
accelerate strategic manufacturing.
We are focusing our efforts on the following
five key areas, supporting companies across
all sizes and development stages by offering
advice, providing financing and, in some cases,
investing capital:
Supply chain and advanced manufacturing
,
including critical minerals, shipbuilding and
robotics, helping ensure access to essential
minerals and gaining dominance in advanced
manufacturing
Defense and aerospace
, including defense
technology, autonomous systems, drones,
next-generation connectivity and secure
communications, helping defend our nation
Energy independence and resilience
,
including battery storage, grid resilience
and distributed energy, helping build energy
systems to meet the increased demand of
technologies like AI and data centers
Frontier and strategic technologies
, including
AI, cybersecurity and quantum computing
Pharmaceuticals and health technologies
,
including medicines, essential medical
supplies, devices and technology
CRITICAL ISSUES FACING AMERICA AND THE WORLD
35
The initiative will also include special, thematic
research focused on private industries and
supply chain weaknesses like rare earths, AI
and technology. It will be complemented by
the firm’s recently launched JPMorganChase
Center for Geopolitics, which provides us and
clients with timely analysis and insights on top
global trends.
Policy is essential, too. So our objectives will
include designing practices that can accelerate
these efforts, including research and develop
ment (R&D), permitting reform, rapid and multi-
year procurement, and regulations conducive to
growth. As our firm intensifies its focus on those
industries essential to our nation’s security and
resiliency, we will also continue to work closely
with our community and business partners to
champion these enterprises, foster talent and
support skills training to ensure companies can
fill critical jobs.
Since the launch of our Security and Resiliency
Initiative at the end of 2025, the response has
been nothing short of remarkable. We have
received more than 750 business opportunities
from company leaders and government officials
across critical sectors. To handle this momen
tum, we are assembling a dedicated 30+ person
SRI global banking and investment team (sup
ported by much of the rest of the company) with
the experience and vision necessary to drive
meaningful impact.
In addition, we announced the formation of an
external advisory council composed of experi
enced leaders and exceptional thinkers from
both the public and private sectors (from mili
tary generals to former secretaries of state and
defense to business executives and CEOs) to
help guide the SRI’s direction and strategy.
I have the privilege of chairing this council,
which recently convened in person in Washing
ton, D.C., alongside many of JPMorganChase’s
top leaders.
Building on advice from the advisory council, we
are hosting our inaugural Defense Action Forum
this month. Unlike typical industry conferences,
our forum is designed to foster collaboration
and generate practical solutions that drive
meaningful change. The sessions will bring
together leading experts to explore the pivotal
role that the private sector can play in ensuring
our nation’s enduring strength and security. We
hope to make some real progress, which will be
shared broadly.
Our SRI work is more comprehensive than
American security alone. This initiative will
continue to be extended, as appropriate, to
other allied nations. The SRI can help allied and
partner countries and companies as they make
the investments and reforms necessary to play
a more active role in our nations’ common
defense needs.
The foundation of America’s strength
is predicated on remaining the
preeminent economy in the world —
what we can do to help: promote
growth policies.
Over the last 20 years or so, U.S. GDP has
averaged about 2% annually — I believe we
could have easily achieved at least 3% growth.
The reason we were able to grow 2% is that
America’s businesses and entrepreneurial spirit
allowed us to overcome a lot of the roadblocks
mentioned later in this section. That 1% differ
ence would have had an enormous impact,
providing Americans with an extra $20,000
GDP per person annually, giving us resources
to take care of nearly all our problems and
jump-starting deficit reduction. Growth is part
of the solution to almost all of our problems.
Achieving such growth also would help restore
trust in our government.
Good policy drives growth, helps all citizens
and has the virtue of being fundamentally
free.
Good policy matters and is at the heart of
sustainable progress. It’s policy, policy,
policy. We’re committed to engaging with
policymakers, supporting sound regulation,
and advocating for growth and security.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
36
We’re investing in strong policy teams and
backing our positions with rigorous analysis.
We have a responsibility to help shape the right
policies, not just for our company but for the
country and the world.
In the
Sturm und Drang
of today’s politics, you
mostly hear about simplistic solutions like rais
ing taxes, taxing the rich and cutting expenses,
but as any businessperson knows, you should
always be asking, “How are you doing with what
you have?” Our inefficiencies, red (and blue)
tape and lack of analysis stifle our growth and
almost always hurt the poor the most. But there
are so many things that could be done that
could make everything better — for all citizens.
And these things would be virtually free.
There are some very basic things that
hamper our growth and really need to
be fixed.
I am going to mention a few damaging policies,
not in detail because I’ve written about them in
the past, but if they aren’t corrected, real prog
ress may be impossible.
Fraud, waste and abuse.
These areas likely
cost U.S. taxpayers many hundreds of bil
lions of dollars annually (according to the
Government Accountability Office). In many
cases, the government does not even have
basic controls in place to manage this waste,
like any good company would. It offends
people and causes them to lose trust in
their government.
Inefficiencies within the federal government
(and within state and local governments,
too).
Every government department should
have detailed budgeting, planning and
analytics; for example, every agency should
be answering this question: “What is the
output of all the money you gave me?” And
writing clearer, more effective legislation
would lessen regulatory overreach and
reduce the ability of political parties to inter
pret the law the way they see fit. Technology
and AI should begin to make this kind of
waste of taxpayers’ money inexcusable,
and the government will have to adapt to
embrace these new technologies.
Mortgage and regulatory policies and local
housing requirements.
Excessive rules
around mortgages (servicing, origination
and securitization) have pushed most of the
mortgage business out of banks and have
increased the cost of mortgages by 20–30
basis points. Mortgage regulatory reform
alone would make the mortgage business far
safer and generate an additional 500,000
mortgages a year.
Local zoning requirements often limit afford
able housing and make it much more expen
sive. In addition, there are many examples of
excellent public/private affordable housing
programs, which only need to be replicated.
Fixing these regulations would go a long way
to helping people achieve this part of the
American Dream.
Red and “blue” tape, permitting reforms and
a little litigation reform.
Some politicians
think that all regulations are good — the more
the better. Given that many of these politicians
come from the blue side of America’s red-blue
divide, I think it’s more appropriate to call
excessive regulation “blue tape.” We should
aim for “good” regulations, continuously
improved, to both protect the public and
reduce costs. You probably need to have
real-life experience in dealing with regulations
to understand this.
Permitting and many associated regulations
take too long and not only extend the dura
tion of a project but also increase the cost
and sometimes stop projects from beginning.
Many countries, including Canada and
Singapore, have successfully introduced pol
icies to dramatically reduce permitting time.
Proper federal, state and local regulations,
along with permitting reform, are necessary
to reduce delays and legal bottlenecks. Mini
mizing “blue” tape — excessive regulatory
and related litigation costs — would make it
easier, cheaper and faster to build infrastruc
ture such as roads, schools, bridges, energy
facilities and housing. A little common sense
would go a long way.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
37
One last point: Excessive regulations make
it much harder to start a new business, and
they often reduce competition. And they
almost always hurt smaller companies more
than larger ones.
Policy uncertainty.
Legal, regulatory and tax
policies swing dramatically with changes in
administrations. This definitely reduces the
propensity for companies to invest and hire
employees.
Unreliable R&D policies.
We also need policy
certainty around research and development.
Government, businesses and universities are
all essential to our country’s R&D. On the
government side, this includes the Defense
Advanced Research Projects Agency, the
National Aeronautics and Space Administra
tion, and the National Institutes of Health,
among others. Businesses need consistent
tax policy for R&D; universities need consis
tent funding policy. The government is
directly responsible for R&D that no one else
can afford and that has been fundamental to
the country’s success. Government funding
of universities has made possible extraordi
nary discoveries, including many of our new
technologies. Businesses, in turn, use these
new technologies and perform their own
research to create new products and ser
vices. This system has been critical to the
incredible innovation machine of America.
Failure to recognize that capital formation
drives growth.
Central to growth in a country
and growth of its GDP are capital formation
and disciplined capital allocation. Countries
that do not promote capital formation,
including those that tolerate policies inhibit
ing capital formation, fail to thrive. Globally
competitive taxes and policy certainly are
critical for capital formation. Other good
policies include strengthening active capital
markets, tax incentives for capital expendi
tures and R&D, and savings and pension
plans (we support the new “Trump Accounts”
that, over time, will give all Americans an
economic stake in America) that incent
investment in equities, venture capital and
other investments.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
38
2025 estimate
1
Businesses (K)
# of small businesses
2
# of large businesses
3
38,000
22
Employment (M)
# of employees working at small businesses
2
# of employees working at large businesses
3
64
78
R&D (T)
Total spend by businesses
% by large businesses
3
$0.8
80%
CapEx (T)
Total CapEx
% by 1,000 largest U.S. public companies
4
$2.2
70%
1 2025 is projected based on published surveys for prior years, internal JPMorganChase estimates and proprietary
assumptions. Actual results may differ materially.
2 Small businesses defined as companies with fewer than 500 employees, including nonemployers.
3 Large businesses defined as companies with 500 employees or more.
4 Based on companies included in the Russell 1000 Index.
Source: Bloomberg, Annual Capital Expenditures Survey (ACES), U.S. Census Bureau; Business Enterprise Research and
Development (BERD) Survey, National Center for Science and Engineering Statistics and U.S. Census Bureau; FactSet;
Nonemployer Statistics (NES), U.S. Census Bureau; and Statistics of U.S. Businesses (SUSB), U.S. Census Bureau.
CapEx = Capital expenditures
K = Thousands
R&D = Research and development
M = Millions
T = Trillions
Capital Expenditures, Employment and R&D for Small and Large Businesses
There are also some good examples found
in other countries. In Sweden, an investment
savings account is available that simplifies
the investing process with favorable tax
treatment. Account holders can deposit and
withdraw funds at any time, and there is no
capital gains tax — just an annual tax of 1%
on the balance. This has dramatically
increased investment by retail investors into
the Swedish stock market. It may surprise
some of our readers that Sweden’s policies
have created a growing and innovative stock
market and that Sweden has more unicorns
and billionaires per person than America
does. Another example is Australia, which
has a wonderful retirement policy based on
superannuation, a savings account funded
by both employer and employee
contributions.
We must recognize that capital formation
drives capital expenditures and R&D, and
large companies lead the way: 80% of R&D is
done by large companies; and 70% of capital
expenditure comes from the largest 1,000
public companies. This is what drives pro
ductivity and GDP-per-person growth. And
small business and big business are symbi
otic. When a bigger company builds a bil
lion-dollar plant that creates 5,000 jobs, it
may also generate 25,000 jobs surrounding
the facility. These jobs are often small busi
nesses that are developed to support the
plant and those who live nearby.
People often refer to financialization of the
economy as a bad thing — and if they mean
pure speculation, then I understand. But a
country that is a barter economy effectively
has no financial assets. As capital formation
takes place, financial assets, including
stocks, bonds and loans, are created, which
represent all the investment. And as a coun
try grows and continually reinvests in higher
productivity, there will be more financial
assets per person. While the market value
of those assets may fluctuate, the growth in
financial assets is very good.
Reigniting the American Dream is
essential to strengthening our country:
taking three specific steps can help.
The American Dream itself rests upon our pro
viding, as best we can, equal opportunity to all
our citizens. Education and jobs are still the
best way to achieve this. Much of our education
system no longer truly meets our country’s
promise that its students graduate with the
skills they need to attain a good job.
In a number of our inner city and rural high
schools, under 50% of the students graduate,
and those who do often don’t have the skills
they need to hold a well-paying job. Increas
ingly, poverty has become intergenerational.
High schools and colleges should be judged
by their outcomes — do the students
graduate with job offers, and what do they
pay?
The growth of America was always driven by
productivity that matched capital investment
with skills, which is also the driver of individual
income. Fortunately, to fix our problems, all we
need to do is reorient what we do today. No
investment is required. It is essentially free; we
just need to redirect existing resources (the
United States spends almost $1 trillion a year
on K–12 education) into better outcomes.
We know exactly what to do, though systems
change is hard. There are millions of jobs avail
able for which training could be done in high
school, community college or special programs
outside of school. For example, there are train
ing programs lasting 12–24 weeks in computer
science, advanced manufacturing, cyber, data
science, program management, and nursing
and healthcare-related areas, among others.
These trainings should be certified and counted
as credits for an undergraduate or graduate
education. Many unions run excellent appren
ticeship and training programs that certify
workers for badly needed high-skilled jobs like
welding, electrical work, plumbing and others.
These jobs can pay well in excess of $100,000
a year.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
39
The federal government should use its consid
erable power to ask every school to report on
the jobs and income levels that their students
achieve when they leave school. This alone
would put tremendous pressure on schools
to become accountable — everyone would be
seeking out best practices so as not to be left
behind. I would even consider tying teacher
and administrator compensation to these goals.
We should double the Earned Income Tax
Credit, which raises the income of our
lowest-paid citizens, creates better social
outcomes and has the virtue of incenting
employment.
It is clear that, over the decades, the income
levels of low-wage workers have not kept up
with general growth and overall salaries despite
the fact that their work is still essential. It is also
clear that in any economy, there are groups of
people who are struggling to get ahead.
Approximately 23% of American workers make
less than $17 an hour. And close to 10% have
an income of $20,000 a year or less, partially
because they only have part-time jobs. Some
surveys show that over 60% of workers today
are living paycheck to paycheck, that hourly
workers have less predictable incomes and
that 35% of households with incomes below
$50,000 spend 95% on necessities — these
conditions are likely very stressful for many
families. We need to fix this.
Dramatically expanding the Earned Income
Tax Credit (EITC) does not help everyone, but it
would go a long way in helping those who need
it most. The tax code could play an important
role in easing the stress of individuals and fami
lies at the bottom of the economic ladder. One
way the code could incentivize labor force par
ticipation is to expand and reform the EITC. The
EITC gives an individual earning $18,000 a year
with two children a maximum tax credit of
$7,152 (and with no children a maximum tax
credit of $649). The average EITC across all
recipients is approximately $2,900, and close to
20% of eligible taxpayers don’t apply. I would
double this tax credit and remove the child
requirement. I would effectively make it a nega
tive monthly income tax as opposed to a year-
end credit. (It’s also important that any tax
credit and social benefits program be properly
phased in so it is both fair and it doesn’t dis-
incent work.)
While this would cost a lot of money, it has many
excellent virtues. It would give those with lower
income far more money to spend, without
government interference, on what they and
their families need — education, food, better
housing and so on. And much of it would be
spent locally, in lower-income neighborhoods.
This plan has the benefit of both rewarding work
and bringing more people into the workforce,
which would grow GDP. Jobs not only bring dig
nity but better social outcomes in terms of less
homelessness and crime, improved health out
comes and more household formation, among
other upsides. For many people, that first job
is just the first rung on the ladder of a career.
I have little doubt that this plan would more than
pay for itself over time. Many Republicans and
Democrats support this proposal as it helps to
create the American Dream for many people.
Now that we have strong border control,
we should finish proper immigration reform.
Uncontrolled immigration is highly disturbing
to affected populations around the world and
reduces the ability to manage legal and needed
immigration. In the United States, the number of
immigrants has increased by more than 60%
over the last 25 years. Since we have finally
gained control of our borders, I believe most
Americans would support the following:
increasing merit-based immigration, allowing
anyone who earns a degree here to stay, ensur
ing there are proper visas for seasonal workers,
enabling children born in this country to remain
and providing a rigorous path to citizenship for
law-abiding, undocumented immigrants.
Healthy and proper immigration would bring
great talent to our country and has been shown
to actually help grow the economy. There are
over 150,000 foreign students who receive a
degree annually in science, technology, engi
neering or math but have no guaranteed way of
staying here for the long term, although many
would choose to do so. Most students from
CRITICAL ISSUES FACING AMERICA AND THE WORLD
40
countries outside the United States pay full
freight to attend our universities, but many are
forced to take the skills they learned here back
home. From my vantage point, that means one
of our largest exports is brainpower.
The last time we had major immigration reform
was in 1986 under President Reagan. There
have been two times in the last 20 years when
Congress almost passed an immigration reform
bill that looks a lot like what I outlined above.
Let’s just get it done this time.
The Congressional Budget Office estimated
that the failure to pass immigration reform is
costing us 0.3% of GDP a year. Immigration has
been one of the great strengths of this country
— we should never forget that.
Good U.S. foreign economic policy
ensures that America is first (though
not alone) — it strengthens the U.S.
economy and that of our critical allies.
The goal of U.S. economic foreign policy should
be twofold (after protecting national security):
1.
Maximize the growth and competitiveness
of America — both in the United States and
for our companies doing business
internationally.
2. Simultaneously strengthen our allies
economically and bind them closer to the
United States and like-minded Western
democracies.
Economic weakening of the world’s democra
cies or a fragmentation of their economic bonds
could lead to truly adverse consequences. This is
precisely what some of our adversaries and many
autocratic nations want — it is their stated objec
tive. They would like to see all of our allies far less
dependent on the United States and therefore far
more dependent on them. In this scenario, many
countries would be compelled to seek deeper
economic bonds with some possible bad actors
— over time, they could become vassals of these
countries and unable to avoid coercion from
them. The following are a few ideas on how we
can promote healthy economic engagement
(and combat unfair trade) while strengthening
both our own and our allies’ economies. And I will
leave you with one big, bold idea.
There are many ways to promote good U.S.
foreign economic policy.
America’s ties with the rest of the world are
already extensive (see U.S. global foreign direct
investment and portfolio investment), and the
levers to accomplish our foreign policy goals
extend to tax policy (and our international com
petitiveness), investment policy and trade pol
icy, which encompass tariffs, quotas, regulatory
barriers, immigration policies and so on. While
tariffs have certainly “brought people to the
table” and have allowed us to start to correct
some of our past bad trade practices, we need
to look at U.S. foreign economic policy compre
hensively. The ultimate goal should be to create
a system with our allies of stability and consis
tency, in addition to fairness and mutual benefit.
Not only should our foreign economic policy
help us grow as a nation, but it should also help
other countries grow. For example, the United
States has the best capital markets in the world,
large and small, public and private, and we have
already described how proper capital formation
and allocation are key to America’s vibrant
economic system. Another goal of our foreign
economic policy should be to help other coun
tries develop their capital markets. In addition,
there are excellent economic policies found
elsewhere in the world, and we should emulate
them to help more countries thrive.
Even the proper use of strategic communica
tions can foster entrepreneurship and the
universal principles of freedom, which will also
drive growth and prosperity.
The United States does not do enough to foster
American business expansion overseas, partic
ularly in complex parts of the world. Most other
nations, China in particular, encourage the
growth of their companies overseas. China,
through their Belt & Road Initiative and basic
foreign direct investment (see Size of the
Financial Sector/Industry chart on page 29),
has massively invested, particularly in emerg
ing and developing countries around the world.
America has recently begun to expand its
development finance institution and its
Export-Import Bank to help U.S. businesses
grow overseas. This should be encouraged.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
41
However, the worst outcome to trade’s evolution
over the past several decades is that Americans
have become too dependent on some non
aligned foreign countries for many things
essential to our national security and resiliency.
This extends, as mentioned previously, from
rare earths to the manufacturing of semicon
ductors. Unfortunately, we need industrial
policy to remedy this.
America already trades with more than 200
countries and territories. We should strike the
best — and, of course, the most fair — trade
agreements that we can. We can do this while
maintaining our close economic relations with
our allies.
Industrial policy has become a necessary
tool now, but it should be done right. It
should be limited and market-based.
Unfortunately, we need industrial policy to guar
antee our national security and resiliency. And it
also could be used to combat unfair mercantilist
policies around critical industries. These policies
uniquely could be completely
unilateral
.
Industrial policy mechanisms, when used,
should be as targeted and as simple as possi
ble. They come in many guises: grants, cheap
loans, equity investing, purchase agreements
and others. The cleanest of these is tax credits
in various forms. Whatever the policy, two rules
should not be violated: (1) there should be no
social engineering — this is not a jobs program
(the Jones Act meant to preserve jobs in the
Merchant Marine has basically destroyed our
Merchant Marine and merchant ship building
business) and (2) for the most part, the market
should allocate capital, not the government.
Industrial policy can easily devolve into a
buffet where corporate America gorges at the
expense of the taxpayer. While there are certain
circumstances that require the government
to allocate capital (think infrastructure and
national security), generally the government is
simply not good at allocating capital in a free
market. America does best not with central
planning but with consistent and clear policies
that are conducive to growth.
We need to combat unfair trade — and
strive for free and fair trade.
For hundreds of years, countries have used
trade practices to get a leg up on other coun
tries. This economic competition is often exer
cised through industrial and trade policy, and it
comes in many forms: banning or limiting trade
(quotas), tariffs, subsidies, grants, tax credits
or accelerated depreciation, loan guarantees,
long-term purchase agreements and capital
controls. There are also other unfair trade prac
tices that need to be mentioned; e.g., nontrade
barriers, such as regulations that effectively
stop specific types of trade and various unfair
tax policies that range from value-added taxes
to a particular country’s tax schemes. Practices
such as permitting countries to circumvent
trade restrictions imposed on them — for exam
ple, allowing any country to use agreements it
has with other nations to bypass tariffs on their
goods — can and should be stopped.
All of these trade practices are generally used
as tools to give a company or an industry an
unfair competitive advantage, and when used
together, they can create unbeatable econo
mies of scale. In their harshest form, trade prac
tices can be used by countries as a tactic to try
to unfairly dominate whole industries. This
should not be allowed.
Trade agreements have many flaws and need to
be carefully negotiated. Had the World Trade
Organization done its job well, we would not
have such serious trade issues — it is in need
of serious reform. Obviously, where the United
States is treated unfairly, we should demand
that those agreements be fixed. It would also be
good to acknowledge that we have sometimes
treated others unfairly (for example, parts of the
Inflation Reduction Act unfairly favor American
business).
We also need to acknowledge that there have
been real negative job impacts as a result of
trade (in 1990, there were 18 million jobs in
manufacturing in this country versus 13 million
today), which are usually concentrated around
certain geographic areas and businesses. The
loss of these jobs also had a serious negative
effect on social outcomes, including depres
sion, divorce and others.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
42
The reason we need industrial policy is because
many of the things we need to do for national
security would fail without government support.
It just needs to be designed wisely. The ques
tion, however, is: What conditions require indus
trial policy and what guardrails are needed so
the policy does not grow unchecked and distort
the free market?
Trade is increasingly complex, and the
United States needs to stay deeply
engaged.
Trade is very complex and constantly changing.
I have no doubt that other nations will be thinking
about their future trade policies as they try to
adjust to demands from both the United States
and China, as well as weigh their own national
security needs. It is in our country’s interest that
our allies remain economically tied to the United
States. Many nations have joined, or are negoti
ating to join, large transregional free trade
groups. Europe, for goods, is already essentially
one, and the European Union (EU) signed a free
trade agreement with India and the EU-Mercosur
Partnership Agreement, a large free trade agree
ment with Argentina, Brazil, Paraguay and
Uruguay. The Comprehensive and Progressive
Agreement for Trans-Pacific Partnership is
another large free trade agreement between
12 countries in the West and Indo-Pacific. Being
excluded from an increasing number of these
free trade agreements will, over time, weaken
America’s competitiveness and companies. It
will also mean that America will not have a seat
at the table when policies, strategies and proc
esses are being established. Therefore, I believe
formulating trade agreements should be drawn
up
alongside
our allies if possible.
America needs Europe to succeed — and
it’s currently on a bad path.
It is very hard to predict the future, and even
when we analyze history, hindsight is not 20/20.
We still analyze the disintegration of the Roman
Empire, the British Empire, the Chinese Empire
and the failures after World War I that led to
Nazi Germany. However, there are major trends
that we should study — they are like shifting
tectonic plates that can determine the future
course of history.
I believe we are staring one in the face: the slow
but constant decline and fragmentation of
Europe. Europe is entering a decisive decade,
and it is unable to act. The EU was an extraordi
nary accomplishment — nations coming
together and using political and peaceful
means to settle differences. And this after
a millennium of terrible wars. It worked, but it
only went halfway. Europe never finished the
economic union (see the Draghi report), which
meant that European countries constantly
underperformed economically. This has led to
their GDP relative to the United States going
from 90% in the year 2000 to approximately
70% today. This fragmentation remains a
structural drag on competitiveness. As former
European Central Bank President Mario Draghi
has noted, internal EU market barriers function
like “hard tariffs” of approximately 45% for
manufacturing and 110% for services. Those
barriers reflect not a failure of ambition but
rather a failure of integration. This has led to
a lack of scale for their major businesses and
a lack of mobility for both capital and people.
EU nations also created whole new layers of
bureaucracy that reduced innovation, growth
and investment among other things. This will
continue unless European leaders dramatically
change course. If they don’t, they will eventually
be unable to afford their social safety nets,
restrengthen their nations’ militaries and grow
their economies. The EU is currently home to
world-class companies, deep pools of savings
and a talented workforce. But without new EU
direction, their major global companies will
weaken, faced with very strong American and
Chinese competition. The ultimate loser in all
this will be Europe and all its citizens — and it
will hurt the United States as well.
Europe and America are each other’s largest
trade partners at $2 trillion a year. The United
States and Europe remain the twin engines of
the world economy, with the transatlantic rela
tionship reaching a record $9.8 trillion in 2025.
While America and Europe do have real differ
ences, we believe that a stronger Europe,
militarily and economically, is in America’s
self-interest.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
43
Europe needs to rebuild its military and its
defense industrial base.
Almost all European countries have dramati
cally increased their budgets to strengthen
their militaries — all allies now meet or exceed
their current North Atlantic Treaty Organization
(NATO) commitments. We can and should clarify
and reaffirm NATO’s goals and mission. The
goal should be to end up with a far stronger
NATO and fit for purpose.
Yet Europe’s defense industrial base is still not
fit for purpose. This is as much an economic
and industrial challenge as a military one. The
continent needs enduring production capacity,
coordinated procurement and dual-use manu
facturing that serves both commercial and
defense sectors.
Europe’s defense will also benefit from main
taining the deep interconnectedness with the
United States that has anchored Euro-Atlantic
security for decades. Efforts to grow Europe’s
defense industrial base should avoid measures
— such as strict “Buy European” content
requirements — designed to favor EU suppliers
but that end up shutting out U.S. firms and, with
them, the small- and medium-sized suppliers
that many European defense manufacturers still
rely upon.
Europe will have a hard time competing with the
United States on the large-scale production of
certain very advanced military capabilities, like
nuclear submarines, advanced airplanes, mili
tary intelligence and satellites among others.
They should rely on our country for this, which
means we need to be totally reliable. European
nations should focus on the types of things they
can build very effectively, like drones, tanks,
armaments and others. They do, however, need
to do this efficiently — not inefficiently. They do
this now by, for example, building 14 different
types of tanks all over the continent. The military
equipment of NATO needs to be interoperable.
While they need several manufacturers to
compete to build most types of equipment,
they should not have so many that it’s highly
inefficient. And while the successful manufac
turers can have plants in different countries,
this should not be treated as a jobs creation
program.
Finally, a transatlantic approach to some
defense production — such as RTX’s partner
ship with Germany’s Diehl Defence on air
defense systems — will deliver more scale,
more interchangeability and more capability
than any go-it-alone model.
We need one big, beautiful trade deal for
Europe.
The United States should do whatever it can
to help — or even push — Europe to take all
necessary steps to reverse its decline and
strengthen its economy. We should support
them to act on what is in their own self-interest:
adopting the reforms in the Draghi report. For
example, strengthening the EU’s internal mar
ket structure — through completion of the Capi
tal Markets Union and Banking Union — would
be transformative for Europe’s ability to scale
and compete. A more integrated financial
system would unlock investment for strategic
industries; enhance stability and reduce frag
mentation costs; enable more European banks
to compete globally; and make the continent a
more attractive environment for foreign firms.
For companies like ours, it would create tougher
competition (which in the long run is good), but
it would also enable us to serve clients more
efficiently across borders — lowering complex
ity, improving capital allocation and, ultimately,
increasing growth.
I know this is a long shot, but we could offer
Europe one unbelievable inducement: If it
commits to economic and military reforms, the
United States would negotiate
one big, beautiful
free trade agreement with all of Europe
. If I
could, I would throw in similar action with
Australia, Japan, the Philippines, South Korea
and other nations. This would be an economic
and geopolitical home run for the United States
and for Europe, allowing us to set the global
rules around trade (if you want to access to over
40% of the world’s market), and it would bind
Western allies together in the face of autocratic
pressure.
We tried this before in the so-called T-TIP
(Transatlantic Trade and Investment Partner
ship) proposal a decade ago. Clearly, it would be
hard to do because we would need to resolve
existing tax and regulatory issues around digi
tal services, as well as extraterritorial regula
CRITICAL ISSUES FACING AMERICA AND THE WORLD
44
“We hold these truths to be self-evident, that all men
are created equal.”
“That they are endowed by their Creator with certain
unalienable Rights, that among these are Life, Liberty
and the pursuit of Happiness.”
“With liberty and justice for all.”
tions around climate reporting (the highly mis
guided Corporate Sustainability Due Diligence
Directive disclosure rules). And of course, we
are all going to have to be a little flexible about
one of the most challenging issues — agricul
ture — but with hard work, all of these concerns
could be resolved. And the benefits would be
enormous. Doing big things is never easy.
Strong American leadership is required —
there is no real alternative.
Some political leaders have said that there is a
“rupture” between America and the Western
world —that the red lines have been crossed
and there is no return to the prior system. I com
pletely disagree. There is no practical replace
ment to the prior system. It has not ruptured,
but it needs reform. The middle-sized nations
do not have real alternatives in terms of building
a unified military or a unified economy that can
compete effectively with the United States and
China. If these middle nations did, the result
would look a lot like what Europe is today:
dysfunctional. The only practical alternative
is to fix the current situation.
The United States and Europe have an extraordi
nary number of commonalities, including values
deeply held. For more than 75 years since the
end of World War II, the United States and Europe
have worked together to resolve most major
global economic or military challenges and in
fighting terrorism and nuclear proliferation. We
need this cooperation for the next 75 years.
I do not want to contemplate the opposite. With
out American leadership, there would be a huge
vacuum. If not us, who? We are the only country
that has the capability to do it. Fragmented
relationships with and among our extensive
allies could lead to an “every nation for them
selves” mentality. America would become more
isolated, the U.S. dollar would no longer be the
world’s reserve currency and autocratic nations
would rejoice. Need I say more?
We need to strengthen our commitment
to the values and virtues that created
America and to the Constitution, which
embeds these values in law.
The Constitution is the legal embodiment of
the values and principles that define America.
We pledge allegiance to the Constitution, but
it’s the values that are the true foundation of
America’s success.
The values we uphold unite us.
Our country’s values transcend any political
stance — libertarian, conservative, progressive,
Democrat or Republican. These values reach
deep into American life: to provide justice and
equal opportunity to all, to try to lift up all of
our citizens, to dedicate to a strong national
defense, to promote free enterprise, to have
freedom of religion, and to respect family,
country, self-reliance, labor and laborers, and
common sense. These values are not mutually
exclusive and should be embraced and upheld
by all of us.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
45
We need to be stronger.
These principles allow individuals to pursue
life as they lawfully see fit. These extraordinary
legal rights come with important civic responsi
bilities. To be able to address our problems at
home and abroad, we must be strong. And our
core strength is based upon our commitment to
our values. If the soul of America is not strong,
then the rest will be weak.
While we should acknowledge America’s flaws,
they should not be used to pull apart our coun
try. We need to believe in ourselves and get
back to work, not tear each other down. Many
of the blind ideologies being bandied about
run counter to our fundamental principles.
Ideologues often adhere to rigid beliefs and,
when extreme, seek to impose those beliefs on
others; in radical forms of fanaticism, there is
no room for individual differences. While we
should listen to all people and all viewpoints,
we should not allow ourselves to become wea
ponized. We should fight blind ideologies, like
anti-Semitism, and any form of racism however
and whenever it rears its ugly head.
I believe we have gotten a little too soft.
Working hard, having ambition, demonstrating
self-responsibility and loving your nation
(particularly this nation) are wonderful qualities.
We need to rededicate ourselves to these
values. Proper civic engagement should better
reflect President Kennedy’s statement, “Ask
not what your country can do for you, but what
you can do for your country.”
We also cannot forget that we have to deal
with the world we have — not the one we want.
Directly related to our values should be our
strong commitment to defending them, includ
ing militarily. Tough minds and realpolitik are
absolutely required in our complex world and
in our global relationships.
It is incumbent on us to educate ourselves,
our fellow citizens and future generations —
starting in grammar school — about American
values, our history and our ongoing pursuit of
a more perfect democracy.
CRITICAL ISSUES FACING AMERICA AND THE WORLD
46
Jamie Dimon
Chairman and Chief Executive Officer
April 6, 2026
In Closing
I hope you are as proud of what we all have achieved — as a business, as a
bank and as a community investor — as I am. I can’t even begin to express
my heartfelt appreciation and respect for the tremendous character and
capabilities of the management team that guided us through the good times
and the bad times to where we stand today. And I recognize that we are
enormously indebted to the achievements of many others who came before
us in building this exceptional company of ours.
We are delighted to have opened our new headquarters in New York City,
which is a beautiful physical manifestation of our company. It is a great example
of how we treat our people with wonderful places to work — in New York City,
across the country and around the world. Our new headquarters also shows
how you can deconstruct something and rebuild it in a powerful way — that’s
good for our colleagues, our clients and our community.
I would also like to express my deep gratitude to the 320,000+ employees,
and their families, of JPMorganChase. Through these annual letters, I hope
shareholders and all readers have gained a deeper understanding of what
it takes to keep your company strong in a rapidly changing world.
Finally, we sincerely hope to see the world on the path to peace and prosperity.
47
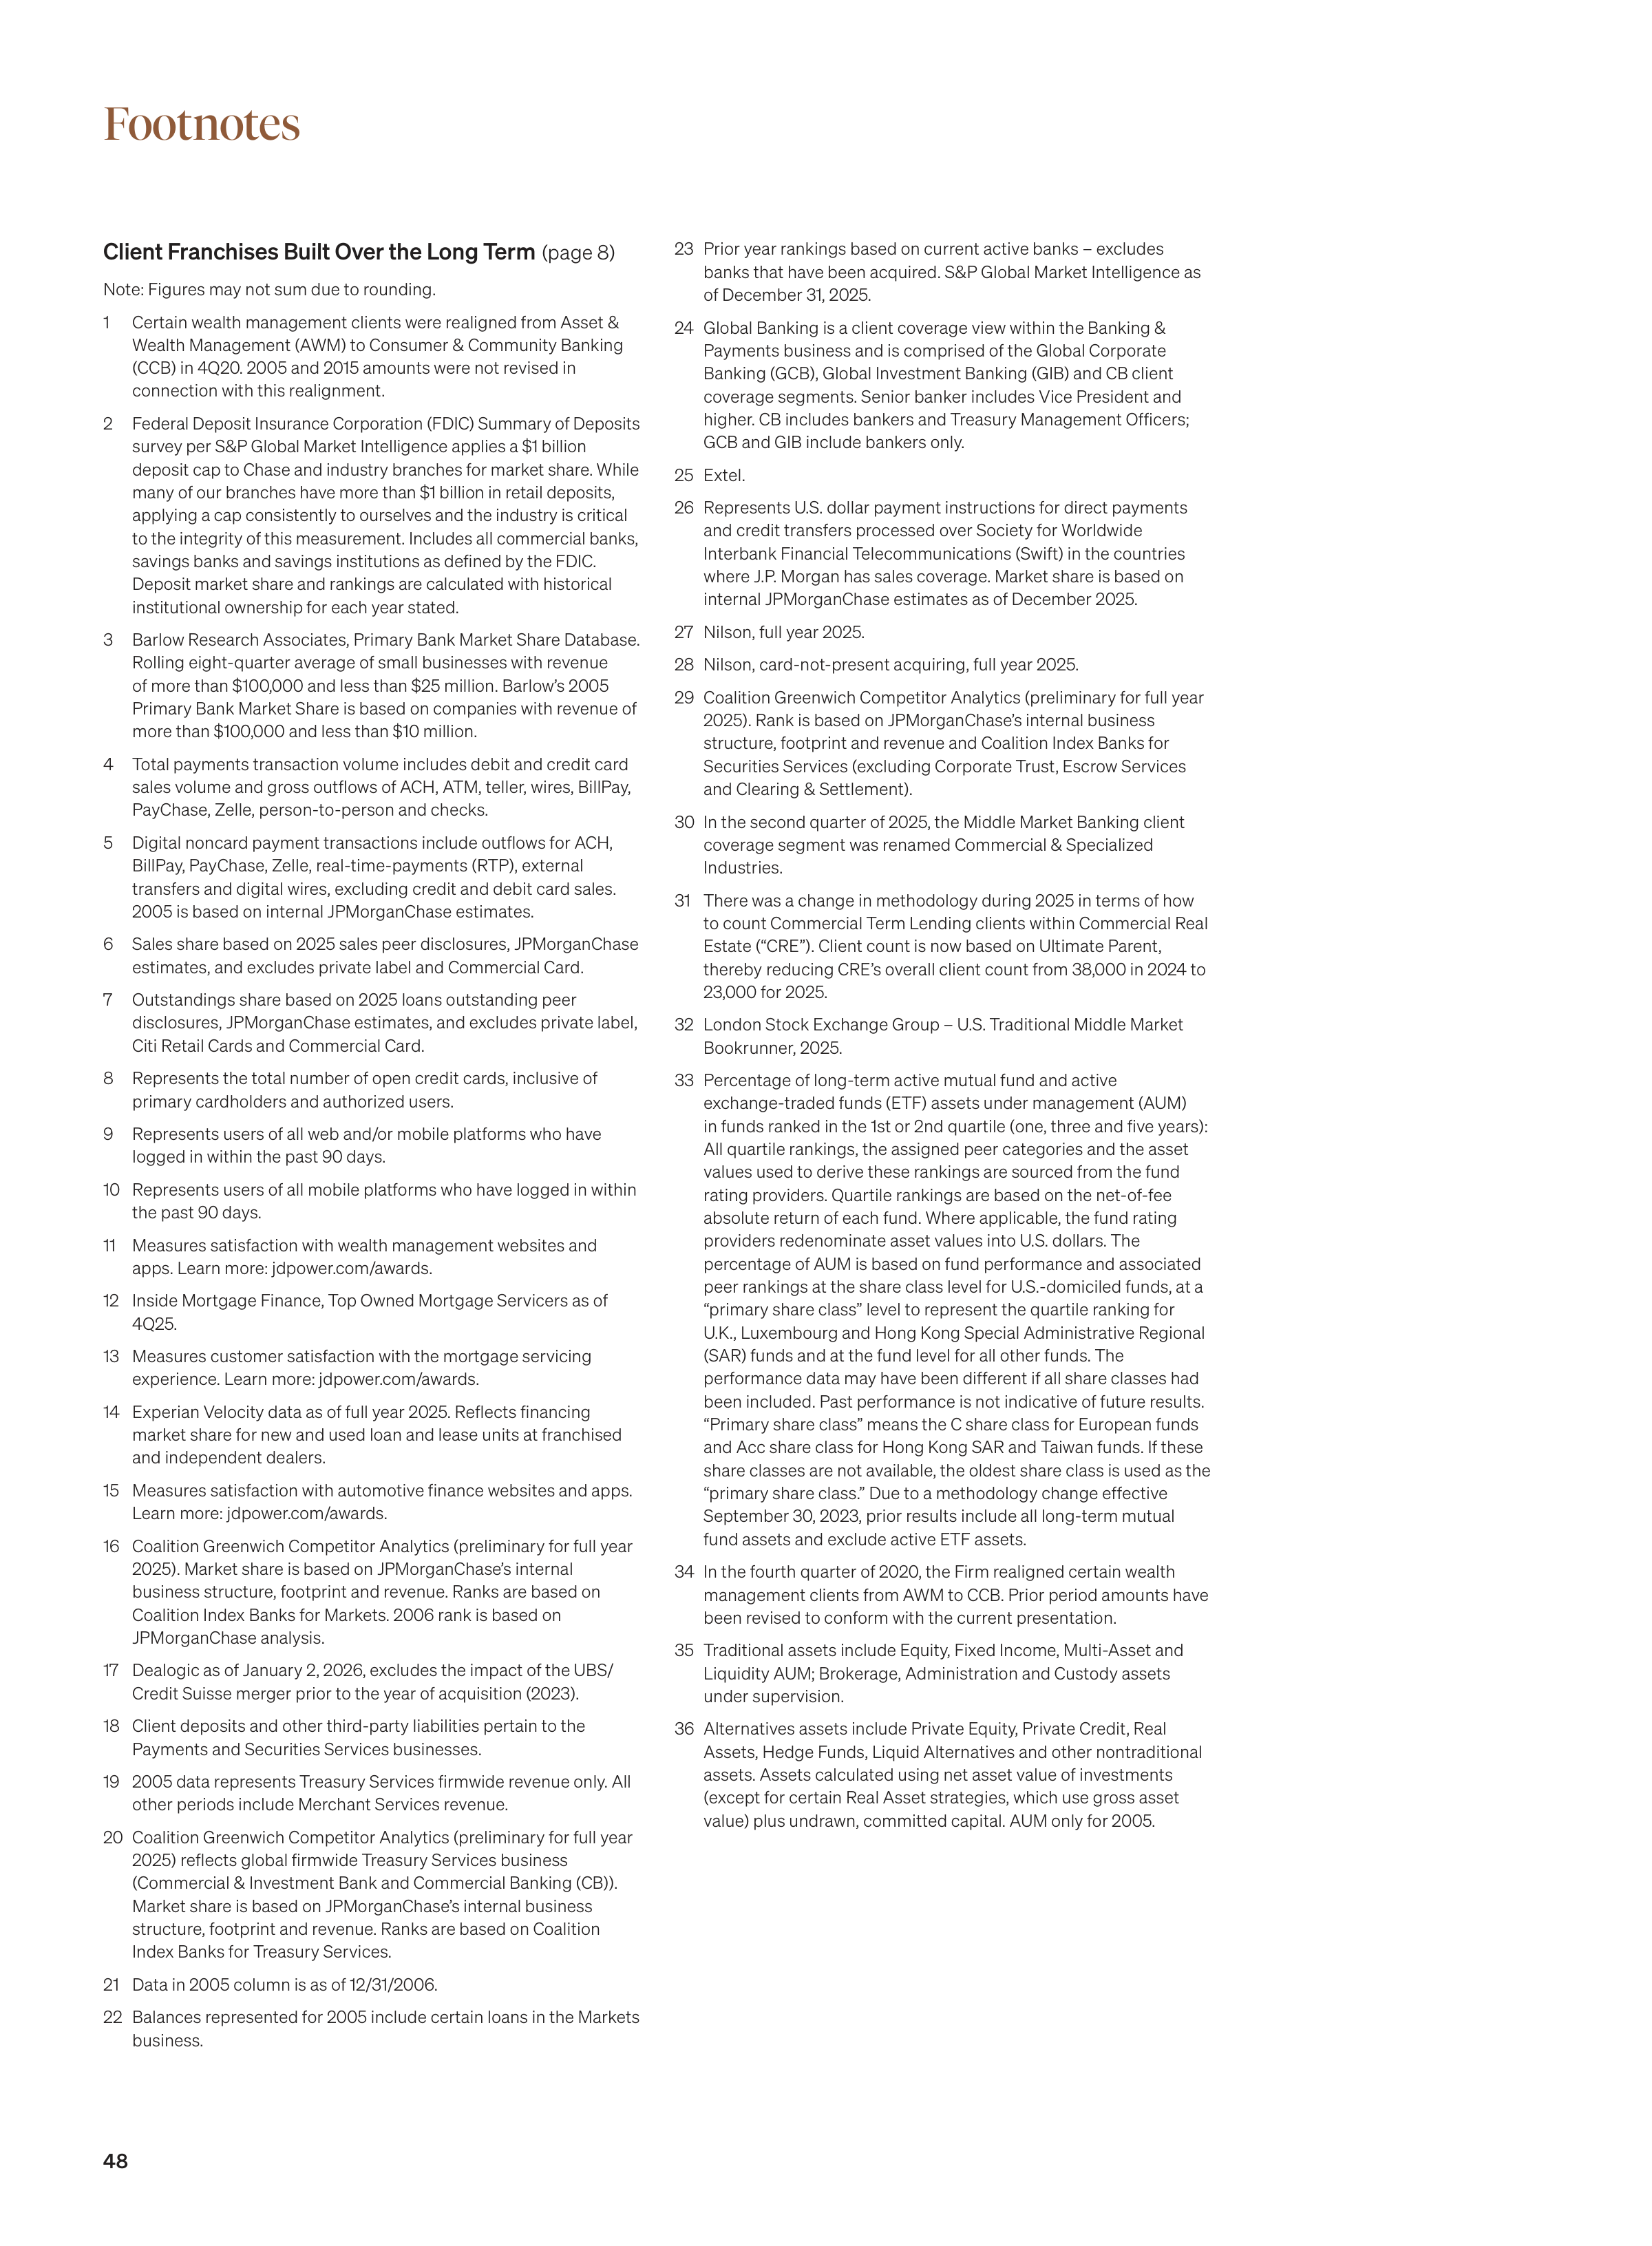
Client Franchises Built Over the Long Term
(page 8)
Note: Figures may not sum due to rounding.
1
Certain wealth management clients were realigned from Asset &
Wealth Management (AWM) to Consumer & Community Banking
(CCB) in 4Q20. 2005 and 2015 amounts were not revised in
connection with this realignment.
2
Federal Deposit Insurance Corporation (FDIC) Summary of Deposits
survey per S&P Global Market Intelligence applies a $1 billion
deposit cap to Chase and industry branches for market share. While
many of our branches have more than $1 billion in retail deposits,
applying a cap consistently to ourselves and the industry is critical
to the integrity of this measurement. Includes all commercial banks,
savings banks and savings institutions as defined by the FDIC.
Deposit market share and rankings are calculated with historical
institutional ownership for each year stated.
3
Barlow Research Associates, Primary Bank Market Share Database.
Rolling eight-quarter average of small businesses with revenue
of more than $100,000 and less than $25 million. Barlow’s 2005
Primary Bank Market Share is based on companies with revenue of
more than $100,000 and less than $10 million.
4
Total payments transaction volume includes debit and credit card
sales volume and gross outflows of ACH, ATM, teller, wires, BillPay,
PayChase, Zelle, person-to-person and checks.
5
Digital noncard payment transactions include outflows for ACH,
BillPay, PayChase, Zelle, real-time-payments (RTP), external
transfers and digital wires, excluding credit and debit card sales.
2005 is based on internal JPMorganChase estimates.
6
Sales share based on 2025 sales peer disclosures, JPMorganChase
estimates, and excludes private label and Commercial Card.
7
Outstandings share based on 2025 loans outstanding peer
disclosures, JPMorganChase estimates, and excludes private label,
Citi Retail Cards and Commercial Card.
8
Represents the total number of open credit cards, inclusive of
primary cardholders and authorized users.
9
Represents users of all web and/or mobile platforms who have
logged in within the past 90 days.
10 Represents users of all mobile platforms who have logged in within
the past 90 days.
11
Measures satisfaction with wealth management websites and
apps. Learn more: jdpower.com/awards.
12
Inside Mortgage Finance, Top Owned Mortgage Servicers as of
4Q25.
13
Measures customer satisfaction with the mortgage servicing
experience. Learn more: jdpower.com/awards.
14 Experian Velocity data as of full year 2025. Reflects financing
market share for new and used loan and lease units at franchised
and independent dealers.
15
Measures satisfaction with automotive finance websites and apps.
Learn more: jdpower.com/awards.
16
Coalition Greenwich Competitor Analytics (preliminary for full year
2025). Market share is based on JPMorganChase’s internal
business structure, footprint and revenue. Ranks are based on
Coalition Index Banks for Markets. 2006 rank is based on
JPMorganChase analysis.
17
Dealogic as of January 2, 2026, excludes the impact of the UBS/
Credit Suisse merger prior to the year of acquisition (2023).
18 Client deposits and other third-party liabilities pertain to the
Payments and Securities Services businesses.
19
2005 data represents Treasury Services firmwide revenue only. All
other periods include Merchant Services revenue.
20 Coalition Greenwich Competitor Analytics (preliminary for full year
2025) reflects global firmwide Treasury Services business
(Commercial & Investment Bank and Commercial Banking (CB)).
Market share is based on JPMorganChase’s internal business
structure, footprint and revenue. Ranks are based on Coalition
Index Banks for Treasury Services.
21
Data in 2005 column is as of 12/31/2006.
22 Balances represented for 2005 include certain loans in the Markets
business.
Footnotes
23 Prior year rankings based on current active banks – excludes
banks that have been acquired. S&P Global Market Intelligence as
of December 31, 2025.
24 Global Banking is a client coverage view within the Banking &
Payments business and is comprised of the Global Corporate
Banking (GCB), Global Investment Banking (GIB) and CB client
coverage segments. Senior banker includes Vice President and
higher. CB includes bankers and Treasury Management Officers;
GCB and GIB include bankers only.
25 Extel.
26 Represents U.S. dollar payment instructions for direct payments
and credit transfers processed over Society for Worldwide
Interbank Financial Telecommunications (Swift) in the countries
where J.P. Morgan has sales coverage. Market share is based on
internal JPMorganChase estimates as of December 2025.
27 Nilson, full year 2025.
28 Nilson, card-not-present acquiring, full year 2025.
29 Coalition Greenwich Competitor Analytics (preliminary for full year
2025). Rank is based on JPMorganChase’s internal business
structure, footprint and revenue and Coalition Index Banks for
Securities Services (excluding Corporate Trust, Escrow Services
and Clearing & Settlement).
30 In the second quarter of 2025, the Middle Market Banking client
coverage segment was renamed Commercial & Specialized
Industries.
31
There was a change in methodology during 2025 in terms of how
to count Commercial Term Lending clients within Commercial Real
Estate (“CRE”). Client count is now based on Ultimate Parent,
thereby reducing CRE’s overall client count from 38,000 in 2024 to
23,000 for 2025.
32 London Stock Exchange Group – U.S. Traditional Middle Market
Bookrunner, 2025.
33 Percentage of long-term active mutual fund and active
exchange-traded funds (ETF) assets under management (AUM)
in funds ranked in the 1st or 2nd quartile (one, three and five years):
All quartile rankings, the assigned peer categories and the asset
values used to derive these rankings are sourced from the fund
rating providers. Quartile rankings are based on the net-of-fee
absolute return of each fund. Where applicable, the fund rating
providers redenominate asset values into U.S. dollars. The
percentage of AUM is based on fund performance and associated
peer rankings at the share class level for U.S.-domiciled funds, at a
“primary share class” level to represent the quartile ranking for
U.K., Luxembourg and Hong Kong Special Administrative Regional
(SAR) funds and at the fund level for all other funds. The
performance data may have been different if all share classes had
been included. Past performance is not indicative of future results.
“Primary share class” means the C share class for European funds
and Acc share class for Hong Kong SAR and Taiwan funds. If these
share classes are not available, the oldest share class is used as the
“primary share class.” Due to a methodology change effective
September 30, 2023, prior results include all long-term mutual
fund assets and exclude active ETF assets.
34 In the fourth quarter of 2020, the Firm realigned certain wealth
management clients from AWM to CCB. Prior period amounts have
been revised to conform with the current presentation.
35 Traditional assets include Equity, Fixed Income, Multi-Asset and
Liquidity AUM; Brokerage, Administration and Custody assets
under supervision.
36 Alternatives assets include Private Equity, Private Credit, Real
Assets, Hedge Funds, Liquid Alternatives and other nontraditional
assets. Assets calculated using net asset value of investments
(except for certain Real Asset strategies, which use gross asset
value) plus undrawn, committed capital. AUM only for 2005.
48
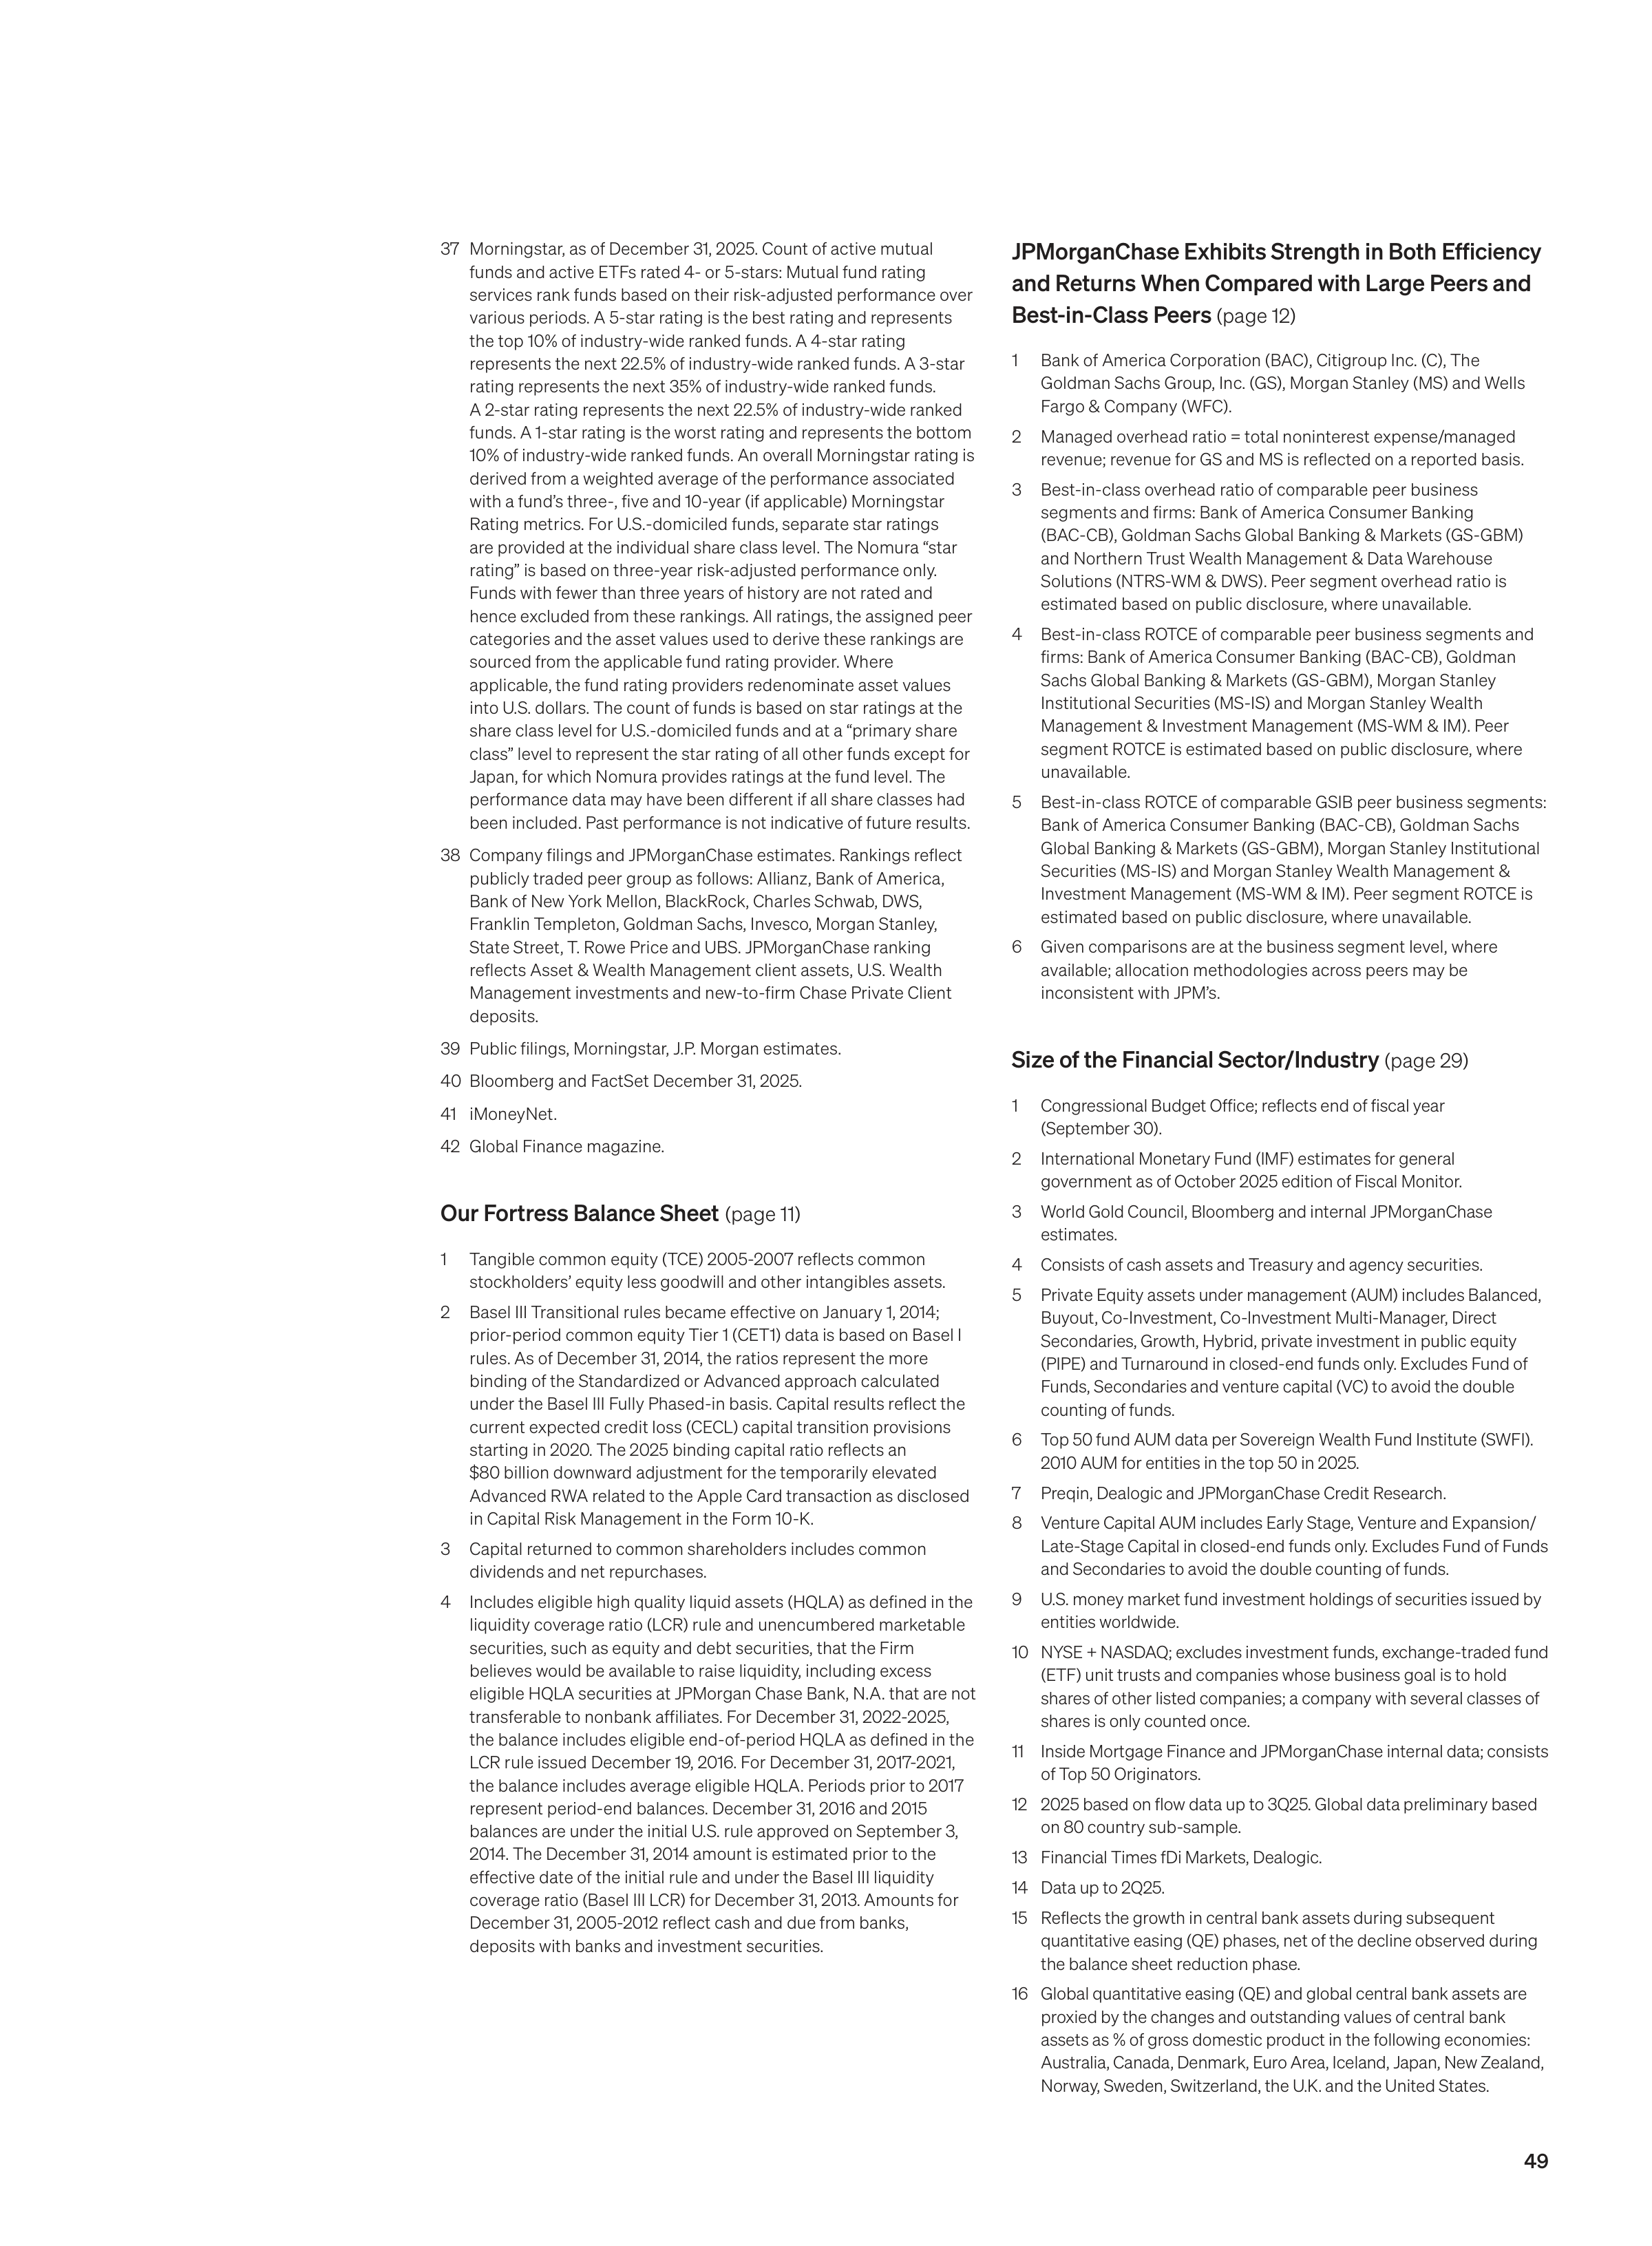
37 Morningstar, as of December 31, 2025. Count of active mutual
funds and active ETFs rated 4- or 5-stars: Mutual fund rating
services rank funds based on their risk-adjusted performance over
various periods. A 5-star rating is the best rating and represents
the top 10% of industry-wide ranked funds. A 4-star rating
represents the next 22.5% of industry-wide ranked funds. A 3-star
rating represents the next 35% of industry-wide ranked funds.
A 2-star rating represents the next 22.5% of industry-wide ranked
funds. A 1-star rating is the worst rating and represents the bottom
10% of industry-wide ranked funds. An overall Morningstar rating is
derived from a weighted average of the performance associated
with a fund’s three-, five and 10-year (if applicable) Morningstar
Rating metrics. For U.S.-domiciled funds, separate star ratings
are provided at the individual share class level. The Nomura “star
rating” is based on three-year risk-adjusted performance only.
Funds with fewer than three years of history are not rated and
hence excluded from these rankings. All ratings, the assigned peer
categories and the asset values used to derive these rankings are
sourced from the applicable fund rating provider. Where
applicable, the fund rating providers redenominate asset values
into U.S. dollars. The count of funds is based on star ratings at the
share class level for U.S.-domiciled funds and at a “primary share
class” level to represent the star rating of all other funds except for
Japan, for which Nomura provides ratings at the fund level. The
performance data may have been different if all share classes had
been included. Past performance is not indicative of future results.
38 Company filings and JPMorganChase estimates. Rankings reflect
publicly traded peer group as follows: Allianz, Bank of America,
Bank of New York Mellon, BlackRock, Charles Schwab, DWS,
Franklin Templeton, Goldman Sachs, Invesco, Morgan Stanley,
State Street, T. Rowe Price and UBS. JPMorganChase ranking
reflects Asset & Wealth Management client assets, U.S. Wealth
Management investments and new-to-firm Chase Private Client
deposits.
39 Public filings, Morningstar, J.P. Morgan estimates.
40 Bloomberg and FactSet December 31, 2025.
41
iMoneyNet.
42 Global Finance magazine.
Our Fortress Balance Sheet
(page 11)
1
Tangible common equity (TCE) 2005-2007 reflects common
stockholders’ equity less goodwill and other intangibles assets.
2
Basel III Transitional rules became effective on January 1, 2014;
prior-period common equity Tier 1 (CET1) data is based on Basel I
rules. As of December 31, 2014, the ratios represent the more
binding of the Standardized or Advanced approach calculated
under the Basel III Fully Phased-in basis. Capital results reflect the
current expected credit loss (CECL) capital transition provisions
starting in 2020. The 2025 binding capital ratio reflects an
$80 billion downward adjustment for the temporarily elevated
Advanced RWA related to the Apple Card transaction as disclosed
in Capital Risk Management in the Form 10-K.
3
Capital returned to common shareholders includes common
dividends and net repurchases.
4
Includes eligible high quality liquid assets (HQLA) as defined in the
liquidity coverage ratio (LCR) rule and unencumbered marketable
securities, such as equity and debt securities, that the Firm
believes would be available to raise liquidity, including excess
eligible HQLA securities at JPMorgan Chase Bank, N.A. that are not
transferable to nonbank affiliates. For December 31, 2022-2025,
the balance includes eligible end-of-period HQLA as defined in the
LCR rule issued December 19, 2016. For December 31, 2017-2021,
the balance includes average eligible HQLA. Periods prior to 2017
represent period-end balances. December 31, 2016 and 2015
balances are under the initial U.S. rule approved on September 3,
2014. The December 31, 2014 amount is estimated prior to the
effective date of the initial rule and under the Basel III liquidity
coverage ratio (Basel III LCR) for December 31, 2013. Amounts for
December 31, 2005-2012 reflect cash and due from banks,
deposits with banks and investment securities.
JPMorganChase Exhibits Strength in Both Efficiency
and Returns When Compared with Large Peers and
Best-in-Class Peers
(page 12)
1
Bank of America Corporation (BAC), Citigroup Inc. (C), The
Goldman Sachs Group, Inc. (GS), Morgan Stanley (MS) and Wells
Fargo & Company (WFC).
2
Managed overhead ratio = total noninterest expense/managed
revenue; revenue for GS and MS is reflected on a reported basis.
3
Best-in-class overhead ratio of comparable peer business
segments and firms: Bank of America Consumer Banking
(BAC-CB), Goldman Sachs Global Banking & Markets (GS-GBM)
and Northern Trust Wealth Management & Data Warehouse
Solutions (NTRS-WM & DWS). Peer segment overhead ratio is
estimated based on public disclosure, where unavailable.
4
Best-in-class ROTCE of comparable peer business segments and
firms: Bank of America Consumer Banking (BAC-CB), Goldman
Sachs Global Banking & Markets (GS-GBM), Morgan Stanley
Institutional Securities (MS-IS) and Morgan Stanley Wealth
Management & Investment Management (MS-WM & IM). Peer
segment ROTCE is estimated based on public disclosure, where
unavailable.
5
Best-in-class ROTCE of comparable GSIB peer business segments:
Bank of America Consumer Banking (BAC-CB), Goldman Sachs
Global Banking & Markets (GS-GBM), Morgan Stanley Institutional
Securities (MS-IS) and Morgan Stanley Wealth Management &
Investment Management (MS-WM & IM). Peer segment ROTCE is
estimated based on public disclosure, where unavailable.
6
Given comparisons are at the business segment level, where
available; allocation methodologies across peers may be
inconsistent with JPM’s.
Size of the Financial Sector/Industry
(page 29)
1
Congressional Budget Office; reflects end of fiscal year
(September 30).
2
International Monetary Fund (IMF) estimates for general
government as of October 2025 edition of Fiscal Monitor.
3
World Gold Council, Bloomberg and internal JPMorganChase
estimates.
4
Consists of cash assets and Treasury and agency securities.
5
Private Equity assets under management (AUM) includes Balanced,
Buyout, Co-Investment, Co-Investment Multi-Manager, Direct
Secondaries, Growth, Hybrid, private investment in public equity
(PIPE) and Turnaround in closed-end funds only. Excludes Fund of
Funds, Secondaries and venture capital (VC) to avoid the double
counting of funds.
6
Top 50 fund AUM data per Sovereign Wealth Fund Institute (SWFI).
2010 AUM for entities in the top 50 in 2025.
7
Preqin, Dealogic and JPMorganChase Credit Research.
8
Venture Capital AUM includes Early Stage, Venture and Expansion/
Late-Stage Capital in closed-end funds only. Excludes Fund of Funds
and Secondaries to avoid the double counting of funds.
9
U.S. money market fund investment holdings of securities issued by
entities worldwide.
10
NYSE + NASDAQ; excludes investment funds, exchange-traded fund
(ETF) unit trusts and companies whose business goal is to hold
shares of other listed companies; a company with several classes of
shares is only counted once.
11
Inside Mortgage Finance and JPMorganChase internal data; consists
of Top 50 Originators.
12
2025 based on flow data up to 3Q25. Global data preliminary based
on 80 country sub-sample.
13
Financial Times fDi Markets, Dealogic.
14
Data up to 2Q25.
15
Reflects the growth in central bank assets during subsequent
quantitative easing (QE) phases, net of the decline observed during
the balance sheet reduction phase.
16
Global quantitative easing (QE) and global central bank assets are
proxied by the changes and outstanding values of central bank
assets as % of gross domestic product in the following economies:
Australia, Canada, Denmark, Euro Area, Iceland, Japan, New Zealand,
Norway, Sweden, Switzerland, the U.K. and the United States.
49
FUTURE-READY BY DESIGN: STRENGTHENING OUR COMPANY AND OPERATIONS
50
Future-Ready by Design: Strengthening
Our Company and Operations
As Chief Operating Officer of
JPMorganChase, it is a privilege to
oversee the operations that enable
our employees to serve clients with
excellence, supporting governments,
businesses, nonprofits, individuals
and communities around the world.
Our Purpose is clear: Make dreams
possible for everyone, everywhere,
every day. Guided by our values —
Service, Heart, Curiosity, Courage and
Excellence — we continuously improve
and relentlessly learn, treat clients and
one another with respect, and uphold
rigorous governance and controls. With
320,000+ employees in 66 countries
across the world, our people are the
engine of our success, delivering for
clients, strengthening our franchise and
building durable value for the long term.
Investing in technology, data
and AI
We are as much a technology-driven
company as we are a bank. With
a technology budget for 2026 of
approximately $19.8 billion, we oper
ate at unmatched scale, built on mod
ern cloud and data foundations and
resilient, secure infrastructure. We
innovate safely and reliably, protecting
the trust we’ve earned while moving
faster than ever.
More than 10 years into our advanced
machine learning and artificial intelli
gence (AI) journey, we’re delivering
measurable value across credit, fraud
and personalization, demonstrated
through better products, stronger
controls and tangible financial results.
We’re deploying generative AI at enter
prise scale, enabling faster develop
ment and more efficient operations
and stronger risk management, and we
expect this momentum to accelerate,
with a relentless focus on business
transformation and value creation.
Data powers it all — and data remains a
competitive advantage. We’ve run one
of the world’s most sophisticated finan
cial data operations for decades, and
that scale is a strategic asset. Data is
powerful not simply because of its vol
ume; when it is AI‑ready and consum
able at the point of decision, it allows the
right insights to drive better outcomes.
We also treat data as a responsibility.
We take cybersecurity very seriously
and work to continuously protect
our systems and customer data with
physical, electronic and procedural
safeguards while giving customers the
ability to manage and control how they
share their personal information. As we
embed AI across the firm, we connect
models to well‑governed data, with
safeguards that protect clients, the
firm and the financial system, ensuring
innovation advances without compro
mising safety or trust. We know that as
AI agents continue to evolve, security
must evolve, and scale, alongside it.
Together, these capabilities are chang
ing how we work. We can move faster
— turning ideas into products in weeks
or months, no longer in years — and
deliver more personalized, proactive
experiences for clients. Modern, modu
lar systems allow us to test quickly,
learn in real time and scale efficiently.
That speed helps us reach markets
sooner, spend less time on mainte
nance and focus more on innovation.
We’re already seeing productivity gains
that will free up capacity, which we will
reinvest in growth. We will continue to
upskill, reskill and redeploy talent as
technology evolves and productivity
increases. While it will likely be the
outcome in certain jobs, the goal is
not fewer headcount; the goal is com
pounding performance with a growth-
first mindset.
Across cycles and through change,
we’ve shown the ability to adapt quickly
and continue innovating in service to
our clients. As technology reshapes
how products are built and delivered,
we believe the future plays to our
strengths, where scale, brand trust
and deep relationships will extend our
competitive advantage.
Investing in our workforce
The depth and breadth of our footprint
across businesses and geographies
give employees unmatched opportuni
ties to grow and build a long-term
career. Every year, we fill thousands of
roles, a large share through internal
mobility opportunities, reflecting our
commitment to growth and develop
ment. Associate bankers become
market directors; analysts and interns
grow to lead big businesses.
We are intentional about developing
talent, investing in training — including
AI upskilling — and education benefits
that help our people grow, adapt and
deliver at pace.
AI‑powered tools are also transform
ing the employee experience. Enabled
by tools like our homegrown LLM
Suite, we are simplifying work, giving
employees time back and improving
quality. We recently rolled out the
Employee Assistant, a personalized
AI-powered agent to provide employ
ees a single resource to get help and
take action across the firm.
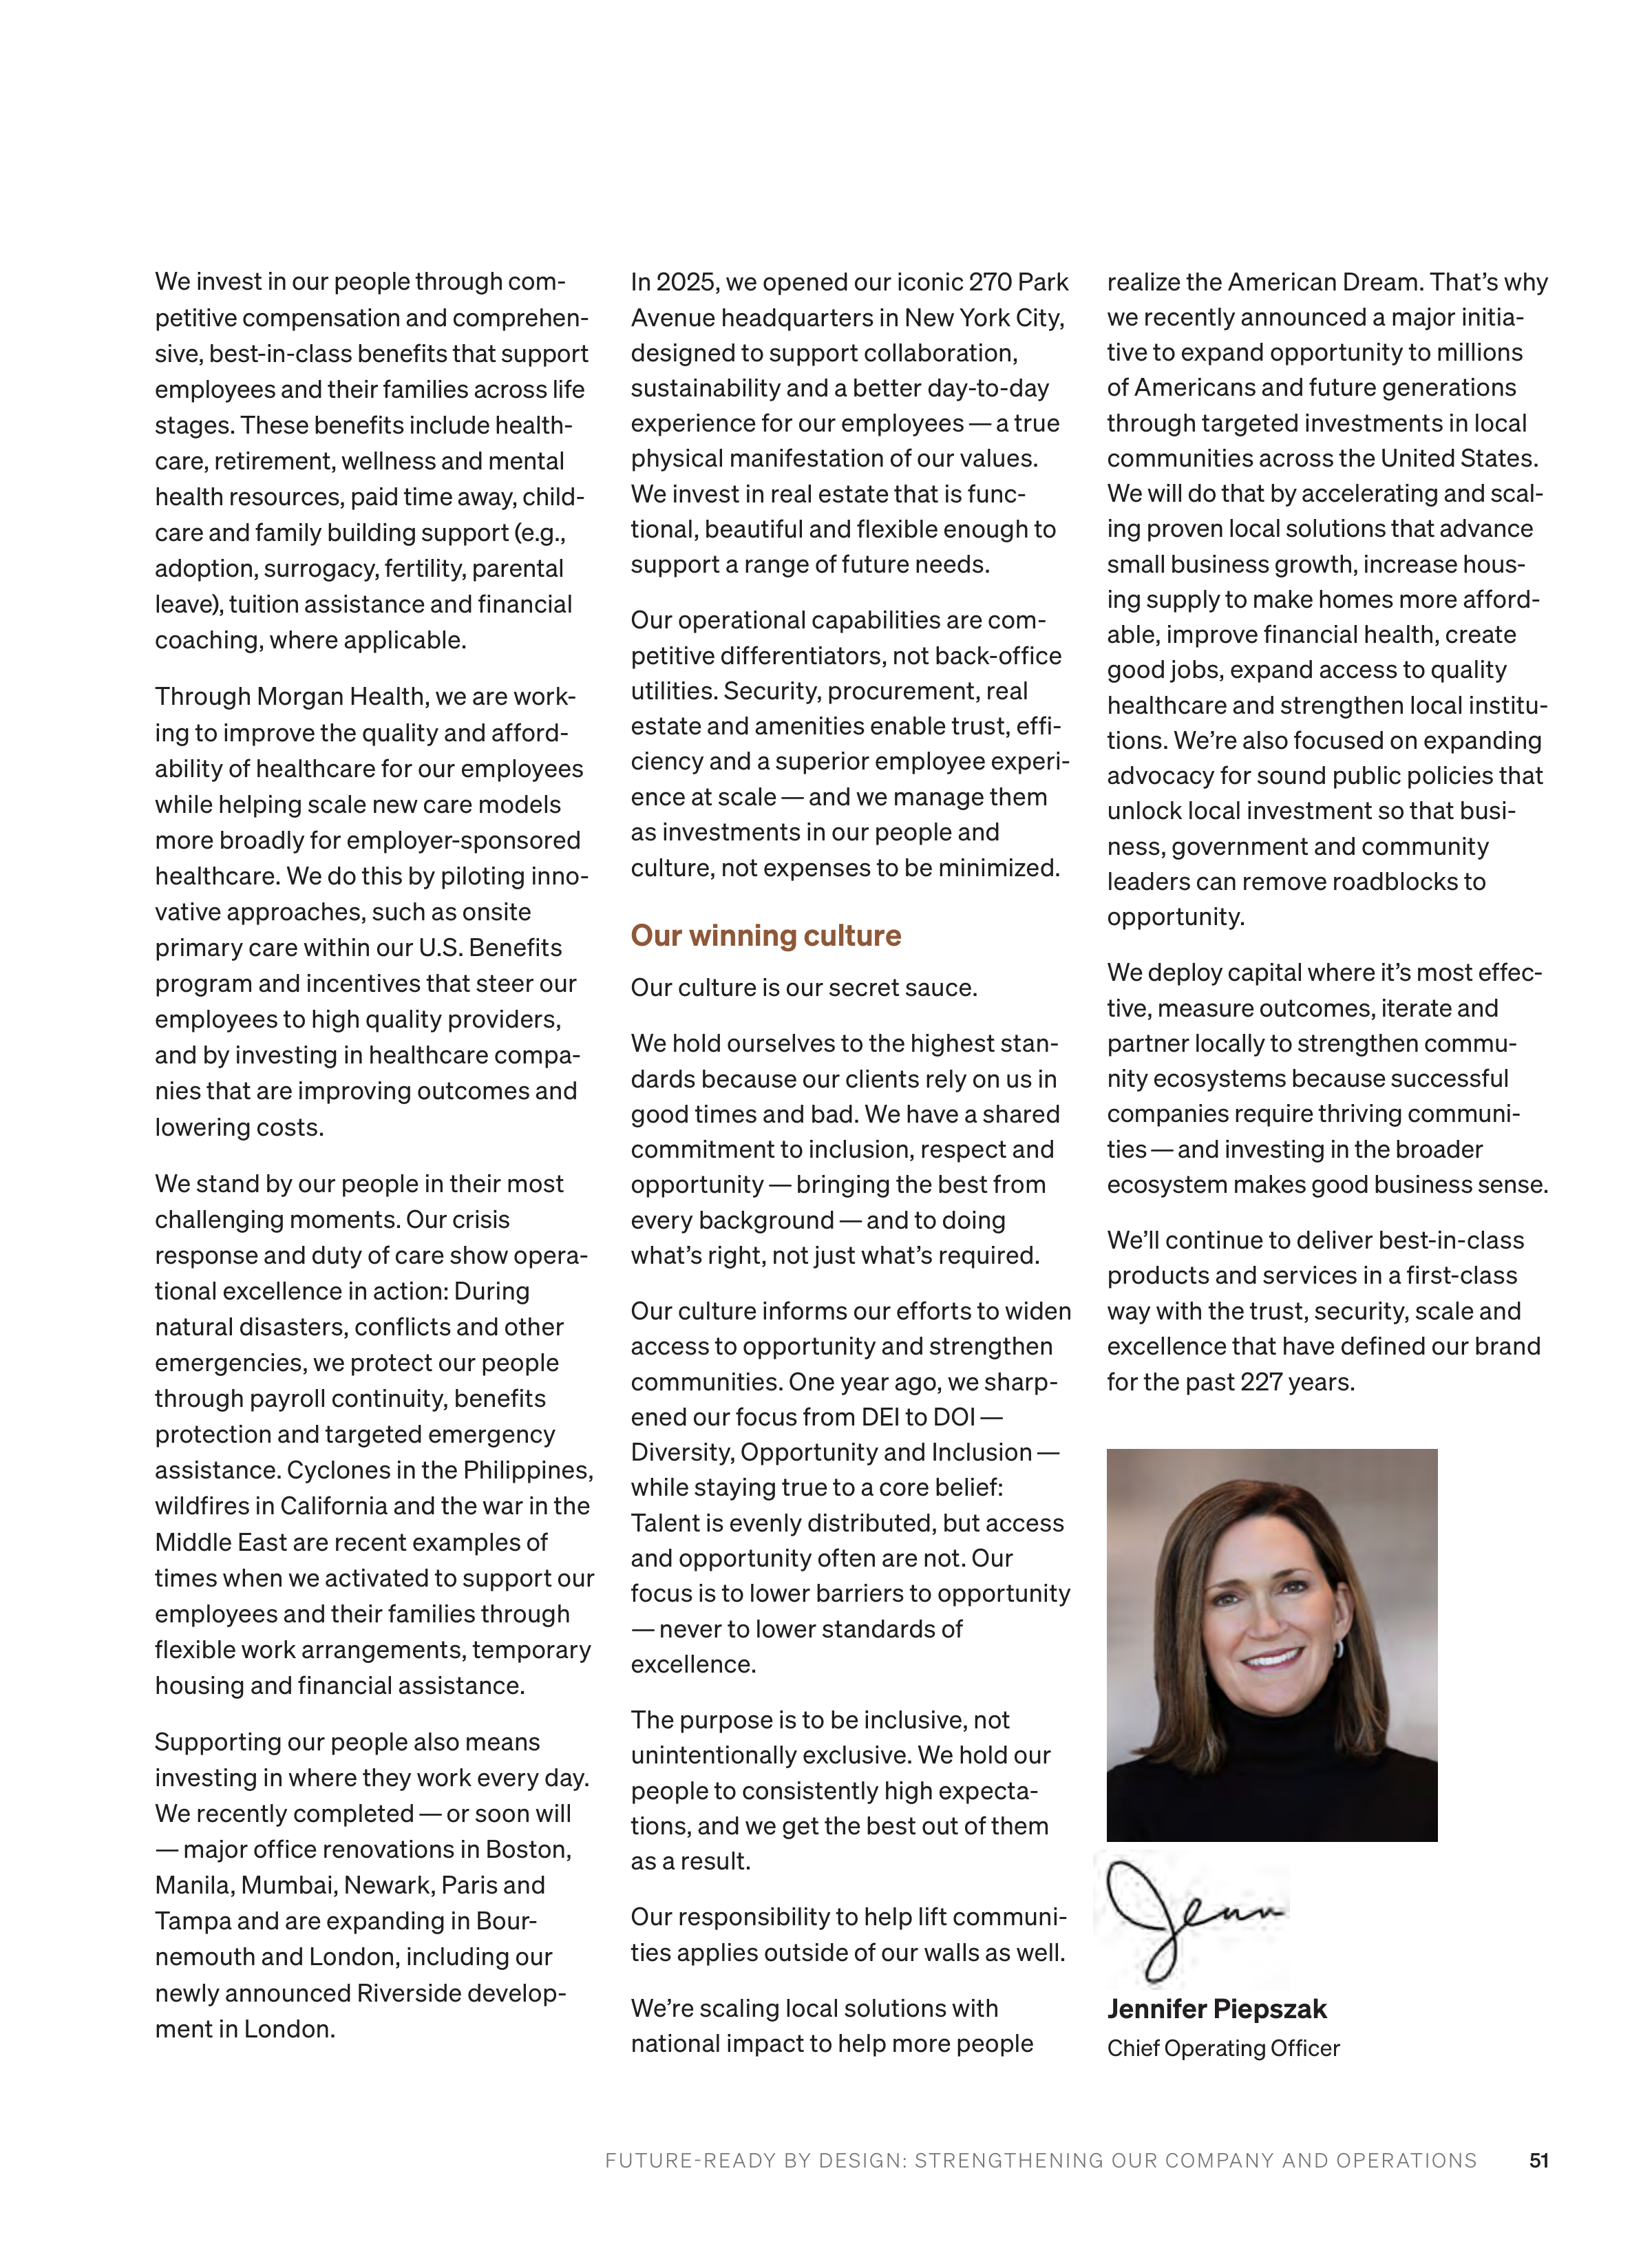
FUTURE-READY BY DESIGN: STRENGTHENING OUR COMPANY AND OPERATIONS
51
We invest in our people through com
petitive compensation and comprehen
sive, best-in-class benefits that support
employees and their families across life
stages. These benefits include health
care, retirement, wellness and mental
health resources, paid time away, child
care and family building support (e.g.,
adoption, surrogacy, fertility, parental
leave), tuition assistance and financial
coaching, where applicable.
Through Morgan Health, we are work
ing to improve the quality and afford
ability of healthcare for our employees
while helping scale new care models
more broadly for employer-sponsored
healthcare. We do this by piloting inno
vative approaches, such as onsite
primary care within our U.S. Benefits
program and incentives that steer our
employees to high quality providers,
and by investing in healthcare compa
nies that are improving outcomes and
lowering costs.
We stand by our people in their most
challenging moments. Our crisis
response and duty of care show opera
tional excellence in action: During
natural disasters, conflicts and other
emergencies, we protect our people
through payroll continuity, benefits
protection and targeted emergency
assistance. Cyclones in the Philippines,
wildfires in California and the war in the
Middle East are recent examples of
times when we activated to support our
employees and their families through
flexible work arrangements, temporary
housing and financial assistance.
Supporting our people also means
investing in where they work every day.
We recently completed — or soon will
— major office renovations in Boston,
Manila, Mumbai, Newark, Paris and
Tampa and are expanding in Bour
nemouth and London, including our
newly announced Riverside develop
ment in London.
In 2025, we opened our iconic 270 Park
Avenue headquarters in New York City,
designed to support collaboration,
sustainability and a better day‑to‑day
experience for our employees — a true
physical manifestation of our values.
We invest in real estate that is func
tional, beautiful and flexible enough to
support a range of future needs.
Our operational capabilities are com
petitive differentiators, not back-office
utilities. Security, procurement, real
estate and amenities enable trust, effi
ciency and a superior employee experi
ence at scale — and we manage them
as investments in our people and
culture, not expenses to be minimized.
Our winning culture
Our culture is our secret sauce.
We hold ourselves to the highest stan
dards because our clients rely on us in
good times and bad. We have a shared
commitment to inclusion, respect and
opportunity — bringing the best from
every background — and to doing
what’s right, not just what’s required.
Our culture informs our efforts to widen
access to opportunity and strengthen
communities. One year ago, we sharp
ened our focus from DEI to DOI —
Diversity, Opportunity and Inclusion —
while staying true to a core belief:
Talent is evenly distributed, but access
and opportunity often are not. Our
focus is to lower barriers to opportunity
— never to lower standards of
excellence.
The purpose is to be inclusive, not
unintentionally exclusive. We hold our
people to consistently high expecta
tions, and we get the best out of them
as a result.
Our responsibility to help lift communi
ties applies outside of our walls as well.
We’re scaling local solutions with
national impact to help more people
realize the American Dream. That’s why
we recently announced a major initia
tive to expand opportunity to millions
of Americans and future generations
through targeted investments in local
communities across the United States.
We will do that by accelerating and scal
ing proven local solutions that advance
small business growth, increase hous
ing supply to make homes more afford
able, improve financial health, create
good jobs, expand access to quality
healthcare and strengthen local institu
tions. We’re also focused on expanding
advocacy for sound public policies that
unlock local investment so that busi
ness, government and community
leaders can remove roadblocks to
opportunity.
We deploy capital where it’s most effec
tive, measure outcomes, iterate and
partner locally to strengthen commu
nity ecosystems because successful
companies require thriving communi
ties — and investing in the broader
ecosystem makes good business sense.
We’ll continue to deliver best-in-class
products and services in a first-class
way with the trust, security, scale and
excellence that have defined our brand
for the past 227 years.
Jennifer Piepszak
Chief Operating Officer
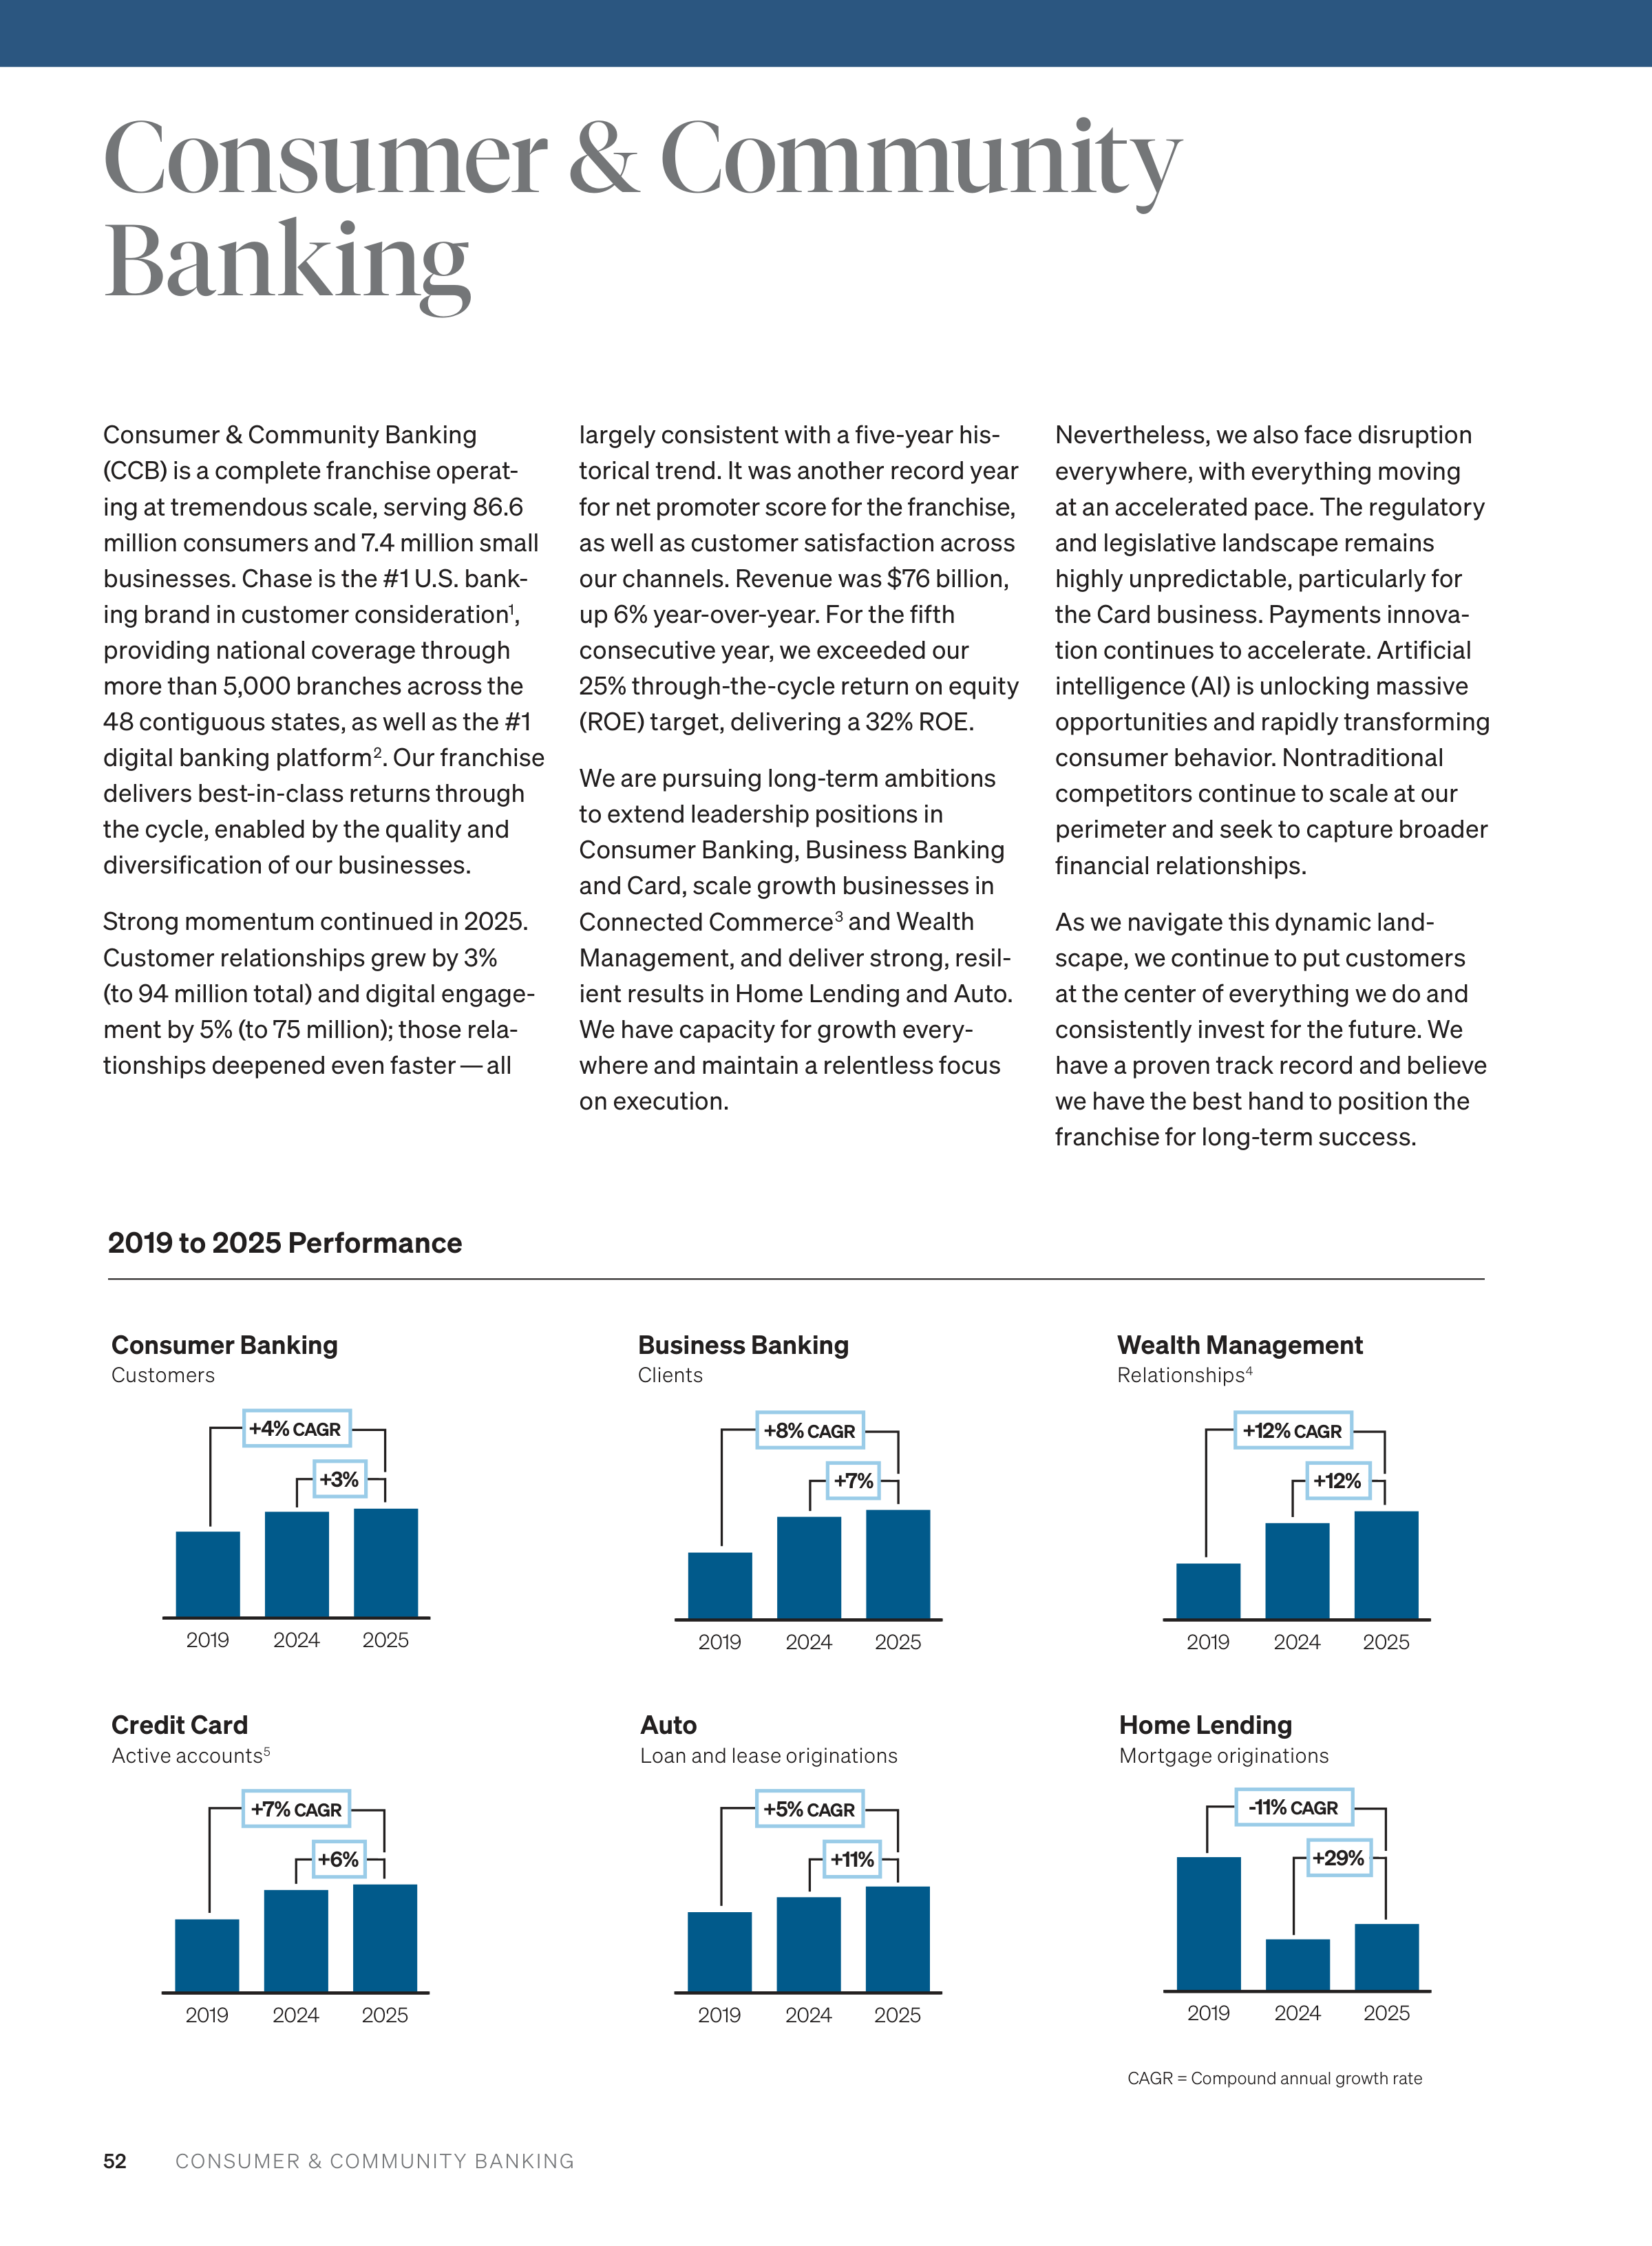
CONSUMER & COMMUNITY BANKING
52
Consumer & Community Banking
(CCB) is a complete franchise operat
ing at tremendous scale, serving 86.6
million consumers and 7.4 million small
businesses. Chase is the #1 U.S. bank
ing brand in customer consideration
1
,
providing national coverage through
more than 5,000 branches across the
48 contiguous states, as well as the #1
digital banking platform
2
. Our franchise
delivers best-in-class returns through
the cycle, enabled by the quality and
diversification of our businesses.
Strong momentum continued in 2025.
Customer relationships grew by 3%
(to 94 million total) and digital engage
ment by 5% (to 75 million); those rela
tionships deepened even faster — all
Consumer & Community
Banking
largely consistent with a five-year his
torical trend. It was another record year
for net promoter score for the franchise,
as well as customer satisfaction across
our channels. Revenue was $76 billion,
up 6% year-over-year. For the fifth
consecutive year, we exceeded our
25% through-the-cycle return on equity
(ROE) target, delivering a 32% ROE.
We are pursuing long-term ambitions
to extend leadership positions in
Consumer Banking, Business Banking
and Card, scale growth businesses in
Connected Commerce
3
and Wealth
Management, and deliver strong, resil
ient results in Home Lending and Auto.
We have capacity for growth every
where and maintain a relentless focus
on execution.
Nevertheless, we also face disruption
everywhere, with everything moving
at an accelerated pace. The regulatory
and legislative landscape remains
highly unpredictable, particularly for
the Card business. Payments innova
tion continues to accelerate. Artificial
intelligence (AI) is unlocking massive
opportunities and rapidly transforming
consumer behavior. Nontraditional
competitors continue to scale at our
perimeter and seek to capture broader
financial relationships.
As we navigate this dynamic land
scape, we continue to put customers
at the center of everything we do and
consistently invest for the future. We
have a proven track record and believe
we have the best hand to position the
franchise for long-term success.
2025
2024
2019
+3%
+4%
CAGR
2025
2024
2019
+7%
+8%
CAGR
2025
2024
2019
+12%
+12%
CAGR
Consumer Banking
Customers
Credit Card
Active accounts
5
Auto
Loan and lease originations
Home Lending
Mortgage originations
Business Banking
Clients
Wealth Management
Relationships
4
2019 to 2025 Performance
2025
2024
2019
+6%
+7%
CAGR
2025
2024
2019
+11%
+5%
CAGR
2025
2024
2019
+29%
-11%
CAGR
CAGR = Compound annual growth rate
CONSUMER & COMMUNITY BANKING
53
Extending leadership positions
We continue to capture primary
relationships across customer seg
ments by investing in distribution and
tailoring solutions in Consumer and
Business Banking, as well as Card.
Consumer and Business Banking:
Chase is the #1 retail bank with 11.1%
national deposit share, up 200 basis
points since 2019. In 2025, we contin
ued to outperform large bank peers,
though overall share was down 20
basis points year-over-year due to
post-pandemic normalization. We
delivered strong growth, with 1.7 million
net new checking accounts across
Consumer and Business Banking.
About 80% of consumers and 70% of
small business owners who bank with
Chase consider us their primary bank
6
.
Banking is local. In 2018, we began
expanding the Chase branch network
and laid the foundation for capturing
share in underpenetrated markets
that represent 40% of total U.S. retail
deposits. We’ve opened over 1,000
new branches since then, more than all
large bank peers combined. Last year,
we shared that new builds contributed
about 40% of market share gains since
2019; these younger branches have
embedded deposit growth opportuni
ties as they continue to season for a
decade and beyond. We continue to
expand, with a goal of reaching 75%
of the national population within an
accessible drive to a branch (up from
69% today) and expect new builds
to contribute a similar proportion
of future share gains. Our mature
network will continue to deliver the
majority of share gains, underpinned
by our strong brand, culture and tal
ent, products and services, customer
experience and real estate.
In addition to investing locally, we
remain committed to evolving banking
products, services and experiences
to meet the unique needs of each
customer segment. We continue to
enhance Secure Banking
SM
, which is
geared toward younger and lower-
income consumers and growing at a
22% rate since 2019. Excitingly, the
product is now available with no
monthly service fee for 17-24 year olds.
In the affluent segment, we’re getting
clients into the right products as we
grow Chase Private Client at a 6% rate
and scale J.P. Morgan Private Client
(JPM PC), a new tier providing elevated
banking and wealth experiences for
clients with more than $1 million in
assets. We’re seeing strong early
performance in JPM PC and are accel
erating plans to extend coverage for
this segment. In small business, we’re
growing at a healthy 8% rate across
segments and have more than doubled
the number of large clients covered
by business relationship managers
since 2019.
These strategies will fuel our path to
15% retail deposit share.
Card
:
We are the #1 credit card issuer
in the United States, with 23.6% share
of sales
7
, up 130 basis points since
2019 (30 basis points year-over-year).
In outstandings, we have 17.7% share,
up 130 basis points (40 basis points
year-over-year), reflecting continued
strong growth in active accounts and
outstandings to $232 billion, growing
at a 7% rate since 2019.
Ongoing investments in marketing
distribution drive strong new account
production. Since 2022, we’ve booked
approximately 10 million new accounts
each year with strong, predictable
returns. We continue to invest in capa
bilities that maximize the benefit of
our owned channels and data, includ
ing enhanced credit line strategies to
qualified borrowers.
A comprehensive product set serving
customer needs across segments also
fuels growth. We have award-winning
cards, driving record top-of-wallet
8
behavior of more than 60%, up 6 per
centage points since 2019. We continu
ously invest in benefits and capabilities
to keep our cards fresh and relevant.
We recently:
•
Refreshed the Sapphire Reserve®
card, raising potential annual card
holder value to over $3,000 in travel
and lifestyle benefits
•
Launched the Sapphire Reserve for
Business
SM
card, extending valuable
benefits to high-spending business
owners
•
Refreshed the United family of cards
and Southwest Rapid Rewards®
credit cards with new and enhanced
benefits
•
Announced that Chase will become
the new issuer of Apple Card
•
Reintroduced the Slate® card with a
prolonged introductory APR offer —
now at 21 months
We continue to focus on key segments
with outsized opportunity, growing both
premium and small business accounts
at a 12% rate since 2019. The new
Sapphire offerings are resonating with
customers, and we continue to invest in
lifestyle benefits, including additional
Sapphire Lounges (recently named
Best Lounge Network by The Points
Guy) and a partnership with OpenTable
that offers exclusive reservations to
Sapphire cardmembers. In the starter
segment, we’ve opened more than
1 million new accounts since the launch
of Freedom Rise® in 2023 and grown
share of outstandings with Gen Z by
nearly 600 basis points since 2019.
These strategies will fuel our path to
20% share of outstandings.
Scaling growth businesses
In Connected Commerce and Wealth
Management, we have the assets to
win and outsized opportunity to grow
given the scale and depth of CCB
relationships. These businesses are
natural adjacencies to credit cards
and banking, and both strengthen
and diversify the CCB franchise.
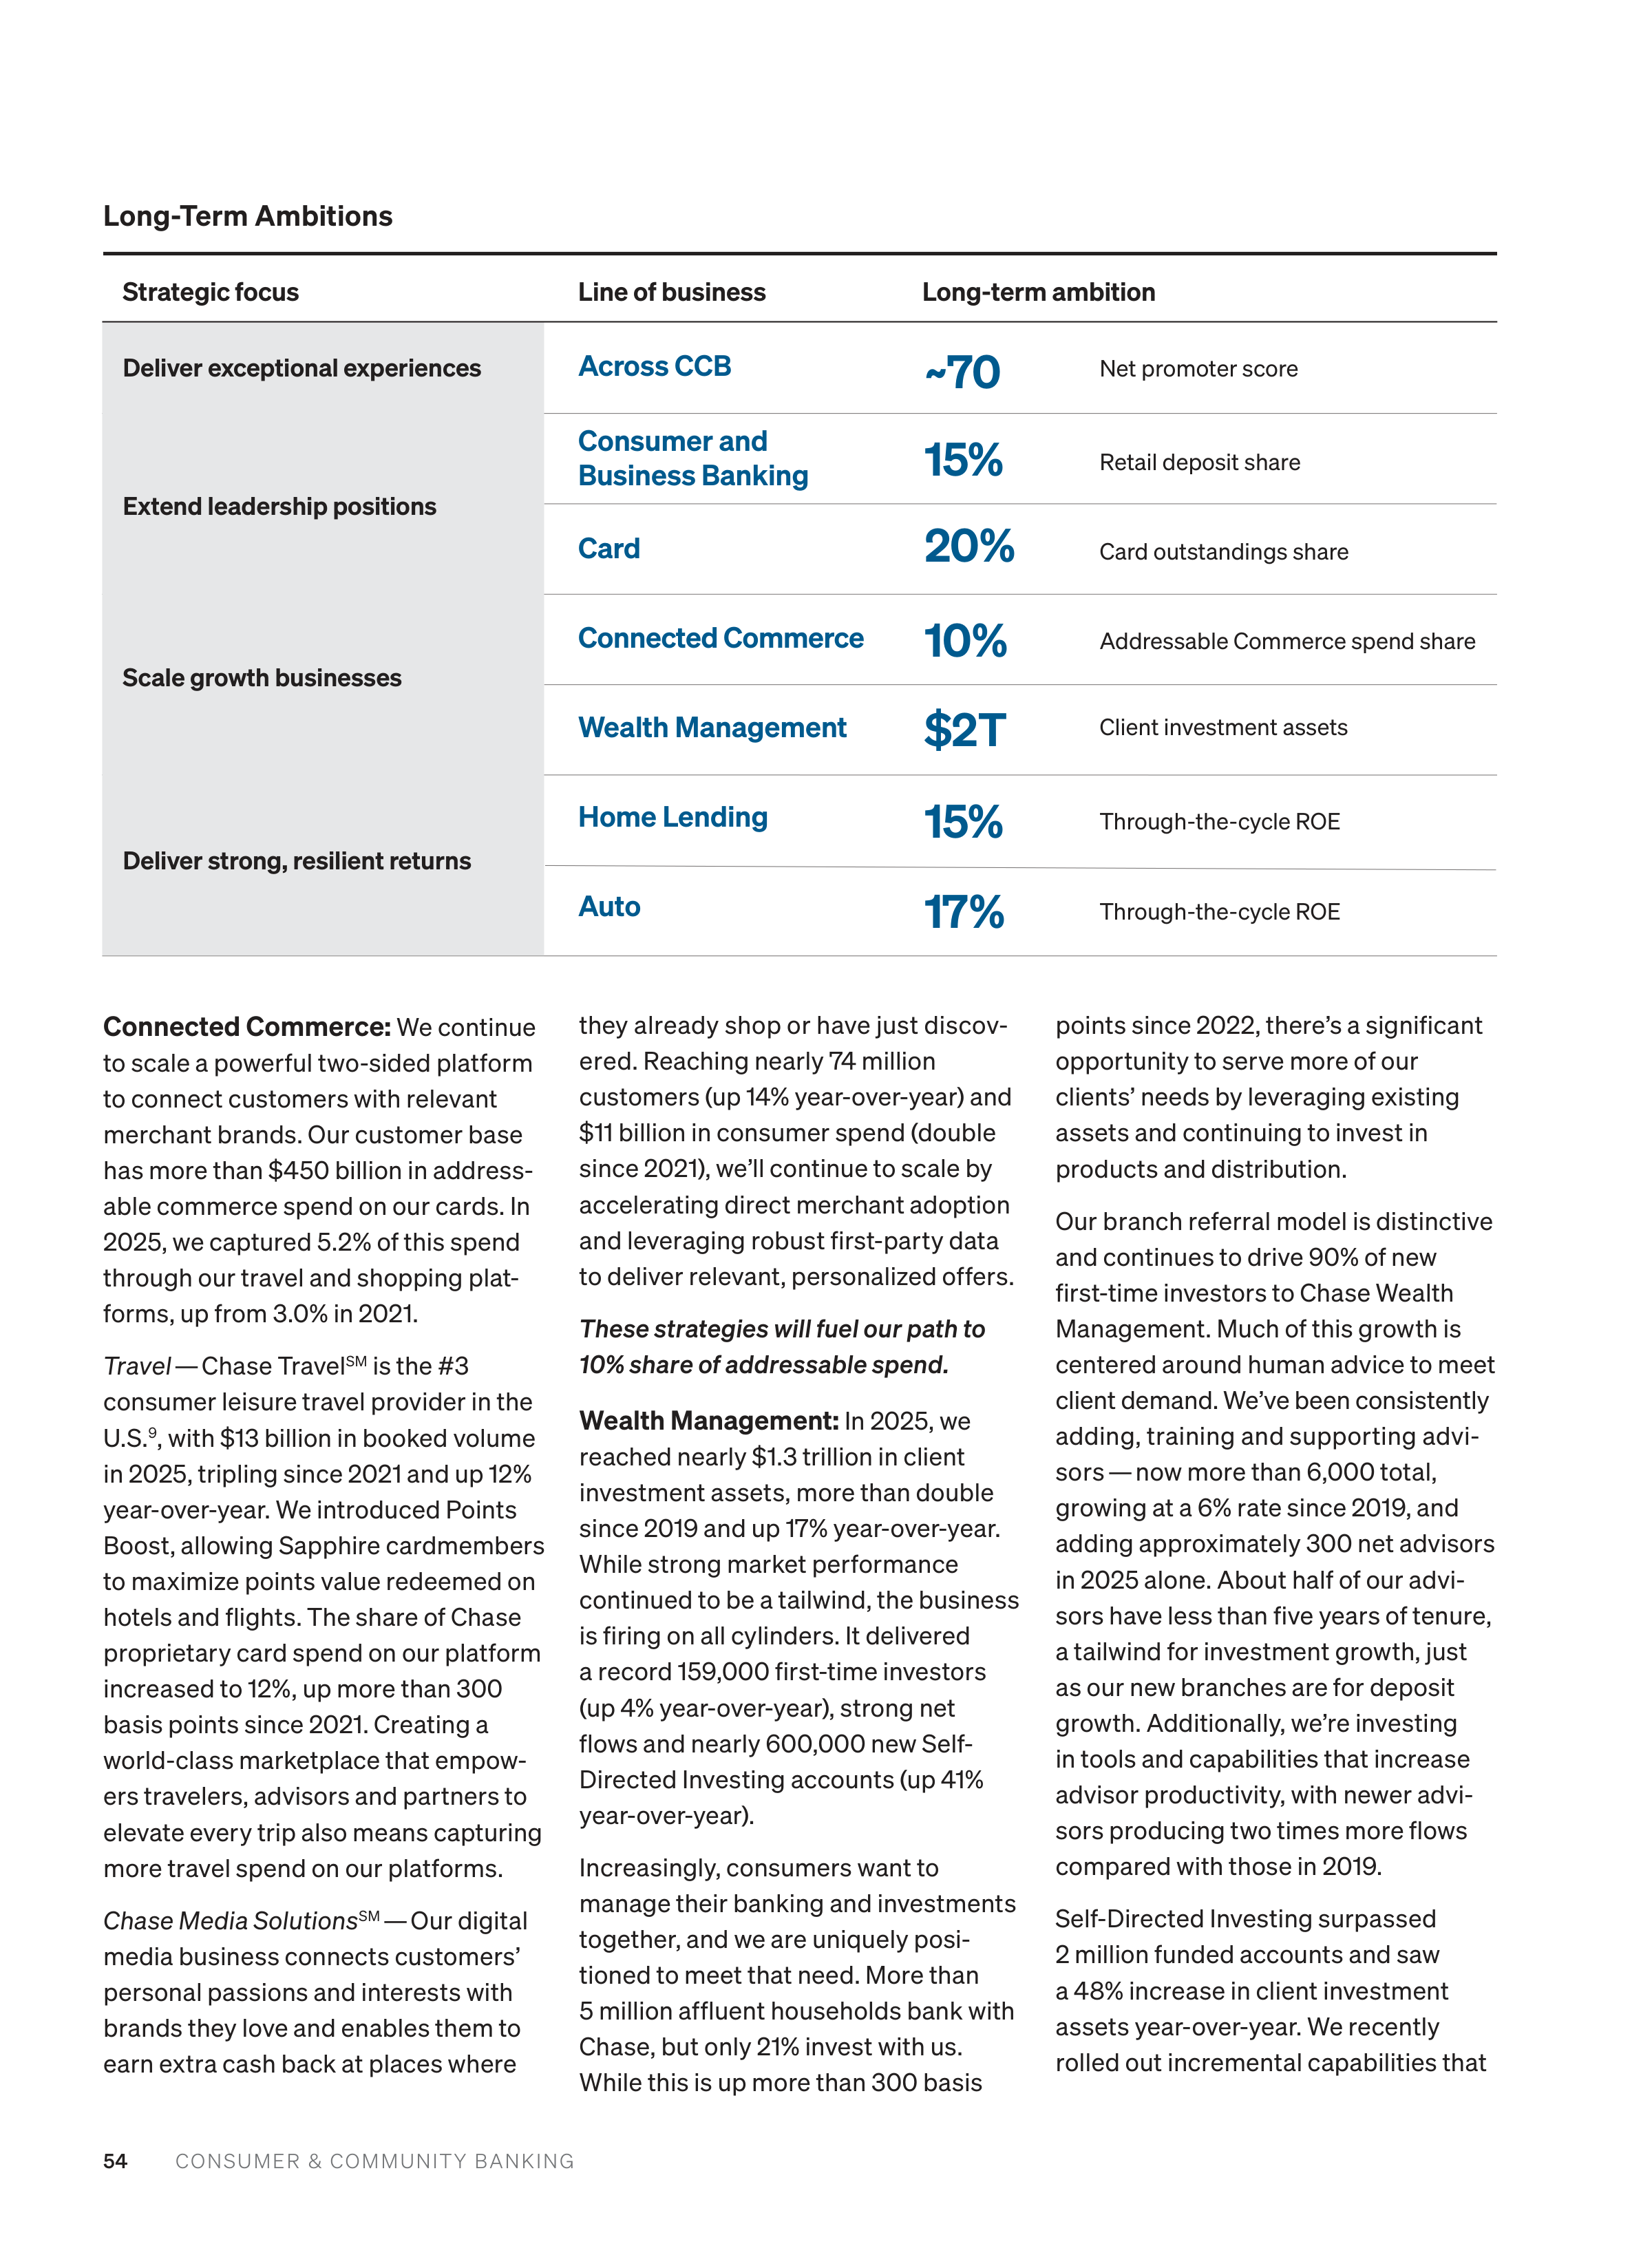
CONSUMER & COMMUNITY BANKING
54
Connected Commerce:
We continue
to scale a powerful two-sided platform
to connect customers with relevant
merchant brands. Our customer base
has more than $450 billion in address
able commerce spend on our cards. In
2025, we captured 5.2% of this spend
through our travel and shopping plat
forms, up from 3.0% in 2021.
Travel
— Chase Travel
SM
is the #3
consumer leisure travel provider in the
U.S.
9
, with $13 billion in booked volume
in 2025, tripling since 2021 and up 12%
year-over-year. We introduced Points
Boost, allowing Sapphire cardmembers
to maximize points value redeemed on
hotels and flights. The share of Chase
proprietary card spend on our platform
increased to 12%, up more than 300
basis points since 2021. Creating a
world-class marketplace that empow
ers travelers, advisors and partners to
elevate every trip also means capturing
more travel spend on our platforms.
Chase Media Solutions
SM
— Our digital
media business connects customers’
personal passions and interests with
brands they love and enables them to
earn extra cash back at places where
they already shop or have just discov
ered. Reaching nearly 74 million
customers (up 14% year-over-year) and
$11 billion in consumer spend (double
since 2021), we’ll continue to scale by
accelerating direct merchant adoption
and leveraging robust first-party data
to deliver relevant, personalized offers.
These strategies will fuel our path to
10% share of addressable spend.
Wealth Management
:
In 2025, we
reached nearly $1.3 trillion in client
investment assets, more than double
since 2019 and up 17% year-over-year.
While strong market performance
continued to be a tailwind, the business
is firing on all cylinders. It delivered
a record 159,000 first-time investors
(up 4% year-over-year), strong net
flows and nearly 600,000 new Self-
Directed Investing accounts (up 41%
year-over-year).
Increasingly, consumers want to
manage their banking and investments
together, and we are uniquely posi
tioned to meet that need. More than
5 million affluent households bank with
Chase, but only 21% invest with us.
While this is up more than 300 basis
points since 2022, there’s a significant
opportunity to serve more of our
clients’ needs by leveraging existing
assets and continuing to invest in
products and distribution.
Our branch referral model is distinctive
and continues to drive 90% of new
first-time investors to Chase Wealth
Management. Much of this growth is
centered around human advice to meet
client demand. We’ve been consistently
adding, training and supporting advi
sors — now more than 6,000 total,
growing at a 6% rate since 2019, and
adding approximately 300 net advisors
in 2025 alone. About half of our advi
sors have less than five years of tenure,
a tailwind for investment growth, just
as our new branches are for deposit
growth. Additionally, we’re investing
in tools and capabilities that increase
advisor productivity, with newer advi
sors producing two times more flows
compared with those in 2019.
Self-Directed Investing surpassed
2 million funded accounts and saw
a 48% increase in client investment
assets year-over-year. We recently
rolled out incremental capabilities that
Strategic focus
Line of business
Long-term ambition
Across CCB
Consumer and
Business Banking
Card
Connected Commerce
Wealth Management
Home Lending
Auto
~70
15%
20%
10%
$2T
15%
17%
Net promoter score
Retail deposit share
Card outstandings share
Addressable Commerce spend share
Client investment assets
Through-the-cycle ROE
Through-the-cycle ROE
Deliver exceptional experiences
Extend leadership positions
Scale growth businesses
Deliver strong, resilient returns
Long-Term Ambitions
CONSUMER & COMMUNITY BANKING
55
include extended-hours trading,
new options trading tools, and improve
ments to integrated online and mobile
platforms. This offering is well-
positioned for our core clients and
is fully integrated into the #1 digital
banking platform in the U.S.
These strategies will fuel our path to
$2 trillion in client investment assets.
Delivering strong, resilient
returns
Home Lending and Auto are strategi
cally important, meeting customer
needs in key life moments while also
providing diversification benefits for
the franchise. For these businesses,
we continue to make ongoing invest
ments in products, experiences and
technology to drive growth and strong
through-the-cycle returns.
Home Lending:
Home Lending is a
relationship business that allows us to
deepen customer relationships while
protecting and growing deposits and
investments. While we are at a low
point in the mortgage market cycle,
we remain confident in our ability to
achieve our target of 15% through-the-
cycle ROE. The business today is deliv
ering a 17% ROE with marginal returns
in the mid-teens in every part of the
business. Home Lending had positive
traction in 2025, increasing origination
market share by more than 40 basis
points to 3.3%.
We aim to grow market share while
investing in technology, data and AI to
drive growth, innovation and efficiency.
In 2025, our digital home shopping
platform, Chase MyHome®, continued
momentum, and unique users grew
20% year-over-year to more than 11
million. With our continued focus on
digitizing and investing in generative
AI, we aim to increase productivity and
reimagine the home lending experience.
These strategies will fuel our path to
15% through-the-cycle ROE in Home
Lending.
Auto:
Auto is an important relationship
business for consumers, dealers and
manufacturers. While the auto industry
faced many challenges last year,
including ongoing recovery from
pandemic-era supply chain issues,
tariffs and the expiry of clean vehicle
tax credits, the industry showed
remarkable resilience. The market has
largely recovered from pandemic lows,
and industry sales have rebounded to
about 95% of pre-pandemic levels. Our
business continued to deliver strong
results, with total originations of $45
billion across leases and loans, growing
at a 5% rate since 2019 and 11% year-
over-year. Lease mix returned to above
30% in 2025, due to positive industry
momentum and growth from manufac
turer partners.
Chase is the #1 private label provider
among banks by a wide margin. We
renewed our partnership with Jaguar
Land Rover, which provides custom
ized loan and lease financing and stra
tegic support to retailers across the
country. We continue to explore ways
to provide partners with value across
our whole ecosystem, including
leveraging owned marketing channels
and assets.
In our retail and consumer business, we
continue to enhance digital capabilities
to deepen engagement. Finance &
Drive
SM
, our digital car shopping and
financing platform, scaled to nearly
15 million unique users, and we saw a
24% year-over-year increase in custom
ers who engage with high-value fea
tures (including shopping for a car and
prequalifying for a loan).
We continue to support auto dealer
ships across the country by providing
floorplan, acquisition and real estate
loans, as well as banking and treasury
services.
These strategies will fuel our path to
17% through-the-cycle ROE in Auto.
Building an international
consumer bank
This is the first year I’m discussing our
International Consumer Banking (ICB)
initiatives
10
alongside CCB. In ICB, we’re
building a multi-country, digital busi
ness with aspirations to become a
leading banking and investment
provider. We’re focused on capturing
primary relationships at scale and are
powering expansion across Europe
through a single, cloud-native platform.
While CCB and ICB have distinct strate
gies, they are symbiotic and will con
tinue to inform and benefit from each
other’s success.
Chase U.K. has shown strong momen
tum, and we are building on that perfor
mance by attracting more customers,
growing balances and expanding prod
uct offerings. Since launching in 2021,
we’ve scaled to 2.8 million customers
and over $35 billion in balances
.
We
have an award-winning digital experi
ence with the Chase U.K. app, which
was named Banking App of the Year
11
for the third consecutive year. In 2025,
we launched our first lending product
— credit cards — which demonstrated
strong early momentum. Our invest
ments business, J.P. Morgan Personal
Investing (recently rebranded from
Nutmeg), has scaled to nearly 280,000
customers and $12.5 billion in client
investment assets. We continue to
launch new investment products,
including self-directed investing later
this year, and we are revamping our
personal pension solution with the
recent acquisition of WealthOS, a
wealth technology platform.
We are expanding into Germany in the
second quarter of 2026, starting with
an instant-access savings account.
In a highly competitive market with
fast-growing direct and challenger
banks, we’ll differentiate our offering
through intuitive digital experiences
and a customer-first proposition.
CONSUMER & COMMUNITY BANKING
56
Navigating a dynamic
environment
We operate in a highly competitive
industry and face constant disruption,
ranging from regulation and competi
tion to the potential impacts of AI.
Disruption is not new, and we have a
successful track record of adapting
and winning. But we are not complacent
and recognize that the breadth and
pace of change today is extraordinary.
Credit card legislation:
The regulatory
and legislative landscape is highly vola
tile, with continued efforts to push the
Credit Card Competition Act, introduc
tion of a new late fee bill in Congress,
a call for price caps on APRs and state-
level interchange actions. These are all
ways of inserting price controls into the
credit card industry, where consumers
and merchants already have many
choices, and competitive market forces
are already working.
Credit cards provide significant utility
to both consumers and merchants.
For consumers, they offer flexible,
unsecured credit to manage everyday
expenses and financial needs. They
are also incredibly valuable for the
merchant ecosystem as they improve
conversions, increase basket sizes and
offer a safer, cheaper alternative to
other payment methods such as cash.
Providing this credit comes with real
costs and risks, and many of the
current legislative proposals fail to
account for these financial realities.
We share the consensus view that
these proposals would have an
overwhelmingly negative impact
on consumers, businesses and the
economy as a whole.
We continually plan for a wide range
of potential scenarios and will respond
strategically and thoughtfully. We’re
familiar with responding to disruption in
all its forms, but it’s important that the
utility of credit cards is not legislated
away because a growing credit card
market is good for the economy overall.
Open banking and data sharing:
JPMorganChase supports open bank
ing. In 2025, we helped more than 32
million customers share their data with
more than 15,000 apps. Our data APIs
are called nearly 2 billion times per
month
12
(over 700 calls per second).
We believe consumers should have
control of their data and its use, and
data shared should be fit for purpose,
permissioned only for what is intended
and not siphoned off for secondary
commercial purposes. Unfortunately,
consumers don’t have full control as
too many disclosures provide an all-
or-nothing approach to data-sharing
and customers don’t know that their
data is being commercialized — a
problem that we believe will only be
exacerbated in an agentic world. We
have successfully addressed this
problem with win-win commercial
agreements that create clear, com
mon-sense customer disclosures,
incentives for data harvesters to mini
mize the data they collect from cus
tomers and shared investment in the
ecosystem to protect customer data.
Payments and lending innovation:
Payments are core to everything we
do because they are core to everything
customers do. We saw $7 trillion in
payments volume last year, growing
at an 11% rate since 2019 (up 9% year-
over-year). The payments landscape
is increasingly dynamic, with rapid
innovation in new payment methods
reshaping how customers transact.
We continue to invest in a suite of
payments and lending options to give
customers flexibility in how they pay
and borrow.
Trust & Security
— We’re relentlessly
focused on driving bad actors out of
the payments ecosystem and investing
in new capabilities to strengthen cus
tomer protections. This includes block
ing higher-risk transactions that origi
nate from social media on the Zelle®
platform. Additionally, we are rolling
out new authentication methods, such
as improved models to detect suspi
cious logins, passkeys for logins on
Chase.com and verification of higher-
risk transactions within the Chase app.
As a result of ongoing efforts, we’ve
seen a 21% year-over-year reduction
in fraud and scam claim rates across
payment methods
13
.
Payments innovation
— To continue
to facilitate new, secure payments solu
tions, we’ve expanded Paze
SM
, a digital
wallet created in partnership with
Early Warning Services. There are
42 merchants signed, of which 31 are
live today. Additionally, as announced,
we plan to deliver fast and reliable
cross-border money movement using
Zelle by leveraging stablecoins to
send international payments.
Lending innovation
— We’ve seen
strong customer adoption across our
range of Pay Over Time® solutions, with
more than 6 million customers totaling
$10.8 billion in originations. Customers
have responded very favorably to
our offerings, and we just ranked #1
in J.D. Power’s Buy Now Pay Later
Satisfaction Study
14
.
We continue to invest in improved
solutions so customers keep coming
to Chase for all their payment needs.
Nontraditional competitors:
Our
focus is on competing at a granular
level — not as a monolithic consumer
franchise. We compete nationally and
also locally — and at the level of strate
gic business units, such as branch
banking, premium card, advised wealth
management and so on. We operate
in highly competitive markets and see
traditional competitors expanding
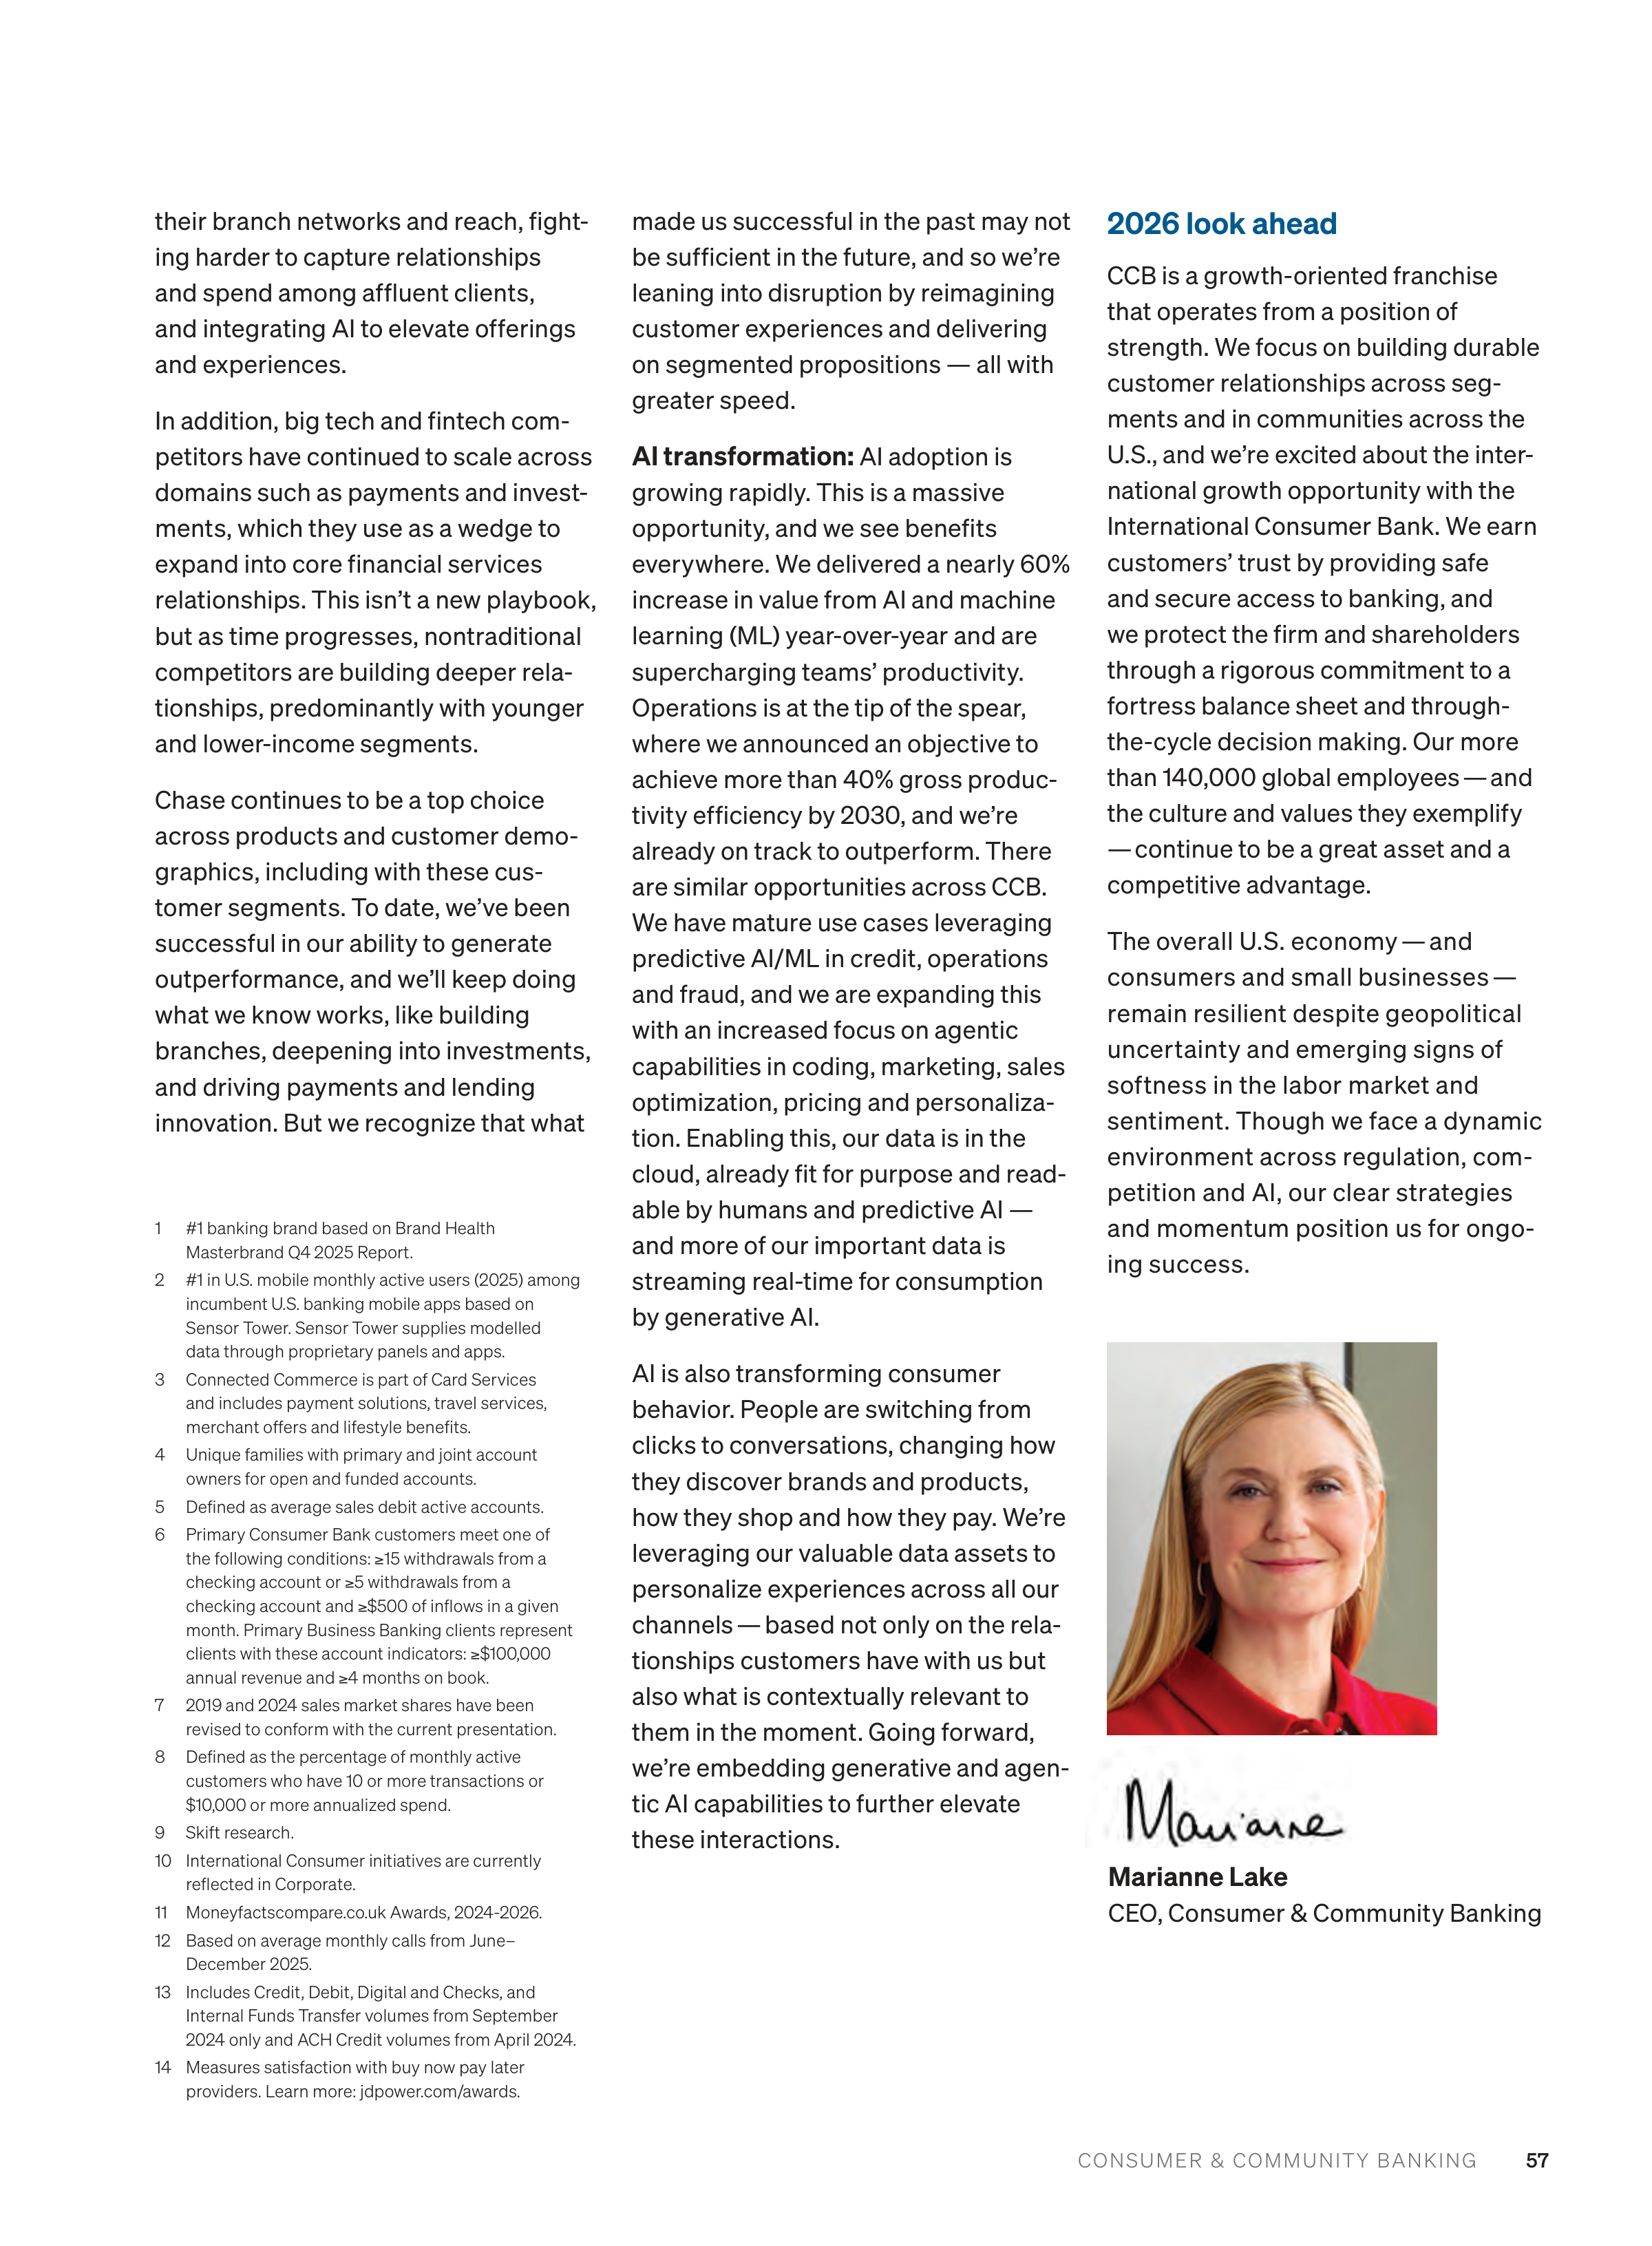

CONSUMER & COMMUNITY BANKING
57
their branch networks and reach, fight
ing harder to capture relationships
and spend among affluent clients,
and integrating AI to elevate offerings
and experiences.
In addition, big tech and fintech com
petitors have continued to scale across
domains such as payments and invest
ments, which they use as a wedge to
expand into core financial services
relationships. This isn’t a new playbook,
but as time progresses, nontraditional
competitors are building deeper rela
tionships, predominantly with younger
and lower-income segments.
Chase continues to be a top choice
across products and customer demo
graphics, including with these cus
tomer segments. To date, we’ve been
successful in our ability to generate
outperformance, and we’ll keep doing
what we know works, like building
branches, deepening into investments,
and driving payments and lending
innovation. But we recognize that what
made us successful in the past may not
be sufficient in the future, and so we’re
leaning into disruption by reimagining
customer experiences and delivering
on segmented propositions — all with
greater speed.
AI transformation
:
AI adoption is
growing rapidly. This is a massive
opportunity, and we see benefits
everywhere. We delivered a nearly 60%
increase in value from AI and machine
learning (ML) year-over-year and are
supercharging teams’ productivity.
Operations is at the tip of the spear,
where we announced an objective to
achieve more than 40% gross produc
tivity efficiency by 2030, and we’re
already on track to outperform. There
are similar opportunities across CCB.
We have mature use cases leveraging
predictive AI/ML in credit, operations
and fraud, and we are expanding this
with an increased focus on agentic
capabilities in coding, marketing, sales
optimization, pricing and personaliza
tion. Enabling this, our data is in the
cloud, already fit for purpose and read
able by humans and predictive AI —
and more of our important data is
streaming real-time for consumption
by generative AI.
AI is also transforming consumer
behavior. People are switching from
clicks to conversations, changing how
they discover brands and products,
how they shop and how they pay. We’re
leveraging our valuable data assets to
personalize experiences across all our
channels — based not only on the rela
tionships customers have with us but
also what is contextually relevant to
them in the moment. Going forward,
we’re embedding generative and agen
tic AI capabilities to further elevate
these interactions.
2026 look ahead
CCB is a growth-oriented franchise
that operates from a position of
strength. We focus on building durable
customer relationships across seg
ments and in communities across the
U.S., and we’re excited about the inter
national growth opportunity with the
International Consumer Bank. We earn
customers’ trust by providing safe
and secure access to banking, and
we protect the firm and shareholders
through a rigorous commitment to a
fortress balance sheet and through-
the-cycle decision making. Our more
than 140,000 global employees — and
the culture and values they exemplify
— continue to be a great asset and a
competitive advantage.
The overall U.S. economy — and
consumers and small businesses —
remain resilient despite geopolitical
uncertainty and emerging signs of
softness in the labor market and
sentiment. Though we face a dynamic
environment across regulation, com
petition and AI, our clear strategies
and momentum position us for ongo
ing success.
1
#1 banking brand based on Brand Health
Masterbrand Q4 2025 Report.
2
#1 in U.S. mobile monthly active users (2025) among
incumbent U.S. banking mobile apps based on
Sensor Tower. Sensor Tower supplies modelled
data through proprietary panels and apps.
3
Connected Commerce is part of Card Services
and includes payment solutions, travel services,
merchant offers and lifestyle benefits.
4
Unique families with primary and joint account
owners for open and funded accounts.
5
Defined as average sales debit active accounts.
6
Primary Consumer Bank customers meet one of
the following conditions:
≥
15 withdrawals from a
checking account or
≥
5 withdrawals from a
checking account and
≥
$500 of inflows in a given
month. Primary Business Banking clients represent
clients with these account indicators:
≥
$100,000
annual revenue and
≥
4 months on book.
7
2019 and 2024 sales market shares have been
revised to conform with the current presentation.
8
Defined as the percentage of monthly active
customers who have 10 or more transactions or
$10,000 or more annualized spend.
9
Skift research.
10
International Consumer initiatives are currently
reflected in Corporate.
11
Moneyfactscompare.co.uk Awards, 2024-2026.
12
Based on average monthly calls from June–
December 2025.
13
Includes Credit, Debit, Digital and Checks, and
Internal Funds Transfer volumes from September
2024 only and ACH Credit volumes from April 2024.
14
Measures satisfaction with buy now pay later
providers. Learn more: jdpower.com/awards.
Marianne Lake
CEO, Consumer & Community Banking
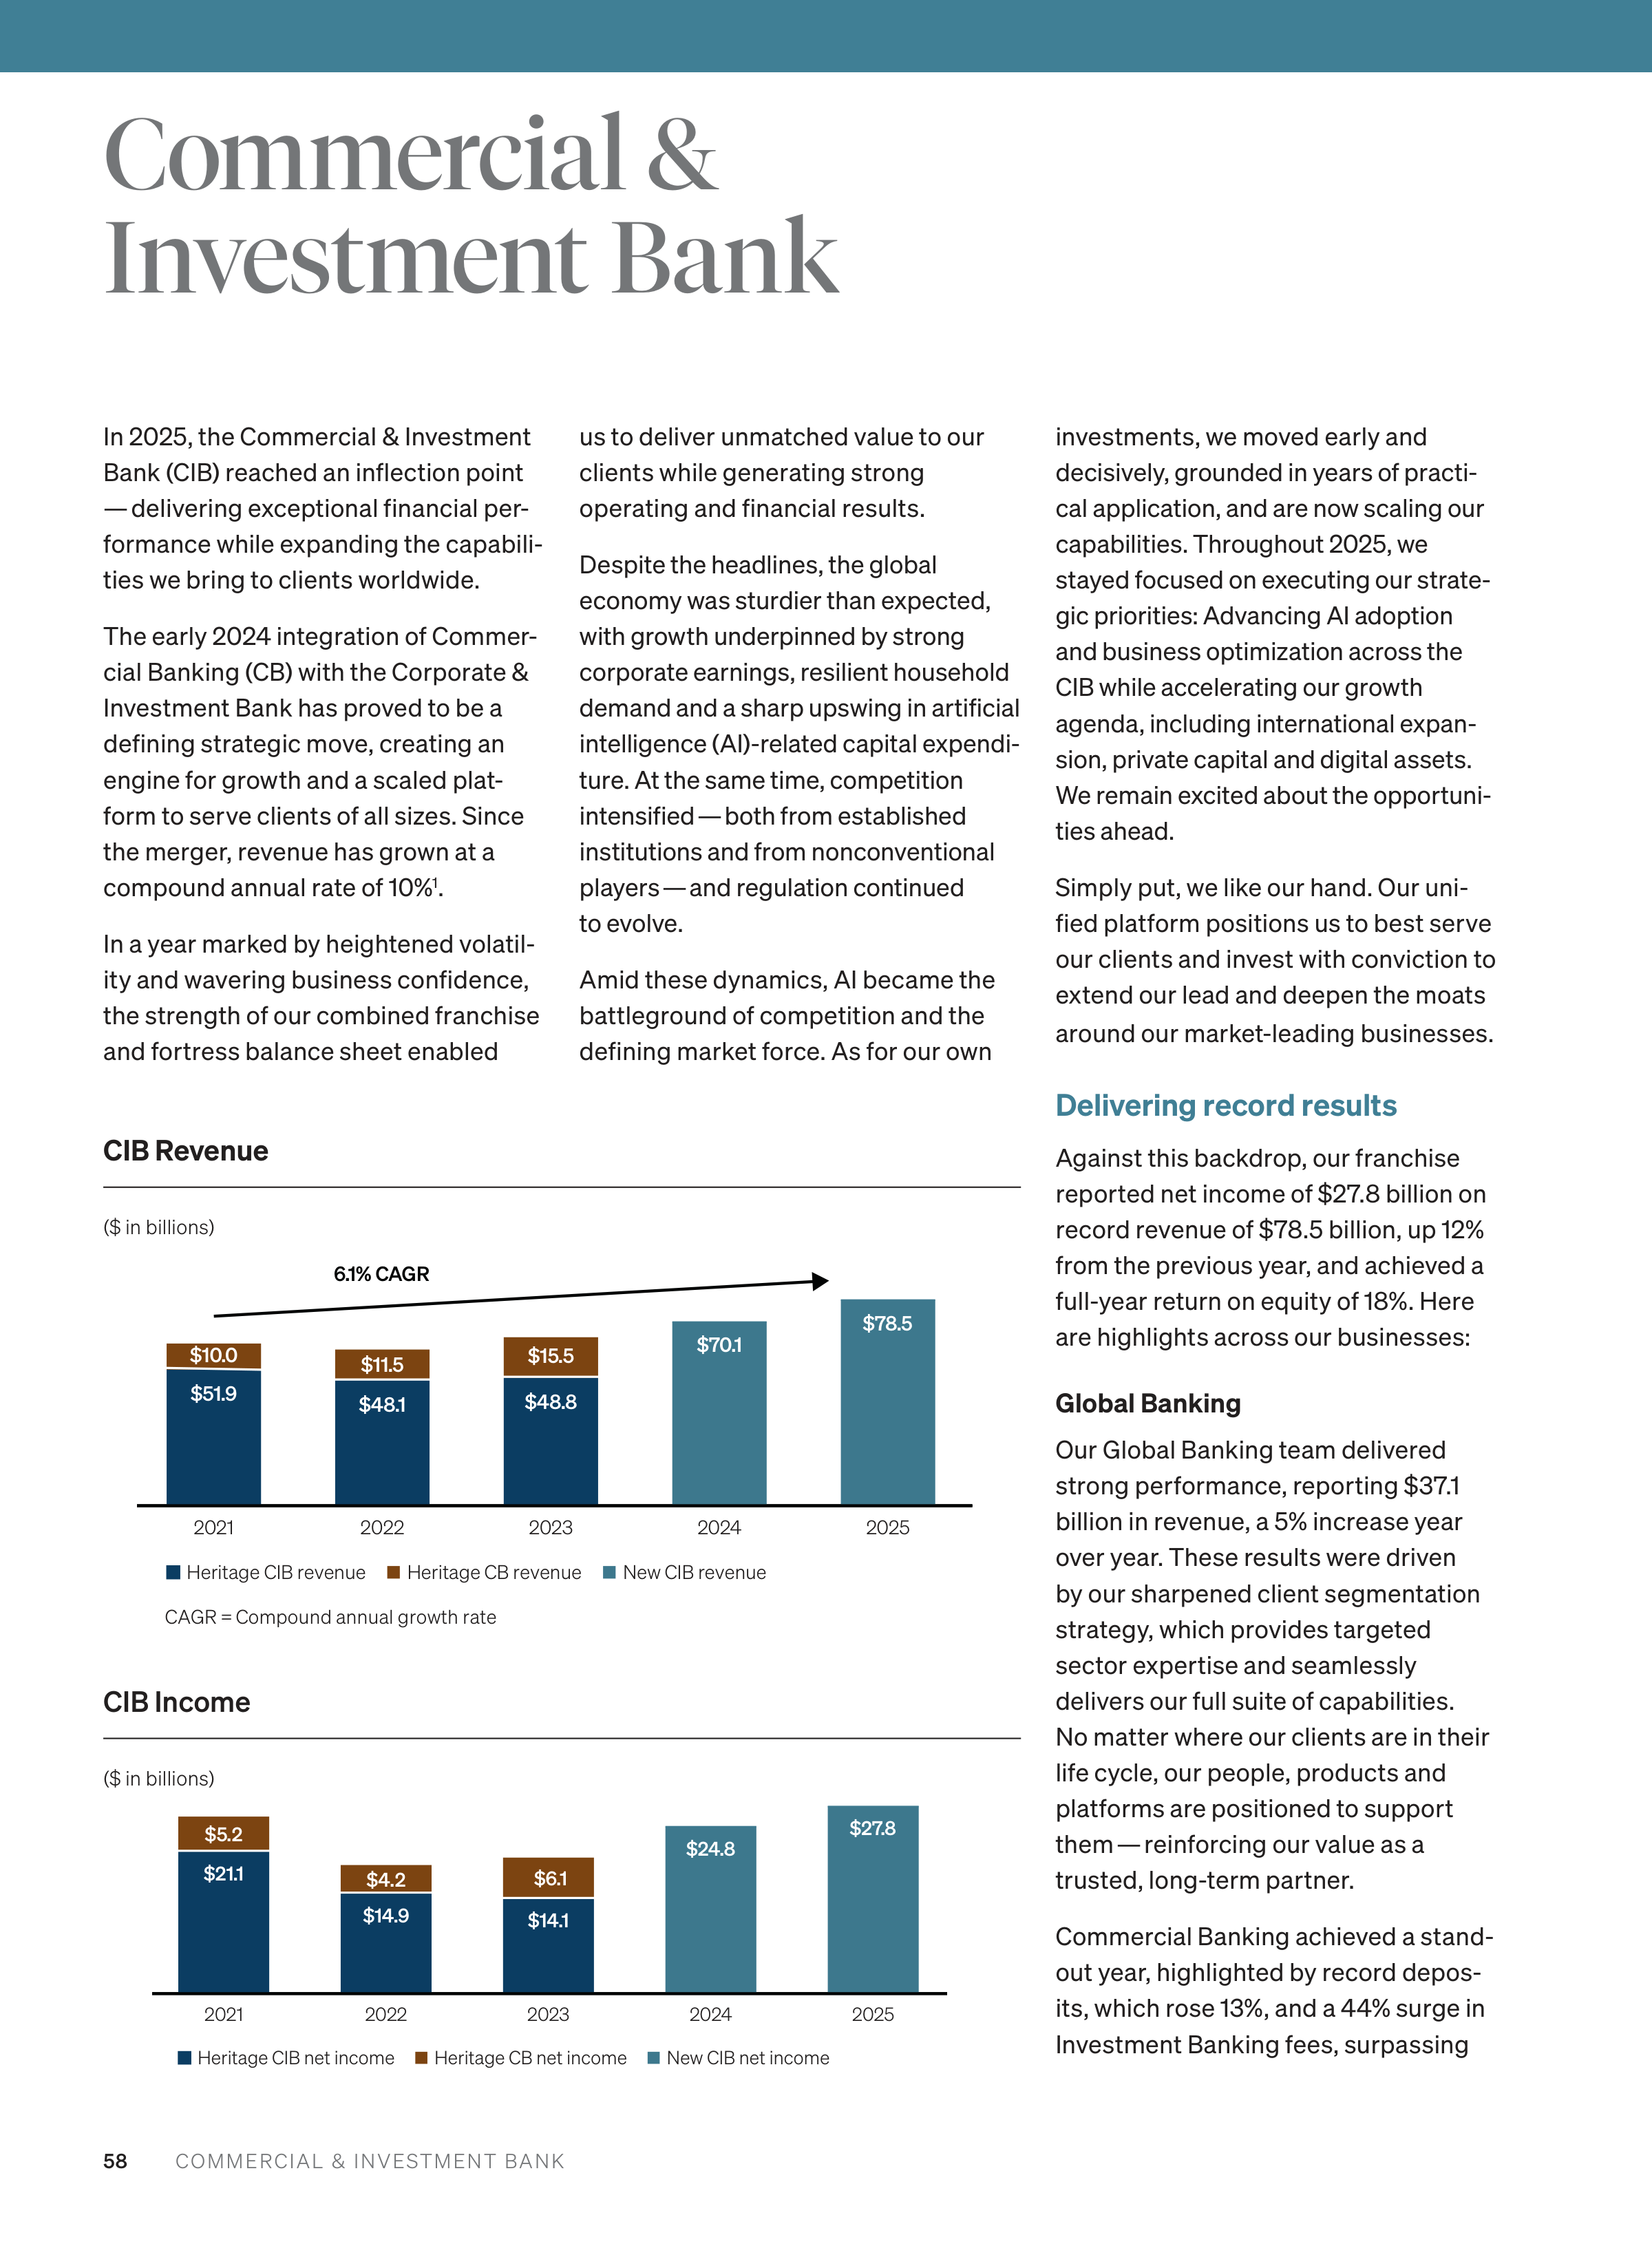
58
COMMERCIAL & INVESTMENT BANK
us to deliver unmatched value to our
clients while generating strong
operating and financial results.
Despite the headlines, the global
economy was sturdier than expected,
with growth underpinned by strong
corporate earnings, resilient household
demand and a sharp upswing in artificial
intelligence (AI)-related capital expendi
ture. At the same time, competition
intensified — both from established
institutions and from nonconventional
players — and regulation continued
to evolve.
Amid these dynamics, AI became the
battleground of competition and the
defining market force. As for our own
investments, we moved early and
decisively, grounded in years of practi
cal application, and are now scaling our
capabilities. Throughout 2025, we
stayed focused on executing our strate
gic priorities: Advancing AI adoption
and business optimization across the
CIB while accelerating our growth
agenda, including international expan
sion, private capital and digital assets.
We remain excited about the opportuni
ties ahead.
Simply put, we like our hand. Our uni
fied platform positions us to best serve
our clients and invest with conviction to
extend our lead and deepen the moats
around our market-leading businesses.
Delivering record results
Against this backdrop, our franchise
reported net income of $27.8 billion on
record revenue of $78.5 billion, up 12%
from the previous year, and achieved a
full-year return on equity of 18%. Here
are highlights across our businesses:
Global Banking
Our Global Banking team delivered
strong performance, reporting $37.1
billion in revenue, a 5% increase year
over year. These results were driven
by our sharpened client segmentation
strategy, which provides targeted
sector expertise and seamlessly
delivers our full suite of capabilities.
No matter where our clients are in their
life cycle, our people, products and
platforms are positioned to support
them — reinforcing our value as a
trusted, long-term partner.
Commercial Banking achieved a stand
out year, highlighted by record depos
its, which rose 13%, and a 44% surge in
Investment Banking fees, surpassing
Commercial &
Investment Bank
In 2025, the Commercial & Investment
Bank (CIB) reached an inflection point
— delivering exceptional financial per
formance while expanding the capabili
ties we bring to clients worldwide.
The early 2024 integration of Commer
cial Banking (CB) with the Corporate &
Investment Bank has proved to be a
defining strategic move, creating an
engine for growth and a scaled plat
form to serve clients of all sizes. Since
the merger, revenue has grown at a
compound annual rate of 10%
1
.
In a year marked by heightened volatil
ity and wavering business confidence,
the strength of our combined franchise
and fortress balance sheet enabled
CIB Revenue
($ in billions)
CIB Income
($ in billions)
Heritage CIB revenue
Heritage CB revenue
New CIB revenue
2025
2024
2023
2022
2021
$51.9
$10.0
$48.1
$11.5
6.1% CAGR
$48.8
$15.5
$70.1
$78.5
CAGR = Compound annual growth rate
Heritage CIB net income
Heritage CB net income
New CIB net income
2025
2024
2023
2022
2021
$21.1
$5.2
$14.9
$4.2
$14.1
$6.1
$24.8
$27.8
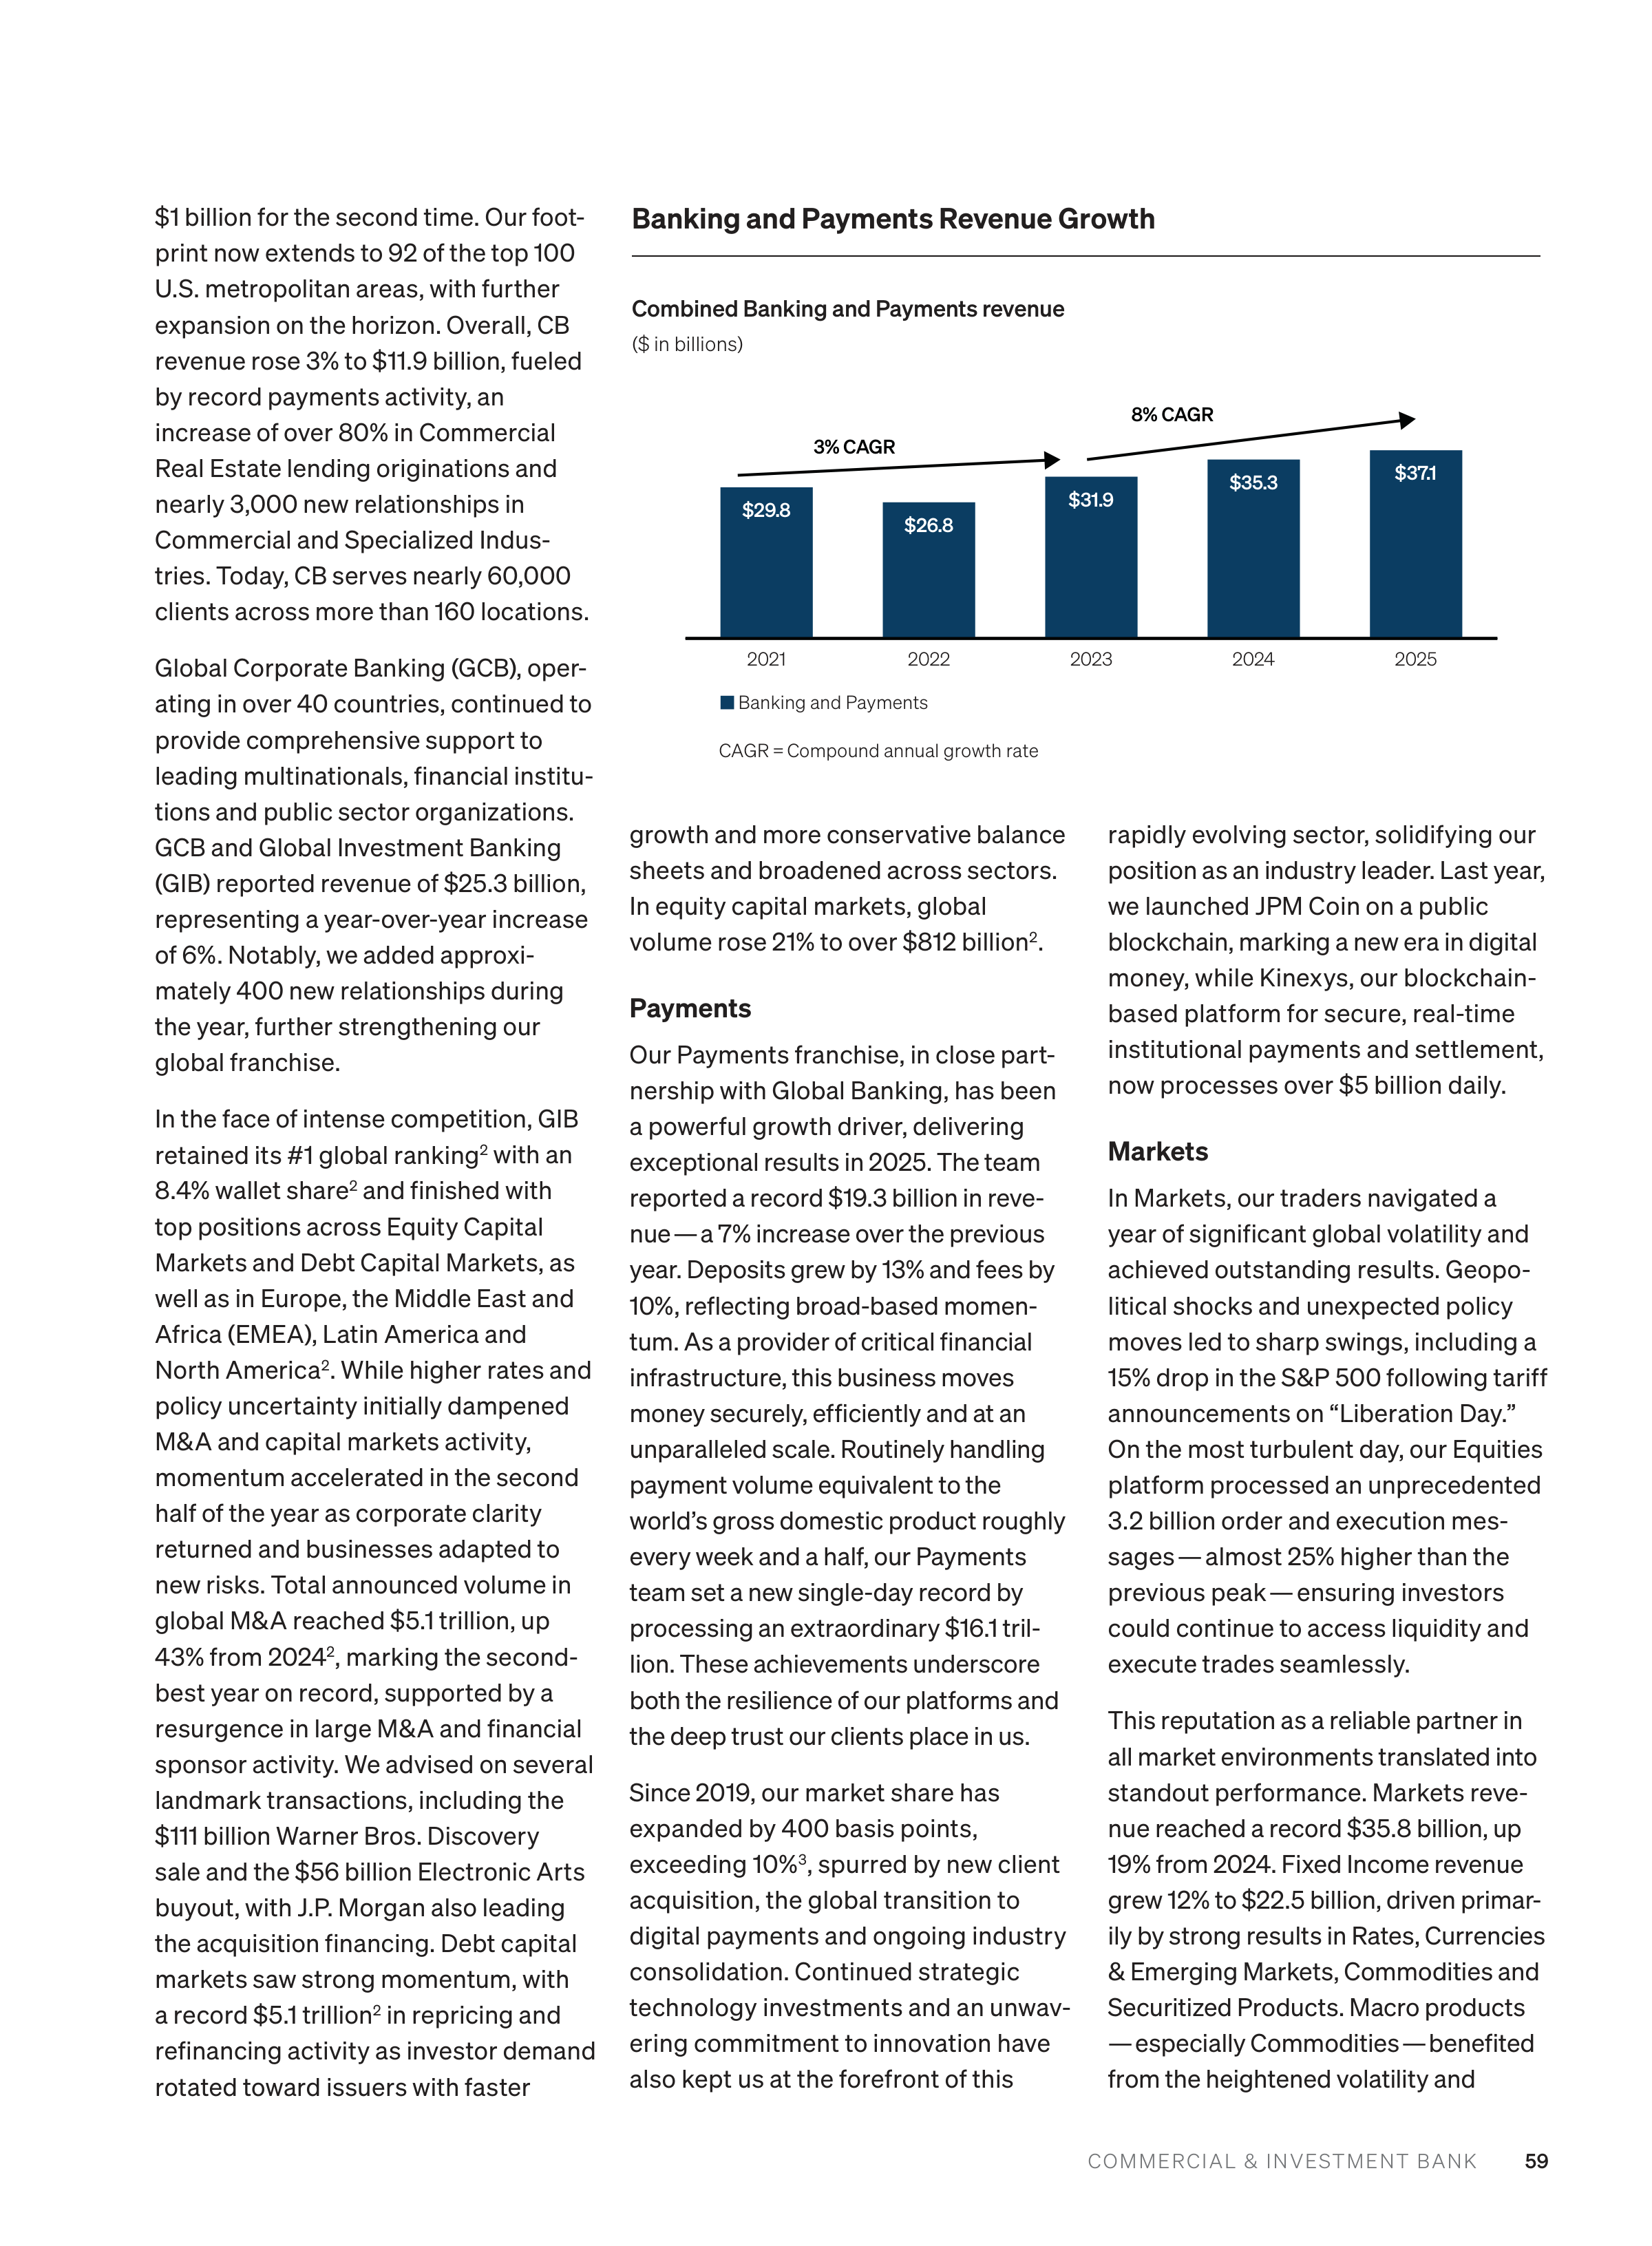
59
COMMERCIAL & INVESTMENT BANK
$1 billion for the second time. Our foot
print now extends to 92 of the top 100
U.S. metropolitan areas, with further
expansion on the horizon. Overall, CB
revenue rose 3% to $11.9 billion, fueled
by record payments activity, an
increase of over 80% in Commercial
Real Estate lending originations and
nearly 3,000 new relationships in
Commercial and Specialized Indus
tries. Today, CB serves nearly 60,000
clients across more than 160 locations.
Global Corporate Banking (GCB), oper
ating in over 40 countries, continued to
provide comprehensive support to
leading multinationals, financial institu
tions and public sector organizations.
GCB and Global Investment Banking
(GIB) reported revenue of $25.3 billion,
representing a year-over-year increase
of 6%. Notably, we added approxi
mately 400 new relationships during
the year, further strengthening our
global franchise.
In the face of intense competition, GIB
retained its #1 global ranking
2
with an
8.4% wallet share
2
and finished with
top positions across Equity Capital
Markets and Debt Capital Markets, as
well as in Europe, the Middle East and
Africa (EMEA), Latin America and
North America
2
. While higher rates and
policy uncertainty initially dampened
M&A and capital markets activity,
momentum accelerated in the second
half of the year as corporate clarity
returned and businesses adapted to
new risks. Total announced volume in
global M&A reached $5.1 trillion, up
43% from 2024
2
, marking the second-
best year on record, supported by a
resurgence in large M&A and financial
sponsor activity. We advised on several
landmark transactions, including the
$111 billion Warner Bros. Discovery
sale and the $56 billion Electronic Arts
buyout, with J.P. Morgan also leading
the acquisition financing. Debt capital
markets saw strong momentum, with
a record $5.1 trillion
2
in repricing and
refinancing activity as investor demand
rotated toward issuers with faster
growth and more conservative balance
sheets and broadened across sectors.
In equity capital markets, global
volume rose 21% to over $812 billion
2
.
Payments
Our Payments franchise, in close part
nership with Global Banking, has been
a powerful growth driver, delivering
exceptional results in 2025. The team
reported a record $19.3 billion in reve
nue — a 7% increase over the previous
year. Deposits grew by 13% and fees by
10%, reflecting broad-based momen
tum. As a provider of critical financial
infrastructure, this business moves
money securely, efficiently and at an
unparalleled scale. Routinely handling
payment volume equivalent to the
world’s gross domestic product roughly
every week and a half, our Payments
team set a new single-day record by
processing an extraordinary $16.1 tril
lion. These achievements underscore
both the resilience of our platforms and
the deep trust our clients place in us.
Since 2019, our market share has
expanded by 400 basis points,
exceeding 10%
3
, spurred by new client
acquisition, the global transition to
digital payments and ongoing industry
consolidation. Continued strategic
technology investments and an unwav
ering commitment to innovation have
also kept us at the forefront of this
rapidly evolving sector, solidifying our
position as an industry leader. Last year,
we launched JPM Coin on a public
blockchain, marking a new era in digital
money, while Kinexys, our blockchain-
based platform for secure, real-time
institutional payments and settlement,
now processes over $5 billion daily.
Markets
In Markets, our traders navigated a
year of significant global volatility and
achieved outstanding results. Geopo
litical shocks and unexpected policy
moves led to sharp swings, including a
15% drop in the S&P 500 following tariff
announcements on “Liberation Day.”
On the most turbulent day, our Equities
platform processed an unprecedented
3.2 billion order and execution mes
sages — almost 25% higher than the
previous peak — ensuring investors
could continue to access liquidity and
execute trades seamlessly.
This reputation as a reliable partner in
all market environments translated into
standout performance. Markets reve
nue reached a record $35.8 billion, up
19% from 2024. Fixed Income revenue
grew 12% to $22.5 billion, driven primar
ily by strong results in Rates, Currencies
& Emerging Markets, Commodities and
Securitized Products. Macro products
— especially Commodities — benefited
from the heightened volatility and
Banking and Payments Revenue Growth
Combined Banking and Payments revenue
($ in billions)
Banking and Payments
CAGR = Compound annual growth rate
2025
2024
2023
2022
2021
$29.8
$26.8
$31.9
$35.3
$37.1
3% CAGR
8% CAGR
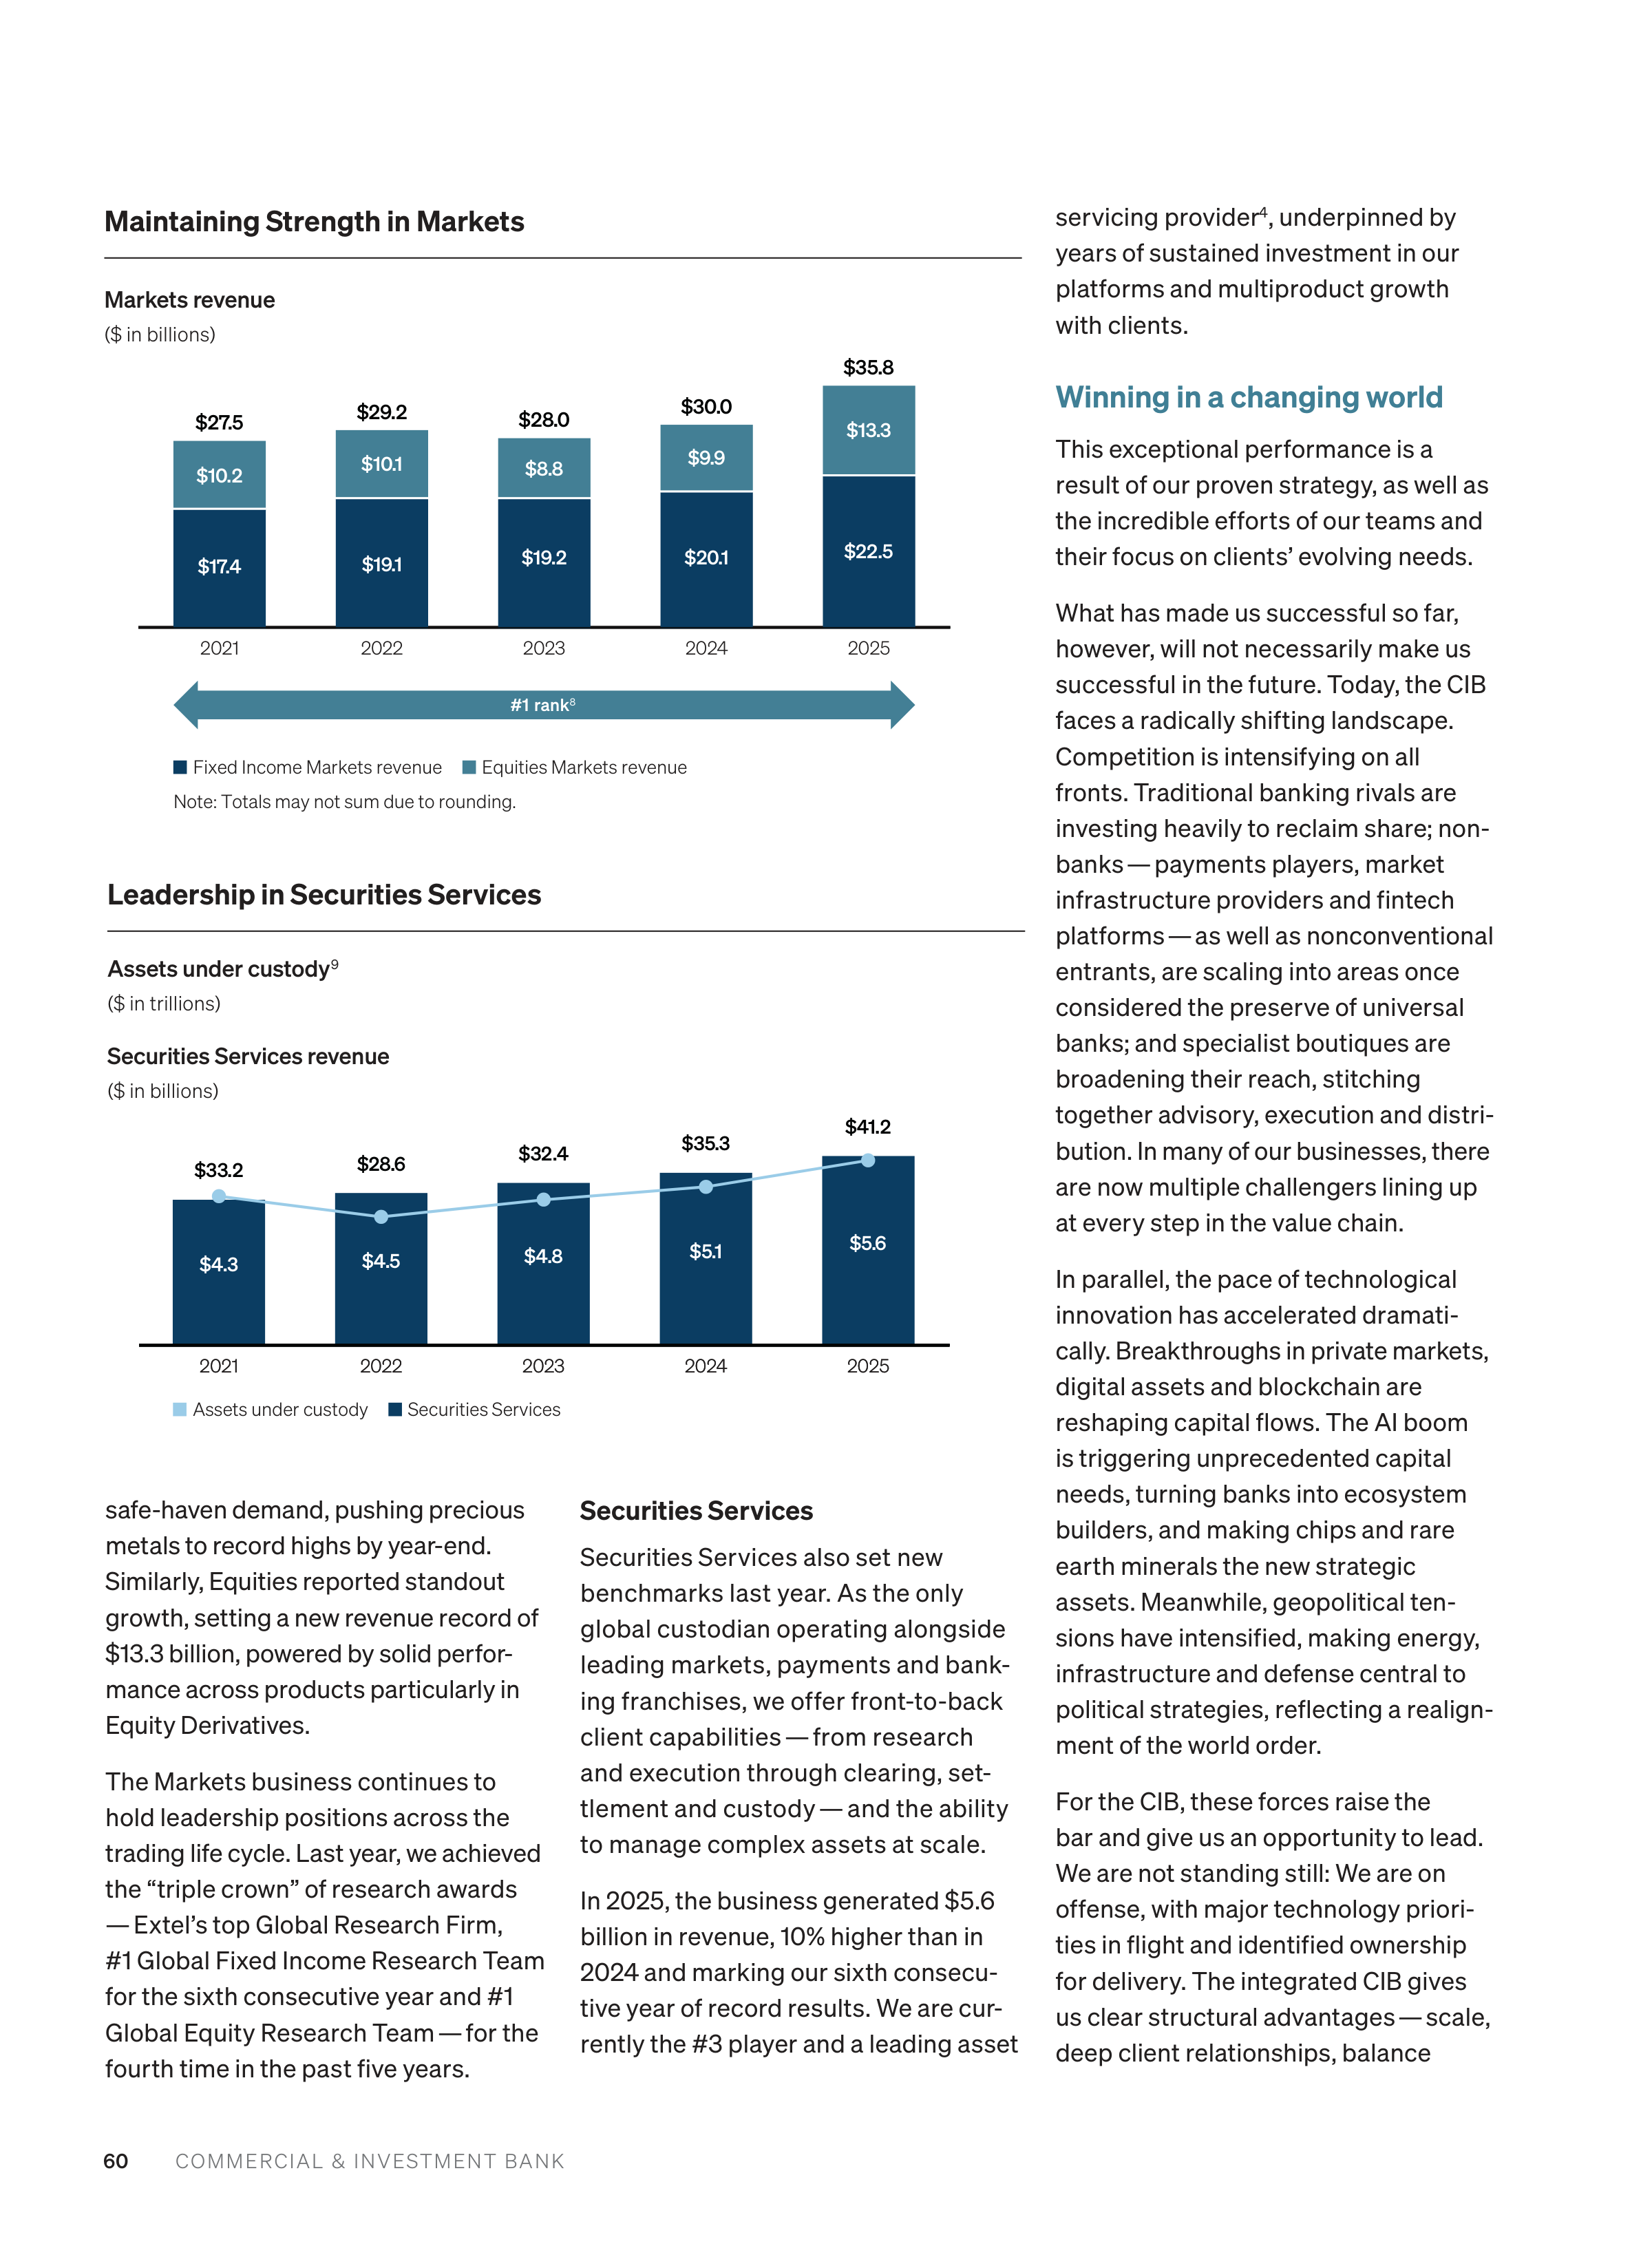
60
COMMERCIAL & INVESTMENT BANK
safe-haven demand, pushing precious
metals to record highs by year-end.
Similarly, Equities reported standout
growth, setting a new revenue record of
$13.3 billion, powered by solid perfor
mance across products particularly in
Equity Derivatives.
The Markets business continues to
hold leadership positions across the
trading life cycle. Last year, we achieved
the “triple crown” of research awards
— Extel’s top Global Research Firm,
#1 Global Fixed Income Research Team
for the sixth consecutive year and #1
Global Equity Research Team — for the
fourth time in the past five years.
Securities Services
Securities Services also set new
benchmarks last year. As the only
global custodian operating alongside
leading markets, payments and bank
ing franchises, we offer front-to-back
client capabilities — from research
and execution through clearing, set
tlement and custody — and the ability
to manage complex assets at scale.
In 2025, the business generated $5.6
billion in revenue, 10% higher than in
2024 and marking our sixth consecu
tive year of record results. We are cur
rently the #3 player and a leading asset
servicing provider
4
, underpinned by
years of sustained investment in our
platforms and multiproduct growth
with clients.
Winning in a changing world
This exceptional performance is a
result of our proven strategy, as well as
the incredible efforts of our teams and
their focus on clients’ evolving needs.
What has made us successful so far,
however, will not necessarily make us
successful in the future. Today, the CIB
faces a radically shifting landscape.
Competition is intensifying on all
fronts. Traditional banking rivals are
investing heavily to reclaim share; non
banks — payments players, market
infrastructure providers and fintech
platforms — as well as nonconventional
entrants, are scaling into areas once
considered the preserve of universal
banks; and specialist boutiques are
broadening their reach, stitching
together advisory, execution and distri
bution. In many of our businesses, there
are now multiple challengers lining up
at every step in the value chain.
In parallel, the pace of technological
innovation has accelerated dramati
cally. Breakthroughs in private markets,
digital assets and blockchain are
reshaping capital flows. The AI boom
is triggering unprecedented capital
needs, turning banks into ecosystem
builders, and making chips and rare
earth minerals the new strategic
assets. Meanwhile, geopolitical ten
sions have intensified, making energy,
infrastructure and defense central to
political strategies, reflecting a realign
ment of the world order.
For the CIB, these forces raise the
bar and give us an opportunity to lead.
We are not standing still: We are on
offense, with major technology priori
ties in flight and identified ownership
for delivery. The integrated CIB gives
us clear structural advantages — scale,
deep client relationships, balance
Maintaining Strength in Markets
Markets revenue
($ in billions)
Leadership in Securities Services
Assets under custody
9
($ in trillions)
Securities Services revenue
($ in billions)
Fixed Income Markets revenue
Equities Markets revenue
Note: Totals may not sum due to rounding.
#1 rank
8
2025
2024
2023
2022
2021
$17.4
$10.2
$27.5
$19.1
$10.1
$29.2
$19.2
$8.8
$20.1
$9.9
$22.5
$13.3
$28.0
$30.0
$35.8
Assets under custody
Securities Services
2025
2024
2023
2022
2021
2025
2024
2023
2022
2021
$4.3
$33.2
$4.5
$4.8
$5.1
$5.6
$28.6
$32.4
$35.3
$41.2
61
COMMERCIAL & INVESTMENT BANK
sheet capacity, global reach, AI capa
bilities and a vast data set. Our task
now is to convert those strengths into
simpler, more seamless client experi
ences and higher return growth.
Here’s how we’re positioning to stay
ahead:
1. Igniting growth through our
integration
The integration of our businesses
has created a powerful “combustion
effect” — igniting growth and unlock
ing new opportunities across our
expanded organization. Uniting our
teams has amplified our collective
impact, making the whole greater
than the sum of its parts.
For example, in Global Banking, by
combining our leading U.S. Commer
cial and Specialized Industries fran
chise with the deep sector expertise
of our investment bankers, we are sup
porting clients with high-value oppor
tunities, including sell-side mandates
and capital raising. This drives deeper
client engagement and expands our
share of wallet.
Our industry coverage is also comple
mented by a targeted focus on high-
growth subsectors, such as enterprise
and cloud, applied technology, biotech
and healthcare services, where our
bankers’ expertise delivers differenti
ated value and positions us to capture
outsized growth.
At the same time, our larger business
footprint creates more scope to broaden
client engagement with macro solu
tions, especially foreign exchange.
While we have long been strong in the
U.S. dollar and other major currencies,
the integrated platform is accelerating
our expansion into new markets,
offering clients a more comprehensive
suite of solutions and deepening our
relationships.
2. Powering private markets
Despite increased scrutiny of private
credit in recent months, we believe
private markets will remain an import
ant part of the financial system over
the long term.
Today, private companies far outnum
ber public ones, with many choosing to
remain private longer due to the high
costs and complexities of public list
ings. Simultaneously, surging investor
appetite for private assets is reshaping
capital flows and creating new oppor
tunities for growth. Assets under man
agement in private markets have grown
at an annual rate of 14% since 2013
5
and
are projected to nearly double — from
around $17 trillion in 2024 to $32 trillion
in 2030
6
.
Clients in these markets are increas
ingly interconnected, forming a network
where limited partners, general
partners and portfolio companies
collaborate and influence each other’s
banking, financing and advisory needs.
To best serve this ecosystem, the CIB
has launched several initiatives. We
have reorganized our coverage model
to serve the private capital markets in
a more integrated way, creating a joint
venture between the CIB and the
Private Bank to deliver seamless solu
tions — from frictionless access to
liquidity to creative monetization strat
egies — at every stage of the private
capital life cycle. Meanwhile, our new
Private Capital Advisory & Solutions
team provides clients with comprehen
sive advice across the private capital
spectrum, connecting investors and
companies well before any IPO or sale.
On the financing side, we remain
a reliable provider of credit to well-
established direct lenders. In addition,
last year, we launched the Strategic
Financing Solutions group, combining
Global Banking and Markets structur
ing expertise to offer clients a compre
hensive suite of financing options —
from direct lending to syndicated loans
and high yield. Our direct lending
platform has expanded as well, with
$14 billion total exposure
7
from our
$50 billion commitment to private
credit, alongside over $25 billion of
partner capital available.
Finally, in an industry first, we intro
duced private company sell-side
research last year, providing in-depth
analysis on influential companies such
as OpenAI, Anthropic and Stripe —
businesses driving innovation in their
sectors.
3. Expanding in international
markets
Today, nearly 40% of the CIB’s revenue
originates from outside the United
States with broad-based growth across
Asia Pacific, EMEA and Latin America.
Our scale, deep local expertise and
ability to navigate complex regulatory
and geopolitical landscapes have
enabled us to deliver effective solu
tions to clients worldwide.
The opportunity ahead is significant:
International markets are poised to
outpace domestic growth, fueled
by economic diversification, rising
cross-border trade and a new wave of
investment — particularly in the Middle
East, North Africa and Turkey. Amid
evolving regional dynamics, we are
advancing with a measured, phased
approach designed to protect continu
ity of service and client outcomes.
To capture this regional growth, we are
investing in our capabilities in Bahrain,
Saudi Arabia and the United Arab
Emirates, as well as expanding our
franchise in Turkey. In addition, we’re
increasing critical infrastructure in
Africa, including a new onshore pres
ence on the Ivory Coast and Kenya. Our
focus extends beyond serving large
multinationals to include international
mid-cap and institutional clients, as
well as subsidiaries of U.S.-based firms.
62
COMMERCIAL & INVESTMENT BANK
A key driver of our expansion is extend
ing our Payments solutions in new
geographies. Today, the firm processes
around 65 million transactions daily
and moves nearly $12 trillion across
120 currencies. But the ambition is
broader — to expand coverage and
products across venture capital, the
Innovation Economy and mid-cap
corporates while deepening our offer
ings in equities and fixed income.
4. Building an AI-powered business
Across the CIB, we’re rewiring our
business to embed AI in every process,
maintain modern data architecture and
drive measurable business outcomes.
AI is already creating material effi
ciency gains. In transaction screening,
AI has enabled us to review more than
double the volume while halving the
number of manual operator checks.
That means quicker turnaround for
clients and fewer delays. AI is also
elevating how we work — cutting man
ual tasks, accelerating innovation and
improving client outcomes. Over 90%
of our engineers now use AI code
assistants, and more than 65,000
CIB colleagues actively use LLM Suite,
our generative AI platform.
We’re deploying AI proactively for
clients, too — corporate treasury
clients now have a cash-flow-
forecasting tool that supports smarter
liquidity management. In Markets,
Prime Finance applies AI to manage
our inventory of securities, sharpen
pricing, strengthen risk management
and optimize capital efficiency.
Rather than a one-size-fits-all
approach, each of our businesses has
its own AI strategy aligned to the end-
to-end client journey, ensuring AI is
applied where it creates the most value
— all underpinned by a large, well-
organized data estate.
5. Transforming the client
experience
Likewise, we’re continuing to invest
significantly in our digital capabilities,
focusing on improving every aspect of
the client experience, reducing unnec
essary hurdles and giving clients a uni
fied view of their financial information.
Our leading digital platforms now sup
port more than 400,000 users, ranging
from small businesses to large global
companies. These platforms bring
together account management, pay
ments and cash flow tools so clients
can handle their finances more easily
and efficiently in one place.
We’re also investing in new solutions
tailored to the needs of unique client
segments. For example, U.S. technol
ogy startups benefit from a full digital
onboarding and banking experience
built for founders, plus dedicated Inno
vation Economy coverage supported
by 550 bankers, so they can expand
from seed to IPO. Midsized companies
get access to automated payment
solutions and real-time financial
insights, making it easier for them
to scale their businesses.
By combining these efforts, we’re com
mitted to delivering a faster, smarter
and more seamless digital experience
for all our clients.
6. Leading the way in digital assets
Once a niche innovation, digital assets
have developed into a significant eco
system, changing how value is stored,
transferred and accessed. Crypto
assets, formerly on the fringe, have
also experienced notable growth, and
stablecoins are increasingly being
used for transactions. As adoption
expands among corporations and
financial institutions, tokenized assets
— digital tokens representing real-
world assets — are expected to see
continued growth, with some projec
tions estimating the market could
reach $13 trillion by 2030, highlighting
the ongoing evolution of digital finance.
The CIB has been at the forefront of
this shift with its Kinexys platform,
launched in 2019, which enables busi
nesses to make fast, secure payments
using blockchain technology. We have
also developed new blockchain-based
products, such as deposit tokens and
tokenized money market funds, that
deliver faster settlement, greater
transparency and improved efficiency
compared with traditional banking.
Since 2023, the number of transactions
on these platforms has grown thirty
fold. By investing early in digital pay
ments, financing and crypto solutions,
we are well-positioned to compete with
emerging digital-native financial firms
while capitalizing on the trust and reli
ability that J.P. Morgan is known for.
2025 marked the first U.S. commercial
paper issuance on the Solana public
blockchain for Galaxy Digital Holdings,
settled using stablecoin and digital
custody. This milestone demonstrates
that public blockchains can support
institutional-grade transactions, offer
ing lower costs and access to new
sources of liquidity.
Broader adoption hinges on regulatory
clarity. Ultimately, the firm supports
regulation that encourages innovation
but also includes clear frameworks
and safeguards so that tokenized
assets are treated consistently with
traditional ones.
7. Banking for impact
As we continue to innovate and grow
our business, we remain equally
committed to harnessing our scale and
resources to drive positive change in
society — deploying capital and exper
tise to strengthen resilience and
expand economic opportunity in the
United States and key international
markets. Our work reflects a core
belief: Commercial success and social
impact are mutually reinforcing.
Central to this mission is the firm’s $1.5
trillion Security & Resiliency Initiative, a
decade-long effort to facilitate, finance
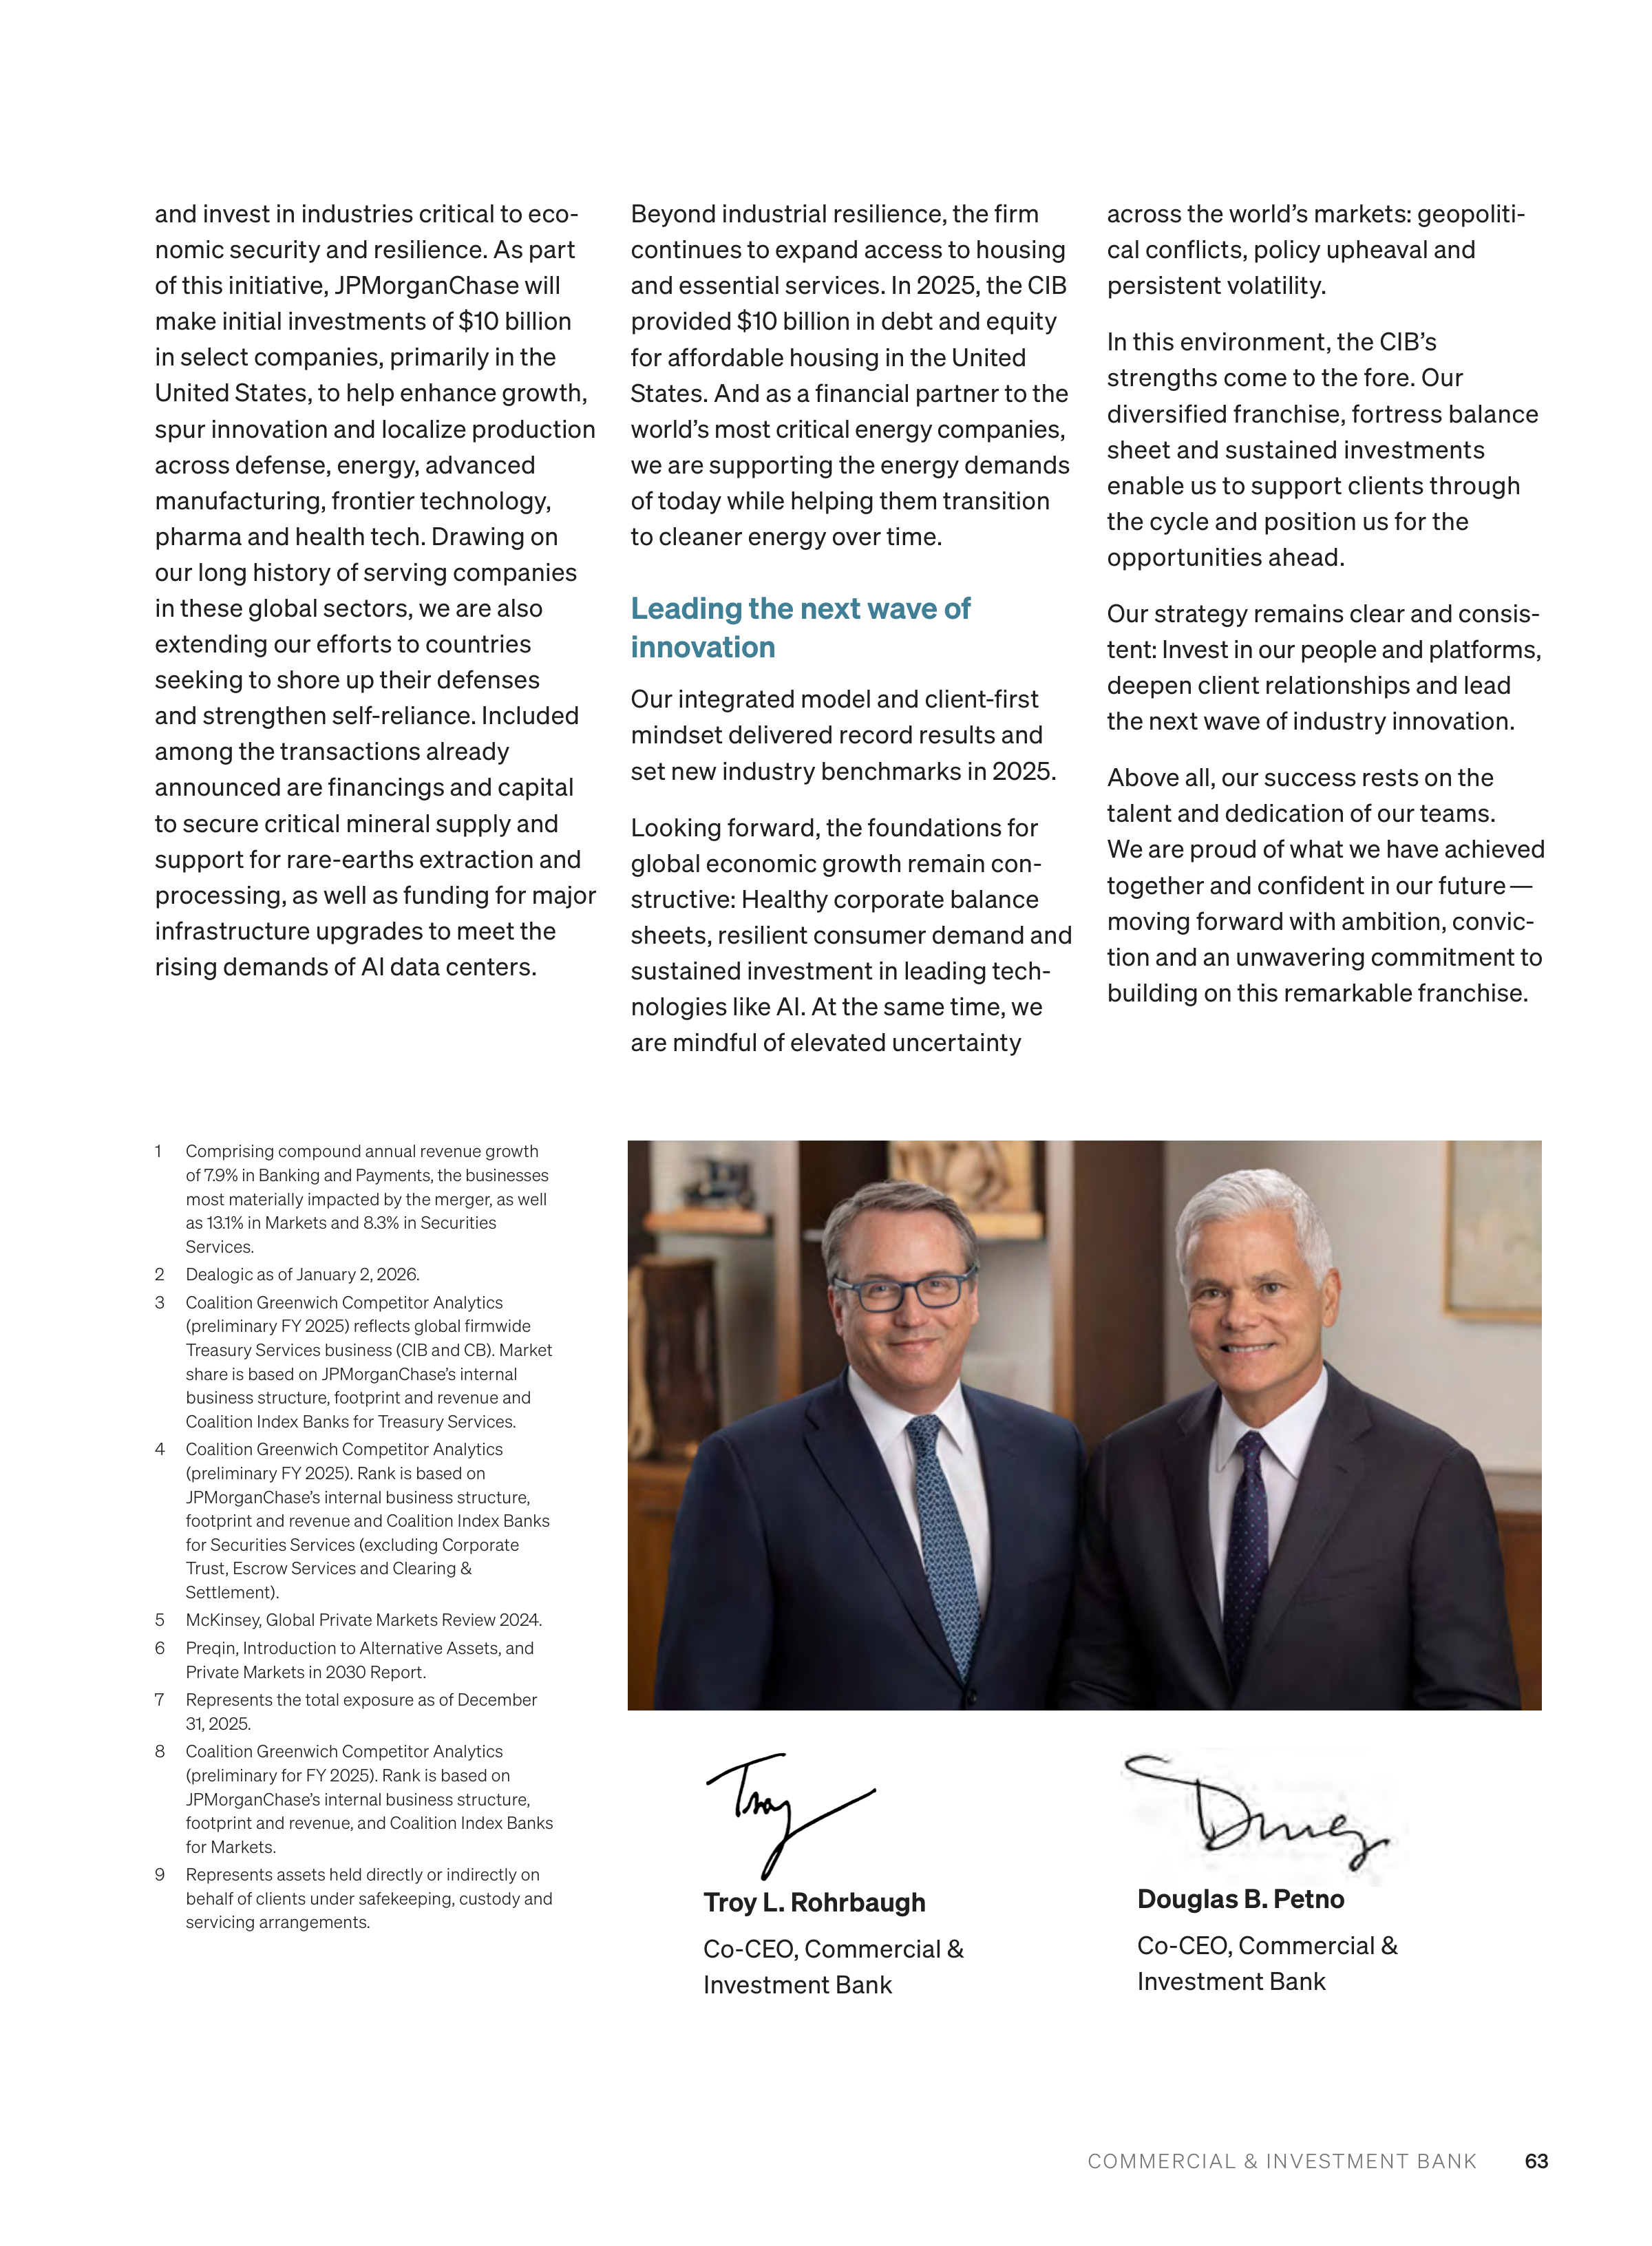
63
COMMERCIAL & INVESTMENT BANK
and invest in industries critical to eco
nomic security and resilience. As part
of this initiative, JPMorganChase will
make initial investments of $10 billion
in select companies, primarily in the
United States, to help enhance growth,
spur innovation and localize production
across defense, energy, advanced
manufacturing, frontier technology,
pharma and health tech. Drawing on
our long history of serving companies
in these global sectors, we are also
extending our efforts to countries
seeking to shore up their defenses
and strengthen self-reliance. Included
among the transactions already
announced are financings and capital
to secure critical mineral supply and
support for rare-earths extraction and
processing, as well as funding for major
infrastructure upgrades to meet the
rising demands of AI data centers.
Beyond industrial resilience, the firm
continues to expand access to housing
and essential services. In 2025, the CIB
provided $10 billion in debt and equity
for affordable housing in the United
States. And as a financial partner to the
world’s most critical energy companies,
we are supporting the energy demands
of today while helping them transition
to cleaner energy over time.
Leading the next wave of
innovation
Our integrated model and client-first
mindset delivered record results and
set new industry benchmarks in 2025.
Looking forward, the foundations for
global economic growth remain con
structive: Healthy corporate balance
sheets, resilient consumer demand and
sustained investment in leading tech
nologies like AI. At the same time, we
are mindful of elevated uncertainty
across the world’s markets: geopoliti
cal conflicts, policy upheaval and
persistent volatility.
In this environment, the CIB’s
strengths come to the fore. Our
diversified franchise, fortress balance
sheet and sustained investments
enable us to support clients through
the cycle and position us for the
opportunities ahead.
Our strategy remains clear and consis
tent: Invest in our people and platforms,
deepen client relationships and lead
the next wave of industry innovation.
Above all, our success rests on the
talent and dedication of our teams.
We are proud of what we have achieved
together and confident in our future —
moving forward with ambition, convic
tion and an unwavering commitment to
building on this remarkable franchise.
1
Comprising compound annual revenue growth
of 7.9% in Banking and Payments, the businesses
most materially impacted by the merger, as well
as 13.1% in Markets and 8.3% in Securities
Services.
2
Dealogic as of January 2, 2026.
3
Coalition Greenwich Competitor Analytics
(preliminary FY 2025) reflects global firmwide
Treasury Services business (CIB and CB). Market
share is based on JPMorganChase’s internal
business structure, footprint and revenue and
Coalition Index Banks for Treasury Services.
4
Coalition Greenwich Competitor Analytics
(preliminary FY 2025). Rank is based on
JPMorganChase’s internal business structure,
footprint and revenue and Coalition Index Banks
for Securities Services (excluding Corporate
Trust, Escrow Services and Clearing &
Settlement).
5
McKinsey, Global Private Markets Review 2024.
6
Preqin, Introduction to Alternative Assets, and
Private Markets in 2030 Report.
7
Represents the total exposure as of December
31, 2025.
8
Coalition Greenwich Competitor Analytics
(preliminary for FY 2025). Rank is based on
JPMorganChase’s internal business structure,
footprint and revenue, and Coalition Index Banks
for Markets.
9
Represents assets held directly or indirectly on
behalf of clients under safekeeping, custody and
servicing arrangements.
Troy L. Rohrbaugh
Co-CEO, Commercial &
Investment Bank
Douglas B. Petno
Co-CEO, Commercial &
Investment Bank
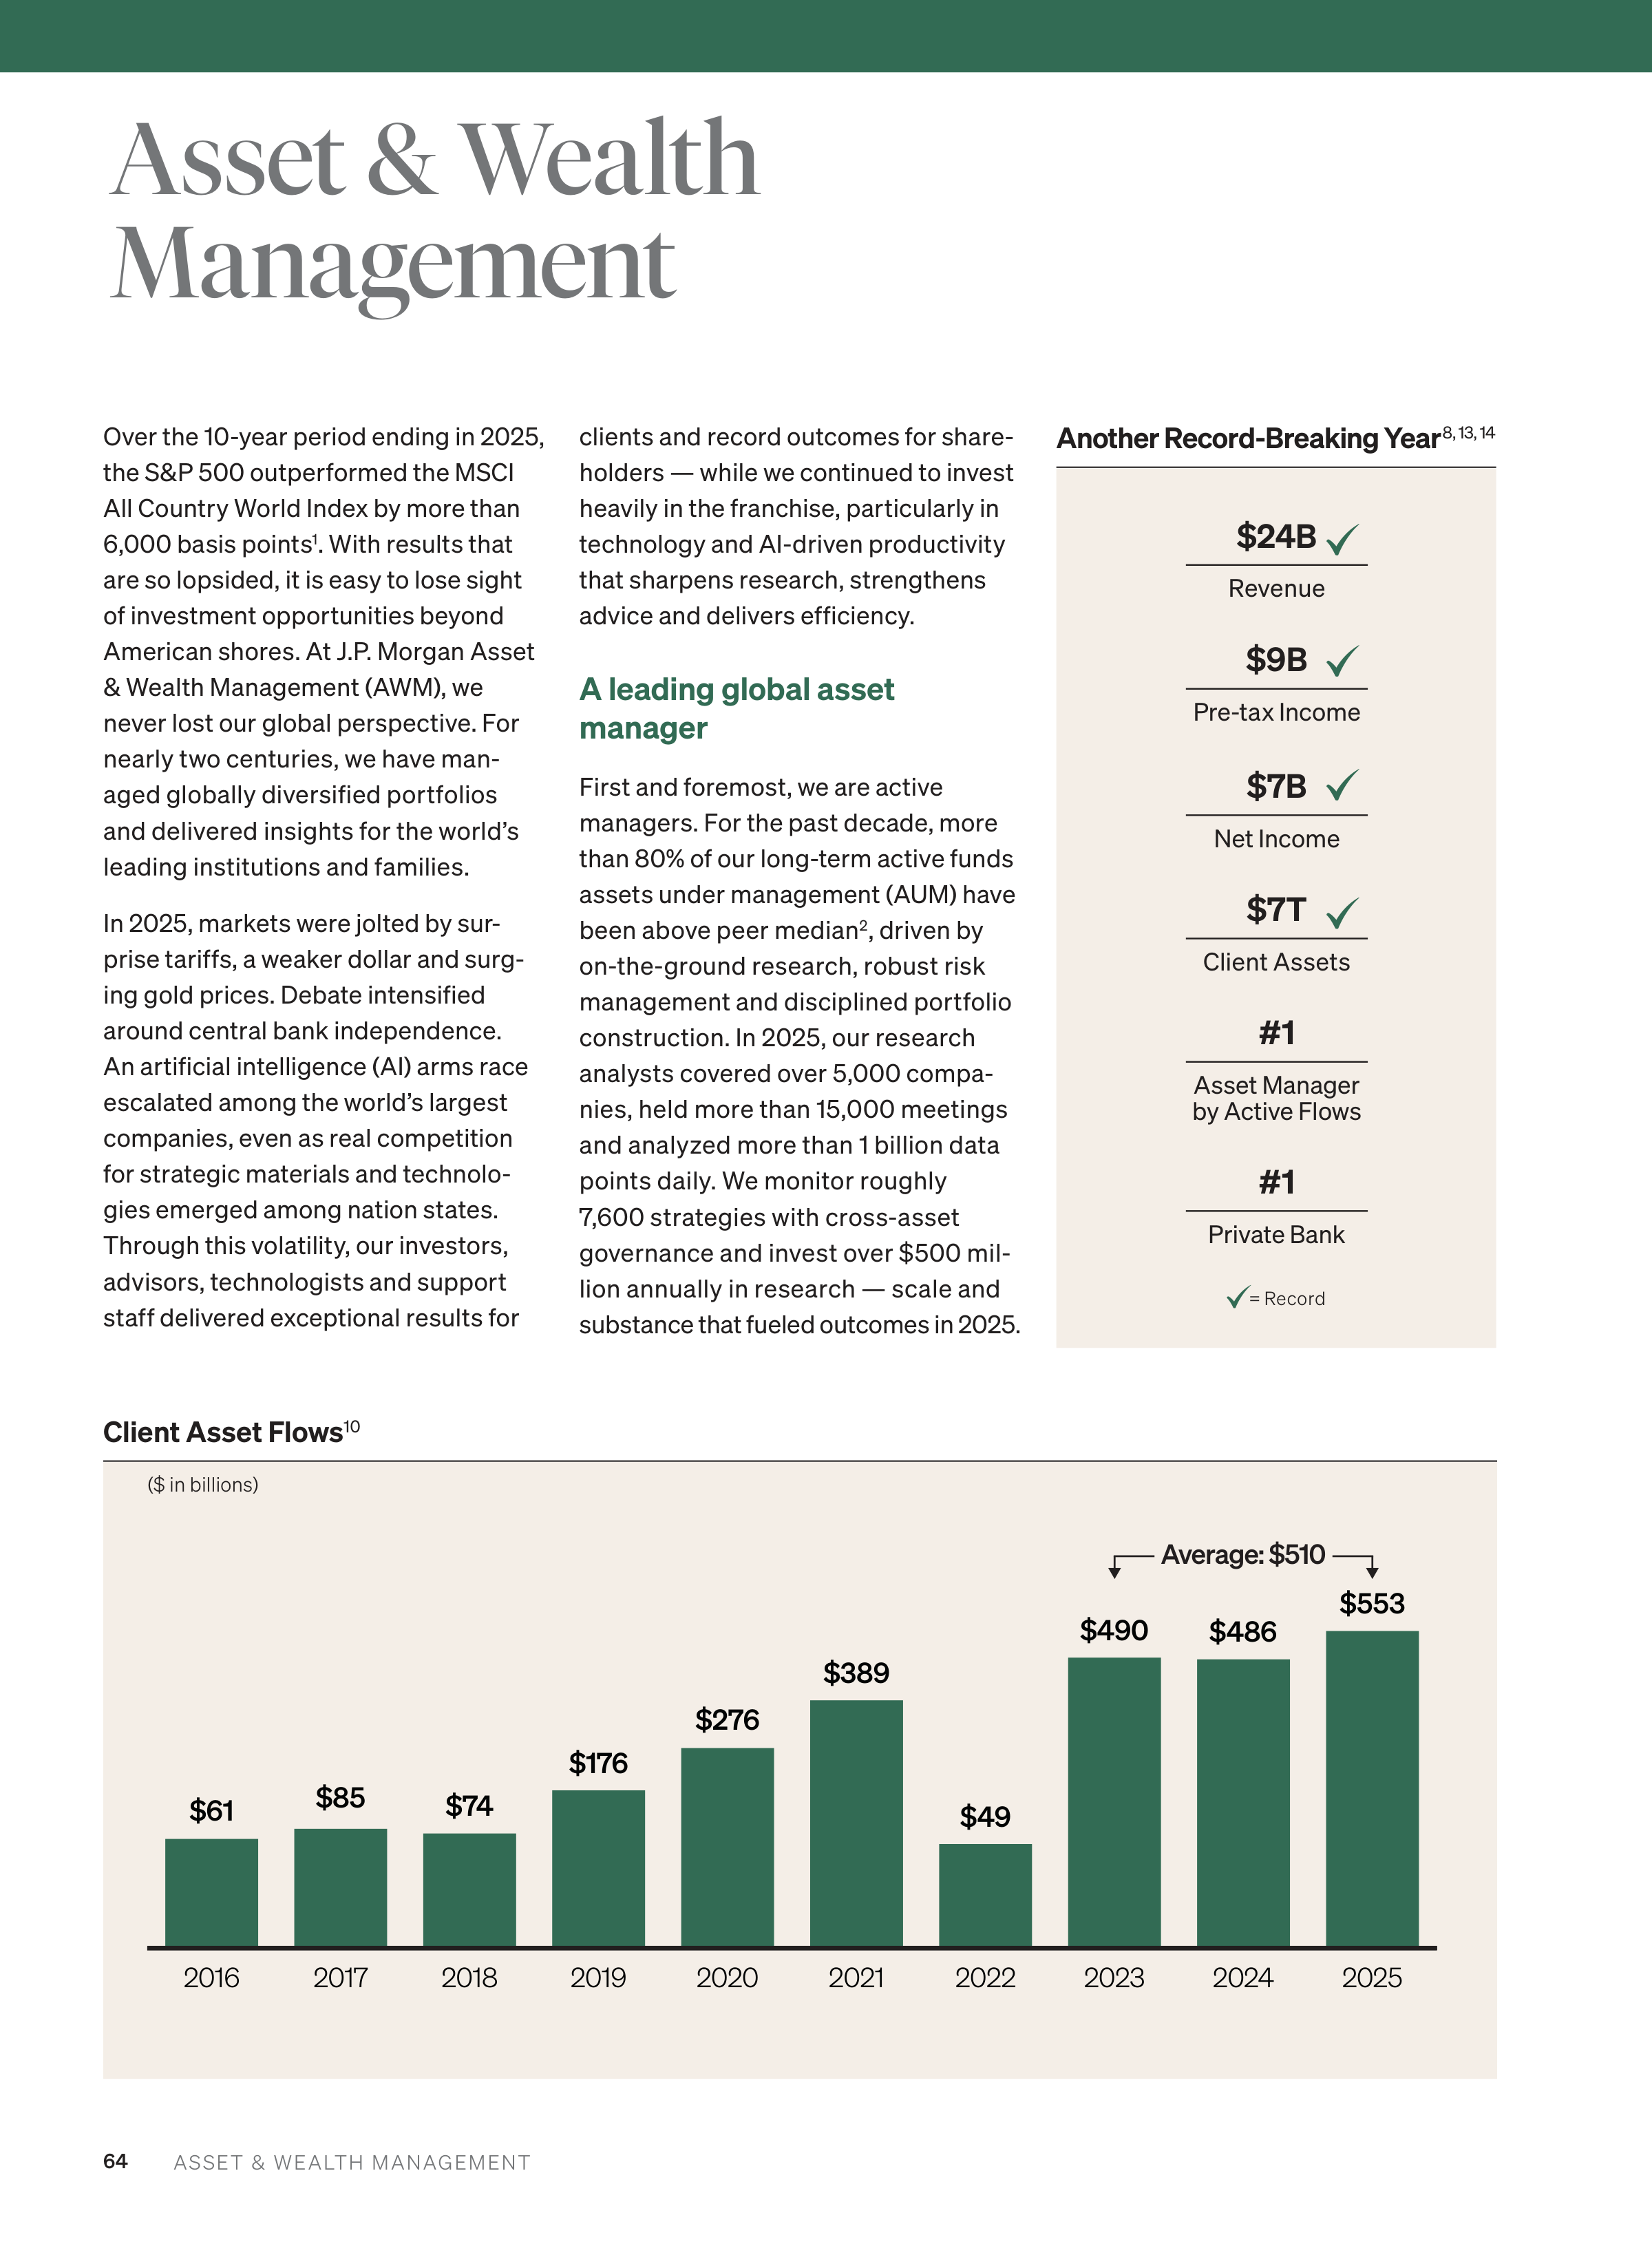
64
ASSET & WEALTH MANAGEMENT
Over the 10-year period ending in 2025,
the S&P 500 outperformed the MSCI
All Country World Index by more than
6,000 basis points
1
. With results that
are so lopsided, it is easy to lose sight
of investment opportunities beyond
American shores. At J.P. Morgan Asset
& Wealth Management (AWM), we
never lost our global perspective. For
nearly two centuries, we have man
aged globally diversified portfolios
and delivered insights for the world’s
leading institutions and families.
In 2025, markets were jolted by sur
prise tariffs, a weaker dollar and surg
ing gold prices. Debate intensified
around central bank independence.
An artificial intelligence (AI) arms race
escalated among the world’s largest
companies, even as real competition
for strategic materials and technolo
gies emerged among nation states.
Through this volatility, our investors,
advisors, technologists and support
staff delivered exceptional results for
clients and record outcomes for share
holders — while we continued to invest
heavily in the franchise, particularly in
technology and AI-driven productivity
that sharpens research, strengthens
advice and delivers efficiency.
A leading global asset
manager
First and foremost, we are active
managers. For the past decade, more
than 80% of our long-term active funds
assets under management (AUM) have
been above peer median
2
, driven by
on-the-ground research, robust risk
management and disciplined portfolio
construction. In 2025, our research
analysts covered over 5,000 compa
nies, held more than 15,000 meetings
and analyzed more than 1 billion data
points daily. We monitor roughly
7,600 strategies with cross-asset
governance and invest over $500 mil
lion annually in research — scale and
substance that fueled outcomes in 2025.
Asset & Wealth
Management
Another Record-Breaking Year
8, 13, 14
$24B
Revenue
$7T
Client Assets
$9B
Pre-tax Income
$7B
Net Income
#1
Asset Manager
by Active Flows
#1
Private Bank
= Record
($ in billions)
Client Asset Flows
10
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
$61
$85
$74
$176
$276
$389
$49
$486
$490
$553
Average: $510
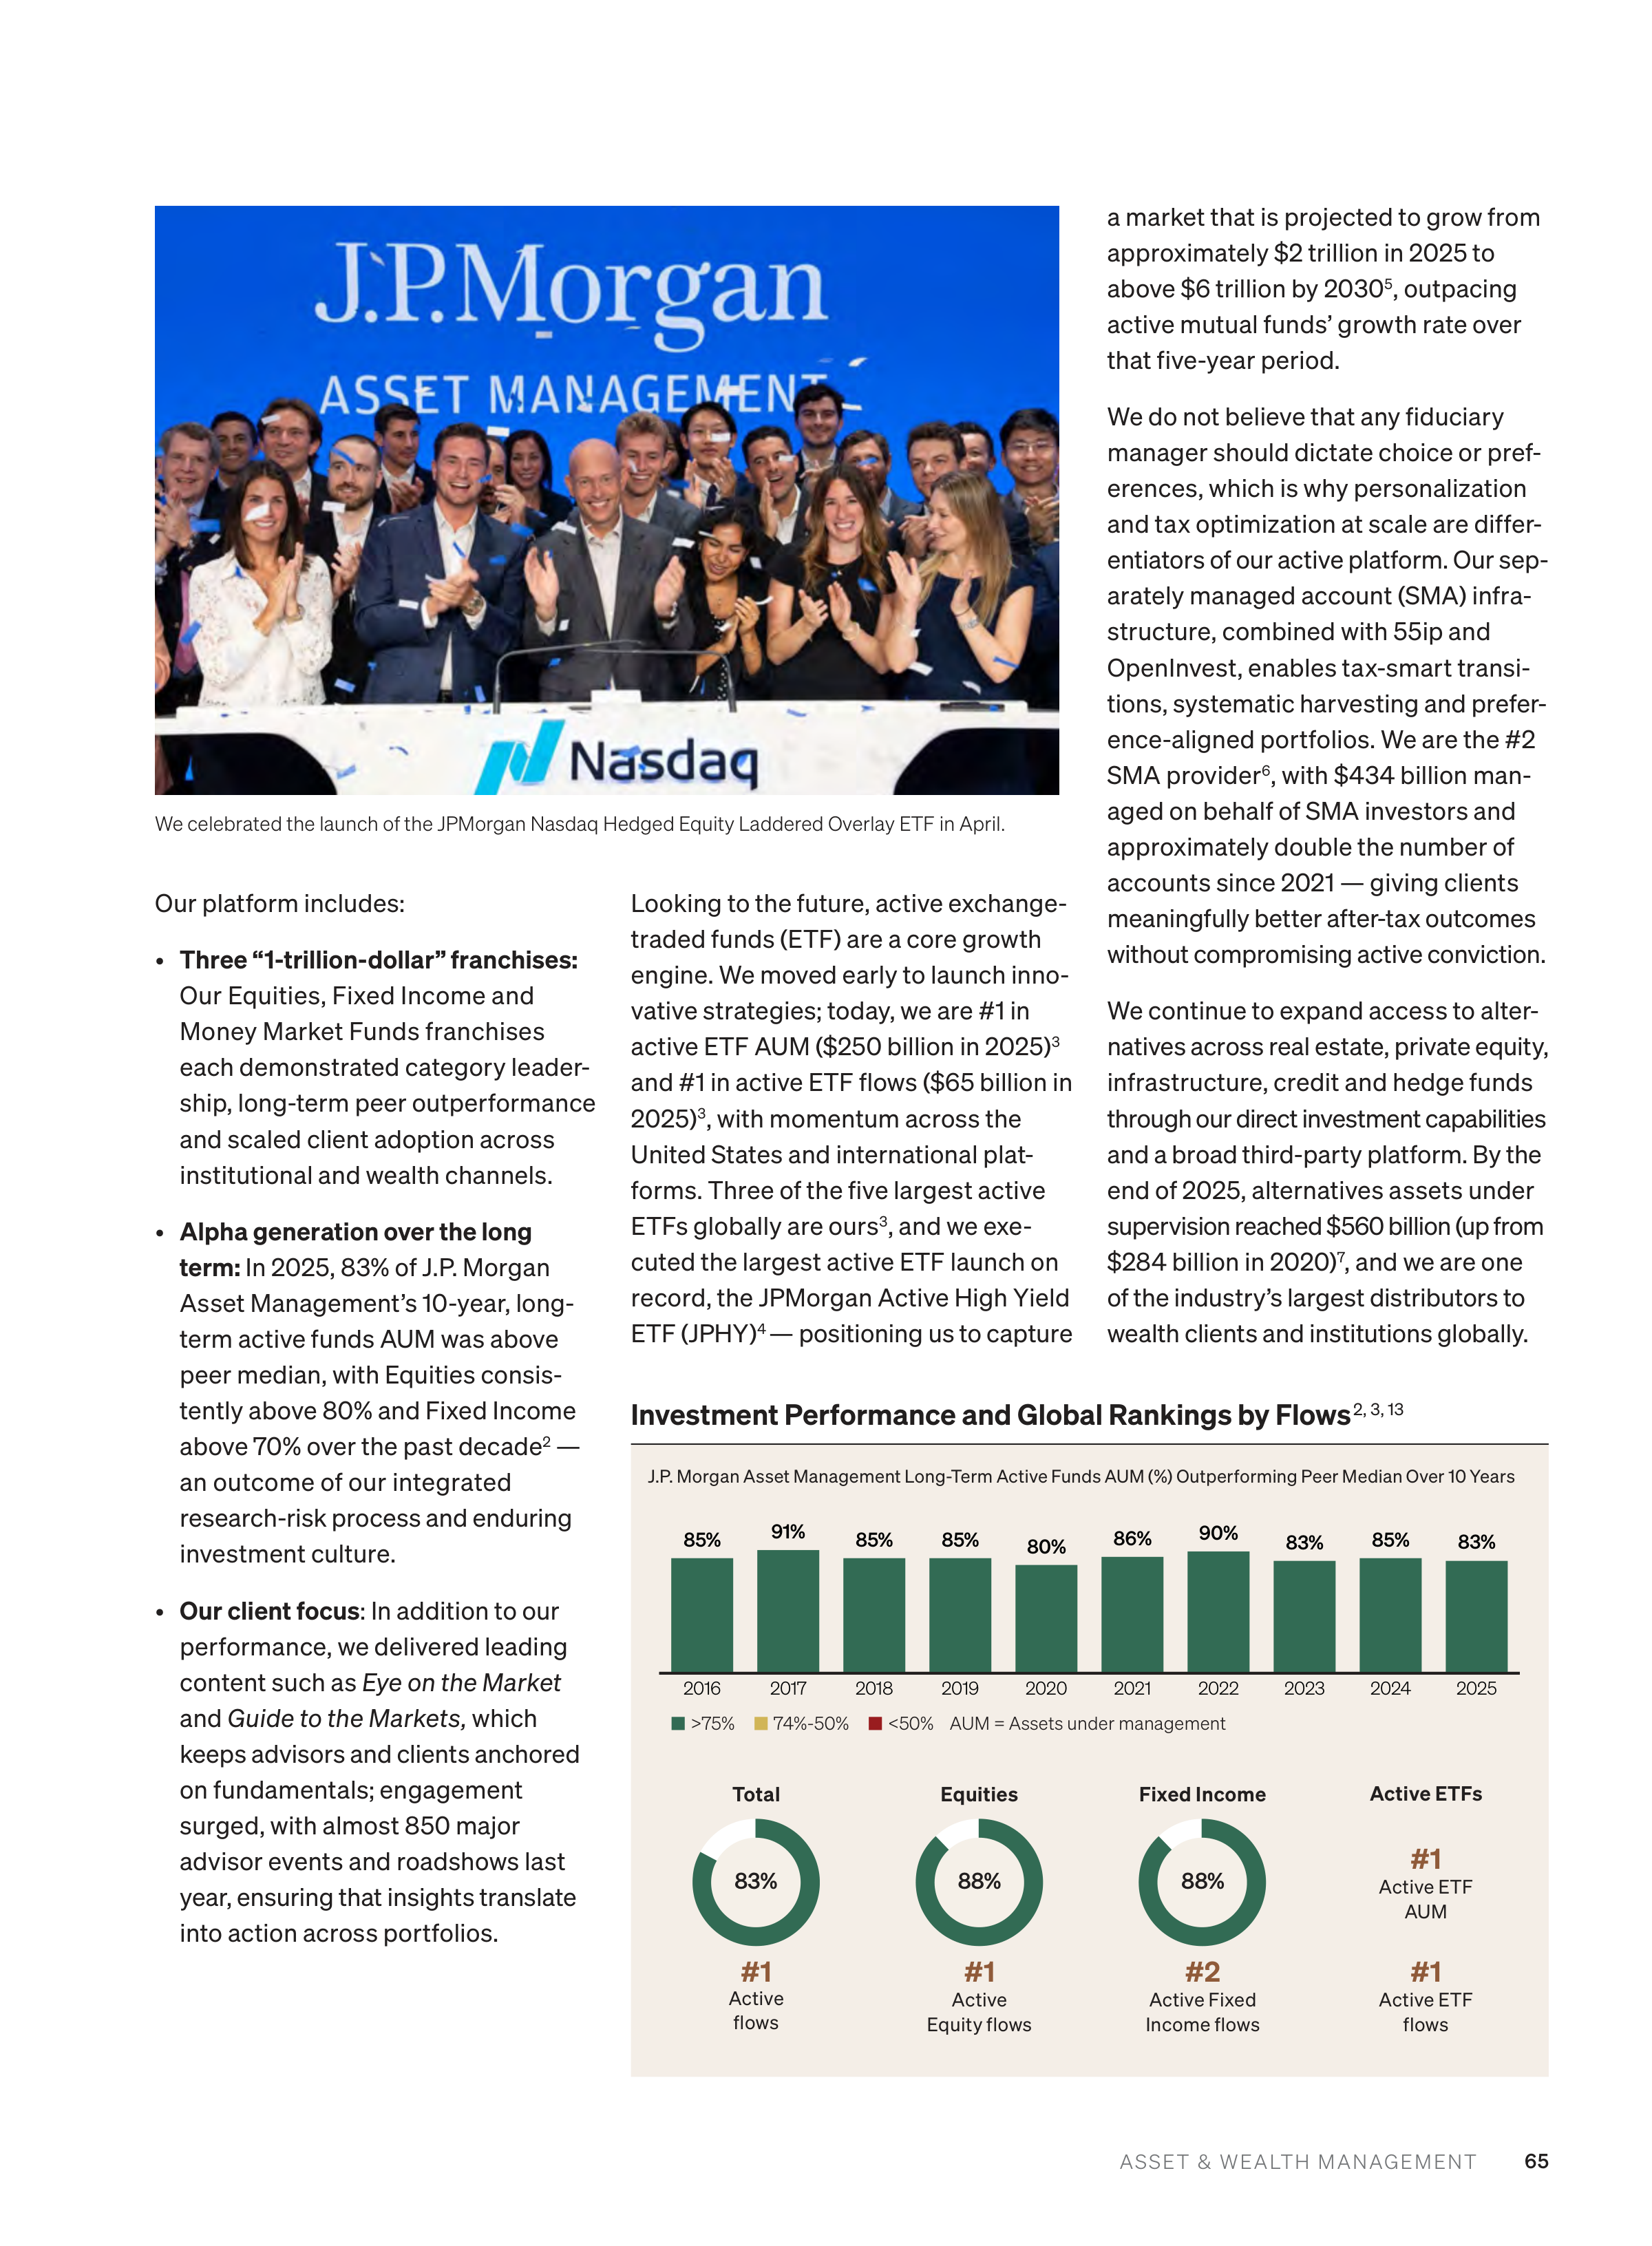
65
ASSET & WEALTH MANAGEMENT
Our platform includes:
•
Three “1-trillion-dollar” franchises:
Our Equities, Fixed Income and
Money Market Funds franchises
each demonstrated category leader
ship, long-term peer outperformance
and scaled client adoption across
institutional and wealth channels.
•
Alpha generation over the long
term:
In 2025, 83% of J.P. Morgan
Asset Management’s 10-year, long-
term active funds AUM was above
peer median, with Equities consis
tently above 80% and Fixed Income
above 70% over the past decade
2
—
an outcome of our integrated
research-risk process and enduring
investment culture.
•
Our client focus
: In addition to our
performance, we delivered leading
content such as
Eye on the Market
and
Guide to the Markets,
which
keeps advisors and clients anchored
on fundamentals; engagement
surged, with almost 850 major
advisor events and roadshows last
year, ensuring that insights translate
into action across portfolios.
Looking to the future, active exchange-
traded funds (ETF) are a core growth
engine. We moved early to launch inno
vative strategies; today, we are #1 in
active ETF AUM ($250 billion in 2025)
3
and #1 in active ETF flows ($65 billion in
2025)
3
, with momentum across the
United States and international plat
forms. Three of the five largest active
ETFs globally are ours
3
, and we exe
cuted the largest active ETF launch on
record, the JPMorgan Active High Yield
ETF (JPHY)
4
— positioning us to capture
a market that is projected to grow from
approximately $2 trillion in 2025 to
above $6 trillion by 2030
5
, outpacing
active mutual funds’ growth rate over
that five-year period.
We do not believe that any fiduciary
manager should dictate choice or pref
erences, which is why personalization
and tax optimization at scale are differ
entiators of our active platform. Our sep
arately managed account (SMA) infra
structure, combined with 55ip and
OpenInvest, enables tax-smart transi
tions, systematic harvesting and prefer
ence-aligned portfolios. We are the #2
SMA provider
6
, with $434 billion man
aged on behalf of SMA investors and
approximately double the number of
accounts since 2021 — giving clients
meaningfully better after-tax outcomes
without compromising active conviction.
We continue to expand access to alter
natives across real estate, private equity,
infrastructure, credit and hedge funds
through our direct investment capabilities
and a broad third-party platform. By the
end of 2025, alternatives assets under
supervision reached $560 billion (up from
$284 billion in 2020)
7
, and we are one
of the industry’s largest distributors to
wealth clients and institutions globally.
We celebrated the launch of the JPMorgan Nasdaq Hedged Equity Laddered Overlay ETF in April.
#1
Active ETF
AUM
#1
Active ETF
flows
#1
Active
flows
Total
83%
#1
Active
Equity flows
Equities
88%
Active ETFs
#2
Active Fixed
Income flows
Fixed Income
88%
Investment Performance and Global Rankings by Flows
2, 3, 13
J.P. Morgan Asset Management Long-Term Active Funds AUM (%) Outperforming Peer Median Over 10 Years
>75%
74%-50%
<50%
AUM = Assets under management
2025
2024
2023
2022
2021
2020
2019
2018
2017
2016
85%
91%
85%
85%
80%
86%
90%
83%
85%
83%
66
ASSET & WEALTH MANAGEMENT
A truly global private bank
We believe we operate the only private
bank in the industry with a uniform
business model globally, enabling con
sistent advice, governance and prod
uct delivery worldwide, as recognized
by
Global Finance
magazine, which
named us the #1 Private Bank in the
World
8
. We are the largest U.S. bank in
the high-net-worth-plus segment inter
nationally — growing at double-digit
rates where we already lead and have
substantial runway in markets where
our current share is below 1%
9
— and
are supported by significant and sus
tained investment in talent and plat
form capabilities.
•
Advisor hiring and productivity
:
Our Global Private Bank (GPB) advi
sor population grew from approxi
mately 2,200 in 2010 to 2,500 in 2020
and to 4,100 in 2025
10
, a 1% compound
annual growth rate from 2010 to 2020
that accelerated to 11% from 2020 to
2025. Our over 60% growth since
2020 outpaced major peers, and rev
enue per average banker increased
15% from 2020 to 2025 — proof that
quality and scale can rise together.
•
Advisor training as a force multiplier
:
We have tripled total training hours
for GPB advisors since 2019 and
nearly quadrupled the number of pro
grams. Hands-on practice exercises
increased by 150% from 2022 to 2025
with AI-driven role plays — all accom
plished without requiring more time
from our top advisor faculty. Even as
quality improved, since 2019, training
expenses as a share of GPB expenses
fell by about one-third, cost per advi
sor trained declined by 27% and
training headcount per 100 advisors
fell by 47% — compelling evidence of
increased operating leverage.
•
Fortress foundation
: Our highly col
lateralized loan book, #1 institutional
money market franchise
11
, and the
trust and confidence of our clients,
which translates to net deposit
migration remaining within the firm,
amplify advice and execution
throughout the cycle.
•
Workplace as a flywheel
: Since
acquiring Global Shares in 2022,
assets under administration and par
ticipants have doubled to $372 bil
lion and 1.8 million, respectively; the
platform is increasingly more geo
graphically diversified and deeply
connected across the firm — convert
ing senior executives into new Private
Bank relationships — and poised to
be a growing flows engine as advisor
hiring normalizes later this decade.
This combination — world-class advi
sors, scaled training, fortress balance
sheet and cross line-of-business con
nectivity — is why over 95% of our top
50 AWM clients also work with our
other lines of business and why our
ecosystem consistently deepens rela
tionships and outcomes for clients.
2025
2022
372
181
+2x
Assets under administration
($ in billions)
2025
2022
2
1
+2x
Participants
(in millions)
Workplace
Global Private Bank (GPB)
U.S. Wealth Management
2025
2020
10
7
+1.5x
Wealth Management advisors
(in thousands)
2025
2019
+3x
Total GPB advisor training hours
2025
2019
-27%
Cost per advisor trained
Advisor Hiring
Our Steering Committee for the J.P. Morgan Advisors Exchange, an annual Global Private Bank
event for our family office clients, is shown above.
67
ASSET & WEALTH MANAGEMENT
Investing in our people,
platforms and AI
We invest through the cycle to
improve performance, strengthen
advice and achieve operational excel
lence — relentlessly driving out ineffi
ciency so every dollar of investment
translates into better outcomes for cli
ents and shareholders. In 2025, we
increased investment across active
management, ETFs, alternatives, our
Workplace platform, GPB advisors,
personalization and AI — while main
taining discipline on overall headcount
growth and efficiency.
There are three AI investment examples
I would like to highlight:
•
SpectrumIQ
: Our proprietary suite of
AI capabilities embedded directly in
Spectrum ties together research,
data and risk. We have automated
nearly 75% of equity trading (saving
clients about $4 billion in trading
costs since inception) and almost
85% of foreign exchange trading, and
now rebalance trades for more than
2,500 clients each month. Data cov
erage has expanded from 8,000 to
90,000 securities and 22 million
documents, and we ingest about
7,000 broker research reports daily.
Smart Monitor, our investor AI assis
tant, learns investor preferences
and pushes prioritized, explainable
insights in real time, reducing hours
of manual research to a click and
compressing time-to-insight by 80%.
•
Connect Coach
: Launched just over a
year ago, Connect Coach now serves
12,000 users across the Private Bank
and U.S. Wealth Management and
includes 25 specialized AI agents.
The platform proactively pushes
1 million personalized AI-driven
insights straight to our front-office
users, unlocking prospecting and
relationship-deepening opportunities
with our clients. Advisors use Con
nect Coach to accelerate meeting
preparation, support portfolio analy
sis and generate call summaries, cre
ating valuable capacity for advisors
to spend more time with clients — a
practical step toward having every
advisor operate like our very best and
every client feel like our only one.
•
Proxy Voting powered by
SpectrumIQ
: Our independent stew
ardship workflow aggregates and
analyzes proprietary data from more
than 3,000 annual company meet
ings across the U.S. equity markets.
Our NextGen employee participants at our Global Innovation Summit presented technological
solutions they created to improve the client and advisor experience.
AI Use Case Examples
Our suite of AI capabilities that ties
together research, data and risk,
covering about 90,000 securities
and 22 million documents
Our stewardship workflow aggre
gates and analyzes proprietary
data from 3,000+ company
meetings in U.S. equity markets
Our tool with 25 specialized AI
agents proactively delivering per
sonalized outreach ideas so advi
sors can focus on clients
80%
Reduction in time from manual
research to insight
1 million
Custom AI-driven insights straight
to our 5,000 GPB users in real time
1st
Major asset manager to fully
disengage from external proxy
advisors in U.S. voting
Proxy Voting powered by
68
ASSET & WEALTH MANAGEMENT
1
Bloomberg.
2
For footnote, refer to page 48 footnote 33 in this
Annual Report.
3
Bloomberg and FactSet as of December 31, 2025.
4
J.P. Morgan Asset Management, Bloomberg and
Morningstar. U.S. Active ETF launches. Does not
include mutual fund conversions (as of May 31, 2025).
5
Morningstar, J.P. Morgan estimates.
6
Cerulli 2025 U.S. Managed Accounts Report.
7
JPM alternative assets includes private equity, private
credit, real assets, hedge funds, liquid alternatives
and other nontraditional assets which may be
presented using net asset value (NAV) of investments.
In quarterly filings, assets are predominantly
presented using NAV and certain of these assets are
reflected in other asset classes or categories
comprising total Client Assets.
8
Global Finance magazine 2025.
9
Company filings, J.P. Morgan estimates.
10
For footnote, refer to page 48 footnote 34 in this
Annual Report.
11
iMoneyNet.
12
Wall Street Journal.
13
Public filings, Morningstar, J.P. Morgan estimates.
14
In the fourth quarter of 2020, the Firm realigned
certain Wealth Management clients from Asset &
Wealth Management to Consumer & Community
Banking. Prior-period amounts have been revised to
conform with the current presentation. Historical
revenue revised as a result of the adoption of the new
accounting guidance for revenue recognition,
effective January 1, 2018.
15
Company filings and websites, J.P. Morgan estimates.
Transition to exclusive use for U.S.
proxy votes began in the first quar
ter of 2026 with full implementation
as of April 1, 2026, making us the
first major asset manager to fully
disengage from external proxy advi
sors in U.S. voting
12
. Integrating
investor insights with voting deci
sions at the scale of more than $7
trillion in client assets reinforces
independent stewardship aligned
with long-term value creation.
We have made significant investments
in our tools and resources, many of
which have been developed and
enhanced by our employees. Their
creativity and ingenuity have driven
innovative solutions that directly ben
efit our clients. We have also heavily
invested in our teams that provide
seamless, around-the-clock support
to clients, ensuring exceptional ser
vice and responsiveness at all times.
A leading industry position
In 2025, we were recognized as the
#1 Asset Manager by active flows
13
and the #1 Private Bank in the World
8
,
reflecting the strength of our invest
ment engine and advice platform.
Our clients continue to vote with their
flows, driving record total client asset
flows of $553 billion — our 22nd
consecutive year of positive net new
inflows — record client assets of
$7 trillion and record revenue for the
ninth consecutive year at $24 billion
14
.
Total client asset flows exceeded
$1 trillion over the last two years; that
amount by itself would rank among
the top 30 asset managers
15
. Culmi
nating a year of strong execution, we
delivered a
40% return on equity
in
the 2025 fiscal year (up from 34% in
2024), reflecting expense and capital
discipline and highly selective
headcount growth, with the latter
primarily consisting of GPB advisors.
These extraordinary results belong to
our more than 29,000 AWM profes
sionals across 48 countries who show
up every day to earn our clients’ trust. I
am especially grateful to my Operating
Committee partners in AWM, whose
leadership across our investment, advi
sory, technology and operations teams
makes this performance possible — and
whose unwavering ambition for what
comes next continues to raise the bar.
Thank you for your trust in us. Our North
Star has never changed: to be the best
in the industry for our clients, not the
biggest — and our fiduciary commit
ment to deliver investment perfor
mance remains the way we prove it
every day. We will keep investing in our
people, research and platforms; extend
leadership in active management and
active ETFs; expand our leading global
private bank; broaden access to alter
natives and personalization; and embed
AI across the franchise to elevate advice
and outcomes — leveraging the unpar
alleled strength of JPMorganChase for
our clients and shareholders.
Our clients continue to vote with
their flows, driving record total client
asset flows of $553 billion — our
22nd consecutive year of positive net
new inflows — record client assets of
$7 trillion and record revenue for the
ninth consecutive year at $24 billion.
Total client asset flows exceeded
$1 trillion over the last two years; that
amount by itself would rank among
the top 30 asset managers.”
“
Mary Callahan Erdoes
CEO, Asset & Wealth Management
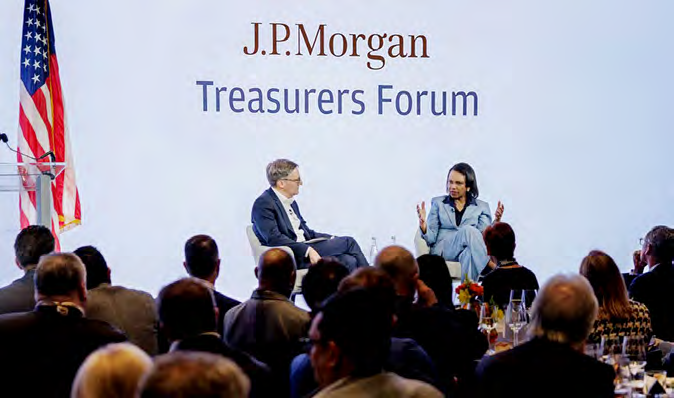
69
CORPORATE RESPONSIBILITY
For more than 225 years, JPMorgan
Chase has been an anchor and an accel
erator for the global economy, financing
the historic and the everyday — from the
Brooklyn Bridge and Allied efforts in
World War I to the house down the block
and the small business on Main Street.
We take on great economic challenges
while showing up locally for customers,
clients and communities. That vantage
point helps give us a clear view of the
problems facing economies big and
small, as well as the ability to act in ways
that few institutions can.
But today, the economy isn’t working
for everyone. Buying a home, starting a
business, finding a good job and saving
money have all become harder. These
challenges are playing out against the
backdrop of an increasingly complex
and dynamic global environment that
could generate additional headwinds.
As a firm, we believe we have a respon
sibility to use our scale and expertise to
make a real difference for families,
workers and small businesses — turn
ing insight into practical solutions for
the people and places we serve.
Geopolitical insights that move
decisions
The world is changing quickly. From
conflicts in the Middle East to the rise of
artificial intelligence, the continuing dis
ruption can make some days feel like
the ground is shifting beneath our feet.
JPMorganChase serves corporations
and clients in more than 100 countries
so we feel these movements every day.
What sets our firm apart is our ability to
connect global insights to local execu
tion. This helps clients spot challenges
and opportunities — from supply chain
shifts to global trade realignments to
regulatory changes — and move
quickly whether they’re in Houston,
London or Tokyo. Treated as a tool —
not background noise — geopolitics
can inform decisions for our clients
and communities.
To help do this, last year we launched
the JPMorganChase Center for Geopol
itics. The Center works alongside
experts across our lines of business to
combine regional knowledge with intel
ligence, policy and market insights —
assessing how world events affect
markets, operations and industries.
Through the Center’s reports, briefings
and customized offerings, we deepen
our clients’ ability to form practical,
risk‑aware strategies that create
long‑term value.
Building on the Center’s success, the
firm launched Special Advisory Services
to broaden our clients’ access to exper
tise in areas like supply chains and
cybersecurity. We saw an expanded
opportunity to help clients prepare for
the business environment of the future
and put our resources behind it, calling
it the Security and Resiliency Initiative.
The Security and Resiliency
Initiative: Supporting industries
critical to national and economic
security
National security and economic secu
rity are intertwined. Today, too many
critical inputs, from rare earth minerals
and pharmaceutical ingredients to
advanced materials, are regularly
unavailable within a nation’s borders.
When supply chains are concentrated
and there are talent shortages, every
one is at risk, including families, busi
nesses and governments.
That risk is amplified when essential
infrastructure, such as the power grid,
faces mounting pressure from rising
demand. By modernizing transmission
and distribution systems, integrating
innovative technologies and streamlin
ing permitting processes, it’s possible
to alleviate bottlenecks, strengthen
Corporate Responsibility
Derek Chollet, Head of the JPMorganChase Center for Geopolitics, talked with Secretary Condoleezza
Rice about how global conflicts affect business.
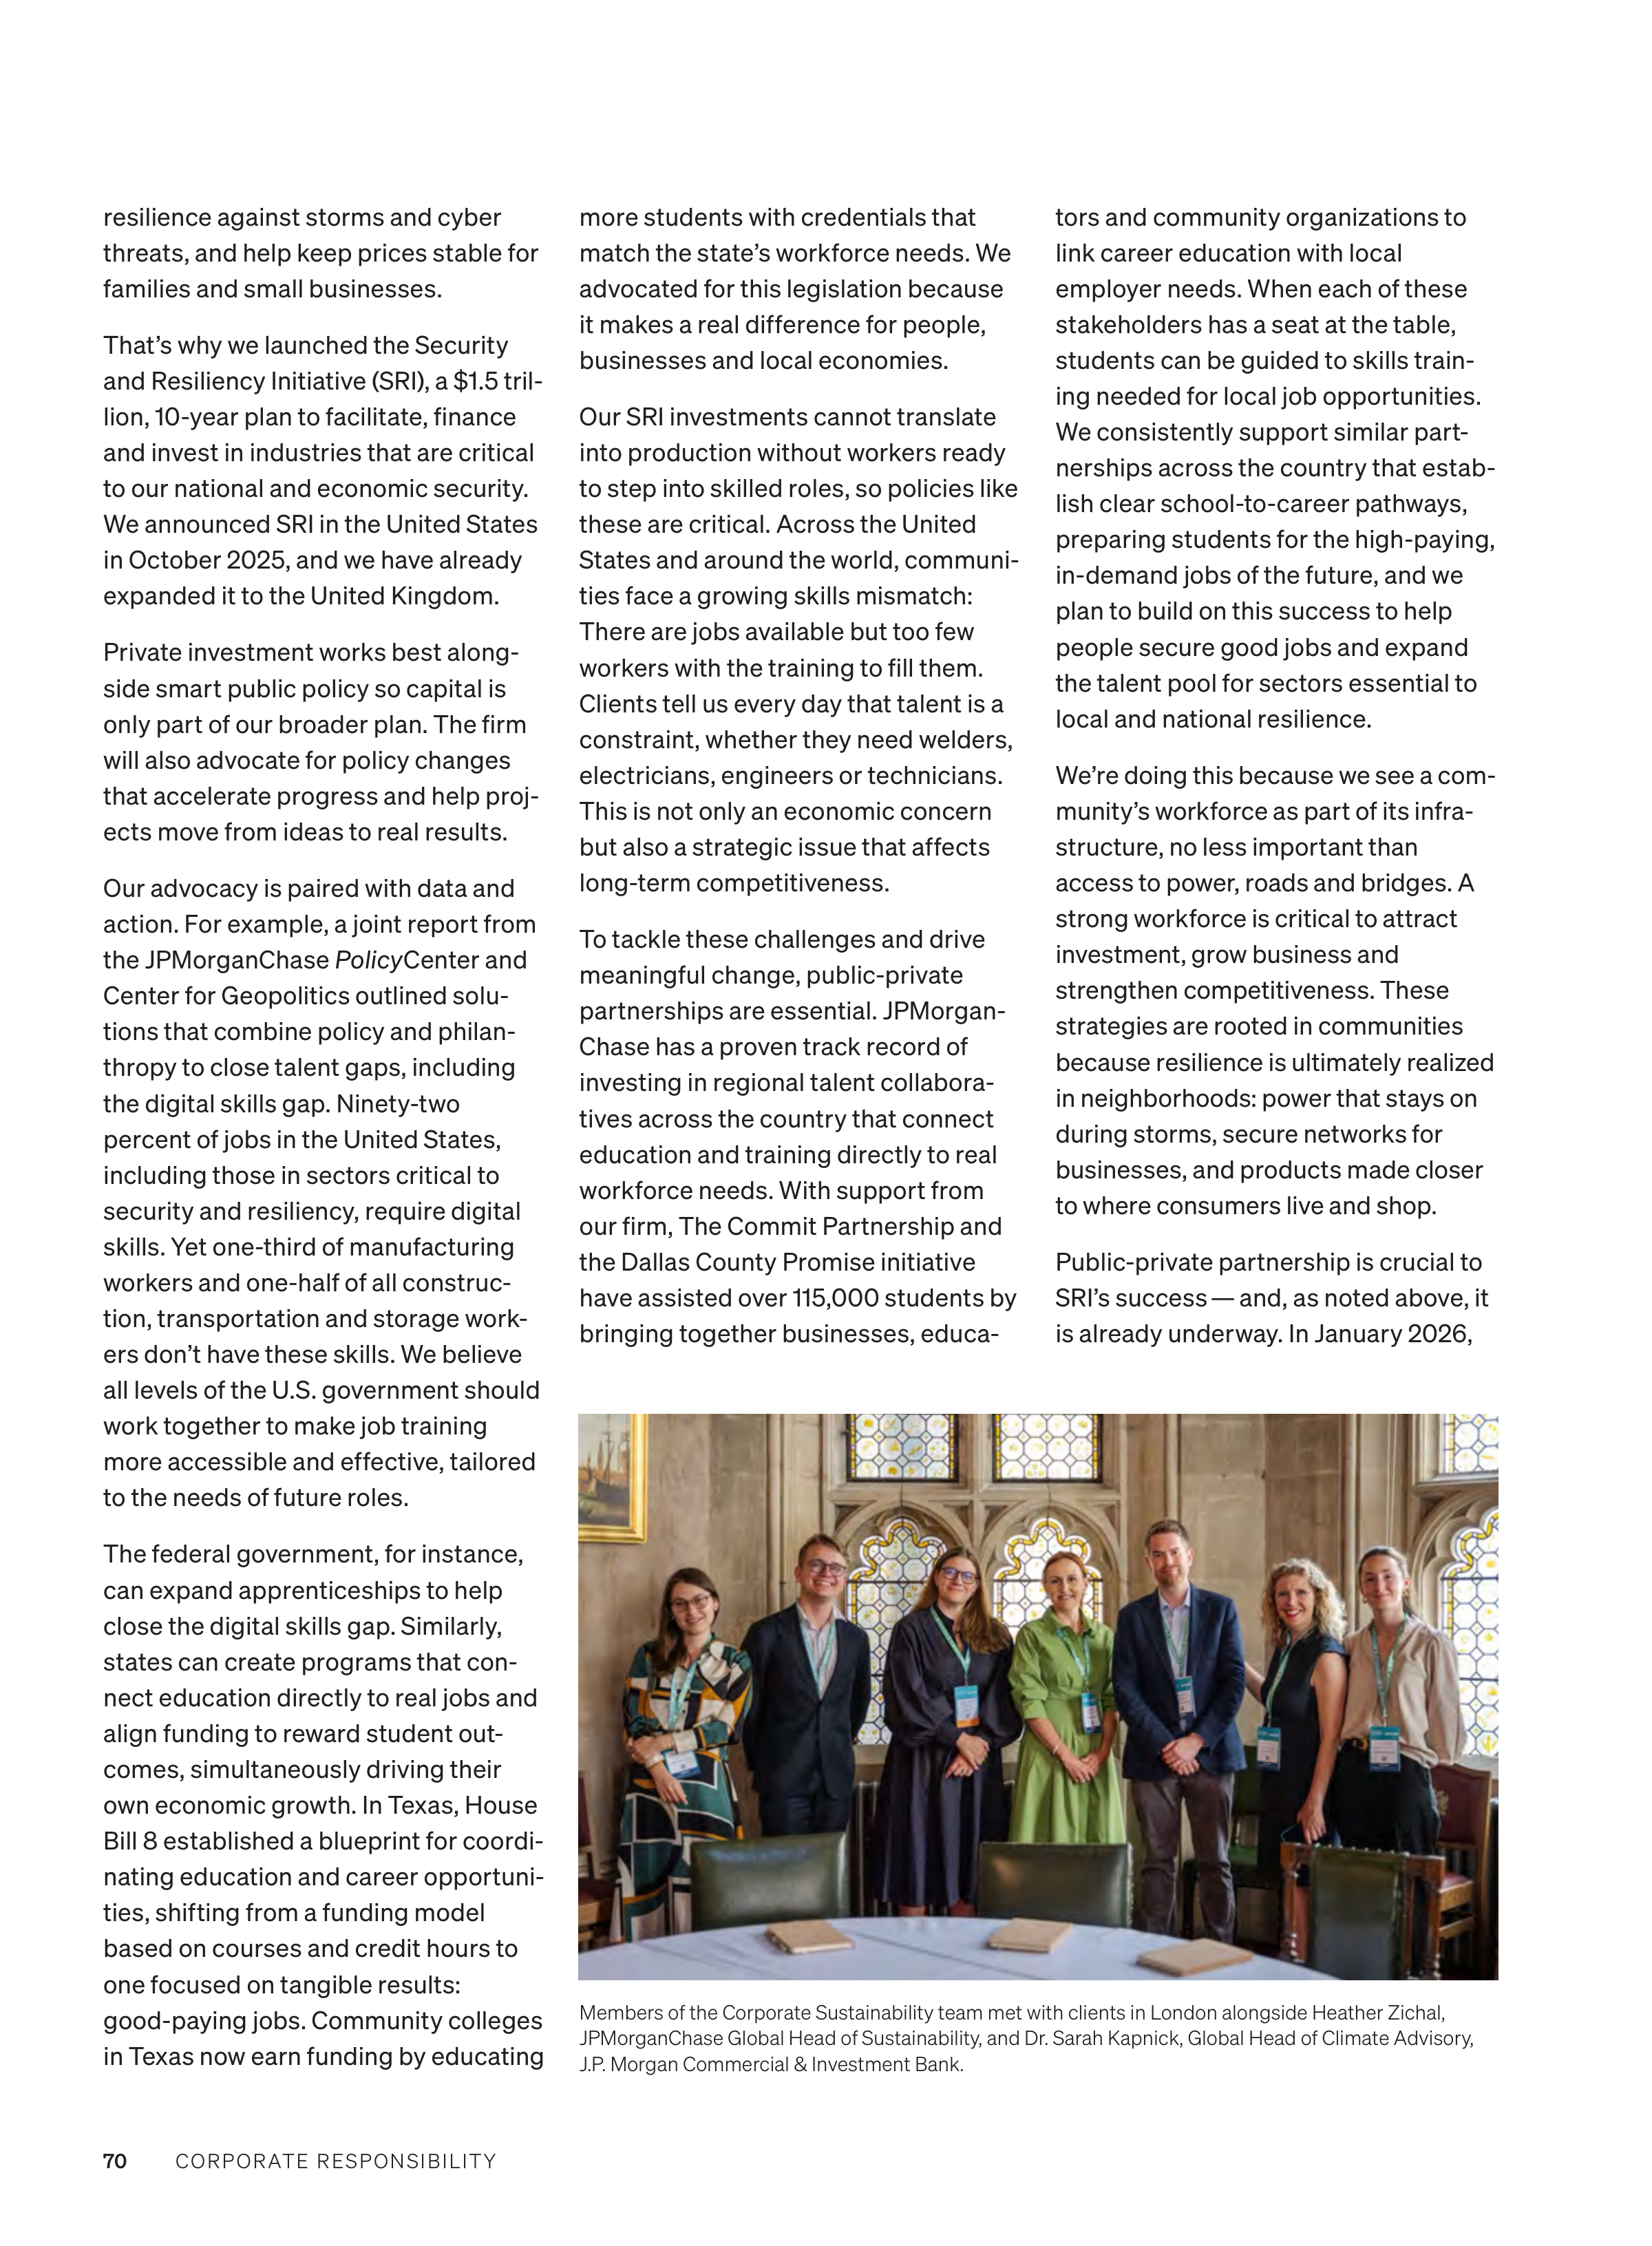
70
CORPORATE RESPONSIBILITY
resilience against storms and cyber
threats, and help keep prices stable for
families and small businesses.
That’s why we launched the Security
and Resiliency Initiative (SRI), a $1.5 tril
lion, 10‑year plan to facilitate, finance
and invest in industries that are critical
to our national and economic security.
We announced SRI in the United States
in October 2025, and we have already
expanded it to the United Kingdom.
Private investment works best along
side smart public policy so capital is
only part of our broader plan. The firm
will also advocate for policy changes
that accelerate progress and help proj
ects move from ideas to real results.
Our advocacy is paired with data and
action. For example, a joint report from
the JPMorganChase
Policy
Center and
Center for Geopolitics outlined solu
tions that combine policy and philan
thropy to close talent gaps, including
the digital skills gap. Ninety‑two
percent of jobs in the United States,
including those in sectors critical to
security and resiliency, require digital
skills. Yet one‑third of manufacturing
workers and one-half of all construc
tion, transportation and storage work
ers don’t have these skills. We believe
all levels of the U.S. government should
work together to make job training
more accessible and effective, tailored
to the needs of future roles.
The federal government, for instance,
can expand apprenticeships to help
close the digital skills gap. Similarly,
states can create programs that con
nect education directly to real jobs and
align funding to reward student out
comes, simultaneously driving their
own economic growth. In Texas, House
Bill 8 established a blueprint for coordi
nating education and career opportuni
ties, shifting from a funding model
based on courses and credit hours to
one focused on tangible results:
good-paying jobs. Community colleges
in Texas now earn funding by educating
more students with credentials that
match the state’s workforce needs. We
advocated for this legislation because
it makes a real difference for people,
businesses and local economies.
Our SRI investments cannot translate
into production without workers ready
to step into skilled roles, so policies like
these are critical. Across the United
States and around the world, communi
ties face a growing skills mismatch:
There are jobs available but too few
workers with the training to fill them.
Clients tell us every day that talent is a
constraint, whether they need welders,
electricians, engineers or technicians.
This is not only an economic concern
but also a strategic issue that affects
long‑term competitiveness.
To tackle these challenges and drive
meaningful change, public-private
partnerships are essential. JPMorgan
Chase has a proven track record of
investing in regional talent collabora
tives across the country that connect
education and training directly to real
workforce needs. With support from
our firm, The Commit Partnership and
the Dallas County Promise initiative
have assisted over 115,000 students by
bringing together businesses, educa
tors and community organizations to
link career education with local
employer needs. When each of these
stakeholders has a seat at the table,
students can be guided to skills train
ing needed for local job opportunities.
We consistently support similar part
nerships across the country that estab
lish clear school-to-career pathways,
preparing students for the high-paying,
in-demand jobs of the future, and we
plan to build on this success to help
people secure good jobs and expand
the talent pool for sectors essential to
local and national resilience.
We’re doing this because we see a com
munity’s workforce as part of its infra
structure, no less important than
access to power, roads and bridges. A
strong workforce is critical to attract
investment, grow business and
strengthen competitiveness. These
strategies are rooted in communities
because resilience is ultimately realized
in neighborhoods: power that stays on
during storms, secure networks for
businesses, and products made closer
to where consumers live and shop.
Public‑private partnership is crucial to
SRI’s success — and, as noted above, it
is already underway. In January 2026,
Members of the Corporate Sustainability team met with clients in London alongside Heather Zichal,
JPMorganChase Global Head of Sustainability, and Dr. Sarah Kapnick, Global Head of Climate Advisory,
J.P. Morgan Commercial & Investment Bank.
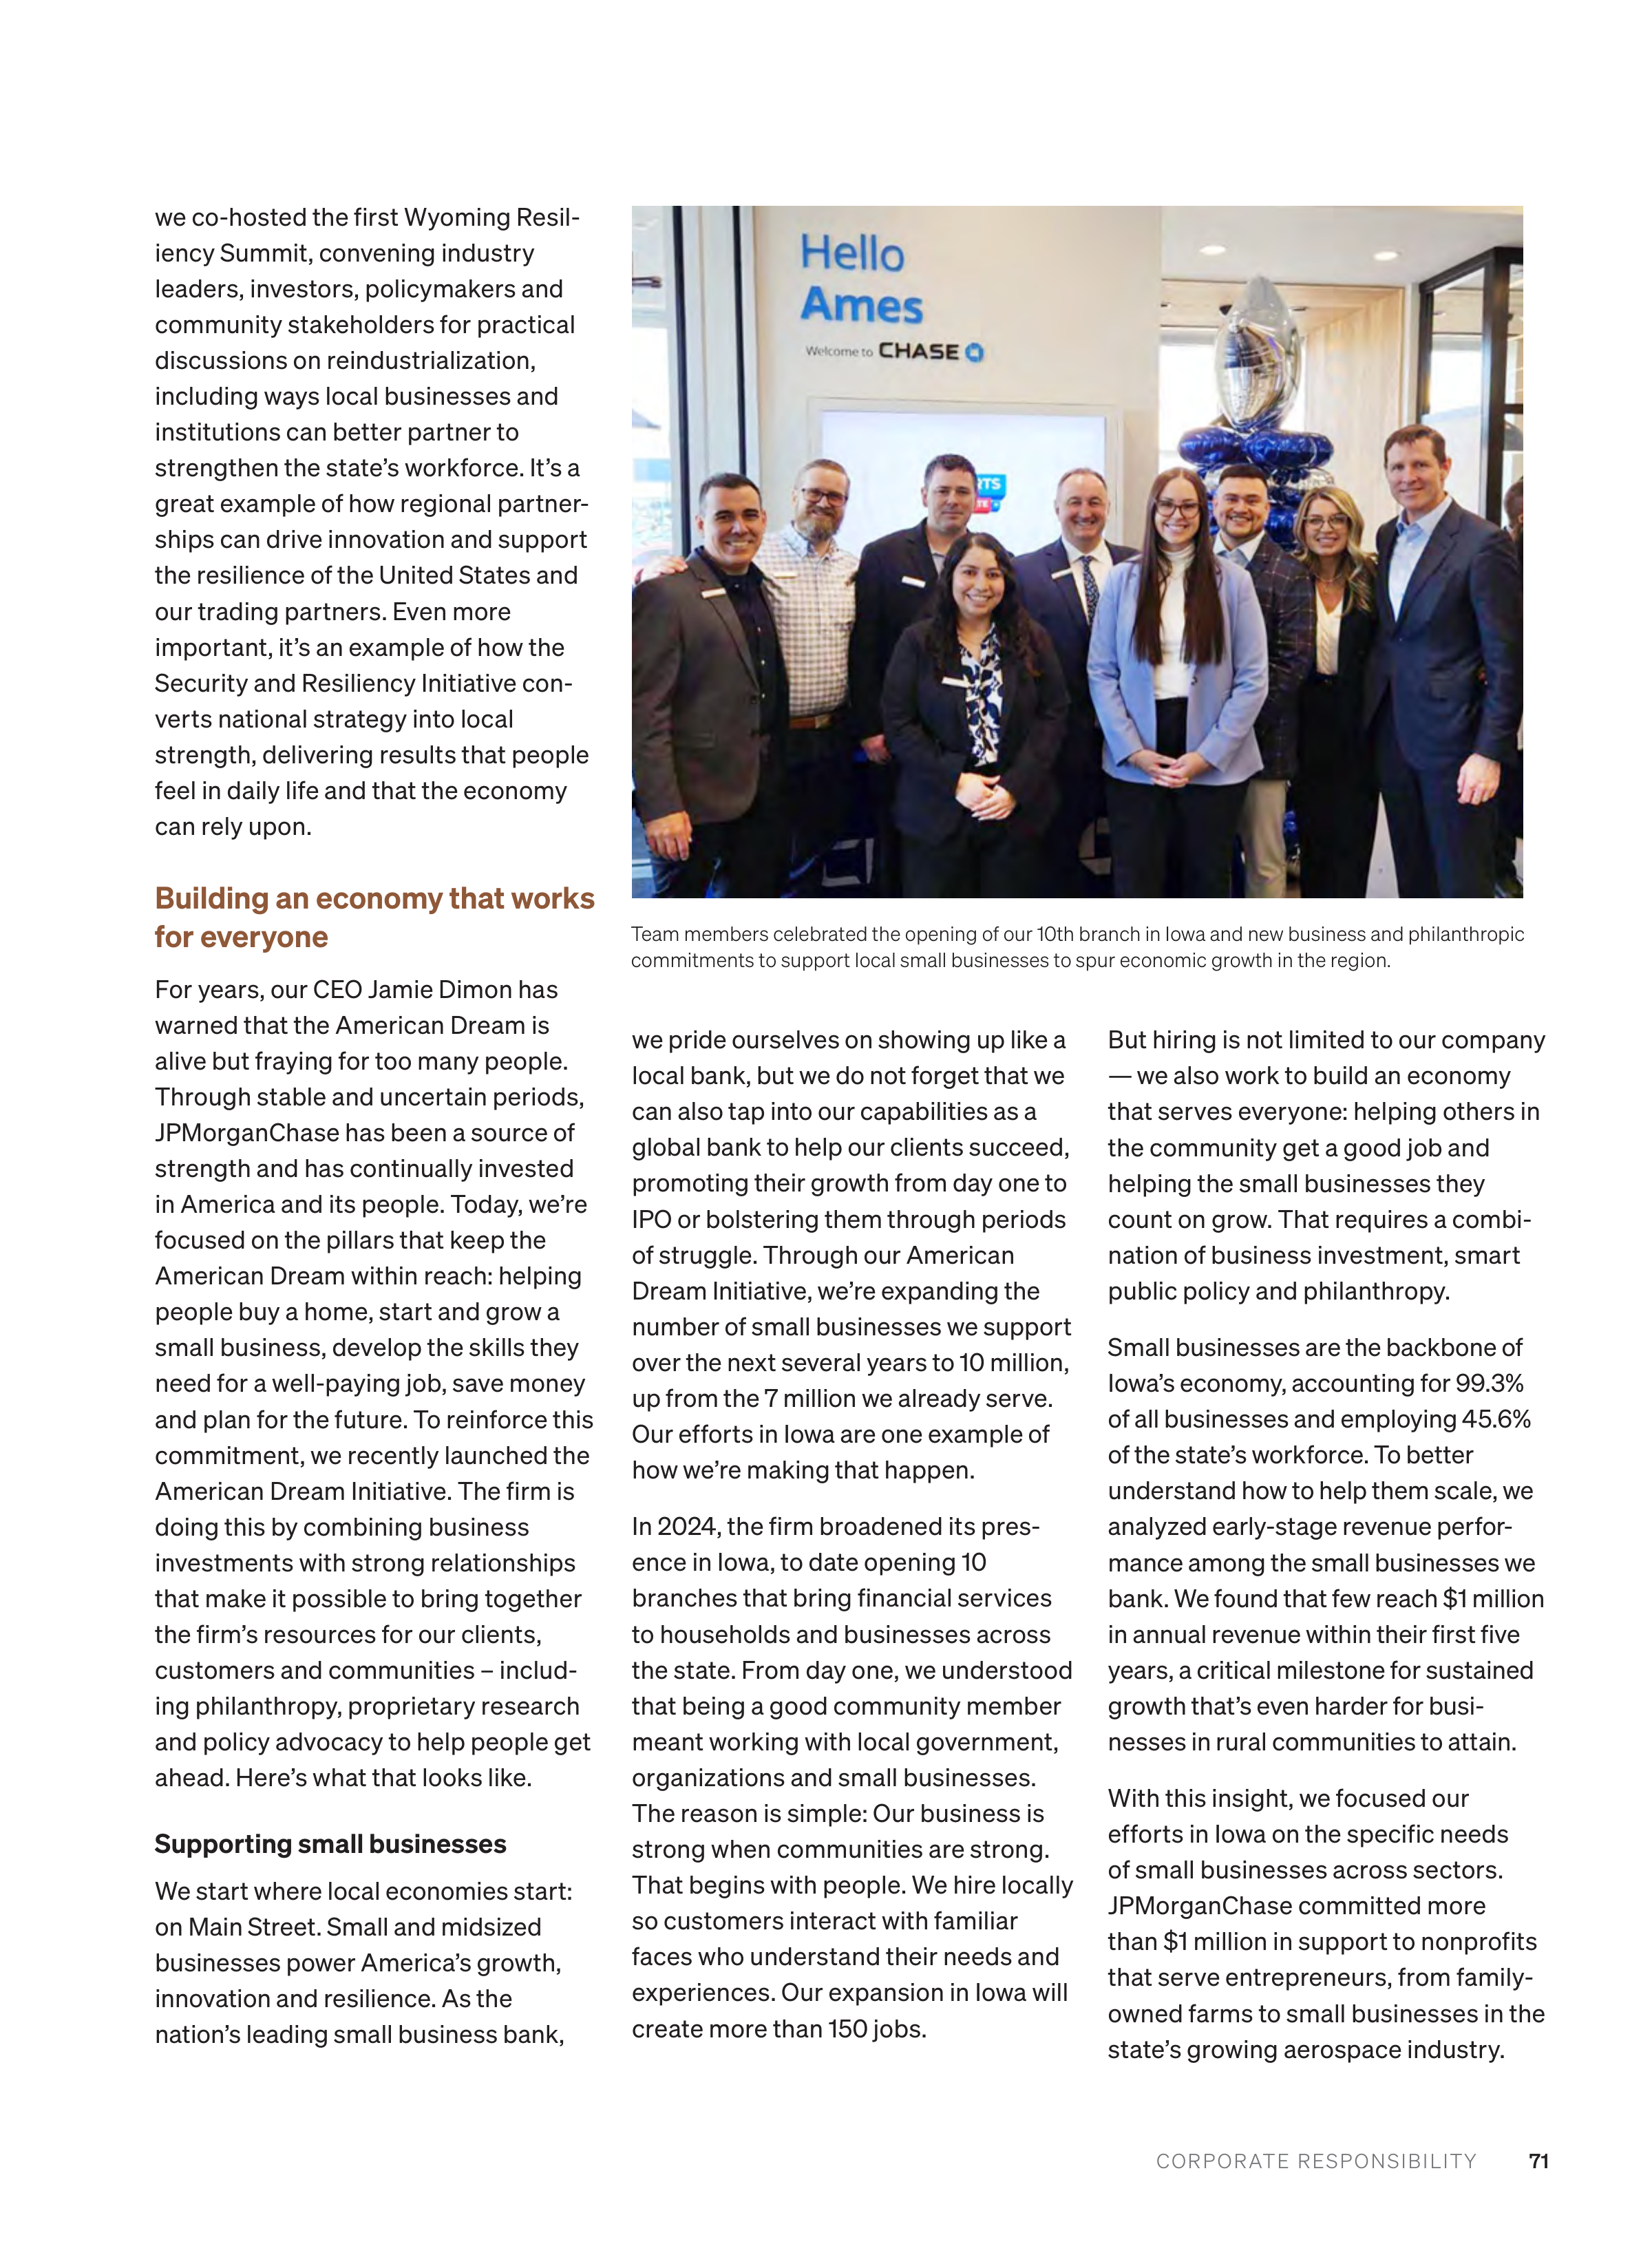
71
CORPORATE RESPONSIBILITY
we co-hosted the first Wyoming Resil
iency Summit, convening industry
leaders, investors, policymakers and
community stakeholders for practical
discussions on reindustrialization,
including ways local businesses and
institutions can better partner to
strengthen the state’s workforce. It’s a
great example of how regional partner
ships can drive innovation and support
the resilience of the United States and
our trading partners. Even more
important, it’s an example of how the
Security and Resiliency Initiative con
verts national strategy into local
strength, delivering results that people
feel in daily life and that the economy
can rely upon.
Building an economy that works
for everyone
For years, our CEO Jamie Dimon has
warned that the American Dream is
alive but fraying for too many people.
Through stable and uncertain periods,
JPMorganChase has been a source of
strength and has continually invested
in America and its people. Today, we’re
focused on the pillars that keep the
American Dream within reach: helping
people buy a home, start and grow a
small business, develop the skills they
need for a well-paying job, save money
and plan for the future. To reinforce this
commitment, we recently launched the
American Dream Initiative. The firm is
doing this by combining business
investments with strong relationships
that make it possible to bring together
the firm’s resources for our clients,
customers and communities – includ
ing philanthropy, proprietary research
and policy advocacy to help people get
ahead. Here’s what that looks like.
Supporting small businesses
We start where local economies start:
on Main Street. Small and midsized
businesses power America’s growth,
innovation and resilience. As the
nation’s leading small business bank,
we pride ourselves on showing up like a
local bank, but we do not forget that we
can also tap into our capabilities as a
global bank to help our clients succeed,
promoting their growth from day one to
IPO or bolstering them through periods
of struggle. Through our American
Dream Initiative, we’re expanding the
number of small businesses we support
over the next several years to 10 million,
up from the 7 million we already serve.
Our efforts in Iowa are one example of
how we’re making that happen.
In 2024, the firm broadened its pres
ence in Iowa, to date opening 10
branches that bring financial services
to households and businesses across
the state. From day one, we understood
that being a good community member
meant working with local government,
organizations and small businesses.
The reason is simple: Our business is
strong when communities are strong.
That begins with people. We hire locally
so customers interact with familiar
faces who understand their needs and
experiences. Our expansion in Iowa will
create more than 150 jobs.
But hiring is not limited to our company
— we also work to build an economy
that serves everyone: helping others in
the community get a good job and
helping the small businesses they
count on grow. That requires a combi
nation of business investment, smart
public policy and philanthropy.
Small businesses are the backbone of
Iowa’s economy, accounting for 99.3%
of all businesses and employing 45.6%
of the state’s workforce. To better
understand how to help them scale, we
analyzed early‑stage revenue perfor
mance among the small businesses we
bank. We found that few reach $1 million
in annual revenue within their first five
years, a critical milestone for sustained
growth that’s even harder for busi
nesses in rural communities to attain.
With this insight, we focused our
efforts in Iowa on the specific needs
of small businesses across sectors.
JPMorganChase committed more
than $1 million in support to nonprofits
that serve entrepreneurs, from family‑
owned farms to small businesses in the
state’s growing aerospace industry.
Team members celebrated the opening of our 10th branch in Iowa and new business and philanthropic
commitments to support local small businesses to spur economic growth in the region.

72
CORPORATE RESPONSIBILITY
This investment will help strengthen
Iowa’s economy and builds on our
strong track record of lending to more
than 20,000 Iowa businesses. Policy
matters, too. We will continue to advo
cate for a stronger small business eco
system at the federal, state and local
levels by removing unnecessary barri
ers and expanding access to capital.
Increasing access to stable,
affordable housing
Homeownership is a core pillar of the
American Dream. As a major lender and
investor in affordable housing across
the United States, we have seen first
hand that families are facing historic
housing challenges. The list is long:
Construction costs are high, regula
tions hinder the pace of building and
gaps in funding inhibit innovation.
These issues limit the number of avail
able homes and raise prices. The ripple
effects are real: People live farther from
work, local businesses are under pres
sure and households are spending less.
Federal, state and local policymakers
see the opportunity to act and are
working to address these problems.
We’re working alongside them.
Last year in Atlanta, we convened poli
cymakers, community advocates and
business leaders to find practical ways
to improve housing affordability and to
share lessons that may be helpful to
other cities. It’s one way we mobilize the
full breadth of the firm to help people
and their communities.
To ground the discussion, we analyzed
data on housing challenges across the
Atlanta metro area and looked at strat
egies that have worked in locations
with similar conditions, including Texas
and Montana. This underscores what
sets JPMorganChase apart: our ability
to leverage our presence around the
world to spot trends, learn what works,
make policy recommendations and
scale effective approaches from other
communities.
We focused on solutions that increase
supply and speed delivery: building
and preserving affordable homes,
updating zoning and permitting where
appropriate, and using new financing
tools to close funding gaps. To support
the construction of affordable housing,
we dedicated $40 million in new phil
anthropic funding to help address
the shortage. This builds on the more
than $5 billion in debt and equity that
JPMorganChase provided in 2025
across the country to help create and
preserve affordable housing.
Our housing work demonstrates our
approach: Use data to identify gaps,
partner locally to act and carry what
works to other communities. It is the
same advantage we bring to tables of
all kinds.
The JPMorganChase advantage
From small towns to big cities,
JPMorganChase helps power the global
economy. Our scale, networks and
resources let us take on big problems.
We are uniquely positioned to bring
people together and get things done
with the resources and know-how to
open doors to opportunity. In a world
where partisanship and polarization
can stall progress, we move the needle
by authentically earning the trust of
those we serve.
One of the many ways we do this is
through our Market Leadership Team
program. Organized to help leaders
from across the firm develop and imple
ment holistic business strategies that
address key community priorities, the
Market Leadership Team program
opens doors to opportunity.
We work across the public, private and
nonprofit sectors to solve complex
issues with practical solutions. Our
global network and data help us spot
patterns early, and our local partner
ships help us execute quickly and tailor
our approach to communities. We com
bine research, policy and investment to
turn ideas into outcomes, and we show
up in schools, neighborhoods, city halls
and on shop floors to make progress
you can feel.
The American Dream endures when
opportunity is within reach. JPMorgan
Chase will continue to pair data with
action, capital with creative thinking and
ambition with local execution — so fami
lies can buy a home, small businesses
can hire and grow, and workers can gain
the skills that lead to good jobs. We will
leverage our balance sheet, talent and
expertise; champion policies that
strengthen our economy and security;
and work across sectors to turn smart
strategies into measurable wins.
Our responsibility is to focus on what
matters most to families, workers and
businesses because when communi
ties thrive, our firm thrives. If we stay
focused on what matters most and
scale what works, we can help power
the next chapter of growth — building
resilience at home, expanding opportu
nity with our partners around the world
and leaving future generations better
off than those before them.
Tim Berry
Global Head of Corporate Responsibility,
Chairman of the Mid-Atlantic Region
Financial:
Page
Three-Year Summary of Consolidated Financial
Highlights
44
Five-Year Stock Performance
45
Management’s discussion and analysis:
Introduction
46
Executive Overview
47
Consolidated Results of Operations
51
Consolidated Balance Sheets and Cash Flows
Analysis
55
Explanation and Reconciliation of the Firm’s Use
of Non-GAAP Financial Measures
59
Business Segment & Corporate Results
62
Firmwide Risk Management
83
Strategic Risk Management
88
Capital Risk Management
89
Liquidity Risk Management
100
Reputation Risk Management
108
Credit and Investment Risk Management
109
Credit Portfolio
111
Consumer Credit Portfolio
112
Wholesale Credit Portfolio
118
Allowance for Credit Losses
129
Investment Portfolio Risk Management
132
Market Risk Management
133
Country Risk Management
143
Climate Risk Management
145
Operational Risk Management
146
Critical Accounting Estimates Used by the Firm
154
Accounting and Reporting Developments
158
Forward-Looking Statements
160
Audited financial statements:
Management’s Report on Internal Control Over
Financial Reporting
161
Report of Independent Registered Public
Accounting Firm
162
Consolidated Financial Statements
165
Note:
The following pages from JPMorgan Chase & Co.’s 2025
Form 10-K are not included herein: 1-42, 328
Notes to consolidated financial statements:
Page
Note 1 - Basis of presentation
170
Note 2 - Fair value measurement
174
Note 3 - Fair value option
196
Note 4 - Credit risk concentrations
200
Note 5 - Derivative instruments
202
Note 6 - Noninterest revenue and noninterest
expense
218
Note 7 - Interest income and interest expense
222
Note 8 - Pension and other postretirement
employee benefit plans
223
Note 9 - Employee share-based incentives
226
Note 10 - Investment securities
228
Note 11 - Securities financing activities
233
Note 12 - Loans
236
Note 13 - Allowance for credit losses
258
Note 14 - Variable interest entities
263
Note 15 - Goodwill, mortgage servicing rights,
and other intangible assets
272
Note 16 - Premises and equipment
277
Note 17 - Deposits
277
Note 18 - Leases
278
Note 19 - Accounts payable and other liabilities
280
Note 20 - Long-term debt
281
Note 21 - Preferred stock
283
Note 22 - Common stock
285
Note 23 - Earnings per share
286
Note 24 - Accumulated other comprehensive
income/(loss)
287
Note 25 - Income taxes
288
Note 26 - Restricted cash, other restricted
assets and intercompany funds transfers
292
Note 27 - Regulatory capital
293
Note 28 - Off-balance sheet lending-related
financial instruments, guarantees, and other
commitments
295
Note 29 - Pledged assets and collateral
301
Note 30 - Litigation
302
Note 31 – International operations
305
Note 32 – Business segments & Corporate
306
Note 33 – Parent Company
310
Note 34 – Business combinations
312
Supplementary Information:
Distribution of assets, liabilities and
stockholders’ equity; interest rates and
interest differentials
315
Glossary of Terms and Acronyms
320
Table of contents
JPMorgan Chase & Co./2025 Form 10-K
43
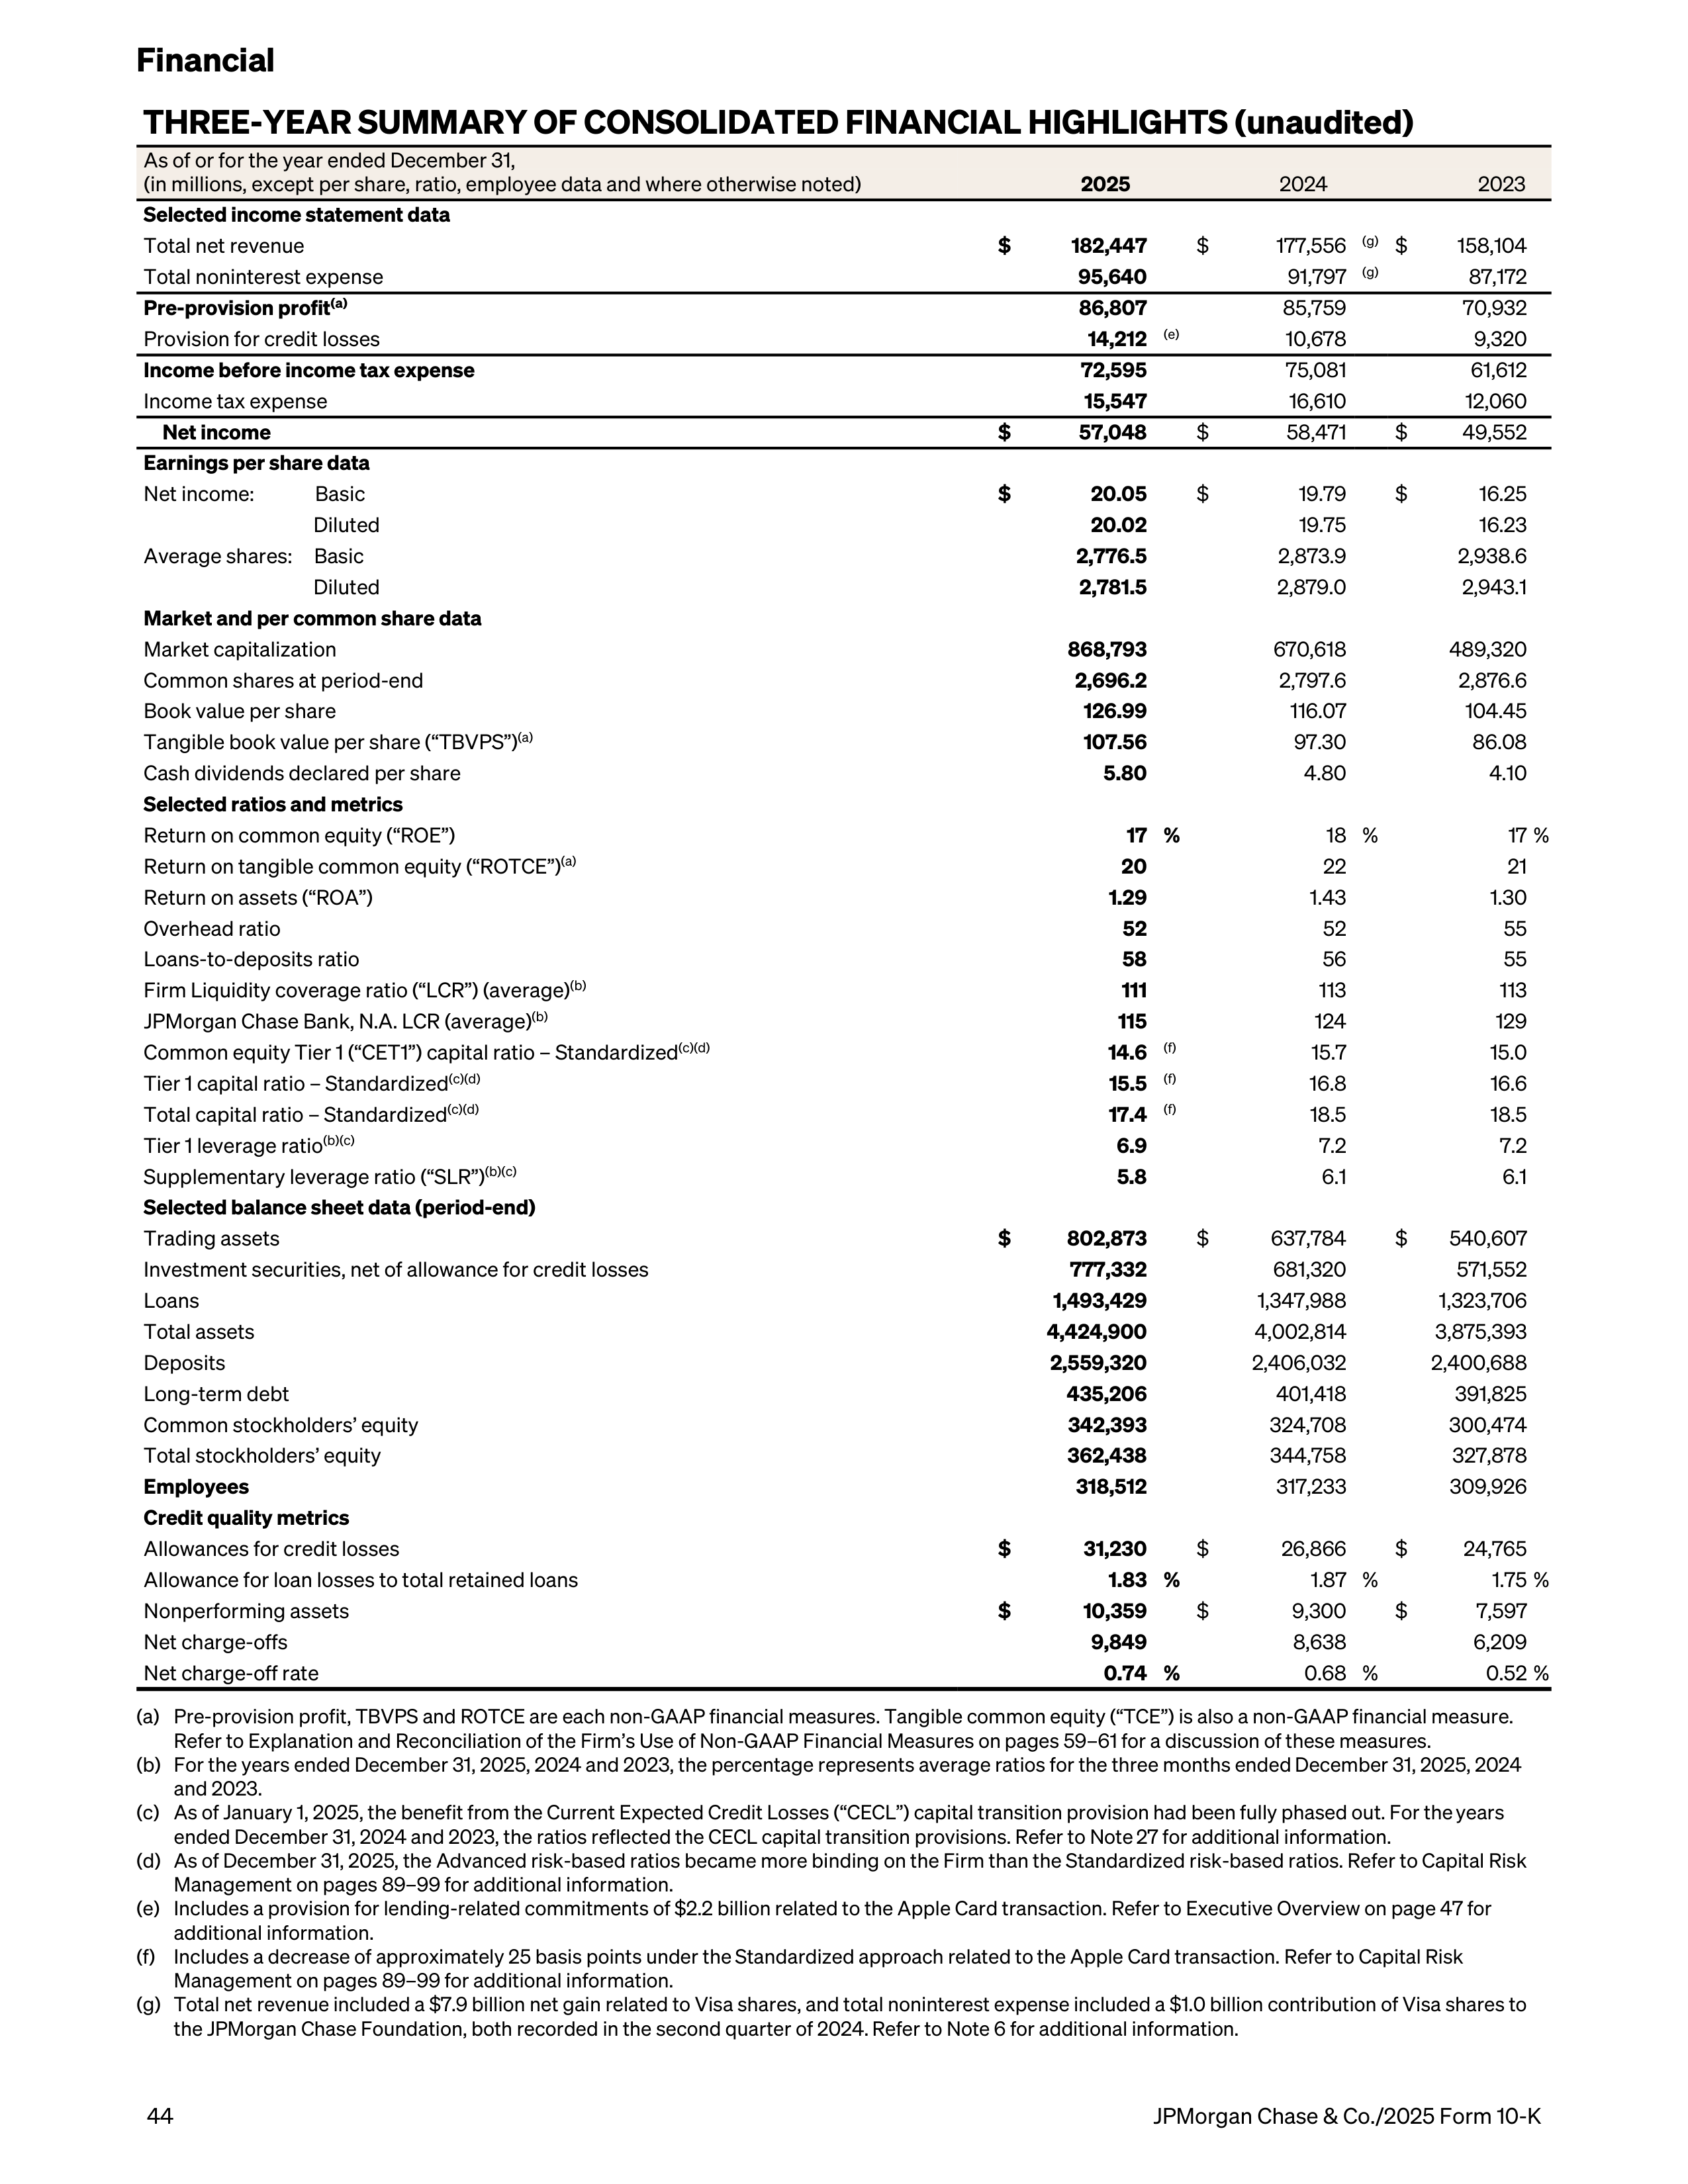
THREE-YEAR SUMMARY OF CONSOLIDATED FINANCIAL HIGHLIGHTS (unaudited)
2025
2024
2023
Selected income statement data
Total net revenue
$
182,447
$
177,556
(g)
$
158,104
Total noninterest expense
95,640
91,797
(g)
87,172
Pre-provision profit
(a)
86,807
85,759
70,932
Provision for credit losses
14,212
(e)
10,678
9,320
Income before income tax expense
72,595
75,081
61,612
Income tax expense
15,547
16,610
12,060
Net income
$
57,048
$
58,471
$
49,552
Earnings per share data
Net income: Basic
$
20.05
$
19.79
$
16.25
Diluted
20.02
19.75
16.23
Average shares: Basic
2,776.5
2,873.9
2,938.6
Diluted
2,781.5
2,879.0
2,943.1
Market and per common share data
Market capitalization
868,793
670,618
489,320
Common shares at period-end
2,696.2
2,797.6
2,876.6
Book value per share
126.99
116.07
104.45
Tangible book value per share (“TBVPS”)
(a)
107.56
97.30
86.08
Cash dividends declared per share
5.80
4.80
4.10
Selected ratios and metrics
Return on common equity (“ROE”)
17 %
18 %
17 %
Return on tangible common equity (“ROTCE”)
(a)
20
22
21
Return on assets (“ROA”)
1.29
1.43
1.30
Overhead ratio
52
52
55
Loans-to-deposits ratio
58
56
55
Firm Liquidity coverage ratio (“LCR”) (average)
(b)
111
113
113
JPMorgan Chase Bank, N.A. LCR (average)
(b)
115
124
129
Common equity Tier 1 (“CET1”) capital ratio – Standardized
(c)(d)
14.6
(f)
15.7
15.0
Tier 1 capital ratio – Standardized
(c)(d)
15.5
(f)
16.8
16.6
Total capital ratio – Standardized
(c)(d)
17.4
(f)
18.5
18.5
Tier 1 leverage ratio
(b)(c)
6.9
7.2
7.2
Supplementary leverage ratio (“SLR”)
(b)(c)
5.8
6.1
6.1
Selected balance sheet data (period-end)
Trading assets
$
802,873
$
637,784
$
540,607
Investment securities, net of allowance for credit losses
777,332
681,320
571,552
Loans
1,493,429
1,347,988
1,323,706
Total assets
4,424,900
4,002,814
3,875,393
Deposits
2,559,320
2,406,032
2,400,688
Long-term debt
435,206
401,418
391,825
Common stockholders’ equity
342,393
324,708
300,474
Total stockholders’ equity
362,438
344,758
327,878
Employees
318,512
317,233
309,926
Credit quality metrics
Allowances for credit losses
$
31,230
$
26,866
$
24,765
Allowance for loan losses to total retained loans
1.83 %
1.87 %
1.75 %
Nonperforming assets
$
10,359
$
9,300
$
7,597
Net charge-offs
9,849
8,638
6,209
Net charge-off rate
0.74 %
0.68 %
0.52 %
As of or for the year ended December 31,
(in millions, except per share, ratio, employee data and where otherwise noted)
(a)
Pre-provision profit, TBVPS and ROTCE are each non-GAAP financial measures. Tangible common equity (“TCE”) is also a non-GAAP financial measure.
Refer to Explanation and Reconciliation of the Firm’s Use of Non-GAAP Financial Measures on pages 59–61 for a discussion of these measures.
(b)
For the years ended December 31, 2025, 2024 and 2023, the percentage represents average ratios for the three months ended December 31, 2025, 2024
and 2023.
(c)
As of January 1, 2025, the benefit from the Current Expected Credit Losses (“CECL”) capital transition provision had been fully phased out. For the years
ended December 31, 2024 and 2023, the ratios reflected the CECL capital transition provisions. Refer to Note 27 for additional information.
(d)
As of December 31, 2025, the Advanced risk-based ratios became more binding on the Firm than the Standardized risk-based ratios. Refer to Capital Risk
Management on pages 89–99 for additional information.
(e)
Includes a provision for lending-related commitments of $2.2 billion related to the Apple Card transaction. Refer to Executive Overview on page 47 for
additional information.
(f)
Includes a decrease of approximately 25 basis points under the Standardized approach related to the Apple Card transaction. Refer to Capital Risk
Management on pages 89–99 for additional information.
(g)
Total net revenue included a $7.9 billion net gain related to Visa shares, and total noninterest expense included a $1.0 billion contribution of Visa shares to
the JPMorgan Chase Foundation, both recorded in the second quarter of 2024. Refer to Note 6 for additional information.
Financial
44
JPMorgan Chase & Co./2025 Form 10-K
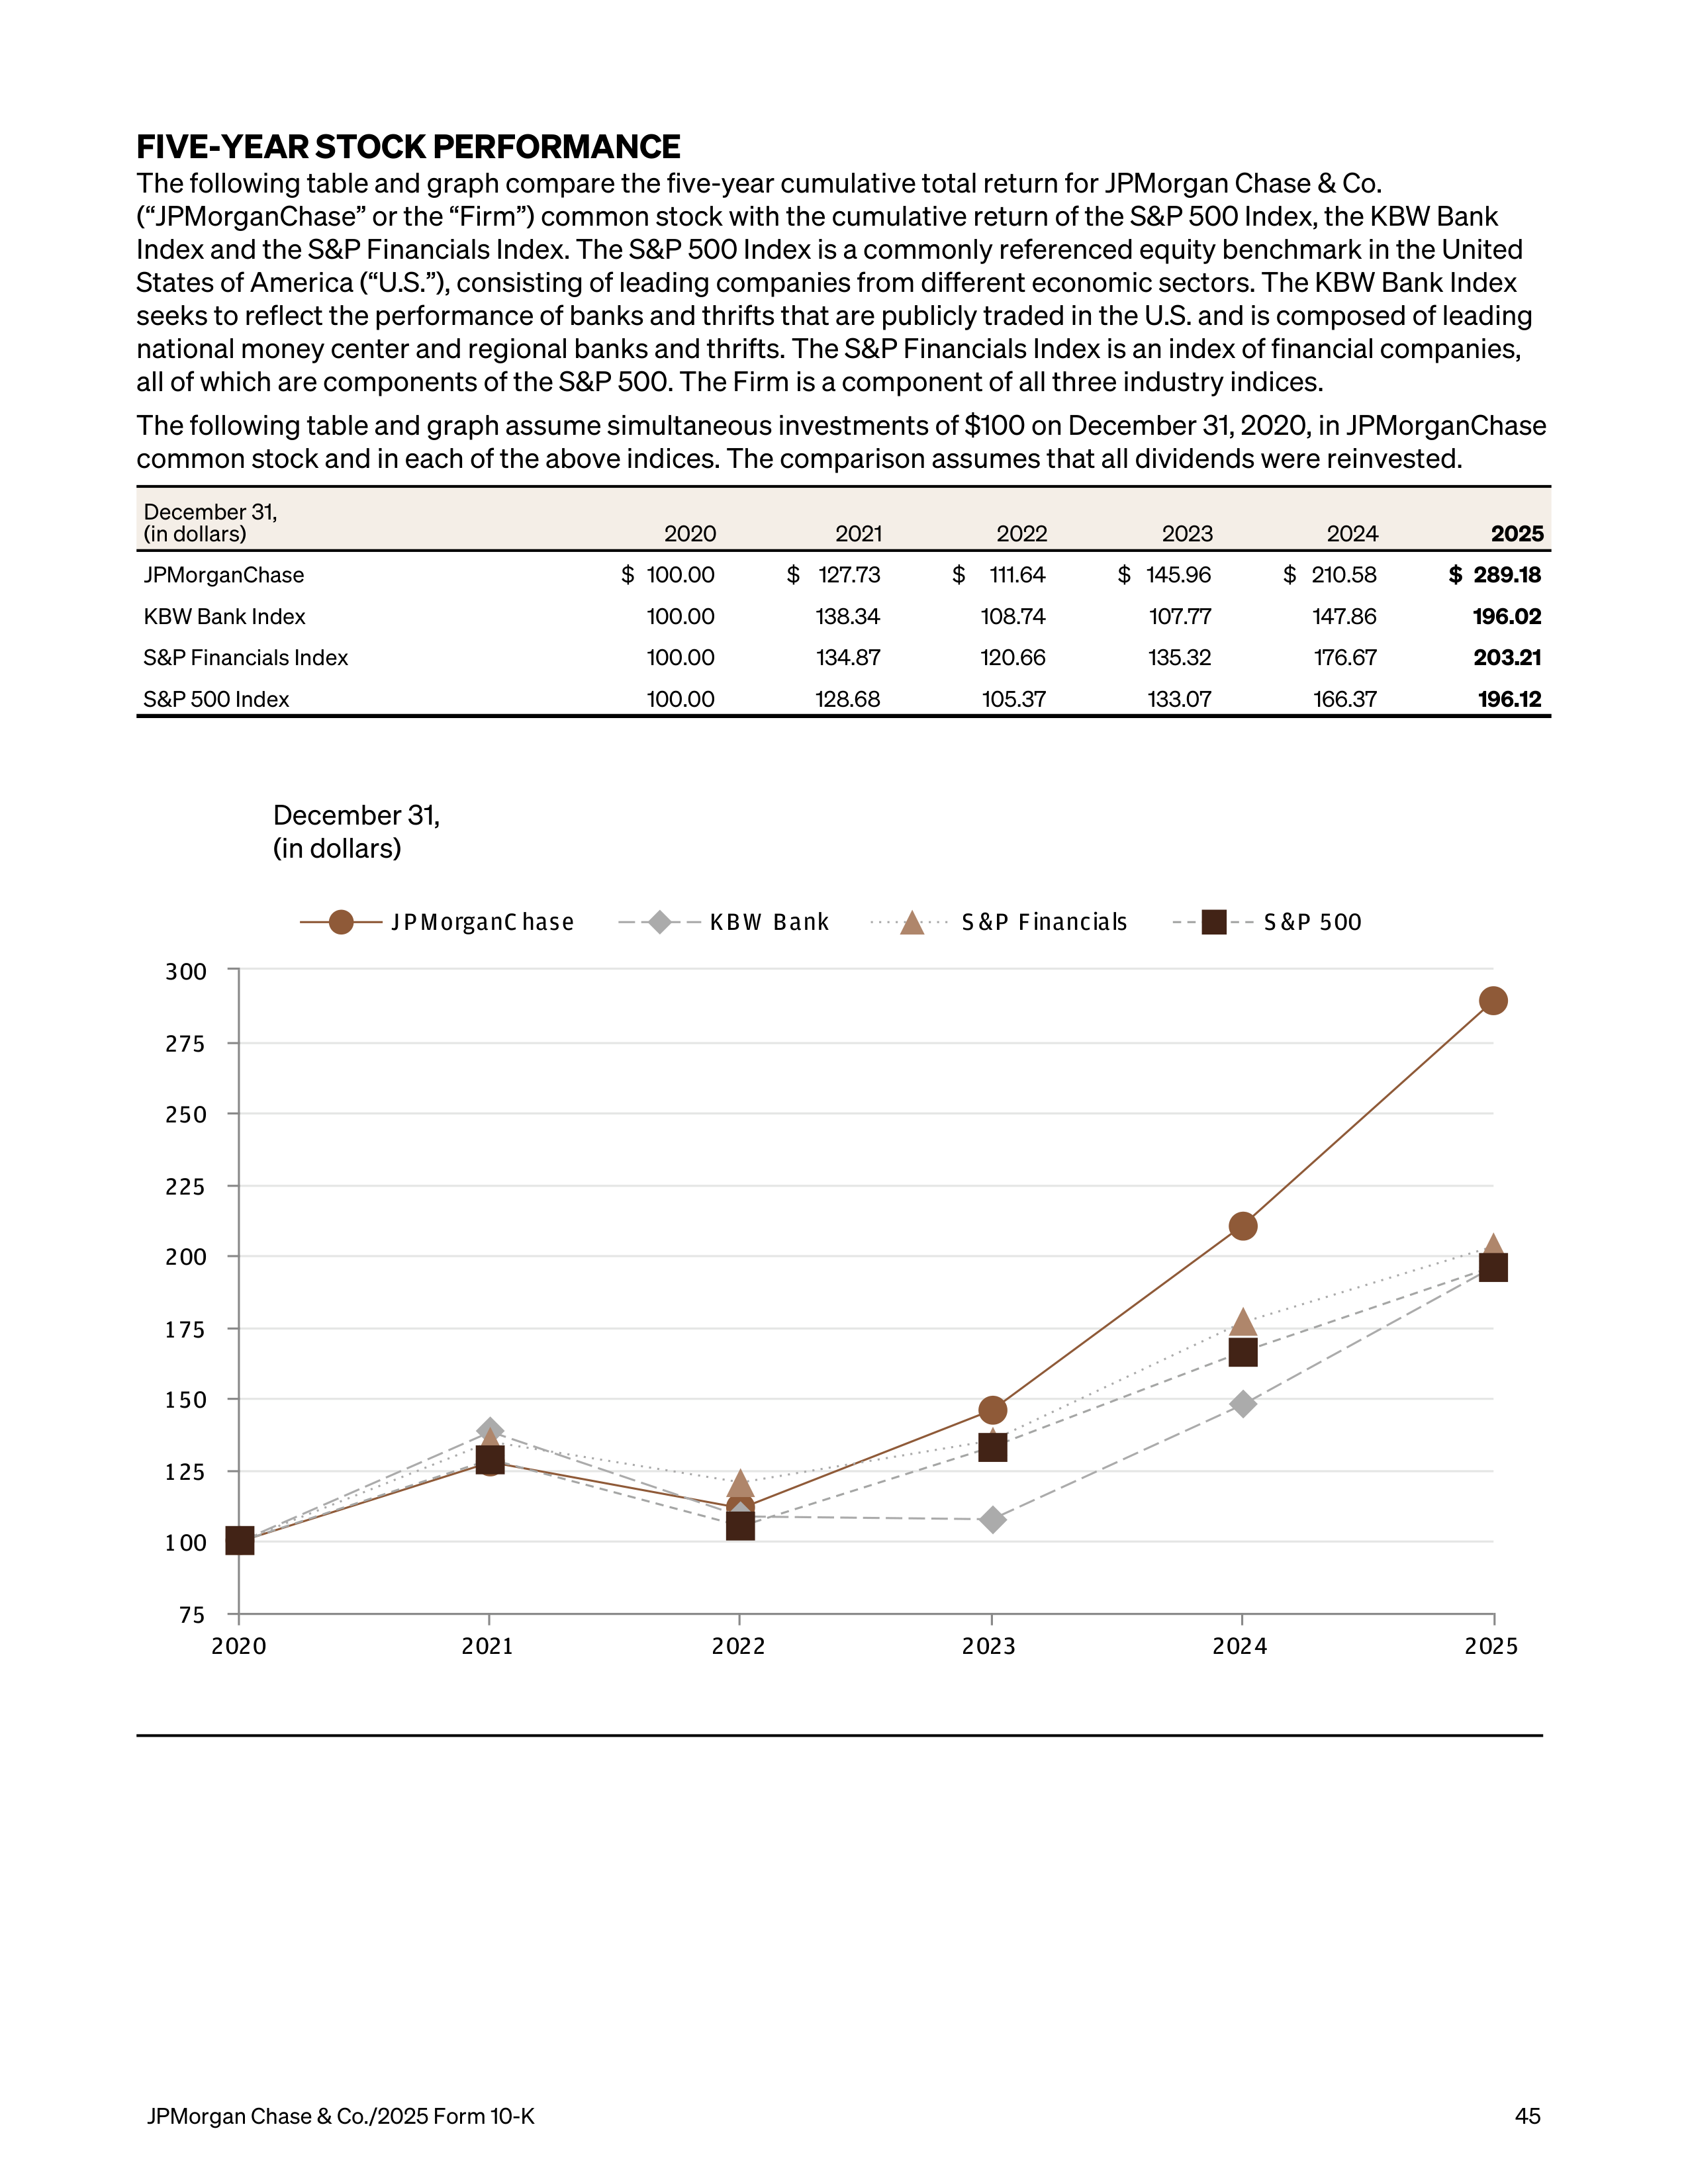
FIVE-YEAR STOCK PERFORMANCE
The following table and graph compare the five-year cumulative total return for JPMorgan Chase & Co.
(“JPMorganChase” or the “Firm”) common stock with the cumulative return of the S&P 500 Index, the KBW Bank
Index and the S&P Financials Index. The S&P 500 Index is a commonly referenced equity benchmark in the United
States of America (“U.S.”), consisting of leading companies from different economic sectors. The KBW Bank Index
seeks to reflect the performance of banks and thrifts that are publicly traded in the U.S. and is composed of leading
national money center and regional banks and thrifts. The S&P Financials Index is an index of financial companies,
all of which are components of the S&P 500. The Firm is a component of all three industry indices.
The following table and graph assume simultaneous investments of $100 on December 31, 2020, in JPMorganChase
common stock and in each of the above indices. The comparison assumes that all dividends were reinvested.
December 31,
(in dollars)
2020
2021
2022
2023
2024
2025
JPMorganChase
$ 100.00
$ 127.73
$
111.64
$ 145.96
$ 210.58
$ 289.18
KBW Bank Index
100.00
138.34
108.74
107.77
147.86
196.02
S&P Financials Index
100.00
134.87
120.66
135.32
176.67
203.21
S&P 500 Index
100.00
128.68
105.37
133.07
166.37
196.12
December 31,
(in dollars)
JPMorganC hase
KBW Bank
S &P Financials
S &P 500
2020
2021
2022
2023
2024
2025
75
1 00
1 25
1 50
1 75
200
225
250
275
300
JPMorgan Chase & Co./2025 Form 10-K
45
The following is Management’s discussion and analysis of the financial condition and results of operations (“MD&A”)
of JPMorganChase for the year ended December 31, 2025. The MD&A is included in both JPMorganChase’s Annual
Report for the year ended December 31, 2025 (“Annual Report”) and its Annual Report on Form 10-K for the year
ended December 31, 2025 (“2025 Form 10-K” or “Form 10-K”) filed with the Securities and Exchange Commission
(“SEC”). Refer to the Glossary of terms and acronyms on pages 320–327 for definitions of terms and acronyms used
throughout the Annual Report and the 2025 Form 10-K.
This Form 10-K contains forward-looking statements within the meaning of the Private Securities Litigation Reform
Act of 1995. These forward-looking statements are based on the current beliefs and expectations of
JPMorganChase’s management, speak only as of the date of this Form 10-K and are subject to significant risks and
uncertainties. Refer to Forward-looking Statements on page 160 and Part 1, Item 1A: Risk Factors in this Form 10-K
on pages 9–31 for a discussion of certain of those risks and uncertainties and the factors that could cause
JPMorganChase’s actual results to differ materially because of those risks and uncertainties. There is no assurance
that actual results will be in line with any outlook information set forth herein, and the Firm does not undertake to
update any forward-looking statements.
INTRODUCTION
JPMorgan Chase & Co. (NYSE: JPM), a financial holding
company incorporated under Delaware law in 1968, is
a leading financial services firm based in the United
States of America (“U.S.”), with operations worldwide.
JPMorganChase had $4.4 trillion in assets and $362.4
billion in stockholders’ equity as of December 31, 2025.
The Firm is a leader in investment banking, financial
services for consumers and small businesses,
commercial banking, financial transaction processing
and asset management. Under the J.P. Morgan and
Chase brands, the Firm serves millions of customers,
predominantly in the U.S., and many of the world’s
most prominent corporate, institutional and
government clients globally.
JPMorganChase’s principal bank subsidiary is
JPMorgan Chase Bank, National Association
(“JPMorgan Chase Bank, N.A.”), a national banking
association with U.S. branches in 48 states and
Washington, D.C. JPMorganChase’s principal non-
bank subsidiary is J.P. Morgan Securities LLC (“J.P.
Morgan Securities”), a U.S. broker-dealer. The bank
and non-bank subsidiaries of JPMorganChase operate
nationally as well as through overseas branches and
subsidiaries, representative offices and subsidiary
foreign banks. The Firm’s principal operating
subsidiaries outside the U.S. are J.P. Morgan Securities
plc and J.P. Morgan SE (“JPMSE”), which are
subsidiaries of JPMorgan Chase Bank, N.A. and are
based in the United Kingdom (“U.K.”) and Germany,
respectively.
For management reporting purposes, the Firm has
three reportable business segments – Consumer &
Community Banking (“CCB”), Commercial &
Investment Bank (“CIB”) and Asset & Wealth
Management (“AWM”) – with the remaining activities
in Corporate. The Firm's consumer business segment
is CCB, and the Firm's wholesale business segments
are CIB and AWM. Refer to Business Segment &
Corporate Results on pages 62–82 and Note 32 for a
description of the Firm’s reportable business
segments and the products and services that they
provide to their respective client bases, as well as a
description of Corporate activities.
The Firm’s website is www.jpmorganchase.com.
JPMorganChase makes available on its website, free of
charge, annual reports on Form 10-K, quarterly reports
on Form 10-Q and current reports on Form 8-K
pursuant to Section 13(a) or Section 15(d) of the
Securities Exchange Act of 1934, as soon as
reasonably practicable after it electronically files or
furnishes such material to the U.S. Securities and
Exchange Commission (the “SEC”) at www.sec.gov.
JPMorganChase makes new and important
information about the Firm available on its website at
https://www.jpmorganchase.com, including on the
Investor Relations section of its website at https://
www.jpmorganchase.com/ir. Information on the Firm's
website, including documents on the website that are
referenced in this Form 10-K, is not incorporated by
reference into this 2025 Form 10-K or the Firm’s other
filings with the SEC.
Management’s discussion and analysis
46
JPMorgan Chase & Co./2025 Form 10-K
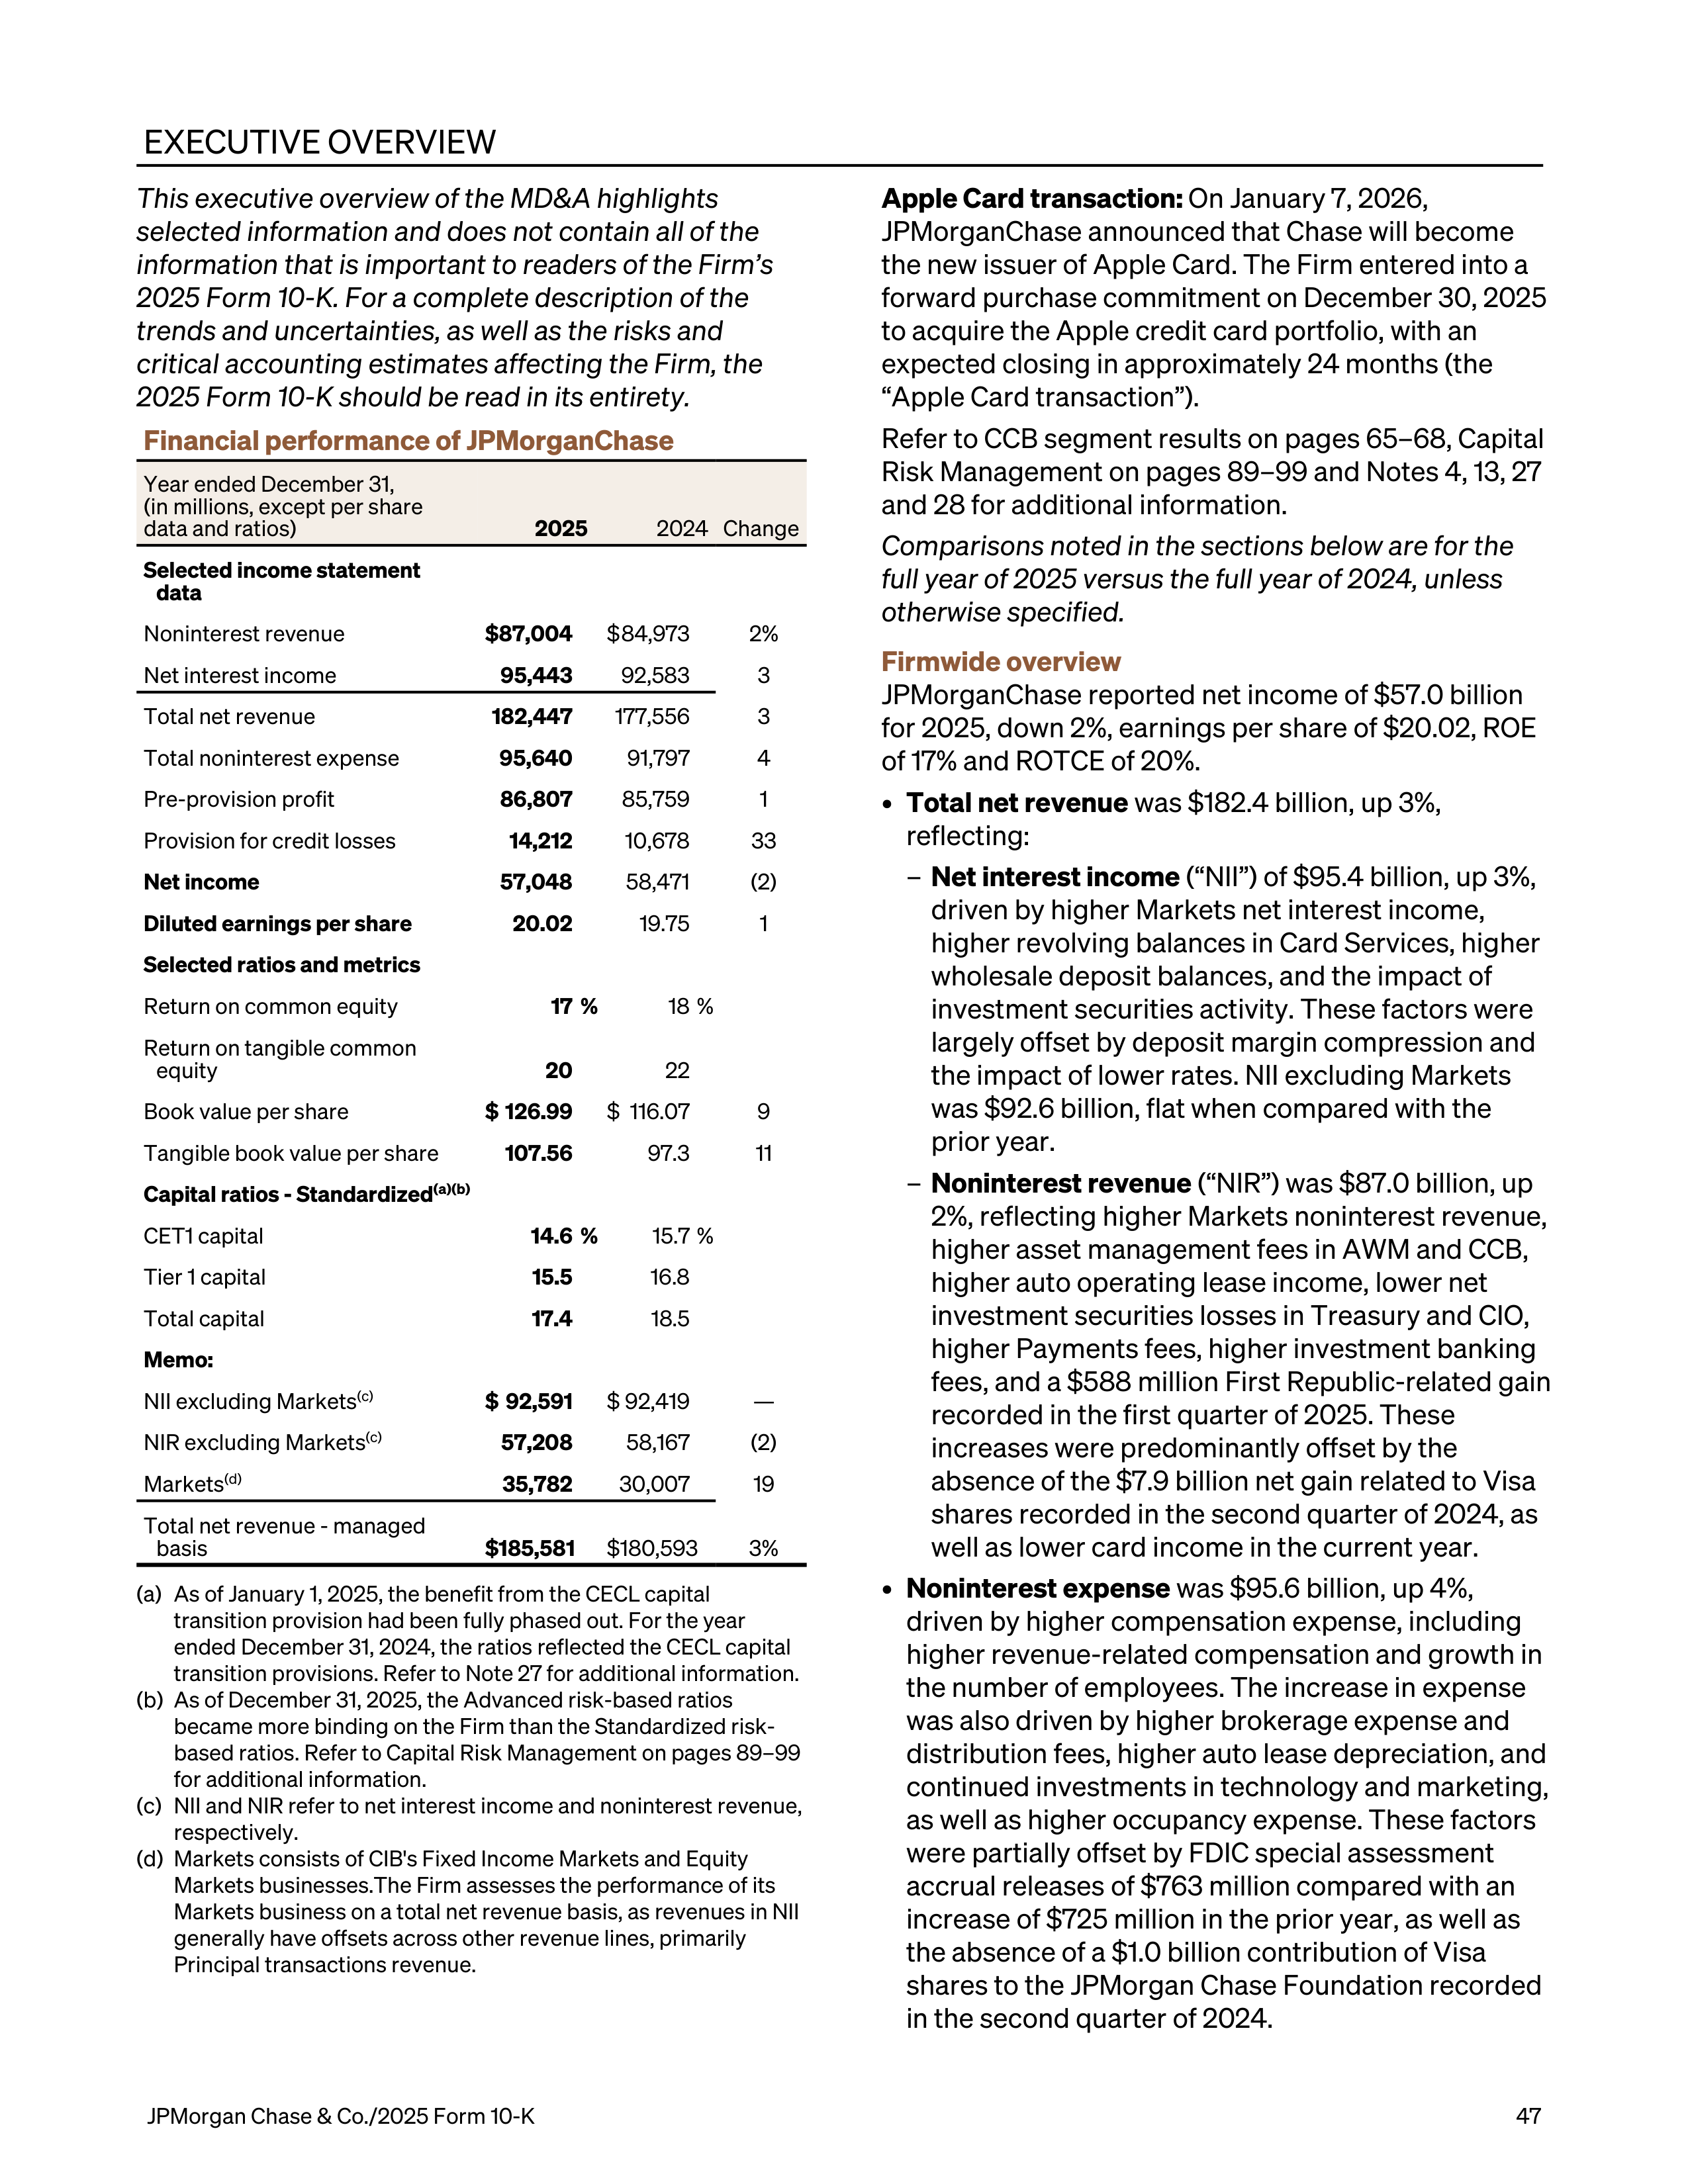
EXECUTIVE OVERVIEW
This executive overview of the MD&A highlights
selected information and does not contain all of the
information that is important to readers of the Firm’s
2025 Form 10-K. For a complete description of the
trends and uncertainties, as well as the risks and
critical accounting estimates affecting the Firm, the
2025 Form 10-K should be read in its entirety.
Financial performance of JPMorganChase
Year ended December 31,
(in millions, except per share
data and ratios)
2025
2024
Change
Selected income statement
data
Noninterest revenue
$ 87,004
$ 84,973
2%
Net interest income
95,443
92,583
3
Total net revenue
182,447
177,556
3
Total noninterest expense
95,640
91,797
4
Pre-provision profit
86,807
85,759
1
Provision for credit losses
14,212
10,678
33
Net income
57,048
58,471
(2)
Diluted earnings per share
20.02
19.75
1
Selected ratios and metrics
Return on common equity
17 %
18 %
Return on tangible common
equity
20
22
Book value per share
$ 126.99
$ 116.07
9
Tangible book value per share
107.56
97.3
11
Capital ratios - Standardized
(a)(b)
CET1 capital
14.6 %
15.7 %
Tier 1 capital
15.5
16.8
Total capital
17.4
18.5
Memo:
NII excluding Markets
(c)
$ 92,591
$ 92,419
—
NIR excluding Markets
(c)
57,208
58,167
(2)
Markets
(d)
35,782
30,007
19
Total net revenue - managed
basis
$ 185,581
$ 180,593
3%
(a) As of January 1, 2025, the benefit from the CECL capital
transition provision had been fully phased out. For the year
ended December 31, 2024, the ratios reflected the CECL capital
transition provisions. Refer to Note 27 for additional information.
(b) As of December 31, 2025, the Advanced risk-based ratios
became more binding on the Firm than the Standardized risk-
based ratios. Refer to Capital Risk Management on pages 89–99
for additional information.
(c) NII and NIR refer to net interest income and noninterest revenue,
respectively.
(d) Markets consists of CIB's Fixed Income Markets and Equity
Markets businesses.The Firm assesses the performance of its
Markets business on a total net revenue basis, as revenues in NII
generally have offsets across other revenue lines, primarily
Principal transactions revenue.
Apple Card transaction:
On January 7, 2026,
JPMorganChase announced that Chase will become
the new issuer of Apple Card. The Firm entered into a
forward purchase commitment on December 30, 2025
to acquire the Apple credit card portfolio, with an
expected closing in approximately 24 months (the
“Apple Card transaction”).
Refer to CCB segment results on pages 65–68, Capital
Risk Management on pages 89–99 and Notes 4, 13, 27
and 28 for additional information.
Comparisons noted in the sections below are for the
full year of 2025 versus the full year of 2024, unless
otherwise specified.
Firmwide overview
JPMorganChase reported net income of $57.0 billion
for 2025, down 2%, earnings per share of $20.02, ROE
of 17% and ROTCE of 20%.
•
Total net revenue
was $182.4 billion, up 3%,
reflecting:
–
Net interest income
(“NII”) of $95.4 billion, up 3%,
driven by higher Markets net interest income,
higher revolving balances in Card Services, higher
wholesale deposit balances, and the impact of
investment securities activity. These factors were
largely offset by deposit margin compression and
the impact of lower rates. NII excluding Markets
was $92.6 billion, flat when compared with the
prior year.
–
Noninterest revenue
(“NIR”) was $87.0 billion, up
2%, reflecting higher Markets noninterest revenue,
higher asset management fees in AWM and CCB,
higher auto operating lease income, lower net
investment securities losses in Treasury and CIO,
higher Payments fees, higher investment banking
fees, and a $588 million First Republic-related gain
recorded in the first quarter of 2025. These
increases were predominantly offset by the
absence of the $7.9 billion net gain related to Visa
shares recorded in the second quarter of 2024, as
well as lower card income in the current year.
•
Noninterest expense
was $95.6 billion, up 4%,
driven by higher compensation expense, including
higher revenue-related compensation and growth in
the number of employees. The increase in expense
was also driven by higher brokerage expense and
distribution fees, higher auto lease depreciation, and
continued investments in technology and marketing,
as well as higher occupancy expense. These factors
were partially offset by FDIC special assessment
accrual releases of $763 million compared with an
increase of $725 million in the prior year, as well as
the absence of a $1.0 billion contribution of Visa
shares to the JPMorgan Chase Foundation recorded
in the second quarter of 2024.
JPMorgan Chase & Co./2025 Form 10-K
47
•
The
provision for credit losses
was $14.2 billion. Net
charge-offs were $9.8 billion, up $1.2 billion,
predominantly driven by Wholesale and Card
Services. The net addition to the allowance for credit
losses was $4.4 billion and consisted of $3.3 billion
in
consumer
, which included $2.2 billion related to
the Apple Card transaction, and $1.1 billion in
wholesale
.
In the prior year, the provision was $10.7 billion, net
charge-offs were $8.6 billion and the net addition to
the allowance for credit losses was $2.0 billion.
•
The total
allowance for credit losses
was $31.2
billion at December 31, 2025. The Firm had an
allowance for loan losses to retained loans coverage
ratio of 1.83%, compared with 1.87% in the prior year.
Refer to Consolidated Results of Operations and
Consolidated Balance Sheets Analysis on pages 51–54
and pages 55–57, respectively, for a further discussion
of the Firm's results, including the provision for credit
losses.
Pre-provision profit, ROTCE, TCE, TBVPS, NII and NIR
excluding Markets, and total net revenue on a
managed basis, are non-GAAP financial measures.
Refer to Explanation and Reconciliation of the Firm’s
Use of Non-GAAP Financial Measures on pages 59–61
for a further discussion of each of these measures.
•
The Firm’s
nonperforming assets
totaled $10.4
billion at December 31, 2025, up 11%, driven by:
–
higher consumer nonaccrual loans, predominantly
due to the impact of the wildfires in California in
January 2025, as well as higher loans at fair value
in CIB, and
–
higher wholesale nonaccrual loans, reflecting
downgrades to exposures in certain industries,
predominantly offset by net portfolio activity and
upgrades.
Refer to Wholesale Credit Portfolio and Consumer
Credit Portfolio on pages 118–128 and pages 112–117,
respectively, for additional information.
•
Firmwide
average loans
of $1.4 trillion were up 6%,
predominantly driven by higher loans in CIB and
AWM.
•
Firmwide
average deposits
of $2.5 trillion were up
5%, reflecting:
–
net inflows related to client-driven activities in
Payments and Securities Services, and
–
growth in both new accounts and balances in
existing accounts in AWM,
partially offset by
–
a decrease in CCB primarily driven by increased
customer spending.
Refer to Liquidity Risk Management on pages 100–107
for additional information.
Selected capital and other metrics
•
CET1 capital
was $288.5 billion, and the
Standardized and Advanced CET1 ratios were 14.6%
and 14.1%, respectively.
•
SLR
was 5.8%.
•
TBVPS
grew 10.5%, ending 2025 at $107.56.
•
As of December 31, 2025, the Firm had eligible end-
of-period
High Quality Liquid Assets
(“HQLA”) of
approximately $915 billion and
unencumbered
marketable securities
with a fair value of
approximately $548 billion, resulting in
approximately $1.5 trillion of liquidity sources.
Refer to Capital Risk Management and Liquidity Risk
Management on pages 89–99 and pages 100–107,
respectively, for additional information.
48
JPMorgan Chase & Co./2025 Form 10-K
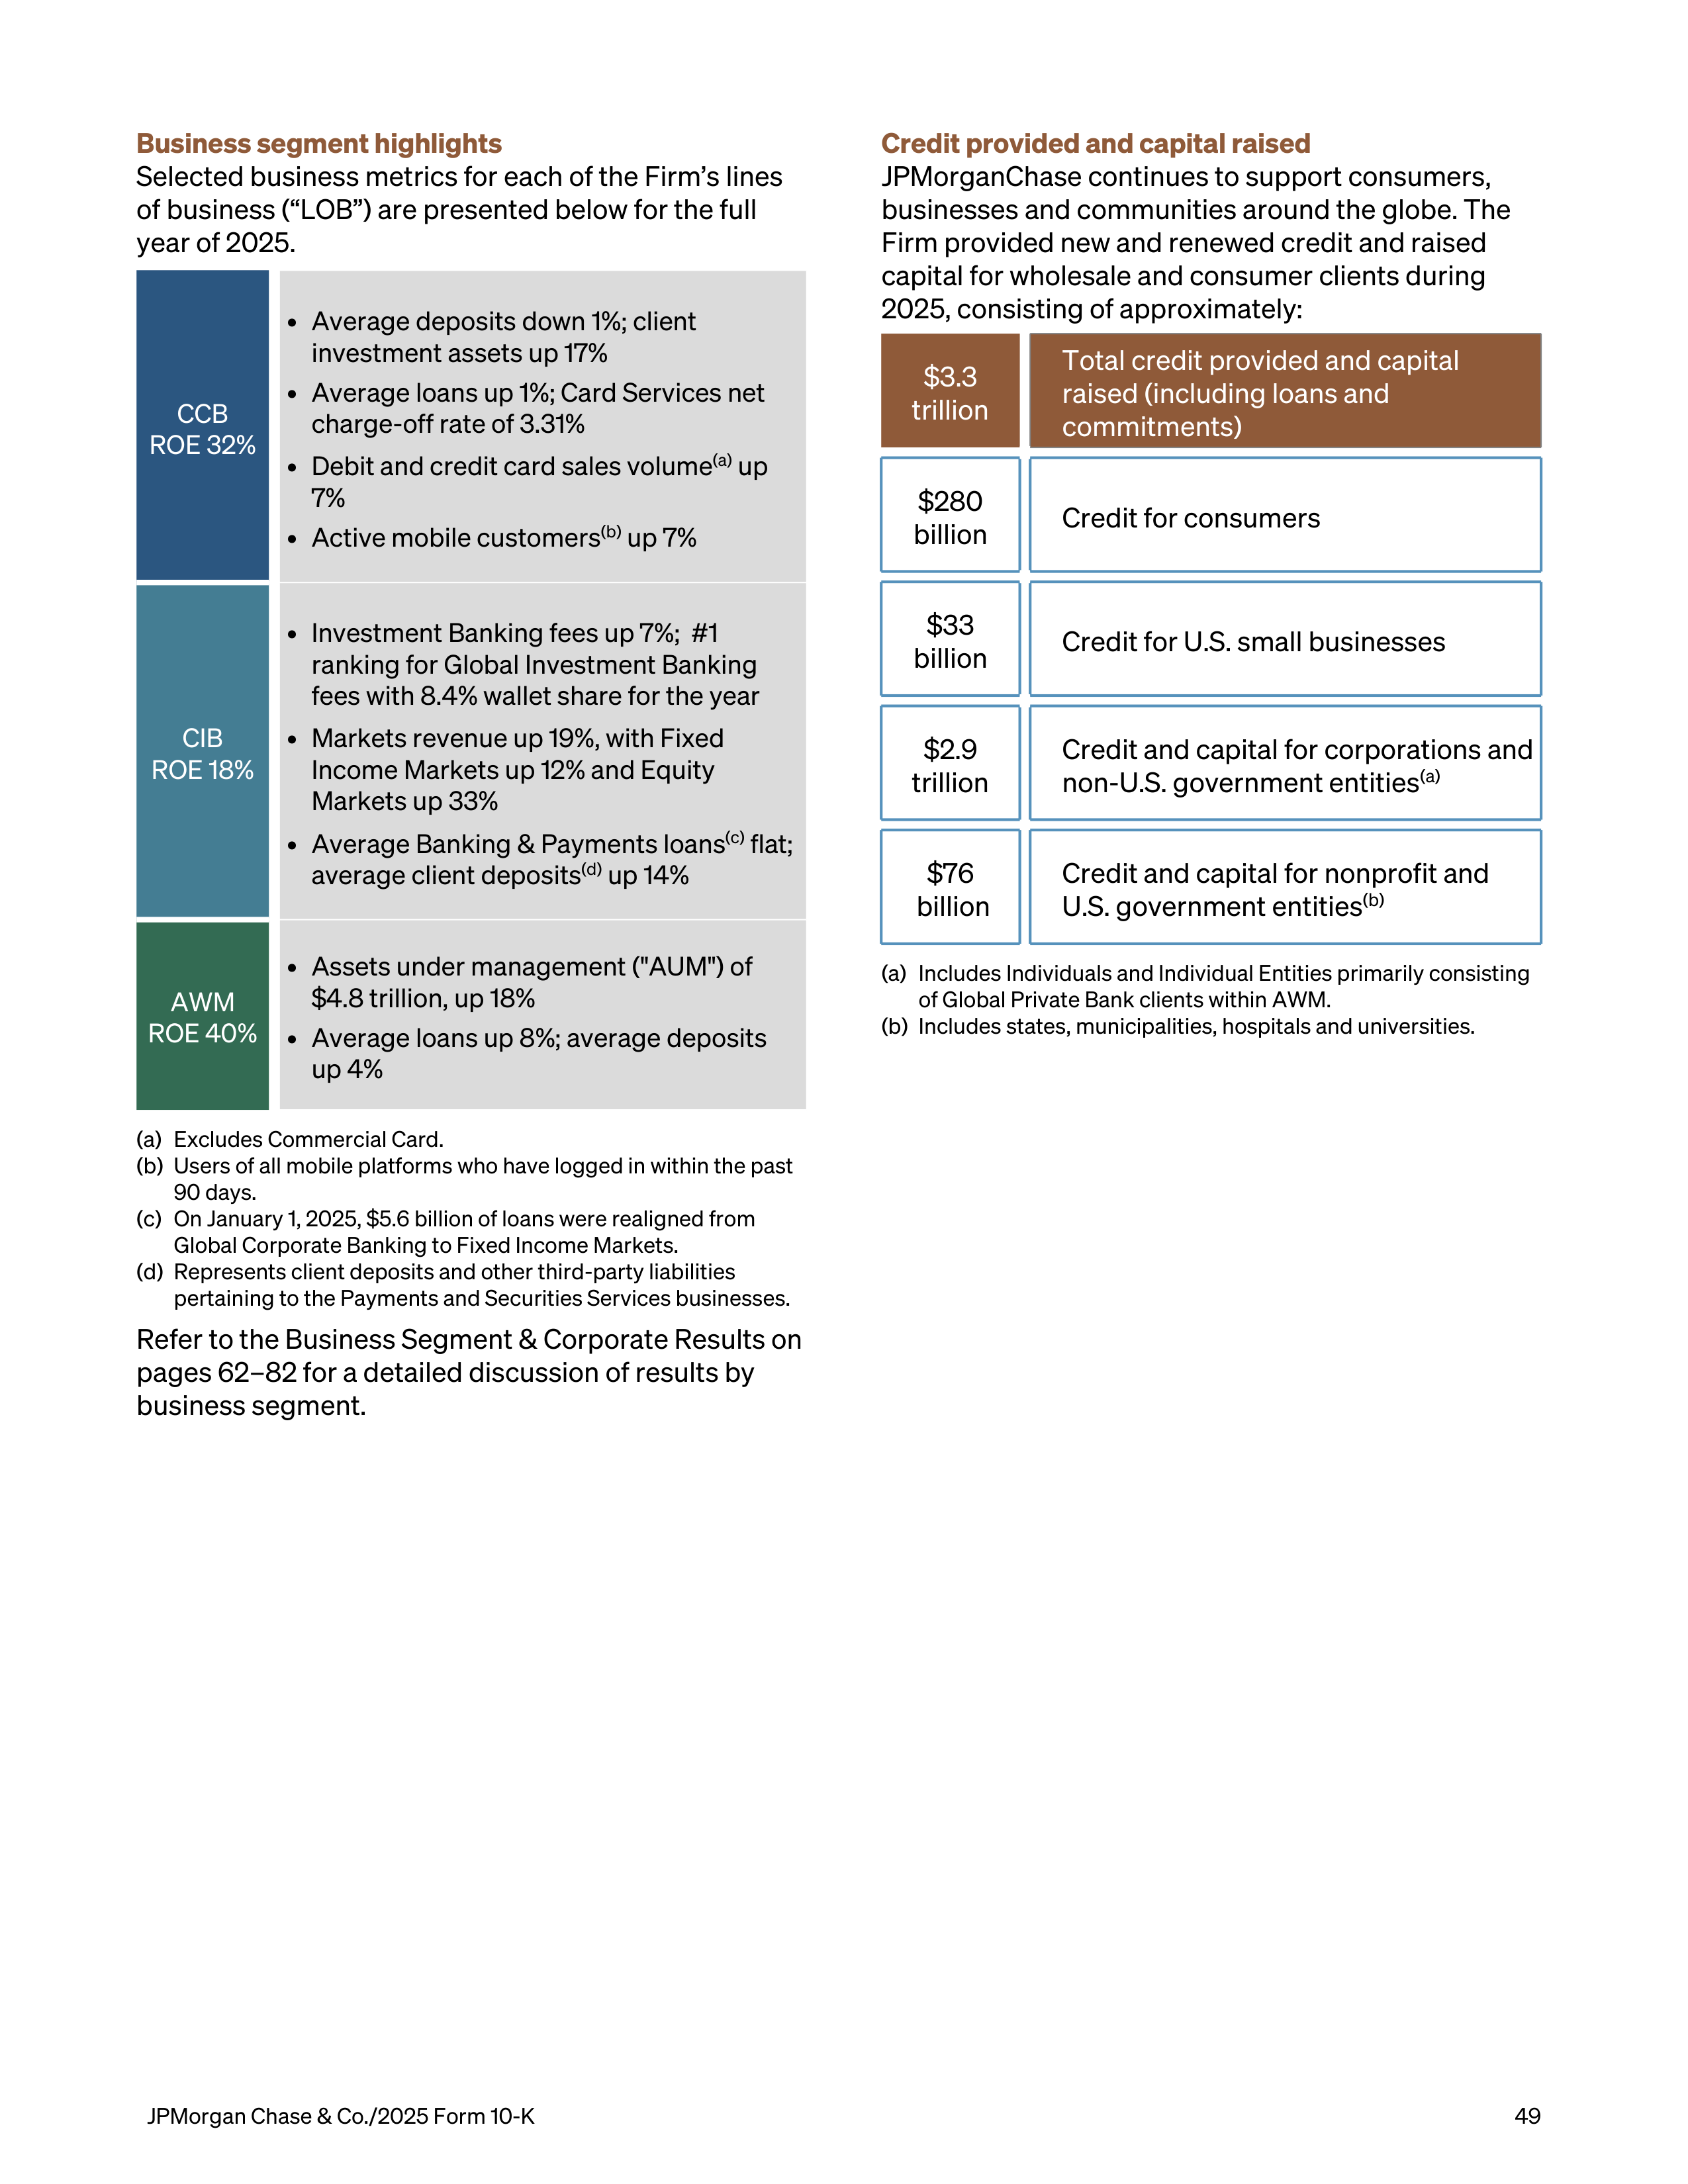
Business segment highlights
Selected business metrics for each of the Firm’s lines
of business (“LOB”) are presented below for the full
year of 2025.
CCB
ROE 32%
•
Average deposits down 1%; client
investment assets up 17%
•
Average loans up 1%; Card Services net
charge-off rate of 3.31%
•
Debit and credit card sales volume
(a)
up
7%
•
Active mobile customers
(b)
up 7%
CIB
ROE 18%
•
Investment Banking fees up 7%; #1
ranking for Global Investment Banking
fees with 8.4% wallet share for the year
•
Markets revenue up 19%, with Fixed
Income Markets up 12% and Equity
Markets up 33%
•
Average Banking & Payments loans
(c)
flat;
average client deposits
(d)
up 14%
AWM
ROE 40%
•
Assets under management ("AUM") of
$4.8 trillion, up 18%
•
Average loans up 8%; average deposits
up 4%
(a)
Excludes Commercial Card.
(b)
Users of all mobile platforms who have logged in within the past
90 days.
(c)
On January 1, 2025, $5.6 billion of loans were realigned from
Global Corporate Banking to Fixed Income Markets.
(d)
Represents client deposits and other third-party liabilities
pertaining to the Payments and Securities Services businesses.
Refer to the Business Segment & Corporate Results on
pages 62–82 for a detailed discussion of results by
business segment.
Credit provided and capital raised
JPMorganChase continues to support consumers,
businesses and communities around the globe. The
Firm provided new and renewed credit and raised
capital for wholesale and consumer clients during
2025, consisting of approximately:
$3.3
trillion
Total credit provided and capital
raised (including loans and
commitments)
$280
billion
Credit for consumers
$33
billion
Credit for U.S. small businesses
$2.9
trillion
Credit and capital for corporations and
non-U.S. government entities
(a)
$76
billion
Credit and capital for nonprofit and
U.S. government entities
(b)
(a)
Includes Individuals and Individual Entities primarily consisting
of Global Private Bank clients within AWM.
(b)
Includes states, municipalities, hospitals and universities.
JPMorgan Chase & Co./2025 Form 10-K
49
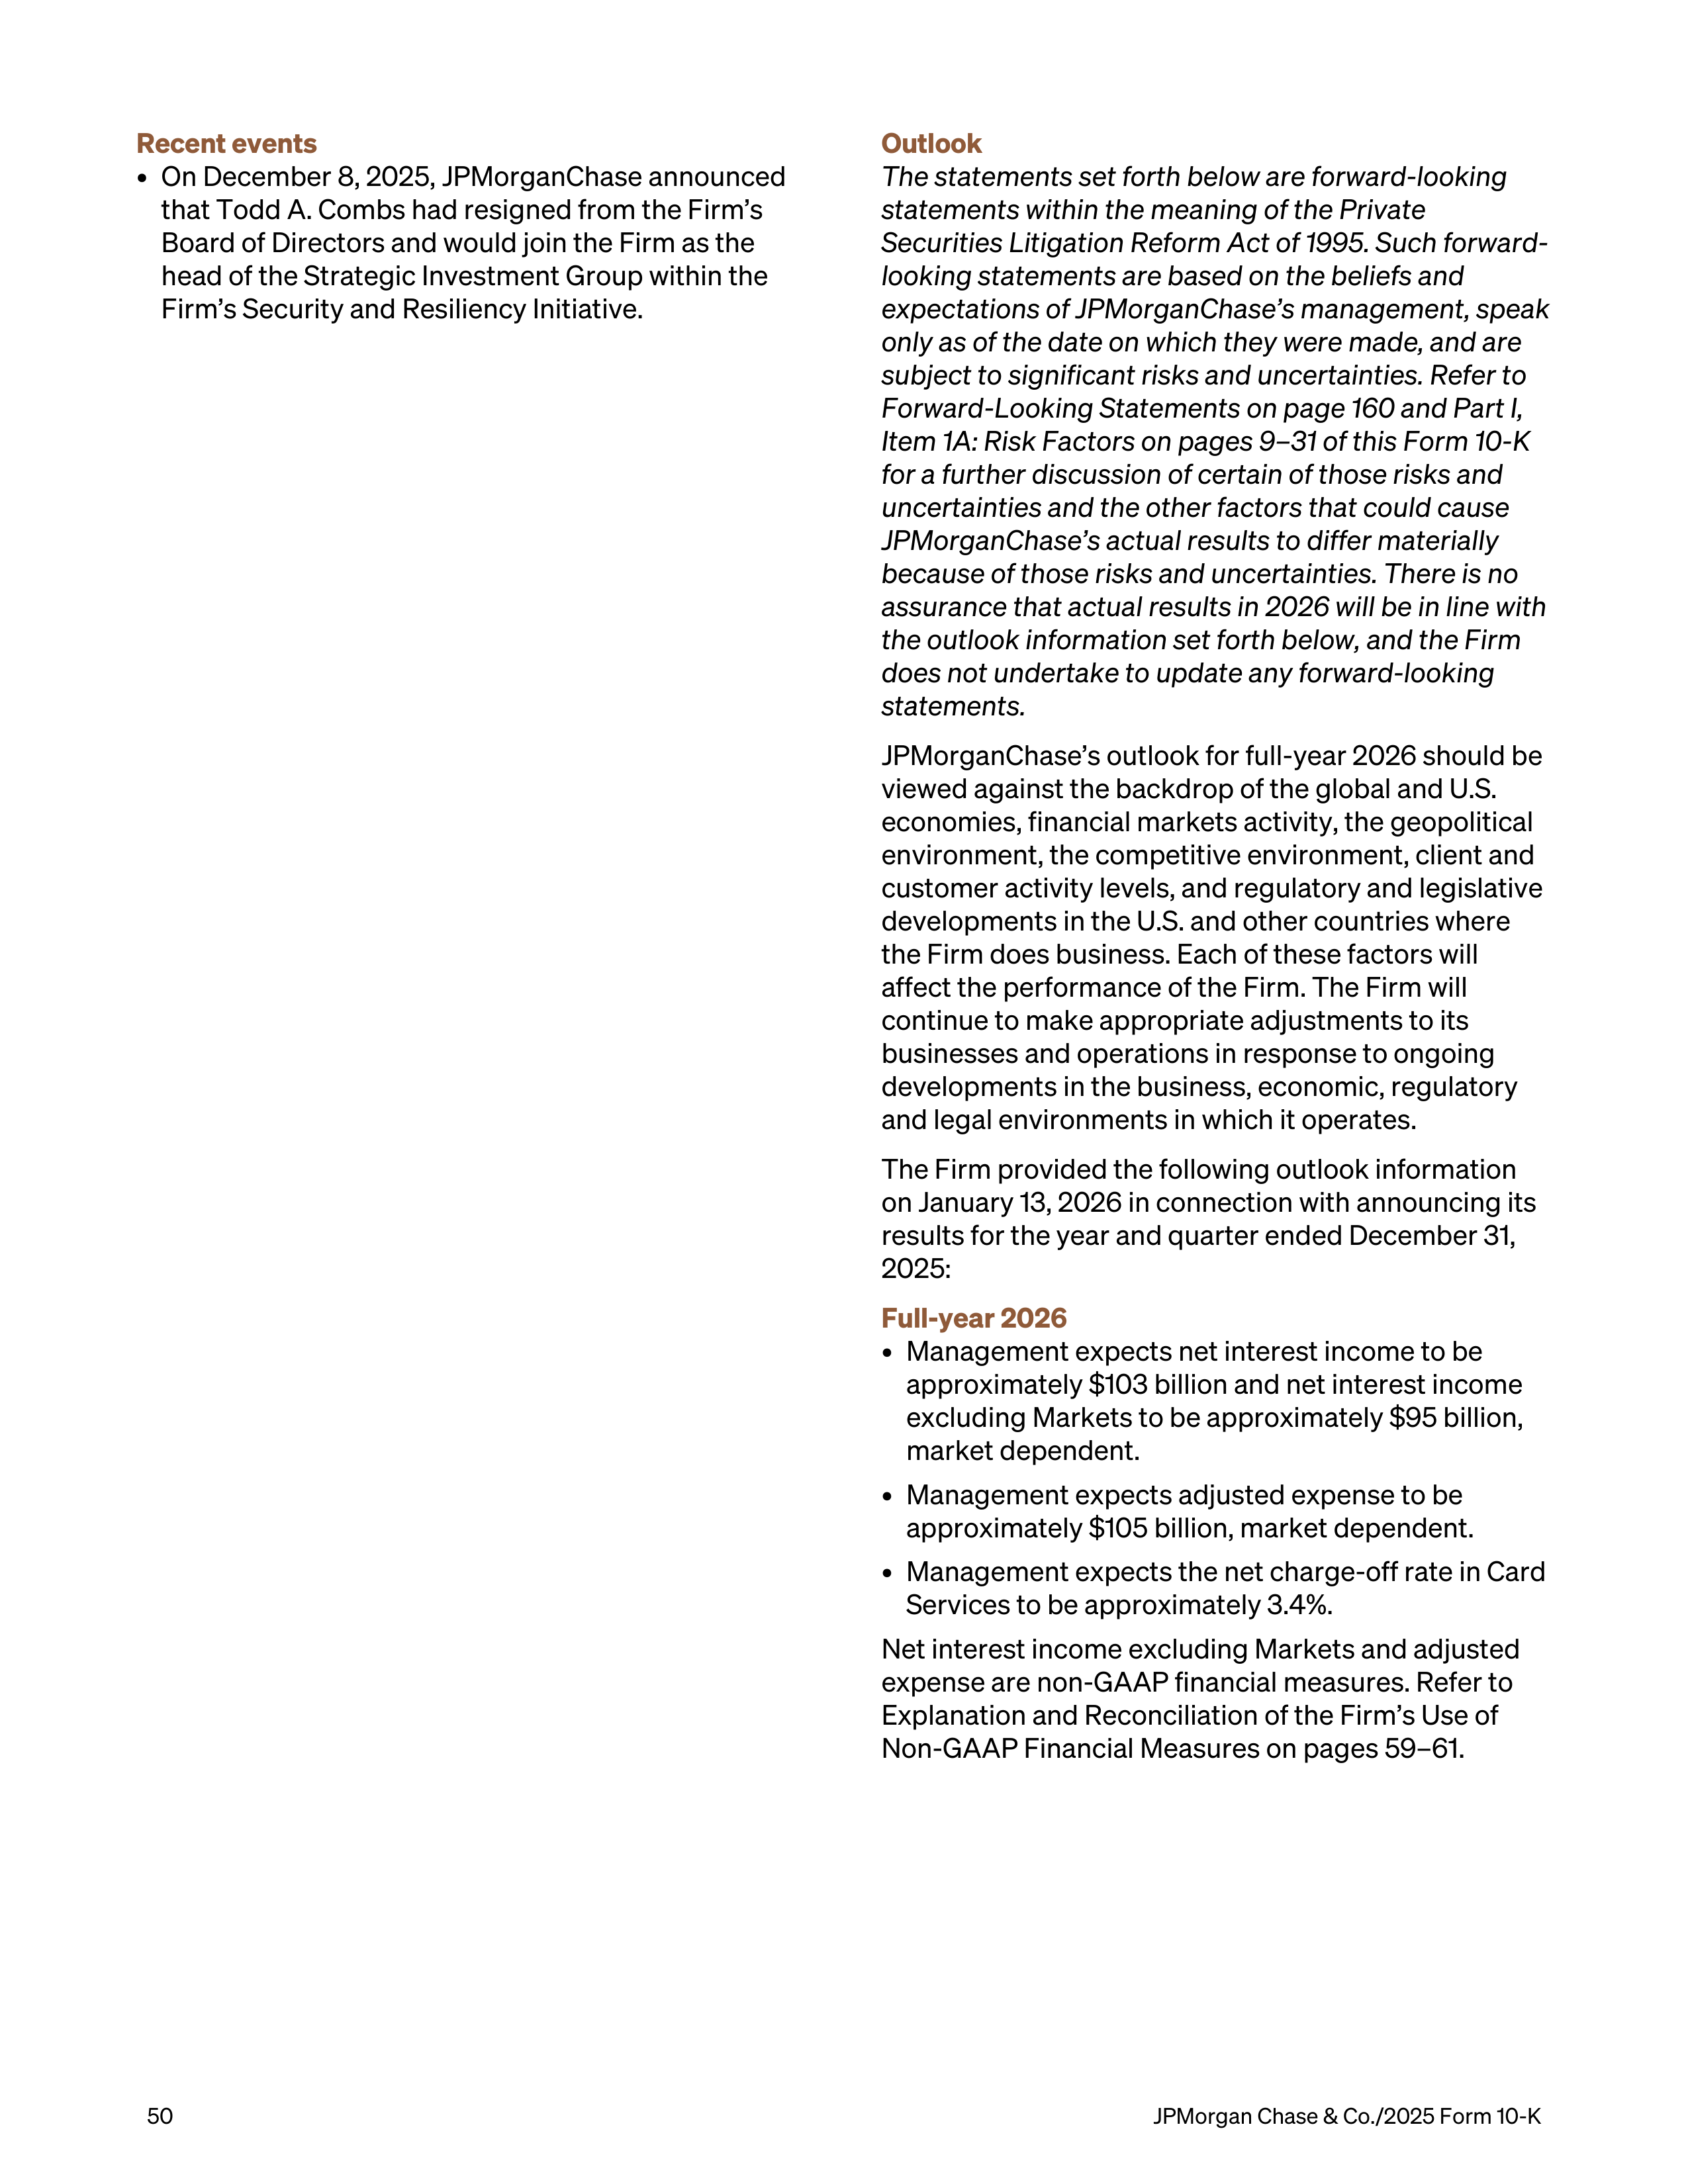
Recent events
•
On December 8, 2025, JPMorganChase announced
that Todd A. Combs had resigned from the Firm’s
Board of Directors and would join the Firm as the
head of the Strategic Investment Group within the
Firm’s Security and Resiliency Initiative.
Outlook
The statements set forth below are forward-looking
statements within the meaning of the Private
Securities Litigation Reform Act of 1995. Such forward-
looking statements are based on the beliefs and
expectations of JPMorganChase’s management, speak
only as of the date on which they were made, and are
subject to significant risks and uncertainties. Refer to
Forward-Looking Statements on page 160 and Part I,
Item 1A: Risk Factors on pages 9–31 of this Form 10-K
for a further discussion of certain of those risks and
uncertainties and the other factors that could cause
JPMorganChase’s actual results to differ materially
because of those risks and uncertainties. There is no
assurance that actual results in 2026 will be in line with
the outlook information set forth below, and the Firm
does not undertake to update any forward-looking
statements.
JPMorganChase’s outlook for full-year 2026 should be
viewed against the backdrop of the global and U.S.
economies, financial markets activity, the geopolitical
environment, the competitive environment, client and
customer activity levels, and regulatory and legislative
developments in the U.S. and other countries where
the Firm does business. Each of these factors will
affect the performance of the Firm. The Firm will
continue to make appropriate adjustments to its
businesses and operations in response to ongoing
developments in the business, economic, regulatory
and legal environments in which it operates.
The Firm provided the following outlook information
on January 13, 2026 in connection with announcing its
results for the year and quarter ended December 31,
2025:
Full-year 2026
•
Management expects net interest income to be
approximately $103 billion and net interest income
excluding Markets to be approximately $95 billion,
market dependent.
•
Management expects adjusted expense to be
approximately $105 billion, market dependent.
•
Management expects the net charge-off rate in Card
Services to be approximately 3.4%.
Net interest income excluding Markets and adjusted
expense are non-GAAP financial measures. Refer to
Explanation and Reconciliation of the Firm’s Use of
Non-GAAP Financial Measures on pages 59–61.
50
JPMorgan Chase & Co./2025 Form 10-K
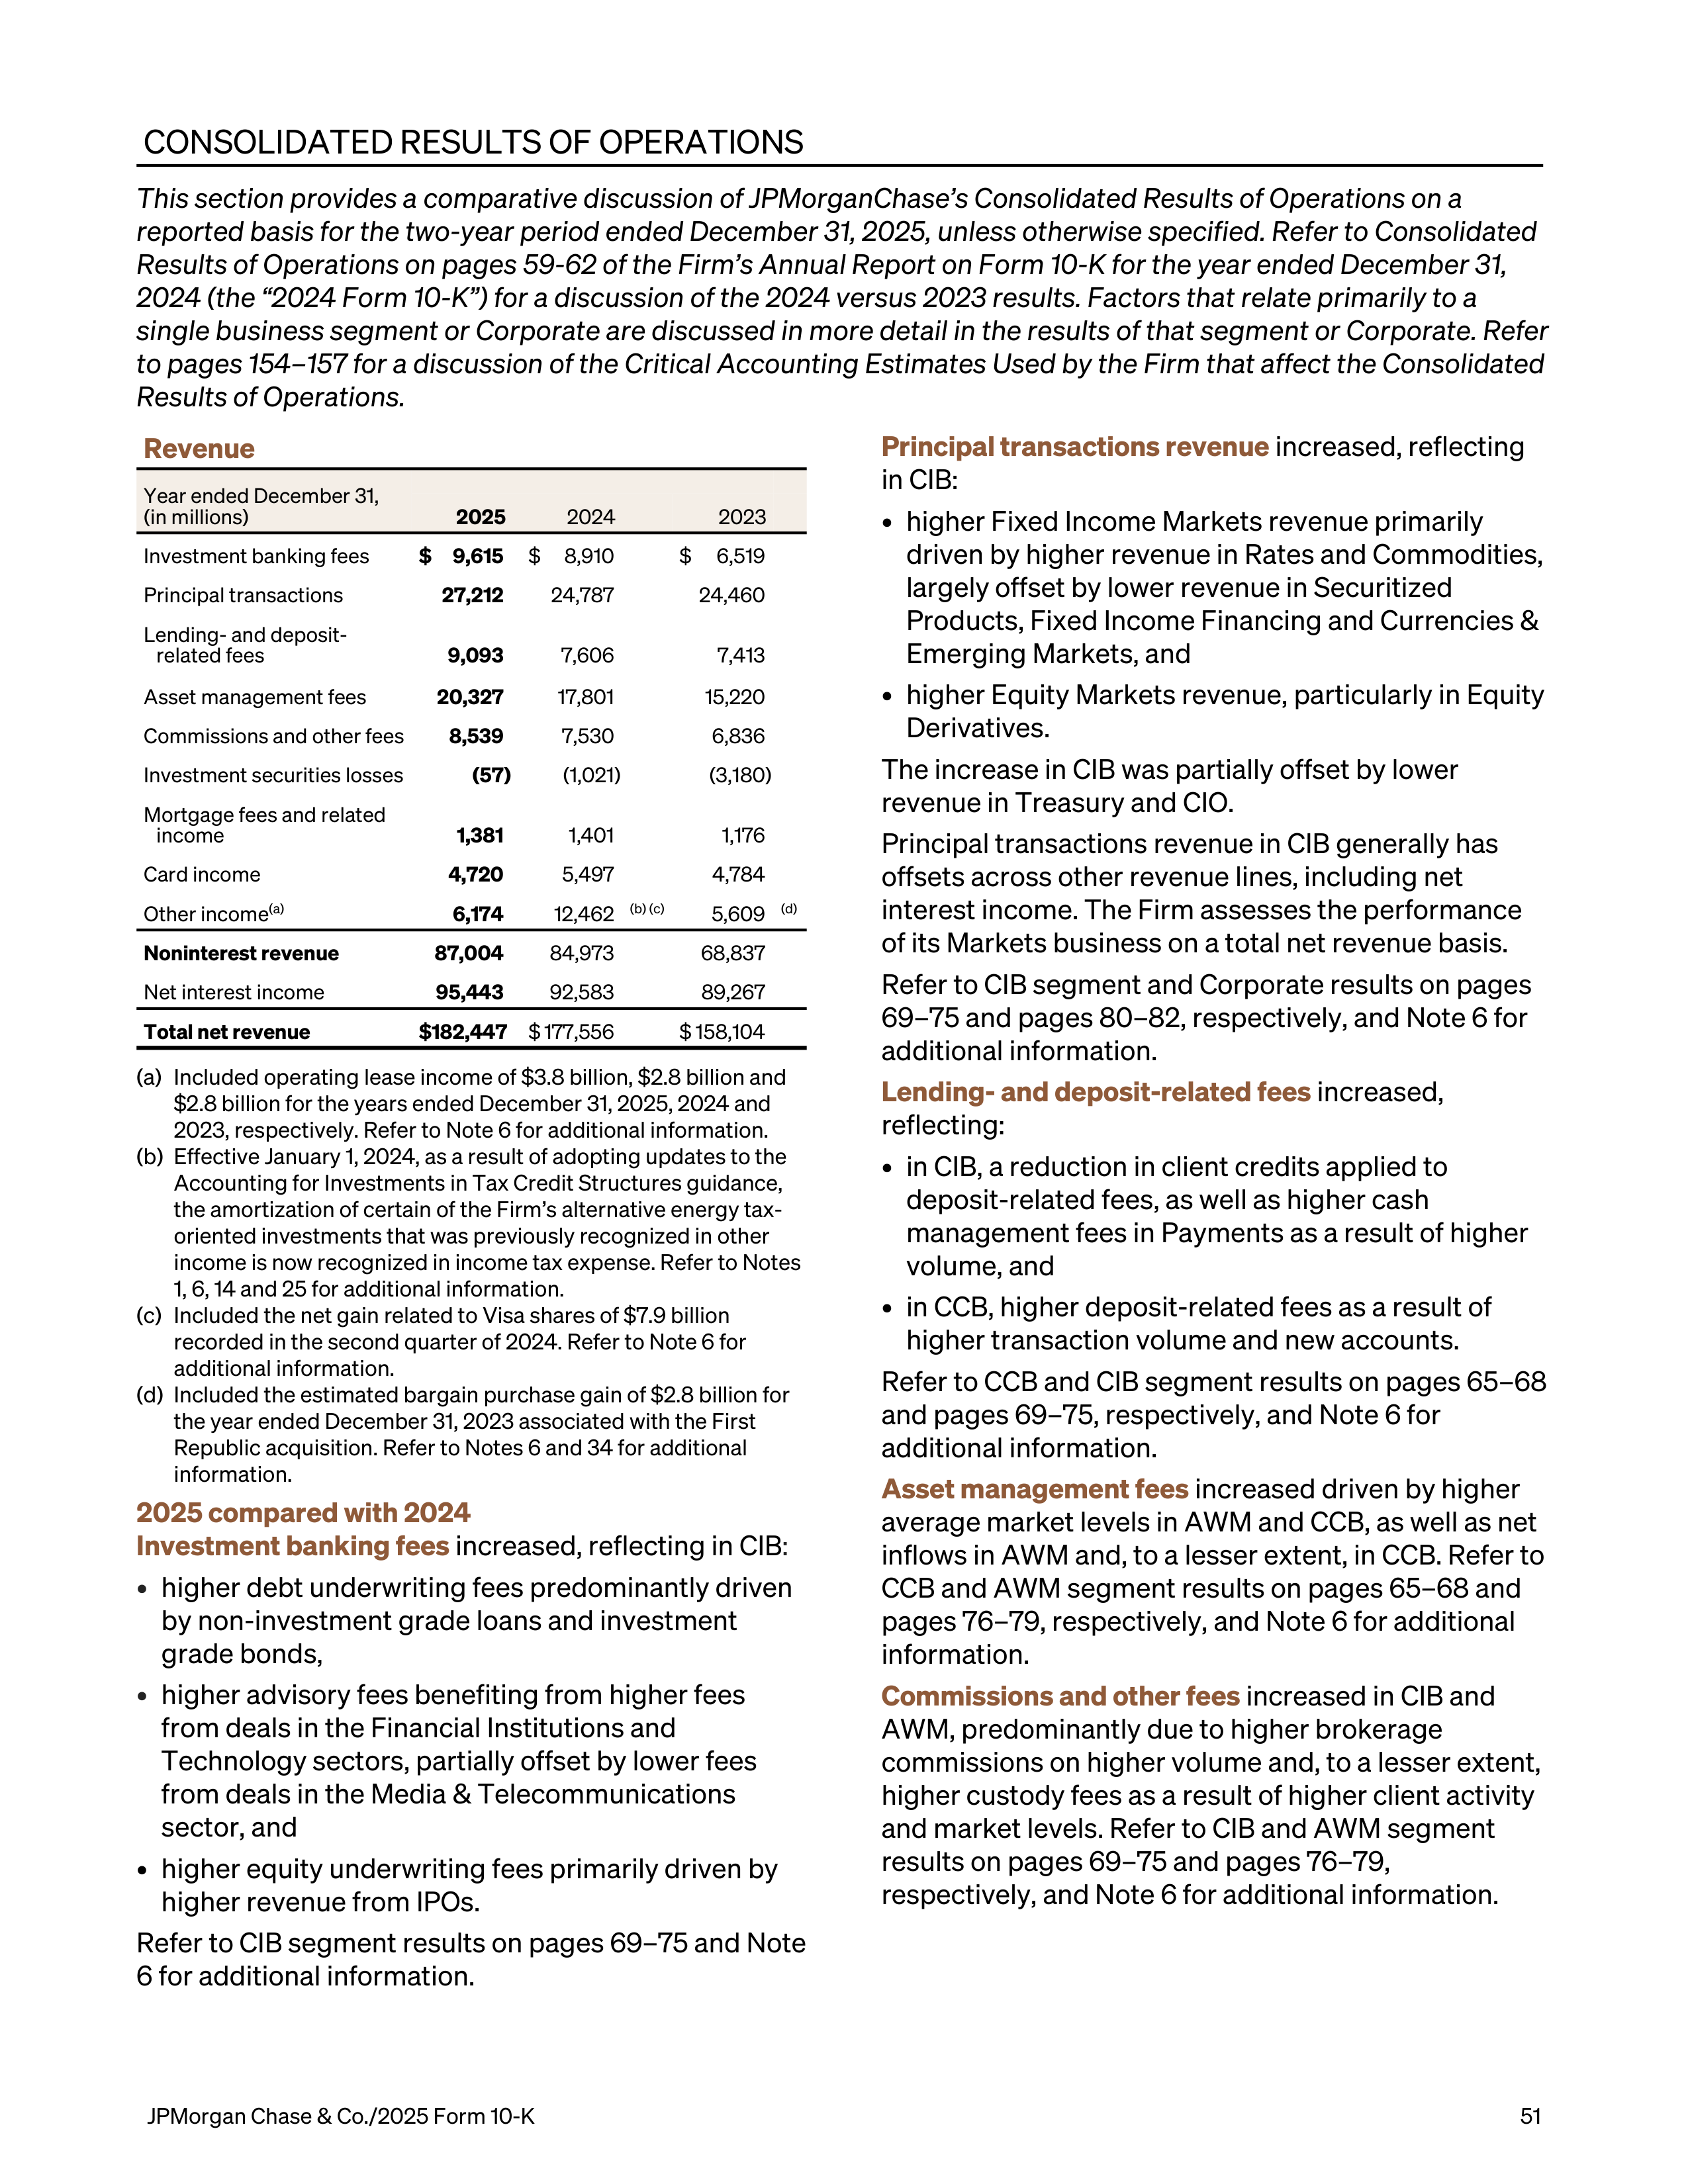
CONSOLIDATED RESULTS OF OPERATIONS
This section provides a comparative discussion of JPMorganChase’s Consolidated Results of Operations on a
reported basis for the two-year period ended December 31, 2025, unless otherwise specified. Refer to Consolidated
Results of Operations on pages 59-62 of the Firm’s Annual Report on Form 10-K for the year ended December 31,
2024 (the “2024 Form 10-K”) for a discussion of the 2024 versus 2023 results. Factors that relate primarily to a
single business segment or Corporate are discussed in more detail in the results of that segment or Corporate. Refer
to pages 154–157 for a discussion of the Critical Accounting Estimates Used by the Firm that affect the Consolidated
Results of Operations.
Revenue
Year ended December 31,
(in millions)
2025
2024
2023
Investment banking fees
$
9,615
$
8,910
$
6,519
Principal transactions
27,212
24,787
24,460
Lending- and deposit-
related fees
9,093
7,606
7,413
Asset management fees
20,327
17,801
15,220
Commissions and other fees
8,539
7,530
6,836
Investment securities losses
(57)
(1,021)
(3,180)
Mortgage fees and related
income
1,381
1,401
1,176
Card income
4,720
5,497
4,784
Other income
(a)
6,174
12,462
(b) (c)
5,609
(d)
Noninterest revenue
87,004
84,973
68,837
Net interest income
95,443
92,583
89,267
Total net revenue
$ 182,447
$ 177,556
$ 158,104
(a)
Included operating lease income of $3.8 billion, $2.8 billion and
$2.8 billion for the years ended December 31, 2025, 2024 and
2023, respectively. Refer to Note 6 for additional information.
(b)
Effective January 1, 2024, as a result of adopting updates to the
Accounting for Investments in Tax Credit Structures guidance,
the amortization of certain of the Firm’s alternative energy tax-
oriented investments that was previously recognized in other
income is now recognized in income tax expense. Refer to Notes
1, 6, 14 and 25 for additional information.
(c)
Included the net gain related to Visa shares of $7.9 billion
recorded in the second quarter of 2024. Refer to Note 6 for
additional information.
(d)
Included the estimated bargain purchase gain of $2.8 billion for
the year ended December 31, 2023 associated with the First
Republic acquisition. Refer to Notes 6 and 34 for additional
information.
2025 compared with 2024
Investment banking fees
increased, reflecting in CIB
:
•
higher debt underwriting fees predominantly driven
by non-investment grade loans and investment
grade bonds,
•
higher advisory fees benefiting from higher fees
from deals in the Financial Institutions and
Technology sectors, partially offset by lower fees
from deals in the Media & Telecommunications
sector, and
•
higher equity underwriting fees primarily driven by
higher revenue from IPOs.
Refer to CIB segment results on pages 69–75 and Note
6 for additional information.
Principal transactions revenue
increased, reflecting
in CIB:
•
higher Fixed Income Markets revenue primarily
driven by higher revenue in Rates and Commodities,
largely offset by lower revenue in Securitized
Products, Fixed Income Financing and Currencies &
Emerging Markets, and
•
higher Equity Markets revenue, particularly in Equity
Derivatives.
The increase in CIB was partially offset by lower
revenue in Treasury and CIO.
Principal transactions revenue in CIB generally has
offsets across other revenue lines, including net
interest income. The Firm assesses the performance
of its Markets business on a total net revenue basis.
Refer to CIB segment and Corporate results on pages
69–75 and pages 80–82, respectively, and Note 6 for
additional information.
Lending- and deposit-related fees
increased,
reflecting:
•
in CIB, a reduction in client credits applied to
deposit-related fees, as well as higher cash
management fees in Payments as a result of higher
volume, and
•
in CCB, higher deposit-related fees as a result of
higher transaction volume and new accounts.
Refer to CCB and CIB segment results on pages 65–68
and pages 69–75, respectively, and Note 6 for
additional information.
Asset management fees
increased driven by higher
average market levels in AWM and CCB, as well as net
inflows in AWM and, to a lesser extent, in CCB. Refer to
CCB and AWM segment results on pages 65–68 and
pages 76–79, respectively, and Note 6 for additional
information.
Commissions and other fees
increased in CIB and
AWM, predominantly due to higher brokerage
commissions on higher volume and, to a lesser extent,
higher custody fees as a result of higher client activity
and market levels. Refer to CIB and AWM segment
results on pages 69–75 and pages 76–79,
respectively, and Note 6 for additional information.
JPMorgan Chase & Co./2025 Form 10-K
51
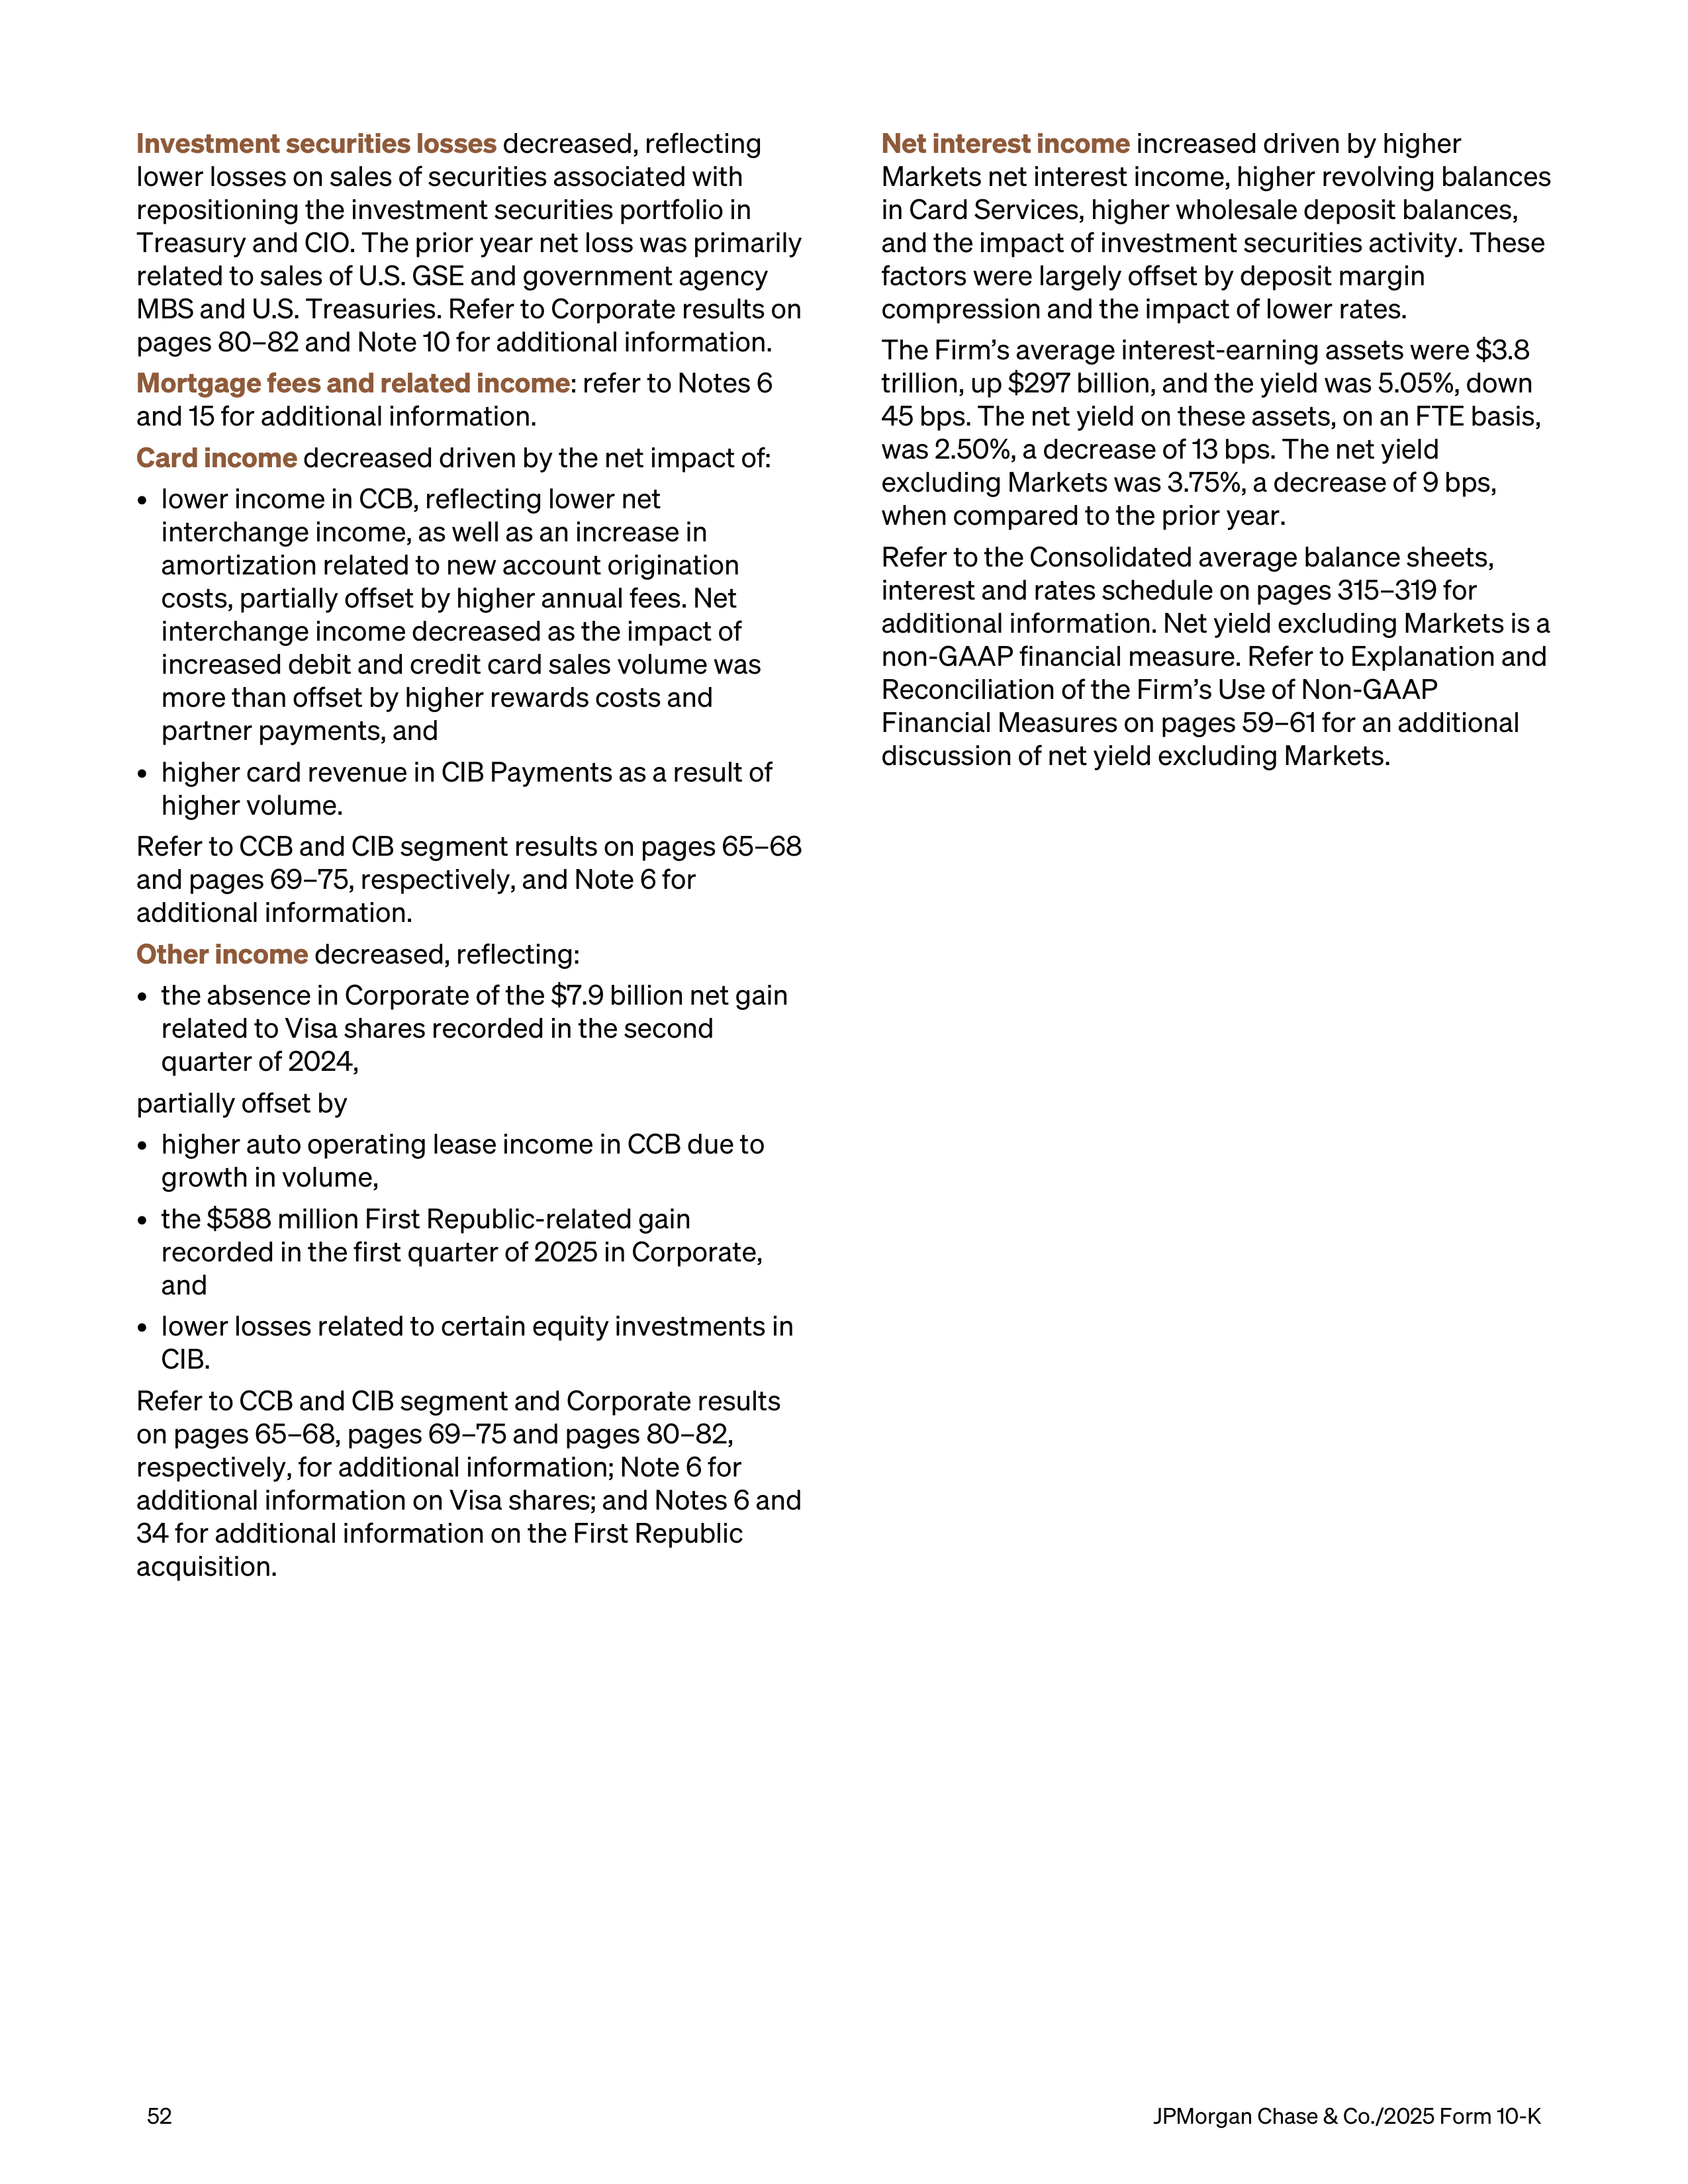
Investment securities losses
decreased, reflecting
lower losses on sales of securities associated with
repositioning the investment securities portfolio in
Treasury and CIO. The prior year net loss was primarily
related to sales of U.S. GSE and government agency
MBS and U.S. Treasuries. Refer to Corporate results on
pages 80–82 and Note 10 for additional information.
Mortgage fees and related income
: refer to Notes 6
and 15 for additional information.
Card income
decreased driven by the net impact of:
•
lower income in CCB, reflecting lower net
interchange income, as well as an increase in
amortization related to new account origination
costs, partially offset by higher annual fees. Net
interchange income decreased as the impact of
increased debit and credit card sales volume was
more than offset by higher rewards costs and
partner payments, and
•
higher card revenue in CIB Payments as a result of
higher volume.
Refer to CCB and CIB segment results on pages 65–68
and pages 69–75, respectively, and Note 6 for
additional information.
Other income
decreased, reflecting:
•
the absence in Corporate of the $7.9 billion net gain
related to Visa shares recorded in the second
quarter of 2024,
partially offset by
•
higher auto operating lease income in CCB due to
growth in volume,
•
the $588 million First Republic-related gain
recorded in the first quarter of 2025 in Corporate,
and
•
lower losses related to certain equity investments in
CIB.
Refer to CCB and CIB segment and Corporate results
on pages 65–68, pages 69–75 and pages 80–82,
respectively, for additional information; Note 6 for
additional information on Visa shares; and Notes 6 and
34 for additional information on the First Republic
acquisition.
Net interest income
increased driven by higher
Markets net interest income, higher revolving balances
in Card Services, higher wholesale deposit balances,
and the impact of investment securities activity. These
factors were largely offset by deposit margin
compression and the impact of lower rates.
The Firm’s average interest-earning assets were $3.8
trillion, up $297 billion, and the yield was 5.05%, down
45 bps. The net yield on these assets, on an FTE basis,
was 2.50%, a decrease of 13 bps. The net yield
excluding Markets was 3.75%, a decrease of 9 bps,
when compared to the prior year.
Refer to the Consolidated average balance sheets,
interest and rates schedule on pages 315–319 for
additional information. Net yield excluding Markets is a
non-GAAP financial measure. Refer to Explanation and
Reconciliation of the Firm’s Use of Non-GAAP
Financial Measures on pages 59–61 for an additional
discussion of net yield excluding Markets.
52
JPMorgan Chase & Co./2025 Form 10-K
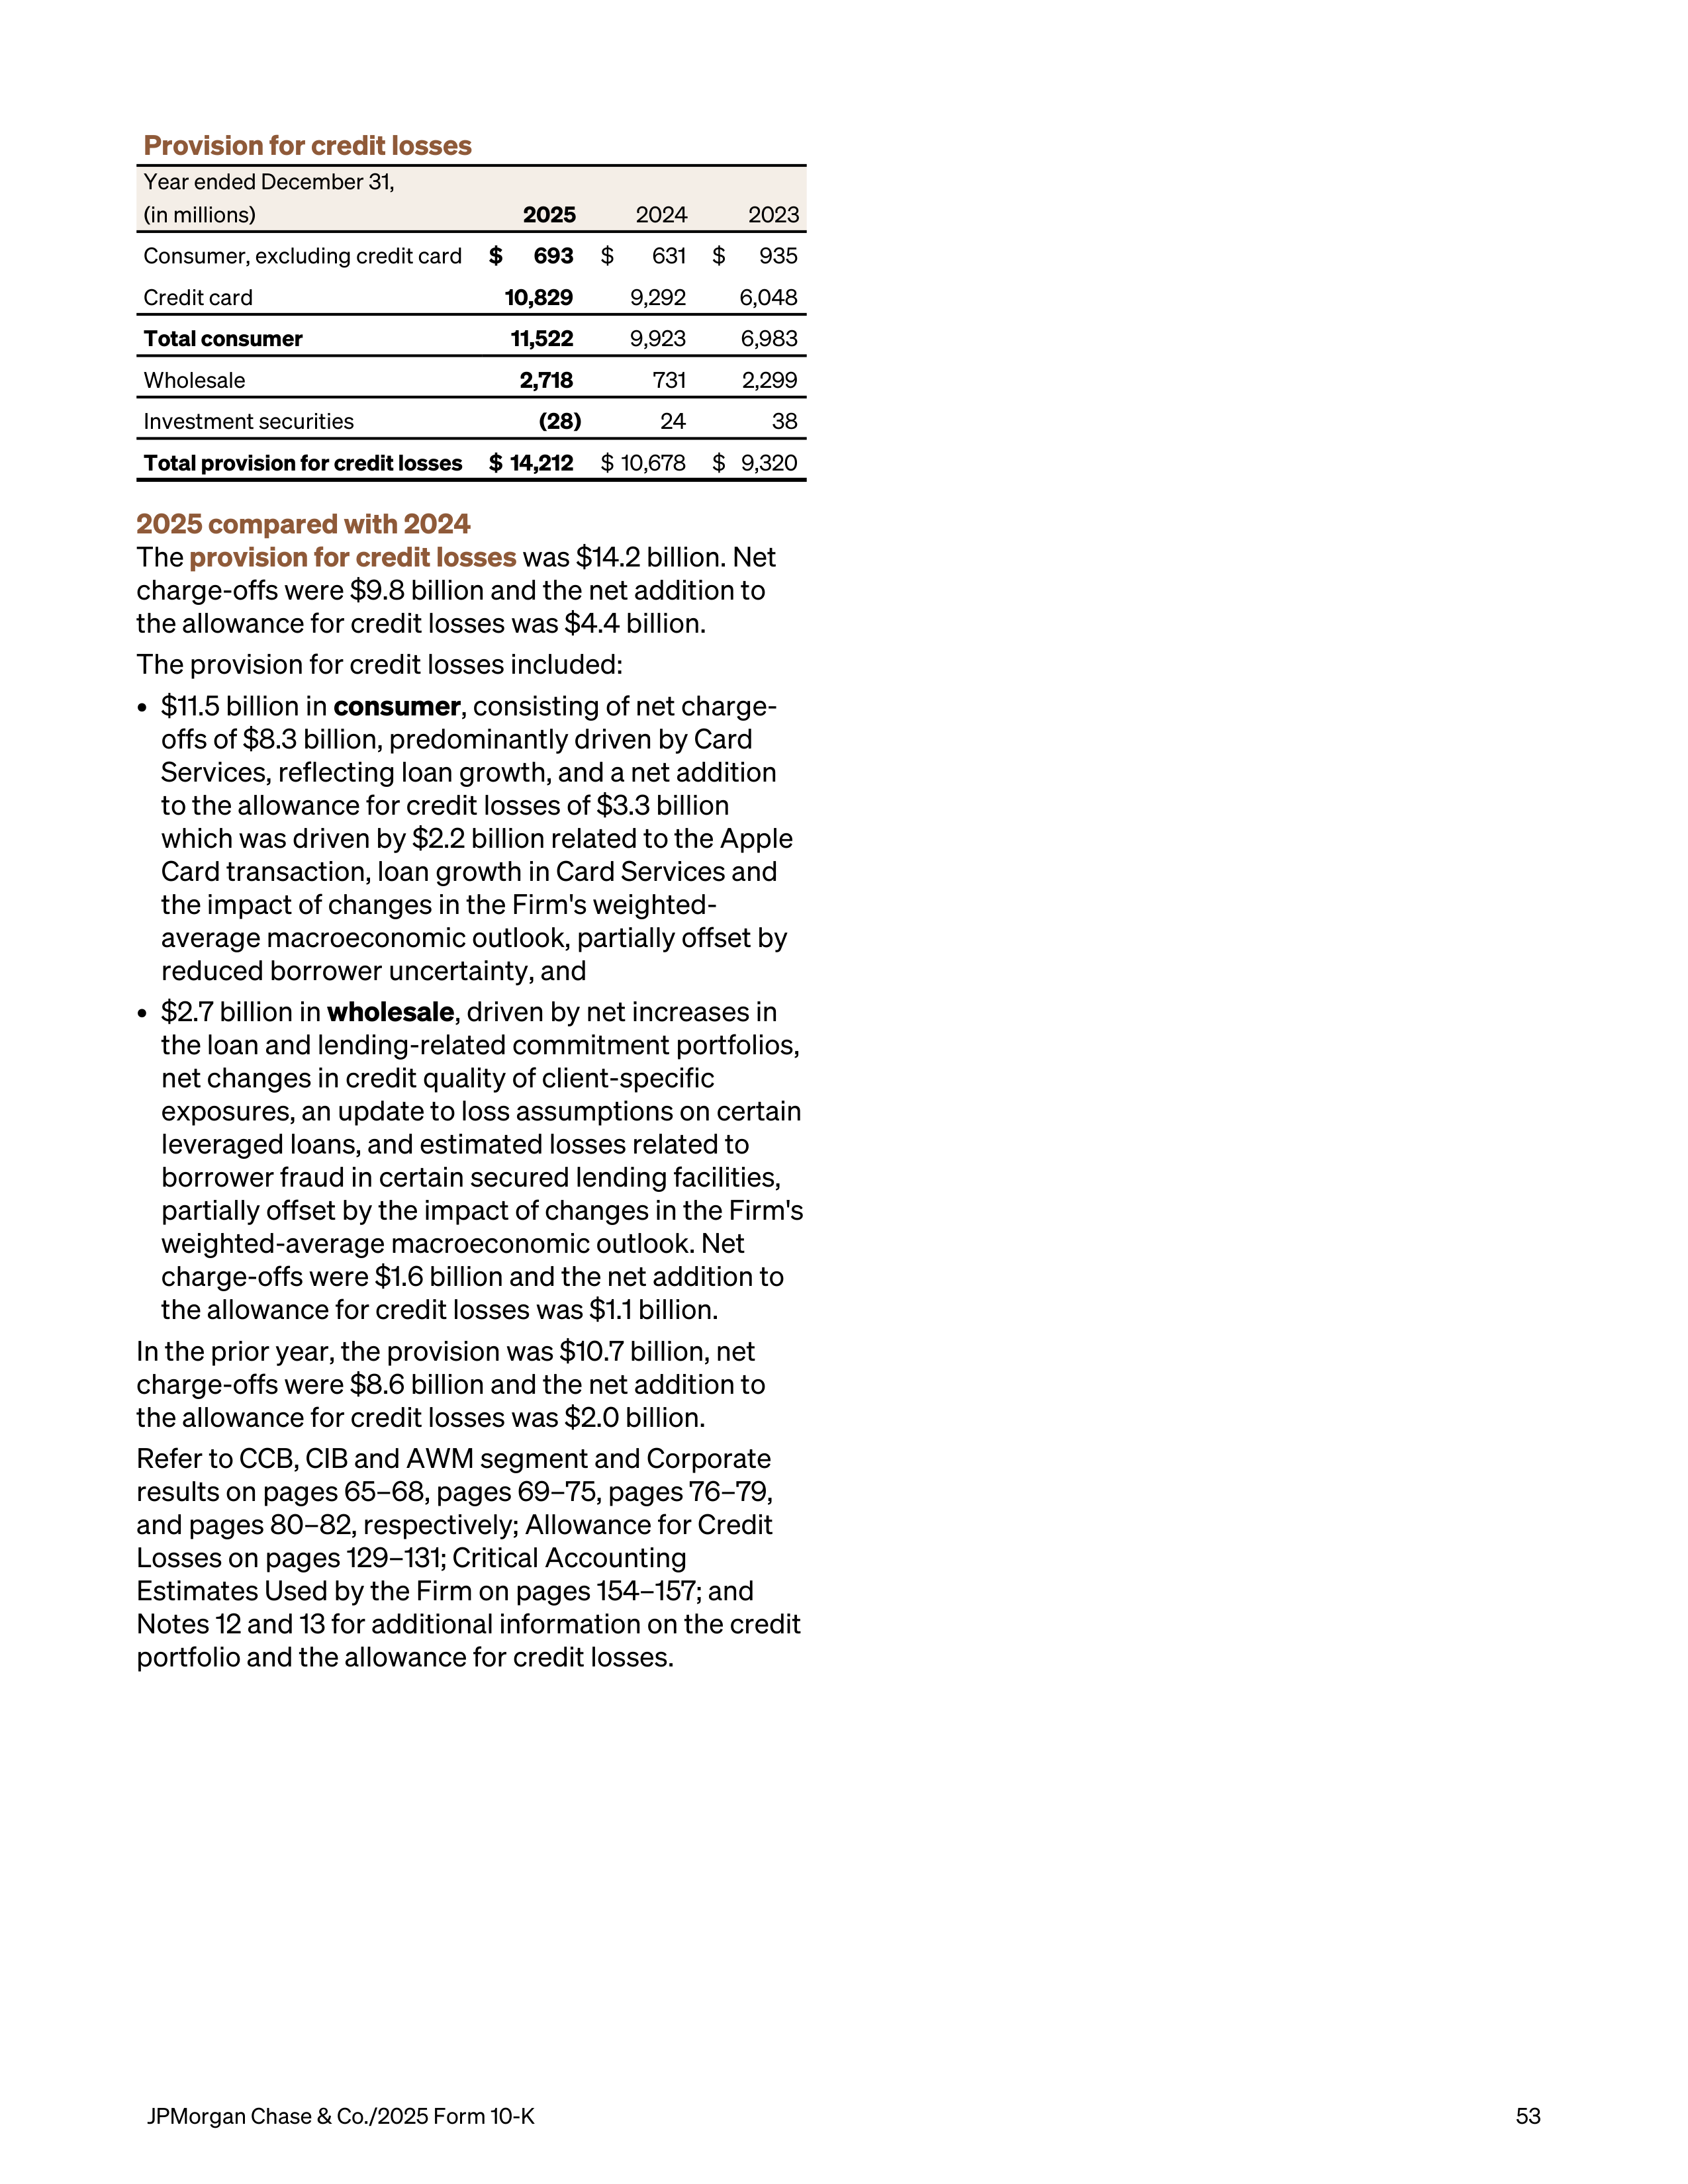
Provision for credit losses
Year ended December 31,
(in millions)
2025
2024
2023
Consumer, excluding credit card
$
693
$
631
$
935
Credit card
10,829
9,292
6,048
Total consumer
11,522
9,923
6,983
Wholesale
2,718
731
2,299
Investment securities
(28)
24
38
Total provision for credit losses
$ 14,212
$ 10,678
$ 9,320
2025 compared with 2024
The
provision for credit losses
was $14.2 billion. Net
charge-offs were $9.8 billion and the net addition to
the allowance for credit losses was $4.4 billion.
The provision for credit losses included:
•
$11.5 billion in
consumer
, consisting of net charge-
offs of $8.3 billion, predominantly driven by Card
Services, reflecting loan growth, and a net addition
to the allowance for credit losses of $3.3 billion
which was driven by $2.2 billion related to the Apple
Card transaction, loan growth in Card Services and
the impact of changes in the Firm's weighted-
average macroeconomic outlook, partially offset by
reduced borrower uncertainty, and
•
$2.7 billion in
wholesale
, driven by net increases in
the loan and lending-related commitment portfolios,
net changes in credit quality of client-specific
exposures, an update to loss assumptions on certain
leveraged loans, and estimated losses related to
borrower fraud in certain secured lending facilities,
partially offset by the impact of changes in the Firm's
weighted-average macroeconomic outlook. Net
charge-offs were $1.6 billion and the net addition to
the allowance for credit losses was $1.1 billion.
In the prior year, the provision was $10.7 billion, net
charge-offs were $8.6 billion and the net addition to
the allowance for credit losses was $2.0 billion.
Refer to CCB, CIB and AWM segment and Corporate
results on pages 65–68, pages 69–75, pages 76–79,
and pages 80–82, respectively; Allowance for Credit
Losses on pages 129–131; Critical Accounting
Estimates Used by the Firm on pages 154–157; and
Notes 12 and 13 for additional information on the credit
portfolio and the allowance for credit losses.
JPMorgan Chase & Co./2025 Form 10-K
53
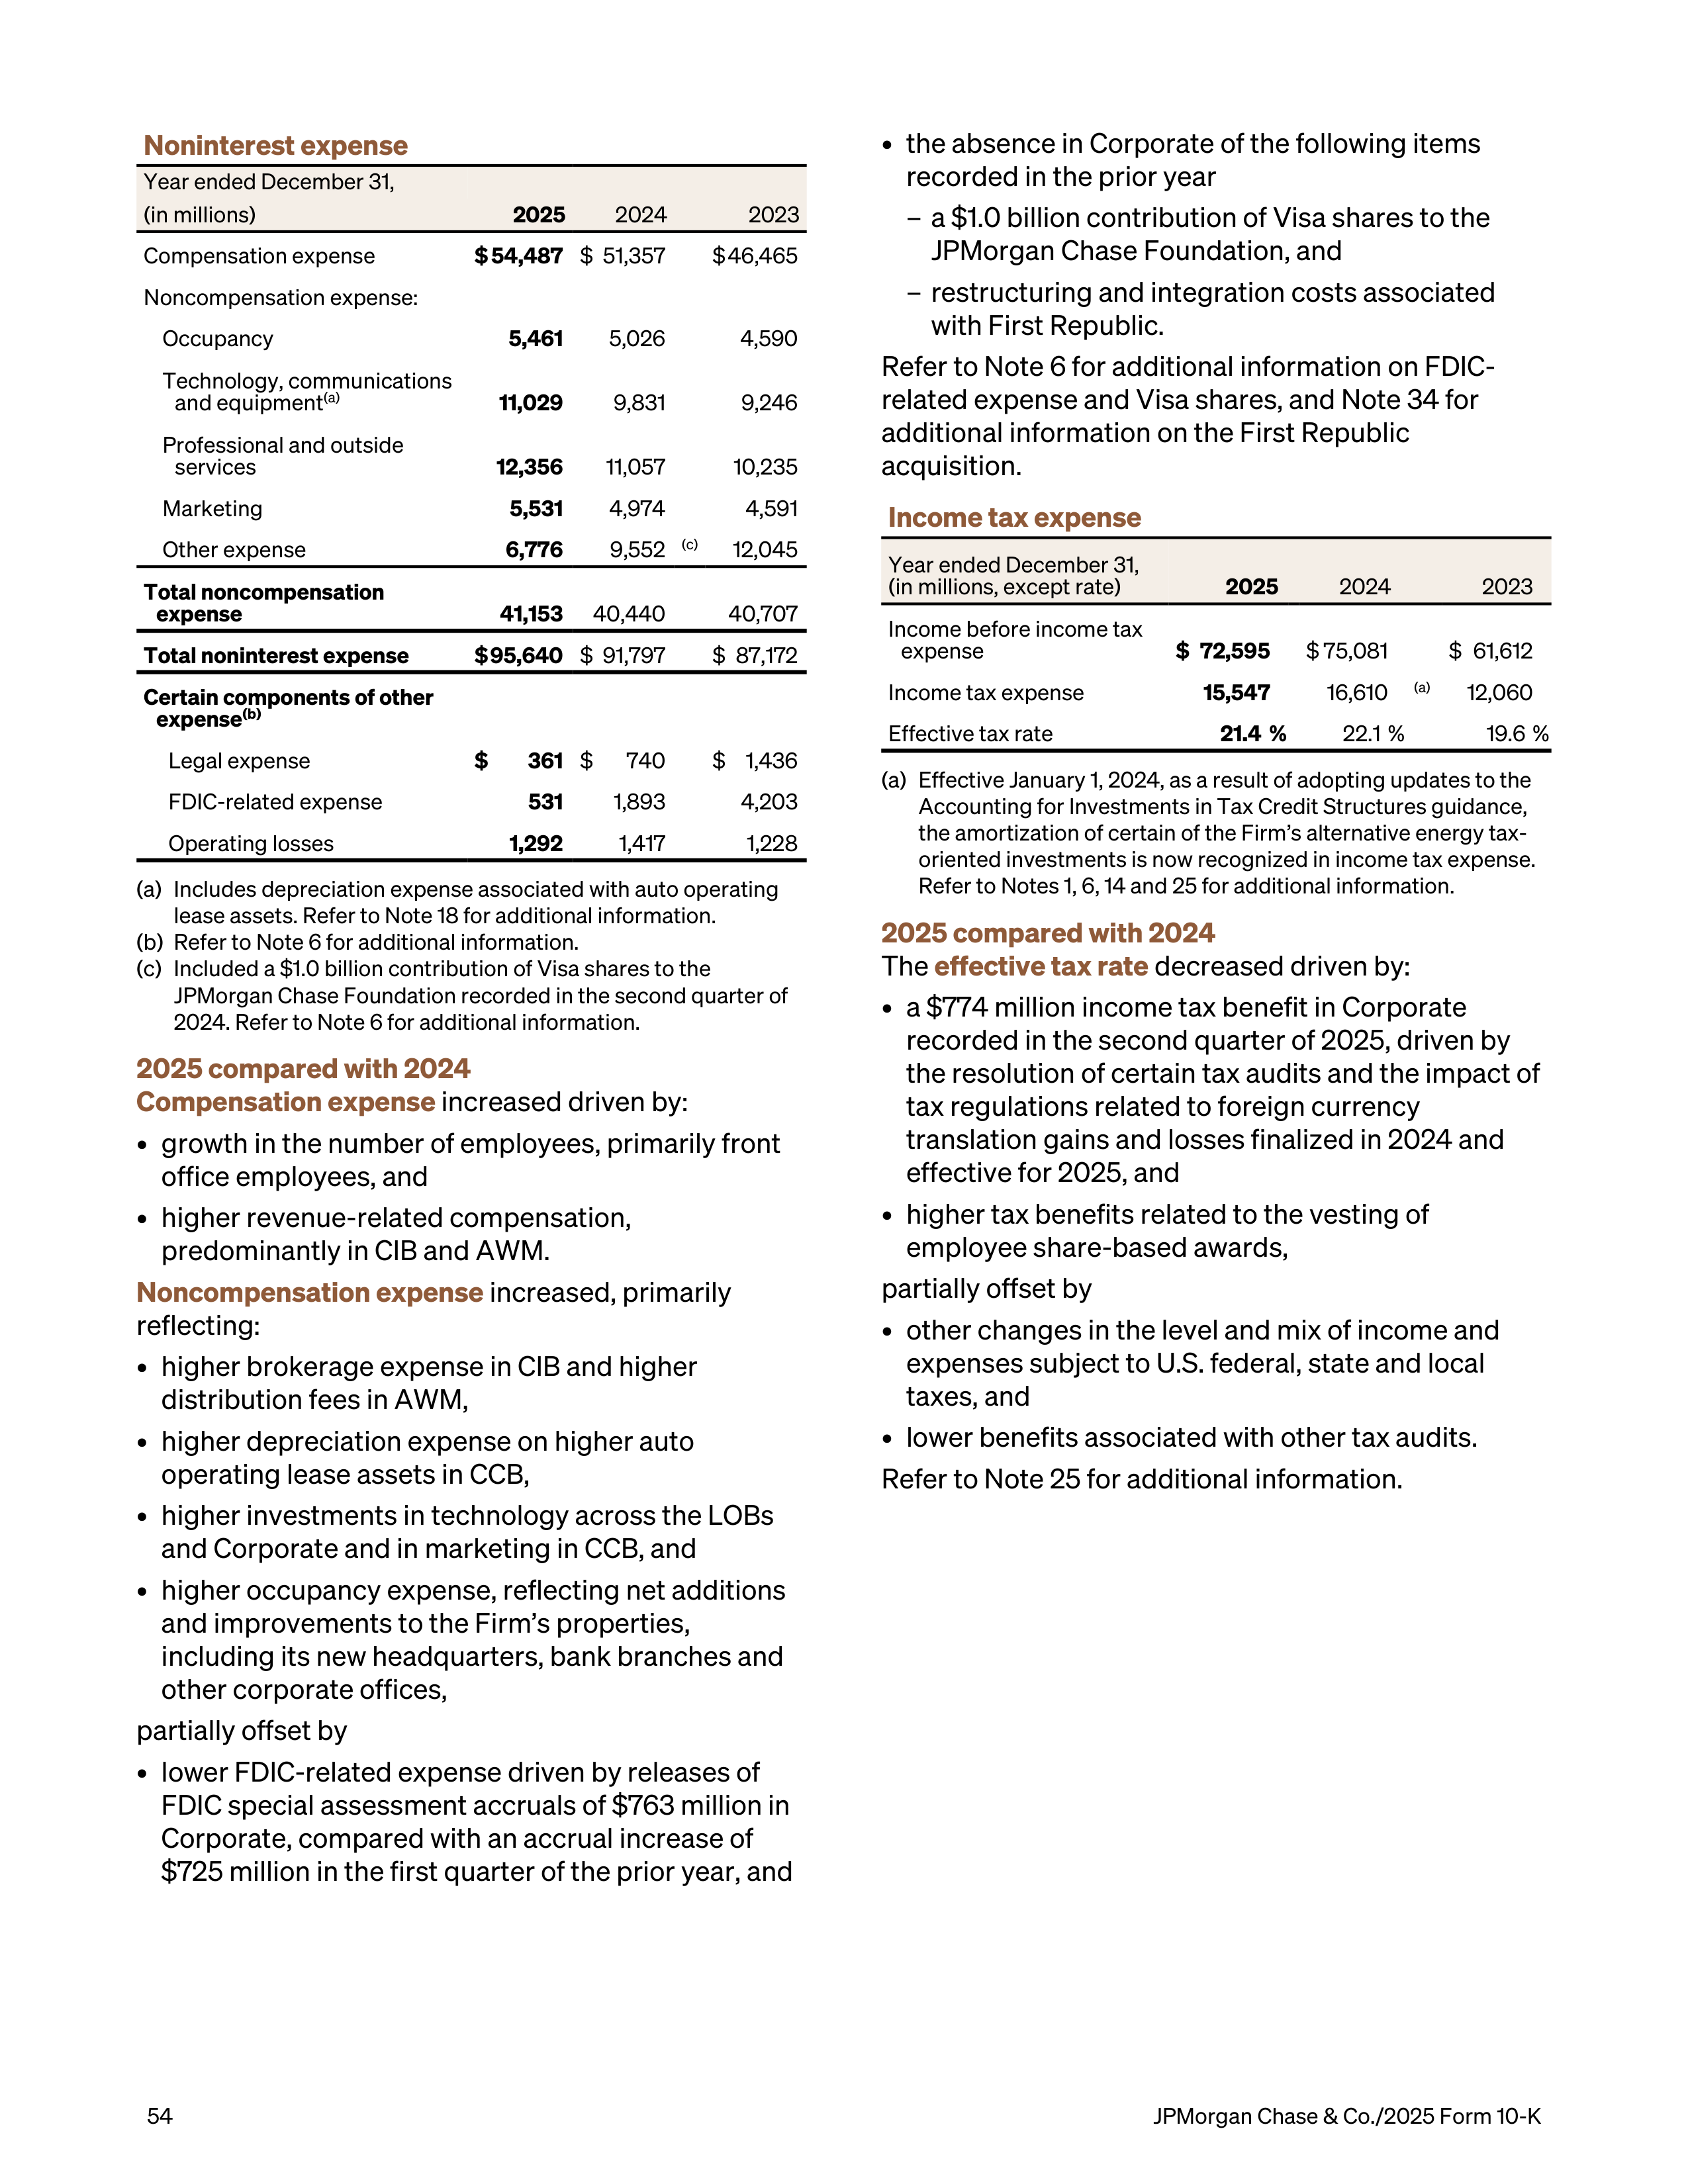
Noninterest expense
Year ended December 31,
(in millions)
2025
2024
2023
Compensation expense
$ 54,487
$ 51,357
$ 46,465
Noncompensation expense:
Occupancy
5,461
5,026
4,590
Technology, communications
and equipment
(a)
11,029
9,831
9,246
Professional and outside
services
12,356
11,057
10,235
Marketing
5,531
4,974
4,591
Other expense
6,776
9,552
(c)
12,045
Total noncompensation
expense
41,153
40,440
40,707
Total noninterest expense
$ 95,640
$ 91,797
$ 87,172
Certain components of other
expense
(b)
Legal expense
$
361
$
740
$ 1,436
FDIC-related expense
531
1,893
4,203
Operating losses
1,292
1,417
1,228
(a)
Includes depreciation expense associated with auto operating
lease assets. Refer to Note 18 for additional information.
(b)
Refer to Note 6 for additional information.
(c)
Included a $1.0 billion contribution of Visa shares to the
JPMorgan Chase Foundation recorded in the second quarter of
2024. Refer to Note 6 for additional information.
2025 compared with 2024
Compensation expense
increased driven by:
•
growth in the number of employees, primarily front
office employees, and
•
higher revenue-related compensation,
predominantly in CIB and AWM.
Noncompensation expense
increased, primarily
reflecting:
•
higher brokerage expense in CIB and higher
distribution fees in AWM,
•
higher depreciation expense on higher auto
operating lease assets in CCB,
•
higher investments in technology across the LOBs
and Corporate and in marketing in CCB, and
•
higher occupancy expense, reflecting net additions
and improvements to the Firm’s properties,
including its new headquarters, bank branches and
other corporate offices,
partially offset by
•
lower FDIC-related expense driven by releases of
FDIC special assessment accruals of $763 million in
Corporate, compared with an accrual increase of
$725 million in the first quarter of the prior year, and
•
the absence in Corporate of the following items
recorded in the prior year
–
a $1.0 billion contribution of Visa shares to the
JPMorgan Chase Foundation, and
–
restructuring and integration costs associated
with First Republic.
Refer to Note 6 for additional information on FDIC-
related expense and Visa shares, and Note 34 for
additional information on the First Republic
acquisition.
Income tax expense
Year ended December 31,
(in millions, except rate)
2025
2024
2023
Income before income tax
expense
$ 72,595
$ 75,081
$ 61,612
Income tax expense
15,547
16,610
(a)
12,060
Effective tax rate
21.4 %
22.1 %
19.6 %
(a)
Effective January 1, 2024, as a result of adopting updates to the
Accounting for Investments in Tax Credit Structures guidance,
the amortization of certain of the Firm’s alternative energy tax-
oriented investments is now recognized in income tax expense.
Refer to Notes 1, 6, 14 and 25 for additional information.
2025 compared with 2024
The
effective tax rate
decreased driven by:
•
a $774 million income tax benefit in Corporate
recorded in the second quarter of 2025, driven by
the resolution of certain tax audits and the impact of
tax regulations related to foreign currency
translation gains and losses finalized in 2024 and
effective for 2025, and
•
higher tax benefits related to the vesting of
employee share-based awards,
partially offset by
•
other changes in the level and mix of income and
expenses subject to U.S. federal, state and local
taxes, and
•
lower benefits associated with other tax audits.
Refer to Note 25 for additional information.
54
JPMorgan Chase & Co./2025 Form 10-K
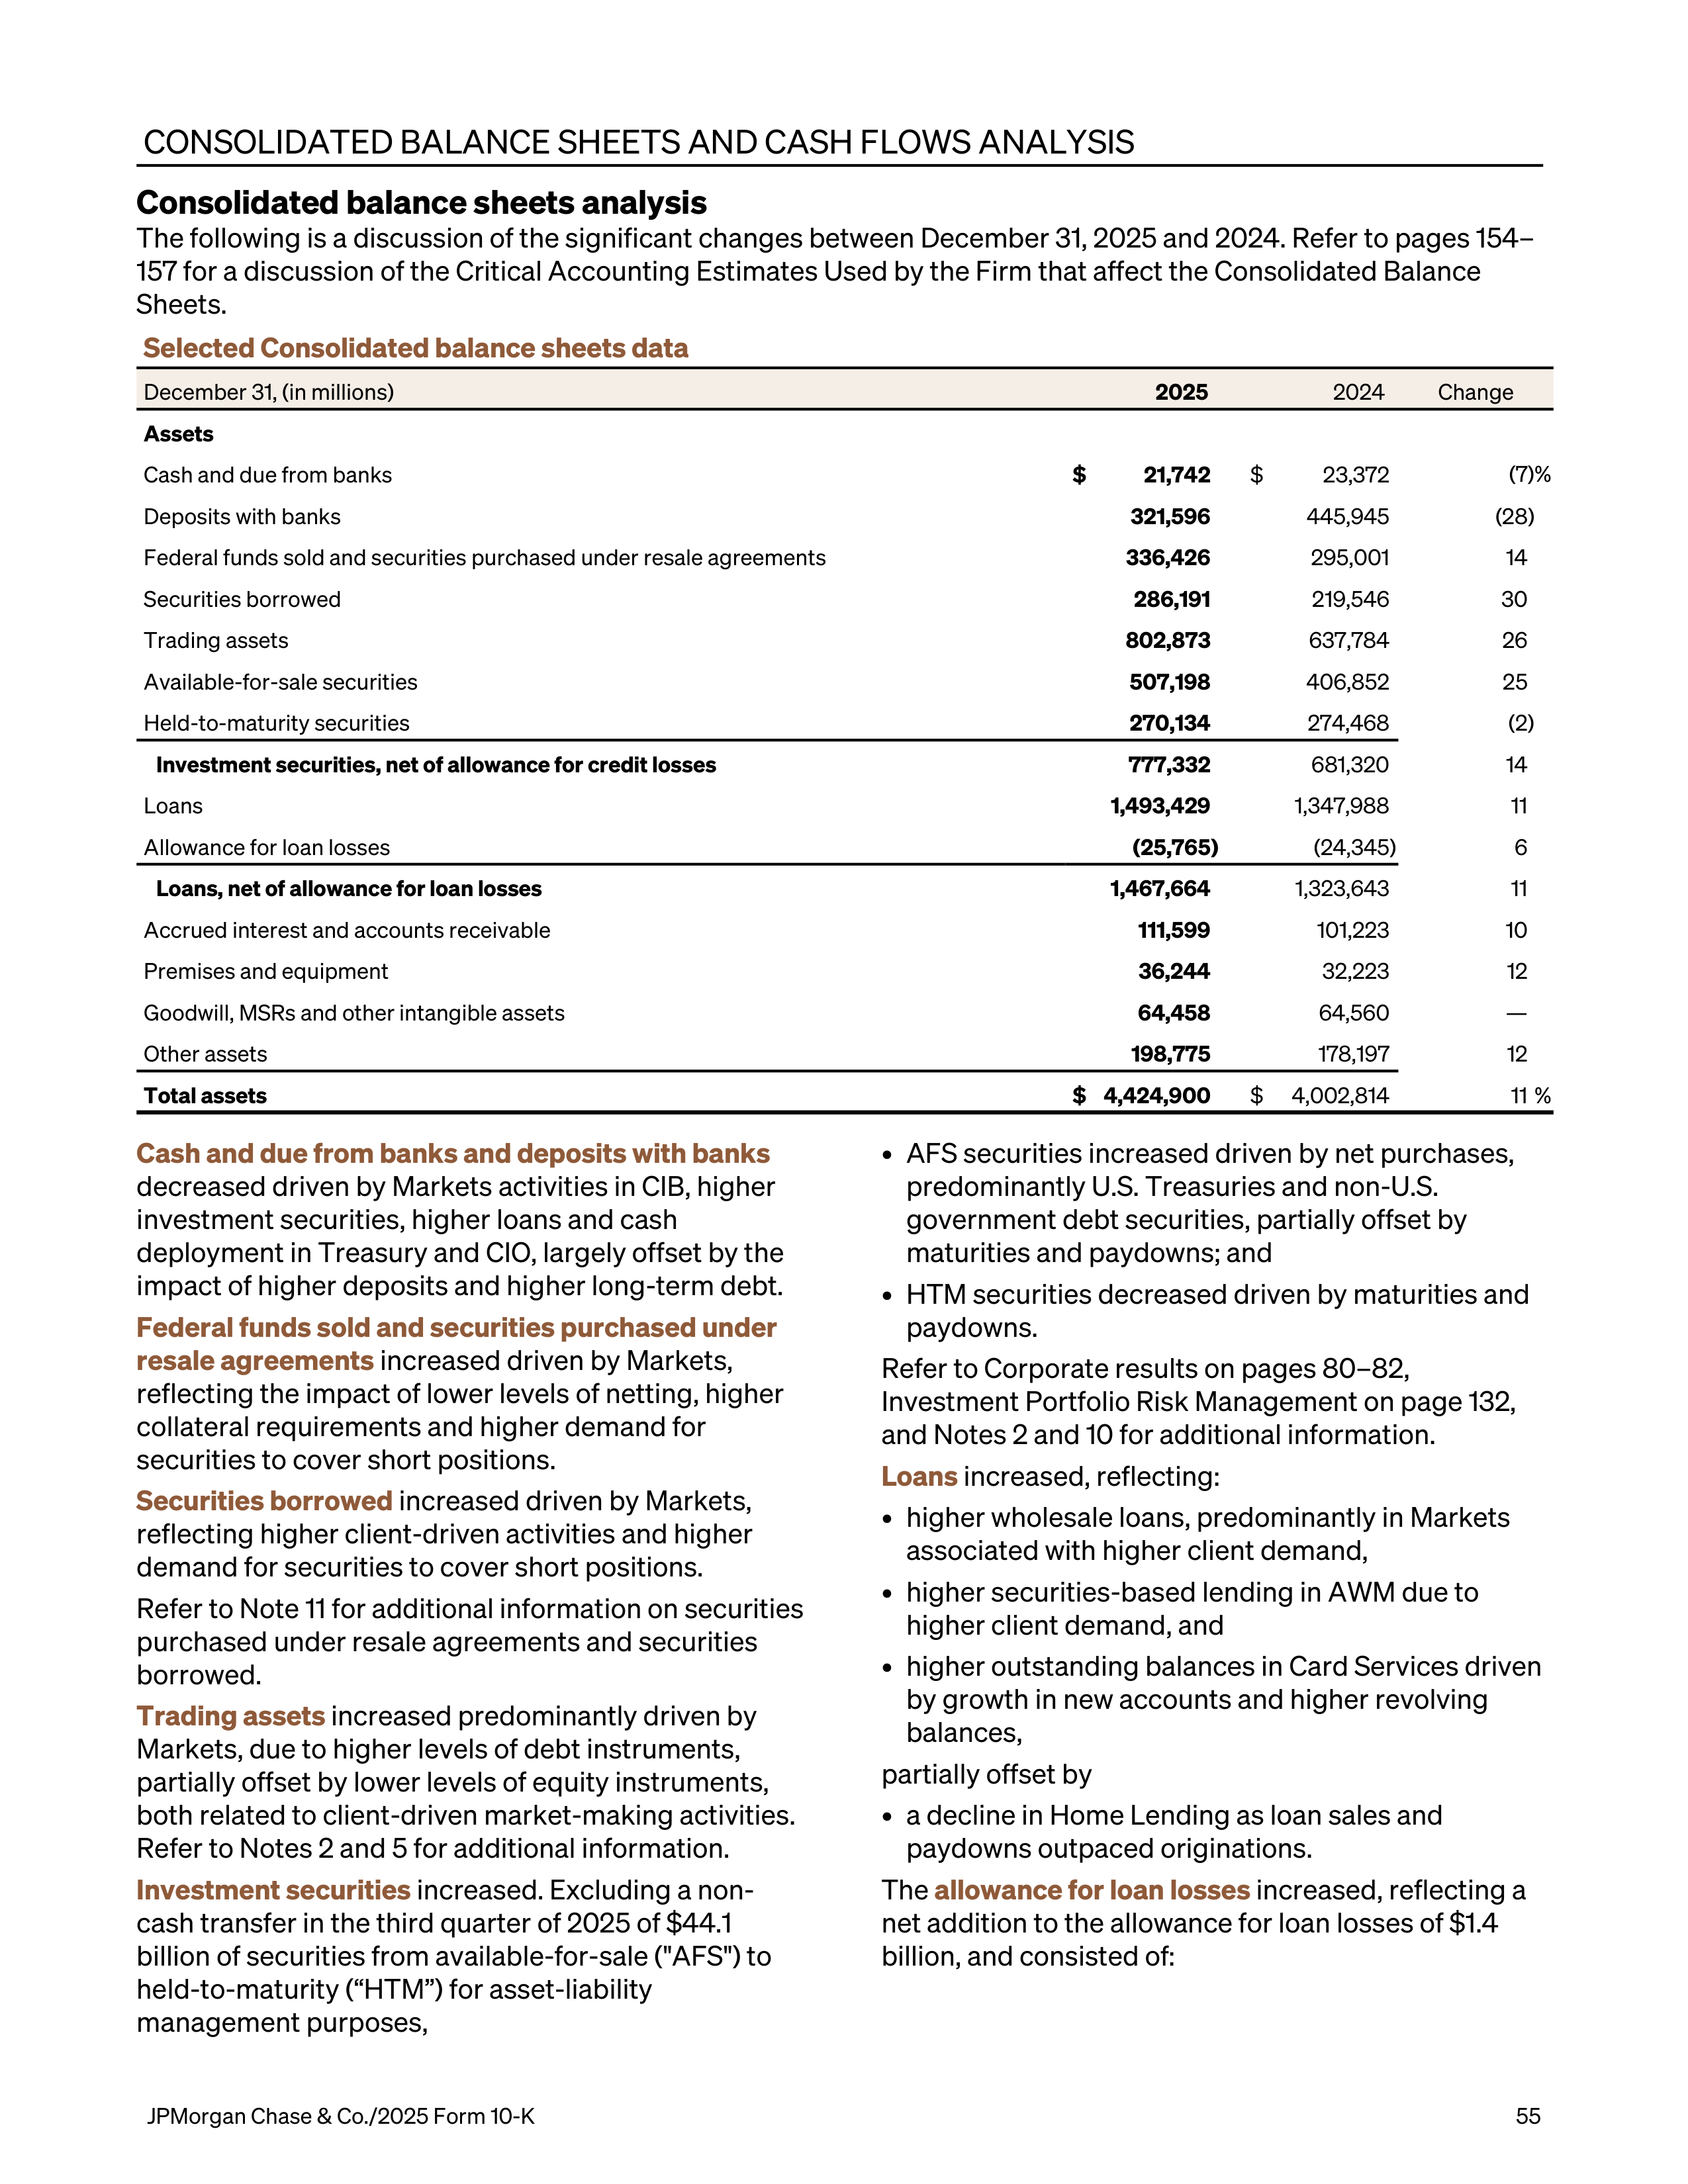
CONSOLIDATED BALANCE SHEETS AND CASH FLOWS ANALYSIS
Consolidated balance sheets analysis
The following is a discussion of the significant changes between December 31, 2025 and 2024. Refer to pages 154–
157 for a discussion of the Critical Accounting Estimates Used by the Firm that affect the Consolidated Balance
Sheets.
Selected Consolidated balance sheets data
December 31, (in millions)
2025
2024
Change
Assets
Cash and due from banks
$
21,742
$
23,372
(7) %
Deposits with banks
321,596
445,945
(28)
Federal funds sold and securities purchased under resale agreements
336,426
295,001
14
Securities borrowed
286,191
219,546
30
Trading assets
802,873
637,784
26
Available-for-sale securities
507,198
406,852
25
Held-to-maturity securities
270,134
274,468
(2)
Investment securities, net of allowance for credit losses
777,332
681,320
14
Loans
1,493,429
1,347,988
11
Allowance for loan losses
(25,765)
(24,345)
6
Loans, net of allowance for loan losses
1,467,664
1,323,643
11
Accrued interest and accounts receivable
111,599
101,223
10
Premises and equipment
36,244
32,223
12
Goodwill, MSRs and other intangible assets
64,458
64,560
—
Other assets
198,775
178,197
12
Total assets
$ 4,424,900
$
4,002,814
11 %
Cash and due from banks and deposits with banks
decreased driven by Markets activities in CIB, higher
investment securities, higher loans and cash
deployment in Treasury and CIO, largely offset by the
impact of higher deposits and higher long-term debt.
Federal funds sold and securities purchased under
resale agreements
increased driven by Markets,
reflecting the impact of lower levels of netting, higher
collateral requirements and higher demand for
securities to cover short positions.
Securities borrowed
increased driven by Markets,
reflecting higher client-driven activities and higher
demand for securities to cover short positions.
Refer to Note 11 for additional information on securities
purchased under resale agreements and securities
borrowed.
Trading assets
increased predominantly driven by
Markets, due to higher levels of debt instruments,
partially offset by lower levels of equity instruments,
both related to client-driven market-making activities.
Refer to Notes 2 and 5 for additional information.
Investment securities
increased. Excluding a non-
cash transfer in the third quarter of 2025 of $44.1
billion of securities from available-for-sale ("AFS") to
held-to-maturity (“HTM”) for asset-liability
management purposes,
•
AFS securities increased driven by net purchases,
predominantly U.S. Treasuries and non-U.S.
government debt securities, partially offset by
maturities and paydowns; and
•
HTM securities decreased driven by maturities and
paydowns.
Refer to Corporate results on pages 80–82,
Investment Portfolio Risk Management on page 132,
and Notes 2 and 10 for additional information.
Loans
increased, reflecting:
•
higher wholesale loans, predominantly in Markets
associated with higher client demand,
•
higher securities-based lending in AWM due to
higher client demand, and
•
higher outstanding balances in Card Services driven
by growth in new accounts and higher revolving
balances,
partially offset by
•
a decline in Home Lending as loan sales and
paydowns outpaced originations.
The
allowance for loan losses
increased, reflecting a
net addition to the allowance for loan losses of $1.4
billion, and consisted of:
JPMorgan Chase & Co./2025 Form 10-K
55
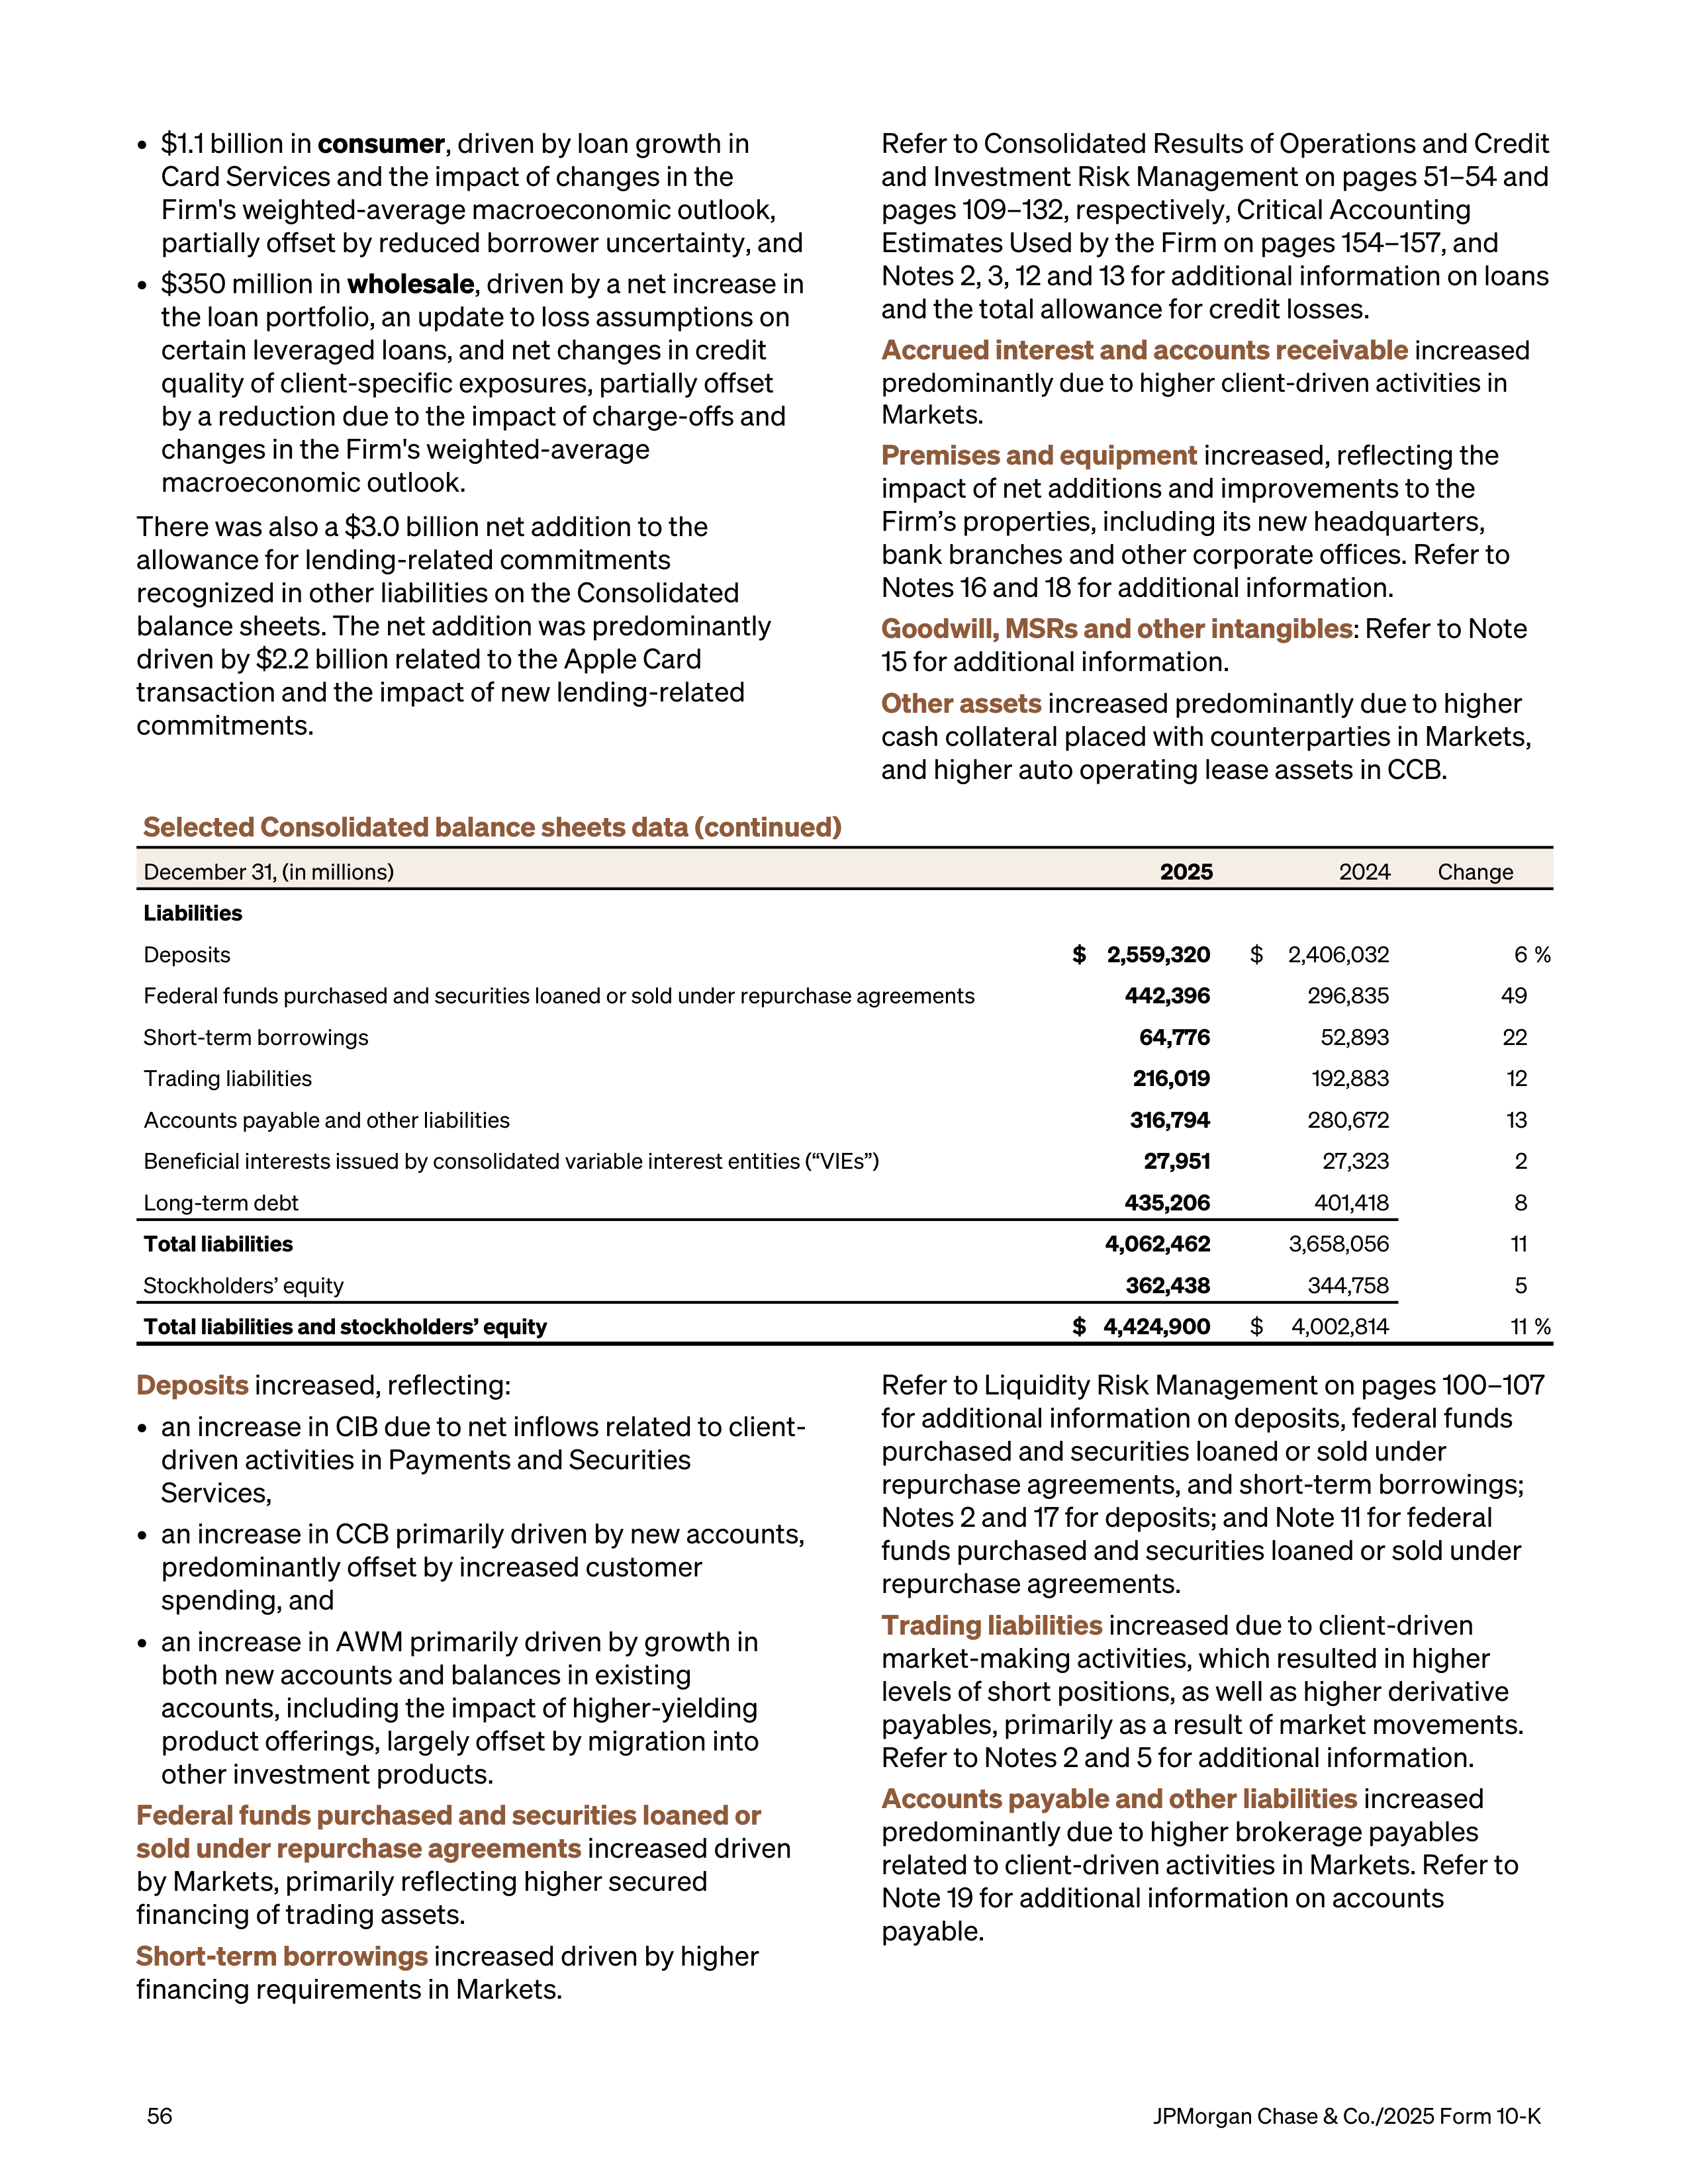
•
$1.1 billion in
consumer
, driven by loan growth in
Card Services and the impact of changes in the
Firm's weighted-average macroeconomic outlook,
partially offset by reduced borrower uncertainty, and
•
$350 million in
wholesale
, driven by a net increase in
the loan portfolio, an update to loss assumptions on
certain leveraged loans, and net changes in credit
quality of client-specific exposures, partially offset
by a reduction due to the impact of charge-offs and
changes in the Firm's weighted-average
macroeconomic outlook.
There was also a $3.0 billion net addition to the
allowance for lending-related commitments
recognized in other liabilities on the Consolidated
balance sheets. The net addition was predominantly
driven by $2.2 billion related to the Apple Card
transaction and the impact of new lending-related
commitments.
Refer to Consolidated Results of Operations and Credit
and Investment Risk Management on pages 51–54 and
pages 109–132, respectively, Critical Accounting
Estimates Used by the Firm on pages 154–157, and
Notes 2, 3, 12 and 13 for additional information on loans
and the total allowance for credit losses.
Accrued interest and accounts receivable
increased
predominantly due to higher client-driven activities in
Markets.
Premises and equipment
increased, reflecting the
impact of net additions and improvements to the
Firm’s properties, including its new headquarters,
bank branches and other corporate offices. Refer to
Notes 16 and 18 for additional information.
Goodwill, MSRs and other intangibles
:
Refer to Note
15 for additional information.
Other assets
increased predominantly due to higher
cash collateral placed with counterparties in Markets,
and higher auto operating lease assets in CCB.
Selected Consolidated balance sheets data (continued)
December 31, (in millions)
2025
2024
Change
Liabilities
Deposits
$ 2,559,320
$
2,406,032
6 %
Federal funds purchased and securities loaned or sold under repurchase agreements
442,396
296,835
49
Short-term borrowings
64,776
52,893
22
Trading liabilities
216,019
192,883
12
Accounts payable and other liabilities
316,794
280,672
13
Beneficial interests issued by consolidated variable interest entities (“VIEs”)
27,951
27,323
2
Long-term debt
435,206
401,418
8
Total liabilities
4,062,462
3,658,056
11
Stockholders’ equity
362,438
344,758
5
Total liabilities and stockholders’ equity
$ 4,424,900
$
4,002,814
11 %
Deposits
increased, reflecting:
•
an increase in CIB due to net inflows related to client-
driven activities in Payments and Securities
Services,
•
an increase in CCB primarily driven by new accounts,
predominantly offset by increased customer
spending, and
•
an increase in AWM primarily driven by growth in
both new accounts and balances in existing
accounts, including the impact of higher-yielding
product offerings, largely offset by migration into
other investment products.
Federal funds purchased and securities loaned or
sold under repurchase agreements
increased driven
by Markets, primarily reflecting higher secured
financing of trading assets.
Short-term borrowings
increased driven by higher
financing requirements in Markets.
Refer to Liquidity Risk Management on pages 100–107
for additional information on deposits, federal funds
purchased and securities loaned or sold under
repurchase agreements, and short-term borrowings;
Notes 2 and 17 for deposits; and Note 11 for federal
funds purchased and securities loaned or sold under
repurchase agreements.
Trading liabilities
increased due to client-driven
market-making activities, which resulted in higher
levels of short positions, as well as higher derivative
payables, primarily as a result of market movements.
Refer to Notes 2 and 5 for additional information.
Accounts payable and other liabilities
increased
predominantly
due to higher brokerage payables
related to client-driven activities in Markets. Refer to
Note 19 for additional information on accounts
payable.
56
JPMorgan Chase & Co./2025 Form 10-K
Beneficial interests issued by consolidated VIEs
:
Refer to Liquidity Risk Management on pages 100–107;
and Notes 14 and 28 for additional information related
to Firm-sponsored VIEs and loan securitization trusts.
Long-term debt
increased driven by net issuances of
structured notes in Markets due to client demand and
an increase in the fair value of such instruments, as
well as net issuances of long-term debt in Treasury
and CIO, partially offset by a net reduction in Federal
Home Loan Bank ("FHLB") advances
.
Refer to Liquidity
Risk Management on pages 100–107 for additional
information.
Stockholders’ equity
increased, reflecting:
•
net income, and
•
net unrealized gains in AOCI in Treasury and CIO,
driven by the impact of lower interest rates on AFS
securities and cash flow hedges, and spreads
tightening on AFS securities,
largely offset by
•
the impact of capital actions, including net
repurchases of common shares and dividend
payments on common and preferred stock.
Refer to Consolidated Statements of changes in
stockholders’ equity
on page 168, Capital Actions on
page 97, and Note 24 for additional information.
JPMorgan Chase & Co./2025 Form 10-K
57
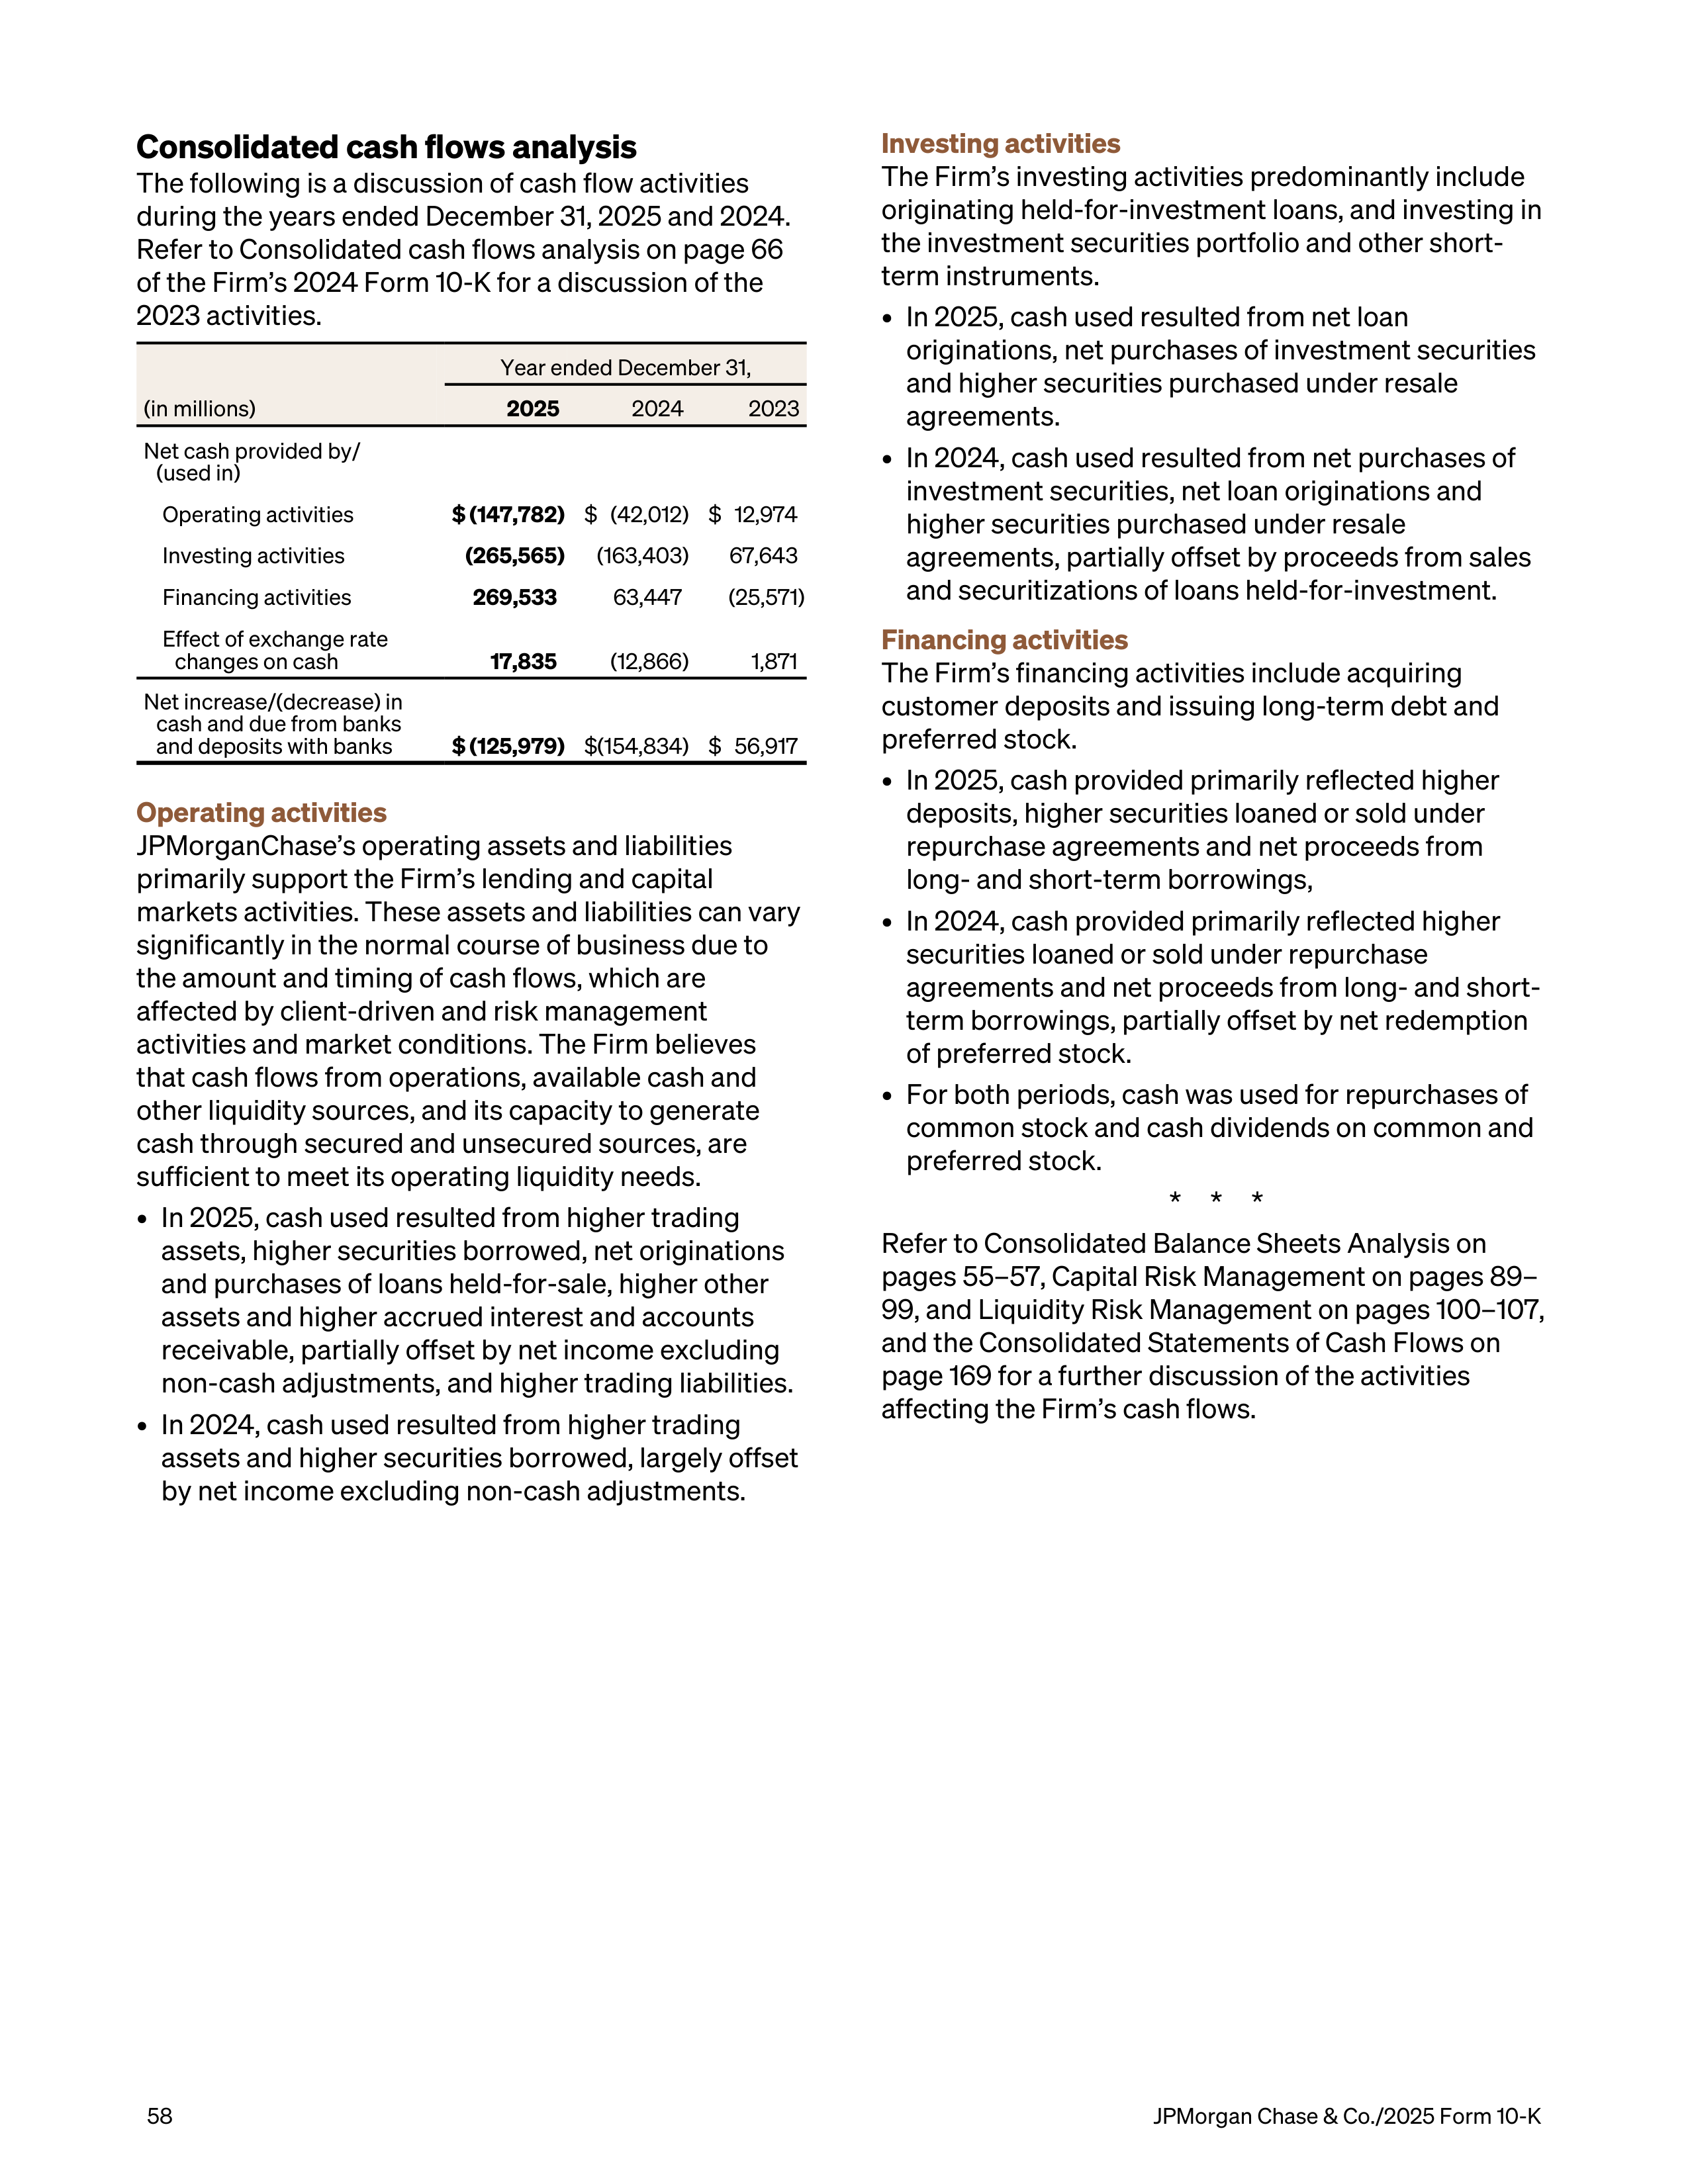
Consolidated cash flows analysis
The following is a discussion of cash flow activities
during the years ended December 31, 2025 and 2024.
Refer to Consolidated cash flows analysis on page 66
of the Firm’s 2024 Form 10-K for a discussion of the
2023 activities.
(in millions)
Year ended December 31,
2025
2024
2023
Net cash provided by/
(used in)
Operating activities
$ (147,782)
$ (42,012) $ 12,974
Investing activities
(265,565)
(163,403) 67,643
Financing activities
269,533
63,447
(25,571)
Effect of exchange rate
changes on cash
17,835
(12,866)
1,871
Net increase/(decrease) in
cash and due from banks
and deposits with banks
$ (125,979)
$ (154,834) $ 56,917
Operating activities
JPMorganChase’s operating assets and liabilities
primarily support the Firm’s lending and capital
markets activities. These assets and liabilities can vary
significantly in the normal course of business due to
the amount and timing of cash flows, which are
affected by client-driven and risk management
activities and market conditions. The Firm believes
that cash flows from operations, available cash and
other liquidity sources, and its capacity to generate
cash through secured and unsecured sources, are
sufficient to meet its operating liquidity needs.
•
In 2025, cash used resulted from higher trading
assets, higher securities borrowed, net originations
and purchases of loans held-for-sale, higher other
assets and higher accrued interest and accounts
receivable, partially offset by net income excluding
non-cash adjustments, and higher trading liabilities.
•
In 2024, cash used resulted from higher trading
assets and higher securities borrowed, largely offset
by net income excluding non-cash adjustments.
Investing activities
The Firm’s investing activities predominantly include
originating held-for-investment loans, and investing in
the investment securities portfolio and other short-
term instruments.
•
In 2025, cash used resulted from net loan
originations, net purchases of investment securities
and higher securities purchased under resale
agreements.
•
In 2024, cash used resulted from net purchases of
investment securities, net loan originations and
higher securities purchased under resale
agreements, partially offset by proceeds from sales
and securitizations of loans held-for-investment.
Financing activities
The Firm’s financing activities include acquiring
customer deposits and issuing long-term debt and
preferred stock.
•
In 2025, cash provided primarily reflected higher
deposits, higher securities loaned or sold under
repurchase agreements and net proceeds from
long- and short-term borrowings,
•
In 2024, cash provided primarily reflected higher
securities loaned or sold under repurchase
agreements and net proceeds from long- and short-
term borrowings, partially offset by net redemption
of preferred stock.
•
For both periods, cash was used for repurchases of
common stock and cash dividends on common and
preferred stock.
* * *
Refer to Consolidated Balance Sheets Analysis on
pages 55–57, Capital Risk Management on pages 89–
99, and Liquidity Risk Management on pages 100–107,
and the Consolidated Statements of Cash Flows on
page 169 for a further discussion of the activities
affecting the Firm’s cash flows.
58
JPMorgan Chase & Co./2025 Form 10-K
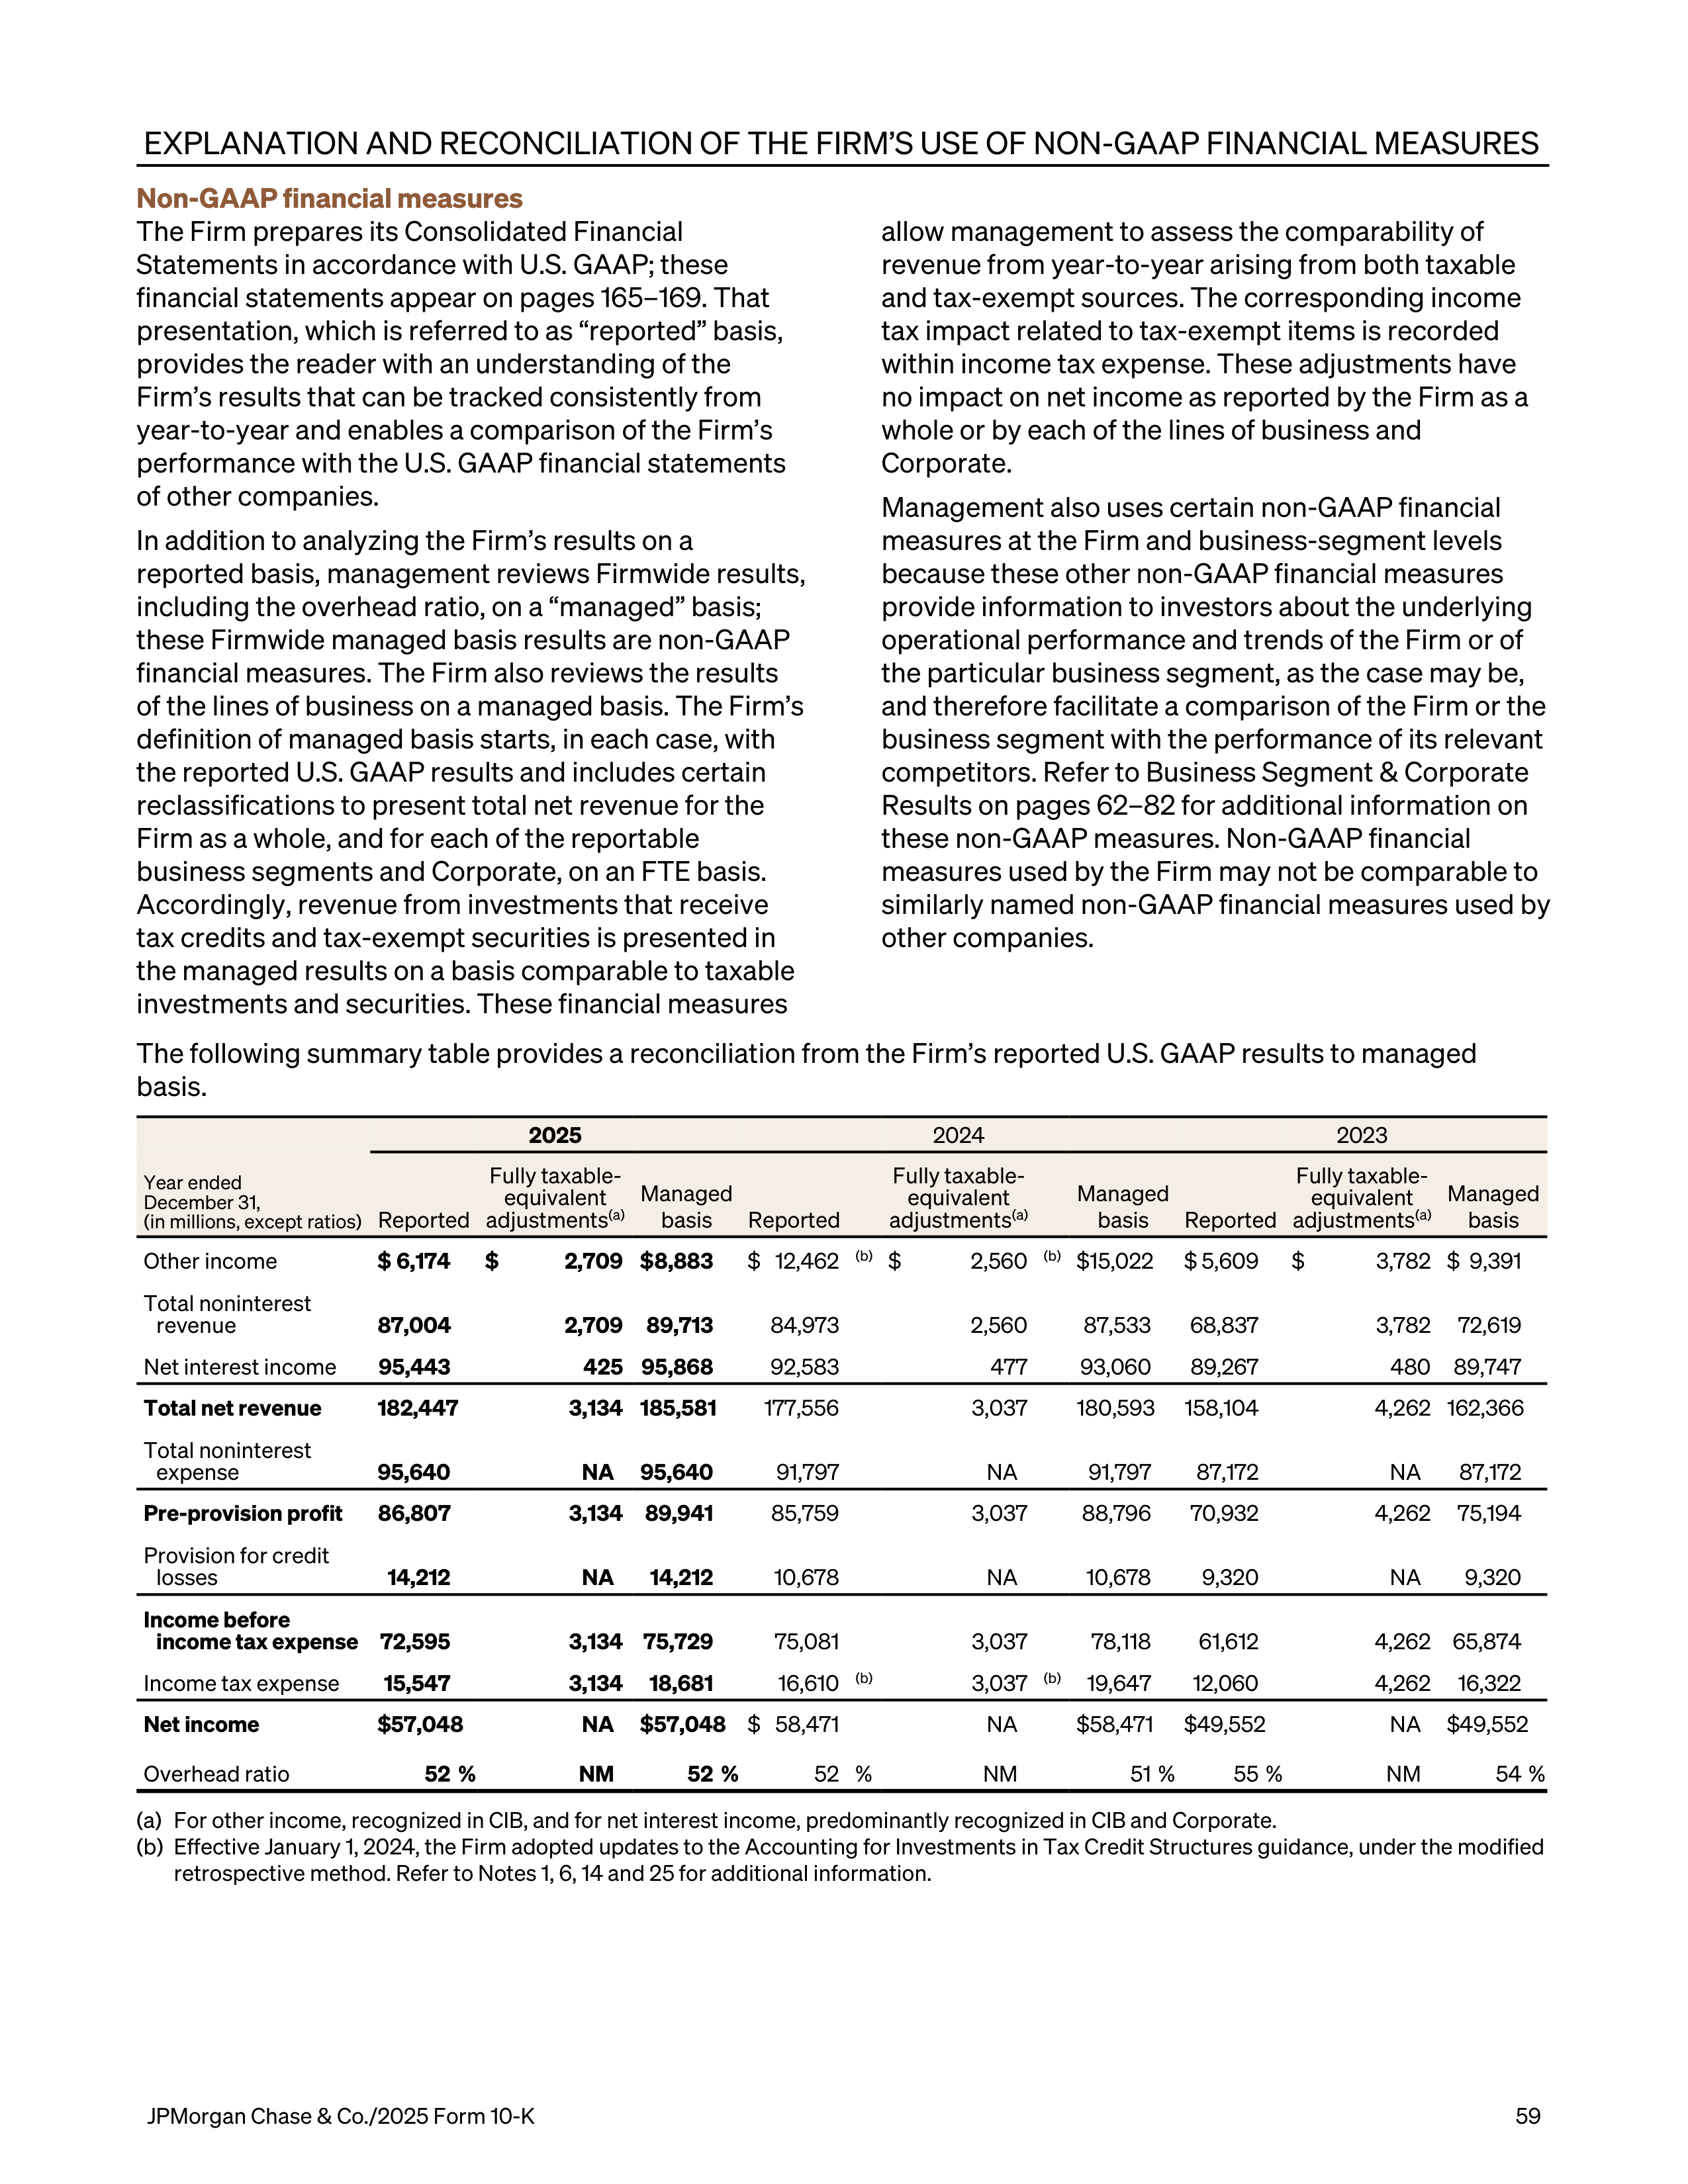
EXPLANATION AND RECONCILIATION OF THE FIRM’S USE OF NON-GAAP FINANCIAL MEASURES
Non-GAAP financial measures
The Firm prepares its Consolidated Financial
Statements in accordance with U.S. GAAP; these
financial statements appear on pages 165–169. That
presentation, which is referred to as “reported” basis,
provides the reader with an understanding of the
Firm’s results that can be tracked consistently from
year-to-year and enables a comparison of the Firm’s
performance with the U.S. GAAP financial statements
of other companies.
In addition to analyzing the Firm’s results on a
reported basis, management reviews Firmwide results,
including the overhead ratio, on a “managed” basis;
these Firmwide managed basis results are non-GAAP
financial measures. The Firm also reviews the results
of the lines of business on a managed basis. The Firm’s
definition of managed basis starts, in each case, with
the reported U.S. GAAP results and includes certain
reclassifications to present total net revenue for the
Firm as a whole, and for each of the reportable
business segments and Corporate, on an FTE basis.
Accordingly, revenue from investments that receive
tax credits and tax-exempt securities is presented in
the managed results on a basis comparable to taxable
investments and securities. These financial measures
allow management to assess the comparability of
revenue from year-to-year arising from both taxable
and tax-exempt sources. The corresponding income
tax impact related to tax-exempt items is recorded
within income tax expense. These adjustments have
no impact on net income as reported by the Firm as a
whole or by each of the lines of business and
Corporate.
Management also uses certain non-GAAP financial
measures at the Firm and business-segment levels
because these other non-GAAP financial measures
provide information to investors about the underlying
operational performance and trends of the Firm or of
the particular business segment, as the case may be,
and therefore facilitate a comparison of the Firm or the
business segment with the performance of its relevant
competitors. Refer to Business Segment & Corporate
Results on pages 62–82 for additional information on
these non-GAAP measures. Non-GAAP financial
measures used by the Firm may not be comparable to
similarly named non-GAAP financial measures used by
other companies.
The following summary table provides a reconciliation from the Firm’s reported U.S. GAAP results to managed
basis.
2025
2024
2023
Year ended
December 31,
(in millions, except ratios)
Reported
Fully taxable-
equivalent
adjustments
(a)
Managed
basis
Reported
Fully taxable-
equivalent
adjustments
(a)
Managed
basis
Reported
Fully taxable-
equivalent
adjustments
(a)
Managed
basis
Other income
$ 6,174
$
2,709 $ 8,883
$ 12,462
(b)
$
2,560
(b)
$ 15,022
$ 5,609
$
3,782 $ 9,391
Total noninterest
revenue
87,004
2,709 89,713
84,973
2,560
87,533
68,837
3,782 72,619
Net interest income
95,443
425 95,868
92,583
477
93,060
89,267
480 89,747
Total net revenue
182,447
3,134 185,581
177,556
3,037
180,593
158,104
4,262 162,366
Total noninterest
expense
95,640
NA
95,640
91,797
NA
91,797
87,172
NA
87,172
Pre-provision profit
86,807
3,134 89,941
85,759
3,037
88,796
70,932
4,262 75,194
Provision for credit
losses
14,212
NA
14,212
10,678
NA
10,678
9,320
NA
9,320
Income before
income tax expense
72,595
3,134 75,729
75,081
3,037
78,118
61,612
4,262 65,874
Income tax expense
15,547
3,134 18,681
16,610
(b)
3,037
(b)
19,647
12,060
4,262 16,322
Net income
$ 57,048
NA
$ 57,048
$ 58,471
NA
$ 58,471
$ 49,552
NA
$ 49,552
Overhead ratio
52 %
NM
52 %
52 %
NM
51 %
55 %
NM
54 %
(a)
For other income, recognized in CIB, and for net interest income, predominantly recognized in CIB and Corporate.
(b)
Effective January 1, 2024, the Firm adopted updates to the Accounting for Investments in Tax Credit Structures guidance, under the modified
retrospective method. Refer to Notes 1, 6, 14 and 25 for additional information.
JPMorgan Chase & Co./2025 Form 10-K
59
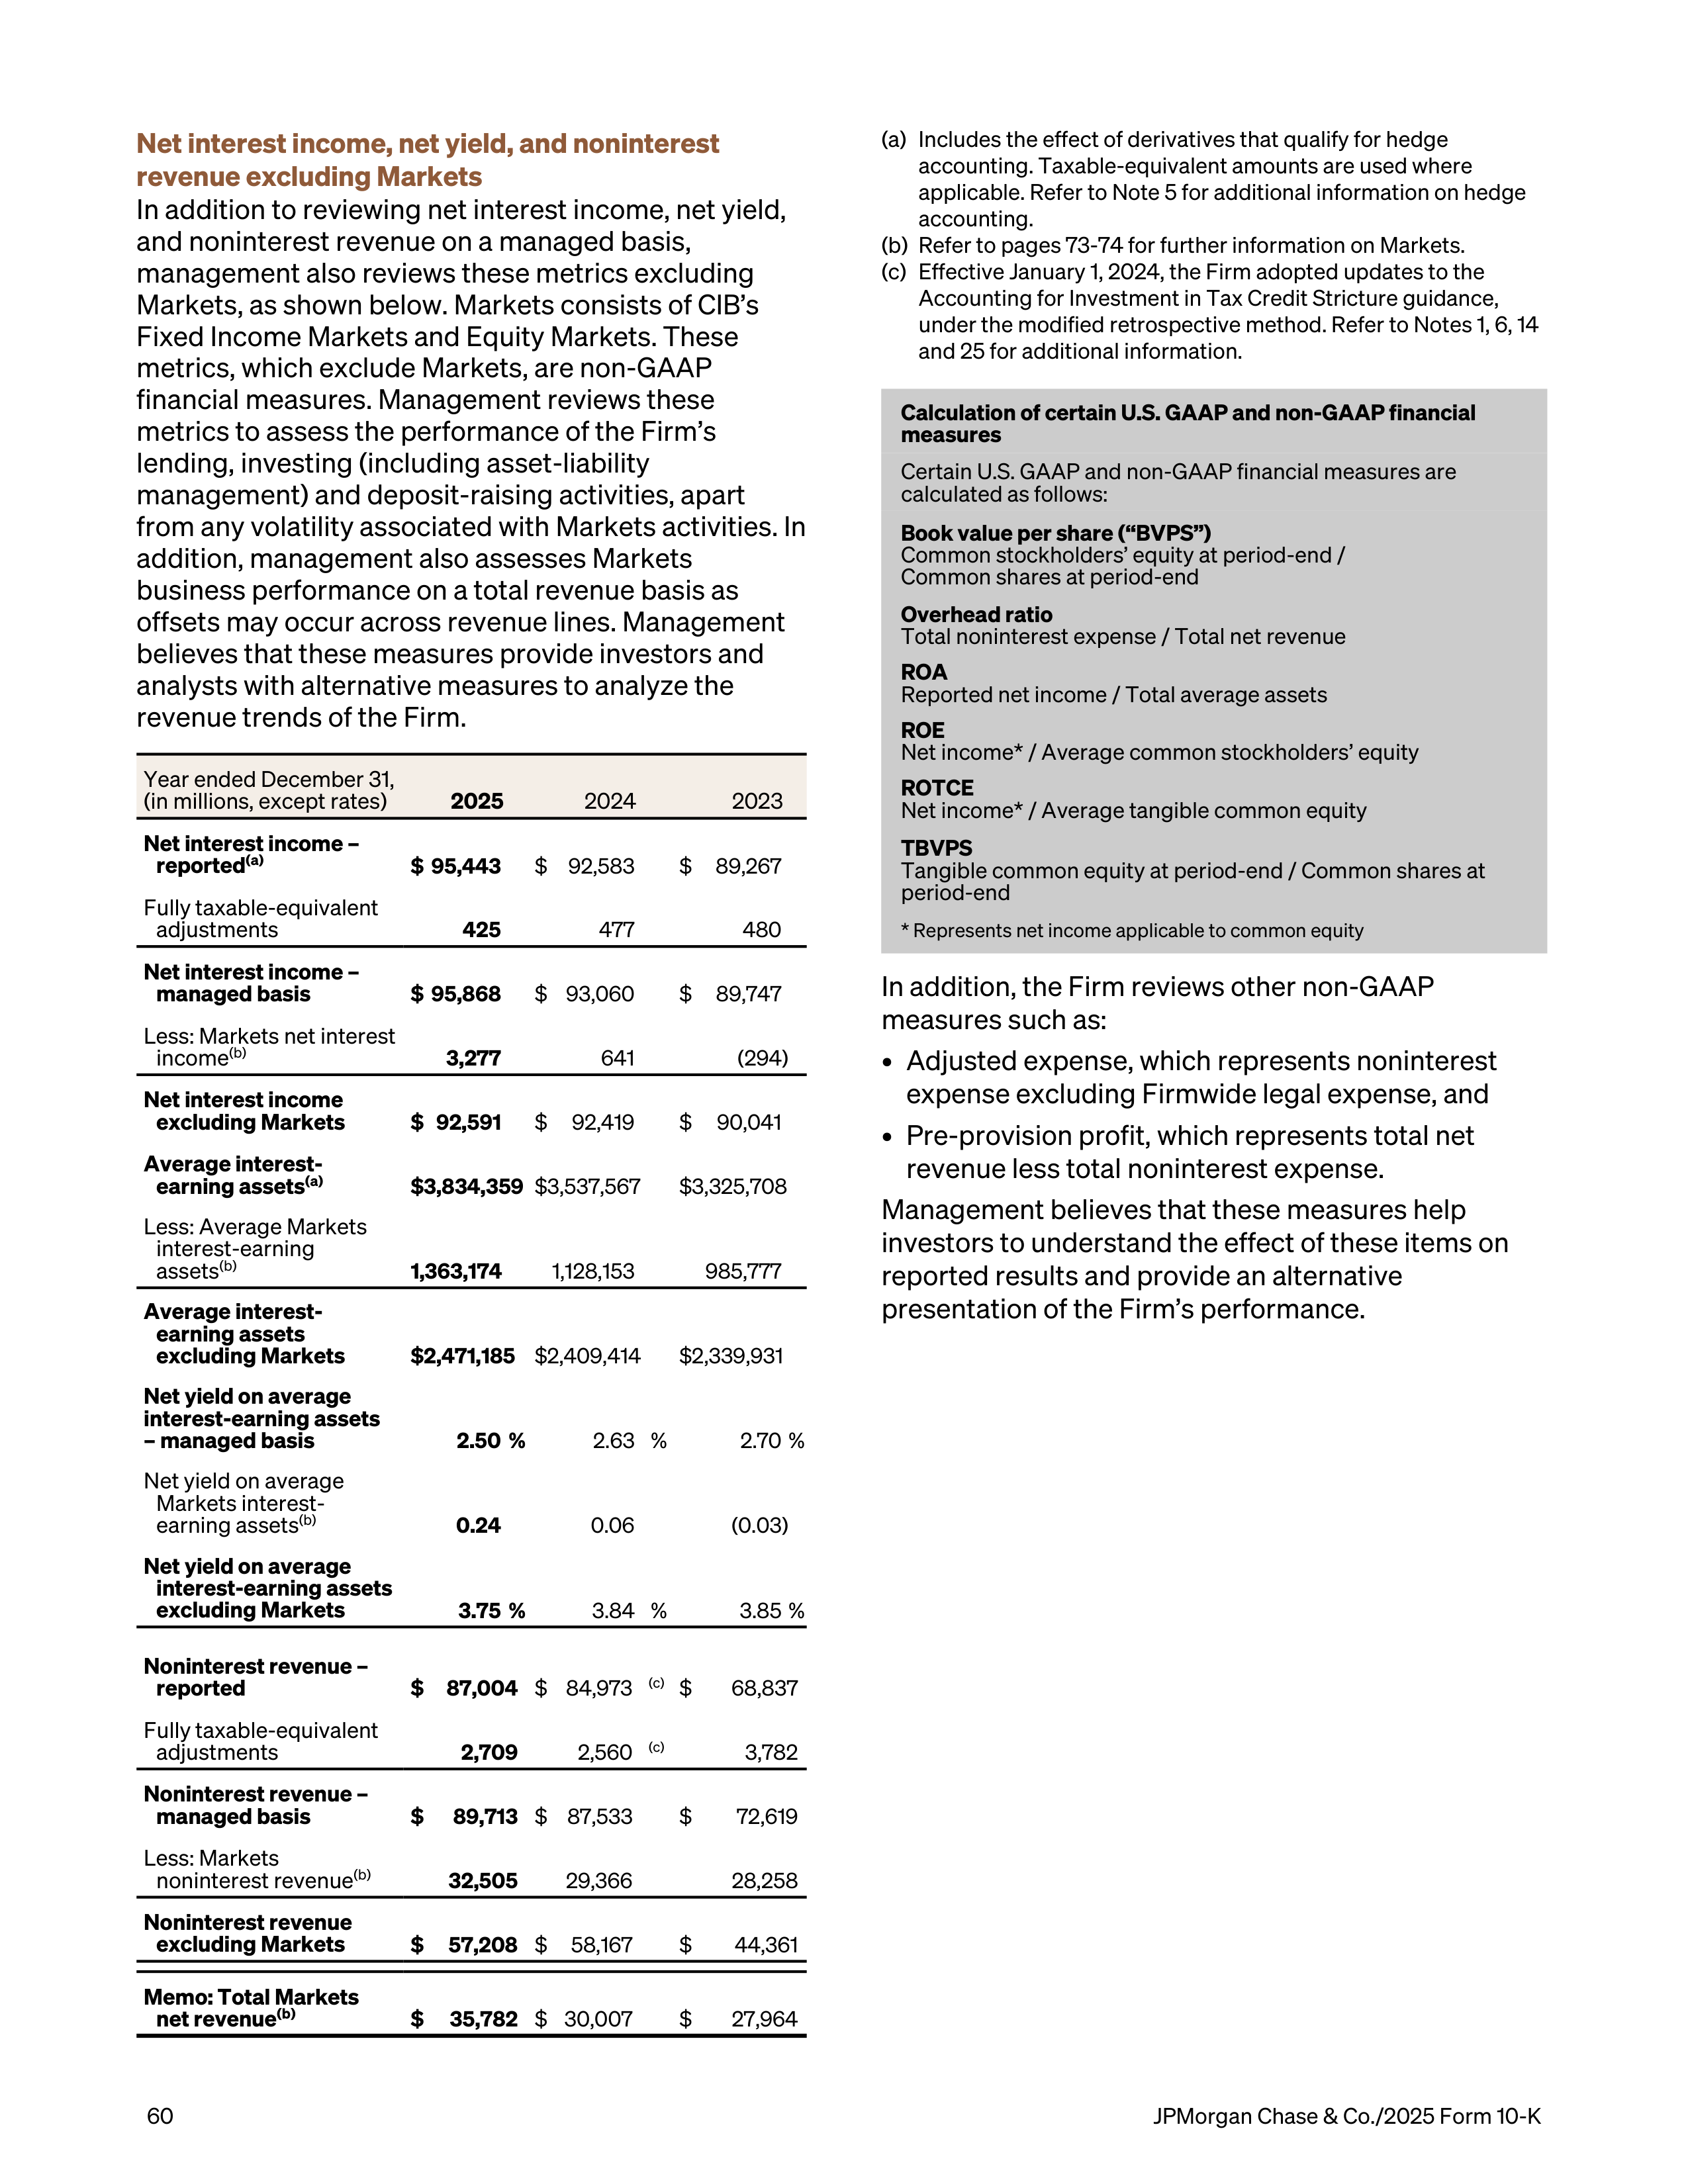
Net interest income, net yield, and noninterest
revenue excluding Markets
In addition to reviewing net interest income, net yield,
and noninterest revenue on a managed basis,
management also reviews these metrics excluding
Markets, as shown below. Markets consists of CIB’s
Fixed Income Markets and Equity Markets. These
metrics, which exclude Markets, are non-GAAP
financial measures. Management reviews these
metrics to assess the performance of the Firm’s
lending, investing (including asset-liability
management) and deposit-raising activities, apart
from any volatility associated with Markets activities. In
addition, management also assesses Markets
business performance on a total revenue basis as
offsets may occur across revenue lines. Management
believes that these measures provide investors and
analysts with alternative measures to analyze the
revenue trends of the Firm.
Year ended December 31,
(in millions, except rates)
2025
2024
2023
Net interest income –
reported
(a)
$ 95,443
$ 92,583
$
89,267
Fully taxable-equivalent
adjustments
425
477
480
Net interest income –
managed basis
$ 95,868
$ 93,060
$
89,747
Less: Markets net interest
income
(b)
3,277
641
(294)
Net interest income
excluding Markets
$ 92,591
$
92,419
$
90,041
Average interest-
earning assets
(a)
$ 3,834,359
$ 3,537,567
$ 3,325,708
Less: Average Markets
interest-earning
assets
(b)
1,363,174
1,128,153
985,777
Average interest-
earning assets
excluding Markets
$ 2,471,185
$ 2,409,414
$ 2,339,931
Net yield on average
interest-earning assets
– managed basis
2.50 %
2.63 %
2.70 %
Net yield on average
Markets interest-
earning assets
(b)
0.24
0.06
(0.03)
Net yield on average
interest-earning assets
excluding Markets
3.75 %
3.84 %
3.85 %
Noninterest revenue –
reported
$
87,004
$ 84,973
(c)
$
68,837
Fully taxable-equivalent
adjustments
2,709
2,560
(c)
3,782
Noninterest revenue –
managed basis
$
89,713
$ 87,533
$
72,619
Less: Markets
noninterest revenue
(b)
32,505
29,366
28,258
Noninterest revenue
excluding Markets
$
57,208
$
58,167
$
44,361
Memo: Total Markets
net revenue
(b)
$
35,782
$ 30,007
$
27,964
(a)
Includes the effect of derivatives that qualify for hedge
accounting. Taxable-equivalent amounts are used where
applicable. Refer to Note 5 for additional information on hedge
accounting.
(b)
Refer to pages 73-74 for further information on Markets.
(c)
Effective January 1, 2024, the Firm adopted updates to the
Accounting for Investment in Tax Credit Stricture guidance,
under the modified retrospective method. Refer to Notes 1, 6, 14
and 25 for additional information.
Calculation of certain U.S. GAAP and non-GAAP financial
measures
Certain U.S. GAAP and non-GAAP financial measures are
calculated as follows:
Book value per share (“BVPS”)
Common stockholders’ equity at period-end /
Common shares at period-end
Overhead ratio
Total noninterest expense / Total net revenue
ROA
Reported net income / Total average assets
ROE
Net income* / Average common stockholders’ equity
ROTCE
Net income* / Average tangible common equity
TBVPS
Tangible common equity at period-end / Common shares at
period-end
* Represents net income applicable to common equity
In addition, the Firm reviews other non-GAAP
measures such as:
•
Adjusted expense, which represents noninterest
expense excluding Firmwide legal expense, and
•
Pre-provision profit, which represents total net
revenue less total noninterest expense.
Management believes that these measures help
investors to understand the effect of these items on
reported results and provide an alternative
presentation of the Firm’s performance.
60
JPMorgan Chase & Co./2025 Form 10-K
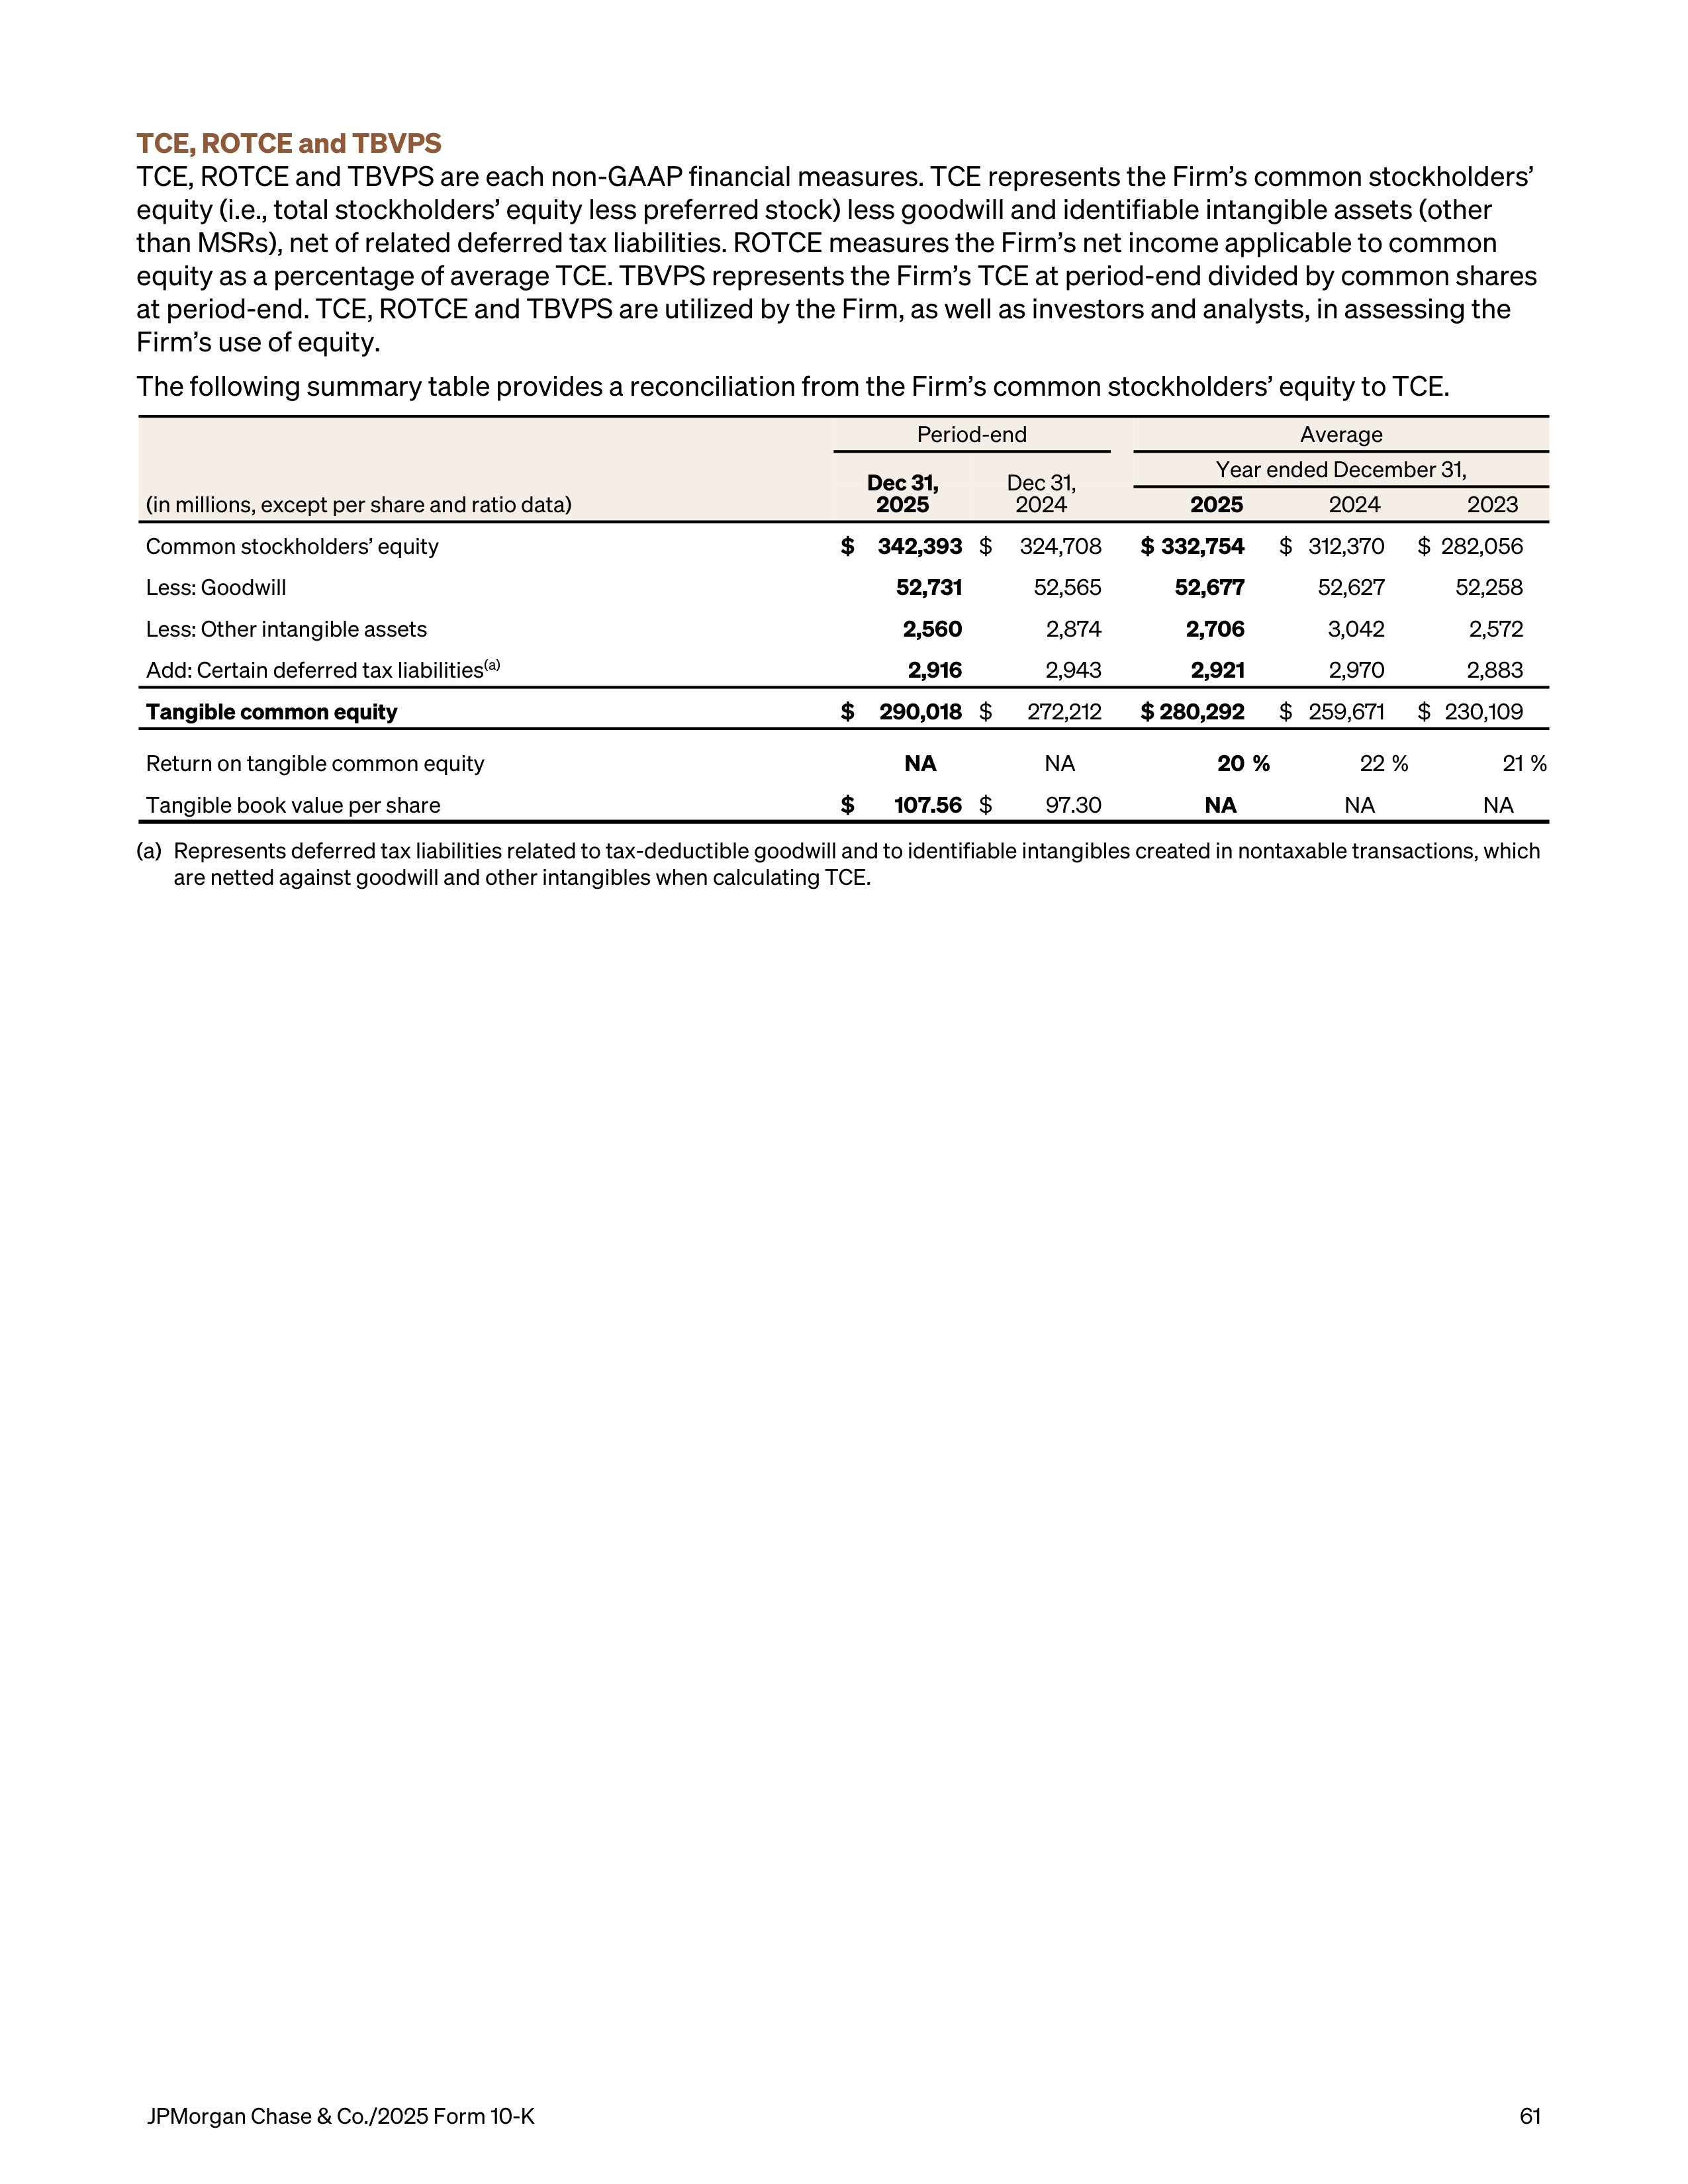
TCE, ROTCE and TBVPS
TCE, ROTCE and TBVPS are each non-GAAP financial measures. TCE represents the Firm’s common stockholders’
equity (i.e., total stockholders’ equity less preferred stock) less goodwill and identifiable intangible assets (other
than MSRs), net of related deferred tax liabilities. ROTCE measures the Firm’s net income applicable to common
equity as a percentage of average TCE. TBVPS represents the Firm’s TCE at period-end divided by common shares
at period-end. TCE, ROTCE and TBVPS are utilized by the Firm, as well as investors and analysts, in assessing the
Firm’s use of equity.
The following summary table provides a reconciliation from the Firm’s common stockholders’ equity to TCE.
Period-end
Average
Dec 31,
2025
Dec 31,
2024
Year ended December 31,
(in millions, except per share and ratio data)
2025
2024
2023
Common stockholders’ equity
$
342,393
$
324,708
$ 332,754
$ 312,370
$ 282,056
Less: Goodwill
52,731
52,565
52,677
52,627
52,258
Less: Other intangible assets
2,560
2,874
2,706
3,042
2,572
Add: Certain deferred tax liabilities
(a)
2,916
2,943
2,921
2,970
2,883
Tangible common equity
$
290,018
$
272,212
$ 280,292
$ 259,671
$ 230,109
Return on tangible common equity
NA
NA
20 %
22 %
21 %
Tangible book value per share
$
107.56
$
97.30
NA
NA
NA
(a)
Represents deferred tax liabilities related to tax-deductible goodwill and to identifiable intangibles created in nontaxable transactions, which
are netted against goodwill and other intangibles when calculating TCE.
JPMorgan Chase & Co./2025 Form 10-K
61
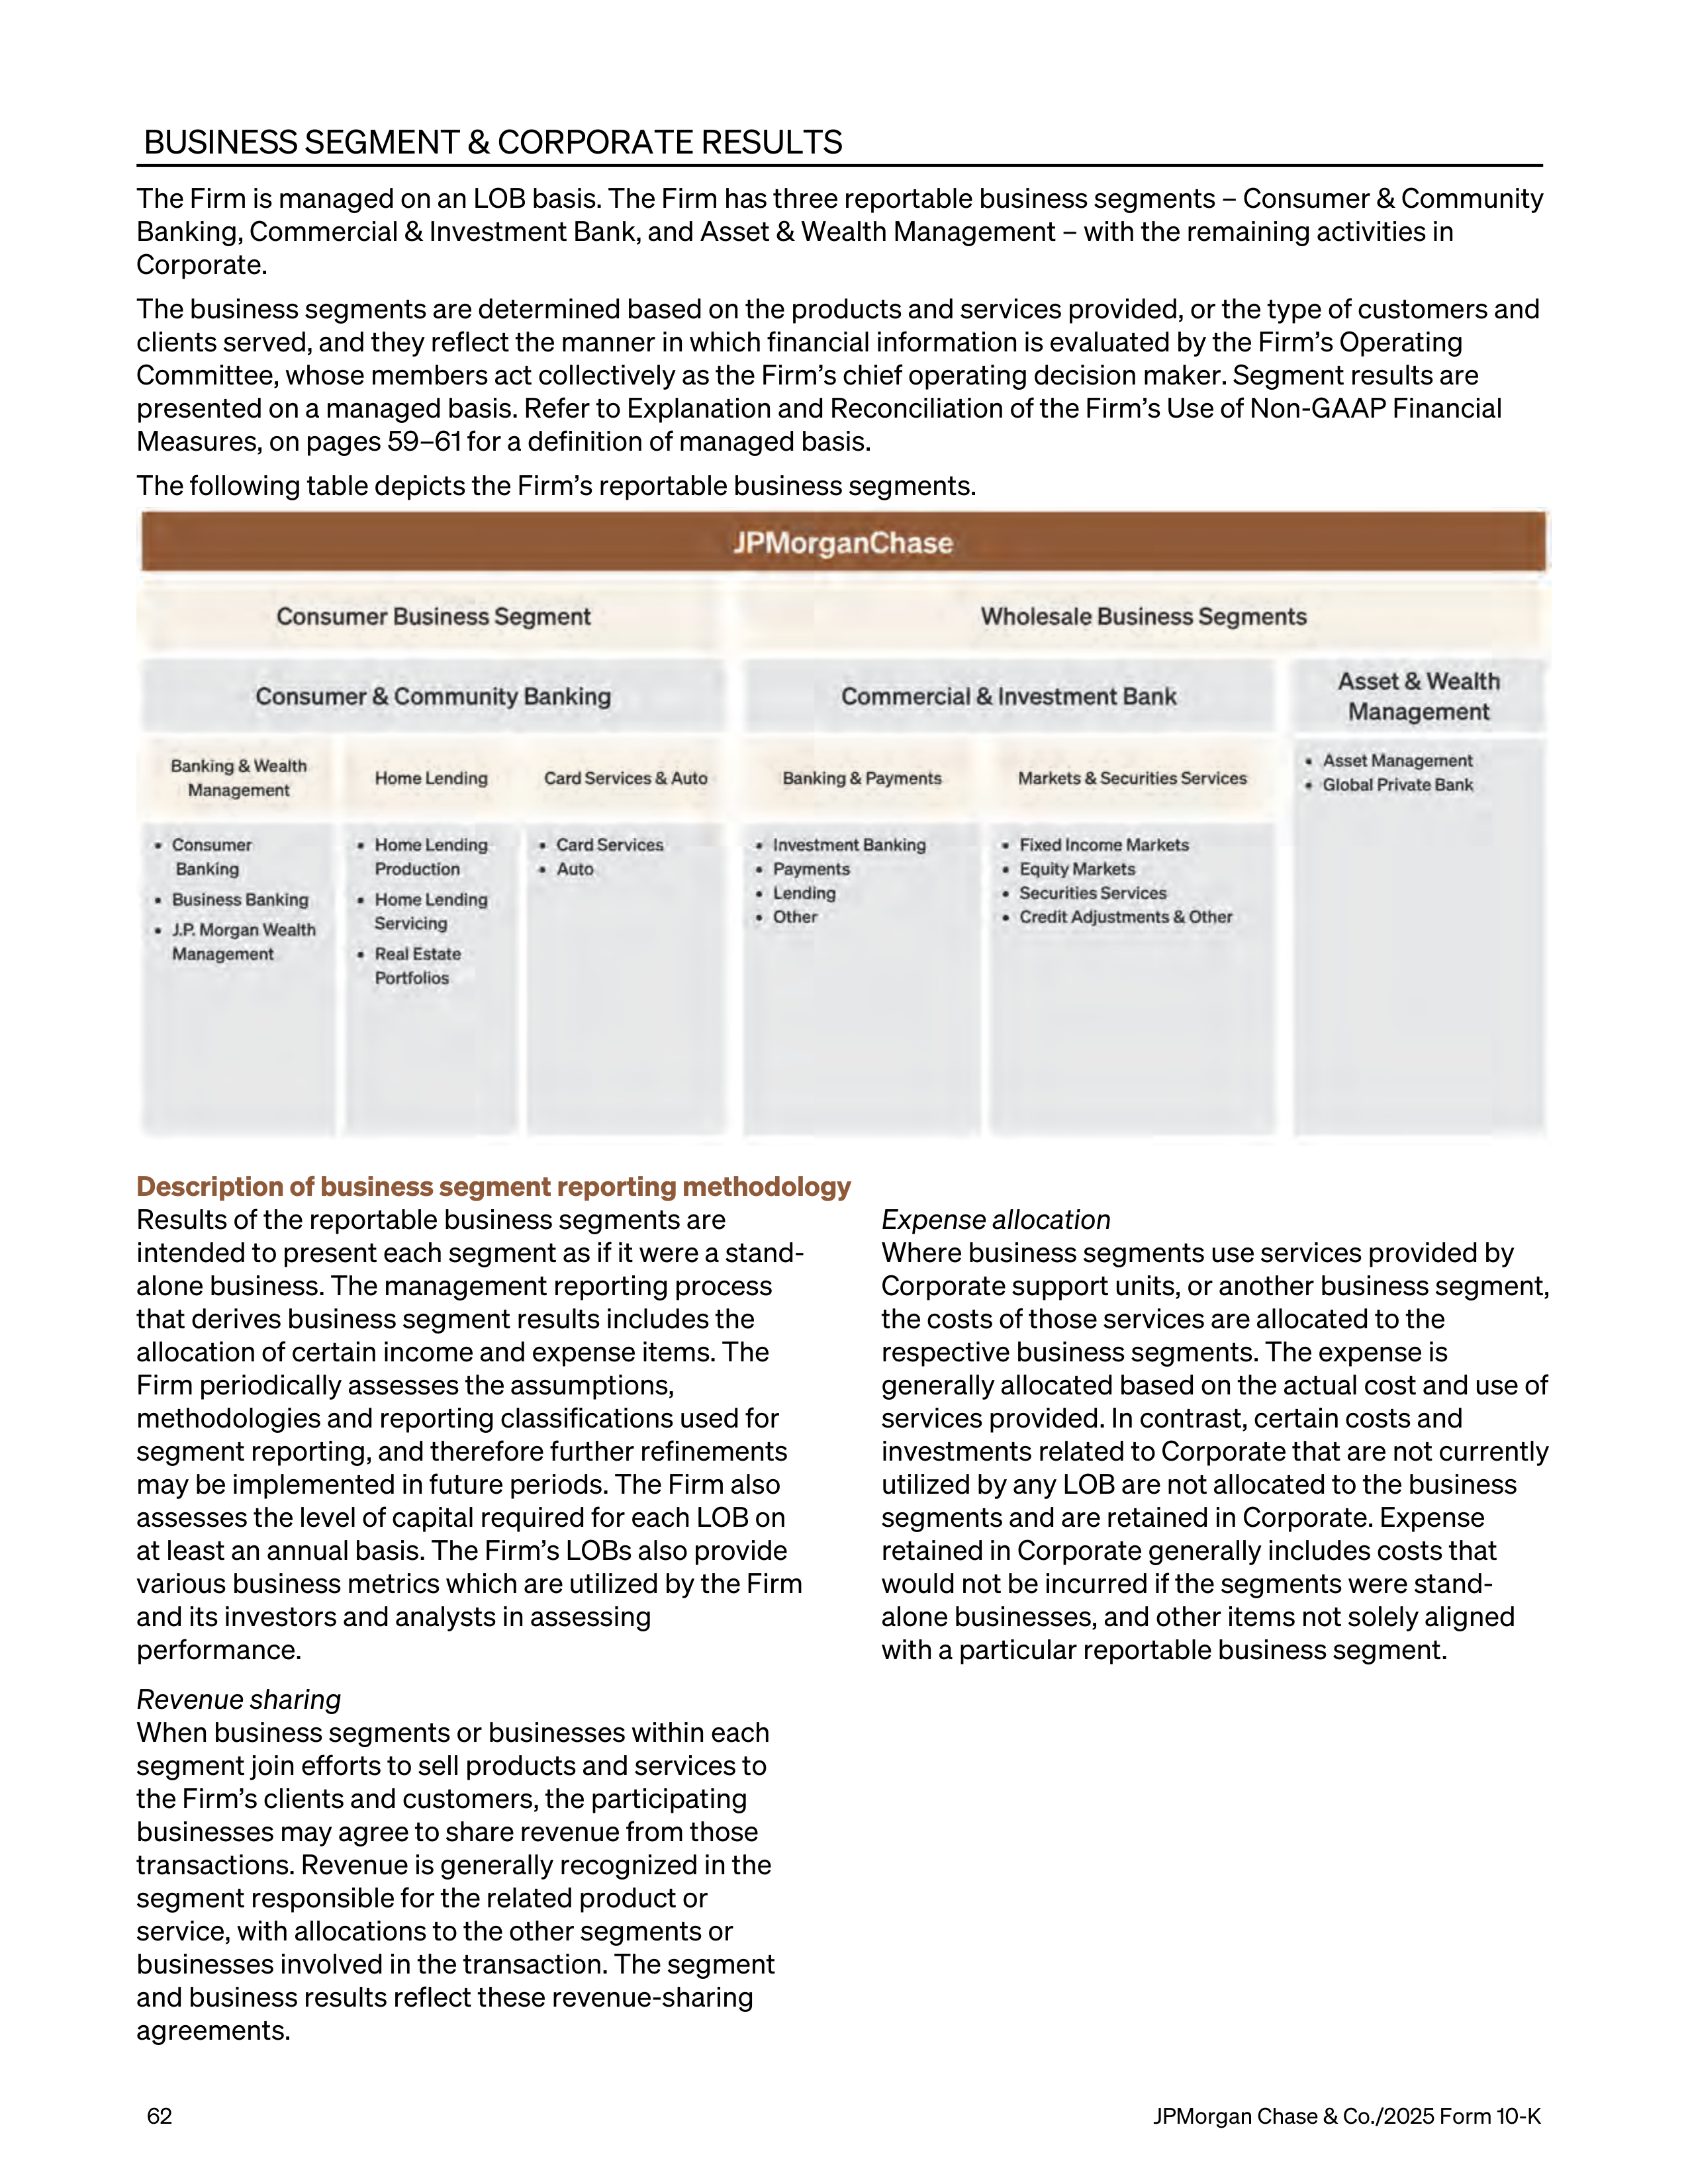

BUSINESS SEGMENT & CORPORATE RESULTS
The Firm is managed on an LOB basis. The Firm has three reportable business segments – Consumer & Community
Banking, Commercial & Investment Bank, and Asset & Wealth Management – with the remaining activities in
Corporate.
The business segments are determined based on the products and services provided, or the type of customers and
clients served, and they reflect the manner in which financial information is evaluated by the Firm’s Operating
Committee, whose members act collectively as the Firm’s chief operating decision maker. Segment results are
presented on a managed basis. Refer to Explanation and Reconciliation of the Firm’s Use of Non-GAAP Financial
Measures, on pages 59–61 for a definition of managed basis.
The following table depicts the Firm’s reportable business segments.
Description of business segment reporting methodology
Results of the reportable business segments are
intended to present each segment as if it were a stand-
alone business. The management reporting process
that derives business segment results includes the
allocation of certain income and expense items. The
Firm periodically assesses the assumptions,
methodologies and reporting classifications used for
segment reporting, and therefore further refinements
may be implemented in future periods. The Firm also
assesses the level of capital required for each LOB on
at least an annual basis. The Firm’s LOBs also provide
various business metrics which are utilized by the Firm
and its investors and analysts in assessing
performance.
Revenue sharing
When business segments or businesses within each
segment join efforts to sell products and services to
the Firm’s clients and customers, the participating
businesses may agree to share revenue from those
transactions. Revenue is generally recognized in the
segment responsible for the related product or
service, with allocations to the other segments or
businesses involved in the transaction. The segment
and business results reflect these revenue-sharing
agreements.
Expense allocation
Where business segments use services provided by
Corporate support units, or another business segment,
the costs of those services are allocated to the
respective business segments. The expense is
generally allocated based on the actual cost and use of
services provided. In contrast, certain costs and
investments related to Corporate that are not currently
utilized by any LOB are not allocated to the business
segments and are retained in Corporate. Expense
retained in Corporate generally includes costs that
would not be incurred if the segments were stand-
alone businesses, and other items not solely aligned
with a particular reportable business segment.
62
JPMorgan Chase & Co./2025 Form 10-K
Funds transfer pricing
Funds transfer pricing (“FTP”) is the process by which
the Firm allocates interest income and expense to the
LOBs and Other Corporate and transfers the primary
interest rate risk and liquidity risk to Treasury and CIO.
The funds transfer pricing process considers the
interest rate and liquidity risk characteristics of assets
and liabilities and off-balance sheet products.
Periodically, the methodology and assumptions
utilized in the FTP process are adjusted to reflect
economic conditions and other factors, which may
impact the allocation of net interest income to the
segments. Effective in the fourth quarter of 2024, the
Firm updated its FTP with respect to consumer
deposits, which resulted in an increase in the funding
benefit reflected within CCB’s net interest income that
is fully offset in Corporate, with no effect on the Firm’s
net interest income.
As a result of lower average interest rates in the
current year, the cost of funding for assets and the
funding benefit earned for liabilities generally
decreased compared with the prior year. During the
period ended December 31, 2025, this resulted in a
lower cost of funds for loans and Markets activities. In
addition, the FTP benefit for deposits generally
decreased more than the decrease in rates paid to
deposit holders during the year, resulting in an overall
deposit margin compression.
Foreign exchange risk
Foreign exchange risk is transferred from the LOBs
and Other Corporate to Treasury and CIO for certain
revenues and expenses. Treasury and CIO manages
these risks centrally and reports the impact of foreign
exchange rate movements related to the transferred
risk in its results. Refer to Market Risk Management on
page 142 for additional information.
Debt expense and preferred stock dividend allocation
As part of the FTP process, almost all of the cost of the
credit spread component of outstanding unsecured
long-term debt and preferred stock dividends is
allocated to the reportable business segments, while
the balance of the cost is retained in Corporate. The
methodology to allocate the cost of unsecured long-
term debt and preferred stock dividends to the
business segments is aligned with the relevant
regulatory capital requirements and funding needs of
the LOBs, as applicable. The allocated cost of
unsecured long-term debt is included in a business
segment’s net interest income, and net income is
reduced by preferred stock dividends, to arrive at a
business segment’s net income applicable to common
equity. Refer to Capital Risk Management on pages
89–99 for additional information.
Capital allocation
The amount of capital assigned to each LOB and
Corporate is referred to as equity. The Firm’s current
equity allocation methodology incorporates Basel III
Standardized risk-weighted assets (“RWA”) and the
global systemically important banks (“GSIB”)
surcharge, both under rules currently in effect, as well
as a simulation of capital depletion in a severe stress
environment. At least annually, the assumptions,
judgments and methodologies used to allocate capital
are reassessed and, as a result, the capital allocated to
the LOBs and Corporate may change. Refer to Line of
business and Corporate equity on page 96 for
additional information on capital allocation.
JPMorgan Chase & Co./2025 Form 10-K
63
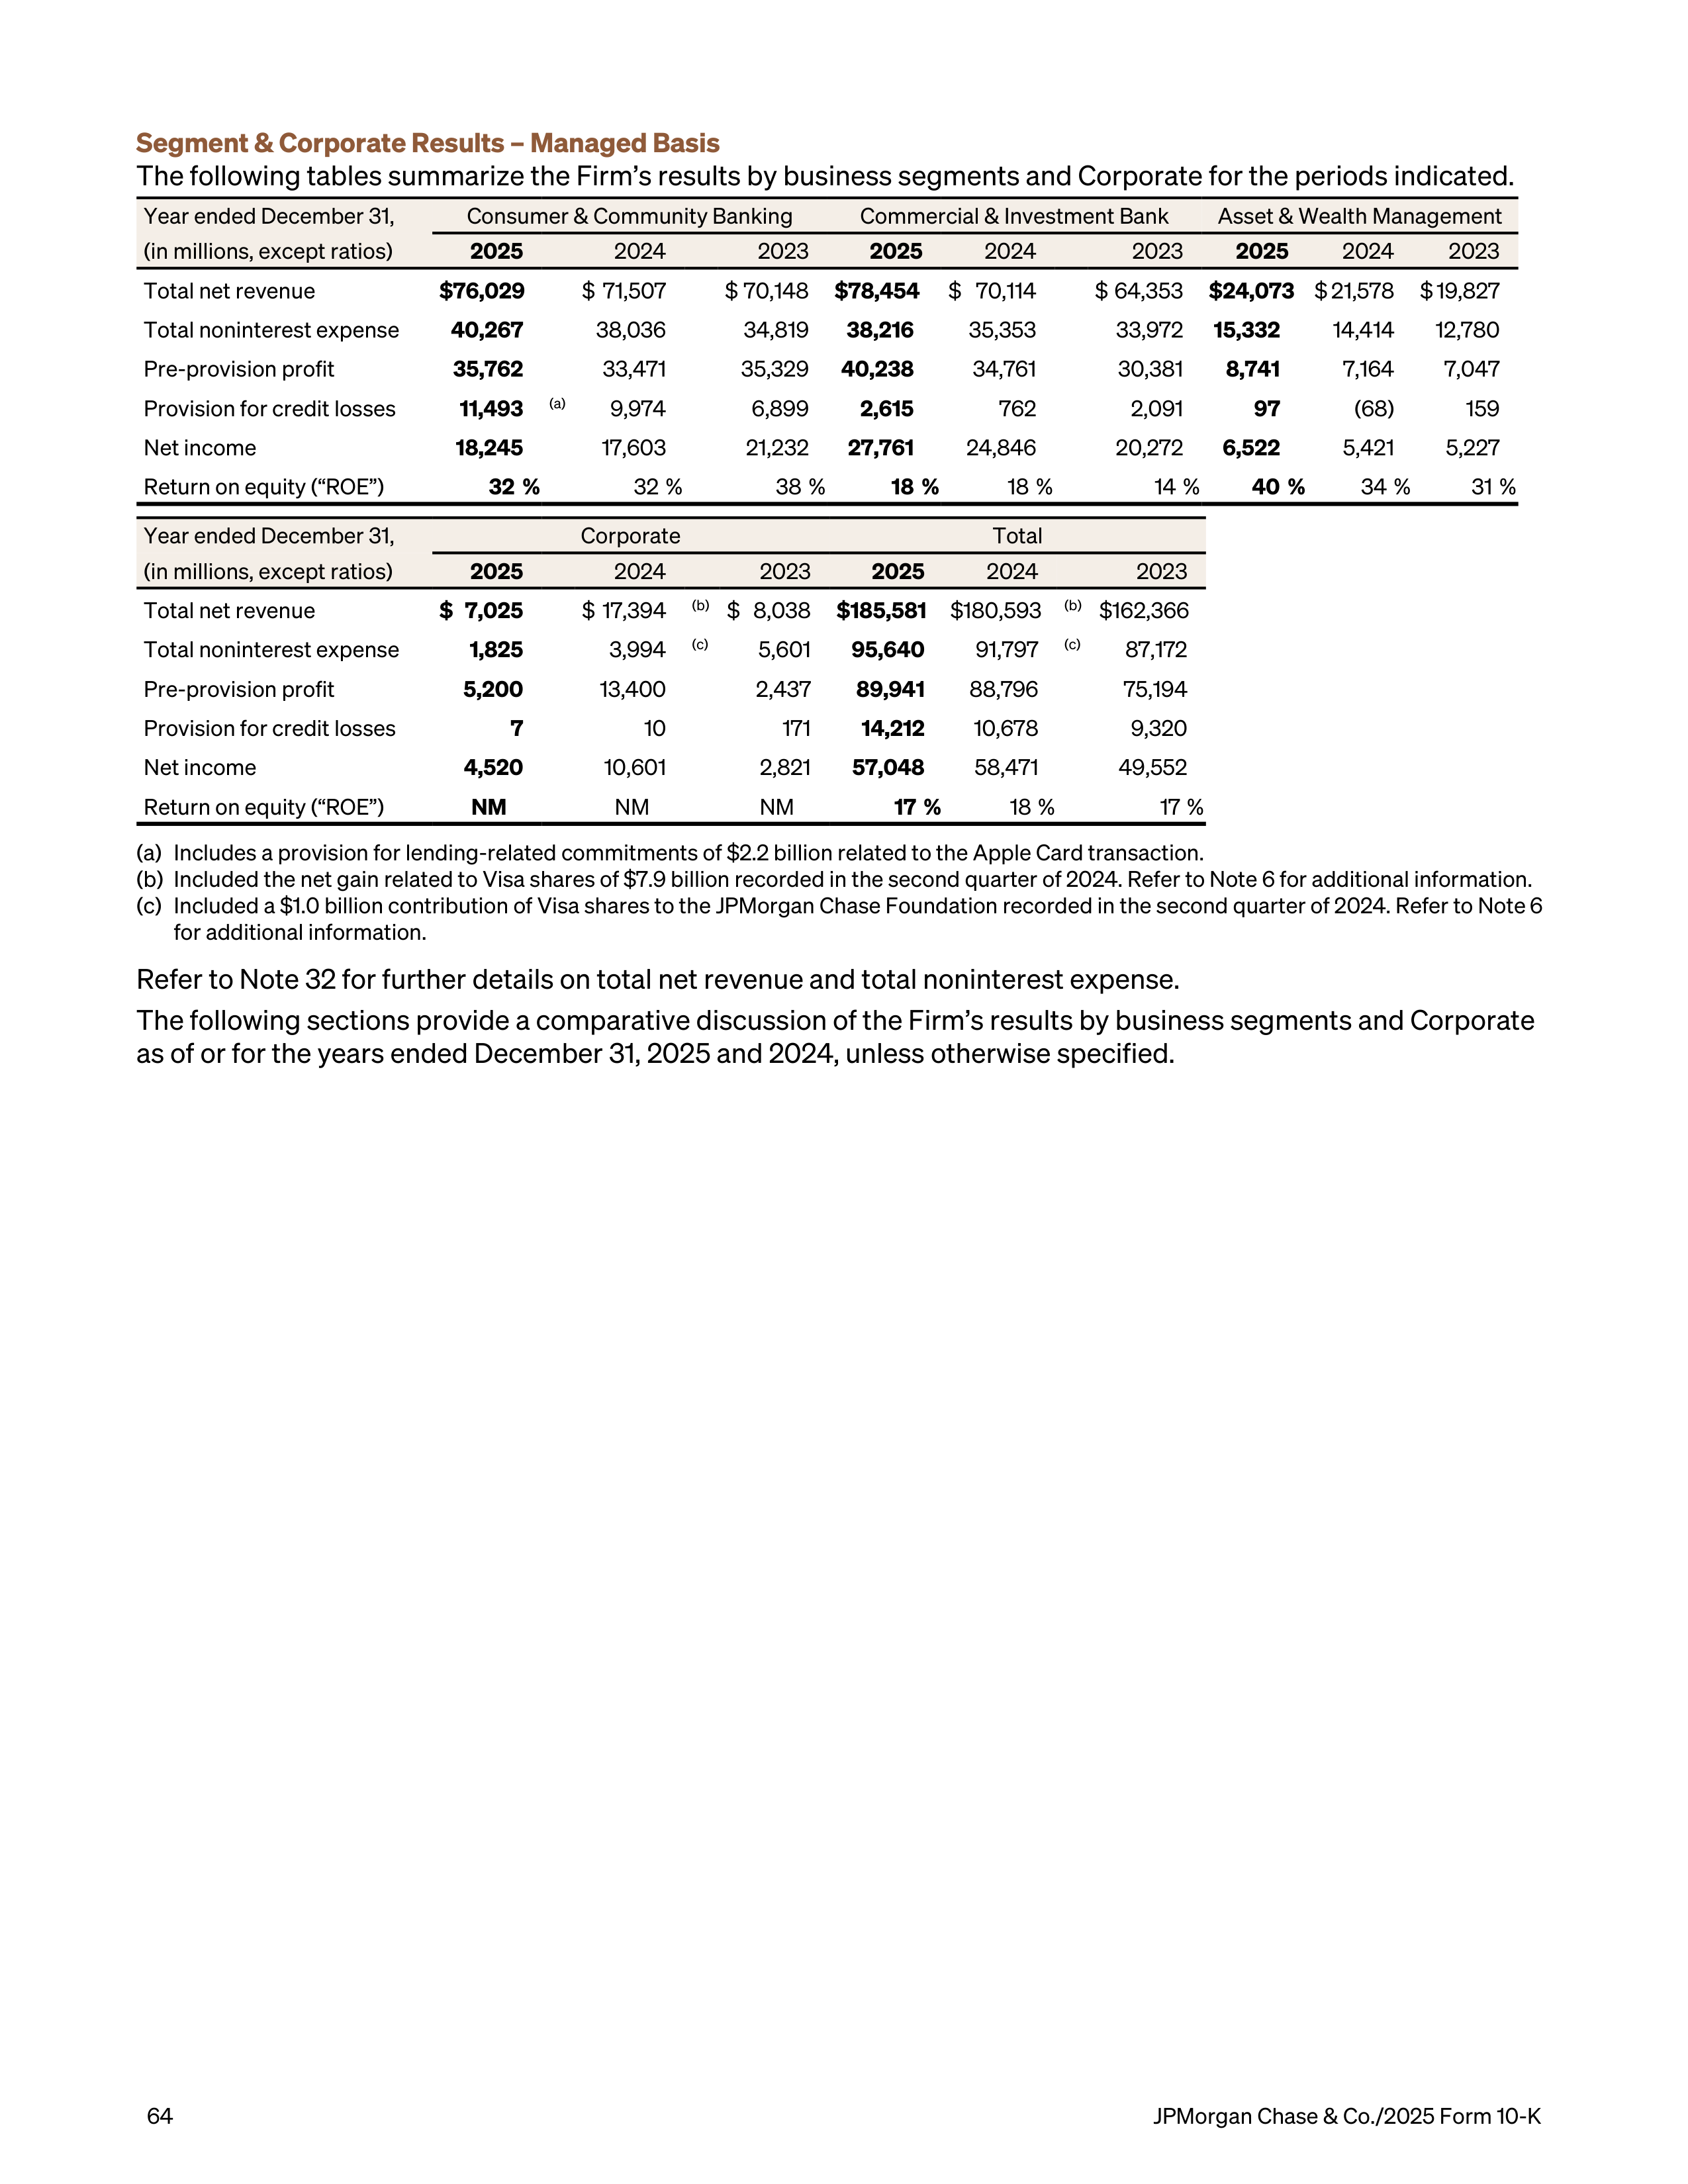
Segment & Corporate Results – Managed Basis
The following tables summarize the Firm’s results by business segments and Corporate for the periods indicated.
Year ended December 31,
Consumer & Community Banking
Commercial & Investment Bank
Asset & Wealth Management
(in millions, except ratios)
2025
2024
2023
2025
2024
2023
2025
2024
2023
Total net revenue
$ 76,029
$ 71,507
$ 70,148
$ 78,454
$ 70,114
$ 64,353
$ 24,073
$ 21,578
$ 19,827
Total noninterest expense
40,267
38,036
34,819
38,216
35,353
33,972
15,332
14,414
12,780
Pre-provision profit
35,762
33,471
35,329
40,238
34,761
30,381
8,741
7,164
7,047
Provision for credit losses
11,493
(a)
9,974
6,899
2,615
762
2,091
97
(68)
159
Net income
18,245
17,603
21,232
27,761
24,846
20,272
6,522
5,421
5,227
Return on equity (“ROE”)
32 %
32 %
38 %
18 %
18 %
14 %
40 %
34 %
31 %
Year ended December 31,
Corporate
Total
(in millions, except ratios)
2025
2024
2023
2025
2024
2023
Total net revenue
$ 7,025
$ 17,394
(b)
$ 8,038
$ 185,581
$ 180,593
(b)
$ 162,366
Total noninterest expense
1,825
3,994
(c)
5,601
95,640
91,797
(c)
87,172
Pre-provision profit
5,200
13,400
2,437
89,941
88,796
75,194
Provision for credit losses
7
10
171
14,212
10,678
9,320
Net income
4,520
10,601
2,821
57,048
58,471
49,552
Return on equity (“ROE”)
NM
NM
NM
17 %
18 %
17 %
(a)
Includes a provision for lending-related commitments of $2.2 billion related to the Apple Card transaction.
(b)
Included the net gain related to Visa shares of $7.9 billion recorded in the second quarter of 2024. Refer to Note 6 for additional information.
(c)
Included a $1.0 billion contribution of Visa shares to the JPMorgan Chase Foundation recorded in the second quarter of 2024. Refer to Note 6
for additional information.
Refer to Note 32 for further details on total net revenue and total noninterest expense.
The following sections provide a comparative discussion of the Firm’s results by business segments and Corporate
as of or for the years ended December 31, 2025 and 2024, unless otherwise specified.
64
JPMorgan Chase & Co./2025 Form 10-K
CONSUMER & COMMUNITY BANKING
Consumer & Community Banking offers products
and services to consumers and small businesses
through bank branches, ATMs, digital (including
mobile and online) and telephone banking. CCB is
organized into Banking & Wealth Management
(including Consumer Banking, Business Banking
and J.P. Morgan Wealth Management), Home
Lending (including Home Lending Production,
Home Lending Servicing and Real Estate
Portfolios) and Card Services & Auto. Banking &
Wealth Management offers deposit, investment
and lending products, cash management,
payments and services. Home Lending includes
mortgage origination and servicing activities, as
well as portfolios consisting of residential
mortgages and home equity loans. Card Services
issues credit cards and offers payment solutions,
travel services, merchant offers and lifestyle
benefits. Auto originates and services auto loans
and leases.
Selected income statement data
Year ended December 31,
(in millions, except ratios)
2025
2024
2023
Revenue
Lending- and deposit-
related fees
$ 3,669
$ 3,387
$ 3,356
Asset management fees
4,669
4,014
3,282
Mortgage fees and
related income
1,326
1,378
1,175
Card income
2,230
3,139
2,532
All other income
(a)
5,901
4,731
4,773
Noninterest revenue
17,795
16,649
15,118
Net interest income
58,234
54,858
55,030
Total net revenue
76,029
71,507
70,148
Provision for credit losses
11,493
(d)
9,974
6,899
Noninterest expense
Compensation expense
17,669
17,045
15,171
Noncompensation
expense
(b)
22,598
20,991
19,648
Total noninterest
expense
40,267
38,036
34,819
Income before income
tax expense
24,269
23,497
28,430
Income tax expense
6,024
5,894
7,198
Net income
$ 18,245
$ 17,603
$ 21,232
Revenue by business
Banking & Wealth
Management
$ 42,862
$ 40,943
$ 43,199
Home Lending
4,966
5,097
4,140
Card Services & Auto
28,201
25,467
22,809
Mortgage fees and
related income details:
Production revenue
622
627
421
Net mortgage servicing
revenue
(c)
704
751
754
Mortgage fees and
related income
$ 1,326
$ 1,378
$
1,175
Financial ratios
Return on equity
32 %
32 %
38 %
Overhead ratio
53
53
50
(a)
Primarily includes operating lease income and commissions and
other fees. Operating lease income was $3.8 billion, $2.8 billion
and $2.8 billion for the years ended December 31, 2025, 2024
and 2023, respectively.
(b)
Included depreciation expense on leased assets of $2.4 billion,
$1.7 billion and $1.7 billion for the years ended December 31,
2025, 2024 and 2023, respectively.
(c)
Included MSR risk management results of $118 million, $159
million and $131 million for the years ended December 31, 2025,
2024 and 2023, respectively.
(d)
Includes a provision for lending-related commitments of $2.2
billion related to the Apple Card transaction.
JPMorgan Chase & Co./2025 Form 10-K
65
2025 compared with 2024
Net income was $18.2 billion, up 4%.
Net revenue was $76.0 billion, up 6%.
Net interest income was $58.2 billion, up 6%,
reflecting:
•
higher NII in Card Services, predominantly driven by
higher revolving balances, and
•
higher NII in Banking & Wealth Management
(“BWM”), driven by higher deposit margin, reflecting
the impact of changes in FTP, partially offset by
lower average deposit balances.
Refer to Business Segment & Corporate Results on
page 63 for additional information on FTP.
Noninterest revenue was $17.8 billion, up 7%, driven
by:
•
higher auto operating lease income as a result of
growth in volume, and
•
in BWM, higher asset management fees, reflecting
higher average market levels and net inflows, as well
as higher deposit-related fees as a result of higher
transaction volume and new accounts,
partially offset by
•
lower card income, reflecting lower net interchange,
as well as an increase in amortization related to new
account origination costs, partially offset by higher
annual fees. Net interchange decreased as the
impact of increased debit and credit card sales
volume was more than offset by higher rewards
costs and partner payments.
Refer to Note 6 for additional information on card
income, asset management fees, and deposit-related
fees; and Critical Accounting Estimates on pages 154–
157 for additional information on the credit card
rewards liability.
Noninterest expense was $40.3 billion, up 6%,
reflecting:
•
higher noncompensation expense, predominantly
driven by higher auto lease depreciation on higher
auto operating lease assets, and continued
investments in marketing and technology, as well as
•
higher compensation expense, predominantly for
bankers and advisors, and employees in technology.
The provision for credit losses was $11.5 billion. Net
charge-offs were $8.2 billion, up $319 million, primarily
driven by Card Services, reflecting loan growth. The
net addition to the allowance for credit losses of $3.2
billion which was driven by $2.2 billion related to the
Apple Card transaction, loan growth in Card Services
and the impact of changes in the Firm's weighted-
average macroeconomic outlook, partially offset by
reduced borrower uncertainty.
In the prior year, the provision was $10.0 billion, net
charge-offs were $7.9 billion and the net addition to
the allowance for credit losses was $2.0 billion.
Refer to Credit and Investment Risk Management on
pages 109–132 and Allowance for Credit Losses on
pages 129–131 for a further discussion of the credit
portfolios and the allowance for credit losses.
66
JPMorgan Chase & Co./2025 Form 10-K
Selected metrics
As of or for the year ended
December 31,
(in millions, except
employees)
2025
2024
2023
Selected balance sheet
data (period-end)
Total assets
$ 664,669
$ 650,268
$ 642,951
Loans:
Banking & Wealth
Management
33,005
33,221
31,142
Home Lending
(a)
240,724
246,498
259,181
Card Services
247,753
233,016
211,175
Auto
70,585
73,619
77,705
Total loans
592,067
586,354
579,203
Deposits
(b)
1,072,792
1,056,652
1,094,738
Equity
56,000
54,500
55,500
Selected balance sheet
data (average)
Total assets
$ 646,820
$ 631,648
$ 584,367
Loans:
Banking & Wealth
Management
33,241
31,544
30,142
Home Lending
(b)
242,595
252,542
232,115
Card Services
231,720
214,139
191,424
Auto
71,359
75,009
72,674
Total loans
578,915
573,234
526,355
Deposits
1,057,232
1,064,215
1,126,552
Equity
56,000
54,500
54,349
Employees
144,196
(c)
144,989
141,640
(a)
At December 31, 2025, 2024 and 2023, Home Lending loans
held-for-sale and loans at fair value were $11.0 billion, $8.1 billion
and $3.4 billion, respectively.
(b)
Average Home Lending loans held-for-sale and loans at fair
value were $9.5 billion, $7.1 billion and $4.8 billion for the years
ended December 31, 2025, 2024 and 2023, respectively.
(c)
In the first quarter of 2025, 419 employees were transferred to
Corporate as a result of the centralization of certain functions.
Selected metrics
As of or for the year ended
December 31,
(in millions, except ratio
data)
2025
2024
2023
Credit data and quality
statistics
Nonaccrual loans
(a)
$ 3,484
$ 3,366
$ 3,740
Net charge-offs/(recoveries)
Banking & Wealth
Management
356
442
340
Home Lending
(122)
(106)
(56)
Card Services
7,678
7,148
4,699
Auto
335
444
357
Total net charge-offs/
(recoveries)
$ 8,247
$ 7,928
$ 5,340
Net charge-off/(recovery)
rate
Banking & Wealth
Management
1.07 %
1.40 %
1.13 %
Home Lending
(0.05)
(0.04)
(0.02)
Card Services
3.31
3.34
2.45
Auto
0.47
0.59
0.49
Total net charge-off/
(recovery) rate
1.45 %
1.40 %
1.02 %
30+ day delinquency rate
Home Lending
(b)
0.86 %
0.78 %
0.66 %
Card Services
2.16
2.17
2.14
Auto
1.33
1.43
1.19
90+ day delinquency rate -
Card Services
1.10 %
1.14 %
1.05 %
Allowance for credit losses:
Allowance for loan losses
Banking & Wealth
Management
$
765
$
764
$
685
Home Lending
647
447
578
Card Services
15,558
14,608
12,453
Auto
587
692
742
Total allowance for
loan losses
$ 17,557
$ 16,511
$ 14,458
Allowance for lending-
related commitments
$ 2,290
(c)
$
91
$
97
Total allowance for
credit losses
$ 19,847
$ 16,602
$ 14,555
(a)
Excludes mortgage loans past due and insured by U.S.
government agencies, which are primarily 90 or more days past
due. These loans have been excluded based upon the
government guarantee. At December 31, 2025, 2024 and 2023,
mortgage loans 90 or more days past due and insured by U.S.
government agencies were $70 million, $84 million and $123
million, respectively. In addition, the Firm’s policy is generally to
exempt credit card loans from being placed on nonaccrual
status as permitted by regulatory guidance.
(b)
At December 31, 2025, 2024 and 2023, excluded mortgage
loans insured by U.S. government agencies of $102 million, $122
million and $176 million, respectively, that are 30 or more days
past due. These amounts have been excluded based upon the
government guarantee.
(c)
Includes $2.2 billion related to the Apple Card transaction.
JPMorgan Chase & Co./2025 Form 10-K
67
Selected metrics
As of or for the year
ended December 31,
(in billions, except ratios
and where otherwise
noted)
2025
2024
2023
Business Metrics
CCB Consumer
customers (in millions)
86.6
84.4
82.1
CCB Small business
customers (in millions)
7.4
7.0
6.4
Number of branches
5,083
4,966
4,897
Active digital customers
(in thousands)
(a)
74,646
70,813
66,983
Active mobile customers
(in thousands)
(b)
61,736
57,821
53,828
Debit and credit card
sales volume
$ 1,940.7
$ 1,805.4
$ 1,678.6
Total payments
transaction volume (in
trillions)
(c)
7.0
6.4
5.9
Banking & Wealth
Management
Average deposits
$ 1,040.8
$ 1,049.3
$ 1,111.7
Deposit margin
2.74 %
2.66 %
2.84 %
Business Banking
average loans
$
19.1
$
19.5
$
19.6
Business Banking
origination volume
3.2
4.5
4.8
Client investment
assets
(d)
1,269.9
1,087.6
951.1
Number of client advisors
6,049
5,755
5,456
Home Lending
Mortgage origination
volume by channel
Retail
$
33.0
$
25.5
$
22.4
Correspondent
19.8
15.3
12.7
Total mortgage
origination volume
(e)
$
52.8
$
40.8
$
35.1
Third-party mortgage
loans serviced (period-
end)
$ 661.9
$ 648.0
$
631.2
MSR carrying value
(period-end)
9.1
9.1
8.5
Card Services
Sales volume, excluding
commercial card
$ 1,354.7
$ 1,259.3
$ 1,163.6
Net revenue rate
10.08 %
10.03 %
9.72 %
Net yield on average
loans
10.26
9.73
9.61
New credit card accounts
opened (in millions)
10.4
10.0
10.0
Cards in force
(in millions)
(f)
116.5
111.7
106.8
Auto
Loan and lease
origination volume
$
44.8
$
40.3
$
41.3
Average auto
operating lease assets
16.2
11.1
10.9
(a)
Users of all web and/or mobile platforms who have logged in
within the past 90 days.
(b)
Users of all mobile platforms who have logged in within the past
90 days.
(c)
Total payments transaction volume includes debit and credit
card sales volume and gross outflows of ACH, ATM, teller, wires,
BillPay, PayChase, Zelle, person-to-person and checks.
(d)
Includes assets invested in managed accounts and J.P. Morgan
mutual funds where AWM is the investment manager. Refer to
AWM segment results on pages 76–79 for additional
information.
(e)
Firmwide mortgage origination volume was $63.4 billion, $47.4
billion and $41.4 billion for the years ended December 31, 2025,
2024 and 2023, respectively.
(f)
Represents the total number of open credit cards, inclusive of
primary cardholders and authorized users.
68
JPMorgan Chase & Co./2025 Form 10-K
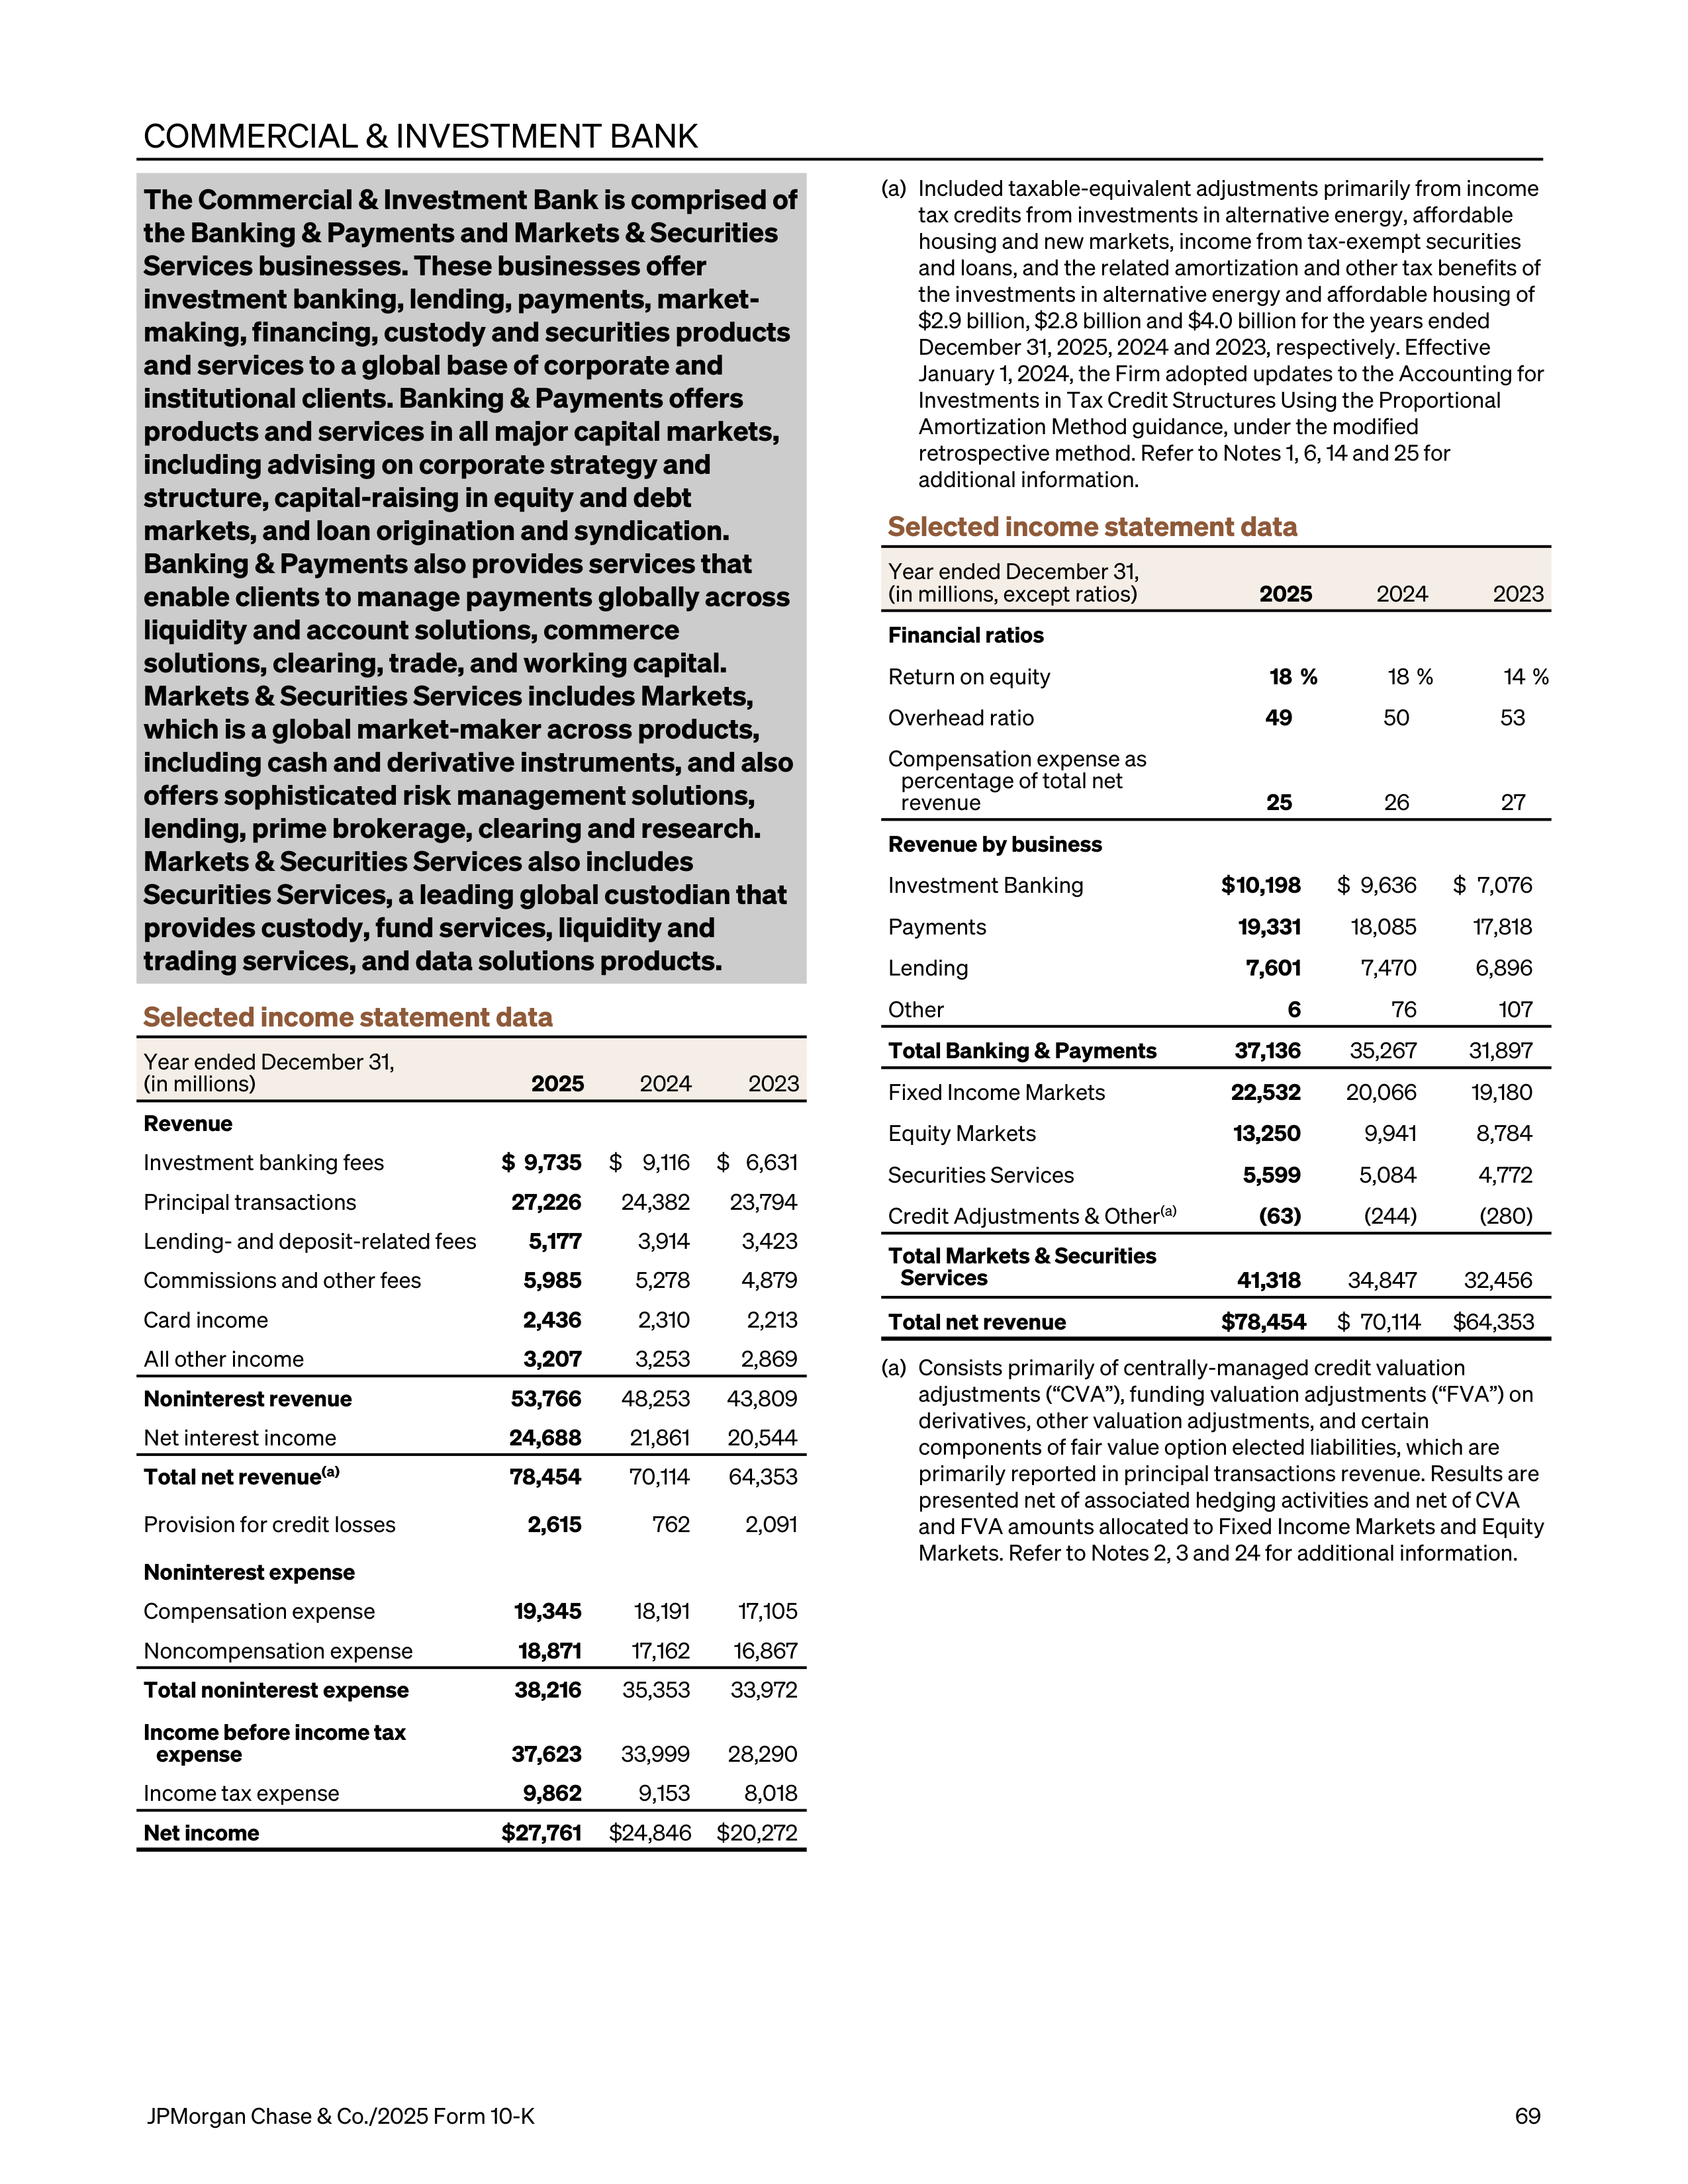
COMMERCIAL & INVESTMENT BANK
The Commercial & Investment Bank is comprised of
the Banking & Payments and Markets & Securities
Services businesses. These businesses offer
investment banking, lending, payments, market-
making, financing, custody and securities products
and services to a global base of corporate and
institutional clients. Banking & Payments offers
products and services in all major capital markets,
including advising on corporate strategy and
structure, capital-raising in equity and debt
markets, and loan origination and syndication.
Banking & Payments also provides services that
enable clients to manage payments globally across
liquidity and account solutions, commerce
solutions, clearing, trade, and working capital.
Markets & Securities Services includes Markets,
which is a global market-maker across products,
including cash and derivative instruments, and also
offers sophisticated risk management solutions,
lending, prime brokerage, clearing and research.
Markets & Securities Services also includes
Securities Services, a leading global custodian that
provides custody, fund services, liquidity and
trading services, and data solutions products.
Selected income statement data
Year ended December 31,
(in millions)
2025
2024
2023
Revenue
Investment banking fees
$ 9,735
$ 9,116
$ 6,631
Principal transactions
27,226
24,382
23,794
Lending- and deposit-related fees
5,177
3,914
3,423
Commissions and other fees
5,985
5,278
4,879
Card income
2,436
2,310
2,213
All other income
3,207
3,253
2,869
Noninterest revenue
53,766
48,253
43,809
Net interest income
24,688
21,861
20,544
Total net revenue
(a)
78,454
70,114
64,353
Provision for credit losses
2,615
762
2,091
Noninterest expense
Compensation expense
19,345
18,191
17,105
Noncompensation expense
18,871
17,162
16,867
Total noninterest expense
38,216
35,353
33,972
Income before income tax
expense
37,623
33,999
28,290
Income tax expense
9,862
9,153
8,018
Net income
$ 27,761
$ 24,846
$ 20,272
(a)
Included taxable-equivalent adjustments primarily from income
tax credits from investments in alternative energy, affordable
housing and new markets, income from tax-exempt securities
and loans, and the related amortization and other tax benefits of
the investments in alternative energy and affordable housing of
$2.9 billion, $2.8 billion and $4.0 billion for the years ended
December 31, 2025, 2024 and 2023, respectively. Effective
January 1, 2024, the Firm adopted updates to the Accounting for
Investments in Tax Credit Structures Using the Proportional
Amortization Method guidance, under the modified
retrospective method. Refer to Notes 1, 6, 14 and 25 for
additional information.
Selected income statement data
Year ended December 31,
(in millions, except ratios)
2025
2024
2023
Financial ratios
Return on equity
18 %
18 %
14 %
Overhead ratio
49
50
53
Compensation expense as
percentage of total net
revenue
25
26
27
Revenue by business
Investment Banking
$ 10,198
$ 9,636
$ 7,076
Payments
19,331
18,085
17,818
Lending
7,601
7,470
6,896
Other
6
76
107
Total Banking & Payments
37,136
35,267
31,897
Fixed Income Markets
22,532
20,066
19,180
Equity Markets
13,250
9,941
8,784
Securities Services
5,599
5,084
4,772
Credit Adjustments & Other
(a)
(63)
(244)
(280)
Total Markets & Securities
Services
41,318
34,847
32,456
Total net revenue
$ 78,454
$ 70,114
$ 64,353
(a)
Consists primarily of centrally-managed credit valuation
adjustments (“CVA”), funding valuation adjustments (“FVA”) on
derivatives, other valuation adjustments, and certain
components of fair value option elected liabilities, which are
primarily reported in principal transactions revenue. Results are
presented net of associated hedging activities and net of CVA
and FVA amounts allocated to Fixed Income Markets and Equity
Markets. Refer to Notes 2, 3 and 24 for additional information.
JPMorgan Chase & Co./2025 Form 10-K
69
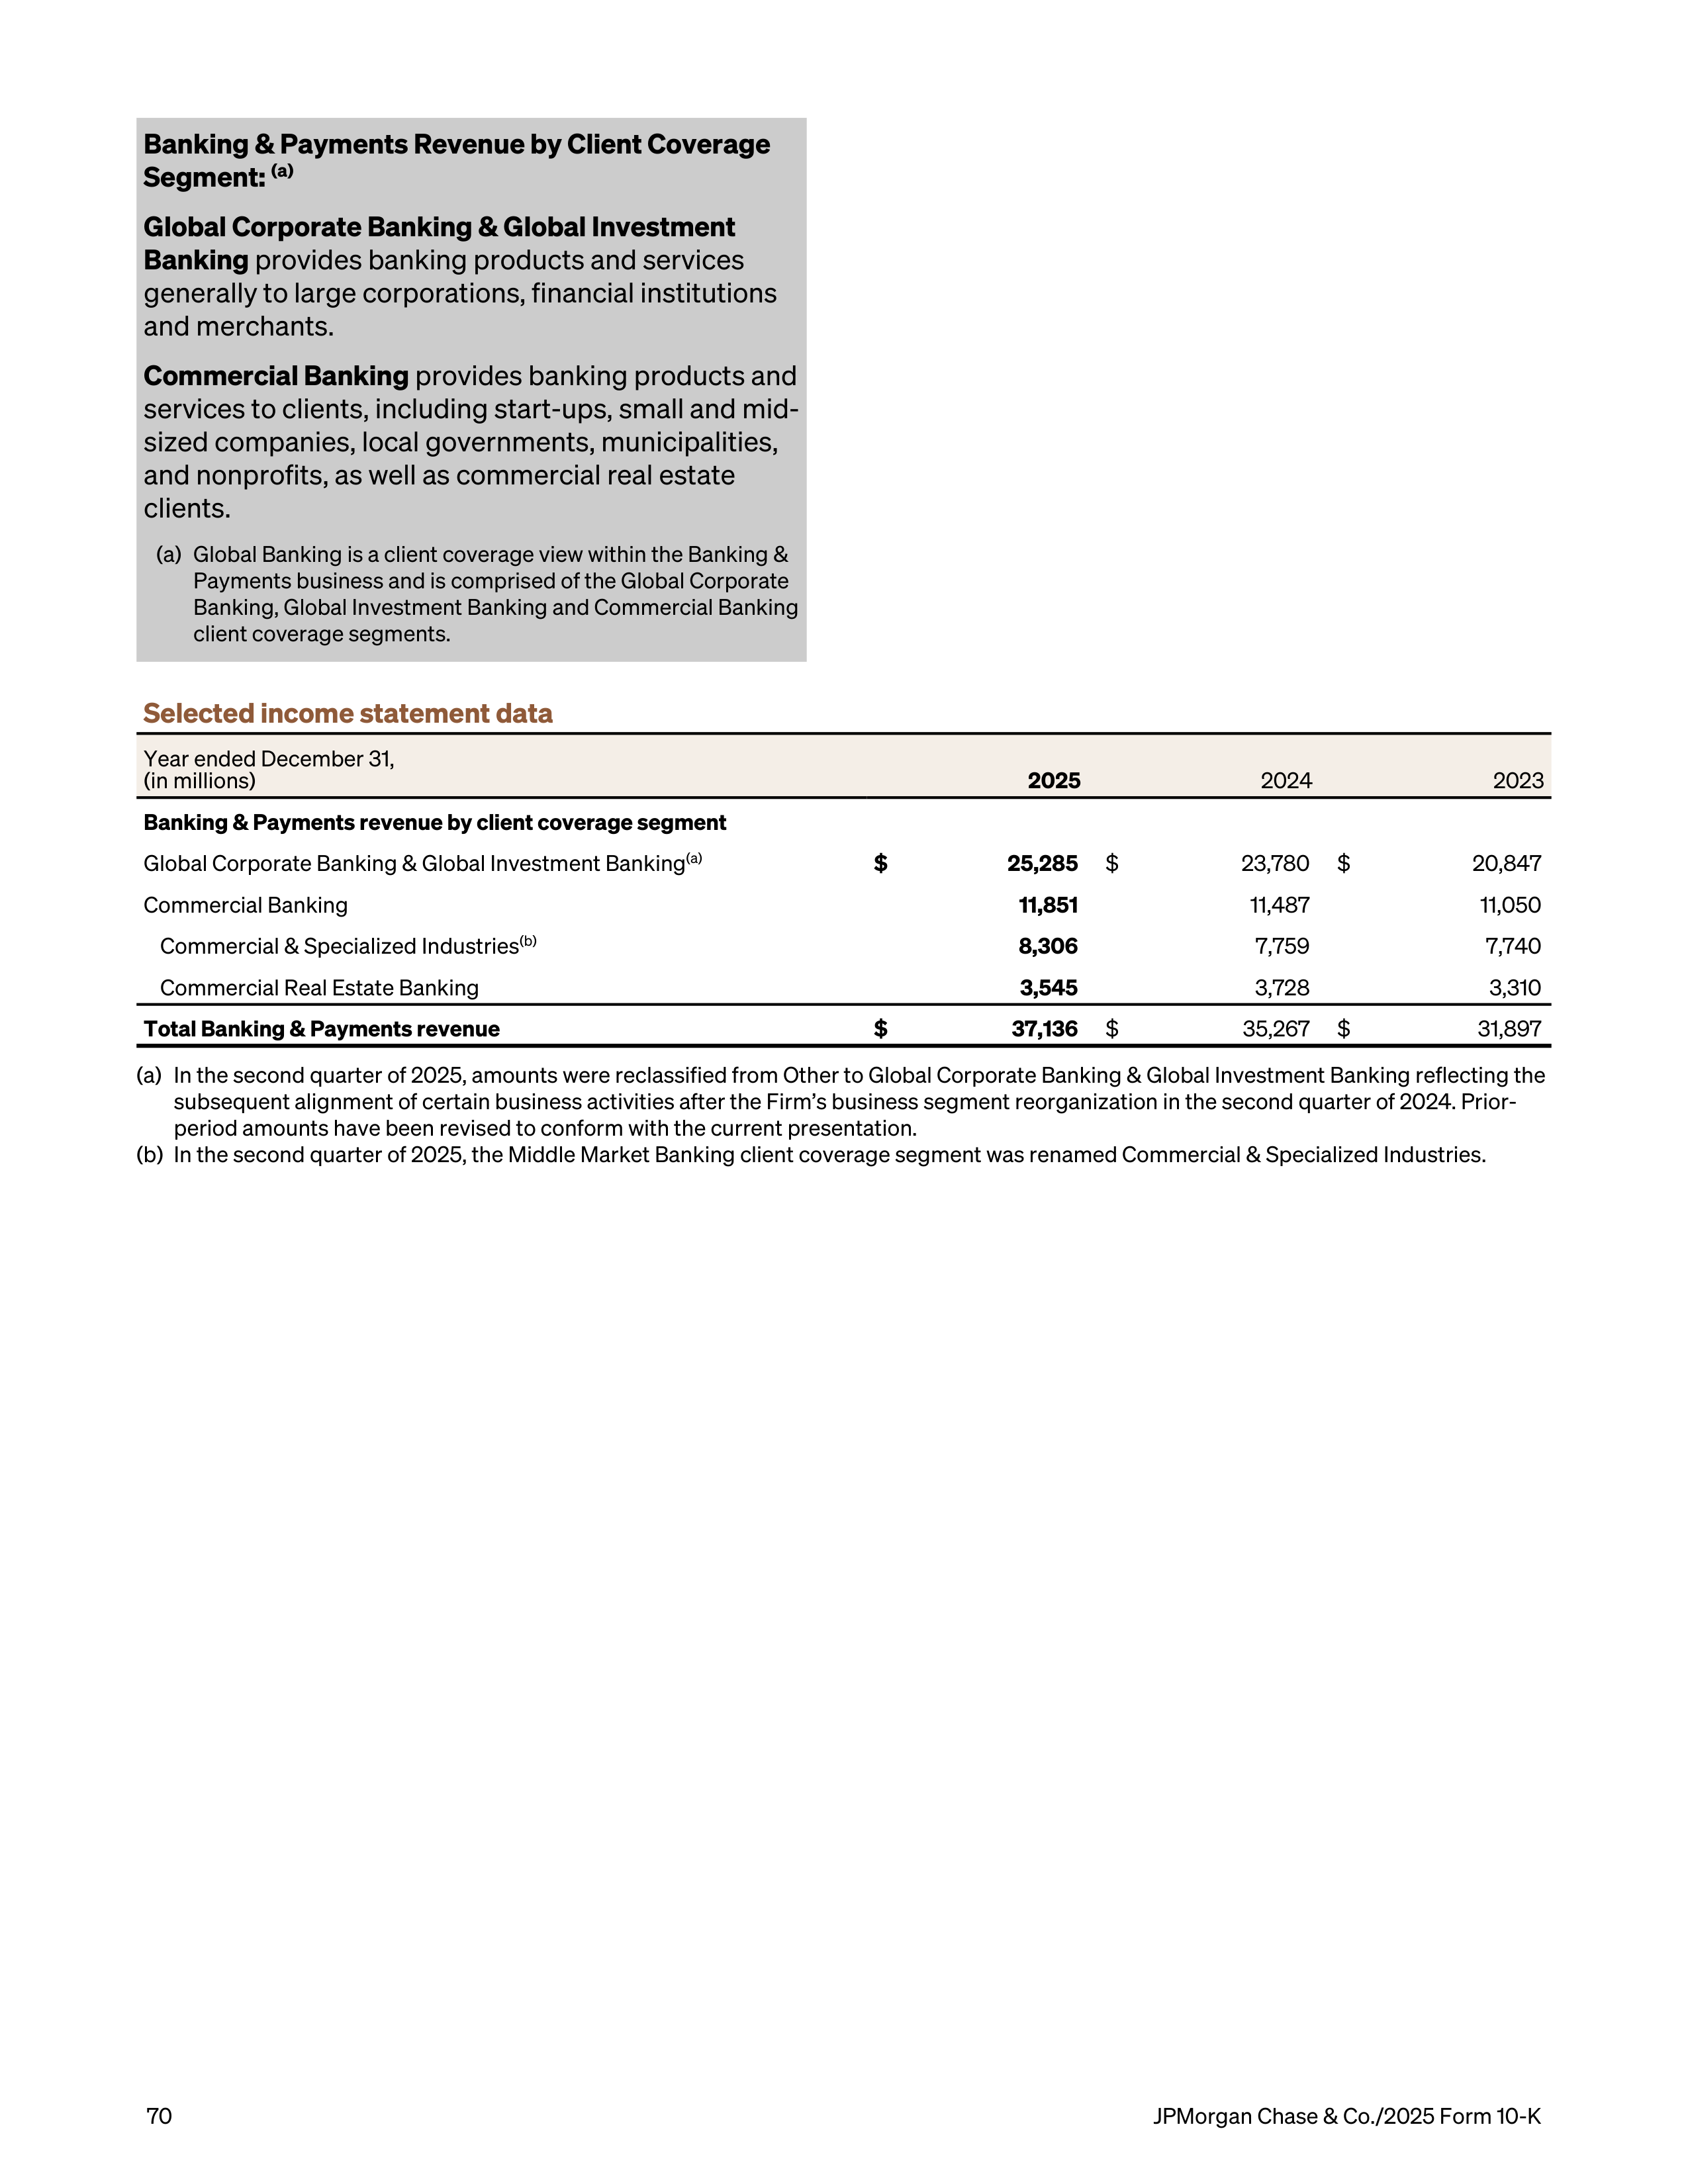
Banking & Payments Revenue by Client Coverage
Segment:
(a)
Global Corporate Banking & Global Investment
Banking
provides banking products and services
generally to large corporations, financial institutions
and merchants.
Commercial Banking
provides banking products and
services to clients, including start-ups, small and mid-
sized companies, local governments, municipalities,
and nonprofits, as well as commercial real estate
clients.
(a)
Global Banking is a client coverage view within the Banking &
Payments business and is comprised of the Global Corporate
Banking, Global Investment Banking and Commercial Banking
client coverage segments.
Selected income statement data
Year ended December 31,
(in millions)
2025
2024
2023
Banking & Payments revenue by client coverage segment
Global Corporate Banking & Global Investment Banking
(a)
$
25,285
$
23,780
$
20,847
Commercial Banking
11,851
11,487
11,050
Commercial & Specialized Industries
(b)
8,306
7,759
7,740
Commercial Real Estate Banking
3,545
3,728
3,310
Total Banking & Payments revenue
$
37,136
$
35,267
$
31,897
(a)
In the second quarter of 2025, amounts were reclassified from Other to Global Corporate Banking & Global Investment Banking reflecting the
subsequent alignment of certain business activities after the Firm’s business segment reorganization in the second quarter of 2024. Prior-
period amounts have been revised to conform with the current presentation.
(b)
In the second quarter of 2025, the Middle Market Banking client coverage segment was renamed Commercial & Specialized Industries.
70
JPMorgan Chase & Co./2025 Form 10-K
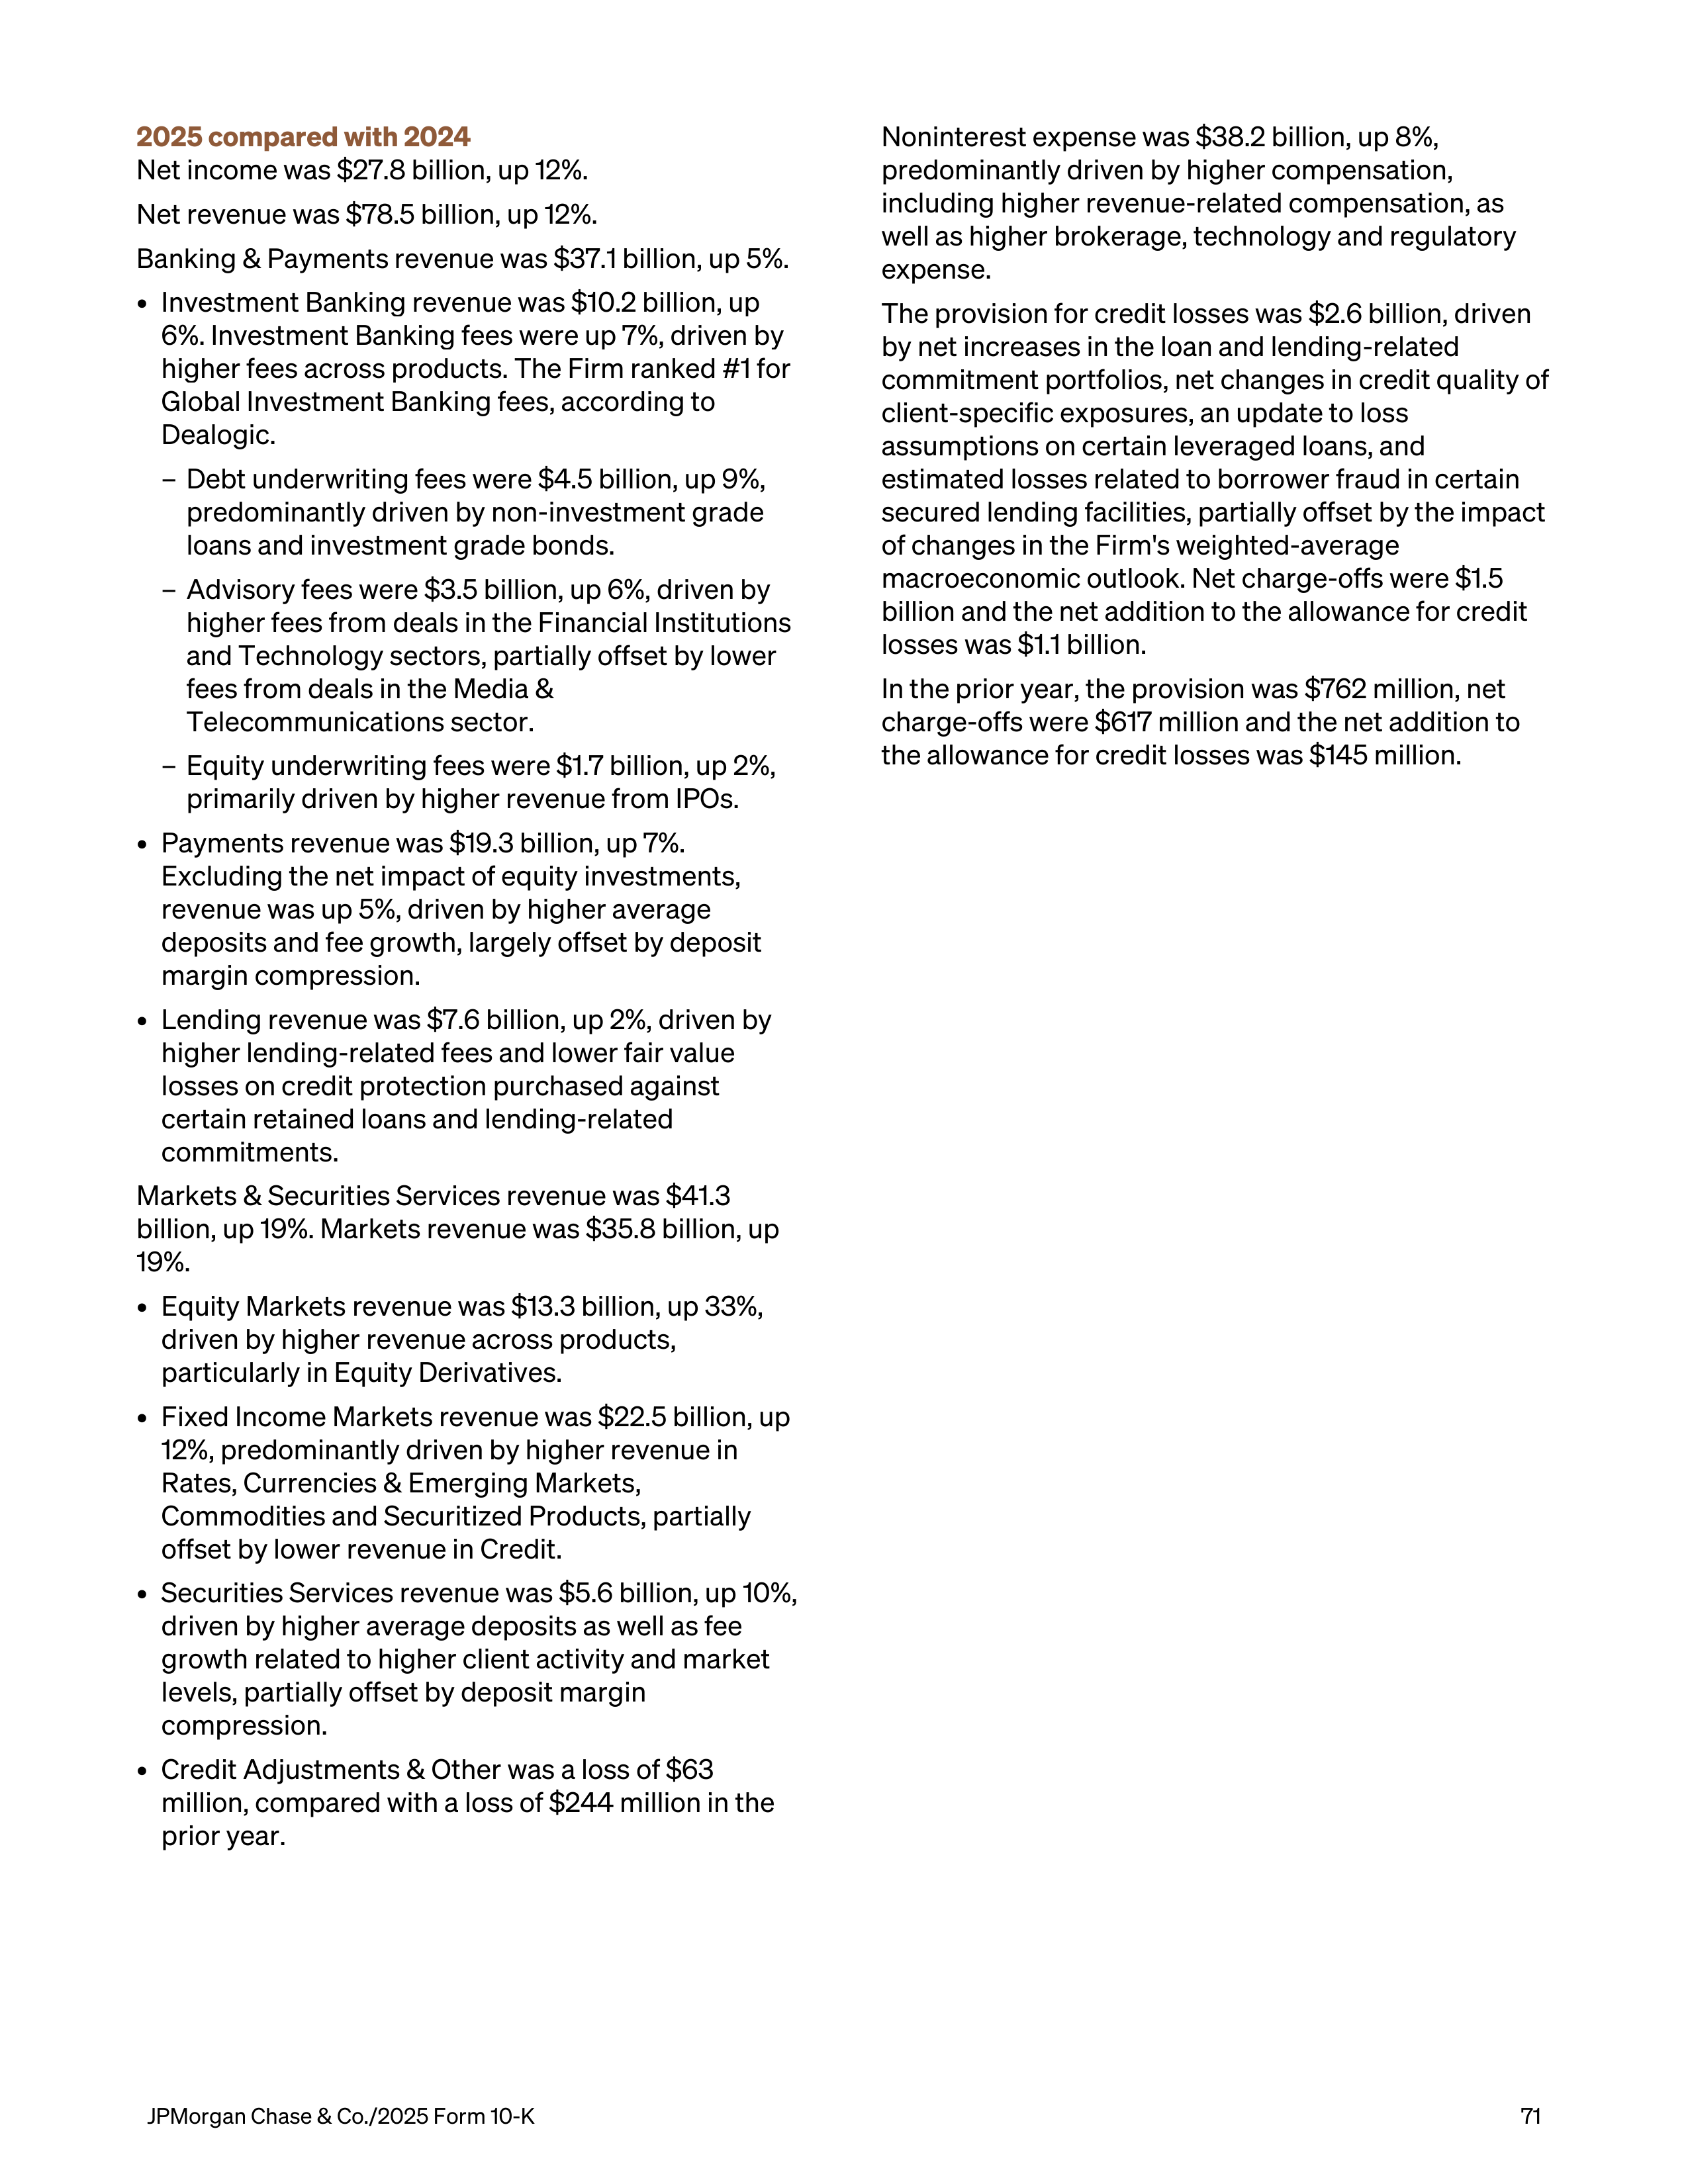
2025 compared with 2024
Net income was $27.8 billion, up 12%.
Net revenue was $78.5 billion, up 12%.
Banking & Payments
revenue was $37.1 billion, up 5%.
•
Investment Banking revenue was $10.2 billion, up
6%. Investment Banking fees were up 7%, driven by
higher fees across products. The Firm ranked #1 for
Global Investment Banking fees, according to
Dealogic.
–
Debt underwriting fees were $4.5 billion, up 9%,
predominantly driven by non-investment grade
loans and investment grade bonds.
–
Advisory fees were $3.5 billion, up 6%, driven by
higher fees from deals in the Financial Institutions
and Technology sectors, partially offset by lower
fees from deals in the Media &
Telecommunications sector.
–
Equity underwriting fees were $1.7 billion, up 2%,
primarily driven by higher revenue from IPOs.
•
Payments revenue was $19.3 billion, up 7%.
Excluding the net impact of equity investments,
revenue was up 5%, driven by higher average
deposits and fee growth, largely offset by deposit
margin compression.
•
Lending revenue was $7.6 billion, up 2%, driven by
higher lending-related fees and lower fair value
losses on credit protection purchased against
certain retained loans and lending-related
commitments.
Markets & Securities Services revenue was $41.3
billion, up 19%. Markets revenue was $35.8 billion, up
19%.
•
Equity Markets revenue was $13.3 billion, up 33%,
driven by higher revenue across products,
particularly in Equity Derivatives.
•
Fixed Income Markets revenue was $22.5 billion, up
12%, predominantly driven by higher revenue in
Rates, Currencies & Emerging Markets,
Commodities and Securitized Products, partially
offset by lower revenue in Credit.
•
Securities Services revenue was $5.6 billion, up 10%,
driven by higher average deposits as well as fee
growth related to higher client activity and market
levels, partially offset by deposit margin
compression.
•
Credit Adjustments & Other was a loss of $63
million, compared with a loss of $244 million in the
prior year.
Noninterest expense was $38.2 billion, up 8%,
predominantly driven by higher compensation,
including higher revenue-related compensation, as
well as higher brokerage, technology and regulatory
expense.
The provision for credit losses was $2.6 billion, driven
by net increases in the loan and lending-related
commitment portfolios, net changes in credit quality of
client-specific exposures, an update to loss
assumptions on certain leveraged loans, and
estimated losses related to borrower fraud in certain
secured lending facilities, partially offset by the impact
of changes in the Firm's weighted-average
macroeconomic outlook. Net charge-offs were $1.5
billion and the net addition to the allowance for credit
losses was $1.1 billion.
In the prior year, the provision was $762 million, net
charge-offs were $617 million and the net addition to
the allowance for credit losses was $145 million.
JPMorgan Chase & Co./2025 Form 10-K
71
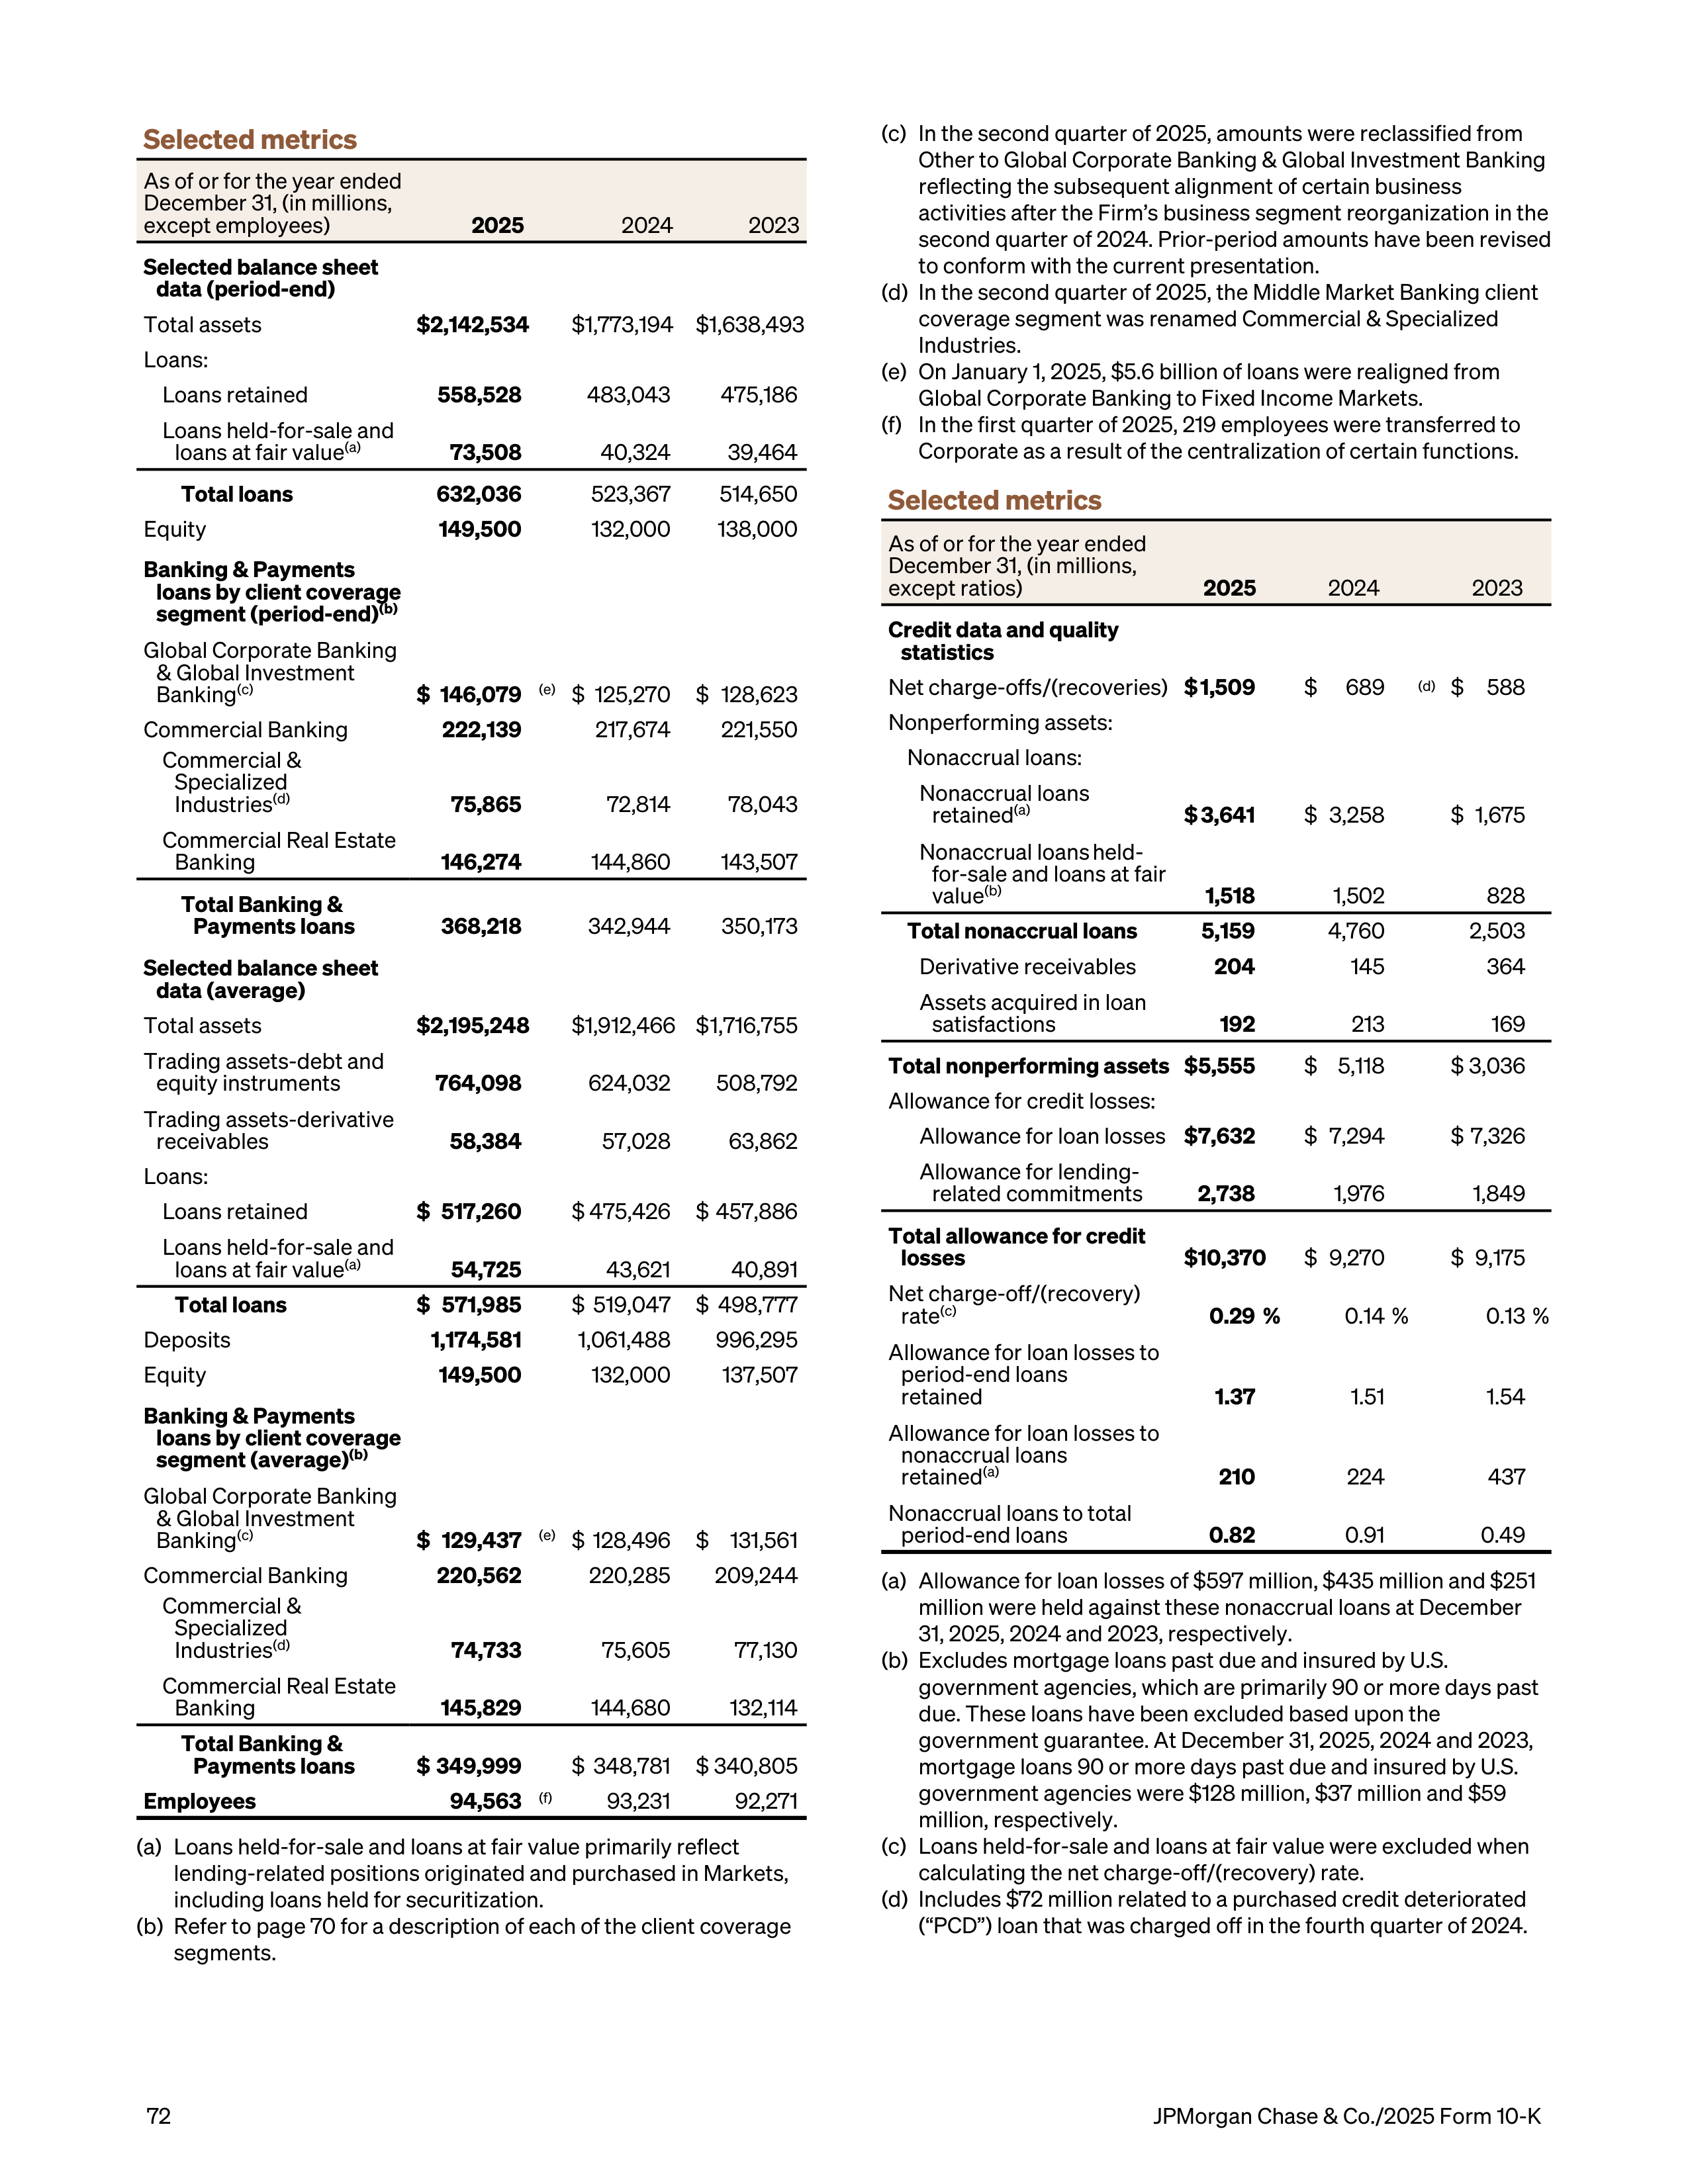
Selected metrics
As of or for the year ended
December 31, (in millions,
except employees)
2025
2024
2023
Selected balance sheet
data (period-end)
Total assets
$ 2,142,534
$ 1,773,194
$ 1,638,493
Loans:
Loans retained
558,528
483,043
475,186
Loans held-for-sale and
loans at fair value
(a)
73,508
40,324
39,464
Total loans
632,036
523,367
514,650
Equity
149,500
132,000
138,000
Banking & Payments
loans by client coverage
segment (period-end)
(b)
Global Corporate Banking
& Global Investment
Banking
(c)
$ 146,079
(e)
$ 125,270
$ 128,623
Commercial Banking
222,139
217,674
221,550
Commercial &
Specialized
Industries
(d)
75,865
72,814
78,043
Commercial Real Estate
Banking
146,274
144,860
143,507
Total Banking &
Payments loans
368,218
342,944
350,173
Selected balance sheet
data (average)
Total assets
$ 2,195,248
$ 1,912,466 $ 1,716,755
Trading assets-debt and
equity instruments
764,098
624,032
508,792
Trading assets-derivative
receivables
58,384
57,028
63,862
Loans:
Loans retained
$ 517,260
$ 475,426
$ 457,886
Loans held-for-sale and
loans at fair value
(a)
54,725
43,621
40,891
Total loans
$ 571,985
$ 519,047
$ 498,777
Deposits
1,174,581
1,061,488
996,295
Equity
149,500
132,000
137,507
Banking & Payments
loans by client coverage
segment (average)
(b)
Global Corporate Banking
& Global Investment
Banking
(c)
$ 129,437
(e)
$ 128,496
$ 131,561
Commercial Banking
220,562
220,285
209,244
Commercial &
Specialized
Industries
(d)
74,733
75,605
77,130
Commercial Real Estate
Banking
145,829
144,680
132,114
Total Banking &
Payments loans
$ 349,999
$ 348,781
$ 340,805
Employees
94,563
(f)
93,231
92,271
(a)
Loans held-for-sale and loans at fair value primarily reflect
lending-related positions originated and purchased in Markets,
including loans held for securitization.
(b)
Refer to page 70 for a description of each of the client coverage
segments.
(c)
In the second quarter of 2025, amounts were reclassified from
Other to Global Corporate Banking & Global Investment Banking
reflecting the subsequent alignment of certain business
activities after the Firm’s business segment reorganization in the
second quarter of 2024. Prior-period amounts have been revised
to conform with the current presentation.
(d)
In the second quarter of 2025, the Middle Market Banking client
coverage segment was renamed Commercial & Specialized
Industries.
(e)
On January 1, 2025, $5.6 billion of loans were realigned from
Global Corporate Banking to Fixed Income Markets.
(f)
In the first quarter of 2025, 219 employees were transferred to
Corporate as a result of the centralization of certain functions.
Selected metrics
As of or for the year ended
December 31, (in millions,
except ratios)
2025
2024
2023
Credit data and quality
statistics
Net charge-offs/(recoveries)
$ 1,509
$
689
(d)
$
588
Nonperforming assets:
Nonaccrual loans:
Nonaccrual loans
retained
(a)
$ 3,641
$ 3,258
$ 1,675
Nonaccrual loans
held-
for-sale and loans at fair
value
(b)
1,518
1,502
828
Total nonaccrual loans
5,159
4,760
2,503
Derivative receivables
204
145
364
Assets acquired in loan
satisfactions
192
213
169
Total nonperforming assets
$ 5,555
$ 5,118
$ 3,036
Allowance for credit losses:
Allowance for loan losses
$ 7,632
$ 7,294
$ 7,326
Allowance for lending-
related commitments
2,738
1,976
1,849
Total allowance for credit
losses
$ 10,370
$ 9,270
$ 9,175
Net charge-off/(recovery)
rate
(c)
0.29 %
0.14 %
0.13 %
Allowance for loan losses to
period-end loans
retained
1.37
1.51
1.54
Allowance for loan losses to
nonaccrual loans
retained
(a)
210
224
437
Nonaccrual loans to total
period-end loans
0.82
0.91
0.49
(a)
Allowance for loan losses of $597 million, $435 million and $251
million were held against these nonaccrual loans at December
31, 2025, 2024 and 2023, respectively.
(b)
Excludes mortgage loans past due and insured by U.S.
government agencies, which are primarily 90 or more days past
due. These loans have been excluded based upon the
government guarantee. At December 31, 2025, 2024 and 2023,
mortgage loans 90 or more days past due and insured by U.S.
government agencies were $128 million, $37 million and $59
million, respectively.
(c)
Loans held-for-sale and loans at fair value were excluded when
calculating the net charge-off/(recovery) rate.
(d)
Includes $72 million related to a purchased credit deteriorated
(“PCD”) loan that was charged off in the fourth quarter of 2024.
72
JPMorgan Chase & Co./2025 Form 10-K
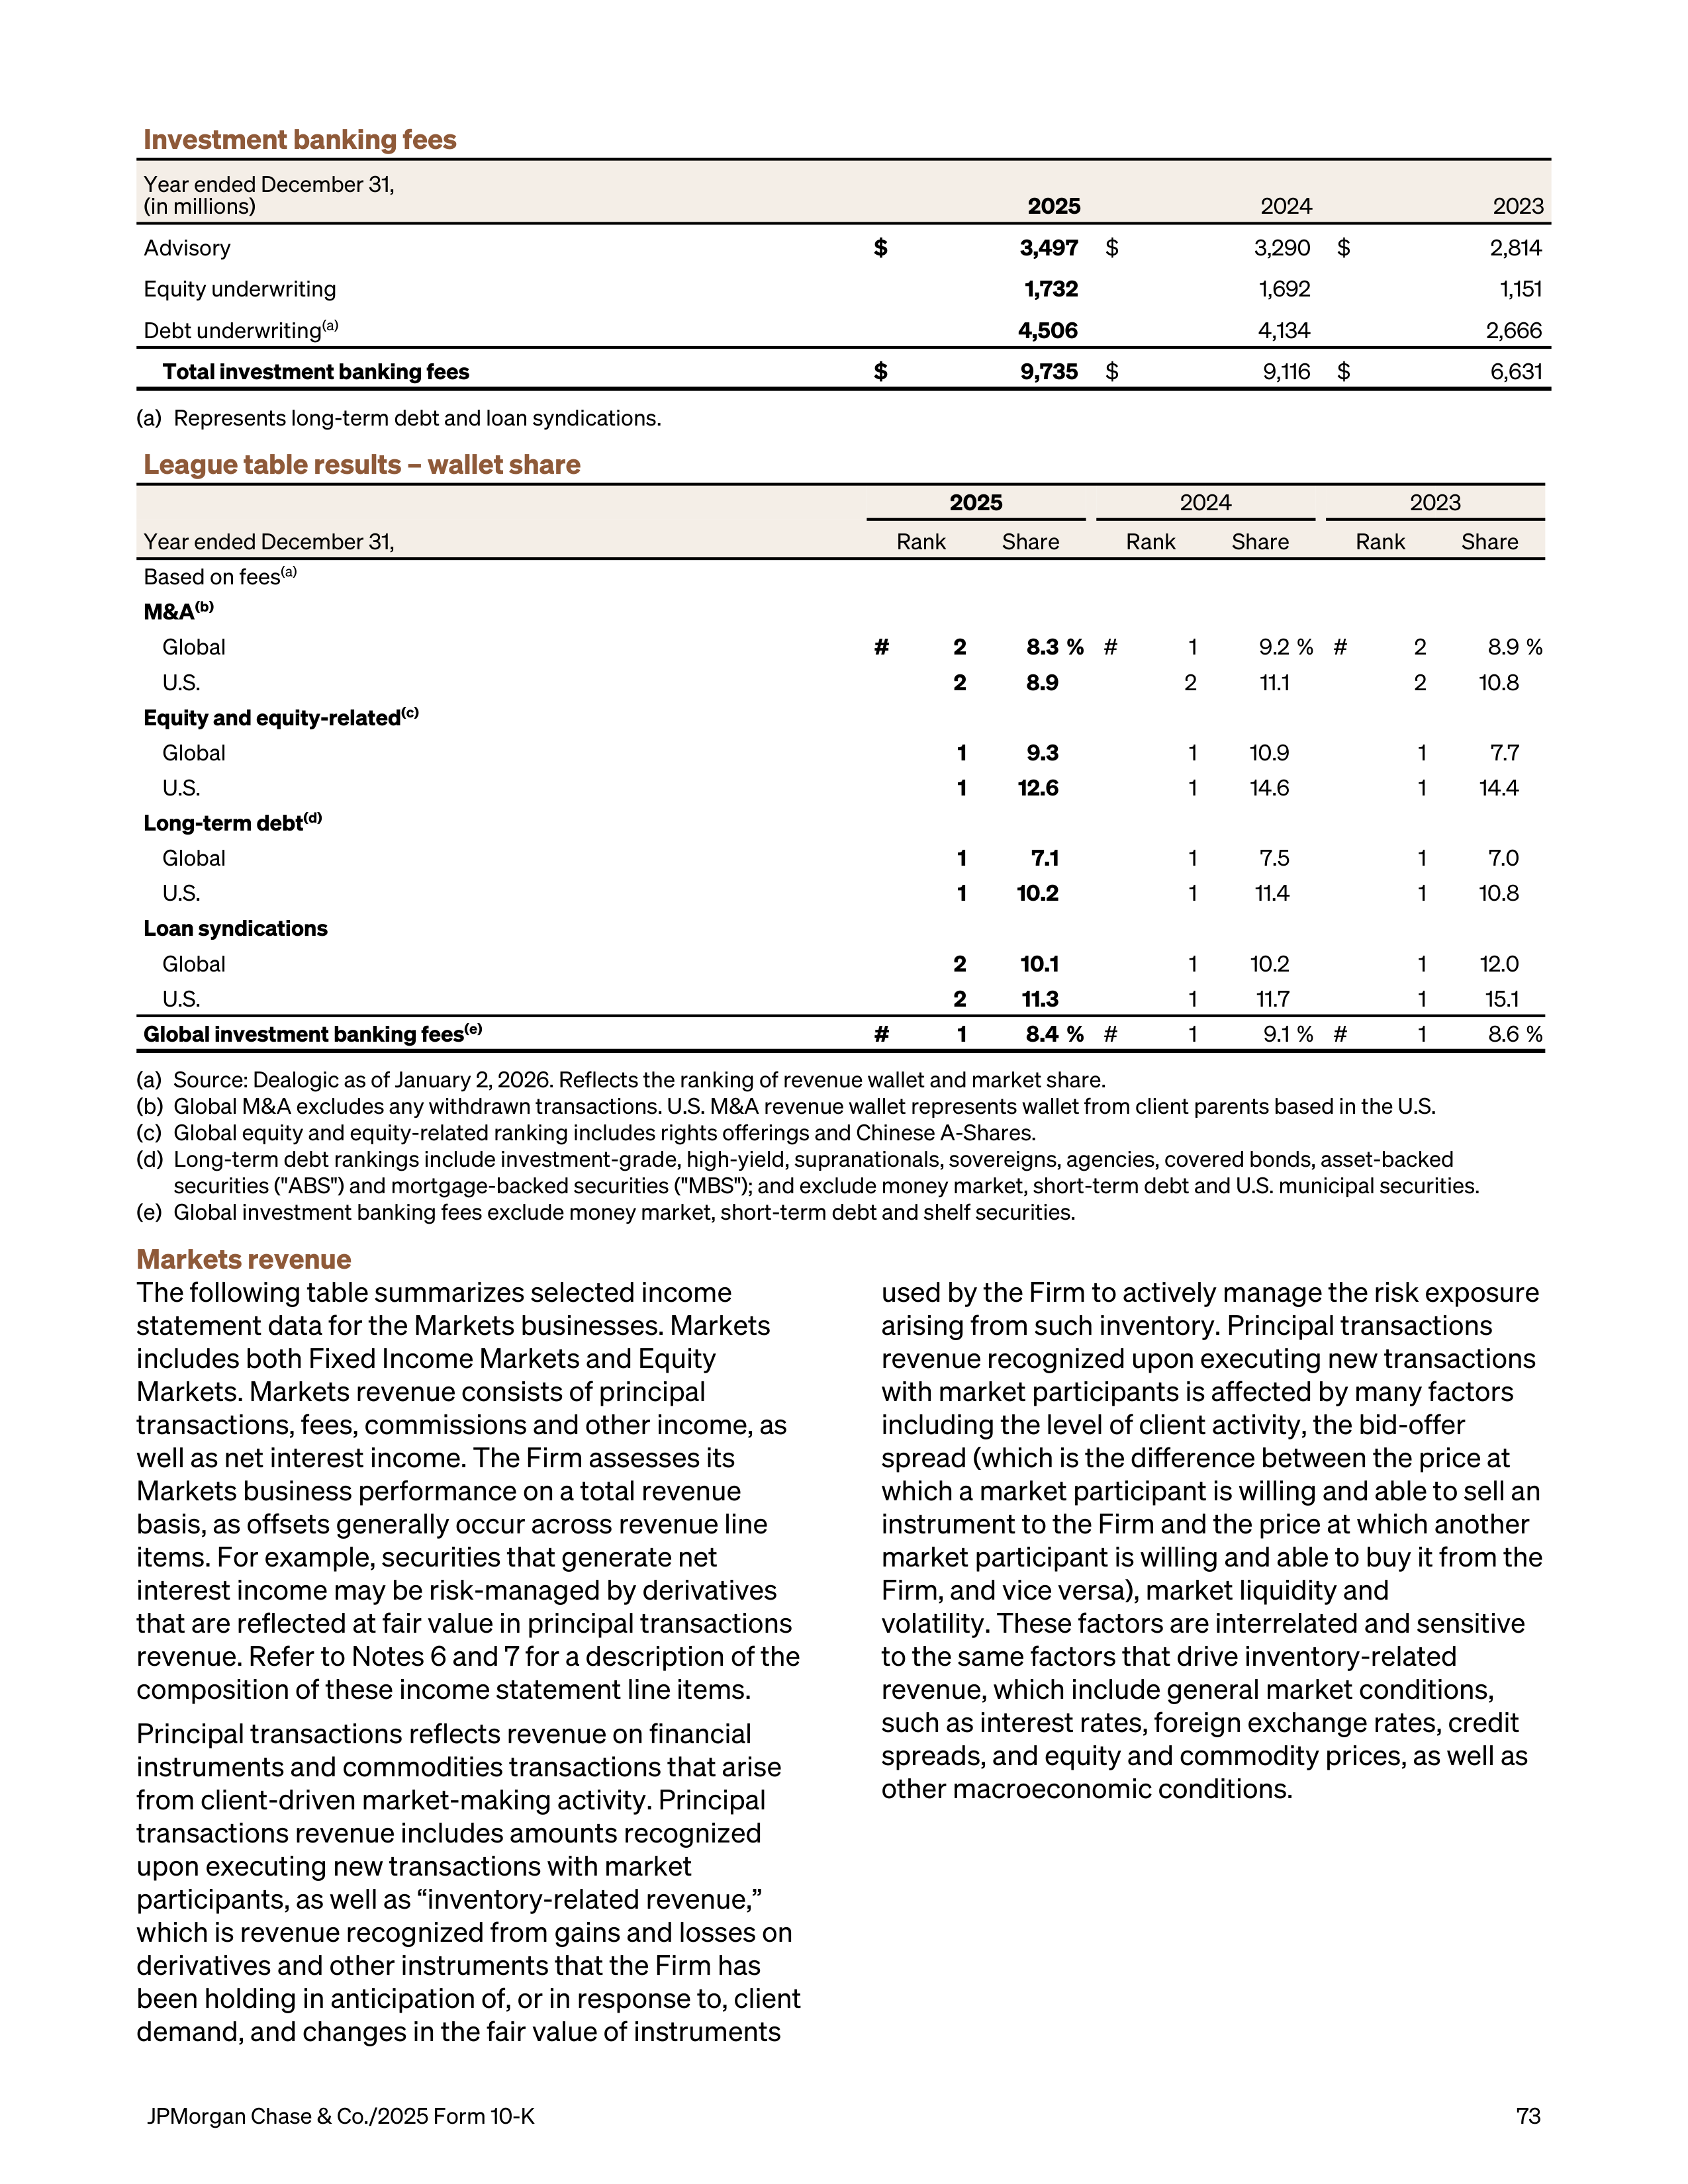
Investment banking fees
Year ended December 31,
(in millions)
2025
2024
2023
Advisory
$
3,497
$
3,290
$
2,814
Equity underwriting
1,732
1,692
1,151
Debt underwriting
(a)
4,506
4,134
2,666
Total investment banking fees
$
9,735
$
9,116
$
6,631
(a)
Represents long-term debt and loan syndications.
League table results – wallet share
2025
2024
2023
Year ended December 31,
Rank
Share
Rank
Share
Rank
Share
Based on fees
(a)
M&A
(b)
Global
#
2
8.3 %
#
1
9.2 %
#
2
8.9 %
U.S.
2
8.9
2
11.1
2
10.8
Equity and equity-related
(c)
Global
1
9.3
1
10.9
1
7.7
U.S.
1
12.6
1
14.6
1
14.4
Long-term debt
(d)
Global
1
7.1
1
7.5
1
7.0
U.S.
1
10.2
1
11.4
1
10.8
Loan syndications
Global
2
10.1
1
10.2
1
12.0
U.S.
2
11.3
1
11.7
1
15.1
Global investment banking fees
(e)
#
1
8.4 %
#
1
9.1 %
#
1
8.6 %
(a)
Source: Dealogic as of January 2, 2026. Reflects the ranking of revenue wallet and market share.
(b)
Global M&A excludes any withdrawn transactions. U.S. M&A revenue wallet represents wallet from client parents based in the U.S.
(c)
Global equity and equity-related ranking includes rights offerings and Chinese A-Shares.
(d)
Long-term debt rankings include investment-grade, high-yield, supranationals, sovereigns, agencies, covered bonds, asset-backed
securities ("ABS") and mortgage-backed securities ("MBS"); and exclude money market, short-term debt and U.S. municipal securities.
(e)
Global investment banking fees exclude money market, short-term debt and shelf securities.
Markets revenue
The following table summarizes selected income
statement data for the Markets businesses. Markets
includes both Fixed Income Markets and Equity
Markets. Markets revenue consists of principal
transactions, fees, commissions and other income, as
well as net interest income. The Firm assesses its
Markets business performance on a total revenue
basis, as offsets generally occur across revenue line
items. For example, securities that generate net
interest income may be risk-managed by derivatives
that are reflected at fair value in principal transactions
revenue. Refer to Notes 6 and 7 for a description of the
composition of these income statement line items.
Principal transactions reflects revenue on financial
instruments and commodities transactions that arise
from client-driven market-making activity. Principal
transactions revenue includes amounts recognized
upon executing new transactions with market
participants, as well as “inventory-related revenue,”
which is revenue recognized from gains and losses on
derivatives and other instruments that the Firm has
been holding in anticipation of, or in response to, client
demand, and changes in the fair value of instruments
used by the Firm to actively manage the risk exposure
arising from such inventory. Principal transactions
revenue recognized upon executing new transactions
with market participants is affected by many factors
including the level of client activity, the bid-offer
spread (which is the difference between the price at
which a market participant is willing and able to sell an
instrument to the Firm and the price at which another
market participant is willing and able to buy it from the
Firm, and vice versa), market liquidity and
volatility. These factors are interrelated and sensitive
to the same factors that drive inventory-related
revenue, which include general market conditions,
such as interest rates, foreign exchange rates, credit
spreads, and equity and commodity prices, as well as
other macroeconomic conditions.
JPMorgan Chase & Co./2025 Form 10-K
73
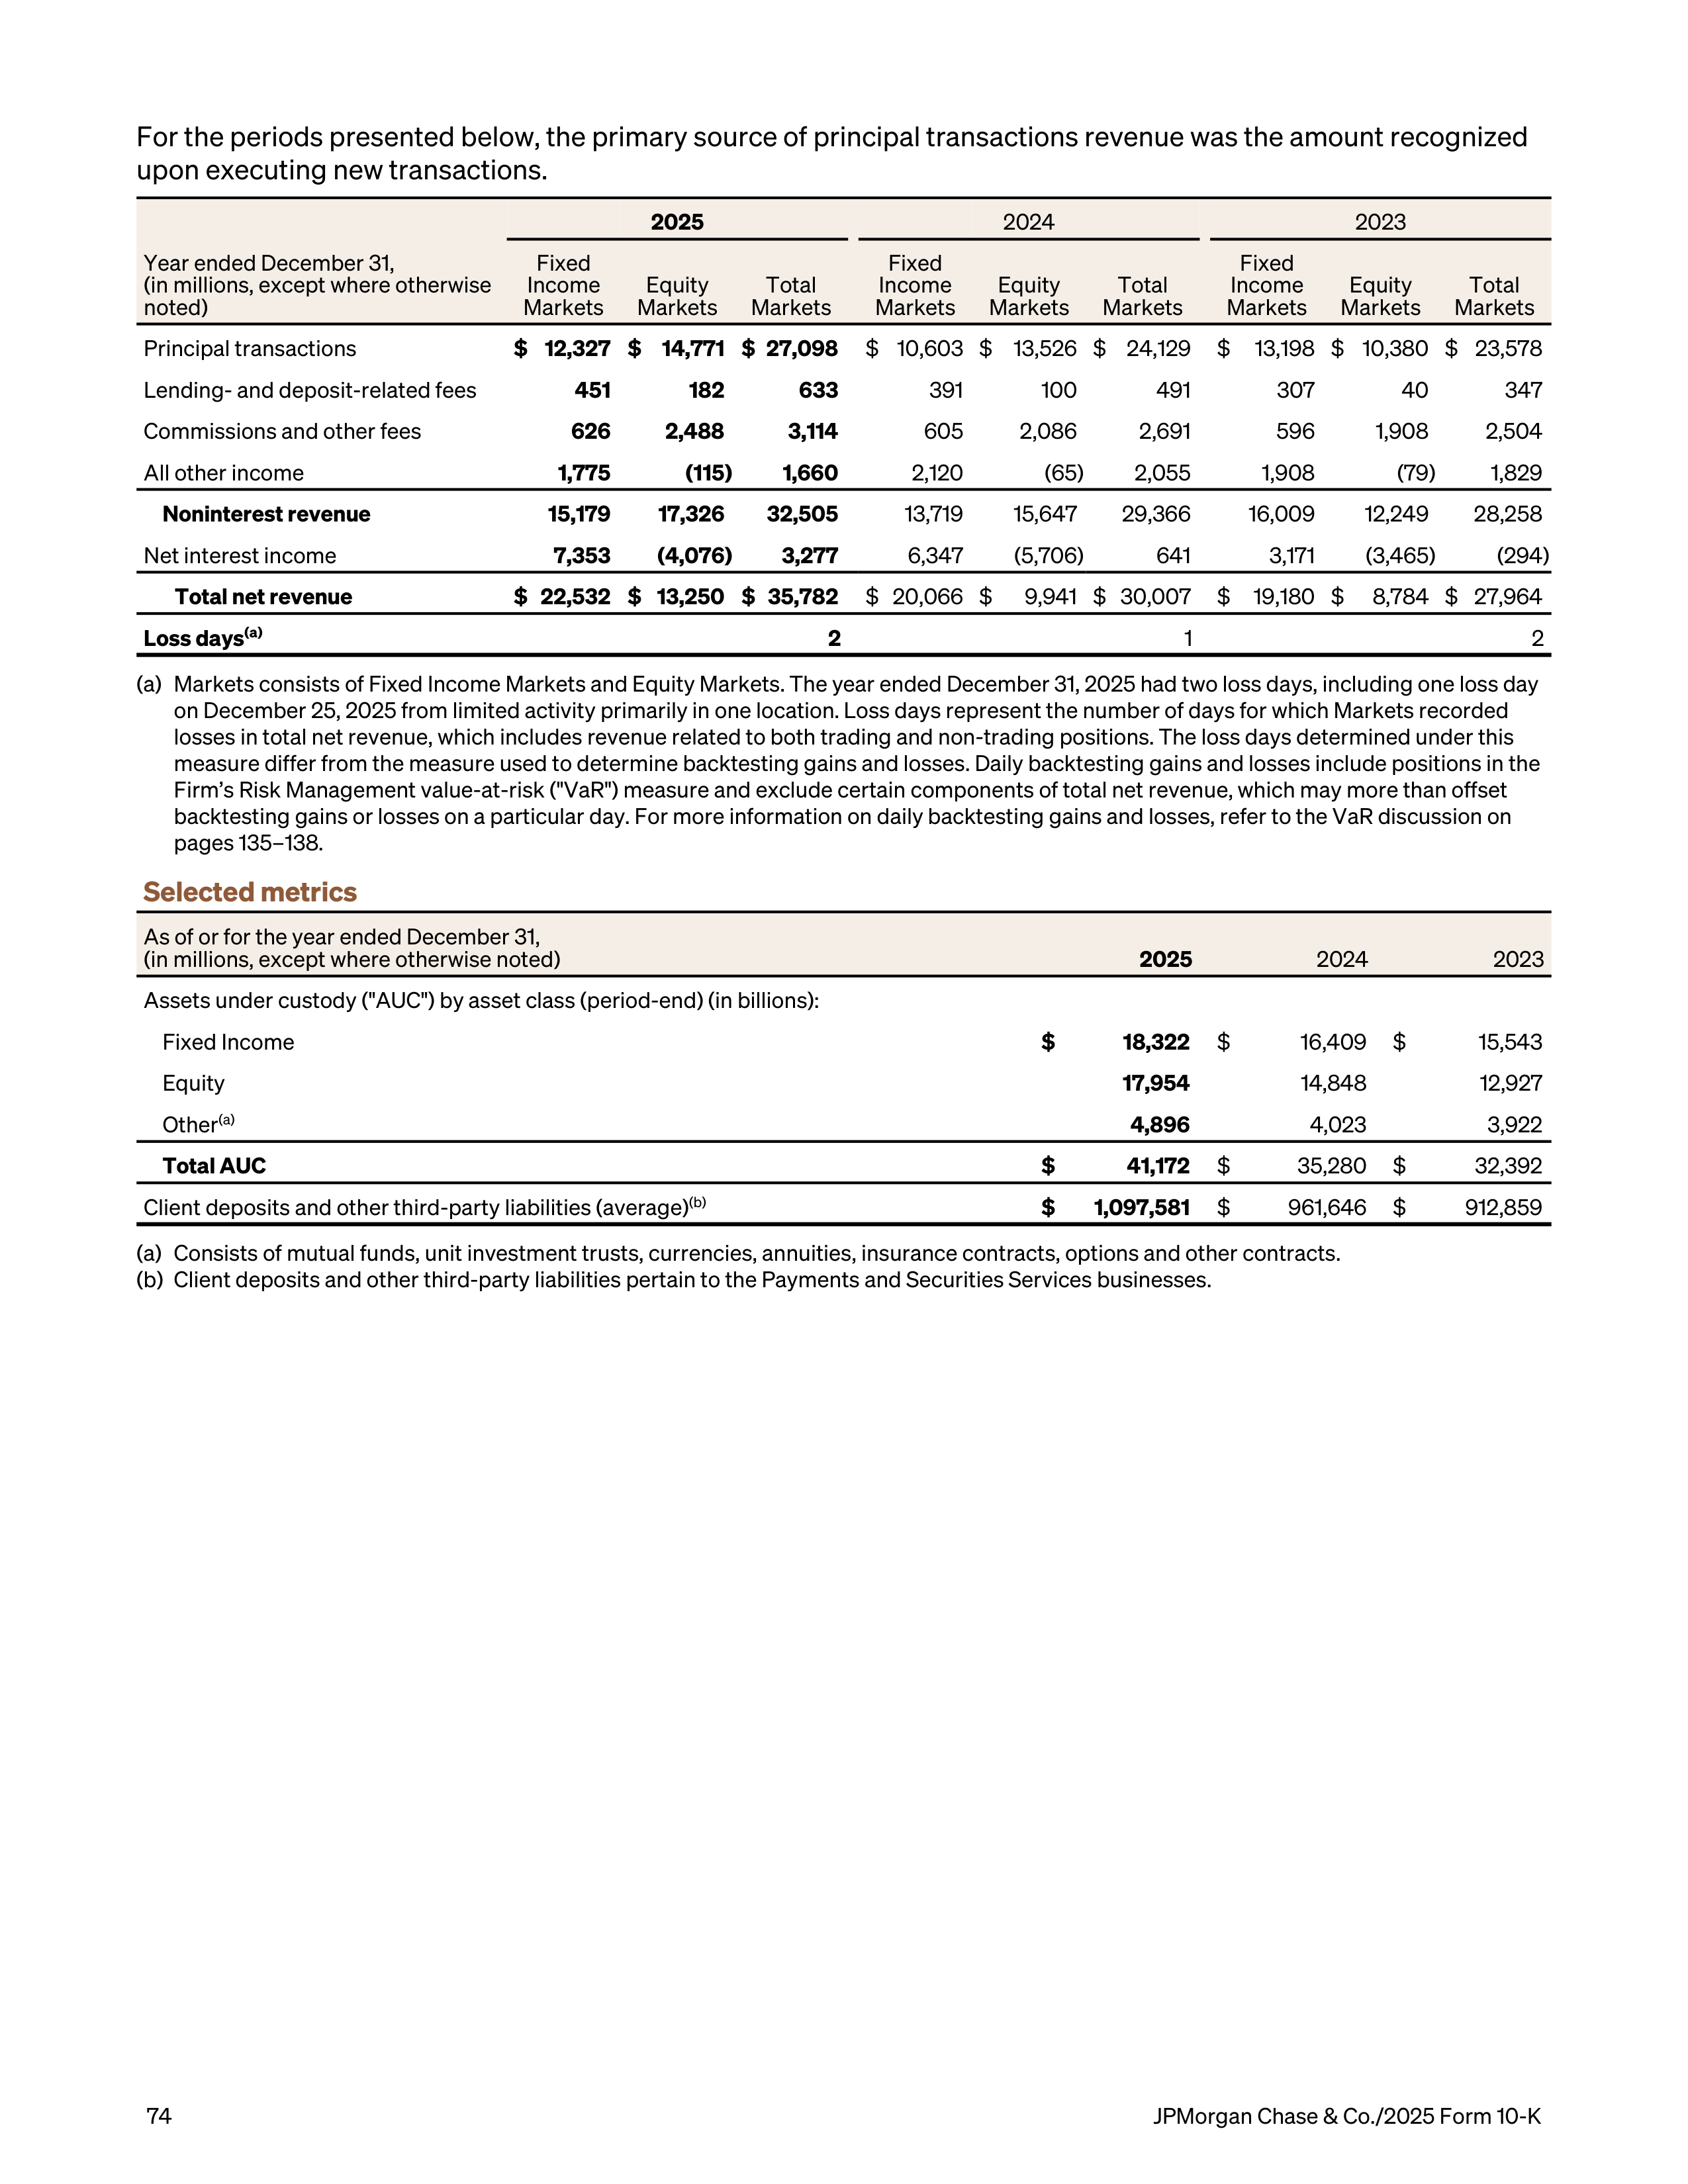
For the periods presented below, the primary source of principal transactions revenue was the amount recognized
upon executing new transactions.
2025
2024
2023
Year ended December 31,
(in millions, except where otherwise
noted)
Fixed
Income
Markets
Equity
Markets
Total
Markets
Fixed
Income
Markets
Equity
Markets
Total
Markets
Fixed
Income
Markets
Equity
Markets
Total
Markets
Principal transactions
$ 12,327 $ 14,771 $ 27,098
$ 10,603 $ 13,526 $ 24,129
$
13,198 $ 10,380 $ 23,578
Lending- and deposit-related fees
451
182
633
391
100
491
307
40
347
Commissions and other fees
626
2,488
3,114
605
2,086
2,691
596
1,908
2,504
All other income
1,775
(115)
1,660
2,120
(65)
2,055
1,908
(79)
1,829
Noninterest revenue
15,179
17,326
32,505
13,719
15,647
29,366
16,009
12,249
28,258
Net interest income
7,353
(4,076)
3,277
6,347
(5,706)
641
3,171
(3,465)
(294)
Total net revenue
$ 22,532 $ 13,250 $ 35,782
$ 20,066 $
9,941 $ 30,007
$
19,180 $
8,784 $ 27,964
Loss days
(a)
2
1
2
(a)
Markets consists of Fixed Income Markets and Equity Markets. The year ended December 31, 2025 had two loss days, including one loss day
on December 25, 2025 from limited activity primarily in one location. Loss days represent the number of days for which Markets recorded
losses in total net revenue, which includes revenue related to both trading and non-trading positions. The loss days determined under this
measure differ from the measure used to determine backtesting gains and losses. Daily backtesting gains and losses include positions in the
Firm’s Risk Management value-at-risk ("VaR") measure and exclude certain components of total net revenue, which may more than offset
backtesting gains or losses on a particular day. For more information on daily backtesting gains and losses, refer to the VaR discussion on
pages 135–138.
Selected metrics
As of or for the year ended December 31,
(in millions, except where otherwise noted)
2025
2024
2023
Assets under custody ("AUC") by asset class (period-end) (in billions):
Fixed Income
$
18,322
$
16,409
$
15,543
Equity
17,954
14,848
12,927
Other
(a)
4,896
4,023
3,922
Total AUC
$
41,172
$
35,280
$
32,392
Client deposits and other third-party liabilities (average)
(b)
$
1,097,581
$
961,646
$
912,859
(a)
Consists of mutual funds, unit investment trusts, currencies, annuities, insurance contracts, options and other contracts.
(b)
Client deposits and other third-party liabilities pertain to the Payments and Securities Services businesses.
74
JPMorgan Chase & Co./2025 Form 10-K
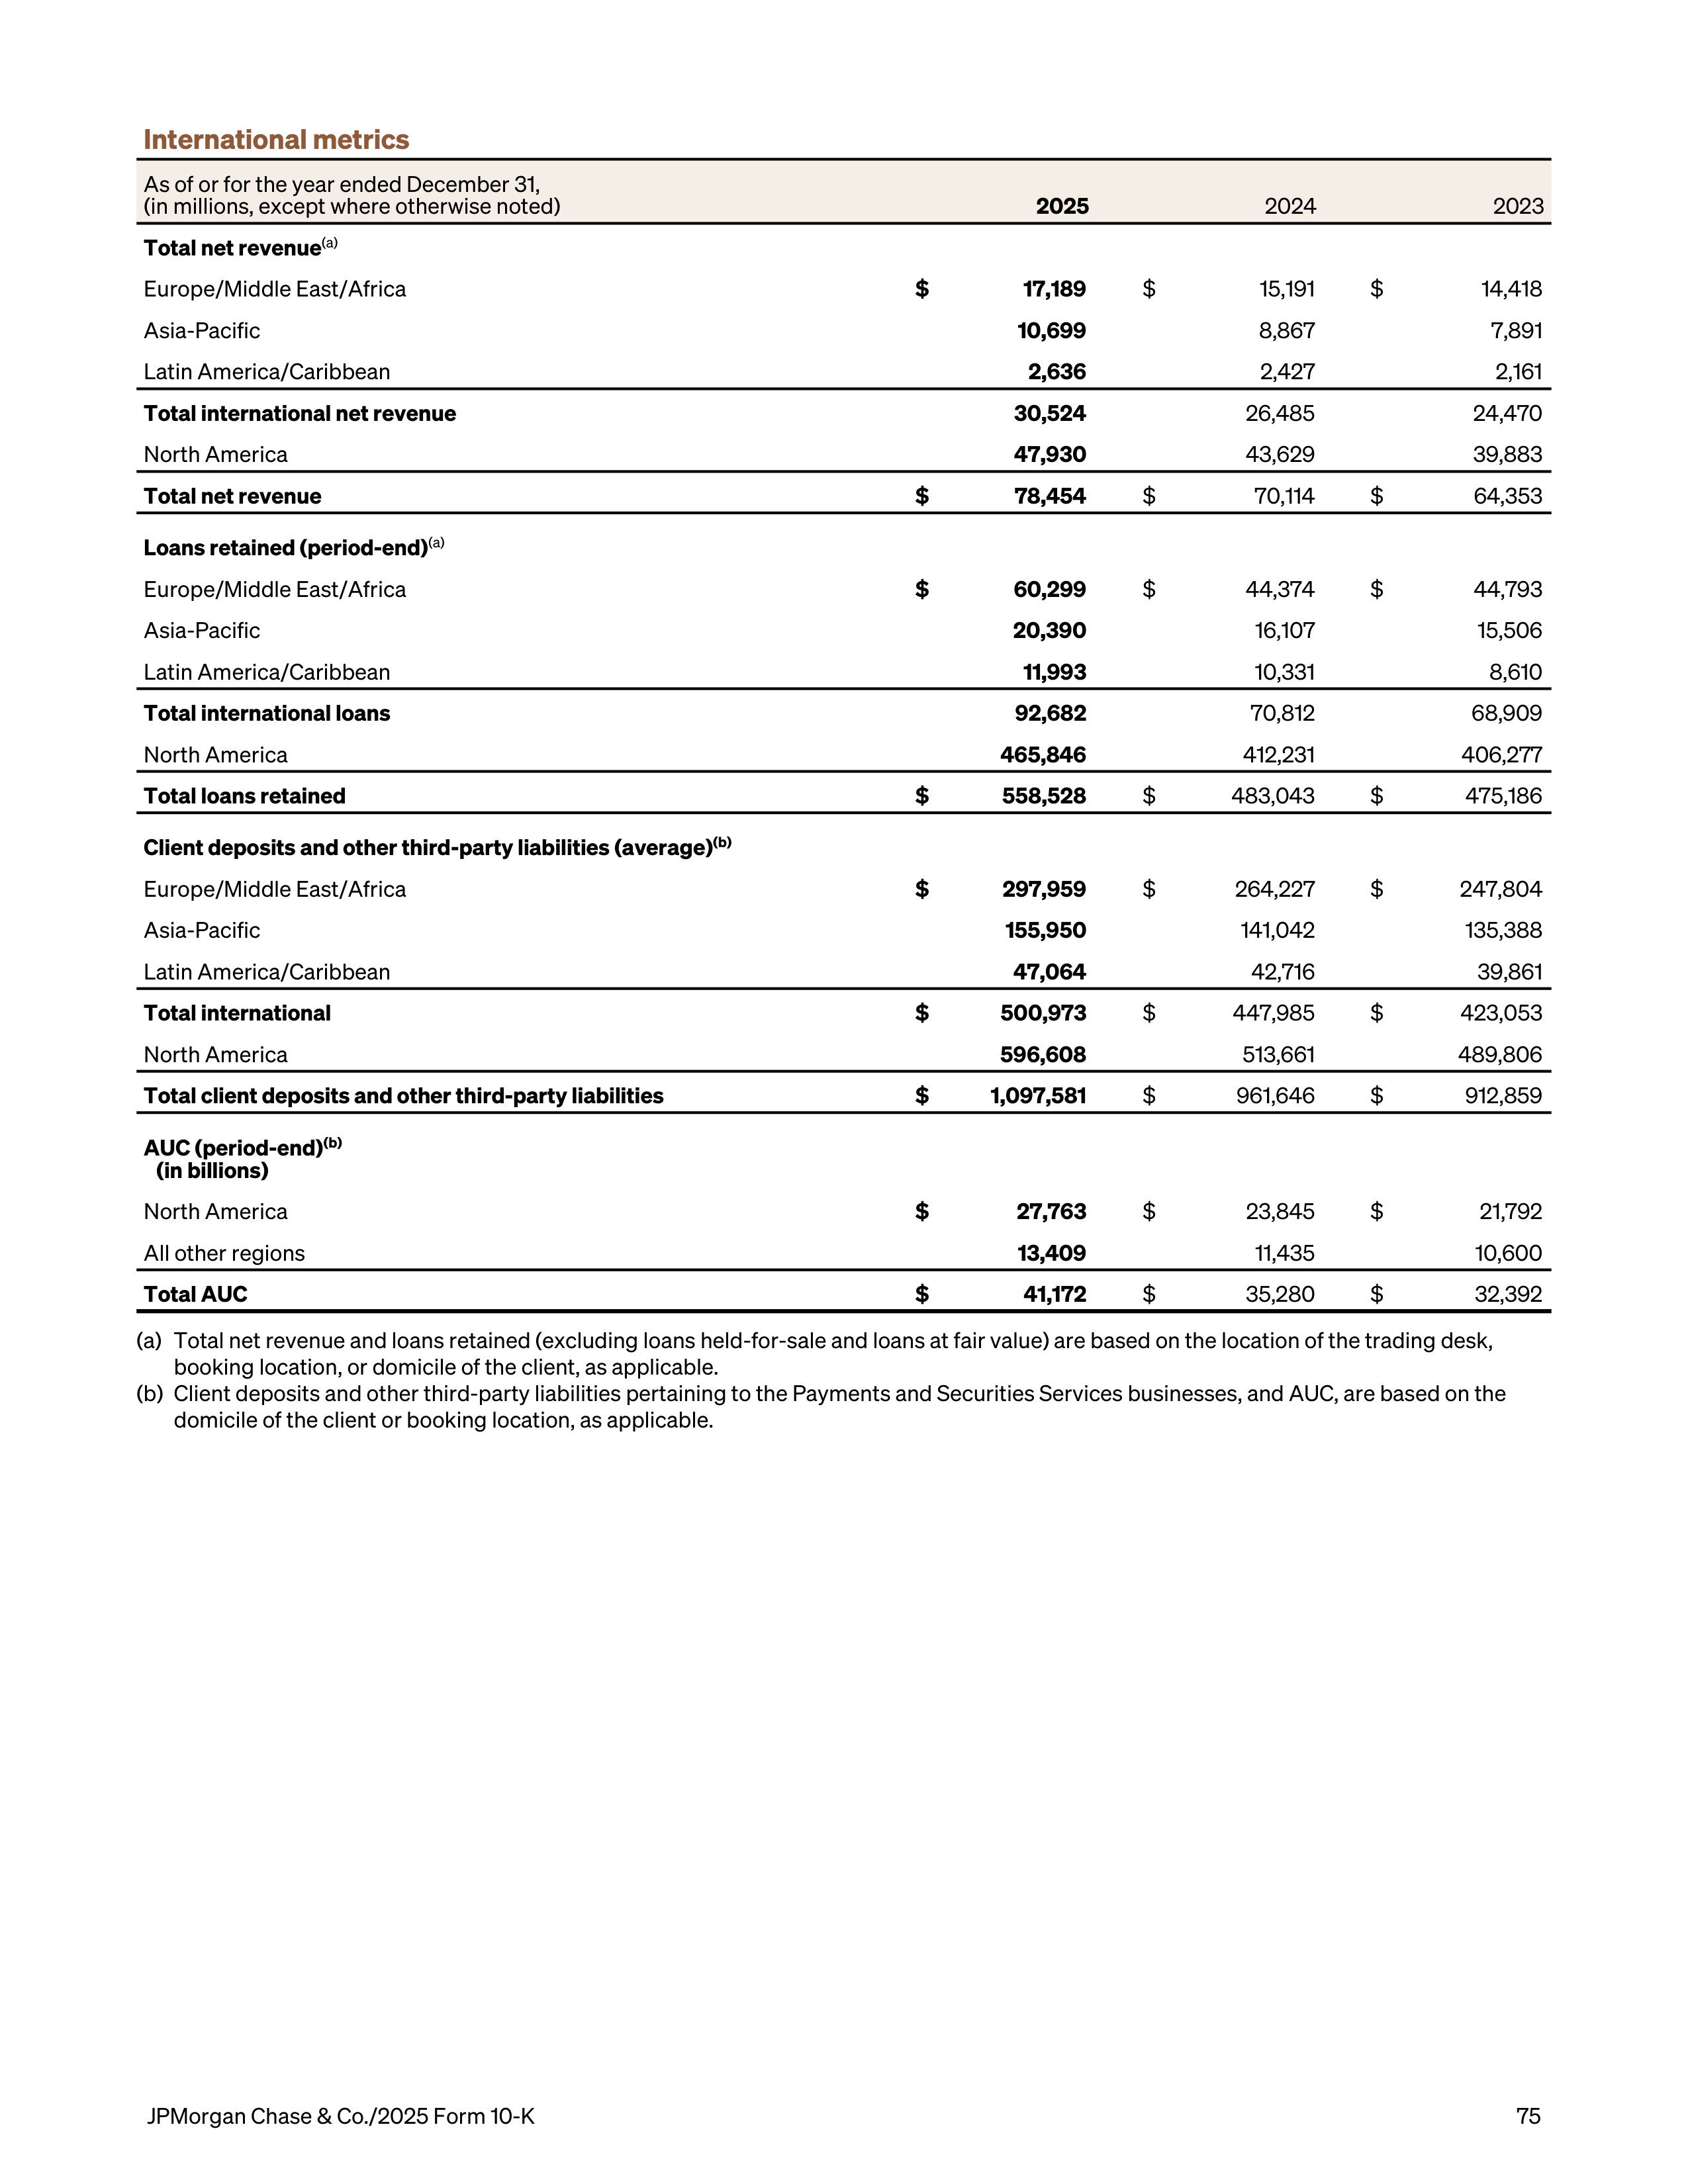
International metrics
As of or for the year ended December 31,
(in millions, except where otherwise noted)
2025
2024
2023
Total net revenue
(a)
Europe/Middle East/Africa
$
17,189
$
15,191
$
14,418
Asia-Pacific
10,699
8,867
7,891
Latin America/Caribbean
2,636
2,427
2,161
Total international net revenue
30,524
26,485
24,470
North America
47,930
43,629
39,883
Total net revenue
$
78,454
$
70,114
$
64,353
Loans retained (period-end)
(a)
Europe/Middle East/Africa
$
60,299
$
44,374
$
44,793
Asia-Pacific
20,390
16,107
15,506
Latin America/Caribbean
11,993
10,331
8,610
Total international loans
92,682
70,812
68,909
North America
465,846
412,231
406,277
Total loans retained
$
558,528
$
483,043
$
475,186
Client deposits and other third-party liabilities (average)
(b)
Europe/Middle East/Africa
$
297,959
$
264,227
$
247,804
Asia-Pacific
155,950
141,042
135,388
Latin America/Caribbean
47,064
42,716
39,861
Total international
$
500,973
$
447,985
$
423,053
North America
596,608
513,661
489,806
Total client deposits and other third-party liabilities
$
1,097,581
$
961,646
$
912,859
AUC (period-end)
(b)
(in billions)
North America
$
27,763
$
23,845
$
21,792
All other regions
13,409
11,435
10,600
Total AUC
$
41,172
$
35,280
$
32,392
(a)
Total net revenue and loans retained (excluding loans held-for-sale and loans at fair value) are based on the location of the trading desk,
booking location, or domicile of the client, as applicable.
(b)
Client deposits and other third-party liabilities pertaining to the Payments and Securities Services businesses, and AUC, are based on the
domicile of the client or booking location, as applicable.
JPMorgan Chase & Co./2025 Form 10-K
75
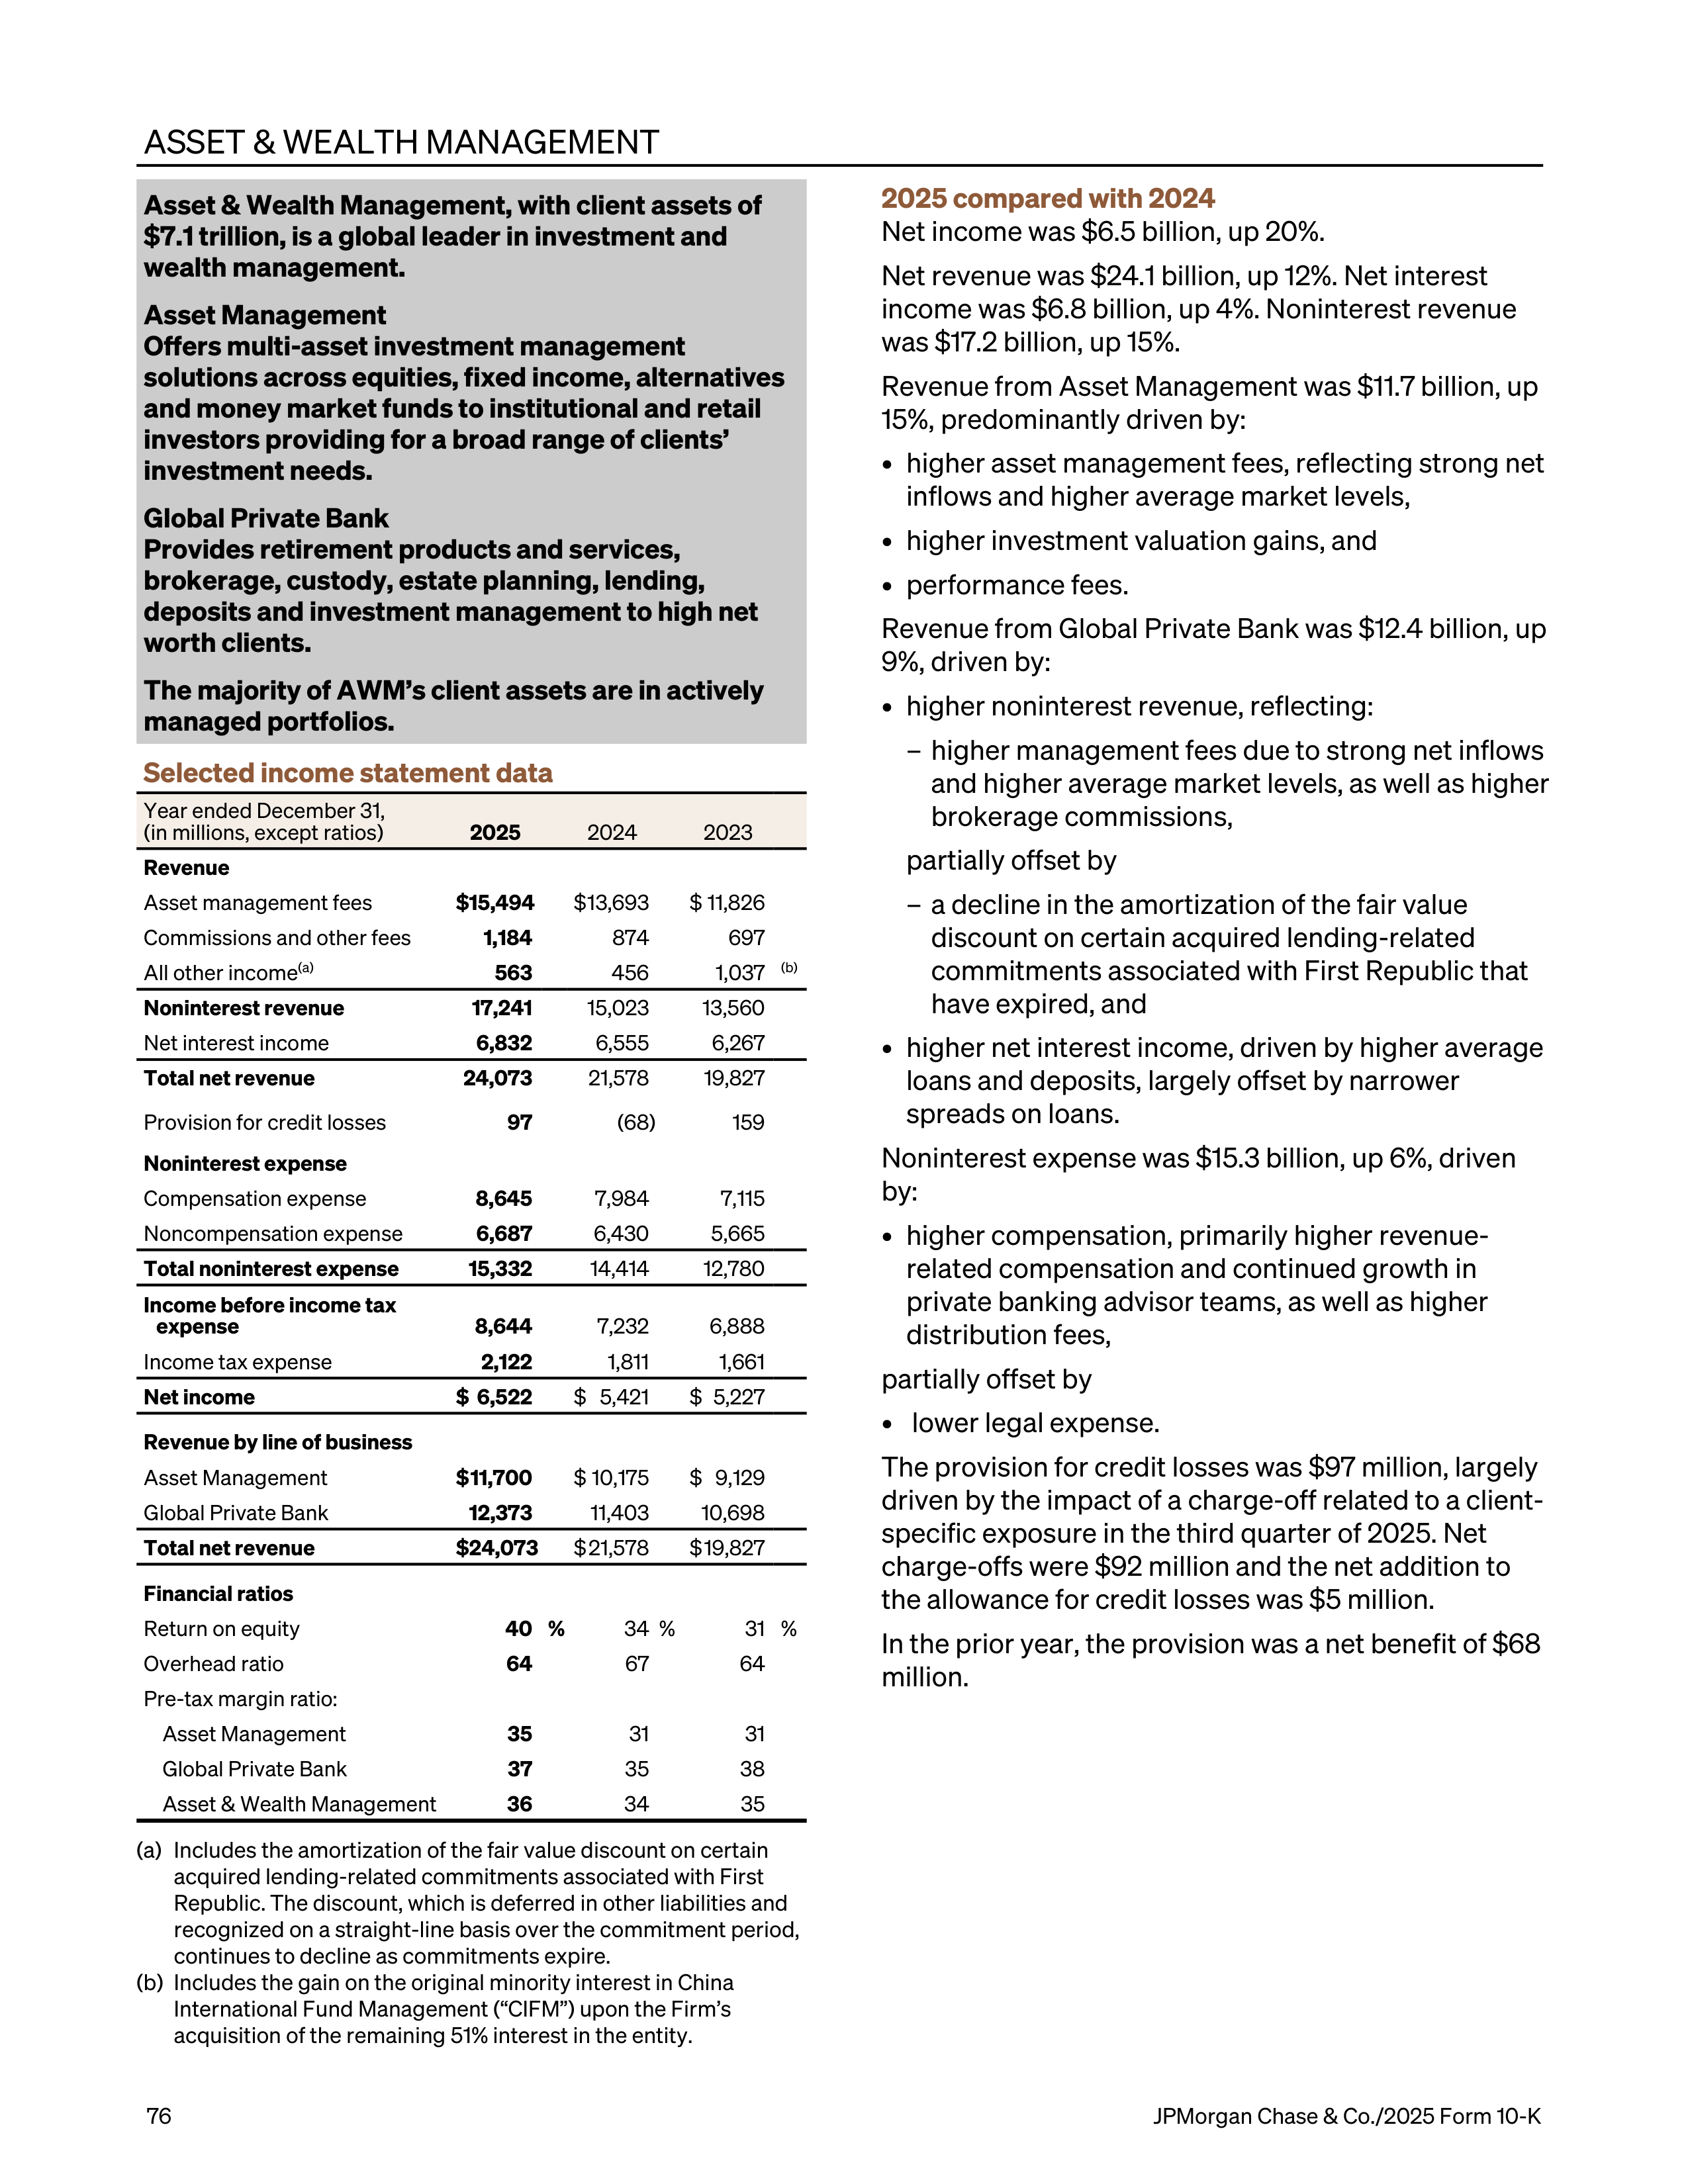
ASSET & WEALTH MANAGEMENT
Asset & Wealth Management, with client assets of
$7.1 trillion, is a global leader in investment and
wealth management.
Asset Management
Offers multi-asset investment management
solutions across equities, fixed income, alternatives
and money market funds to institutional and retail
investors providing for a broad range of clients’
investment needs.
Global Private Bank
Provides retirement products and services,
brokerage, custody, estate planning, lending,
deposits and investment management to high net
worth clients.
The majority of AWM’s client assets are in actively
managed portfolios.
Selected income statement data
Year ended December 31,
(in millions, except ratios)
2025
2024
2023
Revenue
Asset management fees
$ 15,494
$ 13,693
$ 11,826
Commissions and other fees
1,184
874
697
All other income
(a)
563
456
1,037
(b)
Noninterest revenue
17,241
15,023
13,560
Net interest income
6,832
6,555
6,267
Total net revenue
24,073
21,578
19,827
Provision for credit losses
97
(68)
159
Noninterest expense
Compensation expense
8,645
7,984
7,115
Noncompensation expense
6,687
6,430
5,665
Total noninterest expense
15,332
14,414
12,780
Income before income tax
expense
8,644
7,232
6,888
Income tax expense
2,122
1,811
1,661
Net income
$ 6,522
$ 5,421
$ 5,227
Revenue by line of business
Asset Management
$ 11,700
$ 10,175
$ 9,129
Global Private Bank
12,373
11,403
10,698
Total net revenue
$ 24,073
$ 21,578
$ 19,827
Financial ratios
Return on equity
40 %
34 %
31 %
Overhead ratio
64
67
64
Pre-tax margin ratio:
Asset Management
35
31
31
Global Private Bank
37
35
38
Asset & Wealth Management
36
34
35
(a)
Includes the amortization of the fair value discount on certain
acquired lending-related commitments associated with First
Republic. The discount, which is deferred in other liabilities and
recognized on a straight-line basis over the commitment period,
continues to decline as commitments expire.
(b)
Includes the gain on the original minority interest in China
International Fund Management (“CIFM”) upon the Firm’s
acquisition of the remaining 51% interest in the entity.
2025 compared with 2024
Net income was $6.5 billion, up 20%.
Net revenue was $24.1 billion, up 12%. Net interest
income was $6.8 billion, up 4%. Noninterest revenue
was $17.2 billion, up 15%.
Revenue from Asset Management was $11.7 billion, up
15%, predominantly driven by:
•
higher asset management fees, reflecting strong net
inflows and higher average market levels,
•
higher investment valuation gains, and
•
performance fees.
Revenue from Global Private Bank was $12.4 billion, up
9%, driven by:
•
higher noninterest revenue, reflecting:
–
higher management fees due to strong net inflows
and higher average market levels, as well as higher
brokerage commissions,
partially offset by
–
a decline in the amortization of the fair value
discount on certain acquired lending-related
commitments associated with First Republic that
have expired, and
•
higher net interest income, driven by higher average
loans and deposits, largely offset by narrower
spreads on loans.
Noninterest expense was $15.3 billion, up 6%, driven
by:
•
higher compensation, primarily higher revenue-
related compensation and continued growth in
private banking advisor teams, as well as higher
distribution fees,
partially offset by
• lower legal expense.
The provision for credit losses was $97 million, largely
driven by the impact of a charge-off related to a client-
specific exposure in the third quarter of 2025. Net
charge-offs were $92 million and the net addition to
the allowance for credit losses was $5 million.
In the prior year, the provision was a net benefit of $68
million.
76
JPMorgan Chase & Co./2025 Form 10-K
Asset Management has two high-level measures
of its overall fund performance.
•
Percentage of active mutual fund and active ETF assets under
management in funds rated 4- or 5-star:
Mutual fund rating
services rank funds based on their risk adjusted performance
over various periods. A 5-star rating is the best rating and
represents the top 10% of industry-wide ranked funds. A 4-star
rating represents the next 22.5% of industry-wide ranked funds.
A 3-star rating represents the next 35% of industry-wide ranked
funds. A 2-star rating represents the next 22.5% of industry-
wide ranked funds. A 1-star rating is the worst rating and
represents the bottom 10% of industry-wide ranked funds. An
overall Morningstar rating is derived from a weighted average of
the performance associated with a fund’s three-, five and ten-
year (if applicable) Morningstar Rating metrics. For U.S.-
domiciled funds, separate star ratings are provided at the
individual share class level. The Nomura “star rating” is based
on three-year risk-adjusted performance only. Funds with fewer
than three years of history are not rated and hence excluded
from these rankings. All ratings, the assigned peer categories
and the asset values used to derive these rankings are sourced
from the applicable fund rating provider. Where applicable, the
fund rating providers redenominate asset values into U.S.
dollars. The percentage of AUM is based on star ratings at the
share class level for U.S.-domiciled funds, and at a “primary
share class” level to represent the star rating of all other funds,
except for Japan, for which Nomura provides ratings at the fund
level. The performance data may have been different if all share
classes had been included. Past performance is not indicative of
future results.
•
Percentage of active mutual fund and active ETF assets under
management in funds ranked in the 1st or 2nd quartile (one,
three and five years)
: All quartile rankings, the assigned peer
categories and the asset values used to derive these rankings
are sourced from the fund rating providers. Quartile rankings
are based on the net-of-fee absolute return of each fund. Where
applicable, the fund rating providers redenominate asset values
into U.S. dollars. The percentage of AUM is based on fund
performance and associated peer rankings at the share class
level for U.S.-domiciled funds, at a “primary share class” level to
represent the quartile ranking for U.K., Luxembourg and Hong
Kong SAR funds and at the fund level for all other funds. The
performance data may have been different if all share classes
had been included. Past performance is not indicative of future
results.
“
Primary share class
” means the C share class for European
funds and Acc share class for Hong Kong SAR and Taiwan
funds. If these share classes are not available, the oldest share
class is used as the primary share class.
Selected metrics
As of or for the year
ended December 31,
(in millions, except
ranking data, ratios and
employees)
2025
2024
2023
% of JPM mutual fund
assets and ETFs rated
as 4- or 5-star
(a)
60 %
69 %
69 %
% of JPM mutual fund
assets and ETFs ranked
in 1
st
or 2
nd
quartile:
(b)
1 year
44
73
40
3 years
54
75
67
5 years
73
77
71
Selected balance sheet
data (period-end)
(c)
Total assets
$ 288,065
$ 255,385
$ 245,512
Loans
266,385
236,303
227,929
Deposits
257,316
248,287
233,232
Equity
16,000
15,500
17,000
Selected balance sheet
data (average)
(c)
Total assets
$ 267,986
$ 246,254
$ 240,222
Loans
246,596
227,676
220,487
Deposits
245,248
235,146
216,178
Equity
16,000
15,500
16,671
Employees
29,722
(d)
29,403
28,485
Number of Global
Private Bank client
advisors
4,101
3,775
3,515
Credit data and quality
statistics
(c)
Net charge-offs/
(recoveries)
$
92
$
21
$
13
Nonaccrual loans
1,199
700
650
Allowance for credit
losses:
Allowance for loan
losses
$
536
$
539
$
633
Allowance for lending-
related commitments
43
35
28
Total allowance for
credit losses
$
579
$
574
$
661
Net charge-off/(recovery)
rate
0.04 %
0.01 %
0.01 %
Allowance for loan losses
to period-end loans
0.20
0.23
0.28
Allowance for loan losses
to nonaccrual loans
45
77
97
Nonaccrual loans to
period-end loans
0.45
0.30
0.29
(a)
Represents the Morningstar Rating for all domiciled funds except
for Japan domiciled funds which use Nomura. Includes only Asset
Management retail active open-ended mutual funds and active
ETFs that have a rating. Excludes money market funds,
Undiscovered Managers Fund, and Brazil domiciled funds.
JPMorgan Chase & Co./2025 Form 10-K
77
(b)
Quartile ranking sourced from Morningstar, Lipper and Nomura
based on country of domicile. Includes only Asset Management
retail active open-ended mutual funds and active ETFs that are
ranked by the aforementioned sources. Excludes money market
funds, Undiscovered Managers Fund, and Brazil domiciled funds.
(c)
Loans, deposits and related credit data and quality statistics
relate to the Global Private Bank business.
(d)
In
the first quarter of 2025, 130 employees were transferred to
Corporate as a result of the centralization of certain functions.
Client assets
2025 compared with 2024
Assets under management were $4.8 trillion, up 18%,
and client assets were $7.1 trillion, up 20%. These
increases were driven by higher market levels and
continued net inflows.
Client assets
December 31,
(in billions)
2025
2024
2023
Assets by asset class
Liquidity
$
1,279
$
1,083 $
926
Fixed income
998
851
751
Equity
1,400
1,128
868
Multi-asset
884
764
680
Alternatives
230
219
197
Total assets under
management
4,791
4,045
3,422
Custody/brokerage/
administration/deposits
2,327
1,887
1,590
Total client assets
(a)
$
7,118
$
5,932 $
5,012
Assets by client segment
Private Banking
(b)
$
1,414
$
1,162 $
924
Global Institutional
1,953
1,692
1,488
Global Funds
(b)
1,424
1,191
1,010
Total assets under
management
$
4,791
$
4,045 $
3,422
Private Banking
(b)
$ 3,549
$
2,902 $
2,402
Global Institutional
2,121
1,820
1,594
Global Funds
(b)
1,448
1,210
1,016
Total client assets
(a)
$
7,118
$
5,932 $
5,012
(a)
Includes CCB client investment assets invested in managed
accounts and J.P. Morgan mutual funds where AWM is the
investment manager.
(b)
In the first quarter of 2025, the Firm realigned certain client
assets from Private Banking to Global Funds to reflect them in
the client segment where the assets are invested. Prior period
amounts have been revised to conform with the current
presentation.
Client assets (continued)
Year ended December 31,
(in billions)
2025
2024
2023
Assets under management
rollforward
Beginning balance
$ 4,045
$
3,422 $
2,766
Net asset flows:
Liquidity
183
140
242
Fixed income
94
91
70
Equity
95
114
70
Multi-asset
16
19
1
Alternatives
4
10
(1)
Market/performance/other
impacts
354
249
274
Ending balance, December 31
$
4,791
$
4,045 $
3,422
Client assets rollforward
Beginning balance
$ 5,932
$
5,012 $
4,048
Net asset flows
553
486
490
Market/performance/other
impacts
633
434
474
Ending balance, December 31
$
7,118
$
5,932 $
5,012
Selected Metrics
As of December 31,
2025
2024
Change
Firmwide Wealth Management
Client assets (in billions)
(a)
$ 4,521
$ 3,756
20 %
Number of client advisors
10,150
9,530
7
Stock Plan Administration
Number of stock plan
participants (in thousands)
1,794
1,327
35
Client assets (in billions)
$
372
$
270
38 %
(a)
Consists of Global Private Bank in AWM and client investment
assets in J.P. Morgan Wealth Management in CCB.
78
JPMorgan Chase & Co./2025 Form 10-K
International metrics
Year ended December 31,
(in billions, except where
otherwise noted)
2025
2024
2023
Total net revenue (in millions)
(a)
Europe/Middle East/Africa
$ 4,049
$
3,563 $
3,377
Asia-Pacific
2,432
2,023
1,876
Latin America/Caribbean
1,228
1,065
985
Total international net revenue
7,709
6,651
6,238
North America
16,364
14,927
13,589
Total net revenue
(a)
$ 24,073
$ 21,578 $ 19,827
Assets under management
Europe/Middle East/Africa
$
709
$
604 $
539
Asia-Pacific
374
302
263
Latin America/Caribbean
126
106
86
Total international assets under
management
1,209
1,012
888
North America
3,582
3,033
2,534
Total assets under
management
$
4,791
$
4,045 $
3,422
Client assets
Europe/Middle East/Africa
$
1,035
$
841 $
740
Asia-Pacific
620
482
406
Latin America/Caribbean
310
254
232
Total international client assets
1,965
1,577
1,378
North America
5,153
4,355
3,634
Total client assets
$
7,118
$
5,932 $
5,012
(a)
Regional revenue is based on the domicile of the client.
JPMorgan Chase & Co./2025 Form 10-K
79
CORPORATE
Corporate consists of Treasury and Chief
Investment Office (“CIO”) and Other Corporate.
Treasury and CIO is predominantly responsible
for measuring, monitoring, reporting and
managing the Firm’s liquidity, funding, capital,
structural interest rate and foreign exchange
risks.
Other Corporate includes staff functions and
expense that is centrally managed as well as
certain Firm initiatives and activities not solely
aligned to a specific LOB. The major Other
Corporate functions include Real Estate,
Technology, Legal, Corporate Finance, Human
Resources, Internal Audit, Risk Management,
Compliance, Control Management, Corporate
Responsibility and various Other Corporate
groups.
Selected income statement and balance sheet data
As of or for the year
ended December 31,
(in millions, except
employees)
2025
2024
2023
Revenue
Principal
transactions
$
(339)
$
152
$
302
Investment
securities losses
(58)
(1,020)
(3,180)
All other income
1,308
8,476
(f)
3,010
(h)
Noninterest
revenue
911
7,608
132
Net interest income
6,114
9,786
7,906
Total net revenue
(a)
7,025
17,394
8,038
Provision for credit
losses
7
10
171
Noninterest
expense
(b)
1,825
3,994
(g)
5,601
Income before
income tax
expense
5,193
13,390
2,266
Income tax
expense/(benefit)
673
(d)
2,789
(555)
(i)
Net income
$
4,520
$
10,601
$
2,821
Total net revenue
Treasury and CIO
6,501
9,638
6,072
Other Corporate
524
7,756
1,966
Total net revenue
$
7,025
$ 17,394
$
8,038
Net income/(loss)
Treasury and CIO
4,565
7,013
4,206
Other Corporate
(b)
(45)
3,588
(1,385)
Total net income
$
4,520
$
10,601
$
2,821
Total assets
(period-end)
$ 1,329,632
$ 1,323,967
$ 1,348,437
Loans (period-end)
2,941
1,964
1,924
Deposits
(c)
35,874
27,581
21,826
Employees
50,031
(e)
49,610
47,530
(a)
Included taxable-equivalent adjustments, predominantly driven
by tax-exempt income from municipal bonds, of $154 million,
$182 million and $211 million for the years ended December 31,
2025, 2024 and 2023, respectively.
(b)
Included FDIC special assessment accrual releases of
$763 million and an accrual increase of $725 million for the years
ended December 31, 2025 and 2024, respectively, which are
adjustments to the initial $2.9 billion estimate recorded in the
fourth quarter of 2023.
(c)
Predominantly relates to the Firm's international consumer
initiatives.
(d)
Included a $774 million income tax benefit recorded in the
second quarter of 2025, driven by the resolution of certain tax
audits and the impact of tax regulations related to foreign
currency translation gains and losses finalized in 2024 and
effective for 2025.
(e)
In the first quarter of 2025, 768 employees were transferred from
the LOBs to Corporate as a result of the centralization of certain
functions.
(f)
Included the net gain related to Visa shares of $7.9 billion
recorded in the second quarter of 2024. Refer to Note 6 for
additional information.
(g)
Included a $1.0 billion contribution of Visa shares to the
JPMorgan Chase Foundation recorded in the second quarter of
2024. Refer to Note 6 for additional information.
(h)
Included the estimated bargain purchase gain of $2.8 billion for
the year ended December 31, 2023 associated with the First
Republic acquisition. Refer to Notes 6 and 34 for additional
information.
(i)
Income taxes associated with the First Republic acquisition were
reflected in the estimated bargain purchase gain.
80
JPMorgan Chase & Co./2025 Form 10-K
2025 compared with 2024
Net income was $4.5 billion, compared with $10.6
billion in the prior year.
Net revenue was $7.0 billion, compared with $17.4
billion in the prior year.
Net interest income was $6.1 billion, down $3.7 billion,
driven by the impact of lower rates and changes in FTP
for consumer deposits, partially offset by the impact of
investment securities activity.
Refer to Business Segment & Corporate Results on
page 63 for additional information on FTP.
Noninterest revenue was $911 million, compared with
$7.6 billion in the prior year, driven by:
•
the absence of the $7.9 billion net gain related to
Visa shares recorded in the second quarter of 2024,
partially offset by
•
lower net investment securities losses associated
with repositioning the investment securities portfolio
in Treasury and CIO. The prior year net loss was
primarily related to sales of U.S. GSE and
government agency MBS and U.S. Treasuries, and
•
the $588 million First Republic-related gain
recorded in the first quarter of 2025.
Noninterest expense was $1.8 billion, down 54%,
primarily driven by:
•
lower FDIC-related expense driven by releases of
FDIC special assessment accruals of $763 million,
compared with an accrual increase of $725 million in
the first quarter of the prior year, and
•
the absence of the following items recorded in the
prior year
–
a $1.0 billion contribution of Visa shares to the
JPMorgan Chase Foundation, and
–
restructuring and integration costs associated
with First Republic.
Refer to Note 6 for additional information on Visa
shares and FDIC-related expense, Note 10 and Note 13
for additional information on the investment securities
portfolio and the allowance for credit losses, and Note
6 and Note 34 for additional information on the First
Republic acquisition.
The current period income tax expense was driven by:
•
changes in the level and mix of income and
expenses subject to U.S. federal, state and local
taxes,
partially offset by
•
a $774 million income tax benefit recorded in the
second quarter of 2025, driven by the resolution of
certain tax audits and the impact of tax regulations
related to foreign currency translation gains and
losses finalized in 2024 and effective for 2025.
Other Corporate includes the Strategic Investment
Group within the Firm’s Security and Resiliency
Initiative, as well as the Firm's international consumer
initiatives, which primarily consist of Chase U.K., J.P.
Morgan Personal Investing (formerly Nutmeg) and an
ownership stake in C6 Bank.
The deposits within Corporate relate to the Firm’s
international consumer initiatives and have increased
as a result of growth in customer accounts.
JPMorgan Chase & Co./2025 Form 10-K
81
Treasury and CIO overview
Treasury and CIO is predominantly responsible for
measuring, monitoring, reporting and managing the
Firm’s liquidity, funding, capital, structural interest rate
and foreign exchange risks. The risks managed by
Treasury and CIO arise from the activities undertaken
by the Firm’s three reportable business segments to
serve their respective customer and client bases,
which generate both on- and off-balance sheet assets
and liabilities.
Treasury and CIO seeks to achieve the Firm’s asset-
liability management objectives generally by investing
in high quality securities that are managed for the
longer-term as part of the Firm’s investment securities
portfolio. Treasury and CIO also uses derivatives to
meet the Firm’s asset-liability management objectives.
Refer to Note 5 for further information on derivatives.
In addition, Treasury and CIO manages the Firm’s cash
position primarily through deposits at central banks
and investments in short-term instruments. Refer to
Liquidity Risk Management on pages 100–107 for
further information on liquidity and funding risk. Refer
to Market Risk Management on pages 133-142 for
information on interest rate and foreign exchange
risks.
The investment securities portfolio predominantly
consists of U.S. and non-U.S. government securities,
U.S. GSE and government agency and nonagency
mortgage-backed securities, collateralized loan
obligations, obligations of U.S. states and
municipalities and other ABS. At December 31, 2025,
the Treasury and CIO investment securities portfolio,
net of the allowance for credit losses, was $774.0
billion, and the average credit rating of the securities
comprising the portfolio was AA+ (based upon
external ratings where available and, where not
available, based primarily upon internal risk ratings).
Refer to Note 10 for further information on the Firm’s
investment securities portfolio and internal risk
ratings.
Selected income statement and balance sheet data
As of or for the year
ended December 31,
(in millions)
2025
2024
2023
Investment securities
losses
$
(58)
$
(1,020) $
(3,180)
Available-for-sale
securities (average)
$ 463,541
(b)
$ 287,260
$ 200,708
(c)
Held-to-maturity
securities (average)
271,309
(b)
321,384
402,010
(c)
Investment securities
portfolio (average)
$ 734,850
$ 608,644
$ 602,718
Available-for-sale
securities (period-
end)
$ 503,896
(b)
$ 403,796
$ 199,354
(c)
Held-to-maturity
securities (period–
end)
270,134
(b)
274,468
369,848
(c)
Investment securities
portfolio, net of
allowance for credit
losses (period–end)
(a)
$ 774,030
$ 678,264
$ 569,202
(a)
As of December 31, 2025, 2024 and 2023, the allowance for
credit losses on investment securities was $73 million,
$105 million and $94 million, respectively.
(b)
During the third quarter of 2025, the Firm transferred $44.1
billion of investment securities from AFS to HTM for asset-
liability management purposes.
(c)
Effective January 1, 2023, the Firm adopted the portfolio layer
method hedge accounting guidance. As permitted by the
guidance, the Firm elected to transfer $7.1 billion of investment
securities from HTM to AFS. Refer to Note 1 and Note 10 for
additional information.
82
JPMorgan Chase & Co./2025 Form 10-K
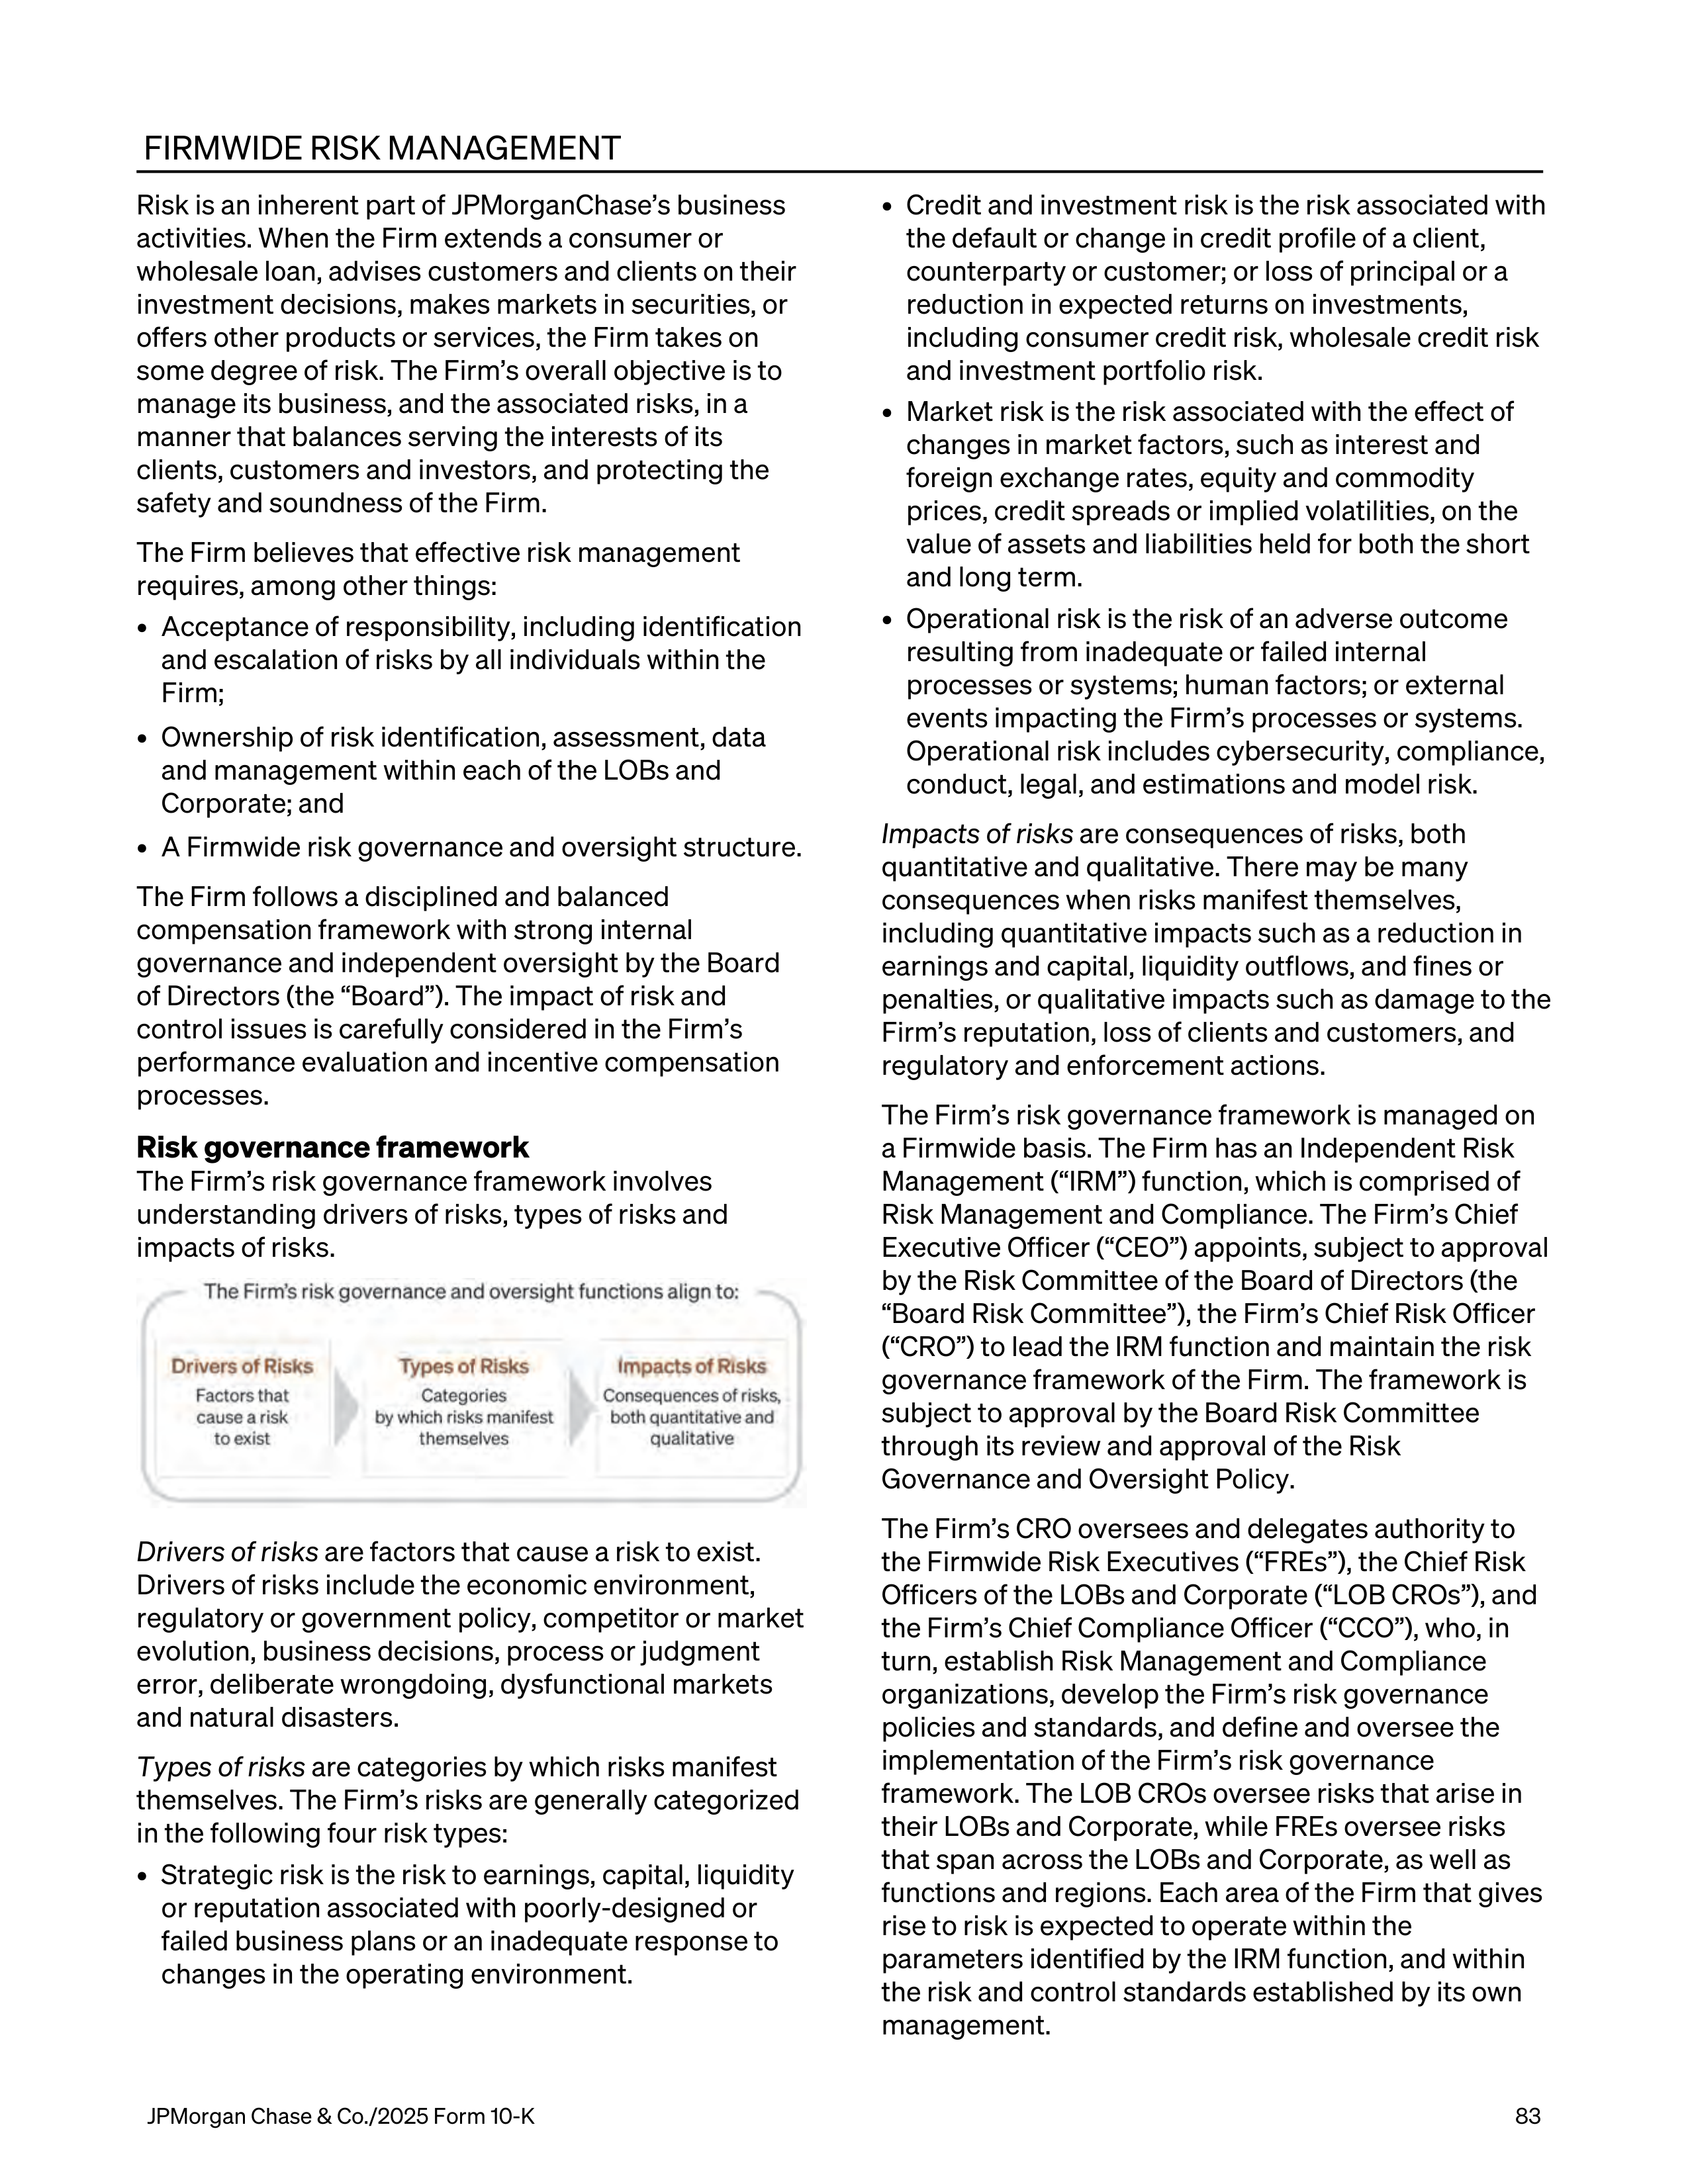

FIRMWIDE RISK MANAGEMENT
Risk is an inherent part of JPMorganChase’s business
activities. When the Firm extends a consumer or
wholesale loan, advises customers and clients on their
investment decisions, makes markets in securities, or
offers other products or services, the Firm takes on
some degree of risk. The Firm’s overall objective is to
manage its business, and the associated risks, in a
manner that balances serving the interests of its
clients, customers and investors, and protecting the
safety and soundness of the Firm.
The Firm believes that effective risk management
requires, among other things:
•
Acceptance of responsibility, including identification
and escalation of risks by all individuals within the
Firm;
•
Ownership of risk identification, assessment, data
and management within each of the LOBs and
Corporate; and
•
A Firmwide risk governance and oversight structure.
The Firm follows a disciplined and balanced
compensation framework with strong internal
governance and independent oversight by the Board
of Directors (the “Board”). The impact of risk and
control issues is carefully considered in the Firm’s
performance evaluation and incentive compensation
processes.
Risk governance framework
The Firm’s risk governance framework involves
understanding drivers of risks, types of risks and
impacts of risks.
Drivers of risks
are factors that cause a risk to exist.
Drivers of risks include the economic environment,
regulatory or government policy, competitor or market
evolution, business decisions, process or judgment
error, deliberate wrongdoing, dysfunctional markets
and natural disasters.
Types of risks
are categories by which risks manifest
themselves. The Firm’s risks are generally categorized
in the following four risk types:
•
Strategic risk is the risk to earnings, capital, liquidity
or reputation associated with poorly-designed or
failed business plans or an inadequate response to
changes in the operating environment.
•
Credit and investment risk is the risk associated with
the default or change in credit profile of a client,
counterparty or customer; or loss of principal or a
reduction in expected returns on investments,
including consumer credit risk, wholesale credit risk
and investment portfolio risk.
•
Market risk is the risk associated with the effect of
changes in market factors, such as interest and
foreign exchange rates, equity and commodity
prices, credit spreads or implied volatilities, on the
value of assets and liabilities held for both the short
and long term.
•
Operational risk is the risk of an adverse outcome
resulting from inadequate or failed internal
processes or systems; human factors; or external
events impacting the Firm’s processes or systems.
Operational risk includes cybersecurity, compliance,
conduct, legal, and estimations and model risk.
Impacts of risks
are consequences of risks, both
quantitative and qualitative. There may be many
consequences when risks manifest themselves,
including quantitative impacts such as a reduction in
earnings and capital, liquidity outflows, and fines or
penalties, or qualitative impacts such as damage to the
Firm’s reputation, loss of clients and customers, and
regulatory and enforcement actions.
The Firm’s risk governance framework is managed on
a Firmwide basis. The Firm has an Independent Risk
Management (“IRM”) function, which is comprised of
Risk Management and Compliance. The Firm’s Chief
Executive Officer (“CEO”) appoints, subject to approval
by the Risk Committee of the Board of Directors (the
“Board Risk Committee”), the Firm’s Chief Risk Officer
(“CRO”) to lead the IRM function and maintain the risk
governance framework of the Firm. The framework is
subject to approval by the Board Risk Committee
through its review and approval of the Risk
Governance and Oversight Policy.
The Firm’s CRO oversees and delegates authority to
the Firmwide Risk Executives (“FREs”), the Chief Risk
Officers of the LOBs and Corporate (“LOB CROs”), and
the Firm’s Chief Compliance Officer (“CCO”), who, in
turn, establish Risk Management and Compliance
organizations, develop the Firm’s risk governance
policies and standards, and define and oversee the
implementation of the Firm’s risk governance
framework. The LOB CROs oversee risks that arise in
their LOBs and Corporate, while FREs oversee risks
that span across the LOBs and Corporate, as well as
functions and regions. Each area of the Firm that gives
rise to risk is expected to operate within the
parameters identified by the IRM function, and within
the risk and control standards established by its own
management.
JPMorgan Chase & Co./2025 Form 10-K
83
Three lines of defense
The Firm’s “three lines of defense” are as follows:
The
first line of defense consists of each LOB, Treasury
and CIO, and certain Other Corporate initiatives,
including their aligned Operations, Technology and
Control Management. The first line of defense owns
the risks, and identification of risks, associated with
their respective activities and the design and
execution of controls to manage those risks.
Responsibilities also include adherence to applicable
laws, rules and regulations and implementation of the
risk governance framework established by IRM, which
may include policies, standards, limits, thresholds and
controls.
The second line of defense is the IRM function, which is
separate from the first line of defense and is
responsible for independently measuring risk, as well
as assessing and challenging the risk management
activities of the first line of defense. IRM is also
responsible for the identification of risks within its
organization, its own adherence to applicable laws,
rules and regulations and for the development and
implementation of policies and standards with respect
to its own processes.
The third line of defense is Internal Audit, an
independent function that provides objective
assessment of the adequacy and effectiveness of
Firmwide processes, controls, governance and risk
management. The Internal Audit function is led by the
General Auditor, who reports to the Audit Committee
and administratively to the CEO.
In addition, there are other functions that contribute to
the Firmwide control environment but are not
considered part of a particular line of defense,
including Corporate Finance, Human Resources and
Legal. These other functions are responsible for the
identification of risks within their respective
organizations, adherence to applicable laws, rules and
regulations and implementation of the risk governance
framework established by IRM.
Risk identification and ownership
The LOBs and Corporate are responsible for the
identification of risks within their respective
organizations, as well as the design and execution of
controls, including IRM-specified controls, to manage
those risks. The IRM function reviews and challenges
the material risks identified by each LOB and
Corporate, and maintains a risk identification
framework and a central risk inventory.
Risk appetite
The Firm’s overall appetite for risk is governed by Risk
Appetite frameworks for quantitative and qualitative
risks. The Firm’s risk appetite is periodically set and
approved by senior management (including the CEO
and CRO) and approved by the Board Risk Committee.
Quantitative and qualitative risks are assessed to
monitor and measure the Firm’s capacity to take risk
consistent with its stated risk appetite. Risk appetite
results are reported to the Board Risk Committee.
Management’s discussion and analysis
84
JPMorgan Chase & Co./2025 Form 10-K
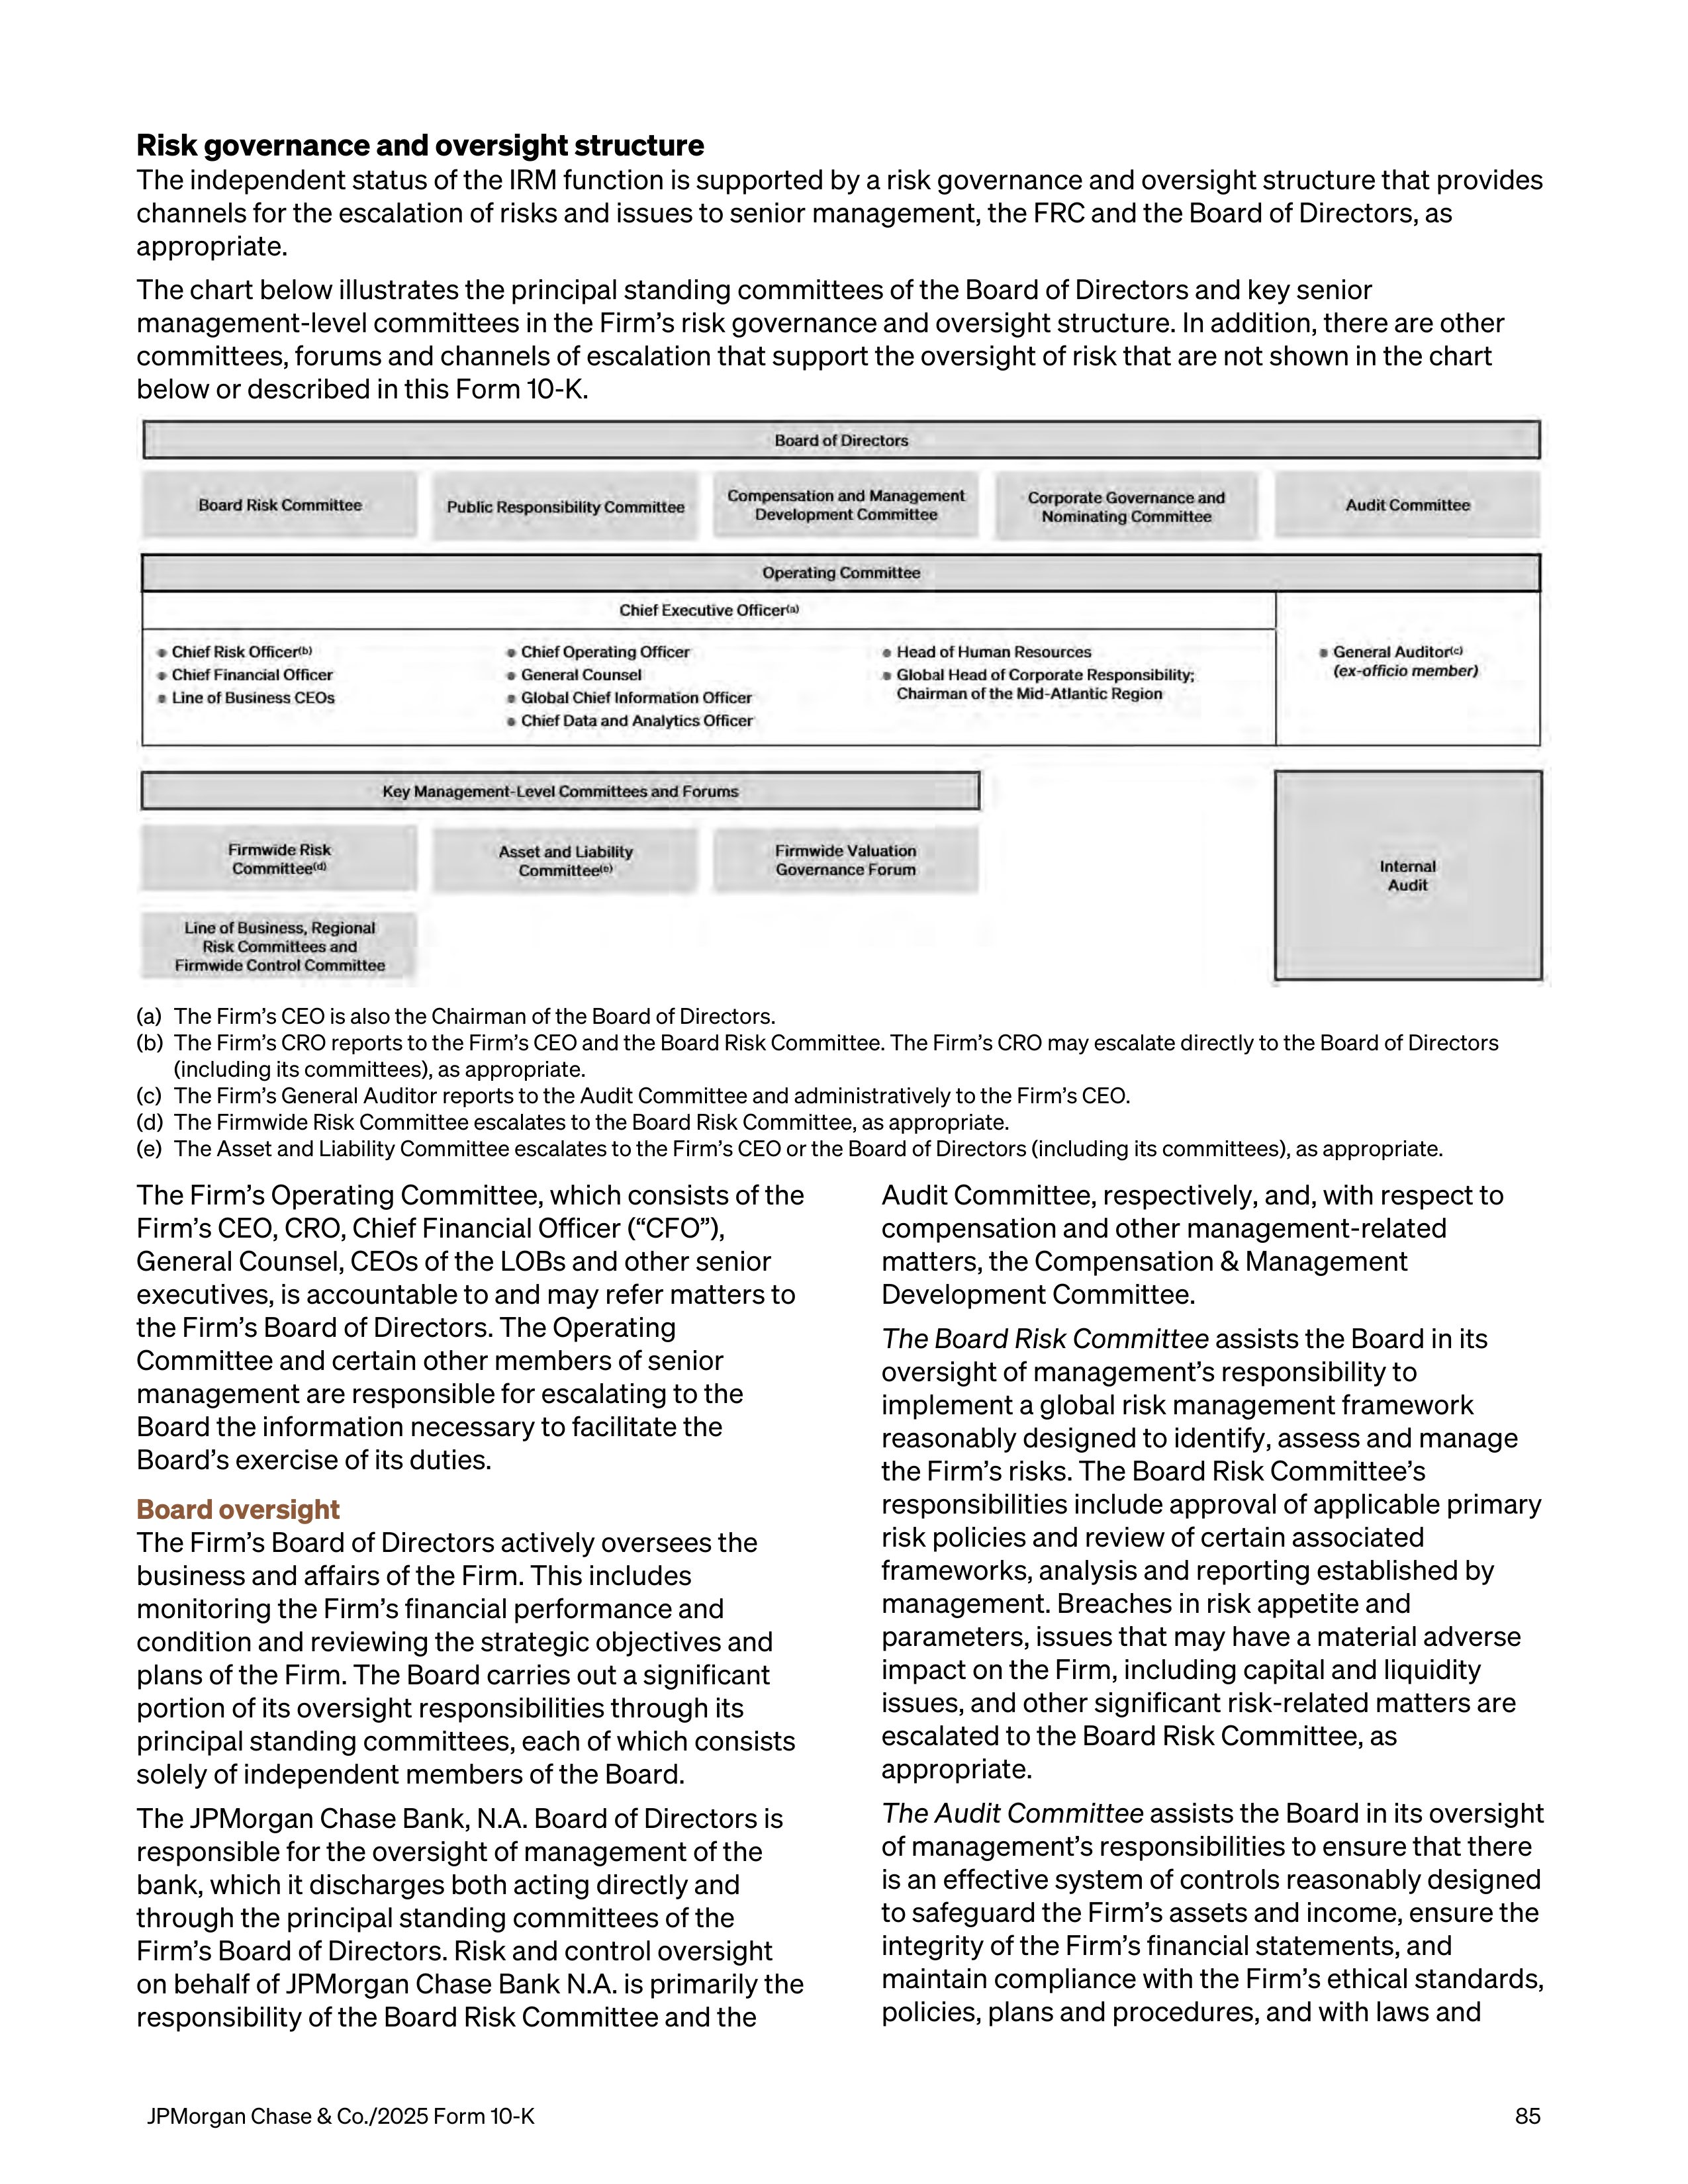
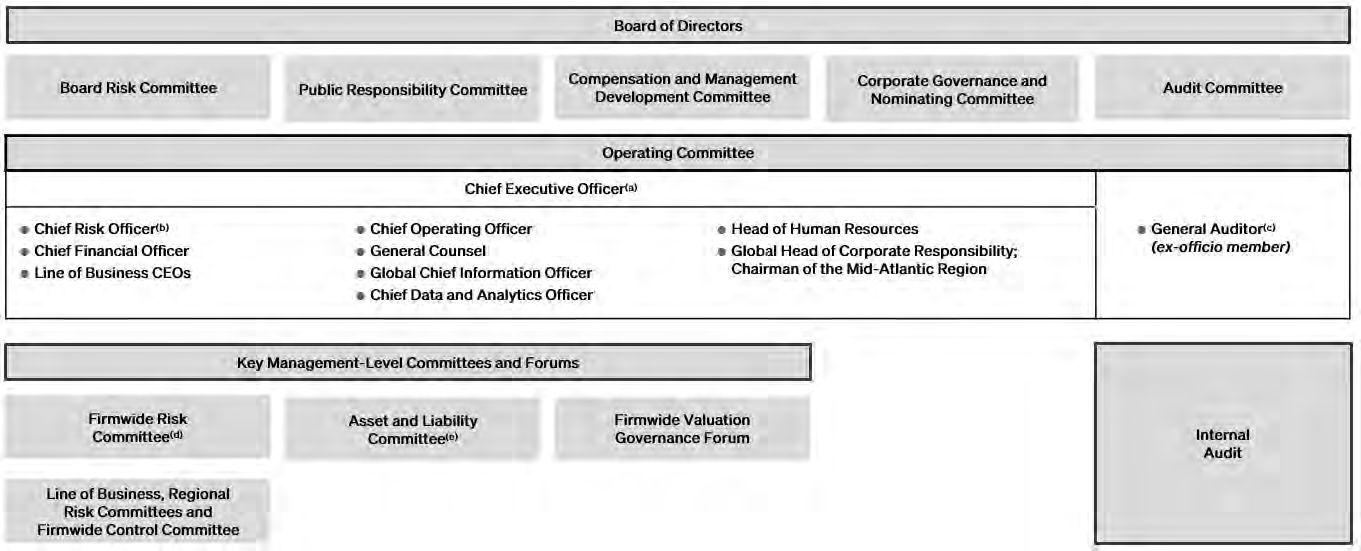
Risk governance and oversight structure
The independent status of the IRM function is supported by a risk governance and oversight structure that provides
channels for the escalation of risks and issues to senior management, the FRC and the Board of Directors, as
appropriate.
The chart below illustrates the principal standing committees of the Board of Directors and key senior
management-level committees in the Firm’s risk governance and oversight structure. In addition, there are other
committees, forums and channels of escalation that support the oversight of risk that are not shown in the chart
below or described in this Form 10-K.
(a)
The Firm’s CEO is also the Chairman of the Board of Directors.
(b)
The Firm’s CRO reports to the Firm’s CEO and the Board Risk Committee. The Firm’s CRO may escalate directly to the Board of Directors
(including its committees), as appropriate.
(c)
The Firm’s General Auditor reports to the Audit Committee and administratively to the Firm’s CEO.
(d)
The Firmwide Risk Committee escalates to the Board Risk Committee, as appropriate.
(e)
The Asset and Liability Committee escalates to the Firm’s CEO or the Board of Directors (including its committees), as appropriate.
The Firm’s Operating Committee, which consists of the
Firm’s CEO, CRO, Chief Financial Officer (“CFO”),
General Counsel, CEOs of the LOBs and other senior
executives, is accountable to and may refer matters to
the Firm’s Board of Directors. The Operating
Committee and certain other members of senior
management are responsible for escalating to the
Board the information necessary to facilitate the
Board’s exercise of its duties.
Board oversight
The Firm’s Board of Directors actively oversees the
business and affairs of the Firm. This includes
monitoring the Firm’s financial performance and
condition and reviewing the strategic objectives and
plans of the Firm. The Board carries out a significant
portion of its oversight responsibilities through its
principal standing committees, each of which consists
solely of independent members of the Board.
The JPMorgan Chase Bank, N.A. Board of Directors is
responsible for the oversight of management of the
bank, which it discharges both acting directly and
through the principal standing committees of the
Firm’s Board of Directors. Risk and control oversight
on behalf of JPMorgan Chase Bank N.A. is primarily the
responsibility of the Board Risk Committee and the
Audit Committee, respectively, and, with respect to
compensation and other management-related
matters, the Compensation & Management
Development Committee.
The Board Risk Committee
assists the Board in its
oversight of management’s responsibility to
implement a global risk management framework
reasonably designed to identify, assess and manage
the Firm’s risks. The Board Risk Committee’s
responsibilities include approval of applicable primary
risk policies and review of certain associated
frameworks, analysis and reporting established by
management. Breaches in risk appetite and
parameters, issues that may have a material adverse
impact on the Firm, including capital and liquidity
issues, and other significant risk-related matters are
escalated to the Board Risk Committee, as
appropriate.
The Audit Committee
assists the Board in its oversight
of management’s responsibilities to ensure that there
is an effective system of controls reasonably designed
to safeguard the Firm’s assets and income, ensure the
integrity of the Firm’s financial statements, and
maintain compliance with the Firm’s ethical standards,
policies, plans and procedures, and with laws and
JPMorgan Chase & Co./2025 Form 10-K
85
regulations. It also assists the Board in its oversight of
the qualifications, independence and performance of
the Firm’s independent registered public accounting
firm, and of the performance of the Firm’s Internal
Audit function.
The Compensation & Management Development
Committee
(“CMDC”)
assists the Board in its oversight
of the Firm’s compensation principles and practices.
The CMDC reviews and approves the Firm’s
compensation and qualified benefits programs. The
Committee reviews the performance of Operating
Committee members against their goals, and
approves their compensation awards. In addition, the
CEO’s compensation award is subject to ratification by
the independent directors of the Board. The CMDC
also reviews the development of and succession for
key executives. As part of the Board’s role of
reinforcing, demonstrating and communicating the
“tone at the top,” the CMDC oversees the Firm’s
culture, including reviewing updates from
management regarding significant conduct issues and
any related actions with respect to employees,
including compensation actions.
The Public Responsibility Committee
oversees and
reviews the Firm's positions and practices on public
responsibility matters such as community investment,
fair lending, sustainability, consumer practices and
other public policy issues that reflect the Firm's values
and character and could impact the Firm's reputation
among its stakeholders. The Committee also provides
guidance on these matters to management and the
Board, as appropriate.
The Corporate Governance & Nominating Committee
exercises general oversight with respect to the
governance of the Board of Directors. It reviews the
qualifications of and recommends to the Board
proposed nominees for election to the Board. The
Committee evaluates and recommends to the Board
corporate governance practices applicable to the
Firm. It also reviews the framework for assessing the
Board’s performance and self-evaluation.
Management oversight
The Firm’s senior management-level committees that
are primarily responsible for key risk-related functions
include:
The Firmwide Risk Committee (“FRC”)
is the Firm’s
highest management-level risk committee. It oversees
the risks inherent in the Firm’s business and provides a
forum for discussion of risk-related and other topics
and issues that are raised or escalated by its members
and other committees.
The Firmwide Control Committee (“FCC”)
is an
escalation committee for senior management to
review and discuss the Firmwide compliance and
operational risk environment, including identified
issues, compliance and operational risk metrics and
significant events that have been escalated.
Line of Business and Regional Risk Committees
are
responsible for overseeing the governance, limits and
controls that have been established within the scope
of their respective activities. These committees
review
the ways in which the particular LOB or the businesses
operating in a particular region could be exposed to
adverse outcomes, with a focus on identifying,
accepting, escalating and/or requiring remediation of
matters brought to these committees.
The Control Committees for the LOBs and certain of
the Corporate functions
over
see the risk and control
environment of their respective business or function,
inclusive of Operational Risk, Compliance and Conduct
Risks. As part of that mandate, they are responsible for
reviewing indicators of elevated or emerging risks and
other data that may impact the level of compliance and
operational risk in a business or function, addressing
key compliance and operational risk issues
, with an
emphasis on processes with control concerns, and
overseeing control remediation.
The
Asset and Liability Committee (“ALCO”)
is
responsible for overseeing the Firm’s asset and liability
management (“ALM”), including the activities and
frameworks supporting management of the balance
sheet, liquidity risk, interest rate risk and capital risk.
The Firmwide Valuation Governance Forum (“VGF”)
is
composed of senior finance and risk executives and is
responsible for overseeing the management of risks
arising from valuation activities conducted across the
Firm.
Management’s discussion and analysis
86
JPMorgan Chase & Co./2025 Form 10-K
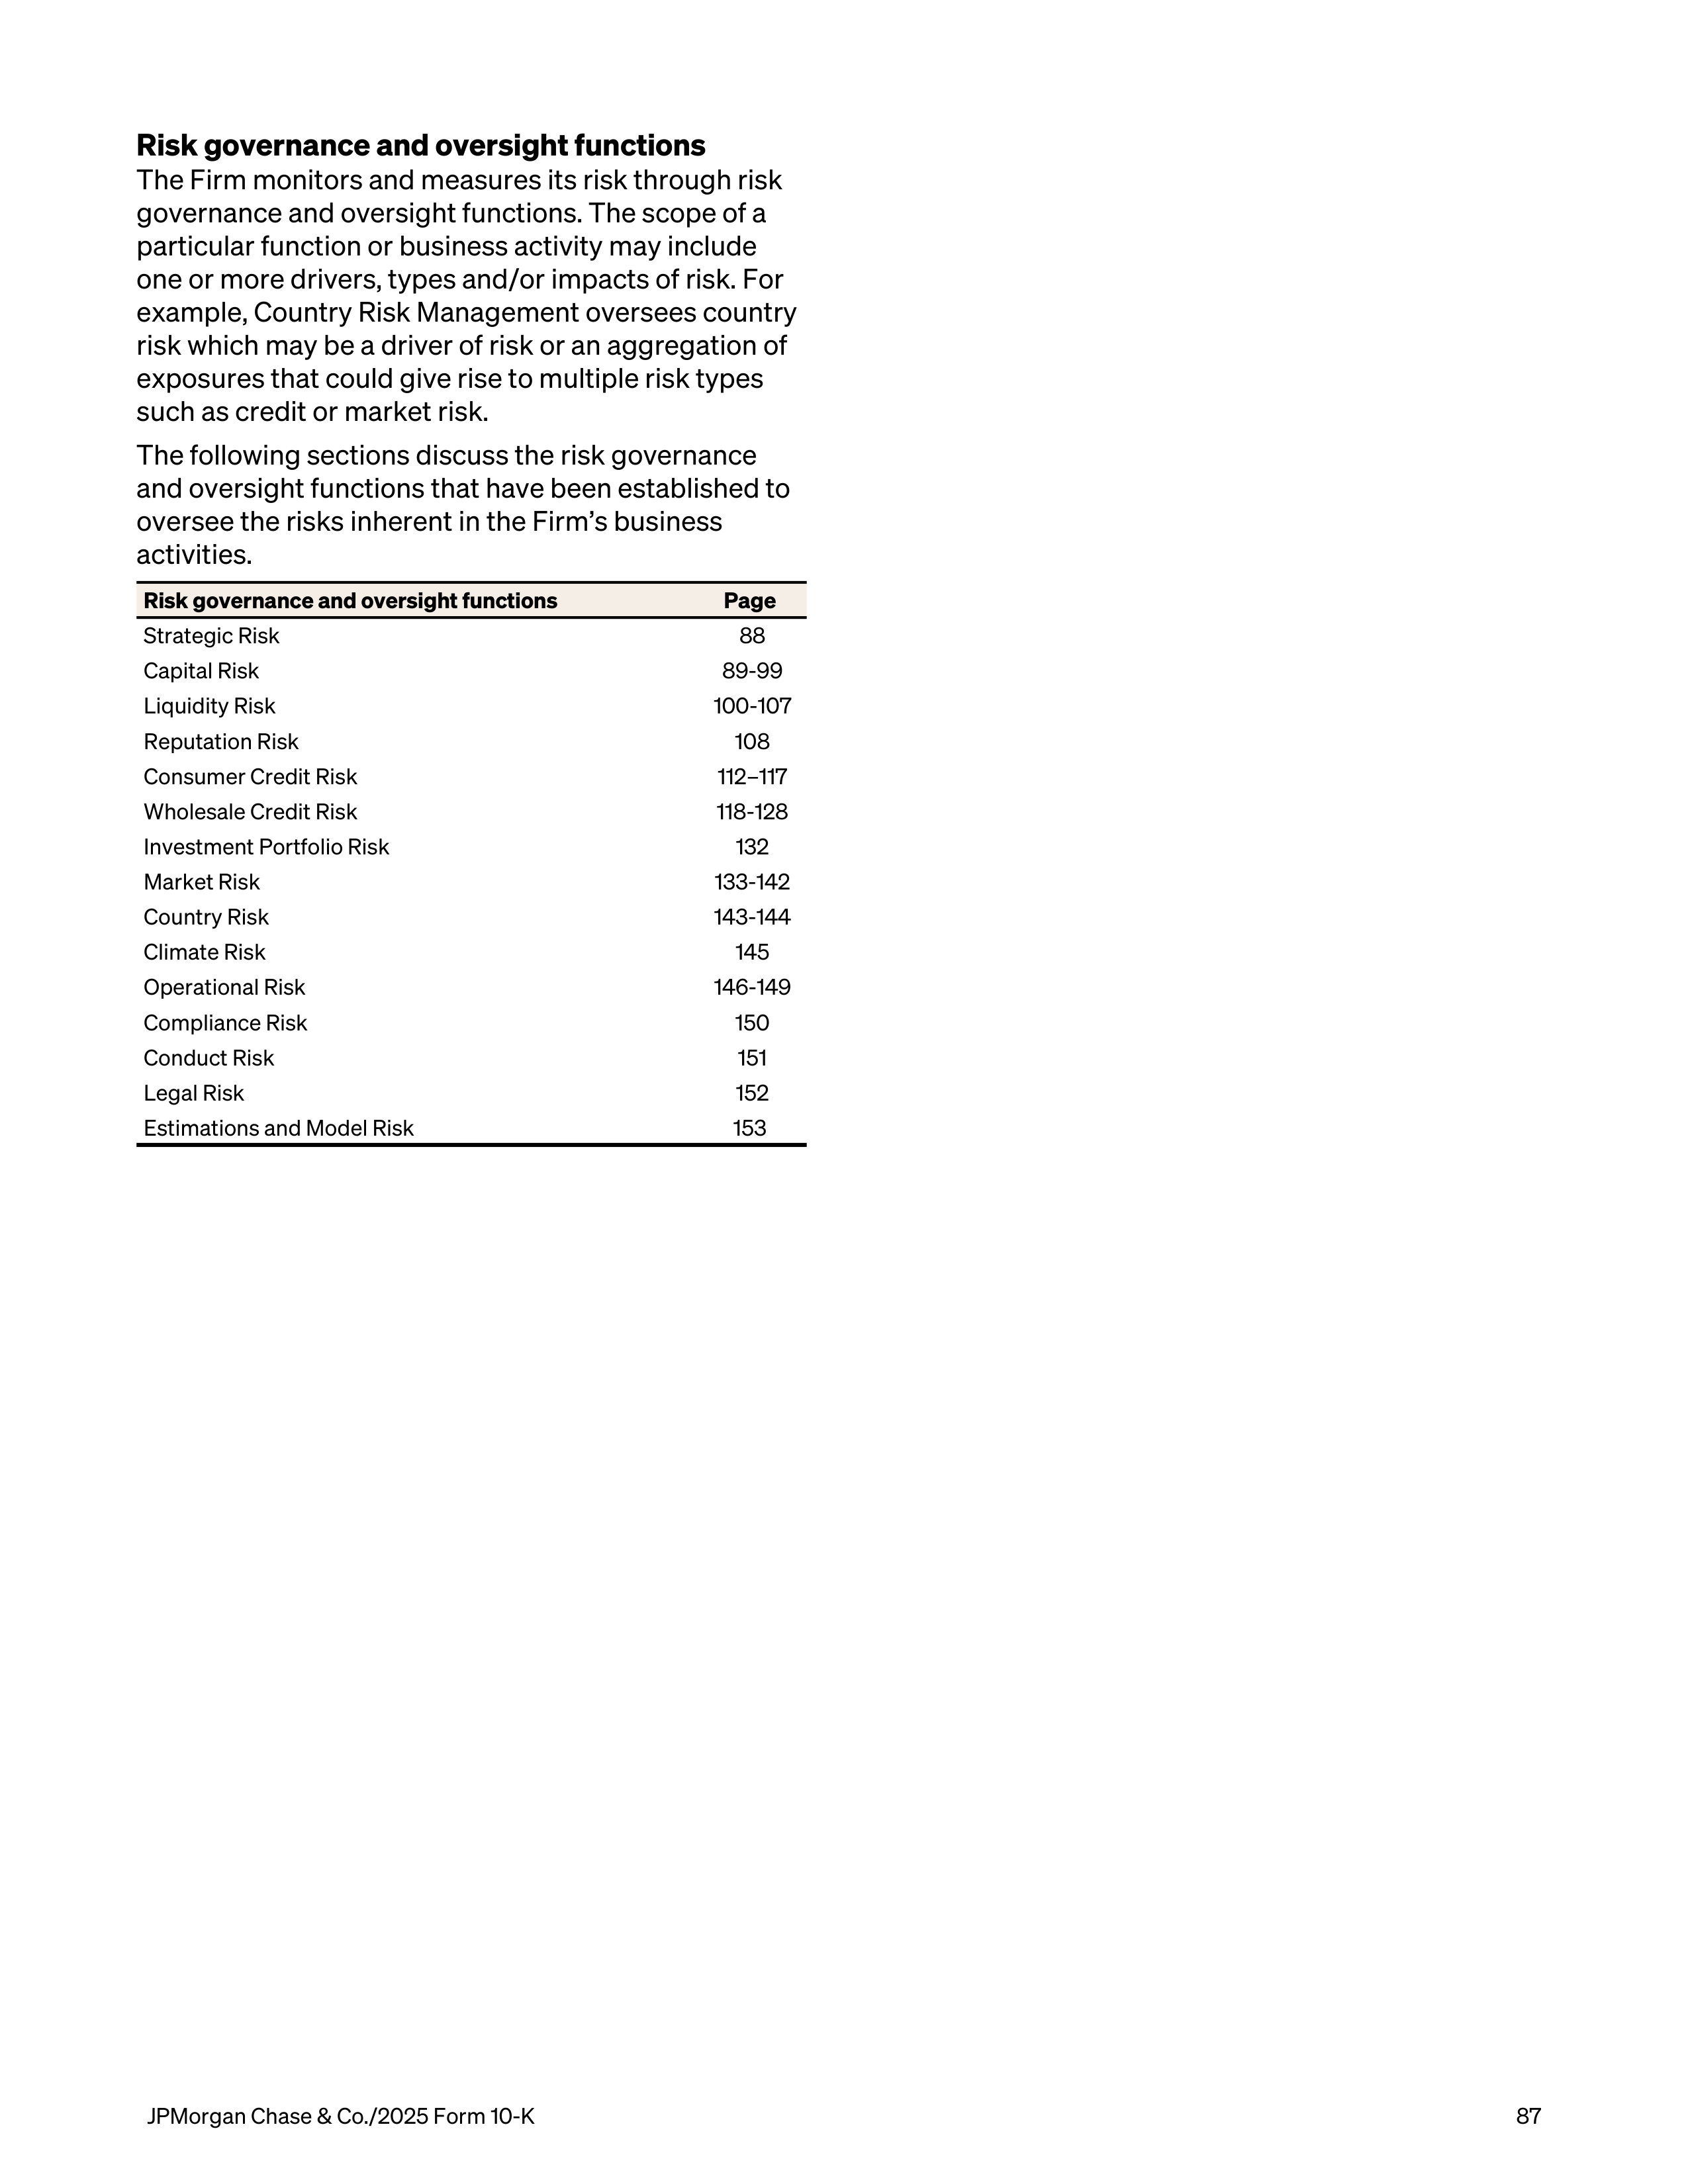
Risk governance and oversight functions
The Firm monitors and measures its risk through risk
governance and oversight functions. The scope of a
particular function or business activity may include
one or more drivers, types and/or impacts of risk. For
example, Country Risk Management oversees country
risk which may be a driver of risk or an aggregation of
exposures that could give rise to multiple risk types
such as credit or market risk.
The following sections discuss the risk governance
and oversight functions that have been established to
oversee the risks inherent in the Firm’s business
activities.
Risk governance and oversight functions
Page
Strategic Risk
88
Capital Risk
89-99
Liquidity Risk
100-107
Reputation Risk
108
Consumer Credit Risk
112–117
Wholesale Credit Risk
118-128
Investment Portfolio Risk
132
Market Risk
133-142
Country Risk
143-144
Climate Risk
145
Operational Risk
146-149
Compliance Risk
150
Conduct Risk
151
Legal Risk
152
Estimations and Model Risk
153
JPMorgan Chase & Co./2025 Form 10-K
87
STRATEGIC RISK MANAGEMENT
Strategic risk is the risk to earnings, capital, liquidity or
reputation associated with poorly-designed or failed
business plans or an inadequate response to changes
in the operating environment.
Management and oversight
The Operating Committee, together with the senior
leadership of each LOB and Corporate, are responsible
for managing strategic risk. IRM engages regularly in
strategic business discussions and decision-making,
including participation in relevant business reviews
and senior management meetings, risk and control
committees and other relevant governance forums,
and review of acquisitions and new business initiatives.
The Board of Directors oversees management’s
strategic decisions, and the Board Risk Committee
oversees IRM and the Firm’s risk governance
framework.
In addition, IRM conducts a qualitative assessment of
the LOB and Corporate strategic initiatives to assess
their impact on the risk profile of the Firm.
The Firm’s strategic planning process, which includes
the development of the Firm’s strategic plan and other
strategic initiatives, is one component of managing the
Firm’s strategic risk. The strategic plan outlines the
Firm’s strategic framework and initiatives, and
includes components such as budget, risk appetite,
capital, earnings and asset-liability management
objectives. Guided by the Firm’s Business Principles,
the Operating Committee and senior management
teams in each LOB and Corporate review and update
the strategic plan periodically, including evaluating the
strategic framework and performance of strategic
initiatives, assessing the operating environment,
refining existing strategies and developing new
strategies.
The Firm’s strategic plan, together with IRM’s
assessment, are provided to the Board as part of its
review and approval of the Firm’s strategic plan, and
the plan is also reflected in the Firm's budget.
The Firm’s balance sheet strategy, which focuses on
risk-adjusted returns, strong capital and robust
liquidity, is also a component in the management of
strategic risk. Refer to Capital Risk Management on
pages 89–99 for further information on capital risk.
Refer to Liquidity Risk Management on pages 100–107
for further information on liquidity risk. Refer to
Reputation Risk Management on page 108 for further
information on reputation risk.
Management’s discussion and analysis
88
JPMorgan Chase & Co./2025 Form 10-K
CAPITAL RISK MANAGEMENT
Capital risk is the risk that the Firm has an insufficient
level or composition of capital to support the Firm’s
business activities and associated risks during normal
economic environments and under stressed
conditions.
A strong capital position is essential to the Firm’s
business strategy and competitive position.
Maintaining a strong balance sheet to manage through
economic volatility is a strategic imperative of the
Firm’s Board of Directors, CEO and Operating
Committee. The Firm’s “fortress balance sheet”
philosophy focuses on risk-adjusted returns, strong
capital and robust liquidity. The Firm’s capital risk
management strategy focuses on maintaining long-
term stability to enable the Firm to build and invest in
market-leading businesses, including in highly
stressed environments. Senior management considers
the implications on the Firm’s capital prior to making
significant decisions that could impact future business
activities. In addition to considering the Firm’s
earnings outlook, senior management evaluates all
sources and uses of capital with a view to ensuring the
Firm’s capital strength.
Capital risk management
The Firm has a Capital Risk Management function
whose primary objective is to provide independent
oversight of capital risk across the Firm.
Capital Risk Management’s responsibilities include:
•
Defining, monitoring and reporting capital risk
metrics;
•
Establishing, calibrating and monitoring capital risk
limits and indicators, including capital risk appetite;
•
Developing processes to classify, monitor and report
capital limit breaches;
•
Performing assessments of the Firm’s capital
management activities, including changes made to
the Contingency Capital Plan described below; and
•
Conducting independent review of the Firm's
interpretation of and compliance with the applicable
regulatory capital rules and guidance relating to the
calculation of regulatory capital.
Capital management
Treasury and CIO is responsible for capital
management.
The primary objectives of the Firm’s capital
management are to:
•
Maintain sufficient capital in order to continue to
build and invest in the Firm’s businesses through
normal economic cycles and in stressed
environments;
•
Retain flexibility to take advantage of future
investment opportunities;
•
Promote the Parent Company’s ability to serve as a
source of strength to its subsidiaries;
•
Ensure the Firm operates above the minimum
regulatory capital ratios as well as maintain “well-
capitalized” status for the Firm and its principal
insured depository institution (“IDI”) subsidiary,
JPMorgan Chase Bank, N.A., at all times under
applicable regulatory capital requirements;
•
Meet capital distribution objectives; and
•
Maintain sufficient capital resources to operate
throughout a resolution period in accordance with
the Firm’s preferred resolution strategy.
The Firm addresses these objectives through:
•
Establishing internal minimum capital requirements
and maintaining a strong capital governance
framework. The internal minimum capital levels
consider the Firm’s regulatory capital requirements
as well as an internal assessment of capital
adequacy, in normal economic cycles and in stress
events;
•
Retaining flexibility in order to react to a range of
potential events; and
•
Regularly monitoring the Firm’s capital position and
following prescribed escalation protocols, both at
the Firm and material legal entity levels.
Governance
Committees responsible for overseeing the Firm’s
capital management include the Capital Governance
Committee, the Firmwide ALCO as well as regional
ALCOs, and the CIO, Treasury and Corporate (“CTC”)
Risk Committee. In addition, the Board Risk Committee
periodically reviews the Firm’s capital risk tolerance.
Refer to Firmwide Risk Management on pages 83–87
for additional discussion of the Firmwide ALCO and
other risk-related committees.
Capital planning and stress testing
Comprehensive Capital Analysis and Review
The Federal Reserve requires the Firm, as a large Bank
Holding Company (“BHC”), to submit at least annually
a capital plan that has been reviewed and approved by
the Board of Directors. The Federal Reserve uses
Comprehensive Capital Analysis and Review (“CCAR”)
and other stress testing processes to assess whether
large BHCs, such as the Firm, have sufficient capital
during periods of economic and financial stress, and
have robust, forward-looking capital assessment and
planning processes in place that address each BHC’s
unique risks to enable it to absorb losses under certain
stress scenarios. Through CCAR, the Federal Reserve
evaluates each BHC’s capital adequacy and internal
capital adequacy assessment processes (“ICAAP”), as
well as its plans to make capital distributions, such as
dividend payments or stock repurchases. The Federal
JPMorgan Chase & Co./2025 Form 10-K
89
Reserve uses results under the severely adverse
scenario from its supervisory stress test to determine
each firm’s Stress Capital Buffer (“SCB”) requirement
for the coming year.
The Firm's current SCB requirement is 2.5% and will
remain in effect through September 30, 2027, based
on the current rules. The Firm’s Standardized CET1
capital ratio requirement, including regulatory buffers,
was 11.5% as of December 31, 2025. Refer to Key
Regulatory Developments on page 91 for information
related to proposed changes to the SCB requirement
and stress testing framework.
Refer to Capital actions on page 97 for information on
actions taken by the Firm’s Board of Directors.
Internal Capital Adequacy Assessment Process
Annually, the Firm prepares the ICAAP, which informs
the Board of Directors of the ongoing assessment of
the Firm’s processes for managing the sources and
uses of capital as well as compliance with supervisory
expectations for capital planning and capital
adequacy. The Firm’s ICAAP integrates stress testing
protocols with capital planning. The Firm’s Audit
Committee is responsible for reviewing and approving
the capital planning framework.
Stress testing assesses the potential impact of
alternative economic and business scenarios on the
Firm’s earnings and capital. Economic scenarios, and
the parameters underlying those scenarios, are
defined centrally and applied uniformly across the
businesses. These scenarios are articulated in terms of
macroeconomic factors, which are key drivers of
business results; global market shocks, which
generate short-term but severe trading losses; and
idiosyncratic operational risk events. The scenarios
are intended to capture and stress key vulnerabilities
and idiosyncratic risks facing the Firm. In addition to
CCAR and other periodic stress testing, management
also considers tailored stress scenarios and sensitivity
analyses, as necessary.
Contingency Capital Plan
The Firm’s Contingency Capital Plan establishes the
capital management framework for the Firm and
specifies the principles underlying the Firm’s approach
towards capital management in normal economic
conditions and in stressed environments. The
Contingency Capital Plan defines how the Firm
calibrates its targeted capital levels and meets
minimum capital requirements, monitors the ongoing
appropriateness of planned capital distributions, and
sets out the capital contingency actions that are
expected to be taken or considered at various levels of
capital depletion during a period of stress.
Regulatory capital
The Federal Reserve establishes capital requirements,
including well-capitalized standards, for the Firm as a
consolidated financial holding company. The Office of
the Comptroller of the Currency ("OCC") establishes
similar minimum capital requirements and standards
for the Firm’s principal IDI subsidiary, JPMorgan Chase
Bank, N.A. The U.S. capital requirements generally
follow the Capital Accord of the Basel Committee, as
amended from time to time.
Basel III Overview
The capital rules under Basel III establish minimum
capital ratios and overall capital adequacy standards
for large and internationally active U.S. BHCs and
banks, including the Firm and JPMorgan Chase Bank,
N.A. The minimum amount of regulatory capital that
must be held by BHCs and banks is determined by
calculating RWA, which are on-balance sheet assets
and off-balance sheet exposures, weighted according
to risk. Under the rules currently in effect, two
comprehensive approaches are prescribed for
calculating Basel III RWA: a standardized approach
(“Standardized”), and an advanced approach
(“Advanced”).
For each of these risk-based capital ratios, the capital
adequacy of the Firm is evaluated against the lower of
the Standardized or Advanced approaches compared
to their respective regulatory capital ratio
requirements.
The current Basel III rules establish capital
requirements for calculating credit risk RWA and
market risk RWA, and in the case of Advanced,
operational risk RWA. Key differences in the
calculation of credit risk RWA between the
Standardized and Advanced approaches are that for
Advanced, credit risk RWA is based on risk-sensitive
approaches which largely rely on the use of internal
credit models and parameters, whereas for
Standardized, credit risk RWA is generally based on
supervisory risk-weightings which vary primarily by
counterparty type and asset class. The models used in
Advanced are subject to periodic review and
calibration, which can impact RWA results. Market risk
RWA is generally calculated consistently between
Standardized and Advanced. In addition to the RWA
calculated under these approaches, the Firm may
supplement such amounts to incorporate
management judgment and feedback from its
regulators.
As of December 31, 2025, the Advanced risk-based
ratios became more binding on the Firm than the
Standardized risk-based ratios, primarily reflecting the
increase in Advanced RWA related to the Apple Card
transaction and a reduction in the Firm’s SCB
requirement which only applies to the Standardized
risk-based ratios.
Management’s discussion and analysis
90
JPMorgan Chase & Co./2025 Form 10-K
Additionally, Basel III requires that Advanced
Approaches banking organizations, including the Firm,
calculate their SLRs. Refer to page 96 for additional
information on SLR.
Key Regulatory Developments
Enhanced SLR Final Rule
In November 2025, the Federal Reserve, the OCC and
the FDIC issued the final rule amending the enhanced
Supplementary Leverage Ratio (“eSLR”) requirements
for Global Systemically Important Banks (“GSIB”) BHCs
and their IDI subsidiaries by revising the current static
leverage buffers at the BHC and IDI levels to 50% of
the BHC’s U.S. Method 1 GSIB Surcharge, which is
referred to as the “eSLR buffer.” For IDI subsidiaries,
the eSLR buffer is capped at 1%. In addition, the rule
made corresponding adjustments to the leverage-
based total loss-absorbing capacity (“TLAC”) and
eligible long-term debt (“eligible LTD”) requirements
by replacing the former TLAC leverage buffer with the
eSLR buffer and replacing the former static leverage-
based eligible LTD requirement with a requirement of
2.5% plus the eSLR buffer. Further, the rule removes
the eSLR threshold for an IDI subsidiary of a U.S. GSIB
to be considered “well capitalized” under the prompt
corrective action framework and instead applies the
eSLR as a capital buffer requirement. The final rule,
with an effective date of April 1, 2026, allows for early
adoption, which the Firm has elected, effective January
1, 2026.
Refer to page 92 for information on the U.S. Method 1
GSIB Surcharge.
Enhanced Transparency and Public Accountability
of the Supervisory Stress Test
In October 2025, the Federal Reserve issued proposals
to enhance the transparency and public accountability
of its annual stress test. The proposals would require
the Federal Reserve to publish for public comment
comprehensive documentation concerning the
supervisory stress test models and annual stress test
scenarios, including the scenarios for the upcoming
2026 stress test. The proposals also introduce an
enhanced disclosure process under which material
changes to stress test models and scenarios would be
subject to public comment prior to implementation.
Based on the Federal Reserve’s analysis, the proposed
changes to the stress test models and scenarios are
not expected to change materially the SCB for firms,
such as JPMorganChase, that are subject to the
supervisory stress test. In February 2026, the Federal
Reserve released the final 2026 supervisory stress test
scenarios, while announcing that SCB requirements for
large banks, including the Firm, will remain at current
levels through September 30, 2027 with new
requirements to be calculated in 2027 based on
revised models that incorporate public feedback.
SCB Volatility Reduction
In April 2025, the Federal Reserve proposed changes
to the calculation of the SCB for large BHCs, including
the Firm. The proposal aims to reduce SCB volatility by
using the average of supervisory stress results from
the previous two annual stress tests to calculate the
SCB. The proposal would also modify the annual
effective date of the SCB from October 1 to January 1
and make targeted changes to reporting requirements
in order to streamline data collection.
U.S. Basel III Finalization
In July 2023, the Federal Reserve, the OCC and the
FDIC released a proposal to amend the risk-based
capital framework, entitled "Regulatory capital rule:
Amendments applicable to large banking
organizations and to banking organizations with
significant trading activity", which is referred to in this
Form 10-K as the "U.S. Basel III proposal." Under this
proposal, changes to the framework would include
replacement of the Advanced approach with an
expanded risk-based approach for the calculation of
RWA. In addition, the stress capital buffer requirement
would be applicable to both the expanded risk-based
approach and the Standardized approach.
GSIB Surcharge and TLAC and Eligible LTD
Requirements
In July 2023, the Federal Reserve released a proposal
to amend the calculation of the GSIB surcharge. Under
the proposal, the annual GSIB surcharge would be
based on an average of the quarterly surcharge
calculations throughout the calendar year, with daily
averaging required for certain measures. The proposal
would also reduce surcharge increments from 50 bps
to 10 bps and includes other technical amendments to
the “Method 2” calculation. The proposed changes
would revise risk-based capital requirements for the
Firm and other U.S. GSIBs. Refer to Risk-based Capital
Regulatory Requirements on page 92 for further
information on the GSIB surcharge.
Additionally, in August 2023, the Federal Reserve, the
FDIC and the OCC released a proposal to expand the
eligible long-term debt ("eligible LTD") and clean
holding company requirements under the existing
total loss-absorbing capacity ("TLAC") rule to apply to
non-GSIB banks with $100 billion or more in total
consolidated assets. The proposal would also reduce
the amount of LTD with remaining maturities of less
than two years that count towards a U.S. GSIB's TLAC
requirement and expand the existing capital deduction
framework for LTD issued by GSIBs to include LTD
issued by non-GSIB banks subject to the LTD
requirements.
Finalization of the above proposals, including the
required implementation dates, is uncertain. The Firm
continues to monitor developments and potential
impacts.
JPMorgan Chase & Co./2025 Form 10-K
91
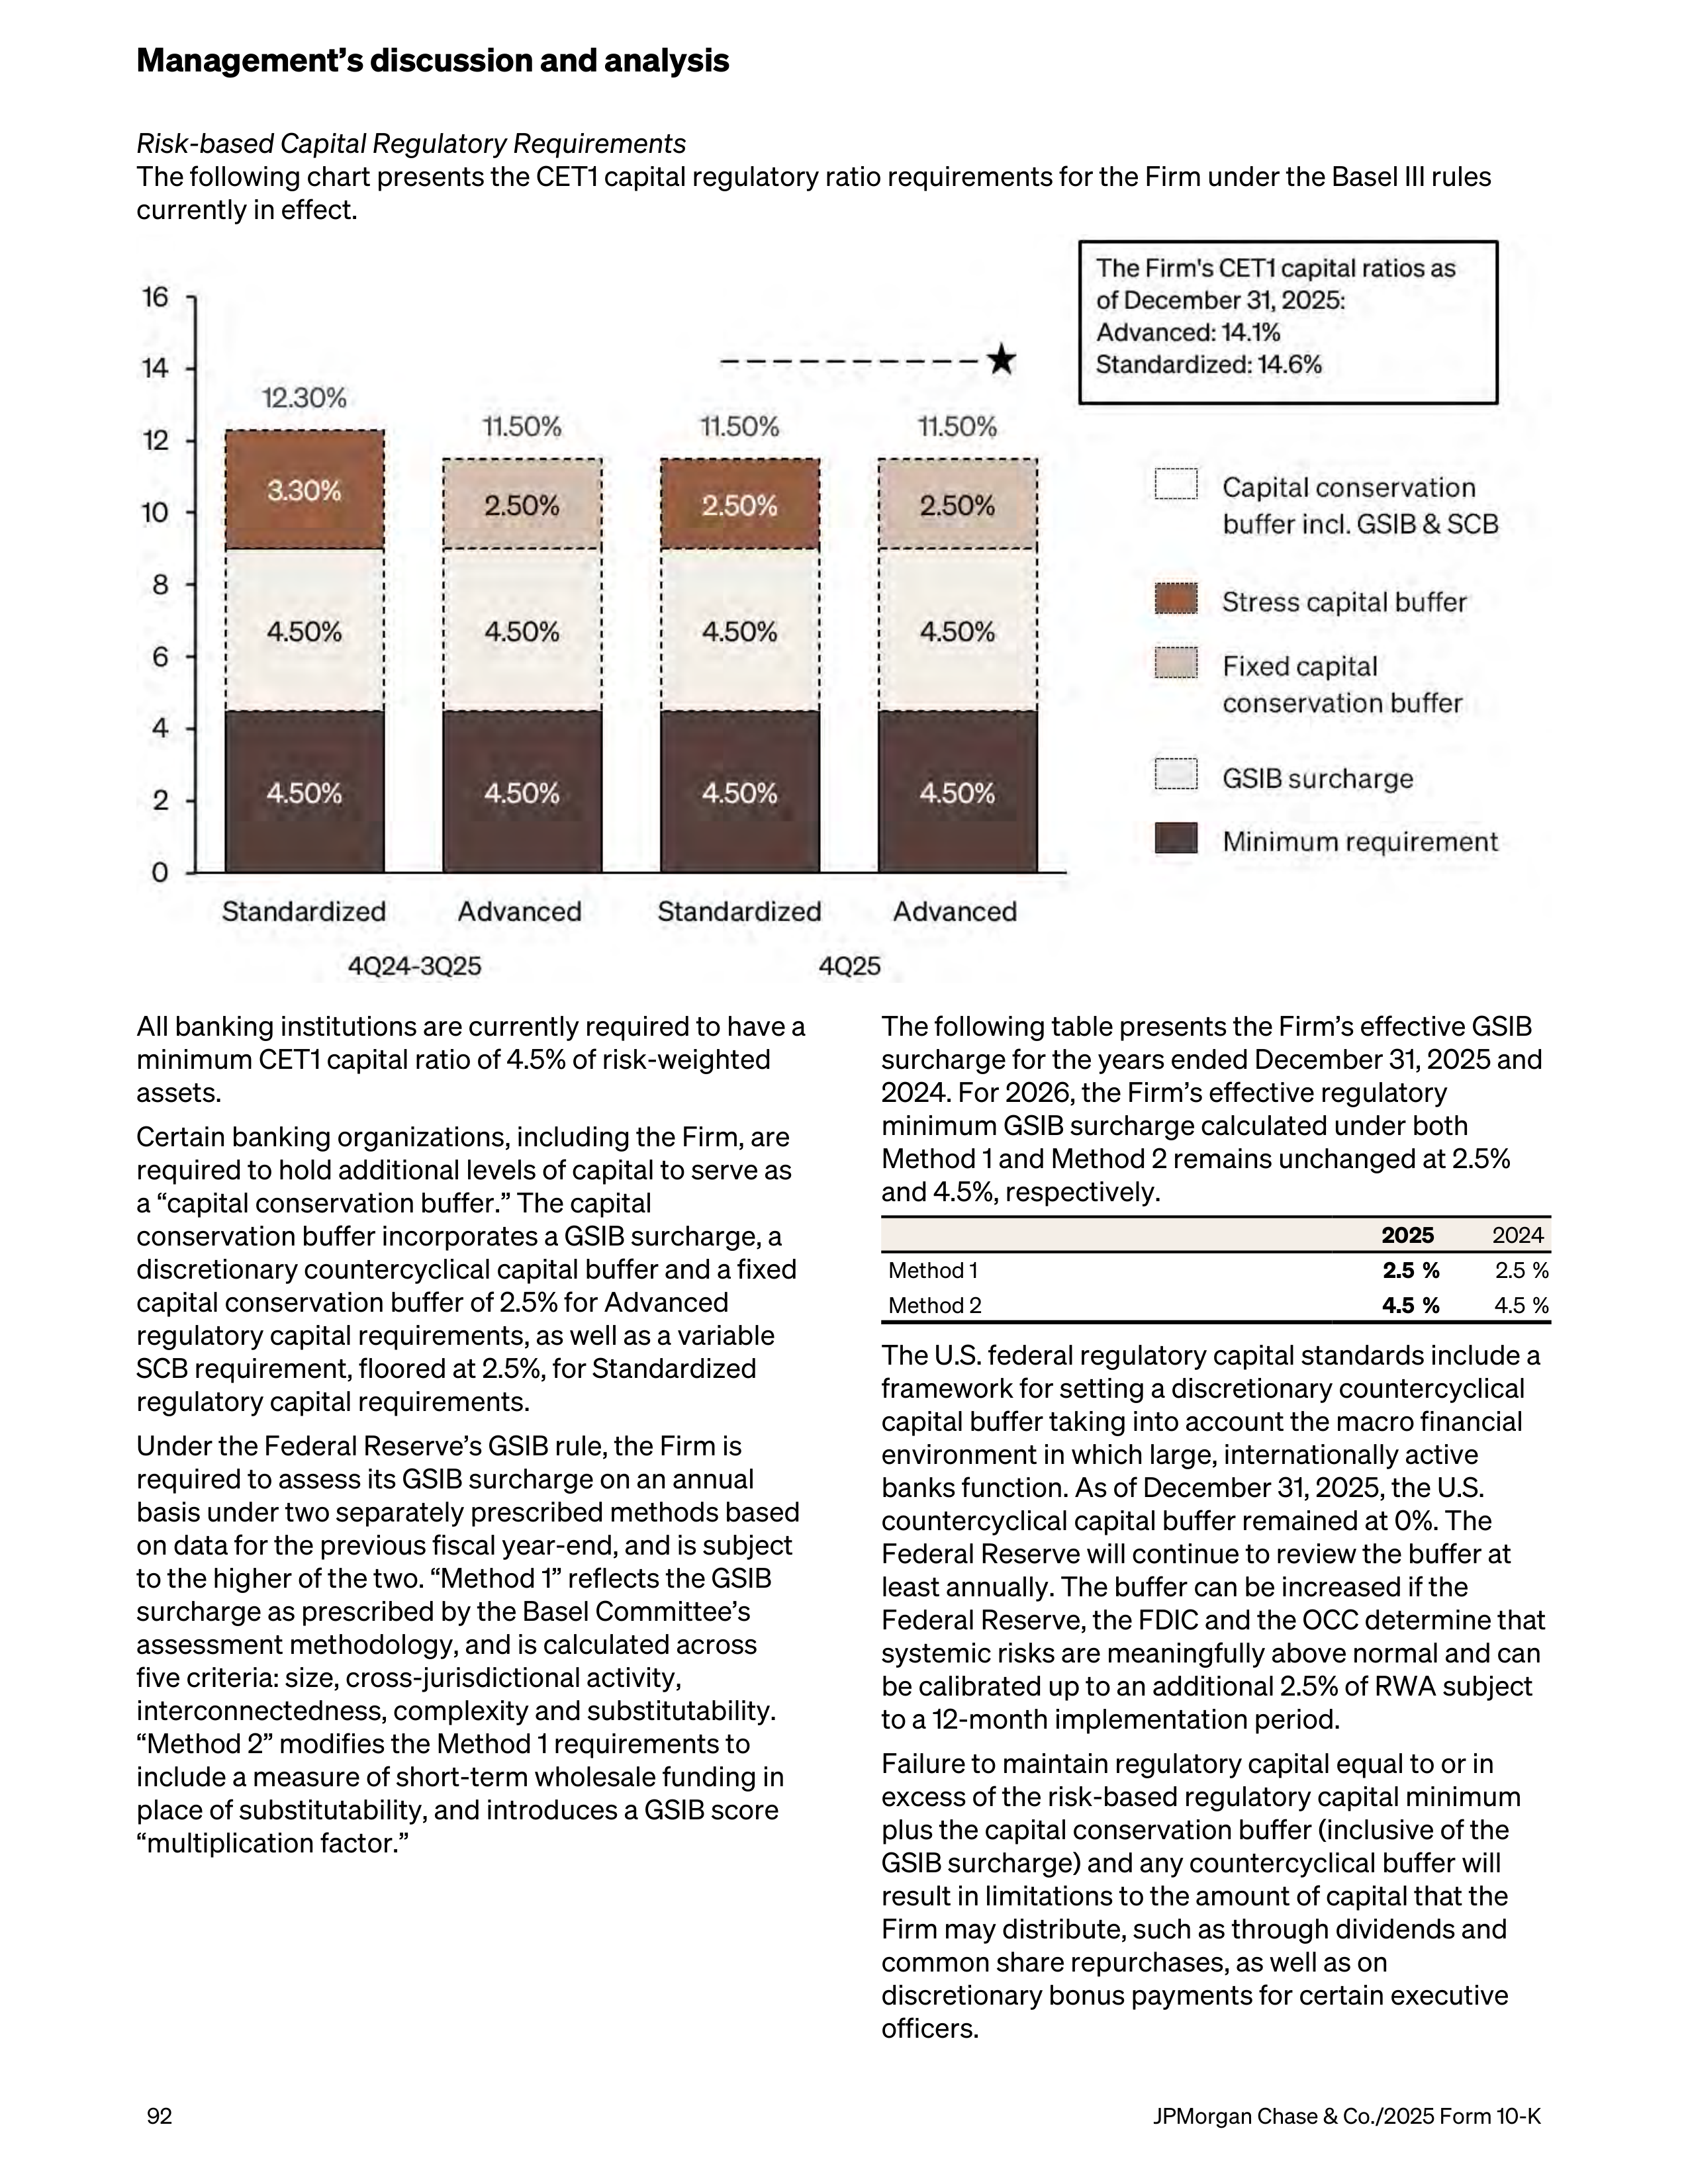
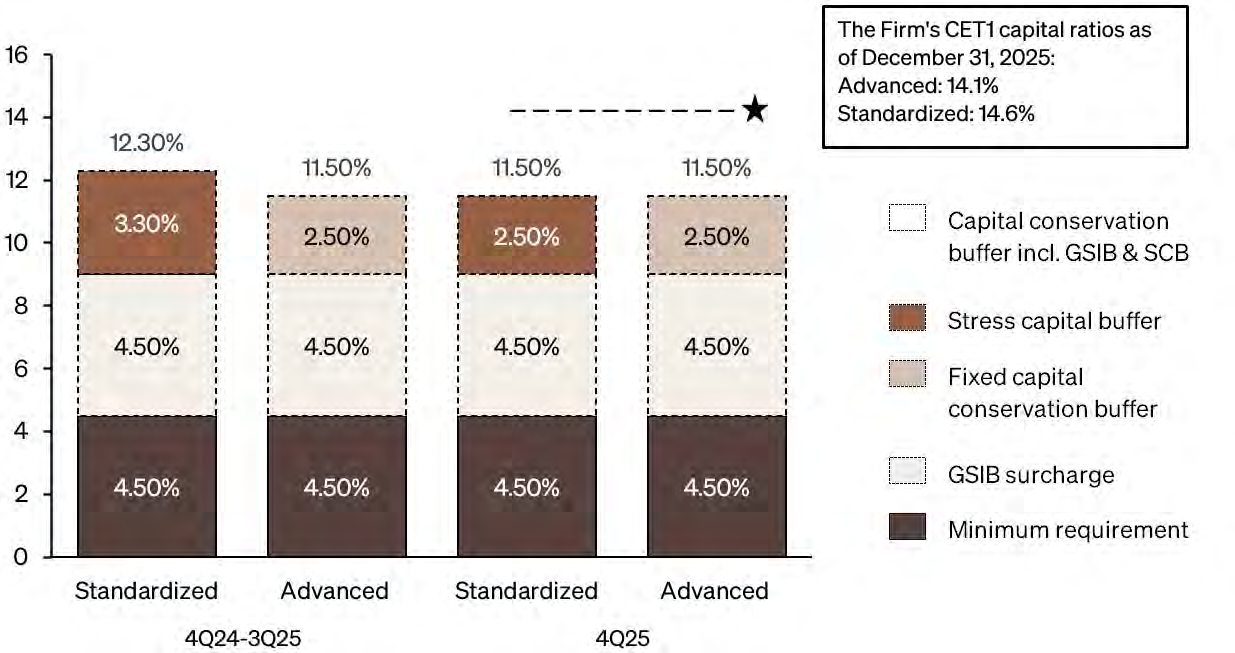
Risk-based Capital Regulatory Requirements
The following chart presents the CET1 capital regulatory ratio requirements for the Firm under the Basel III rules
currently in effect.
All banking institutions are currently required to have a
minimum CET1 capital ratio of 4.5% of risk-weighted
assets.
Certain banking organizations, including the Firm, are
required to hold additional levels of capital to serve as
a “capital conservation buffer.” The capital
conservation buffer incorporates a GSIB surcharge, a
discretionary countercyclical capital buffer and a fixed
capital conservation buffer of 2.5% for Advanced
regulatory capital requirements, as well as a variable
SCB requirement, floored at 2.5%, for Standardized
regulatory capital requirements.
Under the Federal Reserve’s GSIB rule, the Firm is
required to assess its GSIB surcharge on an annual
basis under two separately prescribed methods based
on data for the previous fiscal year-end, and is subject
to the higher of the two. “Method 1” reflects the GSIB
surcharge as prescribed by the Basel Committee’s
assessment methodology, and is calculated across
five criteria: size, cross-jurisdictional activity,
interconnectedness, complexity and substitutability.
“Method 2” modifies the Method 1 requirements to
include a measure of short-term wholesale funding in
place of substitutability, and introduces a GSIB score
“multiplication factor.”
The following table presents the Firm’s effective GSIB
surcharge for the years ended December 31, 2025 and
2024. For 2026, the Firm’s effective regulatory
minimum GSIB surcharge calculated under both
Method 1 and Method 2 remains unchanged at 2.5%
and 4.5%, respectively.
2025
2024
Method 1
2.5 %
2.5 %
Method 2
4.5 %
4.5 %
The U.S. federal regulatory capital standards include a
framework for setting a discretionary countercyclical
capital buffer taking into account the macro financial
environment in which large, internationally active
banks function. As of December 31, 2025, the U.S.
countercyclical capital buffer remained at 0%. The
Federal Reserve will continue to review the buffer at
least annually. The buffer can be increased if the
Federal Reserve, the FDIC and the OCC determine that
systemic risks are meaningfully above normal and can
be calibrated up to an additional 2.5% of RWA subject
to a 12-month implementation period.
Failure to maintain regulatory capital equal to or in
excess of the risk-based regulatory capital minimum
plus the capital conservation buffer (inclusive of the
GSIB surcharge) and any countercyclical buffer will
result in limitations to the amount of capital that the
Firm may distribute, such as through dividends and
common share repurchases, as well as on
discretionary bonus payments for certain executive
officers.
Management’s discussion and analysis
92
JPMorgan Chase & Co./2025 Form 10-K
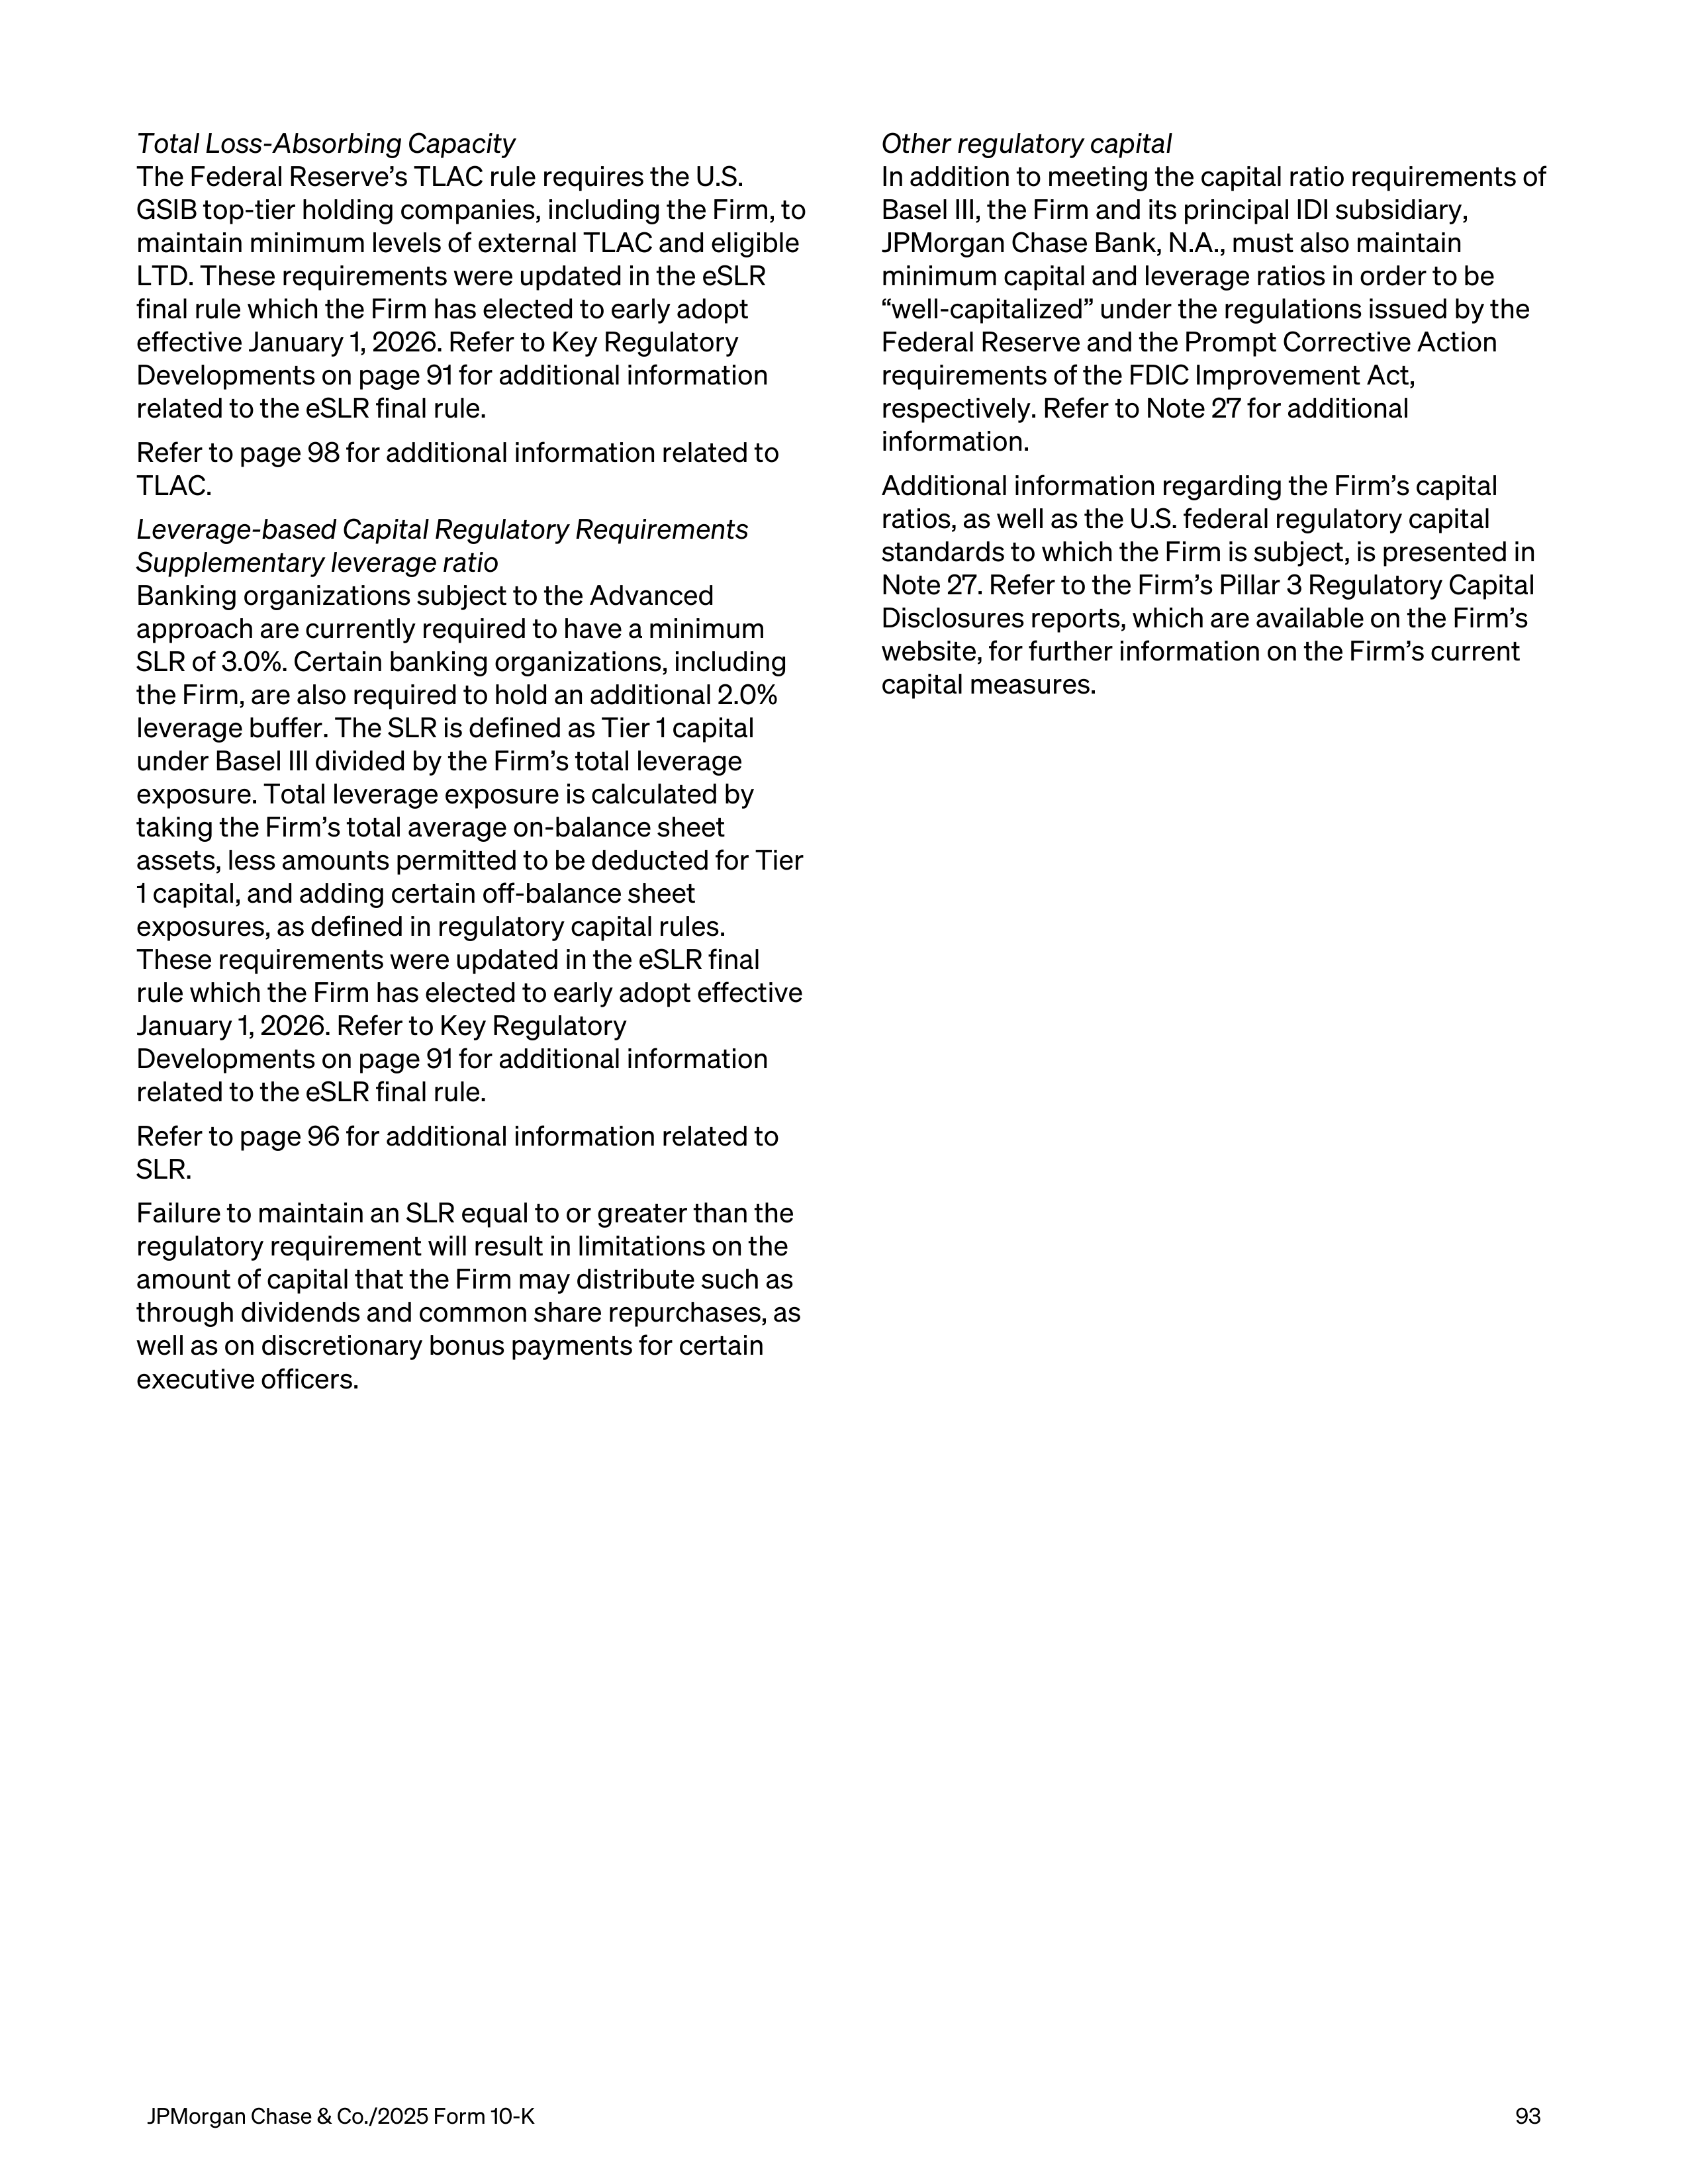
Total Loss-Absorbing Capacity
The Federal Reserve’s TLAC rule requires the U.S.
GSIB top-tier holding companies, including the Firm, to
maintain minimum levels of external TLAC and eligible
LTD. These requirements were updated in the eSLR
final rule which the Firm has elected to early adopt
effective January 1, 2026. Refer to Key Regulatory
Developments on page 91 for additional information
related to the eSLR final rule.
Refer to page 98 for additional information related to
TLAC.
Leverage-based Capital Regulatory Requirements
Supplementary leverage ratio
Banking organizations subject to the Advanced
approach are currently required to have a minimum
SLR of 3.0%. Certain banking organizations, including
the Firm, are also required to hold an additional 2.0%
leverage buffer. The SLR is defined as Tier 1 capital
under Basel III divided by the Firm’s total leverage
exposure. Total leverage exposure is calculated by
taking the Firm’s total average on-balance sheet
assets, less amounts permitted to be deducted for Tier
1 capital, and adding certain off-balance sheet
exposures, as defined in regulatory capital rules.
These requirements were updated in the eSLR final
rule which the Firm has elected to early adopt effective
January 1, 2026. Refer to Key Regulatory
Developments on page 91 for additional information
related to the eSLR final rule.
Refer to page 96 for additional information related to
SLR.
Failure to maintain an SLR equal to or greater than the
regulatory requirement will result in limitations on the
amount of capital that the Firm may distribute such as
through dividends and common share repurchases, as
well as on discretionary bonus payments for certain
executive officers.
Other regulatory capital
In addition to meeting the capital ratio requirements of
Basel III, the Firm and its principal IDI subsidiary,
JPMorgan Chase Bank, N.A., must also maintain
minimum capital and leverage ratios in order to be
“well-capitalized” under the regulations issued by the
Federal Reserve and the Prompt Corrective Action
requirements of the FDIC Improvement Act,
respectively. Refer to Note 27 for additional
information.
Additional information regarding the Firm’s capital
ratios, as well as the U.S. federal regulatory capital
standards to which the Firm is subject, is presented in
Note 27. Refer to the Firm’s Pillar 3 Regulatory Capital
Disclosures reports, which are available on the Firm’s
website, for further information on the Firm’s current
capital measures.
JPMorgan Chase & Co./2025 Form 10-K
93
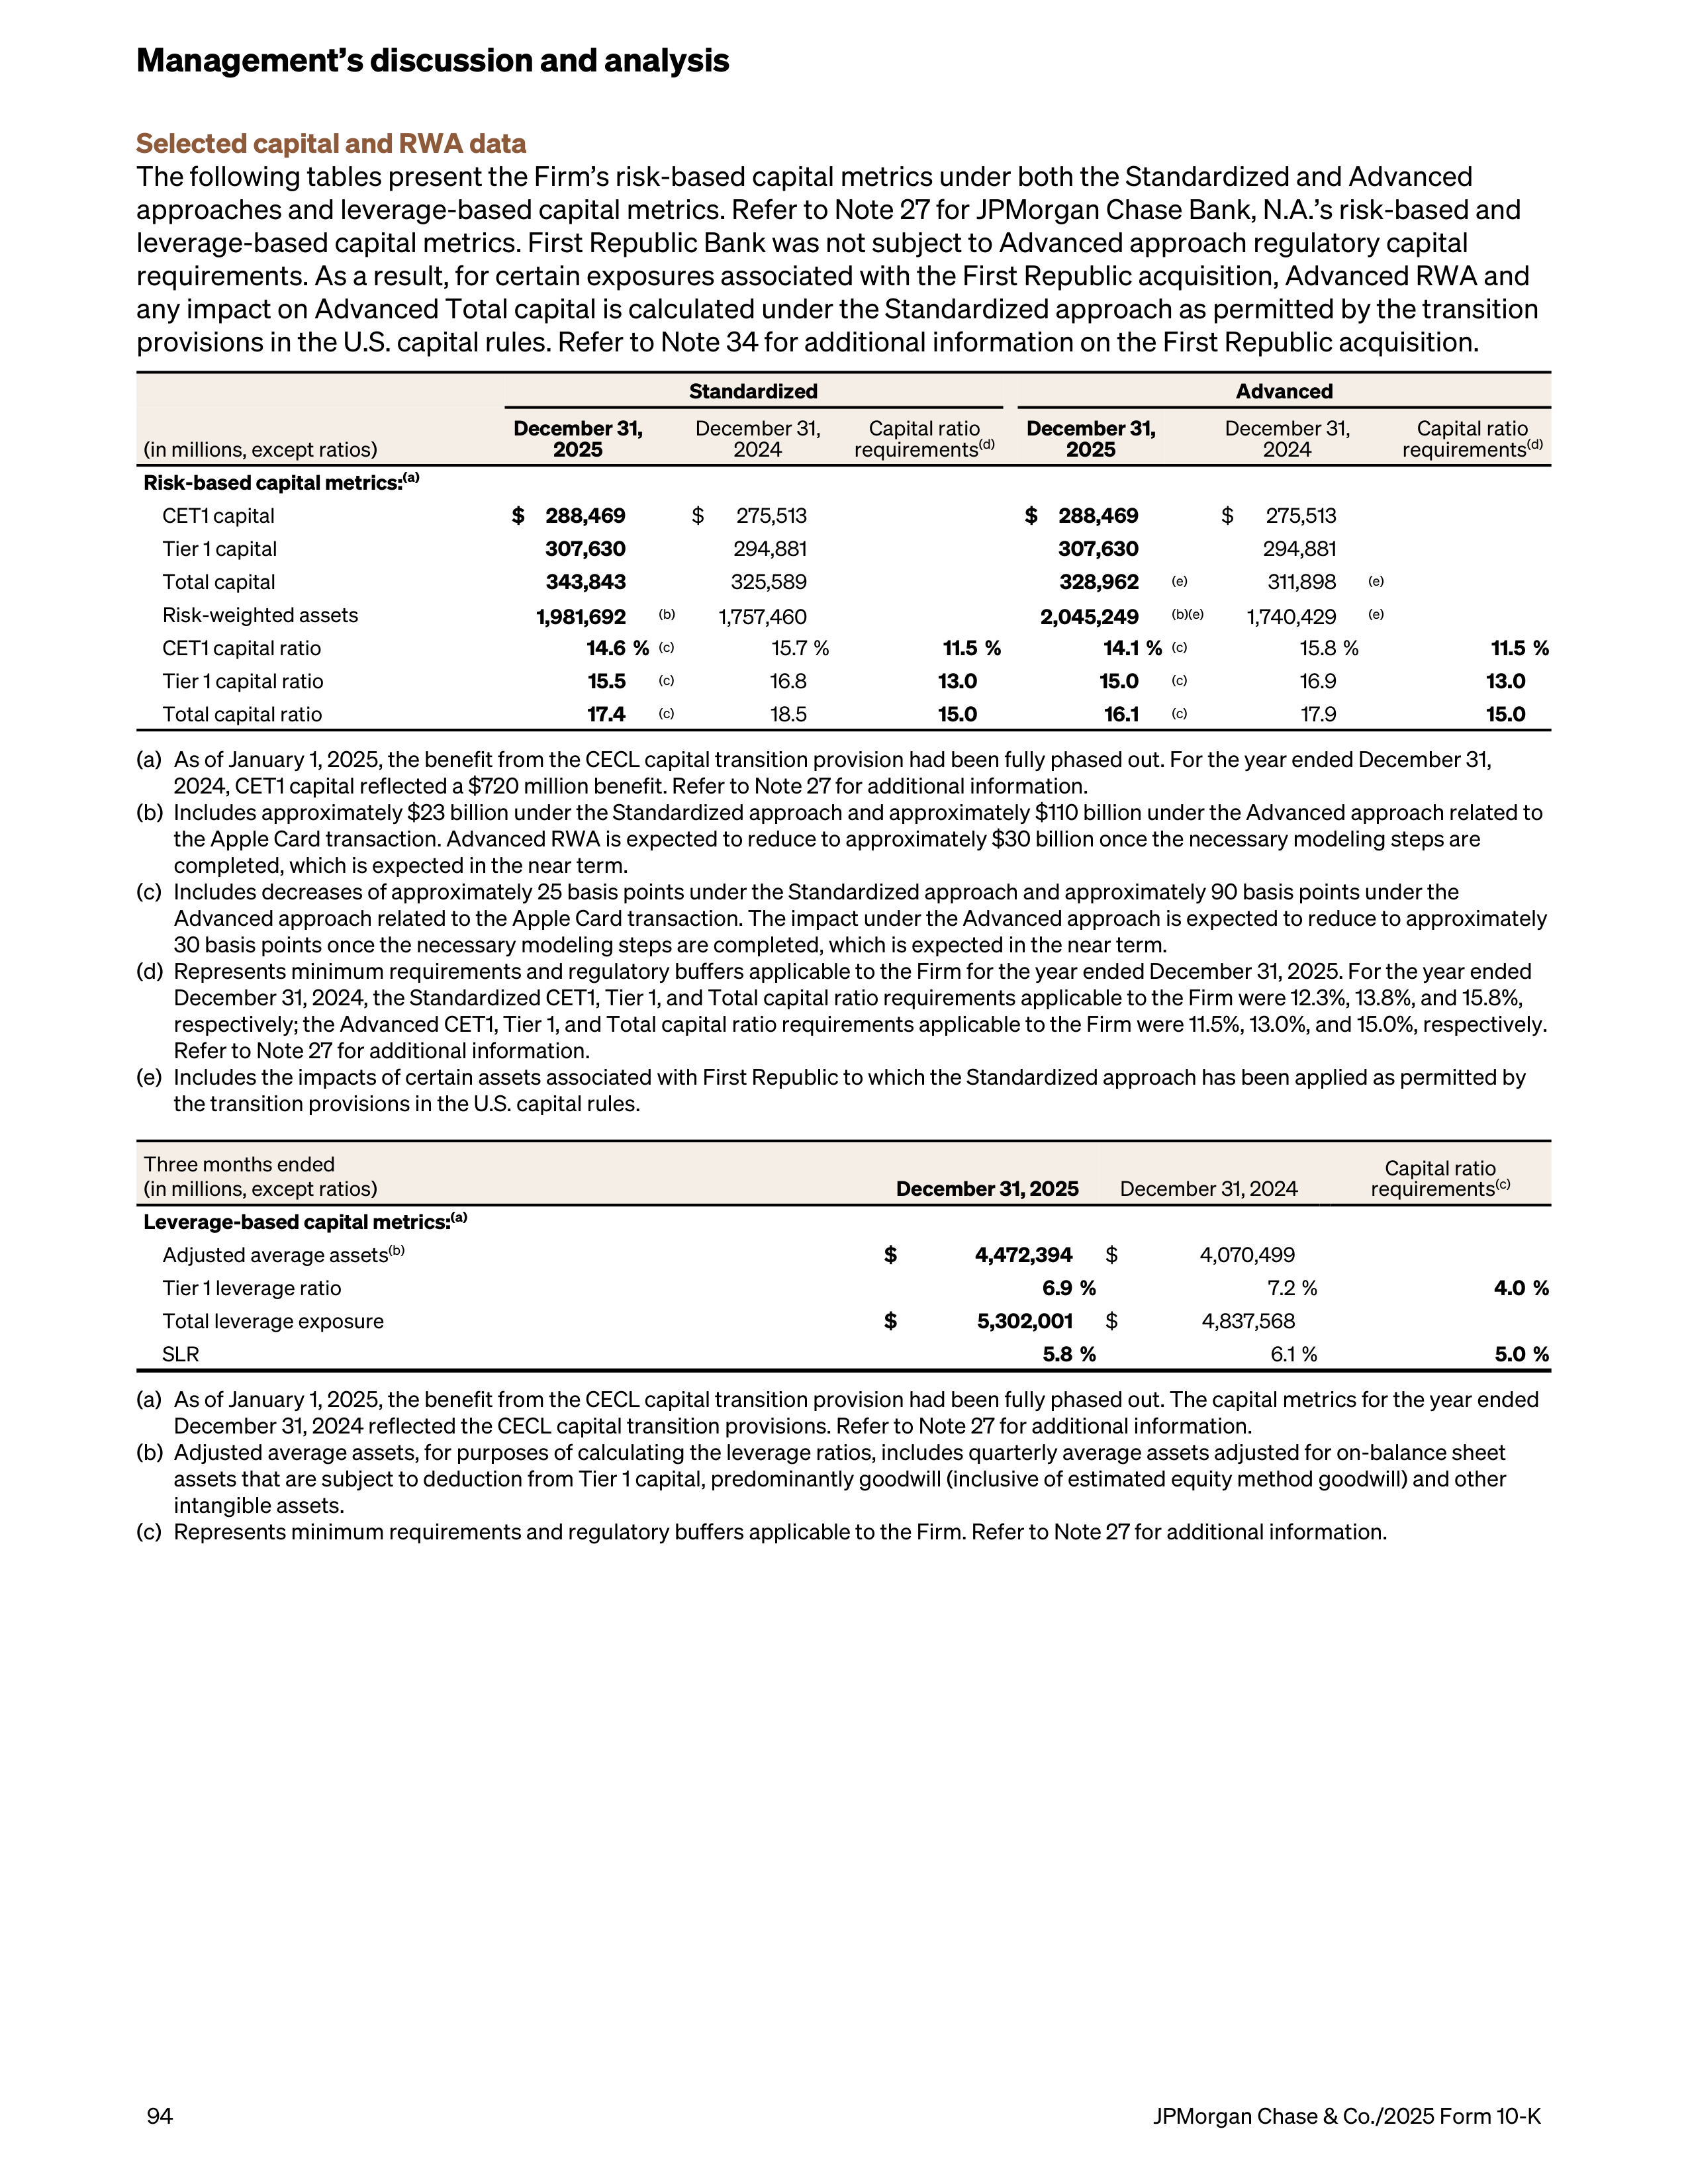
Selected capital and RWA data
The following tables present the Firm’s risk-based capital metrics under both the Standardized and Advanced
approaches and leverage-based capital metrics. Refer to Note 27 for JPMorgan Chase Bank, N.A.’s risk-based and
leverage-based capital metrics. First Republic Bank was not subject to Advanced approach regulatory capital
requirements. As a result, for certain exposures associated with the First Republic acquisition, Advanced RWA and
any impact on Advanced Total capital is calculated under the Standardized approach as permitted by the transition
provisions in the U.S. capital rules. Refer to Note 34 for additional information on the First Republic acquisition.
Standardized
Advanced
(in millions, except ratios)
December 31,
2025
December 31,
2024
Capital ratio
requirements
(d)
December 31,
2025
December 31,
2024
Capital ratio
requirements
(d)
Risk-based capital metrics:
(a)
CET1 capital
$
288,469
$
275,513
$
288,469
$
275,513
Tier 1 capital
307,630
294,881
307,630
294,881
Total capital
343,843
325,589
328,962
(e)
311,898
(e)
Risk-weighted assets
1,981,692
(b)
1,757,460
2,045,249
(b)(e)
1,740,429
(e)
CET1 capital ratio
14.6 %
(c)
15.7 %
11.5 %
14.1 %
(c)
15.8 %
11.5 %
Tier 1 capital ratio
15.5
(c)
16.8
13.0
15.0
(c)
16.9
13.0
Total capital ratio
17.4
(c)
18.5
15.0
16.1
(c)
17.9
15.0
(a)
As of January 1, 2025, the benefit from the CECL capital transition provision had been fully phased out. For the year ended December 31,
2024, CET1 capital reflected a $720 million benefit. Refer to Note 27 for additional information.
(b)
Includes approximately $23 billion under the Standardized approach and approximately $110 billion under the Advanced approach related to
the Apple Card transaction. Advanced RWA is expected to reduce to approximately $30 billion once the necessary modeling steps are
completed, which is expected in the near term.
(c)
Includes decreases of approximately 25 basis points under the Standardized approach and approximately 90 basis points under the
Advanced approach related to the Apple Card transaction. The impact under the Advanced approach is expected to reduce to approximately
30 basis points once the necessary modeling steps are completed, which is expected in the near term.
(d)
Represents minimum requirements and regulatory buffers applicable to the Firm for the year ended December 31, 2025. For the year ended
December 31, 2024, the Standardized CET1, Tier 1, and Total capital ratio requirements applicable to the Firm were 12.3%, 13.8%, and 15.8%,
respectively; the Advanced CET1, Tier 1, and Total capital ratio requirements applicable to the Firm were 11.5%, 13.0%, and 15.0%, respectively.
Refer to Note 27 for additional information.
(e)
Includes the impacts of certain assets associated with First Republic to which the Standardized approach has been applied as permitted by
the transition provisions in the U.S. capital rules.
Three months ended
(in millions, except ratios)
December 31, 2025
December 31, 2024
Capital ratio
requirements
(c)
Leverage-based capital metrics:
(a)
Adjusted average assets
(b)
$
4,472,394
$
4,070,499
Tier 1 leverage ratio
6.9 %
7.2 %
4.0 %
Total leverage exposure
$
5,302,001
$
4,837,568
SLR
5.8 %
6.1 %
5.0 %
(a)
As of January 1, 2025, the benefit from the CECL capital transition provision had been fully phased out. The capital metrics for the year ended
December 31, 2024 reflected the CECL capital transition provisions. Refer to Note 27 for additional information.
(b)
Adjusted average assets, for purposes of calculating the leverage ratios, includes quarterly average assets adjusted for on-balance sheet
assets that are subject to deduction from Tier 1 capital, predominantly goodwill (inclusive of estimated equity method goodwill) and other
intangible assets.
(c)
Represents minimum requirements and regulatory buffers applicable to the Firm. Refer to Note 27 for additional information.
Management’s discussion and analysis
94
JPMorgan Chase & Co./2025 Form 10-K
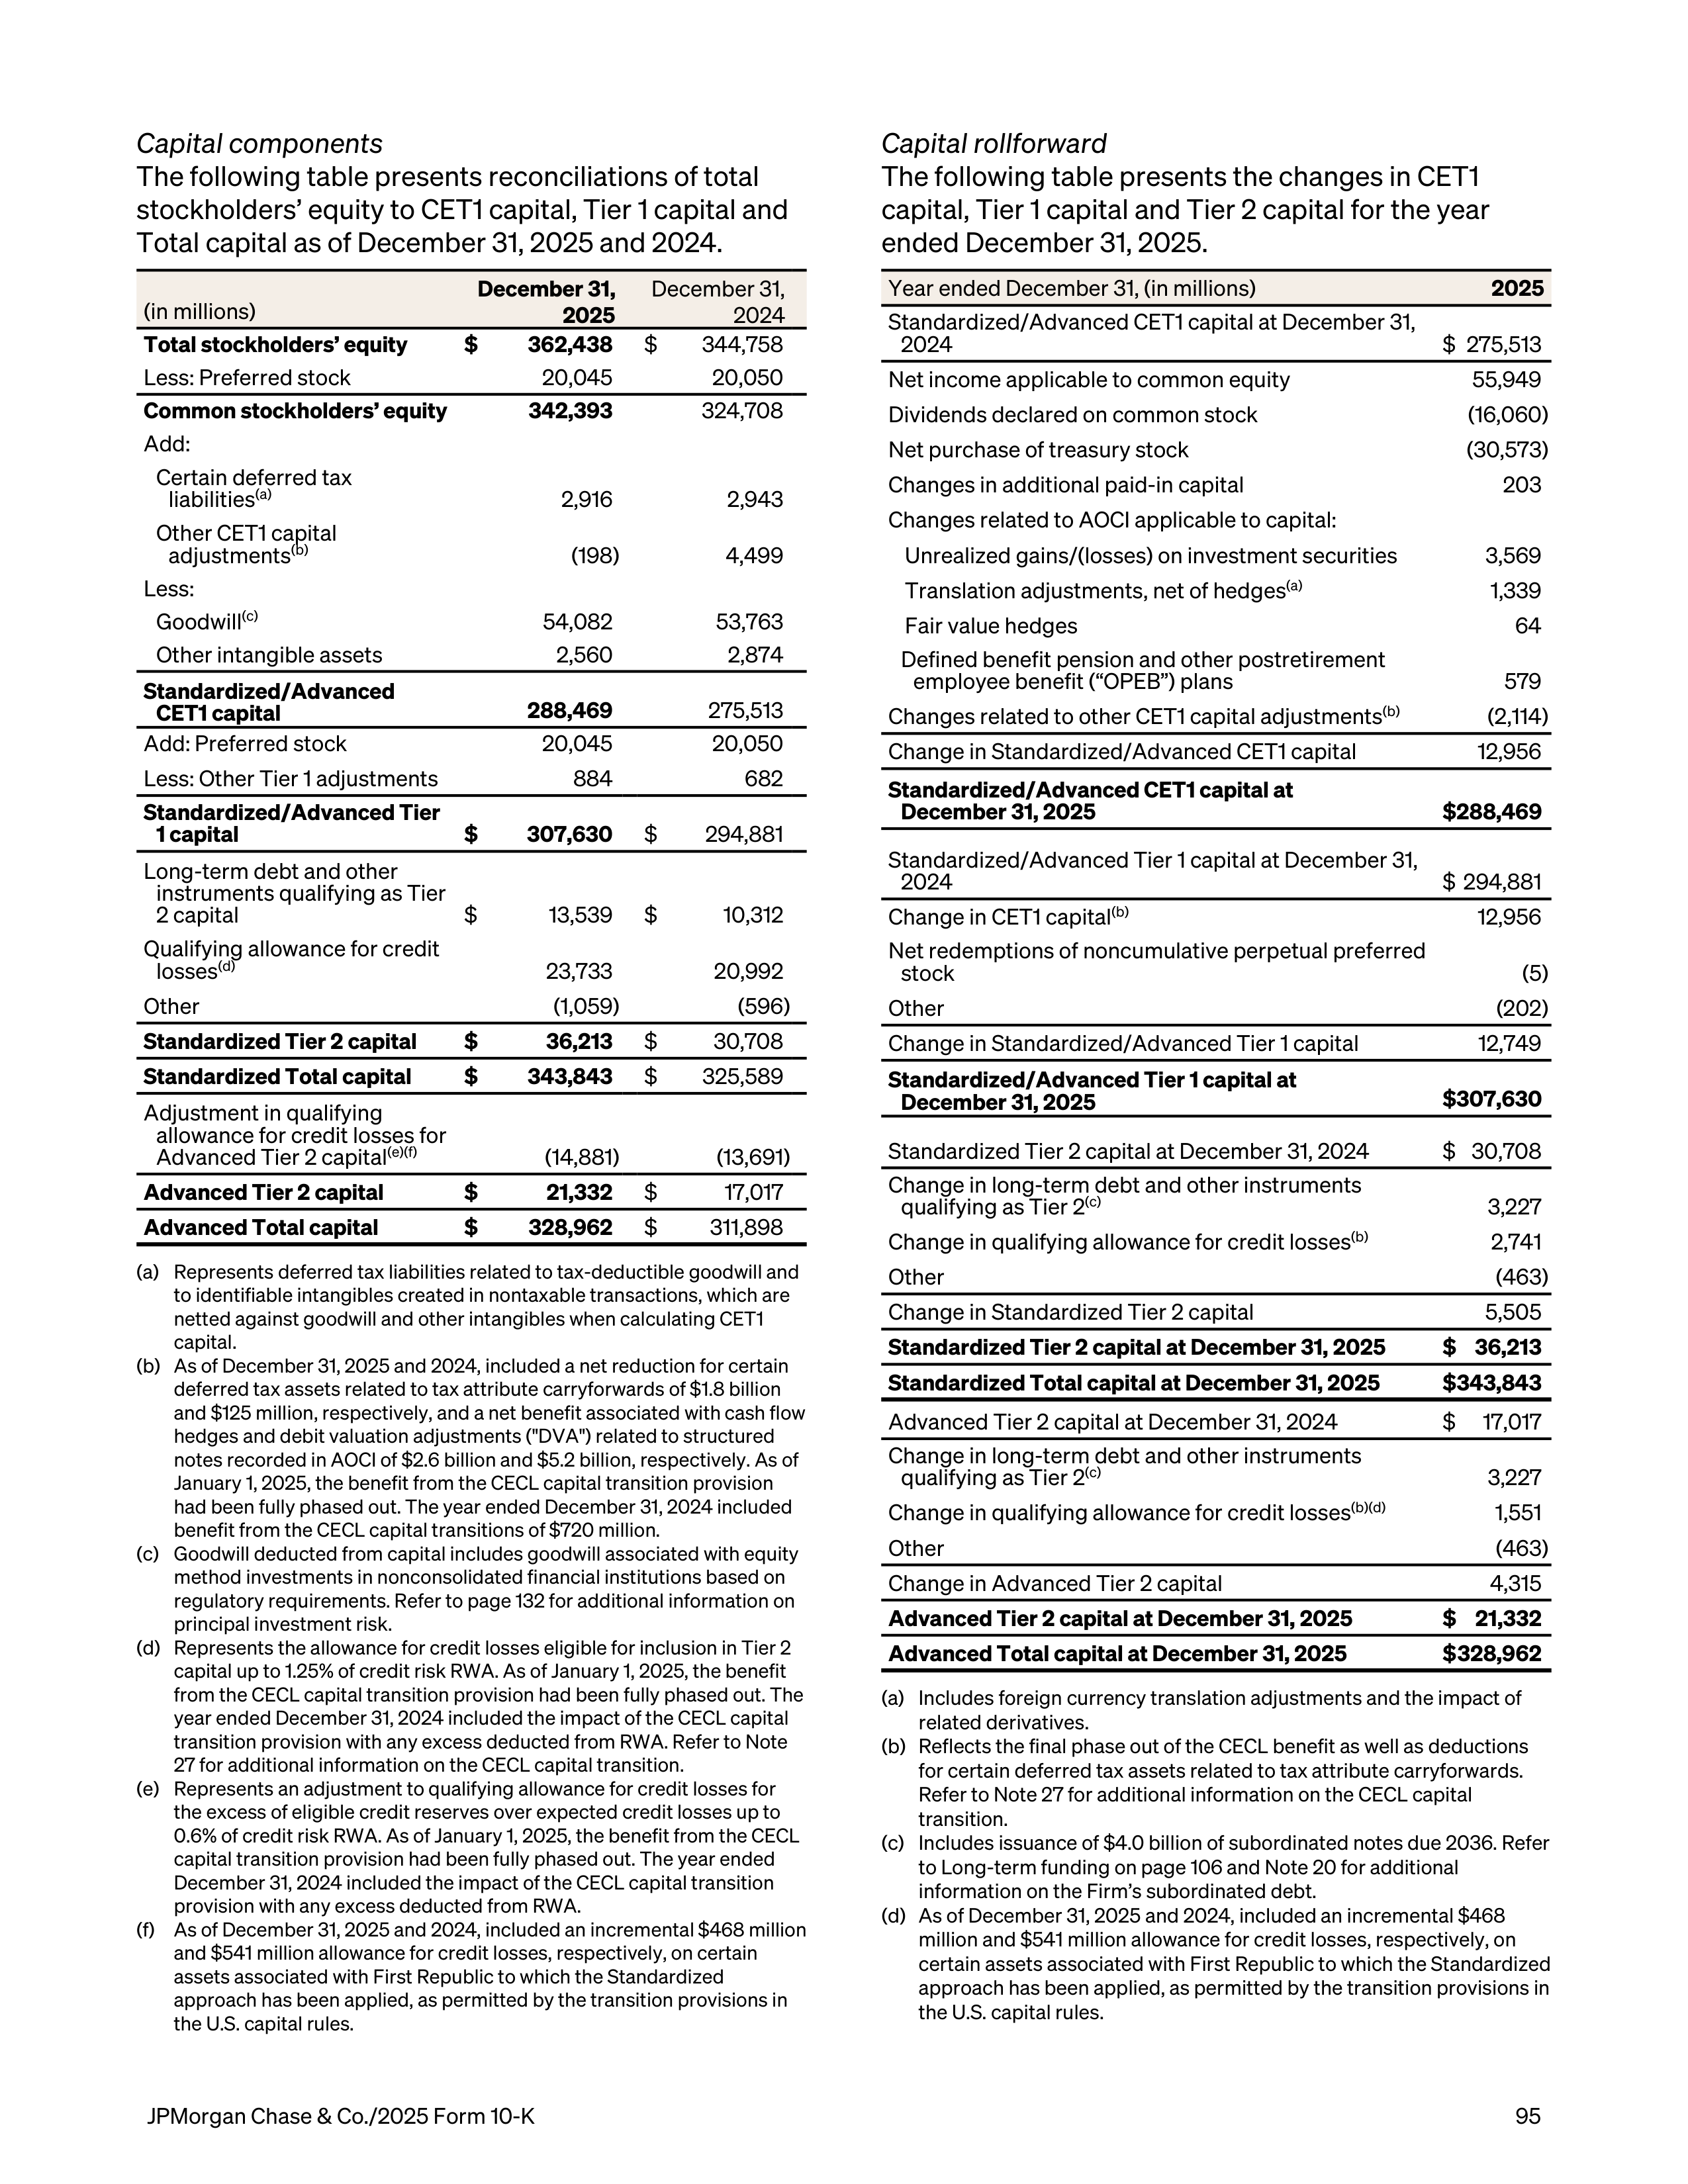
Capital components
The following table presents reconciliations of total
stockholders’ equity to CET1 capital, Tier 1 capital and
Total capital as of December 31, 2025 and 2024.
(in millions)
December 31,
2025
December 31,
2024
Total stockholders’ equity
$
362,438
$
344,758
Less: Preferred stock
20,045
20,050
Common stockholders’ equity
342,393
324,708
Add:
Certain deferred tax
liabilities
(a)
2,916
2,943
Other CET1 capital
adjustments
(b)
(198)
4,499
Less:
Goodwill
(c)
54,082
53,763
Other intangible assets
2,560
2,874
Standardized/Advanced
CET1 capital
288,469
275,513
Add: Preferred stock
20,045
20,050
Less: Other Tier 1 adjustments
884
682
Standardized/Advanced Tier
1 capital
$
307,630
$
294,881
Long-term debt and other
instruments qualifying as Tier
2 capital
$
13,539
$
10,312
Qualifying allowance for credit
losses
(d)
23,733
20,992
Other
(1,059)
(596)
Standardized Tier 2 capital
$
36,213
$
30,708
Standardized Total capital
$
343,843
$
325,589
Adjustment in qualifying
allowance for credit losses for
Advanced Tier 2 capital
(e)(f)
(14,881)
(13,691)
Advanced Tier 2 capital
$
21,332
$
17,017
Advanced Total capital
$
328,962
$
311,898
(a)
Represents deferred tax liabilities related to tax-deductible goodwill and
to identifiable intangibles created in nontaxable transactions, which are
netted against goodwill and other intangibles when calculating CET1
capital.
(b)
As of December 31, 2025 and 2024, included a net reduction for certain
deferred tax assets related to tax attribute carryforwards of $1.8 billion
and $125 million, respectively, and a net benefit associated with cash flow
hedges and debit valuation adjustments ("DVA") related to structured
notes recorded in AOCI of $2.6 billion and $5.2 billion, respectively. As of
January 1, 2025, the benefit from the CECL capital transition provision
had been fully phased out. The year ended December 31, 2024 included
benefit from the CECL capital transitions of $720 million.
(c)
Goodwill deducted from capital includes goodwill associated with equity
method investments in nonconsolidated financial institutions based on
regulatory requirements. Refer to page 132 for additional information on
principal investment risk.
(d)
Represents the allowance for credit losses eligible for inclusion in Tier 2
capital up to 1.25% of credit risk RWA. As of January 1, 2025, the benefit
from the CECL capital transition provision had been fully phased out. The
year ended December 31, 2024 included the impact of the CECL capital
transition provision with any excess deducted from RWA. Refer to Note
27 for additional information on the CECL capital transition.
(e)
Represents an adjustment to qualifying allowance for credit losses for
the excess of eligible credit reserves over expected credit losses up to
0.6% of credit risk RWA. As of January 1, 2025, the benefit from the CECL
capital transition provision had been fully phased out. The year ended
December 31, 2024 included the impact of the CECL capital transition
provision with any excess deducted from RWA.
(f)
As of December 31, 2025 and 2024, included an incremental $468 million
and $541 million allowance for credit losses, respectively, on certain
assets associated with First Republic to which the Standardized
approach has been applied, as permitted by the transition provisions in
the U.S. capital rules.
Capital rollforward
The following table presents the changes in CET1
capital, Tier 1 capital and Tier 2 capital for the year
ended December 31, 2025.
Year ended December 31, (in millions)
2025
Standardized/Advanced CET1 capital at December 31,
2024
$ 275,513
Net income applicable to common equity
55,949
Dividends declared on common stock
(16,060)
Net purchase of treasury stock
(30,573)
Changes in additional paid-in capital
203
Changes related to AOCI applicable to capital:
Unrealized gains/(losses) on investment securities
3,569
Translation adjustments, net of hedges
(a)
1,339
Fair value hedges
64
Defined benefit pension and other postretirement
employee benefit (“OPEB”) plans
579
Changes related to other CET1 capital adjustments
(b)
(2,114)
Change in Standardized/Advanced CET1 capital
12,956
Standardized/Advanced CET1 capital at
December 31, 2025
$ 288,469
Standardized/Advanced Tier 1 capital at December 31,
2024
$ 294,881
Change in CET1 capital
(b)
12,956
Net redemptions of noncumulative perpetual preferred
stock
(5)
Other
(202)
Change in Standardized/Advanced Tier 1 capital
12,749
Standardized/Advanced Tier 1 capital at
December 31, 2025
$ 307,630
Standardized Tier 2 capital at December 31, 2024
$ 30,708
Change in long-term debt and other instruments
qualifying as Tier 2
(c)
3,227
Change in qualifying allowance for credit losses
(b)
2,741
Other
(463)
Change in Standardized Tier 2 capital
5,505
Standardized Tier 2 capital at December 31, 2025
$ 36,213
Standardized Total capital at December 31, 2025
$ 343,843
Advanced Tier 2 capital at December 31, 2024
$
17,017
Change in long-term debt and other instruments
qualifying as Tier 2
(c)
3,227
Change in qualifying allowance for credit losses
(b)(d)
1,551
Other
(463)
Change in Advanced Tier 2 capital
4,315
Advanced Tier 2 capital at December 31, 2025
$ 21,332
Advanced Total capital at December 31, 2025
$ 328,962
(a)
Includes foreign currency translation adjustments and the impact of
related derivatives.
(b)
Reflects the final phase out of the CECL benefit as well as deductions
for certain deferred tax assets related to tax attribute carryforwards.
Refer to Note 27 for additional information on the CECL capital
transition.
(c)
Includes issuance of $4.0 billion of subordinated notes due 2036. Refer
to Long-term funding on page 106 and Note 20 for additional
information on the Firm’s subordinated debt.
(d)
As of December 31, 2025 and 2024, included an incremental $468
million and $541 million allowance for credit losses, respectively, on
certain assets associated with First Republic to which the Standardized
approach has been applied, as permitted by the transition provisions in
the U.S. capital rules.
JPMorgan Chase & Co./2025 Form 10-K
95
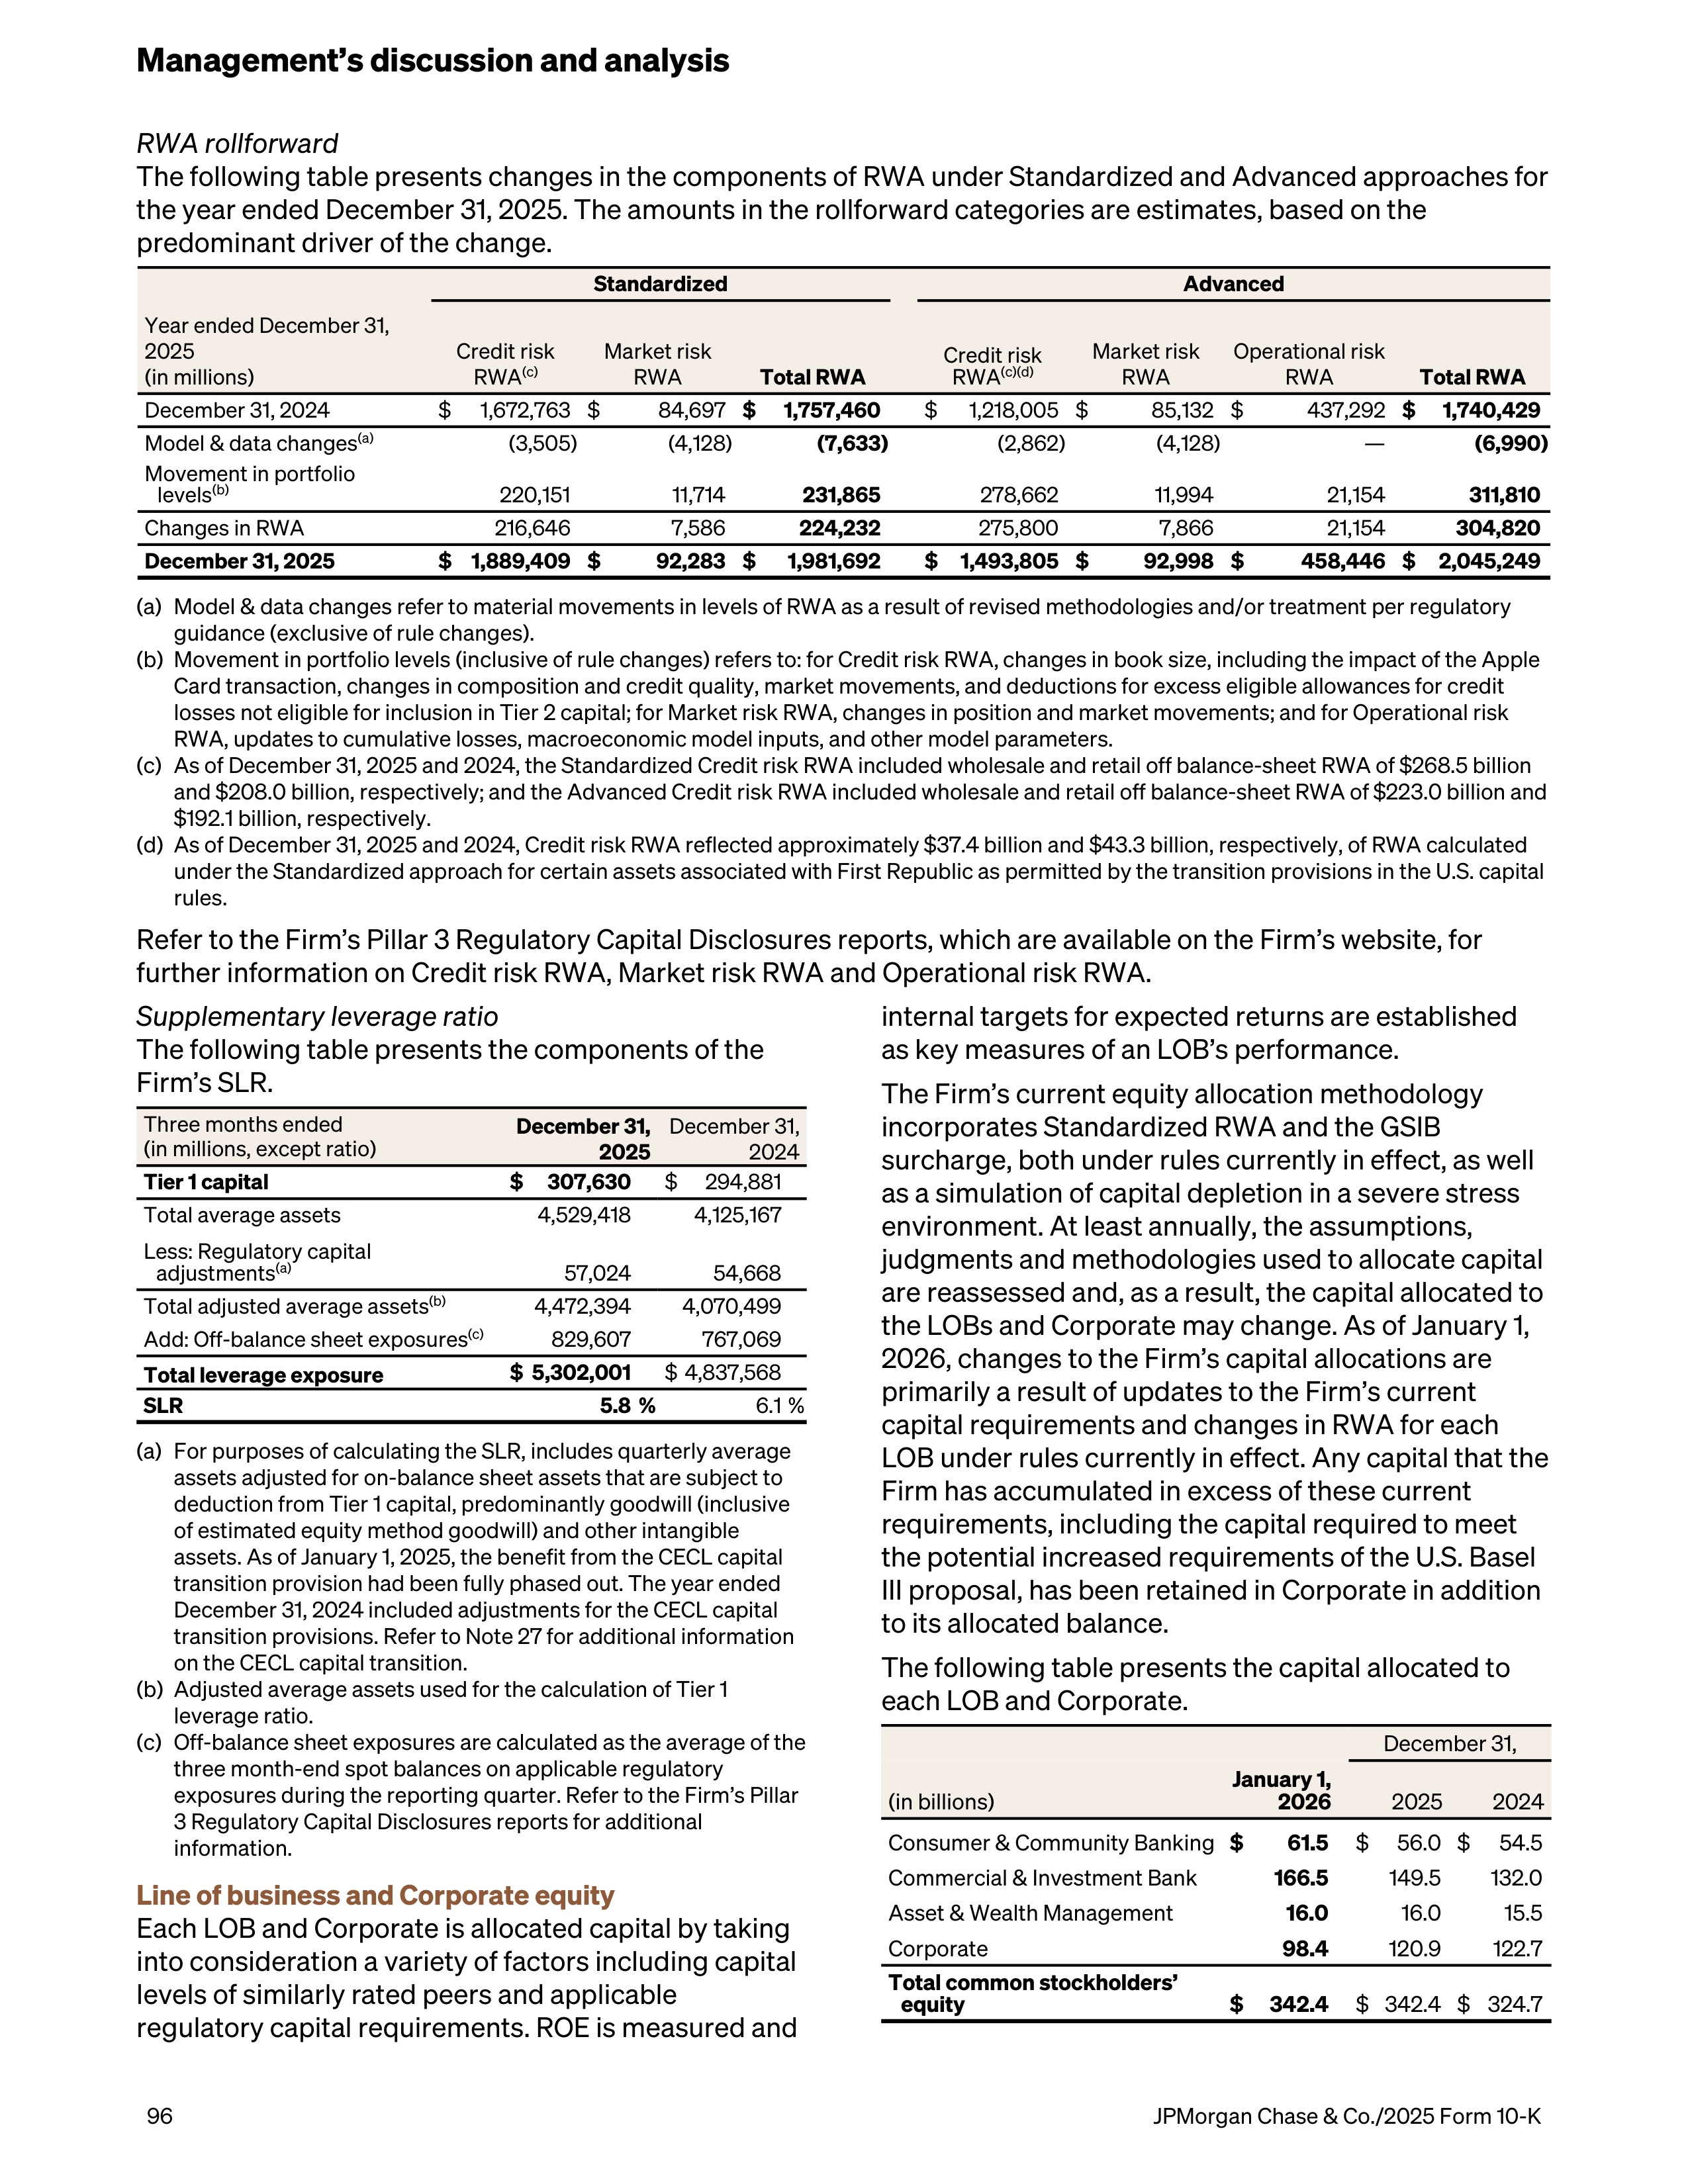
RWA rollforward
The following table presents changes in the components of RWA under Standardized and Advanced approaches for
the year ended December 31, 2025. The amounts in the rollforward categories are estimates, based on the
predominant driver of the change.
Standardized
Advanced
Year ended December 31,
2025
(in millions)
Credit risk
RWA
(c)
Market risk
RWA
Total RWA
Credit risk
RWA
(c)(d)
Market risk
RWA
Operational risk
RWA
Total RWA
December 31, 2024
$
1,672,763 $
84,697
$
1,757,460
$
1,218,005 $
85,132 $
437,292
$
1,740,429
Model & data changes
(a)
(3,505)
(4,128)
(7,633)
(2,862)
(4,128)
—
(6,990)
Movement in portfolio
levels
(b)
220,151
11,714
231,865
278,662
11,994
21,154
311,810
Changes in RWA
216,646
7,586
224,232
275,800
7,866
21,154
304,820
December 31, 2025
$ 1,889,409 $
92,283 $
1,981,692
$
1,493,805 $
92,998 $
458,446 $
2,045,249
(a)
Model & data changes refer to material movements in levels of RWA as a result of revised methodologies and/or treatment per regulatory
guidance (exclusive of rule changes).
(b)
Movement in portfolio levels (inclusive of rule changes) refers to: for Credit risk RWA, changes in book size, including the impact of the Apple
Card transaction, changes in composition and credit quality, market movements, and deductions for excess eligible allowances for credit
losses not eligible for inclusion in Tier 2 capital; for Market risk RWA, changes in position and market movements; and for Operational risk
RWA, updates to cumulative losses, macroeconomic model inputs, and other model parameters.
(c)
As of December 31, 2025 and 2024, the Standardized Credit risk RWA included wholesale and retail off balance-sheet RWA of $268.5 billion
and $208.0 billion, respectively; and the Advanced Credit risk RWA included wholesale and retail off balance-sheet RWA of $223.0 billion and
$192.1 billion, respectively.
(d)
As of December 31, 2025 and 2024, Credit risk RWA reflected approximately $37.4 billion and $43.3 billion, respectively, of RWA calculated
under the Standardized approach for certain assets associated with First Republic as permitted by the transition provisions in the U.S. capital
rules.
Refer to the Firm’s Pillar 3 Regulatory Capital Disclosures reports, which are available on the Firm’s website, for
further information on Credit risk RWA, Market risk RWA and Operational risk RWA.
Supplementary leverage ratio
The following table presents the components of the
Firm’s SLR.
Three months ended
(in millions, except ratio)
December 31,
2025
December 31,
2024
Tier 1 capital
$
307,630
$
294,881
Total average assets
4,529,418
4,125,167
Less: Regulatory capital
adjustments
(a)
57,024
54,668
Total adjusted average assets
(b)
4,472,394
4,070,499
Add: Off-balance sheet exposures
(c)
829,607
767,069
Total leverage exposure
$ 5,302,001
$ 4,837,568
SLR
5.8 %
6.1 %
(a)
For purposes of calculating the SLR, includes quarterly average
assets adjusted for on-balance sheet assets that are subject to
deduction from Tier 1 capital, predominantly goodwill (inclusive
of estimated equity method goodwill) and other intangible
assets. As of January 1, 2025, the benefit from the CECL capital
transition provision had been fully phased out. The year ended
December 31, 2024 included adjustments for the CECL capital
transition provisions. Refer to Note 27 for additional information
on the CECL capital transition.
(b)
Adjusted average assets used for the calculation of Tier 1
leverage ratio.
(c)
Off-balance sheet exposures are calculated as the average of the
three month-end spot balances on applicable regulatory
exposures during the reporting quarter. Refer to the Firm’s Pillar
3 Regulatory Capital Disclosures reports for additional
information.
Line of business and Corporate equity
Each LOB and Corporate is allocated capital by taking
into consideration a variety of factors including capital
levels of similarly rated peers and applicable
regulatory capital requirements. ROE is measured and
internal targets for expected returns are established
as key measures of an LOB’s performance.
The Firm’s current equity allocation methodology
incorporates Standardized RWA and the GSIB
surcharge, both under rules currently in effect, as well
as a simulation of capital depletion in a severe stress
environment. At least annually, the assumptions,
judgments and methodologies used to allocate capital
are reassessed and, as a result, the capital allocated to
the LOBs and Corporate may change. As of January 1,
2026, changes to the Firm’s capital allocations are
primarily a result of updates to the Firm’s current
capital requirements and changes in RWA for each
LOB under rules currently in effect. Any capital that the
Firm has accumulated in excess of these current
requirements, including the capital required to meet
the potential increased requirements of the U.S. Basel
III proposal, has been retained in Corporate in addition
to its allocated balance.
The following table presents the capital allocated to
each LOB and Corporate.
December 31,
(in billions)
January 1,
2026
2025
2024
Consumer & Community Banking
$
61.5
$
56.0 $
54.5
Commercial & Investment Bank
166.5
149.5
132.0
Asset & Wealth Management
16.0
16.0
15.5
Corporate
98.4
120.9
122.7
Total common stockholders’
equity
$
342.4
$ 342.4 $ 324.7
Management’s discussion and analysis
96
JPMorgan Chase & Co./2025 Form 10-K
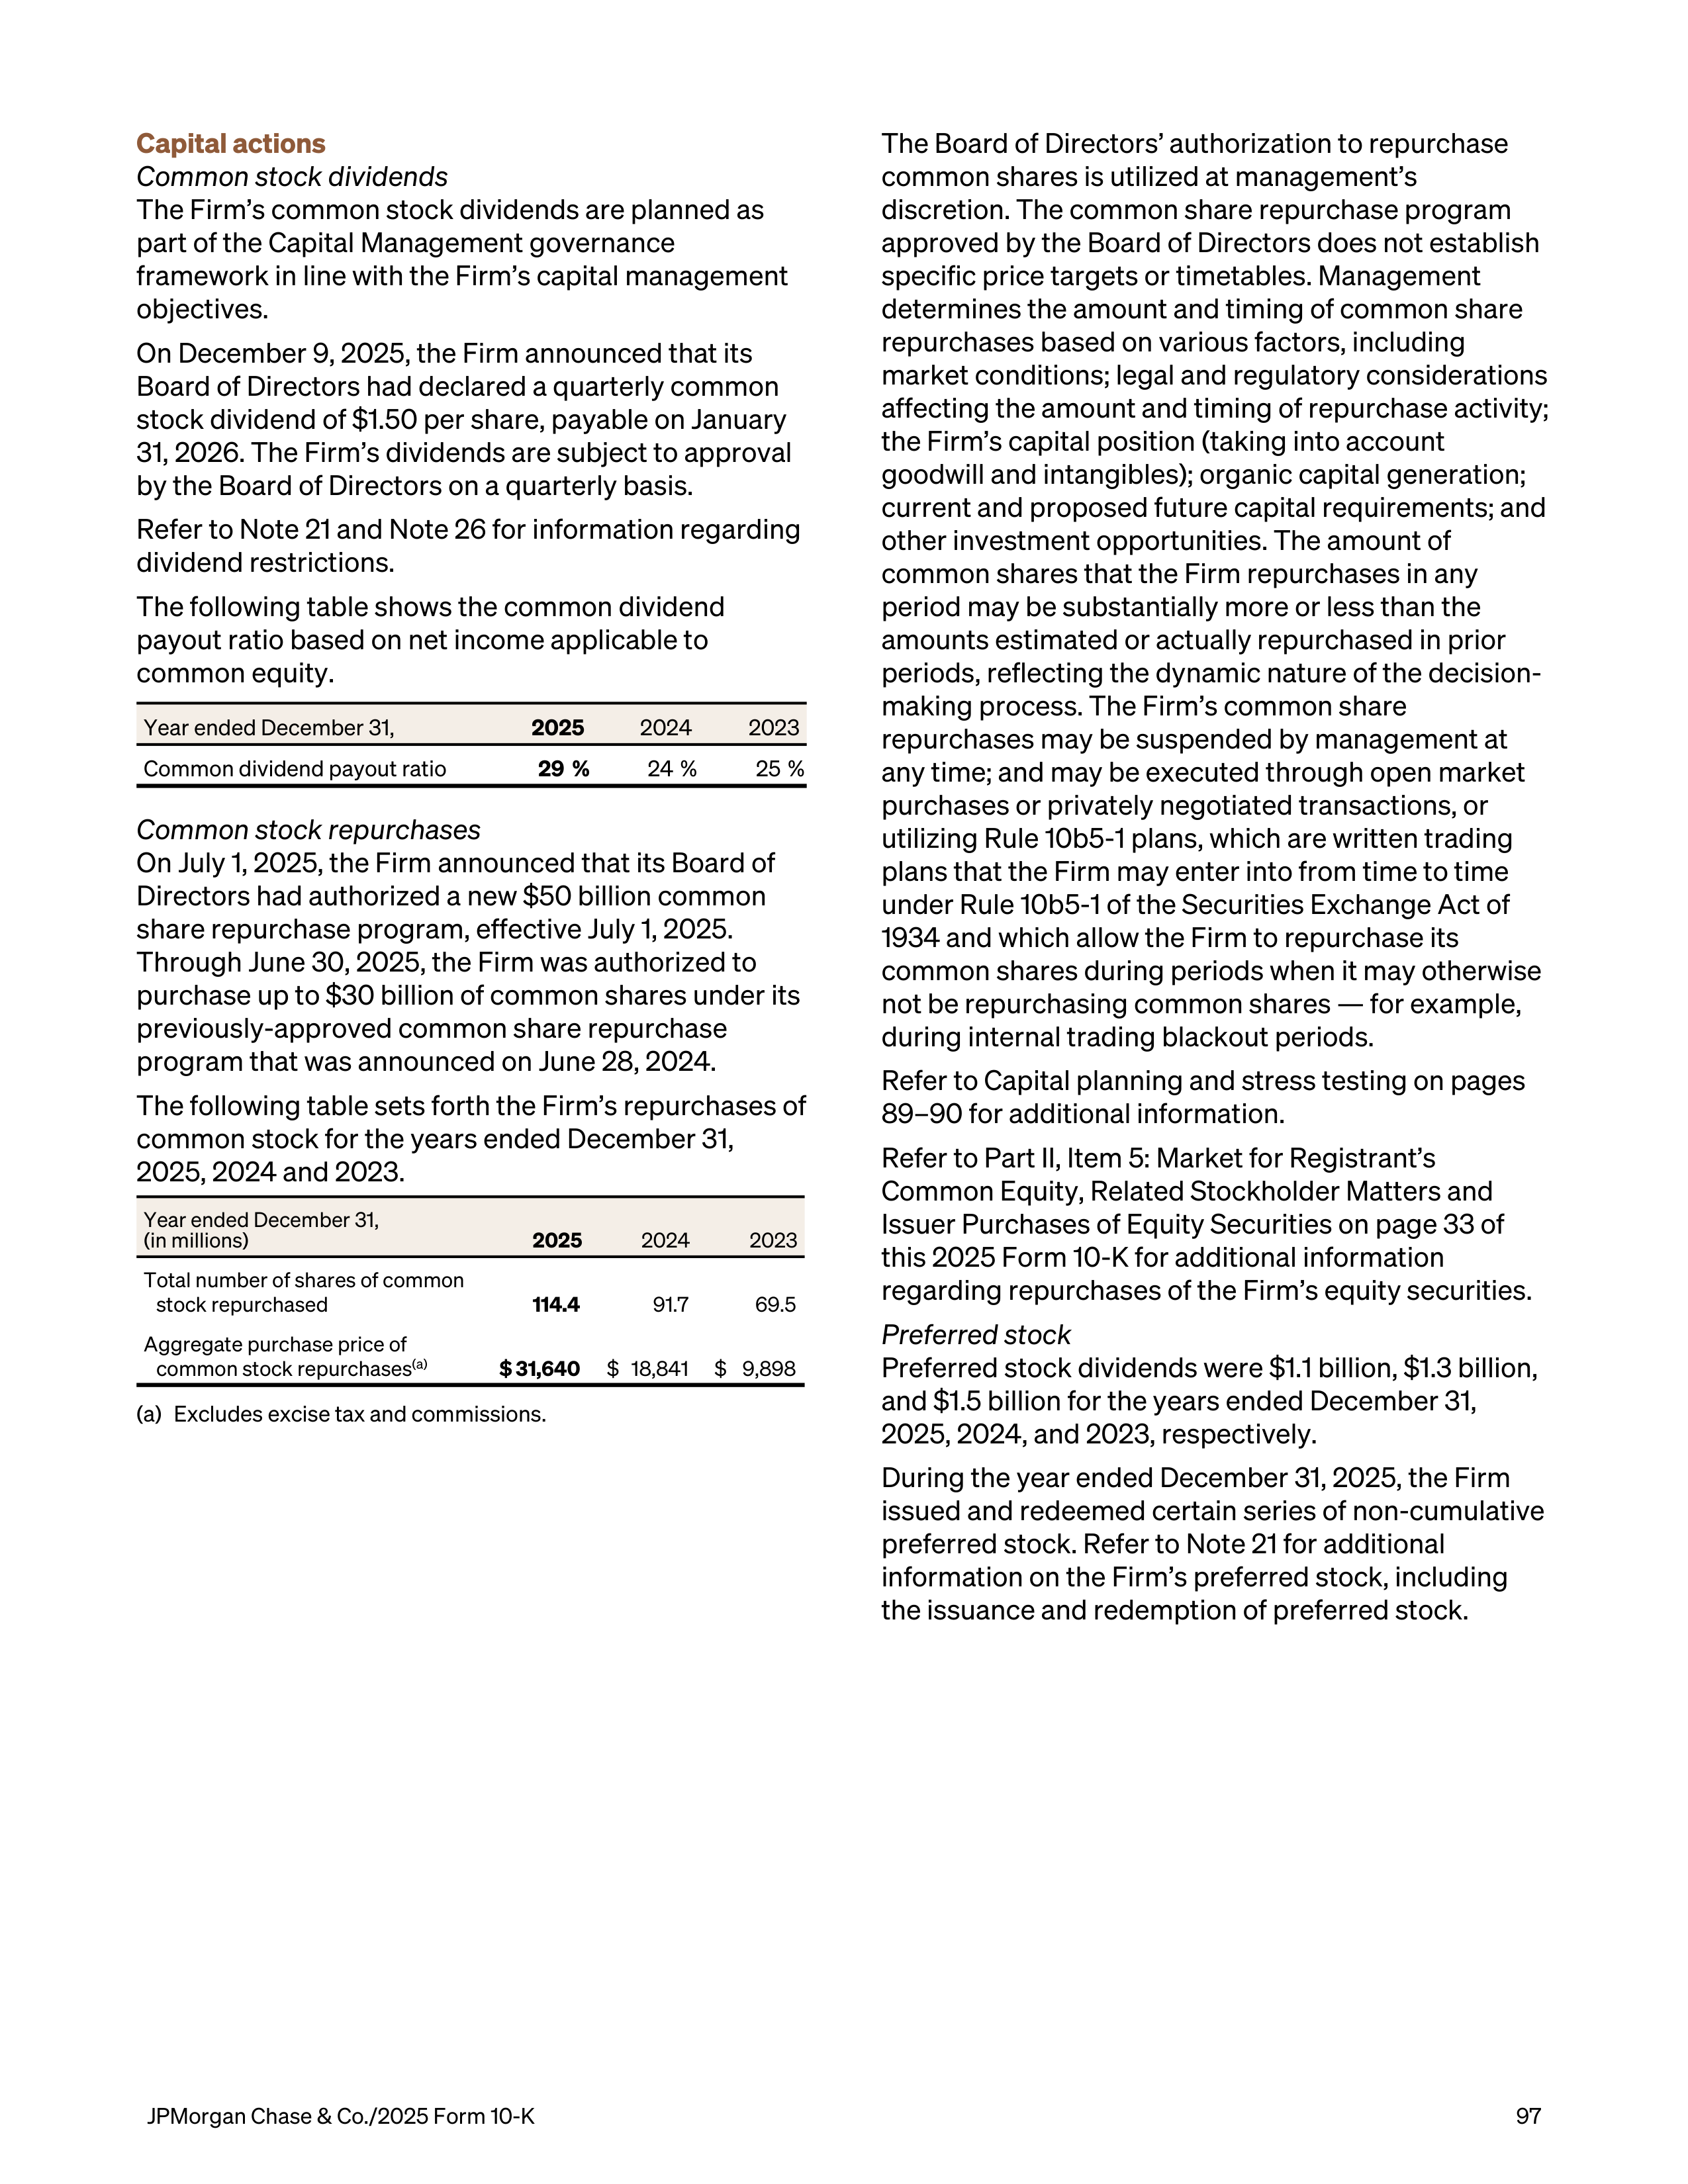
Capital actions
Common stock dividends
The Firm’s common stock dividends are planned as
part of the Capital Management governance
framework in line with the Firm’s capital management
objectives.
On December 9, 2025, the Firm announced that its
Board of Directors had declared a quarterly common
stock dividend of $1.50 per share, payable on January
31, 2026. The Firm’s dividends are subject to approval
by the Board of Directors on a quarterly basis.
Refer to Note 21 and Note 26 for information regarding
dividend restrictions.
The following table shows the common dividend
payout ratio based on net income applicable to
common equity.
Year ended December 31,
2025
2024
2023
Common dividend payout ratio
29 %
24 %
25 %
Common stock repurchases
On July 1, 2025, the Firm announced that its Board of
Directors had authorized a new $50 billion common
share repurchase program, effective July 1, 2025.
Through June 30, 2025, the Firm was authorized to
purchase up to $30 billion of common shares under its
previously-approved common share repurchase
program that was announced on June 28, 2024.
The following table sets forth the Firm’s repurchases of
common stock for the years ended December 31,
2025, 2024 and 2023.
Year ended December 31,
(in millions)
2025
2024
2023
Total number of shares of common
stock repurchased
114.4
91.7
69.5
Aggregate purchase price of
common stock repurchases
(a)
$ 31,640
$ 18,841
$ 9,898
(a)
Excludes excise tax and commissions.
The Board of Directors’ authorization to repurchase
common shares is utilized at management’s
discretion. The common share repurchase program
approved by the Board of Directors does not establish
specific price targets or timetables. Management
determines the amount and timing of common share
repurchases based on various factors, including
market conditions; legal and regulatory considerations
affecting the amount and timing of repurchase activity;
the Firm’s capital position (taking into account
goodwill and intangibles); organic capital generation;
current and proposed future capital requirements; and
other investment opportunities. The amount of
common shares that the Firm repurchases in any
period may be substantially more or less than the
amounts estimated or actually repurchased in prior
periods, reflecting the dynamic nature of the decision-
making process. The Firm’s common share
repurchases may be suspended by management at
any time; and may be executed through open market
purchases or privately negotiated transactions, or
utilizing Rule 10b5-1 plans, which are written trading
plans that the Firm may enter into from time to time
under Rule 10b5-1 of the Securities Exchange Act of
1934 and which allow the Firm to repurchase its
common shares during periods when it may otherwise
not be repurchasing common shares — for example,
during internal trading blackout periods.
Refer to Capital planning and stress testing on pages
89–90 for additional information.
Refer to Part II, Item 5: Market for Registrant’s
Common Equity, Related Stockholder Matters and
Issuer Purchases of Equity Securities on page 33 of
this 2025 Form 10-K for additional information
regarding repurchases of the Firm’s equity securities.
Preferred stock
Preferred stock dividends were $1.1 billion, $1.3 billion,
and $1.5 billion for the years ended December 31,
2025, 2024, and 2023, respectively.
During the year ended December 31, 2025, the Firm
issued and redeemed certain series of non-cumulative
preferred stock. Refer to Note 21 for additional
information on the Firm’s preferred stock, including
the issuance and redemption of preferred stock.
JPMorgan Chase & Co./2025 Form 10-K
97
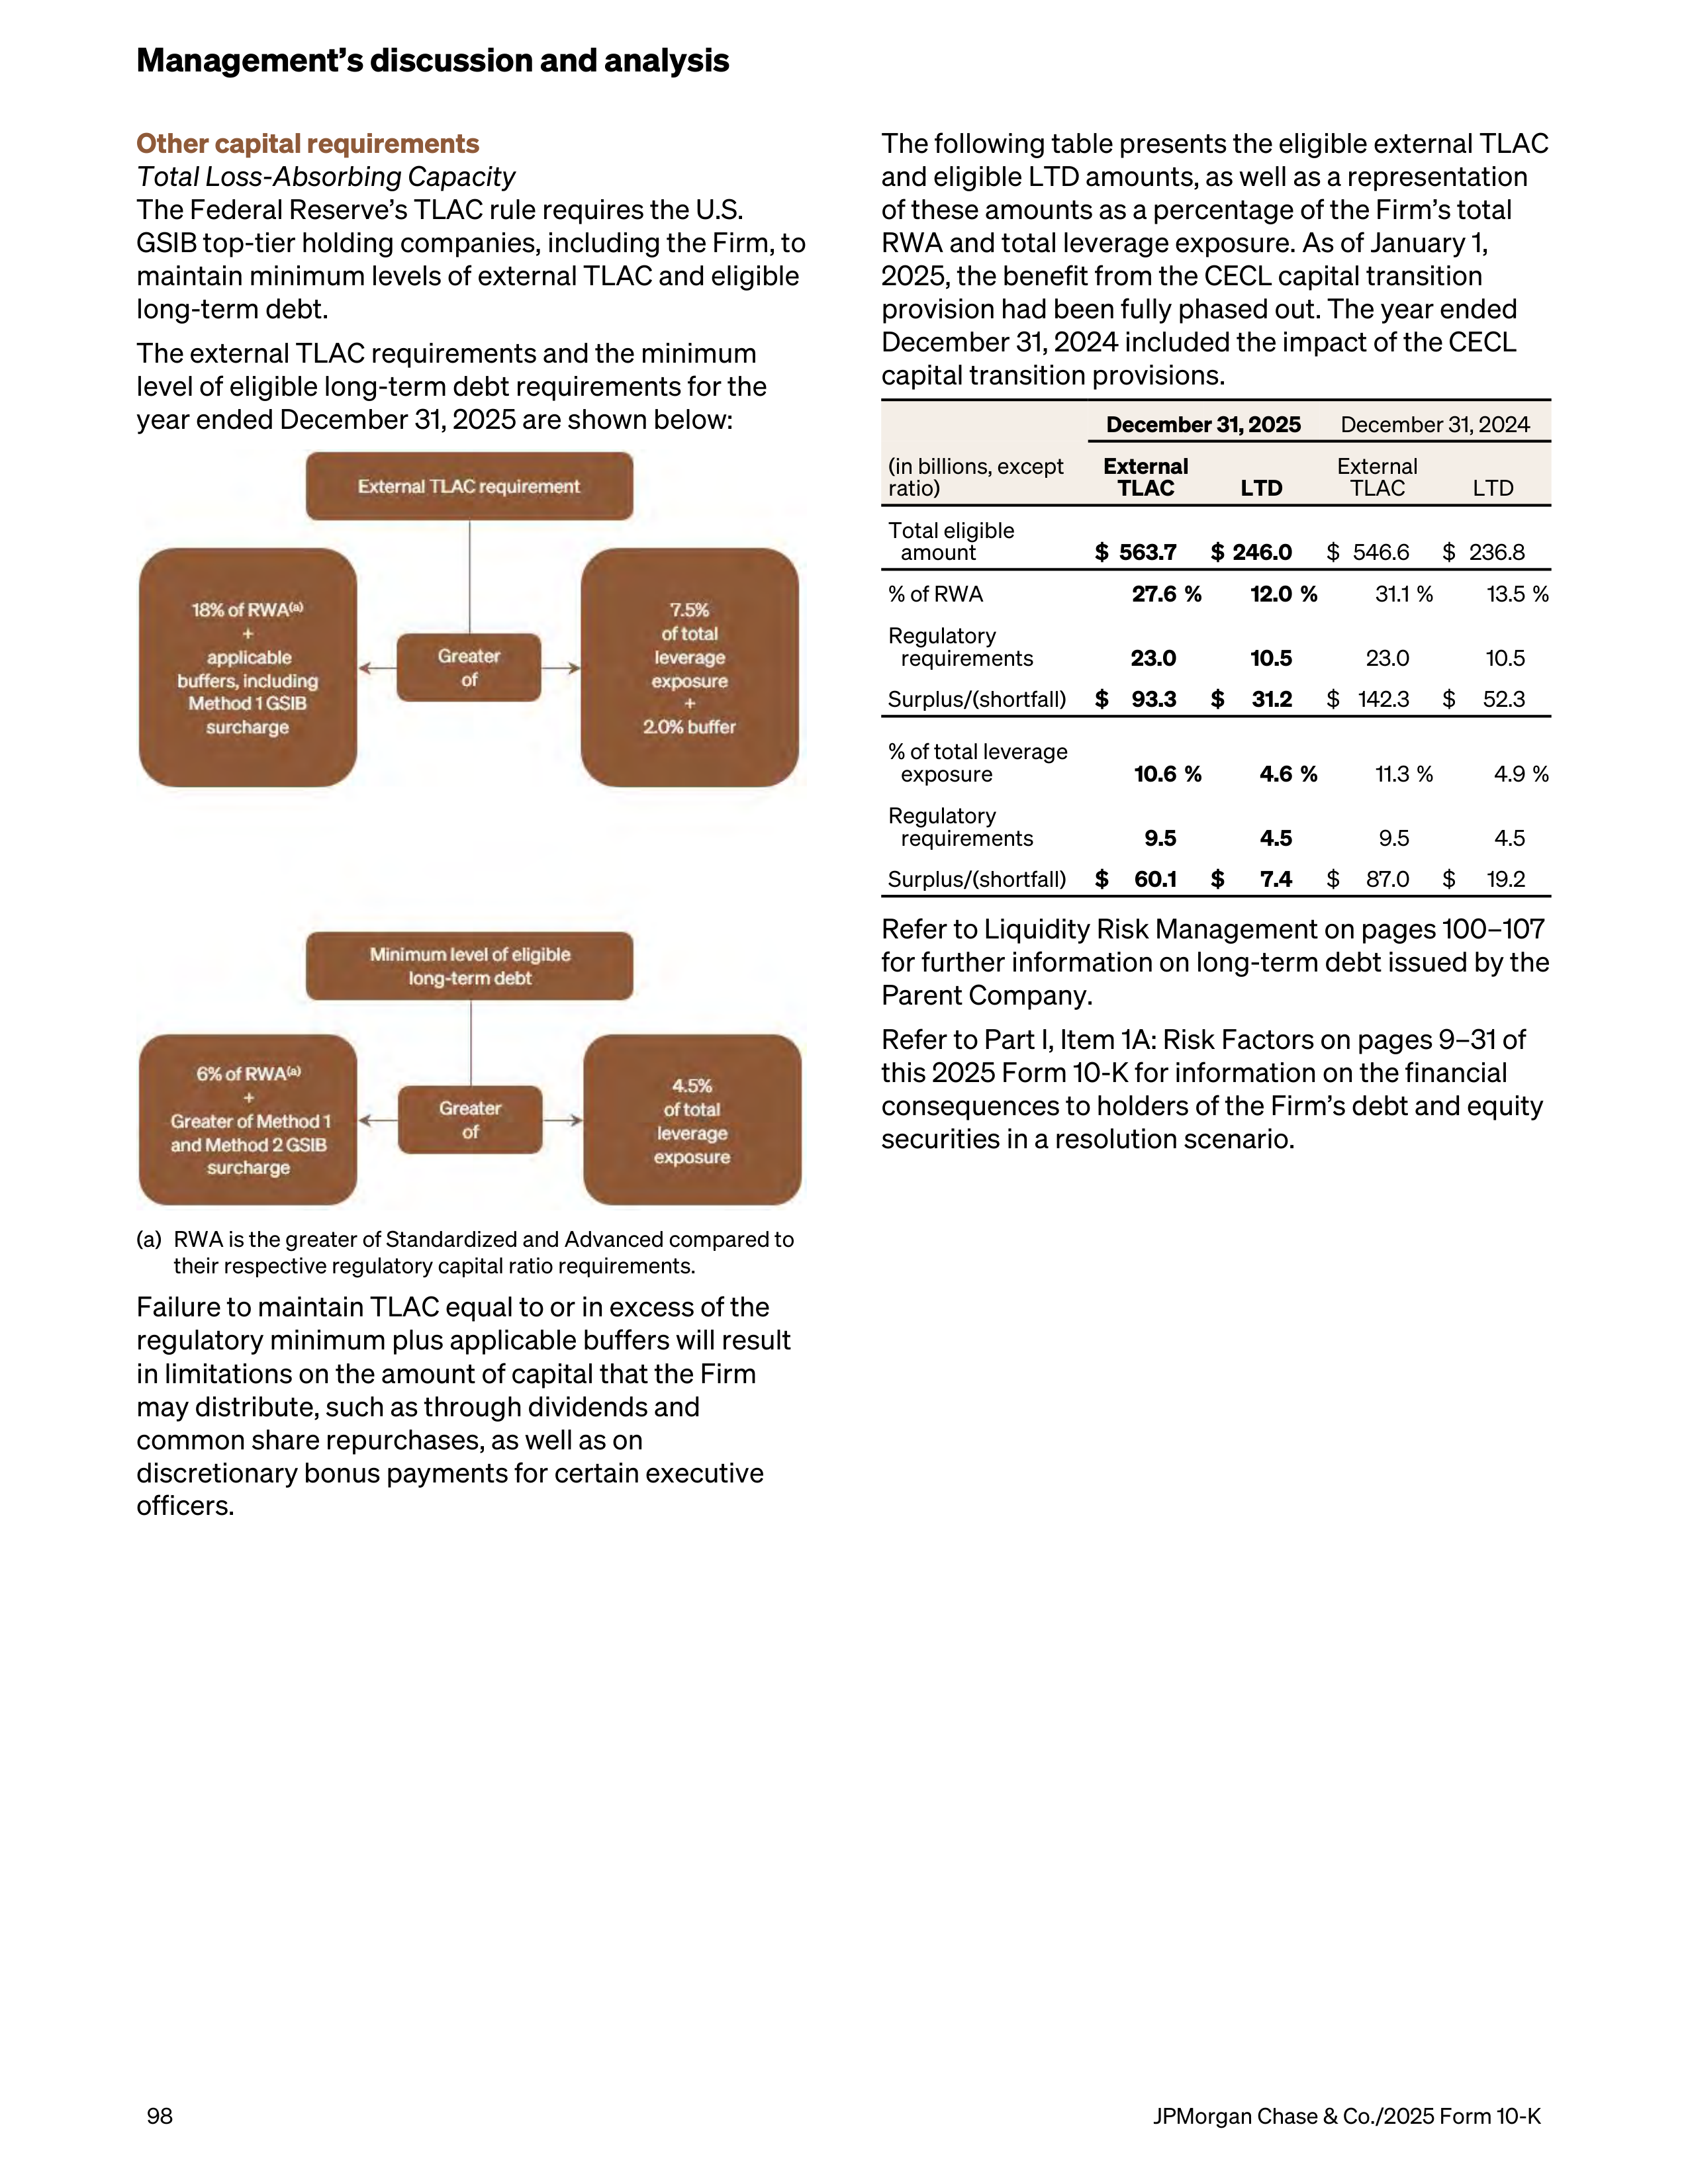
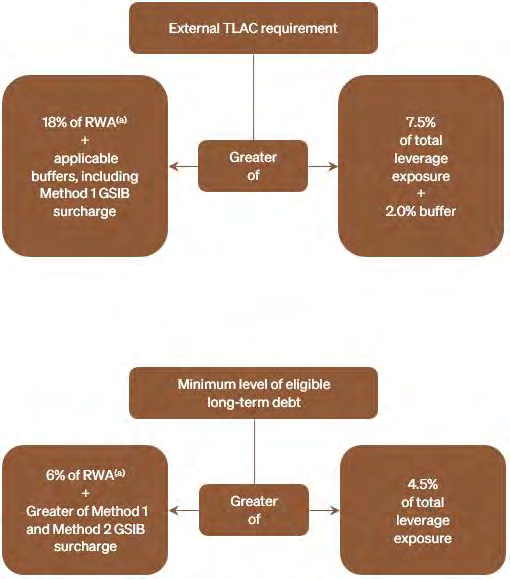
Other capital requirements
Total Loss-Absorbing Capacity
The Federal Reserve’s TLAC rule requires the U.S.
GSIB top-tier holding companies, including the Firm, to
maintain minimum levels of external TLAC and eligible
long-term debt.
The external TLAC requirements and the minimum
level of eligible long-term debt requirements for the
year ended December 31, 2025 are shown below:
(a)
RWA is the greater of Standardized and Advanced compared to
their respective regulatory capital ratio requirements.
Failure to maintain TLAC equal to or in excess of the
regulatory minimum plus applicable buffers will result
in limitations on the amount of capital that the Firm
may distribute, such as through dividends and
common share repurchases, as well as on
discretionary bonus payments for certain executive
officers.
The following table presents the eligible external TLAC
and eligible LTD amounts, as well as a representation
of these amounts as a percentage of the Firm’s total
RWA and total leverage exposure. As of January 1,
2025, the benefit from the CECL capital transition
provision had been fully phased out. The year ended
December 31, 2024 included the impact of the CECL
capital transition provisions.
December 31, 2025
December 31, 2024
(in billions, except
ratio)
External
TLAC
LTD
External
TLAC
LTD
Total eligible
amount
$ 563.7
$ 246.0
$ 546.6
$ 236.8
% of RWA
27.6 %
12.0 %
31.1 %
13.5 %
Regulatory
requirements
23.0
10.5
23.0
10.5
Surplus/(shortfall)
$
93.3
$
31.2
$ 142.3
$
52.3
% of total leverage
exposure
10.6 %
4.6 %
11.3 %
4.9 %
Regulatory
requirements
9.5
4.5
9.5
4.5
Surplus/(shortfall)
$
60.1
$
7.4
$
87.0
$
19.2
Refer to Liquidity Risk Management on pages 100–107
for further information on long-term debt issued by the
Parent Company.
Refer to Part I, Item 1A: Risk Factors on pages 9–31 of
this 2025 Form 10-K for information on the financial
consequences to holders of the Firm’s debt and equity
securities in a resolution scenario.
Management’s discussion and analysis
98
JPMorgan Chase & Co./2025 Form 10-K
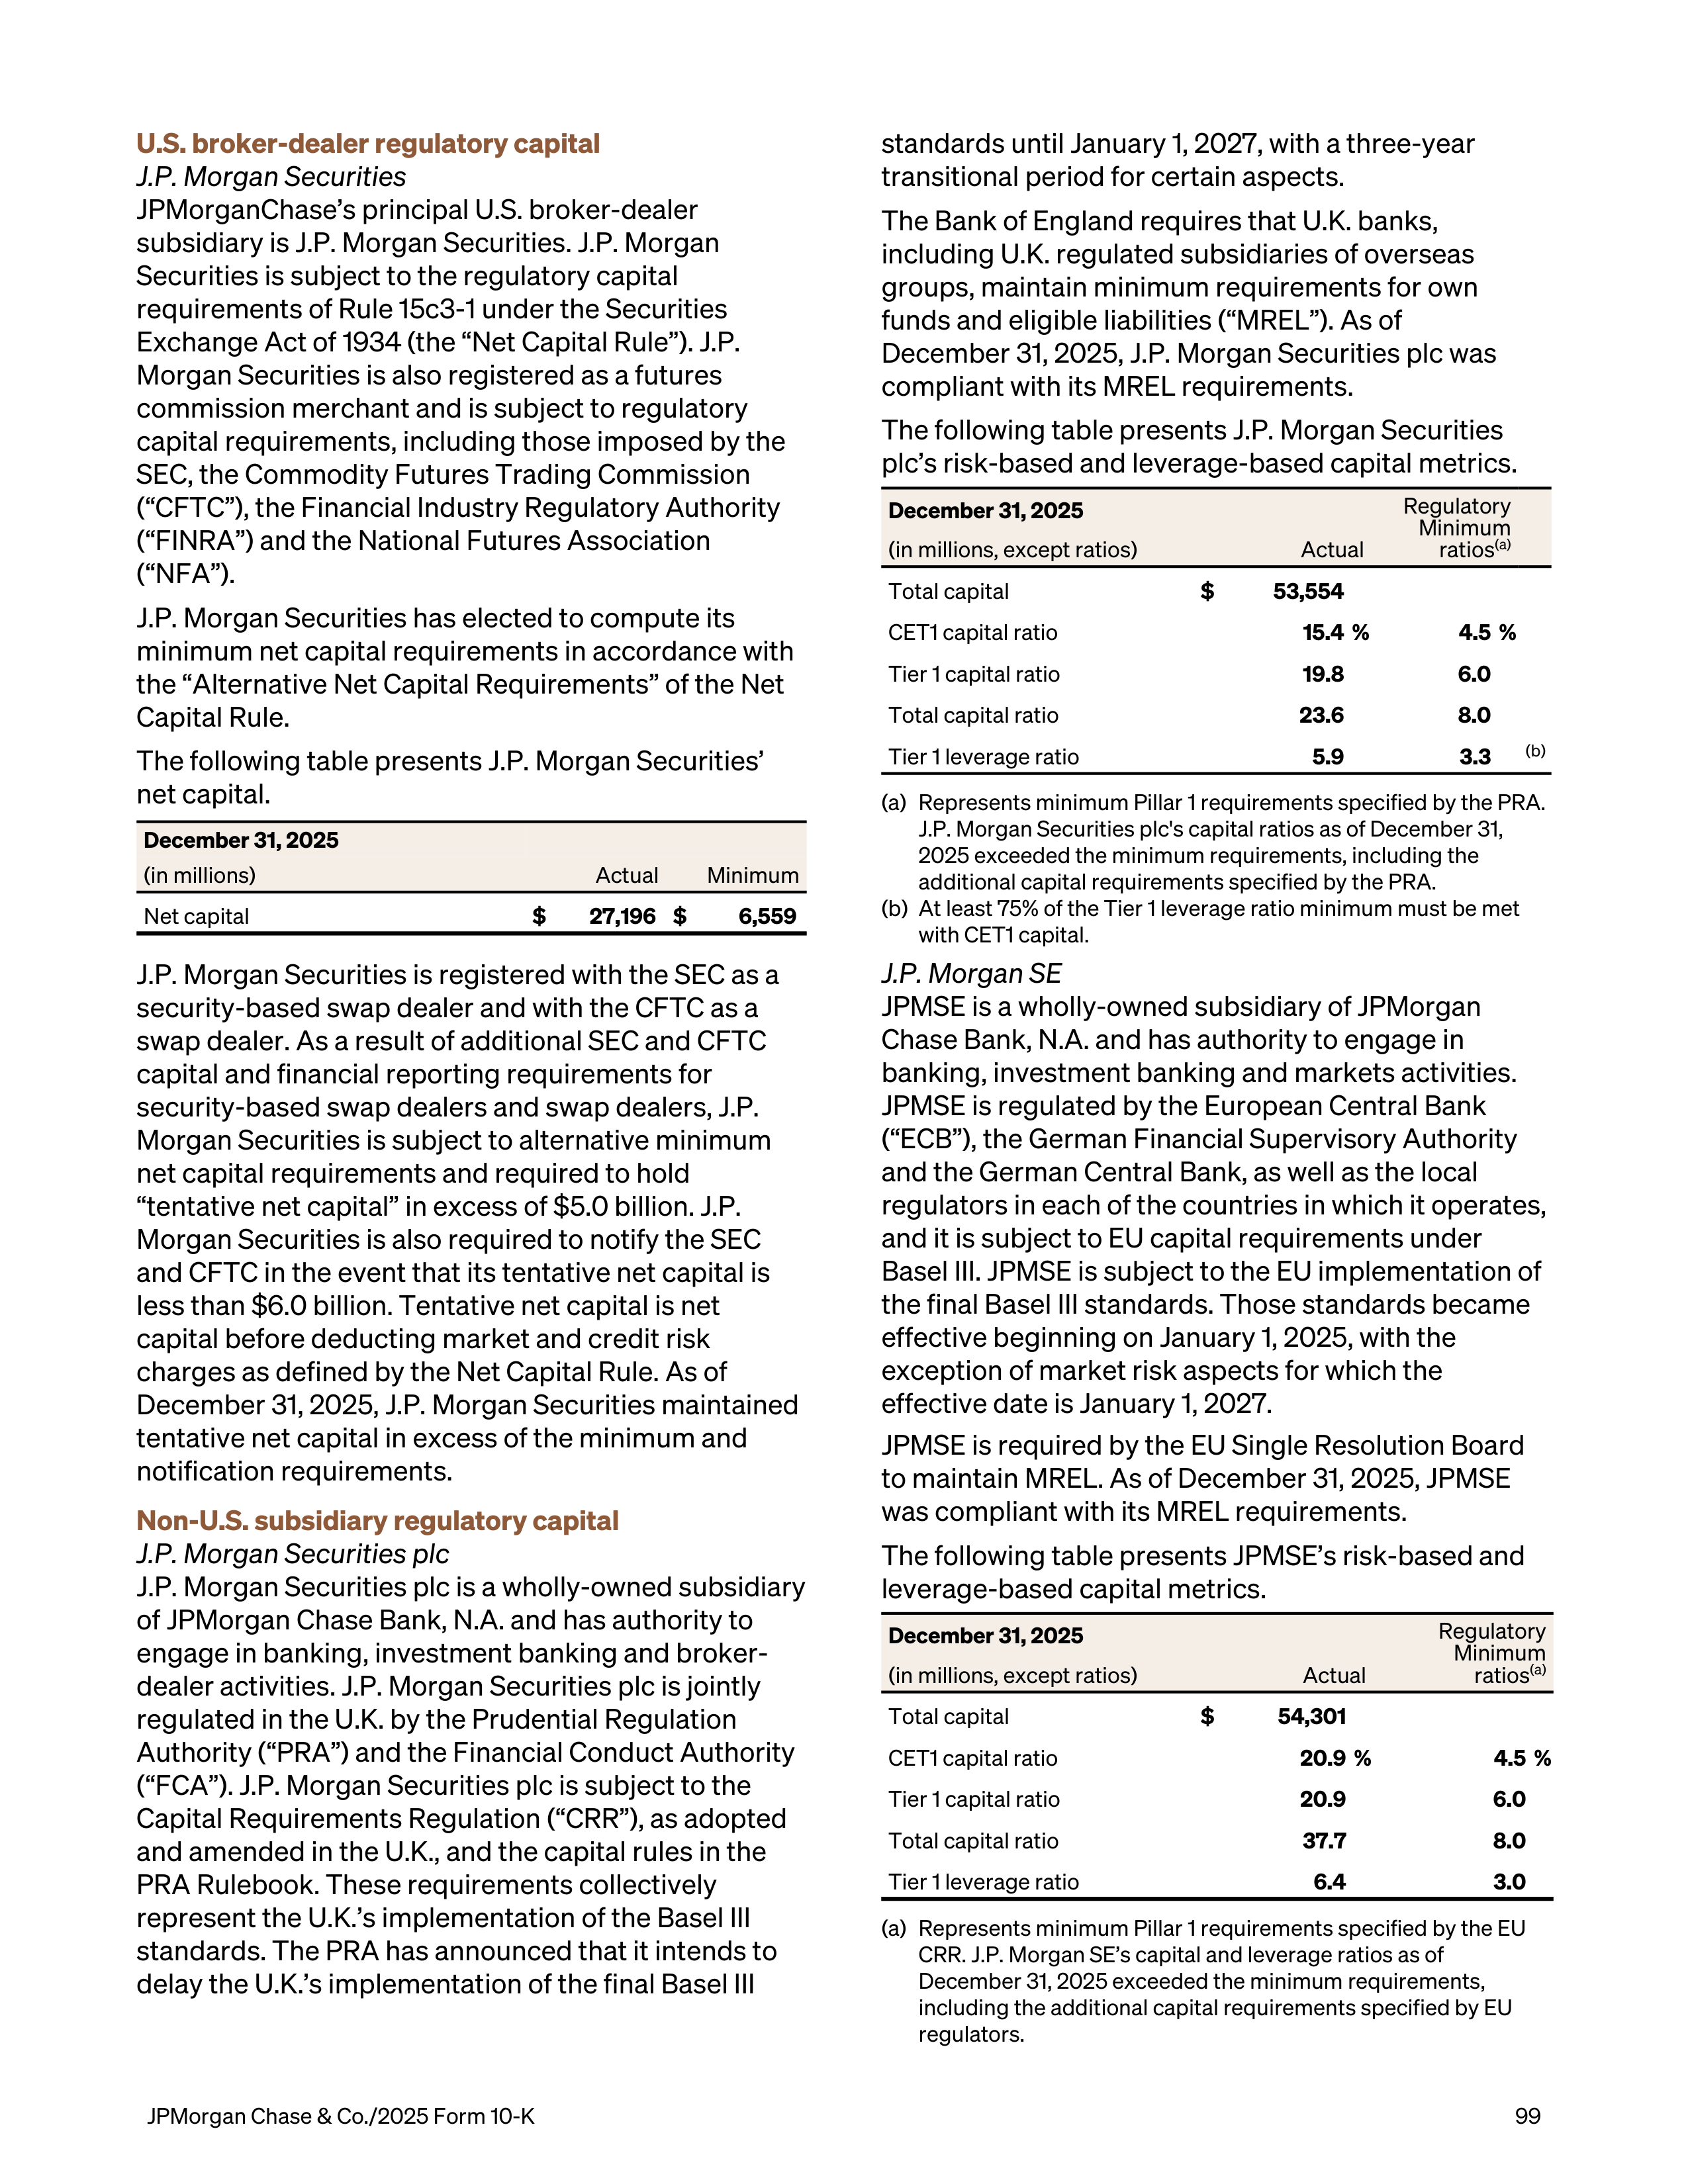
U.S. broker-dealer regulatory capital
J.P. Morgan Securities
JPMorganChase’s principal U.S. broker-dealer
subsidiary is J.P. Morgan Securities. J.P. Morgan
Securities is subject to the regulatory capital
requirements of Rule 15c3-1 under the Securities
Exchange Act of 1934 (the “Net Capital Rule”). J.P.
Morgan Securities is also registered as a futures
commission merchant and is subject to regulatory
capital requirements, including those imposed by the
SEC, the Commodity Futures Trading Commission
(“CFTC”), the Financial Industry Regulatory Authority
(“FINRA”) and the National Futures Association
(“NFA”).
J.P. Morgan Securities has elected to compute its
minimum net capital requirements in accordance with
the “Alternative Net Capital Requirements” of the Net
Capital Rule.
The following table presents J.P. Morgan Securities’
net capital.
December 31, 2025
(in millions)
Actual
Minimum
Net capital
$
27,196 $
6,559
J.P. Morgan Securities is registered with the SEC as a
security-based swap dealer and with the CFTC as a
swap dealer. As a result of additional SEC and CFTC
capital and financial reporting requirements for
security-based swap dealers and swap dealers, J.P.
Morgan Securities is subject to alternative minimum
net capital requirements and required to hold
“tentative net capital” in excess of $5.0 billion. J.P.
Morgan Securities is also required to notify the SEC
and CFTC in the event that its tentative net capital is
less than $6.0 billion. Tentative net capital is net
capital before deducting market and credit risk
charges as defined by the Net Capital Rule. As of
December 31, 2025, J.P. Morgan Securities maintained
tentative net capital in excess of the minimum and
notification requirements.
Non-U.S. subsidiary regulatory capital
J.P. Morgan Securities plc
J.P. Morgan Securities plc is a wholly-owned subsidiary
of JPMorgan Chase Bank, N.A. and has authority to
engage in banking, investment banking and broker-
dealer activities. J.P. Morgan Securities plc is jointly
regulated in the U.K. by the Prudential Regulation
Authority (“PRA”) and the Financial Conduct Authority
(“FCA”). J.P. Morgan Securities plc is subject to the
Capital Requirements Regulation (“CRR”), as adopted
and amended in the U.K., and the capital rules in the
PRA Rulebook. These requirements collectively
represent the U.K.’s implementation of the Basel III
standards. The PRA has announced that it intends to
delay the U.K.’s implementation of the final Basel III
standards until January 1, 2027, with a three-year
transitional period for certain aspects.
The Bank of England requires that U.K. banks,
including U.K. regulated subsidiaries of overseas
groups, maintain minimum requirements for own
funds and eligible liabilities (“MREL”). As of
December 31, 2025, J.P. Morgan Securities plc was
compliant with its MREL requirements.
The following table presents J.P. Morgan Securities
plc’s risk-based and leverage-based capital metrics.
December 31, 2025
Regulatory
Minimum
ratios
(a)
(in millions, except ratios)
Actual
Total capital
$
53,554
CET1 capital ratio
15.4 %
4.5 %
Tier 1 capital ratio
19.8
6.0
Total capital ratio
23.6
8.0
Tier 1 leverage ratio
5.9
3.3
(b)
(a)
Represents minimum Pillar 1 requirements specified by the PRA.
J.P. Morgan Securities plc's capital ratios as of December 31,
2025 exceeded the minimum requirements, including the
additional capital requirements specified by the PRA.
(b)
At least 75% of the Tier 1 leverage ratio minimum must be met
with CET1 capital.
J.P. Morgan SE
JPMSE is a wholly-owned subsidiary of JPMorgan
Chase Bank, N.A. and has authority to engage in
banking, investment banking and markets activities.
JPMSE is regulated by the European Central Bank
(“ECB”), the German Financial Supervisory Authority
and the German Central Bank, as well as the local
regulators in each of the countries in which it operates,
and it is subject to EU capital requirements under
Basel III. JPMSE is subject to the EU implementation of
the final Basel III standards. Those standards became
effective beginning on January 1, 2025, with the
exception of market risk aspects for which the
effective date is January 1, 2027.
JPMSE is required by the EU Single Resolution Board
to maintain MREL. As of December 31, 2025, JPMSE
was compliant with its MREL requirements.
The following table presents JPMSE’s risk-based and
leverage-based capital metrics.
December 31, 2025
Regulatory
Minimum
ratios
(a)
(in millions, except ratios)
Actual
Total capital
$
54,301
CET1 capital ratio
20.9 %
4.5 %
Tier 1 capital ratio
20.9
6.0
Total capital ratio
37.7
8.0
Tier 1 leverage ratio
6.4
3.0
(a)
Represents minimum Pillar 1 requirements specified by the EU
CRR. J.P. Morgan SE’s capital and leverage ratios as of
December 31, 2025 exceeded the minimum requirements,
including the additional capital requirements specified by EU
regulators.
JPMorgan Chase & Co./2025 Form 10-K
99
LIQUIDITY RISK MANAGEMENT
Liquidity risk is the risk that the Firm will be unable to
meet its cash and collateral needs as they arise or that
it does not have the appropriate amount, composition
and tenor of funding and liquidity to support its assets
and liabilities.
Liquidity risk management
The Firm has a Liquidity Risk Management (“LRM”)
function whose primary objective is to provide
independent oversight of liquidity risk across the Firm.
Liquidity Risk Management’s responsibilities include:
•
Defining, monitoring and reporting liquidity risk
metrics;
•
Independently establishing and monitoring limits
and indicators, including liquidity risk appetite;
•
Developing a process to classify, monitor and report
limit breaches;
•
Performing an independent review of liquidity risk
management processes to evaluate their adequacy
and effectiveness;
•
Monitoring and reporting internal Firmwide and legal
entity liquidity stress tests, regulatory defined
metrics, as well as liquidity positions, balance sheet
variances and funding activities; and
•
Approving or escalating for review new or updated
liquidity stress assumptions.
Liquidity management
Treasury and CIO is responsible for liquidity
management.
The primary objectives of the Firm’s liquidity
management are to:
•
Ensure that the Firm’s core businesses and material
legal entities are able to operate in support of client
needs and meet contractual and contingent financial
obligations through normal economic cycles as well
as during stress events, and
•
Manage an optimal funding mix and availability of
liquidity sources.
The Firm addresses these objectives through:
•
Analyzing and understanding the liquidity
characteristics of the assets and liabilities of the
Firm, LOBs, legal entities, as well as currencies,
taking into account legal, regulatory, and operational
restrictions;
•
Developing and maintaining internal liquidity stress
testing assumptions;
•
Defining and monitoring Firmwide and legal entity-
specific liquidity strategies, policies, reporting and
contingency funding plans;
•
Managing liquidity within the Firm’s approved limits
and indicators, including liquidity risk appetite
tolerances;
•
Managing compliance with regulatory requirements
related to funding and liquidity risk; and
•
Setting FTP in accordance with underlying liquidity
characteristics of balance sheet assets and liabilities
as well as certain off-balance sheet items.
As part of the Firm’s overall liquidity management
strategy, the Firm manages liquidity and funding using
a centralized, global approach designed to:
•
Optimize liquidity sources and uses;
•
Monitor exposures;
•
Identify constraints on the transfer of liquidity
between the Firm’s legal entities; and
•
Maintain the appropriate amount of surplus liquidity
at a Firmwide and legal entity level, where relevant.
Governance
Committees responsible for liquidity governance
include the Firmwide ALCO, as well as regional ALCOs,
the Treasurer Committee, and the CTC Risk
Committee. In addition, the Board Risk Committee
reviews and recommends to the Board of Directors, for
approval, the Firm’s liquidity risk tolerances, liquidity
strategy, and liquidity policy. Refer to Firmwide Risk
Management on pages 83–87 for further discussion of
ALCO and other risk-related committees.
Internal stress testing
The Firm conducts internal liquidity stress testing to
identify liquidity risks and monitor liquidity positions at
the Firm and its material legal entities under a variety
of adverse scenarios, including scenarios analyzed as
part of the Firm’s resolution and recovery planning.
Internal stress tests are produced on a daily basis, and
other stress tests are performed in response to
specific market events or concerns. Liquidity stress
tests assume all of the Firm’s contractual financial
obligations are met and take into consideration:
•
Varying levels of access to unsecured and secured
funding markets;
•
Estimated non-contractual and contingent cash
outflows;
•
Credit rating downgrades;
•
Collateral haircuts; and
•
Potential impediments to the availability and
transferability of liquidity between jurisdictions and
material legal entities such as regulatory, legal or
other restrictions.
Liquidity outflows are modeled across a range of time
horizons and currency dimensions and contemplate
both market and idiosyncratic stresses.
Results of stress tests are considered in the
formulation of the Firm’s funding plan and assessment
of its liquidity position. The Parent Company acts as a
source of funding for the Firm through equity and
Management’s discussion and analysis
100
JPMorgan Chase & Co./2025 Form 10-K
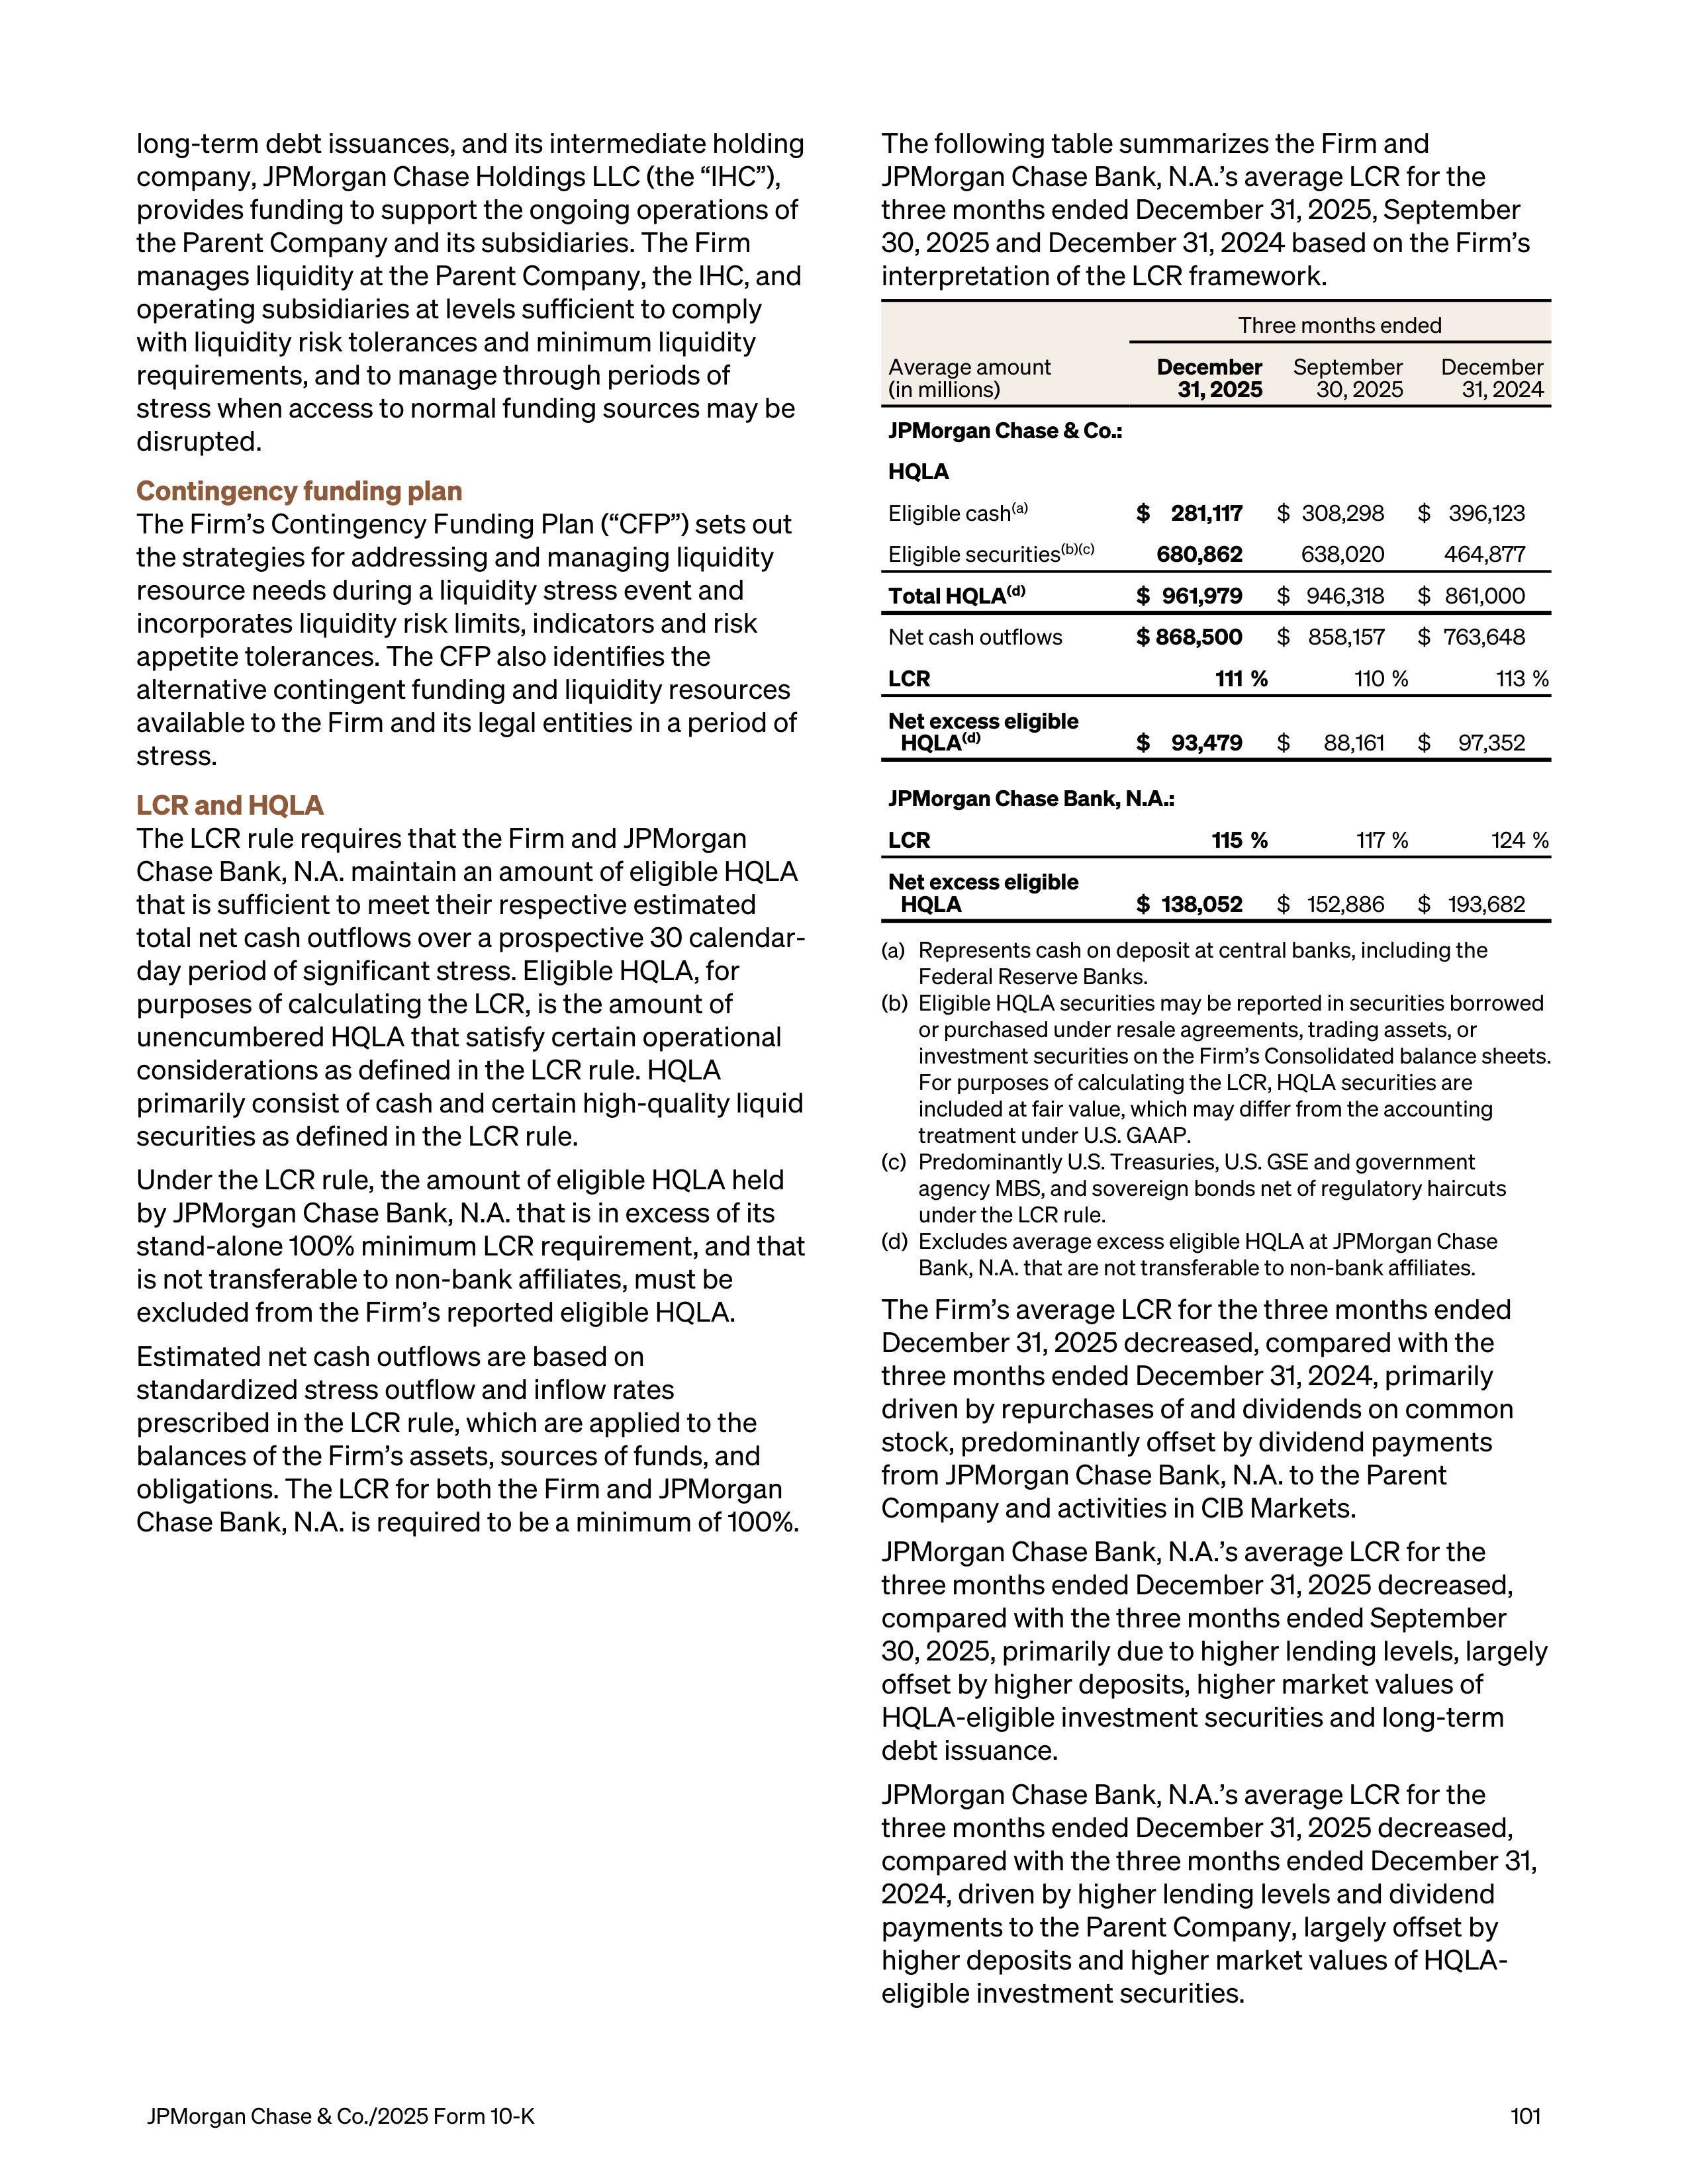
long-term debt issuances, and its intermediate holding
company, JPMorgan Chase Holdings LLC (the “IHC”),
provides funding to support the ongoing operations of
the Parent Company and its subsidiaries. The Firm
manages liquidity at the Parent Company, the IHC, and
operating subsidiaries at levels sufficient to comply
with liquidity risk tolerances and minimum liquidity
requirements, and to manage through periods of
stress when access to normal funding sources may be
disrupted.
Contingency funding plan
The Firm’s Contingency Funding Plan (“CFP”) sets out
the strategies for addressing and managing liquidity
resource needs during a liquidity stress event and
incorporates liquidity risk limits, indicators and risk
appetite tolerances. The CFP also identifies the
alternative contingent funding and liquidity resources
available to the Firm and its legal entities in a period of
stress.
LCR and HQLA
The LCR rule requires that the Firm and JPMorgan
Chase Bank, N.A. maintain an amount of eligible HQLA
that is sufficient to meet their respective estimated
total net cash outflows over a prospective 30 calendar-
day period of significant stress. Eligible HQLA, for
purposes of calculating the LCR, is the amount of
unencumbered HQLA that satisfy certain operational
considerations as defined in the LCR rule. HQLA
primarily consist of cash and certain high-quality liquid
securities as defined in the LCR rule.
Under the LCR rule, the amount of eligible HQLA held
by JPMorgan Chase Bank, N.A. that is in excess of its
stand-alone 100% minimum LCR requirement, and that
is not transferable to non-bank affiliates, must be
excluded from the Firm’s reported eligible HQLA.
Estimated net cash outflows are based on
standardized stress outflow and inflow rates
prescribed in the LCR rule, which are applied to the
balances of the Firm’s assets, sources of funds, and
obligations. The LCR for both the Firm and JPMorgan
Chase Bank, N.A. is required to be a minimum of 100%.
The following table summarizes the Firm and
JPMorgan Chase Bank, N.A.’s average LCR for the
three months ended December 31, 2025, September
30, 2025 and December 31, 2024 based on the Firm’s
interpretation of the LCR framework.
Three months ended
Average amount
(in millions)
December
31, 2025
September
30, 2025
December
31, 2024
JPMorgan Chase & Co.:
HQLA
Eligible cash
(a)
$ 281,117
$ 308,298
$ 396,123
Eligible securities
(b)(c)
680,862
638,020
464,877
Total HQLA
(d)
$ 961,979
$ 946,318
$ 861,000
Net cash outflows
$ 868,500
$ 858,157
$ 763,648
LCR
111 %
110 %
113 %
Net excess eligible
HQLA
(d)
$ 93,479
$
88,161
$
97,352
JPMorgan Chase Bank, N.A.:
LCR
115 %
117 %
124 %
Net excess eligible
HQLA
$ 138,052
$ 152,886
$ 193,682
(a)
Represents cash on deposit at central banks, including the
Federal Reserve Banks.
(b)
Eligible HQLA securities may be reported in securities borrowed
or purchased under resale agreements, trading assets, or
investment securities on the Firm’s Consolidated balance sheets.
For purposes of calculating the LCR, HQLA securities are
included at fair value, which may differ from the accounting
treatment under U.S. GAAP.
(c)
Predominantly U.S. Treasuries, U.S. GSE and government
agency MBS, and sovereign bonds net of regulatory haircuts
under the LCR rule.
(d)
Excludes average excess eligible HQLA at JPMorgan Chase
Bank, N.A. that are not transferable to non-bank affiliates.
The Firm’s average LCR for the three months ended
December 31, 2025 decreased, compared with the
three months ended December 31, 2024, primarily
driven by repurchases of and dividends on common
stock, predominantly offset by dividend payments
from JPMorgan Chase Bank, N.A. to the Parent
Company and activities in CIB Markets.
JPMorgan Chase Bank, N.A.’s average LCR for the
three months ended December 31, 2025 decreased,
compared with the three months ended September
30, 2025, primarily due to higher lending levels, largely
offset by higher deposits, higher market values of
HQLA-eligible investment securities and long-term
debt issuance.
JPMorgan Chase Bank, N.A.’s average LCR for the
three months ended December 31, 2025 decreased,
compared with the three months ended December 31,
2024, driven by higher lending levels and dividend
payments to the Parent Company, largely offset by
higher deposits and higher market values of HQLA-
eligible investment securities.
JPMorgan Chase & Co./2025 Form 10-K
101
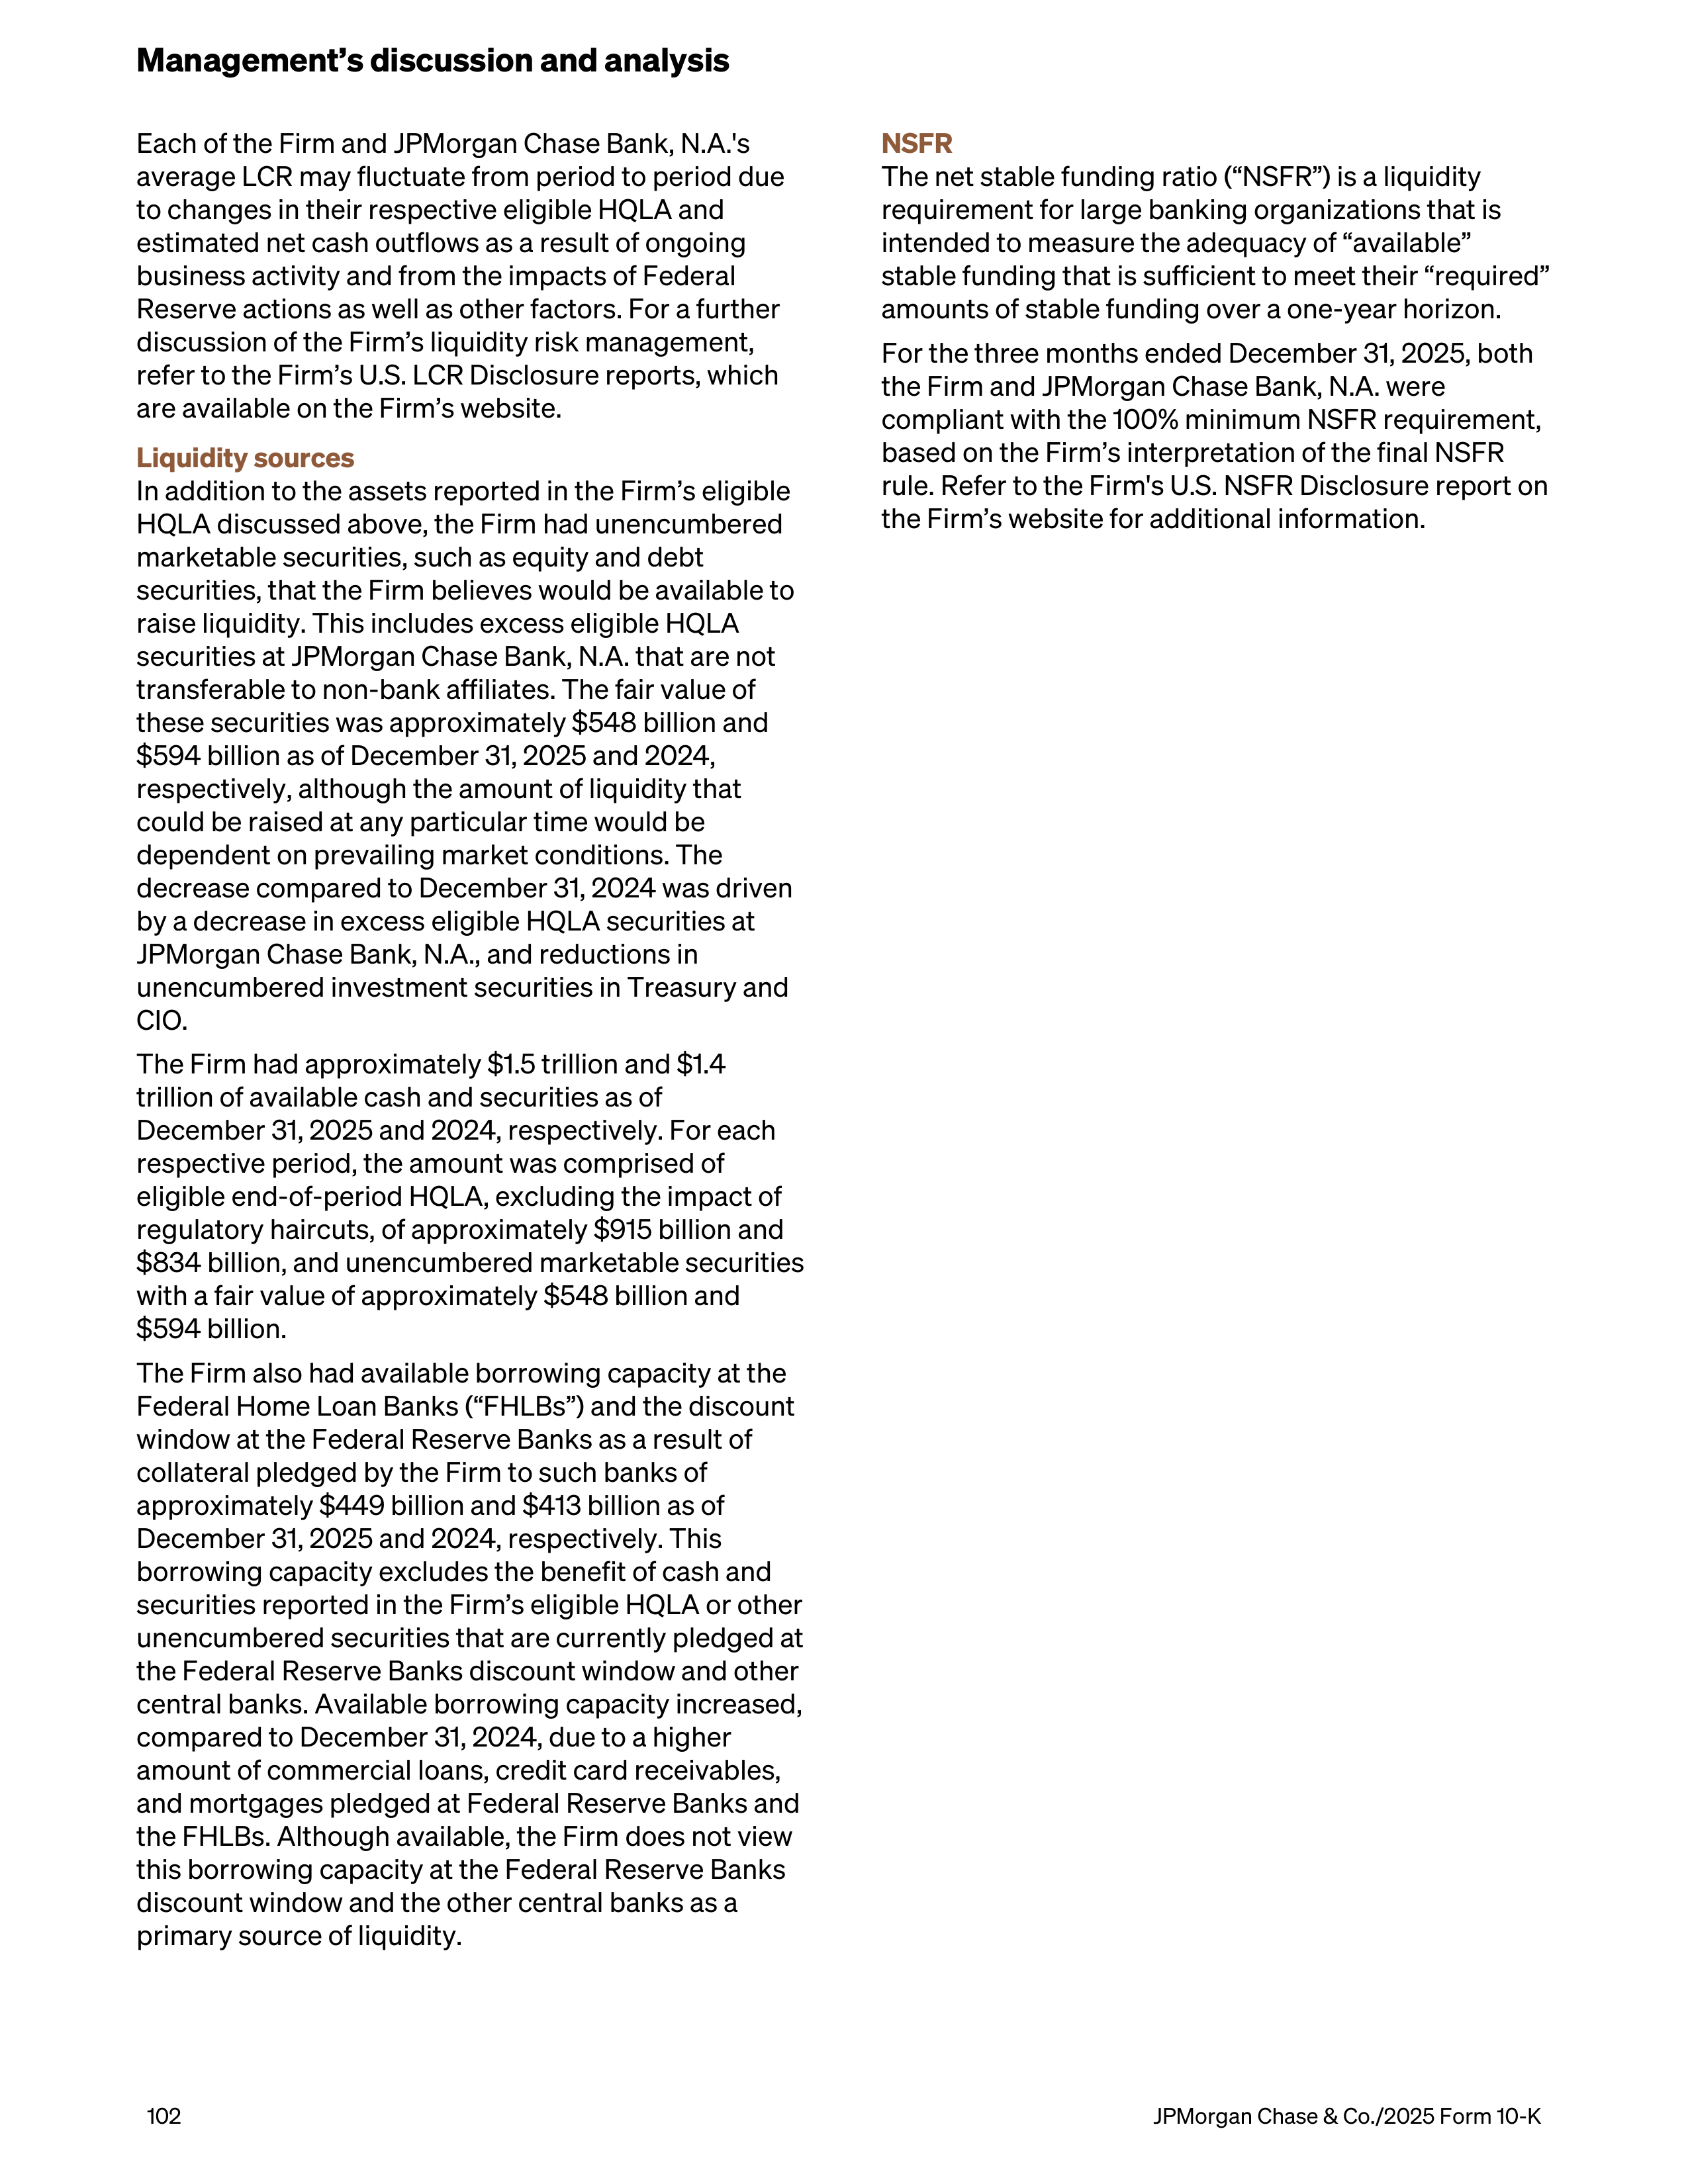
Each of the Firm and JPMorgan Chase Bank, N.A.'s
average LCR may fluctuate from period to period due
to changes in their respective eligible HQLA and
estimated net cash outflows as a result of ongoing
business activity and from the impacts of Federal
Reserve actions as well as other factors. For a further
discussion of the Firm’s liquidity risk management,
refer to the Firm’s U.S. LCR Disclosure reports, which
are available on the Firm’s website.
Liquidity sources
In addition to the assets reported in the Firm’s eligible
HQLA discussed above, the Firm had unencumbered
marketable securities, such as equity and debt
securities, that the Firm believes would be available to
raise liquidity. This includes excess eligible HQLA
securities at JPMorgan Chase Bank, N.A. that are not
transferable to non-bank affiliates. The fair value of
these securities was approximately $548 billion and
$594 billion as of December 31, 2025 and 2024,
respectively, although the amount of liquidity that
could be raised at any particular time would be
dependent on prevailing market conditions. The
decrease compared to December 31, 2024 was driven
by a decrease in excess eligible HQLA securities at
JPMorgan Chase Bank, N.A., and reductions in
unencumbered investment securities in Treasury and
CIO.
The Firm had approximately $1.5 trillion and $1.4
trillion of available cash and securities as of
December 31, 2025 and 2024, respectively. For each
respective period, the amount was comprised of
eligible end-of-period HQLA, excluding the impact of
regulatory haircuts, of approximately $915 billion and
$834 billion, and unencumbered marketable securities
with a fair value of approximately $548 billion and
$594 billion.
The Firm also had available borrowing capacity at the
Federal Home Loan Banks (“FHLBs”) and the discount
window at the Federal Reserve Banks as a result of
collateral pledged by the Firm to such banks of
approximately $449 billion and $413 billion as of
December 31, 2025 and 2024, respectively. This
borrowing capacity excludes the benefit of cash and
securities reported in the Firm’s eligible HQLA or other
unencumbered securities that are currently pledged at
the Federal Reserve Banks discount window and other
central banks. Available borrowing capacity increased,
compared to December 31, 2024, due to a higher
amount of commercial loans, credit card receivables,
and mortgages pledged at Federal Reserve Banks and
the FHLBs. Although available, the Firm does not view
this borrowing capacity at the Federal Reserve Banks
discount window and the other central banks as a
primary source of liquidity.
NSFR
The net stable funding ratio (“NSFR”) is a liquidity
requirement for large banking organizations that is
intended to measure the adequacy of “available”
stable funding that is sufficient to meet their “required”
amounts of stable funding over a one-year horizon.
For the three months ended December 31, 2025, both
the Firm and JPMorgan Chase Bank, N.A. were
compliant with the 100% minimum NSFR requirement,
based on the Firm’s interpretation of the final NSFR
rule. Refer to the Firm's U.S. NSFR Disclosure report on
the Firm’s website for additional information.
Management’s discussion and analysis
102
JPMorgan Chase & Co./2025 Form 10-K
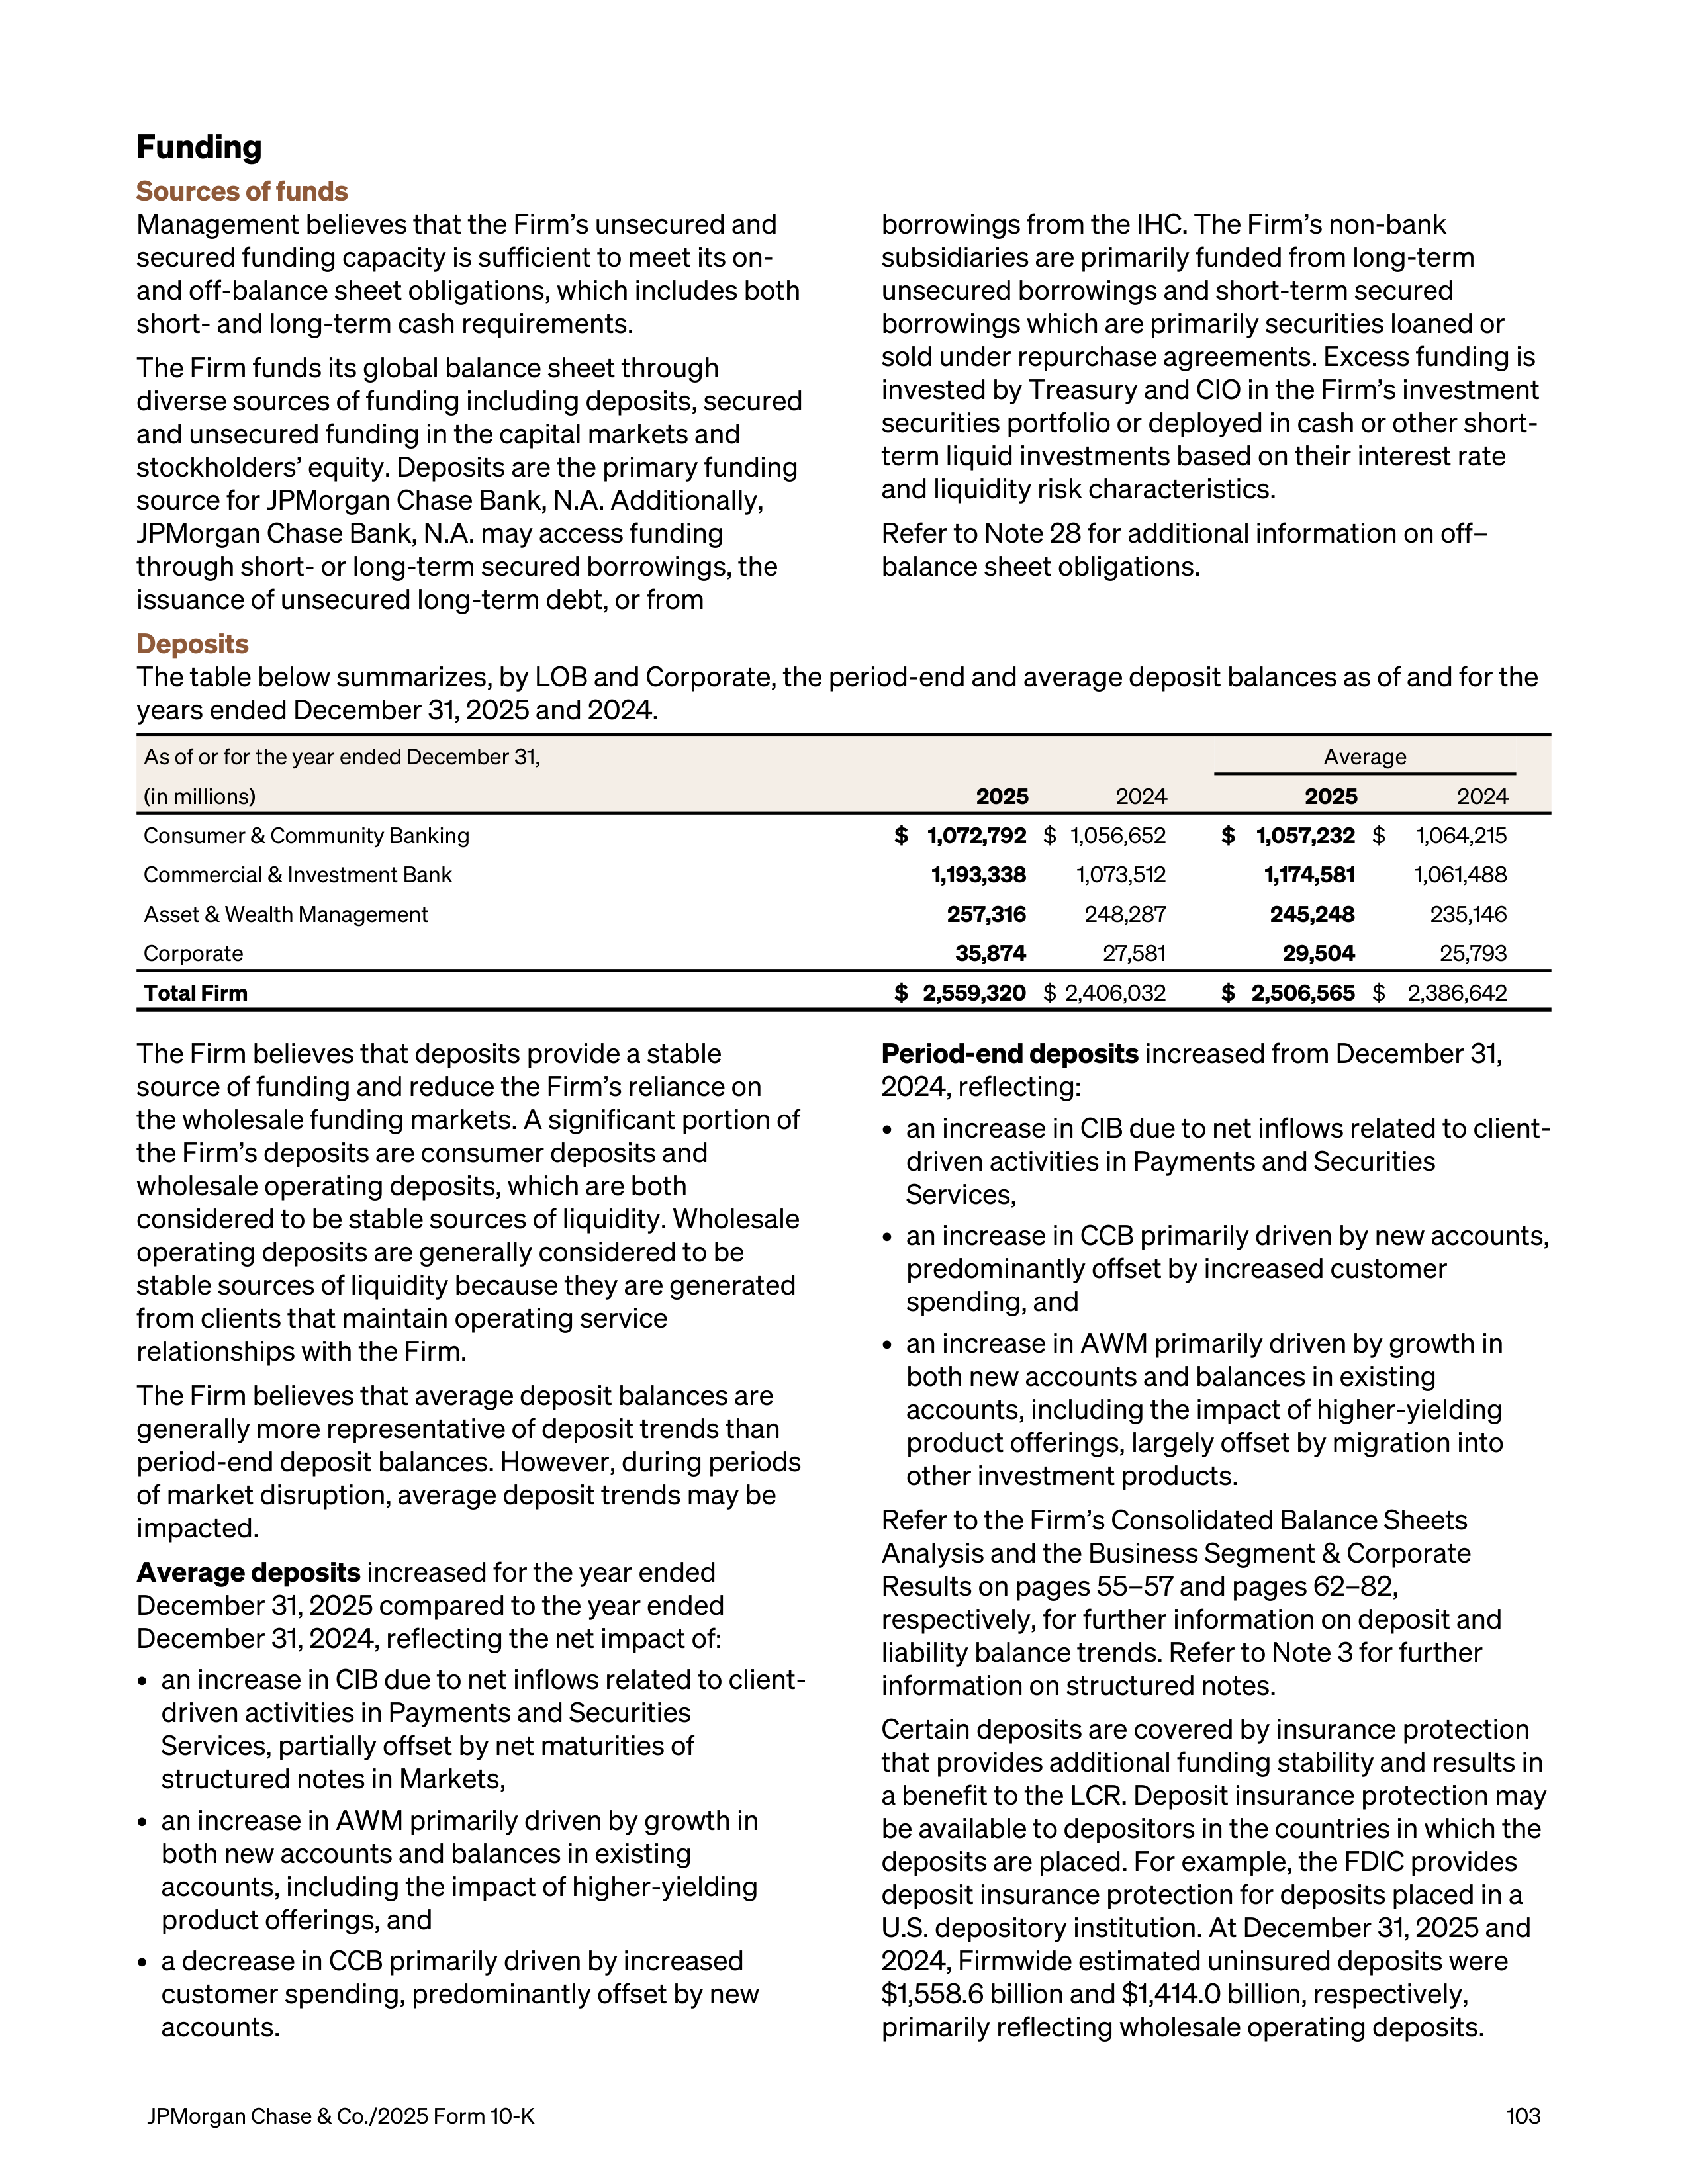
Funding
Sources of funds
Management believes that the Firm’s unsecured and
secured funding capacity is sufficient to meet its on-
and off-balance sheet obligations, which includes both
short- and long-term cash requirements.
The Firm funds its global balance sheet through
diverse sources of funding including deposits, secured
and unsecured funding in the capital markets and
stockholders’ equity. Deposits are the primary funding
source for JPMorgan Chase Bank, N.A. Additionally,
JPMorgan Chase Bank, N.A. may access funding
through short- or long-term secured borrowings, the
issuance of unsecured long-term debt, or from
borrowings from the IHC. The Firm’s non-bank
subsidiaries are primarily funded from long-term
unsecured borrowings and short-term secured
borrowings which are primarily securities loaned or
sold under repurchase agreements. Excess funding is
invested by Treasury and CIO in the Firm’s investment
securities portfolio or deployed in cash or other short-
term liquid investments based on their interest rate
and liquidity risk characteristics.
Refer to Note 28 for additional information on off–
balance sheet obligations.
Deposits
The table below summarizes, by LOB and Corporate, the period-end and average deposit balances as of and for the
years ended December 31, 2025 and 2024.
As of or for the year ended December 31,
Average
(in millions)
2025
2024
2025
2024
Consumer & Community Banking
$ 1,072,792
$ 1,056,652
$ 1,057,232
$
1,064,215
Commercial & Investment Bank
1,193,338
1,073,512
1,174,581
1,061,488
Asset & Wealth Management
257,316
248,287
245,248
235,146
Corporate
35,874
27,581
29,504
25,793
Total Firm
$ 2,559,320
$ 2,406,032
$ 2,506,565
$
2,386,642
The Firm believes that deposits provide a stable
source of funding and reduce the Firm’s reliance on
the wholesale funding markets. A significant portion of
the Firm’s deposits are consumer deposits and
wholesale operating deposits, which are both
considered to be stable sources of liquidity. Wholesale
operating deposits are generally considered to be
stable sources of liquidity because they are generated
from clients that maintain operating service
relationships with the Firm.
The Firm believes that average deposit balances are
generally more representative of deposit trends than
period-end deposit balances. However, during periods
of market disruption, average deposit trends may be
impacted.
Average deposits
increased
for the year ended
December 31, 2025 compared to the year ended
December 31, 2024, reflecting the net impact of:
•
an increase in CIB due to net inflows related to client-
driven activities in Payments
and Securities
Services, partially offset by net maturities of
structured notes in Markets,
•
an increase in AWM primarily driven by growth in
both new accounts and balances in existing
accounts, including the impact of higher-yielding
product offerings, and
•
a decrease in CCB primarily driven by increased
customer spending, predominantly offset by new
accounts.
Period-end deposits
increased from December 31,
2024, reflecting:
•
an increase in CIB due to net inflows related to client-
driven activities in Payments and Securities
Services,
•
an increase in CCB primarily driven by new accounts,
predominantly offset by increased customer
spending, and
•
an increase in AWM primarily driven by growth in
both new accounts and balances in existing
accounts, including the impact of higher-yielding
product offerings, largely offset by migration into
other investment products.
Refer to the Firm’s Consolidated Balance Sheets
Analysis and the Business Segment & Corporate
Results on pages 55–57 and pages 62–82,
respectively, for further information on deposit and
liability balance trends. Refer to Note 3 for further
information on structured notes.
Certain deposits are covered by insurance protection
that provides additional funding stability and results in
a benefit to the LCR. Deposit insurance protection may
be available to depositors in the countries in which the
deposits are placed. For example, the FDIC provides
deposit insurance protection for deposits placed in a
U.S. depository institution. At December 31, 2025 and
2024, Firmwide estimated uninsured deposits were
$1,558.6 billion and $1,414.0 billion, respectively,
primarily reflecting wholesale operating deposits.
JPMorgan Chase & Co./2025 Form 10-K
103
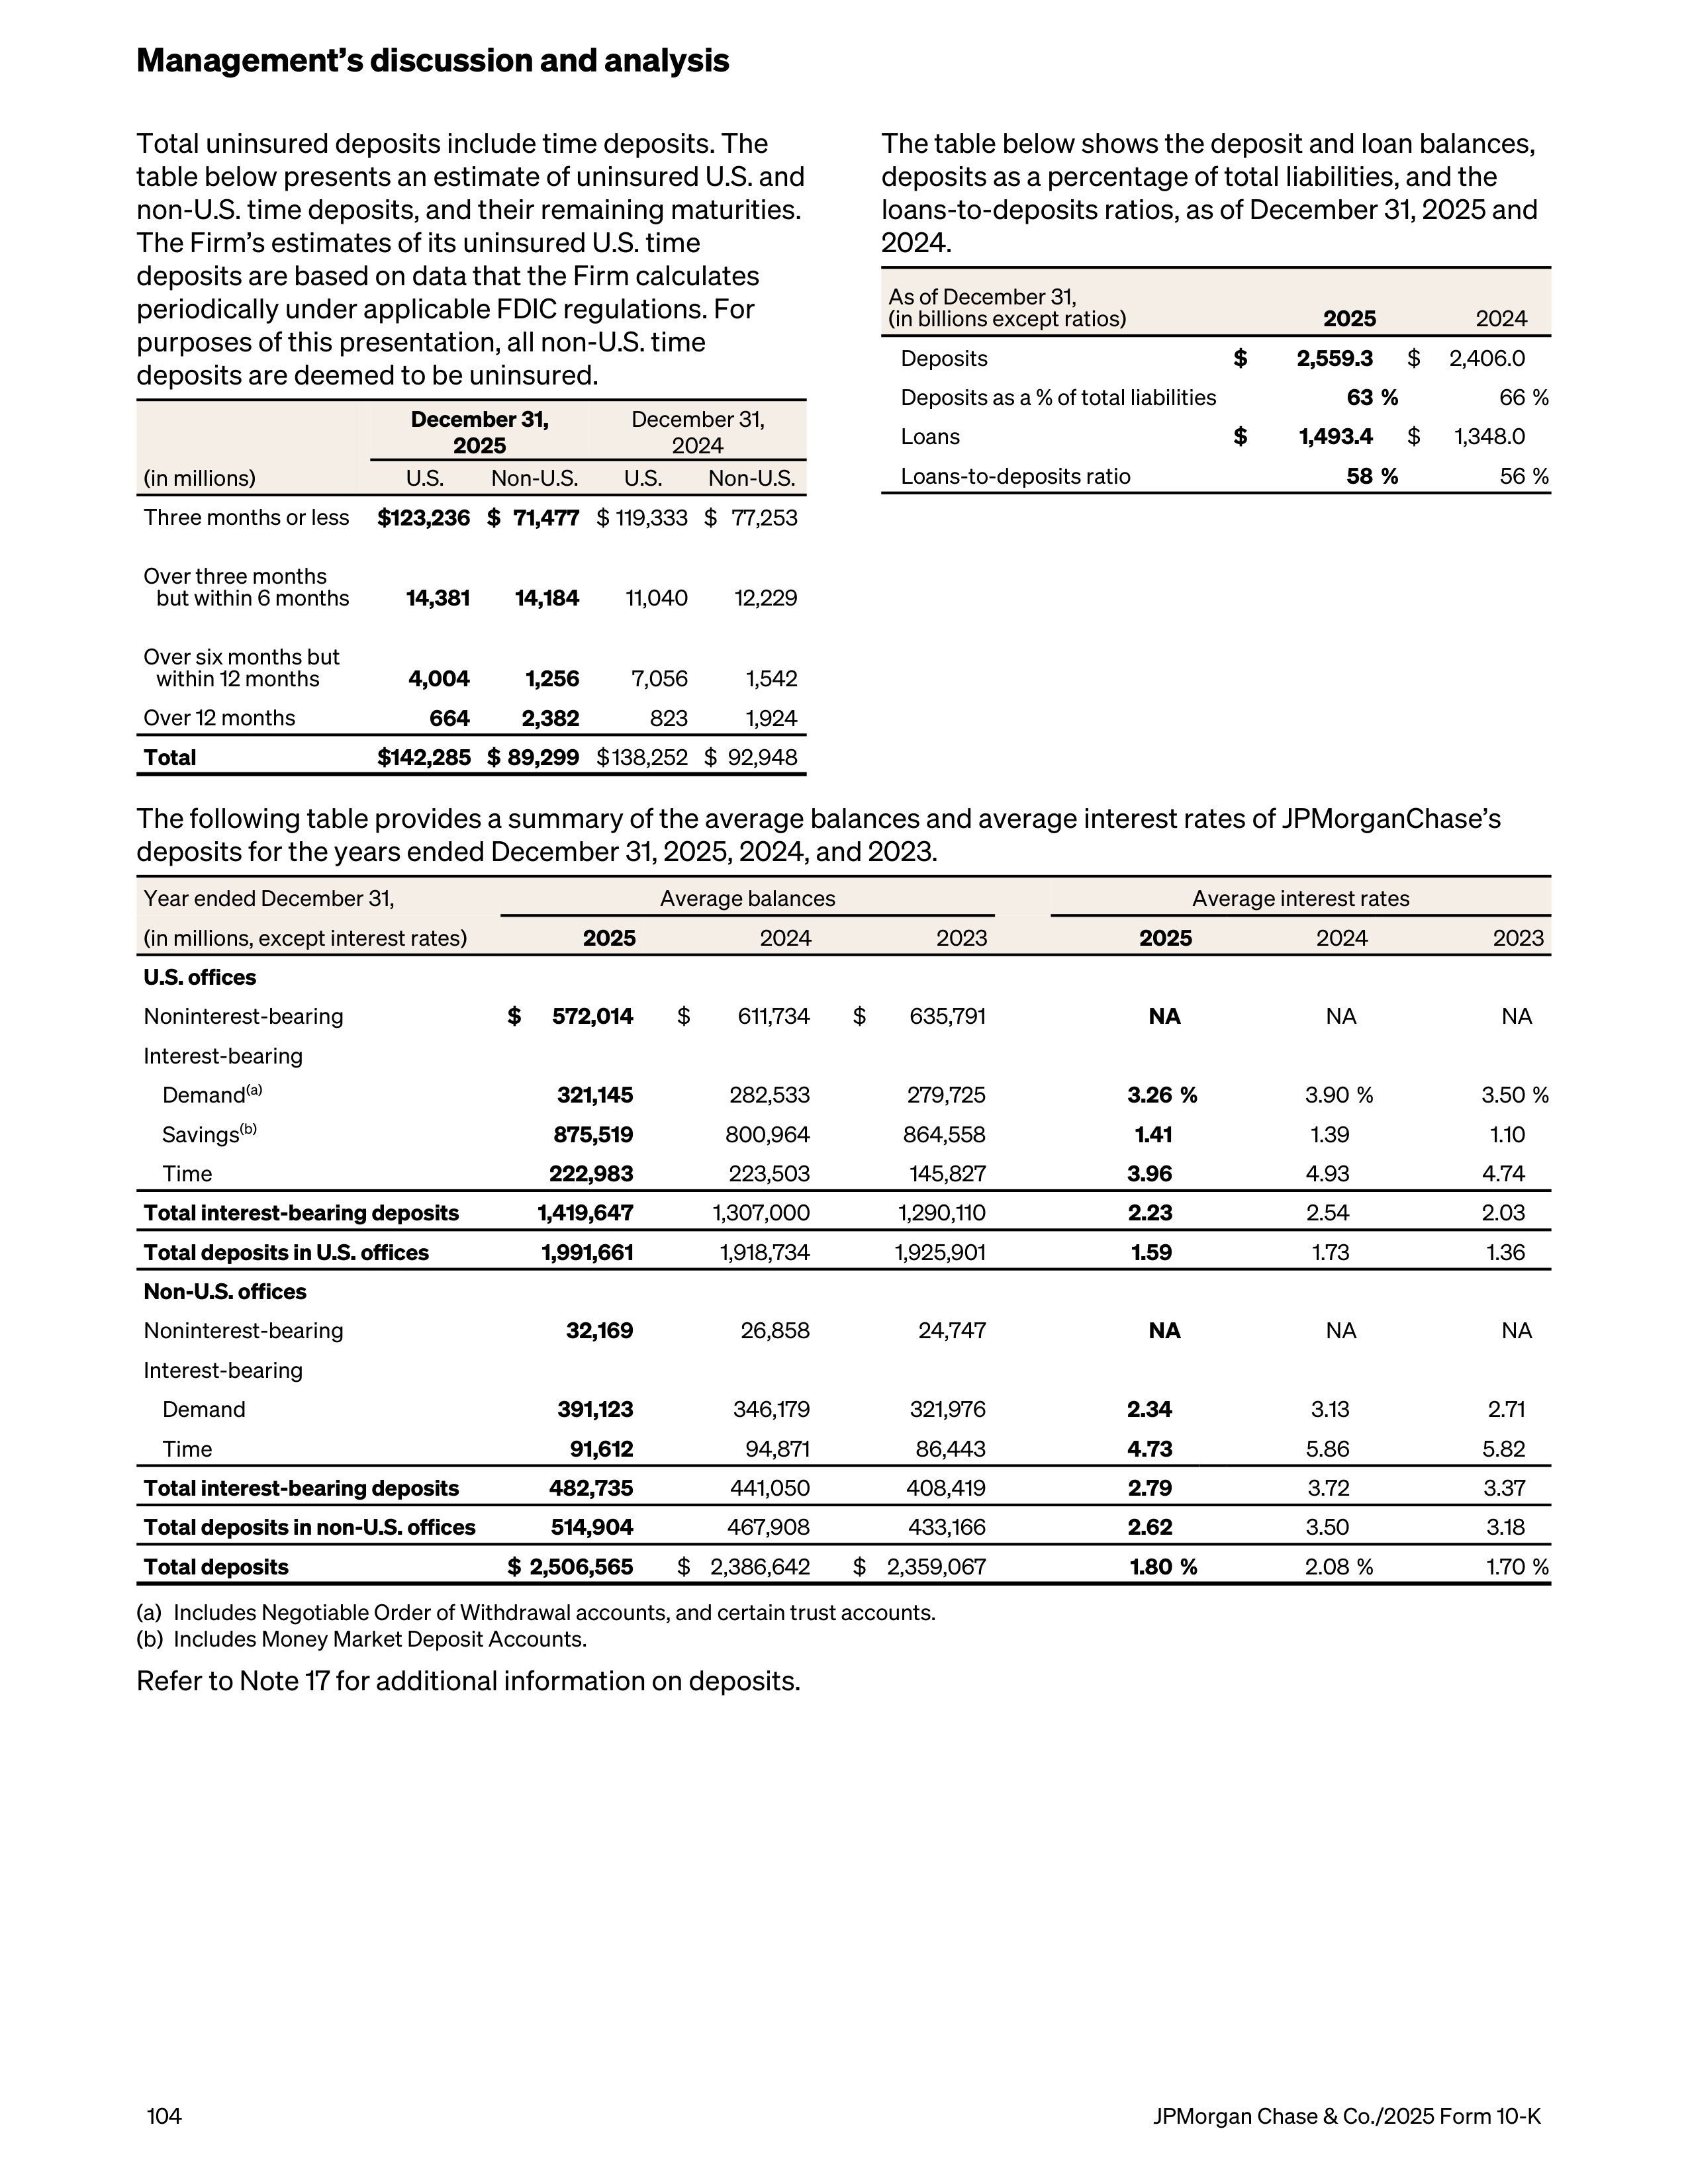
Total uninsured deposits include time deposits. The
table below presents an estimate of uninsured U.S. and
non-U.S. time deposits, and their remaining maturities.
The Firm’s estimates of its uninsured U.S. time
deposits are based on data that the Firm calculates
periodically under applicable FDIC regulations. For
purposes of this presentation, all non-U.S. time
deposits are deemed to be uninsured.
(in millions)
December 31,
2025
December 31,
2024
U.S.
Non-U.S.
U.S.
Non-U.S.
Three months or less
$ 123,236 $ 71,477
$ 119,333 $ 77,253
Over three months
but within 6 months
14,381
14,184
11,040
12,229
Over six months but
within 12 months
4,004
1,256
7,056
1,542
Over 12 months
664
2,382
823
1,924
Total
$ 142,285 $ 89,299
$ 138,252 $ 92,948
The table below shows the deposit and loan balances,
deposits as a percentage of total liabilities, and the
loans-to-deposits ratios, as of December 31, 2025 and
2024.
As of December 31,
(in billions except ratios)
2025
2024
Deposits
$
2,559.3
$
2,406.0
Deposits as a % of total liabilities
63 %
66 %
Loans
$
1,493.4
$
1,348.0
Loans-to-deposits ratio
58 %
56 %
The following table provides a summary of the average balances and average interest rates of JPMorganChase’s
deposits for the years ended December 31, 2025, 2024, and 2023.
Year ended December 31,
Average balances
Average interest rates
(in millions, except interest rates)
2025
2024
2023
2025
2024
2023
U.S. offices
Noninterest-bearing
$
572,014
$
611,734
$
635,791
NA
NA
NA
Interest-bearing
Demand
(a)
321,145
282,533
279,725
3.26 %
3.90 %
3.50 %
Savings
(b)
875,519
800,964
864,558
1.41
1.39
1.10
Time
222,983
223,503
145,827
3.96
4.93
4.74
Total interest-bearing deposits
1,419,647
1,307,000
1,290,110
2.23
2.54
2.03
Total deposits in U.S. offices
1,991,661
1,918,734
1,925,901
1.59
1.73
1.36
Non-U.S. offices
Noninterest-bearing
32,169
26,858
24,747
NA
NA
NA
Interest-bearing
Demand
391,123
346,179
321,976
2.34
3.13
2.71
Time
91,612
94,871
86,443
4.73
5.86
5.82
Total interest-bearing deposits
482,735
441,050
408,419
2.79
3.72
3.37
Total deposits in non-U.S. offices
514,904
467,908
433,166
2.62
3.50
3.18
Total deposits
$ 2,506,565
$ 2,386,642
$ 2,359,067
1.80 %
2.08 %
1.70 %
(a)
Includes Negotiable Order of Withdrawal accounts, and certain trust accounts.
(b)
Includes Money Market Deposit Accounts.
Refer to Note 17 for additional information on deposits.
Management’s discussion and analysis
104
JPMorgan Chase & Co./2025 Form 10-K
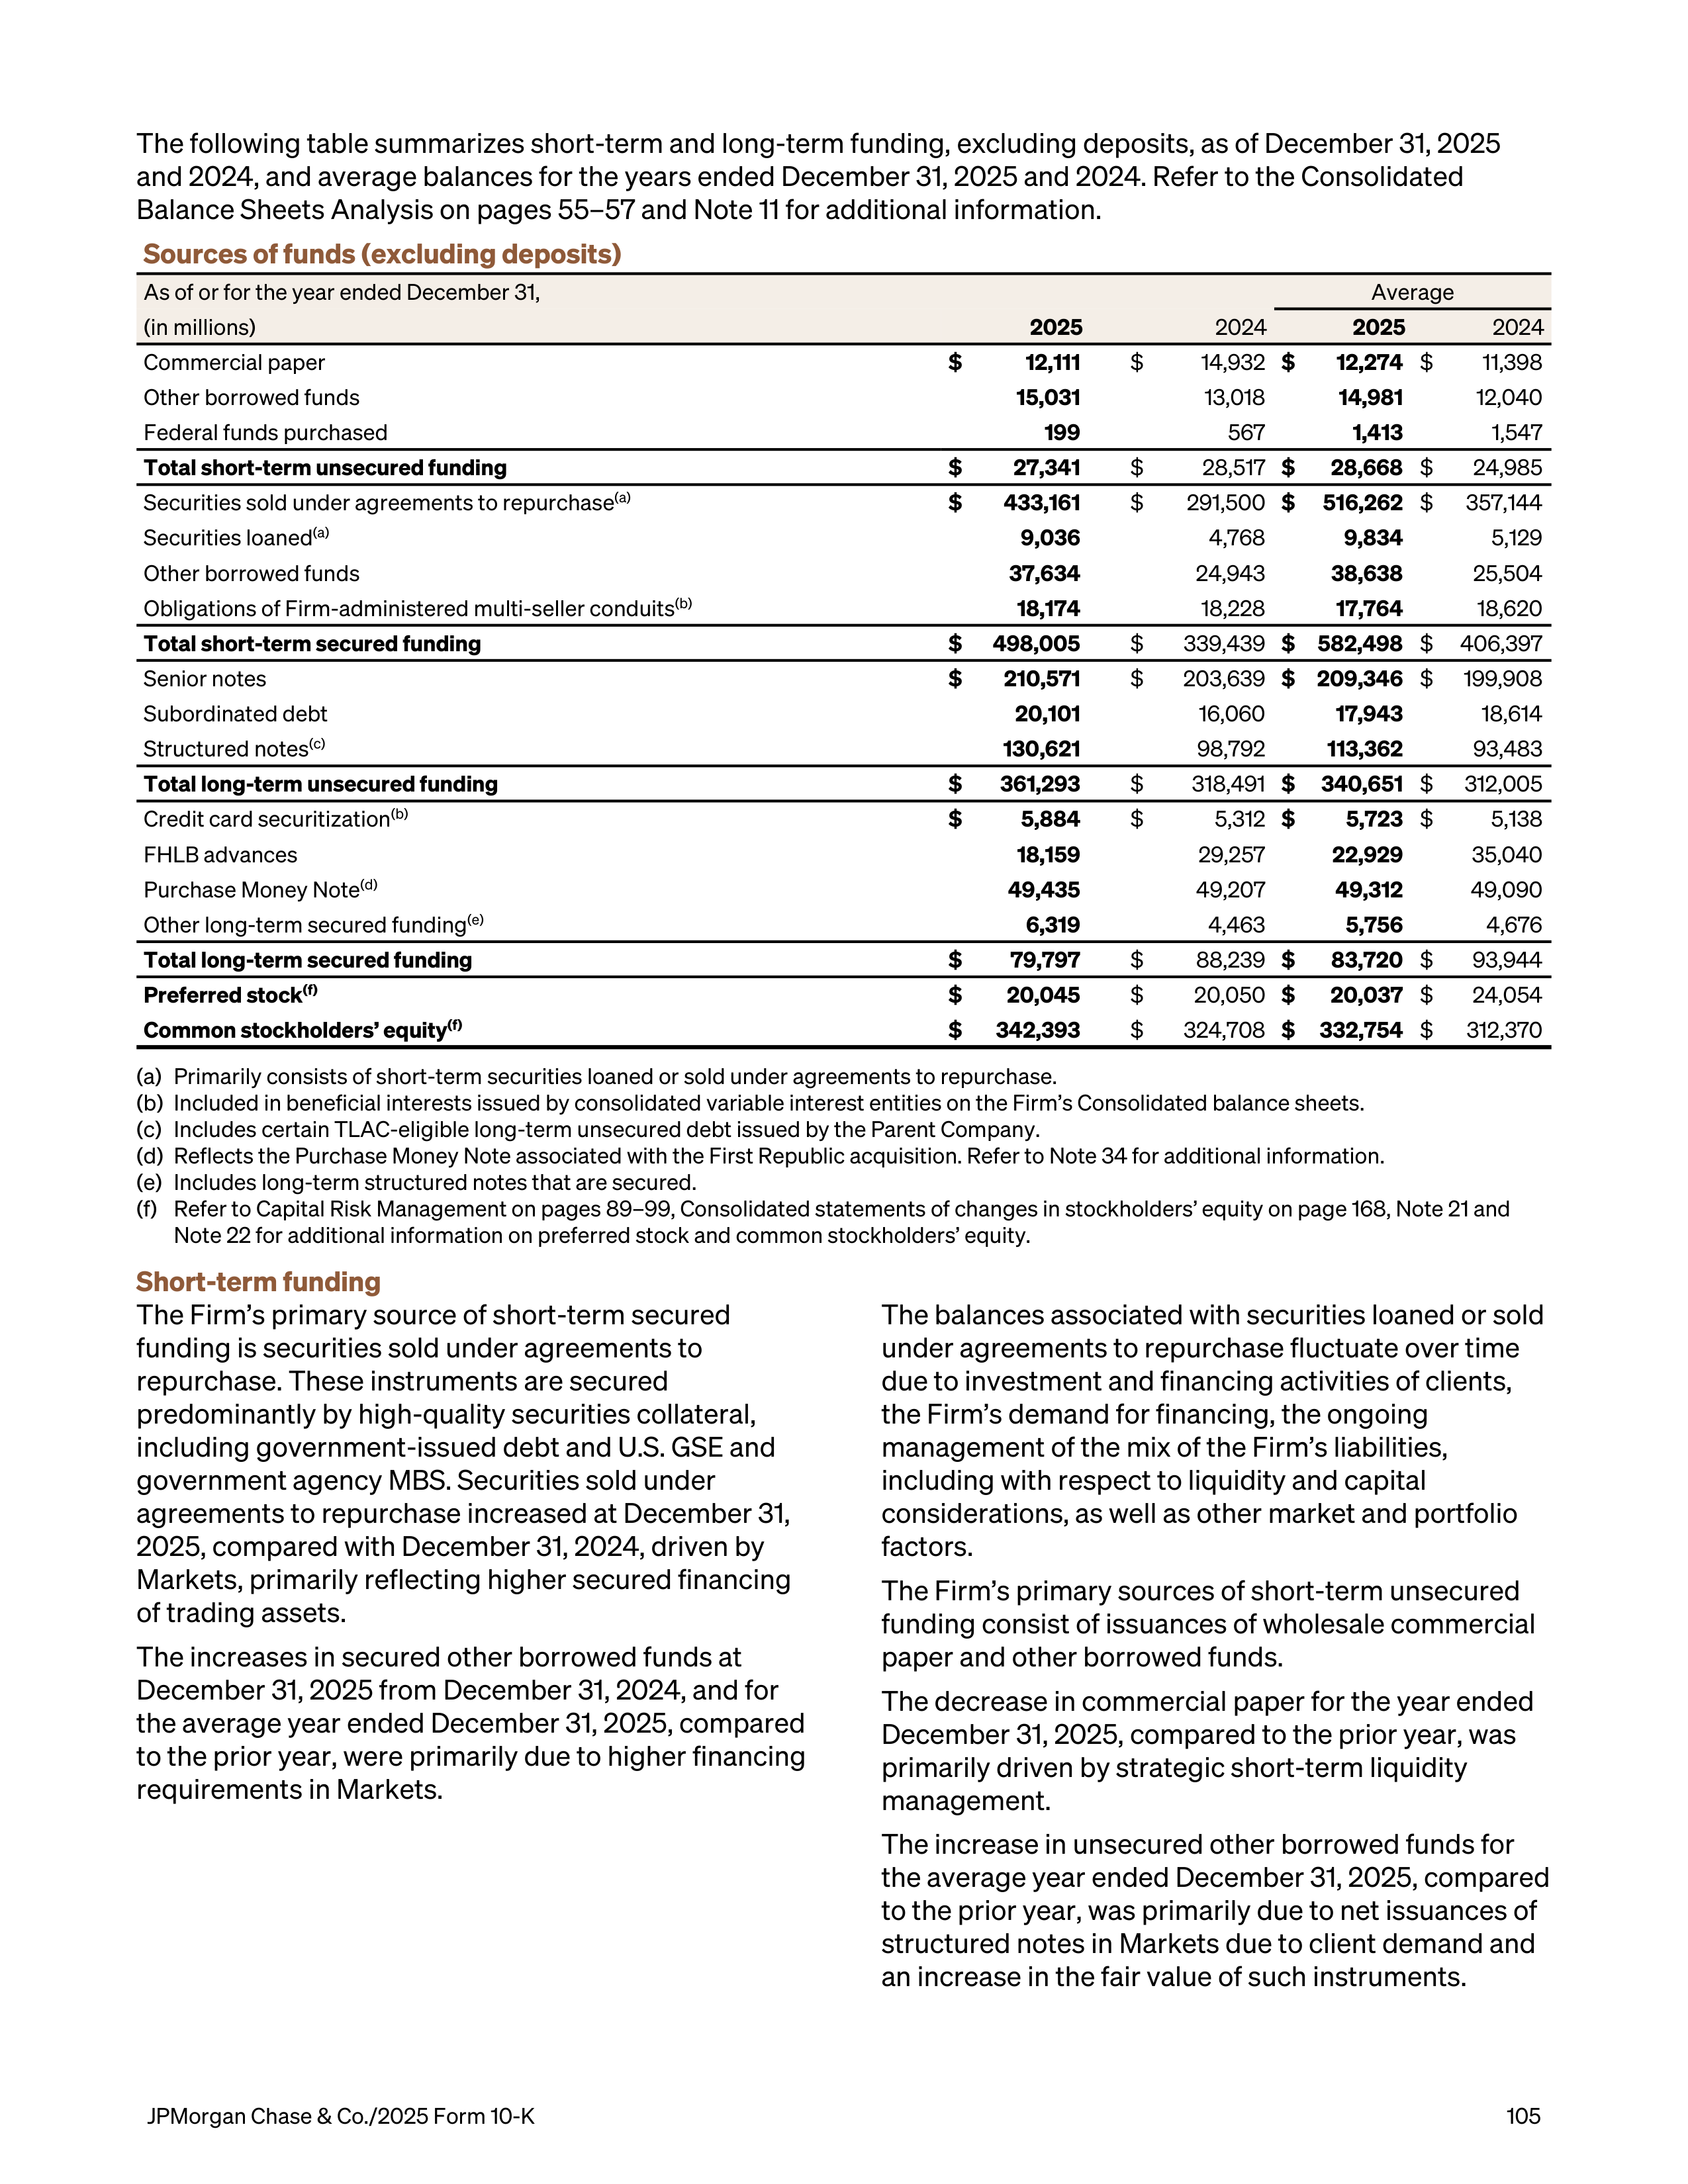
The following table summarizes short-term and long-term funding, excluding deposits, as of December 31, 2025
and 2024, and average balances for the years ended December 31, 2025 and 2024. Refer to the Consolidated
Balance Sheets Analysis on pages 55–57 and Note 11 for additional information.
Sources of funds (excluding deposits)
As of or for the year ended December 31,
Average
(in millions)
2025
2024
2025
2024
Commercial paper
$
12,111
$
14,932
$
12,274
$
11,398
Other borrowed funds
15,031
13,018
14,981
12,040
Federal funds purchased
199
567
1,413
1,547
Total short-term unsecured funding
$
27,341
$
28,517
$
28,668
$
24,985
Securities sold under agreements to repurchase
(a)
$
433,161
$
291,500
$
516,262
$
357,144
Securities loaned
(a)
9,036
4,768
9,834
5,129
Other borrowed funds
37,634
24,943
38,638
25,504
Obligations of Firm-administered multi-seller conduits
(b)
18,174
18,228
17,764
18,620
Total short-term secured funding
$
498,005
$
339,439
$
582,498
$
406,397
Senior notes
$
210,571
$
203,639
$
209,346
$
199,908
Subordinated debt
20,101
16,060
17,943
18,614
Structured notes
(c)
130,621
98,792
113,362
93,483
Total long-term unsecured funding
$
361,293
$
318,491
$
340,651
$
312,005
Credit card securitization
(b)
$
5,884
$
5,312
$
5,723
$
5,138
FHLB advances
18,159
29,257
22,929
35,040
Purchase Money Note
(d)
49,435
49,207
49,312
49,090
Other long-term secured funding
(e)
6,319
4,463
5,756
4,676
Total long-term secured funding
$
79,797
$
88,239
$
83,720
$
93,944
Preferred stock
(f)
$
20,045
$
20,050
$
20,037
$
24,054
Common stockholders’ equity
(f)
$
342,393
$
324,708
$
332,754
$
312,370
(a)
Primarily consists of short-term securities loaned or sold under agreements to repurchase.
(b)
Included in beneficial interests issued by consolidated variable interest entities on the Firm’s Consolidated balance sheets.
(c)
Includes certain TLAC-eligible long-term unsecured debt issued by the Parent Company.
(d)
Reflects the Purchase Money Note associated with the First Republic acquisition. Refer to Note 34 for additional information.
(e)
Includes long-term structured notes that are secured.
(f)
Refer to Capital Risk Management on pages 89–99, Consolidated statements of changes in stockholders’ equity on page 168, Note 21 and
Note 22 for additional information on preferred stock and common stockholders’ equity.
Short-term funding
The Firm’s primary source of short-term secured
funding is securities sold under agreements to
repurchase. These instruments are secured
predominantly by high-quality securities collateral,
including government-issued debt and U.S. GSE and
government agency MBS. Securities sold under
agreements to repurchase increased at December 31,
2025, compared with December 31, 2024, driven by
Markets, primarily reflecting higher secured financing
of trading assets.
The increases in secured other borrowed funds at
December 31, 2025 from December 31, 2024, and for
the average year ended December 31, 2025, compared
to the prior year, were primarily due to higher financing
requirements in Markets.
The balances associated with securities loaned or sold
under agreements to repurchase fluctuate over time
due to investment and financing activities of clients,
the Firm’s demand for financing, the ongoing
management of the mix of the Firm’s liabilities,
including with respect to liquidity and capital
considerations, as well as other market and portfolio
factors.
The Firm’s primary sources of short-term unsecured
funding consist of issuances of wholesale commercial
paper and other borrowed funds.
The decrease in commercial paper for the year ended
December 31, 2025, compared to the prior year, was
primarily driven by strategic short-term liquidity
management.
The increase in unsecured other borrowed funds for
the average year ended December 31, 2025, compared
to the prior year, was primarily due to net issuances of
structured notes in Markets due to client demand and
an increase in the fair value of such instruments.
JPMorgan Chase & Co./2025 Form 10-K
105
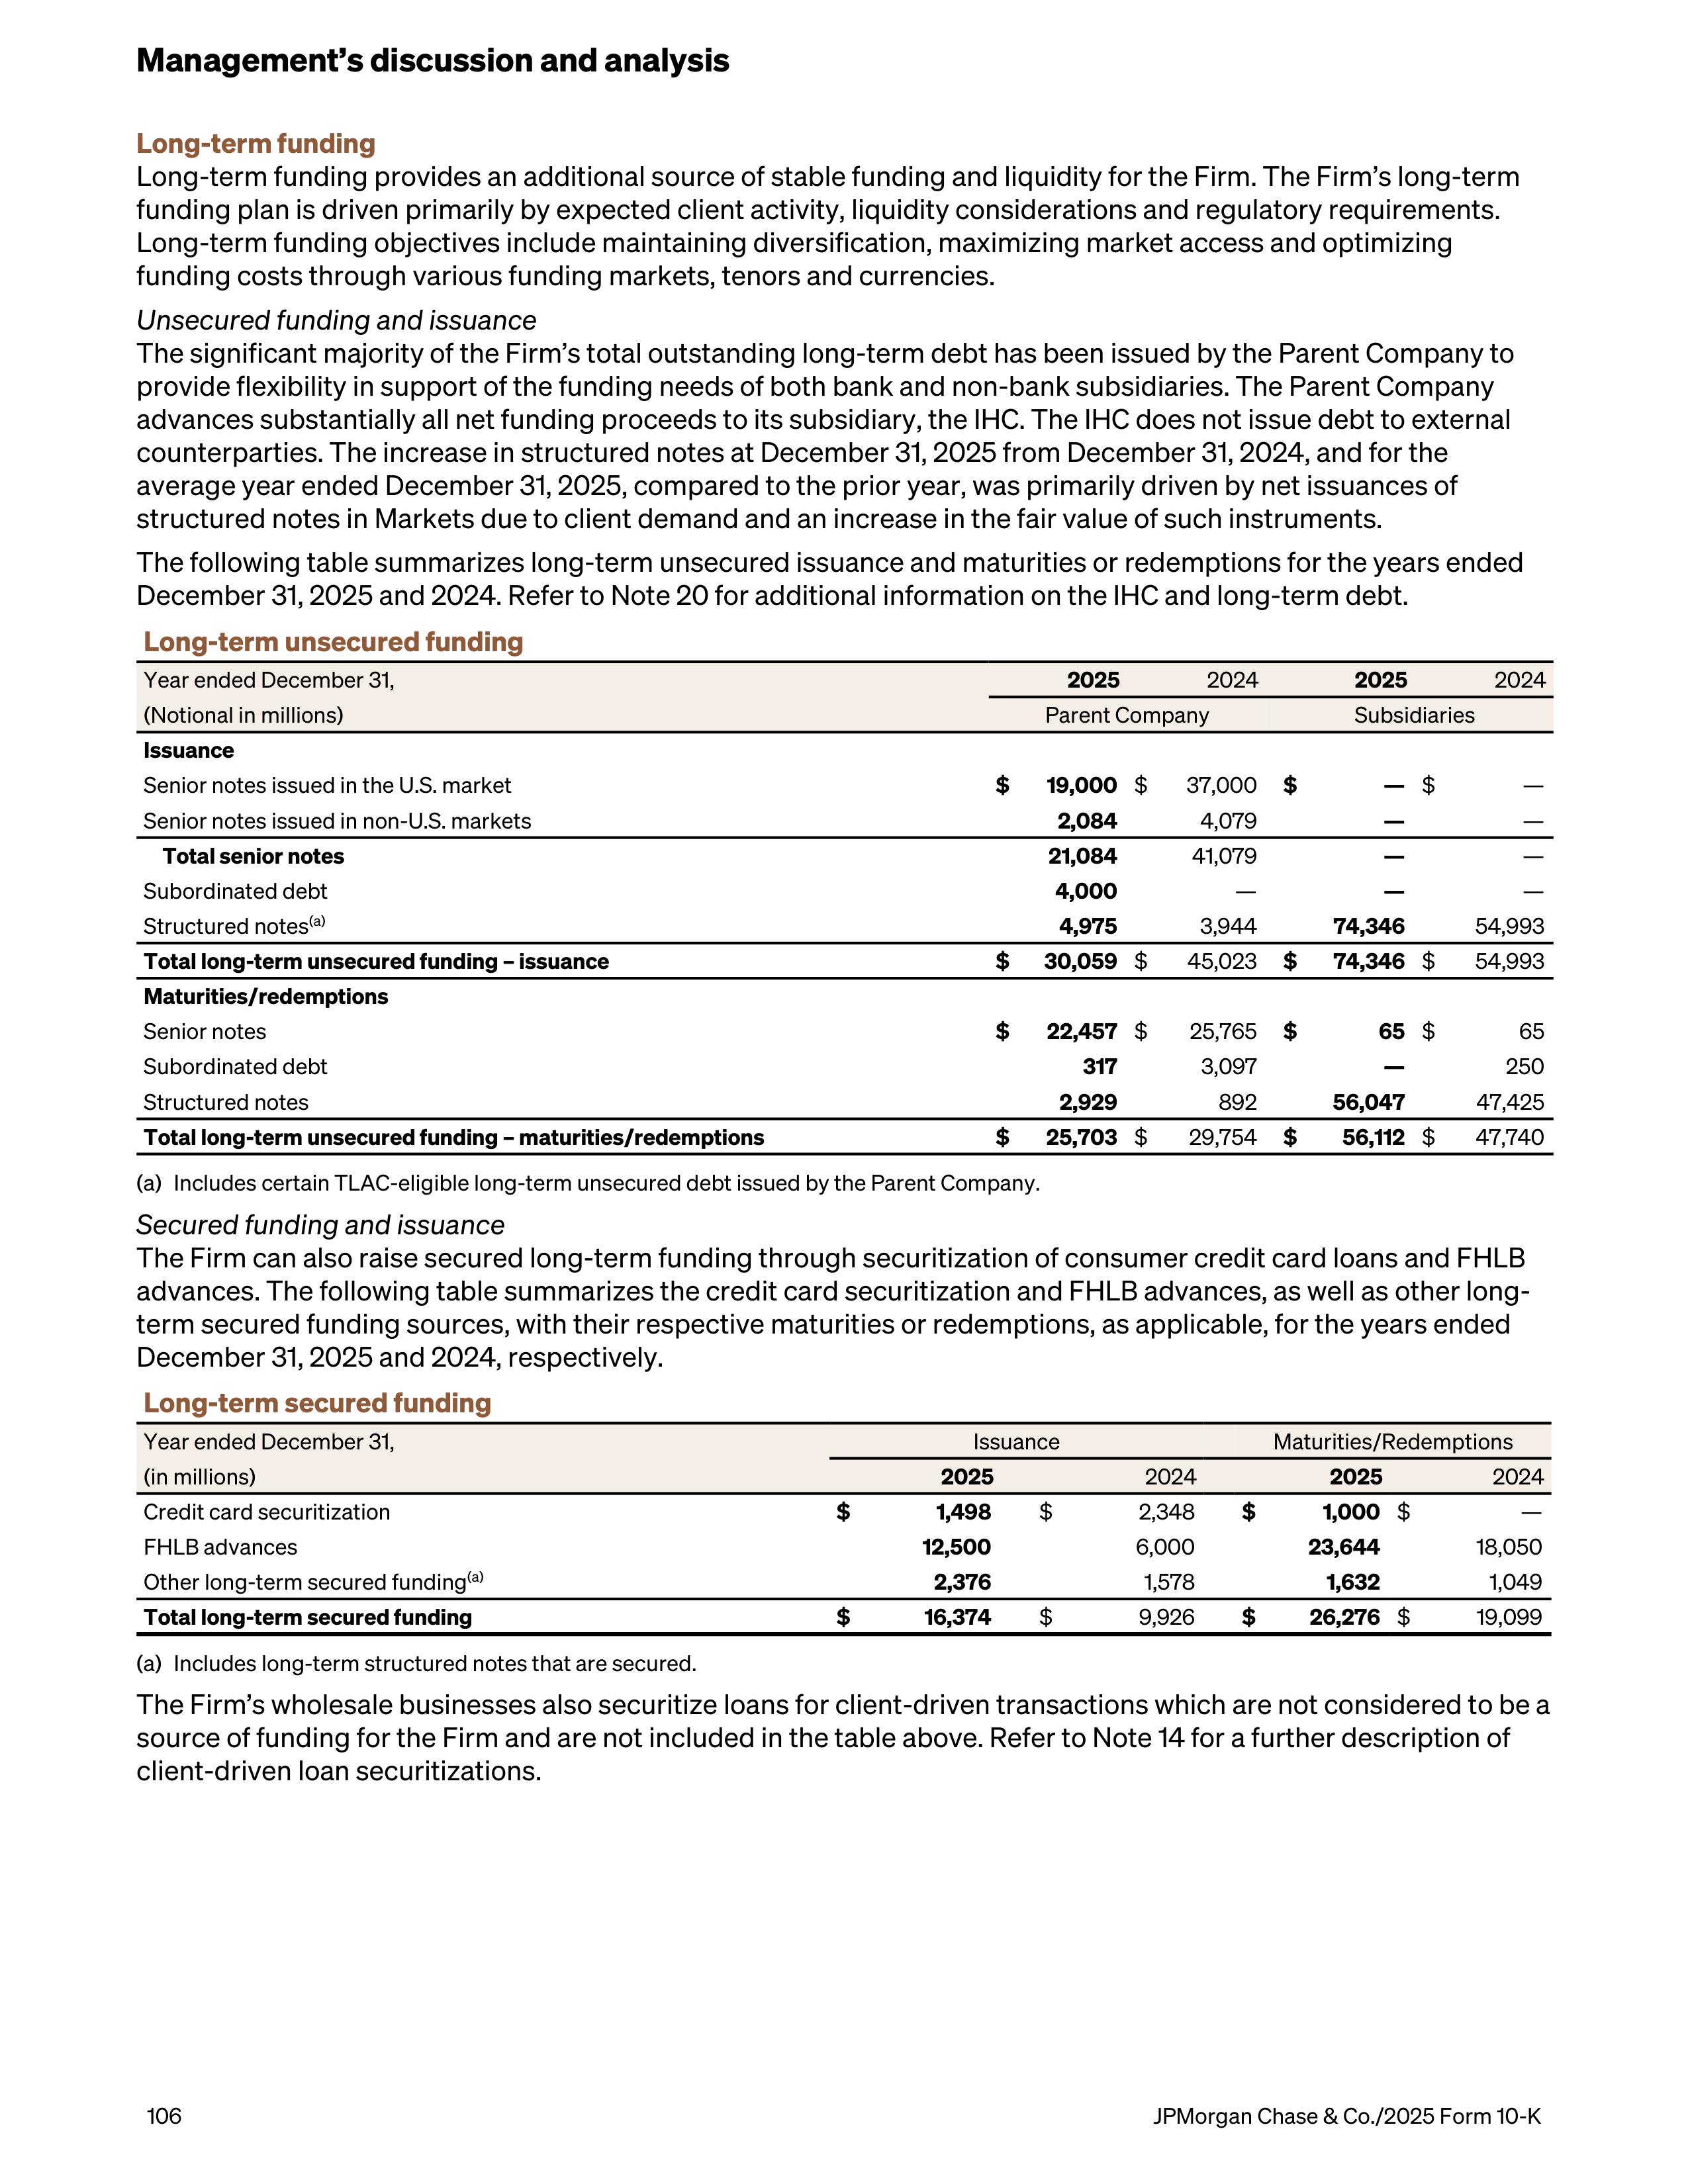
Long-term funding
Long-term funding provides an additional source of stable funding and liquidity for the Firm. The Firm’s long-term
funding plan is driven primarily by expected client activity, liquidity considerations and regulatory requirements.
Long-term funding objectives include maintaining diversification, maximizing market access and optimizing
funding costs through various funding markets, tenors and currencies.
Unsecured funding and issuance
The significant majority of the Firm’s total outstanding long-term debt has been issued by the Parent Company to
provide flexibility in support of the funding needs of both bank and non-bank subsidiaries. The Parent Company
advances substantially all net funding proceeds to its subsidiary, the IHC. The IHC does not issue debt to external
counterparties. The increase in structured notes at December 31, 2025 from December 31, 2024, and for the
average year ended December 31, 2025, compared to the prior year, was primarily driven by net issuances of
structured notes in Markets due to client demand and an increase in the fair value of such instruments.
The following table summarizes long-term unsecured issuance and maturities or redemptions for the years ended
December 31, 2025 and 2024. Refer to Note 20 for additional information on the IHC and long-term debt.
Long-term unsecured funding
Year ended December 31,
2025
2024
2025
2024
(Notional in millions)
Parent Company
Subsidiaries
Issuance
Senior notes issued in the U.S. market
$
19,000
$
37,000
$
—
$
—
Senior notes issued in non-U.S. markets
2,084
4,079
—
—
Total senior notes
21,084
41,079
—
—
Subordinated debt
4,000
—
—
—
Structured notes
(a)
4,975
3,944
74,346
54,993
Total long-term unsecured funding – issuance
$
30,059
$
45,023
$
74,346
$
54,993
Maturities/redemptions
Senior notes
$
22,457
$
25,765
$
65
$
65
Subordinated debt
317
3,097
—
250
Structured notes
2,929
892
56,047
47,425
Total long-term unsecured funding – maturities/redemptions
$
25,703
$
29,754
$
56,112
$
47,740
(a)
Includes certain TLAC-eligible long-term unsecured debt issued by the Parent Company.
Secured funding and issuance
The Firm can also raise secured long-term funding through securitization of consumer credit card loans and FHLB
advances. The following table summarizes the credit card securitization and FHLB advances, as well as other long-
term secured funding sources, with their respective maturities or redemptions, as applicable, for the years ended
December 31, 2025 and 2024, respectively.
Long-term secured funding
Year ended December 31,
Issuance
Maturities/Redemptions
(in millions)
2025
2024
2025
2024
Credit card securitization
$
1,498
$
2,348
$
1,000
$
—
FHLB advances
12,500
6,000
23,644
18,050
Other long-term secured funding
(a)
2,376
1,578
1,632
1,049
Total long-term secured funding
$
16,374
$
9,926
$
26,276
$
19,099
(a)
Includes long-term structured notes that are secured.
The Firm’s wholesale businesses also securitize loans for client-driven transactions which are not considered to be a
source of funding for the Firm and are not included in the table above. Refer to Note 14 for a further description of
client-driven loan securitizations.
Management’s discussion and analysis
106
JPMorgan Chase & Co./2025 Form 10-K
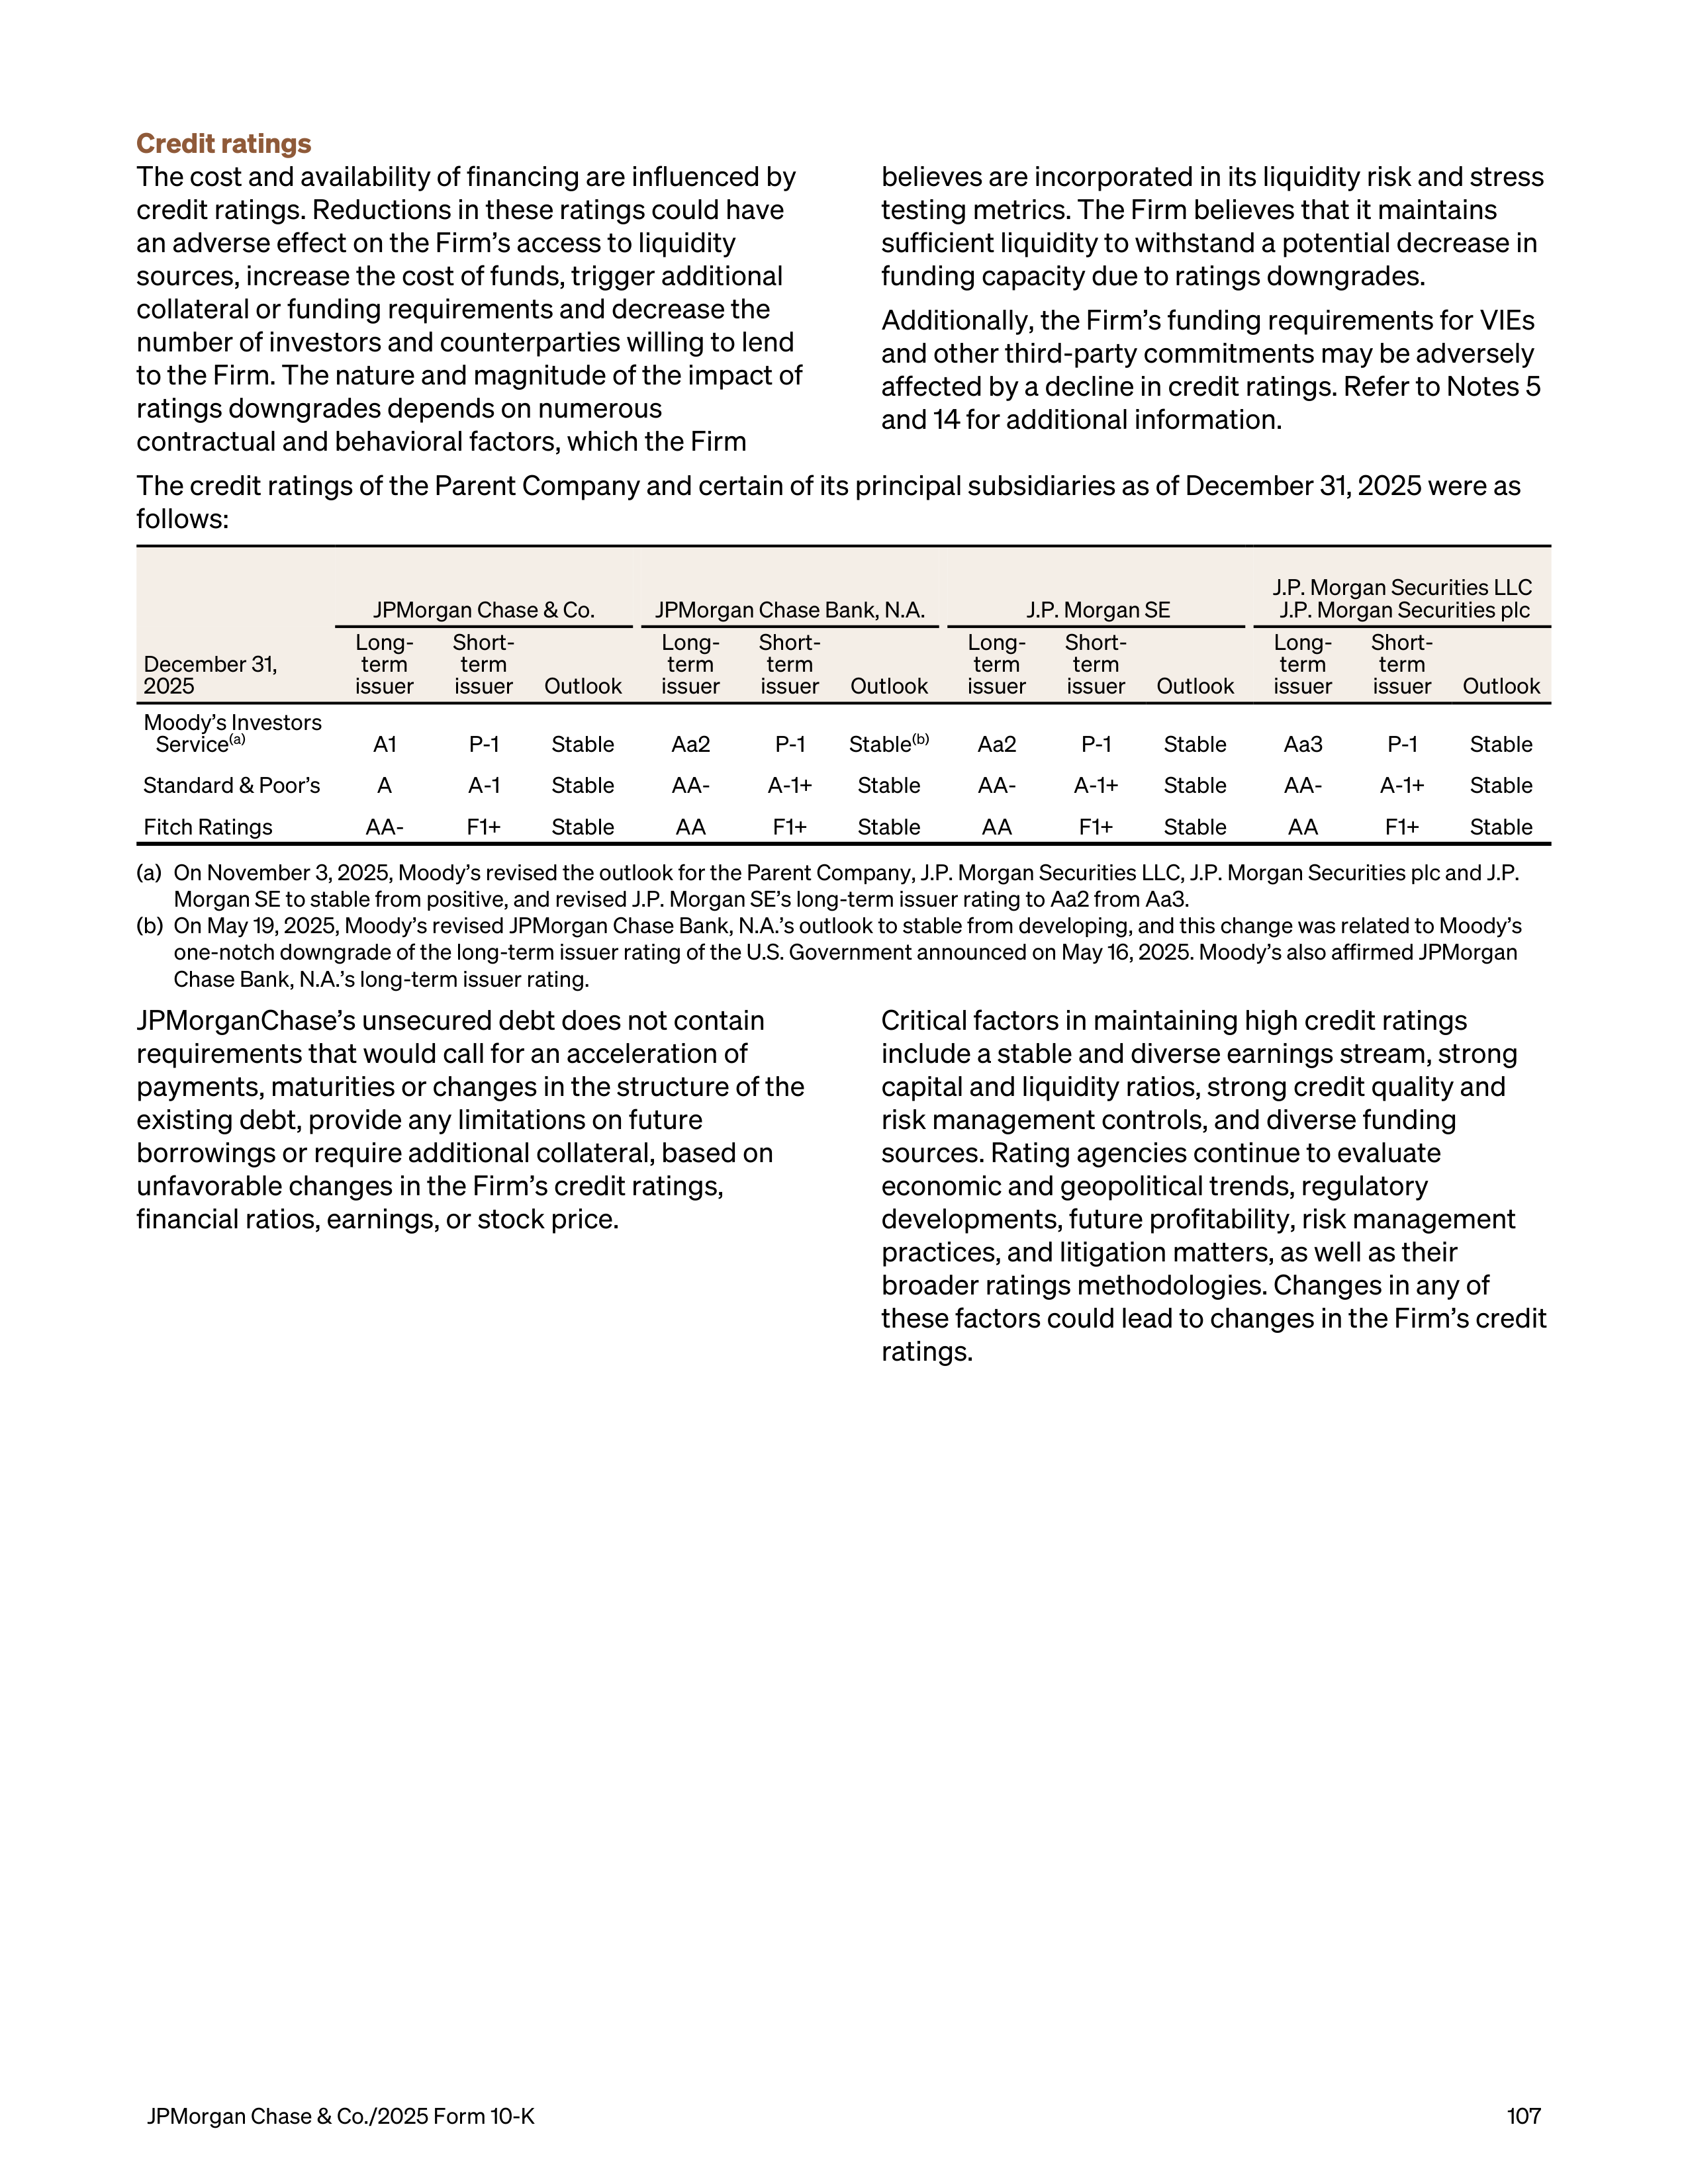
Credit ratings
The cost and availability of financing are influenced by
credit ratings. Reductions in these ratings could have
an adverse effect on the Firm’s access to liquidity
sources, increase the cost of funds, trigger additional
collateral or funding requirements and decrease the
number of investors and counterparties willing to lend
to the Firm. The nature and magnitude of the impact of
ratings downgrades depends on numerous
contractual and behavioral factors, which the Firm
believes are incorporated in its liquidity risk and stress
testing metrics. The Firm believes that it maintains
sufficient liquidity to withstand a potential decrease in
funding capacity due to ratings downgrades.
Additionally, the Firm’s funding requirements for VIEs
and other third-party commitments may be adversely
affected by a decline in credit ratings. Refer to Notes 5
and 14 for additional information.
The credit ratings of the Parent Company and certain of its principal subsidiaries as of December 31, 2025 were as
follows:
JPMorgan Chase & Co.
JPMorgan Chase Bank, N.A.
J.P. Morgan SE
J.P. Morgan Securities LLC
J.P. Morgan Securities plc
December 31,
2025
Long-
term
issuer
Short-
term
issuer
Outlook
Long-
term
issuer
Short-
term
issuer
Outlook
Long-
term
issuer
Short-
term
issuer
Outlook
Long-
term
issuer
Short-
term
issuer
Outlook
Moody’s Investors
Service
(a)
A1
P-1
Stable
Aa2
P-1
Stable
(b)
Aa2
P-1
Stable
Aa3
P-1
Stable
Standard & Poor’s
A
A-1
Stable
AA-
A-1+
Stable
AA-
A-1+
Stable
AA-
A-1+
Stable
Fitch Ratings
AA-
F1+
Stable
AA
F1+
Stable
AA
F1+
Stable
AA
F1+
Stable
(a)
On November 3, 2025, Moody’s revised the outlook for the Parent Company, J.P. Morgan Securities LLC, J.P. Morgan Securities plc and J.P.
Morgan SE to stable from positive, and revised J.P. Morgan SE’s long-term issuer rating to Aa2 from Aa3.
(b)
On May 19, 2025, Moody’s revised JPMorgan Chase Bank, N.A.’s outlook to stable from developing, and this change was related to Moody’s
one-notch downgrade of the long-term issuer rating of the U.S. Government announced on May 16, 2025. Moody’s also affirmed JPMorgan
Chase Bank, N.A.’s long-term issuer rating.
JPMorganChase’s unsecured debt does not contain
requirements that would call for an acceleration of
payments, maturities or changes in the structure of the
existing debt, provide any limitations on future
borrowings or require additional collateral, based on
unfavorable changes in the Firm’s credit ratings,
financial ratios, earnings, or stock price.
Critical factors in maintaining high credit ratings
include a stable and diverse earnings stream, strong
capital and liquidity ratios, strong credit quality and
risk management controls, and diverse funding
sources. Rating agencies continue to evaluate
economic and geopolitical trends, regulatory
developments, future profitability, risk management
practices, and litigation matters, as well as their
broader ratings methodologies. Changes in any of
these factors could lead to changes in the Firm’s credit
ratings.
JPMorgan Chase & Co./2025 Form 10-K
107
REPUTATION RISK MANAGEMENT
Reputation risk is the risk of damage to the trust,
affinity or goodwill for the Firm held by clients,
employees and investors that can result from the
Firm’s decisions to engage or not engage with a client
or in a business activity and which may lead to
negative commercial impacts. The Firm’s decisions
related to clients and business activities are made
based on a range of commercial considerations,
including operational capabilities and expertise,
servicing costs, risk relative to opportunity, the
prioritization of finite resources and, when relevant,
reputation risk considerations. The Firm manages
reputation risk through established policies, standards
and procedures that are integrated across the LOBs
and Corporate functions. Potential reputation risk
matters may be escalated to governance forums, as
appropriate, including LOB Reputation Risk
Committees. The Board Risk Committee also regularly
receives information on reputation risk matters, as
appropriate.
108
JPMorgan Chase & Co./2025 Form 10-K
CREDIT AND INVESTMENT RISK MANAGEMENT
Credit and investment risk is the risk associated with
the default or change in credit profile of a client,
counterparty or customer; or loss of principal or a
reduction in expected returns on investments,
including consumer credit risk, wholesale credit risk,
and investment portfolio risk.
Credit risk management
Credit risk is the risk associated with the default or
change in credit profile of a client, counterparty or
customer. The Firm provides credit to a variety of
clients and customers, ranging from large corporate
and institutional clients to individual consumers and
small businesses. In its consumer businesses, the Firm
is exposed to credit risk primarily through its home
lending, credit card, auto, and business banking
businesses. In its wholesale businesses, the Firm is
exposed to credit risk through its underwriting,
lending, market-making, and hedging activities with
and for clients and counterparties, as well as through
its operating services activities (such as cash
management and clearing activities), and securities
financing activities. The Firm is also exposed to credit
risk through its investment securities portfolio and
cash placed with banks.
Credit Risk Management monitors and measures
credit risk throughout the Firm, and defines credit risk
policies, procedures and limits. The Firm’s credit risk
management governance includes the following
activities:
•
Maintaining a credit risk policy framework
•
Monitoring and measuring credit risk across all
portfolio segments, including transaction and
exposure approval
•
Setting industry and geographic concentration
limits, as appropriate, and setting guidelines for
credit review and analysis
•
Assigning and maintaining credit approval
authorities in connection with the approval of credit
exposure
•
Monitoring and independent assessment of
criticized exposures and delinquent loans, and
•
Estimating credit losses, including periodic review
and refinement of underlying assumptions, and
supporting appropriate credit risk-based capital
management
Risk identification and measurement
To measure credit risk, the Firm employs several
methodologies for estimating the likelihood of obligor
or counterparty default. Methodologies for measuring
credit risk vary depending on several factors, including
type of asset (e.g., consumer versus wholesale), risk
measurement parameters (e.g., delinquency status
and borrower’s credit score versus wholesale risk-
rating) and risk management and collection processes
(e.g., retail collection center versus centrally managed
workout groups). Credit risk measurement is based on
the probability of default of an obligor or counterparty,
the loss severity given a default event and the
exposure at default.
Based on these factors and the methodology and
estimates described in Note 13 and Note 10, the Firm
estimates credit losses for its exposures. The
allowance for loan losses reflects estimated credit
losses related to the consumer and wholesale held-for-
investment loan portfolios, the allowance for lending-
related commitments reflects estimated credit losses
related to the Firm’s lending-related commitments and
the allowance for investment securities reflects
estimated credit losses related to the investment
securities portfolio. Refer to Note 13, Note 10 and
Critical Accounting Estimates used by the Firm on
pages 154–157 for further information.
In addition, potential and unexpected credit losses are
reflected in the allocation of credit risk capital and
represent the potential volatility of actual losses
relative to the established allowances for loan losses
and lending-related commitments. The analyses for
these losses include stress testing that considers
alternative economic scenarios as described below.
Stress testing
Stress testing is important in assessing, measuring
and monitoring credit risk in the Firm’s credit portfolio.
The stress testing process assesses the potential
impact of alternative economic and business scenarios
on estimated credit losses for the Firm. Economic
scenarios and the underlying parameters are defined
centrally, articulated in terms of macroeconomic
factors and applied across the businesses. The stress
test results may indicate credit migration, changes in
delinquency trends and potential losses in the credit
portfolio. In addition to the periodic stress testing
processes, management also considers additional
stresses outside these scenarios, including industry
and country- specific stress scenarios, as appropriate.
The Firm uses stress testing to inform decisions on
setting risk appetite both at a Firm and LOB level, as
well as to assess the impact of stress on individual
counterparties.
JPMorgan Chase & Co./2025 Form 10-K
109
Risk monitoring and management
The Firm has developed policies and practices that are
designed to preserve the independence and integrity
of the approval and decision-making process for
extending credit so that credit risks are assessed
accurately, approved properly, and monitored
regularly at both the transaction and portfolio levels.
The policy framework establishes credit approval
authorities, concentration limits, risk-rating
methodologies, portfolio review parameters and
guidelines for management of distressed exposures. In
addition, certain models, assumptions and inputs used
in evaluating and monitoring credit risk are
independently validated by groups that are separate
from the LOBs.
Consumer credit risk is monitored for delinquency and
other trends, including any concentrations at the
portfolio level, as certain of these trends can be
addressed through changes in underwriting policies
and portfolio guidelines. Consumer Risk Management
evaluates delinquency and other trends against
business expectations, current and forecasted
economic conditions, and industry benchmarks.
Historical and forecasted economic performance and
trends are incorporated into the modeling of estimated
consumer credit losses and are part of the monitoring
of the credit risk profile of the portfolio.
Wholesale credit risk is monitored regularly at an
aggregate portfolio, industry, and individual client and
counterparty level with established concentration
limits that are reviewed and revised periodically as
deemed appropriate by management. Industry and
counterparty limits, as measured in terms of exposure
and risk appetite, are subject to stress-based loss
constraints.
Management of the Firm’s wholesale credit risk
exposure is accomplished through a number of means,
including:
•
Loan underwriting and credit approval processes
•
Loan syndications and participations
•
Loan sales and securitizations
•
Credit derivatives
•
Master netting agreements, and
•
Collateral and other risk-reduction techniques
In addition to Credit Risk Management, an
independent Credit Review function is responsible for:
•
I
ndependently assessing risk ratings assigned to
exposures in the Firm’s wholesale credit portfolio
and the timeliness of risk rating changes initiated by
responsible business units; and
•
Evaluating the effectiveness of the credit
management processes of the LOBs and Corporate,
including the adequacy of credit analyses and risk
rating/loss given default (“LGD”) rationales, proper
monitoring and management of credit exposures,
and compliance with applicable grading policies and
underwriting guidelines.
Refer to Note 12 for further discussion of consumer
and wholesale loans.
Risk reporting
To enable monitoring of credit risk and effective
decision-making, aggregate credit exposure, credit
quality forecasts, concentration levels and risk profile
changes are reported regularly to senior members of
Credit Risk Management. Detailed portfolio reporting
of industry, clients, counterparties and customers,
product and geography are prepared, and the
appropriateness of the allowance for credit losses is
reviewed by senior management at least on a quarterly
basis. Through the risk reporting and governance
structure, credit risk trends and limit exceptions are
provided regularly to, and discussed with, risk
committees, senior management and the Board of
Directors.
Management’s discussion and analysis
110
JPMorgan Chase & Co./2025 Form 10-K
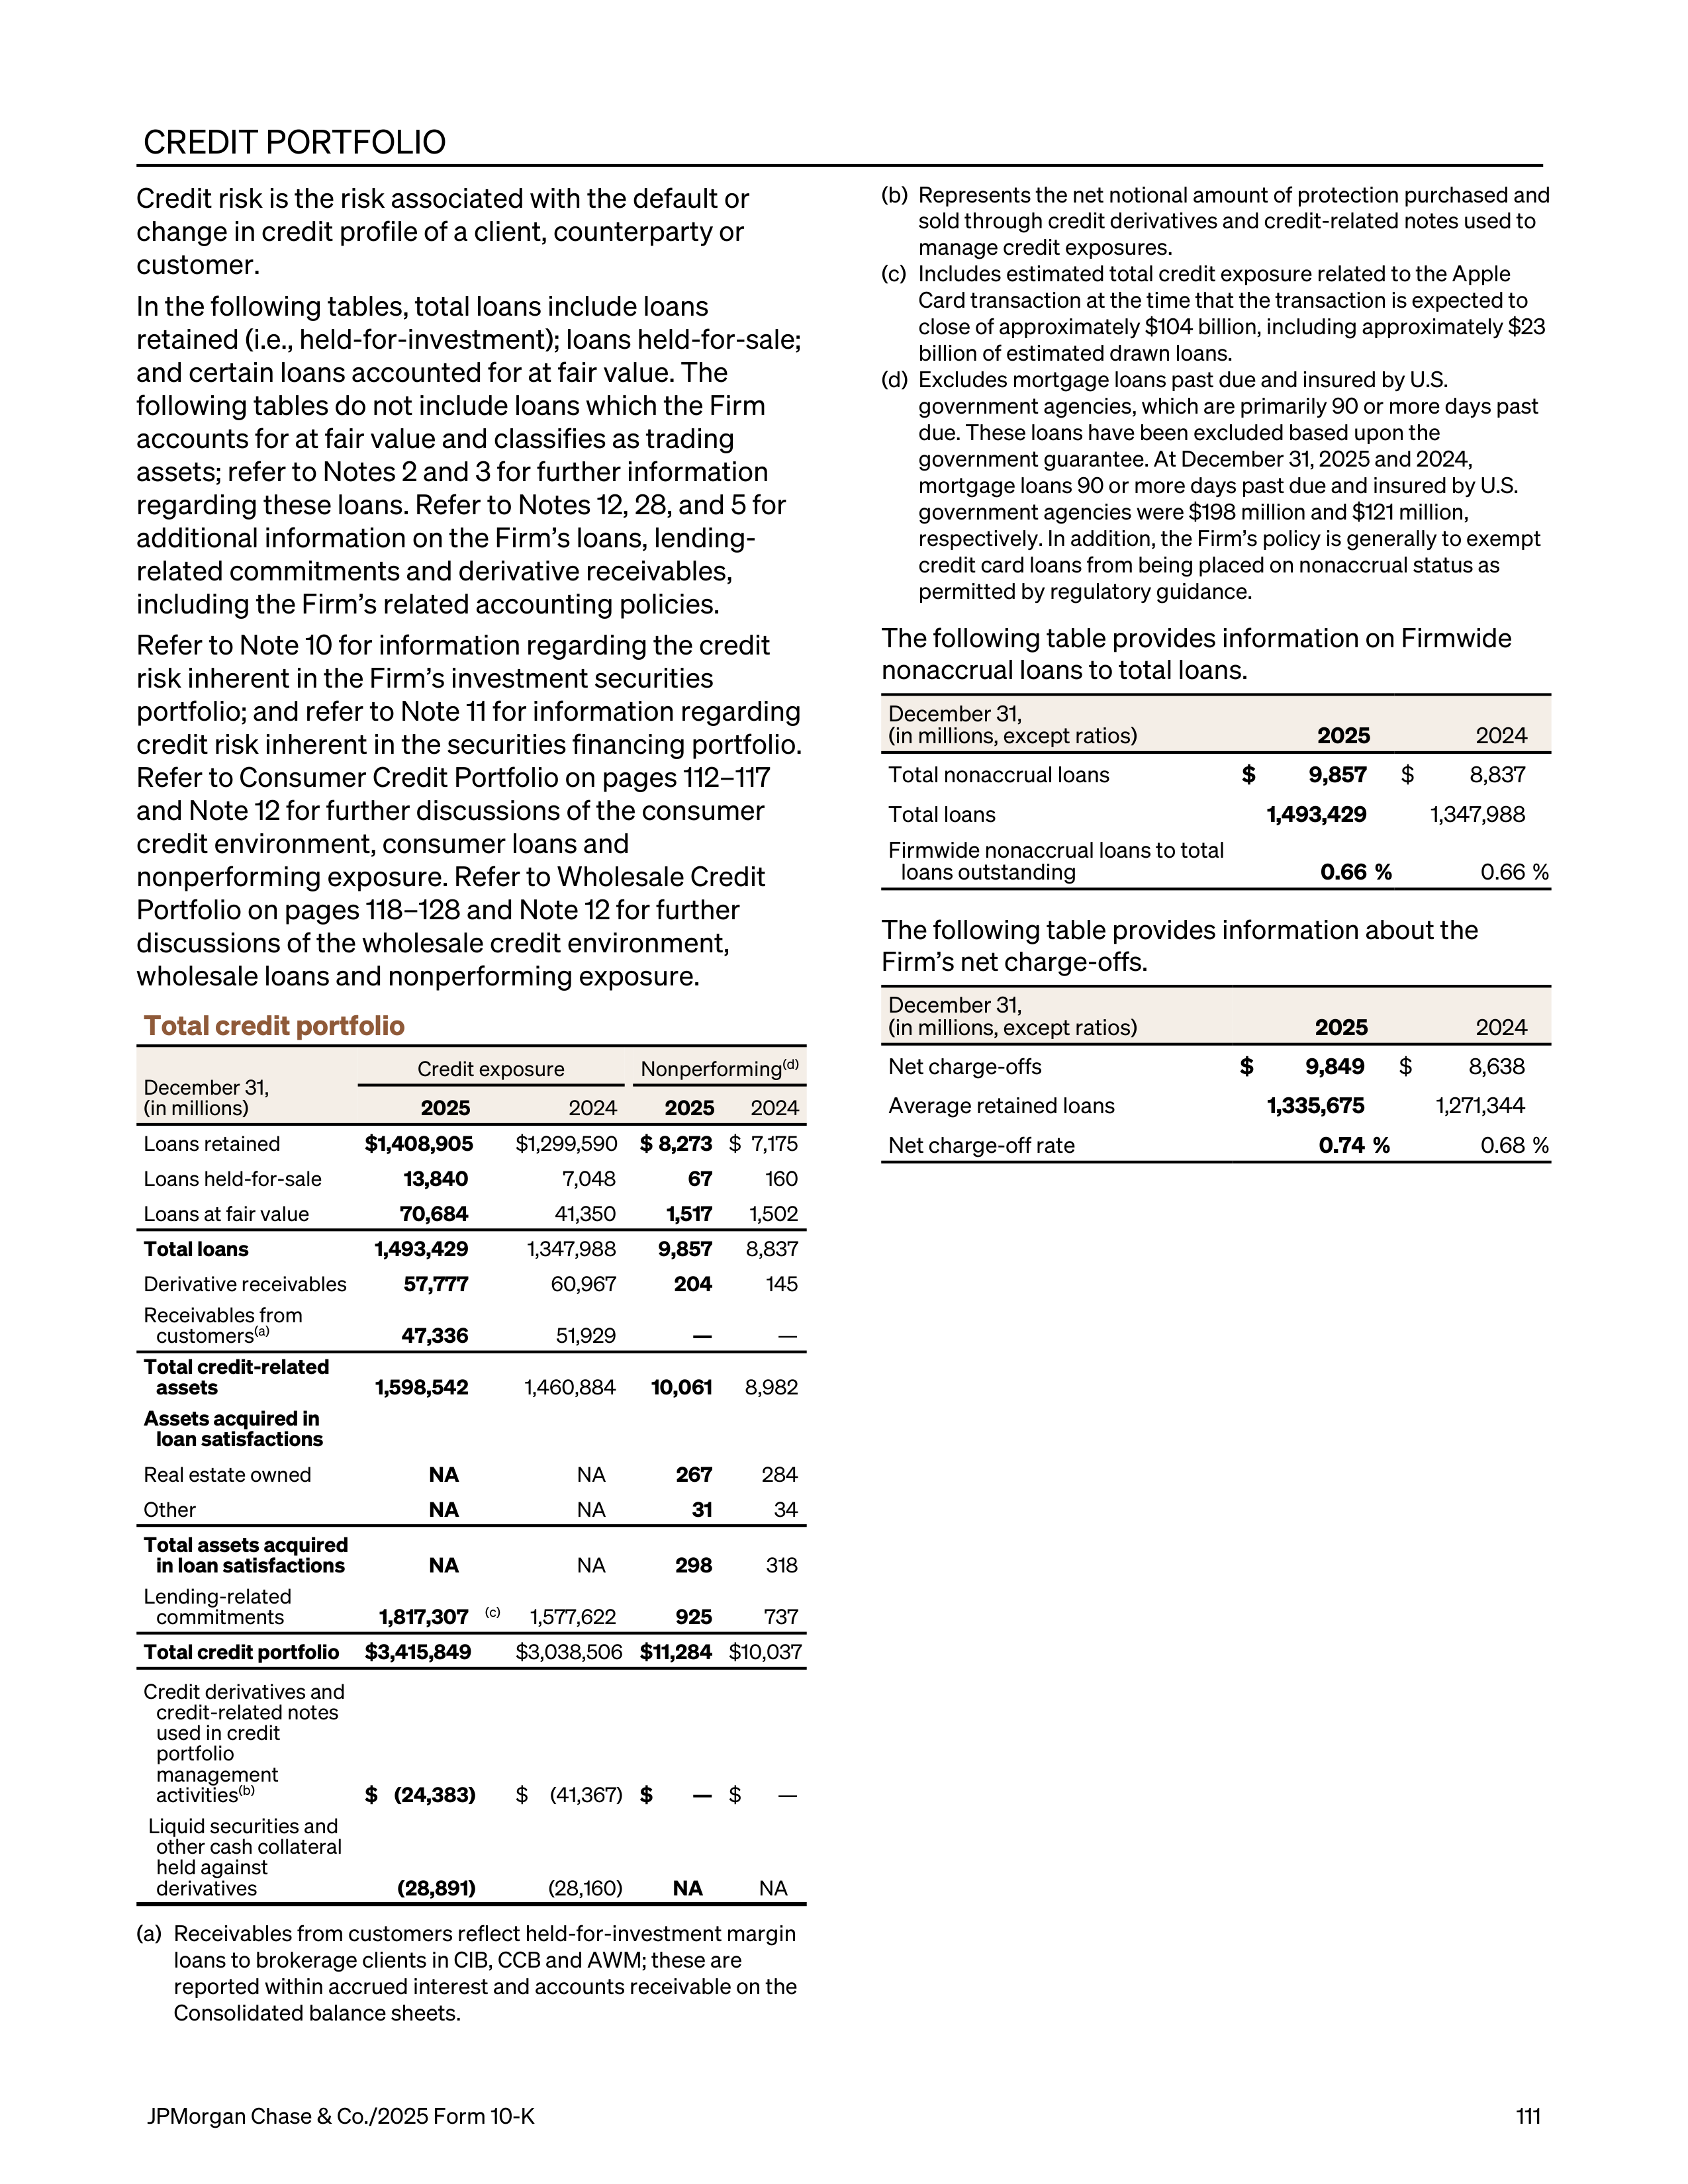
CREDIT PORTFOLIO
Credit risk is the risk associated with the default or
change in credit profile of a client, counterparty or
customer.
In the following tables, total loans include loans
retained (i.e., held-for-investment); loans held-for-sale;
and certain loans accounted for at fair value. The
following tables do not include loans which the Firm
accounts for at fair value and classifies as trading
assets; refer to Notes 2 and 3 for further information
regarding these loans. Refer to Notes 12, 28, and 5 for
additional information on the Firm’s loans, lending-
related commitments and derivative receivables,
including the Firm’s related accounting policies.
Refer to Note 10 for information regarding the credit
risk inherent in the Firm’s investment securities
portfolio; and refer to Note 11 for information regarding
credit risk inherent in the securities financing portfolio.
Refer to Consumer Credit Portfolio on pages 112–117
and Note 12 for further discussions of the consumer
credit environment, consumer loans and
nonperforming exposure. Refer to Wholesale Credit
Portfolio on pages 118–128 and Note 12 for further
discussions of the wholesale credit environment,
wholesale loans and nonperforming exposure.
Total credit portfolio
December 31,
(in millions)
Credit exposure
Nonperforming
(d)
2025
2024
2025
2024
Loans retained
$ 1,408,905
$ 1,299,590
$ 8,273
$ 7,175
Loans held-for-sale
13,840
7,048
67
160
Loans at fair value
70,684
41,350
1,517
1,502
Total loans
1,493,429
1,347,988
9,857
8,837
Derivative receivables
57,777
60,967
204
145
Receivables from
customers
(a)
47,336
51,929
—
—
Total credit-related
assets
1,598,542
1,460,884
10,061
8,982
Assets acquired in
loan satisfactions
Real estate owned
NA
NA
267
284
Other
NA
NA
31
34
Total
assets acquired
in loan satisfactions
NA
NA
298
318
Lending-related
commitments
1,817,307
(c)
1,577,622
925
737
Total credit portfolio
$ 3,415,849
$ 3,038,506
$ 11,284
$ 10,037
Credit derivatives and
credit-related notes
used in credit
portfolio
management
activities
(b)
$ (24,383)
$
(41,367)
$
—
$
—
Liquid securities and
other cash collateral
held against
derivatives
(28,891)
(28,160)
NA
NA
(a)
Receivables from customers reflect held-for-investment margin
loans to brokerage clients in CIB, CCB and AWM; these are
reported within accrued interest and accounts receivable on the
Consolidated balance sheets.
(b)
Represents the net notional amount of protection purchased and
sold through credit derivatives and credit-related notes used to
manage credit exposures.
(c)
Includes estimated total credit exposure related to the Apple
Card transaction at the time that the transaction is expected to
close of approximately $104 billion, including approximately $23
billion of estimated drawn loans.
(d)
Excludes mortgage loans past due and insured by U.S.
government agencies, which are primarily 90 or more days past
due. These loans have been excluded based upon the
government guarantee. At December 31, 2025 and 2024,
mortgage loans 90 or more days past due and insured by U.S.
government agencies were $198 million and $121 million,
respectively. In addition, the Firm’s policy is generally to exempt
credit card loans from being placed on nonaccrual status as
permitted by regulatory guidance.
The following table provides information on Firmwide
nonaccrual loans to total loans.
December 31,
(in millions, except ratios)
2025
2024
Total nonaccrual loans
$
9,857
$
8,837
Total loans
1,493,429
1,347,988
Firmwide nonaccrual loans to total
loans outstanding
0.66 %
0.66 %
The following table provides information about the
Firm’s net charge-offs.
December 31,
(in millions, except ratios)
2025
2024
Net charge-offs
$
9,849
$
8,638
Average retained loans
1,335,675
1,271,344
Net charge-off rate
0.74 %
0.68 %
JPMorgan Chase & Co./2025 Form 10-K
111
CONSUMER CREDIT PORTFOLIO
The Firm’s retained consumer portfolio consists
primarily of loans and lending-related commitments for
residential real estate, credit card, scored auto and
business banking. The consumer credit portfolio also
includes loans at fair value, predominantly in residential
real estate. The Firm’s focus is on serving primarily the
prime segment of the consumer credit market.
Originated mortgage loans are retained in the
residential real estate portfolio, securitized or sold to
U.S. government agencies and U.S. government-
sponsored enterprises; other types of consumer loans
are typically retained on the balance sheet. Refer to
Note 12 for further information on the consumer loan
portfolio. Refer to Note 28 for further information on
lending-related commitments.
Management’s discussion and analysis
112
JPMorgan Chase & Co./2025 Form 10-K
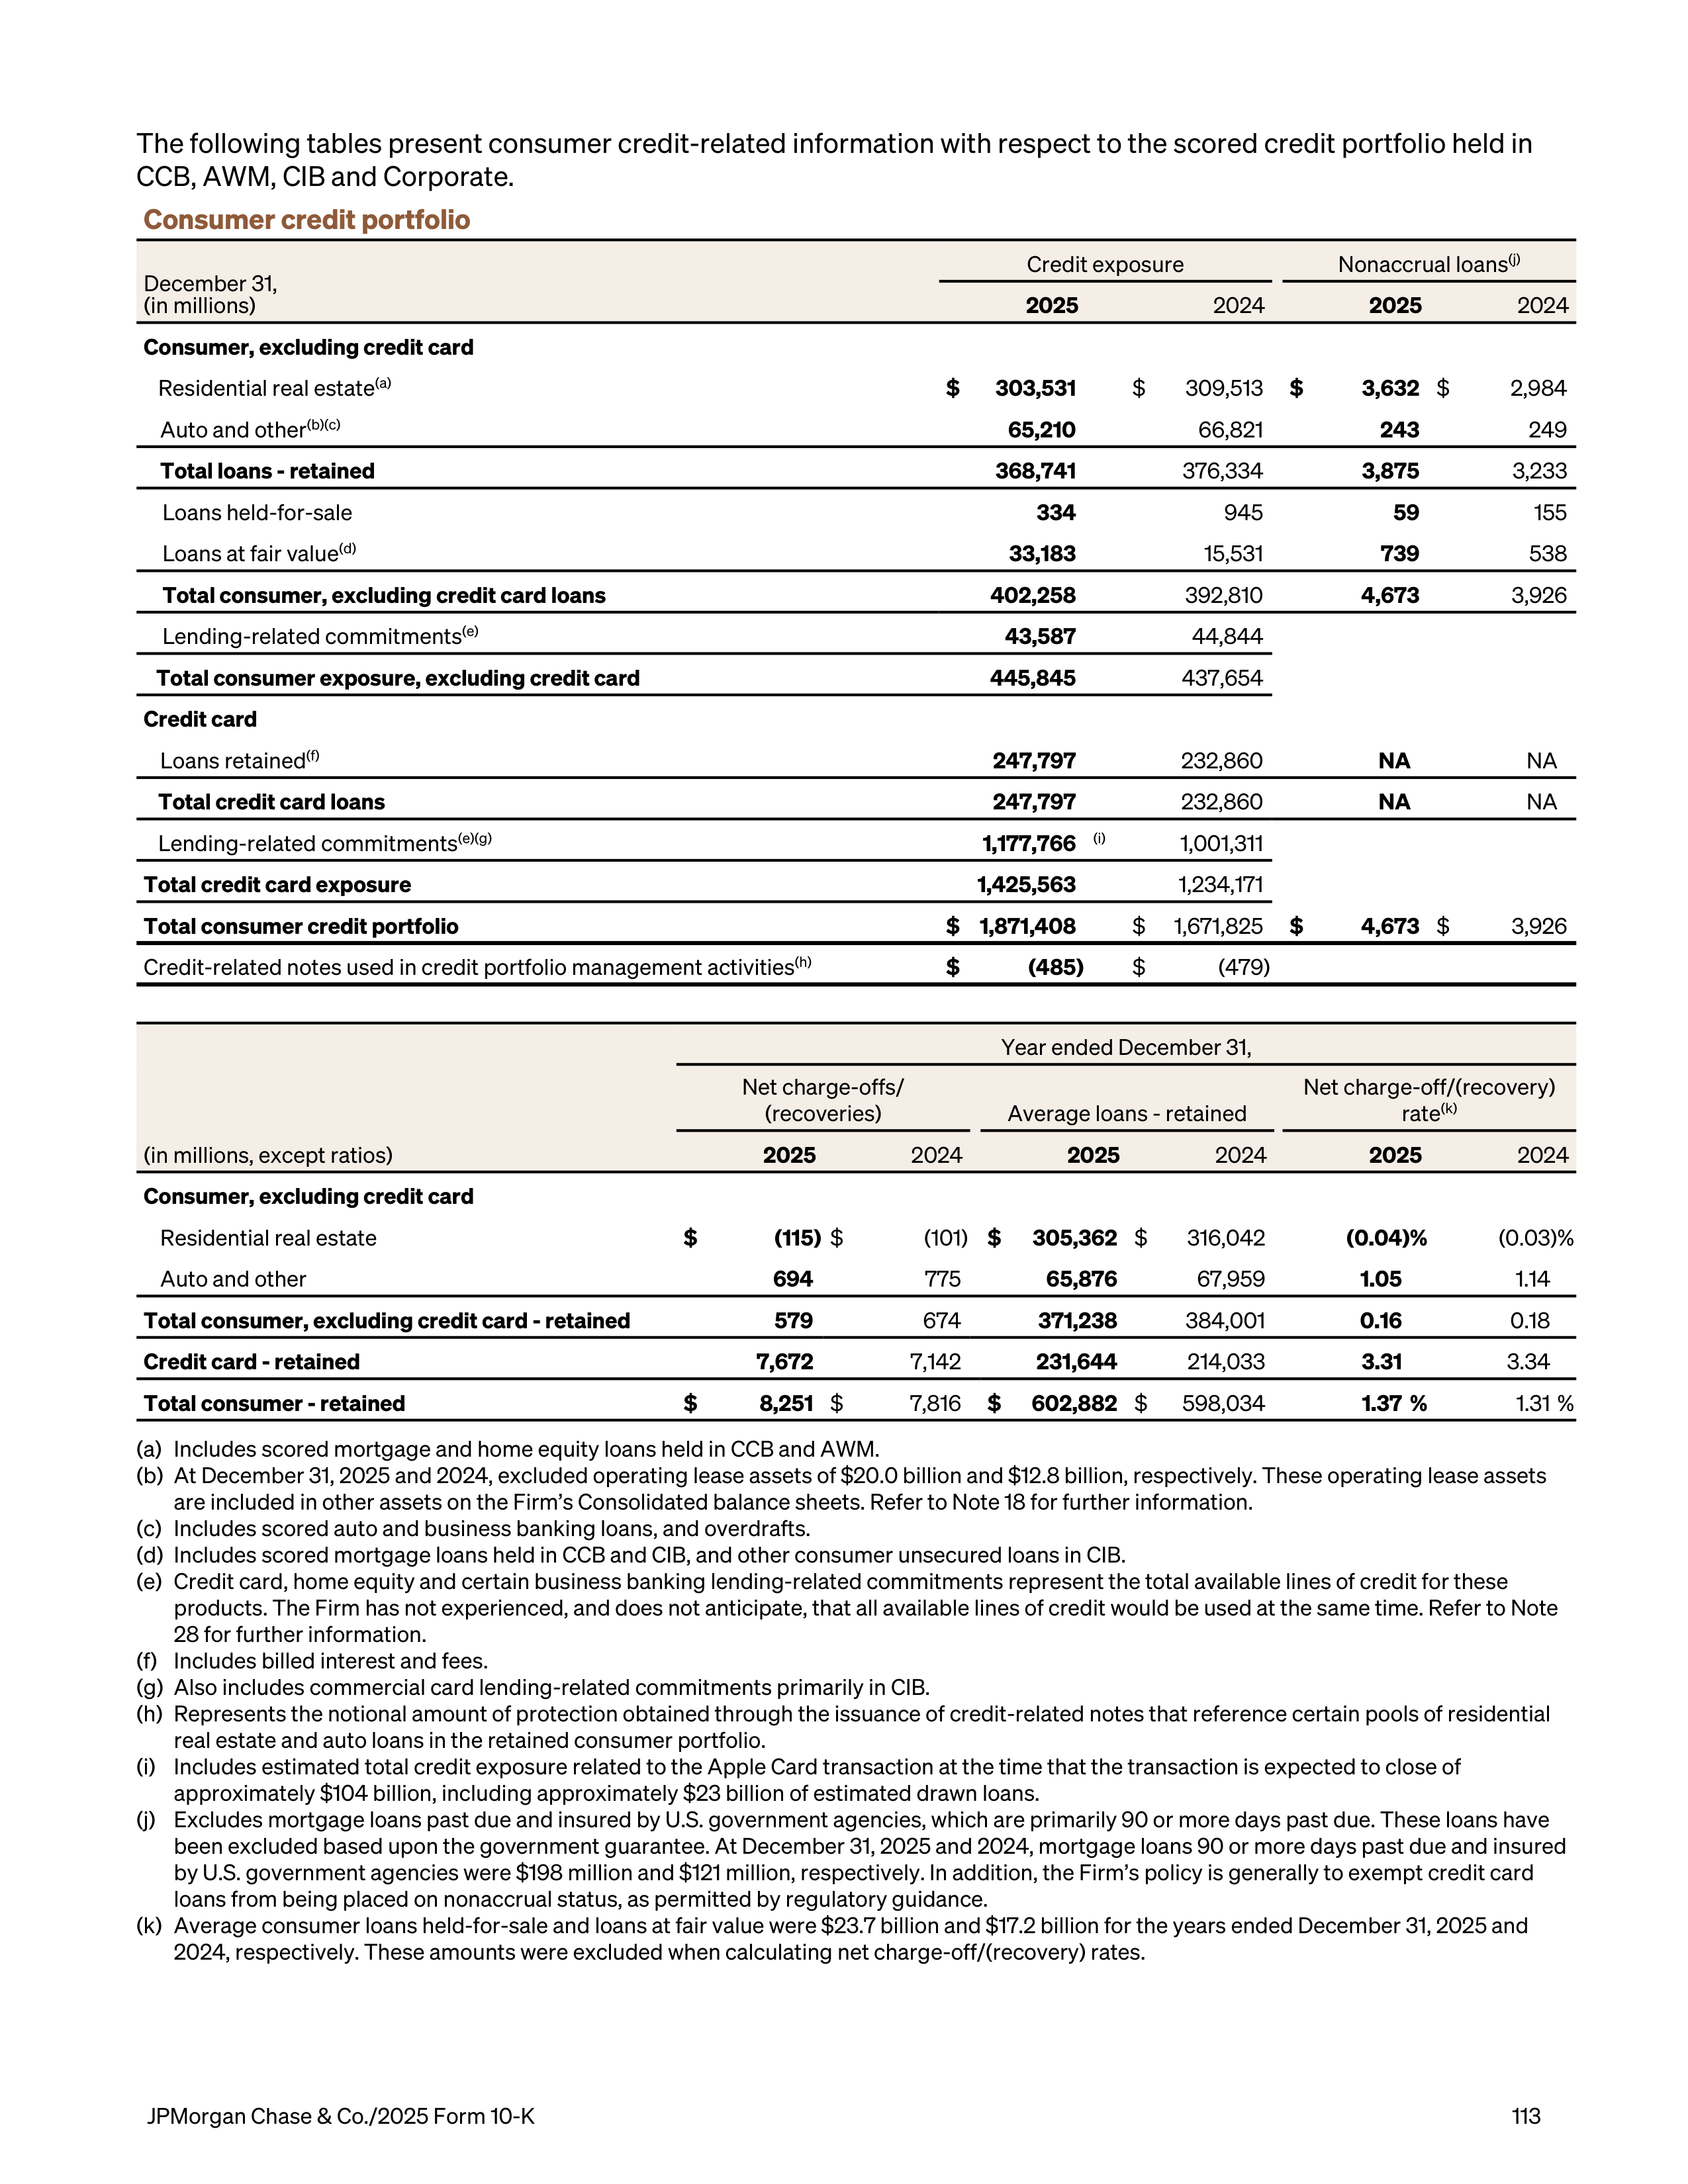
The following tables present consumer credit-related information with respect to the scored credit portfolio held in
CCB, AWM, CIB and Corporate.
Consumer credit portfolio
December 31,
(in millions)
Credit exposure
Nonaccrual loans
(j)
2025
2024
2025
2024
Consumer, excluding credit card
Residential real estate
(a)
$
303,531
$
309,513
$
3,632
$
2,984
Auto and other
(b)(c)
65,210
66,821
243
249
Total loans - retained
368,741
376,334
3,875
3,233
Loans held-for-sale
334
945
59
155
Loans at fair value
(d)
33,183
15,531
739
538
Total consumer, excluding credit card loans
402,258
392,810
4,673
3,926
Lending-related commitments
(e)
43,587
44,844
Total consumer exposure, excluding credit card
445,845
437,654
Credit card
Loans retained
(f)
247,797
232,860
NA
NA
Total credit card loans
247,797
232,860
NA
NA
Lending-related commitments
(e)(g)
1,177,766
(i)
1,001,311
Total credit card exposure
1,425,563
1,234,171
Total consumer credit portfolio
$ 1,871,408
$
1,671,825
$
4,673
$
3,926
Credit-related notes used in credit portfolio management activities
(h)
$
(485)
$
(479)
Year ended December 31,
(in millions, except ratios)
Net charge-offs/
(recoveries)
Average loans - retained
Net charge-off/(recovery)
rate
(k)
2025
2024
2025
2024
2025
2024
Consumer, excluding credit card
Residential real estate
$
(115)
$
(101)
$
305,362
$
316,042
(0.04) %
(0.03) %
Auto and other
694
775
65,876
67,959
1.05
1.14
Total consumer, excluding credit card - retained
579
674
371,238
384,001
0.16
0.18
Credit card - retained
7,672
7,142
231,644
214,033
3.31
3.34
Total consumer - retained
$
8,251
$
7,816
$
602,882
$
598,034
1.37 %
1.31 %
(a)
Includes scored mortgage and home equity loans held in CCB and AWM.
(b)
At December 31, 2025 and 2024, excluded operating lease assets of $20.0 billion and $12.8 billion, respectively. These operating lease assets
are included in other assets on the Firm’s Consolidated balance sheets. Refer to Note 18 for further information.
(c)
Includes scored auto and business banking loans, and overdrafts.
(d)
Includes scored mortgage loans held in CCB and CIB, and other consumer unsecured loans in CIB.
(e)
Credit card, home equity and certain business banking lending-related commitments represent the total available lines of credit for these
products. The Firm has not experienced, and does not anticipate, that all available lines of credit would be used at the same time. Refer to Note
28 for further information.
(f)
Includes billed interest and fees.
(g)
Also includes commercial card lending-related commitments primarily in CIB.
(h)
Represents the notional amount of protection obtained through the issuance of credit-related notes that reference certain pools of residential
real estate and auto loans in the retained consumer portfolio.
(i)
Includes estimated total credit exposure related to the Apple Card transaction at the time that the transaction is expected to close of
approximately $104 billion, including approximately $23 billion of estimated drawn loans.
(j)
Excludes mortgage loans past due and insured by U.S. government agencies, which are primarily 90 or more days past due. These loans have
been excluded based upon the government guarantee. At December 31, 2025 and 2024, mortgage loans 90 or more days past due and insured
by U.S. government agencies were $198 million and $121 million, respectively. In addition, the Firm’s policy is generally to exempt credit card
loans from being placed on nonaccrual status, as permitted by regulatory guidance.
(k)
Average consumer loans held-for-sale and loans at fair value were $23.7 billion and $17.2 billion for the years ended December 31, 2025 and
2024, respectively. These amounts were excluded when calculating net charge-off/(recovery) rates.
JPMorgan Chase & Co./2025 Form 10-K
113
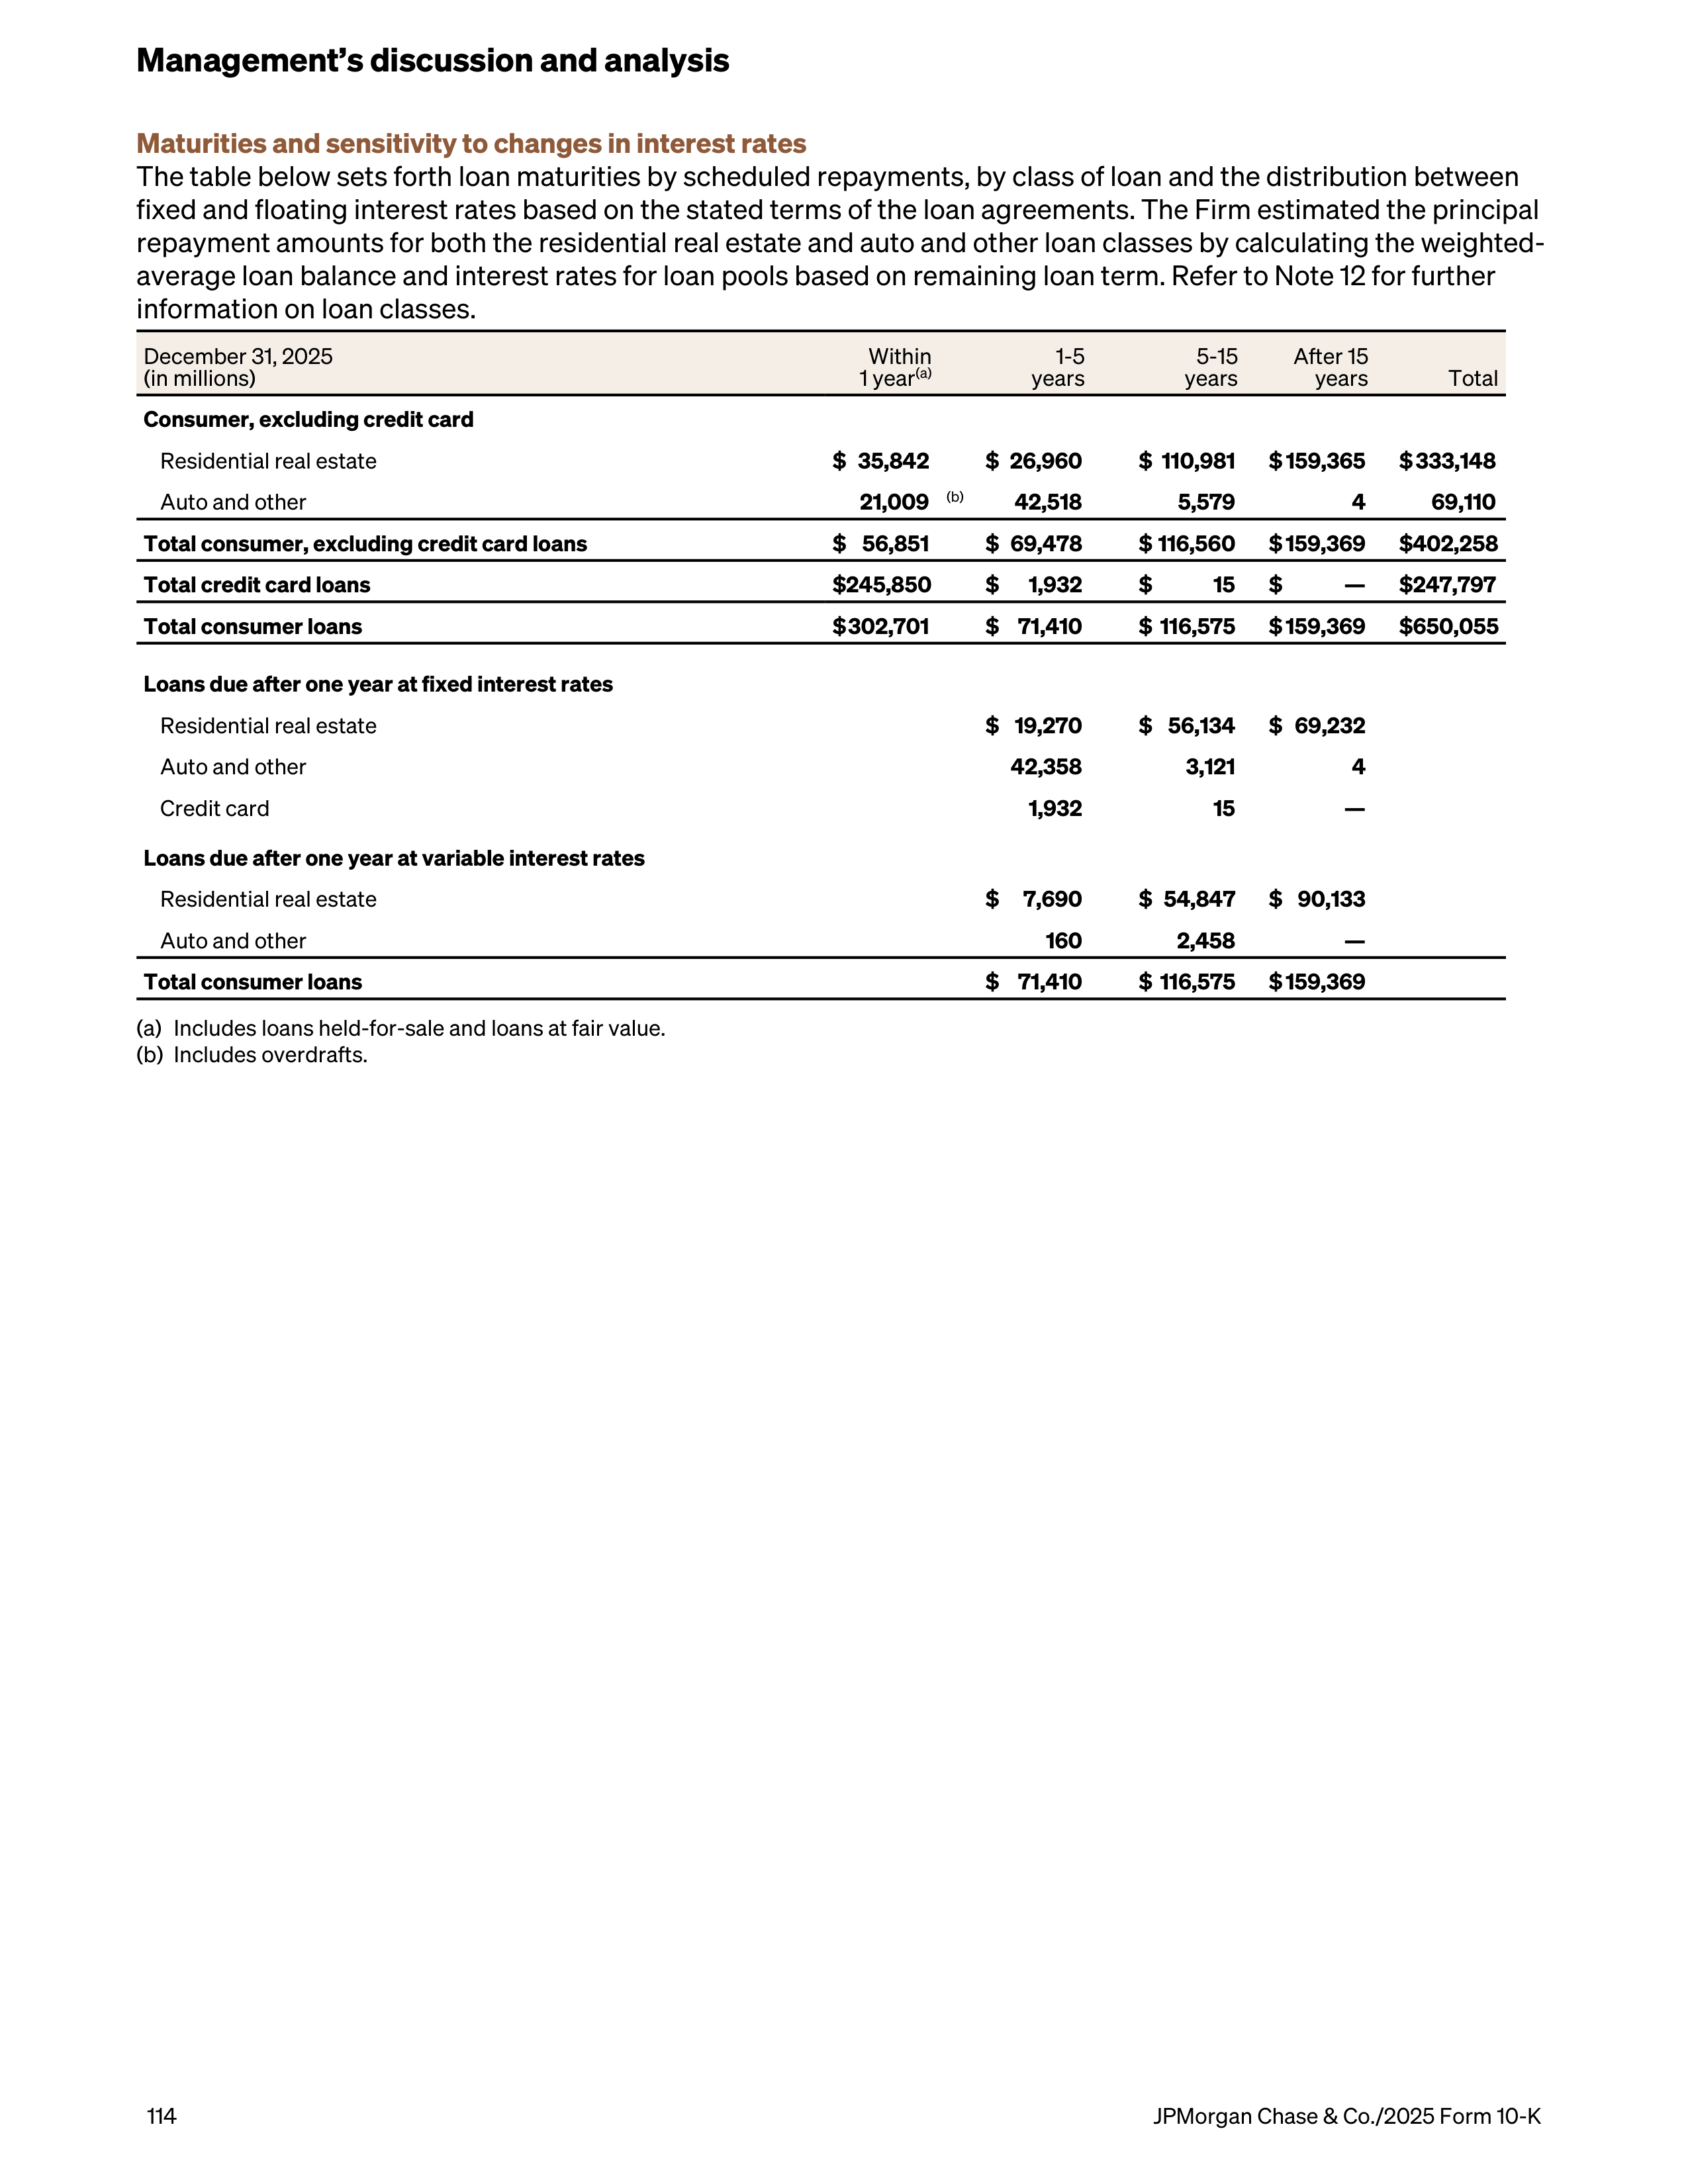
Maturities and sensitivity to changes in interest rates
The table below sets forth loan maturities by scheduled repayments, by class of loan and the distribution between
fixed and floating interest rates based on the stated terms of the loan agreements. The Firm estimated the principal
repayment amounts for both the residential real estate and auto and other loan classes by calculating the weighted-
average loan balance and interest rates for loan pools based on remaining loan term. Refer to Note 12 for further
information on loan classes.
December 31, 2025
(in millions)
Within
1 year
(a)
1-5
years
5-15
years
After 15
years
Total
Consumer, excluding credit card
Residential real estate
$ 35,842
$ 26,960
$ 110,981
$ 159,365
$ 333,148
Auto and other
21,009
(b)
42,518
5,579
4
69,110
Total consumer, excluding credit card loans
$ 56,851
$ 69,478
$ 116,560
$ 159,369
$ 402,258
Total credit card loans
$ 245,850
$
1,932
$
15
$
—
$ 247,797
Total consumer loans
$ 302,701
$ 71,410
$ 116,575
$ 159,369
$ 650,055
Loans due after one year at fixed interest rates
Residential real estate
$ 19,270
$ 56,134
$ 69,232
Auto and other
42,358
3,121
4
Credit card
1,932
15
—
Loans due after one year at variable interest rates
Residential real estate
$
7,690
$ 54,847
$ 90,133
Auto and other
160
2,458
—
Total consumer loans
$ 71,410
$ 116,575
$ 159,369
(a)
Includes loans held-for-sale and loans at fair value.
(b)
Includes overdrafts.
Management’s discussion and analysis
114
JPMorgan Chase & Co./2025 Form 10-K
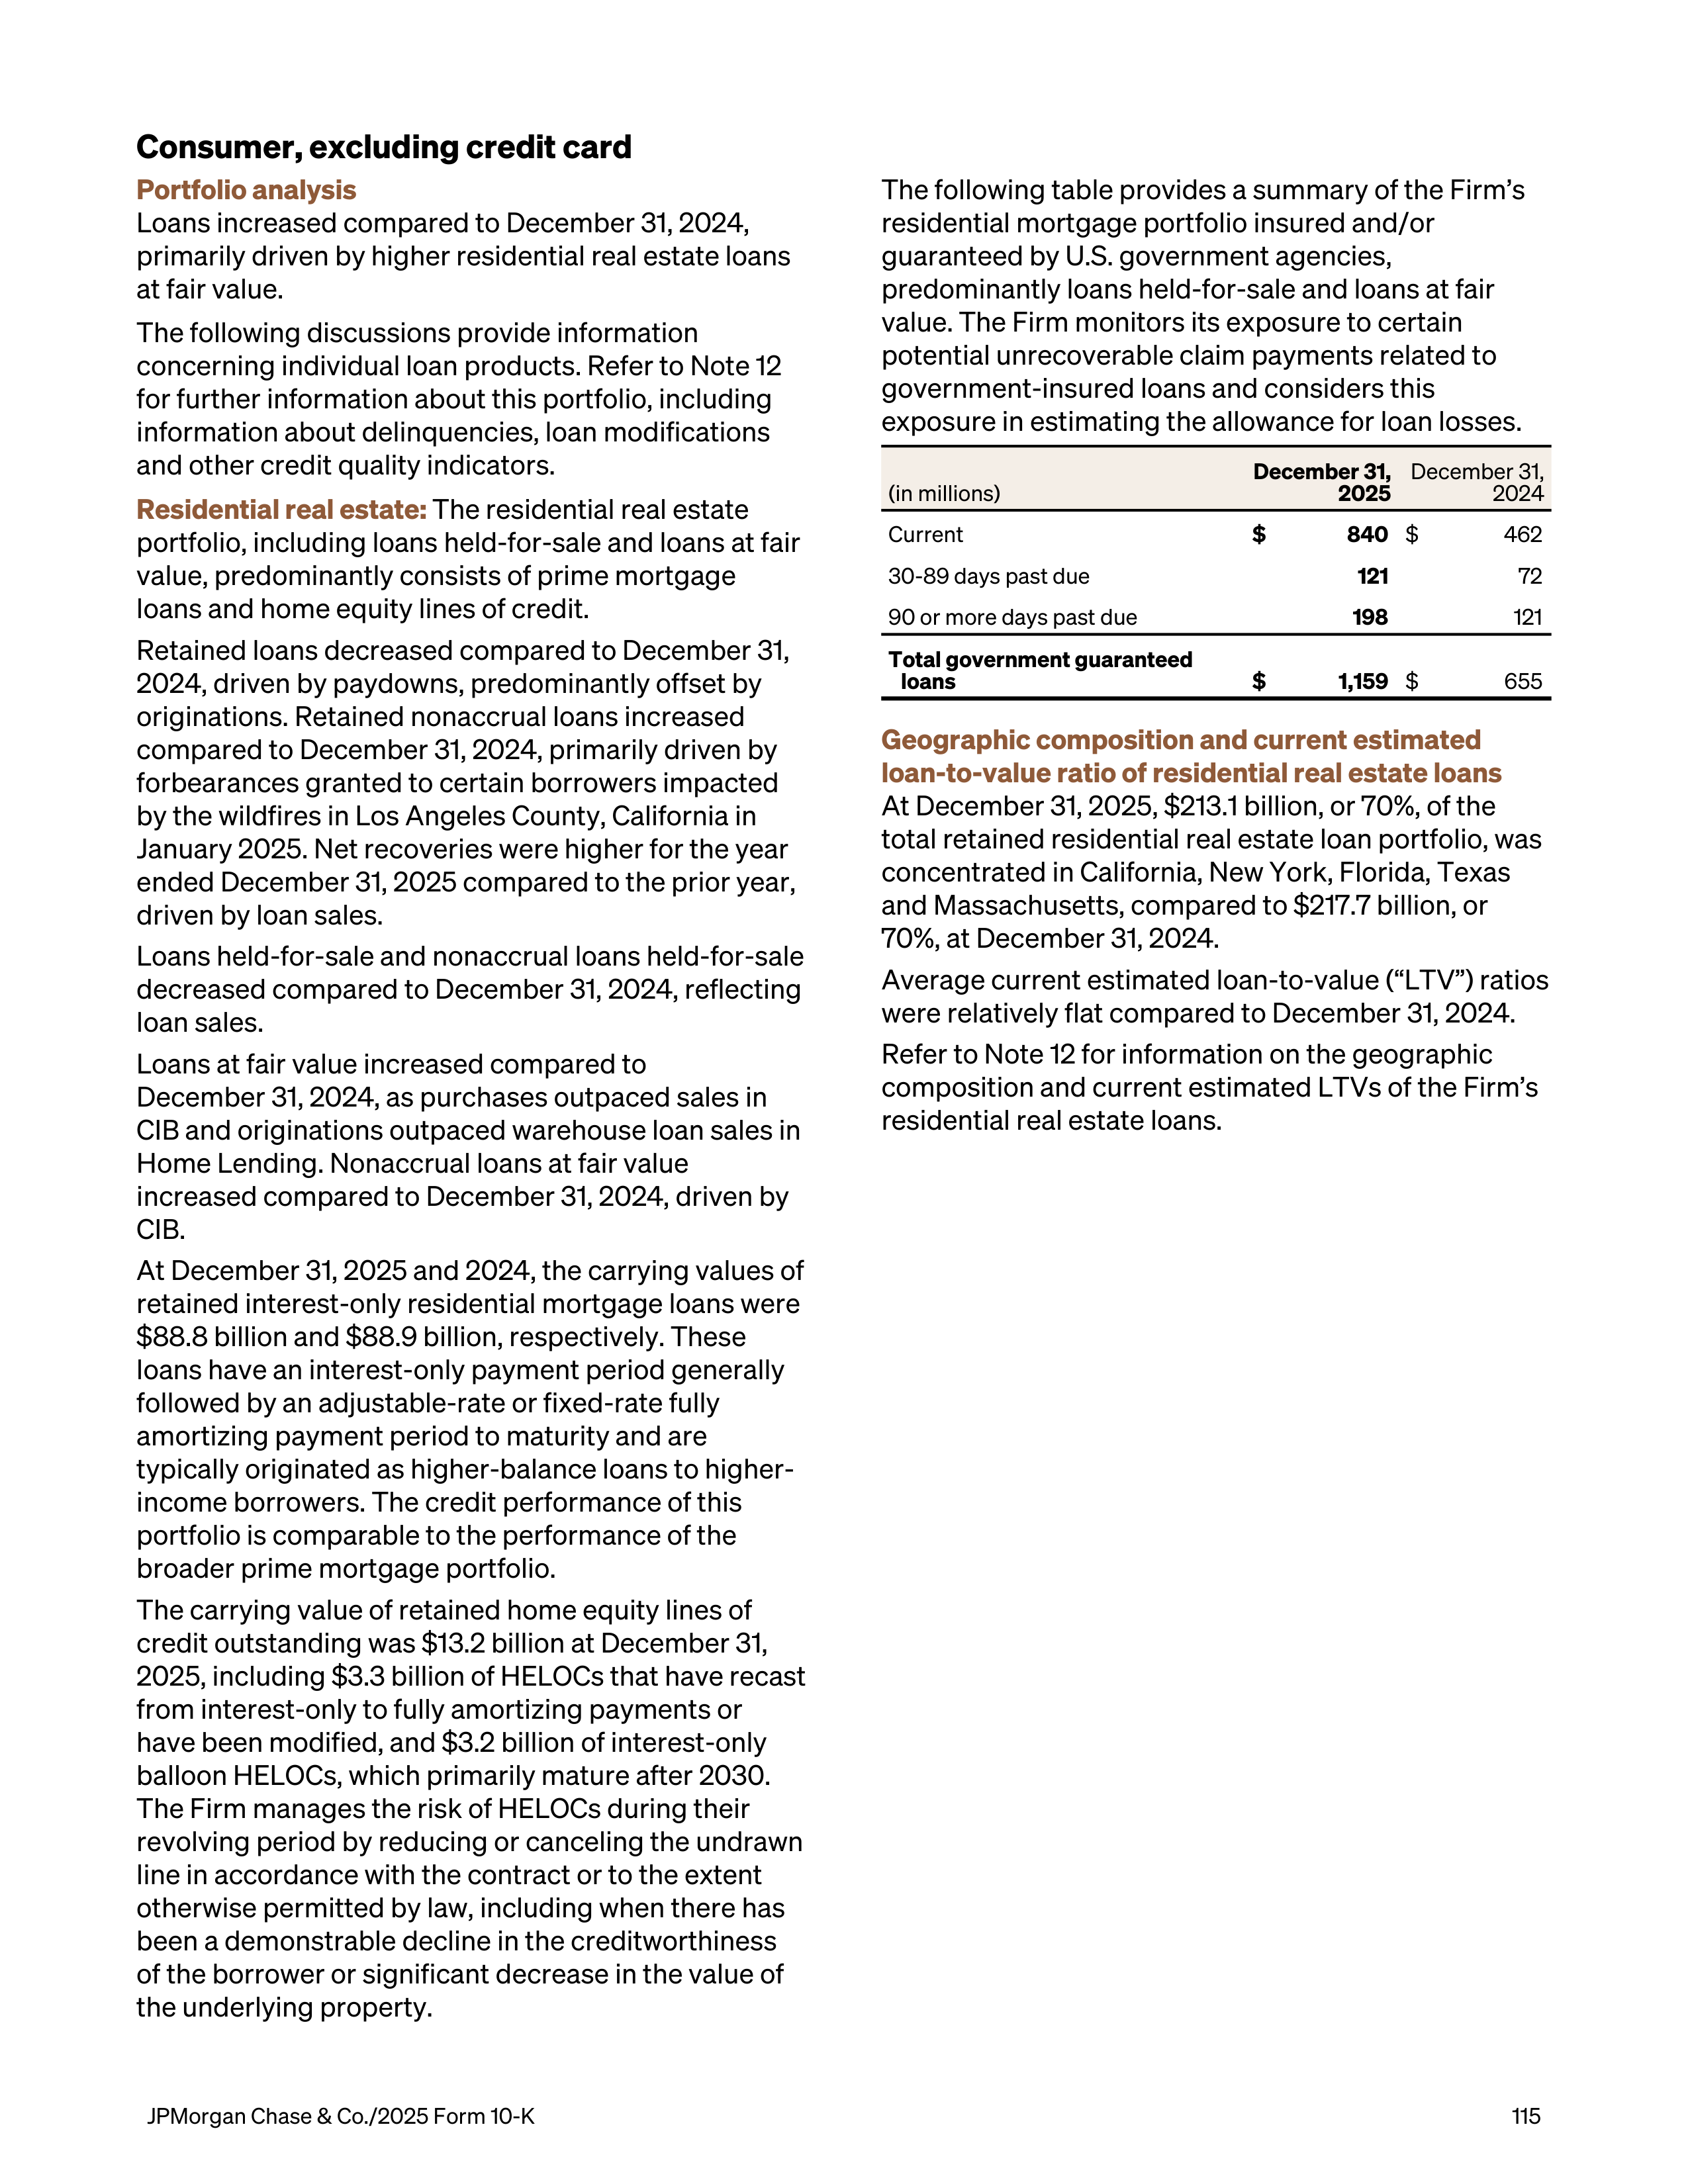
Consumer, excluding credit card
Portfolio analysis
Loans increased compared to December 31, 2024,
primarily driven by higher residential real estate loans
at fair value.
The following discussions provide information
concerning individual loan products. Refer to Note 12
for further information about this portfolio, including
information about delinquencies, loan modifications
and other credit quality indicators.
Residential real estate:
The residential real estate
portfolio, including loans held-for-sale and loans at fair
value, predominantly consists of prime mortgage
loans and home equity lines of credit.
Retained loans decreased compared to December 31,
2024, driven by paydowns, predominantly offset by
originations. Retained nonaccrual loans increased
compared to December 31, 2024, primarily driven by
forbearances granted to certain borrowers impacted
by the wildfires in Los Angeles County, California in
January 2025. Net recoveries were higher for the year
ended December 31, 2025 compared to the prior year,
driven by loan sales.
Loans held-for-sale and nonaccrual loans held-for-sale
decreased compared to December 31, 2024, reflecting
loan sales.
Loans at fair value increased compared to
December 31, 2024, as purchases outpaced sales in
CIB and originations outpaced warehouse loan sales in
Home Lending. Nonaccrual loans at fair value
increased compared to December 31, 2024, driven by
CIB.
At December 31, 2025 and 2024, the carrying values of
retained interest-only residential mortgage loans were
$88.8 billion and $88.9 billion, respectively. These
loans have an interest-only payment period generally
followed by an adjustable-rate or fixed-rate fully
amortizing payment period to maturity and are
typically originated as higher-balance loans to higher-
income borrowers. The credit performance of this
portfolio is comparable to the performance of the
broader prime mortgage portfolio.
The carrying value of retained home equity lines of
credit outstanding was $13.2 billion at December 31,
2025, including $3.3 billion of HELOCs that have recast
from interest-only to fully amortizing payments or
have been modified, and $3.2 billion of interest-only
balloon HELOCs, which primarily mature after 2030.
The Firm manages the risk of HELOCs during their
revolving period by reducing or canceling the undrawn
line in accordance with the contract or to the extent
otherwise permitted by law, including when there has
been a demonstrable decline in the creditworthiness
of the borrower or significant decrease in the value of
the underlying property.
The following table provides a summary of the Firm’s
residential mortgage portfolio insured and/or
guaranteed by U.S. government agencies,
predominantly loans held-for-sale and loans at fair
value. The Firm monitors its exposure to certain
potential unrecoverable claim payments related to
government-insured loans and considers this
exposure in estimating the allowance for loan losses.
(in millions)
December 31,
2025
December 31,
2024
Current
$
840
$
462
30-89 days past due
121
72
90 or more days past due
198
121
Total government guaranteed
loans
$
1,159
$
655
Geographic composition and current estimated
loan-to-value ratio of residential real estate loans
At December 31, 2025, $213.1 billion, or 70%, of the
total retained residential real estate loan portfolio, was
concentrated in California, New York, Florida, Texas
and Massachusetts, compared to $217.7 billion, or
70%, at December 31, 2024.
Average current estimated loan-to-value (“LTV”) ratios
were relatively flat compared to December 31, 2024.
Refer to Note 12 for information on the geographic
composition and current estimated LTVs of the Firm’s
residential real estate loans.
JPMorgan Chase & Co./2025 Form 10-K
115
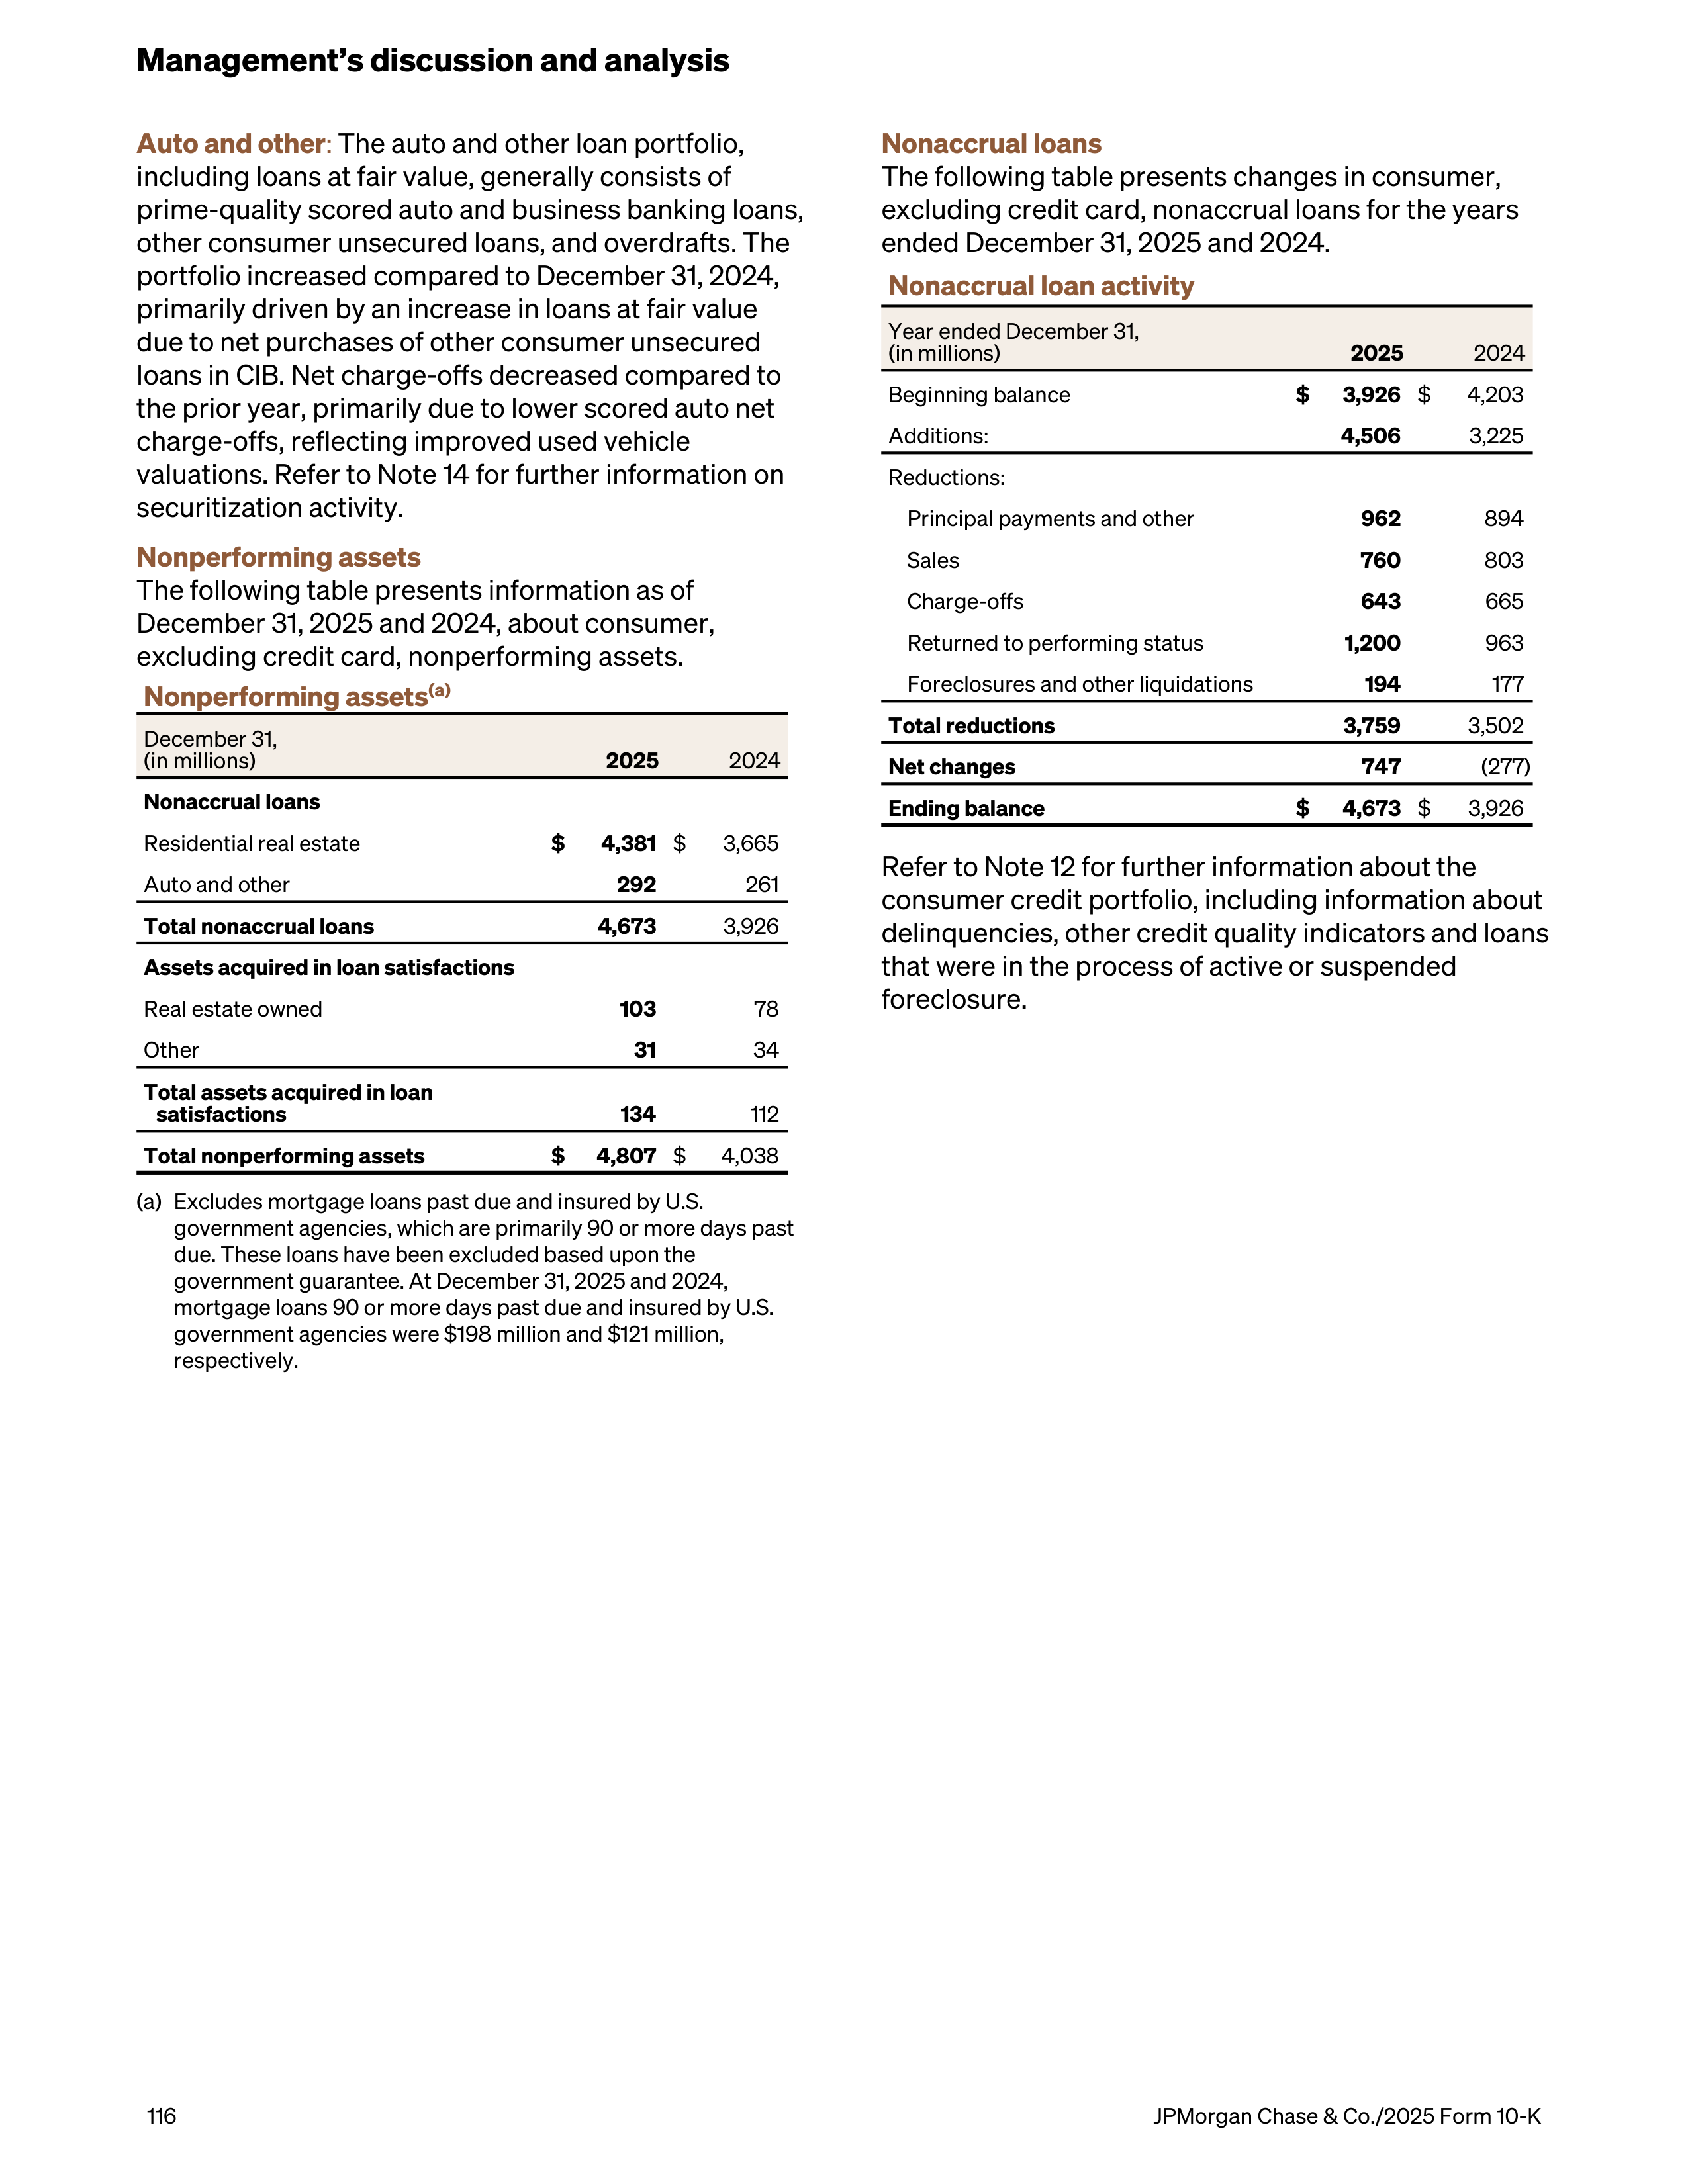
Auto and other
:
The auto and other loan portfolio,
including loans at fair value, generally consists of
prime-quality scored auto and business banking loans,
other consumer unsecured loans, and overdrafts. The
portfolio increased compared to December 31, 2024,
primarily driven by an increase in loans at fair value
due to net purchases of other consumer unsecured
loans in CIB. Net charge-offs decreased compared to
the prior year, primarily due to lower scored auto net
charge-offs, reflecting improved used vehicle
valuations. Refer to Note 14 for further information on
securitization activity.
Nonperforming assets
The following table presents information as of
December 31, 2025 and 2024, about consumer,
excluding credit card, nonperforming assets.
Nonperforming assets
(a)
December 31,
(in millions)
2025
2024
Nonaccrual loans
Residential real estate
$
4,381
$
3,665
Auto and other
292
261
Total nonaccrual loans
4,673
3,926
Assets acquired in loan satisfactions
Real estate owned
103
78
Other
31
34
Total assets acquired in loan
satisfactions
134
112
Total nonperforming assets
$
4,807
$
4,038
(a)
Excludes mortgage loans past due and insured by U.S.
government agencies, which are primarily 90 or more days past
due. These loans have been excluded based upon the
government guarantee. At December 31, 2025 and 2024,
mortgage loans 90 or more days past due and insured by U.S.
government agencies were $198 million and $121 million,
respectively.
Nonaccrual loans
The following table presents changes in consumer,
excluding credit card, nonaccrual loans for the years
ended December 31, 2025 and 2024.
Nonaccrual loan activity
Year ended December 31,
(in millions)
2025
2024
Beginning balance
$
3,926
$
4,203
Additions:
4,506
3,225
Reductions:
Principal payments and other
962
894
Sales
760
803
Charge-offs
643
665
Returned to performing status
1,200
963
Foreclosures and other liquidations
194
177
Total reductions
3,759
3,502
Net changes
747
(277)
Ending balance
$
4,673
$
3,926
Refer to Note 12 for further information about the
consumer credit portfolio, including information about
delinquencies, other credit quality indicators and loans
that were in the process of active or suspended
foreclosure.
Management’s discussion and analysis
116
JPMorgan Chase & Co./2025 Form 10-K
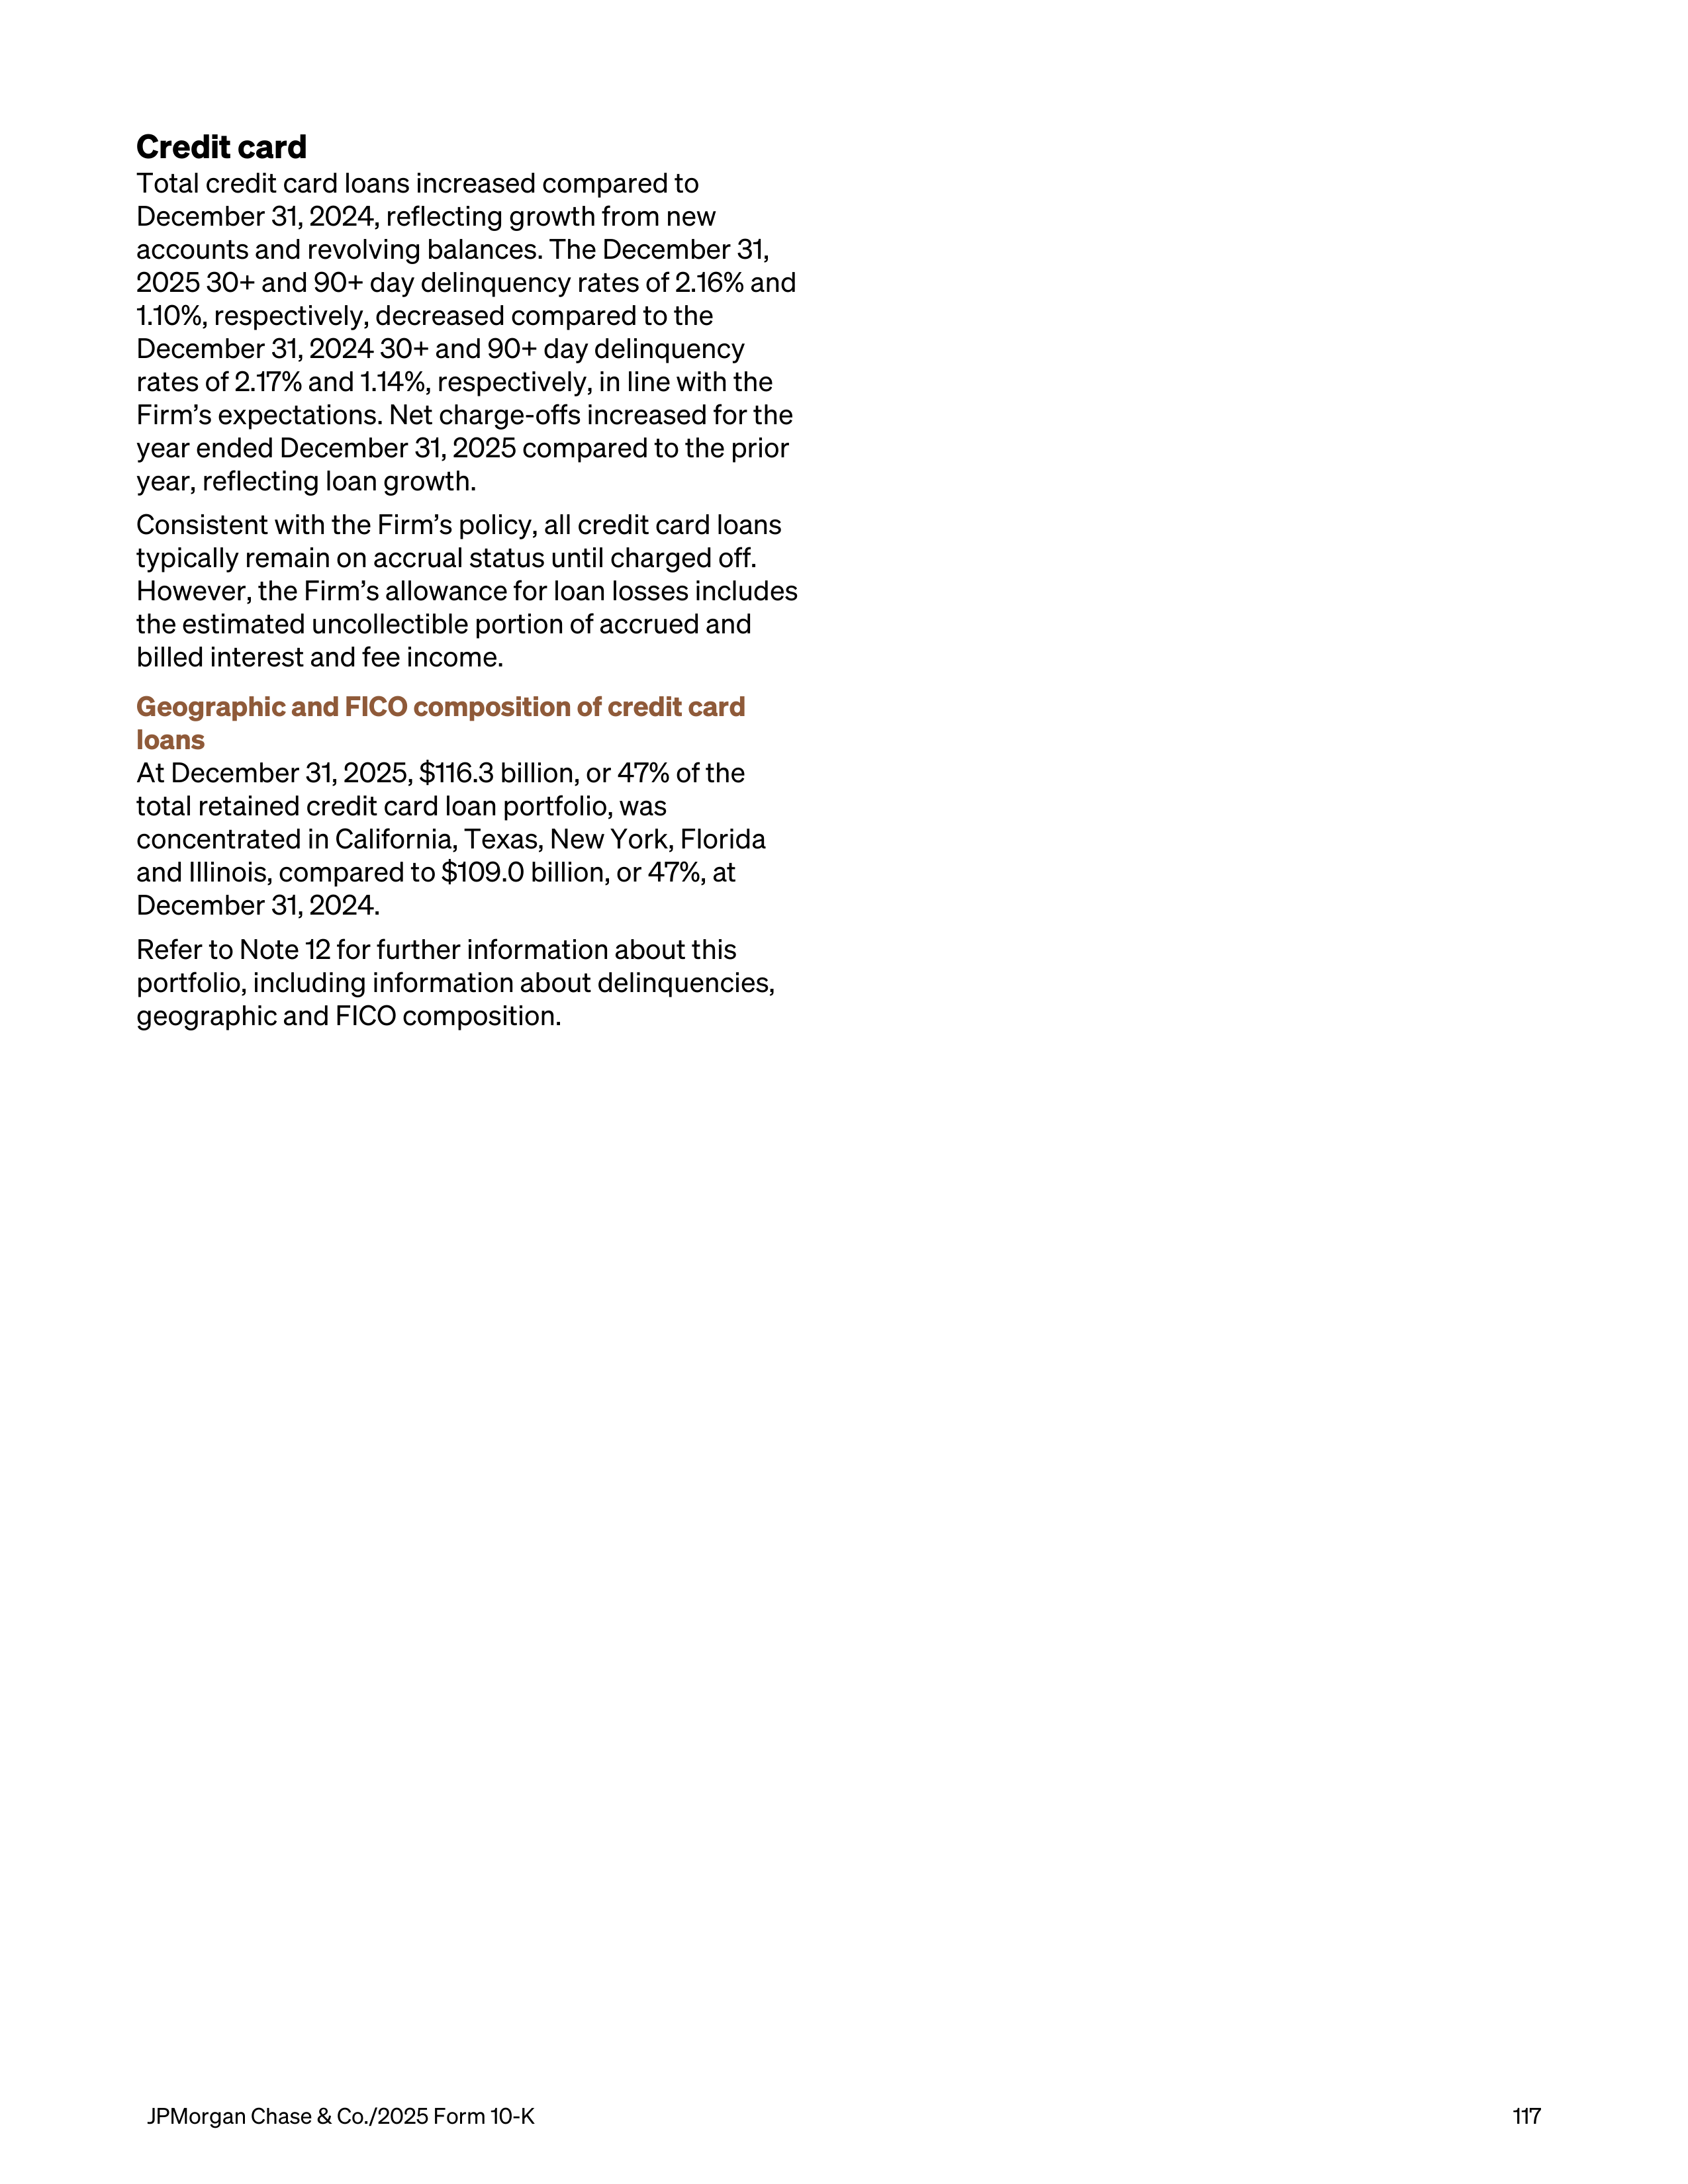
Credit card
Total credit card loans increased compared to
December 31, 2024, reflecting growth from new
accounts and revolving balances. The December 31,
2025 30+ and 90+ day delinquency rates of 2.16% and
1.10%, respectively, decreased compared to the
December 31, 2024 30+ and 90+ day delinquency
rates of 2.17% and 1.14%, respectively, in line with the
Firm’s expectations. Net charge-offs increased for the
year ended December 31, 2025 compared to the prior
year, reflecting loan growth.
Consistent with the Firm’s policy, all credit card loans
typically remain on accrual status until charged off.
However, the Firm’s allowance for loan losses includes
the estimated uncollectible portion of accrued and
billed interest and fee income.
Geographic and FICO composition of credit card
loans
At December 31, 2025, $116.3 billion, or 47% of the
total retained credit card loan portfolio, was
concentrated in California, Texas, New York, Florida
and Illinois, compared to $109.0 billion, or 47%, at
December 31, 2024.
Refer to Note 12 for further information about this
portfolio, including information about delinquencies,
geographic and FICO composition.
JPMorgan Chase & Co./2025 Form 10-K
117
WHOLESALE CREDIT PORTFOLIO
In its wholesale businesses, the Firm is exposed to
credit risk primarily through its underwriting, lending,
market-making, and hedging activities with and for
clients and counterparties, as well as through various
operating services (such as cash management and
clearing activities), securities financing activities and
cash placed with banks. A portion of the loans
originated or acquired by the Firm’s wholesale
businesses is generally retained on the balance sheet.
The Firm distributes a significant percentage of the
loans that it originates into the market as part of its
syndicated loan business and to manage portfolio
concentrations and credit risk. The wholesale portfolio
is actively managed, in part by conducting ongoing, in-
depth reviews of client credit quality and transaction
structure, inclusive of collateral where applicable, and
of industry, product and client concentrations. Refer to
the industry discussion on pages 120–123 for further
information.
The Firm’s wholesale credit portfolio includes
exposure held in CIB, AWM and Corporate, and risk-
rated exposure held in CCB, for which the wholesale
methodology is applied when determining the
allowance for loan losses.
As of December 31, 2025, loans increased by
$121.1 billion, predominantly driven by higher loans in
CIB, primarily in Markets, and higher securities-based
lending in AWM, both associated with higher client
demand. Lending-related commitments increased by
$64.5 billion, predominantly driven by higher
commitments in CIB, including held-for-sale
commitments.
As of December 31, 2025, nonperforming exposure
increased by $478 million, driven by certain exposures
in Technology, Media & Telecommunications, Oil &
Gas and Utilities, in each case primarily resulting from
downgrades, largely offset by certain exposures in
Healthcare and Consumer & Retail, primarily due to
charge-off activity, upgrades, and loan sales.
Wholesale credit portfolio
December 31,
(in millions)
Credit exposure
Nonperforming
2025
2024
2025
2024
Loans retained
$ 792,367
$ 690,396
$ 4,398
$ 3,942
Loans held-for-sale
13,506
6,103
8
5
Loans at fair value
37,501
25,819
778
964
Loans
843,374
722,318
5,184
4,911
Derivative
receivables
57,777
60,967
204
145
Receivables from
customers
(a)
47,336
51,929
—
—
Total wholesale
credit-related
assets
948,487
835,214
5,388
5,056
Assets acquired in
loan satisfactions
Real estate owned
NA
NA
164
206
Total
assets
acquired in loan
satisfactions
NA
NA
164
206
Lending-related
commitments
595,954
531,467
925
737
Total wholesale
credit portfolio
$ 1,544,441
$ 1,366,681
$ 6,477
$ 5,999
Credit derivatives
and credit-related
notes used in credit
portfolio
management
activities
(b)
$ (23,898)
$ (40,888)
$
—
$
—
Liquid securities and
other cash
collateral held
against derivatives
(28,891)
(28,160)
NA
NA
(a)
Receivables from customers reflect held-for-investment margin
loans to brokerage clients in CIB, CCB and AWM; these are
reported within accrued interest and accounts receivable on the
Consolidated balance sheets.
(b)
Represents the net notional amount of protection purchased and
sold through credit derivatives and credit-related notes used to
manage both performing and nonperforming wholesale credit
exposures; these derivatives do not qualify for hedge accounting
under U.S. GAAP. Refer to Credit derivatives on page 128 and
Note 5 for additional information.
Management’s discussion and analysis
118
JPMorgan Chase & Co./2025 Form 10-K
Wholesale credit exposure – maturity and ratings profile
The following tables present the maturity and internal risk ratings profiles of the wholesale credit portfolio as of
December 31, 2025 and 2024. The Firm generally considers internal ratings with qualitative characteristics
equivalent to BBB-/Baa3 or higher as investment grade, and takes into consideration collateral and structural
support when determining the internal risk rating for each credit facility. Refer to Note 12 for further information on
internal risk ratings.
Maturity profile
(d)
Ratings profile
December 31, 2025
(in millions, except ratios)
1 year or
less
After 1 year
through
5 years
After 5
years
Total
Investment-
grade
Noninvestment-
grade
Total
Total %
of IG
Loans retained
$ 271,648 $ 330,900 $ 189,819 $ 792,367
$
541,364 $
251,003 $ 792,367
68 %
Derivative receivables
57,777
57,777
Less: Liquid securities and other cash collateral
held against derivatives
(28,891)
(28,891)
Total derivative receivables, net of collateral
7,941
6,836
14,109
28,886
19,721
9,165
28,886
68
Lending-related commitments
155,797
412,594
27,563
595,954
383,106
212,848
595,954
64
Subtotal
435,386
750,330 231,491 1,417,207
944,191
473,016 1,417,207
67
Loans held-for-sale and loans at fair value
(a)
51,007
51,007
Receivables from customers
47,336
47,336
Total exposure – net of liquid securities and
other cash collateral held against derivatives
$ 1,515,550
$ 1,515,550
Credit derivatives and credit-related notes used
in credit portfolio management activities
(b)(c)
$ (5,356) $ (17,424) $
(1,118) $ (23,898) $
(17,831) $
(6,067) $ (23,898)
75 %
Maturity profile
(d)
Ratings profile
December 31, 2024
(in millions, except ratios)
1 year or
less
After 1 year
through
5 years
After 5
years
Total
Investment-
grade
Noninvestment-
grade
Total
Total %
of IG
Loans retained
$ 225,982 $
289,199 $ 175,215 $ 690,396
$
471,670 $
218,726 $ 690,396
68 %
Derivative receivables
60,967
60,967
Less: Liquid securities and other cash collateral
held against derivatives
(28,160)
(28,160)
Total derivative receivables, net of collateral
11,515
7,418
13,874
32,807
24,707
8,100
32,807
75
Lending-related commitments
121,283
384,529
25,655
531,467
352,082
179,385
531,467
66
Subtotal
358,780
681,146 214,744 1,254,670
848,459
406,211 1,254,670
68
Loans held-for-sale and loans at fair value
(a)
31,922
31,922
Receivables from customers
51,929
51,929
Total exposure – net of liquid securities and
other cash collateral held against derivatives
$ 1,338,521
$ 1,338,521
Credit derivatives and credit-related notes used
in credit portfolio management activities
(b)(c)
$
(5,442) $
(33,751) $
(1,695) $ (40,888) $
(31,691) $
(9,197) $ (40,888)
78 %
(a)
Loans held-for-sale are primarily related to syndicated loans and loans transferred from the retained portfolio.
(b)
These derivatives do not qualify for hedge accounting under U.S. GAAP.
(c)
The notional amounts are presented on a net basis by underlying reference entity and the ratings profile shown is based on the ratings of the
reference entity on which protection has been purchased. Predominantly all of the credit derivatives entered into by the Firm where it has
purchased protection used in credit portfolio management activities are executed with investment-grade counterparties. In addition, the Firm
obtains credit protection against certain loans in the retained loan portfolio through the issuance of credit-related notes.
(d)
The maturity profile of retained loans, lending-related commitments and derivative receivables is generally based on remaining contractual
maturity. Derivative contracts that are in a receivable position at December 31, 2025, may become payable prior to maturity based on their
cash flow profile or changes in market conditions.
JPMorgan Chase & Co./2025 Form 10-K
119
Wholesale credit exposure – industry exposures
The Firm focuses on the management and diversification of its industry exposures, and pays particular attention to
industries with actual or potential credit concerns.
Exposures that are deemed to be criticized align with the U.S. banking regulators’ definition of criticized exposures,
which consist of the special mention, substandard and doubtful categories. Total criticized exposure, excluding
loans held-for-sale and loans at fair value, was $48.5 billion and $44.7 billion as of December 31, 2025 and 2024,
representing approximately 3.4% and 3.5% of total wholesale credit exposure, respectively; of the $48.5 billion,
$42.9 billion was performing. The increase in criticized exposure was driven by SPEs, Consumer & Retail, Banks &
Finance Companies, Healthcare, and Chemicals & Plastics, primarily resulting from downgrades and new lending-
related commitments, partially offset by Real Estate and Industrials, primarily resulting from net portfolio activity
and upgrades.
The table below summarizes by industry the Firm’s exposures as of December 31, 2025 and 2024. The industry of
risk category is generally based on the client or counterparty’s primary business activity. Refer to Note 4 for
additional information on industry concentrations.
Wholesale credit exposure – industries
(a)
Selected metrics
Noninvestment-grade
30 days or
more past
due and
accruing
loans
Net
charge-offs/
(recoveries)
Credit
derivative
and
credit-
related
notes
(h)
Liquid securities
and other cash
collateral held
against
derivative
receivables
As of or for the year ended
December 31, 2025
(in millions)
Credit
exposure
(f)(g)
Investment-
grade
Noncriticized
Criticized
performing
Criticized
nonperforming
Real Estate
$
224,858 $
155,712 $
57,478 $
9,967 $
1,701 $
959 $
380 $
(99) $
—
Individuals and Individual
Entities
(b)
167,700
138,142
28,677
460
421
1,012
(15)
—
—
Asset Managers
152,848
117,426
35,113
304
5
105
1
(5)
(10,626)
Consumer & Retail
133,945
63,523
62,382
7,425
615
115
234
(311)
—
Technology, Media &
Telecommunications
97,816
44,373
42,507
10,135
801
37
281
(1,078)
—
Industrials
80,606
44,078
33,166
3,101
261
470
18
(68)
—
Banks & Finance Companies
75,653
41,904
32,826
903
20
16
8
(574)
(657)
Healthcare
72,218
48,888
19,713
3,059
558
12
191
(67)
—
Utilities
39,005
24,840
12,519
1,254
392
1
63
(203)
—
Oil & Gas
36,497
21,825
14,076
347
249
52
48
(51)
—
Automotive
35,984
19,602
15,397
958
27
109
3
(277)
—
State & Municipal Govt
(c)
32,484
31,372
1,100
3
9
30
—
(3)
—
Insurance
25,031
17,511
7,352
168
—
6
—
(20)
(8,310)
Chemicals & Plastics
23,790
11,251
10,355
2,091
93
2
82
(239)
—
Transportation
20,861
11,450
9,097
285
29
11
(3)
(135)
—
Metals & Mining
17,767
7,459
9,883
406
19
22
4
(39)
(67)
Central Govt
15,164
14,666
245
44
209
8
—
(1,258)
(1,273)
Securities Firms
7,966
4,372
3,593
—
1
1
—
(13)
(2,458)
Financial Markets
Infrastructure
5,734
5,306
358
70
—
—
—
—
—
All other
(d)
180,171
148,214
29,887
1,953
117
3
303
(19,458)
(5,500)
Subtotal
$ 1,446,098 $
971,914 $
425,724 $
42,933 $
5,527 $
2,971 $
1,598 $ (23,898) $
(28,891)
Loans held-for-sale and loans
at fair value
51,007
Receivables from customers
47,336
Total
(e)
$ 1,544,441
Management’s discussion and analysis
120
JPMorgan Chase & Co./2025 Form 10-K
(continued from previous page)
Selected metrics
Noninvestment-grade
30 days or
more past
due and
accruing
loans
Net
charge-offs/
(recoveries)
Credit
derivative
and
credit-
related
notes
(h)
Liquid securities
and other cash
collateral held
against
derivative
receivables
As of or for the year ended
December 31, 2024
(in millions)
Credit
exposure
(f)(g)
Investment-
grade
Noncriticized
Criticized
performing
Criticized
nonperforming
Real Estate
$
207,050 $
143,803 $
50,865 $
10,858 $
1,524 $
913 $
345 $
(584) $
—
Individuals and Individual
Entities
(b)
144,145
118,650
24,831
217
447
831
122
—
—
Asset Managers
135,541
101,150
34,148
206
37
375
2
—
(9,194)
Consumer & Retail
129,815
62,800
60,141
6,055
819
252
123
(4,320)
—
Technology, Media &
Telecommunications
84,716
45,021
28,629
10,592
474
79
94
(4,800)
—
Industrials
72,530
37,572
30,912
3,807
239
185
91
(2,312)
—
Banks & Finance Companies
61,287
36,884
24,119
257
27
36
—
(702)
(729)
Healthcare
64,224
44,135
17,062
2,219
808
245
56
(3,286)
(34)
Utilities
35,871
24,205
10,256
1,273
137
1
—
(2,700)
—
Oil & Gas
31,724
19,053
12,479
188
4
9
(3)
(1,711)
(2)
Automotive
34,336
22,015
11,353
931
37
121
1
(997)
—
State & Municipal Govt
(c)
35,039
33,303
1,711
9
16
90
—
(2)
(1)
Insurance
24,267
17,847
6,198
222
—
2
—
(1,077)
(9,184)
Chemicals & Plastics
20,782
11,013
8,152
1,521
96
31
14
(1,164)
—
Transportation
17,019
9,462
7,135
391
31
17
(20)
(658)
—
Metals & Mining
15,860
7,373
7,860
590
37
9
—
(246)
(2)
Central Govt
13,862
13,580
157
125
—
4
—
(1,490)
(2,051)
Securities Firms
9,443
5,424
4,014
5
—
—
—
(13)
(2,635)
Financial Markets
Infrastructure
4,446
4,201
245
—
—
—
—
(1)
—
All other
(d)
140,873
117,986
22,398
398
91
10
(3)
(14,825)
(4,328)
Subtotal
$
1,282,830 $
875,477 $
362,665 $
39,864 $
4,824 $
3,210 $
822 $ (40,888) $
(28,160)
Loans held-for-sale and
loans at fair value
31,922
Receivables from customers
51,929
Total
(e)
$
1,366,681
(a)
The industry rankings presented in the table as of December 31, 2024, are based on the industry rankings of the corresponding exposures as
of December 31, 2025, not actual rankings of such exposures as of December 31, 2024.
(b)
Individuals and Individual Entities predominantly consists of Global Private Bank clients within AWM and J.P. Morgan Wealth Management
within CCB, and includes exposure to personal investment companies and personal and testamentary trusts.
(c)
In addition to the credit risk exposure to states and municipal governments (both U.S. and non-U.S.) at December 31, 2025 and 2024, noted
above, the Firm held: $6.1 billion of trading assets at both periods; $20.2 billion and $17.9 billion, respectively, of AFS securities; and $8.6
billion and $9.3 billion, respectively, of HTM securities, issued by U.S. state and municipal governments. Refer to Notes 2 and 10 for further
information.
(d)
All other includes: SPEs and Private education and civic organizations, representing approximately 95% and 5%, respectively, at
December 31, 2025, and 94% and 6%, respectively, at December 31, 2024. Refer to Note 14 for more information on exposures to SPEs.
(e)
Excludes cash placed with banks of $333.8 billion and $459.2 billion, at December 31, 2025 and 2024, respectively, which is predominantly
placed with various central banks, primarily Federal Reserve Banks.
(f)
Credit exposure is net of risk participations and excludes the benefit of credit derivatives and credit-related notes used in credit portfolio
management activities held against derivative receivables or loans and liquid securities and other cash collateral held against derivative
receivables.
(g)
Credit exposure includes held-for-sale and fair value option elected lending-related commitments.
(h)
Represents the net notional amounts of protection purchased and sold through credit derivatives and credit-related notes used to manage
the credit exposures; these derivatives do not qualify for hedge accounting under U.S. GAAP. The All other category includes purchased
credit protection on certain credit indices.
JPMorgan Chase & Co./2025 Form 10-K
121
Presented below is additional detail on certain of the Firm’s industry exposures.
Real Estate
Real Estate exposure was $224.9 billion as of December 31, 2025. Criticized exposure decreased by $714 million
from $12.4 billion at December 31, 2024 to $11.7 billion at December 31, 2025, driven by net portfolio activity,
predominantly offset by net downgrades.
December 31, 2025
(in millions, except ratios)
Loans and lending-
related commitments
Derivative
receivables
Credit
exposure
% Investment-grade
% Drawn
(d)
Multifamily
(a)
$
128,864
$
25
$
128,889
78 %
91 %
Other Income Producing Properties
(b)
23,390
229
23,619
46
53
Services and Non Income Producing
20,325
130
20,455
63
35
Industrial
19,541
13
19,554
67
69
Office
15,016
39
15,055
47
80
Retail
12,879
33
12,912
79
74
Lodging
4,366
8
4,374
26
48
Total Real Estate Exposure
(c)
$
224,381
$
477
$
224,858
69 %
77 %
December 31, 2024
(in millions, except ratios)
Loans and lending-
related commitments
Derivative
receivables
Credit
exposure
% Investment-grade
% Drawn
(d)
Multifamily
(a)
$
124,074
$
7
$
124,081
77 %
92 %
Other Income Producing Properties
(b)
16,411
158
16,569
50
63
Services and Non Income Producing
14,047
57
14,104
62
46
Industrial
19,092
17
19,109
65
72
Office
16,331
29
16,360
47
81
Retail
12,230
23
12,253
77
75
Lodging
4,555
19
4,574
31
53
Total Real Estate Exposure
$
206,740
$
310
$
207,050
69 %
82 %
(a)
Total Multifamily exposure is approximately 99% performing. Multifamily exposure is largely in California.
(b)
Other Income Producing Properties consists of clients with diversified property types or other property types, including data centers, outside
of categories listed in the table above.
(c)
Real Estate exposure is approximately 83% secured; unsecured exposure is largely investment-grade primarily to Real Estate Investment
Trusts (“REITs”) and Real Estate Operating Companies (“REOCs”) whose underlying assets are generally diversified.
(d)
Represents drawn exposure as a percentage of credit exposure.
Management’s discussion and analysis
122
JPMorgan Chase & Co./2025 Form 10-K
Consumer & Retail
Consumer & Retail exposure was $133.9 billion as of December 31, 2025. Criticized exposure increased by
$1.2 billion from $6.9 billion at December 31, 2024 to $8.0 billion at December 31, 2025, driven by net downgrades
and new lending-related commitments, largely offset by net portfolio activity.
December 31, 2025
(in millions, except ratios)
Loans and lending-
related commitments
Derivative
receivables
Credit
exposure
% Investment-grade
% Drawn
(d)
Business and Consumer Services
$
38,160
$
501
$
38,661
41 %
43 %
Retail
(a)
36,492
434
36,926
55
29
Food and Beverage
31,513
855
32,368
53
36
Consumer Hard Goods
14,824
309
15,133
43
33
Leisure
(b)
10,721
136
10,857
33
45
Total Consumer & Retail
(c)
$
131,710
$
2,235
$
133,945
47 %
37 %
December 31, 2024
(in millions, except ratios)
Loans and lending-
related commitments
Derivative
receivables
Credit
exposure
% Investment-grade
% Drawn
(d)
Business and Consumer Services
$
34,534
$
412
$
34,946
42 %
41 %
Retail
(a)
34,917
261
35,178
51
31
Food and Beverage
34,774
683
35,457
61
34
Consumer Hard Goods
13,796
208
14,004
43
35
Leisure
(b)
10,186
44
10,230
26
43
Total Consumer & Retail
$
128,207
$
1,608
$
129,815
48 %
36 %
(a)
Retail consists of Home Improvement & Specialty Retailers, Discount & Drug Stores, Restaurants, Specialty Apparel, Supermarkets, and
Department Stores.
(b)
Leisure consists of Arts & Culture, Travel Services, Gaming, and Sports & Recreation. As of December 31, 2025, approximately 88% of the
noninvestment-grade Leisure portfolio is secured.
(c)
Consumer & Retail exposure is approximately 57% secured; unsecured exposure is approximately 77% investment-grade.
(d)
Represents drawn exposure as a percentage of credit exposure.
JPMorgan Chase & Co./2025 Form 10-K
123
Loans
In its wholesale businesses, the Firm provides loans to
a variety of clients, ranging from large corporate and
institutional clients to high-net-worth individuals. Refer
to Note 12 for a further discussion on loans, including
information about delinquencies, loan modifications
and other credit quality indicators.
The following table presents the change in the
nonaccrual loan portfolio for the years ended
December 31, 2025 and 2024. Since December 31,
2024, nonaccrual loan exposure increased by $273
million, driven by certain exposures in Technology,
Media & Telecommunications, Utilities, Central
Government, and Oil & Gas, in each case primarily
resulting from downgrades, largely offset by certain
exposures in Healthcare and Consumer & Retail, in
each case primarily resulting from charge-off activity,
upgrades, and loan sales.
Wholesale nonaccrual loan activity
Year ended December 31,
(in millions)
2025
2024
Beginning balance
$
4,911
$
2,714
Additions
5,343
5,841
Reductions:
Paydowns and other
1,890
2,387
Gross charge-offs
1,481
780
Returned to performing status
1,538
392
Sales
161
85
Total reductions
5,070
3,644
Net changes
273
2,197
Ending balance
$
5,184
$
4,911
The following table presents net charge-offs/
recoveries, which are defined as gross charge-offs less
recoveries, for the years ended December 31, 2025
and 2024. The amounts in the table below do not
include gains or losses from sales of nonaccrual loans
recognized in noninterest revenue.
Wholesale net charge-offs increased for the year
ended December 31, 2025 compared to the prior year,
primarily due to increases in Commercial and
industrial, including in Technology, Media &
Telecommunications and Healthcare, as well as
estimated losses related to borrower fraud in certain
secured lending facilities.
Wholesale net charge-offs/(recoveries)
Year ended December 31,
(in millions, except ratios)
2025
2024
Loans
Average loans retained
$ 732,793
$ 673,310
Gross charge-offs
1,787
1,022
Gross recoveries collected
(189)
(200)
Net charge-offs/(recoveries)
1,598
822
Net charge-off/(recovery) rate
0.22 %
0.12 %
Management’s discussion and analysis
124
JPMorgan Chase & Co./2025 Form 10-K
Maturities and sensitivity to changes in interest rates
The table below sets forth wholesale loan maturities and the distribution between fixed and floating interest rates
based on the stated terms of the loan agreements by loan class. Refer to Note 12 for further information on loan
classes.
December 31, 2025
(in millions)
1 year or less
(b)
After 1 year
through 5 years
After 5 years
through 15 years
After 15 years
Total
Wholesale loans:
Secured by real estate
$
13,998
$
66,811
$
60,499
$
38,638
$
179,946
Commercial and industrial
52,480
118,190
18,486
156
189,312
Other
217,587
203,197
45,169
8,163
474,116
Total wholesale loans
$
284,065
$
388,198
$
124,154
$
46,957
$
843,374
Loans due after one year at fixed interest rates
Secured by real estate
$
14,737
$
14,356
$
915
Commercial and industrial
5,728
2,109
7
Other
28,116
15,459
4,797
Loans due after one year at variable interest rates
(a)
Secured by real estate
$
52,074
$
46,143
$
37,722
Commercial and industrial
112,463
16,377
148
Other
175,080
29,710
3,368
Total wholesale loans
$
388,198
$
124,154
$
46,957
(a)
Includes loans that have an initial fixed interest rate that resets to a variable rate as the variable rate will be the prevailing rate over the life of
the loan.
(b)
Includes loans held-for-sale, demand loans and overdrafts.
The following table presents net charge-offs/recoveries, average retained loans and net charge-off/recovery rate by
loan class for the years ended December 31, 2025 and 2024.
Year ended December 31,
(in millions, except ratios)
Secured by real estate
Commercial and
industrial
Other
Total
2025
2024
2025
2024
2025
2024
2025
2024
Net charge-offs/(recoveries)
$
390
$
313
$
882
$
381
$
326
$
128
$ 1,598
$
822
Average retained loans
162,567
162,653
169,149
169,363
401,077
341,294
732,793
673,310
Net charge-off/(recovery) rate
0.24 %
0.19 %
0.52 %
0.22 %
0.08 %
0.04 %
0.22 %
0.12 %
JPMorgan Chase & Co./2025 Form 10-K
125
Lending-related commitments
The Firm uses lending-related financial instruments,
such as commitments (including revolving credit
facilities) and guarantees, to address the financing
needs of its clients. The contractual amounts of these
financial instruments represent the maximum possible
credit risk should the clients draw down on these
commitments or when the Firm fulfills its obligations
under these guarantees, and the clients subsequently
fail to perform according to the terms of these contracts.
Most of these commitments and guarantees have
historically been refinanced, extended, cancelled, or
expired without being drawn upon or a default
occurring. As a result, the Firm does not believe that the
total contractual amount of these wholesale lending-
related commitments is representative of the Firm’s
expected future credit exposure or funding
requirements. Refer to Note 28 for further information
on wholesale lending-related commitments.
Receivables from customers
Receivables from customers reflect held-for-investment
margin loans to brokerage clients in CIB, CCB and AWM
that are collateralized by assets maintained in the
clients’ brokerage accounts (including cash on deposit,
and primarily liquid and readily marketable debt or
equity securities). To manage its credit risk, the Firm
establishes margin requirements and monitors the
required margin levels on an ongoing basis, and requires
clients to deposit additional cash or other collateral, or
to reduce positions, when appropriate. Credit risk arising
from lending activities subject to collateral maintenance
requirements is generally mitigated by factors such as
the short-term nature of the activity, the fair value of
collateral held and the Firm’s right to call for, and the
borrower’s obligation to provide, additional margin when
the fair value of the collateral declines. Because of these
mitigating factors, these receivables generally do not
require an allowance for credit losses. However, if in
management’s judgment, an allowance for credit losses
is required, the Firm estimates expected credit losses
based on the value of the collateral and probability of
borrower default. These receivables are reported within
accrued interest and accounts receivable on the Firm’s
Consolidated balance sheets.
Refer to Note 13 for further information on the Firm’s
accounting policies for the allowance for credit losses.
Derivative contracts
Derivatives enable clients and counterparties to manage
risk, including credit risk and risks arising from
fluctuations in interest rates, foreign exchange and
equities and commodities prices. The Firm makes
markets in derivatives in order to meet these needs and
uses derivatives to manage certain risks associated with
net open risk positions from its market-making
activities, including the counterparty credit risk arising
from derivative receivables. The Firm also uses
derivative instruments to manage its own credit risk and
other market risk exposure. The nature of the
counterparty and the settlement mechanism of the
derivative affect the credit risk to which the Firm is
exposed. For over-the-counter (“OTC”) derivatives, the
Firm is exposed to the credit risk of the derivative
counterparty. For exchange-traded derivatives (“ETD”),
such as futures and options, and cleared over-the-
counter (“OTC-cleared”) derivatives, the Firm can also
be exposed to the credit risk of the relevant CCP. Where
possible, the Firm seeks to mitigate its credit risk
exposures arising from derivative contracts through the
use of legally enforceable master netting arrangements
and collateral agreements. The percentage of the Firm’s
OTC derivative transactions subject to collateral
agreements — excluding foreign exchange spot trades,
which are not typically covered by collateral agreements
due to their short maturity and centrally cleared trades
that are settled daily — was approximately 86% at both
December 31, 2025 and 2024. Refer to Note 5 for
additional information on the Firm’s use of collateral
agreements and for a further discussion of derivative
contracts, counterparties and settlement types.
The fair value of derivative receivables reported on the
Consolidated balance sheets was $57.8 billion and $61.0
billion at December 31, 2025 and 2024, respectively. The
decrease was primarily as a result of market
movements. Derivative receivables represent the fair
value of the derivative contracts after giving effect to
legally enforceable master netting agreements and the
related cash collateral held by the Firm.
In addition, the Firm holds liquid securities and other
cash collateral that may be used as security when the
fair value of the client’s exposure is in the Firm’s favor.
For these purposes, the definition of liquid securities is
consistent with the definition of high quality liquid assets
as defined in the LCR rule.
In management’s view, the appropriate measure of
current credit risk should also take into consideration
other collateral, which generally represents securities
that do not qualify as high quality liquid assets under the
LCR rule. The benefits of these additional collateral
amounts for each counterparty are subject to a legally
enforceable master netting agreement and limited to the
net amount of the derivative receivables for each
counterparty.
The Firm also holds additional collateral (primarily cash,
G7 government securities, other liquid government
agency and guaranteed securities, and corporate debt
and equity securities) delivered by clients at the
initiation of transactions, as well as collateral related to
contracts that have a non-daily call frequency and
collateral that the Firm has agreed to return but has not
yet settled as of the reporting date. Although this
collateral does not reduce the receivables balances and
is not included in the tables below, it is available as
security against potential exposure that could arise
should the fair value of the client’s derivative contracts
move in the Firm’s favor. Refer to Note 5 for additional
information on the Firm’s use of collateral agreements
for derivative transactions.
Management’s discussion and analysis
126
JPMorgan Chase & Co./2025 Form 10-K
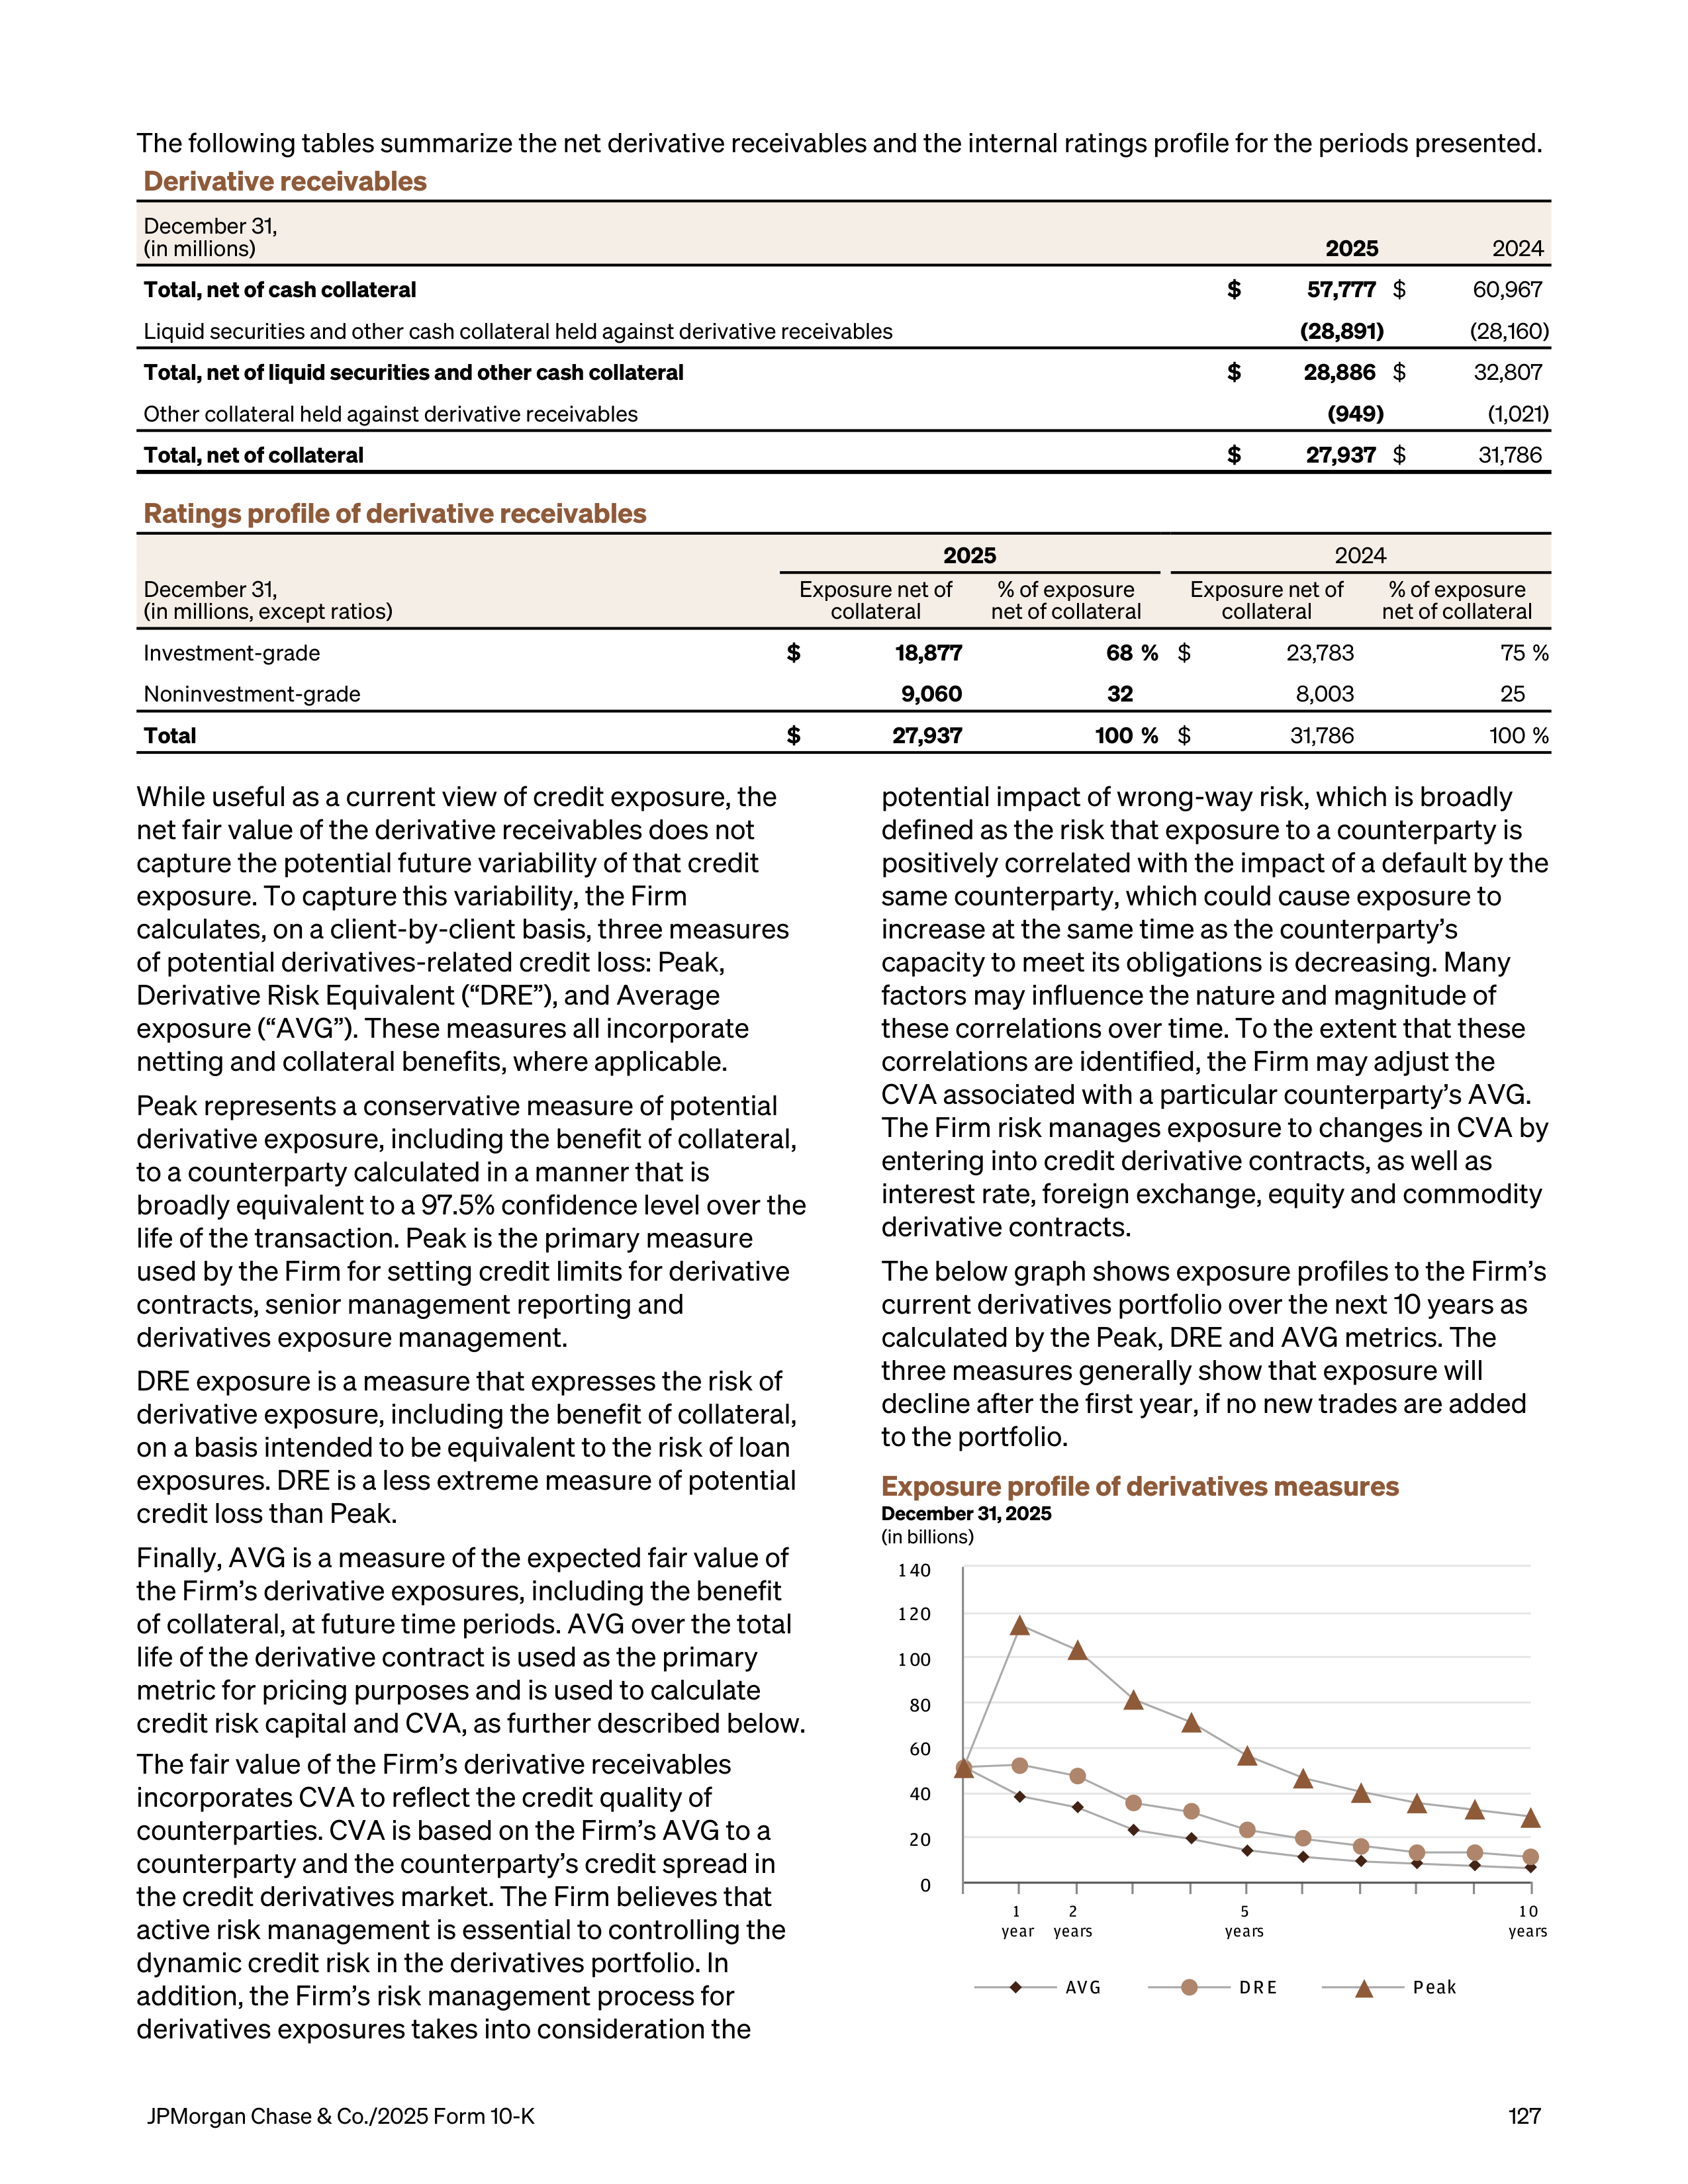
The following tables summarize the net derivative receivables and the internal ratings profile for the periods presented.
Derivative receivables
December 31,
(in millions)
2025
2024
Total, net of cash collateral
$
57,777
$
60,967
Liquid securities and other cash collateral held against derivative receivables
(28,891)
(28,160)
Total, net of liquid securities and other cash collateral
$
28,886
$
32,807
Other collateral held against derivative receivables
(949)
(1,021)
Total, net of collateral
$
27,937
$
31,786
Ratings profile of derivative receivables
2025
2024
December 31,
(in millions, except ratios)
Exposure net of
collateral
% of exposure
net of collateral
Exposure net of
collateral
% of exposure
net of collateral
Investment-grade
$
18,877
68 %
$
23,783
75 %
Noninvestment-grade
9,060
32
8,003
25
Total
$
27,937
100 %
$
31,786
100 %
While useful as a current view of credit exposure, the
net fair value of the derivative receivables does not
capture the potential future variability of that credit
exposure. To capture this variability, the Firm
calculates, on a client-by-client basis, three measures
of potential derivatives-related credit loss: Peak,
Derivative Risk Equivalent (“DRE”), and Average
exposure (“AVG”). These measures all incorporate
netting and collateral benefits, where applicable.
Peak represents a conservative measure of potential
derivative exposure, including the benefit of collateral,
to a counterparty calculated in a manner that is
broadly equivalent to a 97.5% confidence level over the
life of the transaction. Peak is the primary measure
used by the Firm for setting credit limits for derivative
contracts, senior management reporting and
derivatives exposure management.
DRE exposure is a measure that expresses the risk of
derivative exposure, including the benefit of collateral,
on a basis intended to be equivalent to the risk of loan
exposures. DRE is a less extreme measure of potential
credit loss than Peak.
Finally, AVG is a measure of the expected fair value of
the Firm’s derivative exposures, including the benefit
of collateral, at future time periods. AVG over the total
life of the derivative contract is used as the primary
metric for pricing purposes and is used to calculate
credit risk capital and CVA, as further described below.
The fair value of the Firm’s derivative receivables
incorporates CVA to reflect the credit quality of
counterparties. CVA is based on the Firm’s AVG to a
counterparty and the counterparty’s credit spread in
the credit derivatives market. The Firm believes that
active risk management is essential to controlling the
dynamic credit risk in the derivatives portfolio. In
addition, the Firm’s risk management process for
derivatives exposures takes into consideration the
potential impact of wrong-way risk, which is broadly
defined as the risk that exposure to a counterparty is
positively correlated with the impact of a default by the
same counterparty, which could cause exposure to
increase at the same time as the counterparty’s
capacity to meet its obligations is decreasing. Many
factors may influence the nature and magnitude of
these correlations over time. To the extent that these
correlations are identified, the Firm may adjust the
CVA associated with a particular counterparty’s AVG.
The Firm risk manages exposure to changes in CVA by
entering into credit derivative contracts, as well as
interest rate, foreign exchange, equity and commodity
derivative contracts.
The below graph shows exposure profiles to the Firm’s
current derivatives portfolio over the next 10 years as
calculated by the Peak, DRE and AVG metrics. The
three measures generally show that exposure will
decline after the first year, if no new trades are added
to the portfolio.
Exposure profile of derivatives measures
December 31, 2025
(in billions)
AVG
DR E
Peak
1
year
2
years
5
years
1 0
years
0
20
40
60
80
1 00
1 20
1 40
JPMorgan Chase & Co./2025 Form 10-K
127
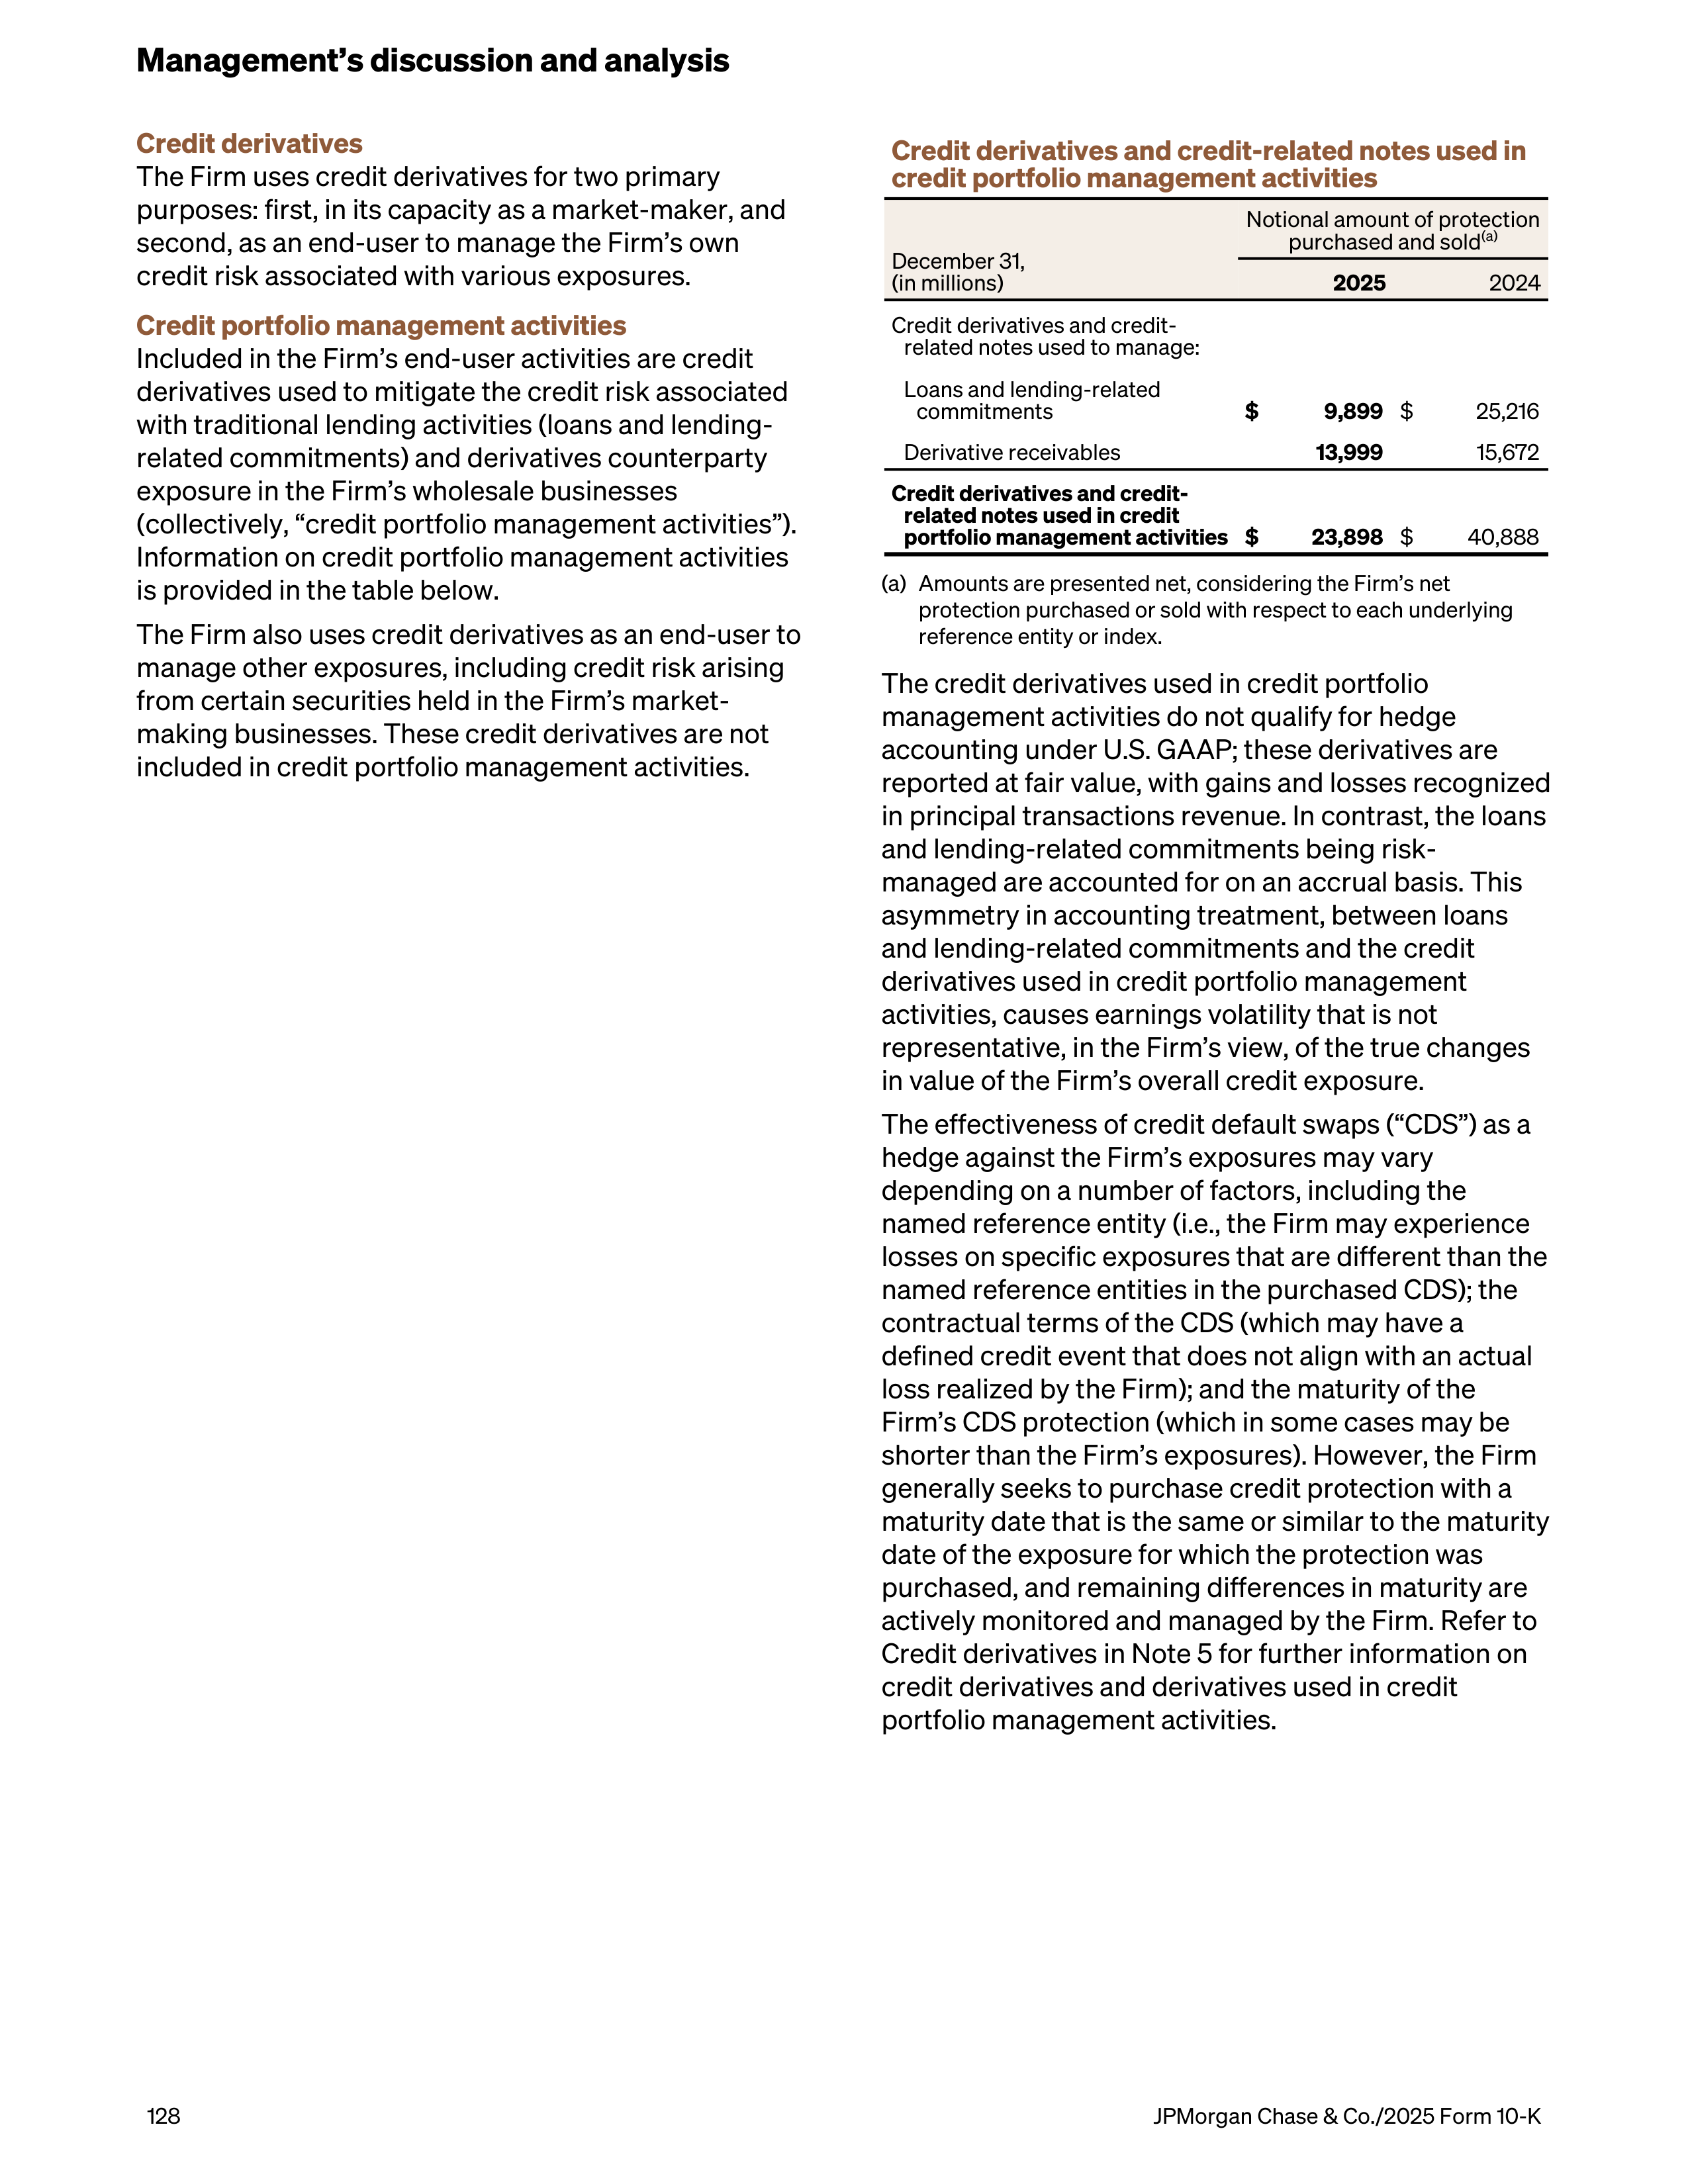
Credit derivatives
The Firm uses credit derivatives for two primary
purposes: first, in its capacity as a market-maker, and
second, as an end-user to manage the Firm’s own
credit risk associated with various exposures.
Credit portfolio management activities
Included in the Firm’s end-user activities are credit
derivatives used to mitigate the credit risk associated
with traditional lending activities (loans and lending-
related commitments) and derivatives counterparty
exposure in the Firm’s wholesale businesses
(collectively, “credit portfolio management activities”).
Information on credit portfolio management activities
is provided in the table below.
The Firm also uses credit derivatives as an end-user to
manage other exposures, including credit risk arising
from certain securities held in the Firm’s market-
making businesses. These credit derivatives are not
included in credit portfolio management activities.
Credit derivatives and credit-related notes used in
credit portfolio management activities
December 31,
(in millions)
Notional amount of protection
purchased and sold
(a)
2025
2024
Credit derivatives and credit-
related notes used to manage:
Loans and lending-related
commitments
$
9,899
$
25,216
Derivative receivables
13,999
15,672
Credit derivatives and credit-
related notes used in credit
portfolio management activities
$
23,898
$
40,888
(a)
Amounts are presented net, considering the Firm’s net
protection purchased or sold with respect to each underlying
reference entity or index.
The credit derivatives used in credit portfolio
management activities do not qualify for hedge
accounting under U.S. GAAP; these derivatives are
reported at fair value, with gains and losses recognized
in principal transactions revenue. In contrast, the loans
and lending-related commitments being risk-
managed are accounted for on an accrual basis. This
asymmetry in accounting treatment, between loans
and lending-related commitments and the credit
derivatives used in credit portfolio management
activities, causes earnings volatility that is not
representative, in the Firm’s view, of the true changes
in value of the Firm’s overall credit exposure.
The effectiveness of credit default swaps (“CDS”) as a
hedge against the Firm’s exposures may vary
depending on a number of factors, including the
named reference entity (i.e., the Firm may experience
losses on specific exposures that are different than the
named reference entities in the purchased CDS); the
contractual terms of the CDS (which may have a
defined credit event that does not align with an actual
loss realized by the Firm); and the maturity of the
Firm’s CDS protection (which in some cases may be
shorter than the Firm’s exposures). However, the Firm
generally seeks to purchase credit protection with a
maturity date that is the same or similar to the maturity
date of the exposure for which the protection was
purchased, and remaining differences in maturity are
actively monitored and managed by the Firm. Refer to
Credit derivatives in Note 5 for further information on
credit derivatives and derivatives used in credit
portfolio management activities.
Management’s discussion and analysis
128
JPMorgan Chase & Co./2025 Form 10-K
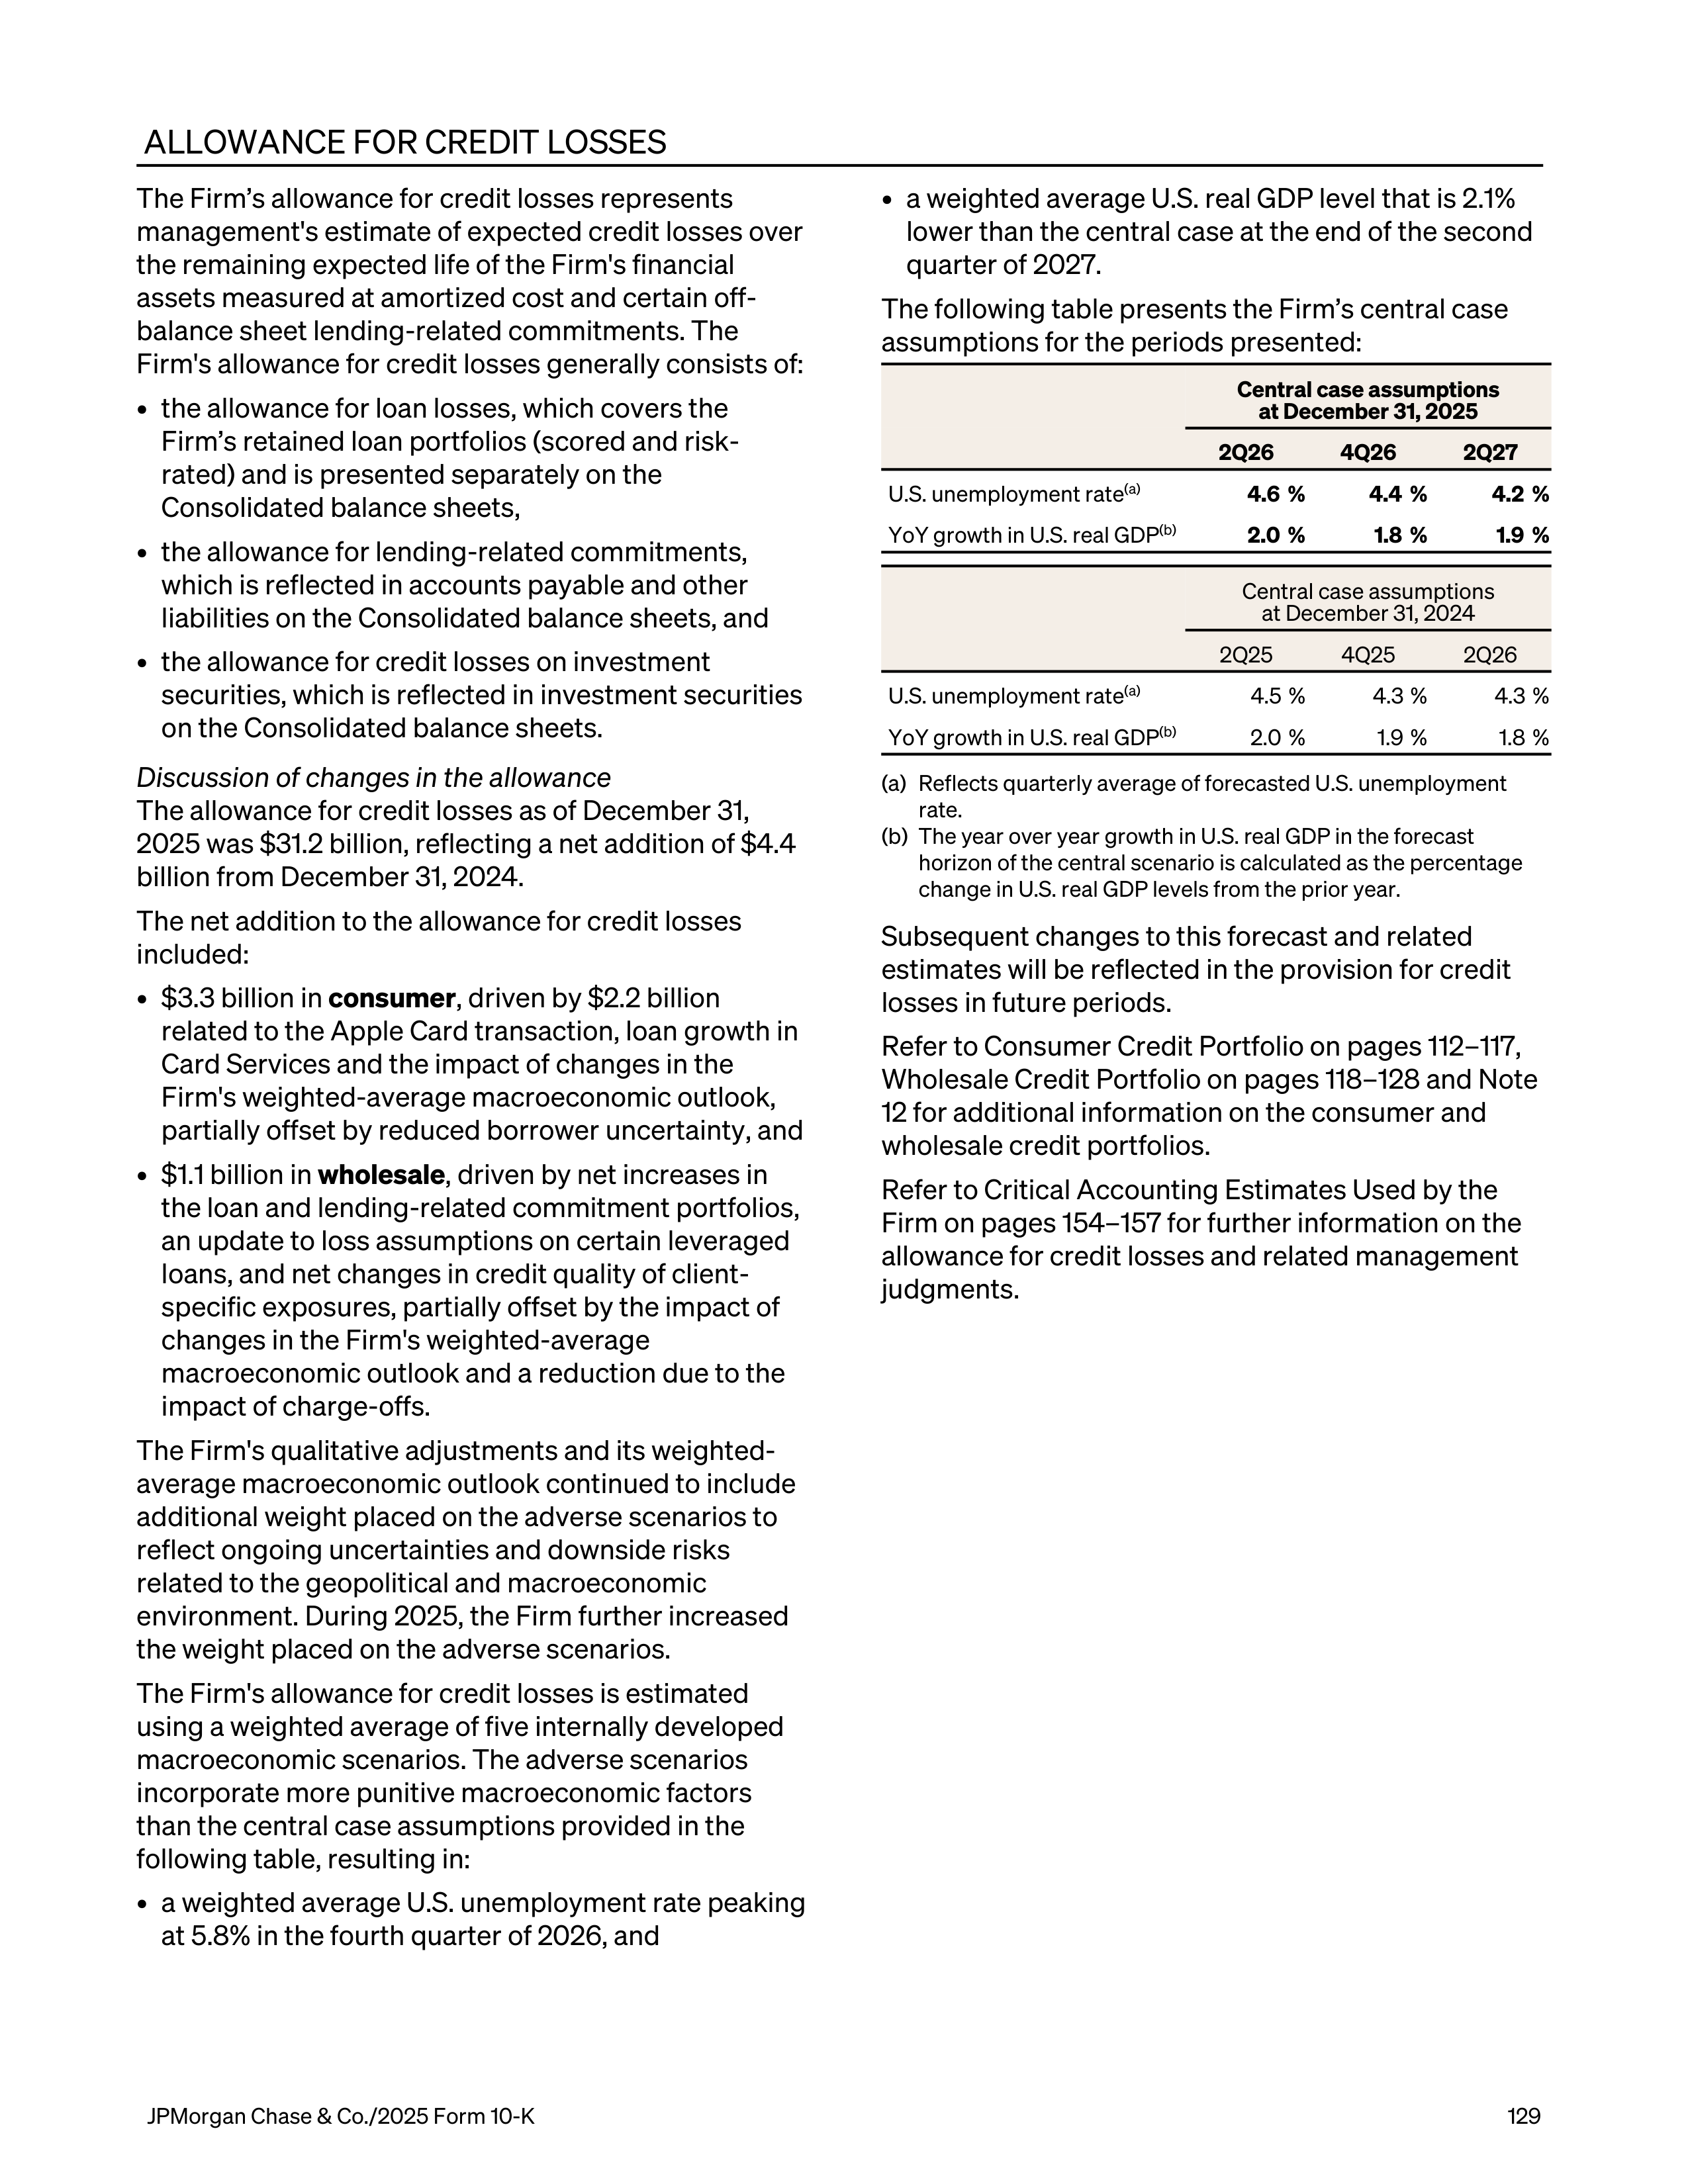
ALLOWANCE FOR CREDIT LOSSES
The Firm’s allowance for credit losses represents
management's estimate of expected credit losses over
the remaining expected life of the Firm's financial
assets measured at amortized cost and certain off-
balance sheet lending-related commitments. The
Firm's allowance for credit losses generally consists of:
•
the allowance for loan losses, which covers the
Firm’s retained loan portfolios (scored and risk-
rated) and is presented separately on the
Consolidated balance sheets,
•
the allowance for lending-related commitments,
which is reflected in accounts payable and other
liabilities on the Consolidated balance sheets, and
•
the allowance for credit losses on investment
securities, which is reflected in investment securities
on the Consolidated balance sheets.
Discussion of changes in the allowance
The allowance for credit losses as of December 31,
2025 was $31.2 billion, reflecting a net addition of $4.4
billion from December 31, 2024.
The net addition to the allowance for credit losses
included:
•
$3.3 billion in
consumer
, driven by $2.2 billion
related to the Apple Card transaction, loan growth in
Card Services and the impact of changes in the
Firm's weighted-average macroeconomic outlook,
partially offset by reduced borrower uncertainty, and
•
$1.1 billion in
wholesale
, driven by net increases in
the loan and lending-related commitment portfolios,
an update to loss assumptions on certain leveraged
loans, and net changes in credit quality of client-
specific exposures, partially offset by the impact of
changes in the Firm's weighted-average
macroeconomic outlook and a reduction due to the
impact of charge-offs.
The Firm's qualitative adjustments and its weighted-
average macroeconomic outlook continued to include
additional weight placed on the adverse scenarios to
reflect ongoing uncertainties and downside risks
related to the geopolitical and macroeconomic
environment. During 2025, the Firm further increased
the weight placed on the adverse scenarios.
The Firm's allowance for credit losses is estimated
using a weighted average of five internally developed
macroeconomic scenarios. The adverse scenarios
incorporate more punitive macroeconomic factors
than the central case assumptions provided in the
following table, resulting in:
•
a weighted average U.S. unemployment rate peaking
at 5.8% in the fourth quarter of 2026, and
•
a weighted average U.S. real GDP level that is 2.1%
lower than the central case at the end of the second
quarter of 2027.
The following table presents the Firm’s central case
assumptions for the periods presented:
Central case assumptions
at December 31, 2025
2Q26
4Q26
2Q27
U.S. unemployment rate
(a)
4.6 %
4.4 %
4.2 %
YoY growth in U.S. real GDP
(b)
2.0 %
1.8 %
1.9 %
Central case assumptions
at December 31, 2024
2Q25
4Q25
2Q26
U.S. unemployment rate
(a)
4.5 %
4.3 %
4.3 %
YoY growth in U.S. real GDP
(b)
2.0 %
1.9 %
1.8 %
(a)
Reflects quarterly average of forecasted U.S. unemployment
rate.
(b)
The year over year growth in U.S. real GDP in the forecast
horizon of the central scenario is calculated as the percentage
change in U.S. real GDP levels from the prior year.
Subsequent changes to this forecast and related
estimates will be reflected in the provision for credit
losses in future periods.
Refer to Consumer Credit Portfolio on pages 112–117,
Wholesale Credit Portfolio on pages 118–128 and Note
12 for additional information on the consumer and
wholesale credit portfolios.
Refer to Critical Accounting Estimates Used by the
Firm on pages 154–157 for further information on the
allowance for credit losses and related management
judgments.
JPMorgan Chase & Co./2025 Form 10-K
129
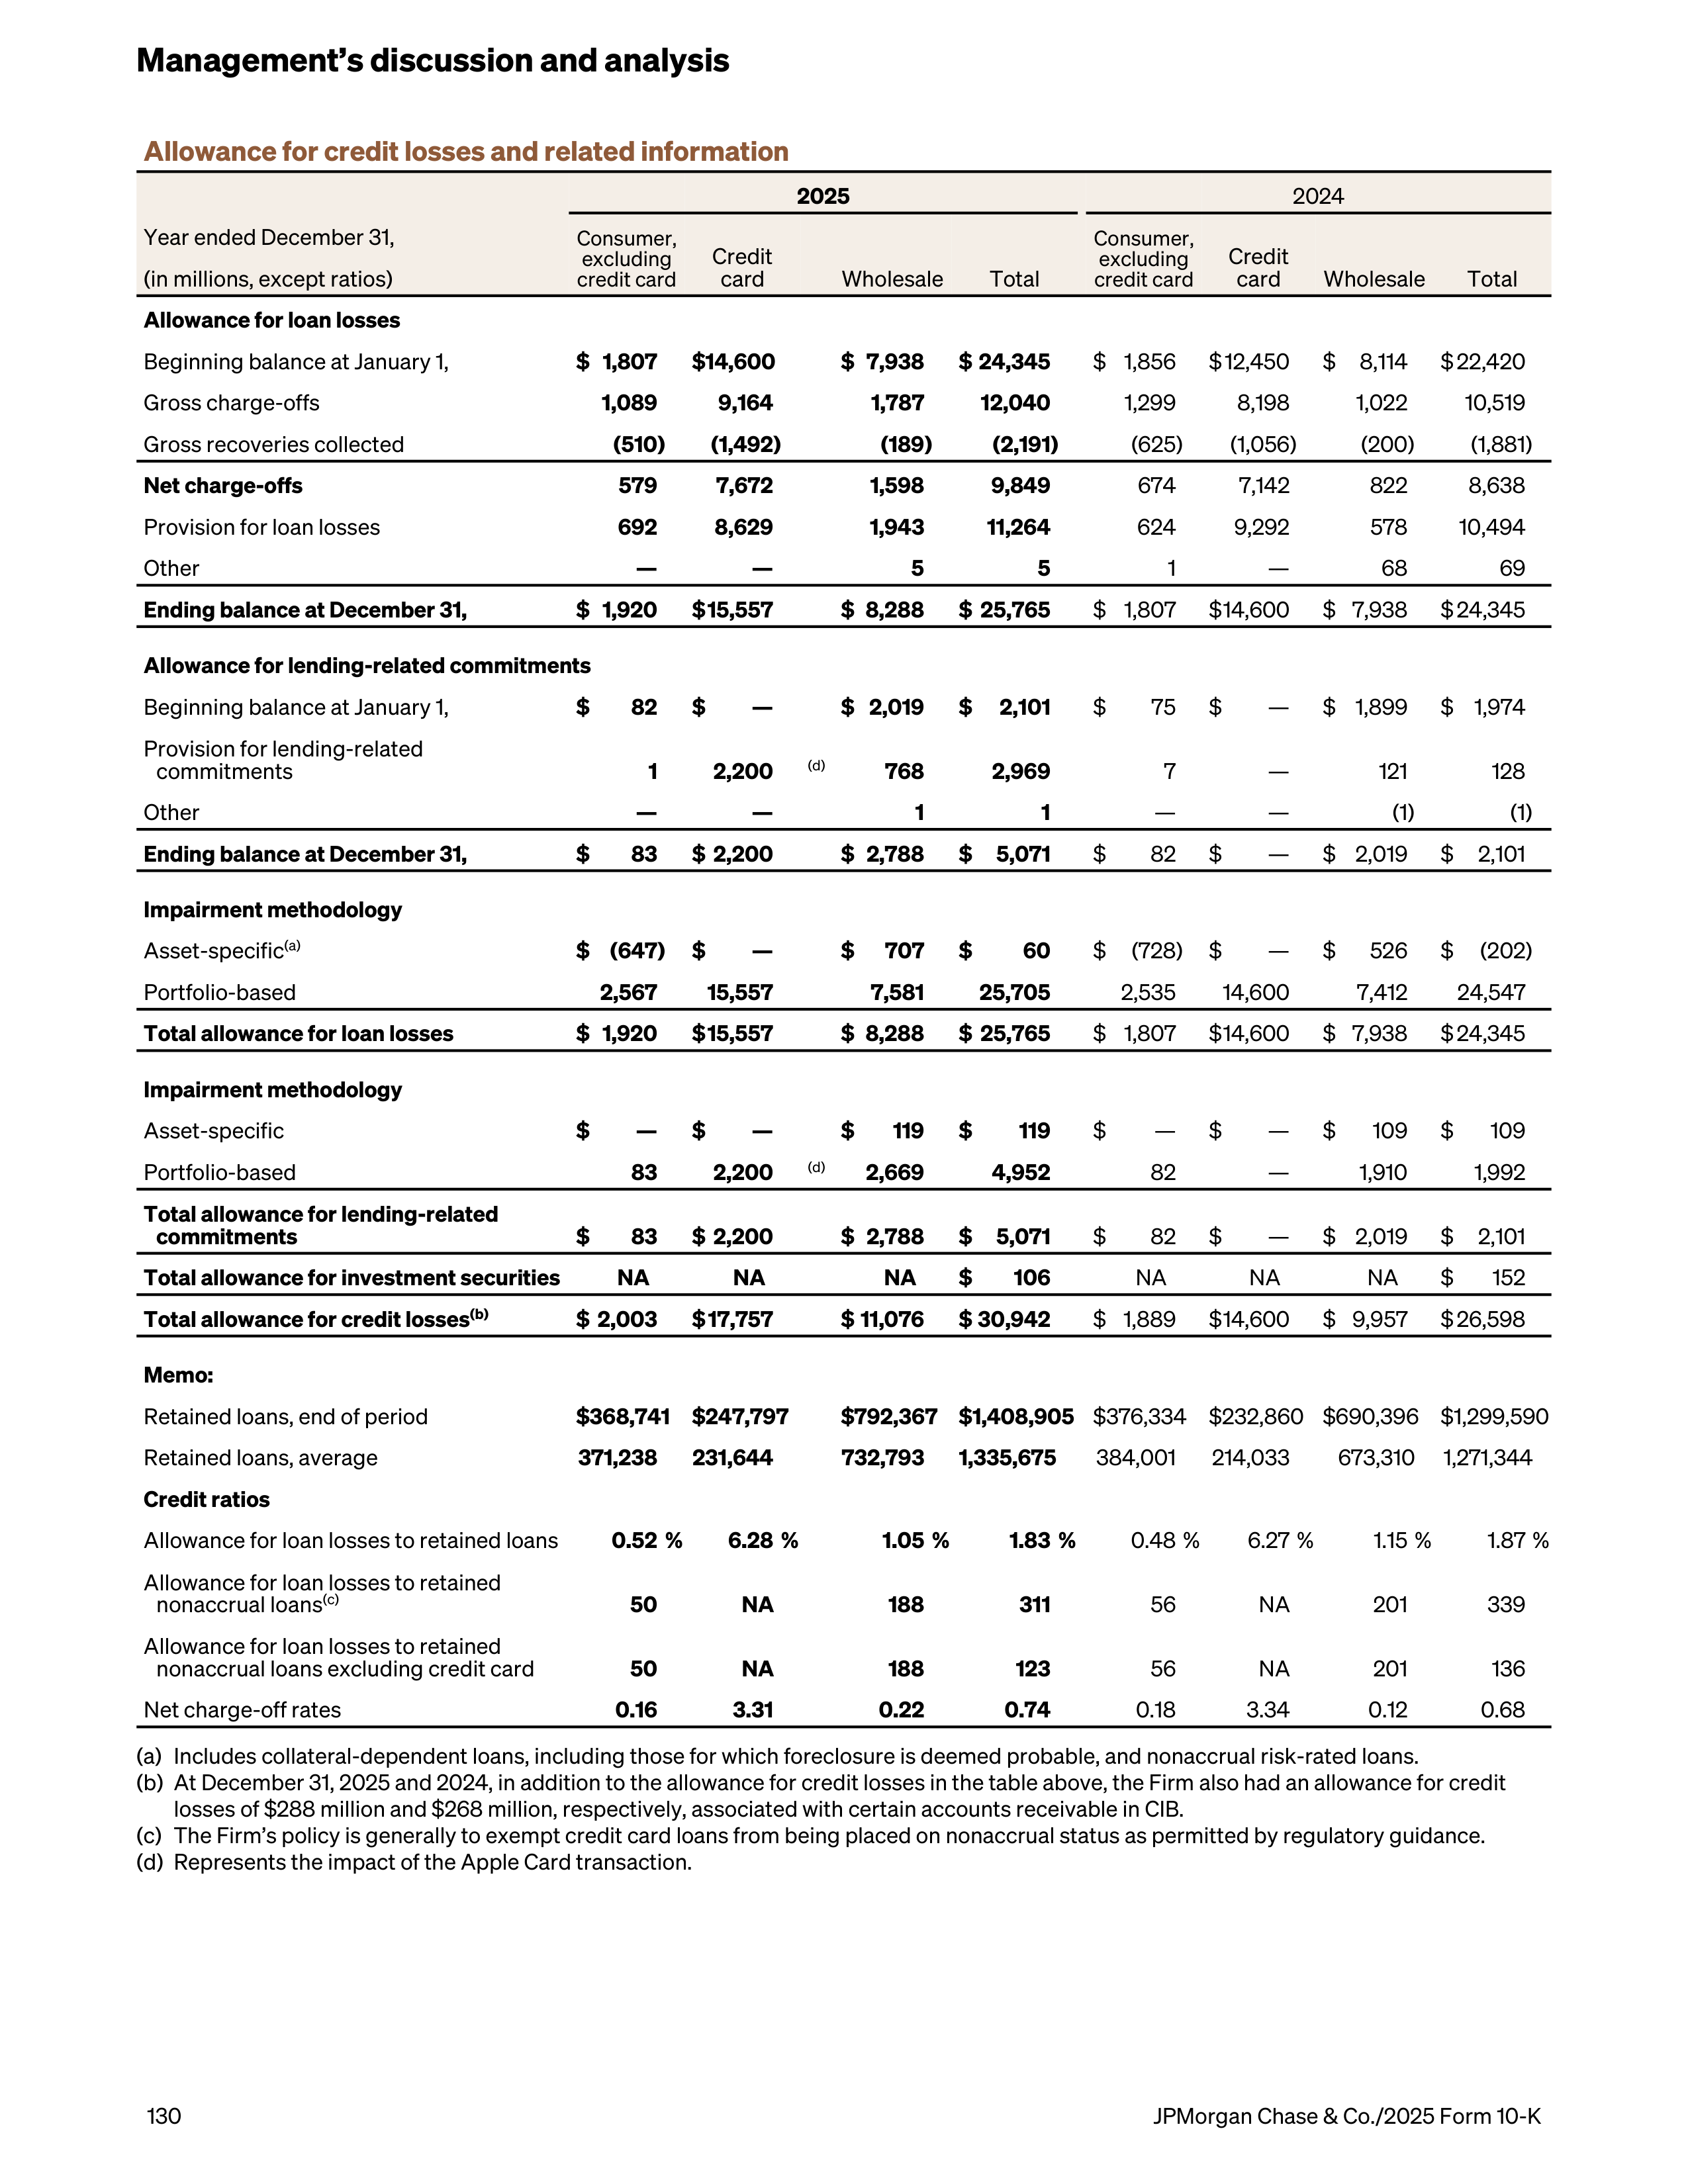
Allowance for credit losses and related information
2025
2024
Year ended December 31,
Consumer,
excluding
credit card
Credit
card
Wholesale
Total
Consumer,
excluding
credit card
Credit
card
Wholesale
Total
(in millions, except ratios)
Allowance for loan losses
Beginning balance at January 1,
$ 1,807
$ 14,600
$ 7,938
$ 24,345
$ 1,856
$ 12,450
$
8,114
$ 22,420
Gross charge-offs
1,089
9,164
1,787
12,040
1,299
8,198
1,022
10,519
Gross recoveries collected
(510)
(1,492)
(189)
(2,191)
(625)
(1,056)
(200)
(1,881)
Net charge-offs
579
7,672
1,598
9,849
674
7,142
822
8,638
Provision for loan losses
692
8,629
1,943
11,264
624
9,292
578
10,494
Other
—
—
5
5
1
—
68
69
Ending balance at December 31,
$ 1,920
$ 15,557
$ 8,288
$ 25,765
$ 1,807
$ 14,600
$ 7,938
$ 24,345
Allowance for lending-related commitments
Beginning balance at January 1,
$
82
$
—
$ 2,019
$
2,101
$
75
$
—
$ 1,899
$ 1,974
Provision for lending-related
commitments
1
2,200
(d)
768
2,969
7
—
121
128
Other
—
—
1
1
—
—
(1)
(1)
Ending balance at December 31,
$
83
$ 2,200
$ 2,788
$
5,071
$
82
$
—
$ 2,019
$
2,101
Impairment methodology
Asset-specific
(a)
$ (647)
$
—
$
707
$
60
$
(728)
$
—
$
526
$
(202)
Portfolio-based
2,567
15,557
7,581
25,705
2,535
14,600
7,412
24,547
Total allowance for loan losses
$ 1,920
$ 15,557
$ 8,288
$ 25,765
$ 1,807
$ 14,600
$ 7,938
$ 24,345
Impairment methodology
Asset-specific
$
—
$
—
$
119
$
119
$
—
$
—
$
109
$
109
Portfolio-based
83
2,200
(d)
2,669
4,952
82
—
1,910
1,992
Total allowance for lending-related
commitments
$
83
$ 2,200
$ 2,788
$
5,071
$
82
$
—
$ 2,019
$
2,101
Total allowance for investment securities
NA
NA
NA
$
106
NA
NA
NA
$
152
Total allowance for credit losses
(b)
$ 2,003
$ 17,757
$ 11,076
$ 30,942
$ 1,889
$ 14,600
$ 9,957
$ 26,598
Memo:
Retained loans, end of period
$ 368,741 $ 247,797
$ 792,367 $ 1,408,905
$ 376,334
$ 232,860 $ 690,396 $ 1,299,590
Retained loans, average
371,238
231,644
732,793
1,335,675
384,001
214,033
673,310
1,271,344
Credit ratios
Allowance for loan losses to retained loans
0.52 %
6.28 %
1.05 %
1.83 %
0.48 %
6.27 %
1.15 %
1.87 %
Allowance for loan losses to retained
nonaccrual loans
(c)
50
NA
188
311
56
NA
201
339
Allowance for loan losses to retained
nonaccrual loans excluding credit card
50
NA
188
123
56
NA
201
136
Net charge-off rates
0.16
3.31
0.22
0.74
0.18
3.34
0.12
0.68
(a)
Includes collateral-dependent loans, including those for which foreclosure is deemed probable, and nonaccrual risk-rated loans.
(b)
At December 31, 2025 and 2024, in addition to the allowance for credit losses in the table above, the Firm also had an allowance for credit
losses of $288 million and $268 million, respectively, associated with certain accounts receivable in CIB.
(c)
The Firm’s policy is generally to exempt credit card loans from being placed on nonaccrual status as permitted by regulatory guidance.
(d)
Represents the impact of the Apple Card transaction.
Management’s discussion and analysis
130
JPMorgan Chase & Co./2025 Form 10-K
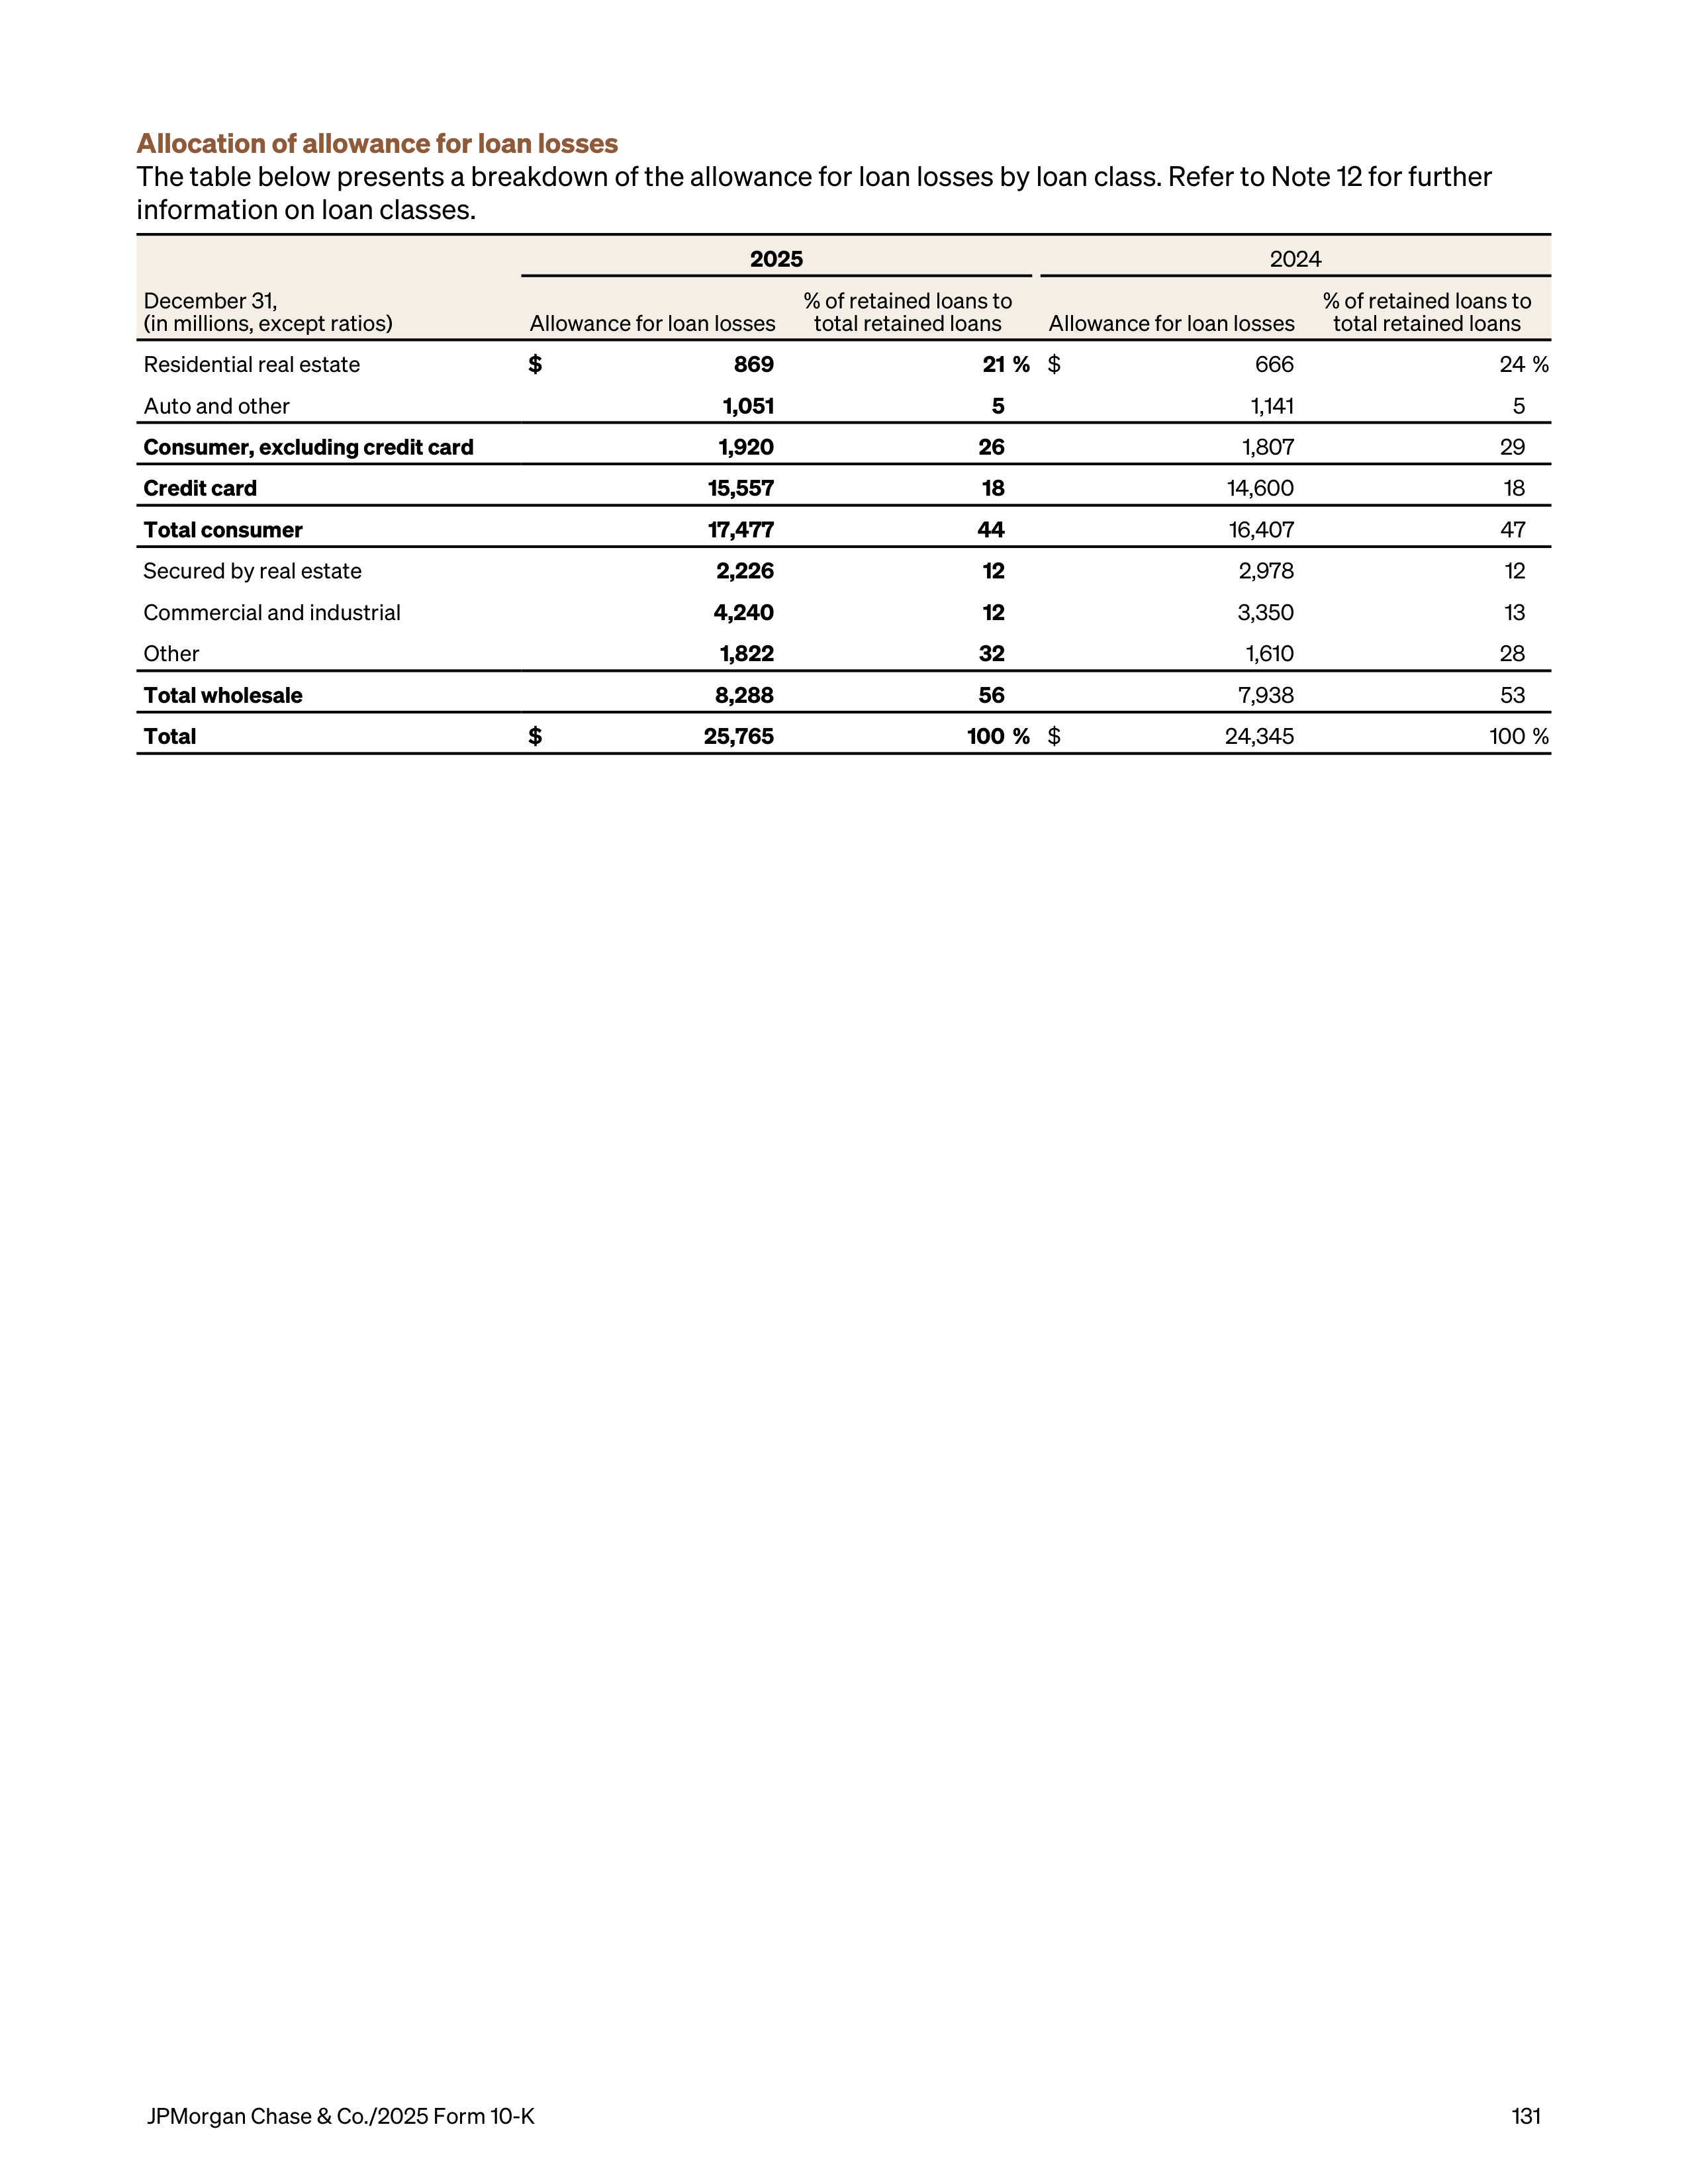
Allocation of allowance for loan losses
The table below presents a breakdown of the allowance for loan losses by loan class. Refer to Note 12 for further
information on loan classes.
2025
2024
December 31,
(in millions, except ratios)
Allowance for loan losses
% of retained loans to
total retained loans
Allowance for loan losses
% of retained loans to
total retained loans
Residential real estate
$
869
21 %
$
666
24 %
Auto and other
1,051
5
1,141
5
Consumer, excluding credit card
1,920
26
1,807
29
Credit card
15,557
18
14,600
18
Total consumer
17,477
44
16,407
47
Secured by real estate
2,226
12
2,978
12
Commercial and industrial
4,240
12
3,350
13
Other
1,822
32
1,610
28
Total wholesale
8,288
56
7,938
53
Total
$
25,765
100 %
$
24,345
100 %
JPMorgan Chase & Co./2025 Form 10-K
131
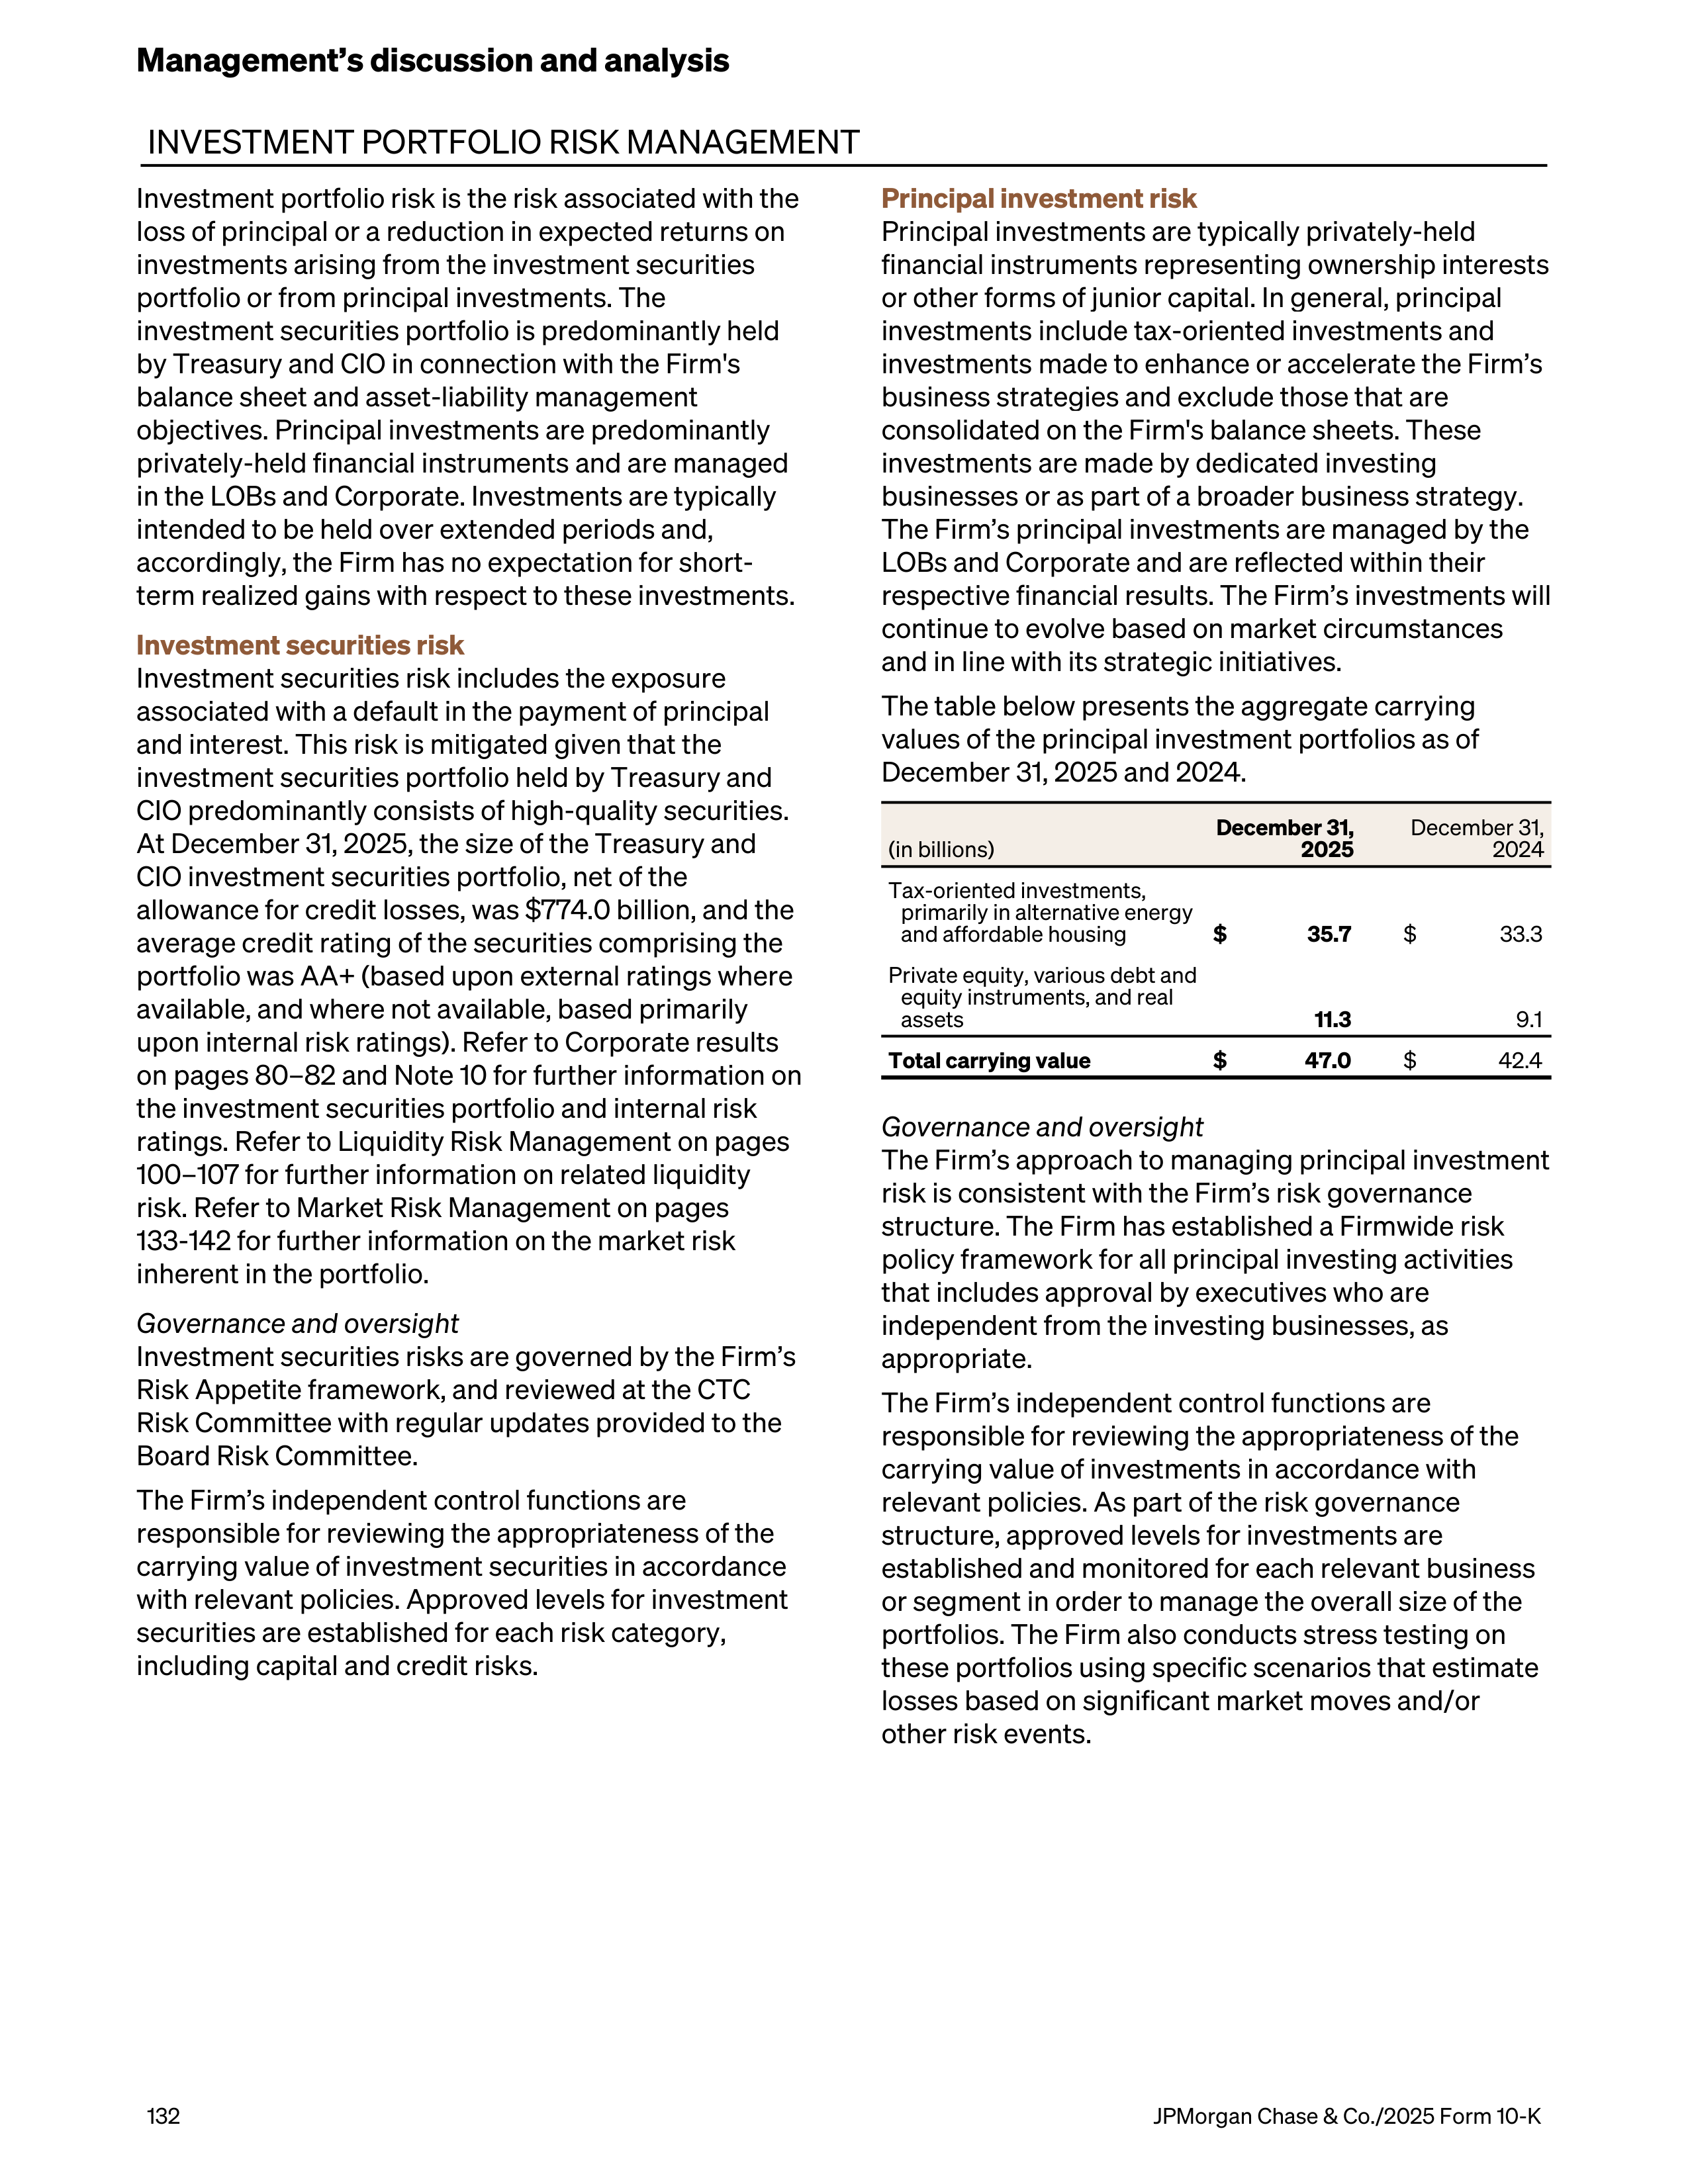
INVESTMENT PORTFOLIO RISK MANAGEMENT
Investment portfolio risk is the risk associated with the
loss of principal or a reduction in expected returns on
investments arising from the investment securities
portfolio or from principal investments. The
investment securities portfolio is predominantly held
by Treasury and CIO in connection with the Firm's
balance sheet and asset-liability management
objectives. Principal investments are predominantly
privately-held financial instruments and are managed
in the LOBs and Corporate. Investments are typically
intended to be held over extended periods and,
accordingly, the Firm has no expectation for short-
term realized gains with respect to these investments.
Investment securities risk
Investment securities risk includes the exposure
associated with a default in the payment of principal
and interest. This risk is mitigated given that the
investment securities portfolio held by Treasury and
CIO predominantly consists of high-quality securities.
At December 31, 2025, the size of the Treasury and
CIO investment securities portfolio, net of the
allowance for credit losses, was $774.0 billion, and the
average credit rating of the securities comprising the
portfolio was AA+ (based upon external ratings where
available, and where not available, based primarily
upon internal risk ratings). Refer to Corporate results
on pages 80–82 and Note 10 for further information on
the investment securities portfolio and internal risk
ratings. Refer to Liquidity Risk Management on pages
100–107 for further information on related liquidity
risk. Refer to Market Risk Management on pages
133-142 for further information on the market risk
inherent in the portfolio.
Governance and oversight
Investment securities risks are governed by the Firm’s
Risk Appetite framework, and reviewed at the CTC
Risk Committee with regular updates provided to the
Board Risk Committee.
The Firm’s independent control functions are
responsible for reviewing the appropriateness of the
carrying value of investment securities in accordance
with relevant policies. Approved levels for investment
securities are established for each risk category,
including capital and credit risks.
Principal investment risk
Principal investments are typically privately-held
financial instruments representing ownership interests
or other forms of junior capital. In general, principal
investments include tax-oriented investments and
investments made to enhance or accelerate the Firm’s
business strategies and exclude those that are
consolidated on the Firm's balance sheets. These
investments are made by dedicated investing
businesses or as part of a broader business strategy.
The Firm’s principal investments are managed by the
LOBs and Corporate and are reflected within their
respective financial results. The Firm’s investments will
continue to evolve based on market circumstances
and in line with its strategic initiatives.
The table below presents the aggregate carrying
values of the principal investment portfolios as of
December 31, 2025 and 2024.
(in billions)
December 31,
2025
December 31,
2024
Tax-oriented investments,
primarily in alternative energy
and affordable housing
$
35.7
$
33.3
Private equity, various debt and
equity instruments, and real
assets
11.3
9.1
Total carrying value
$
47.0
$
42.4
Governance and oversight
The Firm’s approach to managing principal investment
risk is consistent with the Firm’s risk governance
structure. The Firm has established a Firmwide risk
policy framework for all principal investing activities
that includes approval by executives who are
independent from the investing businesses, as
appropriate.
The Firm’s independent control functions
are
responsible for reviewing the appropriateness of the
carrying value of investments in accordance with
relevant policies. As part of the risk governance
structure, approved levels for investments are
established and monitored for each relevant business
or segment in order to manage the overall size of the
portfolios. The Firm also conducts stress testing on
these portfolios using specific scenarios that estimate
losses based on significant market moves and/or
other risk events.
Management’s discussion and analysis
132
JPMorgan Chase & Co./2025 Form 10-K
MARKET RISK MANAGEMENT
Market risk is the risk associated with the effect of
changes in market factors such as interest and foreign
exchange rates, equity and commodity prices, credit
spreads or implied volatilities, on the value of assets
and liabilities held for both the short and long term.
Market Risk Management
Market Risk Management monitors market risks
throughout the Firm and defines market risk policies
and procedures.
Market Risk Management seeks to measure risk,
facilitate efficient risk/return decisions, reduce
volatility in operating performance and provide
transparency into the Firm’s market risk profile for
senior management, the Board of Directors and
regulators. Market Risk Management is responsible for
the following functions:
•
Maintaining a market risk policy framework
•
Independently measuring and monitoring LOB,
Corporate, and Firmwide market risk
•
Defining, approving and monitoring limits
•
Performing stress testing and qualitative risk
assessments
Risk measurement
Measures used to capture market risk
There is no single measure to capture market risk and
therefore Market Risk Management uses various
metrics, both statistical and nonstatistical, to assess
risk including:
•
Value-at-risk
•
Stress testing
•
Profit and loss drawdowns
•
Earnings-at-risk
•
Economic value sensitivity
•
Other sensitivity-based measures
Risk monitoring and control
Market risk exposure is managed primarily through a
series of limits set in the context of the market
environment and business strategy. In setting limits,
Market Risk Management takes into consideration
factors such as market volatility, product liquidity,
accommodation of client business, and management
judgment. Market Risk Management maintains
different levels of limits. Firm level limits include VaR
and stress limits. Similarly, LOB and Corporate limits
include VaR and stress limits and may be
supplemented by certain nonstatistical risk measures
such as profit and loss drawdowns. Limits may also be
set within the LOBs and Corporate, as well as at the
legal entity level.
Market Risk Management sets limits and regularly
reviews and updates them as appropriate. Senior
management is responsible for reviewing and
approving certain of these risk limits on an ongoing
basis. Limits that have not been reviewed within
specified time periods by Market Risk Management
are reported to senior management. The LOBs and
Corporate are responsible for adhering to established
limits against which exposures are monitored and
reported.
Limit breaches are required to be reported in a timely
manner to limit approvers, which include Market Risk
Management and senior management. In the event of
a breach, Market Risk Management consults with
senior members of appropriate groups within the Firm
to determine the suitable course of action required to
return the applicable positions to compliance, which
may include a reduction in risk in order to remedy the
breach or granting a temporary increase in limits to
accommodate an expected increase in client activity
and/or market volatility. Firm, Corporate or LOB-level
limit breaches are escalated as appropriate.
Models used to measure market risk are inherently
imprecise and are limited in their ability to measure
certain risks or to predict losses. This imprecision may
be heightened when sudden or severe shifts in market
conditions occur. For additional discussion on model
uncertainty refer to Estimations and Model Risk
Management on page 153.
Market Risk Management periodically reviews the
Firm’s existing market risk measures to identify
opportunities for enhancement, and to the extent
appropriate, will calibrate those measures accordingly
over time.
JPMorgan Chase & Co./2025 Form 10-K
133
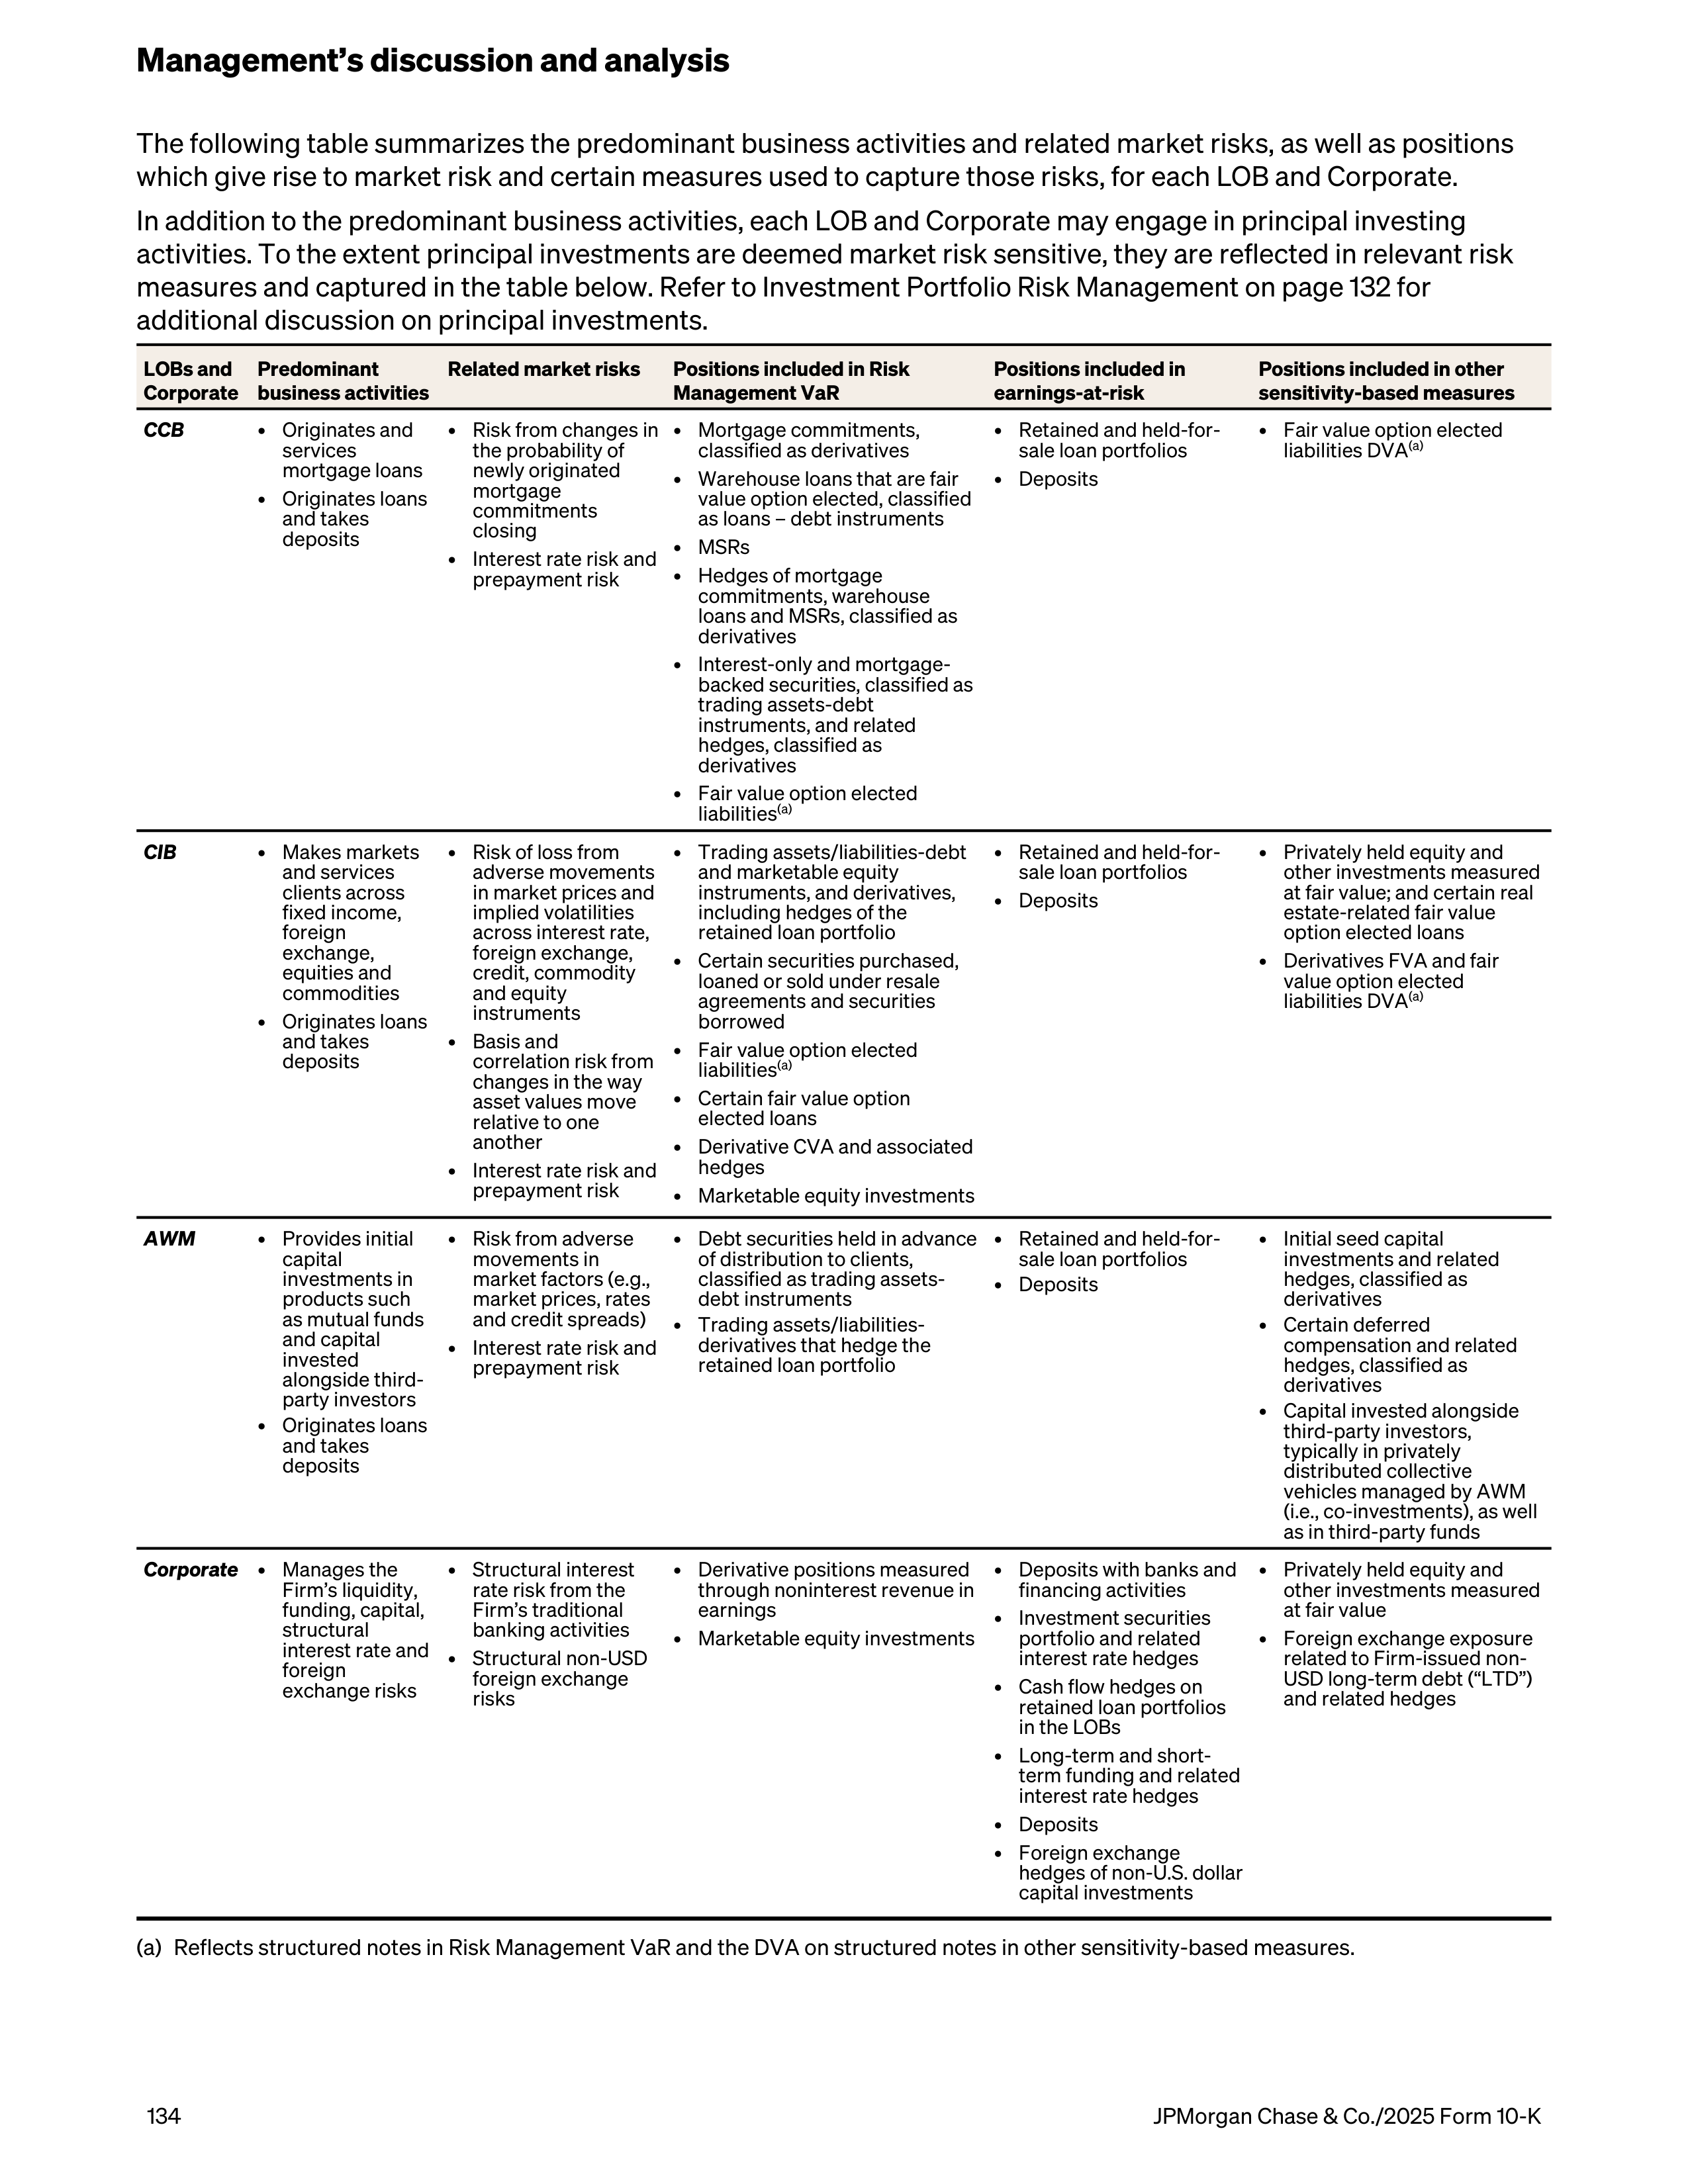
The following table summarizes the predominant business activities and related market risks, as well as positions
which give rise to market risk and certain measures used to capture those risks, for each LOB and Corporate.
In addition to the predominant business activities, each LOB and Corporate may engage in principal investing
activities. To the extent principal investments are deemed market risk sensitive, they are reflected in relevant risk
measures and captured in the table below. Refer to Investment Portfolio Risk Management on page 132 for
additional discussion on principal investments.
LOBs and
Corporate
Predominant
business activities
Related market risks
Positions included in Risk
Management VaR
Positions included in
earnings-at-risk
Positions included in other
sensitivity-based measures
CCB
•
Originates and
services
mortgage loans
•
Originates loans
and takes
deposits
•
Risk from changes in
the probability of
newly originated
mortgage
commitments
closing
•
Interest rate risk and
prepayment risk
•
Mortgage commitments,
classified as derivatives
•
Warehouse loans that are fair
value option elected, classified
as loans – debt instruments
•
MSRs
•
Hedges of mortgage
commitments, warehouse
loans and MSRs, classified as
derivatives
•
Interest-only and mortgage-
backed securities, classified as
trading assets-debt
instruments, and related
hedges, classified as
derivatives
•
Fair value option elected
liabilities
(a)
•
Retained and held-for-
sale loan portfolios
•
Deposits
•
Fair value option elected
liabilities DVA
(a)
CIB
•
Makes markets
and services
clients across
fixed income,
foreign
exchange,
equities and
commodities
•
Originates loans
and takes
deposits
•
Risk of loss from
adverse movements
in market prices and
implied volatilities
across interest rate,
foreign exchange,
credit, commodity
and equity
instruments
•
Basis and
correlation risk from
changes in the way
asset values move
relative to one
another
•
Interest rate risk and
prepayment risk
•
Trading assets/liabilities-debt
and marketable equity
instruments, and derivatives,
including hedges of the
retained loan portfolio
•
Certain securities purchased,
loaned or sold under resale
agreements and securities
borrowed
•
Fair value option elected
liabilities
(a)
•
Certain fair value option
elected loans
•
Derivative CVA and associated
hedges
•
Marketable equity investments
•
Retained and held-for-
sale loan portfolios
•
Deposits
•
Privately held equity and
other investments measured
at fair value; and certain real
estate-related fair value
option elected loans
•
Derivatives FVA and fair
value option elected
liabilities DVA
(a)
AWM
•
Provides initial
capital
investments in
products such
as mutual funds
and capital
invested
alongside third-
party investors
•
Originates loans
and takes
deposits
•
Risk from adverse
movements in
market factors (e.g.,
market prices, rates
and credit spreads)
•
Interest rate risk and
prepayment risk
•
Debt securities held in advance
of distribution to clients,
classified as trading assets-
debt instruments
•
Trading assets/liabilities-
derivatives that hedge the
retained loan portfolio
•
Retained and held-for-
sale loan portfolios
•
Deposits
•
Initial seed capital
investments and related
hedges, classified as
derivatives
•
Certain deferred
compensation and related
hedges, classified as
derivatives
•
Capital invested alongside
third-party investors,
typically in privately
distributed collective
vehicles managed by AWM
(i.e., co-investments), as well
as in third-party funds
Corporate
•
Manages the
Firm’s liquidity,
funding, capital,
structural
interest rate and
foreign
exchange risks
•
Structural interest
rate risk from the
Firm’s traditional
banking activities
•
Structural non-USD
foreign exchange
risks
•
Derivative positions measured
through noninterest revenue in
earnings
•
Marketable equity investments
•
Deposits with banks and
financing activities
•
Investment securities
portfolio and related
interest rate hedges
•
Cash flow hedges on
retained loan portfolios
in the LOBs
•
Long-term and short-
term funding and related
interest rate hedges
•
Deposits
•
Foreign exchange
hedges of non-U.S. dollar
capital investments
•
Privately held equity and
other investments measured
at fair value
•
Foreign exchange exposure
related to Firm-issued non-
USD long-term debt (“LTD”)
and related hedges
(a)
Reflects structured notes in Risk Management VaR and the DVA on structured notes in other sensitivity-based measures.
Management’s discussion and analysis
134
JPMorgan Chase & Co./2025 Form 10-K
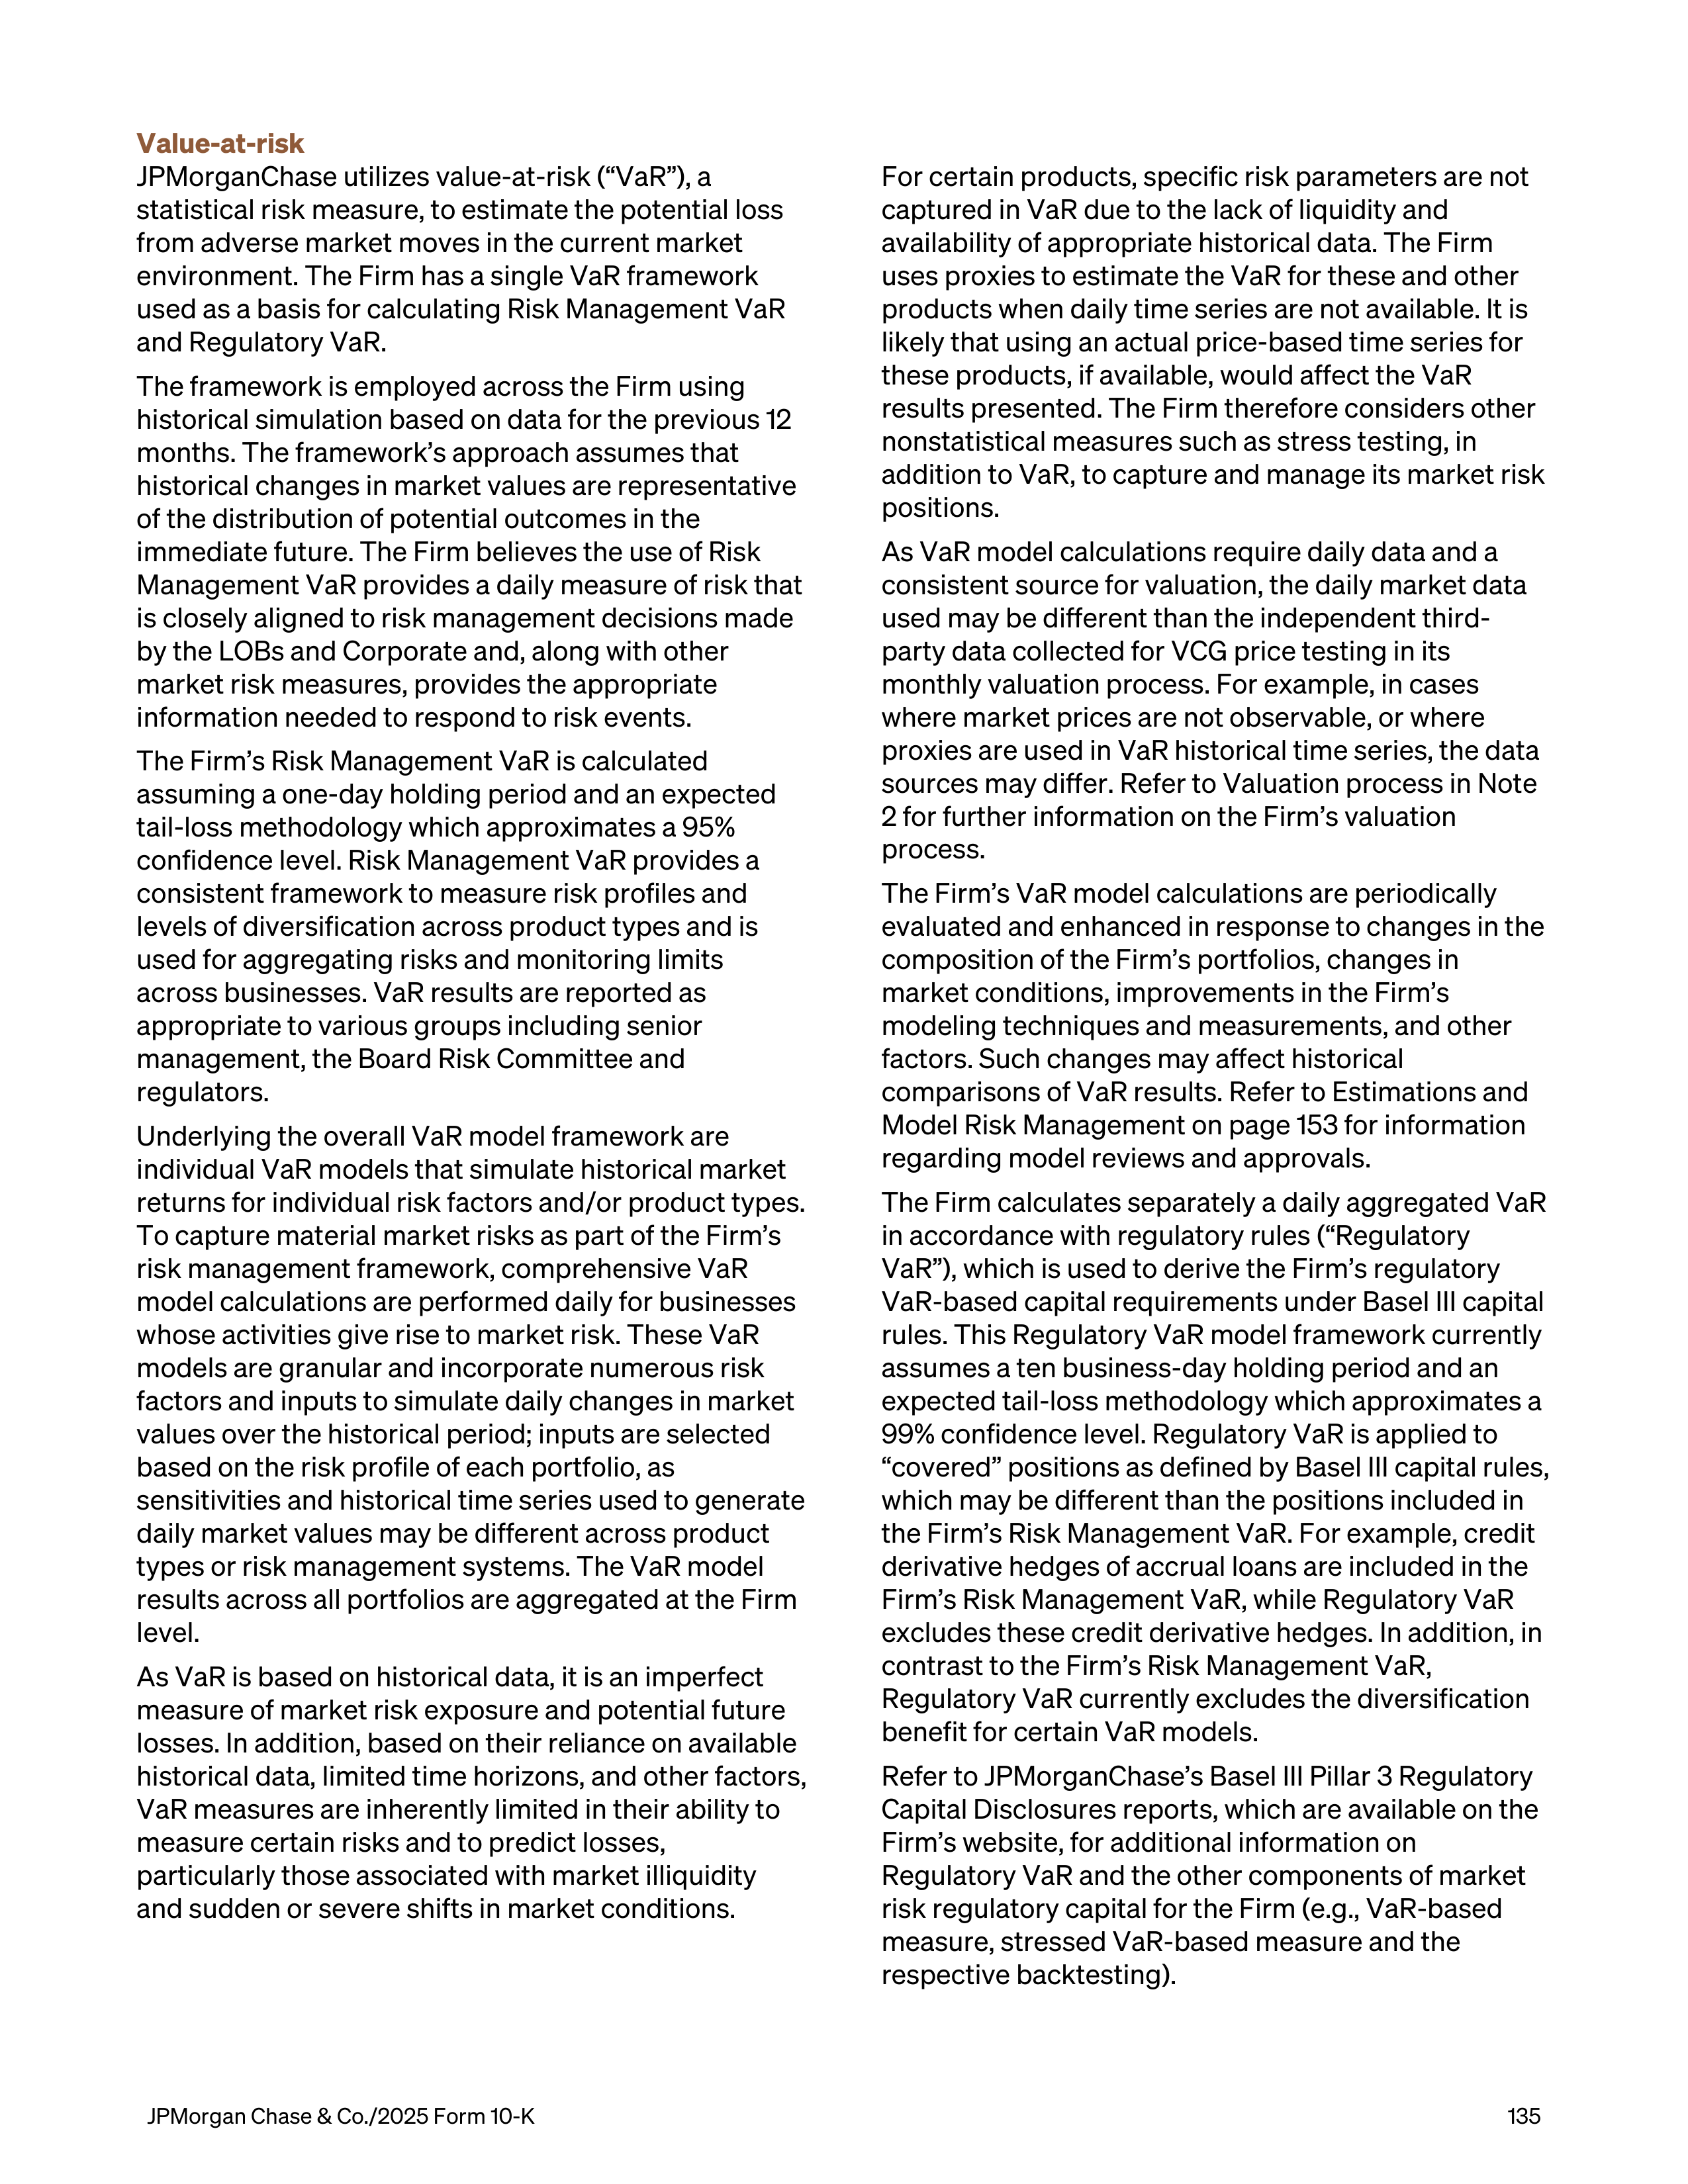
Value-at-risk
JPMorganChase utilizes value-at-risk (“VaR”), a
statistical risk measure, to estimate the potential loss
from adverse market moves in the current market
environment. The Firm has a single VaR framework
used as a basis for calculating Risk Management VaR
and Regulatory VaR.
The framework is employed across the Firm using
historical simulation based on data for the previous 12
months. The framework’s approach assumes that
historical changes in market values are representative
of the distribution of potential outcomes in the
immediate future. The Firm believes the use of Risk
Management VaR provides a daily measure of risk that
is closely aligned to risk management decisions made
by the LOBs and Corporate and, along with other
market risk measures, provides the appropriate
information needed to respond to risk events.
The Firm’s Risk Management VaR is calculated
assuming a one-day holding period and an expected
tail-loss methodology which approximates a 95%
confidence level. Risk Management VaR provides a
consistent framework to measure risk profiles and
levels of diversification across product types and is
used for aggregating risks and monitoring limits
across businesses. VaR results are reported as
appropriate to various groups including senior
management, the Board Risk Committee and
regulators.
Underlying the overall VaR model framework are
individual VaR models that simulate historical market
returns for individual risk factors and/or product types.
To capture material market risks as part of the Firm’s
risk management framework, comprehensive VaR
model calculations are performed daily for businesses
whose activities give rise to market risk. These VaR
models are granular and incorporate numerous risk
factors and inputs to simulate daily changes in market
values over the historical period; inputs are selected
based on the risk profile of each portfolio, as
sensitivities and historical time series used to generate
daily market values may be different across product
types or risk management systems. The VaR model
results across all portfolios are aggregated at the Firm
level.
As VaR is based on historical data, it is an imperfect
measure of market risk exposure and potential future
losses. In addition, based on their reliance on available
historical data, limited time horizons, and other factors,
VaR measures are inherently limited in their ability to
measure certain risks and to predict losses,
particularly those associated with market illiquidity
and sudden or severe shifts in market conditions.
For certain products, specific risk parameters are not
captured in VaR due to the lack of liquidity and
availability of appropriate historical data. The Firm
uses proxies to estimate the VaR for these and other
products when daily time series are not available. It is
likely that using an actual price-based time series for
these products, if available, would affect the VaR
results presented. The Firm therefore considers other
nonstatistical measures such as stress testing, in
addition to VaR, to capture and manage its market risk
positions.
As VaR model calculations require daily data and a
consistent source for valuation, the daily market data
used may be different than the independent third-
party data collected for VCG price testing in its
monthly valuation process. For example, in cases
where market prices are not observable, or where
proxies are used in VaR historical time series, the data
sources may differ. Refer to Valuation process in Note
2 for further information on the Firm’s valuation
process.
The Firm’s VaR model calculations are periodically
evaluated and enhanced in response to changes in the
composition of the Firm’s portfolios, changes in
market conditions, improvements in the Firm’s
modeling techniques and measurements, and other
factors. Such changes may affect historical
comparisons of VaR results. Refer to Estimations and
Model Risk Management on page 153 for information
regarding model reviews and approvals.
The Firm calculates separately a daily aggregated VaR
in accordance with regulatory rules (“Regulatory
VaR”), which is used to derive the Firm’s regulatory
VaR-based capital requirements under Basel III capital
rules. This Regulatory VaR model framework currently
assumes a ten business-day holding period and an
expected tail-loss methodology which approximates a
99% confidence level. Regulatory VaR is applied to
“covered” positions as defined by Basel III capital rules,
which may be different than the positions included in
the Firm’s Risk Management VaR. For example, credit
derivative hedges of accrual loans are included in the
Firm’s Risk Management VaR, while Regulatory VaR
excludes these credit derivative hedges. In addition, in
contrast to the Firm’s Risk Management VaR,
Regulatory VaR currently excludes the diversification
benefit for certain VaR models.
Refer to JPMorganChase’s Basel III Pillar 3 Regulatory
Capital Disclosures reports, which are available on the
Firm’s website, for additional information on
Regulatory VaR and the other components of market
risk regulatory capital for the Firm (e.g., VaR-based
measure, stressed VaR-based measure and the
respective backtesting).
JPMorgan Chase & Co./2025 Form 10-K
135
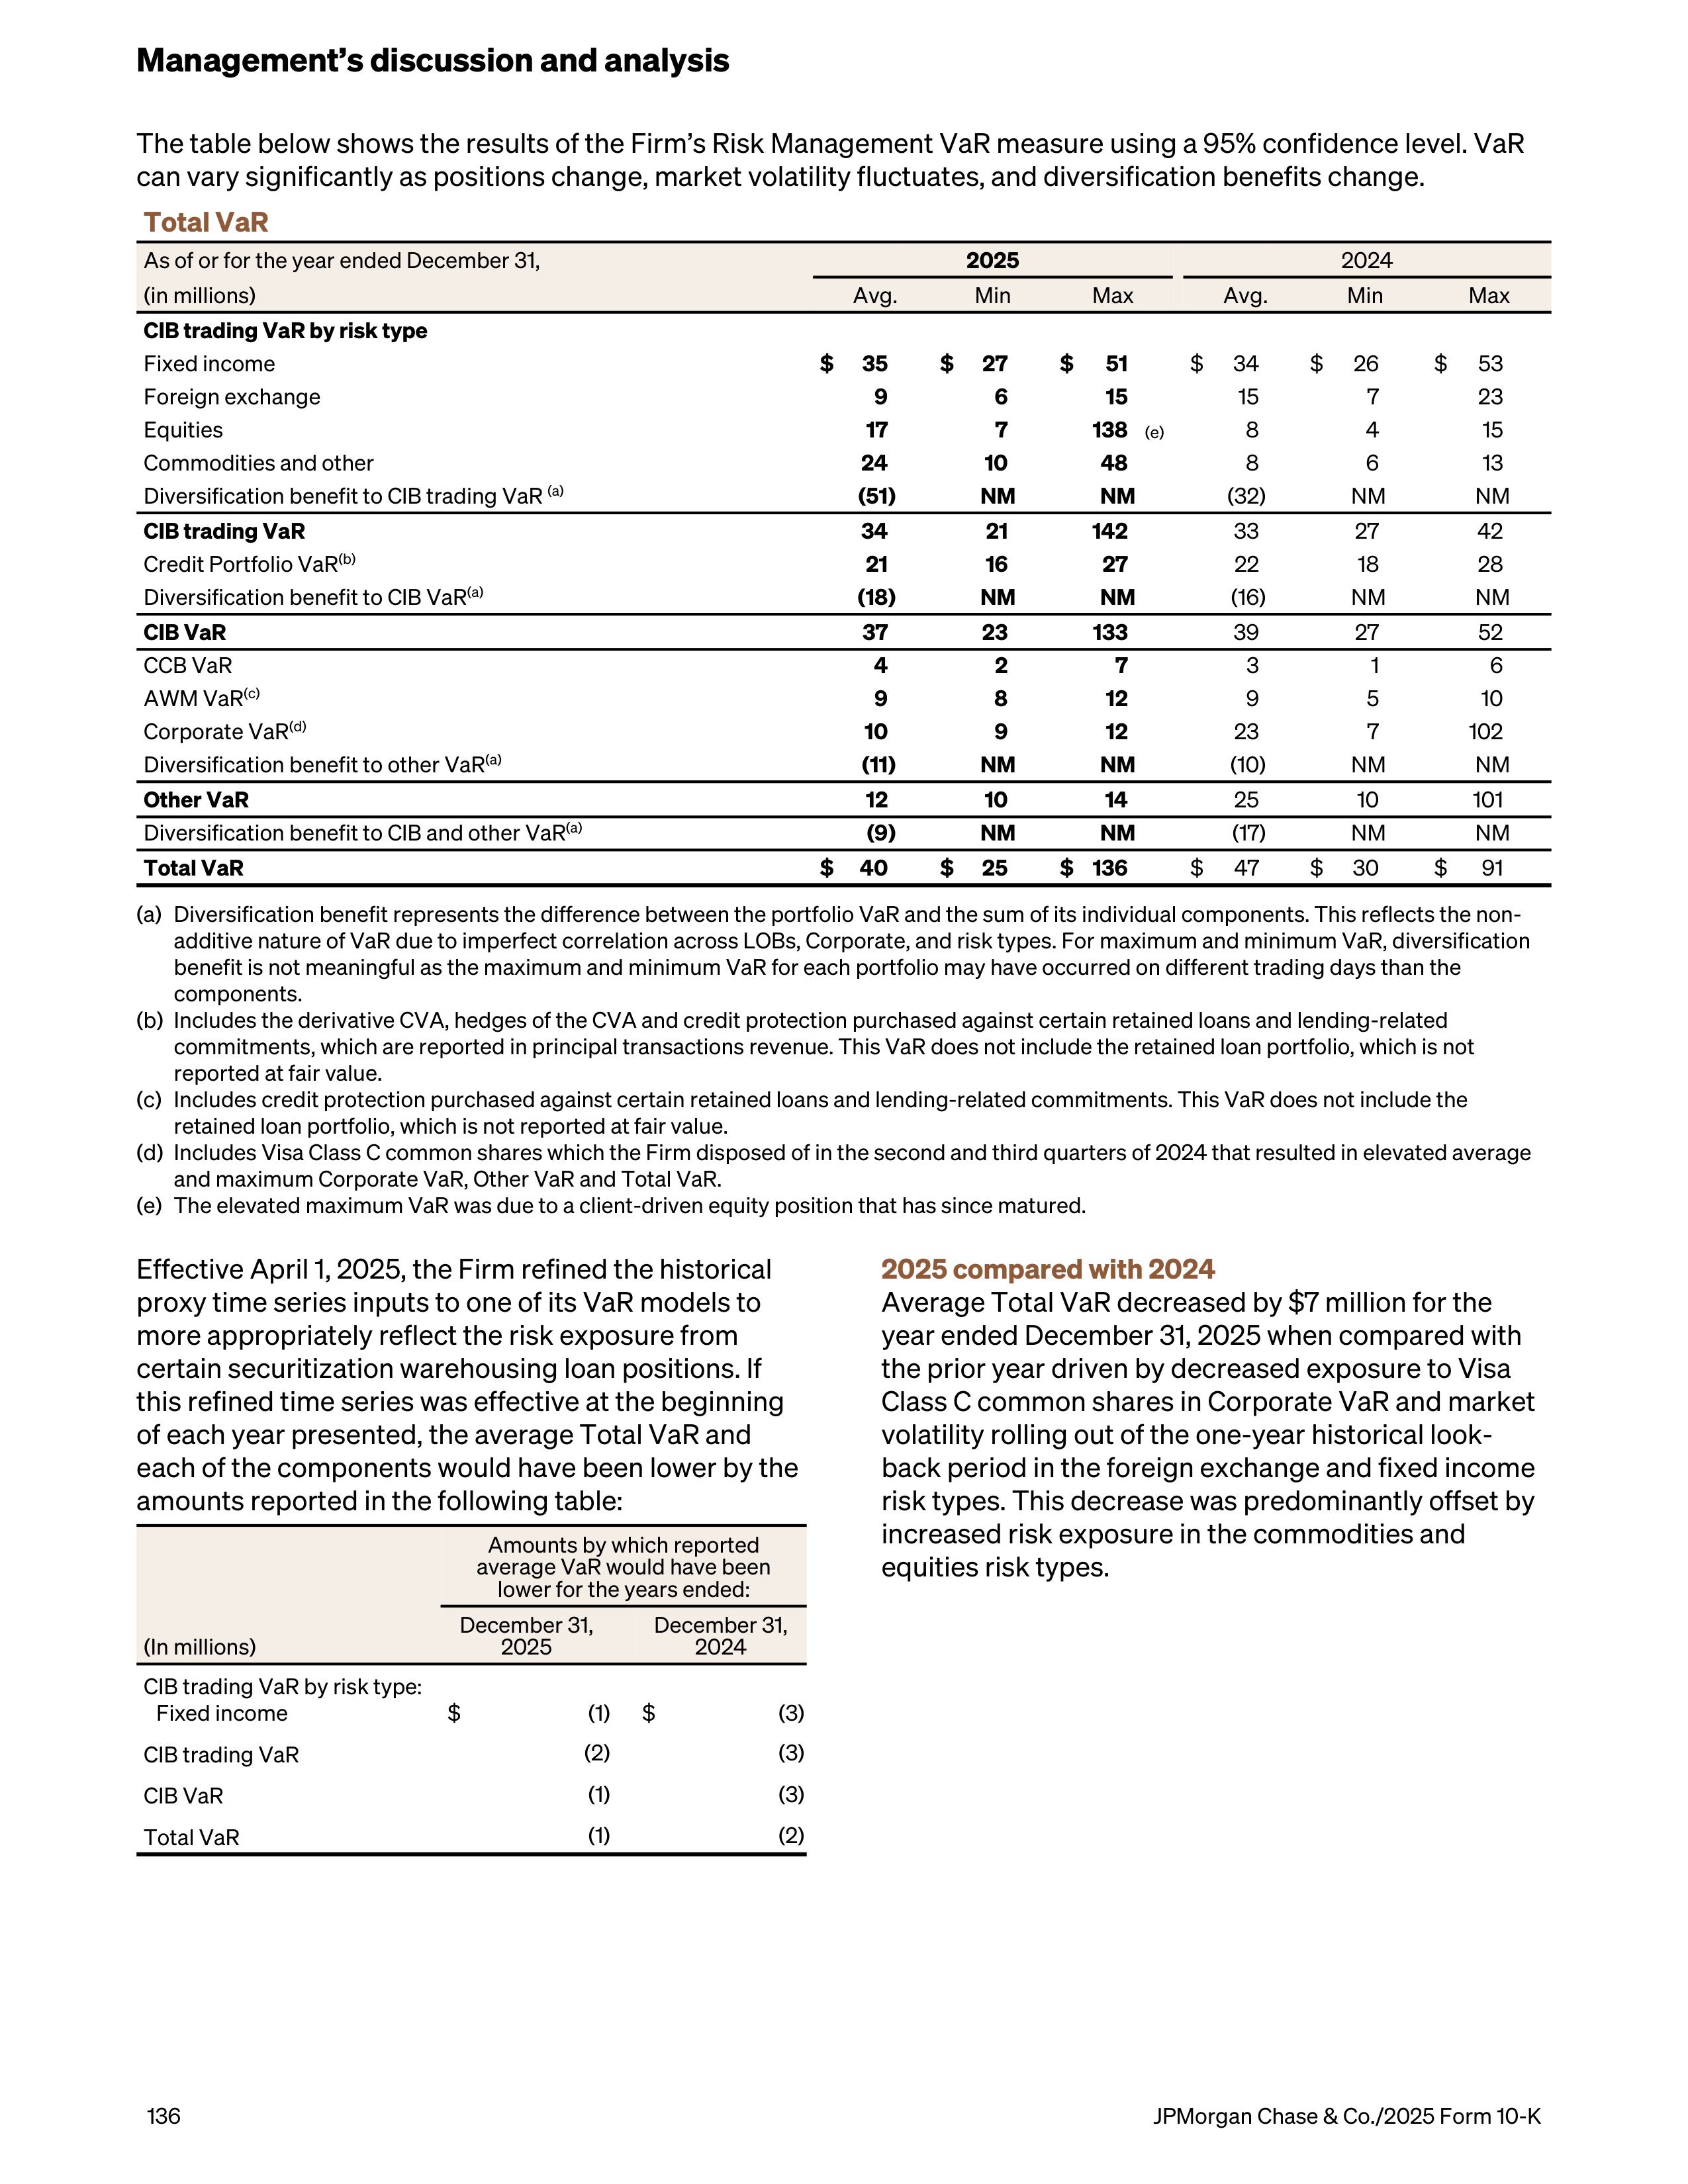
The table below shows the results of the Firm’s Risk Management VaR measure using a 95% confidence level. VaR
can vary significantly as positions change, market volatility fluctuates, and diversification benefits change.
Total VaR
As of or for the year ended December 31,
2025
2024
(in millions)
Avg.
Min
Max
Avg.
Min
Max
CIB trading VaR by risk type
Fixed income
$
35
$
27
$
51
$
34
$
26
$
53
Foreign exchange
9
6
15
15
7
23
Equities
17
7
138
(e)
8
4
15
Commodities and other
24
10
48
8
6
13
Diversification benefit to CIB trading VaR
(a)
(51)
NM
NM
(32)
NM
NM
CIB trading VaR
34
21
142
33
27
42
Credit Portfolio VaR
(b)
21
16
27
22
18
28
Diversification benefit to CIB VaR
(a)
(18)
NM
NM
(16)
NM
NM
CIB VaR
37
23
133
39
27
52
CCB VaR
4
2
7
3
1
6
AWM VaR
(c)
9
8
12
9
5
10
Corporate VaR
(d)
10
9
12
23
7
102
Diversification benefit to other VaR
(a)
(11)
NM
NM
(10)
NM
NM
Other VaR
12
10
14
25
10
101
Diversification benefit to CIB and other VaR
(a)
(9)
NM
NM
(17)
NM
NM
Total VaR
$
40
$
25
$ 136
$
47
$
30
$
91
(a)
Diversification benefit represents the difference between the portfolio VaR and the sum of its individual components. This reflects the non-
additive nature of VaR due to imperfect correlation across LOBs, Corporate, and risk types. For maximum and minimum VaR, diversification
benefit is not meaningful as the maximum and minimum VaR for each portfolio may have occurred on different trading days than the
components.
(b)
Includes the derivative CVA, hedges of the CVA and credit protection purchased against certain retained loans and lending-related
commitments, which are reported in principal transactions revenue. This VaR does not include the retained loan portfolio, which is not
reported at fair value.
(c)
Includes credit protection purchased against certain retained loans and lending-related commitments. This VaR does not include the
retained loan portfolio, which is not reported at fair value.
(d)
Includes Visa Class C common shares which the Firm disposed of in the second and third quarters of 2024 that resulted in elevated average
and maximum Corporate VaR, Other VaR and Total VaR.
(e)
The elevated maximum VaR was due to a client-driven equity position that has since matured.
Effective April 1, 2025, the Firm refined the historical
proxy time series inputs to one of its VaR models to
more appropriately reflect the risk exposure from
certain securitization warehousing loan positions. If
this refined time series was effective at the beginning
of each year presented, the average Total VaR and
each of the components would have been lower by the
amounts reported in the following table:
(In millions)
Amounts by which reported
average VaR would have been
lower for the years ended:
December 31,
2025
December 31,
2024
CIB trading VaR by risk type:
Fixed income
$
(1)
$
(3)
CIB trading VaR
(2)
(3)
CIB VaR
(1)
(3)
Total VaR
(1)
(2)
2025 compared with 2024
Average Total VaR decreased by $7 million for the
year ended December 31, 2025 when compared with
the prior year driven by decreased exposure to Visa
Class C common shares in Corporate VaR and market
volatility rolling out of the one-year historical look-
back period in the foreign exchange and fixed income
risk types. This decrease was predominantly offset by
increased risk exposure in the commodities and
equities risk types.
Management’s discussion and analysis
136
JPMorgan Chase & Co./2025 Form 10-K
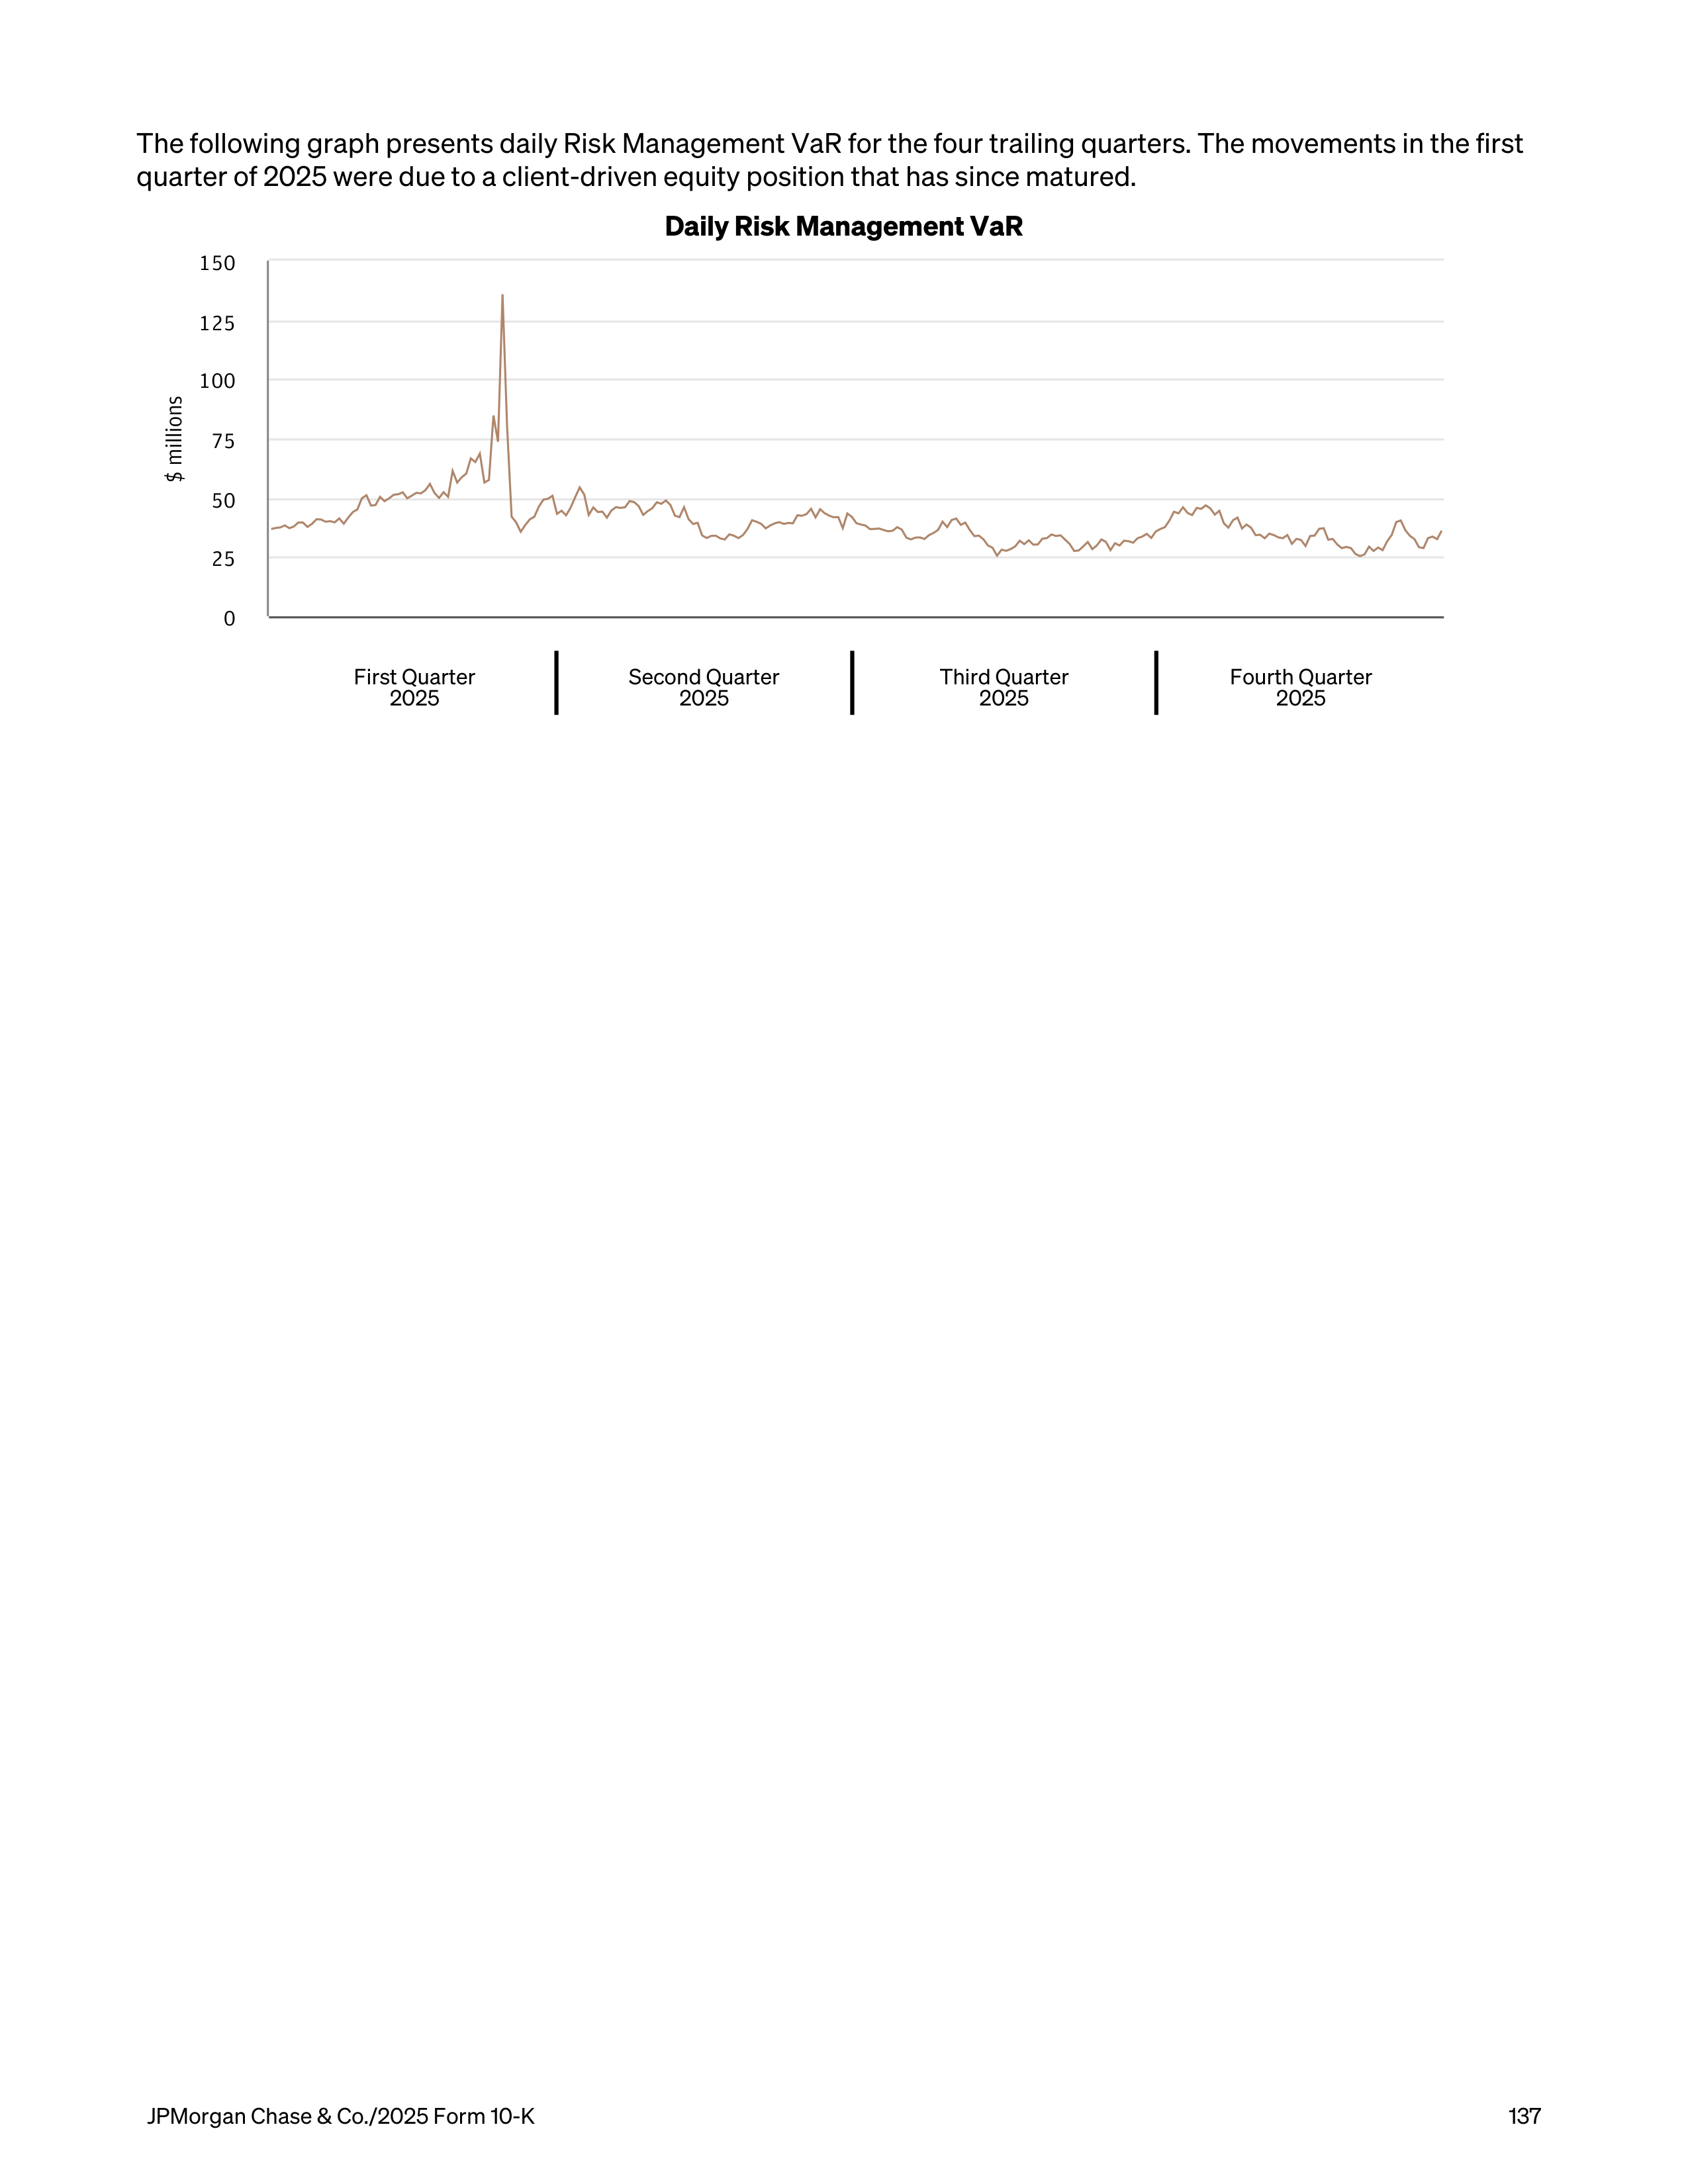
The following graph presents daily Risk Management VaR for the four trailing quarters. The movements in the first
quarter of 2025 were due to a client-driven equity position that has since matured.
Daily Risk Management VaR
$ millions
0
25
50
75
100
125
150
First Quarter
2025
Second Quarter
2025
Third Quarter
2025
Fourth Quarter
2025
JPMorgan Chase & Co./2025 Form 10-K
137
VaR backtesting
The Firm performs daily VaR model backtesting, which
compares the daily Risk Management VaR results with
the daily gains and losses that are utilized for VaR
backtesting purposes. The gains and losses depicted
in the chart below do not reflect the Firm’s reported
revenue as they exclude certain components of total
net revenue, such as those associated with the
execution of new transactions (i.e., intraday client-
driven trading and intraday risk management
activities), fees, commissions, other valuation
adjustments and net interest income. These excluded
components of total net revenue may more than offset
the backtesting gain or loss on a particular day. The
definition of backtesting gains and losses above is
consistent with the requirements for backtesting
under Basel III capital rules.
A backtesting exception occurs when the daily
backtesting loss exceeds the daily Risk Management
VaR for the prior day. Under the Firm’s Risk
Management VaR methodology, assuming current
changes in market values are consistent with the
historical changes used in the simulation, the Firm
would expect to incur VaR backtesting exceptions five
times every 100 trading days on average. The number
of VaR backtesting exceptions observed can differ
from the statistically expected number of backtesting
exceptions if the current level of market volatility is
materially different from the level of market volatility
during the 12 months of historical data used in the VaR
calculation.
For the 12 months ended December 31, 2025, the Firm
posted backtesting gains on 174 of the 259 days, and
observed 12 VaR backtesting exceptions, of which four
were in the three months ended December 31, 2025.
Firmwide backtesting loss days can differ from the
loss days for which Fixed Income Markets and Equity
Markets posted losses, as disclosed in CIB Markets
revenue, as the population of positions which
comprise each metric are different and due to the
exclusion of certain components of total net revenue in
backtesting gains and losses as described above.
The following chart presents the distribution of
Firmwide daily backtesting gains and losses for the
trailing 12 months and three months ended
December 31, 2025. The daily backtesting losses are
displayed as a percentage of the corresponding daily
Risk Management VaR. The count of days with
backtesting losses are shown in aggregate, in fifty
percentage point intervals. Backtesting exceptions are
displayed within the intervals that are greater than one
hundred percent. The results in the chart below differ
from the results of backtesting disclosed in the Market
Risk section of the Firm’s Basel III Pillar 3 Regulatory
Capital Disclosures reports, which are based on
Regulatory VaR applied to the Firm’s covered
positions.
Distribution of Daily Backtesting Gains and Losses
Management’s discussion and analysis
138
JPMorgan Chase & Co./2025 Form 10-K
Other risk measures
Stress testing
Along with VaR, stress testing is an important tool
used to assess risk. While VaR reflects the risk of loss
due to adverse changes in markets using recent
historical market behavior, stress testing reflects the
risk of loss from hypothetical changes in the value of
market risk sensitive positions applied simultaneously.
Stress testing measures the Firm’s vulnerability to
losses under a range of stressed but possible
economic and market scenarios. The results are used
to understand the exposures responsible for those
potential losses and are measured against limits.
The Firm’s stress framework covers market risk
sensitive positions in the LOBs and Corporate. The
framework is used to calculate multiple magnitudes of
potential stress for both market rallies and market sell-
offs, assuming significant changes in market factors
such as credit spreads, equity prices, interest rates,
currency rates and commodity prices, and combines
them in multiple ways to capture an array of
hypothetical economic and market scenarios.
The Firm generates a number of scenarios that focus
on tail events in specific asset classes and
geographies, including how the event may impact
multiple market factors simultaneously. Scenarios also
incorporate specific idiosyncratic risks and stress
basis risk between different products. The flexibility in
the stress framework allows the Firm to construct new
scenarios that can test the outcomes against possible
future stress events. Stress testing results are
reported periodically to senior management of the
Firm, as appropriate.
Stress methodologies are governed by the overall
stress framework, under the oversight of Market Risk
Management. The Firmwide Market Risk Stress
Methodology Committee reviews and approves
changes to stress testing methodology and scenarios
across the Firm. Significant changes to the framework
are escalated to senior management, as appropriate.
In addition, stress methodology and the models to
calculate the stress results are subject to the Firm’s
Estimations and Model Risk Management Policy
The Firm’s stress testing framework is utilized in
calculating the Firm’s CCAR and other stress test
results, which are reported periodically to the Board of
Directors. In addition, stress testing results are
incorporated into the Firm’s Risk Appetite framework,
and are reported periodically to the Board Risk
Committee.
Profit and loss drawdowns
Profit and loss drawdowns are used to highlight
trading losses above certain levels of risk tolerance. A
profit and loss drawdown is a decline in revenue from
its year-to-date peak level.
Structural interest rate risk management
The effect of interest rate exposure on the Firm’s
reported net income is important as interest rate risk
represents one of the Firm’s significant market risks.
Interest rate risk arises not only from trading activities
which are included in VaR, but also from the Firm’s
traditional banking activities, which include extension
of loans and credit facilities, taking deposits, issuing
debt, as well as the investment securities portfolio, and
associated derivative instruments. Refer to the table
on page 134 for a summary by LOB and Corporate
identifying positions included in earnings-at-risk.
Governance
The CTC Risk Committee establishes the Firm’s
interest rate risk management policy and related
limits, which are subject to approval by the Board Risk
Committee. Treasury and CIO, working in partnership
with the LOBs, calculates the Firm’s structural interest
rate risk profile and reviews it with senior
management, including the CTC Risk Committee. In
addition, oversight of structural interest rate risk is
managed through a dedicated risk function reporting
to the CTC CRO. This risk function is responsible for
providing independent oversight and governance
around assumptions and establishing and monitoring
limits for structural interest rate risk, including limits
related to earnings-at-risk and economic value
sensitivity. The Firm manages structural interest rate
risk generally through its investment securities
portfolio and interest rate derivatives.
Key risk drivers and risk management process
Structural interest rate risk can arise due to a variety of
factors, including:
•
Differences in timing among the maturity or
repricing of assets, liabilities and off-balance sheet
instruments
•
Differences in the amounts of assets, liabilities and
off-balance sheet instruments that are maturing or
repricing at the same time
•
Differences in the amounts by which short-term and
long-term market interest rates change (for
example, changes in the slope of the yield curve)
•
The impact of changes in the maturity of various
assets, liabilities or off-balance sheet instruments as
interest rates change
The Firm manages interest rate exposure related to its
assets and liabilities on a consolidated, Firmwide
basis. Business units transfer their interest rate risk to
Treasury and CIO through funds transfer pricing,
which takes into account the elements of interest rate
exposure that can be risk-managed in financial
markets. These elements include asset and liability
balances and contractual rates of interest, contractual
principal payment schedules, expected prepayment
JPMorgan Chase & Co./2025 Form 10-K
139
experience, interest rate reset dates and maturities,
rate indices used for repricing, and any interest rate
ceilings or floors for adjustable rate products.
Earnings-at-risk
One way that the Firm evaluates its structural interest
rate risk is through earnings-at-risk. Earnings-at-risk
estimates the Firm’s interest rate exposure for a given
interest rate scenario. It is presented as a sensitivity to
a baseline, which includes net interest income and
certain interest rate sensitive fees. The baseline uses
market interest rates and, in the case of deposits,
pricing assumptions. The Firm conducts simulations of
changes to this baseline for interest rate-sensitive
assets and liabilities denominated in U.S. dollars and
other currencies (“non-U.S. dollar” currencies). These
simulations primarily include retained and held-for-
sale loans, deposits, deposits with banks and financing
activities, investment securities, long-term debt,
related interest rate hedges, and funds transfer pricing
of other positions in risk management VaR and other
sensitivity-based measures as described on page 134.
These simulations also include hedges of non-U.S.
dollar foreign exchange exposures arising from capital
investments. Refer to non-U.S. dollar foreign exchange
risk on page 142 for more information.
Earnings-at-risk scenarios estimate the potential
change to a baseline over the following 12 months
utilizing multiple assumptions. These scenarios
include a parallel shift involving changes to both short-
term and long-term rates by an equal amount; a
steeper yield curve involving holding short-term rates
constant and increasing long-term rates; and a flatter
yield curve involving increasing short-term rates and
holding long-term rates constant or holding short-
term rates constant and decreasing long-term rates.
These scenarios consider many different factors,
including:
•
The impact on exposures as a result of
instantaneous changes in interest rates from
baseline rates.
•
Forecasted balance sheet, as well as modeled
prepayment and reinvestment behavior, but
excluding assumptions about actions that could be
taken by the Firm or its clients and customers in
response to instantaneous rate changes. Mortgage
prepayment assumptions are based on the interest
rates used in the scenarios compared with
underlying contractual rates, the time since
origination, and other factors which are updated
periodically based on historical experience. Deposit
forecasts are a key assumption in the Firm’s
earnings-at-risk. The baseline reflects certain
assumptions relating to the Federal Reserve’s
balance sheet policy (e.g., quantitative tightening
and usage at the Reverse Repurchase Facility) that
require management judgment. The amount of
deposits that the Firm holds at any given time may
be influenced by Federal Reserve actions, as well as
broader monetary conditions and competition for
deposits.
•
The pricing sensitivity of deposits, known as deposit
betas, represent the amount by which deposit rates
paid could change upon a given change in market
interest rates. Actual deposit rates paid may differ
from the modeled assumptions, primarily due to
customer behavior and competition for deposits.
The Firm performs sensitivity analyses of the
assumptions used in earnings-at-risk scenarios,
including with respect to deposit betas and forecasts
of deposit balances, both of which are especially
significant in the case of consumer deposits. The
results of these sensitivity analyses are reported to the
CTC Risk Committee and the Board Risk Committee.
The Firm’s earnings-at-risk scenarios are periodically
evaluated and enhanced in response to changes in the
composition of the Firm’s balance sheet, changes in
market conditions, improvements in the Firm’s
simulation and other factors.
The Firm’s earnings-at-risk sensitivities are measures
of the Firm’s interest rate exposure. The Firm’s actual
net interest income for the rate changes presented
may differ as the earnings-at-risk scenarios are
modelled as instantaneous changes and exclude any
actions that could be taken by the Firm or its clients or
customers in response to rate changes. Other
significant assumptions in the earnings-at-risk
scenarios, including mortgage prepayments and
deposit rates paid, may also differ from actual results.
The Firm’s forecast for net interest income is included
in the Firm’s outlook on page 50.
Management’s discussion and analysis
140
JPMorgan Chase & Co./2025 Form 10-K
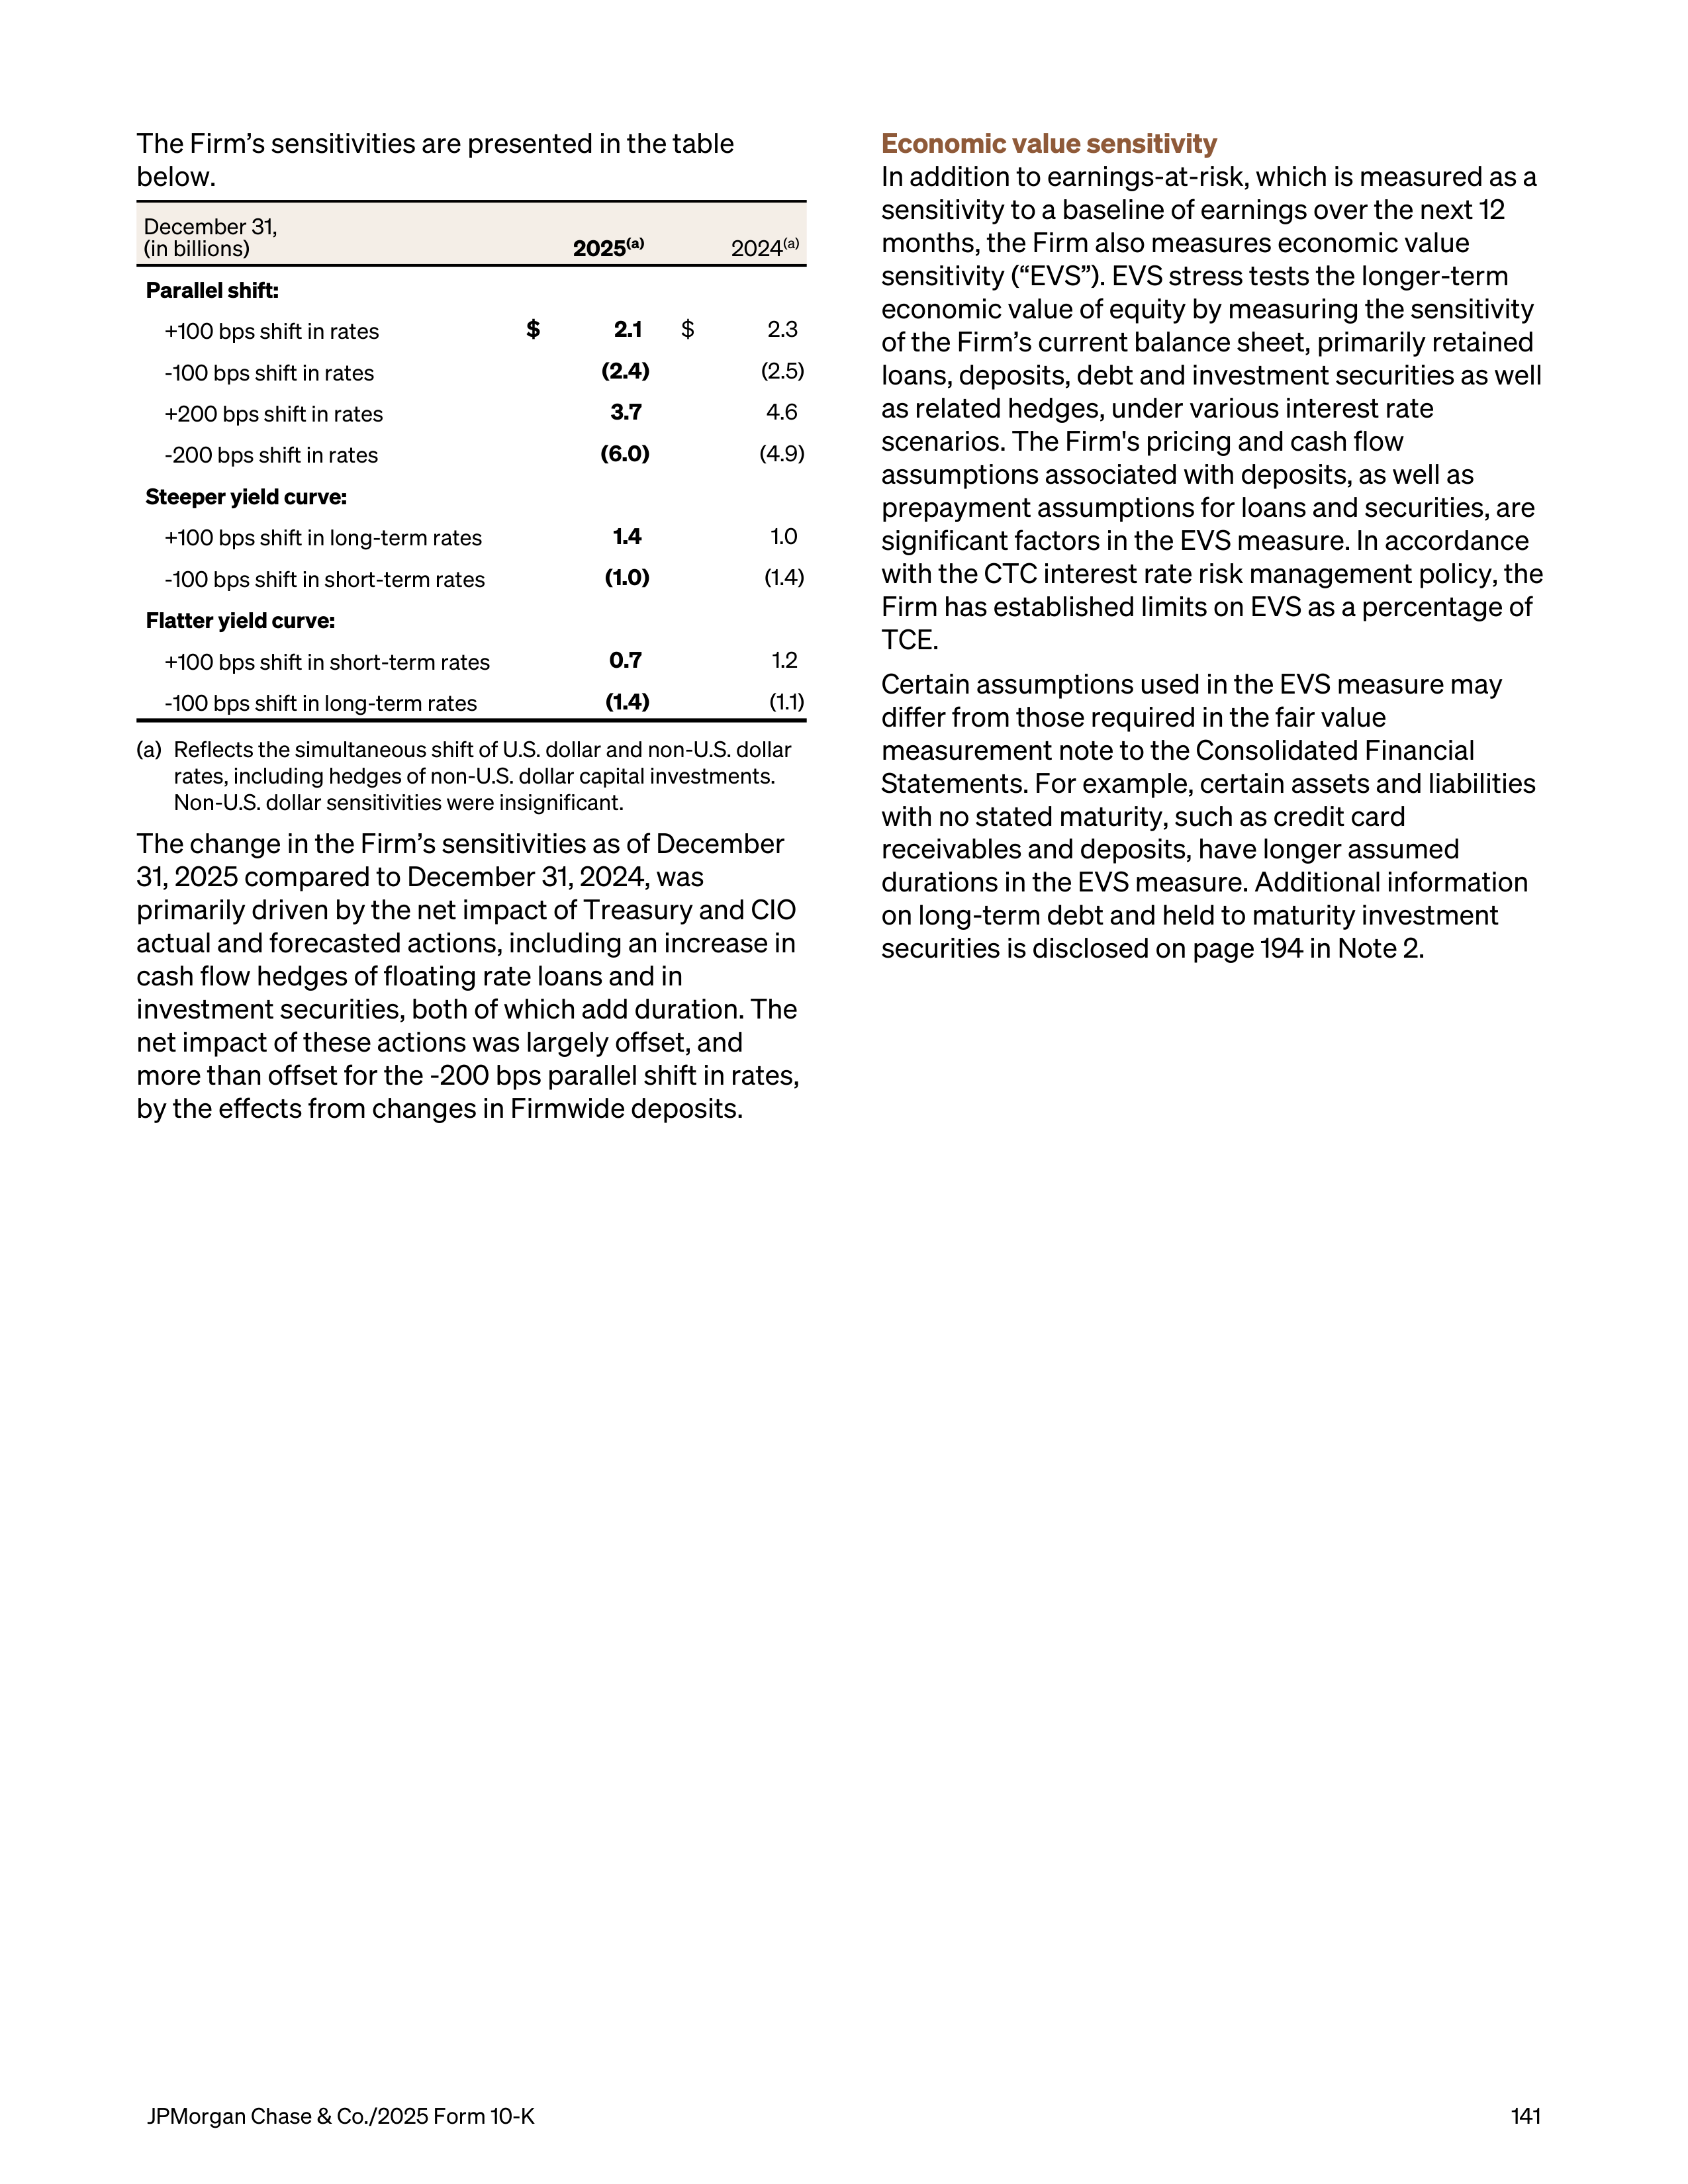
The Firm’s sensitivities are presented in the table
below.
December 31,
(in billions)
2025
(a)
2024
(a)
Parallel shift:
+100 bps shift in rates
$
2.1
$
2.3
-100 bps shift in rates
(2.4)
(2.5)
+200 bps shift in rates
3.7
4.6
-200 bps shift in rates
(6.0)
(4.9)
Steeper yield curve:
+100 bps shift in long-term rates
1.4
1.0
-100 bps shift in short-term rates
(1.0)
(1.4)
Flatter yield curve:
+100 bps shift in short-term rates
0.7
1.2
-100 bps shift in long-term rates
(1.4)
(1.1)
(a)
Reflects the simultaneous shift of U.S. dollar and non-U.S. dollar
rates, including hedges of non-U.S. dollar capital investments.
Non-U.S. dollar sensitivities were insignificant.
The change in the Firm’s sensitivities as of December
31, 2025 compared to December 31, 2024, was
primarily driven by the net impact of Treasury and CIO
actual and forecasted actions, including an increase in
cash flow hedges of floating rate loans and in
investment securities, both of which add duration. The
net impact of these actions was largely offset, and
more than offset for the -200 bps parallel shift in rates,
by the effects from changes in Firmwide deposits.
Economic value sensitivity
In addition to earnings-at-risk, which is measured as a
sensitivity to a baseline of earnings over the next 12
months, the Firm also measures economic value
sensitivity (“EVS”). EVS stress tests the longer-term
economic value of equity by measuring the sensitivity
of the Firm’s current balance sheet, primarily retained
loans, deposits, debt and investment securities as well
as related hedges, under various interest rate
scenarios. The Firm's pricing and cash flow
assumptions associated with deposits, as well as
prepayment assumptions for loans and securities, are
significant factors in the EVS measure. In accordance
with the CTC interest rate risk management policy, the
Firm has established limits on EVS as a percentage of
TCE.
Certain assumptions used in the EVS measure may
differ from those required in the fair value
measurement note to the Consolidated Financial
Statements. For example, certain assets and liabilities
with no stated maturity, such as credit card
receivables and deposits, have longer assumed
durations in the EVS measure. Additional information
on long-term debt and held to maturity investment
securities is disclosed on page 194 in Note 2.
JPMorgan Chase & Co./2025 Form 10-K
141
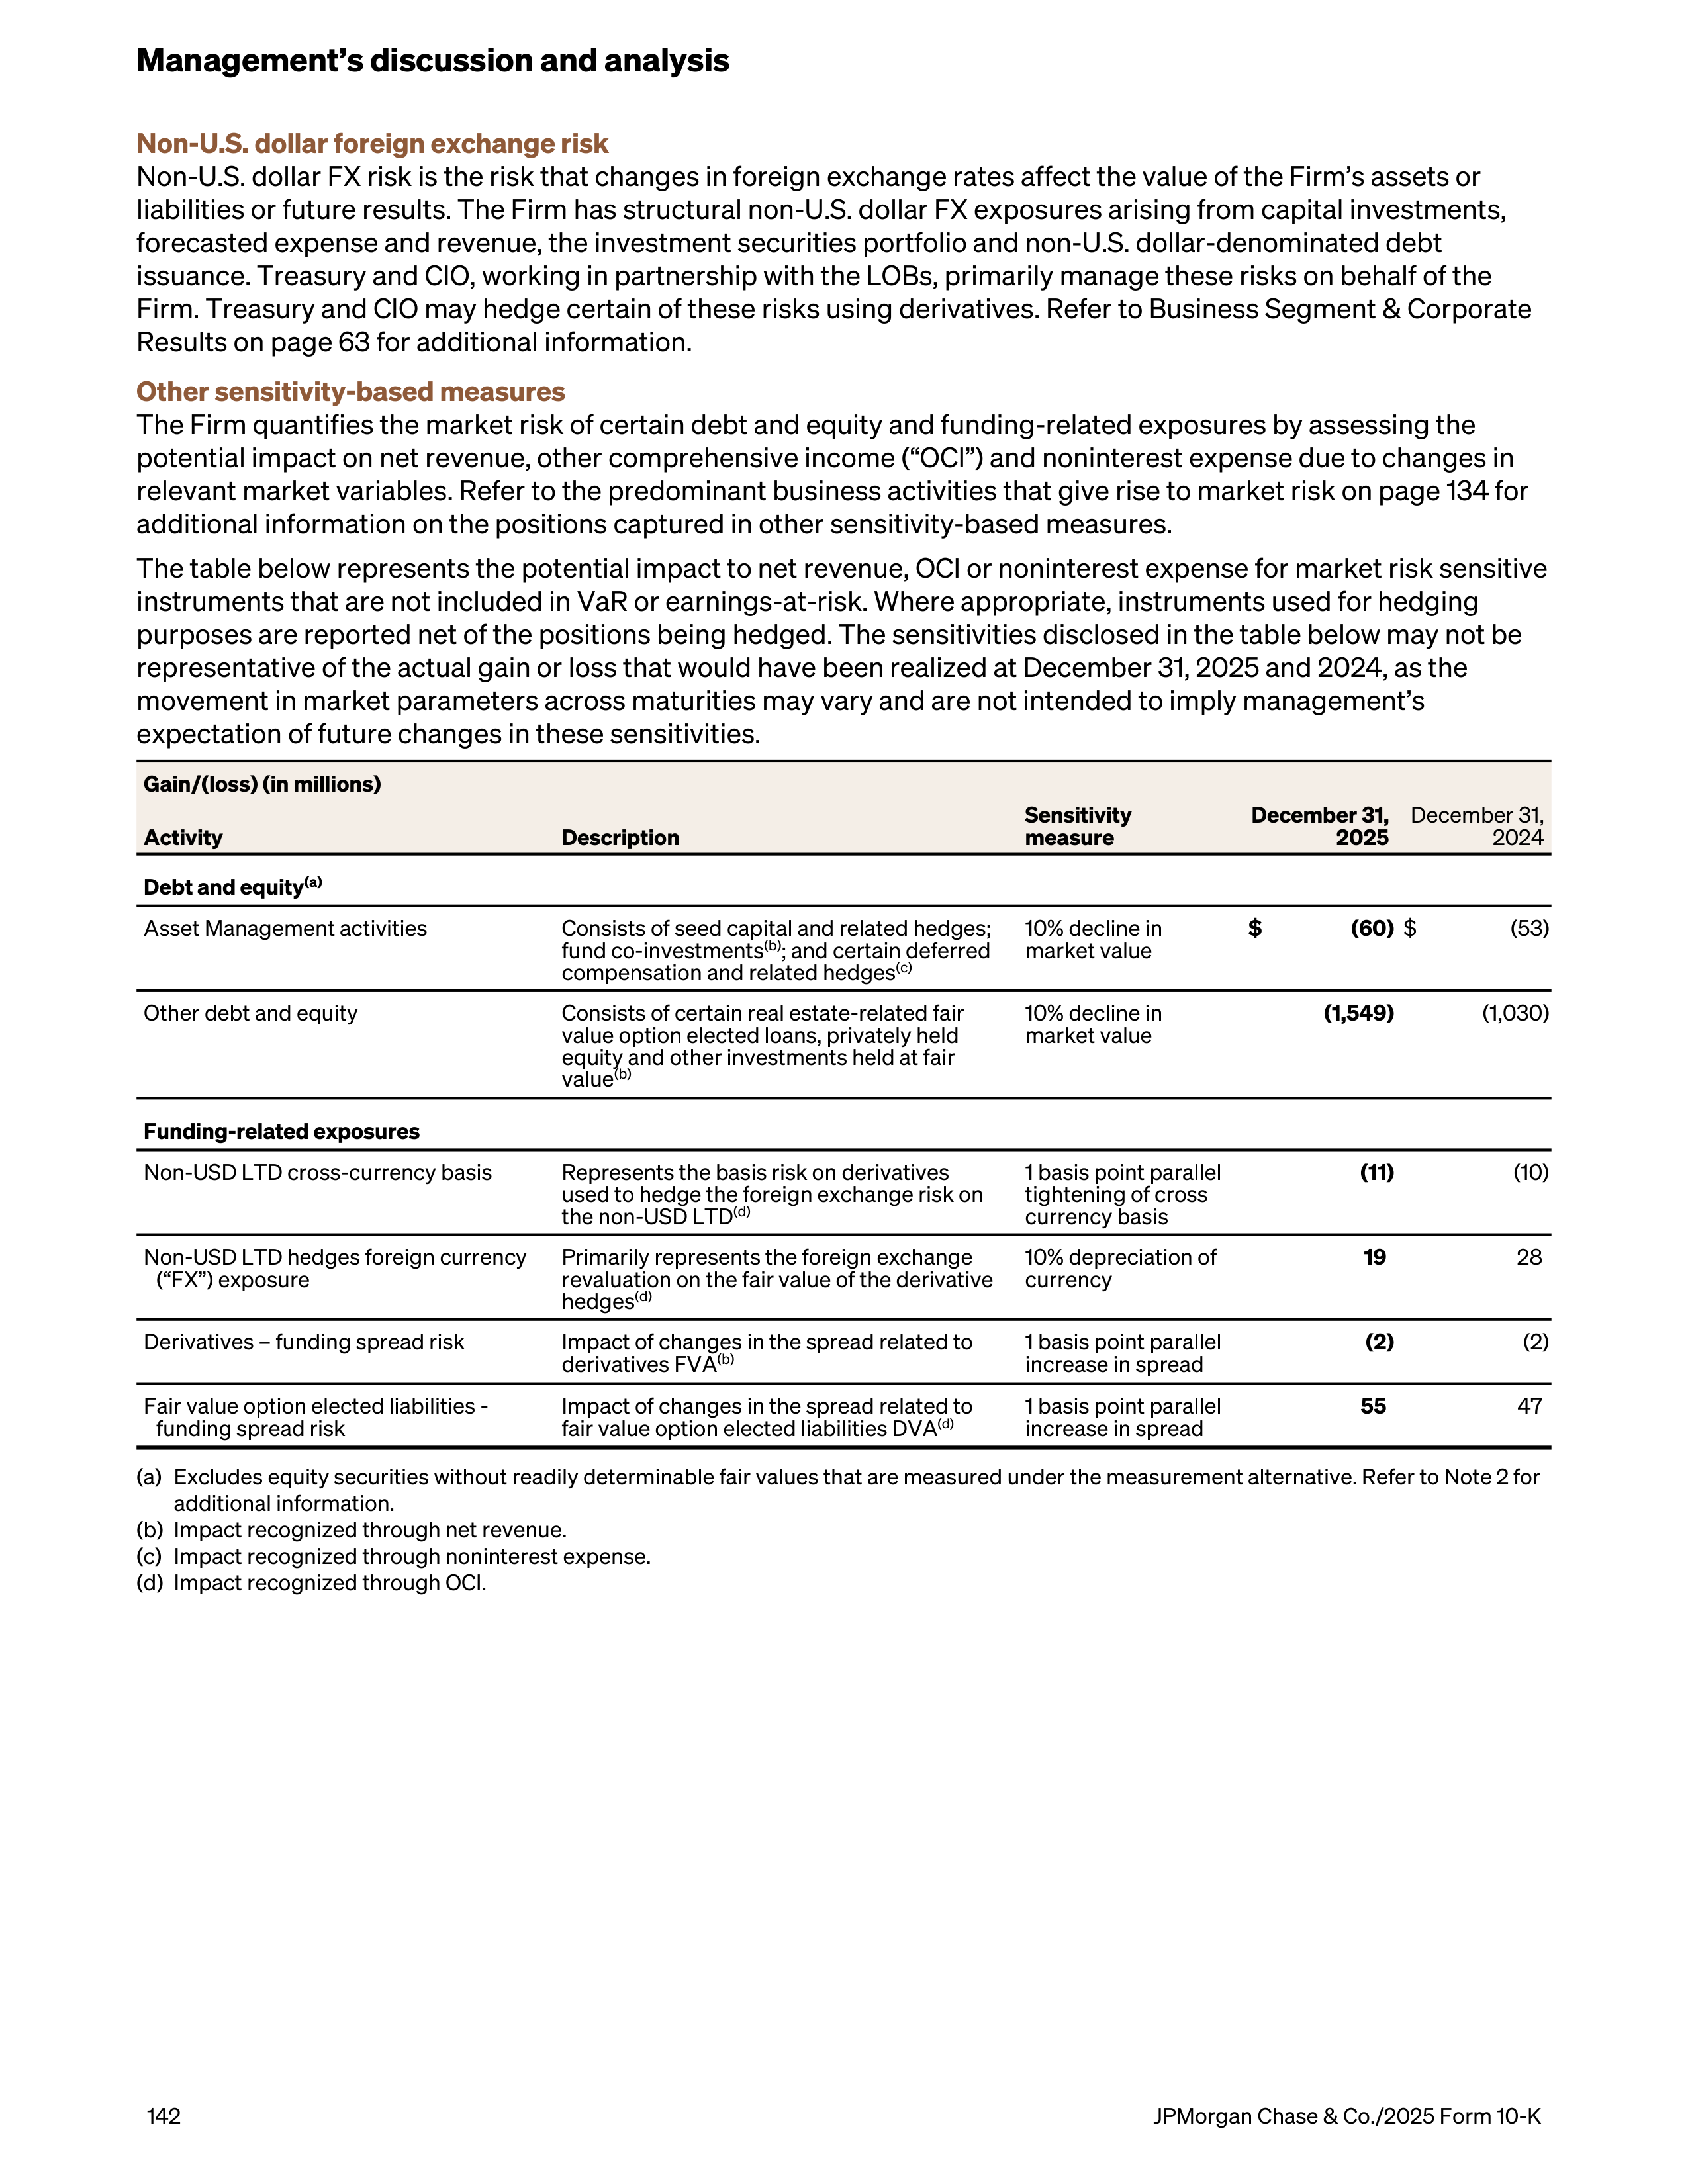
Non-U.S. dollar foreign exchange risk
Non-U.S. dollar FX risk is the risk that changes in foreign exchange rates affect the value of the Firm’s assets or
liabilities or future results. The Firm has structural non-U.S. dollar FX exposures arising from capital investments,
forecasted expense and revenue, the investment securities portfolio and non-U.S. dollar-denominated debt
issuance. Treasury and CIO, working in partnership with the LOBs, primarily manage these risks on behalf of the
Firm. Treasury and CIO may hedge certain of these risks using derivatives. Refer to Business Segment & Corporate
Results on page 63 for additional information.
Other sensitivity-based measures
The Firm quantifies the market risk of certain debt and equity and funding-related exposures by assessing the
potential impact on net revenue, other comprehensive income (“OCI”) and noninterest expense due to changes in
relevant market variables. Refer to the predominant business activities that give rise to market risk on page 134 for
additional information on the positions captured in other sensitivity-based measures.
The table below represents the potential impact to net revenue, OCI or noninterest expense for market risk sensitive
instruments that are not included in VaR or earnings-at-risk. Where appropriate, instruments used for hedging
purposes are reported net of the positions being hedged. The sensitivities disclosed in the table below may not be
representative of the actual gain or loss that would have been realized at December 31, 2025 and 2024, as the
movement in market parameters across maturities may vary and are not intended to imply management’s
expectation of future changes in these sensitivities.
Gain/(loss) (in millions)
Activity
Description
Sensitivity
measure
December 31,
2025
December 31,
2024
Debt and equity
(a)
Asset Management activities
Consists of seed capital and related hedges;
fund co-investments
(b)
; and certain deferred
compensation and related hedges
(c)
10% decline in
market value
$
(60)
$
(53)
Other debt and equity
Consists of certain real estate-related fair
value option elected loans, privately held
equity and other investments held at fair
value
(b)
10% decline in
market value
(1,549)
(1,030)
Funding-related exposures
Non-USD LTD cross-currency basis
Represents the basis risk on derivatives
used to hedge the foreign exchange risk on
the non-USD LTD
(d)
1 basis point parallel
tightening of cross
currency basis
(11)
(10)
Non-USD LTD hedges foreign currency
(“FX”) exposure
Primarily represents the foreign exchange
revaluation on the fair value of the derivative
hedges
(d)
10% depreciation of
currency
19
28
Derivatives – funding spread risk
Impact of changes in the spread related to
derivatives FVA
(b)
1 basis point parallel
increase in spread
(2)
(2)
Fair value option elected liabilities -
funding spread risk
Impact of changes in the spread related to
fair value option elected liabilities DVA
(d)
1 basis point parallel
increase in spread
55
47
(a)
Excludes equity securities without readily determinable fair values that are measured under the measurement alternative. Refer to Note 2 for
additional information.
(b)
Impact recognized through net revenue.
(c)
Impact recognized through noninterest expense.
(d)
Impact recognized through OCI.
Management’s discussion and analysis
142
JPMorgan Chase & Co./2025 Form 10-K
COUNTRY RISK MANAGEMENT
The Firm, through its LOBs and Corporate, may be
exposed to country risk resulting from financial,
economic, political or other significant developments
which adversely affect the value of the Firm’s
exposures related to a particular country or set of
countries. The Country Risk Management group
actively monitors the various portfolios which may be
impacted by these developments and measures the
extent to which
the Firm’s exposures are diversified
given the Firm’s strategy and risk tolerance relative to
a country.
Organization and management
Country Risk Management is an independent risk
management function that assesses, measures and
monitors exposure to country risk across the Firm.
The Firm’s country risk management function includes
the following activities:
•
Maintaining policies, procedures and standards
consistent with a comprehensive country risk
framework
•
Assigning sovereign ratings, assessing country risks
and establishing risk tolerance relative to a country
•
Measuring and monitoring country risk exposure
and stress across the Firm
•
Managing and approving country limits and
reporting trends and limit breaches to senior
management
•
Developing surveillance tools, such as signaling
models and ratings indicators, for early identification
of potential country risk concerns
•
Providing country risk scenario analysis
Sources and measurement
The Firm is exposed to country risk through its lending
and deposits, investing, and market-making activities,
whether cross-border or locally funded. Country
exposure includes activity with both government and
private-sector entities in a country.
Under the Firm’s internal country risk management
approach, attribution of exposure to an individual
country is based on the country where the largest
proportion of the assets of the
counterparty, issuer,
obligor or guarantor are located or where the largest
proportion of its revenue is derived, which may be
different than the domicile (i.e. legal residence) or
country of incorporation.
Individual country exposures reflect an aggregation of
the Firm’s risk to an immediate default, with zero
recovery, of the counterparties, issuers, obligors or
guarantors attributed to that country. Activities which
result in contingent or indirect exposure to a country
are not included in the country exposure measure (for
example, providing clearing services or secondary
exposure to collateral on securities financing
receivables).
Assumptions are sometimes required in determining
the measurement and allocation of country exposure,
particularly in the case of certain non-linear or index
products, or where the nature of the counterparty,
issuer, obligor or guarantor is not suitable for
attribution to an individual country. The use of
different measurement approaches or assumptions
could affect the amount of reported country exposure.
Under the Firm’s internal country risk measurement
framework:
•
Deposits with banks are measured as the cash
balances placed with central banks, commercial
banks, and other financial institutions
•
Lending exposures are measured at the total
committed amount (funded and unfunded), net of
the allowance for credit losses and eligible cash and
marketable securities collateral received
•
Securities financing exposures are measured at their
receivable balance, net of eligible collateral received
•
Debt and equity securities are measured at the fair
value of all positions, including both long and short
positions
•
Counterparty exposure on derivative receivables is
measured at the derivative’s fair value, net of the fair
value of the eligible collateral received
•
Credit derivatives exposure is measured at the net
notional amount of protection purchased or sold for
the same underlying reference entity, inclusive of the
fair value of the derivative receivable or payable,
reflecting the manner in which the Firm manages
these exposures
The Firm’s internal country risk reporting differs from
the reporting provided under the FFIEC bank
regulatory requirements.
JPMorgan Chase & Co./2025 Form 10-K
143
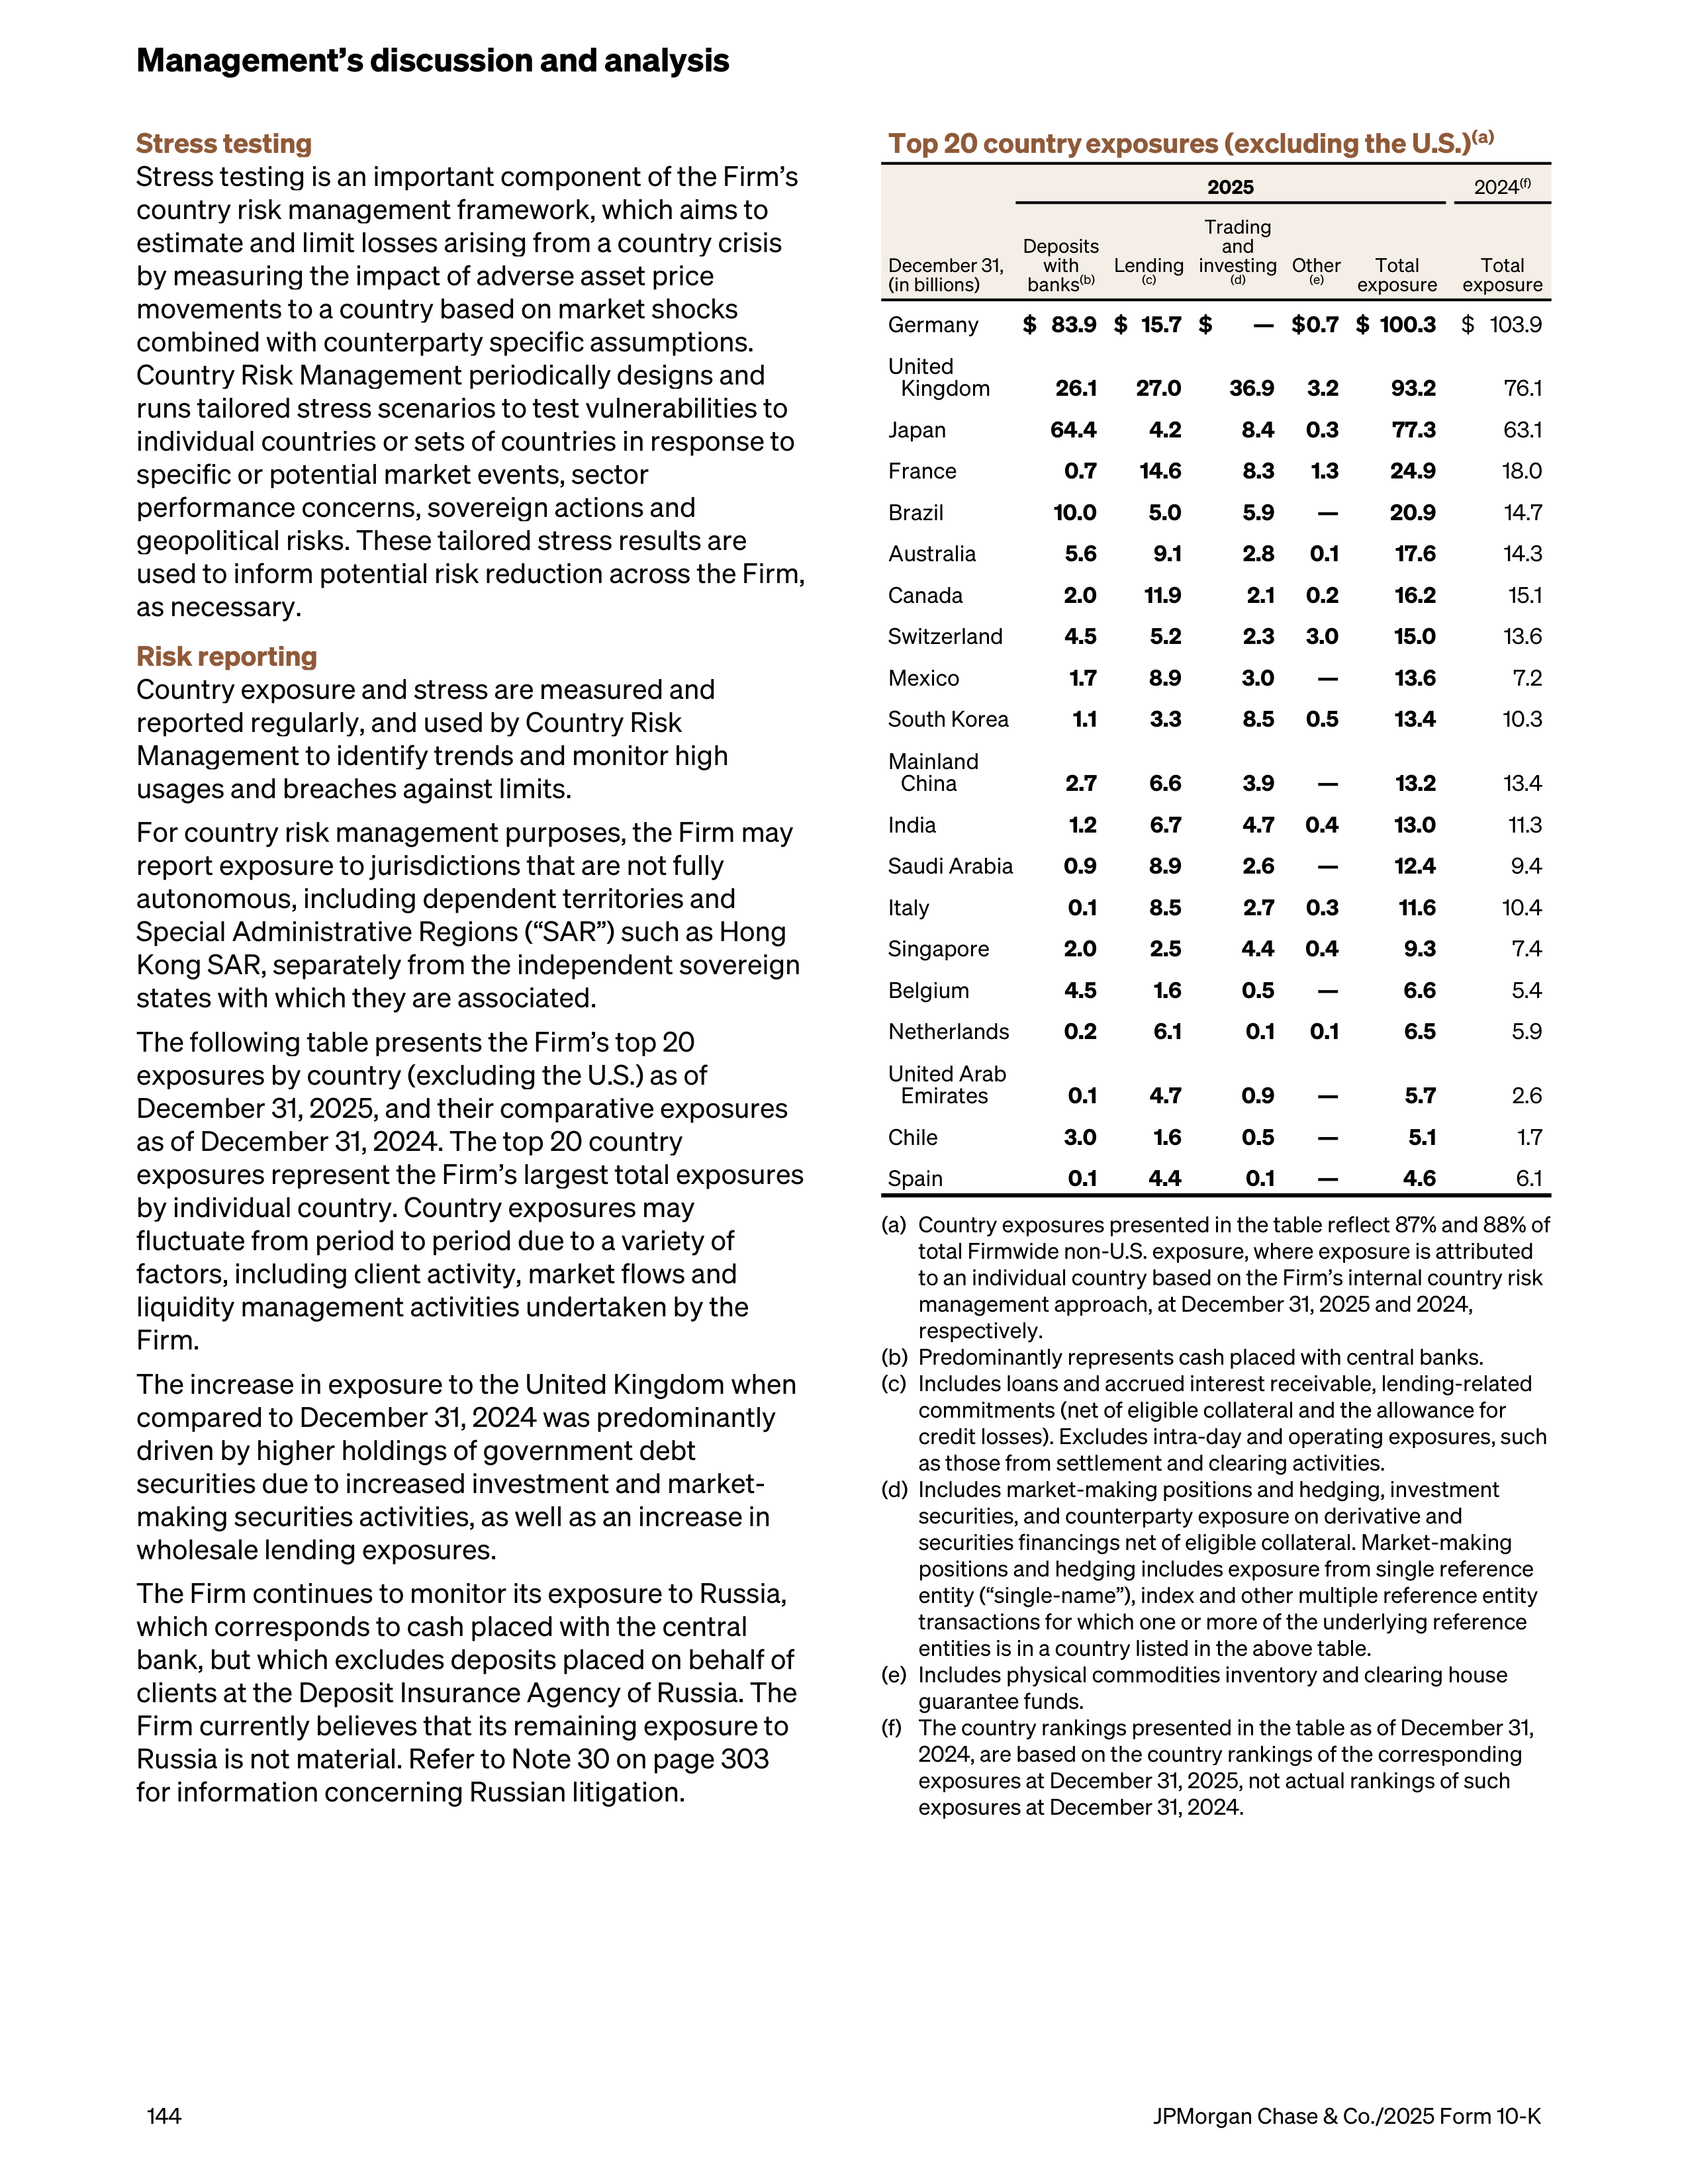
Stress testing
Stress testing is an important component of the Firm’s
country risk management framework, which aims to
estimate and limit losses arising from a country crisis
by measuring the impact of adverse asset price
movements to a country based on market shocks
combined with counterparty specific assumptions.
Country Risk Management periodically designs and
runs tailored stress scenarios to test vulnerabilities to
individual countries or sets
of countries in response to
specific or potential market events, sector
performance concerns, sovereign actions and
geopolitical risks. These tailored stress results are
used to inform potential risk reduction across the Firm,
as necessary.
Risk reporting
Country exposure and stress are measured and
reported regularly, and used by Country Risk
Management to identify trends and monitor high
usages and breaches against limits.
For country risk management purposes, the Firm may
report exposure to jurisdictions that are not fully
autonomous, including dependent territories and
Special Administrative Regions (“SAR”) such as Hong
Kong SAR, separately from the independent sovereign
states with which they are associated.
The following table presents the Firm’s top 20
exposures by country (excluding the U.S.) as of
December 31, 2025, and their comparative exposures
as of December 31, 2024. The top 20 country
exposures represent the Firm’s largest total exposures
by individual country. Country exposures may
fluctuate from period to period due to a variety of
factors, including client activity, market flows and
liquidity management activities undertaken by the
Firm.
The increase in exposure to the United Kingdom when
compared to December 31, 2024 was predominantly
driven by higher holdings of government debt
securities due to increased investment and market-
making securities activities, as well as an increase in
wholesale lending exposures.
The Firm continues to monitor its exposure to Russia,
which corresponds to cash placed with the central
bank, but which excludes deposits placed on behalf of
clients at the Deposit Insurance Agency of Russia. The
Firm currently believes that its remaining exposure to
Russia is not material. Refer to Note 30 on page 303
for information concerning Russian litigation.
Top 20 country
exposures (excluding the U.S.)
(a)
December 31,
(in billions)
2025
2024
(f)
Deposits
with
banks
(b)
Lending
(c)
Trading
and
investing
(d)
Other
(e)
Total
exposure
Total
exposure
Germany
$ 83.9 $ 15.7 $
— $ 0.7 $ 100.3
$ 103.9
United
Kingdom
26.1
27.0
36.9 3.2
93.2
76.1
Japan
64.4
4.2
8.4 0.3
77.3
63.1
France
0.7
14.6
8.3 1.3
24.9
18.0
Brazil
10.0
5.0
5.9
—
20.9
14.7
Australia
5.6
9.1
2.8 0.1
17.6
14.3
Canada
2.0
11.9
2.1 0.2
16.2
15.1
Switzerland
4.5
5.2
2.3 3.0
15.0
13.6
Mexico
1.7
8.9
3.0
—
13.6
7.2
South Korea
1.1
3.3
8.5 0.5
13.4
10.3
Mainland
China
2.7
6.6
3.9
—
13.2
13.4
India
1.2
6.7
4.7 0.4
13.0
11.3
Saudi Arabia
0.9
8.9
2.6
—
12.4
9.4
Italy
0.1
8.5
2.7 0.3
11.6
10.4
Singapore
2.0
2.5
4.4 0.4
9.3
7.4
Belgium
4.5
1.6
0.5
—
6.6
5.4
Netherlands
0.2
6.1
0.1 0.1
6.5
5.9
United Arab
Emirates
0.1
4.7
0.9
—
5.7
2.6
Chile
3.0
1.6
0.5
—
5.1
1.7
Spain
0.1
4.4
0.1
—
4.6
6.1
(a)
Country exposures presented in the table reflect 87% and 88% of
total Firmwide non-U.S. exposure,
where exposure is attributed
to an individual country based on the Firm’s internal country risk
management approach, at December 31, 2025 and 2024,
respectively.
(b)
Predominantly represents cash placed with central banks.
(c)
Includes loans and accrued interest receivable, lending-related
commitments (net of eligible collateral and the allowance for
credit losses). Excludes intra-day and operating exposures, such
as those from settlement and clearing activities.
(d)
Includes market-making positions and hedging, investment
securities, and counterparty exposure on derivative and
securities financings net of eligible collateral. Market-making
positions and hedging includes exposure from single reference
entity (“single-name”), index and other multiple reference entity
transactions for which one or more of the underlying reference
entities is in a country listed in the above table.
(e)
Includes physical commodities inventory and clearing house
guarantee funds.
(f)
The country rankings presented in the table as of December 31,
2024, are based on the country rankings of the corresponding
exposures at December 31, 2025, not actual rankings of such
exposures at December 31, 2024.
Management’s discussion and analysis
144
JPMorgan Chase & Co./2025 Form 10-K
CLIMATE RISK MANAGEMENT
Climate risk refers to the potential threats posed by
climate change to the Firm and its clients, customers,
operations and business strategy. Climate change is
viewed as a driver of risk that may impact existing
types of risks managed by the Firm. Climate risk is
categorized into physical risk and transition risk.
Physical risk involves economic costs and financial
losses due to a changing climate. Acute physical risk
drivers include the increased frequency or severity of
climate and weather events, such as floods, wildfires
and tropical cyclones. Chronic physical risk drivers
include more gradual shifts in the climate, such as sea
level rise, persistent changes in precipitation levels
and increases in average ambient temperatures.
Indirect physical risk drivers include the second-order
effects of these acute and chronic risks, such as supply
chain disruptions or changes to property valuations.
Transition risk involves the financial and economic
consequences of society’s shift toward a lower-carbon
economy. Transition risk drivers include possible
changes in public policy, adoption of new technologies
and shifts in consumer preferences. Transition risks
may also be influenced by changes in the physical
climate.
Organization and management
The Firm’s Climate, Nature and Social Risk
Management function is responsible for establishing
and maintaining the Firmwide framework and strategy
for managing climate risk.
Other responsibilities of that function include:
•
Establishing and maintaining policies, standards,
procedures and processes to support identification,
escalation, monitoring and management of climate
risk across the Firm
•
Developing metrics, scenarios and stress testing
mechanisms designed to assess the range of
potential climate-related financial and economic
impacts to the Firm
•
Establishing a Firmwide climate risk data strategy
and the supporting climate risk technology
infrastructure
The LOBs and Corporate are responsible for the
identification, assessment and management of climate
risks present in their business activities and for the
adherence to applicable climate-related laws, rules
and regulations.
Governance and oversight
The Firm’s framework and strategy for identifying,
monitoring and managing climate risk is integrated
into the Firm’s risk governance framework. This
framework allows for the escalation of significant
climate risk-related issues to LOB Risk Committees.
The Board Risk Committee also receives information
on significant climate risks and climate-related
initiatives, as appropriate.
JPMorgan Chase & Co./2025 Form 10-K
145
OPERATIONAL RISK MANAGEMENT
Operational risk is the risk of an adverse outcome
resulting from inadequate or failed internal processes
or systems; human factors; or external events
impacting the Firm’s processes or systems.
Operational risk includes compliance, conduct, legal,
and estimations and model risk. Operational risk is
inherent in the Firm’s activities and can manifest
itself
in various ways, including fraudulent acts, business
disruptions (including those caused by extraordinary
events beyond the Firm's control), cyber attacks,
inappropriate employee behavior, failure to comply
with applicable laws, rules and regulations or failure of
vendors or other third party providers to perform in
accordance with their agreements. Operational Risk
Management attempts to manage operational risk at
appropriate levels in light of the Firm’s financial
position, the characteristics of its businesses, and the
markets and regulatory environments in which it
operates.
Operational Risk Management Framework
The Firm’s Compliance, Conduct, and Operational Risk
(“CCOR”) Management Framework is designed to
enable the Firm to govern, identify, measure, monitor
and test, manage and report on the Firm’s operational
risk.
Operational Risk Governance
The LOBs and Corporate are responsible for the
management of operational risk. The Control
Management Organization, which consists of control
managers within each LOB and Corporate, is
responsible for the day-to-day execution of the CCOR
Management Framework.
The Firm’s Global Chief Compliance Officer (“CCO”) and
FRE for Operational Risk and Qualitative Risk Appetite
is responsible for defining the CCOR Management
Framework and establishing the minimum standards
for its execution. The LOB and Corporate aligned
officers of the CCOR organization oversee activity
performed by their aligned LOB and Corporate. These
officers report to the Global CCO and FRE for
Operational Risk and Qualitative Risk Appetite and are
independent of the respective businesses or functions
that they oversee. The CCOR Management Framework
is included in the Risk Governance and Oversight
Policy that is reviewed and approved by the Board Risk
Committee periodically.
Operational Risk Identification
The Firm utilizes a structured risk and control self-
assessment process that is executed by the LOBs and
Corporate. As part of this process, the LOBs and
Corporate evaluate the effectiveness of their respective
control environment to assess circumstances in which
controls have failed, and to determine where
remediation efforts may be required. The Firm’s
Operational Risk and Compliance organization
(“Operational Risk and Compliance”) provides
oversight of and challenge to these evaluations and
may also perform independent assessments of
significant operational risk events and areas of
concentrated or emerging risk.
Operational Risk Measurement
The CCOR organization is responsible for providing
independent, risk-based review and oversight of
assessments conducted by the LOBs and Corporate
with respect to compliance, conduct and operational
risks. This includes oversight of the LOBs’ and
Corporate’s assessments of the design, execution, and
evaluation of associated controls, against standards
established by the CCOR organization.
In addition, Operational Risk and Compliance assesses
operational risks through quantitative means, including
operational risk-based capital and estimation of
operational risk losses under both baseline and
stressed conditions.
The primary component of the operational risk-based
capital estimate is the Loss Distribution Approach
(“LDA”) statistical model, which simulates the projected
frequency and severity of operational risk losses based
on historical data. The LDA model is used to estimate
an aggregate operational risk loss over a one-year time
horizon, at a 99.9% confidence level. The LDA model
incorporates actual internal operational risk losses in
the quarter following the period in which those losses
were realized, and the calculation generally continues
to reflect such losses even after the issues or business
activities giving rise to the losses have been
remediated or reduced.
As required under the Basel III capital framework, the
Firm’s operational risk capital methodology, which uses
the Advanced Measurement Approach (“AMA”),
incorporates internal and external losses as well as
management’s view of tail risk captured through
operational risk scenario analysis, and evaluation of key
business environment and internal control metrics. The
Firm does not reflect the impact of insurance in its AMA
estimate of operational risk capital.
The Firm considers the impact of stressed economic
conditions on operational risk losses and develops a
forward looking view of material operational risk events
that may occur in a stressed environment. The Firm’s
operational risk stress testing framework is utilized in
calculating results for the Firm’s CCAR and other stress
testing processes.
Refer to Capital Risk Management on pages 89–99 for
information related to operational risk RWA, and CCAR.
Operational Risk Monitoring and Testing
Independent testing and monitoring of controls are
integral components of the CCOR Management
Framework. These testing and monitoring activities are
Management’s discussion and analysis
146
JPMorgan Chase & Co./2025 Form 10-K
conducted under the CCOR organization’s Monitoring
and Testing Program (“M&T Program”) and:
•
are based upon the Firm’s compliance, conduct and
operational risk assessments;
•
are designed to identify control gaps or deficiencies,
including potential non-compliance with applicable
laws, rules and regulations; and
•
assess whether the procedures, processes and
controls used by the Firm to mitigate compliance,
conduct and operational risk are well-designed and
functioning as intended.
The Testing Center of Excellence (“TCoE”), reporting to
the Control Management Organization, is responsible
for executing testing activities outlined under the M&T
Program, and the CCOR organization Testing Program
Governance and Oversight team provides independent
governance and oversight of both the M&T Program
and the TCoE testing activities through defined
processes and responsibilities.
The results of risk assessments performed by
Operational Risk and Compliance are used in
connection with their independent monitoring and
testing compliance of the LOBs and Corporate with
laws, rules and regulations. Through monitoring and
testing, Operational Risk and Compliance
independently identify areas of heightened operational
risk and tests the effectiveness of controls within the
LOBs and Corporate.
Management of Operational Risk
The operational risk areas or issues identified through
monitoring and testing are escalated to the LOBs and
Corporate to be remediated through action plans, as
needed, to mitigate operational risk. Operational Risk
and Compliance may advise the LOBs and Corporate in
the development and implementation of action plans.
Operational Risk Reporting
All employees of the Firm are expected to escalate
risks appropriately. Risks identified by Operational Risk
and Compliance are escalated to the appropriate LOB
and Corporate Control Committees, as needed.
Operational Risk and Compliance has established
standards designed to ensure that consistent
operational risk reporting and operational risk reports
are produced on a Firmwide basis as well as by the
LOBs and Corporate. Reporting includes the evaluation
of key risk and performance indicators against
established thresholds as well as the assessment of
different types of operational risk against stated risk
appetite. The standards establish escalation protocols
to senior management and to the Board of Directors.
Insurance
One of the ways in which operational risk may be
mitigated is through insurance maintained by the Firm.
The Firm purchases insurance from commercial
insurers and maintains a wholly-owned captive insurer,
Park Assurance Company. Insurance may also be
required by third parties with whom the Firm does
business.
Subcategories and examples of operational risks
Operational risk can manifest itself in various ways.
Operational risk subcategories include Compliance
risk, Conduct risk, Legal risk, and Estimations and
Model risk. Refer to pages 150, 151, 152 and 153,
respectively for more information on Compliance,
Conduct, Legal, and Estimations and Model risk. Details
on other select examples of operational risks such as
firmwide resiliency, payment fraud and third-party
outsourcing, as well as cybersecurity, are provided
below.
Firmwide resiliency risk
Disruptions of the Firm’s business and operations can
occur due to forces beyond the Firm’s control such as
health emergencies, severe weather, natural disasters,
the effects of climate change, utility or
telecommunications failures, interruption of service
from third-party service providers, cyberattacks, civil
unrest or terrorism. The Firm’s resiliency framework is
intended to enable the Firm to prepare for and adapt to
changing conditions and withstand and recover from,
and address adverse effects on its operations caused
by, disruptions that may impact critical business
functions and supporting assets, including its staff,
technology, data and facilities, as well as those of third-
party service providers. The framework includes
governance, awareness training, planning and testing
of recovery strategies, as well as strategic and tactical
initiatives to identify, assess, and manage resiliency
risks. The framework operates in accordance with the
Firm’s overall approach to Operational Risk
Management, including alignment with technology,
cybersecurity, data, physical security, crisis
management, real estate and outsourcing programs.
Payment fraud risk
Payment fraud risk is the risk of external and internal
parties unlawfully obtaining personal monetary benefit
through misdirected or otherwise improper payment.
The Firm employs various controls for managing
payment fraud risk as well as providing employee and
client education and awareness trainings.
Third-party outsourcing risk
The Firm‘s Third-Party Oversight (“TPO”) and Inter-
affiliates Oversight (“IAO”) frameworks assist the LOBs
and Corporate in selecting, documenting, onboarding,
monitoring and managing their supplier relationships
including services provided by affiliates. The objectives
of the TPO framework are to hold suppliers and other
third parties to an appropriate standard of operational
performance and to mitigate key risks, including data
loss and business disruptions. The Corporate Third-
Party Oversight group is responsible for Firmwide
training, monitoring, reporting and standards with
respect to third-party outsourcing risks.
JPMorgan Chase & Co./2025 Form 10-K
147
Cybersecurity risk
Cybersecurity risk is the risk of harm or loss resulting
from misuse or abuse of technology or the
unauthorized disclosure of data.
Overview
Cybersecurity risk is an important and continuously
evolving focus for the Firm. Significant resources are
devoted to protecting and enhancing the security of
computer systems, software, networks, storage
devices, and other technology. The Firm’s security
efforts are designed to protect against, among other
things, cybersecurity attacks that can result in
unauthorized access to confidential information, the
destruction of data, disruptions to or degradations of
service, the sabotaging of systems or other damage.
The Firm has experienced, and expects that it will
continue to experience, a higher volume and
complexity of cyber attacks against the backdrop of
heightened geopolitical tensions and emerging
technologies that can be leveraged by attackers,
including artificial intelligence. The Firm has
implemented measures and controls reasonably
designed to address this evolving environment,
including enhanced threat monitoring. In addition, the
Firm continues to review and enhance its capabilities
to address associated risks, such as those relating to
the management of administrative access to systems.
Third parties with which the Firm does business, that
facilitate the Firm’s business activities (e.g., vendors,
supply chain, exchanges, clearing houses, central
depositories, and financial intermediaries) or that the
Firm has acquired are also sources of cybersecurity
risk to the Firm. Third party incidents such as system
breakdowns or failures, misconduct by the employees
of such parties, or cyber attacks, including
ransomware and supply-chain compromises, could
have a material adverse effect on the Firm, including in
circumstances in which an affected third party is
unable to deliver a product or service to the Firm or
where the incident delivers compromised software to
the Firm or results in lost or compromised information
of the Firm or its clients or customers.
Clients and customers are also sources of
cybersecurity risk to the Firm and its information
assets, particularly when their activities and systems
are beyond the Firm’s own security and control
systems. The Firm engages in periodic discussions
with its clients, customers and other external parties
concerning cybersecurity risks including opportunities
to improve cybersecurity.
Risks from cybersecurity threats, including any
previous cybersecurity events, have not materially
affected the Firm or its business strategy, results of
operations or financial condition. Notwithstanding the
comprehensive approach that the Firm takes to
address cybersecurity risk, the Firm may not be
successful in preventing or mitigating a future
cybersecurity incident that could have a material
adverse effect on the Firm or its business strategy,
results of operations or financial condition.
Organization and management
The Global Chief Information Security Officer (“CISO”)
reports to the Global Chief Information Officer, and is a
member of key cybersecurity governance forums. The
CISO leads the Global Cybersecurity and Technology
Controls organization, which is responsible for
identifying technology and cybersecurity risks and for
implementing and maintaining controls to manage
cybersecurity threats. The CISO and the members of
senior management within Global Technology and the
Cybersecurity and Technology Controls organizations
all have relevant expertise and experience in
cybersecurity and information technology risk
management, including relevant experience at the
Firm, at other financial services companies or in other
highly-regulated industries.
The CISO is responsible for the Firm’s Information
Security Program, which is designed to prevent, detect
and respond to cyber attacks in order to help
safeguard the confidentiality, integrity and availability
of the Firm's infrastructure, resources and information.
The program includes managing the Firm’s global
cybersecurity operations centers, providing training,
conducting cybersecurity event simulation exercises,
implementing the Firm’s policies and standards
relating to technology risk and cybersecurity
management, and enhancing, as needed, the Firm’s
cybersecurity capabilities.
The Firm’s Information Security Program includes the
following functions:
Cyber Operations
, which is responsible for
implementing and maintaining controls designed to
detect and defend the Firm against cyber attacks, and
includes a dedicated function for incident response
and ongoing monitoring for cybersecurity threats and
vulnerabilities, including those among the Firm’s third-
party suppliers.
Technology Governance, Risk & Controls
, which is
responsible for operationalizing technology risk and
control frameworks, analyzing regulatory
developments that may impact the Firm, and
developing control catalogs and assessments of
controls, as well as overseeing governance and
reporting of technology and cybersecurity risk.
Security Awareness
, which provides awareness and
training that reinforces information risk and security
management practices and compliance with the Firm's
policies, standards and practices. The training is
mandatory for all employees globally on a periodic
basis, and it is supplemented by Firmwide testing
initiatives, including periodic phishing tests. The Firm
Management’s discussion and analysis
148
JPMorgan Chase & Co./2025 Form 10-K
also provides specialized security training to
employees in specific roles, such as application
developers. The Firm’s Global Privacy Program
requires all employees to take periodic training on
data privacy that focuses on confidentiality and
security, as well as responding to unauthorized access
to or use of information.
Technology Resiliency
, which establishes control
requirements for planning and testing the prioritized
recovery of technology services in the event of
degradation or outage, including incident response
planning, data backup and retention, and recovery
readiness in support of the Firmwide Business
Resiliency Program and operational risk management
practices.
The Firm has a cybersecurity incident response plan
designed to enable the Firm to respond to attempted
cybersecurity incidents, coordinate as appropriate
with law enforcement and other government agencies,
notify clients and customers, as applicable, and
recover from such incidents. In addition, the Firm
actively partners with appropriate government and law
enforcement agencies and peer industry forums,
participating in discussions and simulations to assist in
understanding the full spectrum of cybersecurity risks
and in enhancing defenses and improving resiliency in
the Firm’s operating environment.
Governance and oversight
The governance structure for the Global Cybersecurity
and Technology Controls organization is designed to
appropriately identify, escalate and mitigate
cybersecurity risks. Cybersecurity risk management
and its governance and oversight are integrated into
the Firm’s operational risk management framework,
including through the escalation of key risk and control
issues to management and the development of risk
mitigation plans for heightened risk and control issues.
IRM independently assesses and challenges the
activities and risk management practices of the Global
Cybersecurity and Technology Controls organization
related to the identification, assessment,
measurement and mitigation of cybersecurity risk. As
needed, the Firm engages third-party assessors or
auditing firms with industry-recognized expertise on
cybersecurity matters to review specific aspects of the
Firm’s cybersecurity risk management framework,
processes and controls.
The governance and oversight for cybersecurity risk
management includes governance forums that inform
management of key areas of concern regarding the
prevention, detection, mitigation and remediation of
cybersecurity risks.
The Cybersecurity and Technology Controls Operating
Committee (“CTOC”) is the principal management
committee that oversees the Firm’s assessment and
management of cybersecurity risk, including oversight
of the implementation and maintenance of appropriate
controls in support of the Firm’s Information Security
Program. The membership of the CTOC includes
senior representatives from the Global Cybersecurity
and Technology Controls organization and relevant
corporate functions, including IRM and Internal Audit.
The CTOC escalates key operational risk and control
issues, as appropriate, to the Global Technology
Operating Committee (“GTOC”) or its business control
committee or to the appropriate LOB and Corporate
Control Committees. The GTOC is responsible for the
governance of the Firmwide Global Technology
organization, including oversight of Firmwide
technology strategies, the delivery of technology and
technology operations, the effective use of information
technology resources, and monitoring and resolving
key operational risk and control matters arising in the
Global Technology organization.
As part of its oversight of management’s
implementation and maintenance of the Firm’s risk
management framework, the Firm’s Board of Directors
receives periodic updates from the CIO, the CISO and
senior members of the CTOC concerning
cybersecurity matters. These updates generally
include information regarding cybersecurity and
technology developments, the Firm’s Information
Security Program and recommended changes to that
program, cybersecurity policies and practices, and
ongoing initiatives to improve information security, as
well as any significant cybersecurity incidents and the
Firm's efforts to address those incidents. The Audit
Committee and the Risk Committee assist the Board in
this oversight.
JPMorgan Chase & Co./2025 Form 10-K
149
COMPLIANCE RISK MANAGEMENT
Compliance risk, a subcategory of operational risk, is
the risk of failing to comply with laws, rules, regulations
or codes of conduct and standards of self-regulatory
organizations.
Overview
Each of the LOBs and Corporate hold primary
ownership of and accountability for managing their
compliance risk. The Firm’s Operational Risk and
Compliance Organization (“Operational Risk and
Compliance”), which is independent of the LOBs and
Corporate, provides independent review, monitoring
and oversight of business operations with a focus on
compliance with the laws, rules, and regulations
applicable to the delivery of the Firm’s products and
services to clients and customers.
These compliance risks relate to a wide variety of laws,
rules and regulations across the LOBs and Corporate,
and jurisdictions, and include risks related to financial
products and services, relationships and interactions
with clients and customers, and employee activities.
For example, compliance risks include those
associated with anti-money laundering compliance,
trading activities, market conduct, and complying with
the laws, rules, and regulations related to the offering
of products and services across jurisdictional borders.
Compliance risk is also inherent in the Firm’s fiduciary
activities, including the failure to exercise the
applicable standard of care to act in the best interest
of fiduciary clients and customers or to treat fiduciary
clients and customers fairly.
Other functions provide oversight of significant
regulatory obligations that are specific to their
respective areas of responsibility.
Operational Risk and Compliance implements policies
and standards designed to govern, identify, measure,
monitor and test, manage, and report on compliance
risk.
Governance and oversight
Operational Risk and Compliance is led by the Firm’s
Global CCO and FRE for Operational Risk and
Qualitative Risk Appetite.
The Firm maintains oversight and coordination of its
compliance risk through the CCOR Management
Framework. The Firm’s Global CCO and FRE for
Operational Risk and Qualitative Risk Appetite also
provides regular updates to the Board Risk Committee
and the Audit Committee on significant compliance
risk issues, as appropriate.
Code of Conduct
The Firm has a Code of Conduct (the “Code”) that sets
forth the Firm’s expectation that employees will
conduct themselves with integrity, at all times. The
Code provides the principles that help govern
employee conduct with clients, customers, suppliers,
vendors, shareholders, regulators, other employees, as
well as with the markets and communities in which the
Firm operates. The Code requires employees to
promptly report any potential or actual violation of the
Code, Firm policies, or laws, rules or regulations
applicable to the Firm’s business. It also requires
employees to report any illegal or unethical conduct,
or conduct that violates the underlying principles of
the Code, by any of the Firm’s employees, consultants,
clients, customers, suppliers, contract or temporary
workers, or business partners or agents. Conduct
training is assigned to newly-hired employees after
joining the Firm, and to current employees periodically
thereafter. Employees are required to affirm their
compliance with the Code annually.
Employees can report any potential or actual violations
of the Code through the Firm’s Conduct Hotline (the
“Hotline”) by phone, mobile device or the internet. The
Hotline is anonymous, where permitted by law, is
available at all times globally, has translation services,
and is administered by an outside service provider.
The Code prohibits retaliation against anyone who
raises an issue or concern in good faith or assists with
an inquiry or investigation. Periodically, the Audit
Committee receives reports on the Code of Conduct
program.
Management’s discussion and analysis
150
JPMorgan Chase & Co./2025 Form 10-K
CONDUCT RISK MANAGEMENT
Conduct risk, a subcategory of operational risk, is the
risk that any action or misconduct by an employee
could lead to unfair client or customer outcomes,
impact the integrity of the markets in which the Firm
operates, harm employees or the Firm, or compromise
the Firm’s reputation.
Overview
Each LOB and Corporate is accountable for identifying
and managing its conduct risk to provide appropriate
engagement, ownership and sustainability of a culture
consistent with the Firm’s Business Principles. The
Business Principles serve as a guide for how
employees are expected to conduct themselves. With
the Business Principles serving as a guide, the Firm’s
Code sets out the Firm’s expectations for each
employee and provides information and resources to
help e
mployees conduct business ethically and in
compliance with applicable laws, rules and regulations
everywhere the Firm operates. Refer to Compliance
Risk Management on page 150 for further discussion
of the Code.
Governance and oversight
The Firm’s oversight and coordination of conduct risk
is managed in the same manner as Compliance risk.
Refer to Compliance Risk Management on
page 150
for further information.
Conduct risk management encompasses various
aspects of people management practices throughout
the employee life cycle, including recruiting,
onboarding, training and development, performance
management, promotion and compensation
processes. Each LOB, Treasury and CIO, and each
designated corporate function completes an
assessment of conduct risk periodically, reviews
metrics and issues which may involve conduct risk,
and provides conduct education as appropriate.
JPMorgan Chase & Co./2025 Form 10-K
151
LEGAL RISK MANAGEMENT
Legal risk, a subcategory of operational risk, is the risk
of loss primarily caused by the actual or alleged failure
to meet legal obligations that arise from the rule of law
in jurisdictions in which the Firm operates, agreements
with clients and customers, and products and services
offered by the Firm.
Overview
The global Legal function (“Legal”) provides legal
services and advice to the Firm. Legal is responsible
for managing the Firm’s exposure to legal risk by:
•
managing actual and potential litigation and
enforcement matters, including internal reviews and
investigations related to such matters
•
advising on products and services, including
contract negotiation and documentation
•
advising on offering and marketing documents and
new business initiatives
•
managing dispute resolution
•
interpreting existing laws, rules and regulations, and
advising on changes to them
•
advising on advocacy in connection with
contemplated and proposed laws, rules and
regulations, and
•
providing legal advice to the LOBs, Corporate and
the Board.
Legal selects, engages and manages outside counsel
for the Firm on all matters in which outside counsel is
engaged. In addition, Legal advises the Firm’s Conflicts
Office which reviews the Firm’s wholesale transactions
that may have the potential to create conflicts of
interest for the Firm.
Governance and oversight
The Firm’s General Counsel reports to the CEO and is a
member of the Operating Committee, the Firmwide
Risk Committee and the Firmwide Control Committee.
The Firm’s General Counsel and other members of
Legal report on significant legal matters to the Firm’s
Board of Directors and to the Audit Committee.
Legal serves on and advises various committees and
advises the Firm’s LOBs and Corporate on potential
reputation risk issues.
Management’s discussion and analysis
152
JPMorgan Chase & Co./2025 Form 10-K
ESTIMATIONS AND MODEL RISK MANAGEMENT
Estimations and Model risk, a subcategory of
operational risk, is the potential for adverse
consequences from decisions based on incorrect or
misused estimation outputs.
The Firm uses models and other analytical and
judgment-based estimations, including those based
upon machine learning or artificial intelligence
techniques,
across various businesses and functions.
The estimation methods are of varying levels of
sophistication and are used for many purposes, such
as the valuation of positions and measurement of risk,
assessing regulatory capital requirements, conducting
stress testing, evaluating the allowance for credit
losses and making business decisions. A dedicated
independent function, Model Risk Governance and
Review (“MRGR”), defines and governs the Firm’s
policies relating to the management of model risk and
risks associated with certain analytical and judgment-
based estimations, such as those used in risk
management, budget forecasting and capital planning
and analysis.
Model risks are owned by the users of the models
within the LOBs and Corporate based on the specific
purposes of such models. Users and developers of
models are responsible for developing, implementing
and testing their models, as well as referring models to
MRGR for review and approval. Once models have
been approved, model users and developers are
responsible for maintaining a robust operating
environment, and must monitor and evaluate the
performance of the models on an ongoing basis.
Model users and developers may seek to enhance
models in response to changes in the relevant
portfolios and in product and market developments, as
well as to capture improvements in available modeling
techniques and systems capabilities.
Models are tiered based on an internal standard
according to their complexity, the exposure associated
with the model and the Firm’s reliance on the model.
This tiering is subject to the approval of MRGR. In its
review of a model, MRGR considers whether the model
is suitable for the specific purposes for which it will be
used. When reviewing a model, MRGR analyzes and
challenges the model methodology and the
reasonableness of model assumptions, and may
perform or require additional testing, including back-
testing of model outcomes. Model reviews are
approved by the appropriate level of management
within MRGR based on the relevant model tier.
Under the Firm’s Estimations and Model Risk
Management Policy, MRGR reviews and approves new
models, as well as material changes to existing
models, prior to their use. In certain circumstances,
exceptions may be granted to the Firm’s policy to
allow a model to be used prior to review or approval.
MRGR may also require the user to take appropriate
actions to mitigate the model risk if it is to be used in
the interim. These actions will depend on the model
and may include, for example, limitation of trading
activity.
While models are inherently imprecise, the degree of
imprecision or uncertainty can be heightened by the
market or economic environment. This is particularly
true when the current and forecasted environments
are significantly different from the historical
environments upon which the models were developed.
This increased uncertainty may necessitate a greater
degree of judgment and analytics to inform any
adjustments that the Firm may make to model outputs
than would otherwise be the case. In addition, the Firm
may experience increased uncertainty in its estimates
if assets acquired differ from those used to develop
the models.
Refer to Critical Accounting Estimates Used by the
Firm on pages 154–157 and Note 2 for a summary of
model-based valuations and other valuation
techniques.
JPMorgan Chase & Co./2025 Form 10-K
153
CRITICAL ACCOUNTING ESTIMATES USED BY THE FIRM
JPMorganChase’s accounting policies and use of
estimates are integral to understanding its reported
results. The Firm’s most complex accounting
estimates require management’s judgment to
ascertain the appropriate carrying value of assets and
liabilities. The Firm has established policies and
control procedures intended to ensure that estimation
methods, including any judgments made as part of
such methods, are well-controlled, independently
reviewed and applied consistently from period to
period. The methods used and judgments made
reflect, among other factors, the nature of the assets or
liabilities and the related business and risk
management strategies, which may vary across the
Firm’s businesses and portfolios. In addition, the
policies and procedures are intended to ensure that
the process for changing methodologies occurs in an
appropriate manner. The Firm believes its estimates
for determining the carrying value of its assets and
liabilities are appropriate. The following is a brief
description of the Firm’s critical accounting estimates
involving significant judgments.
Allowance for credit losses
The Firm’s allowance for credit losses represents
management’s estimate of expected credit losses over
the remaining expected life of the Firm’s financial
assets measured at amortized cost and certain off-
balance sheet lending-related commitments. The
allowance for credit losses generally comprises:
•
The allowance for loan losses, which covers the
Firm’s retained loan portfolios (scored and risk-
rated),
•
The allowance for lending-related commitments,
and
•
The allowance for credit losses on investment
securities.
The allowance for credit losses involves significant
judgment on a number of matters including
development and weighting of macroeconomic
forecasts, incorporation of historical loss experience,
assessment of risk characteristics, assignment of risk
ratings, valuation of collateral, and the determination
of remaining expected life. Refer to Notes 10 and 13 for
further information on these judgments as well as the
Firm’s policies and methodologies used to determine
the Firm’s allowance for credit losses.
One of the most significant judgments involved in
estimating the Firm’s allowance for credit losses
relates to the macroeconomic forecasts used to
estimate credit losses over the eight-quarter forecast
period within the Firm’s methodology. The eight-
quarter forecast incorporates hundreds of
macroeconomic variables (“MEVs”) that are relevant
for exposures across the Firm, with modeled credit
losses being driven primarily by a subset of less than
twenty variables. The specific variables that have the
greatest effect on the modeled losses vary by portfolio
and geography.
•
Key MEVs for the consumer portfolio include
regional U.S. unemployment rates and U.S. HPI.
•
Key MEVs for the wholesale portfolio include U.S.
unemployment, U.S. real GDP growth rate, U.S.
equity prices, U.S. interest rates, U.S. corporate
credit spreads, oil prices, U.S. commercial real estate
prices and U.S. HPI.
Changes in the Firm’s assumptions and forecasts of
economic conditions could significantly affect its
estimate of expected credit losses in the portfolio at
the balance sheet date or lead to significant changes in
the estimate from one reporting period to the next.
It is difficult to estimate how potential changes in any
one factor or input might affect the overall allowance
for credit losses because management considers a
wide variety of factors and inputs in estimating the
allowance for credit losses. Changes in the factors and
inputs considered may not occur at the same rate and
may not be consistent across all geographies or
product types, and changes in factors and inputs may
be directionally inconsistent, such that improvement in
one factor or input may offset deterioration in others.
To consider the impact of a hypothetical alternate
macroeconomic forecast, the Firm compared the
modeled credit losses determined using its central
and relative adverse macroeconomic scenarios, which
are two of the five scenarios considered in estimating
the allowances for loan losses and lending-related
commitments. The central and relative adverse
scenarios each included a full suite of MEVs, but
differed in the levels, paths and peaks/troughs of
those variables over the eight-quarter forecast period.
For example, compared to the Firm’s central scenario
shown on page 129 and in Note 13, the Firm’s relative
adverse scenario assumes an elevated U.S.
unemployment rate, averaging approximately 2.0%
higher over the eight-quarter forecast, with a peak
difference of approximately 2.8% in the fourth quarter
of 2026.
This analysis is not intended to estimate expected
future changes in the allowance for credit losses, for a
number of reasons, including:
•
The allowance as of December 31, 2025, reflects
credit losses beyond those estimated under the
central scenario due to the weight placed on the
adverse scenarios.
•
The impacts of changes in many MEVs are both
interrelated and nonlinear, so the results of this
Management’s discussion and analysis
154
JPMorgan Chase & Co./2025 Form 10-K
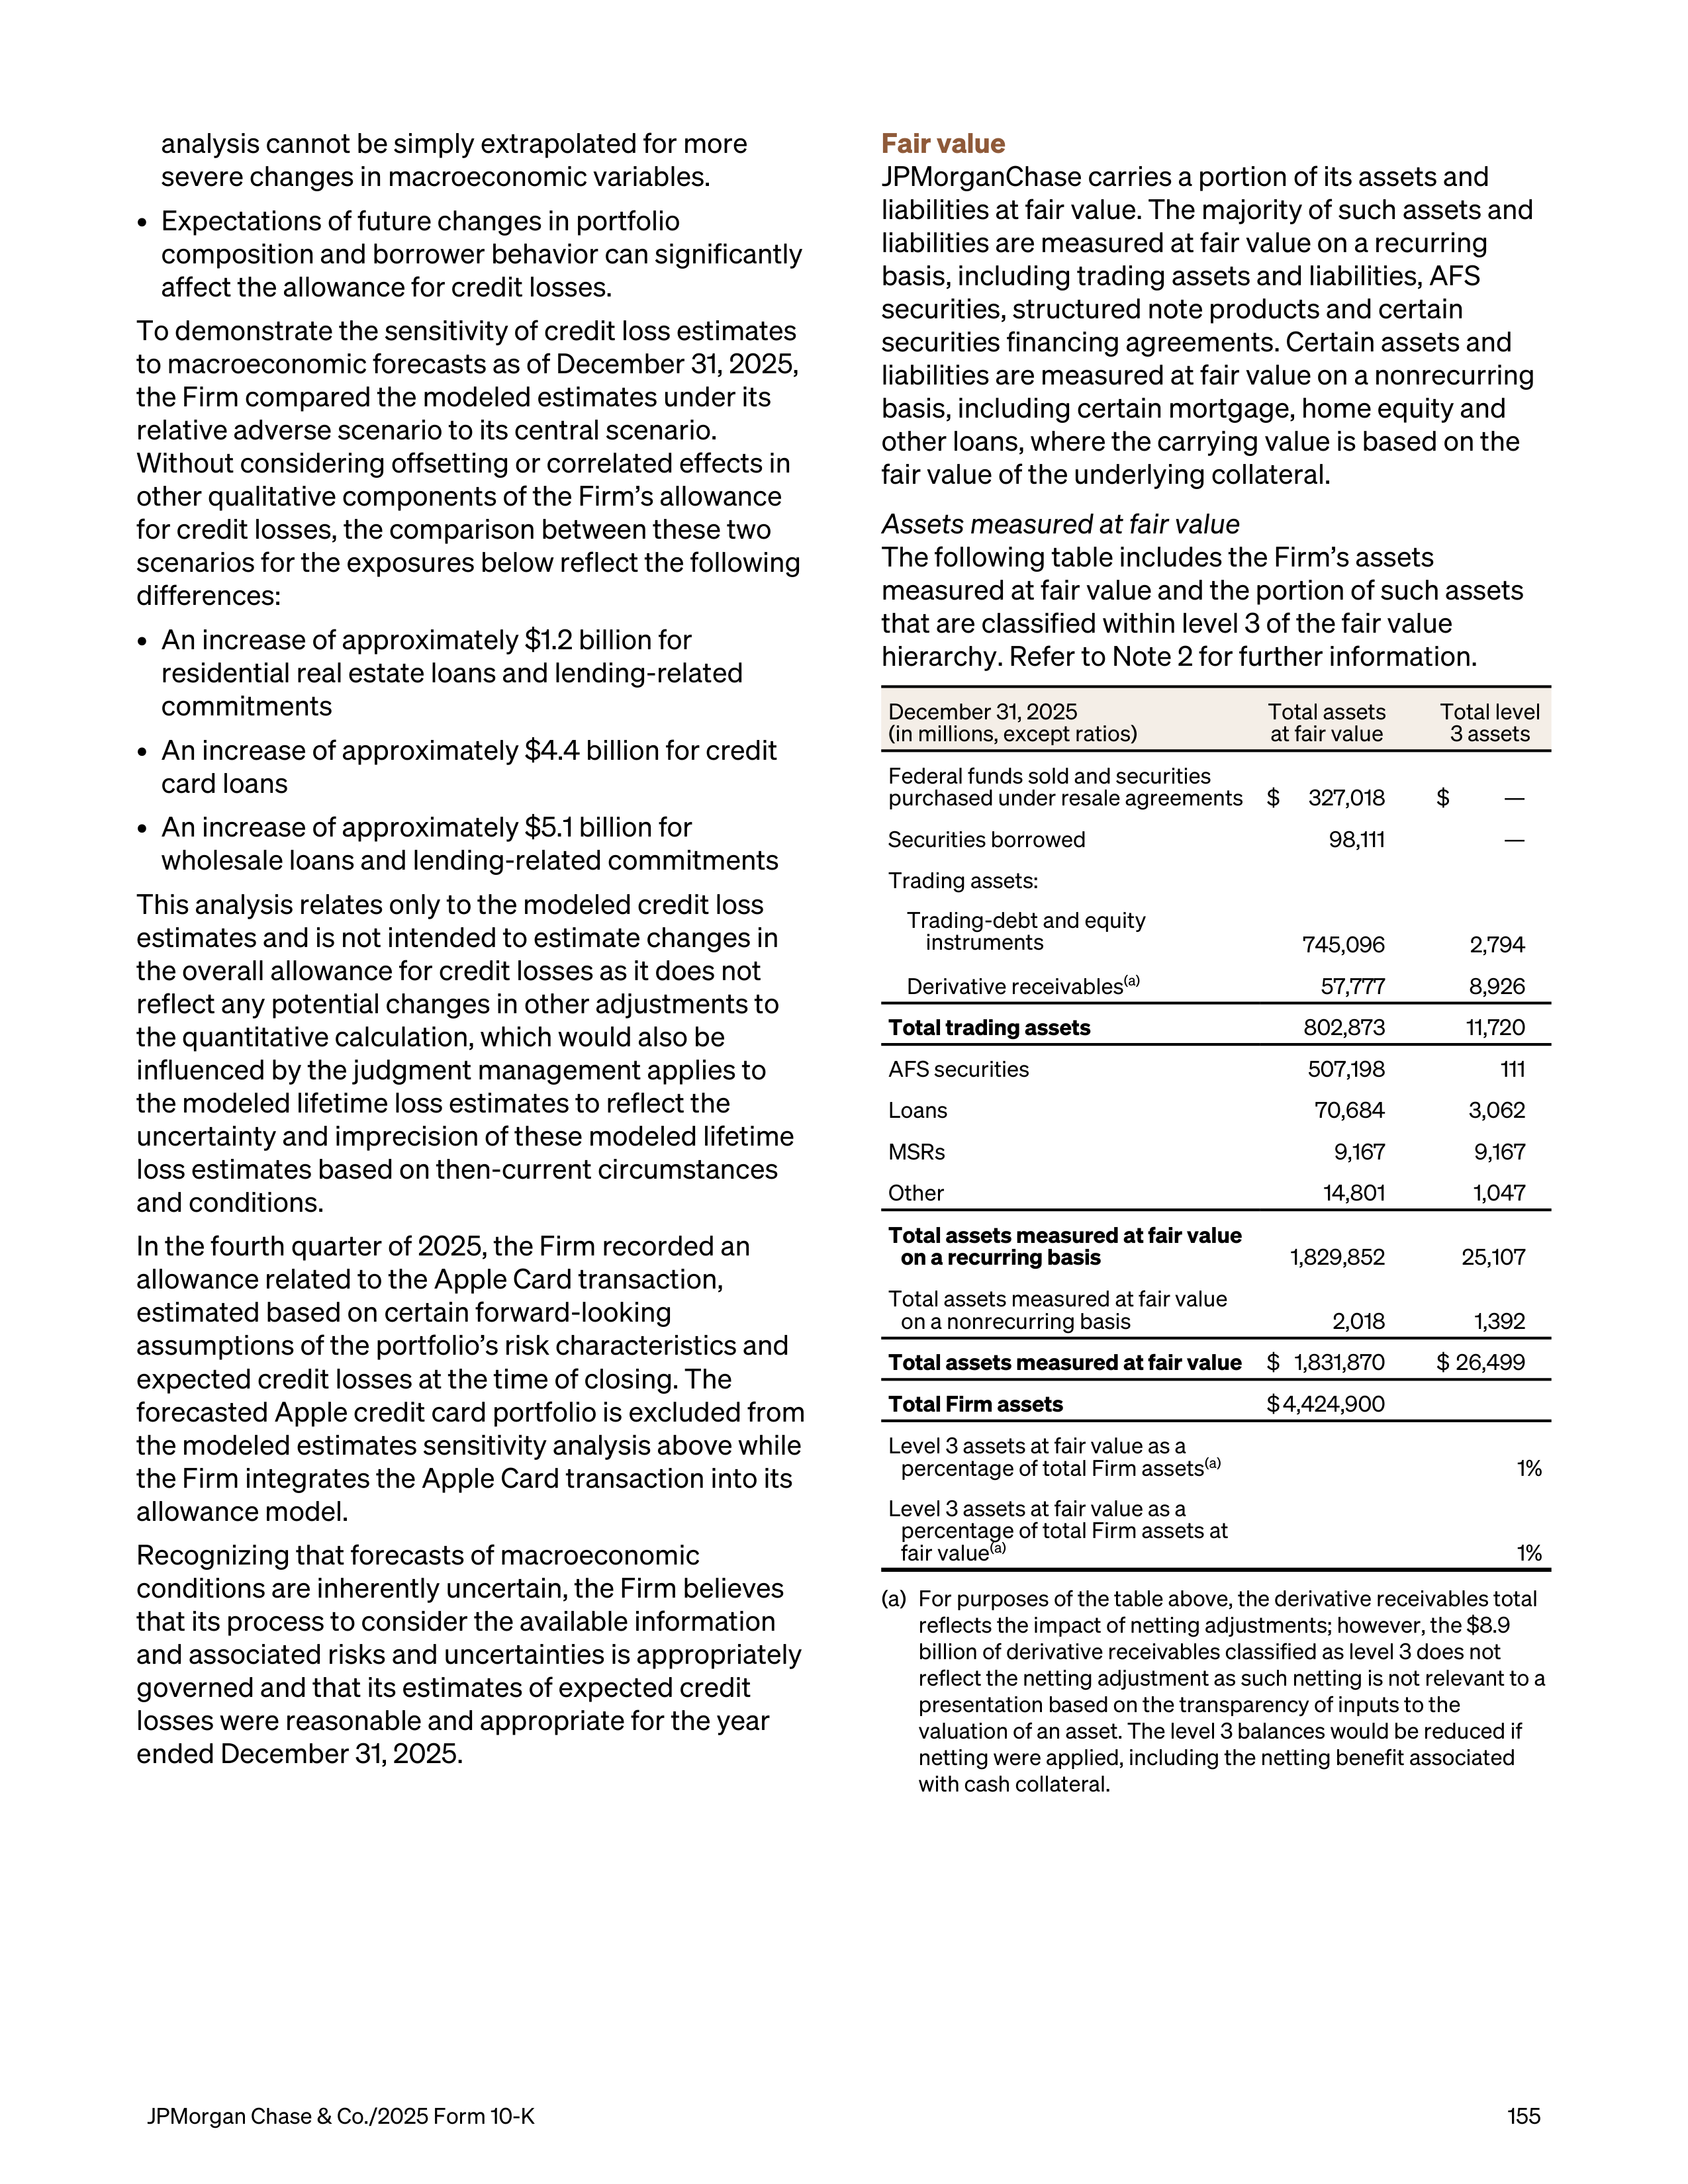
analysis cannot be simply extrapolated for more
severe changes in macroeconomic variables.
•
Expectations of future changes in portfolio
composition and borrower behavior can significantly
affect the allowance for credit losses.
To demonstrate the sensitivity of credit loss estimates
to macroeconomic forecasts as of December 31, 2025,
the Firm compared the modeled estimates under its
relative adverse scenario to its central scenario.
Without considering offsetting or correlated effects in
other qualitative components of the Firm’s allowance
for credit losses, the comparison between these two
scenarios for the exposures below reflect the following
differences:
•
An increase of approximately $1.2 billion for
residential real estate loans and lending-related
commitments
•
An increase of approximately $4.4 billion for credit
card loans
•
An increase of approximately $5.1 billion for
wholesale loans and lending-related commitments
This analysis relates only to the modeled credit loss
estimates and is not intended to estimate changes in
the overall allowance for credit losses as it does not
reflect any potential changes in other adjustments to
the quantitative calculation, which would also be
influenced by the judgment management applies to
the modeled lifetime loss estimates to reflect the
uncertainty and imprecision of these modeled lifetime
loss estimates based on then-current circumstances
and conditions.
In the fourth quarter of 2025, the Firm recorded an
allowance related to the Apple Card transaction,
estimated based on certain forward-looking
assumptions of the portfolio’s risk characteristics and
expected credit losses at the time of closing. The
forecasted Apple credit card portfolio is excluded from
the modeled estimates sensitivity analysis above while
the Firm integrates the Apple Card transaction into its
allowance model.
Recognizing that forecasts of macroeconomic
conditions are inherently uncertain, the Firm believes
that its process to consider the available information
and associated risks and uncertainties is appropriately
governed and that its estimates of expected credit
losses were reasonable and appropriate for the year
ended December 31, 2025.
Fair value
JPMorganChase carries a portion of its assets and
liabilities at fair value. The majority of such assets and
liabilities are measured at fair value on a recurring
basis, including trading assets and liabilities, AFS
securities, structured note products and certain
securities financing agreements. Certain assets and
liabilities are measured at fair value on a nonrecurring
basis, including certain mortgage, home equity and
other loans, where the carrying value is based on the
fair value of the underlying collateral.
Assets measured at fair value
The following table includes the Firm’s assets
measured at fair value and the portion of such assets
that are classified within level 3 of the fair value
hierarchy. Refer to Note 2 for further information.
December 31, 2025
(in millions, except ratios)
Total assets
at fair value
Total level
3 assets
Federal funds sold and securities
purchased under resale agreements
$
327,018
$
—
Securities borrowed
98,111
—
Trading assets:
Trading-debt and equity
instruments
745,096
2,794
Derivative receivables
(a)
57,777
8,926
Total trading assets
802,873
11,720
AFS securities
507,198
111
Loans
70,684
3,062
MSRs
9,167
9,167
Other
14,801
1,047
Total assets measured
at fair value
on a recurring basis
1,829,852
25,107
Total assets measured at fair value
on a nonrecurring basis
2,018
1,392
Total assets measured
at fair value
$ 1,831,870
$ 26,499
Total Firm assets
$ 4,424,900
Level 3 assets at fair value as a
percentage of total Firm assets
(a)
1%
Level 3 assets at fair value as a
percentage of total Firm assets at
fair value
(a)
1%
(a)
For purposes of the table above, the derivative receivables total
reflects the impact of netting adjustments; however, the $8.9
billion of derivative receivables classified as level 3 does not
reflect the netting adjustment as such netting is not relevant to a
presentation based on the transparency of inputs to the
valuation of an asset. The level 3 balances would be reduced if
netting were applied, including the netting benefit associated
with cash collateral.
JPMorgan Chase & Co./2025 Form 10-K
155
Valuation
Details of the Firm’s processes for determining fair
value are set out in Note 2. Estimating fair value
requires the application of judgment. The type and level
of judgment required is largely dependent on the
amount of observable market information available to
the Firm. For instruments valued using internally
developed valuation models and other valuation
techniques that use significant unobservable inputs and
are therefore classified within level 3 of the fair value
hierarchy, judgments used to estimate fair value are
more significant than those required when estimating
the fair value of instruments classified within levels 1
and 2.
In arriving at an estimate of fair value for an instrument
within level 3, management must first determine the
appropriate valuation model or other valuation
technique to use. Second, the lack of observability of
certain significant inputs requires management to
assess relevant empirical data in deriving valuation
inputs including, for example, transaction details, yield
curves, interest rates, prepayment speeds, default
rates, volatilities, correlations, prices (such as
commodity, equity or debt prices), valuations of
comparable instruments, foreign exchange rates and
credit curves. Refer to Note 2 for a further discussion of
the valuation of level 3 instruments, including
unobservable inputs used.
For instruments classified in levels 2 and 3,
management judgment must be applied to assess the
appropriate level of valuation adjustments to reflect
counterparty credit quality, the Firm’s creditworthiness,
market funding rates, liquidity considerations,
unobservable parameters, and for portfolios that meet
specified criteria, the size of the net open risk position.
The judgments made are typically affected by the type
of product and its specific contractual terms, and the
level of liquidity for the product or within the market as a
whole. In periods of heightened market volatility and
uncertainty judgments are further affected by the wider
variation of reasonable valuation estimates, particularly
for positions that are less liquid. Refer to Note 2 for a
further discussion of valuation adjustments applied by
the Firm.
Imprecision in estimating unobservable market inputs
or other factors can affect the amount of gain or loss
recorded for a particular position. Furthermore, while
the Firm believes its valuation methods are appropriate
and consistent with those of other market participants,
the methods and assumptions used reflect
management judgment and may vary across the Firm’s
businesses and portfolios.
The Firm uses various methodologies and assumptions
in the determination of fair value. The use of
methodologies or assumptions different than those
used by the Firm could result in a different estimate of
fair value at the reporting date. Refer to Note 2 for a
detailed discussion of the Firm’s valuation process and
hierarchy, and its determination of fair value for
individual financial instruments.
Goodwill impairment
Under U.S. GAAP, goodwill must be allocated to
reporting units and tested for impairment at least
annually. The Firm’s process and methodology used to
conduct goodwill impairment testing is described in
Note 15.
Management applies significant judgment when testing
goodwill for impairment. The goodwill associated with
each business combination is allocated to the related
reporting units for goodwill impairment testing.
For the year ended December 31, 2025, the Firm
reviewed current economic conditions, estimated
market cost of equity, as well as actual business results
and projections of business performance. Based on
such reviews, the Firm has concluded that goodwill was
not impaired as of December 31, 2025. For each of the
reporting units, fair value exceeded carrying value by at
least 20% and there was no indication of a significant
risk of goodwill impairment based on current
projections and valuations.
The projections for the Firm’s reporting units are
consistent with management’s current business outlook
assumptions in the short term, and the Firm’s best
estimates of long-term growth and return on equity in
the longer term. Where possible, the Firm uses third-
party and peer data to benchmark its assumptions and
estimates.
Refer to Note 15 for additional information on goodwill,
including the goodwill impairment assessment as of
December 31, 2025.
Credit card rewards liability
JPMorganChase offers credit cards with various
rewards programs which allow cardholders to earn
rewards points based on their account activity and the
terms and conditions of the rewards program.
Generally, there are no limits on the points that an
eligible cardholder can earn, nor do the points expire,
and the points can be redeemed for a variety of
rewards, including cash (predominantly in the form of
account credits), gift cards and travel. The Firm
maintains a rewards liability which represents the
estimated cost of rewards points earned and expected
to be redeemed by cardholders. The liability is accrued
as the cardholder earns the benefit and is reduced when
the cardholder redeems points. This liability was $16.0
billion and $14.4 billion at December 31, 2025 and 2024,
respectively, and is recorded in accounts payable and
other liabilities on the Consolidated balance sheets. The
increase in the liability was driven by continued growth
in rewards points earned on higher spend and
promotional offers that has outpaced redemptions
throughout 2025.
The rewards liability is sensitive to redemption rate
(“RR”) and cost per point (“CPP”) assumptions. The RR
Management’s discussion and analysis
156
JPMorgan Chase & Co./2025 Form 10-K
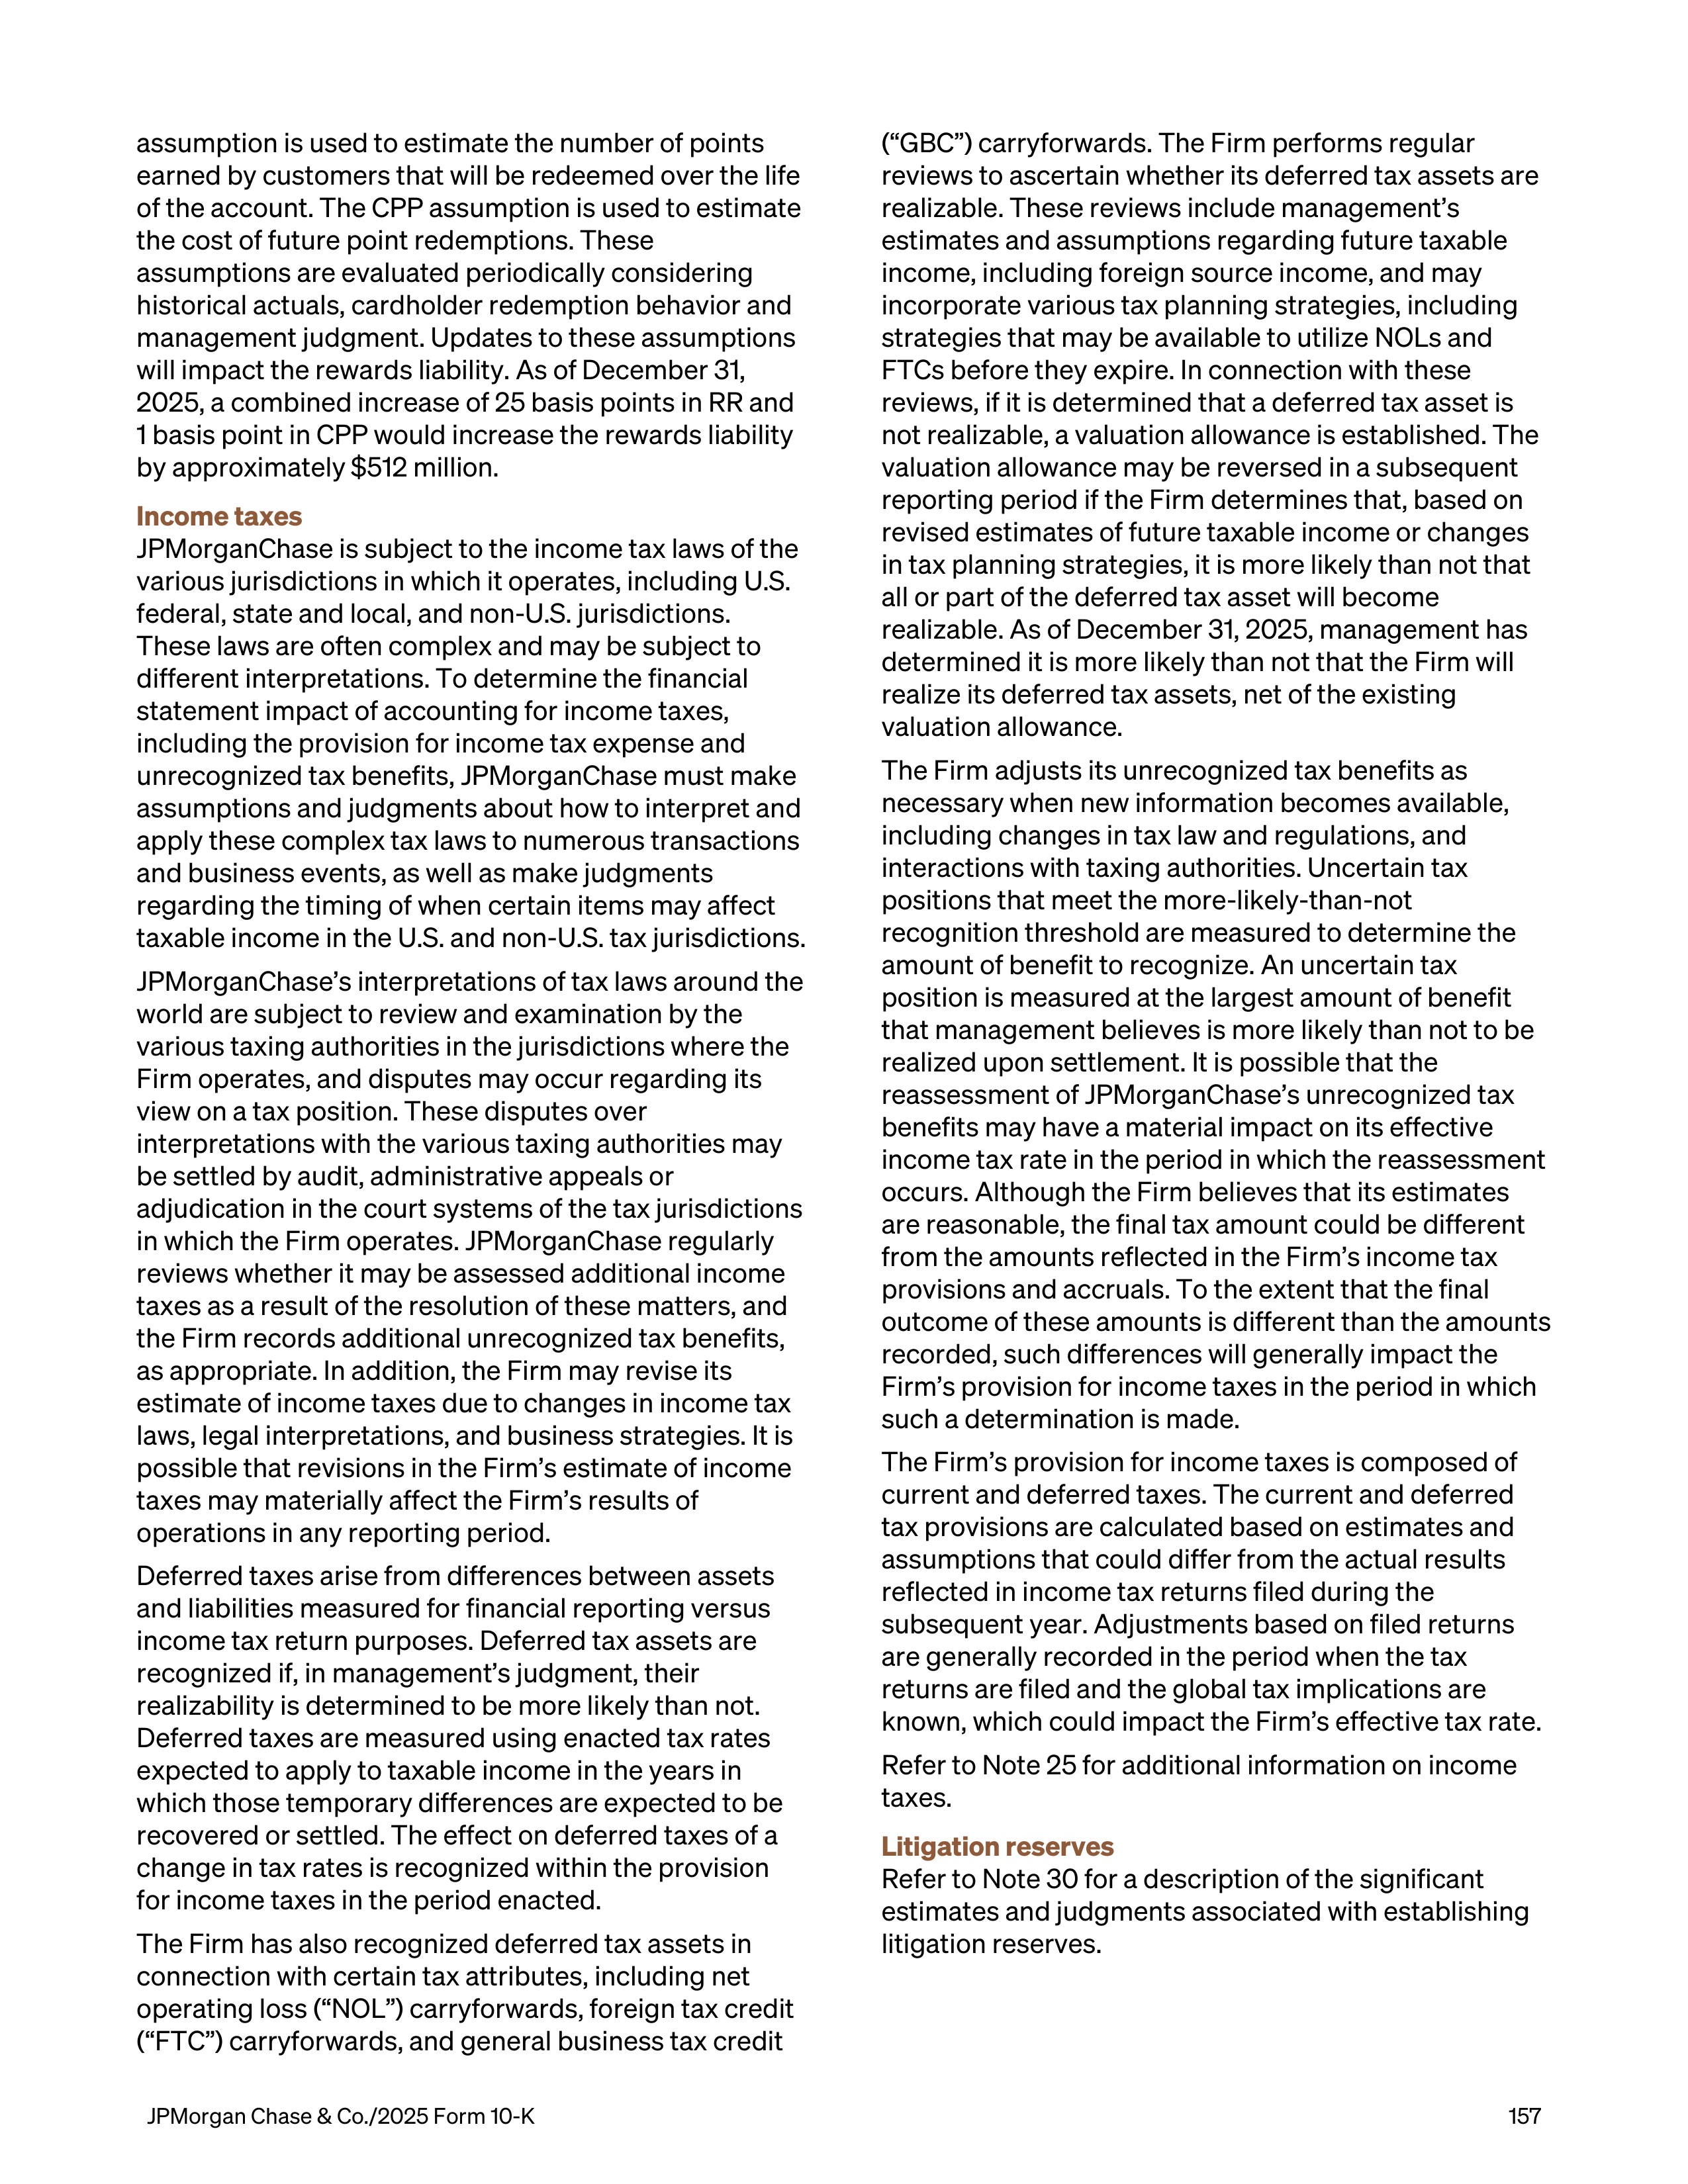
assumption is used to estimate the number of points
earned by customers that will be redeemed over the life
of the account. The CPP assumption is used to estimate
the cost of future point redemptions. These
assumptions are evaluated periodically considering
historical actuals, cardholder redemption behavior and
management judgment. Updates to these assumptions
will impact the rewards liability. As of December 31,
2025, a combined increase of 25 basis points in RR and
1 basis point in CPP would increase the rewards liability
by approximately $512 million.
Income taxes
JPMorganChase is subject to the income tax laws of the
various jurisdictions in which it operates, including U.S.
federal, state and local, and non-U.S. jurisdictions.
These laws are often complex and may be subject to
different interpretations. To determine the financial
statement impact of accounting for income taxes,
including the provision for income tax expense and
unrecognized tax benefits, JPMorganChase must make
assumptions and judgments about how to interpret and
apply these complex tax laws to numerous transactions
and business events, as well as make judgments
regarding the timing of when certain items may affect
taxable income in the U.S. and non-U.S. tax jurisdictions.
JPMorganChase’s interpretations of tax laws around the
world are subject to review and examination by the
various taxing authorities in the jurisdictions where the
Firm operates, and disputes may occur regarding its
view on a tax position. These disputes over
interpretations with the various taxing authorities may
be settled by audit, administrative appeals or
adjudication in the court systems of the tax jurisdictions
in which the Firm operates. JPMorganChase regularly
reviews whether it may be assessed additional income
taxes as a result of the resolution of these matters, and
the Firm records additional unrecognized tax benefits,
as appropriate. In addition, the Firm may revise its
estimate of income taxes due to changes in income tax
laws, legal interpretations, and business strategies. It is
possible that revisions in the Firm’s estimate of income
taxes may materially affect the Firm’s results of
operations in any reporting period.
Deferred taxes arise from differences between assets
and liabilities measured for financial reporting versus
income tax return purposes. Deferred tax assets are
recognized if, in management’s judgment, their
realizability is determined to be more likely than not.
Deferred taxes are measured using enacted tax rates
expected to apply to taxable income in the years in
which those temporary differences are expected to be
recovered or settled. The effect on deferred taxes of a
change in tax rates is recognized within the provision
for income taxes in the period enacted.
The Firm has also recognized deferred tax assets in
connection with certain tax attributes, including net
operating loss (“NOL”) carryforwards, foreign tax credit
(“FTC”) carryforwards, and general business tax credit
(“GBC”) carryforwards. The Firm performs regular
reviews to ascertain whether its deferred tax assets are
realizable. These reviews include management’s
estimates and assumptions regarding future taxable
income, including foreign source income, and may
incorporate various tax planning strategies, including
strategies that may be available to utilize NOLs and
FTCs before they expire. In connection with these
reviews, if it is determined that a deferred tax asset is
not realizable, a valuation allowance is established. The
valuation allowance may be reversed in a subsequent
reporting period if the Firm determines that, based on
revised estimates of future taxable income or changes
in tax planning strategies, it is more likely than not that
all or part of the deferred tax asset will become
realizable. As of December 31, 2025, management has
determined it is more likely than not that the Firm will
realize its deferred tax assets, net of the existing
valuation allowance.
The Firm adjusts its unrecognized tax benefits as
necessary when new information becomes available,
including changes in tax law and regulations, and
interactions with taxing authorities. Uncertain tax
positions that meet the more-likely-than-not
recognition threshold are measured to determine the
amount of benefit to recognize. An uncertain tax
position is measured at the largest amount of benefit
that management believes is more likely than not to be
realized upon settlement. It is possible that the
reassessment of JPMorganChase’s unrecognized tax
benefits may have a material impact on its effective
income tax rate in the period in which the reassessment
occurs. Although the Firm believes that its estimates
are reasonable, the final tax amount could be different
from the amounts reflected in the Firm’s income tax
provisions and accruals. To the extent that the final
outcome of these amounts is different than the amounts
recorded, such differences will generally impact the
Firm’s provision for income taxes in the period in which
such a determination is made.
The Firm’s provision for income taxes is composed of
current and deferred taxes. The current and deferred
tax provisions are calculated based on estimates and
assumptions that could differ from the actual results
reflected in income tax returns filed during the
subsequent year. Adjustments based on filed returns
are generally recorded in the period when the tax
returns are filed and the global tax implications are
known, which could impact the Firm’s effective tax rate.
Refer to Note 25 for additional information on income
taxes.
Litigation reserves
Refer to Note 30 for a description of the significant
estimates and judgments associated with establishing
litigation reserves.
JPMorgan Chase & Co./2025 Form 10-K
157
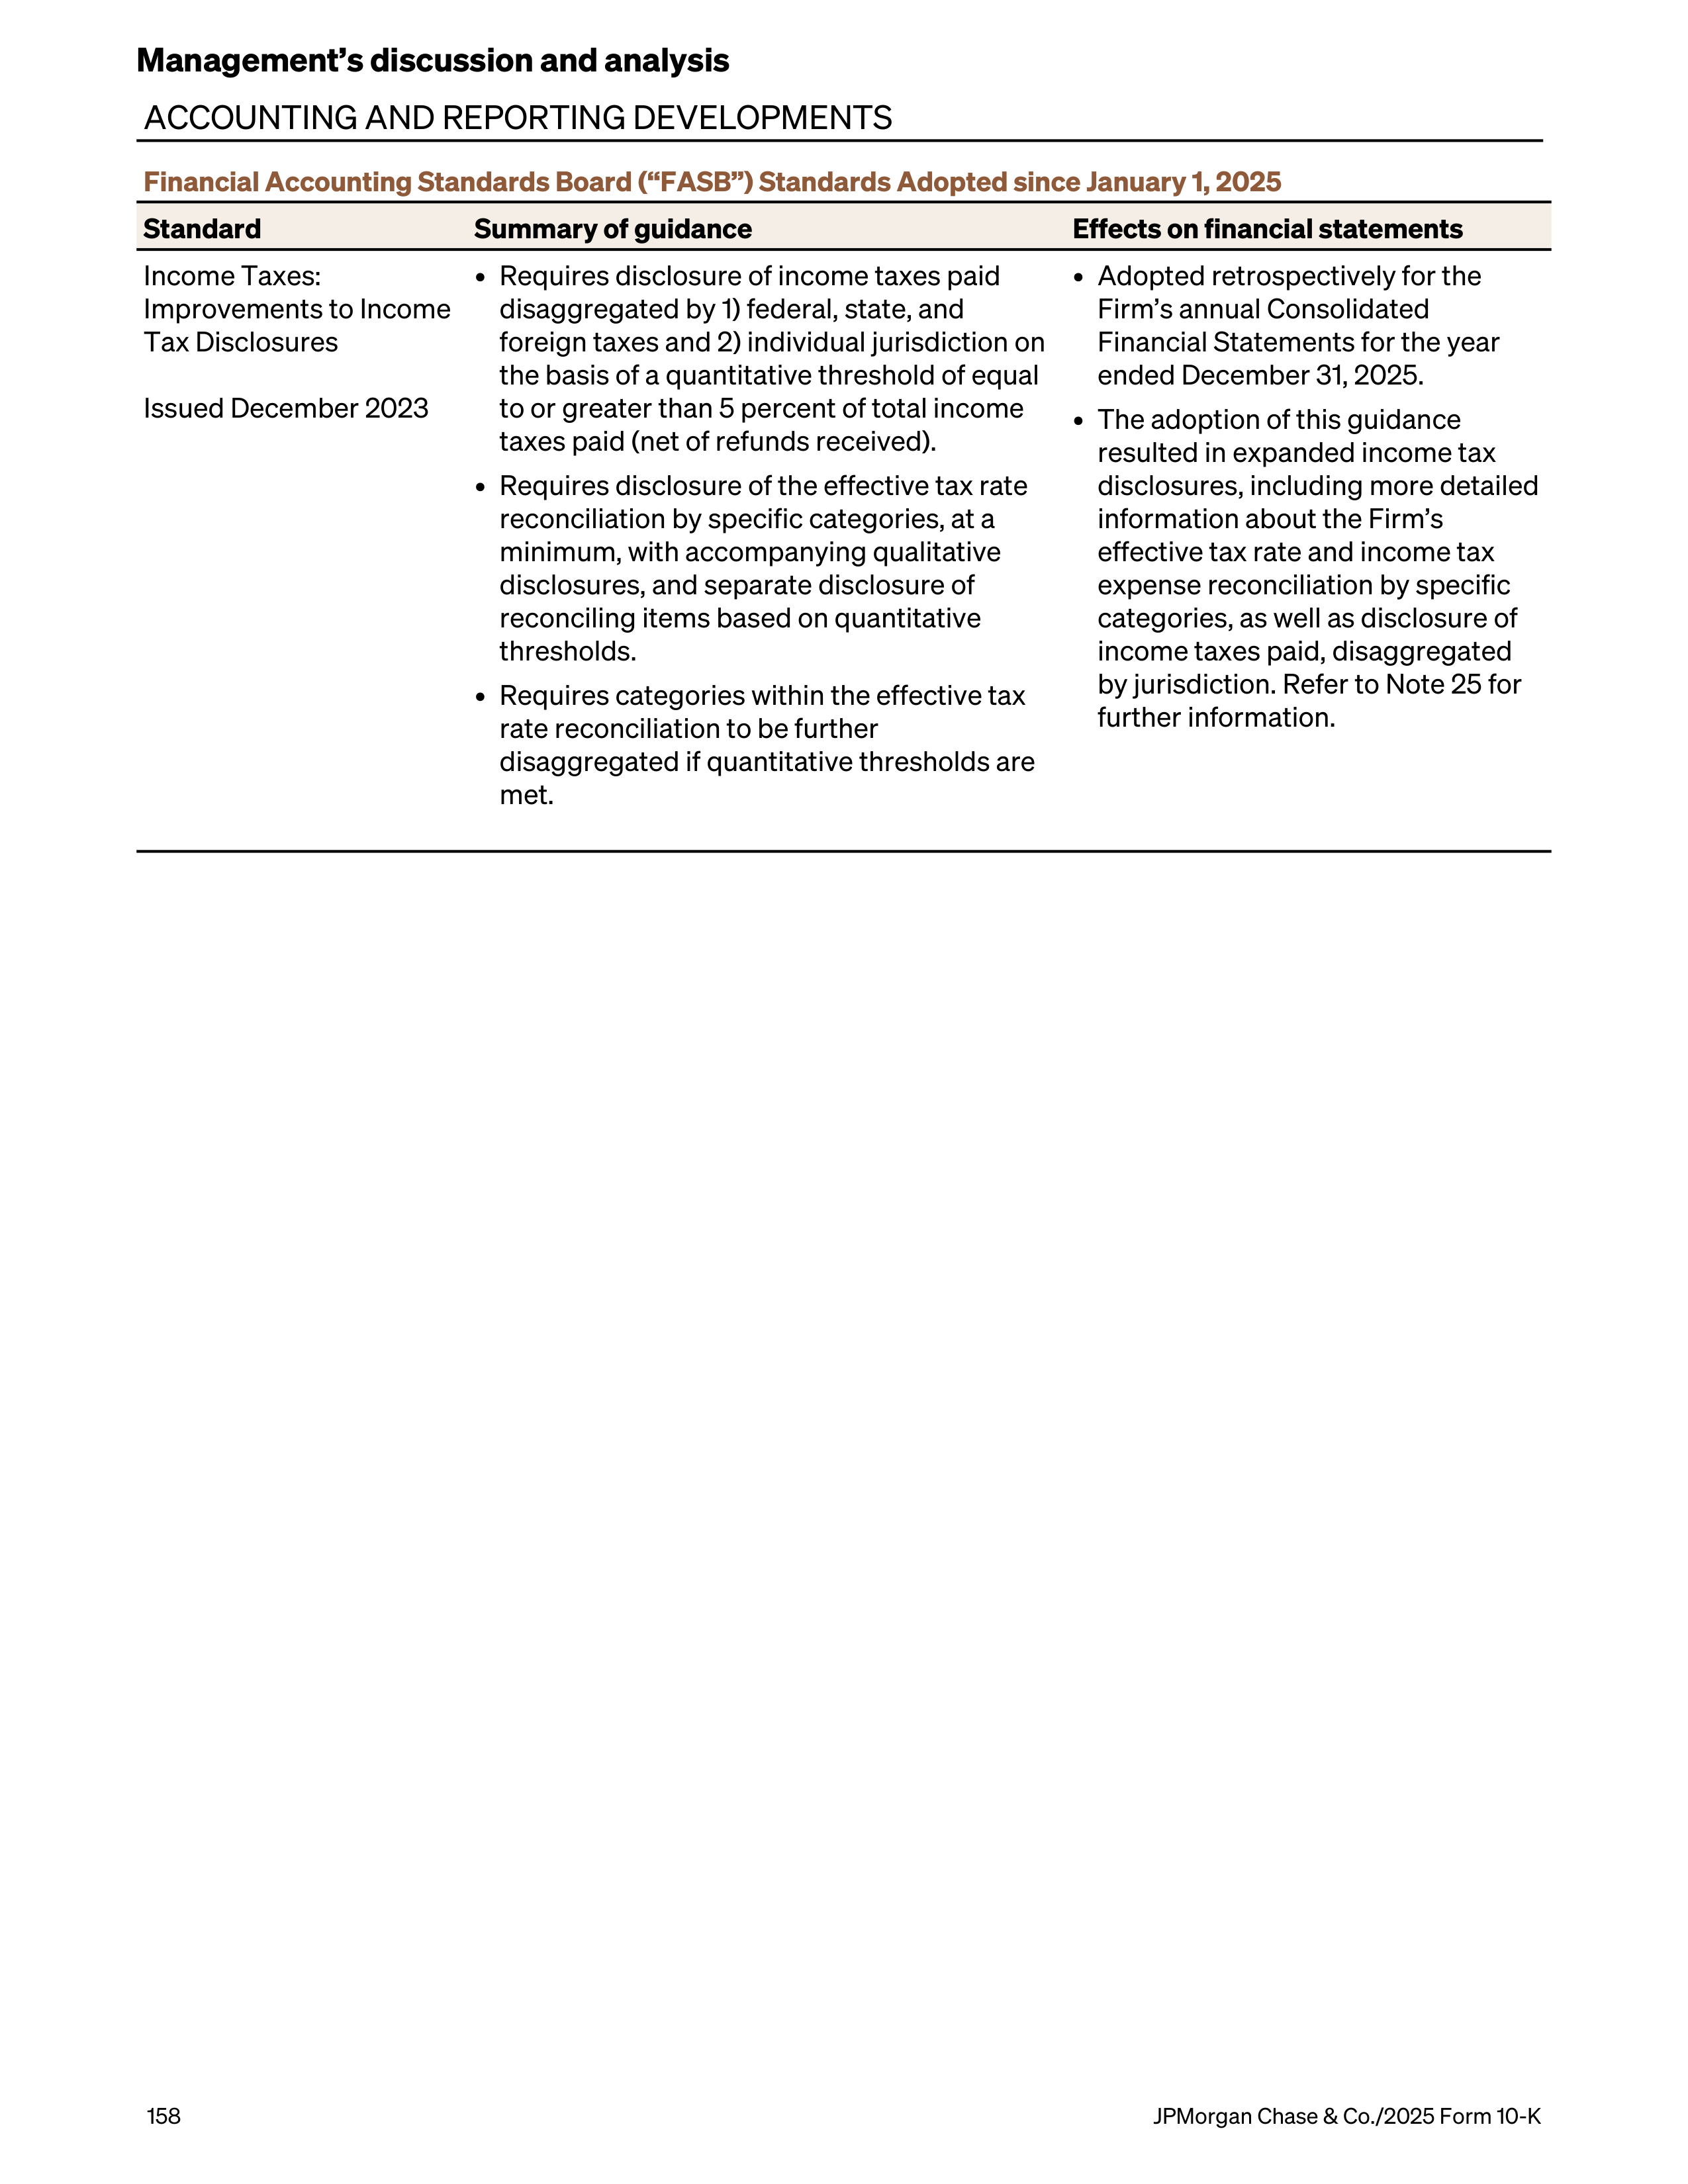
ACCOUNTING AND REPORTING DEVELOPMENTS
Financial Accounting Standards Board (“FASB”) Standards Adopted since January 1, 2025
Standard
Summary of guidance
Effects on financial statements
Income Taxes:
Improvements to Income
Tax Disclosures
Issued December 2023
•
Requires disclosure of income taxes paid
disaggregated by 1) federal, state, and
foreign taxes and 2) individual jurisdiction on
the basis of a quantitative threshold of equal
to or greater than 5 percent of total income
taxes paid (net of refunds received).
•
Requires disclosure of the effective tax rate
reconciliation by specific categories, at a
minimum, with accompanying qualitative
disclosures, and separate disclosure of
reconciling items based on quantitative
thresholds.
•
Requires categories within the effective tax
rate reconciliation to be further
disaggregated if quantitative thresholds are
met.
•
Adopted retrospectively for the
Firm’s annual Consolidated
Financial Statements for the year
ended December 31, 2025.
•
The adoption of this guidance
resulted in expanded income tax
disclosures, including more detailed
information about the Firm’s
effective tax rate and income tax
expense reconciliation by specific
categories, as well as disclosure of
income taxes paid, disaggregated
by jurisdiction. Refer to Note 25 for
further information.
Management’s discussion and analysis
158
JPMorgan Chase & Co./2025 Form 10-K
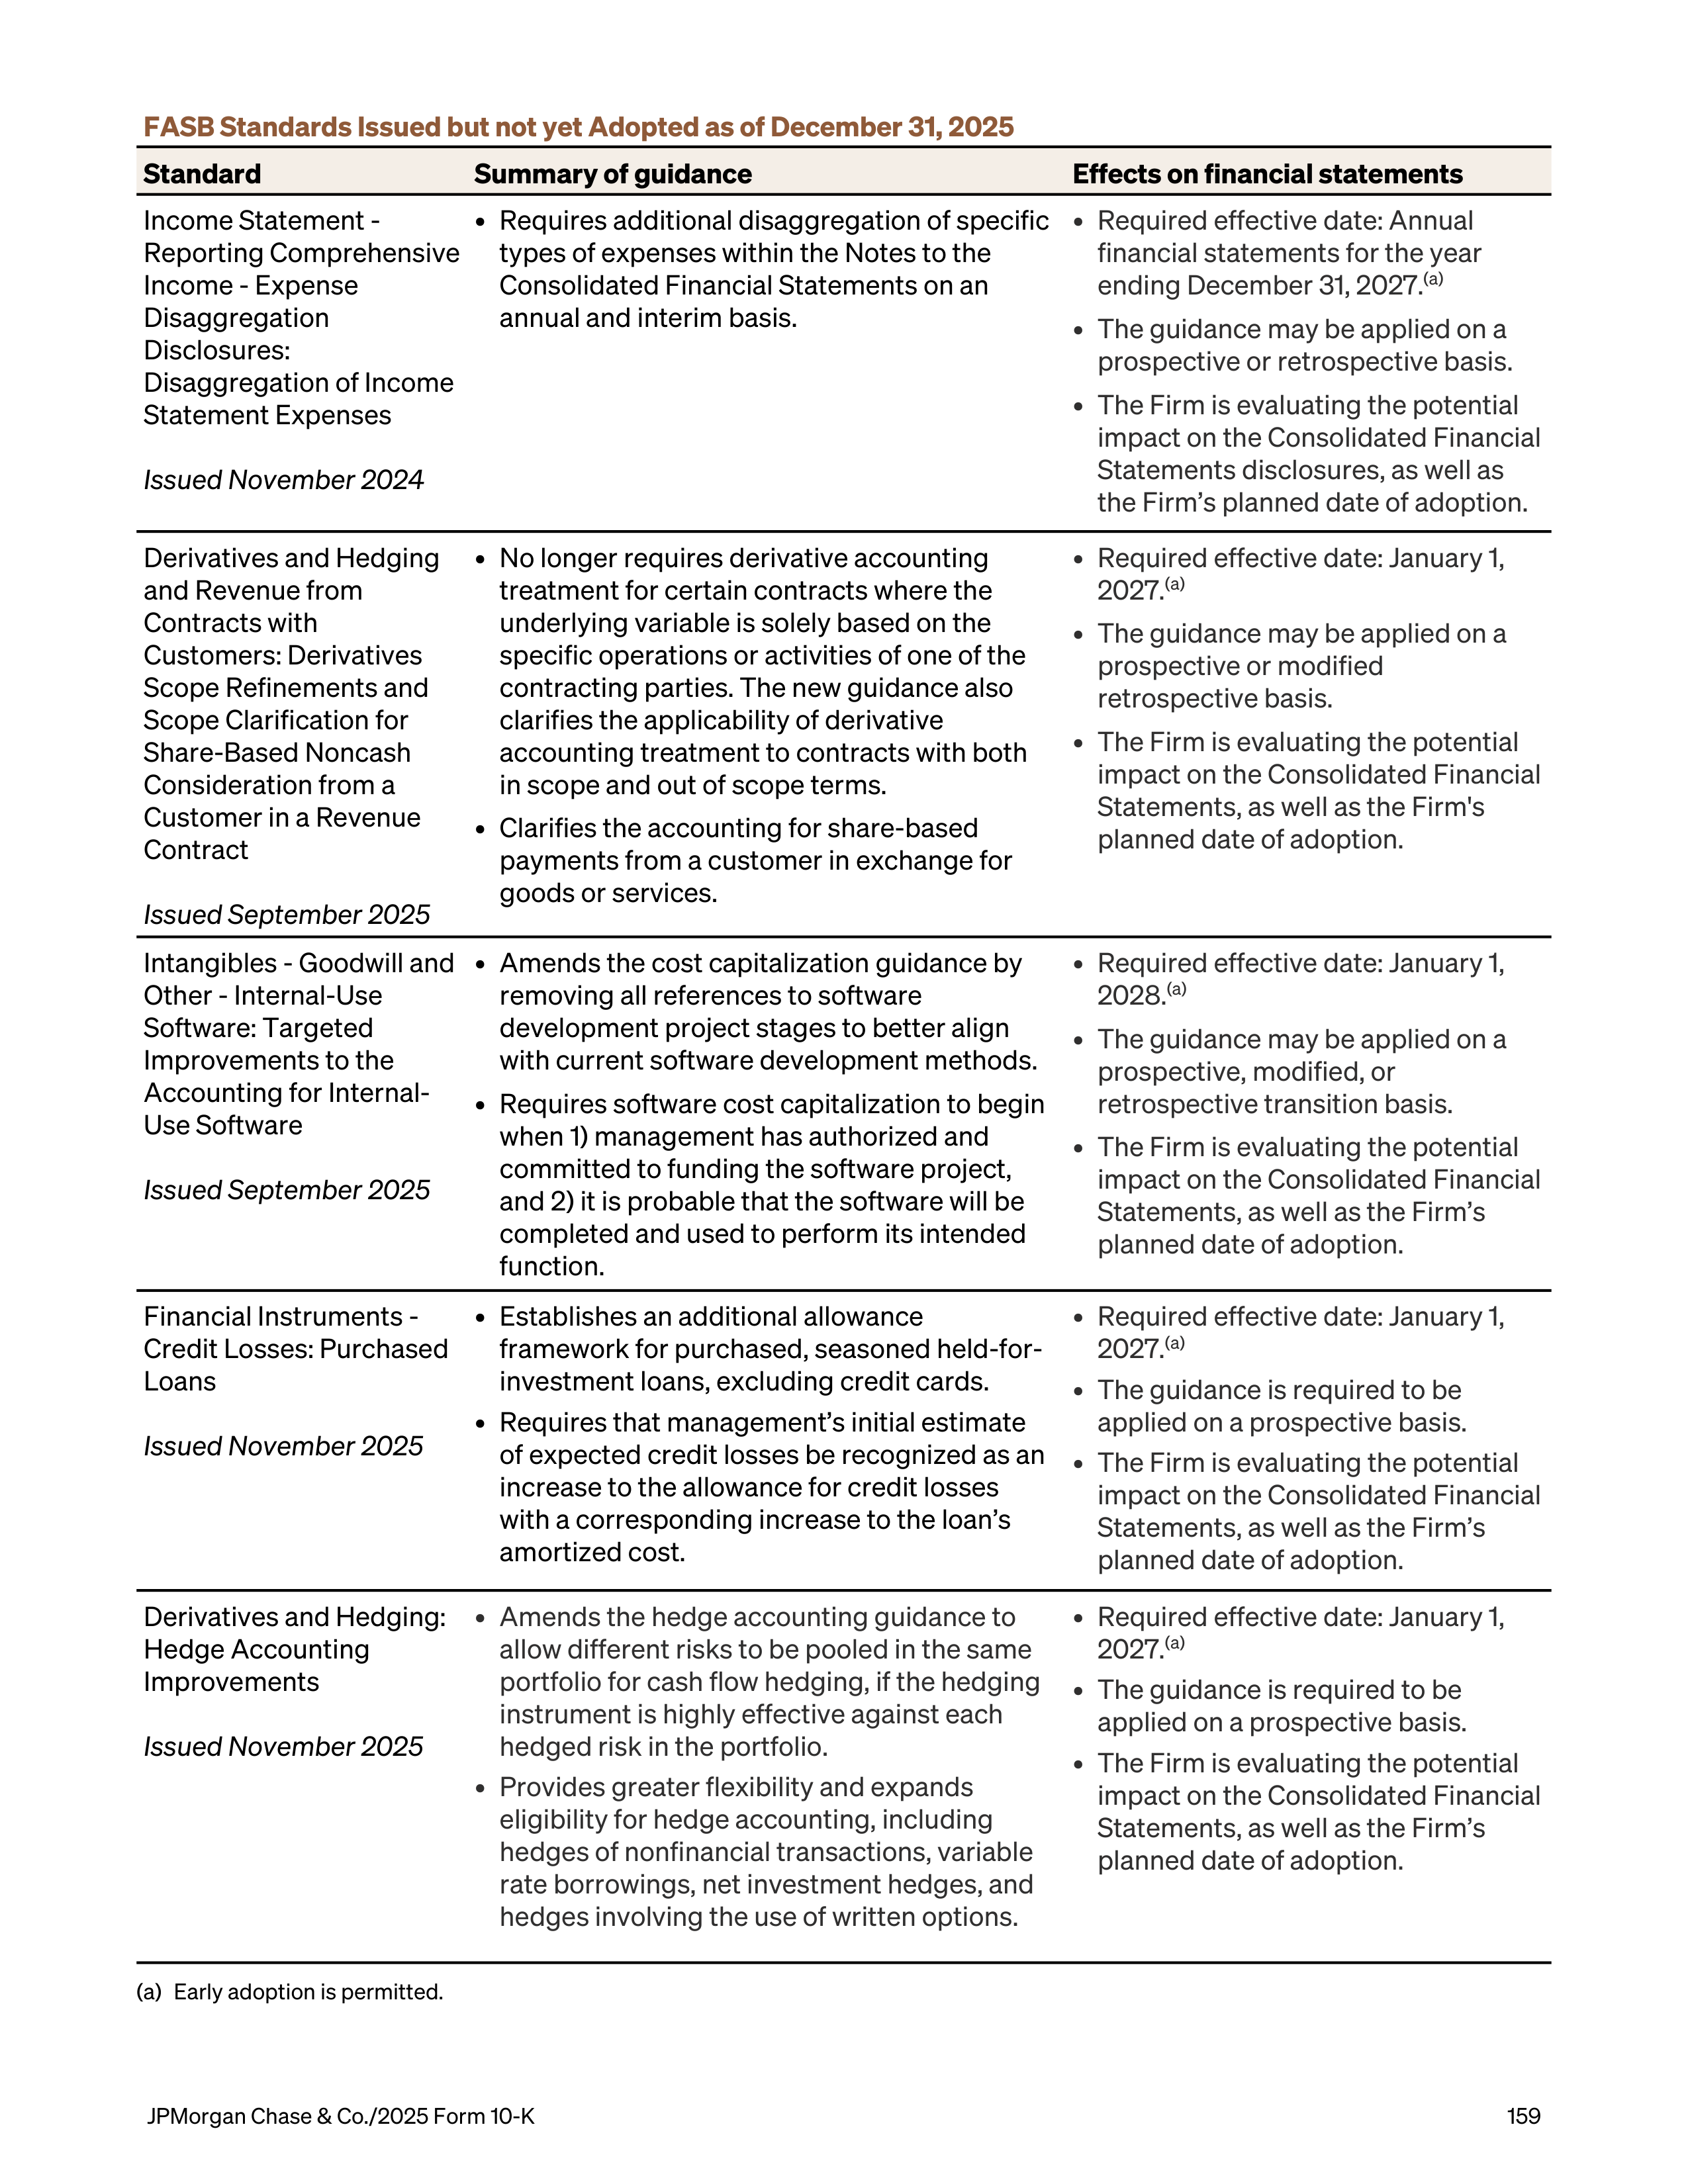
FASB Standards Issued but not yet Adopted as of December 31, 2025
Standard
Summary of guidance
Effects on financial statements
Income Statement -
Reporting Comprehensive
Income - Expense
Disaggregation
Disclosures:
Disaggregation of Income
Statement Expenses
Issued November 2024
•
Requires additional disaggregation of specific
types of expenses within the Notes to the
Consolidated Financial Statements on an
annual and interim basis.
•
Required effective date: Annual
financial statements for the year
ending December 31, 2027.
(a)
•
The guidance may be applied on a
prospective or retrospective basis.
•
The Firm is evaluating the potential
impact on the Consolidated Financial
Statements disclosures, as well as
the Firm’s planned date of adoption.
Derivatives and Hedging
and Revenue from
Contracts with
Customers: Derivatives
Scope Refinements and
Scope Clarification for
Share-Based Noncash
Consideration from a
Customer in a Revenue
Contract
Issued September 2025
•
No longer requires derivative accounting
treatment for certain contracts where the
underlying variable is solely based on the
specific operations or activities of one of the
contracting parties. The new guidance also
clarifies the applicability of derivative
accounting treatment to contracts with both
in scope and out of scope terms.
•
Clarifies the accounting for share-based
payments from a customer in exchange for
goods or services.
•
Required effective date: January 1,
2027.
(a)
•
The guidance may be applied on a
prospective or modified
retrospective basis.
•
The Firm is evaluating the potential
impact on the Consolidated Financial
Statements, as well as the Firm's
planned date of adoption.
Intangibles - Goodwill and
Other - Internal-Use
Software: Targeted
Improvements to the
Accounting for Internal-
Use Software
Issued September 2025
•
Amends the cost capitalization guidance by
removing all references to software
development project stages to better align
with current software development methods.
•
Requires software cost capitalization to begin
when 1) management has authorized and
committed to funding the software project,
and 2) it is probable that the software will be
completed and used to perform its intended
function.
•
Required effective date: January 1,
2028.
(a)
•
The guidance may be applied on a
prospective, modified, or
retrospective transition basis.
•
The Firm is evaluating the potential
impact on the Consolidated Financial
Statements, as well as the Firm’s
planned date of adoption.
Financial Instruments -
Credit Losses: Purchased
Loans
Issued November 2025
•
Establishes an additional allowance
framework for purchased, seasoned held-for-
investment loans, excluding credit cards.
•
Requires that management’s initial estimate
of expected credit losses be recognized as an
increase to the allowance for credit losses
with a corresponding increase to the loan’s
amortized cost.
•
Required effective date: January 1,
2027.
(a)
•
The guidance is required to be
applied on a prospective basis.
•
The Firm is evaluating the potential
impact on the Consolidated Financial
Statements, as well as the Firm’s
planned date of adoption.
Derivatives and Hedging:
Hedge Accounting
Improvements
Issued November 2025
•
Amends the hedge accounting guidance to
allow different risks to be pooled in the same
portfolio for cash flow hedging, if the hedging
instrument is highly effective against each
hedged risk in the portfolio.
•
Provides greater flexibility and expands
eligibility for hedge accounting, including
hedges of nonfinancial transactions, variable
rate borrowings, net investment hedges, and
hedges involving the use of written options.
•
Required effective date: January 1,
2027.
(a)
•
The guidance is required to be
applied on a prospective basis.
•
The Firm is evaluating the potential
impact on the Consolidated Financial
Statements, as well as the Firm’s
planned date of adoption.
(a)
Early adoption is permitted.
JPMorgan Chase & Co./2025 Form 10-K
159
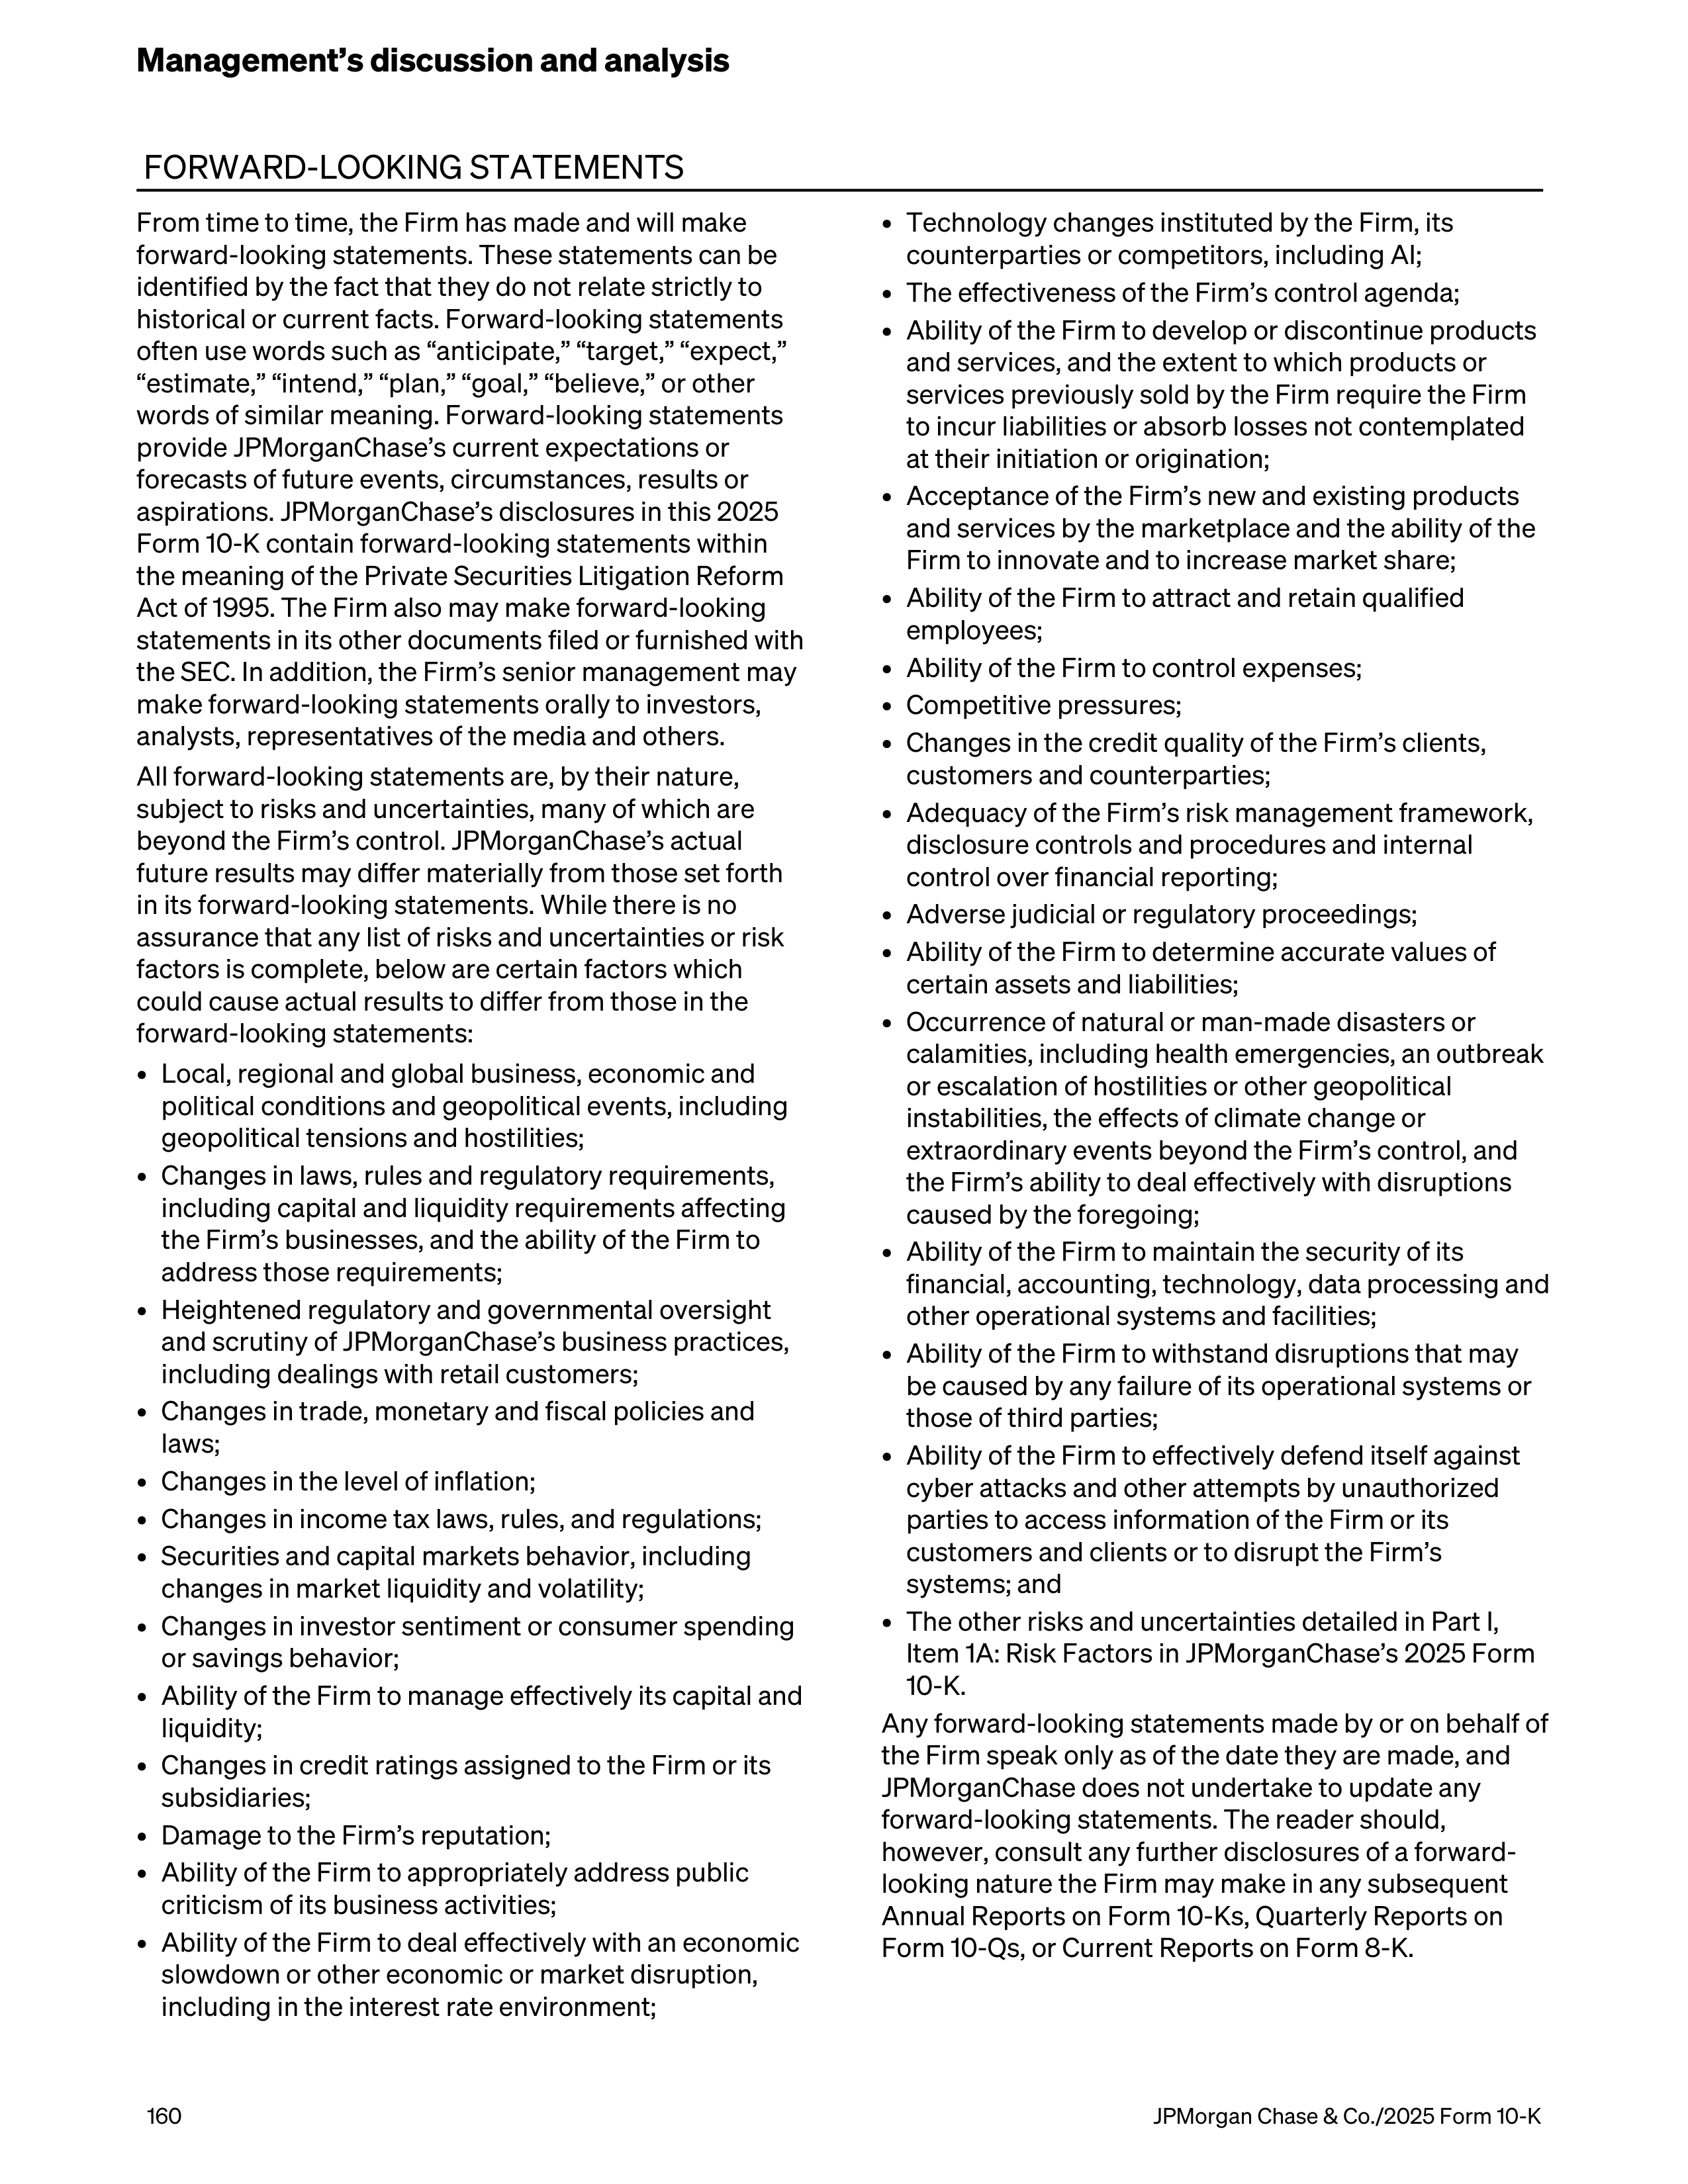
FORWARD-LOOKING STATEMENTS
From time to time, the Firm has made and will make
forward-looking statements. These statements can be
identified by the fact that they do not relate strictly to
historical or current facts. Forward-looking statements
often use words such as “anticipate,” “target,” “expect,”
“estimate,” “intend,” “plan,” “goal,” “believe,” or other
words of similar meaning. Forward-looking statements
provide JPMorganChase’s current expectations or
forecasts of future events, circumstances, results or
aspirations. JPMorganChase’s disclosures in this 2025
Form 10-K contain forward-looking statements within
the meaning of the Private Securities Litigation Reform
Act of 1995. The Firm also may make forward-looking
statements in its other documents filed or furnished with
the SEC. In addition, the Firm’s senior management may
make forward-looking statements orally to investors,
analysts, representatives of the media and others.
All forward-looking statements are, by their nature,
subject to risks and uncertainties, many of which are
beyond the Firm’s control. JPMorganChase’s actual
future results may differ materially from those set forth
in its forward-looking statements. While there is no
assurance that any list of risks and uncertainties or risk
factors is complete, below are certain factors which
could cause actual results to differ from those in the
forward-looking statements:
•
Local, regional and global business, economic and
political conditions and geopolitical events, including
geopolitical tensions and hostilities;
•
Changes in laws, rules and regulatory requirements,
including capital and liquidity requirements affecting
the Firm’s businesses, and the ability of the Firm to
address those requirements;
•
Heightened regulatory and governmental oversight
and scrutiny of JPMorganChase’s business practices,
including dealings with retail customers;
•
Changes in trade, monetary and fiscal policies and
laws;
•
Changes in the level of inflation;
•
Changes in income tax laws, rules, and regulations;
•
Securities and capital markets behavior, including
changes in market liquidity and volatility;
•
Changes in investor sentiment or consumer spending
or savings behavior;
•
Ability of the Firm to manage effectively its capital and
liquidity;
•
Changes in credit ratings assigned to the Firm or its
subsidiaries;
•
Damage to the Firm’s reputation;
•
Ability of the Firm to appropriately address public
criticism of its business activities;
•
Ability of the Firm to deal effectively with an economic
slowdown or other economic or market disruption,
including in the interest rate environment;
•
Technology changes instituted by the Firm, its
counterparties or competitors, including AI;
•
The effectiveness of the Firm’s control agenda;
•
Ability of the Firm to develop or discontinue products
and services, and the extent to which products or
services previously sold by the Firm require the Firm
to incur liabilities or absorb losses not contemplated
at their initiation or origination;
•
Acceptance of the Firm’s new and existing products
and services by the marketplace and the ability of the
Firm to innovate and to increase market share;
•
Ability of the Firm to attract and retain qualified
employees;
•
Ability of the Firm to control expenses;
•
Competitive pressures;
•
Changes in the credit quality of the Firm’s clients,
customers and counterparties;
•
Adequacy of the Firm’s risk management framework,
disclosure controls and procedures and internal
control over financial reporting;
•
Adverse judicial or regulatory proceedings;
•
Ability of the Firm to determine accurate values of
certain assets and liabilities;
•
Occurrence of natural or man-made disasters or
calamities, including health emergencies, an outbreak
or escalation of hostilities or other geopolitical
instabilities, the effects of climate change or
extraordinary events beyond the Firm’s control, and
the Firm’s ability to deal effectively with disruptions
caused by the foregoing;
•
Ability of the Firm to maintain the security of its
financial, accounting, technology, data processing and
other operational systems and facilities;
•
Ability of the Firm to withstand disruptions that may
be caused by any failure of its operational systems or
those of third parties;
•
Ability of the Firm to effectively defend itself against
cyber attacks and other attempts by unauthorized
parties to access information of the Firm or its
customers and clients or to disrupt the Firm’s
systems; and
•
The other risks and uncertainties detailed in Part I,
Item 1A: Risk Factors in JPMorganChase’s 2025 Form
10-K.
Any forward-looking statements made by or on behalf of
the Firm speak only as of the date they are made, and
JPMorganChase does not undertake to update any
forward-looking statements. The reader should,
however, consult any further disclosures of a forward-
looking nature the Firm may make in any subsequent
Annual Reports on Form 10-Ks, Quarterly Reports on
Form 10-Qs, or Current Reports on Form 8-K.
Management’s discussion and analysis
160
JPMorgan Chase & Co./2025 Form 10-K
Management of JPMorgan Chase & Co.
(“JPMorganChase” or the “Firm”) is responsible for
establishing and maintaining adequate internal control
over financial reporting. Internal control over financial
reporting is a process designed by, or under the
supervision of, the Firm’s principal executive and
principal financial officers, or persons performing
similar functions, and effected by JPMorganChase’s
Board of Directors, management and other personnel,
to provide reasonable assurance regarding the
reliability of financial reporting and the preparation of
financial statements for external purposes in
accordance with accounting principles generally
accepted in the United States of America (“U.S. GAAP”).
JPMorganChase’s internal control over financial
reporting includes those policies and procedures that
(1) pertain to the maintenance of records, that, in
reasonable detail, accurately and fairly reflect the
transactions and dispositions of the Firm’s assets; (2)
provide reasonable assurance that transactions are
recorded as necessary to permit preparation of financial
statements in accordance with U.S. GAAP, and that
receipts and expenditures of the Firm are being made
only in accordance with authorizations of
JPMorganChase’s management and directors; and (3)
provide reasonable assurance regarding prevention or
timely detection of unauthorized acquisition, use or
disposition of the Firm’s assets that could have a
material effect on the financial statements.
Because of its inherent limitations, internal control over
financial reporting may not prevent or detect
misstatements. Also, projections of any evaluation of
effectiveness to future periods are subject to the risk
that controls may become inadequate because of
changes in conditions, or that the degree of compliance
with the policies or procedures may deteriorate.
Management has completed an assessment of the
effectiveness of the Firm’s internal control over financial
reporting as of December 31, 2025. In making the
assessment, management used the “Internal Control —
Integrated Framework” (“COSO 2013”) promulgated by
the Committee of Sponsoring Organizations of the
Treadway Commission (“COSO”).
Based upon the assessment performed, management
concluded that as of December 31, 2025,
JPMorganChase’s internal control over financial
reporting was effective based upon the COSO 2013
framework. Additionally, based upon management’s
assessment, the Firm determined that there were no
material weaknesses in its internal control over financial
reporting as of December 31, 2025.
The effectiveness of the Firm’s internal control over
financial reporting as of December 31, 2025, has been
audited by PricewaterhouseCoopers LLP, an
independent registered public accounting firm, as
stated in their report which appears herein.
James Dimon
Chairman and Chief Executive Officer
Jeremy Barnum
Executive Vice President and Chief Financial Officer
February 13, 2026
Management’s report on internal control over financial reporting
JPMorgan Chase & Co./2025 Form 10-K
161
To the Board of Directors and Shareholders of
JPMorgan Chase & Co.:
Opinions on the Financial Statements and Internal
Control over Financial Reporting
We have audited the accompanying consolidated
balance sheets of JPMorgan Chase & Co. and its
subsidiaries (the “Firm”) as of December 31, 2025 and
2024, and the related consolidated statements of
income, comprehensive income, changes in
stockholders’ equity and cash flows for each of the three
years in the period ended December 31, 2025, including
the related notes (collectively referred to as the
“consolidated financial statements”). We also have
audited the Firm’s internal control over financial
reporting as of December 31, 2025, based on criteria
established in
Internal Control - Integrated Framework
(2013) issued by the Committee of Sponsoring
Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements
referred to above present fairly, in all material respects,
the financial position of the Firm as of
December 31,
2025 and 2024, and the results of its operations and its
cash flows for each of the three years in the period
ended December 31, 2025
in conformity with
accounting principles generally accepted in the United
States of America. Also in our opinion, the Firm
maintained, in all material respects, effective internal
control over financial reporting as of December 31,
2025, based on criteria established in
Internal Control –
Integrated Framework
(2013) issued by the COSO.
Basis for Opinions
The Firm’s management is responsible for these
consolidated financial statements, for maintaining
effective internal control over financial reporting, and for
its assessment of the effectiveness of internal control
over financial reporting, included in the accompanying
Management’s report on internal control over financial
reporting. Our responsibility is to express opinions on
the Firm’s consolidated financial statements and on the
Firm’s internal control over financial reporting based on
our audits. We are a public accounting firm registered
with the Public Company Accounting Oversight Board
(United States) (PCAOB) and are required to be
independent with respect to the Firm in accordance with
the U.S. federal securities laws and the applicable rules
and regulations of the Securities and Exchange
Commission and the PCAOB.
We conducted our audits in accordance with the
standards of the PCAOB. Those standards require that
we plan and perform the audits to obtain reasonable
assurance about whether the consolidated financial
statements are free of material misstatement, whether
due to error or fraud, and whether effective internal
control over financial reporting was maintained in all
material respects.
Our audits of the consolidated financial statements
included performing procedures to assess the risks of
material misstatement of the consolidated financial
statements, whether due to error or fraud, and
performing procedures that respond to those risks.
Such procedures included examining, on a test basis,
evidence regarding the amounts and disclosures in the
consolidated financial statements. Our audits also
included evaluating the accounting principles used and
significant estimates made by management, as well as
evaluating the overall presentation of the consolidated
financial statements. Our audit of internal control over
financial reporting included obtaining an understanding
of internal control over financial reporting, assessing the
risk that a material weakness exists, and testing and
evaluating the design and operating effectiveness of
internal control based on the assessed risk. Our audits
also included performing such other procedures as we
considered necessary in the circumstances. We believe
that our audits provide a reasonable basis for our
opinions.
Definition and Limitations of Internal Control over
Financial Reporting
A company’s internal control over financial reporting is a
process designed to provide reasonable assurance
regarding the reliability of financial reporting and the
preparation of financial statements for external
purposes in accordance with generally accepted
accounting principles. A company’s internal control over
financial reporting includes those policies and
procedures that (i) pertain to the maintenance of
records that, in reasonable detail, accurately and fairly
reflect the transactions and dispositions of the assets of
the company; (ii) provide reasonable assurance that
transactions are recorded as necessary to permit
preparation of financial statements in accordance with
generally accepted accounting principles, and that
receipts and expenditures of the company are being
made only in accordance with authorizations of
management and directors of the company; and
(iii) provide reasonable assurance regarding prevention
or timely detection of unauthorized acquisition, use, or
disposition of the company’s assets that could have a
material effect on the financial statements.
Because of its inherent limitations, internal control over
financial reporting may not prevent or detect
misstatements. Also, projections of any evaluation of
effectiveness to future periods are subject to the risk
that controls may become inadequate because of
changes in conditions, or that the degree of compliance
with the policies or procedures may deteriorate.
PricewaterhouseCoopers LLP • 300 Madison Avenue • New York, NY 10017
Report of Independent Registered Public Accounting Firm
162
JPMorgan Chase & Co./2025 Form 10-K
Critical Audit Matters
The critical audit matters communicated below are
matters arising from the current period audit of the
consolidated financial statements that were
communicated or required to be communicated to the
audit committee and that (i) relate to accounts or
disclosures that are material to the consolidated
financial statements and (ii) involved our especially
challenging, subjective, or complex judgments. The
communication of critical audit matters does not alter
in any way our opinion on the consolidated financial
statements, taken as a whole, and we are not, by
communicating the critical audit matters below,
providing separate opinions on the critical audit
matters or on the accounts or disclosures to which
they relate.
Allowance for Loan Losses – Portfolio-Based
Component of the Wholesale and Credit Card Retained
Loan Portfolios
As described in Note 13 to the consolidated financial
statements, as of
December 31, 2025,
the allowance for
loan losses for the portfolio-based component of the
wholesale and credit card retained loan portfolios was
$7.6 billion and $15.6 billion, respectively, on total
portfolio-based wholesale and credit card retained
loans of $788.0 billion and $247.8 billion, respectively.
The Firm’s allowance for loan losses represents
management’s estimate of expected credit losses over
the remaining expected life of the Firm's retained loan
portfolios. The portfolio-based component begins with
a quantitative calculation that covers expected credit
losses over a loan’s expected life. The expected credit
losses are derived using a weighted average of five
internally developed macroeconomic scenarios over
an eight-quarter forecast period. As disclosed by
management, one of the most significant judgments
involved in estimating the allowance for loan losses
relates to the forecasted macroeconomic variables
used to estimate credit losses over the eight-quarter
forecast period within management’s methodology.
The significant forecasted macroeconomic variables
for the consumer portfolio include regional U.S.
unemployment rates and U.S. HPI. The significant
forecasted macroeconomic variables for the wholesale
portfolio include U.S. unemployment, U.S. real GDP
growth rate, U.S. equity prices, U.S. interest rates, U.S.
corporate credit spreads, oil prices, U.S. commercial
real estate prices and U.S. HPI.
The principal considerations for our determination that
performing procedures relating to the allowance for
loan losses for the portfolio-based component of the
wholesale and credit card retained loan portfolios is a
critical audit matter are (i) the significant judgment by
management when developing the allowance for loan
losses related to the portfolio-based component of the
wholesale and credit card retained loan portfolios; (ii) a
high degree of auditor judgment, subjectivity, and
effort in performing procedures and evaluating
management’s significant assumptions related to the
U.S. unemployment and the U.S. real GDP growth rate;
and (iii) the audit effort involved the use of
professionals with specialized skill and knowledge.
Addressing the matter involved performing
procedures and evaluating audit evidence in
connection with forming our overall opinion on the
consolidated financial statements. These procedures
included testing the effectiveness of controls relating
to the allowance for loan losses related to the portfolio-
based component of the wholesale and credit card
retained loan portfolios, including controls over the
development of the forecasted macroeconomic
variables. These procedures also included, among
others, (i) testing management’s process for
developing the allowance for loan losses related to the
portfolio-based component of the wholesale and
credit card retained loan portfolios (ii) testing the
completeness and accuracy of certain data used in
developing the forecasted macroeconomic variables
and (iii) the involvement of professionals with
specialized skill and knowledge to assist in evaluating
(a) the appropriateness of the methodology used by
management in developing the forecasted
macroeconomic variables and (b) the reasonableness
of the U.S. unemployment and the U.S. real GDP
growth rate assumptions.
Fair Value of Certain Level 3 Financial Instruments
As described in Note 2 to the consolidated financial
statements, as of
December 31, 2025, the Firm had
certain financial instruments which included $2.4 billion
of deposits, $5.6 billion of short-term borrowings and
$46.7 billion of long-term debt, which are
measured at
fair value on a recurring basis and are classified as
level 3. Financial instruments valued using internally
developed valuation models and other valuation
techniques that use significant unobservable inputs
are classified within level 3 of the fair value hierarchy.
The principal valuation techniques and unobservable
inputs used by management to measure the fair value
of certain level 3 financial instruments include the
following internally developed valuation models: (i)
option pricing, which uses unobservable inputs related
to interest rate volatility, Bermudan switch value,
interest rate correlation, interest rate-to-foreign
exchange correlation, equity volatility, equity
correlation, equity-to-foreign exchange correlation
and equity-to-interest rate correlation and (ii)
discounted cash flows, which uses unobservable
inputs related to credit correlation, credit spread,
recovery rate, yield and loss severity.
The principal considerations for our determination that
performing procedures relating to the fair value of
certain level 3 financial instruments is a critical audit
matter are (i) the significant judgment by management
when developing the fair value estimate of certain level
Report of Independent Registered Public Accounting Firm
JPMorgan Chase & Co./2025 Form 10-K
163
3 financial instruments; (ii) a high degree of auditor
judgment, subjectivity, and effort in performing
procedures and evaluating audit evidence related to
the aforementioned unobservable inputs; and (iii) the
audit effort involved the use of professionals with
specialized skill and knowledge.
Addressing the matter involved performing
procedures and evaluating audit evidence in
connection with forming our overall opinion on the
consolidated financial statements. These procedures
included testing the effectiveness of controls relating
to the fair value estimate of certain level 3 financial
instruments, including controls over the
aforementioned unobservable inputs. These
procedures also included, among others, (i) testing the
completeness and accuracy of certain data provided
by management and (ii) the involvement of
professionals with specialized skill and knowledge to
assist in evaluating the reasonableness of
management’s estimate by (a) developing an
independent estimate of the fair value for a sample of
certain level 3 financial instruments using
independently developed unobservable inputs and (b)
comparing the independent estimate of the fair value
to management’s estimate.
New York, New York
February 13, 2026
We have served as the Firm’s auditor since 1965.
Report of Independent Registered Public Accounting Firm
164
JPMorgan Chase & Co./2025 Form 10-K
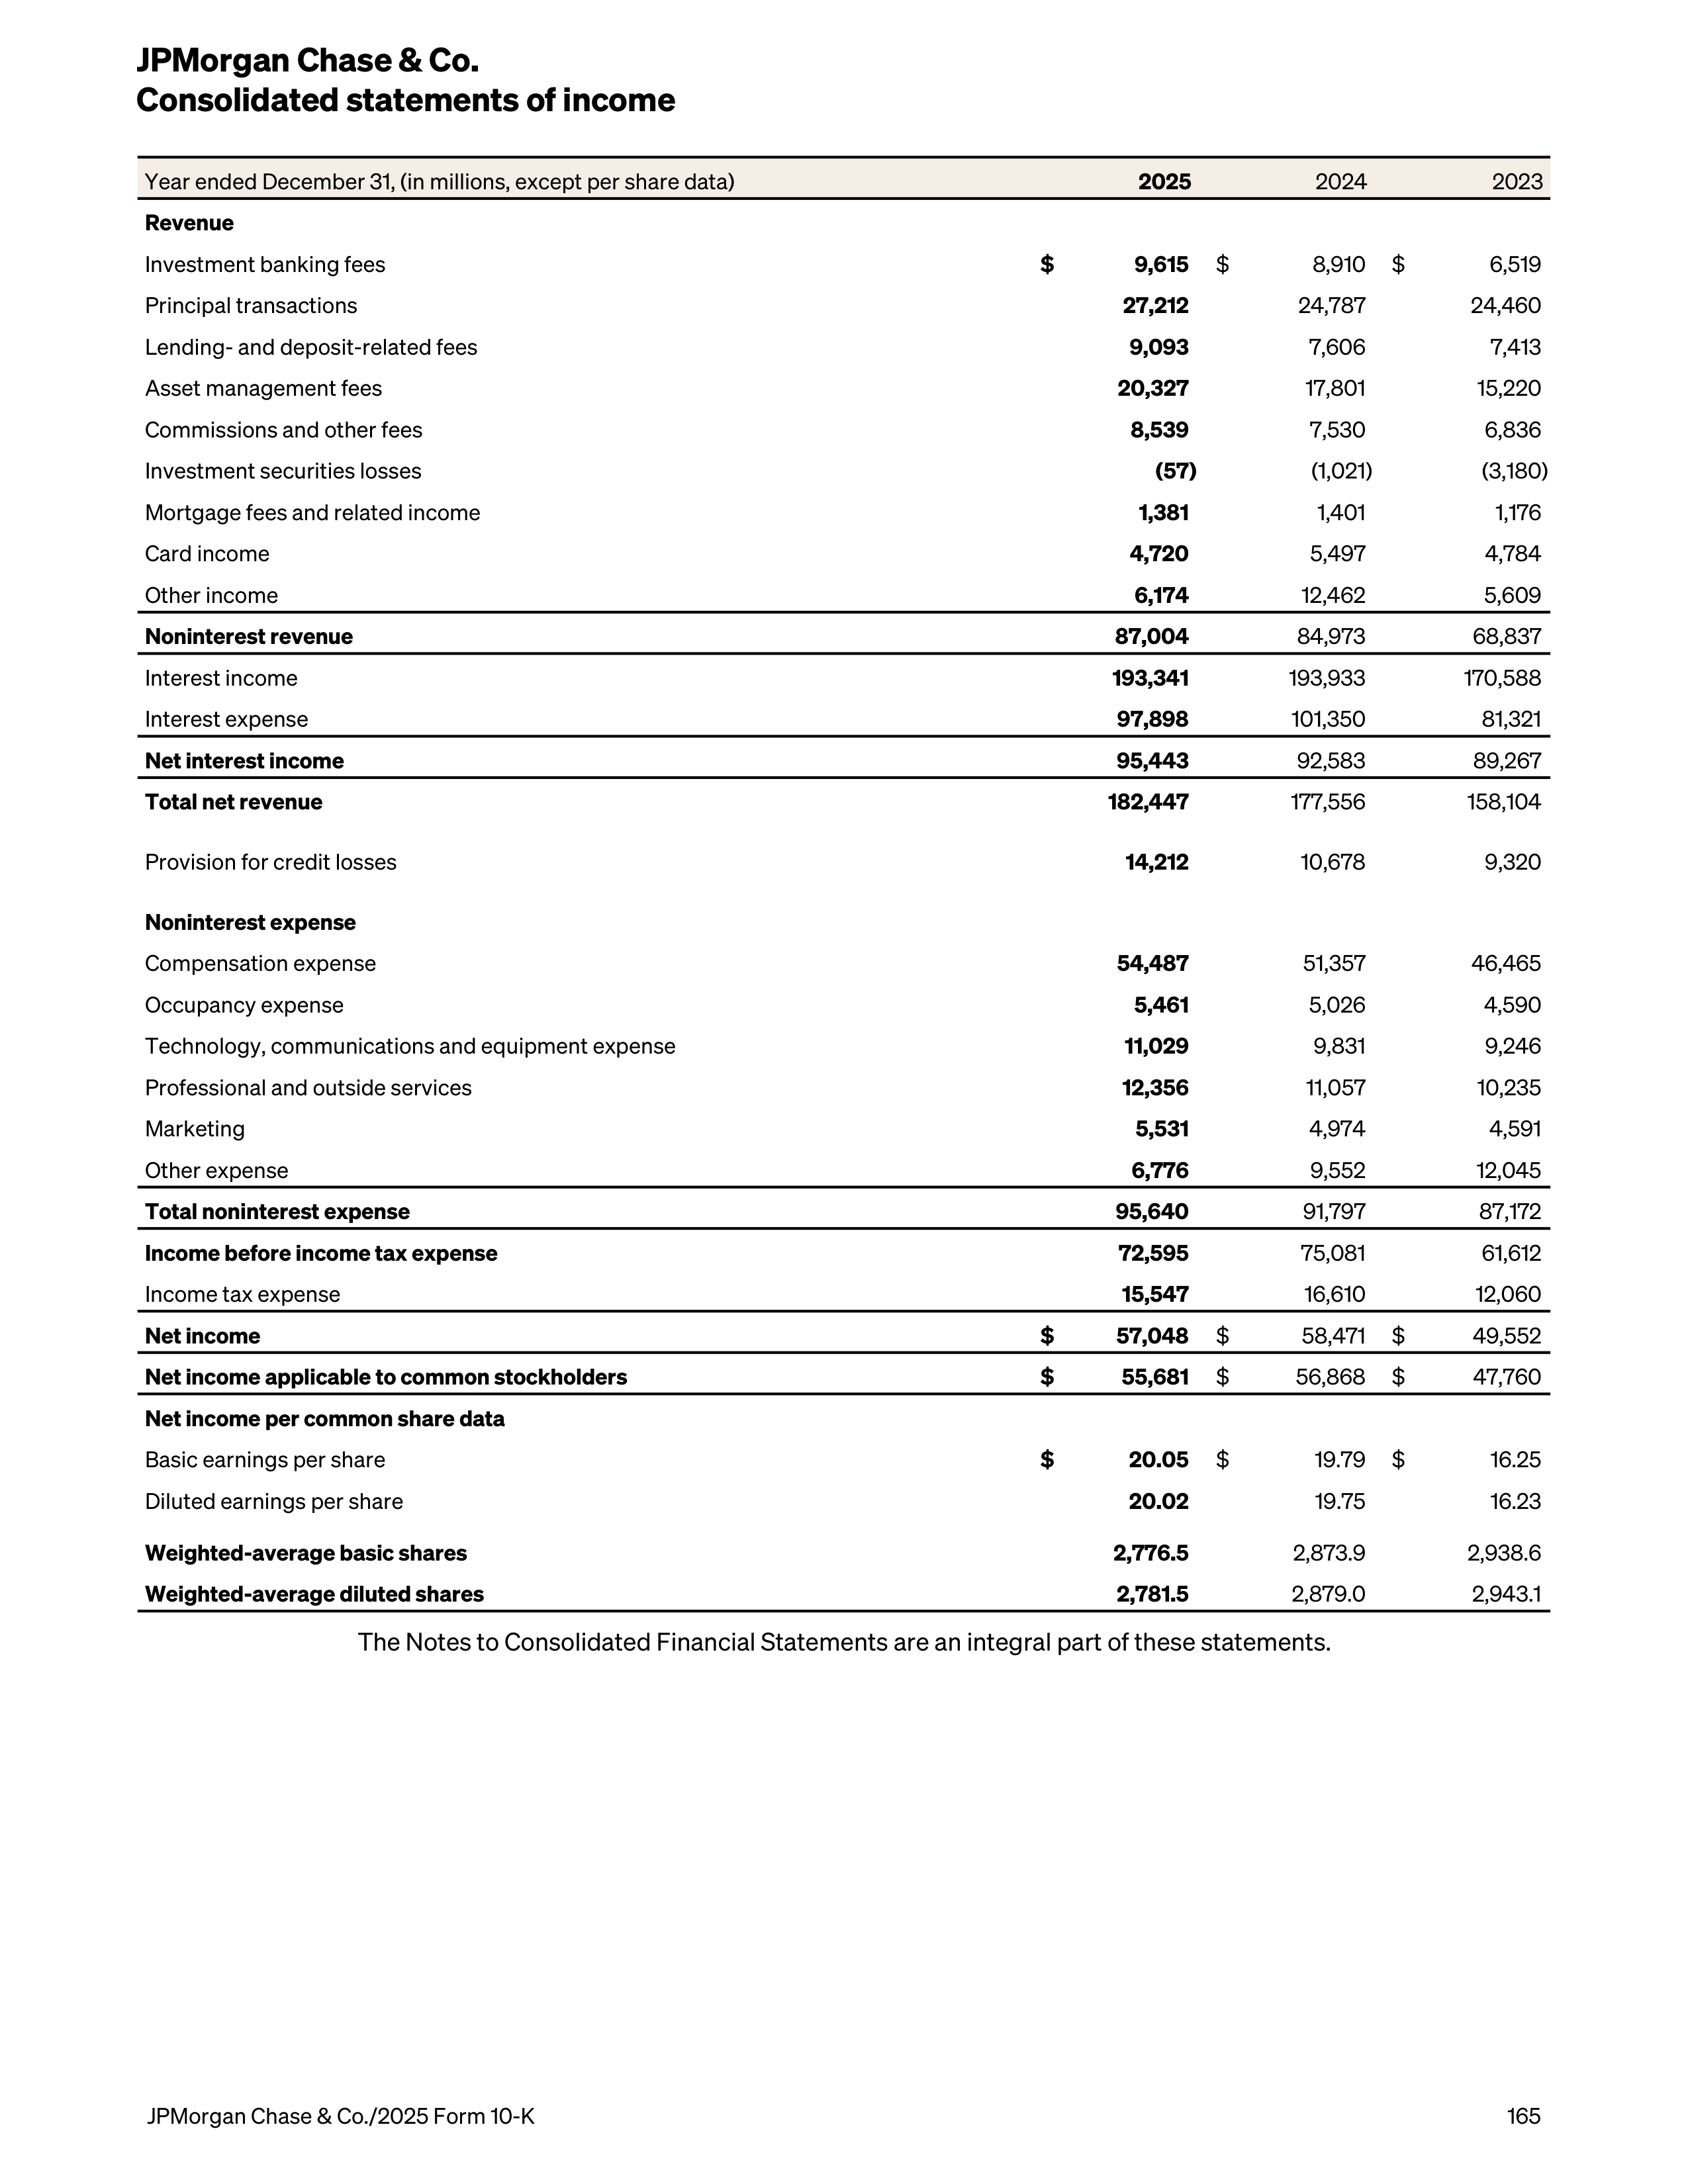
Year ended December 31, (in millions, except per share data)
2025
2024
2023
Revenue
Investment banking fees
$
9,615
$
8,910
$
6,519
Principal transactions
27,212
24,787
24,460
Lending- and deposit-related fees
9,093
7,606
7,413
Asset management fees
20,327
17,801
15,220
Commissions and other fees
8,539
7,530
6,836
Investment securities losses
(57)
(1,021)
(3,180)
Mortgage fees and related income
1,381
1,401
1,176
Card income
4,720
5,497
4,784
Other income
6,174
12,462
5,609
Noninterest revenue
87,004
84,973
68,837
Interest income
193,341
193,933
170,588
Interest expense
97,898
101,350
81,321
Net interest income
95,443
92,583
89,267
Total net revenue
182,447
177,556
158,104
Provision for credit losses
14,212
10,678
9,320
Noninterest expense
Compensation expense
54,487
51,357
46,465
Occupancy expense
5,461
5,026
4,590
Technology, communications and equipment expense
11,029
9,831
9,246
Professional and outside services
12,356
11,057
10,235
Marketing
5,531
4,974
4,591
Other expense
6,776
9,552
12,045
Total noninterest expense
95,640
91,797
87,172
Income before income tax expense
72,595
75,081
61,612
Income tax expense
15,547
16,610
12,060
Net income
$
57,048
$
58,471
$
49,552
Net income applicable to common stockholders
$
55,681
$
56,868
$
47,760
Net income per common share data
Basic earnings per share
$
20.05
$
19.79
$
16.25
Diluted earnings per share
20.02
19.75
16.23
Weighted-average basic shares
2,776.5
2,873.9
2,938.6
Weighted-average diluted shares
2,781.5
2,879.0
2,943.1
The Notes to Consolidated Financial Statements are an integral part of these statements.
JPMorgan Chase & Co.
Consolidated statements of income
JPMorgan Chase & Co./2025 Form 10-K
165
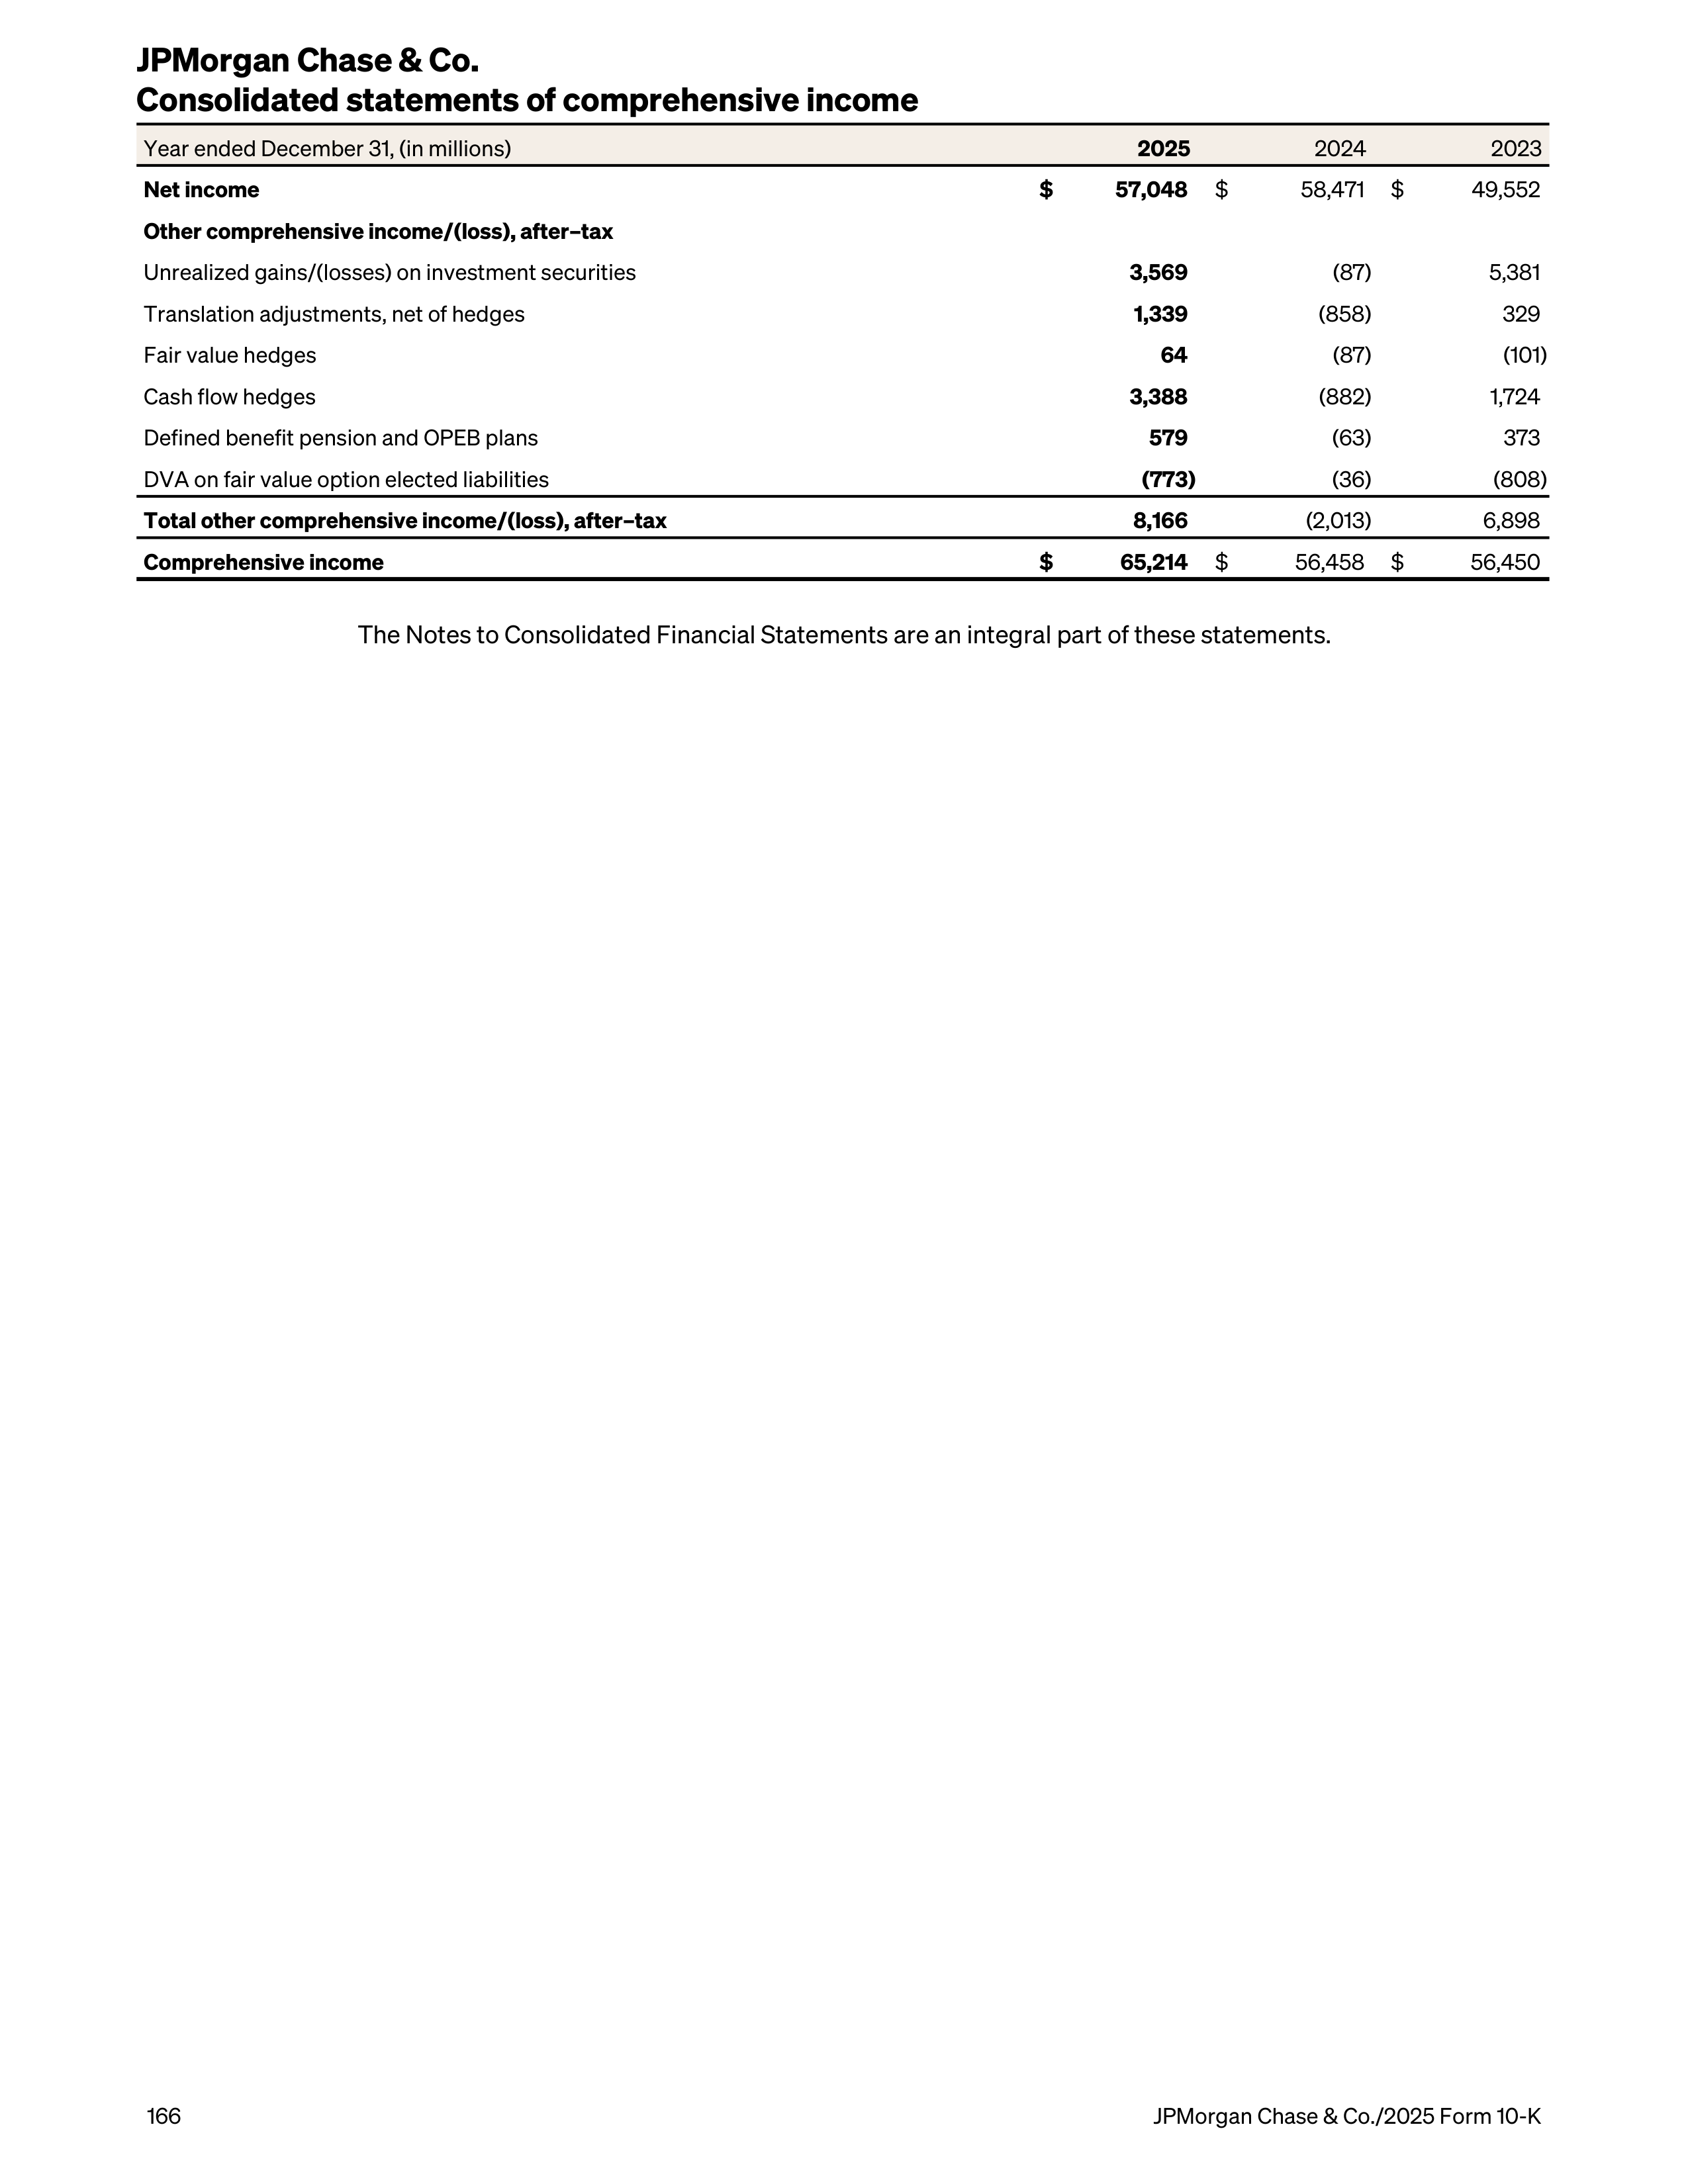
Year ended December 31, (in millions)
2025
2024
2023
Net income
$
57,048
$
58,471
$
49,552
Other comprehensive income/(loss), after–tax
Unrealized gains/(losses) on investment securities
3,569
(87)
5,381
Translation adjustments, net of hedges
1,339
(858)
329
Fair value hedges
64
(87)
(101)
Cash flow hedges
3,388
(882)
1,724
Defined benefit pension and OPEB plans
579
(63)
373
DVA on fair value option elected liabilities
(773)
(36)
(808)
Total other comprehensive income/(loss), after–tax
8,166
(2,013)
6,898
Comprehensive income
$
65,214
$
56,458
$
56,450
The Notes to Consolidated Financial Statements are an integral part of these statements.
JPMorgan Chase & Co.
Consolidated statements of comprehensive income
166
JPMorgan Chase & Co./2025 Form 10-K
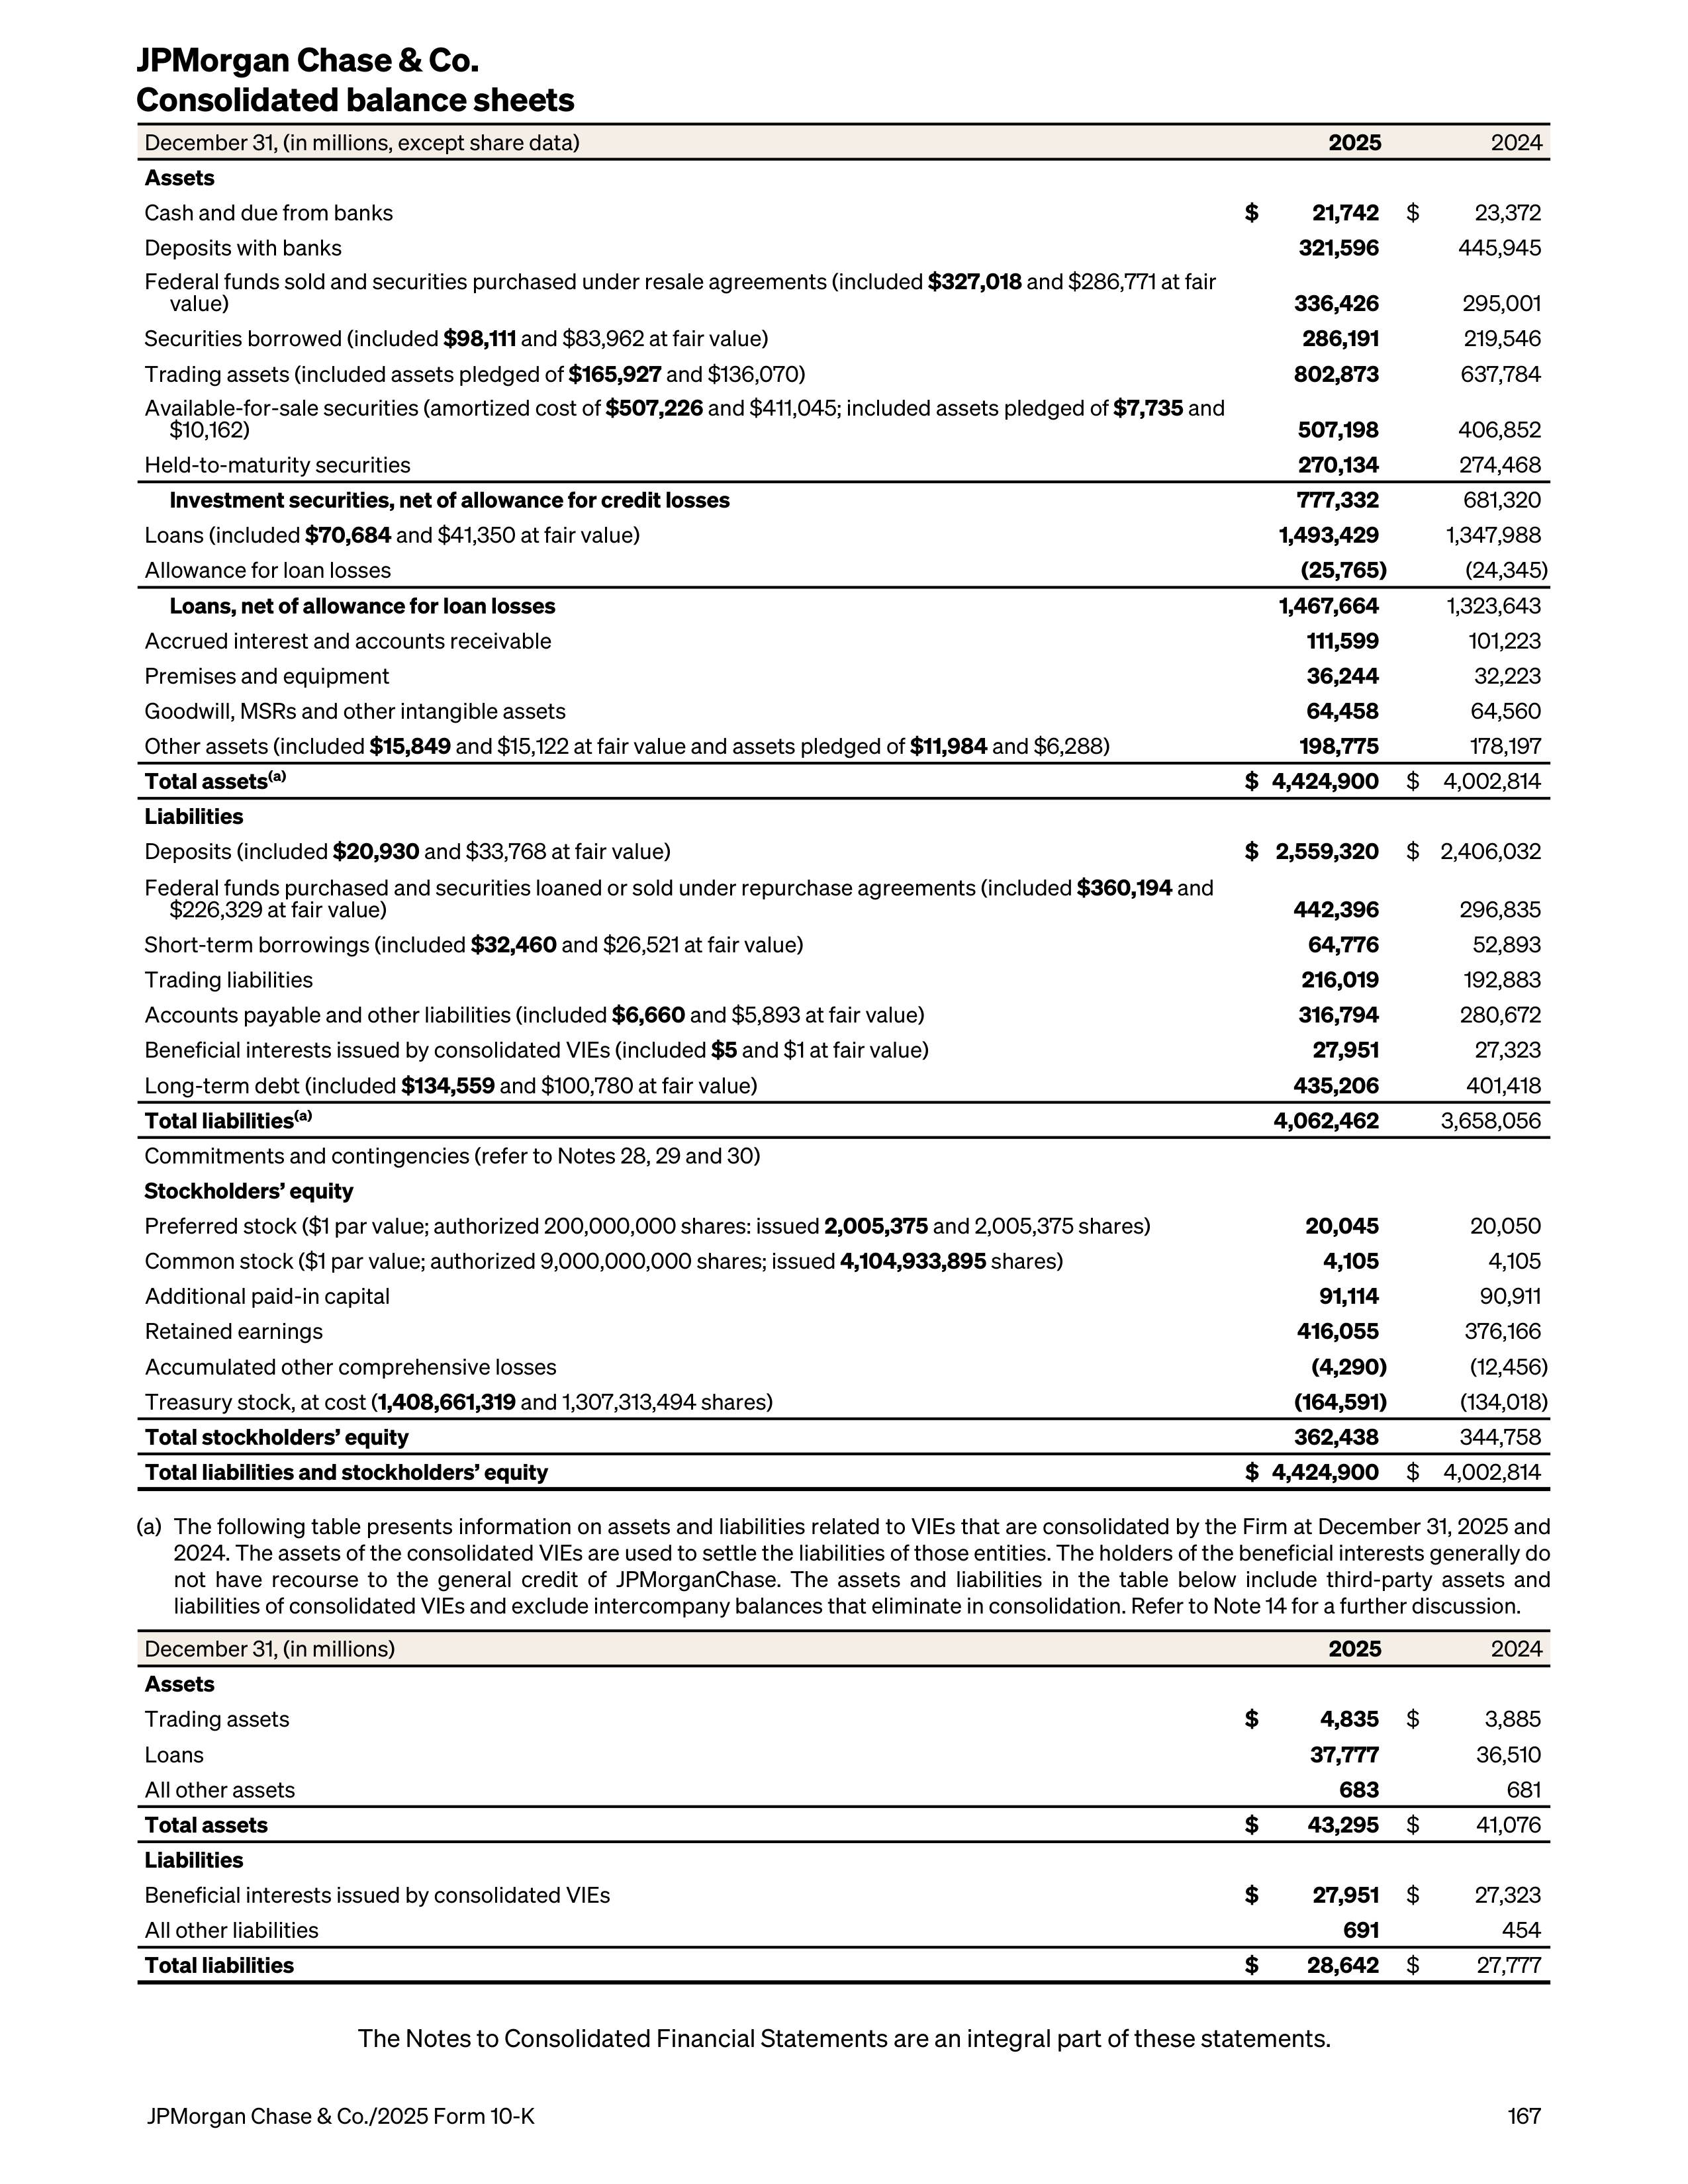
December 31, (in millions, except share data)
2025
2024
Assets
Cash and due from banks
$
21,742
$
23,372
Deposits with banks
321,596
445,945
Federal funds sold and securities purchased under resale agreements (included
$327,018
and $286,771 at fair
value)
336,426
295,001
Securities borrowed (included
$98,111
and $83,962 at fair value)
286,191
219,546
Trading assets (included assets pledged of
$165,927
and $136,070)
802,873
637,784
Available-for-sale securities (amortized cost of
$507,226
and $411,045; included assets pledged of
$7,735
and
$10,162)
507,198
406,852
Held-to-maturity securities
270,134
274,468
Investment securities, net of allowance for credit losses
777,332
681,320
Loans (included
$70,684
and $41,350 at fair value)
1,493,429
1,347,988
Allowance for loan losses
(25,765)
(24,345)
Loans, net of allowance for loan losses
1,467,664
1,323,643
Accrued interest and accounts receivable
111,599
101,223
Premises and equipment
36,244
32,223
Goodwill, MSRs and other intangible assets
64,458
64,560
Other assets (included
$15,849
and $15,122 at fair value and assets pledged of
$11,984
and $6,288)
198,775
178,197
Total assets
(a)
$ 4,424,900
$
4,002,814
Liabilities
Deposits (included
$20,930
and $33,768 at fair value)
$ 2,559,320
$ 2,406,032
Federal funds purchased and securities loaned or sold under repurchase agreements (included
$360,194
and
$226,329 at fair value)
442,396
296,835
Short-term borrowings (included
$32,460
and $26,521 at fair value)
64,776
52,893
Trading liabilities
216,019
192,883
Accounts payable and other liabilities (included
$6,660
and $5,893 at fair value)
316,794
280,672
Beneficial interests issued by consolidated VIEs (included
$5
and $1 at fair value)
27,951
27,323
Long-term debt (included
$134,559
and $100,780 at fair value)
435,206
401,418
Total liabilities
(a)
4,062,462
3,658,056
Commitments and contingencies (refer to Notes 28, 29 and 30)
Stockholders’ equity
Preferred stock ($1 par value; authorized 200,000,000 shares: issued
2,005,375
and 2,005,375 shares)
20,045
20,050
Common stock ($1 par value; authorized 9,000,000,000 shares; issued
4,104,933,895
shares)
4,105
4,105
Additional paid-in capital
91,114
90,911
Retained earnings
416,055
376,166
Accumulated other comprehensive losses
(4,290)
(12,456)
Treasury stock, at cost (
1,408,661,319
and 1,307,313,494 shares)
(164,591)
(134,018)
Total stockholders’ equity
362,438
344,758
Total liabilities and stockholders’ equity
$ 4,424,900
$
4,002,814
(a)
The following table presents information on assets and liabilities related to VIEs that are consolidated by the Firm at December 31, 2025 and
2024. The assets of the consolidated VIEs are used to settle the liabilities of those entities. The holders of the beneficial interests generally do
not have recourse to the general credit of JPMorganChase. The assets and liabilities in the table below include third-party assets and
liabilities of consolidated VIEs and exclude intercompany balances that eliminate in consolidation. Refer to Note 14 for a further discussion.
December 31, (in millions)
2025
2024
Assets
Trading assets
$
4,835
$
3,885
Loans
37,777
36,510
All other assets
683
681
Total assets
$
43,295
$
41,076
Liabilities
Beneficial interests issued by consolidated VIEs
$
27,951
$
27,323
All other liabilities
691
454
Total liabilities
$
28,642
$
27,777
The Notes to Consolidated Financial Statements are an integral part of these statements.
JPMorgan Chase & Co.
Consolidated balance sheets
JPMorgan Chase & Co./2025 Form 10-K
167
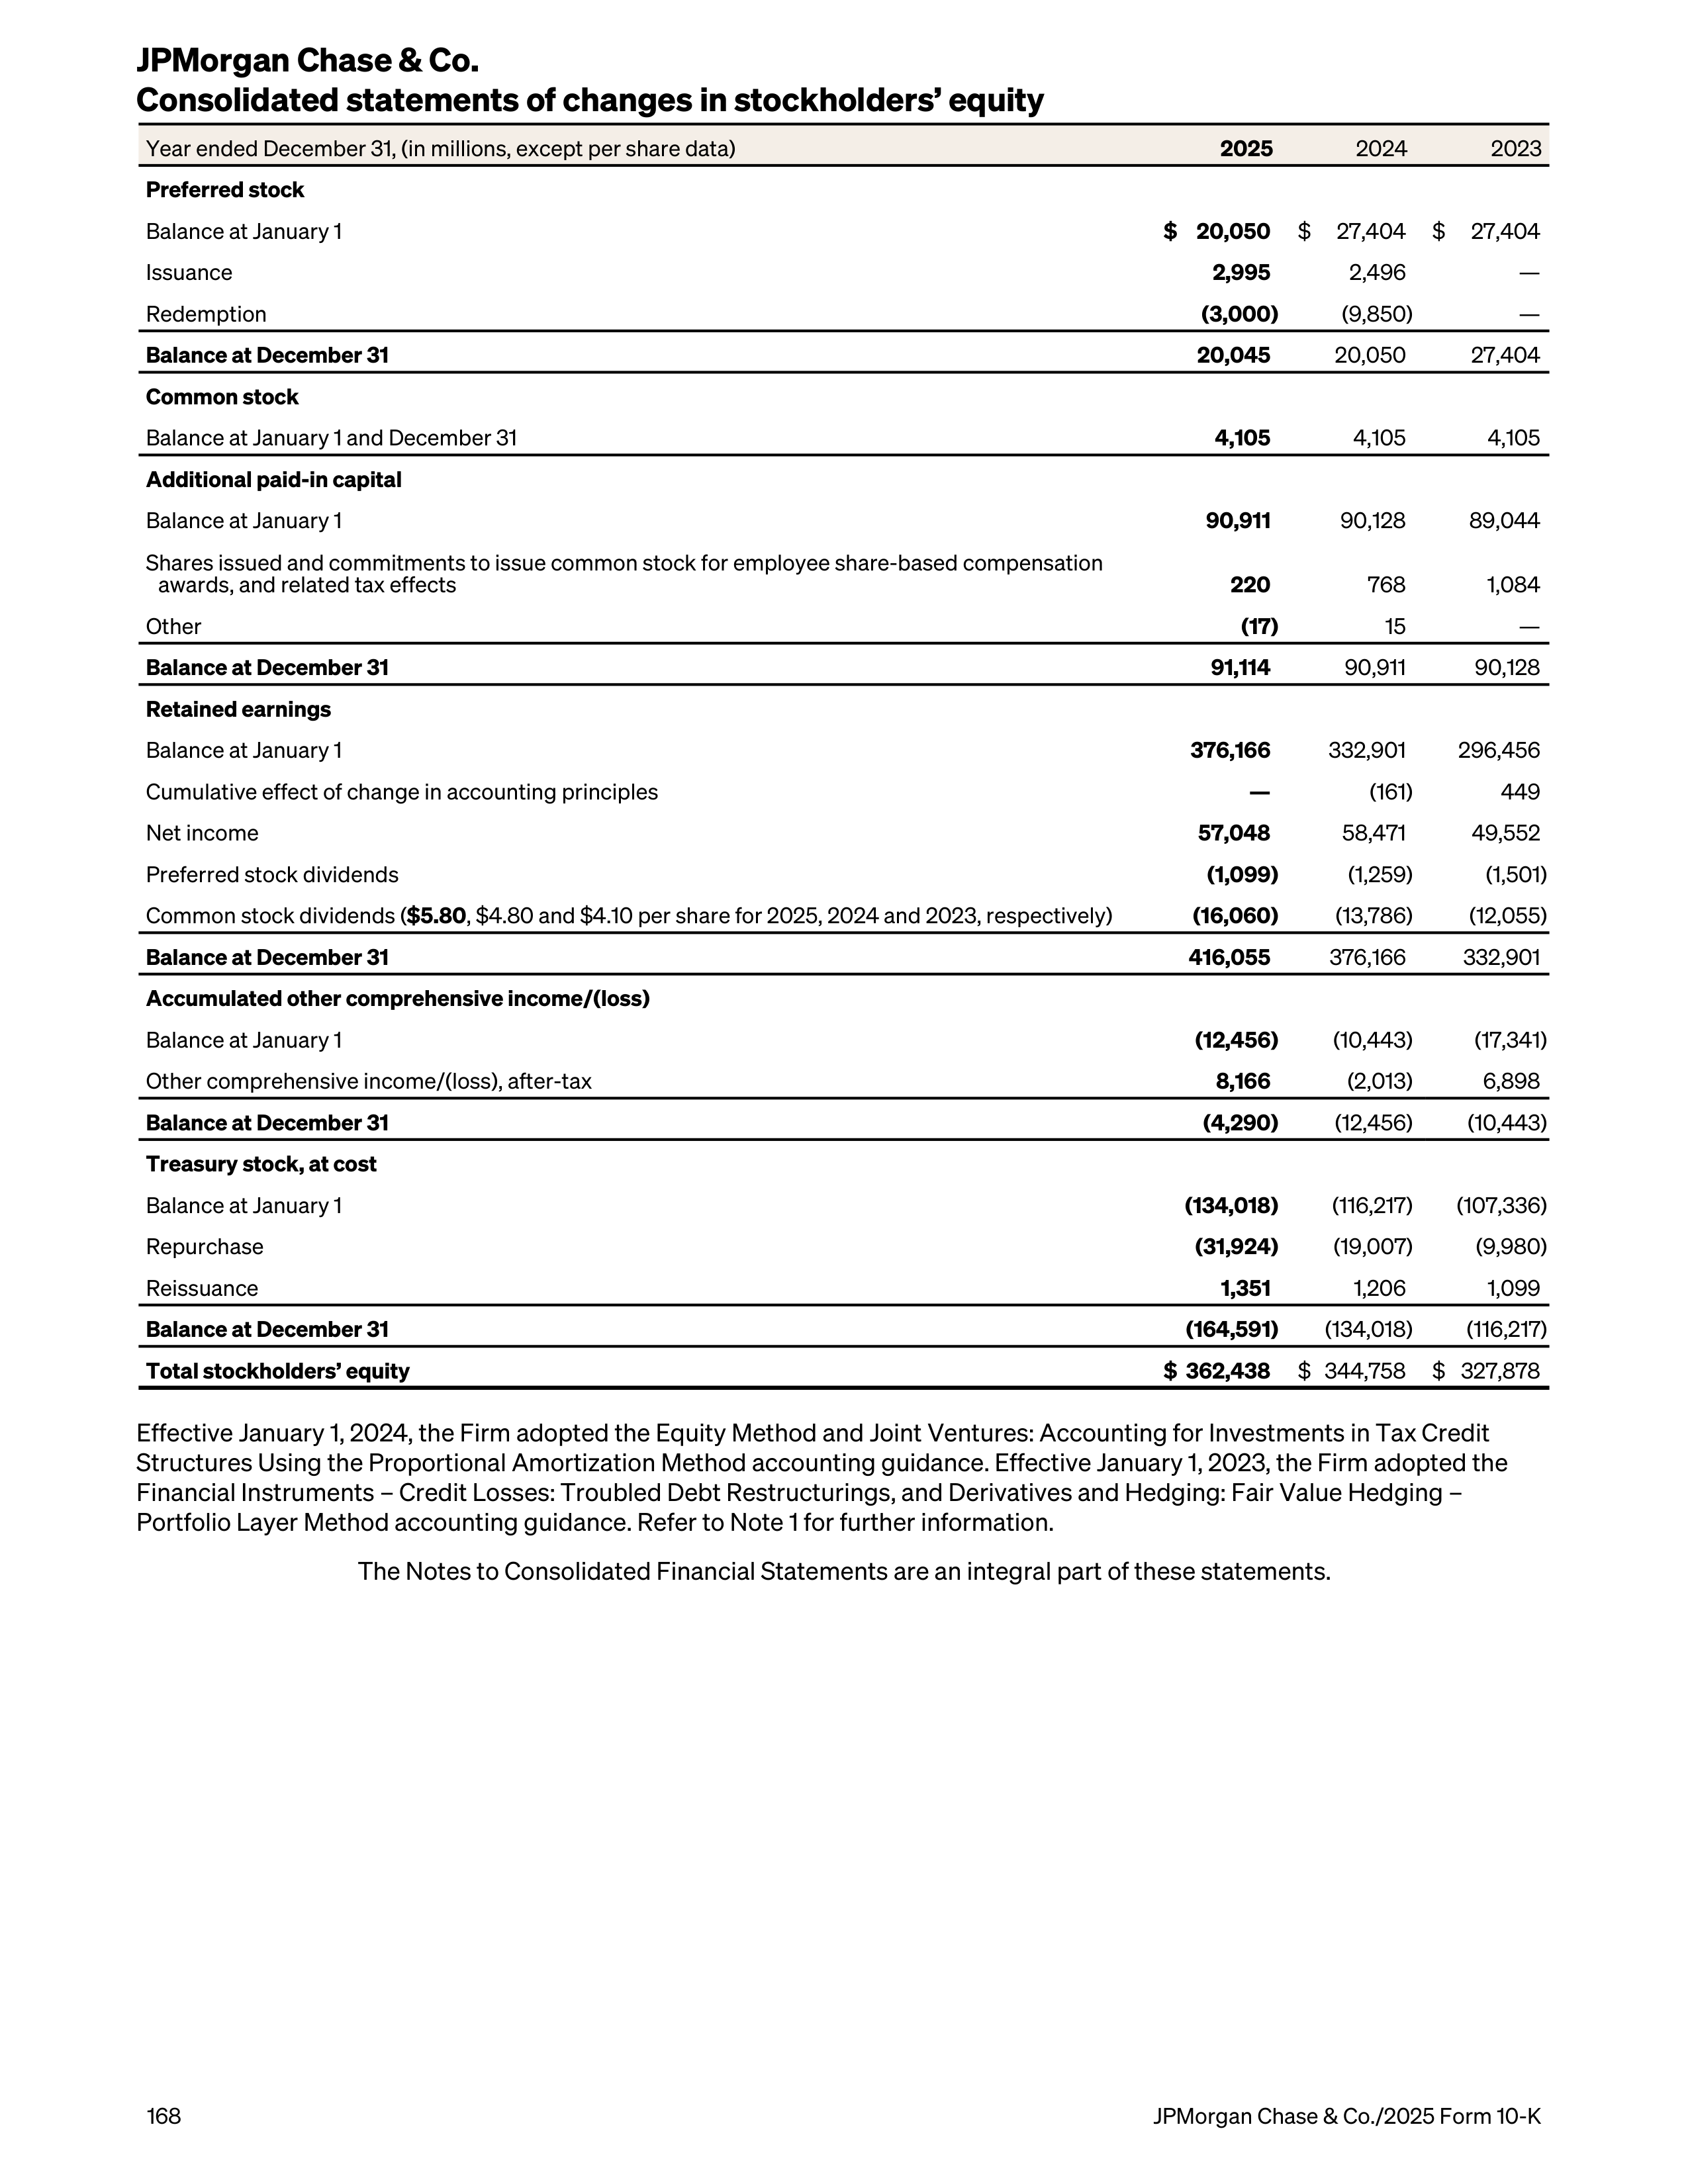
Year ended December 31, (in millions, except per share data)
2025
2024
2023
Preferred stock
Balance at January 1
$ 20,050
$
27,404
$
27,404
Issuance
2,995
2,496
—
Redemption
(3,000)
(9,850)
—
Balance at December 31
20,045
20,050
27,404
Common stock
Balance at January 1 and December 31
4,105
4,105
4,105
Additional paid-in capital
Balance at January 1
90,911
90,128
89,044
Shares issued and commitments to issue common stock for employee share-based compensation
awards, and related tax effects
220
768
1,084
Other
(17)
15
—
Balance at December 31
91,114
90,911
90,128
Retained earnings
Balance at January 1
376,166
332,901
296,456
Cumulative effect of change in accounting principles
—
(161)
449
Net income
57,048
58,471
49,552
Preferred stock dividends
(1,099)
(1,259)
(1,501)
Common stock dividends (
$5.80
, $4.80 and $4.10 per share for 2025, 2024 and 2023, respectively)
(16,060)
(13,786)
(12,055)
Balance at December 31
416,055
376,166
332,901
Accumulated other comprehensive income/(loss)
Balance at January 1
(12,456)
(10,443)
(17,341)
Other comprehensive income/(loss), after-tax
8,166
(2,013)
6,898
Balance at December 31
(4,290)
(12,456)
(10,443)
Treasury stock, at cost
Balance at January 1
(134,018)
(116,217)
(107,336)
Repurchase
(31,924)
(19,007)
(9,980)
Reissuance
1,351
1,206
1,099
Balance at December 31
(164,591)
(134,018)
(116,217)
Total stockholders’ equity
$ 362,438
$ 344,758
$ 327,878
Effective January 1, 2024, the Firm adopted the Equity Method and Joint Ventures: Accounting for Investments in Tax Credit
Structures Using the Proportional Amortization Method accounting guidance. Effective January 1, 2023, the Firm adopted the
Financial Instruments – Credit Losses: Troubled Debt Restructurings, and Derivatives and Hedging: Fair Value Hedging –
Portfolio Layer Method accounting guidance. Refer to Note 1 for further information.
The Notes to Consolidated Financial Statements are an integral part of these statements.
JPMorgan Chase & Co.
Consolidated statements of changes in stockholders’ equity
168
JPMorgan Chase & Co./2025 Form 10-K
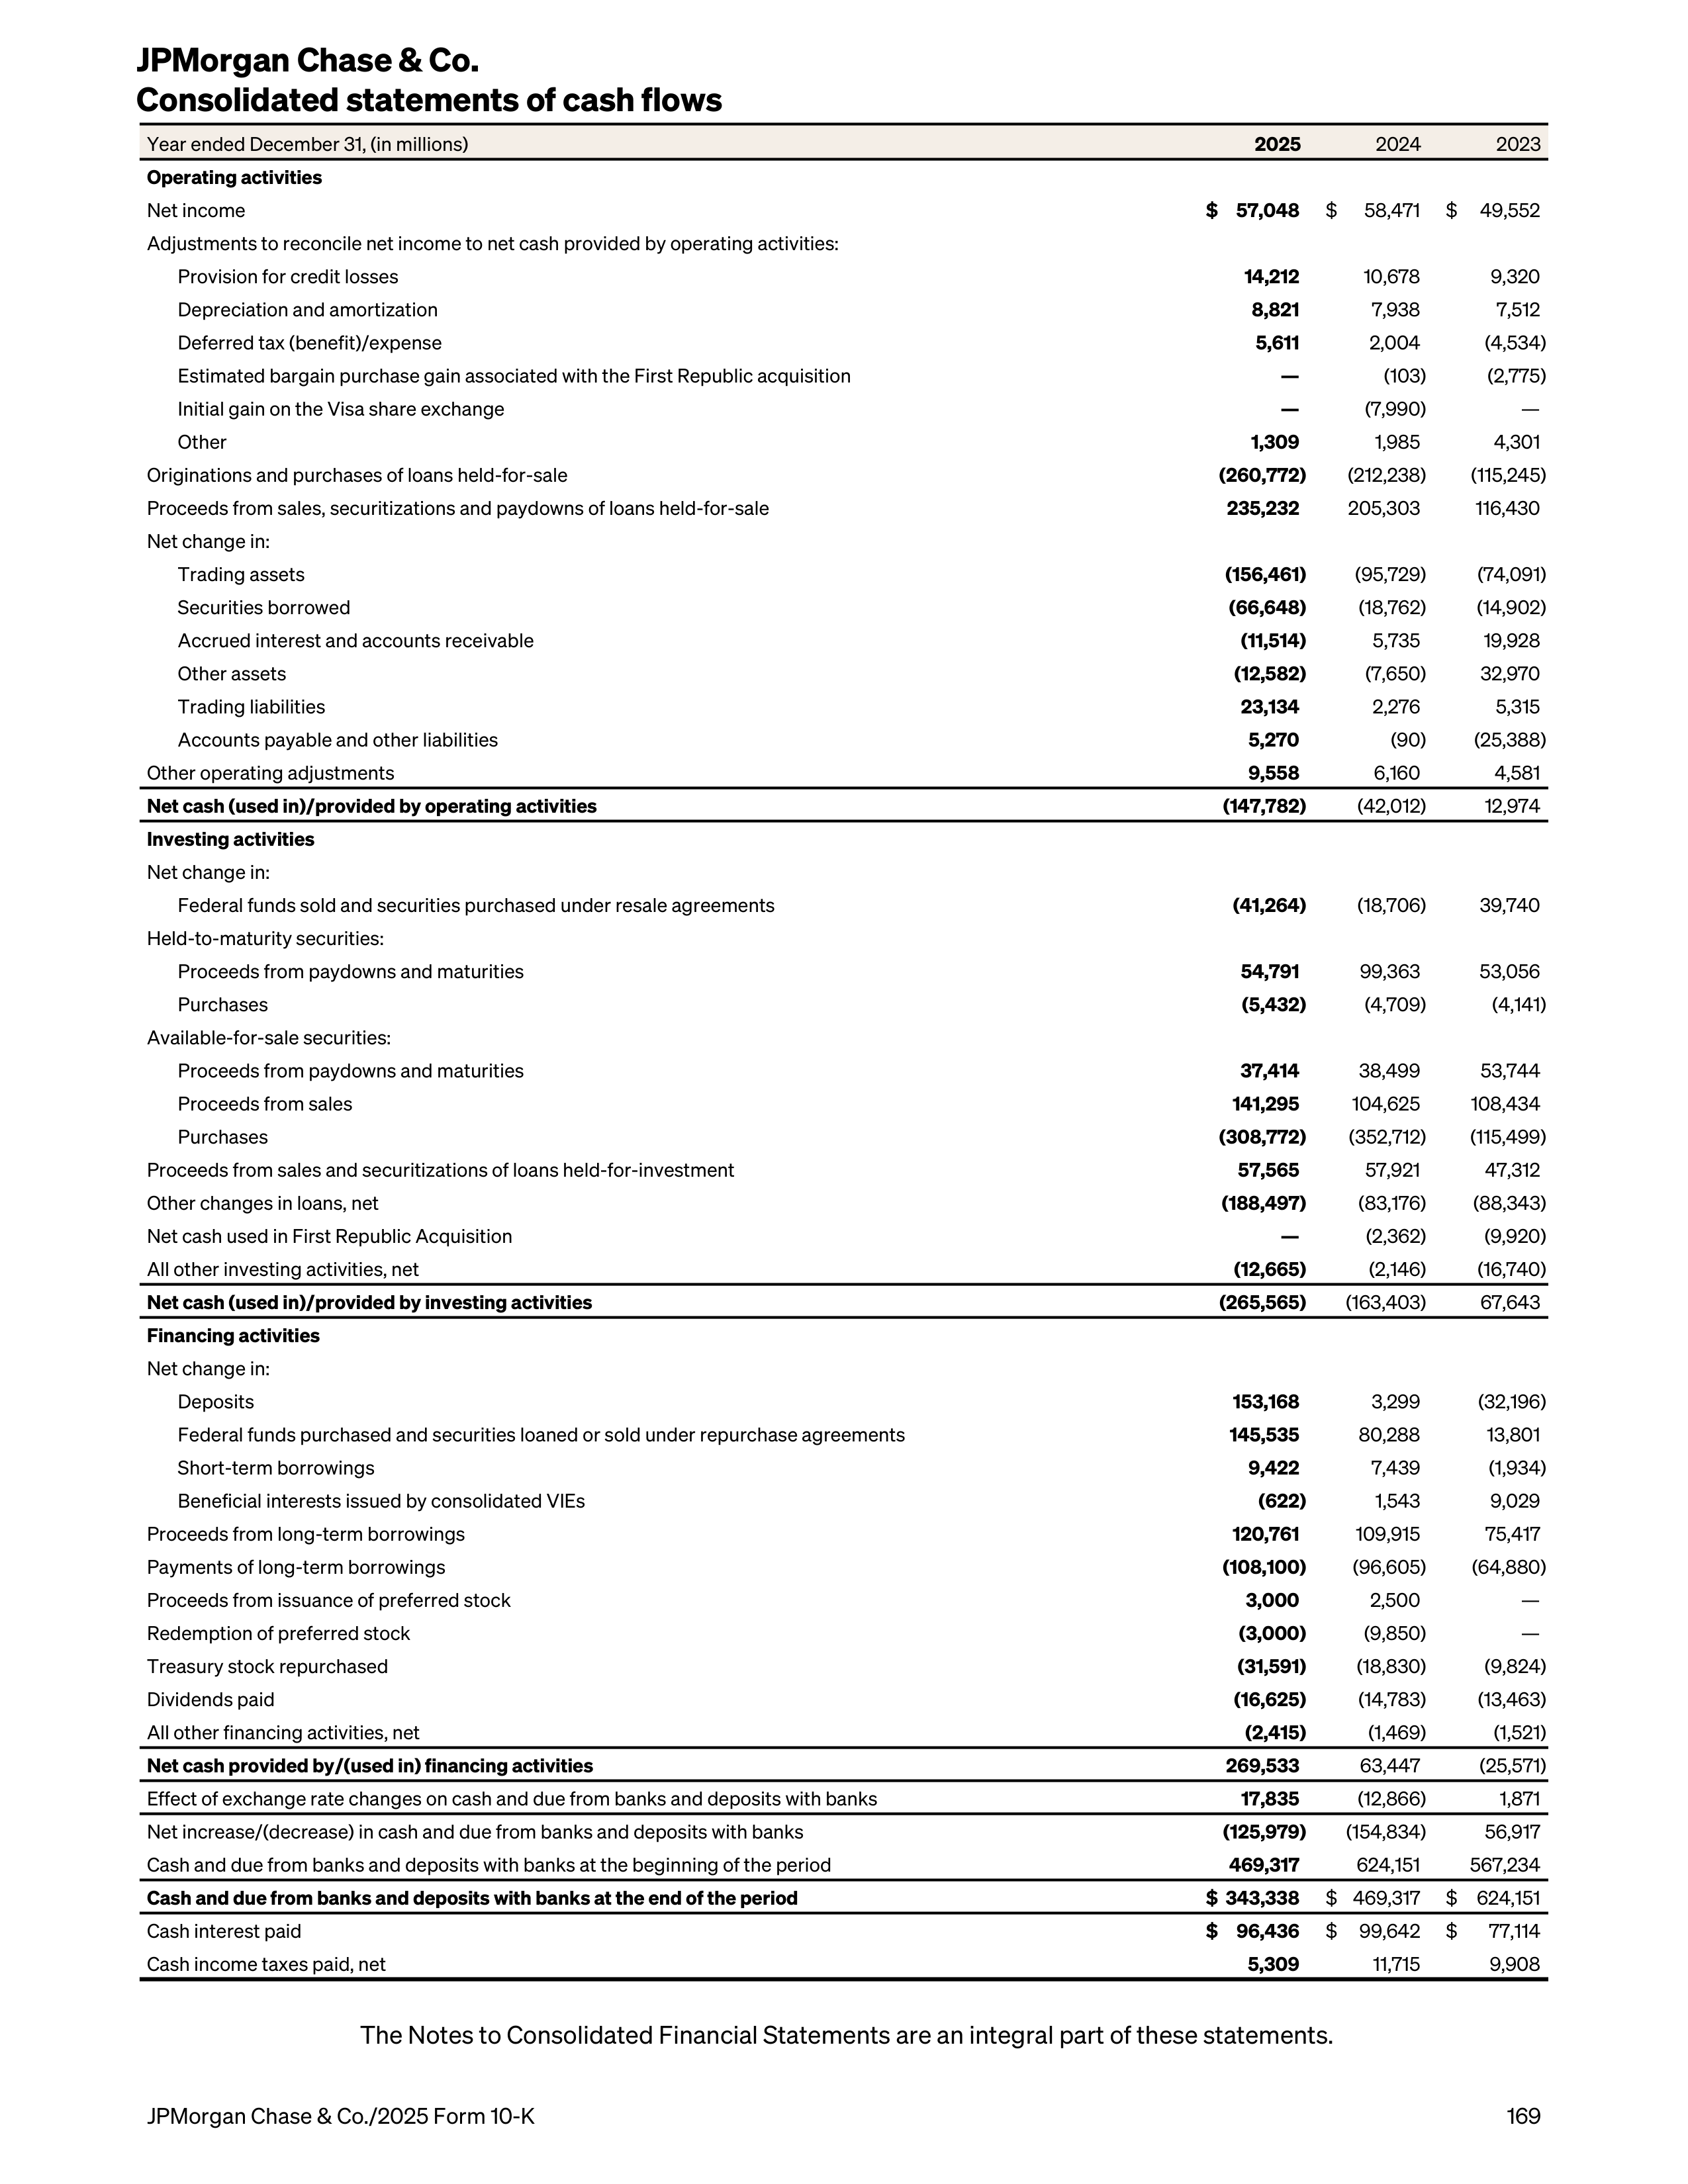
Year ended December 31, (in millions)
2025
2024
2023
Operating activities
Net income
$ 57,048
$
58,471
$
49,552
Adjustments to reconcile net income to net cash provided by operating activities:
Provision for credit losses
14,212
10,678
9,320
Depreciation and amortization
8,821
7,938
7,512
Deferred tax (benefit)/expense
5,611
2,004
(4,534)
Estimated bargain purchase gain associated with the First Republic acquisition
—
(103)
(2,775)
Initial gain on the Visa share exchange
—
(7,990)
—
Other
1,309
1,985
4,301
Originations and purchases of loans held-for-sale
(260,772)
(212,238)
(115,245)
Proceeds from sales, securitizations and paydowns of loans held-for-sale
235,232
205,303
116,430
Net change in:
Trading assets
(156,461)
(95,729)
(74,091)
Securities borrowed
(66,648)
(18,762)
(14,902)
Accrued interest and accounts receivable
(11,514)
5,735
19,928
Other assets
(12,582)
(7,650)
32,970
Trading liabilities
23,134
2,276
5,315
Accounts payable and other liabilities
5,270
(90)
(25,388)
Other operating adjustments
9,558
6,160
4,581
Net cash (used in)/provided by operating activities
(147,782)
(42,012)
12,974
Investing activities
Net change in:
Federal funds sold and securities purchased under resale agreements
(41,264)
(18,706)
39,740
Held-to-maturity securities:
Proceeds from paydowns and maturities
54,791
99,363
53,056
Purchases
(5,432)
(4,709)
(4,141)
Available-for-sale securities:
Proceeds from paydowns and maturities
37,414
38,499
53,744
Proceeds from sales
141,295
104,625
108,434
Purchases
(308,772)
(352,712)
(115,499)
Proceeds from sales and securitizations of loans held-for-investment
57,565
57,921
47,312
Other changes in loans, net
(188,497)
(83,176)
(88,343)
Net cash used in First Republic Acquisition
—
(2,362)
(9,920)
All other investing activities, net
(12,665)
(2,146)
(16,740)
Net cash (used in)/provided by investing activities
(265,565)
(163,403)
67,643
Financing activities
Net change in:
Deposits
153,168
3,299
(32,196)
Federal funds purchased and securities loaned or sold under repurchase agreements
145,535
80,288
13,801
Short-term borrowings
9,422
7,439
(1,934)
Beneficial interests issued by consolidated VIEs
(622)
1,543
9,029
Proceeds from long-term borrowings
120,761
109,915
75,417
Payments of long-term borrowings
(108,100)
(96,605)
(64,880)
Proceeds from issuance of preferred stock
3,000
2,500
—
Redemption of preferred stock
(3,000)
(9,850)
—
Treasury stock repurchased
(31,591)
(18,830)
(9,824)
Dividends paid
(16,625)
(14,783)
(13,463)
All other financing activities, net
(2,415)
(1,469)
(1,521)
Net cash provided by/(used in) financing activities
269,533
63,447
(25,571)
Effect of exchange rate changes on cash and due from banks and deposits with banks
17,835
(12,866)
1,871
Net increase/(decrease) in cash and due from banks and deposits with banks
(125,979)
(154,834)
56,917
Cash and due from banks and deposits with banks at the beginning of the period
469,317
624,151
567,234
Cash and due from banks and deposits with banks at the end of the period
$ 343,338
$ 469,317
$
624,151
Cash interest paid
$ 96,436
$
99,642
$
77,114
Cash income taxes paid, net
5,309
11,715
9,908
The Notes to Consolidated Financial Statements are an integral part of these statements.
JPMorgan Chase & Co.
Consolidated statements of cash flows
JPMorgan Chase & Co./2025 Form 10-K
169
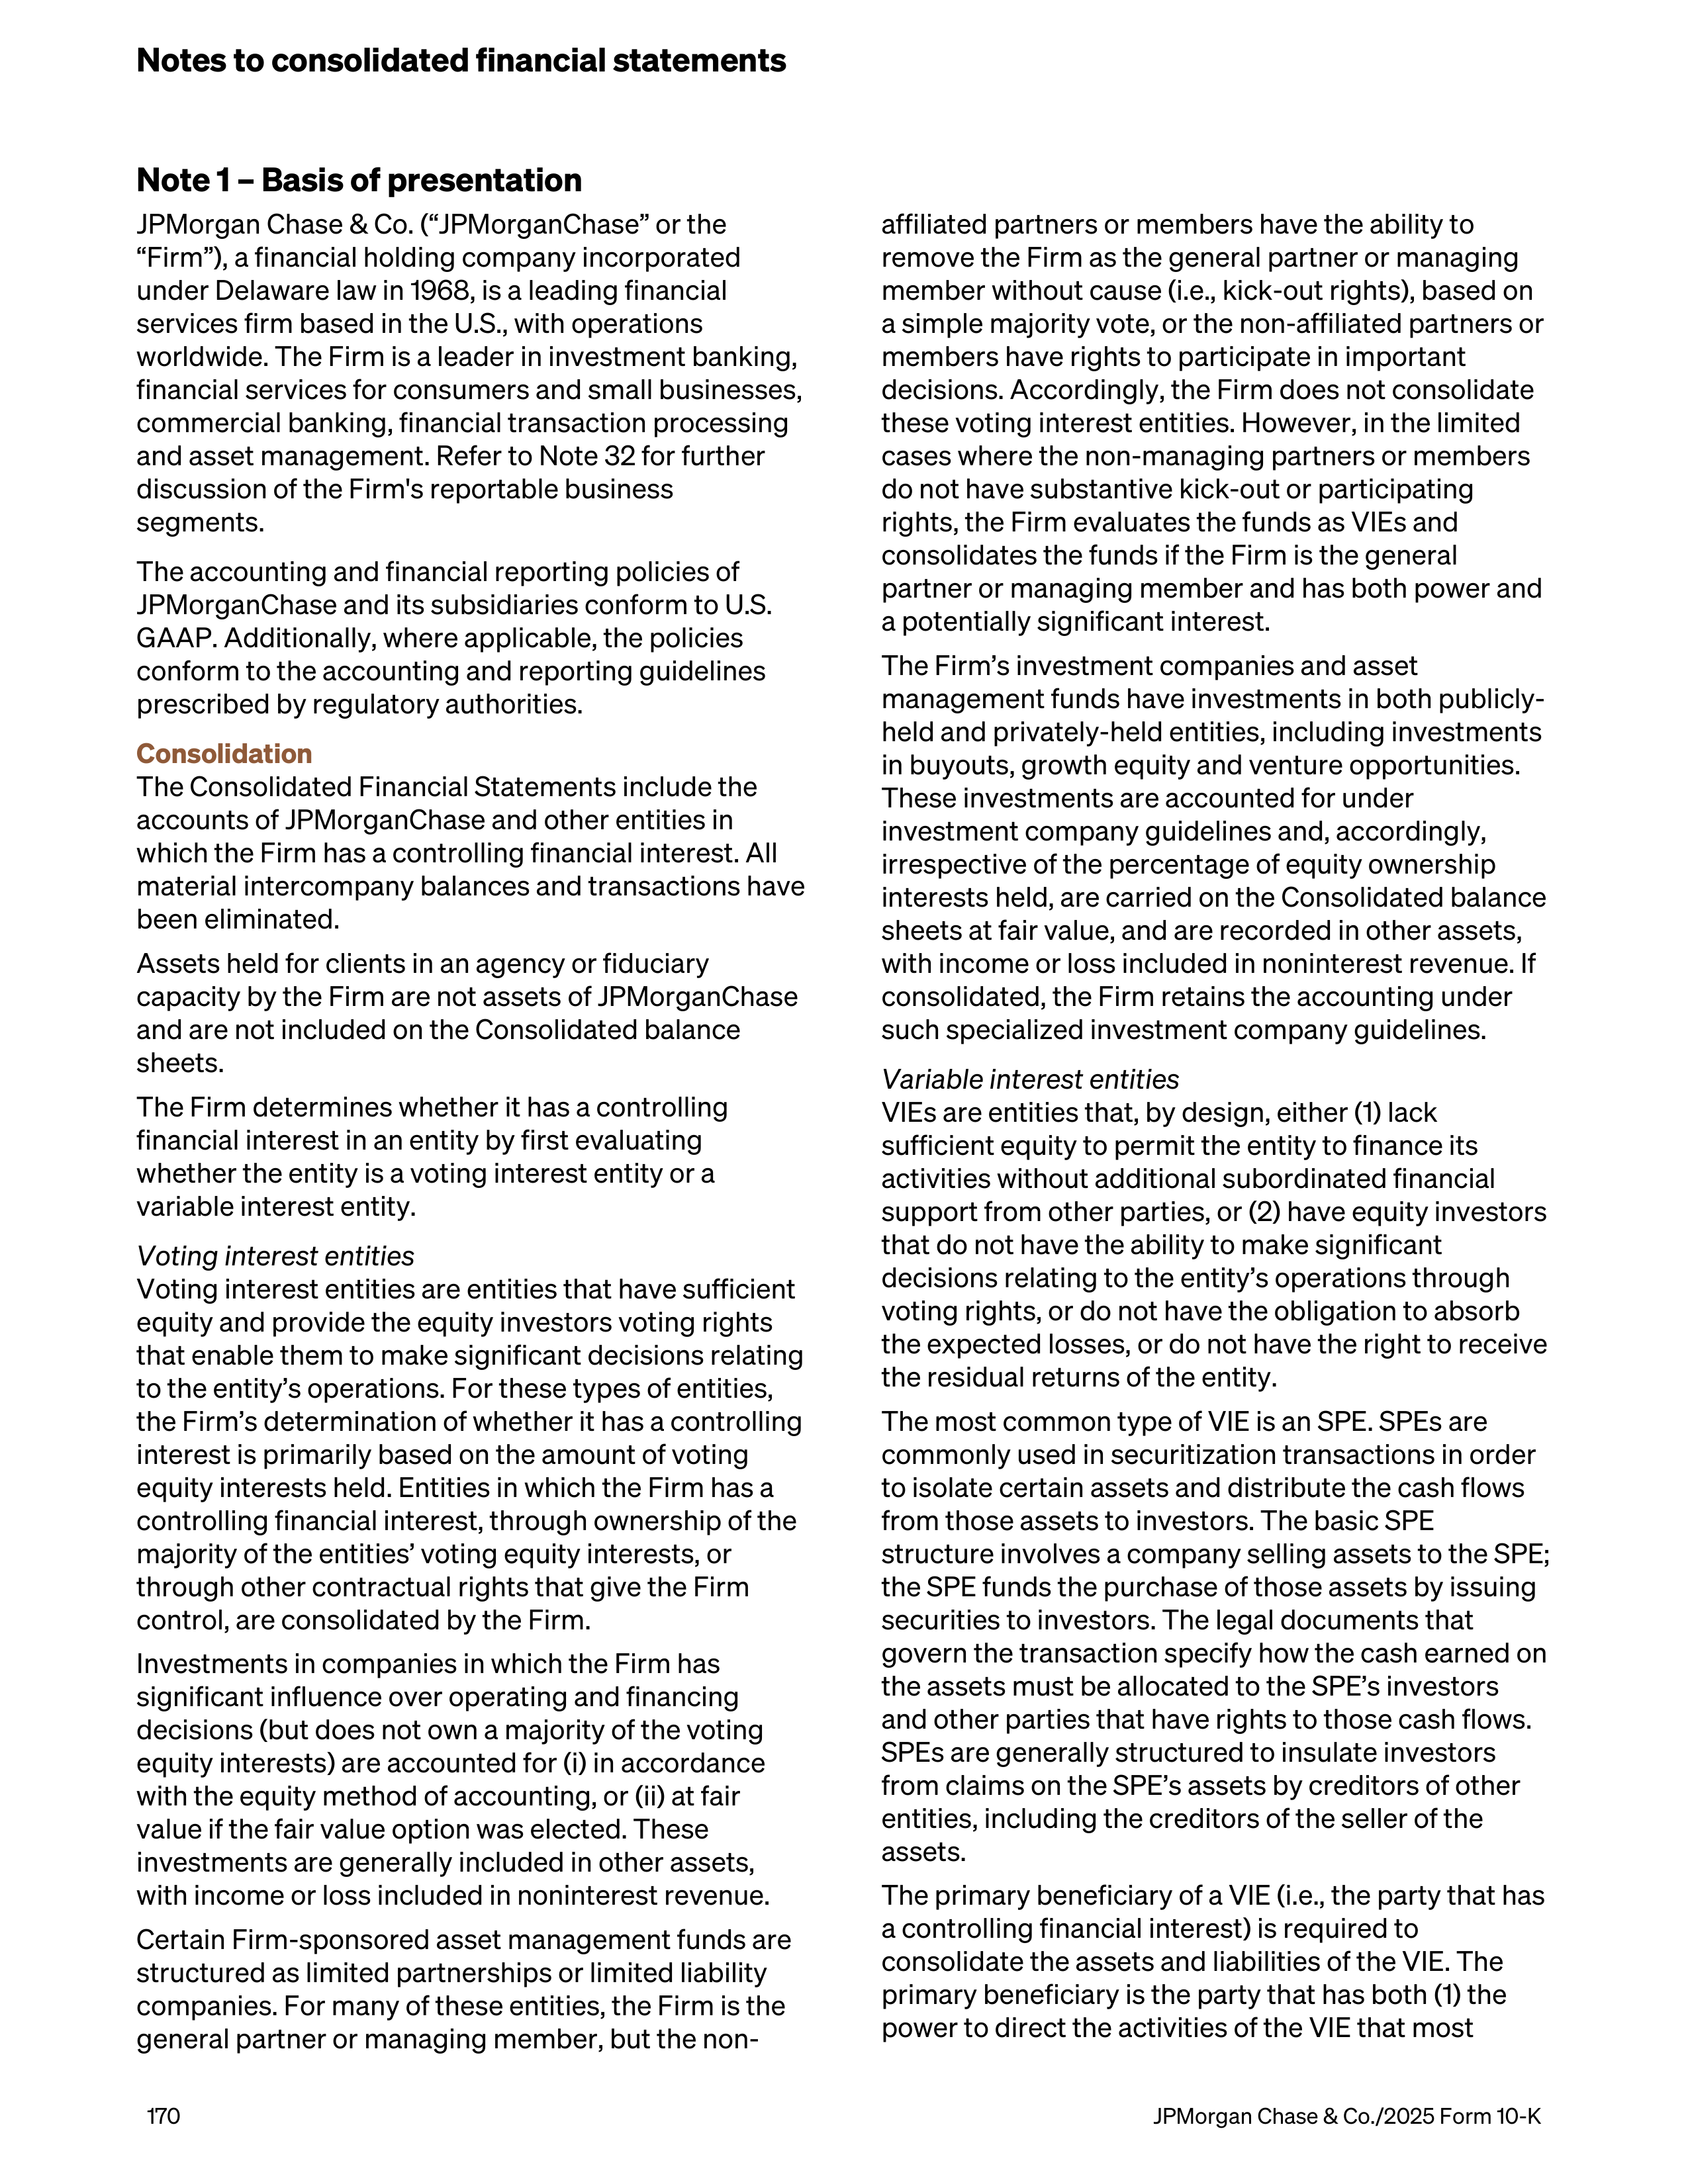
Note 1 – Basis of presentation
JPMorgan Chase & Co. (“JPMorganChase” or the
“Firm”), a financial holding company incorporated
under Delaware law in 1968, is a leading financial
services firm based in the U.S., with operations
worldwide. The Firm is a leader in investment banking,
financial services for consumers and small businesses,
commercial banking, financial transaction processing
and asset management. Refer to Note 32 for further
discussion of the Firm's reportable business
segments.
The accounting and financial reporting policies of
JPMorganChase and its subsidiaries conform to U.S.
GAAP. Additionally, where applicable, the policies
conform to the accounting and reporting guidelines
prescribed by regulatory authorities.
Consolidation
The Consolidated Financial Statements include the
accounts of JPMorganChase and other entities in
which the Firm has a controlling financial interest. All
material intercompany balances and transactions have
been eliminated.
Assets held for clients in an agency or fiduciary
capacity by the Firm are not assets of JPMorganChase
and are not included on the Consolidated balance
sheets.
The Firm determines whether it has a controlling
financial interest in an entity by first evaluating
whether the entity is a voting interest entity or a
variable interest entity.
Voting interest entities
Voting interest entities are entities that have sufficient
equity and provide the equity investors voting rights
that enable them to make significant decisions relating
to the entity’s operations. For these types of entities,
the Firm’s determination of whether it has a controlling
interest is primarily based on the amount of voting
equity interests held. Entities in which the Firm has a
controlling financial interest, through ownership of the
majority of the entities’ voting equity interests, or
through other contractual rights that give the Firm
control, are consolidated by the Firm.
Investments in companies in which the Firm has
significant influence over operating and financing
decisions (but does not own a majority of the voting
equity interests) are accounted for (i) in accordance
with the equity method of accounting, or (ii) at fair
value if the fair value option was elected. These
investments are generally included in other assets,
with income or loss included in noninterest revenue.
Certain Firm-sponsored asset management funds are
structured as limited partnerships or limited liability
companies. For many of these entities, the Firm is the
general partner or managing member, but the non-
affiliated partners or members have the ability to
remove the Firm as the general partner or managing
member without cause (i.e., kick-out rights), based on
a simple majority vote, or the non-affiliated partners or
members have rights to participate in important
decisions. Accordingly, the Firm does not consolidate
these voting interest entities. However, in the limited
cases where the non-managing partners or members
do not have substantive kick-out or participating
rights, the Firm evaluates the funds as VIEs and
consolidates the funds if the Firm is the general
partner or managing member and has both power and
a potentially significant interest.
The Firm’s investment companies and asset
management funds have investments in both publicly-
held and privately-held entities, including investments
in buyouts, growth equity and venture opportunities.
These investments are accounted for under
investment company guidelines and, accordingly,
irrespective of the percentage of equity ownership
interests held, are carried on the Consolidated balance
sheets at fair value, and are recorded in other assets,
with income or loss included in noninterest revenue. If
consolidated, the Firm retains the accounting under
such specialized investment company guidelines.
Variable interest entities
VIEs are entities that, by design, either (1) lack
sufficient equity to permit the entity to finance its
activities without additional subordinated financial
support from other parties, or (2) have equity investors
that do not have the ability to make significant
decisions relating to the entity’s operations through
voting rights, or do not have the obligation to absorb
the expected losses, or do not have the right to receive
the residual returns of the entity.
The most common type of VIE is an SPE. SPEs are
commonly used in securitization transactions in order
to isolate certain assets and distribute the cash flows
from those assets to investors. The basic SPE
structure involves a company selling assets to the SPE;
the SPE funds the purchase of those assets by issuing
securities to investors. The legal documents that
govern the transaction specify how the cash earned on
the assets must be allocated to the SPE’s investors
and other parties that have rights to those cash flows.
SPEs are generally structured to insulate investors
from claims on the SPE’s assets by creditors of other
entities, including the creditors of the seller of the
assets.
The primary beneficiary of a VIE (i.e., the party that has
a controlling financial interest) is required to
consolidate the assets and liabilities of the VIE. The
primary beneficiary is the party that has both (1) the
power to direct the activities of the VIE that most
Notes to consolidated financial statements
170
JPMorgan Chase & Co./2025 Form 10-K
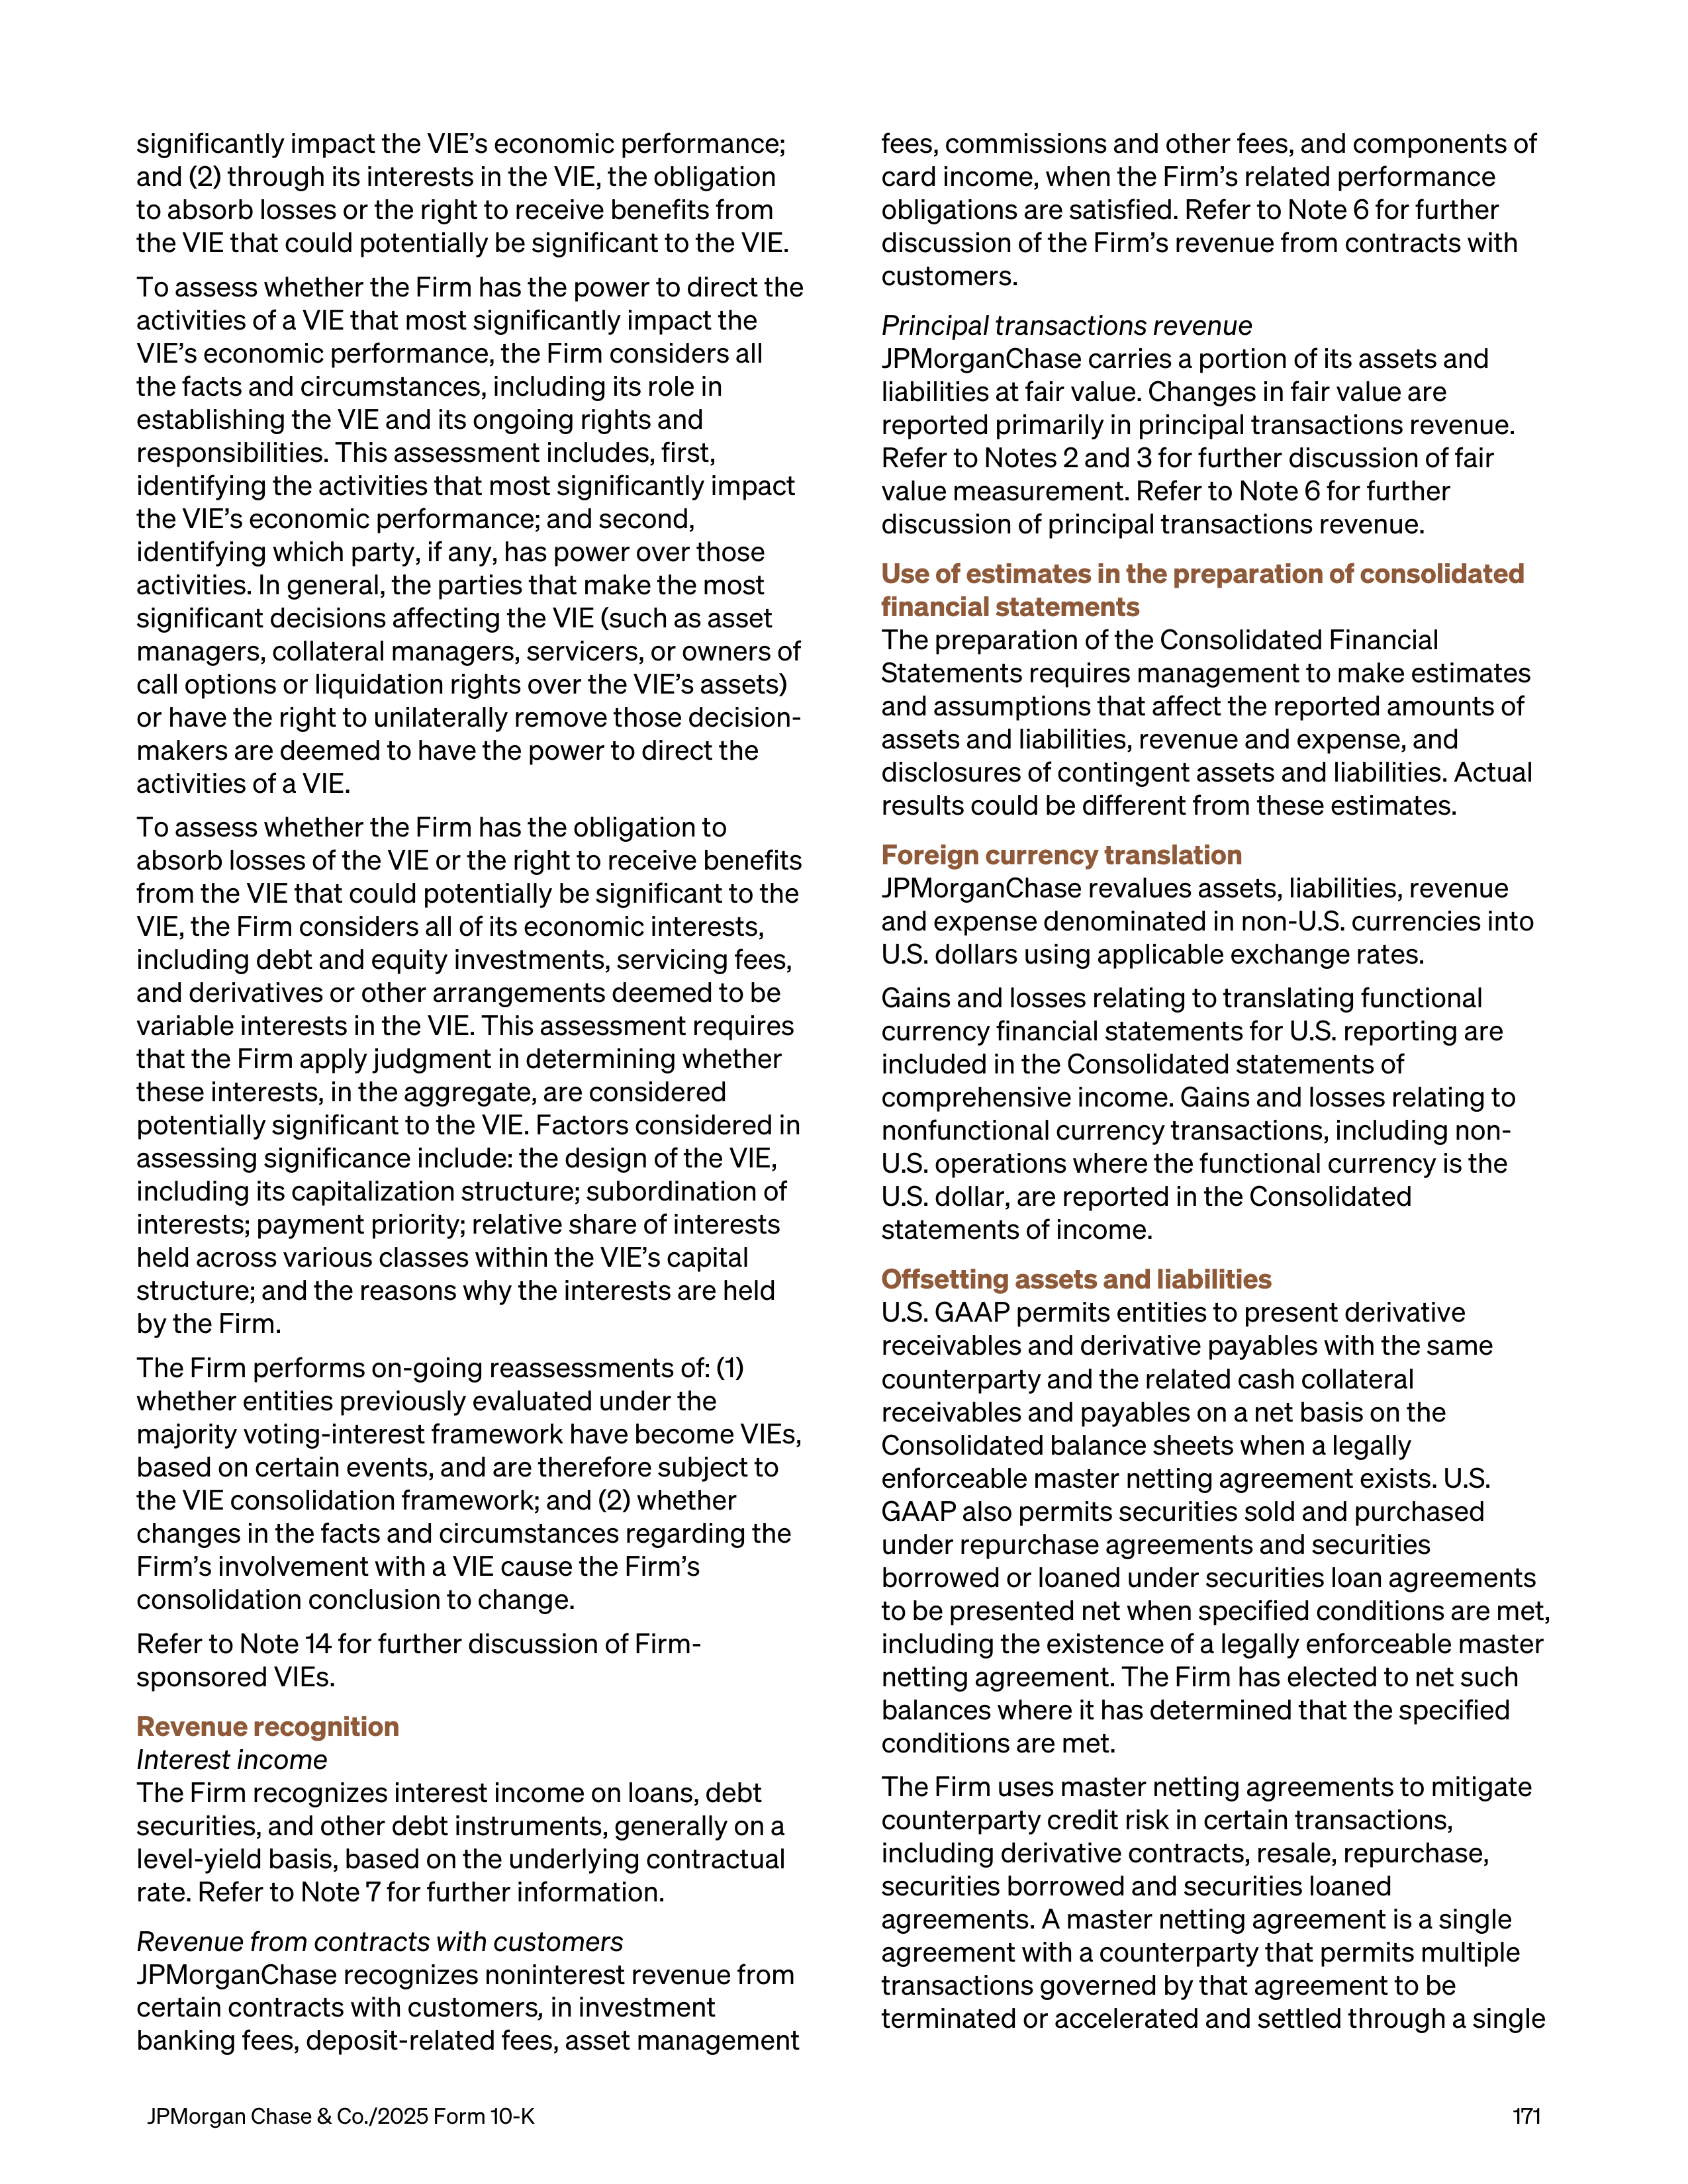
significantly impact the VIE’s economic performance;
and (2) through its interests in the VIE, the obligation
to absorb losses or the right to receive benefits from
the VIE that could potentially be significant to the VIE.
To assess whether the Firm has the power to direct the
activities of a VIE that most significantly impact the
VIE’s economic performance, the Firm considers all
the facts and circumstances, including its role in
establishing the VIE and its ongoing rights and
responsibilities. This assessment includes, first,
identifying the activities that most significantly impact
the VIE’s economic performance; and second,
identifying which party, if any, has power over those
activities. In general, the parties that make the most
significant decisions affecting the VIE (such as asset
managers, collateral managers, servicers, or owners of
call options or liquidation rights over the VIE’s assets)
or have the right to unilaterally remove those decision-
makers are deemed to have the power to direct the
activities of a VIE.
To assess whether the Firm has the obligation to
absorb losses of the VIE or the right to receive benefits
from the VIE that could potentially be significant to the
VIE, the Firm considers all of its economic interests,
including debt and equity investments, servicing fees,
and derivatives or other arrangements deemed to be
variable interests in the VIE. This assessment requires
that the Firm apply judgment in determining whether
these interests, in the aggregate, are considered
potentially significant to the VIE. Factors considered in
assessing significance include: the design of the VIE,
including its capitalization structure; subordination of
interests; payment priority; relative share of interests
held across various classes within the VIE’s capital
structure; and the reasons why the interests are held
by the Firm.
The Firm performs on-going reassessments of: (1)
whether entities previously evaluated under the
majority voting-interest framework have become VIEs,
based on certain events, and are therefore subject to
the VIE consolidation framework; and (2) whether
changes in the facts and circumstances regarding the
Firm’s involvement with a VIE cause the Firm’s
consolidation conclusion to change.
Refer to Note 14 for further discussion of Firm-
sponsored VIEs.
Revenue recognition
Interest income
The Firm recognizes interest income on loans, debt
securities, and other debt instruments, generally on a
level-yield basis, based on the underlying contractual
rate. Refer to Note 7 for further information.
Revenue from contracts with customers
JPMorganChase recognizes noninterest revenue from
certain contracts with customers
,
in investment
banking fees, deposit-related fees, asset management
fees, commissions and other fees, and components of
card income, when the Firm’s related performance
obligations are satisfied. Refer to Note 6 for further
discussion of the Firm’s revenue from contracts with
customers.
Principal transactions revenue
JPMorganChase carries a portion of its assets and
liabilities at fair value. Changes in fair value are
reported primarily in principal transactions revenue.
Refer to Notes 2 and 3 for further discussion of fair
value measurement. Refer to Note 6 for further
discussion of principal transactions revenue.
Use of estimates in the preparation of consolidated
financial statements
The preparation of the Consolidated Financial
Statements requires management to make estimates
and assumptions that affect the reported amounts of
assets and liabilities, revenue and expense, and
disclosures of contingent assets and liabilities. Actual
results could be different from these estimates.
Foreign currency translation
JPMorganChase revalues assets, liabilities, revenue
and expense denominated in non-U.S. currencies into
U.S. dollars using applicable exchange rates.
Gains and losses relating to translating functional
currency financial statements for U.S. reporting are
included in the Consolidated statements of
comprehensive income. Gains and losses relating to
nonfunctional currency transactions, including non-
U.S. operations where the functional currency is the
U.S. dollar, are reported in the Consolidated
statements of income.
Offsetting assets and liabilities
U.S. GAAP permits entities to present derivative
receivables and derivative payables with the same
counterparty and the related cash collateral
receivables and payables on a net basis on the
Consolidated balance sheets when a legally
enforceable master netting agreement exists. U.S.
GAAP also permits securities sold and purchased
under repurchase agreements and securities
borrowed or loaned under securities loan agreements
to be presented net when specified conditions are met,
including the existence of a legally enforceable master
netting agreement. The Firm has elected to net such
balances where it has determined that the specified
conditions are met.
The Firm uses master netting agreements to mitigate
counterparty credit risk in certain transactions,
including derivative contracts, resale, repurchase,
securities borrowed and securities loaned
agreements. A master netting agreement is a single
agreement with a counterparty that permits multiple
transactions governed by that agreement to be
terminated or accelerated and settled through a single
JPMorgan Chase & Co./2025 Form 10-K
171
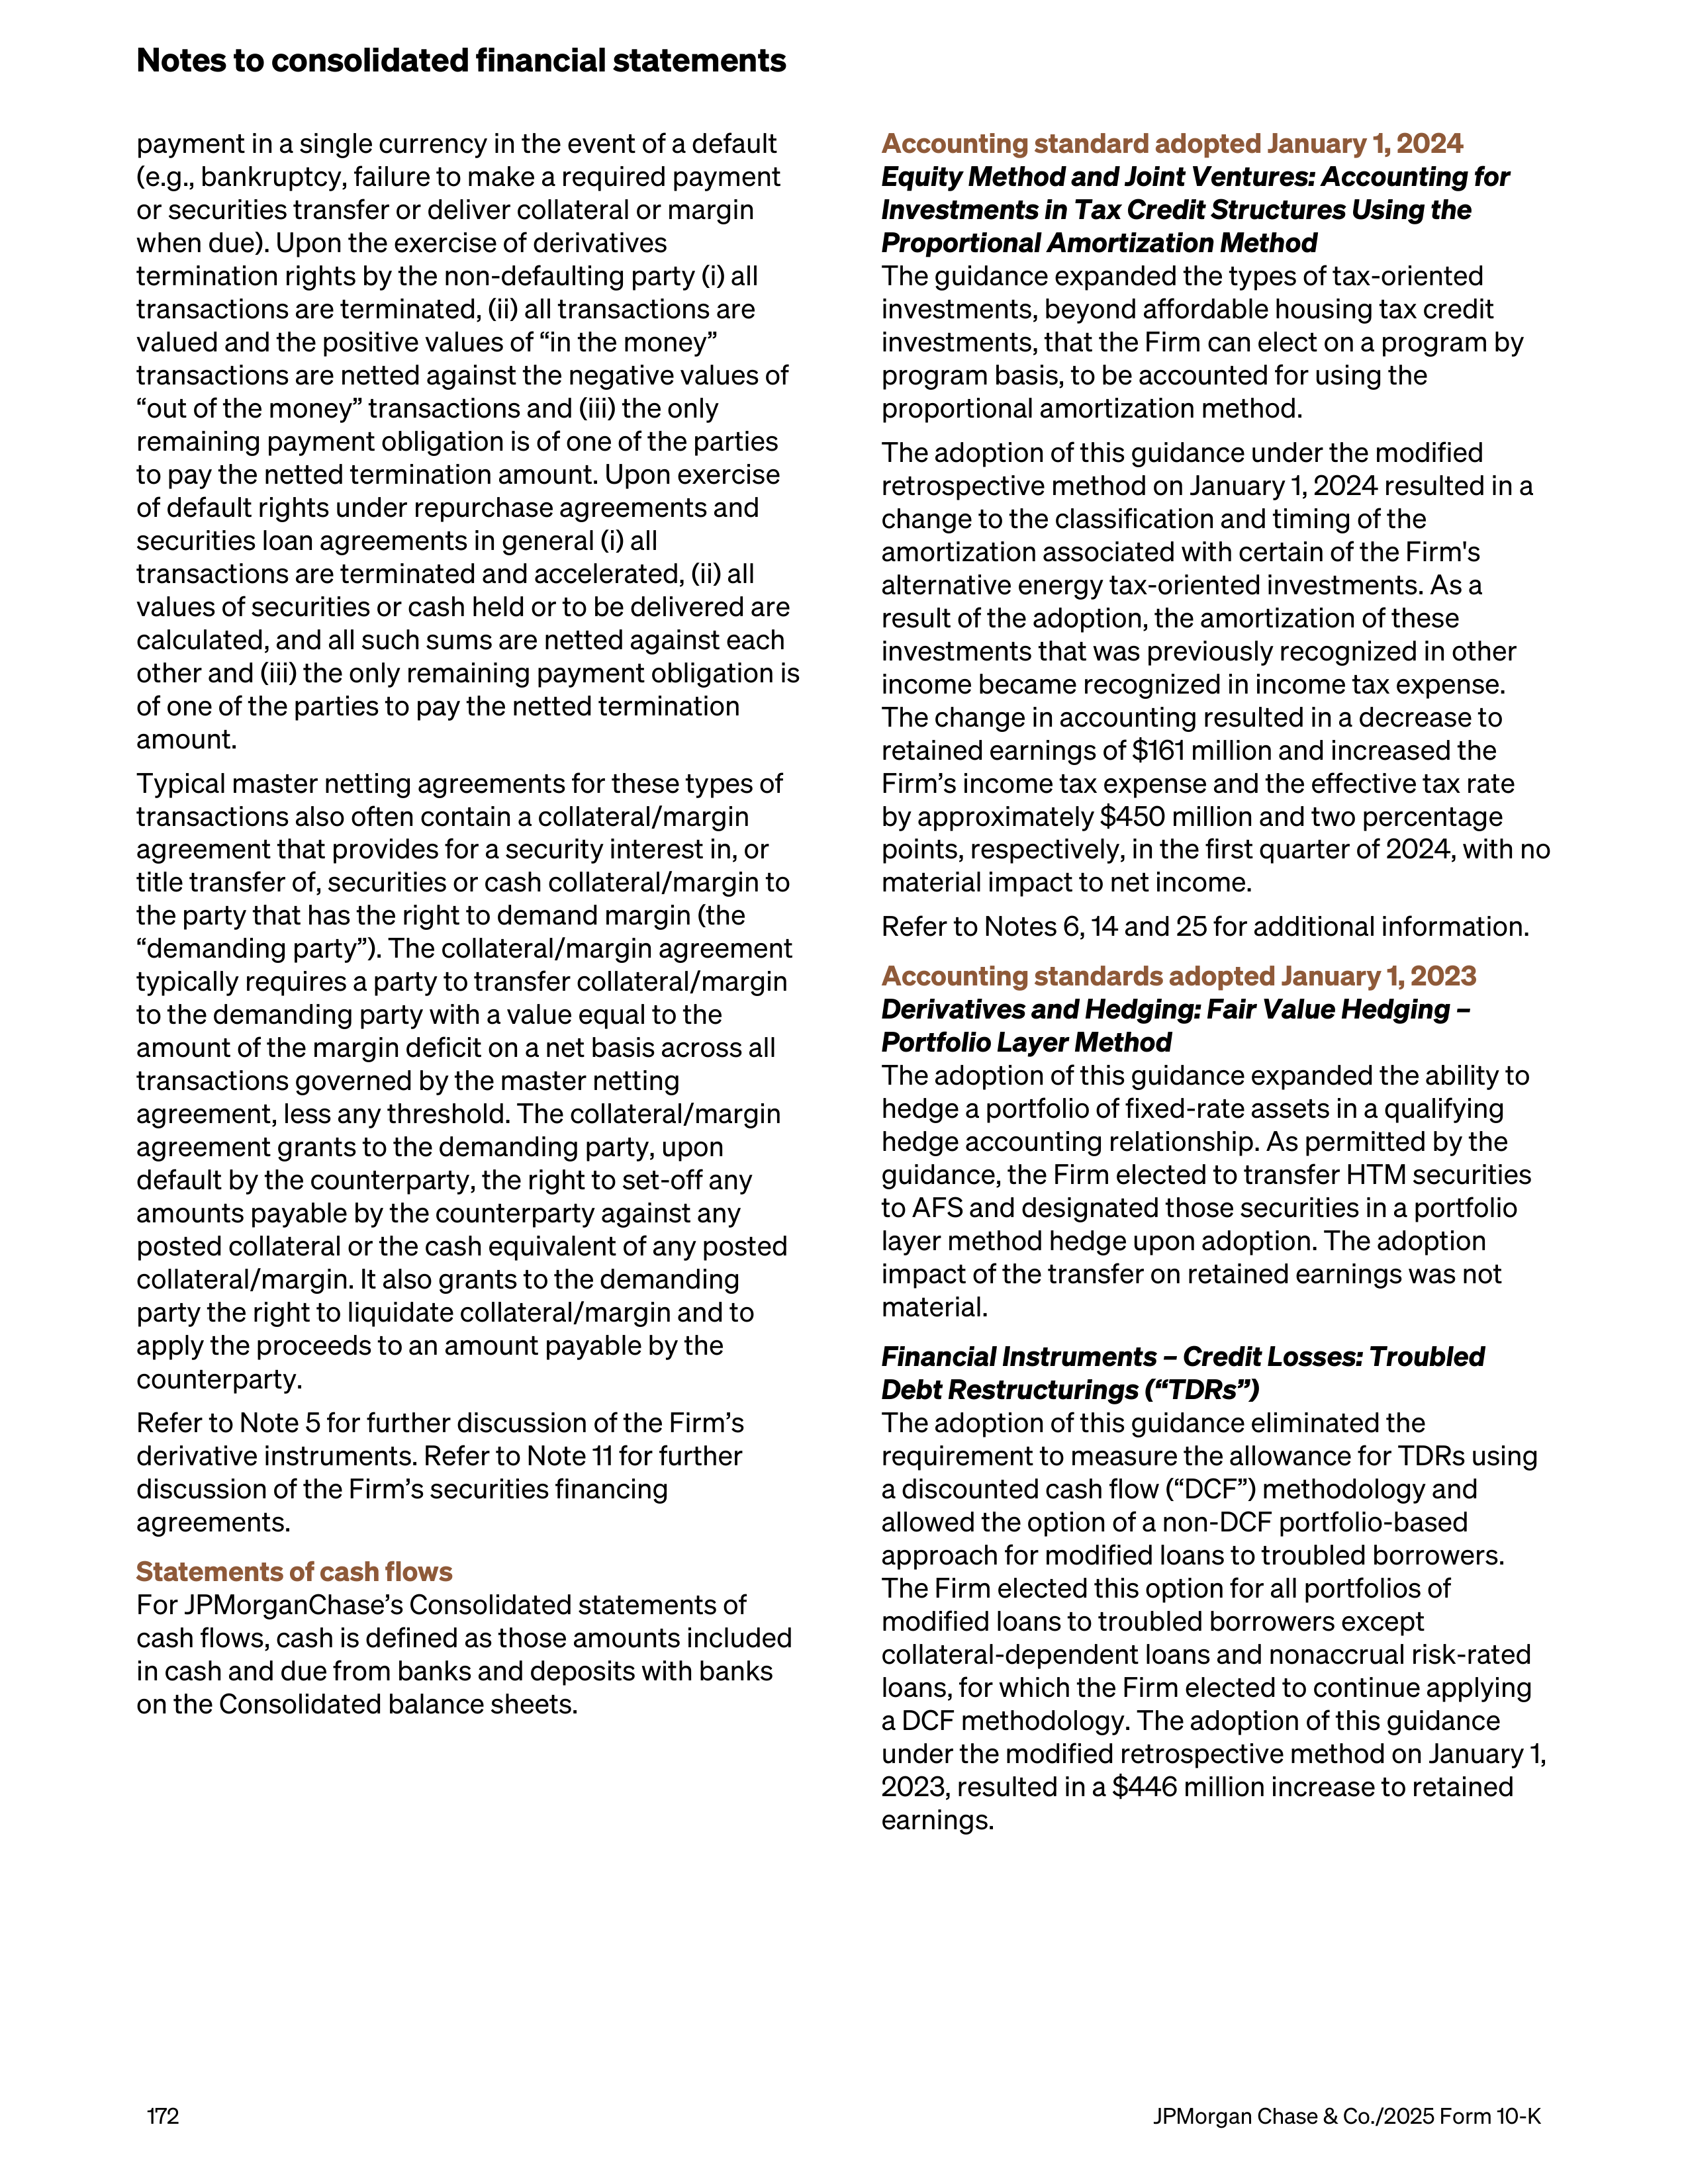
payment in a single currency in the event of a default
(e.g., bankruptcy, failure to make a required payment
or securities transfer or deliver collateral or margin
when due). Upon the exercise of derivatives
termination rights by the non-defaulting party (i) all
transactions are terminated, (ii) all transactions are
valued and the positive values of “in the money”
transactions are netted against the negative values of
“out of the money” transactions and (iii) the only
remaining payment obligation is of one of the parties
to pay the netted termination amount. Upon exercise
of default rights under repurchase agreements and
securities loan agreements in general (i) all
transactions are terminated and accelerated, (ii) all
values of securities or cash held or to be delivered are
calculated, and all such sums are netted against each
other and (iii) the only remaining payment obligation is
of one of the parties to pay the netted termination
amount.
Typical master netting agreements for these types of
transactions also often contain a collateral/margin
agreement that provides for a security interest in, or
title transfer of, securities or cash collateral/margin to
the party that has the right to demand margin (the
“demanding party”). The collateral/margin agreement
typically requires a party to transfer collateral/margin
to the demanding party with a value equal to the
amount of the margin deficit on a net basis across all
transactions governed by the master netting
agreement, less any threshold. The collateral/margin
agreement grants to the demanding party, upon
default by the counterparty, the right to set-off any
amounts payable by the counterparty against any
posted collateral or the cash equivalent of any posted
collateral/margin. It also grants to the demanding
party the right to liquidate collateral/margin and to
apply the proceeds to an amount payable by the
counterparty.
Refer to Note 5 for further discussion of the Firm’s
derivative instruments. Refer to Note 11 for further
discussion of the Firm’s securities financing
agreements.
Statements of cash flows
For JPMorganChase’s Consolidated statements of
cash flows, cash is defined as those amounts included
in cash and due from banks and deposits with banks
on the Consolidated balance sheets.
Accounting standard adopted January 1, 2024
Equity Method and Joint Ventures: Accounting for
Investments in Tax Credit Structures Using the
Proportional Amortization Method
The guidance expanded the types of tax-oriented
investments, beyond affordable housing tax credit
investments, that the Firm can elect on a program by
program basis, to be accounted for using the
proportional amortization method.
The adoption of this guidance under the modified
retrospective method on January 1, 2024 resulted in a
change to the classification and timing of the
amortization associated with certain of the Firm's
alternative energy tax-oriented investments. As a
result of the adoption, the amortization of these
investments that was previously recognized in other
income became recognized in income tax expense.
The change in accounting resulted in a decrease to
retained earnings of $161 million and increased the
Firm’s income tax expense and the effective tax rate
by approximately $450 million and two percentage
points, respectively, in the first quarter of 2024, with no
material impact to net income.
Refer to Notes 6, 14 and 25 for additional information.
Accounting standards adopted January 1, 2023
Derivatives and Hedging: Fair Value Hedging –
Portfolio Layer Method
The adoption of this guidance expanded the ability to
hedge a portfolio of fixed-rate assets in a qualifying
hedge accounting relationship. As permitted by the
guidance, the Firm elected to transfer HTM securities
to AFS and designated those securities in a portfolio
layer method hedge upon adoption. The adoption
impact of the transfer on retained earnings was not
material.
Financial Instruments – Credit Losses: Troubled
Debt Restructurings (“TDRs”)
The adoption of this guidance eliminated the
requirement to measure the allowance for TDRs using
a discounted cash flow (“DCF”) methodology and
allowed the option of a non-DCF portfolio-based
approach for modified loans to troubled borrowers.
The Firm elected this option for all portfolios of
modified loans to troubled borrowers except
collateral-dependent loans and nonaccrual risk-rated
loans, for which the Firm elected to continue applying
a DCF methodology. The adoption of this guidance
under the modified retrospective method on January 1,
2023, resulted in a $446 million increase to retained
earnings.
Notes to consolidated financial statements
172
JPMorgan Chase & Co./2025 Form 10-K
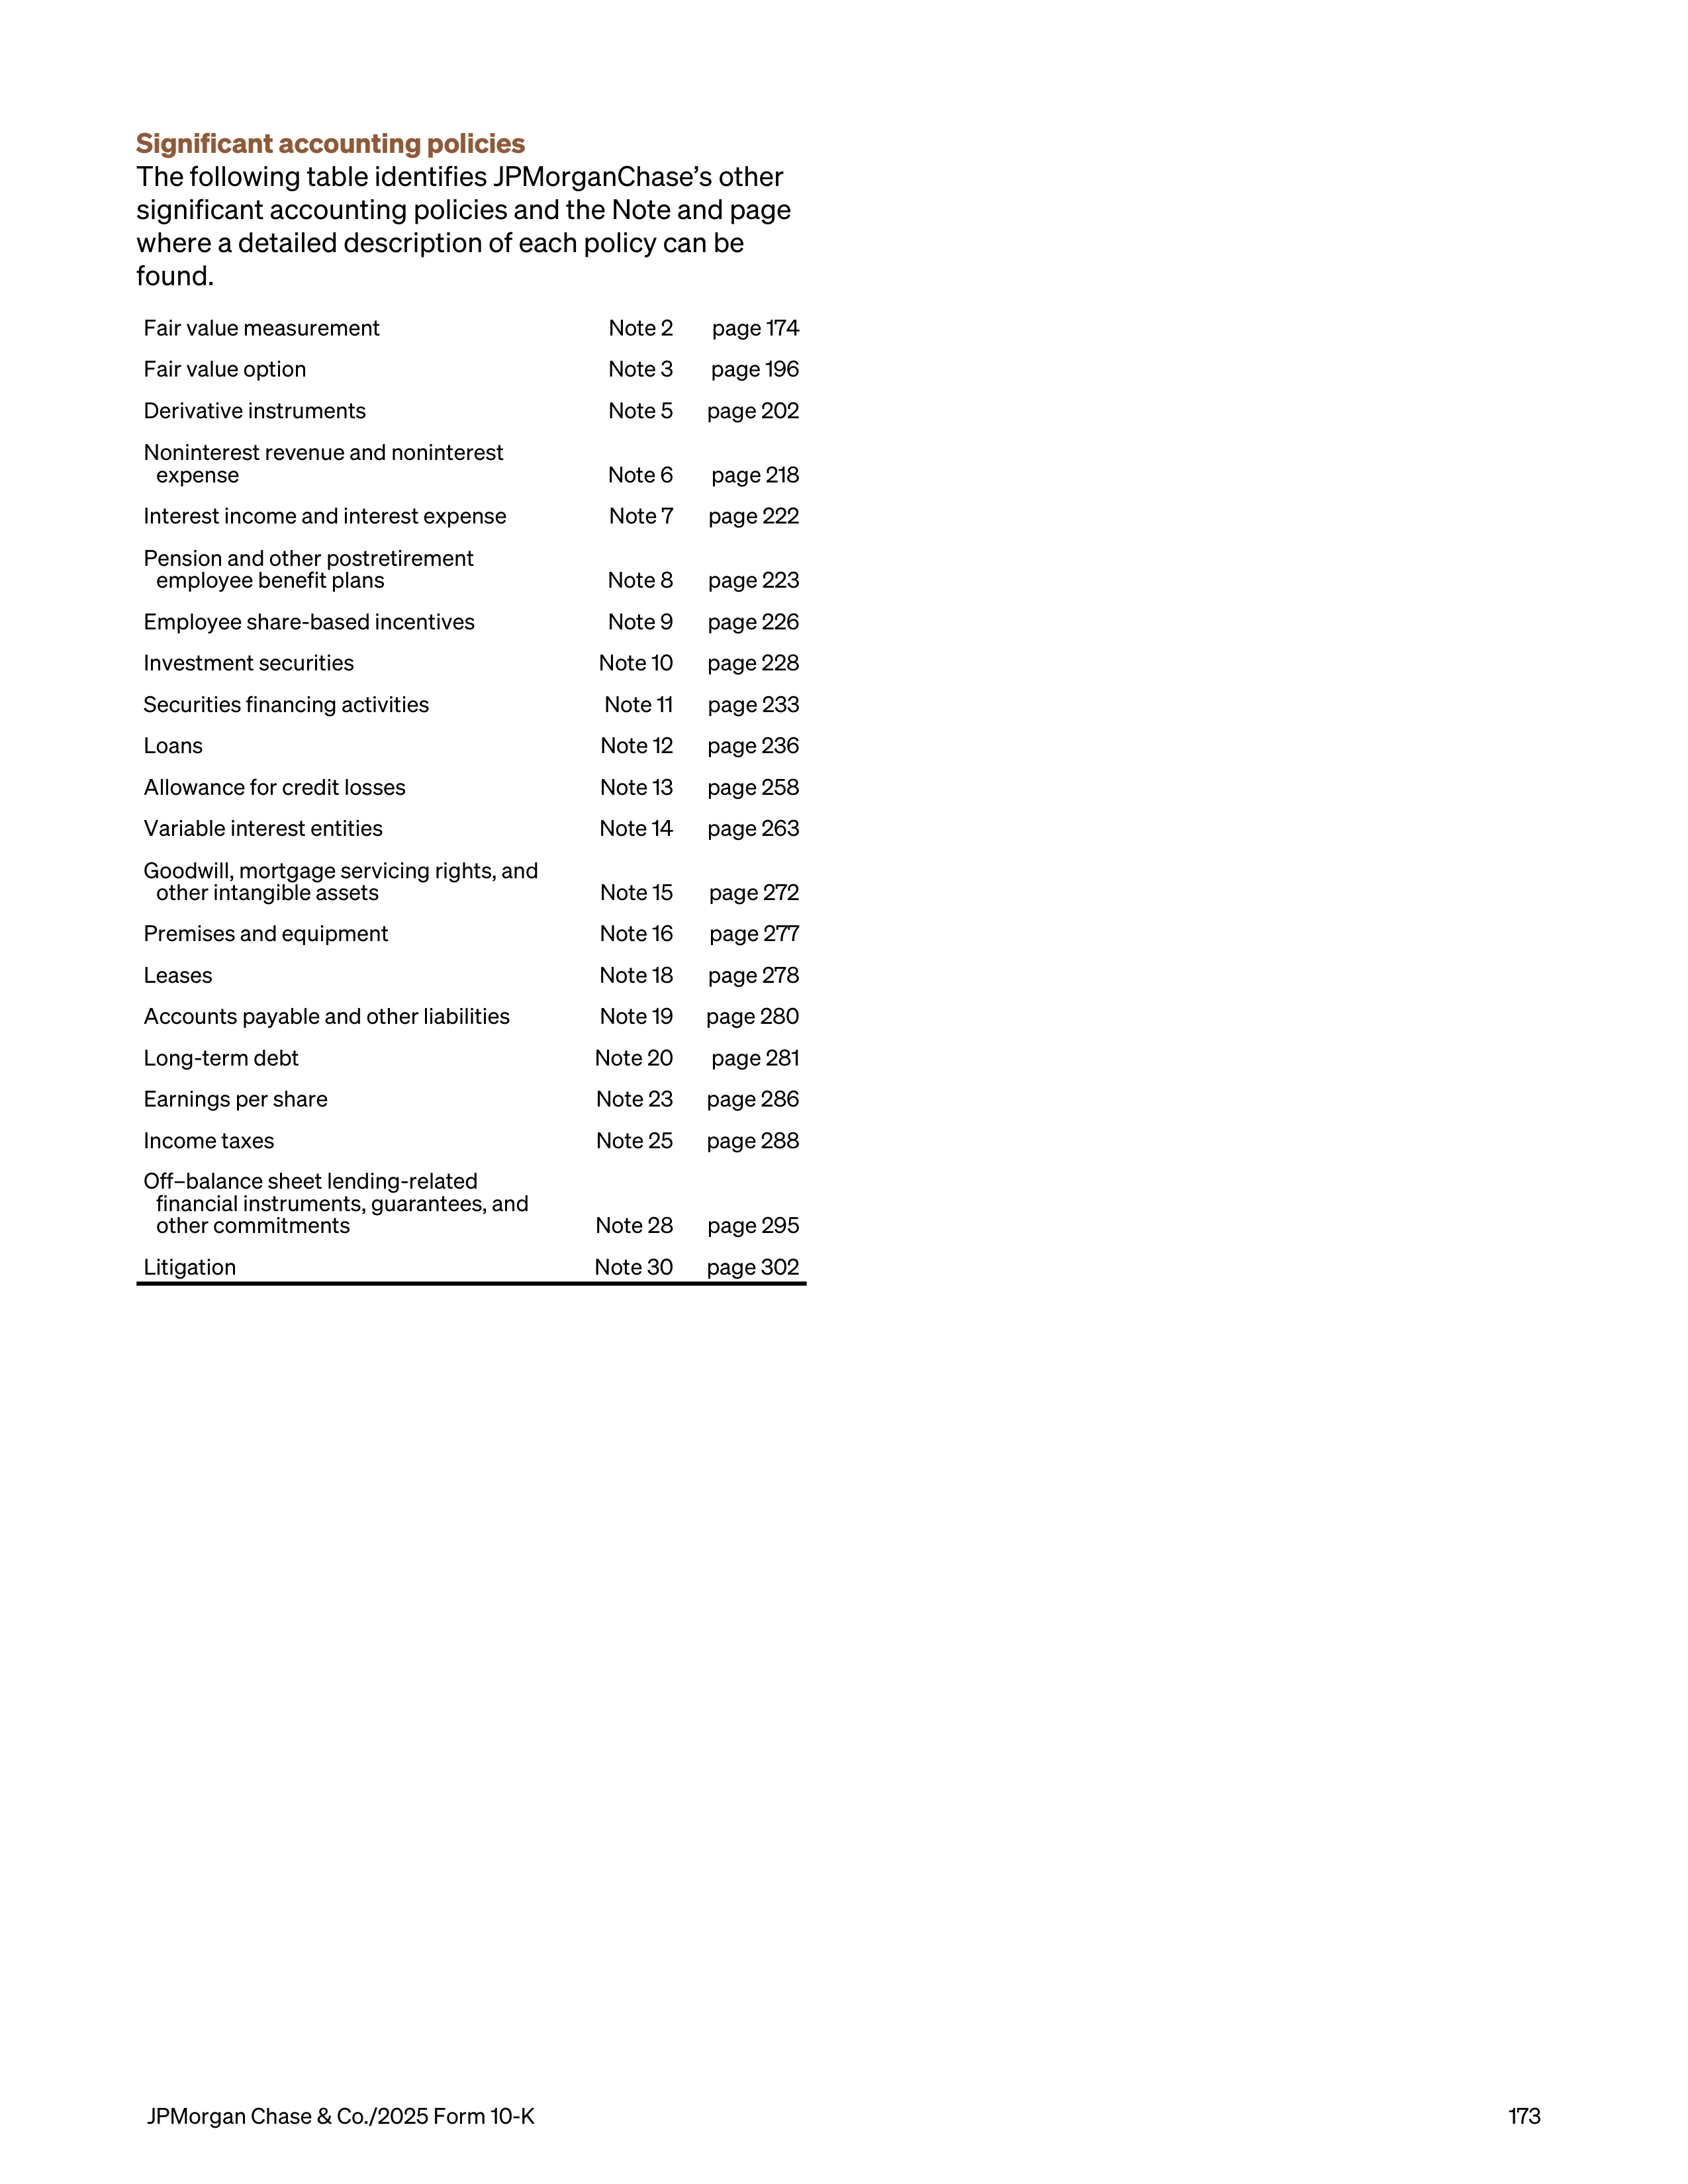
Significant accounting policies
The following table identifies JPMorganChase’s other
significant accounting policies and the Note and page
where a detailed description of each policy can be
found.
Fair value measurement
Note 2
page 174
Fair value option
Note 3
page 196
Derivative instruments
Note 5
page 202
Noninterest revenue and noninterest
expense
Note 6
page 218
Interest income and interest expense
Note 7
page 222
Pension and other postretirement
employee benefit plans
Note 8
page 223
Employee share-based incentives
Note 9
page 226
Investment securities
Note 10
page 228
Securities financing activities
Note 11
page 233
Loans
Note 12
page 236
Allowance for credit losses
Note 13
page 258
Variable interest entities
Note 14
page 263
Goodwill, mortgage servicing rights, and
other intangible assets
Note 15
page 272
Premises and equipment
Note 16
page 277
Leases
Note 18
page 278
Accounts payable and other liabilities
Note 19
page 280
Long-term debt
Note 20
page 281
Earnings per share
Note 23
page 286
Income taxes
Note 25
page 288
Off–balance sheet lending-related
financial instruments, guarantees, and
other commitments
Note 28
page 295
Litigation
Note 30
page 302
JPMorgan Chase & Co./2025 Form 10-K
173
Note 2 – Fair value measurement
JPMorganChase carries a portion of its assets and
liabilities at fair value. These assets and liabilities are
predominantly carried at fair value on a recurring basis
(i.e., assets and liabilities that are measured and
reported at fair value on the Firm’s Consolidated
balance sheets). Certain assets, liabilities and unfunded
lending-related commitments are measured at fair
value on a nonrecurring basis; that is, they are not
measured at fair value on an ongoing basis but are
subject to fair value adjustments only in certain
circumstances (for example, when there is evidence of
impairment).
Fair value is defined as the price that would be received
to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the
measurement date. Fair value is based on quoted
market prices or inputs, where available. If prices or
quotes are not available, fair value is based on valuation
models and other valuation techniques that consider
relevant transaction characteristics (such as maturity)
and use, as inputs, observable or unobservable market
parameters, including yield curves, interest rates,
volatilities, prices (such as commodity, equity or debt
prices), correlations, foreign exchange rates and credit
curves. Fair value may also incorporate valuation
adjustments.
The level of precision in estimating unobservable
market inputs or other factors can affect the amount of
gain or loss recorded for a particular position.
Furthermore, while the Firm believes its valuation
methods are appropriate and consistent with those of
other market participants, the methods and
assumptions used reflect management judgment and
may vary across the Firm’s businesses and portfolios.
The Firm uses various methodologies and assumptions
in the determination of fair value. The use of different
methodologies or assumptions by other market
participants compared with those used by the Firm
could result in the Firm deriving a different estimate of
fair value at the reporting date.
Valuation process
Risk-taking functions are responsible for providing fair
value estimates for assets and liabilities carried on the
Consolidated balance sheets at fair value. The Firm’s
Valuation Control Group (“VCG”), which is part of the
Firm’s Finance function and independent of the risk-
taking functions, is responsible for verifying these
estimates and determining any fair value adjustments
that may be required to ensure that the Firm’s positions
are recorded at fair value. In addition, the Firm’s
Valuation Governance Forum (“VGF”), which is
composed of senior finance and risk executives, is
responsible for overseeing the management of risks
arising from valuation activities conducted across the
Firm. The Firmwide VGF is chaired by the Firmwide
head of the VCG (under the direction of the Firm’s
Controller), and includes sub-forums covering the CIB,
CCB, AWM and certain corporate functions including
Treasury and CIO.
Price verification process
The VCG verifies fair value estimates provided by the
risk-taking functions by leveraging independently
derived prices, valuation inputs and other market data,
where available. Where independent prices or inputs
are not available, the VCG performs additional review to
ensure the reasonableness of the estimates. The
additional review may include evaluating the limited
market activity including client unwinds, benchmarking
valuation inputs to those used for similar instruments,
decomposing the valuation of structured instruments
into individual components, comparing expected to
actual cash flows, reviewing profit and loss trends, and
reviewing trends in collateral valuation. There are also
additional levels of management review for more
significant or complex positions.
The VCG determines any valuation adjustments that
may be required to the estimates provided by the risk-
taking functions. No adjustments to quoted prices are
applied for instruments classified within level 1 of the
fair value hierarchy (refer to the discussion of the fair
value hierarchy on
page 175
for further information). For
other positions, judgment is required to assess the
need for valuation adjustments to appropriately reflect
liquidity considerations, unobservable parameters, and,
for certain portfolios that meet specified criteria, the
size of the net open risk position. The determination of
such adjustments follows a consistent framework
across the Firm:
•
Liquidity valuation adjustments are considered where
an observable external price or valuation parameter
exists but is of lower reliability, potentially due to
lower market activity. Liquidity valuation adjustments
are made based on current market conditions.
Factors that may be considered in determining the
liquidity adjustment include analysis of: (1) the
estimated bid-offer spread for the instrument being
traded; (2) alternative pricing points for similar
instruments in active markets; and (3) the range of
reasonable values that the price or parameter could
take.
•
The Firm manages certain portfolios of financial
instruments on the basis of net open risk exposure
and, as permitted by U.S. GAAP, has elected to
estimate the fair value of such portfolios on the basis
of a transfer of the entire net open risk position in an
orderly transaction. Where this is the case, valuation
adjustments may be necessary to reflect the cost of
exiting a larger-than-normal market-size net open
risk position. Where applied, such adjustments are
based on factors that a relevant market participant
Notes to consolidated financial statements
174
JPMorgan Chase & Co./2025 Form 10-K
would consider in the transfer of the net open risk
position, including the size of the adverse market
move that is likely to occur during the period required
to sufficiently reduce the net open risk position.
•
Uncertainty adjustments related to unobservable
parameters may be made when positions are valued
using prices or input parameters to valuation models
that are unobservable due to a lack of market activity
or because they cannot be implied from observable
market data. Such prices or parameters must be
estimated and are, therefore, subject to management
judgment. Adjustments are made to reflect the
uncertainty inherent in the resulting valuation
estimate.
•
Where appropriate, the Firm also applies adjustments
to its estimates of fair value in order to appropriately
reflect counterparty credit quality (CVA), the Firm’s
own creditworthiness (DVA) and the impact of
funding (FVA), using a consistent framework across
the Firm. Refer to Credit and funding adjustments on
page 191 of this Note for more information on such
adjustments.
Valuation model review and approval
If prices or quotes are not available for an instrument or
a similar instrument, fair value is generally determined
using valuation models that consider relevant
transaction terms such as maturity and use as inputs
market-based or independently sourced parameters.
Where this is the case the price verification process
described above is applied to the inputs in those
models.
Under the Firm’s Estimations and Model Risk
Management Policy, MRGR reviews and approves new
models, as well as material changes to existing models,
prior to implementation in the operating environment.
In certain circumstances exceptions may be granted to
the Firm’s policy to allow a model to be used prior to
review or approval. MRGR may also require the user to
take appropriate actions to mitigate the model risk if it
is to be used in the interim. These actions will depend
on the model and may include, for example, limitation of
trading activity.
Fair value hierarchy
A three-level fair value hierarchy has been established
under U.S. GAAP for disclosure of fair value
measurements. The fair value hierarchy is based on the
observability of inputs to the valuation of an asset or
liability as of the measurement date. The three levels
are defined as follows.
•
Level 1 – inputs to the valuation methodology are
quoted prices (unadjusted) for identical assets or
liabilities in active markets.
•
Level 2 – inputs to the valuation methodology include
quoted prices for similar assets and liabilities in active
markets, and inputs that are observable for the asset
or liability, either directly or indirectly, for
substantially the full term of the financial instrument.
•
Level 3 – one or more inputs to the valuation
methodology are unobservable and significant to the
fair value measurement.
A financial instrument’s categorization within the fair
value hierarchy is based on the lowest level of input that
is significant to the fair value measurement.
JPMorgan Chase & Co./2025 Form 10-K
175
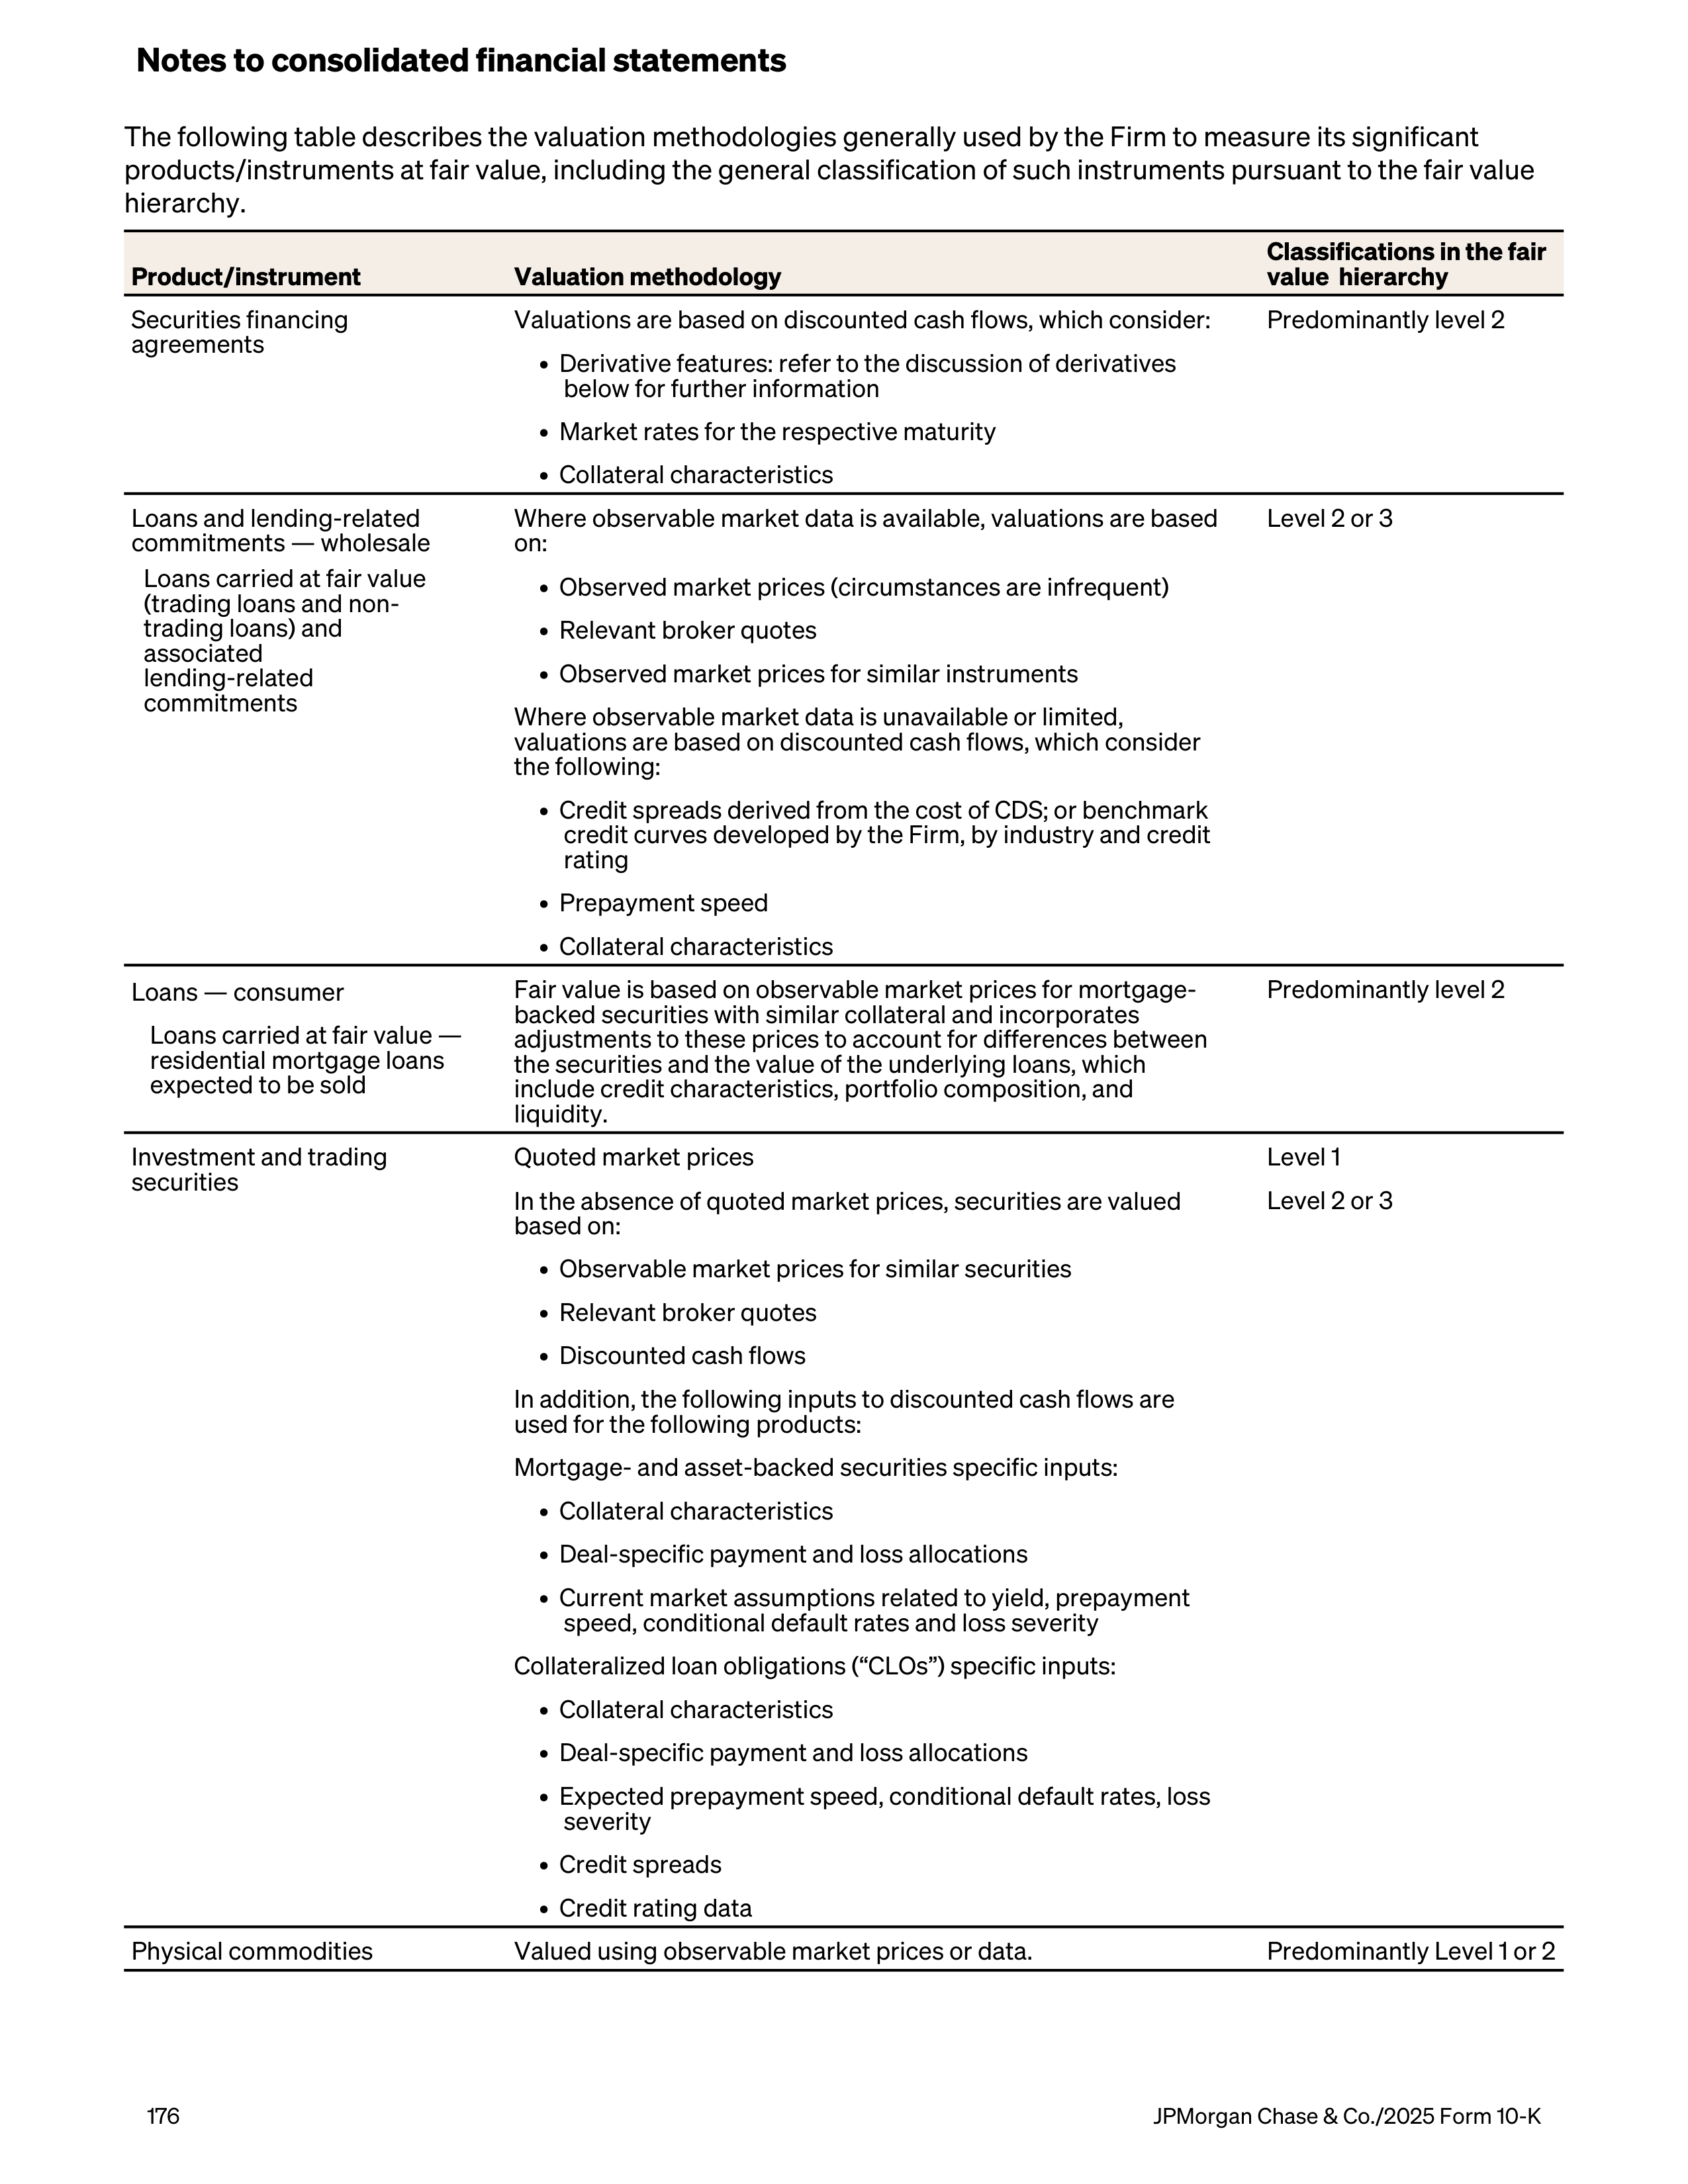
The following table describes the valuation methodologies generally used by the Firm to measure its significant
products/instruments at fair value, including the general classification of such instruments pursuant to the fair value
hierarchy.
Product/instrument
Valuation methodology
Classifications in the fair
value hierarchy
Securities financing
agreements
Valuations are based on discounted cash flows, which consider:
Predominantly level 2
• Derivative features: refer to the discussion of derivatives
below for further information
• Market rates for the respective maturity
• Collateral characteristics
Loans and lending-related
commitments — wholesale
Loans carried at fair value
(trading loans and non-
trading loans) and
associated
lending-related
commitments
Where observable market data is available, valuations are based
on:
Level 2 or 3
• Observed market prices (circumstances are infrequent)
• Relevant broker quotes
• Observed market prices for similar instruments
Where observable market data is unavailable or limited,
valuations are based on discounted cash flows, which consider
the following:
• Credit spreads derived from the cost of CDS; or benchmark
credit curves developed by the Firm, by industry and credit
rating
• Prepayment speed
• Collateral characteristics
Loans — consumer
Fair value is based on observable market prices for mortgage-
backed securities with similar collateral and incorporates
adjustments to these prices to account for differences between
the securities and the value of the underlying loans, which
include credit characteristics, portfolio composition, and
liquidity.
Predominantly level 2
Loans carried at fair value —
residential mortgage loans
expected to be sold
Investment and trading
securities
Quoted market prices
Level 1
In the absence of quoted market prices, securities are valued
based on:
Level 2 or 3
• Observable market prices for similar securities
• Relevant broker quotes
• Discounted cash flows
In addition, the following inputs to discounted cash flows are
used for the following products:
Mortgage- and asset-backed securities specific inputs:
• Collateral characteristics
• Deal-specific payment and loss allocations
• Current market assumptions related to yield, prepayment
speed, conditional default rates and loss severity
Collateralized loan obligations (“CLOs”) specific inputs:
• Collateral characteristics
• Deal-specific payment and loss allocations
• Expected prepayment speed, conditional default rates, loss
severity
• Credit spreads
• Credit rating data
Physical commodities
Valued using observable market prices or data.
Predominantly Level 1 or 2
Notes to consolidated financial statements
176
JPMorgan Chase & Co./2025 Form 10-K
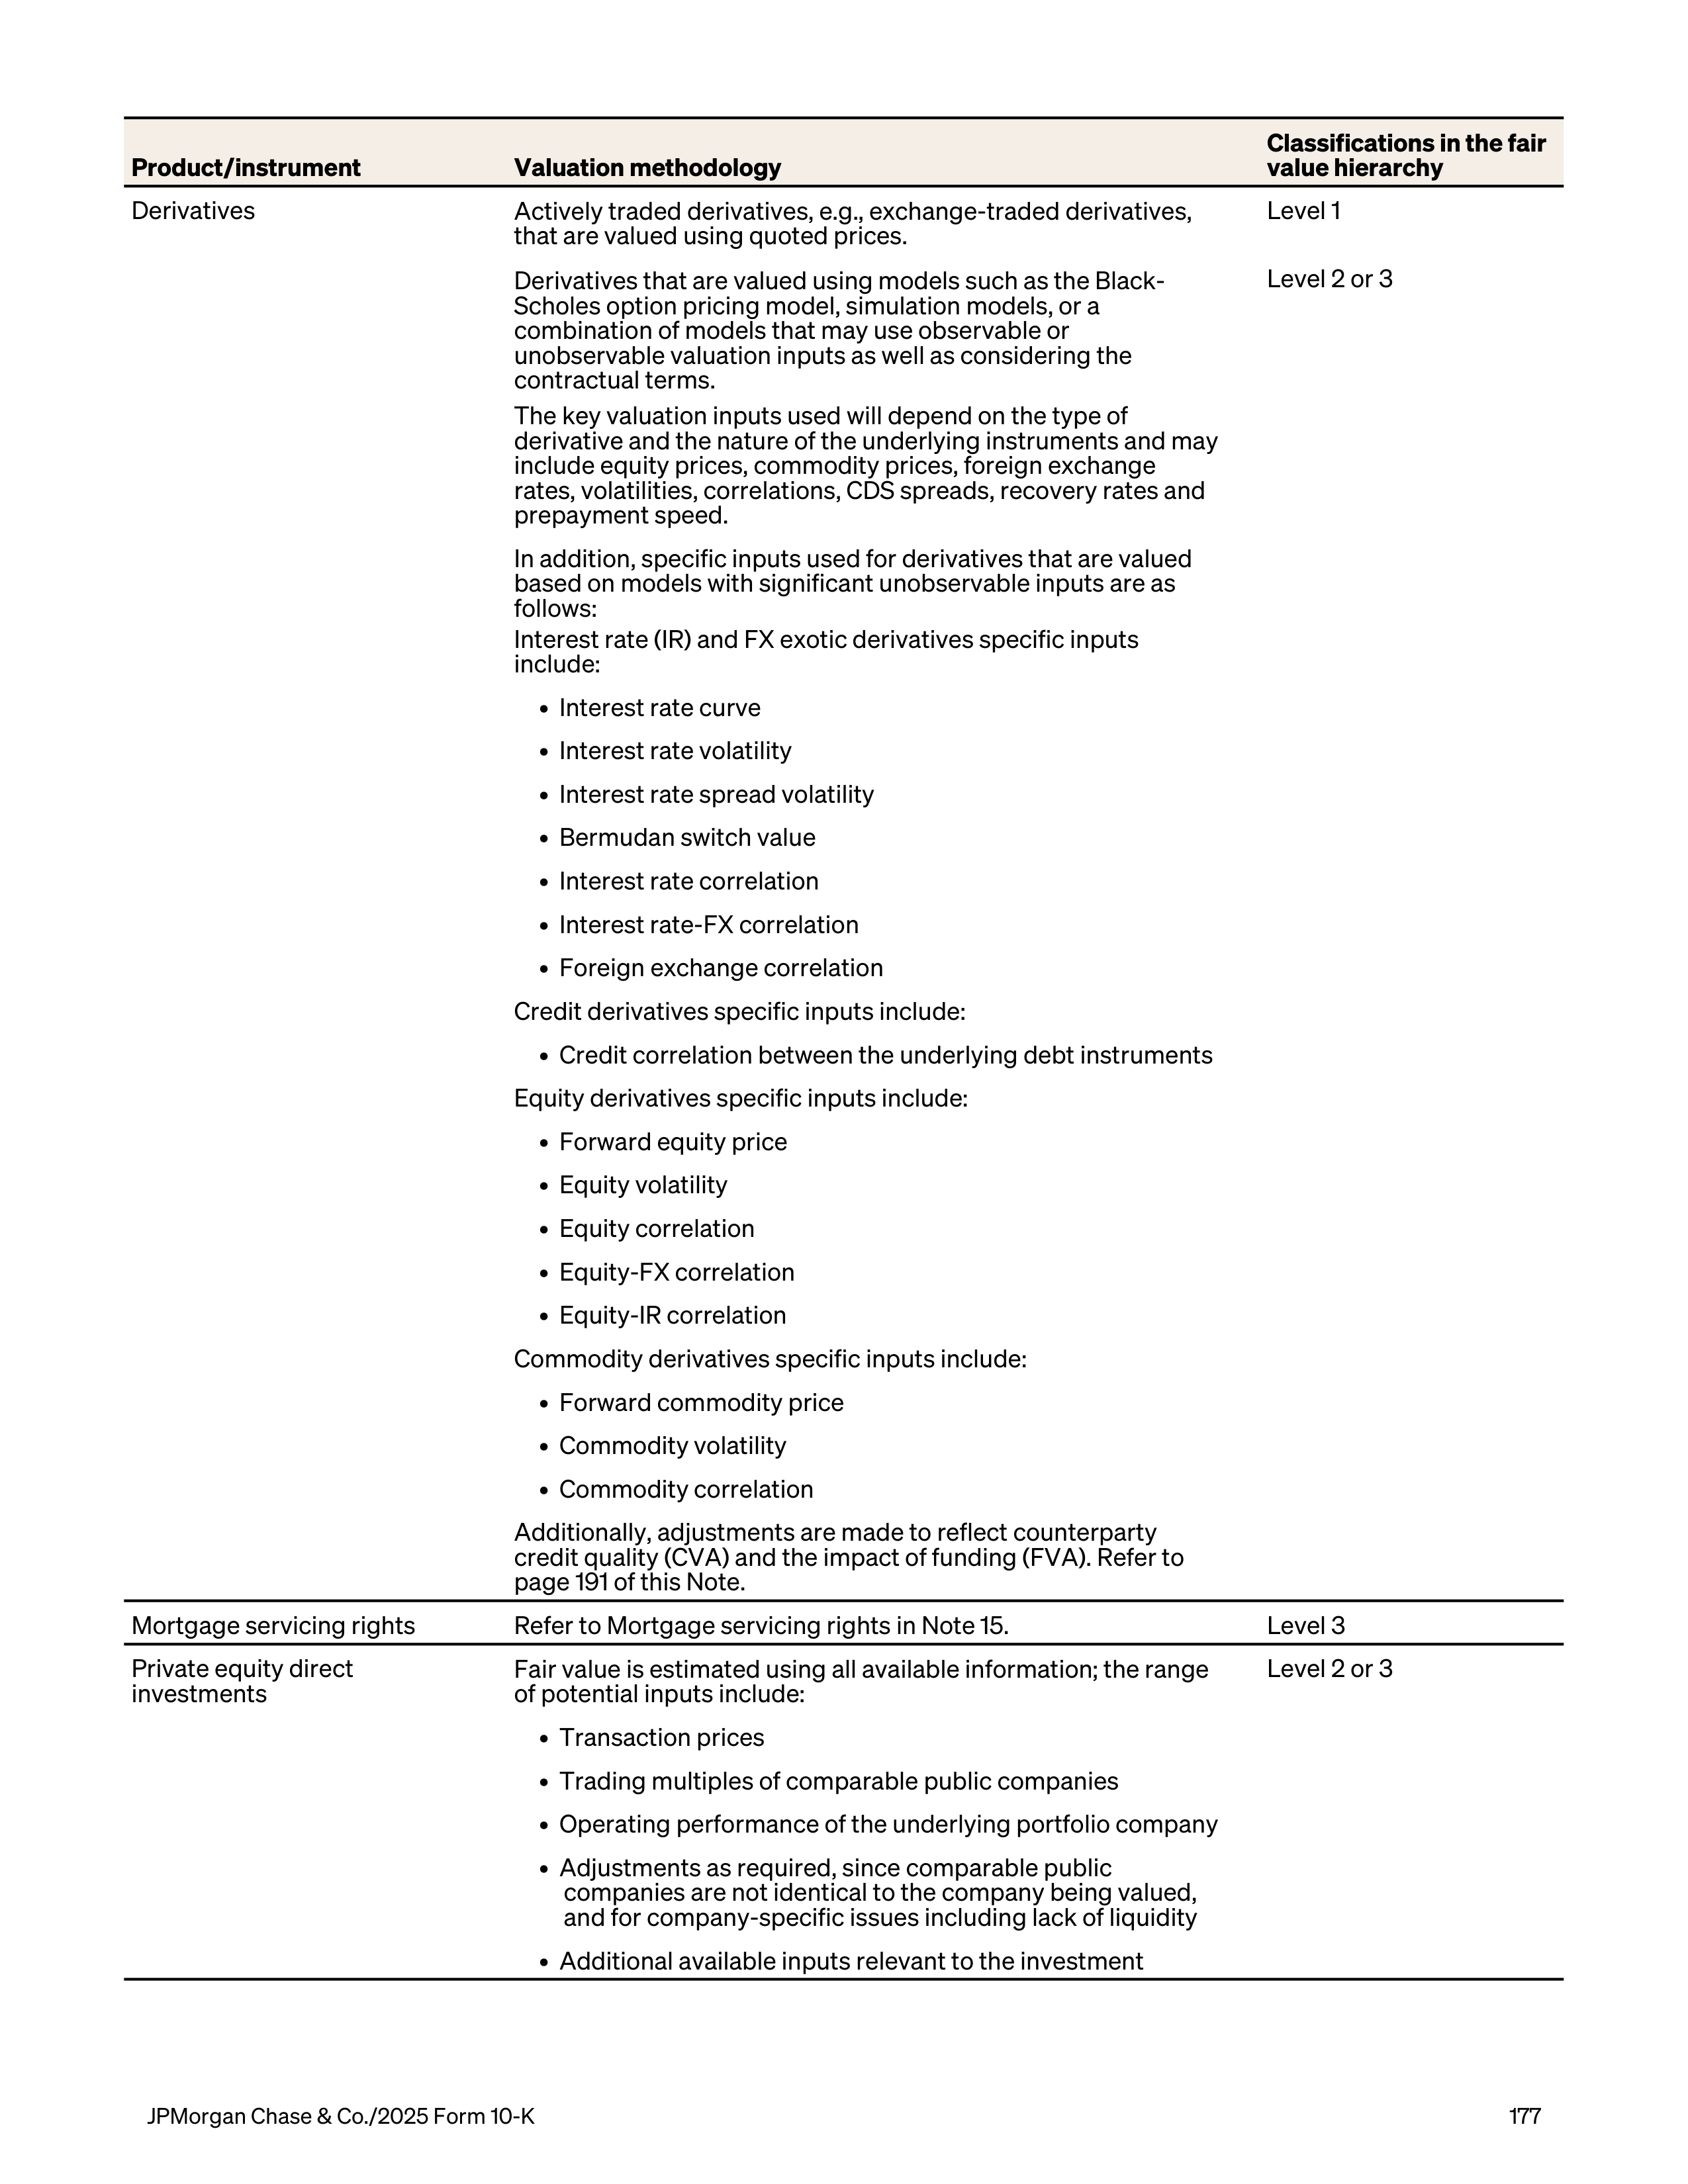
Product/instrument
Valuation methodology
Classifications in the fair
value hierarchy
Derivatives
Actively traded derivatives, e.g., exchange-traded derivatives,
that are valued using quoted prices.
Level 1
Derivatives that are valued using models such as the Black-
Scholes option pricing model, simulation models, or a
combination of models that may use observable or
unobservable valuation inputs as well as considering the
contractual terms.
The key valuation inputs used will depend on the type of
derivative and the nature of the underlying instruments and may
include equity prices, commodity prices, foreign exchange
rates, volatilities, correlations, CDS spreads, recovery rates and
prepayment speed.
Level 2 or 3
In addition, specific inputs used for derivatives that are valued
based on models with significant unobservable inputs are as
follows:
Interest rate (IR) and FX exotic derivatives specific inputs
include:
• Interest rate curve
• Interest rate volatility
• Interest rate spread volatility
• Bermudan switch value
• Interest rate correlation
• Interest rate-FX correlation
• Foreign exchange correlation
Credit derivatives specific inputs include:
• Credit correlation between the underlying debt instruments
Equity derivatives specific inputs include:
• Forward equity price
• Equity volatility
• Equity correlation
• Equity-FX correlation
• Equity-IR correlation
Commodity derivatives specific inputs include:
• Forward commodity price
• Commodity volatility
• Commodity correlation
Additionally, adjustments are made to reflect counterparty
credit quality (CVA) and the impact of funding (FVA). Refer to
page 191 of this Note.
Mortgage servicing rights
Refer to Mortgage servicing rights in Note 15.
Level 3
Private equity direct
investments
Fair value is estimated using all available information; the range
of potential inputs include:
Level 2 or 3
• Transaction prices
• Trading multiples of comparable public companies
• Operating performance of the underlying portfolio company
• Adjustments as required, since comparable public
companies are not identical to the company being valued,
and for company-specific issues including lack of liquidity
• Additional available inputs relevant to the investment
JPMorgan Chase & Co./2025 Form 10-K
177
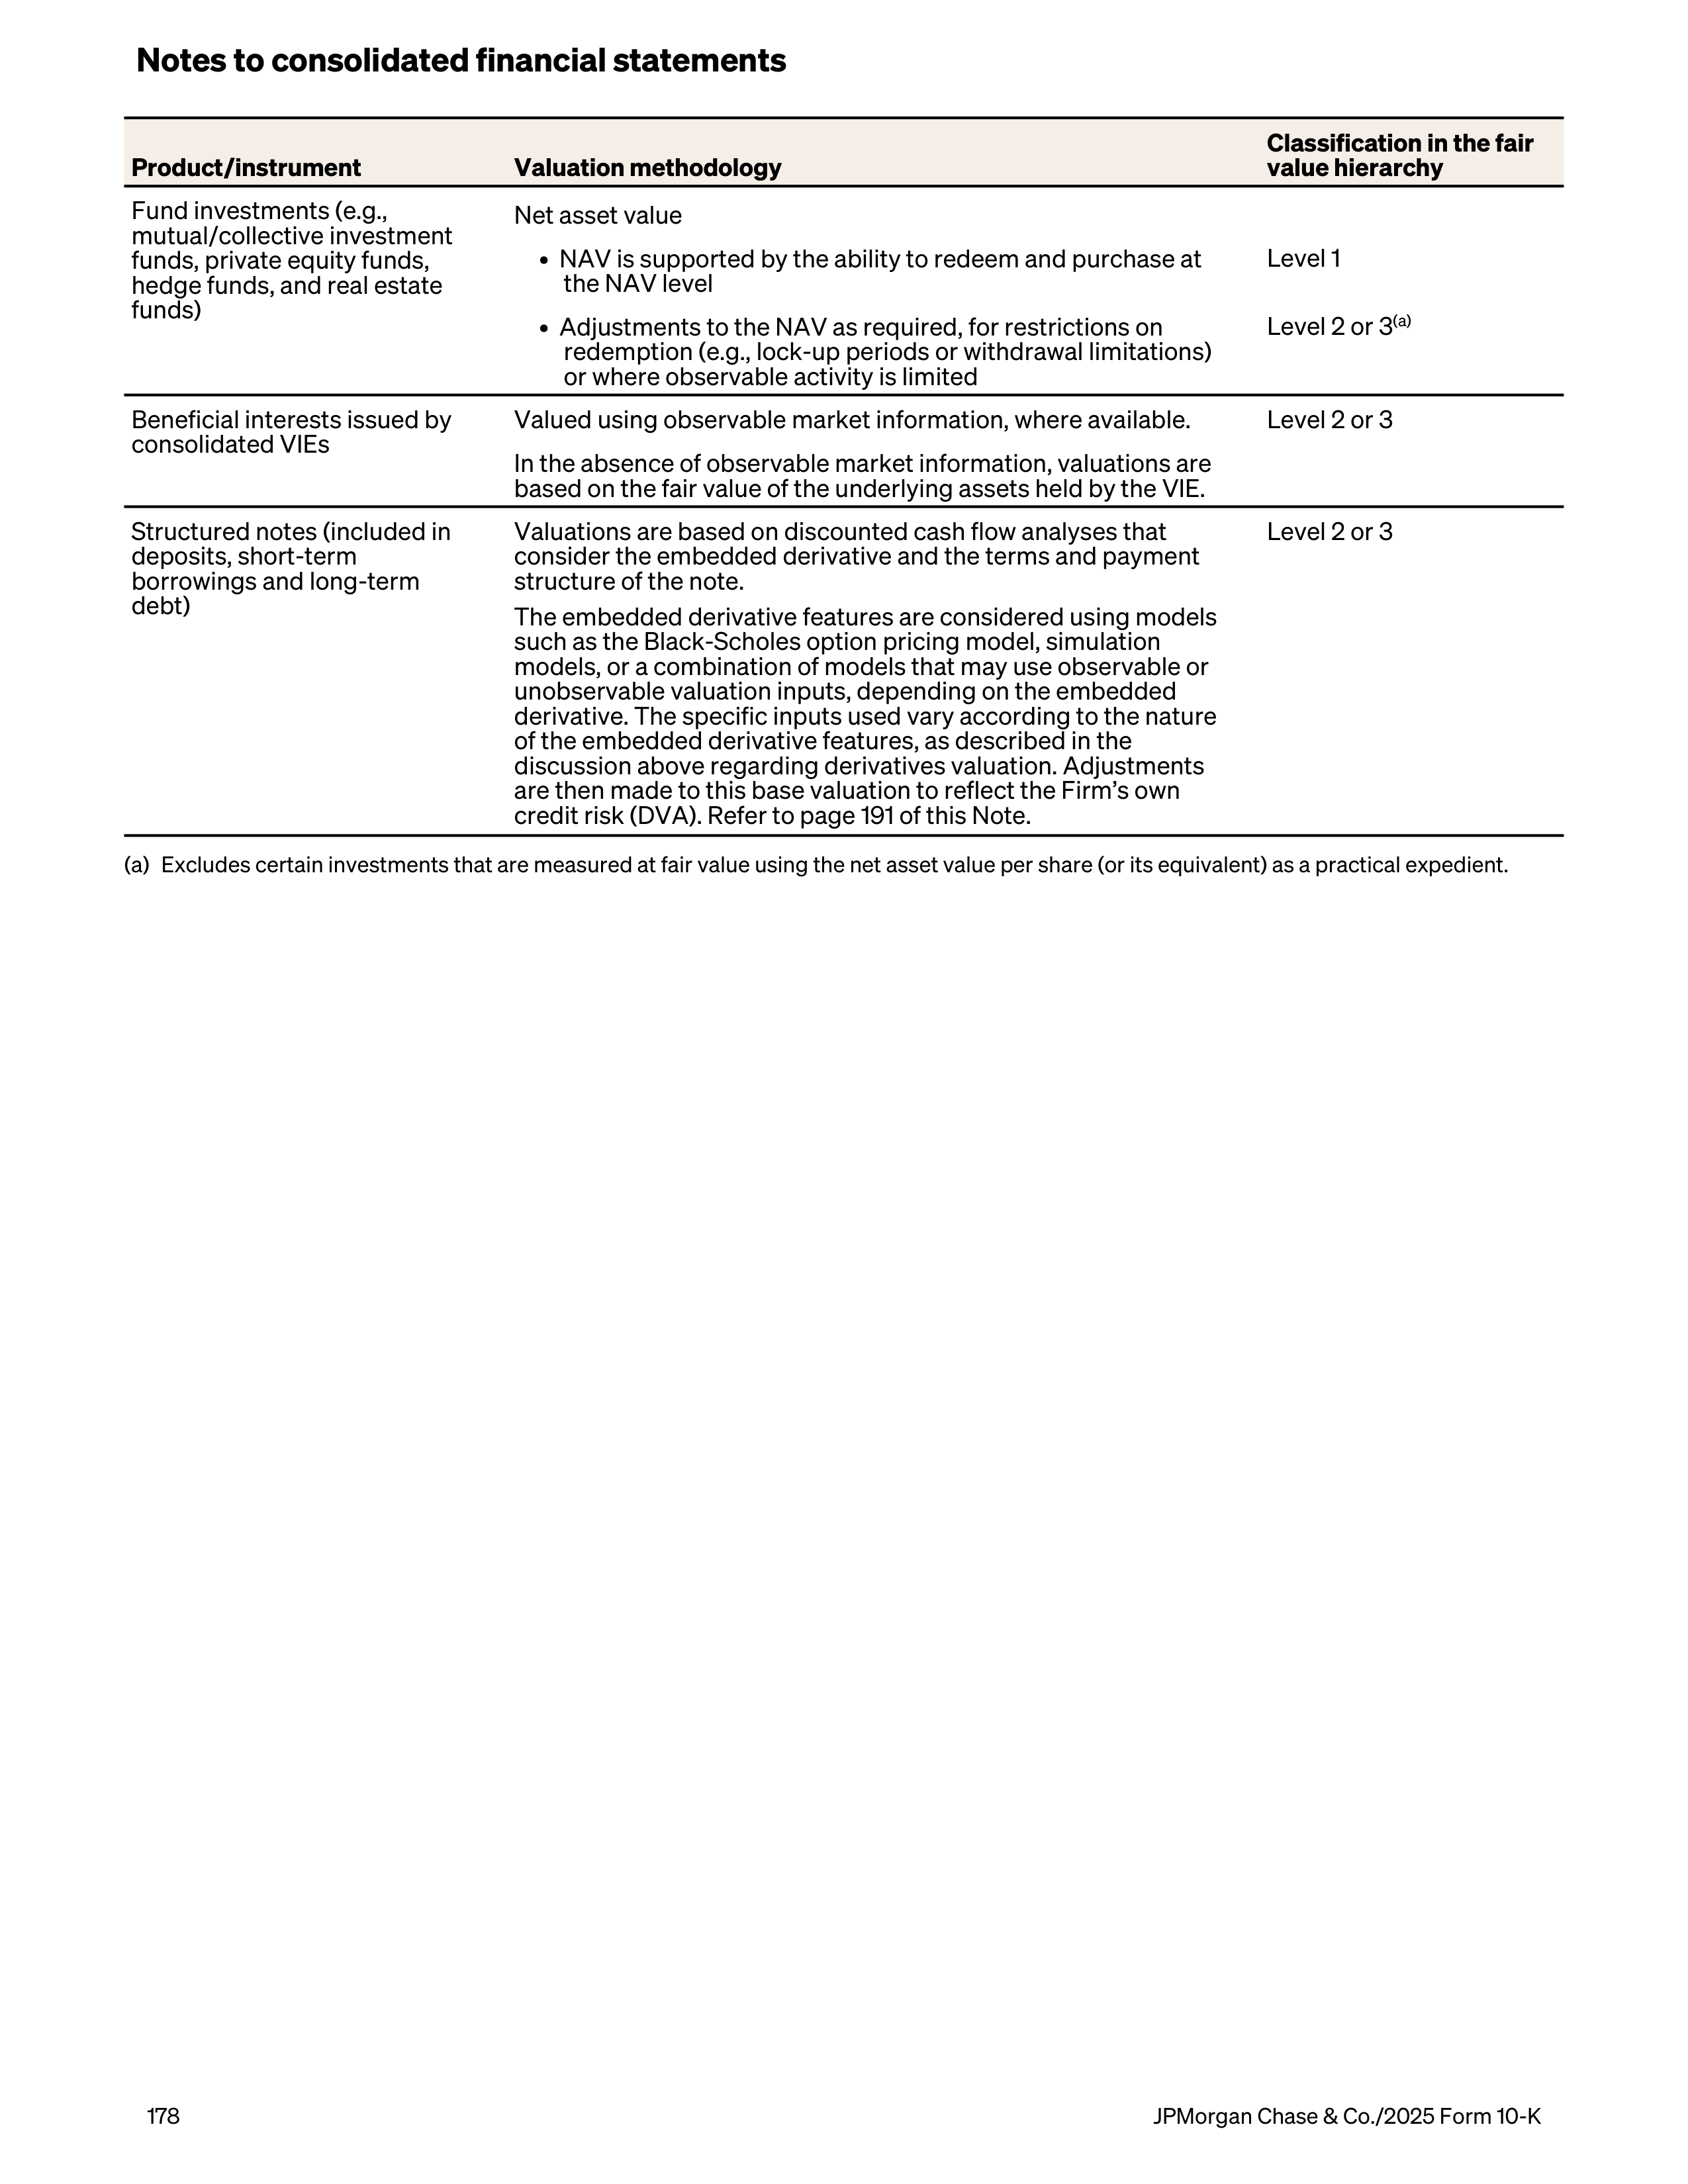
Product/instrument
Valuation methodology
Classification in the fair
value hierarchy
Fund investments (e.g.,
mutual/collective investment
funds, private equity funds,
hedge funds, and real estate
funds)
Net asset value
• NAV is supported by the ability to redeem and purchase at
the NAV level
Level 1
• Adjustments to the NAV as required, for restrictions on
redemption (e.g., lock-up periods or withdrawal limitations)
or where observable activity is limited
Level 2 or 3
(a)
Beneficial interests issued by
consolidated VIEs
Valued using observable market information, where available.
Level 2 or 3
In the absence of observable market information, valuations are
based on the fair value of the underlying assets held by the VIE.
Structured notes (included in
deposits, short-term
borrowings and long-term
debt)
Valuations are based on discounted cash flow analyses that
consider the embedded derivative and the terms and payment
structure of the note.
The embedded derivative features are considered using models
such as the Black-Scholes option pricing model, simulation
models, or a combination of models that may use observable or
unobservable valuation inputs, depending on the embedded
derivative. The specific inputs used vary according to the nature
of the embedded derivative features, as described in the
discussion above regarding derivatives valuation. Adjustments
are then made to this base valuation to reflect the Firm’s own
credit risk (DVA). Refer to page 191 of this Note.
Level 2 or 3
(a)
Excludes certain investments that are measured at fair value using the net asset value per share (or its equivalent) as a practical expedient.
Notes to consolidated financial statements
178
JPMorgan Chase & Co./2025 Form 10-K
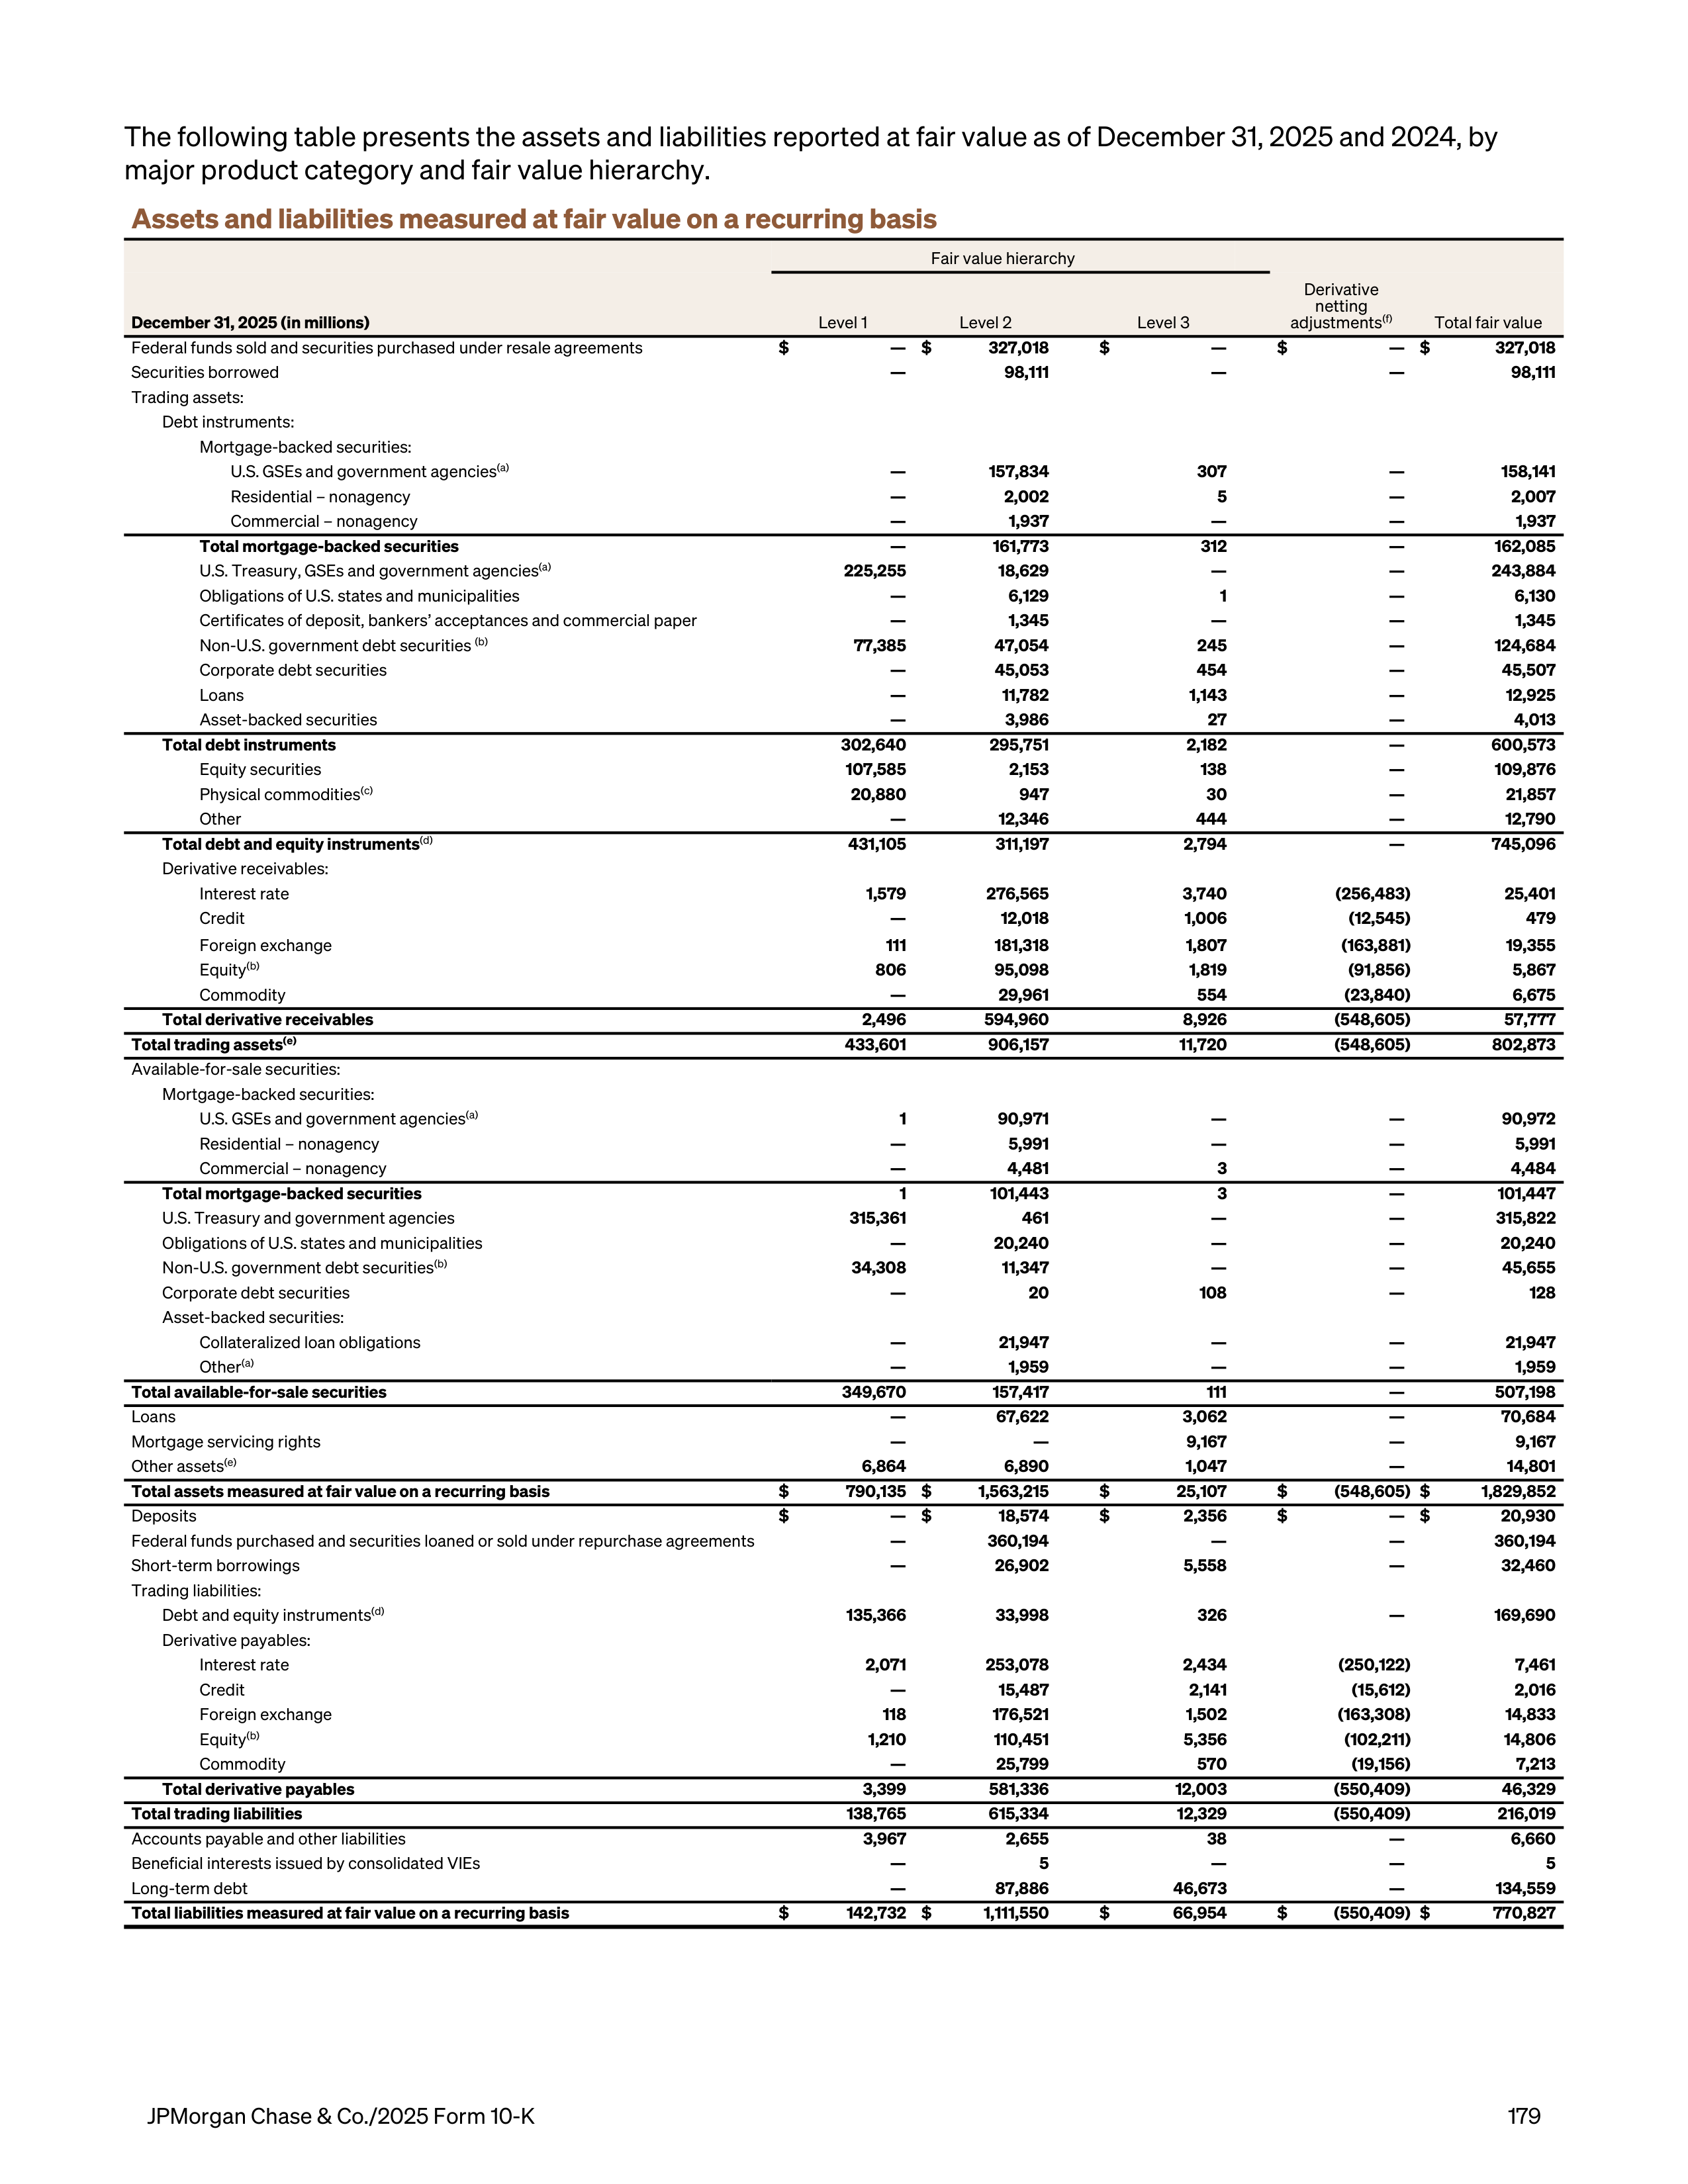
The following table presents the assets and liabilities reported at fair value as of December 31, 2025 and 2024, by
major product category and fair value hierarchy.
Assets and liabilities measured at fair value on a recurring basis
Fair value hierarchy
December 31, 2025 (in millions)
Level 1
Level 2
Level 3
Derivative
netting
adjustments
(f)
Total fair value
Federal funds sold and securities purchased under resale agreements
$
— $
327,018
$
—
$
— $
327,018
Securities borrowed
—
98,111
—
—
98,111
Trading assets:
Debt instruments:
Mortgage-backed securities:
U.S. GSEs and government agencies
(a)
—
157,834
307
—
158,141
Residential – nonagency
—
2,002
5
—
2,007
Commercial – nonagency
—
1,937
—
—
1,937
Total mortgage-backed securities
—
161,773
312
—
162,085
U.S. Treasury, GSEs and government agencies
(a)
225,255
18,629
—
—
243,884
Obligations of U.S. states and municipalities
—
6,129
1
—
6,130
Certificates of deposit, bankers’ acceptances and commercial paper
—
1,345
—
—
1,345
Non-U.S. government debt securities
(b)
77,385
47,054
245
—
124,684
Corporate debt securities
—
45,053
454
—
45,507
Loans
—
11,782
1,143
—
12,925
Asset-backed securities
—
3,986
27
—
4,013
Total debt instruments
302,640
295,751
2,182
—
600,573
Equity securities
107,585
2,153
138
—
109,876
Physical commodities
(c)
20,880
947
30
—
21,857
Other
—
12,346
444
—
12,790
Total debt and equity instruments
(d)
431,105
311,197
2,794
—
745,096
Derivative receivables:
Interest rate
1,579
276,565
3,740
(256,483)
25,401
Credit
—
12,018
1,006
(12,545)
479
Foreign exchange
111
181,318
1,807
(163,881)
19,355
Equity
(b)
806
95,098
1,819
(91,856)
5,867
Commodity
—
29,961
554
(23,840)
6,675
Total derivative receivables
2,496
594,960
8,926
(548,605)
57,777
Total trading assets
(e)
433,601
906,157
11,720
(548,605)
802,873
Available-for-sale securities:
Mortgage-backed securities:
U.S. GSEs and government agencies
(a)
1
90,971
—
—
90,972
Residential – nonagency
—
5,991
—
—
5,991
Commercial – nonagency
—
4,481
3
—
4,484
Total mortgage-backed securities
1
101,443
3
—
101,447
U.S. Treasury and government agencies
315,361
461
—
—
315,822
Obligations of U.S. states and municipalities
—
20,240
—
—
20,240
Non-U.S. government debt securities
(b)
34,308
11,347
—
—
45,655
Corporate debt securities
—
20
108
—
128
Asset-backed securities:
Collateralized loan obligations
—
21,947
—
—
21,947
Other
(a)
—
1,959
—
—
1,959
Total available-for-sale securities
349,670
157,417
111
—
507,198
Loans
—
67,622
3,062
—
70,684
Mortgage servicing rights
—
—
9,167
—
9,167
Other assets
(e)
6,864
6,890
1,047
—
14,801
Total assets measured at fair value on a recurring basis
$
790,135 $
1,563,215
$
25,107
$
(548,605) $
1,829,852
Deposits
$
— $
18,574
$
2,356
$
— $
20,930
Federal funds purchased and securities loaned or sold under repurchase agreements
—
360,194
—
—
360,194
Short-term borrowings
—
26,902
5,558
—
32,460
Trading liabilities:
Debt and equity instruments
(d)
135,366
33,998
326
—
169,690
Derivative payables:
Interest rate
2,071
253,078
2,434
(250,122)
7,461
Credit
—
15,487
2,141
(15,612)
2,016
Foreign exchange
118
176,521
1,502
(163,308)
14,833
Equity
(b)
1,210
110,451
5,356
(102,211)
14,806
Commodity
—
25,799
570
(19,156)
7,213
Total derivative payables
3,399
581,336
12,003
(550,409)
46,329
Total trading liabilities
138,765
615,334
12,329
(550,409)
216,019