Homeownership
Life
Goals
01
Build
the
Financial
Foundation
Goals
1–9 ·
Twelve
to
twenty
-
four
months
before
you
make
an
offer
01
Set
your
housing
number
first
.
Cap
the
total
monthly
payment
—
principal
,
interest
,
property
tax
,
insurance
,
and
HOA
—
at
28%
of
gross
monthly
income
.
Every
later
decision
gets
easier
once
this
line
is
fixed
.
02
Save
toward
a
20%
down
payment
.
On
a
$
420,000
home
that
is
$
84,000.
Below
20%,
you
pay
private
mortgage
insurance
until
you
reach
20%
equity
—
often
$
150
to
$
250
a
month
.
03
Keep
the
emergency
fund
separate
.
Three
to
six
months
of
living
expenses
in
an
account
the
down
payment
is
not
allowed
to
touch
.
Buying
a
house
with
no
reserve
is
how
a
furnace
becomes
a
second
mortgage
.
04
Get
your
debt
-
to
-
income
ratio
under
36%.
Lenders
will
approve
to
43%,
but
36%
keeps
the
payment
comfortable
and
the
approval
clean
if
rates
move
before
you
close
.
05
Pull
all
three
credit
reports
and
dispute
the
errors
.
Target
a
740+
FICO
.
The
rate
difference
between
a
680
and
a
760
on
a
$
340,000
loan
is
roughly
$
120
a
month
,
every
month
.
06
Get
pre
-
approved
,
not
pre
-
qualified
.
Pre
-
approval
means
an
underwriter
has
reviewed
your
documents
.
Sellers
and
their
agents
treat
the
two
very
differently
in
a
competitive
market
.
07
Budget
closing
costs
at
2–5%
of
the
purchase
price
.
On
a
$
420,000
home
,
plan
for
$
9,000
to
$
18,000
beyond
the
down
payment
—
origination
,
title
,
appraisal
,
recording
,
and
prepaid
escrow
.
08
Price
the
move
,
not
just
the
mortgage
.
Moving
,
utility
deposits
,
window
treatments
,
a
lawn
mower
,
and
the
first
round
of
small
repairs
typically
run
$
3,000
to
$
8,000.
09
Write
down
what
you
will
not
sacrifice
.
Two
or
three
non
-
negotiables
—
the
commute
,
the
school
district
,
a
yard
for
the
dog
.
Without
the
list
,
every
compromise
looks
reasonable
in
the
moment
.
02
Choose
the
Right
Place
and
the
Right
Property
Goals
10–17 ·
Three
to
nine
months
before
you
make
an
offer
10
Commit
to
a
ten
-
year
location
.
Buying
only
makes
financial
sense
if
you
stay
long
enough
to
absorb
the
6–8%
of
transaction
costs
in
the
buy
and
the
eventual
sell
.
11
Pick
the
property
type
deliberately
.
A
single
-
family
home
and
a
condominium
build
equity
on
different
timetables
.
Condos
carry
HOA
dues
,
special
assessments
,
and
sometimes
rental
and
financing
restrictions
.
12
Limit
yourself
to
three
must
-
haves
.
More
than
three
and
you
will
not
find
a
house
—
you
will
find
a
reason
to
keep
looking
while
the
right
one
sells
to
someone
else
.
13
Walk
the
neighborhood
at
three
times
of
day
.
Morning
commute
,
after
school
,
and
after
10
p
.
m
.
tell
you
three
different
things
about
traffic
,
noise
,
and
neighbors
.
14
Check
the
property
tax
history
,
not
just
the
current
bill
.
A
recent
reassessment
,
an
expiring
abatement
,
or
a
pending
millage
increase
changes
the
monthly
payment
after
closing
,
not
before
.
1 / 4
15
Verify
flood
zone
and
insurability
before
you
fall
in
love
with
a
listing
.
In
some
markets
a
flood
policy
costs
more
per
year
than
the
property
tax
,
and
a
prior
claim
can
make
a
house
difficult
to
insure
at
all
.
16
Tour
at
least
ten
homes
before
you
make
an
offer
.
Ten
is
the
number
where
your
preferences
stop
being
guesses
and
start
being
criteria
.
17
Ask
what
the
seller
is
not
fixing
.
Inspection
reports
and
disclosure
statements
name
the
problems
that
will
become
yours
.
Read
them
for
what
is
missing
,
not
only
for
what
is
listed
.
03
Offer
,
Inspection
,
and
Closing
Goals
18–27 ·
Sixty
to
ninety
days
from
offer
to
keys
18
Hire
a
buyer
'
s
agent
who
has
closed
in
that
neighborhood
within
the
last
year
.
Local
closing
patterns
,
inspection
quirks
,
and
contract
customs
are
not
transferable
from
another
market
.
19
Make
the
offer
with
a
strategy
,
not
a
single
number
.
Purchase
price
,
earnest
money
,
inspection
window
,
financing
contingency
,
and
closing
date
are
all
negotiating
levers
—
use
more
than
one
.
20
Order
the
inspection
inside
the
window
.
A
general
inspection
plus
a
sewer
scope
on
any
home
older
than
thirty
years
.
Add
radon
and
mold
testing
where
the
region
warrants
it
.
21
Attend
the
inspection
in
person
.
Ninety
minutes
walking
the
house
with
the
inspector
is
the
cheapest
education
you
will
ever
get
on
this
particular
building
.
22
Negotiate
repairs
in
writing
,
with
licensed
-
contractor
quotes
.
Ask
for
quotes
,
not
estimates
from
a
handyman
the
seller
knows
,
and
confirm
the
work
is
permitted
and
inspected
.
23
Lock
your
rate
in
writing
.
Ask
explicitly
whether
the
lock
includes
a
float
-
down
option
and
what
the
extension
cost
is
if
closing
slips
past
the
lock
date
.
24
Read
the
Closing
Disclosure
three
days
before
closing
.
Compare
it
line
by
line
against
the
Loan
Estimate
.
Any
figure
that
moved
needs
an
explanation
before
you
sign
,
not
after
.
25
Buy
an
owner
'
s
title
insurance
policy
.
The
lender
'
s
policy
protects
the
lender
.
The
owner
'
s
policy
protects
you
,
and
no
one
else
will
order
it
.
26
Walk
the
house
the
morning
of
closing
.
Test
every
system
the
seller
agreed
to
repair
,
confirm
the
appliances
remain
,
and
photograph
the
utility
meter
readings
.
27
Set
up
escrow
and
autopay
before
the
first
payment
is
due
.
One
missed
payment
costs
more
in
credit
damage
than
the
escrow
convenience
is
worth
in
savings
.
04
The
First
Twelve
Months
Goals
28–36 ·
Move
-
in
through
the
first
full
year
28
Rekey
every
lock
on
day
one
.
Replace
or
rekey
the
deadbolts
,
reset
the
garage
keypad
code
,
and
reprogram
the
smart
lock
—
you
do
not
know
who
kept
a
key
.
29
Find
the
main
shut
-
offs
and
label
them
.
Water
main
,
gas
valve
,
and
electrical
panel
.
Label
each
one
and
make
sure
every
adult
in
the
house
knows
where
they
are
.
2 / 4
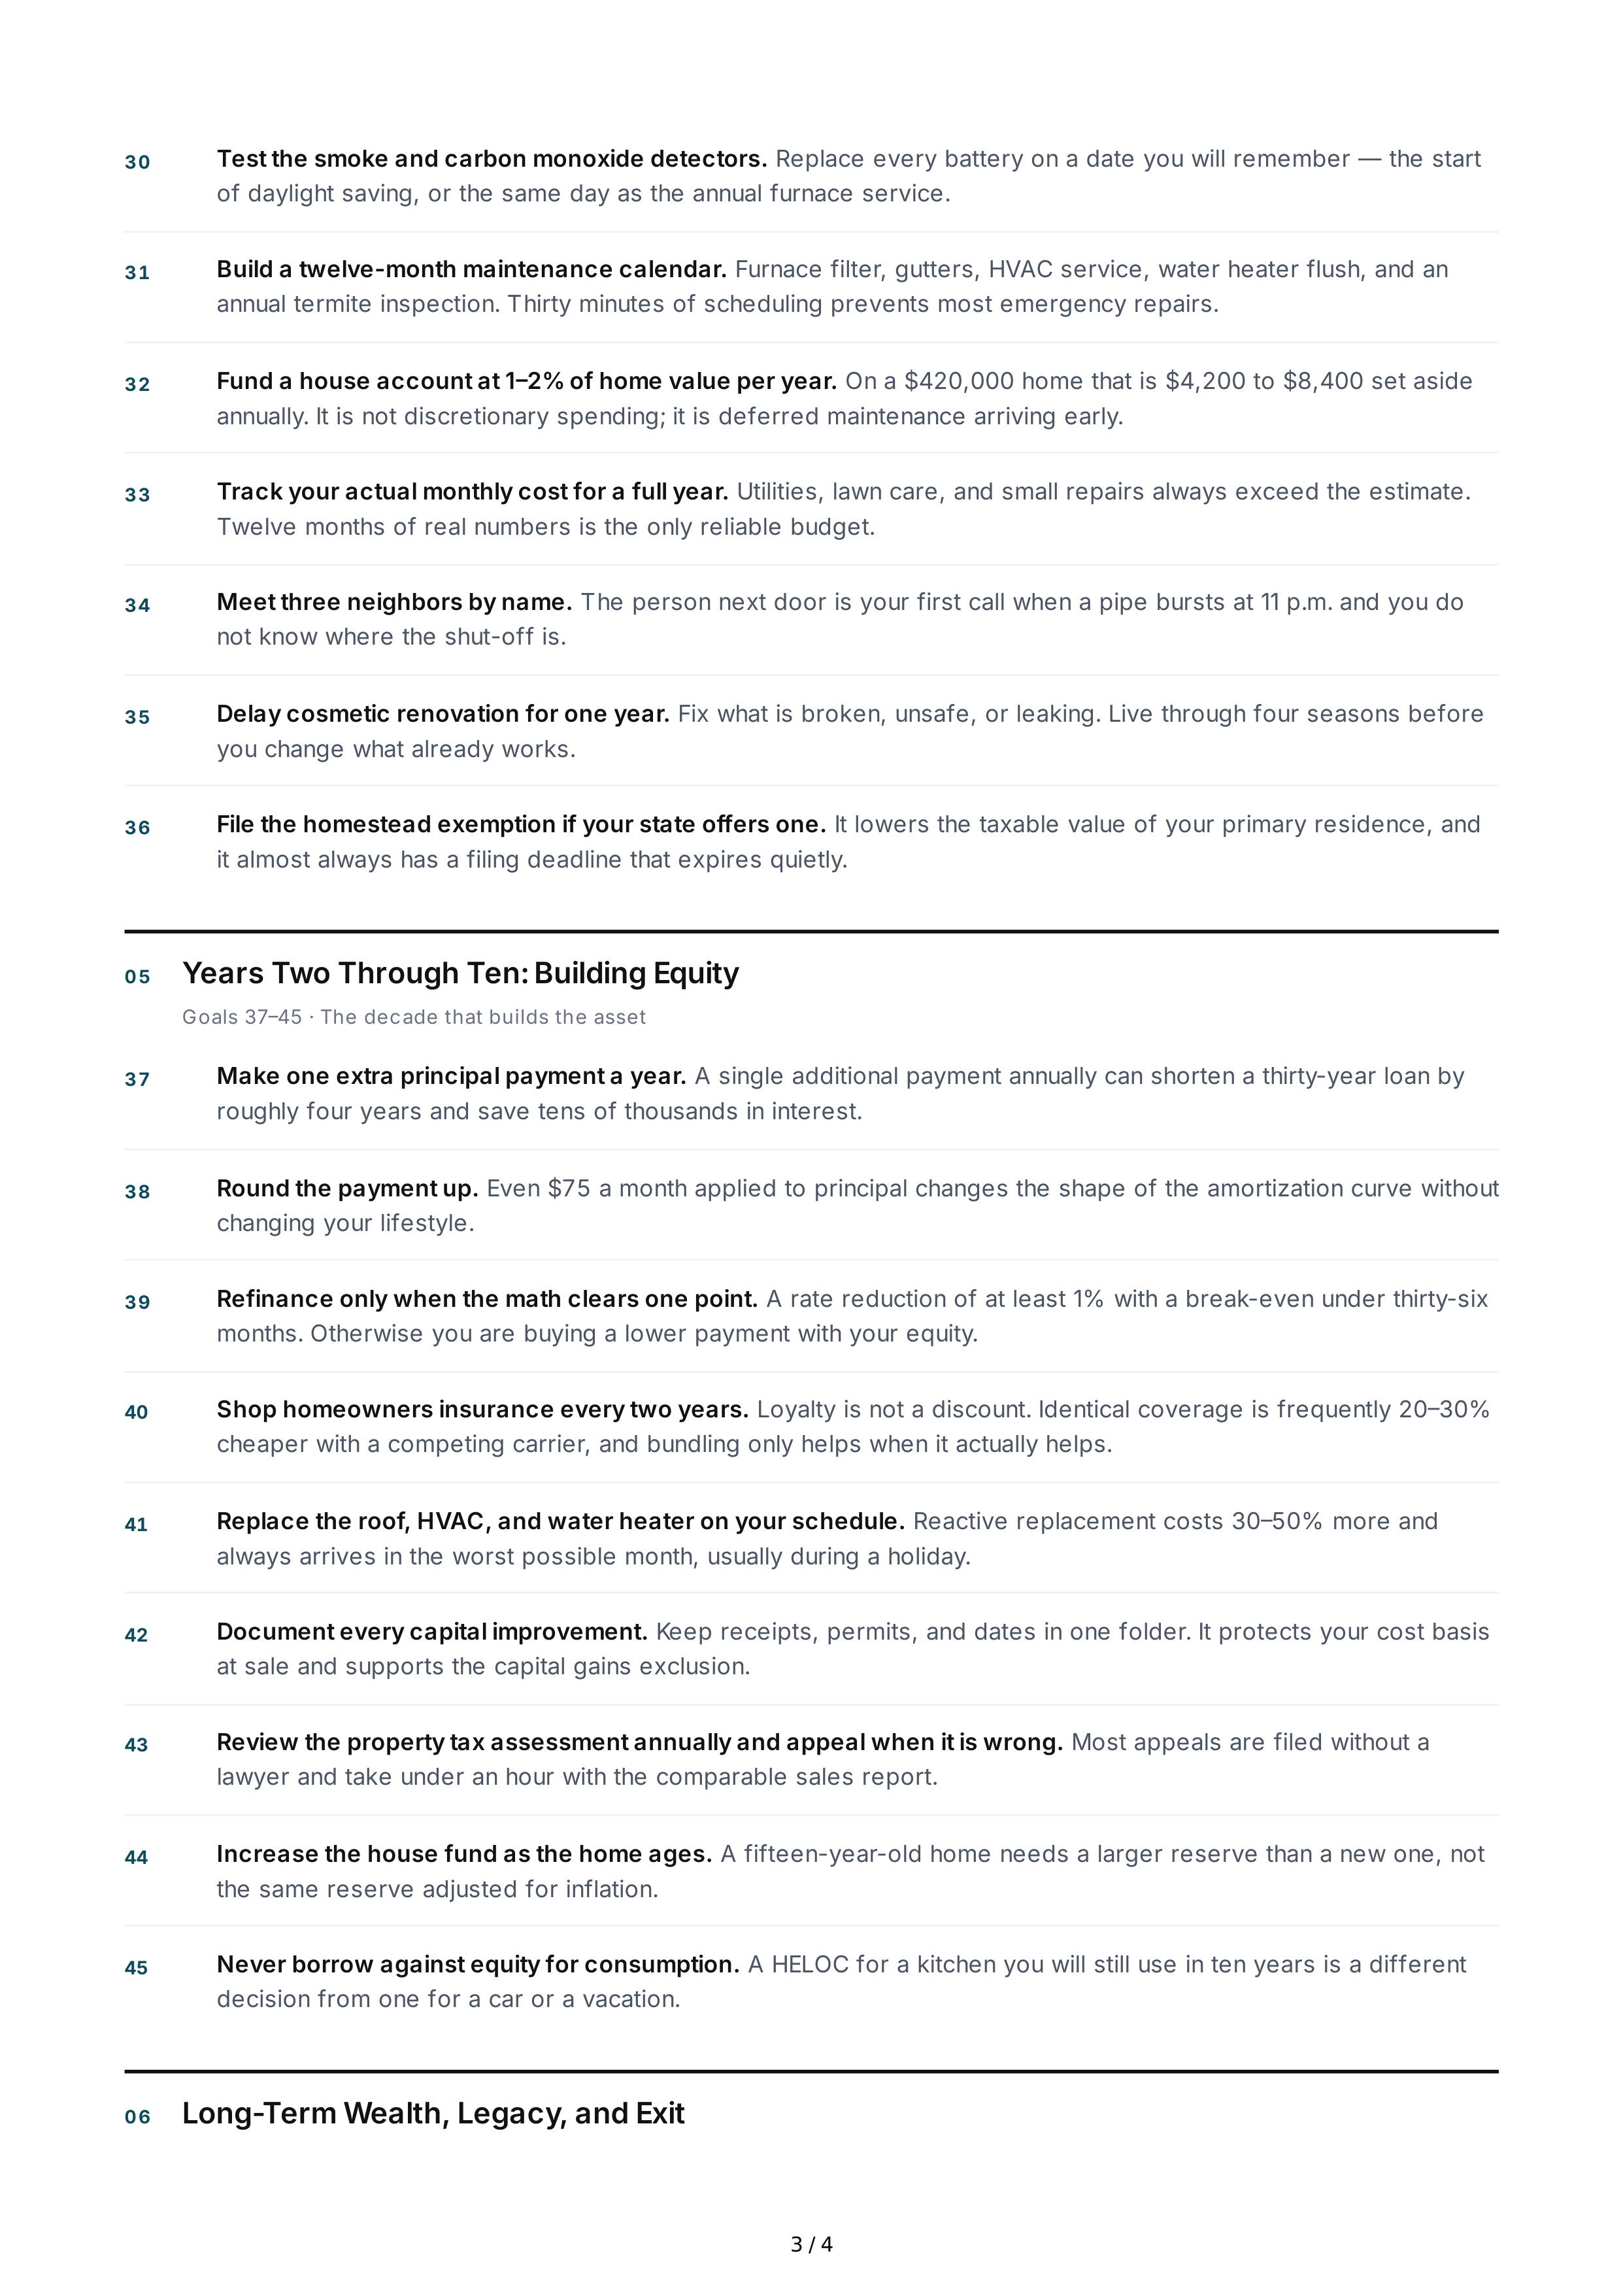
30
Test
the
smoke
and
carbon
monoxide
detectors
.
Replace
every
battery
on
a
date
you
will
remember
—
the
start
of
daylight
saving
,
or
the
same
day
as
the
annual
furnace
service
.
31
Build
a
twelve
-
month
maintenance
calendar
.
Furnace
filter
,
gutters
,
HVAC
service
,
water
heater
flush
,
and
an
annual
termite
inspection
.
Thirty
minutes
of
scheduling
prevents
most
emergency
repairs
.
32
Fund
a
house
account
at
1–2%
of
home
value
per
year
.
On
a
$
420,000
home
that
is
$
4,200
to
$
8,400
set
aside
annually
.
It
is
not
discretionary
spending
;
it
is
deferred
maintenance
arriving
early
.
33
Track
your
actual
monthly
cost
for
a
full
year
.
Utilities
,
lawn
care
,
and
small
repairs
always
exceed
the
estimate
.
Twelve
months
of
real
numbers
is
the
only
reliable
budget
.
34
Meet
three
neighbors
by
name
.
The
person
next
door
is
your
first
call
when
a
pipe
bursts
at
11
p
.
m
.
and
you
do
not
know
where
the
shut
-
off
is
.
35
Delay
cosmetic
renovation
for
one
year
.
Fix
what
is
broken
,
unsafe
,
or
leaking
.
Live
through
four
seasons
before
you
change
what
already
works
.
36
File
the
homestead
exemption
if
your
state
offers
one
.
It
lowers
the
taxable
value
of
your
primary
residence
,
and
it
almost
always
has
a
filing
deadline
that
expires
quietly
.
05
Years
Two
Through
Ten
:
Building
Equity
Goals
37–45 ·
The
decade
that
builds
the
asset
37
Make
one
extra
principal
payment
a
year
.
A
single
additional
payment
annually
can
shorten
a
thirty
-
year
loan
by
roughly
four
years
and
save
tens
of
thousands
in
interest
.
38
Round
the
payment
up
.
Even
$
75
a
month
applied
to
principal
changes
the
shape
of
the
amortization
curve
without
changing
your
lifestyle
.
39
Refinance
only
when
the
math
clears
one
point
.
A
rate
reduction
of
at
least
1%
with
a
break
-
even
under
thirty
-
six
months
.
Otherwise
you
are
buying
a
lower
payment
with
your
equity
.
40
Shop
homeowners
insurance
every
two
years
.
Loyalty
is
not
a
discount
.
Identical
coverage
is
frequently
20–30%
cheaper
with
a
competing
carrier
,
and
bundling
only
helps
when
it
actually
helps
.
41
Replace
the
roof
,
HVAC
,
and
water
heater
on
your
schedule
.
Reactive
replacement
costs
30–50%
more
and
always
arrives
in
the
worst
possible
month
,
usually
during
a
holiday
.
42
Document
every
capital
improvement
.
Keep
receipts
,
permits
,
and
dates
in
one
folder
.
It
protects
your
cost
basis
at
sale
and
supports
the
capital
gains
exclusion
.
43
Review
the
property
tax
assessment
annually
and
appeal
when
it
is
wrong
.
Most
appeals
are
filed
without
a
lawyer
and
take
under
an
hour
with
the
comparable
sales
report
.
44
Increase
the
house
fund
as
the
home
ages
.
A
fifteen
-
year
-
old
home
needs
a
larger
reserve
than
a
new
one
,
not
the
same
reserve
adjusted
for
inflation
.
45
Never
borrow
against
equity
for
consumption
.
A
HELOC
for
a
kitchen
you
will
still
use
in
ten
years
is
a
different
decision
from
one
for
a
car
or
a
vacation
.
06
Long
-
Term
Wealth
,
Legacy
,
and
Exit
3 / 4
Goals
46–50 ·
Ten
years
and
beyond
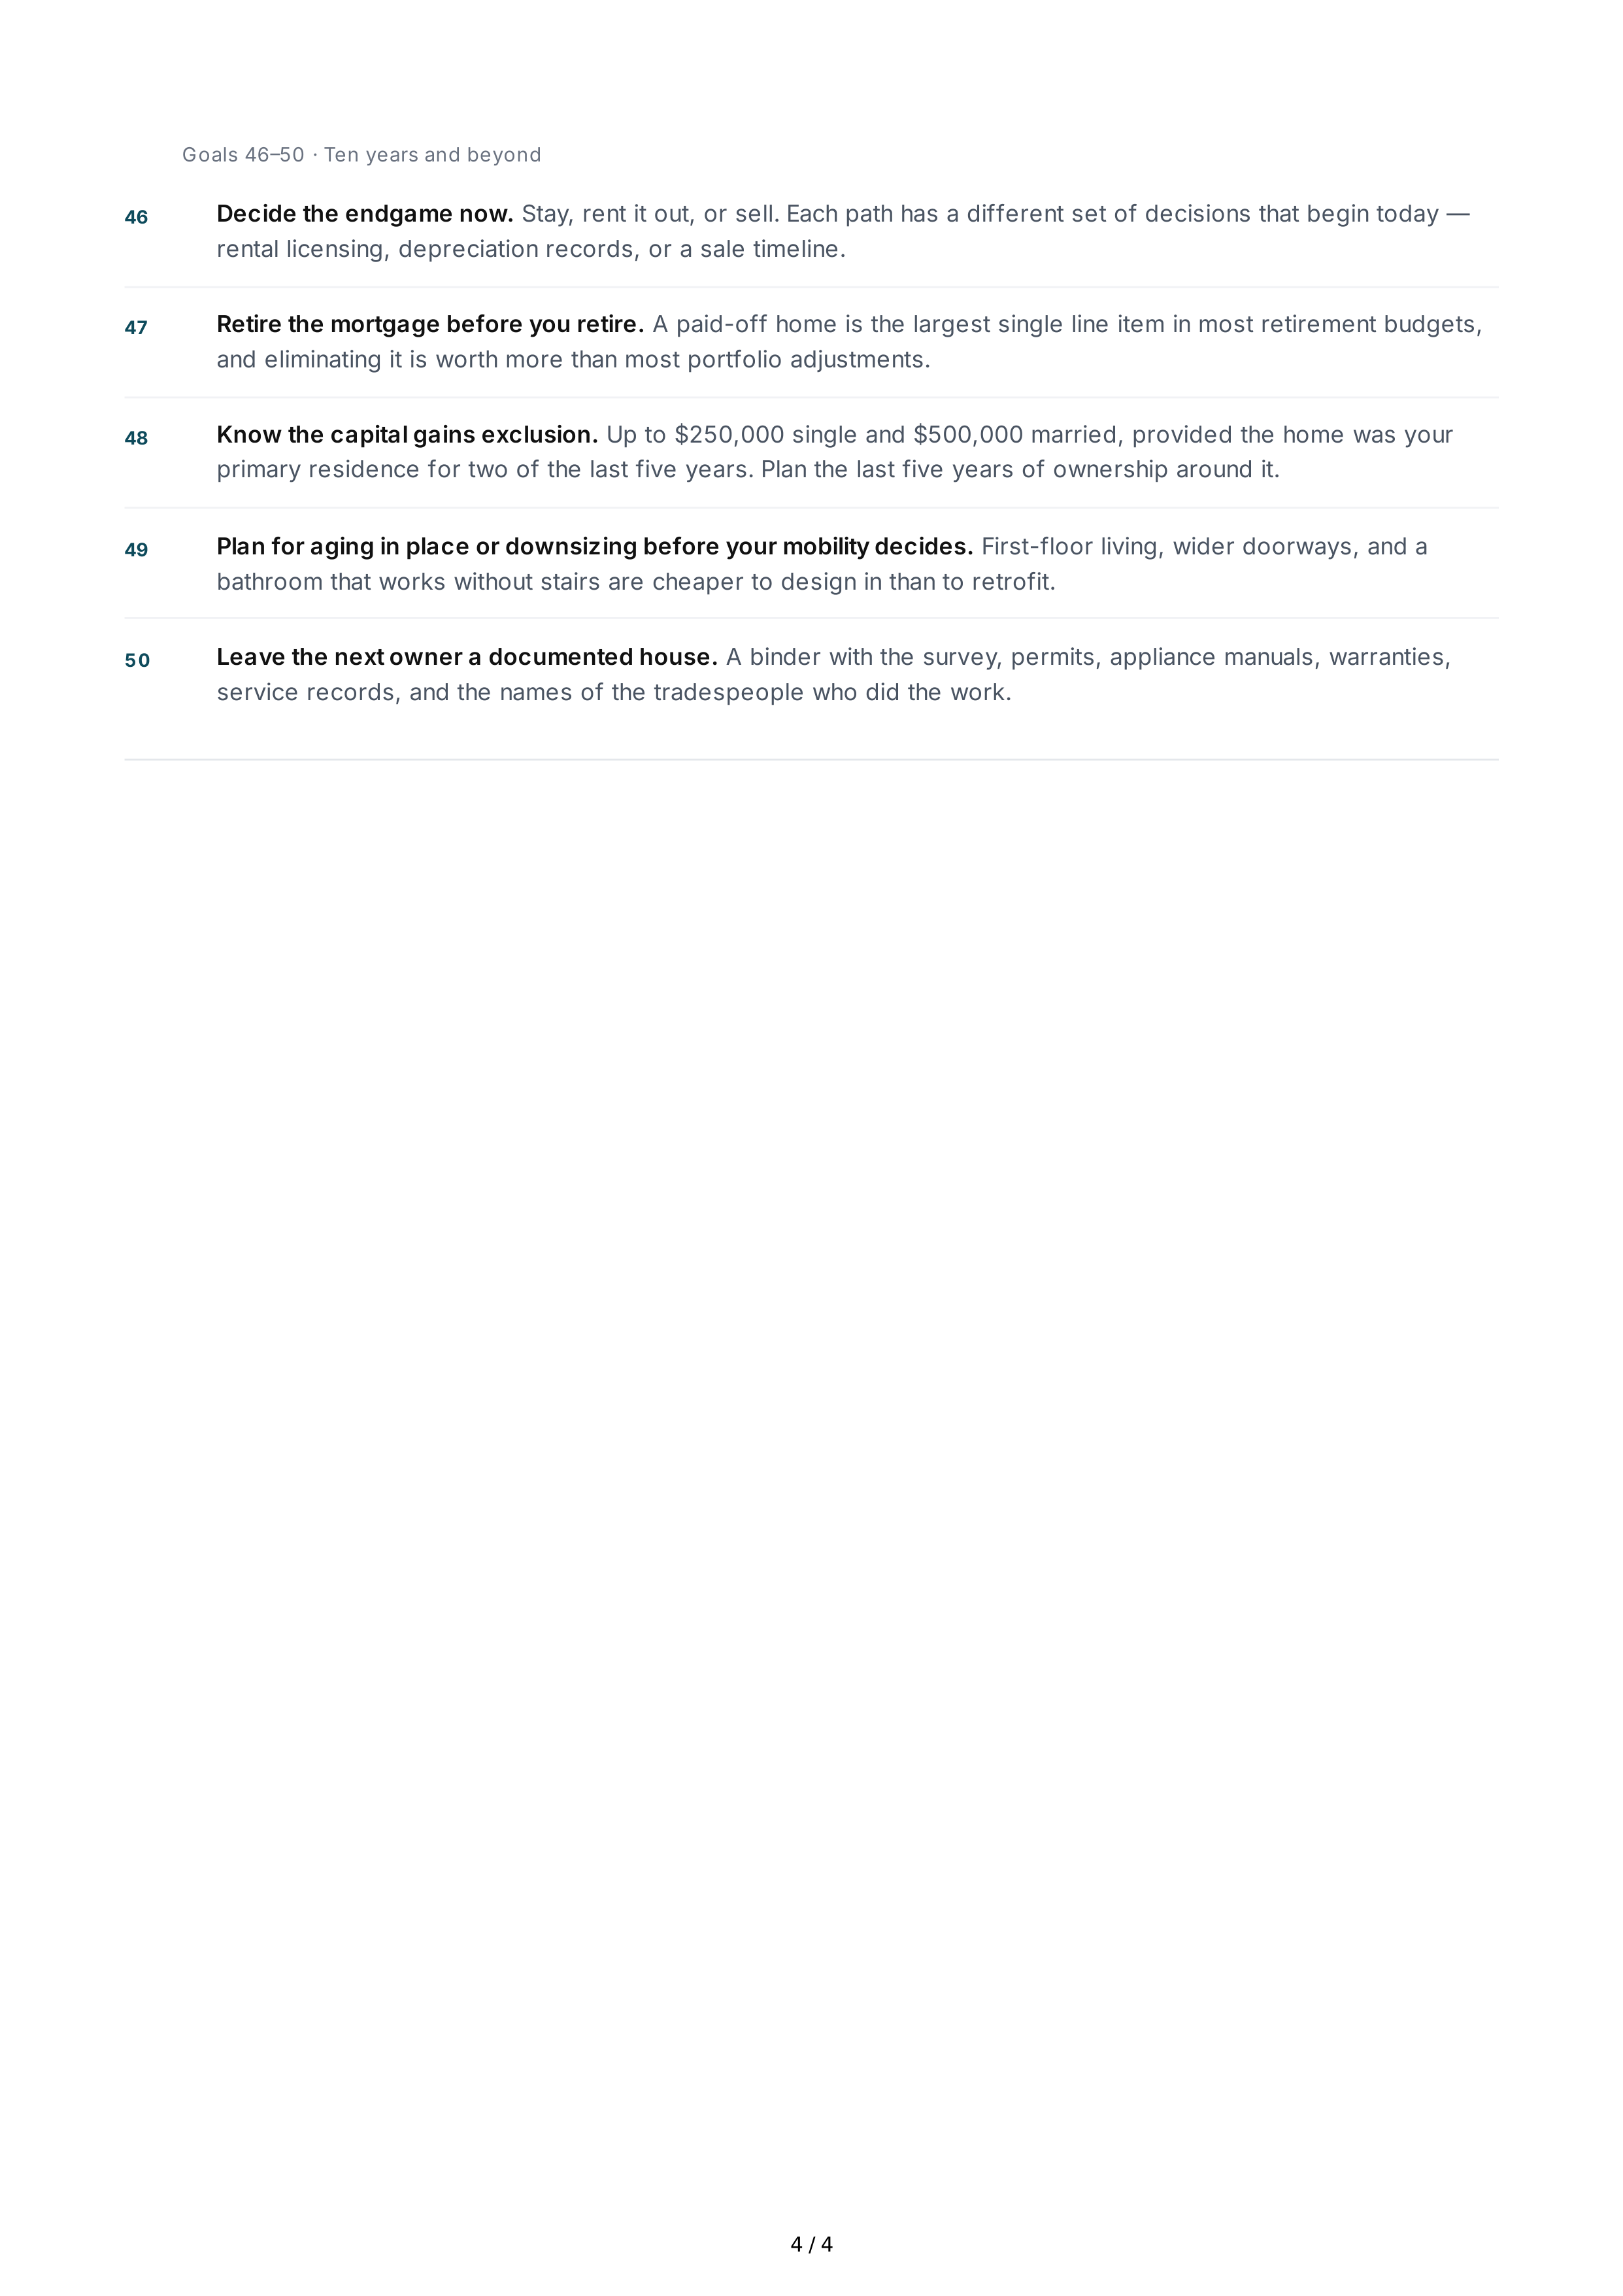
46
Decide
the
endgame
now
.
Stay
,
rent
it
out
,
or
sell
.
Each
path
has
a
different
set
of
decisions
that
begin
today
—
rental
licensing
,
depreciation
records
,
or
a
sale
timeline
.
47
Retire
the
mortgage
before
you
retire
.
A
paid
-
off
home
is
the
largest
single
line
item
in
most
retirement
budgets
,
and
eliminating
it
is
worth
more
than
most
portfolio
adjustments
.
48
Know
the
capital
gains
exclusion
.
Up
to
$
250,000
single
and
$
500,000
married
,
provided
the
home
was
your
primary
residence
for
two
of
the
last
five
years
.
Plan
the
last
five
years
of
ownership
around
it
.
49
Plan
for
aging
in
place
or
downsizing
before
your
mobility
decides
.
First
-
floor
living
,
wider
doorways
,
and
a
bathroom
that
works
without
stairs
are
cheaper
to
design
in
than
to
retrofit
.
50
Leave
the
next
owner
a
documented
house
.
A
binder
with
the
survey
,
permits
,
appliance
manuals
,
warranties
,
service
records
,
and
the
names
of
the
tradespeople
who
did
the
work
.
4 / 4