My Projects
Home
Free AI Life Goals Generator
Investment Life Goals
Investment
Life
Goals
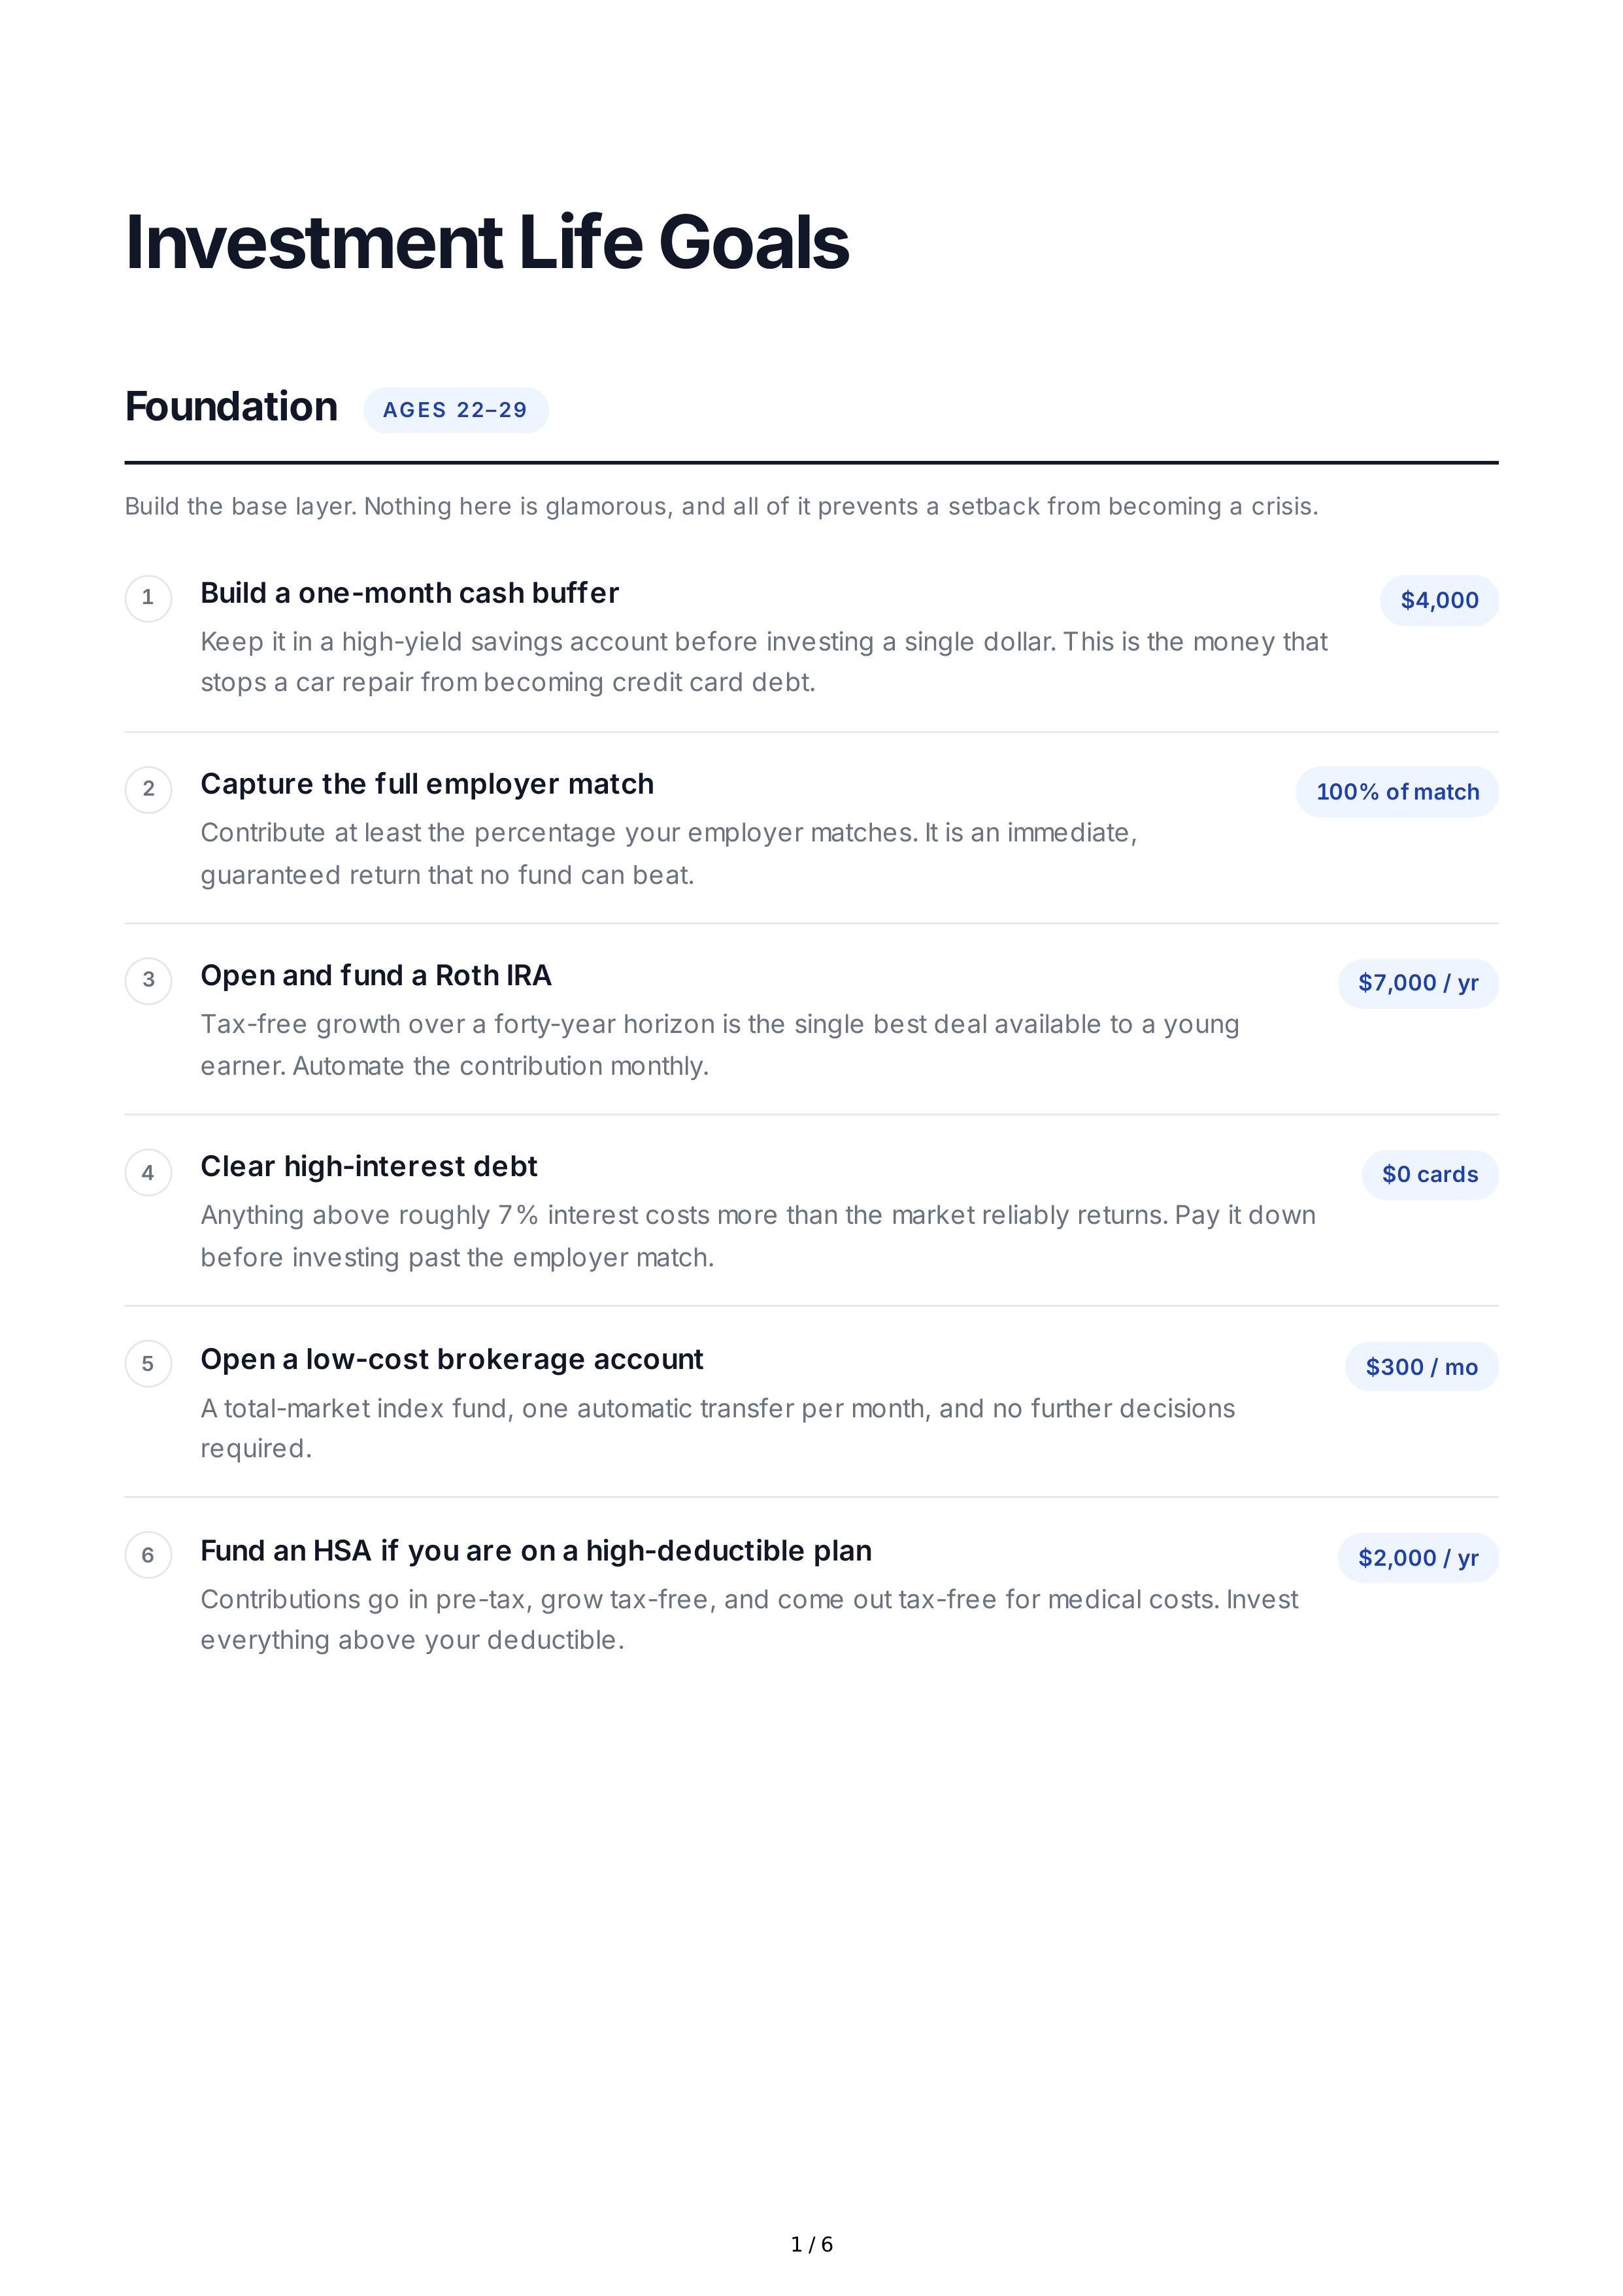
Foundation
Build
the
base
layer
.
Nothing
here
is
glamorous
,
and
all
of
it
prevents
a
setback
from
becoming
a
crisis
.
1
Build
a
one
-
month
cash
buffer
Keep
it
in
a
high
-
yield
savings
account
before
investing
a
single
dollar
.
This
is
the
money
that
stops
a
car
repair
from
becoming
credit
card
debt
.
$
4,000
2
Capture
the
full
employer
match
Contribute
at
least
the
percentage
your
employer
matches
.
It
is
an
immediate
,
guaranteed
return
that
no
fund
can
beat
.
100%
of
match
3
Open
and
fund
a
Roth
IRA
Tax
-
free
growth
over
a
forty
-
year
horizon
is
the
single
best
deal
available
to
a
young
earner
.
Automate
the
contribution
monthly
.
$
7,000 /
yr
4
Clear
high
-
interest
debt
Anything
above
roughly
7%
interest
costs
more
than
the
market
reliably
returns
.
Pay
it
down
before
investing
past
the
employer
match
.
$
0
cards
5
Open
a
low
-
cost
brokerage
account
A
total
-
market
index
fund
,
one
automatic
transfer
per
month
,
and
no
further
decisions
required
.
$
300 /
mo
6
Fund
an
HSA
if
you
are
on
a
high
-
deductible
plan
Contributions
go
in
pre
-
tax
,
grow
tax
-
free
,
and
come
out
tax
-
free
for
medical
costs
.
Invest
everything
above
your
deductible
.
$
2,000 /
yr
AGES
22–29
1 / 6
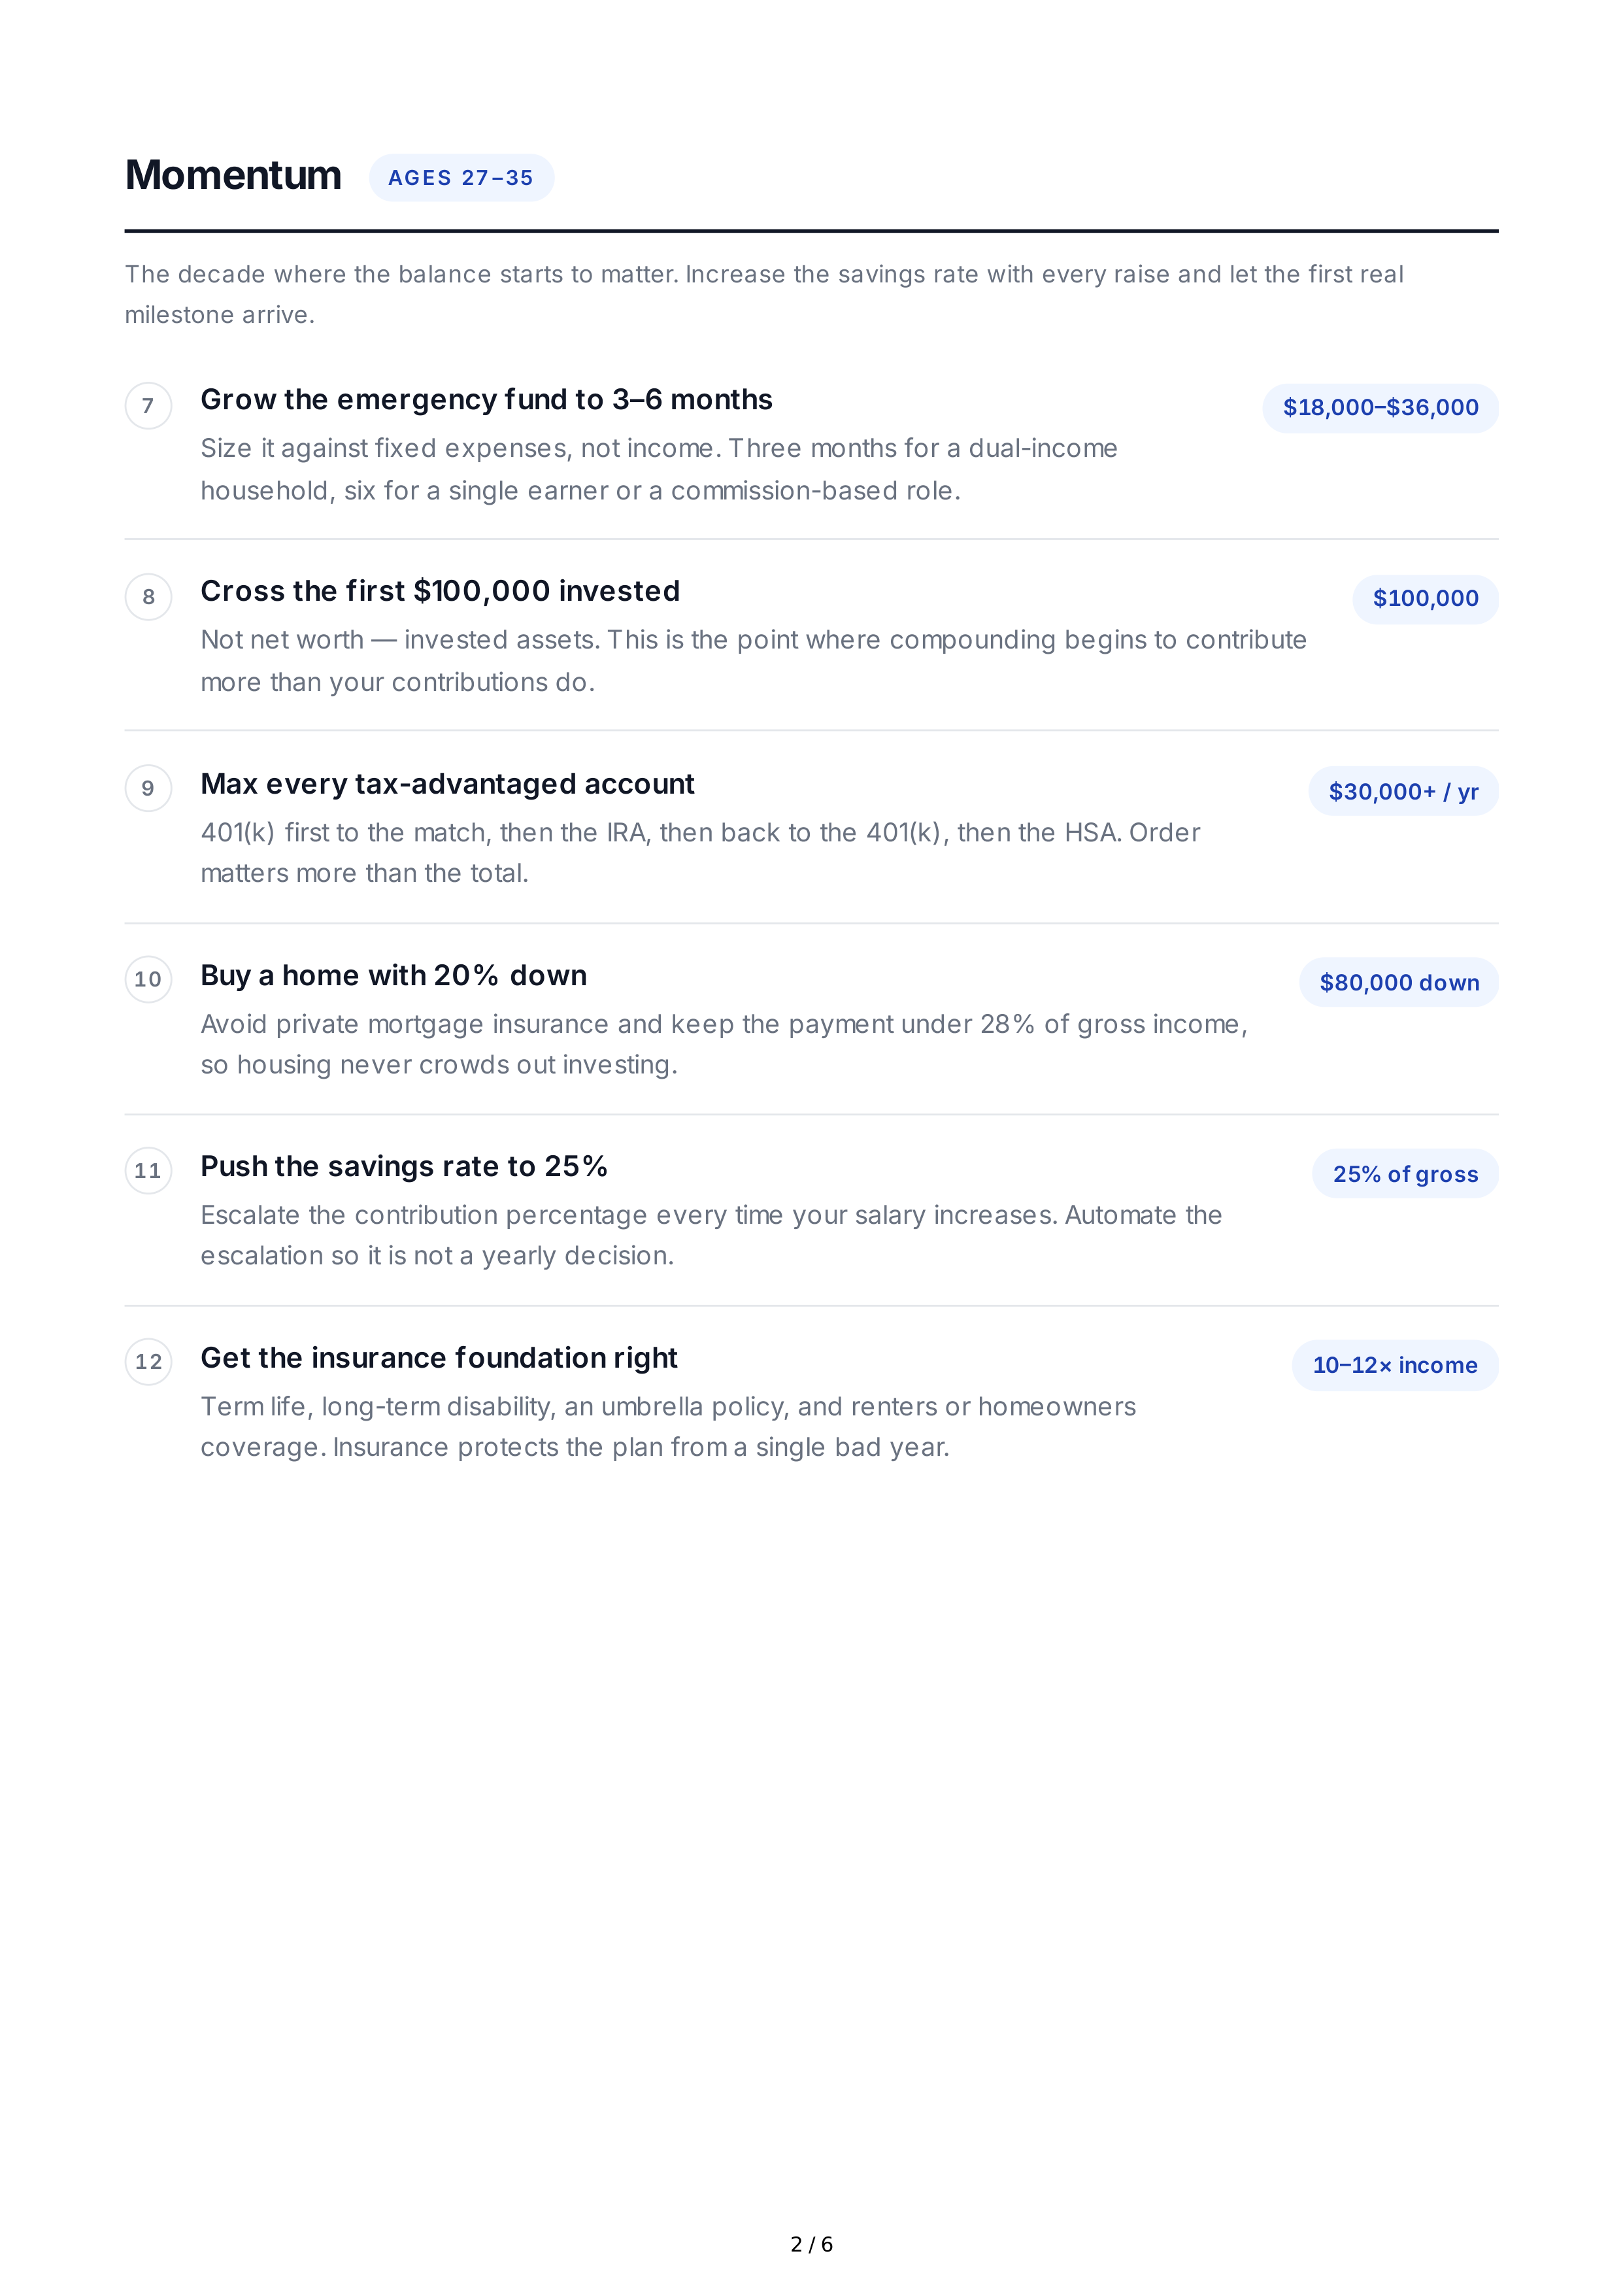
Momentum
The
decade
where
the
balance
starts
to
matter
.
Increase
the
savings
rate
with
every
raise
and
let
the
first
real
milestone
arrive
.
7
Grow
the
emergency
fund
to
3–6
months
Size
it
against
fixed
expenses
,
not
income
.
Three
months
for
a
dual
-
income
household
,
six
for
a
single
earner
or
a
commission
-
based
role
.
$
18,000–
$
36,000
8
Cross
the
first
$
100,000
invested
Not
net
worth
—
invested
assets
.
This
is
the
point
where
compounding
begins
to
contribute
more
than
your
contributions
do
.
$
100,000
9
Max
every
tax
-
advantaged
account
401(
k
)
first
to
the
match
,
then
the
IRA
,
then
back
to
the
401(
k
),
then
the
HSA
.
Order
matters
more
than
the
total
.
$
30,000+ /
yr
10
Buy
a
home
with
20%
down
Avoid
private
mortgage
insurance
and
keep
the
payment
under
28%
of
gross
income
,
so
housing
never
crowds
out
investing
.
$
80,000
down
11
Push
the
savings
rate
to
25%
Escalate
the
contribution
percentage
every
time
your
salary
increases
.
Automate
the
escalation
so
it
is
not
a
yearly
decision
.
25%
of
gross
12
Get
the
insurance
foundation
right
Term
life
,
long
-
term
disability
,
an
umbrella
policy
,
and
renters
or
homeowners
coverage
.
Insurance
protects
the
plan
from
a
single
bad
year
.
10–12×
income
AGES
27 –35
2 / 6
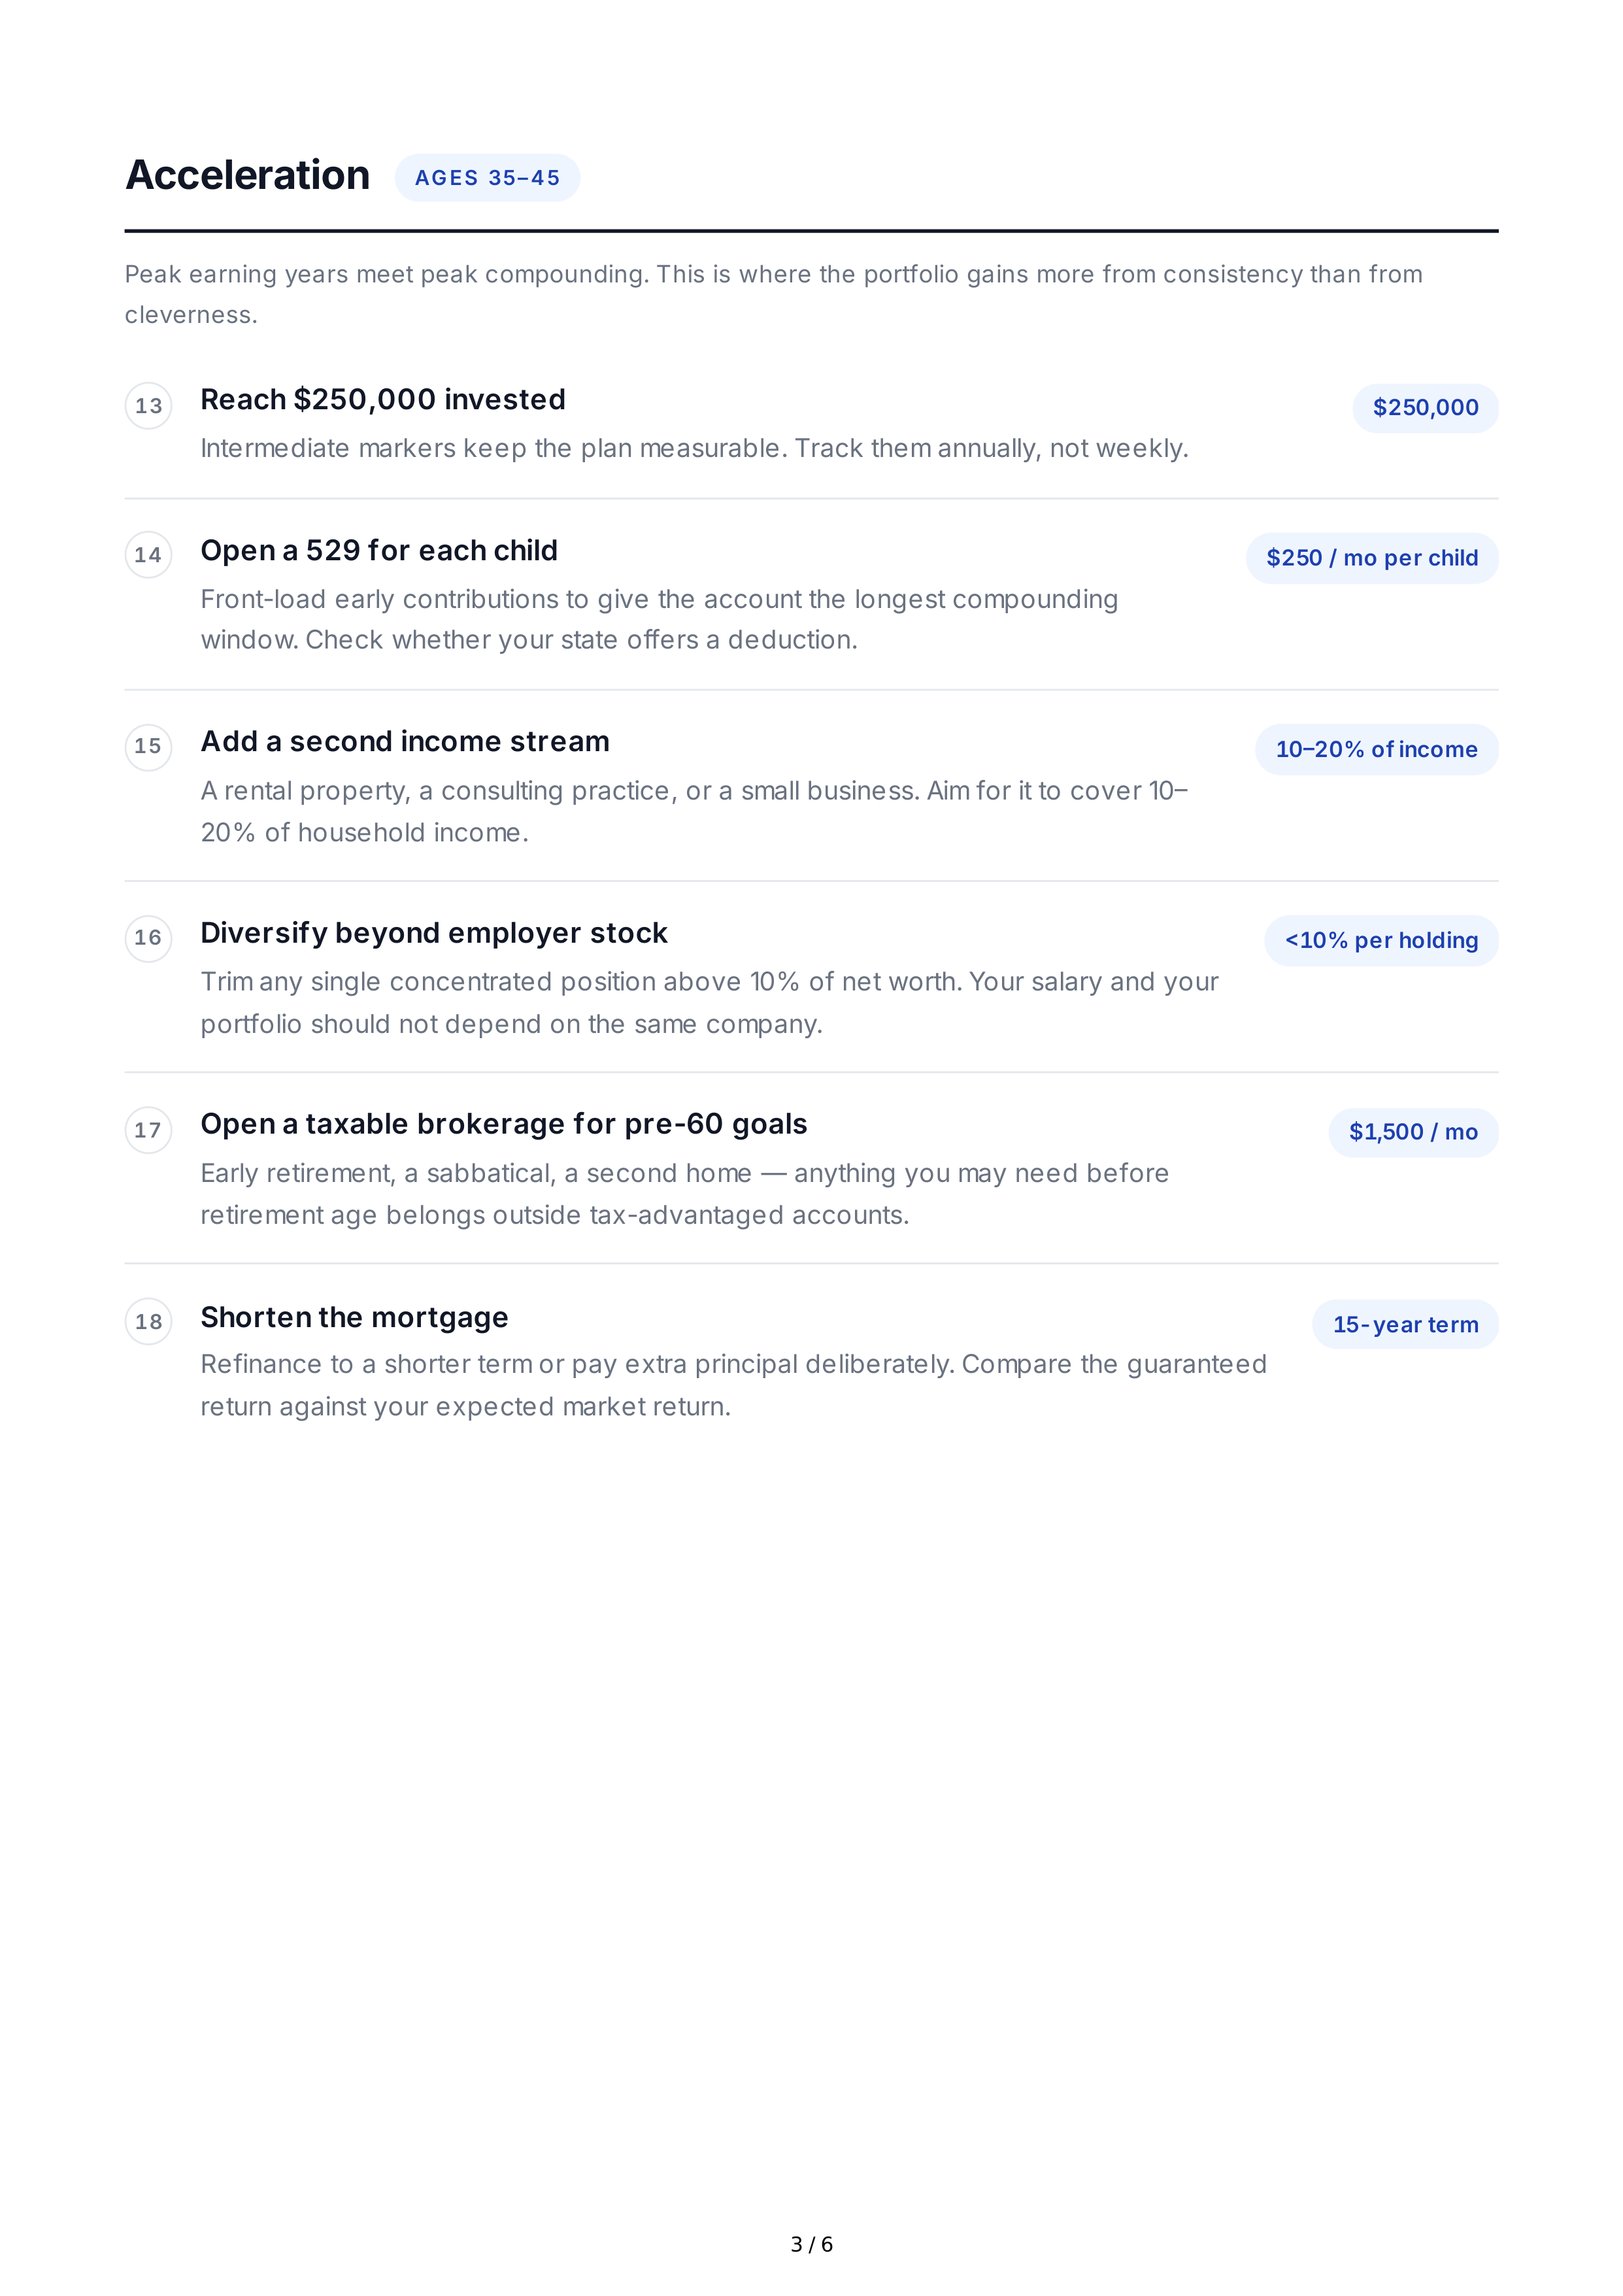
Acceleration
Peak
earning
years
meet
peak
compounding
.
This
is
where
the
portfolio
gains
more
from
consistency
than
from
cleverness
.
13
Reach
$
250,000
invested
Intermediate
markers
keep
the
plan
measurable
.
Track
them
annually
,
not
weekly
.
$
250,000
14
Open
a
529
for
each
child
Front
-
load
early
contributions
to
give
the
account
the
longest
compounding
window
.
Check
whether
your
state
offers
a
deduction
.
$
250 /
mo
per
child
15
Add
a
second
income
stream
A
rental
property
,
a
consulting
practice
,
or
a
small
business
.
Aim
for
it
to
cover
10–
20%
of
household
income
.
10–20%
of
income
16
Diversify
beyond
employer
stock
Trim
any
single
concentrated
position
above
10%
of
net
worth
.
Your
salary
and
your
portfolio
should
not
depend
on
the
same
company
.
<10%
per
holding
17
Open
a
taxable
brokerage
for
pre
-60
goals
Early
retirement
,
a
sabbatical
,
a
second
home
—
anything
you
may
need
before
retirement
age
belongs
outside
tax
-
advantaged
accounts
.
$
1,500 /
mo
18
Shorten
the
mortgage
Refinance
to
a
shorter
term
or
pay
extra
principal
deliberately
.
Compare
the
guaranteed
return
against
your
expected
market
return
.
15-
year
term
AGES
35–45
3 / 6
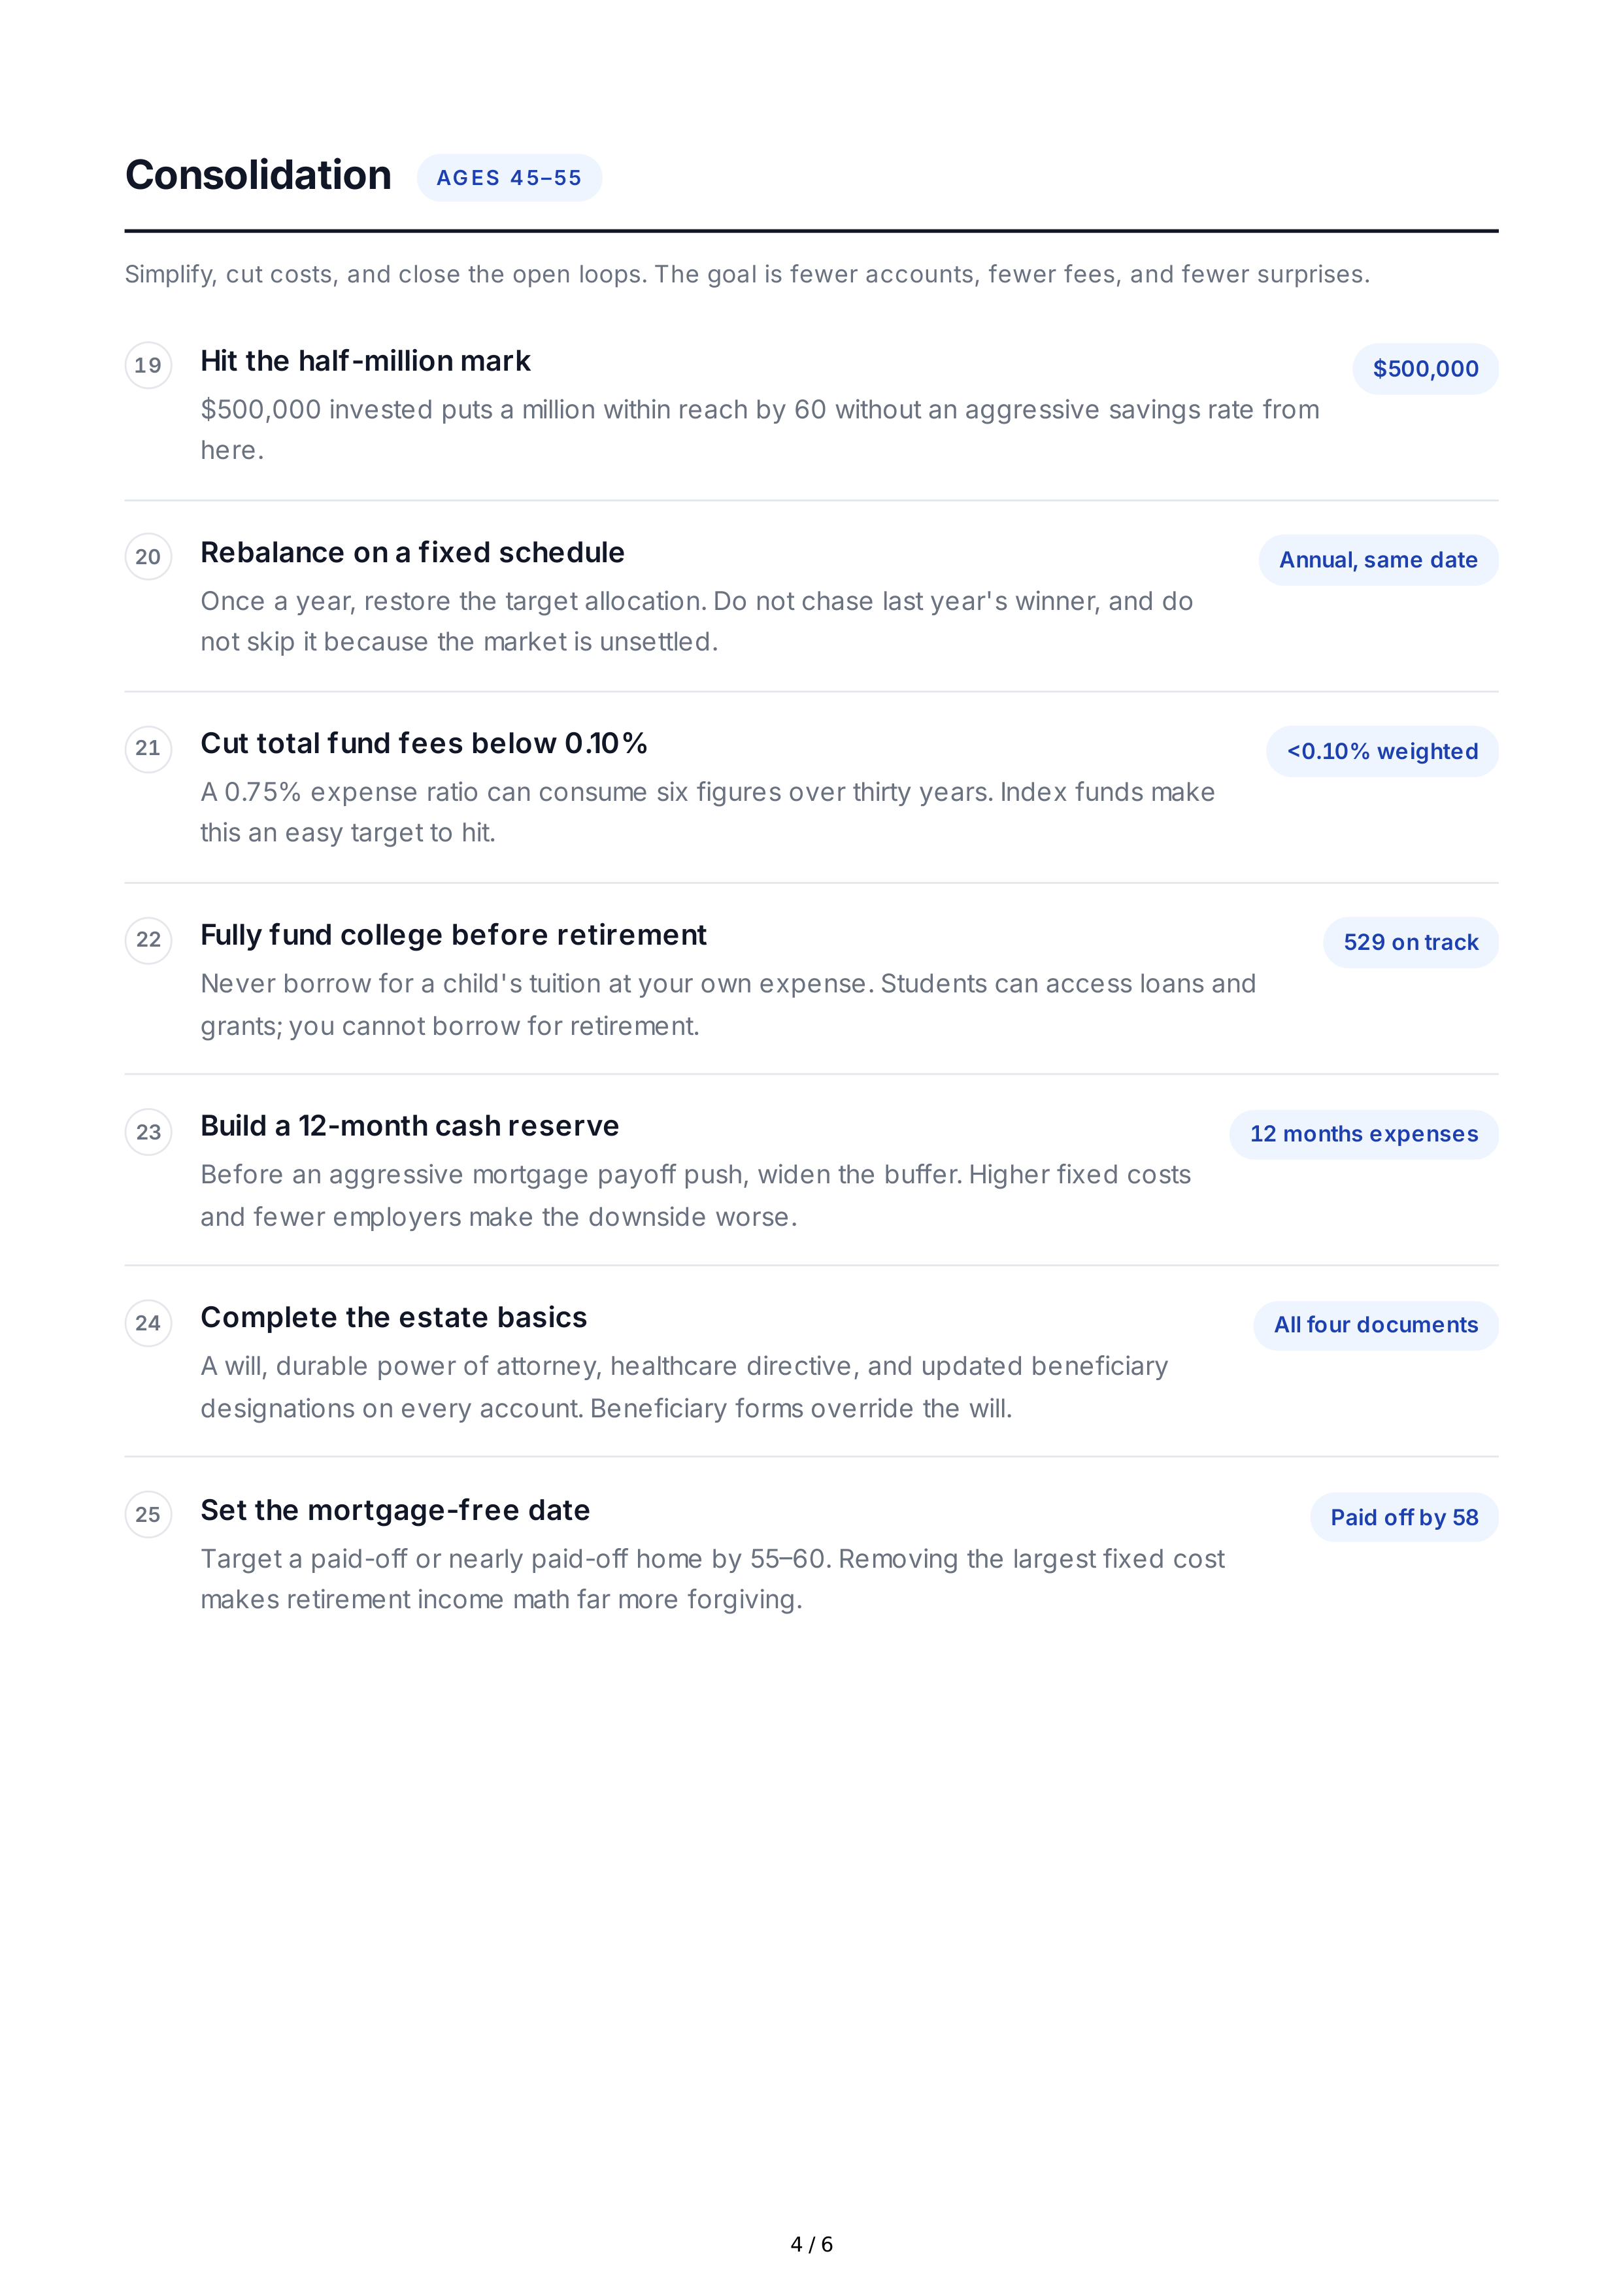
Consolidation
Simplify
,
cut
costs
,
and
close
the
open
loops
.
The
goal
is
fewer
accounts
,
fewer
fees
,
and
fewer
surprises
.
19
Hit
the
half
-
million
mark
$
500,000
invested
puts
a
million
within
reach
by
60
without
an
aggressive
savings
rate
from
here
.
$
500,000
20
Rebalance
on
a
fixed
schedule
Once
a
year
,
restore
the
target
allocation
.
Do
not
chase
last
year
'
s
winner
,
and
do
not
skip
it
because
the
market
is
unsettled
.
Annual
,
same
date
21
Cut
total
fund
fees
below
0.10%
A
0.75%
expense
ratio
can
consume
six
figures
over
thirty
years
.
Index
funds
make
this
an
easy
target
to
hit
.
<0.10%
weighted
22
Fully
fund
college
before
retirement
Never
borrow
for
a
child
'
s
tuition
at
your
own
expense
.
Students
can
access
loans
and
grants
;
you
cannot
borrow
for
retirement
.
529
on
track
23
Build
a
12-
month
cash
reserve
Before
an
aggressive
mortgage
payoff
push
,
widen
the
buffer
.
Higher
fixed
costs
and
fewer
employers
make
the
downside
worse
.
12
months
expenses
24
Complete
the
estate
basics
A
will
,
durable
power
of
attorney
,
healthcare
directive
,
and
updated
beneficiary
designations
on
every
account
.
Beneficiary
forms
override
the
will
.
All
four
documents
25
Set
the
mortgage
-
free
date
Target
a
paid
-
off
or
nearly
paid
-
off
home
by
55–60.
Removing
the
largest
fixed
cost
makes
retirement
income
math
far
more
forgiving
.
Paid
off
by
58
AGES
45–55
4 / 6
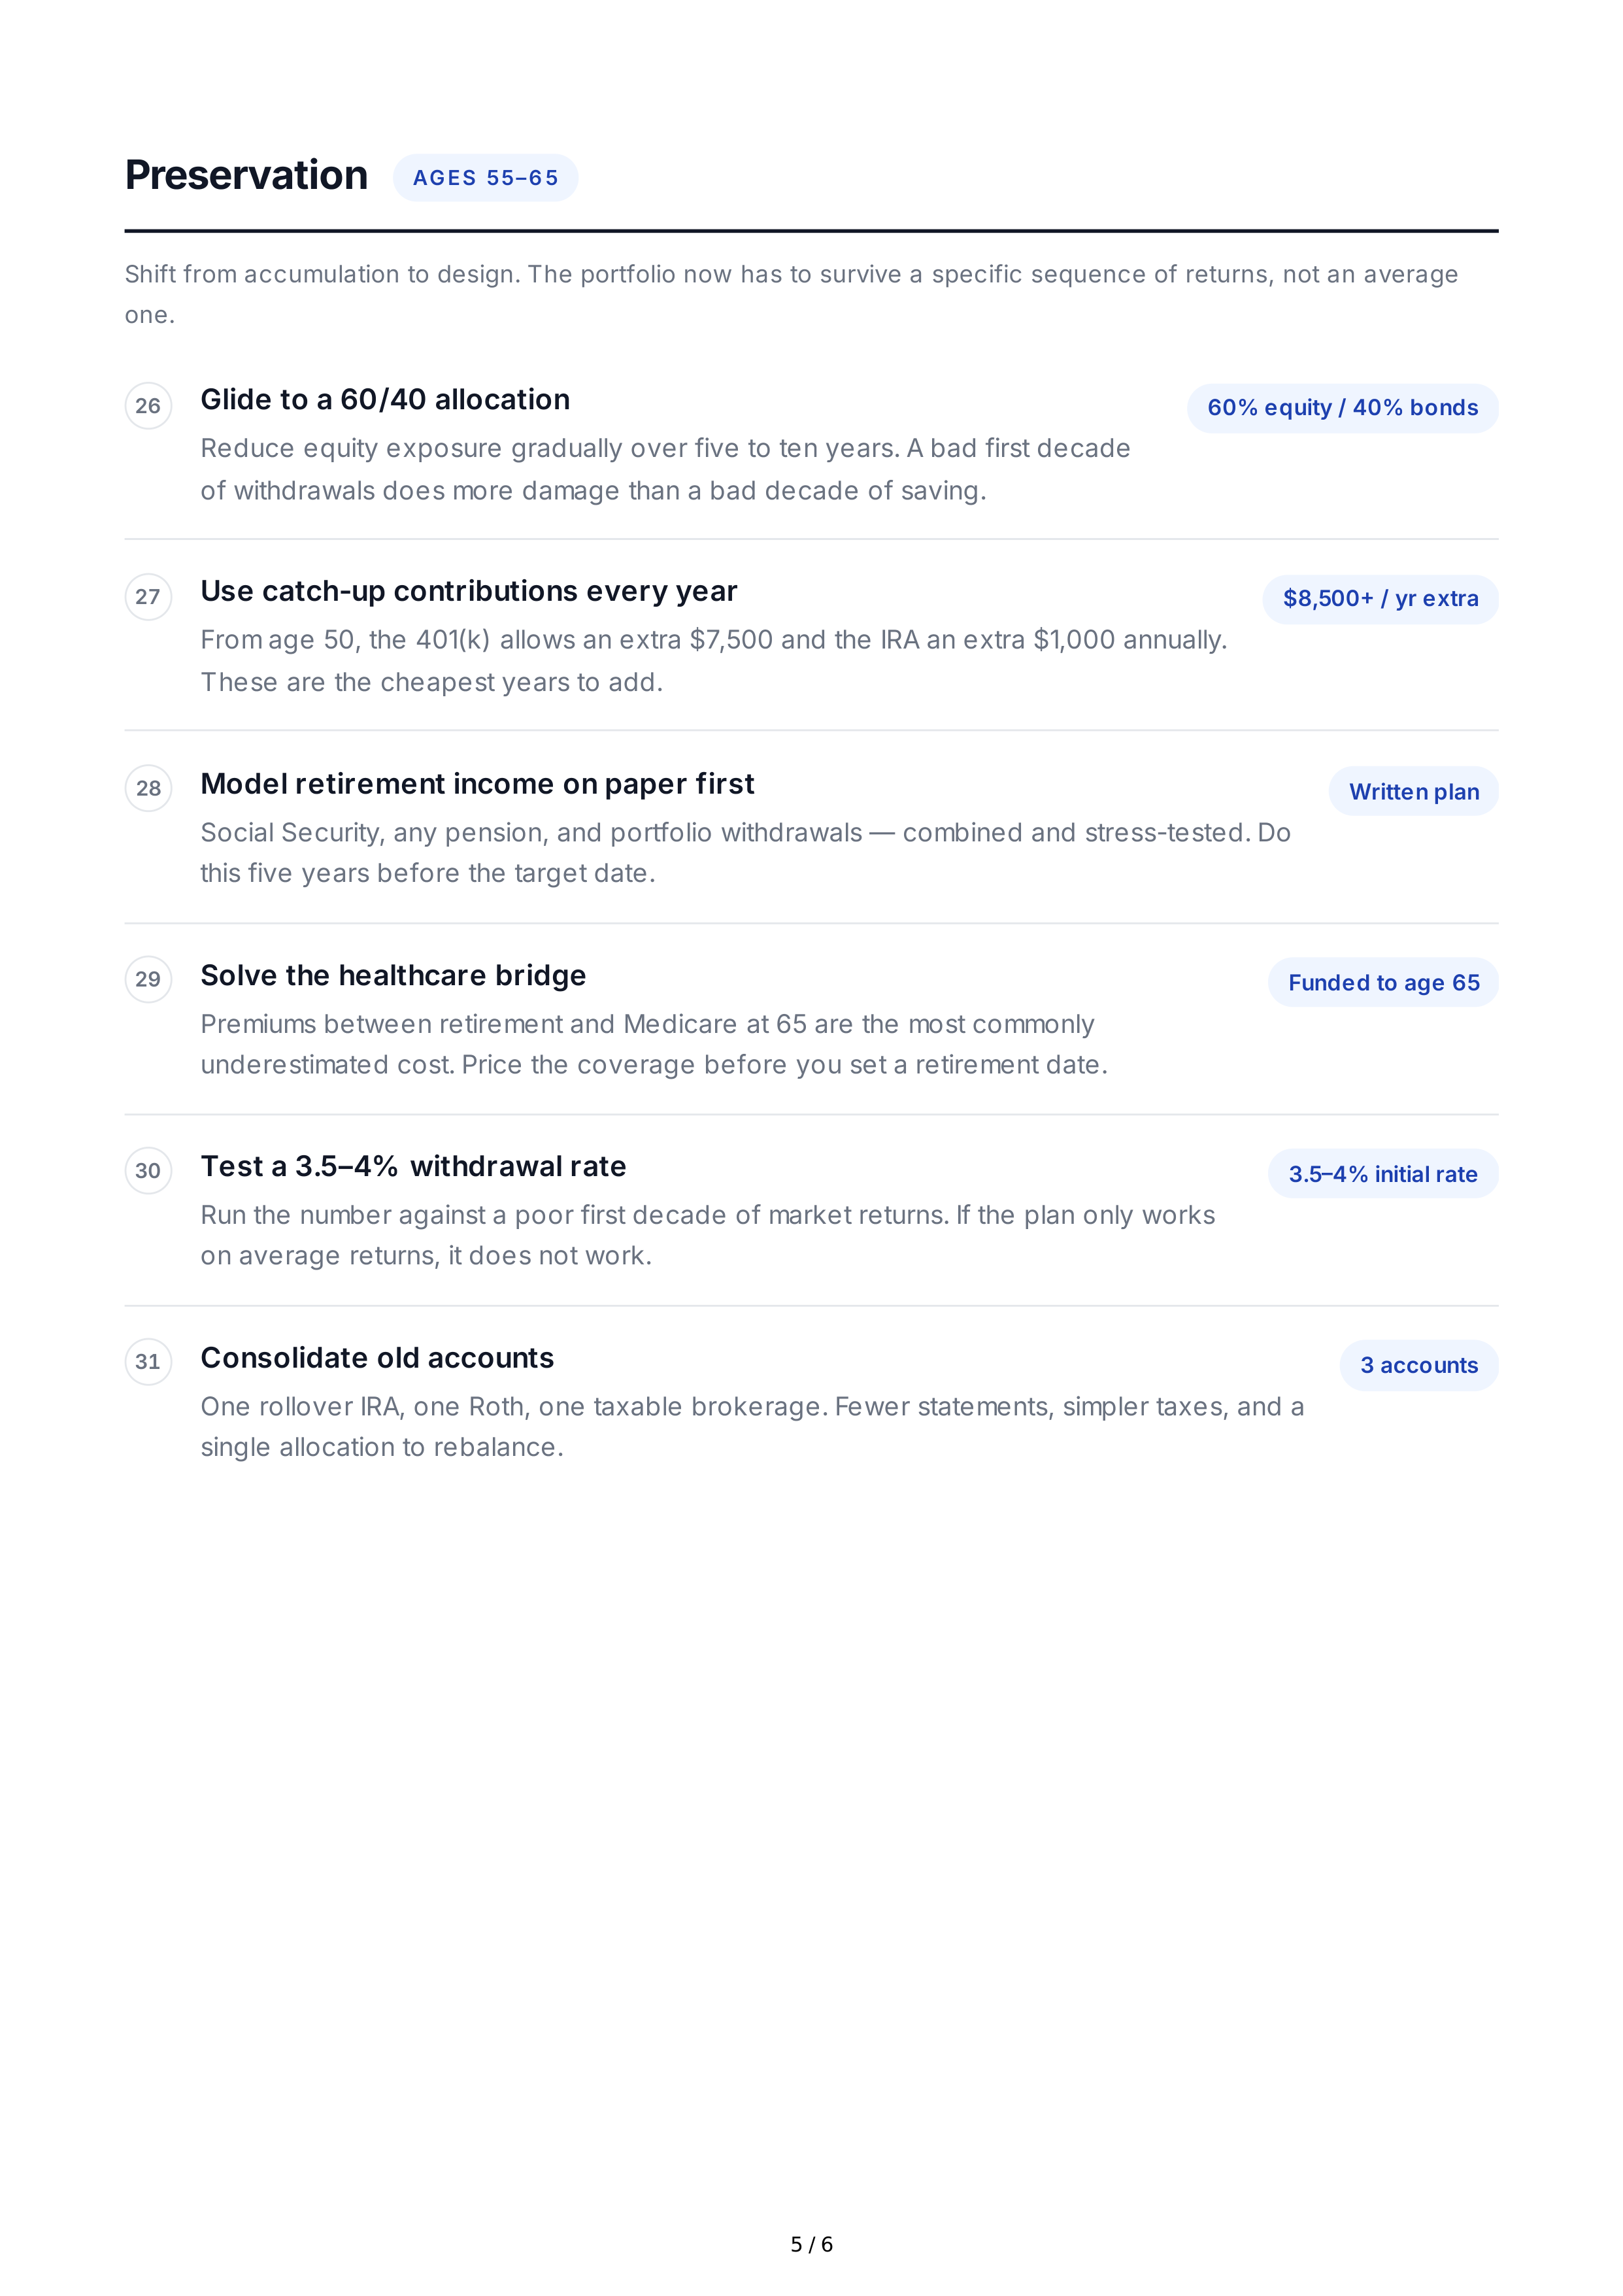
Preservation
Shift
from
accumulation
to
design
.
The
portfolio
now
has
to
survive
a
specific
sequence
of
returns
,
not
an
average
one
.
26
Glide
to
a
60/40
allocation
Reduce
equity
exposure
gradually
over
five
to
ten
years
.
A
bad
first
decade
of
withdrawals
does
more
damage
than
a
bad
decade
of
saving
.
60%
equity
/ 40%
bonds
27
Use
catch
-
up
contributions
every
year
From
age
50,
the
401(
k
)
allows
an
extra
$
7,500
and
the
IRA
an
extra
$
1,000
annually
.
These
are
the
cheapest
years
to
add
.
$
8,500+ /
yr
extra
28
Model
retirement
income
on
paper
first
Social
Security
,
any
pension
,
and
portfolio
withdrawals
—
combined
and
stress
-
tested
.
Do
this
five
years
before
the
target
date
.
Written
plan
29
Solve
the
healthcare
bridge
Premiums
between
retirement
and
Medicare
at
65
are
the
most
commonly
underestimated
cost
.
Price
the
coverage
before
you
set
a
retirement
date
.
Funded
to
age
65
30
Test
a
3.5–4%
withdrawal
rate
Run
the
number
against
a
poor
first
decade
of
market
returns
.
If
the
plan
only
works
on
average
returns
,
it
does
not
work
.
3.5–4%
initial
rate
31
Consolidate
old
accounts
One
rollover
IRA
,
one
Roth
,
one
taxable
brokerage
.
Fewer
statements
,
simpler
taxes
,
and
a
single
allocation
to
rebalance
.
3
accounts
AGES
55–6 5
5 / 6
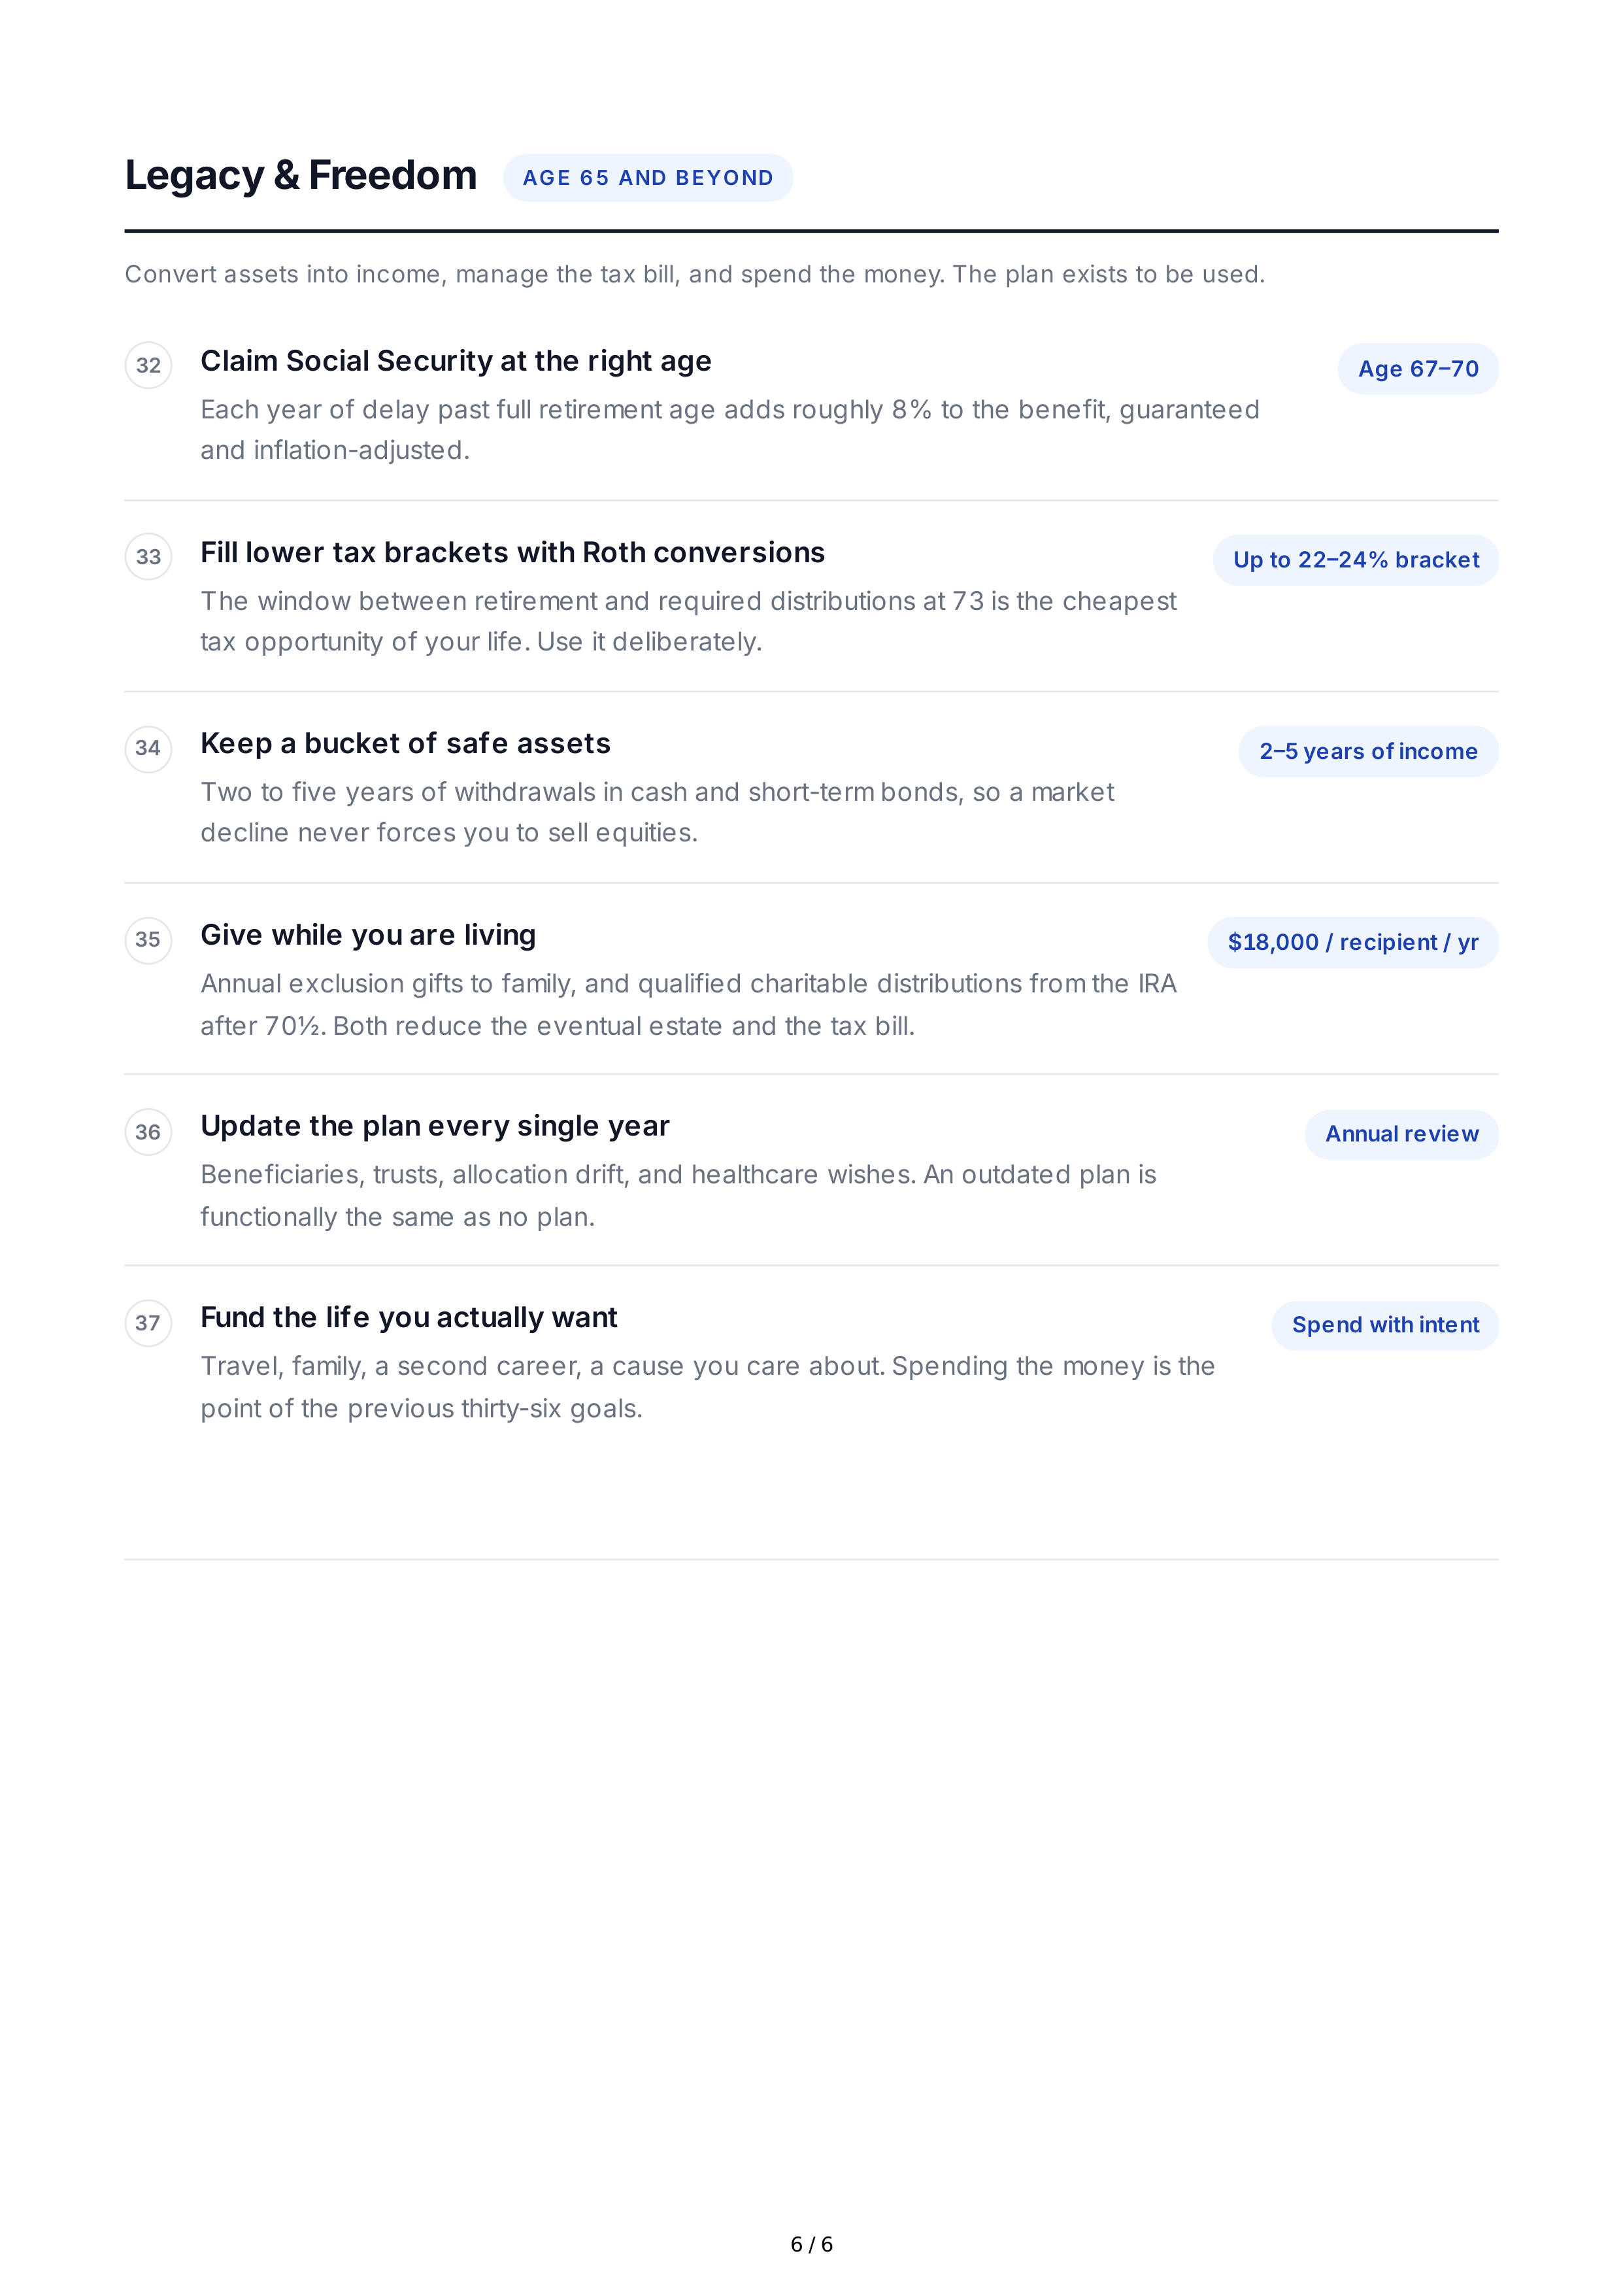
Legacy
&
Freedom
Convert
assets
into
income
,
manage
the
tax
bill
,
and
spend
the
money
.
The
plan
exists
to
be
used
.
32
Claim
Social
Security
at
the
right
age
Each
year
of
delay
past
full
retirement
age
adds
roughly
8%
to
the
benefit
,
guaranteed
and
inflation
-
adjusted
.
Age
67–70
33
Fill
lower
tax
brackets
with
Roth
conversions
The
window
between
retirement
and
required
distributions
at
73
is
the
cheapest
tax
opportunity
of
your
life
.
Use
it
deliberately
.
Up
to
22–24%
bracket
34
Keep
a
bucket
of
safe
assets
Two
to
five
years
of
withdrawals
in
cash
and
short
-
term
bonds
,
so
a
market
decline
never
forces
you
to
sell
equities
.
2–5
years
of
income
35
Give
while
you
are
living
Annual
exclusion
gifts
to
family
,
and
qualified
charitable
distributions
from
the
IRA
after
70½.
Both
reduce
the
eventual
estate
and
the
tax
bill
.
$
18,000 /
recipient
/
yr
36
Update
the
plan
every
single
year
Beneficiaries
,
trusts
,
allocation
drift
,
and
healthcare
wishes
.
An
outdated
plan
is
functionally
the
same
as
no
plan
.
Annual
review
37
Fund
the
life
you
actually
want
Travel
,
family
,
a
second
career
,
a
cause
you
care
about
.
Spending
the
money
is
the
point
of
the
previous
thirty
-
six
goals
.
Spend
with
intent
AGE
6 5
AND
BEYOND
6 / 6
Similar Examples
Generate Similar
Homeownership Life Goals
Generate Similar
Business Ownership Life Goals
Generate Similar
Entrepreneurship Life Goals
Generate Similar
Passive Income Life Goals
Generate Similar
Health Life Goals
Generate Similar
Fitness Life Goals
Generate Similar
Healthy Lifestyle Life Goals
Generate Similar
Nutrition Life Goals
Generate Similar
Weight Management Life Goals
Generate Similar
Longevity Life Goals
Generate Similar
Family Life Goals
Generate Similar
Marriage Life Goals
Generate Similar
Parenthood Life Goals
Generate Similar
Relationship Life Goals