Wealth
-
Building
Life
Goals
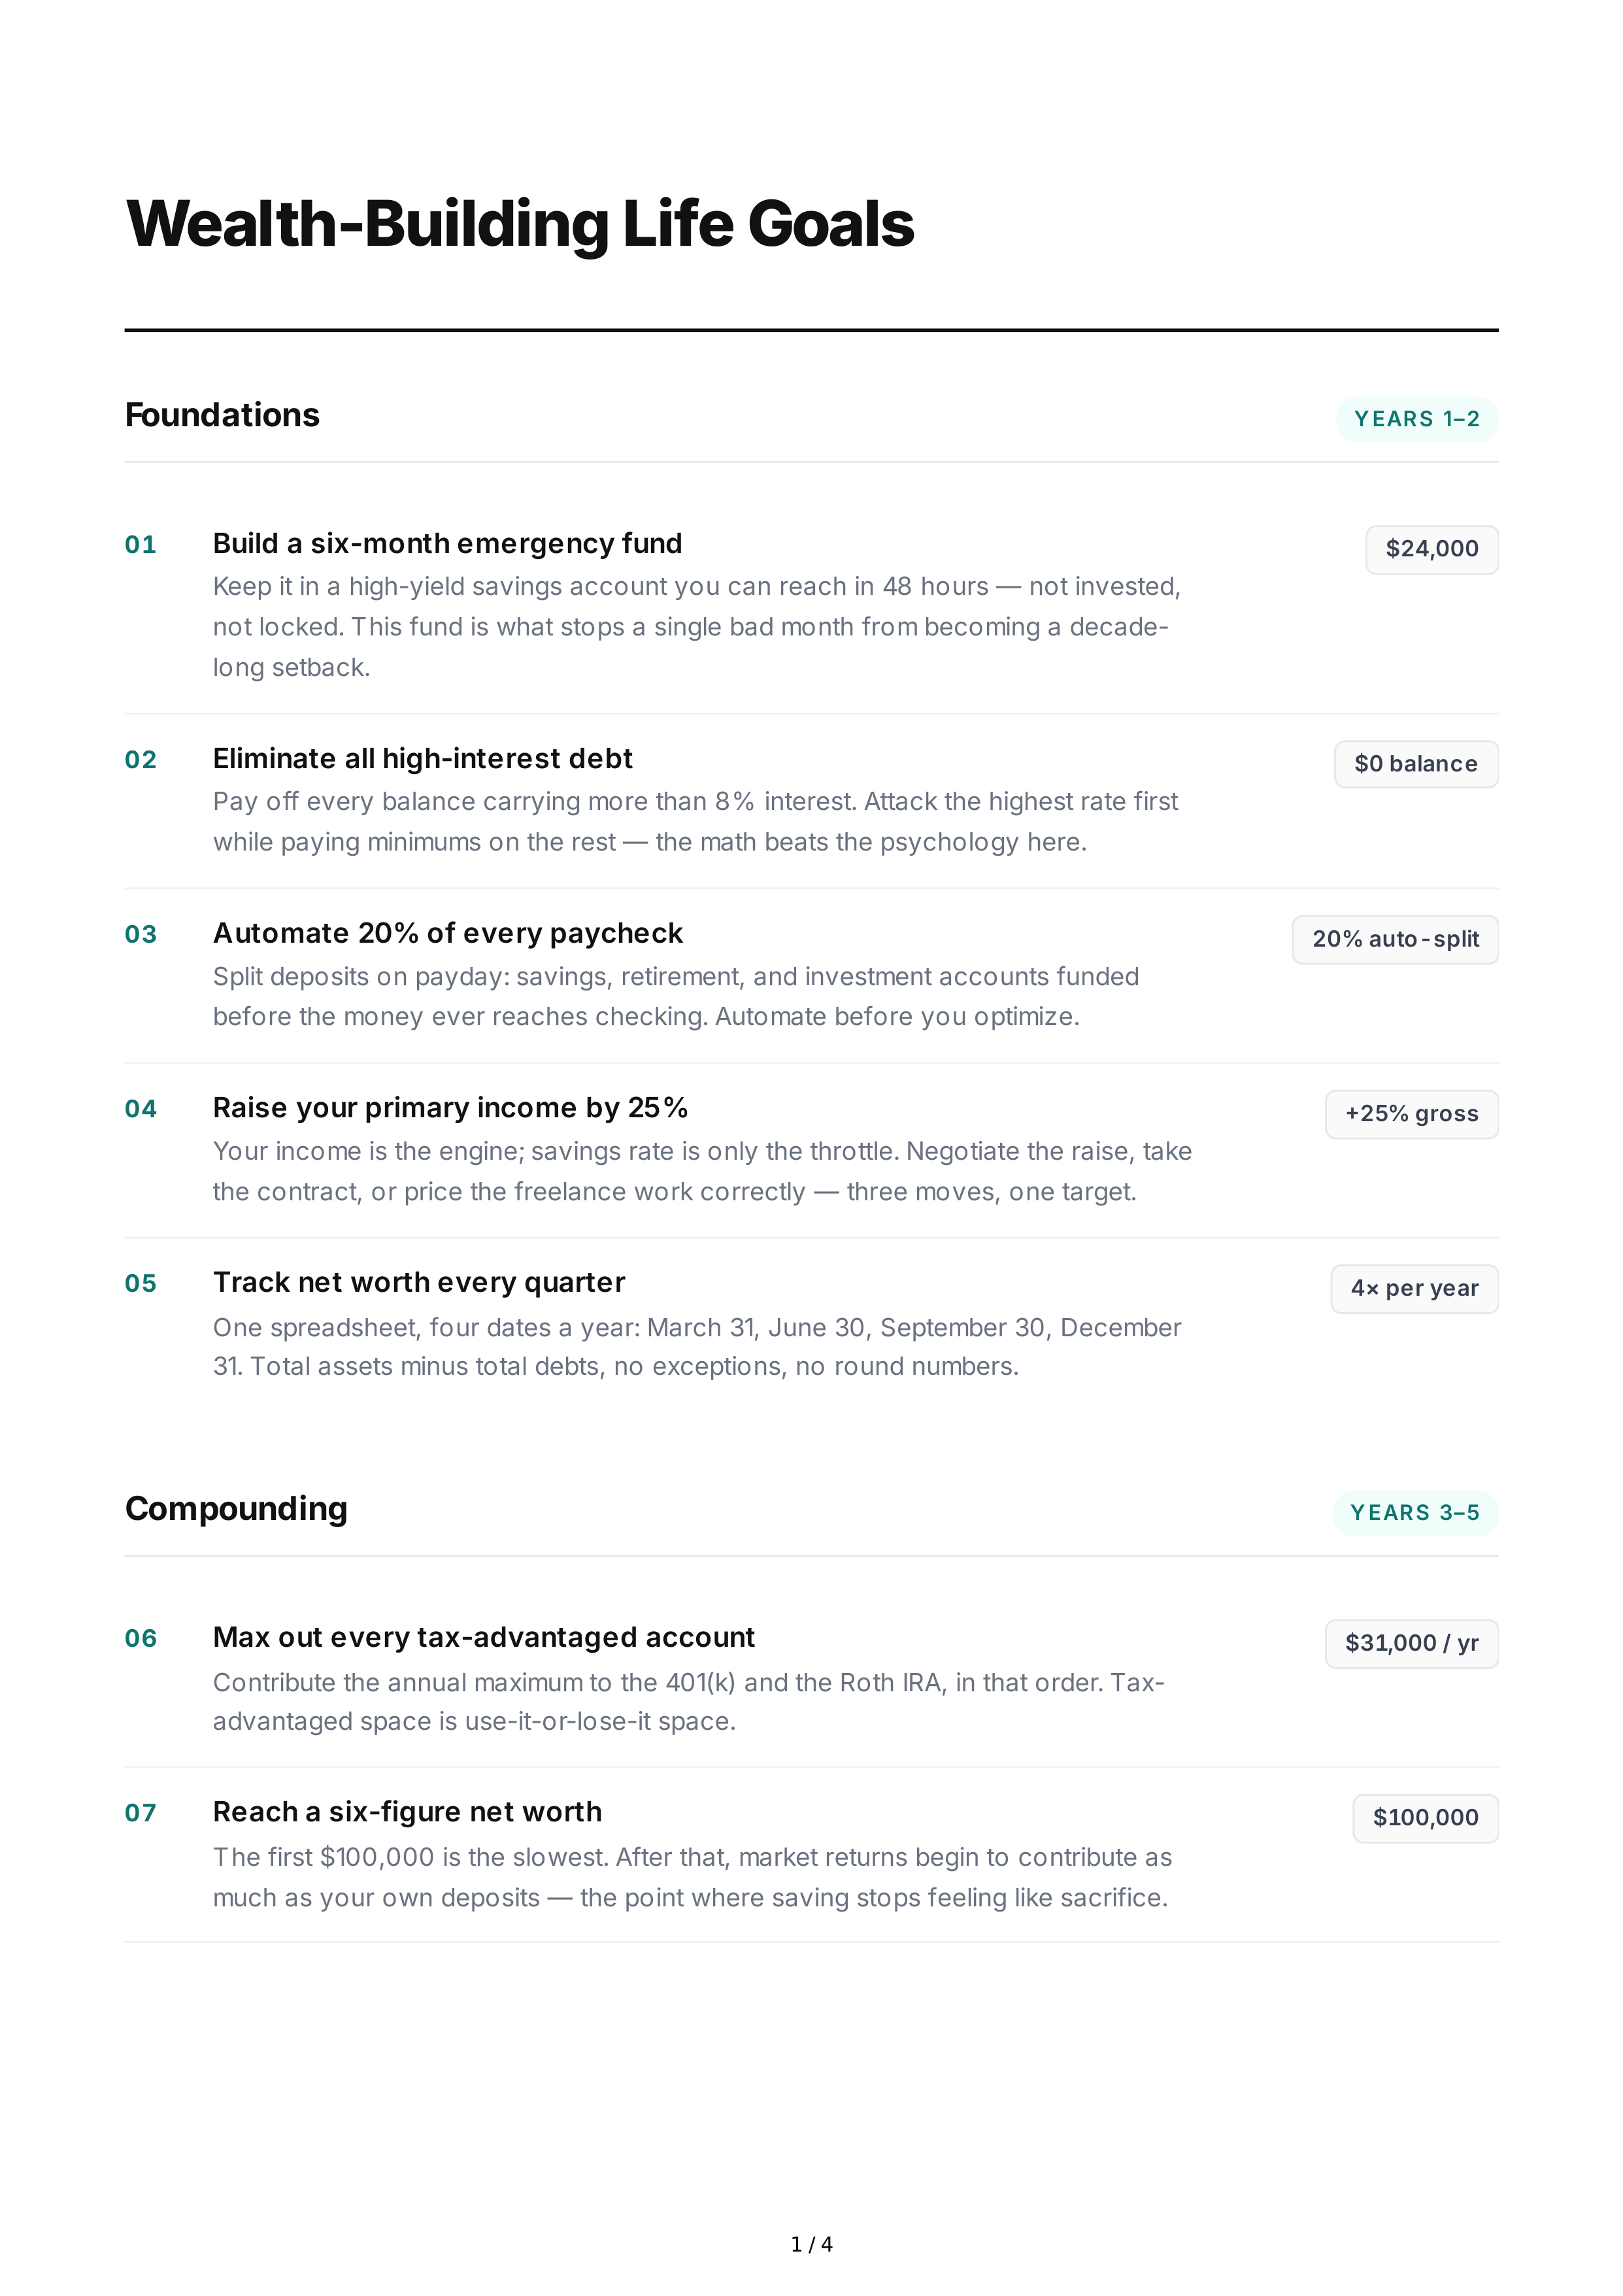
Foundations
YEARS
1–2
01
Build
a
six
-
month
emergency
fund
Keep
it
in
a
high
-
yield
savings
account
you
can
reach
in
48
hours
—
not
invested
,
not
locked
.
This
fund
is
what
stops
a
single
bad
month
from
becoming
a
decade
-
long
setback
.
$
24,000
02
Eliminate
all
high
-
interest
debt
Pay
off
every
balance
carrying
more
than
8%
interest
.
Attack
the
highest
rate
first
while
paying
minimums
on
the
rest
—
the
math
beats
the
psychology
here
.
$
0
balance
03
Automate
20%
of
every
paycheck
Split
deposits
on
payday
:
savings
,
retirement
,
and
investment
accounts
funded
before
the
money
ever
reaches
checking
.
Automate
before
you
optimize
.
20%
auto
-
split
04
Raise
your
primary
income
by
25%
Your
income
is
the
engine
;
savings
rate
is
only
the
throttle
.
Negotiate
the
raise
,
take
the
contract
,
or
price
the
freelance
work
correctly
—
three
moves
,
one
target
.
+25%
gross
05
Track
net
worth
every
quarter
One
spreadsheet
,
four
dates
a
year
:
March
31,
June
30,
September
30,
December
31.
Total
assets
minus
total
debts
,
no
exceptions
,
no
round
numbers
.
4×
per
year
Compounding
YEARS
3–5
06
Max
out
every
tax
-
advantaged
account
Contribute
the
annual
maximum
to
the
401(
k
)
and
the
Roth
IRA
,
in
that
order
.
Tax
-
advantaged
space
is
use
-
it
-
or
-
lose
-
it
space
.
$
31,000 /
yr
07
Reach
a
six
-
figure
net
worth
The
first
$
100,000
is
the
slowest
.
After
that
,
market
returns
begin
to
contribute
as
much
as
your
own
deposits
—
the
point
where
saving
stops
feeling
like
sacrifice
.
$
100,000
1 / 4
08
Launch
a
second
income
stream
Consulting
,
a
productized
service
,
a
small
digital
product
—
something
that
earns
without
requiring
your
hourly
presence
.
The
goal
is
a
second
engine
,
not
a
second
job
.
$
1,500 /
mo
09
Buy
a
first
home
Save
a
20%
down
payment
to
avoid
private
mortgage
insurance
,
and
keep
the
total
housing
cost
under
28%
of
gross
monthly
income
.
Buy
for
the
decade
,
not
the
year
.
20%
down
10
Learn
to
invest
with
conviction
Set
a
written
asset
allocation
and
a
rebalancing
rule
,
then
follow
both
through
a
full
market
cycle
.
Low
-
cost
index
funds
,
automatic
contributions
,
no
tinkering
.
Written
IPS
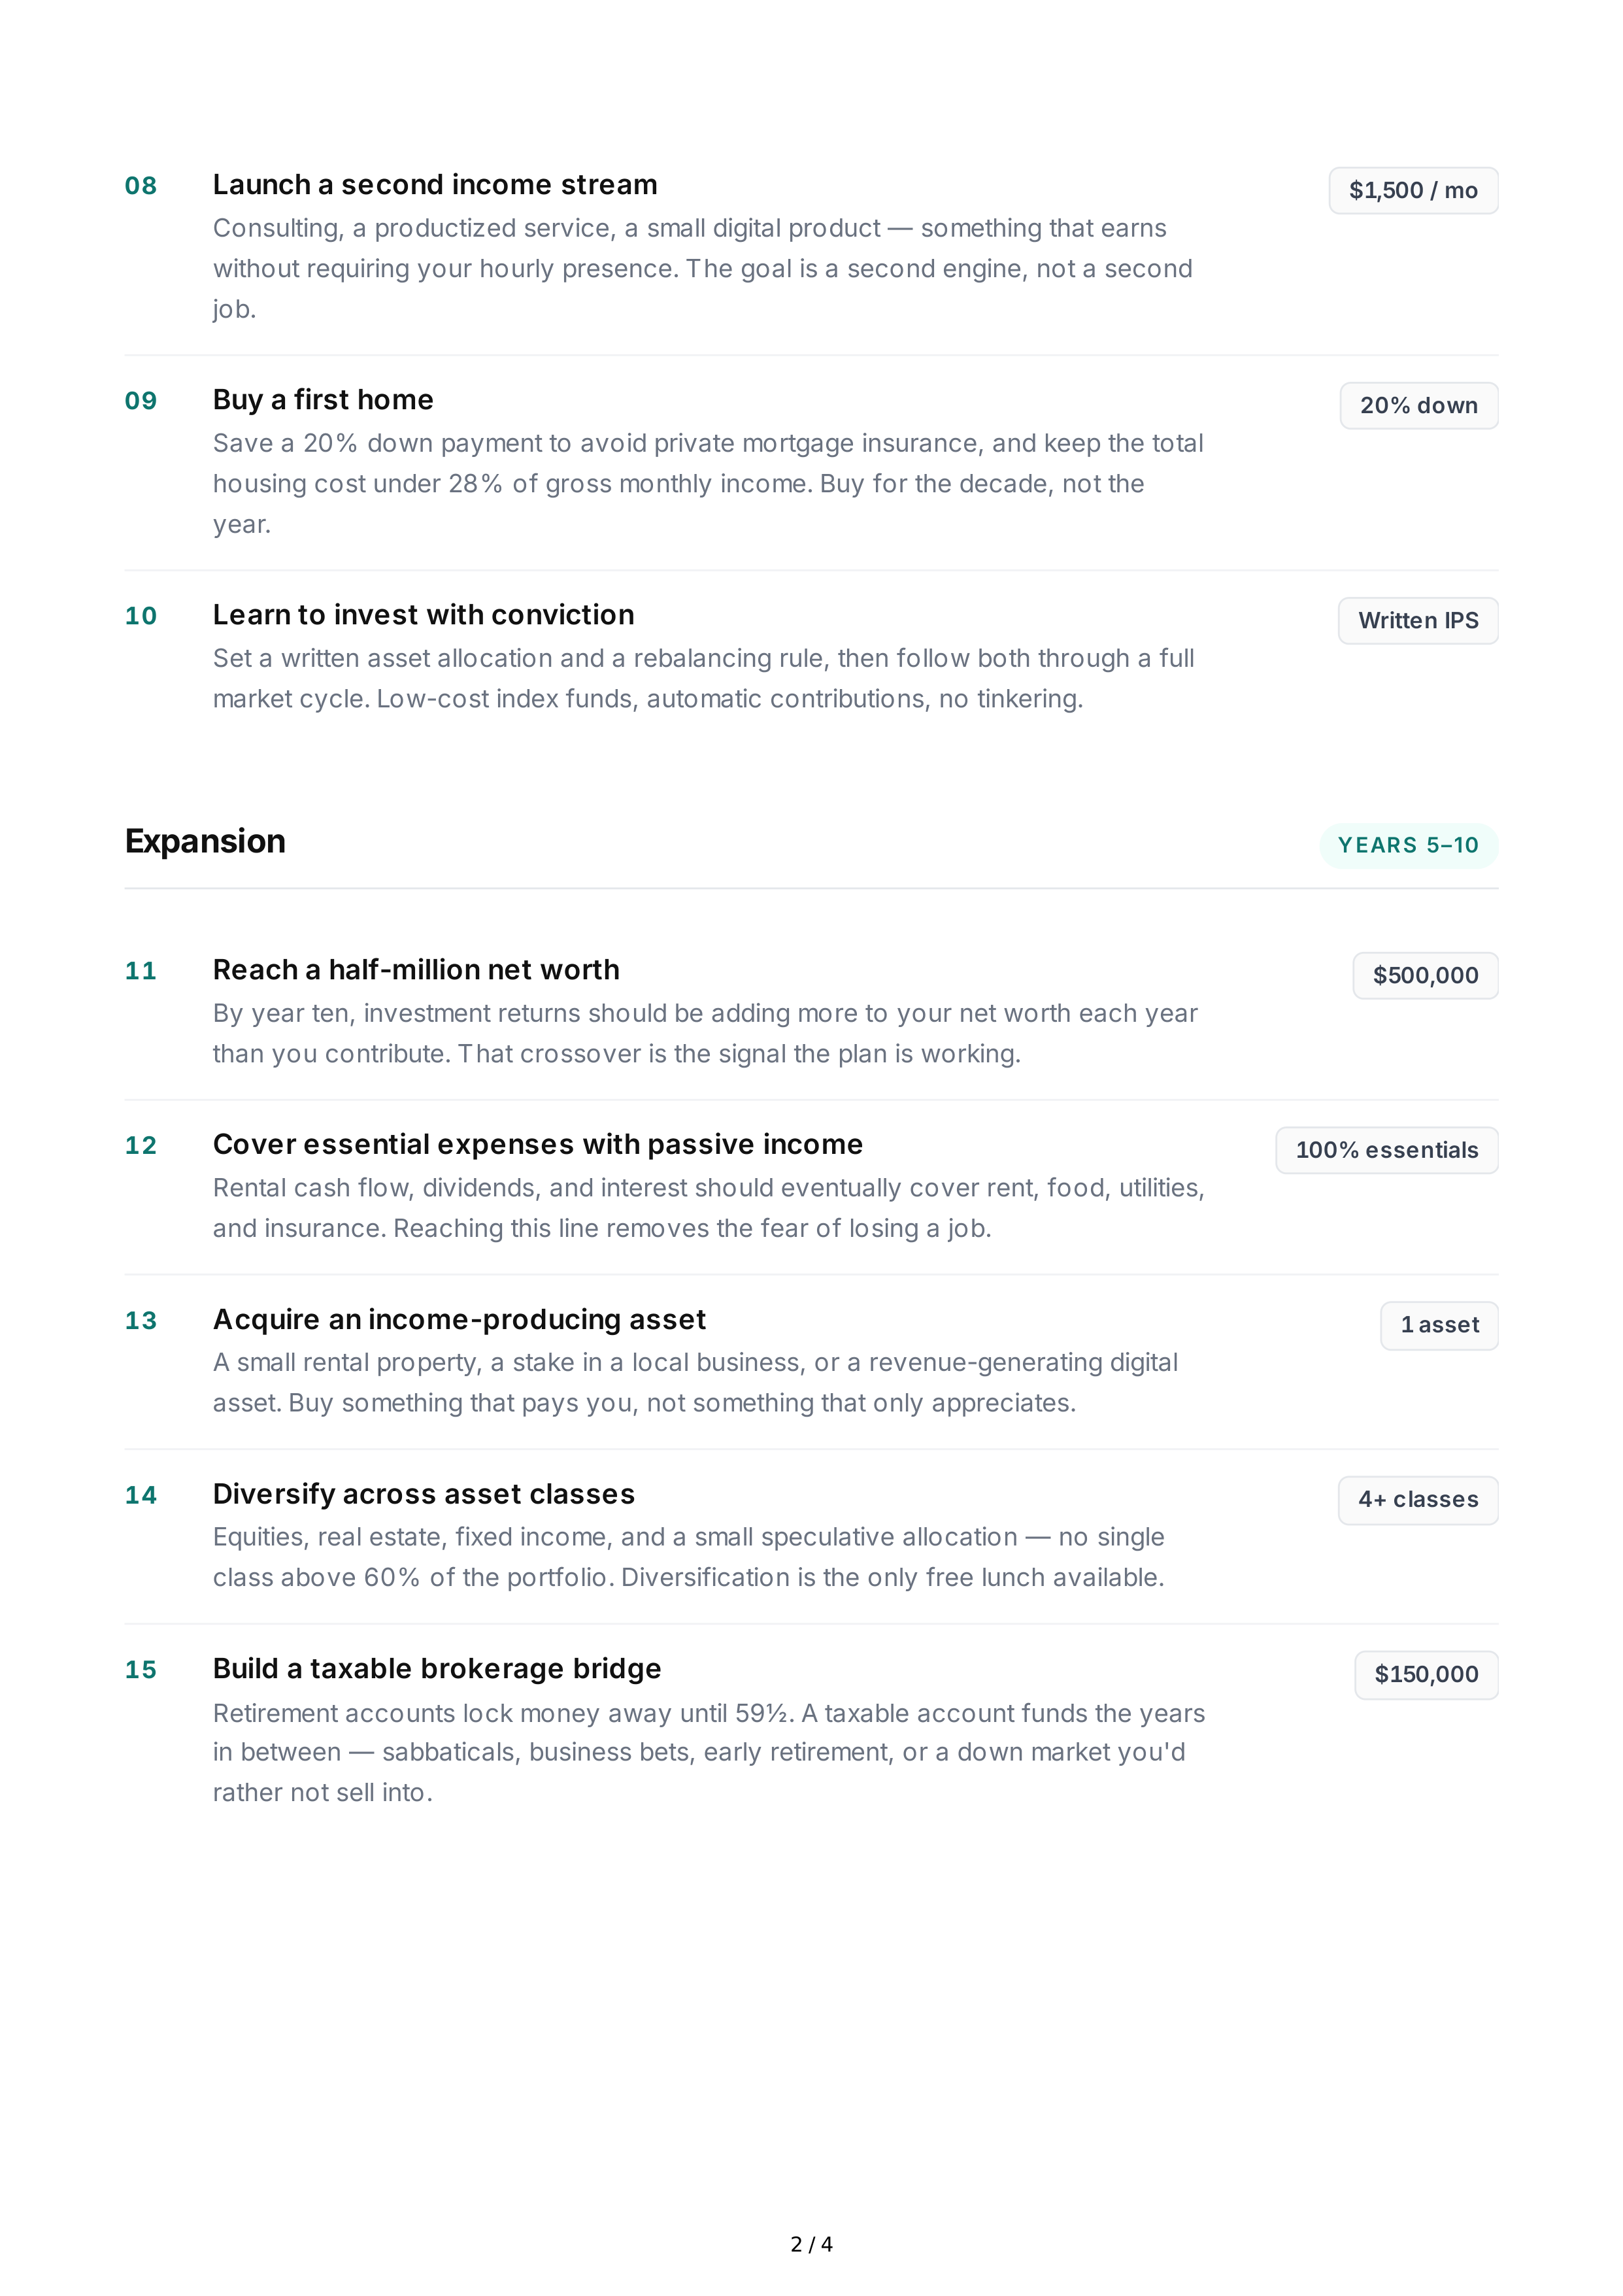
Expansion
YEARS
5–10
11
Reach
a
half
-
million
net
worth
By
year
ten
,
investment
returns
should
be
adding
more
to
your
net
worth
each
year
than
you
contribute
.
That
crossover
is
the
signal
the
plan
is
working
.
$
500,000
12
Cover
essential
expenses
with
passive
income
Rental
cash
flow
,
dividends
,
and
interest
should
eventually
cover
rent
,
food
,
utilities
,
and
insurance
.
Reaching
this
line
removes
the
fear
of
losing
a
job
.
100%
essentials
13
Acquire
an
income
-
producing
asset
A
small
rental
property
,
a
stake
in
a
local
business
,
or
a
revenue
-
generating
digital
asset
.
Buy
something
that
pays
you
,
not
something
that
only
appreciates
.
1
asset
14
Diversify
across
asset
classes
Equities
,
real
estate
,
fixed
income
,
and
a
small
speculative
allocation
—
no
single
class
above
60%
of
the
portfolio
.
Diversification
is
the
only
free
lunch
available
.
4+
classes
15
Build
a
taxable
brokerage
bridge
Retirement
accounts
lock
money
away
until
59½.
A
taxable
account
funds
the
years
in
between
—
sabbaticals
,
business
bets
,
early
retirement
,
or
a
down
market
you
'
d
rather
not
sell
into
.
$
150,000
2 / 4
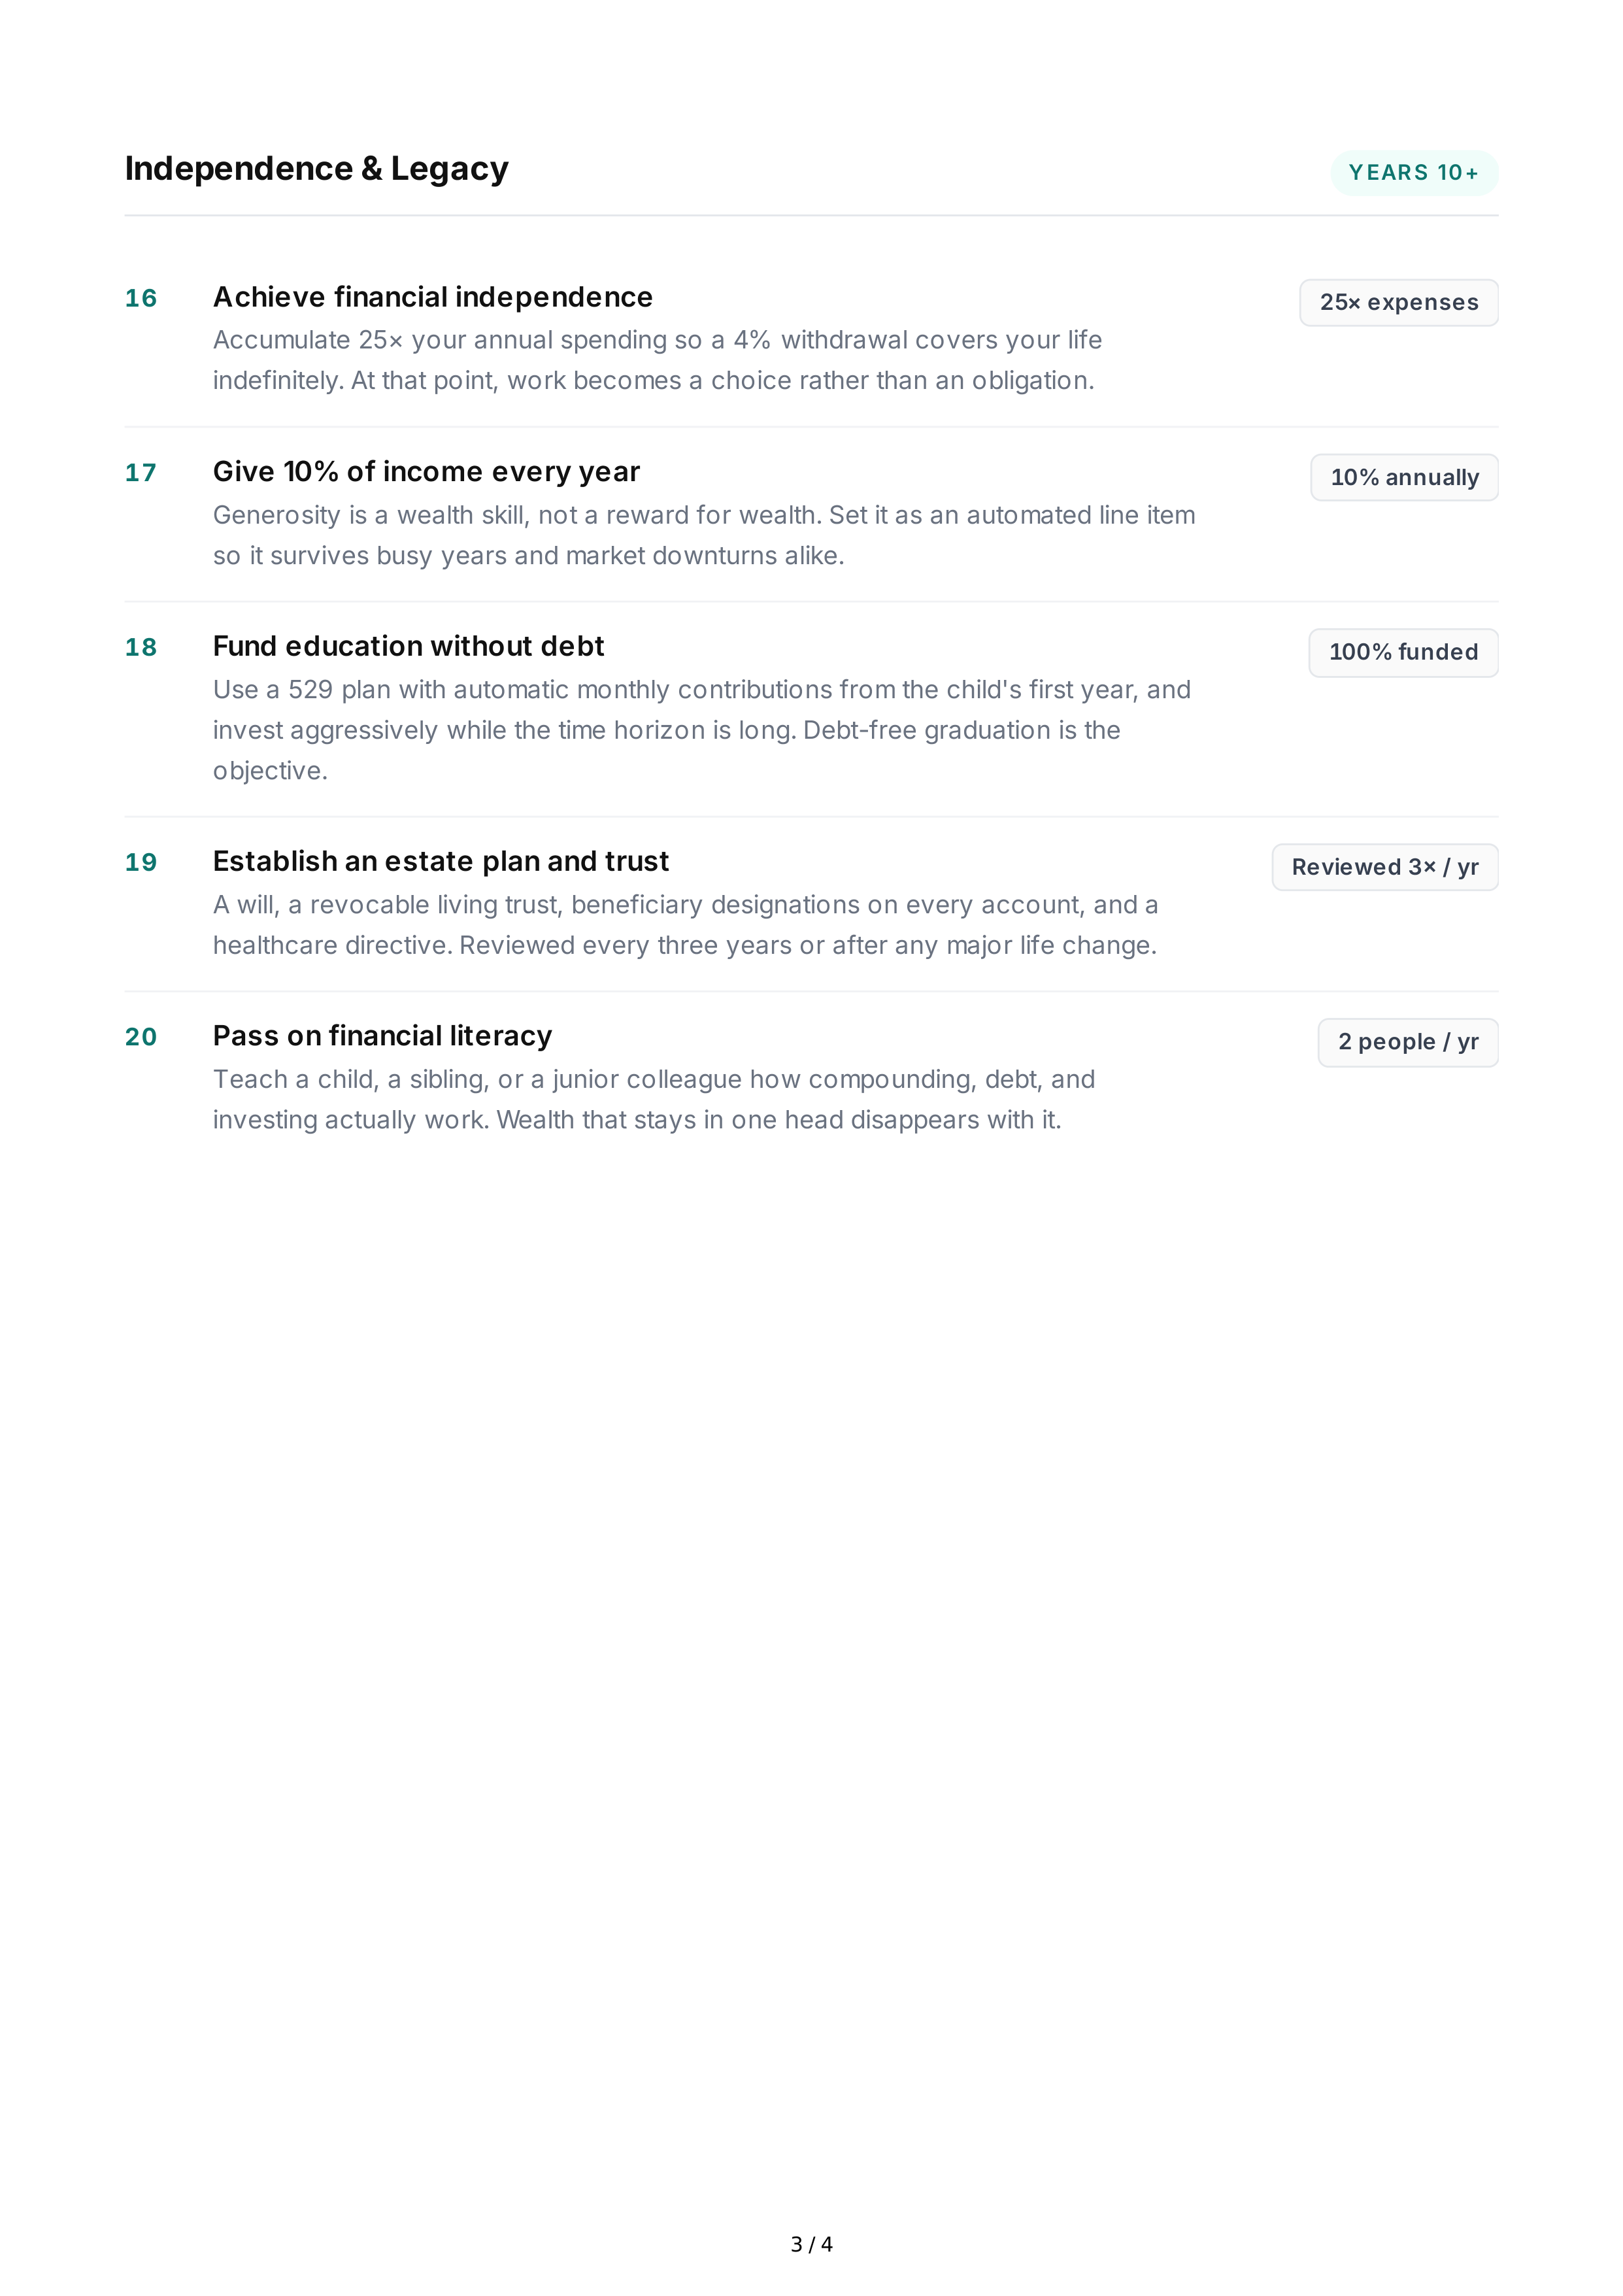
Independence
&
Legacy
YEARS
10+
16
Achieve
financial
independence
Accumulate
25×
your
annual
spending
so
a
4%
withdrawal
covers
your
life
indefinitely
.
At
that
point
,
work
becomes
a
choice
rather
than
an
obligation
.
25×
expenses
17
Give
10%
of
income
every
year
Generosity
is
a
wealth
skill
,
not
a
reward
for
wealth
.
Set
it
as
an
automated
line
item
so
it
survives
busy
years
and
market
downturns
alike
.
10%
annually
18
Fund
education
without
debt
Use
a
529
plan
with
automatic
monthly
contributions
from
the
child
'
s
first
year
,
and
invest
aggressively
while
the
time
horizon
is
long
.
Debt
-
free
graduation
is
the
objective
.
100%
funded
19
Establish
an
estate
plan
and
trust
A
will
,
a
revocable
living
trust
,
beneficiary
designations
on
every
account
,
and
a
healthcare
directive
.
Reviewed
every
three
years
or
after
any
major
life
change
.
Reviewed
3× /
yr
20
Pass
on
financial
literacy
Teach
a
child
,
a
sibling
,
or
a
junior
colleague
how
compounding
,
debt
,
and
investing
actually
work
.
Wealth
that
stays
in
one
head
disappears
with
it
.
2
people
/
yr
3 / 4
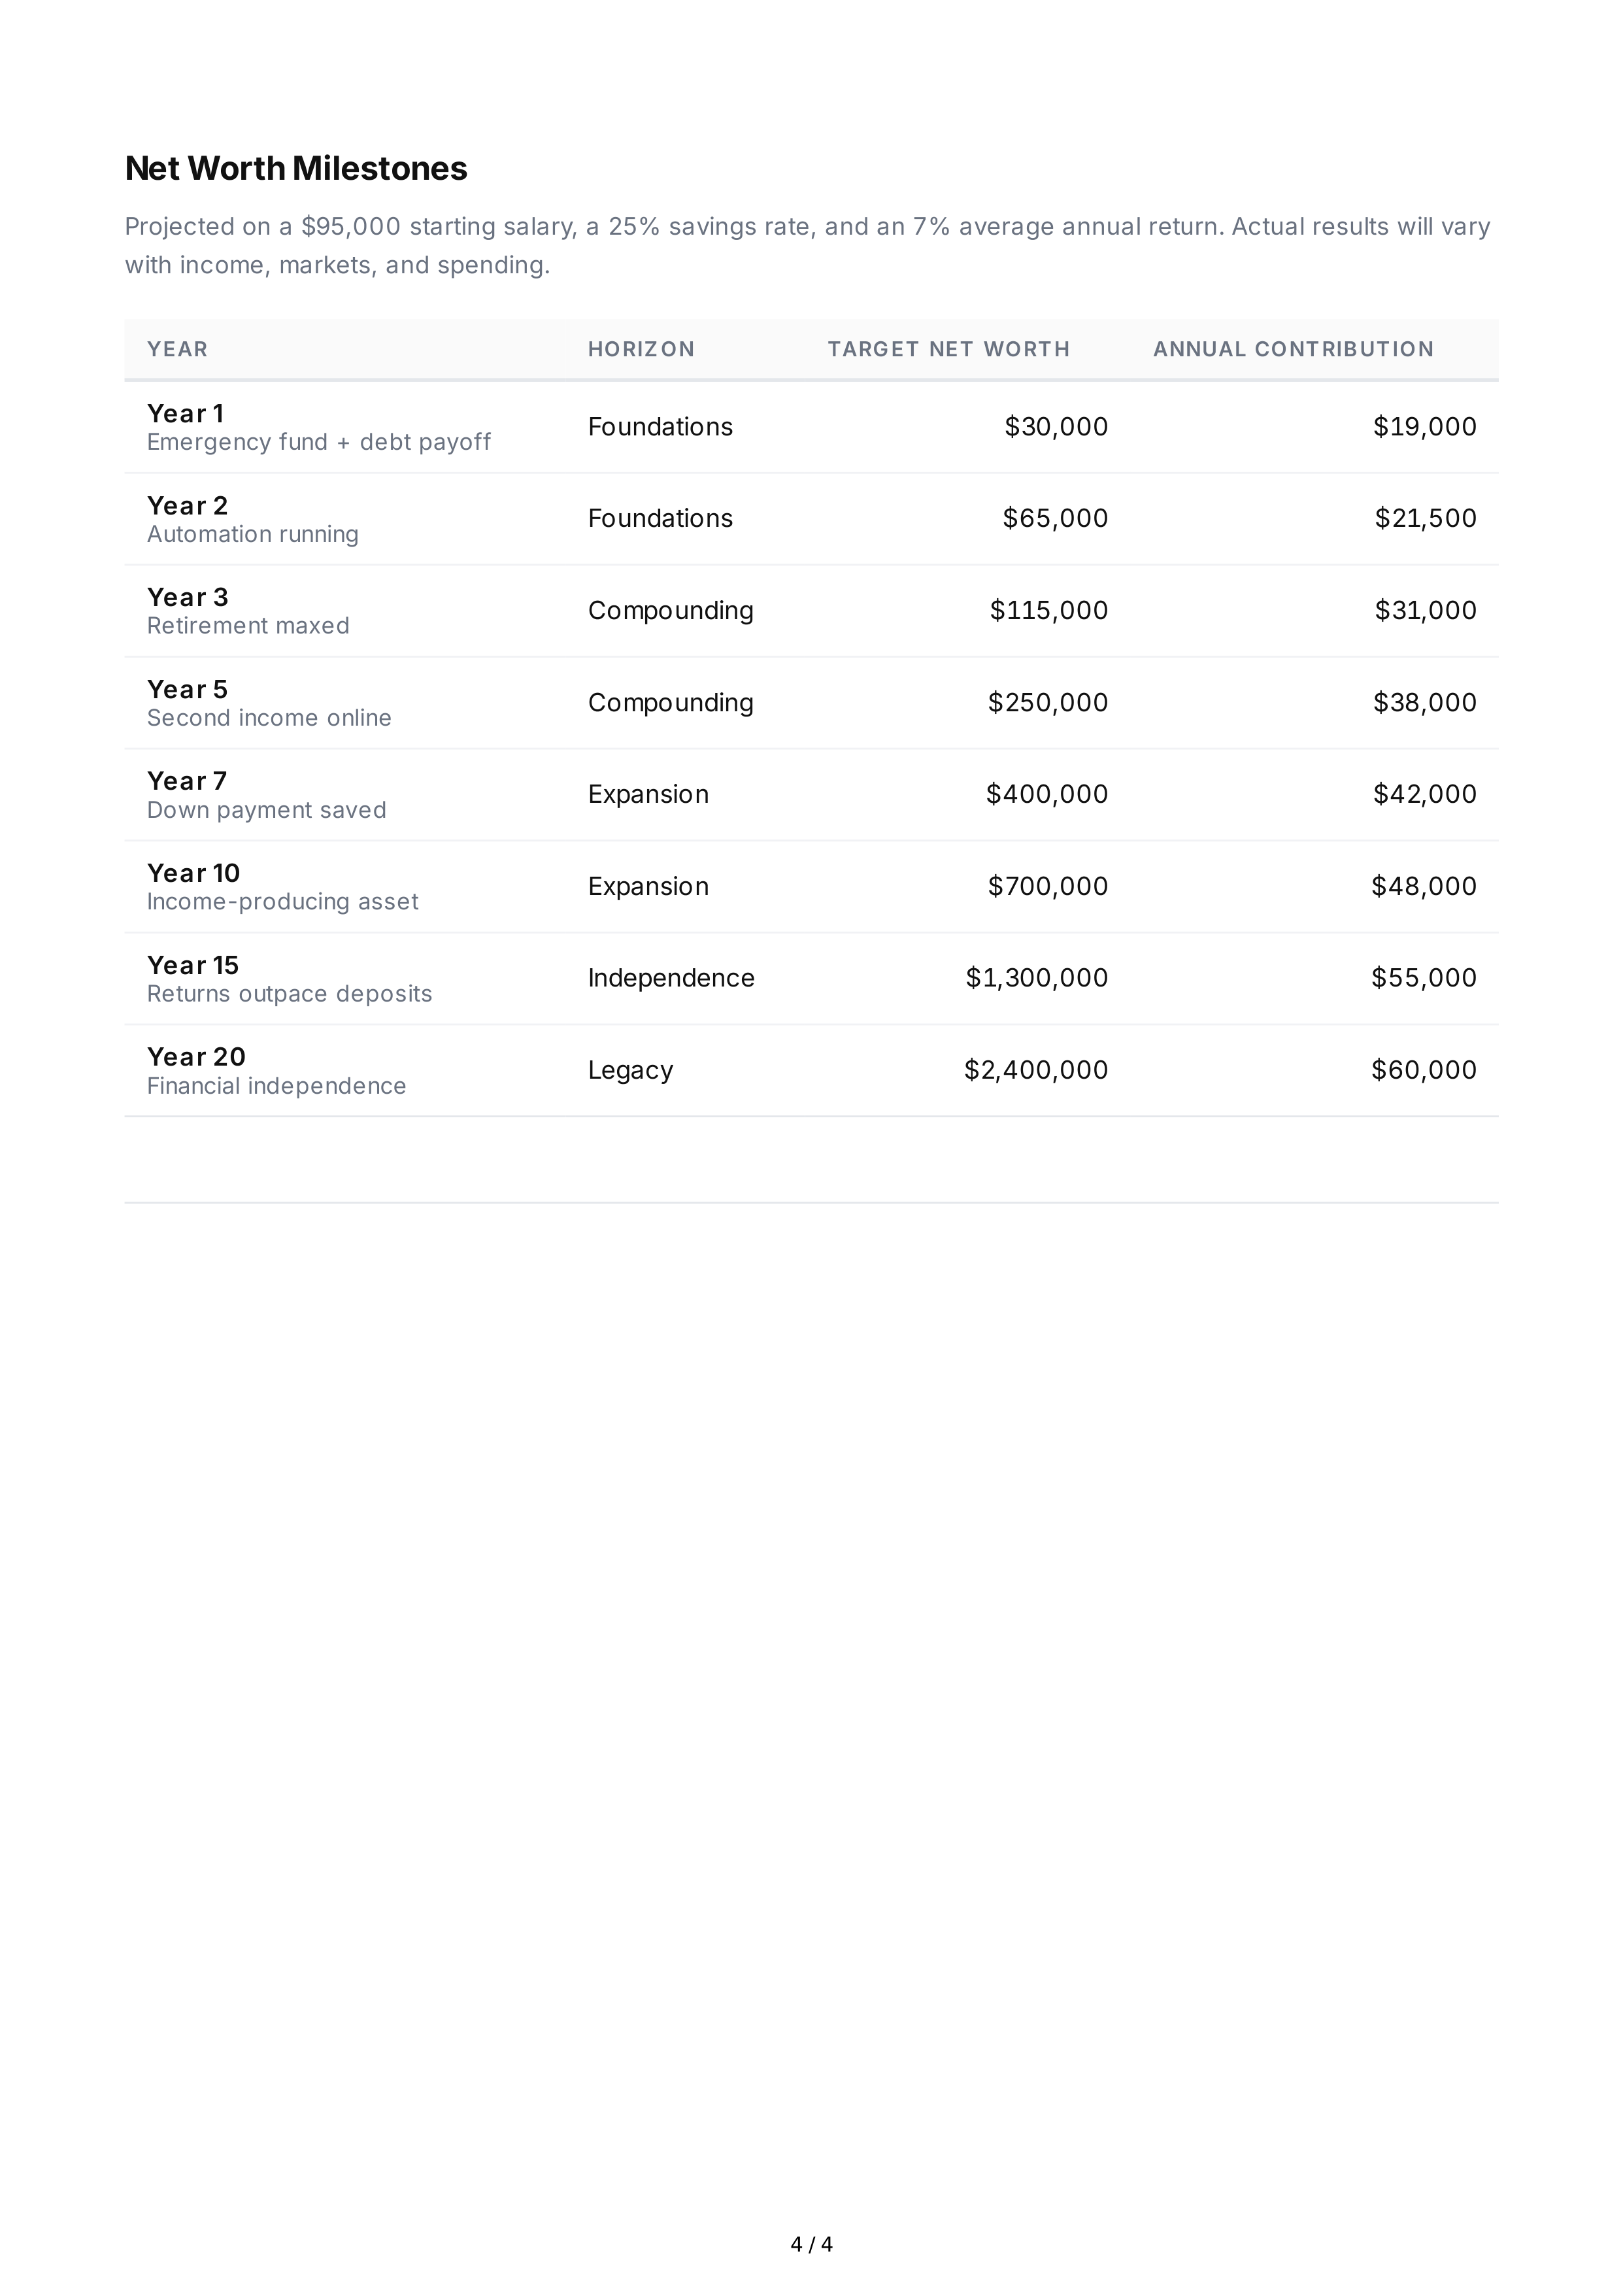
Net
Worth
Milestones
Projected
on
a
$
95,000
starting
salary
,
a
25%
savings
rate
,
and
an
7%
average
annual
return
.
Actual
results
will
vary
with
income
,
markets
,
and
spending
.
YEAR
HORIZON
TARGET
NET
WORTH
ANNUAL
CONTRIBUTION
Year
1
Emergency
fund
+
debt
payoff
Foundations
$
30,000
$
19,000
Year
2
Automation
running
Foundations
$
65,000
$
21,500
Year
3
Retirement
maxed
Compounding
$
115,000
$
31,000
Year
5
Second
income
online
Compounding
$
250,000
$
38,000
Year
7
Down
payment
saved
Expansion
$
400,000
$
42,000
Year
10
Income
-
producing
asset
Expansion
$
700,000
$
48,000
Year
15
Returns
outpace
deposits
Independence
$
1,300,000
$
55,000
Year
20
Financial
independence
Legacy
$
2,400,000
$
60,000
4 / 4