SMART
Financial
Independence
Goals
The
goals
at
a
glance
11
goals
· 2026–2039
01
Build
a
12-
month
emergency
fund
—
$
84,000
in
a
high
-
yield
savings
account
by
Dec
2027
02
Clear
all
consumer
debt
—
$
23,400
across
a
car
loan
and
two
credit
cards
by
Dec
2027
03
Reach
and
hold
a
40%
savings
rate
for
four
consecutive
quarters
by
Jun
2028
04
Grow
the
invested
portfolio
to
the
$
1.2
M
financial
independence
number
by
Jun
2039
05
Max
every
tax
-
advantaged
account
every
year
— 401(
k
),
Roth
IRA
,
HSA
each
Dec
from
2026
06
Raise
household
gross
income
to
$
185,000
without
raising
spending
by
Dec
2027
07
Bring
housing
cost
down
to
25%
of
take
-
home
pay
by
Mar
2029
08
Build
$
2,000
per
month
of
passive
income
that
does
not
depend
on
a
job
by
Dec
2033
09
Cut
recurring
fixed
costs
by
$
480
per
month
,
permanently
by
Jun
2027
10
Complete
the
protection
and
estate
foundation
—
insurance
,
wills
,
beneficiaries
by
Dec
2026
11
Give
10%
of
gross
income
every
year
,
tracked
alongside
the
savings
rate
ongoing
from
2026
1 / 7
Each
goal
,
written
out
in
SMART
form
S
·
M
·
A
·
R
·
T
2 / 7
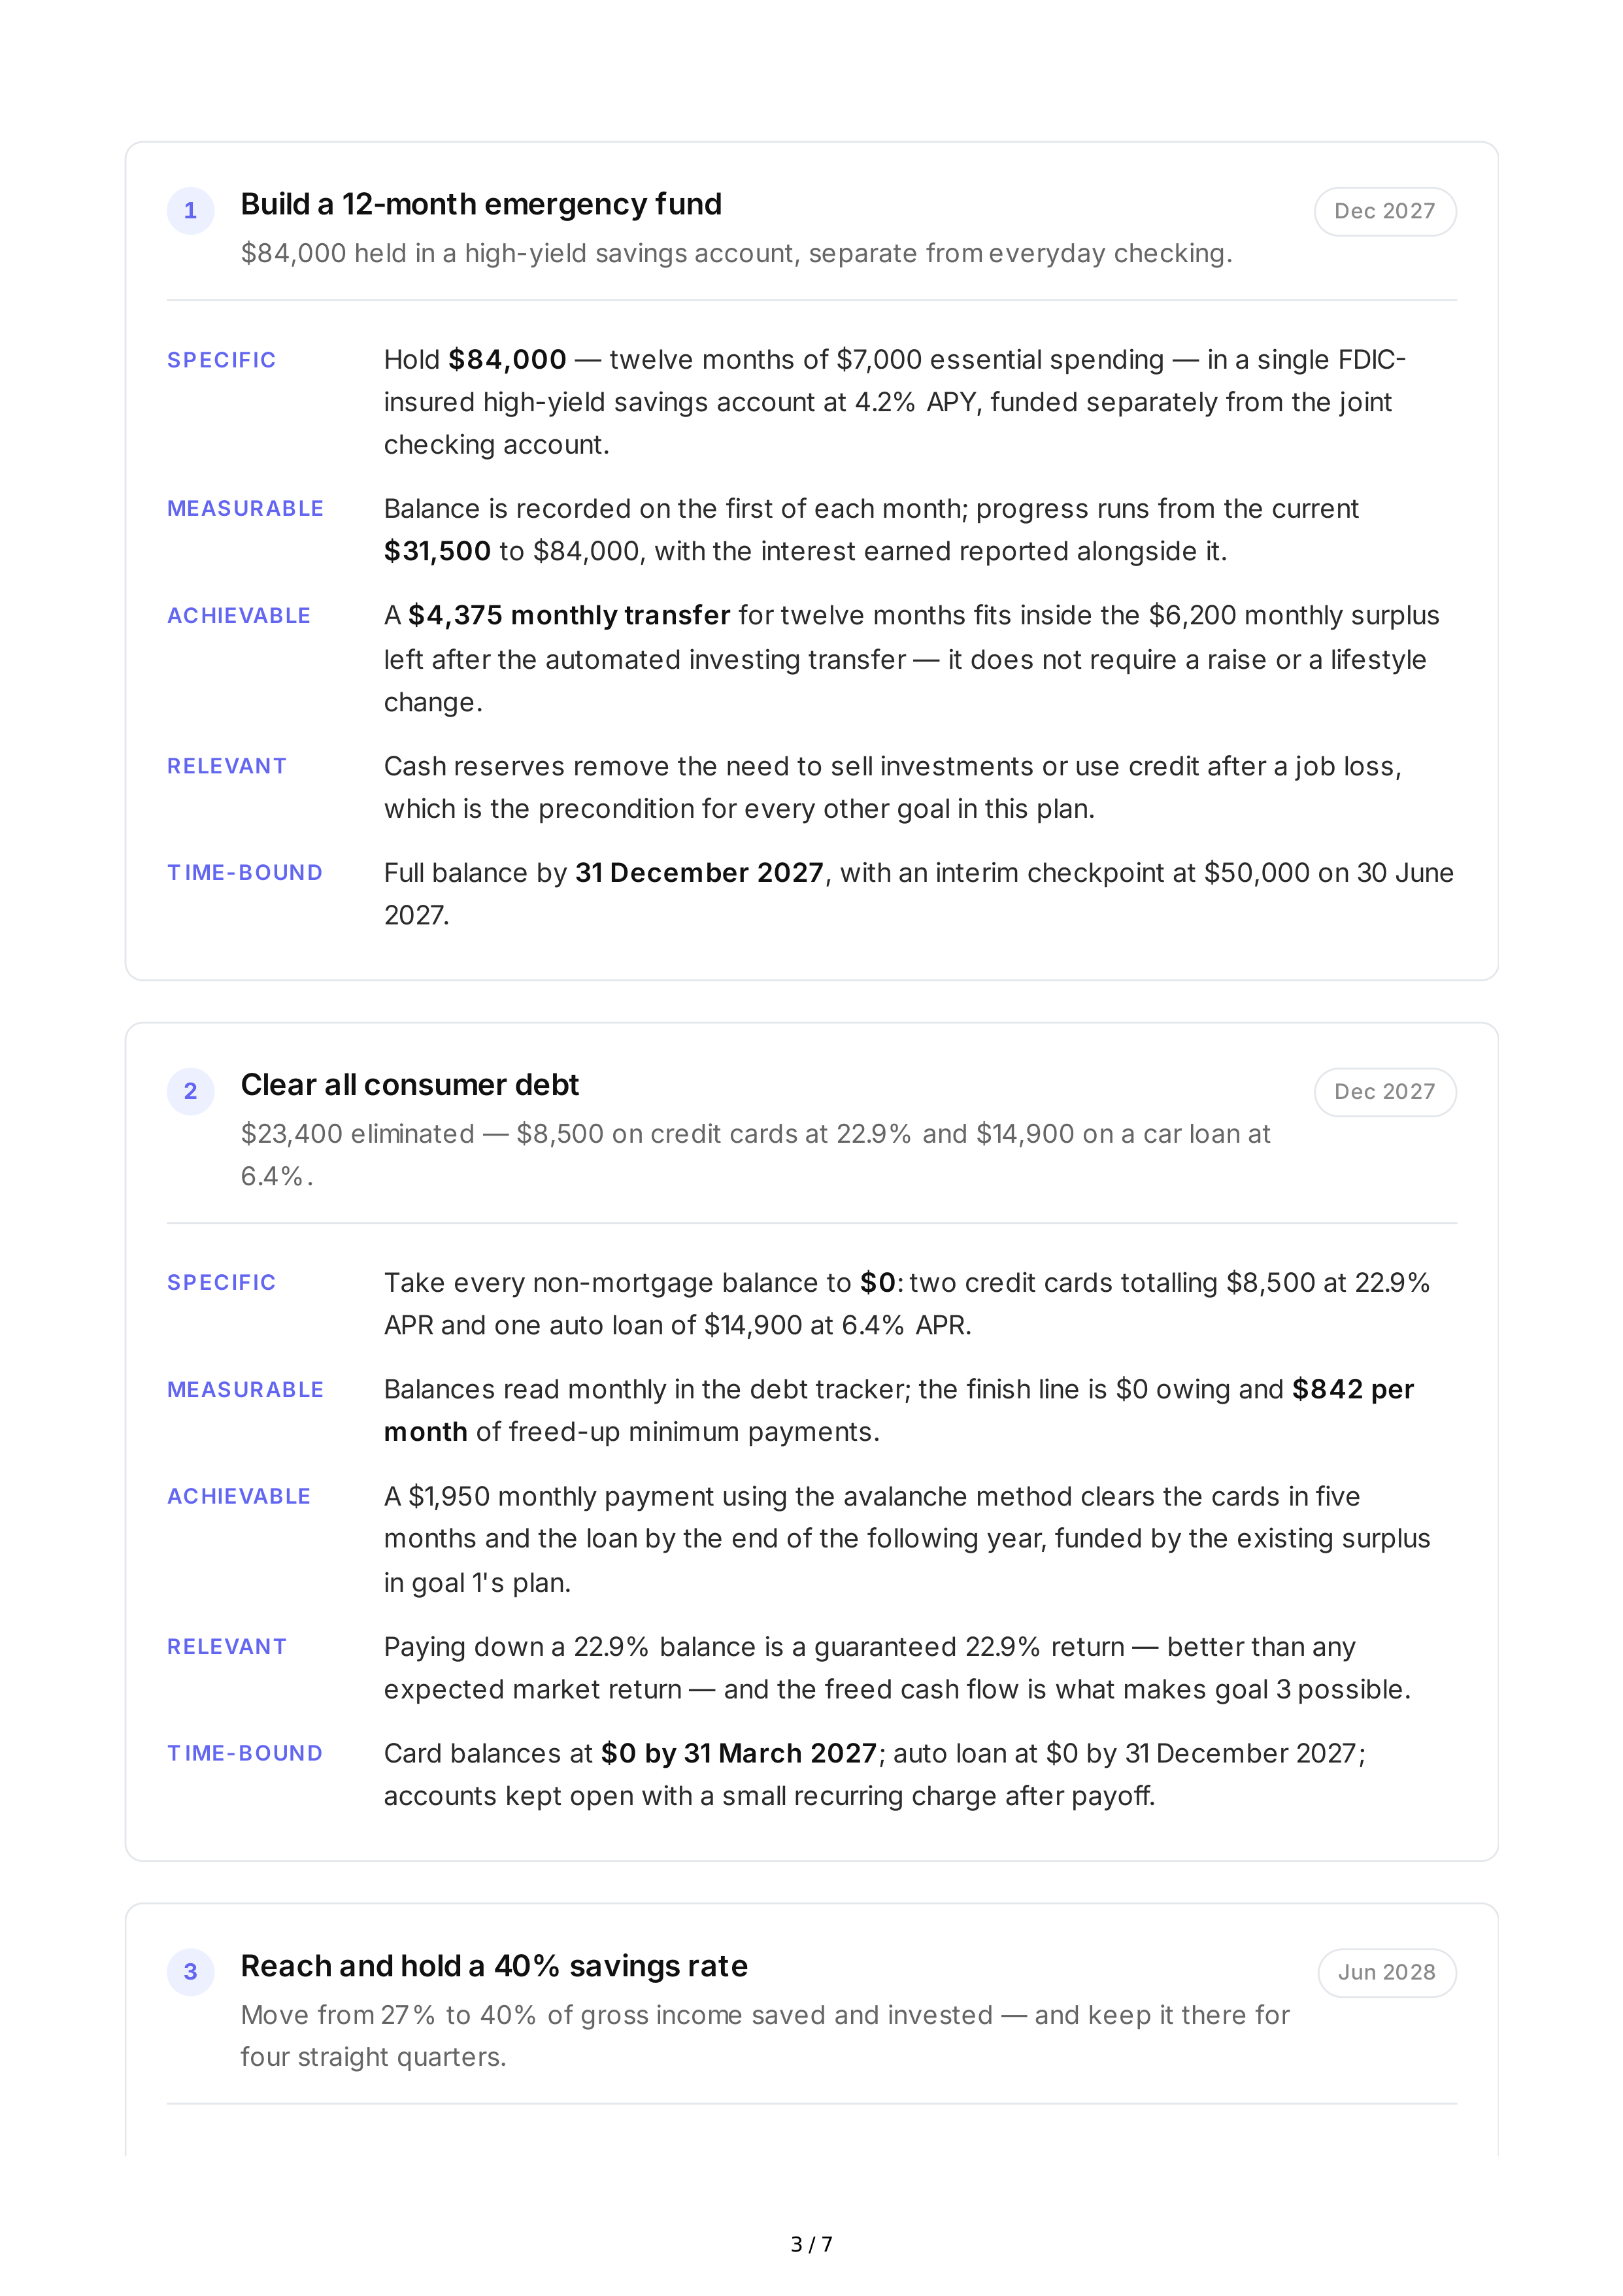
1
Build
a
12-
month
emergency
fund
$
84,000
held
in
a
high
-
yield
savings
account
,
separate
from
everyday
checking
.
Dec
2027
SPECIFIC
Hold
$
84,000
—
twelve
months
of
$
7,000
essential
spending
—
in
a
single
FDIC
-
insured
high
-
yield
savings
account
at
4.2%
APY
,
funded
separately
from
the
joint
checking
account
.
MEASURABLE
Balance
is
recorded
on
the
first
of
each
month
;
progress
runs
from
the
current
$
31,500
to
$
84,000,
with
the
interest
earned
reported
alongside
it
.
ACHIEVABLE
A
$
4,375
monthly
transfer
for
twelve
months
fits
inside
the
$
6,200
monthly
surplus
left
after
the
automated
investing
transfer
—
it
does
not
require
a
raise
or
a
lifestyle
change
.
RELEVANT
Cash
reserves
remove
the
need
to
sell
investments
or
use
credit
after
a
job
loss
,
which
is
the
precondition
for
every
other
goal
in
this
plan
.
T IME
-
BOUND
Full
balance
by
31
December
2027
,
with
an
interim
checkpoint
at
$
50,000
on
30
June
2027.
2
Clear
all
consumer
debt
$
23,400
eliminated
—
$
8,500
on
credit
cards
at
22.9%
and
$
14,900
on
a
car
loan
at
6.4%.
Dec
2027
SPECIFIC
Take
every
non
-
mortgage
balance
to
$
0
:
two
credit
cards
totalling
$
8,500
at
22.9%
APR
and
one
auto
loan
of
$
14,900
at
6.4%
APR
.
MEASURABLE
Balances
read
monthly
in
the
debt
tracker
;
the
finish
line
is
$
0
owing
and
$
842
per
month
of
freed
-
up
minimum
payments
.
ACHIEVABLE
A
$
1,950
monthly
payment
using
the
avalanche
method
clears
the
cards
in
five
months
and
the
loan
by
the
end
of
the
following
year
,
funded
by
the
existing
surplus
in
goal
1'
s
plan
.
RELEVANT
Paying
down
a
22.9%
balance
is
a
guaranteed
22.9%
return
—
better
than
any
expected
market
return
—
and
the
freed
cash
flow
is
what
makes
goal
3
possible
.
T IME
-
BOUND
Card
balances
at
$
0
by
31
March
2027
;
auto
loan
at
$
0
by
31
December
2027;
accounts
kept
open
with
a
small
recurring
charge
after
payoff
.
3
Reach
and
hold
a
40%
savings
rate
Move
from
27%
to
40%
of
gross
income
saved
and
invested
—
and
keep
it
there
for
four
straight
quarters
.
Jun
2028
3 / 7
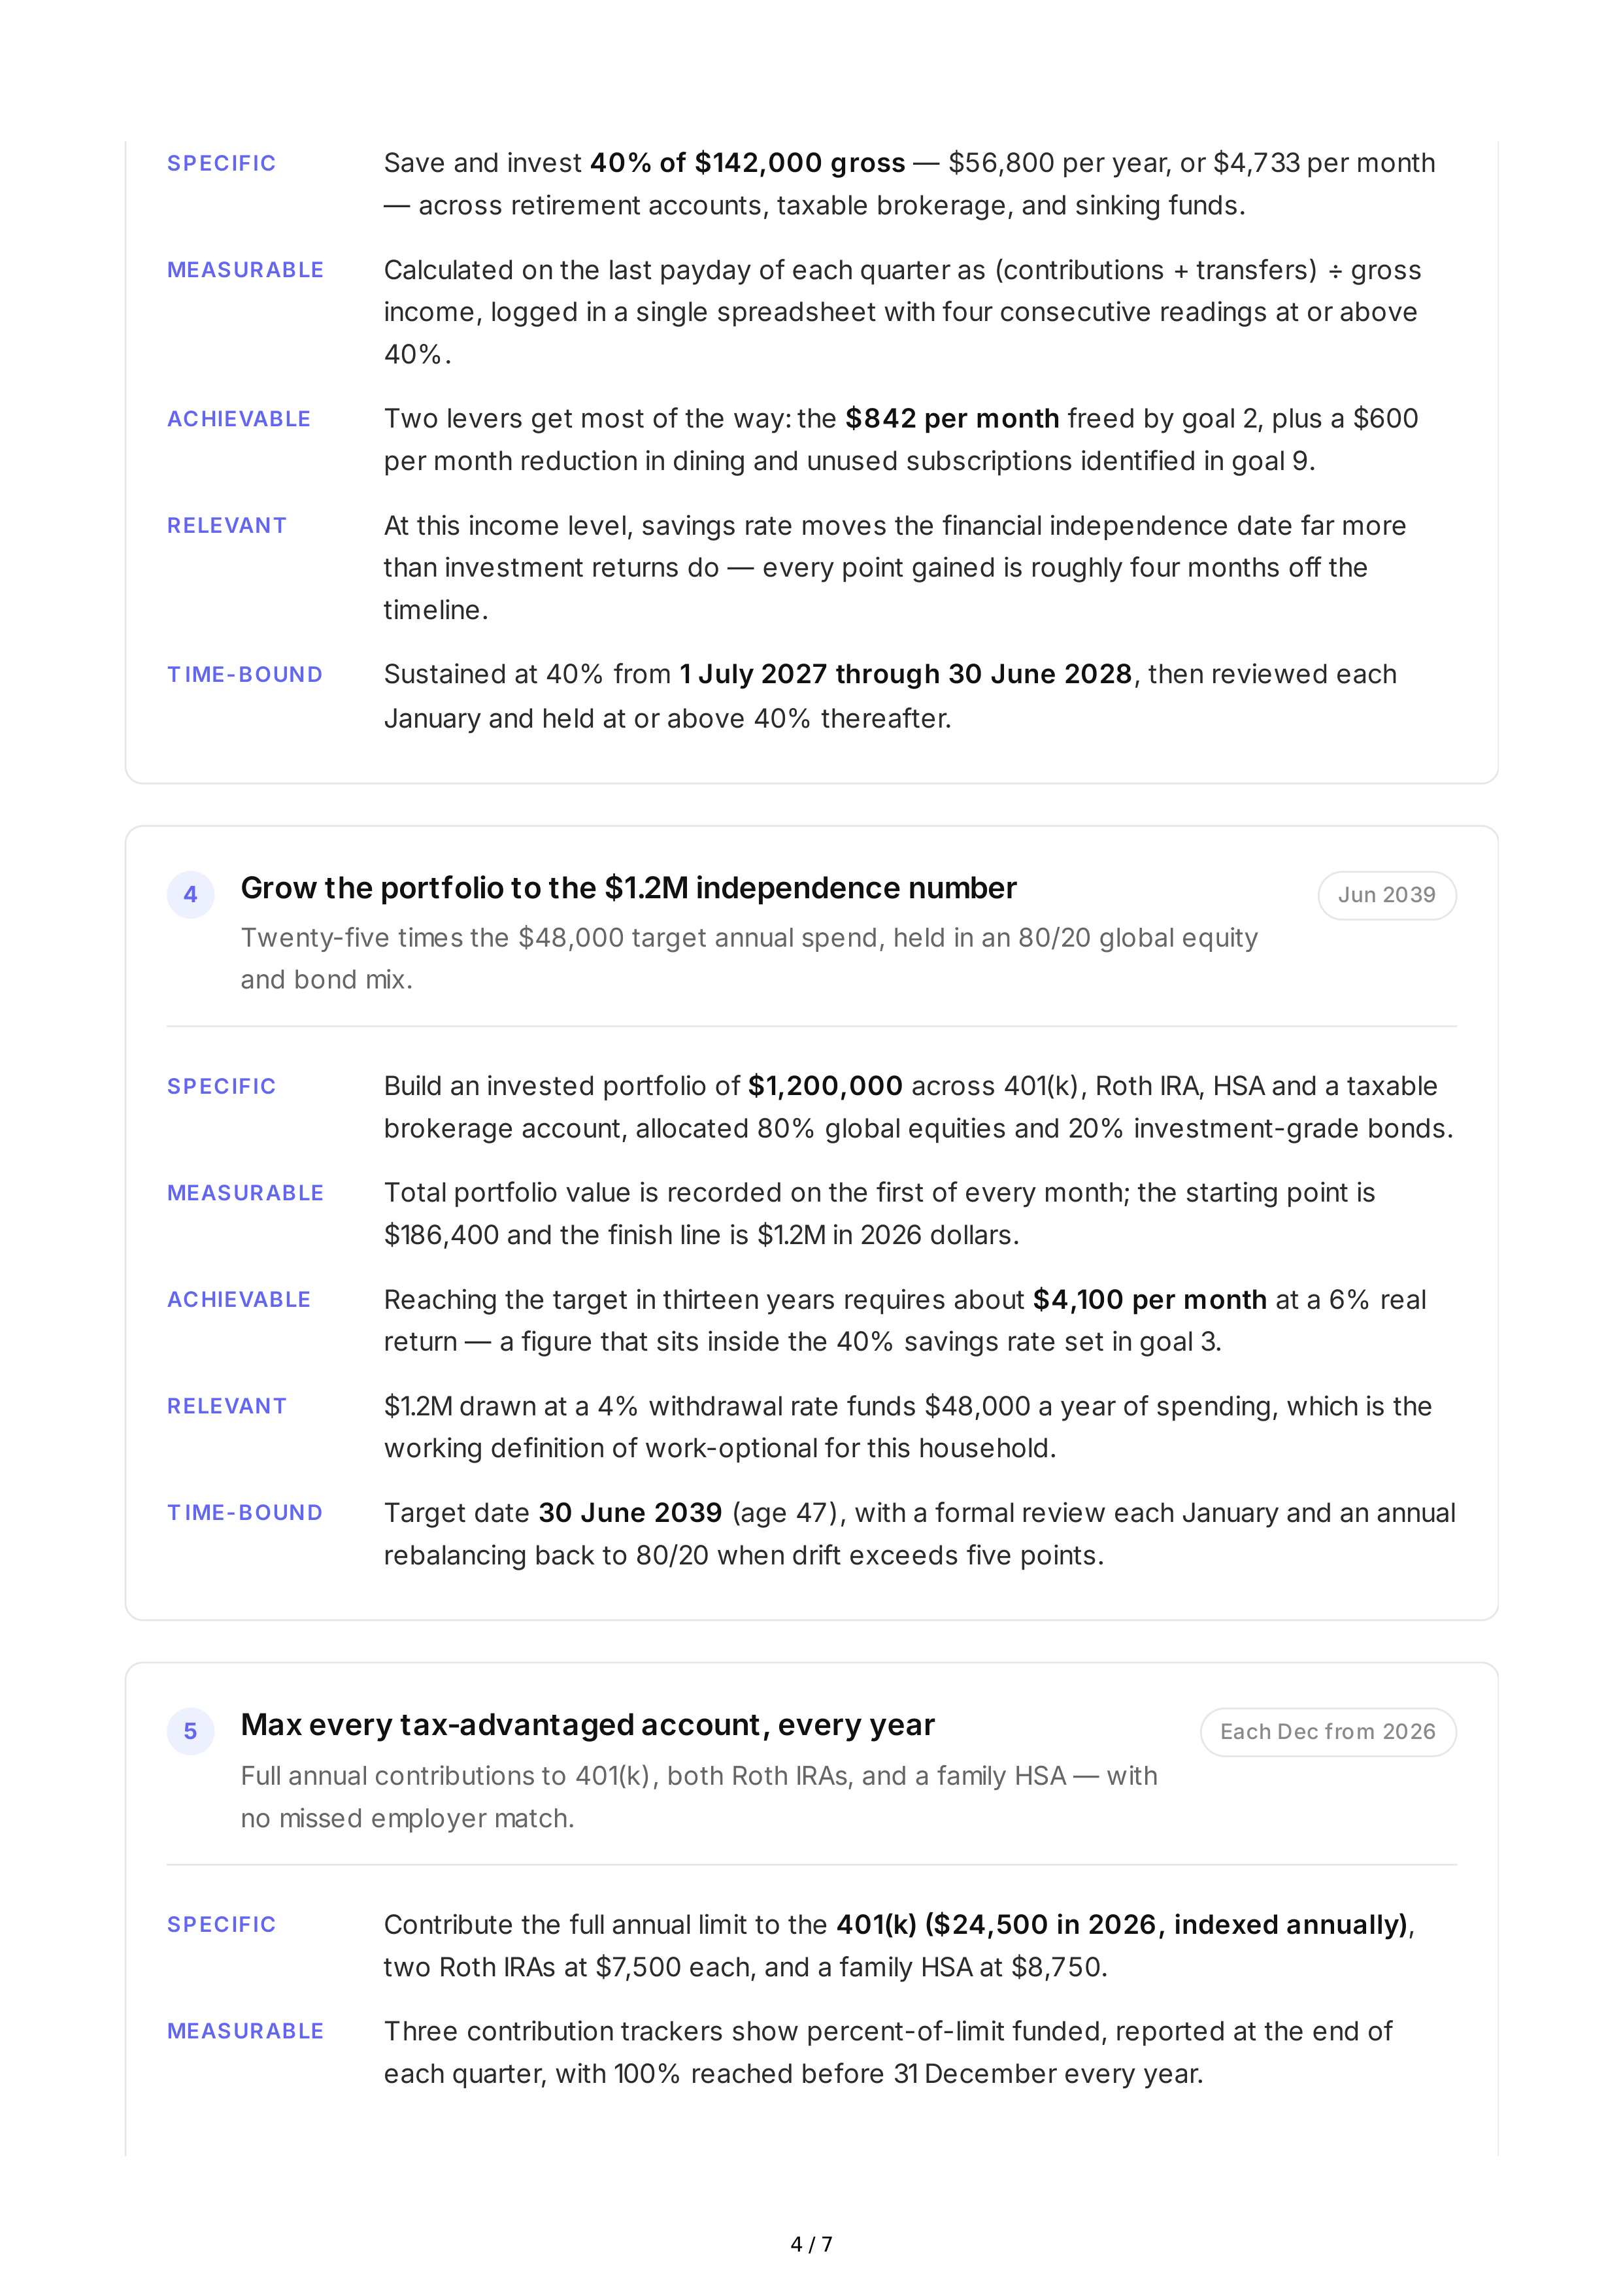
SPECIFIC
Save
and
invest
40%
of
$
142,000
gross
—
$
56,800
per
year
,
or
$
4,733
per
month
—
across
retirement
accounts
,
taxable
brokerage
,
and
sinking
funds
.
MEASURABLE
Calculated
on
the
last
payday
of
each
quarter
as
(
contributions
+
transfers
) ÷
gross
income
,
logged
in
a
single
spreadsheet
with
four
consecutive
readings
at
or
above
40%.
ACHIEVABLE
Two
levers
get
most
of
the
way
:
the
$
842
per
month
freed
by
goal
2,
plus
a
$
600
per
month
reduction
in
dining
and
unused
subscriptions
identified
in
goal
9.
RELEVANT
At
this
income
level
,
savings
rate
moves
the
financial
independence
date
far
more
than
investment
returns
do
—
every
point
gained
is
roughly
four
months
off
the
timeline
.
T IME
-
BOUND
Sustained
at
40%
from
1
July
2027
through
30
June
2028
,
then
reviewed
each
January
and
held
at
or
above
40%
thereafter
.
4
Grow
the
portfolio
to
the
$
1.2
M
independence
number
Twenty
-
five
times
the
$
48,000
target
annual
spend
,
held
in
an
80/20
global
equity
and
bond
mix
.
Jun
2039
SPECIFIC
Build
an
invested
portfolio
of
$
1,200,000
across
401(
k
),
Roth
IRA
,
HSA
and
a
taxable
brokerage
account
,
allocated
80%
global
equities
and
20%
investment
-
grade
bonds
.
MEASURABLE
Total
portfolio
value
is
recorded
on
the
first
of
every
month
;
the
starting
point
is
$
186,400
and
the
finish
line
is
$
1.2
M
in
2026
dollars
.
ACHIEVABLE
Reaching
the
target
in
thirteen
years
requires
about
$
4,100
per
month
at
a
6%
real
return
—
a
figure
that
sits
inside
the
40%
savings
rate
set
in
goal
3.
RELEVANT
$
1.2
M
drawn
at
a
4%
withdrawal
rate
funds
$
48,000
a
year
of
spending
,
which
is
the
working
definition
of
work
-
optional
for
this
household
.
T IME
-
BOUND
Target
date
30
June
2039
(
age
47),
with
a
formal
review
each
January
and
an
annual
rebalancing
back
to
80/20
when
drift
exceeds
five
points
.
5
Max
every
tax
-
advantaged
account
,
every
year
Full
annual
contributions
to
401(
k
),
both
Roth
IRAs
,
and
a
family
HSA
—
with
no
missed
employer
match
.
Each
Dec
from
2026
SPECIFIC
Contribute
the
full
annual
limit
to
the
401(
k
) (
$
24,500
in
2026,
indexed
annually
)
,
two
Roth
IRAs
at
$
7,500
each
,
and
a
family
HSA
at
$
8,750.
MEASURABLE
Three
contribution
trackers
show
percent
-
of
-
limit
funded
,
reported
at
the
end
of
each
quarter
,
with
100%
reached
before
31
December
every
year
.
4 / 7
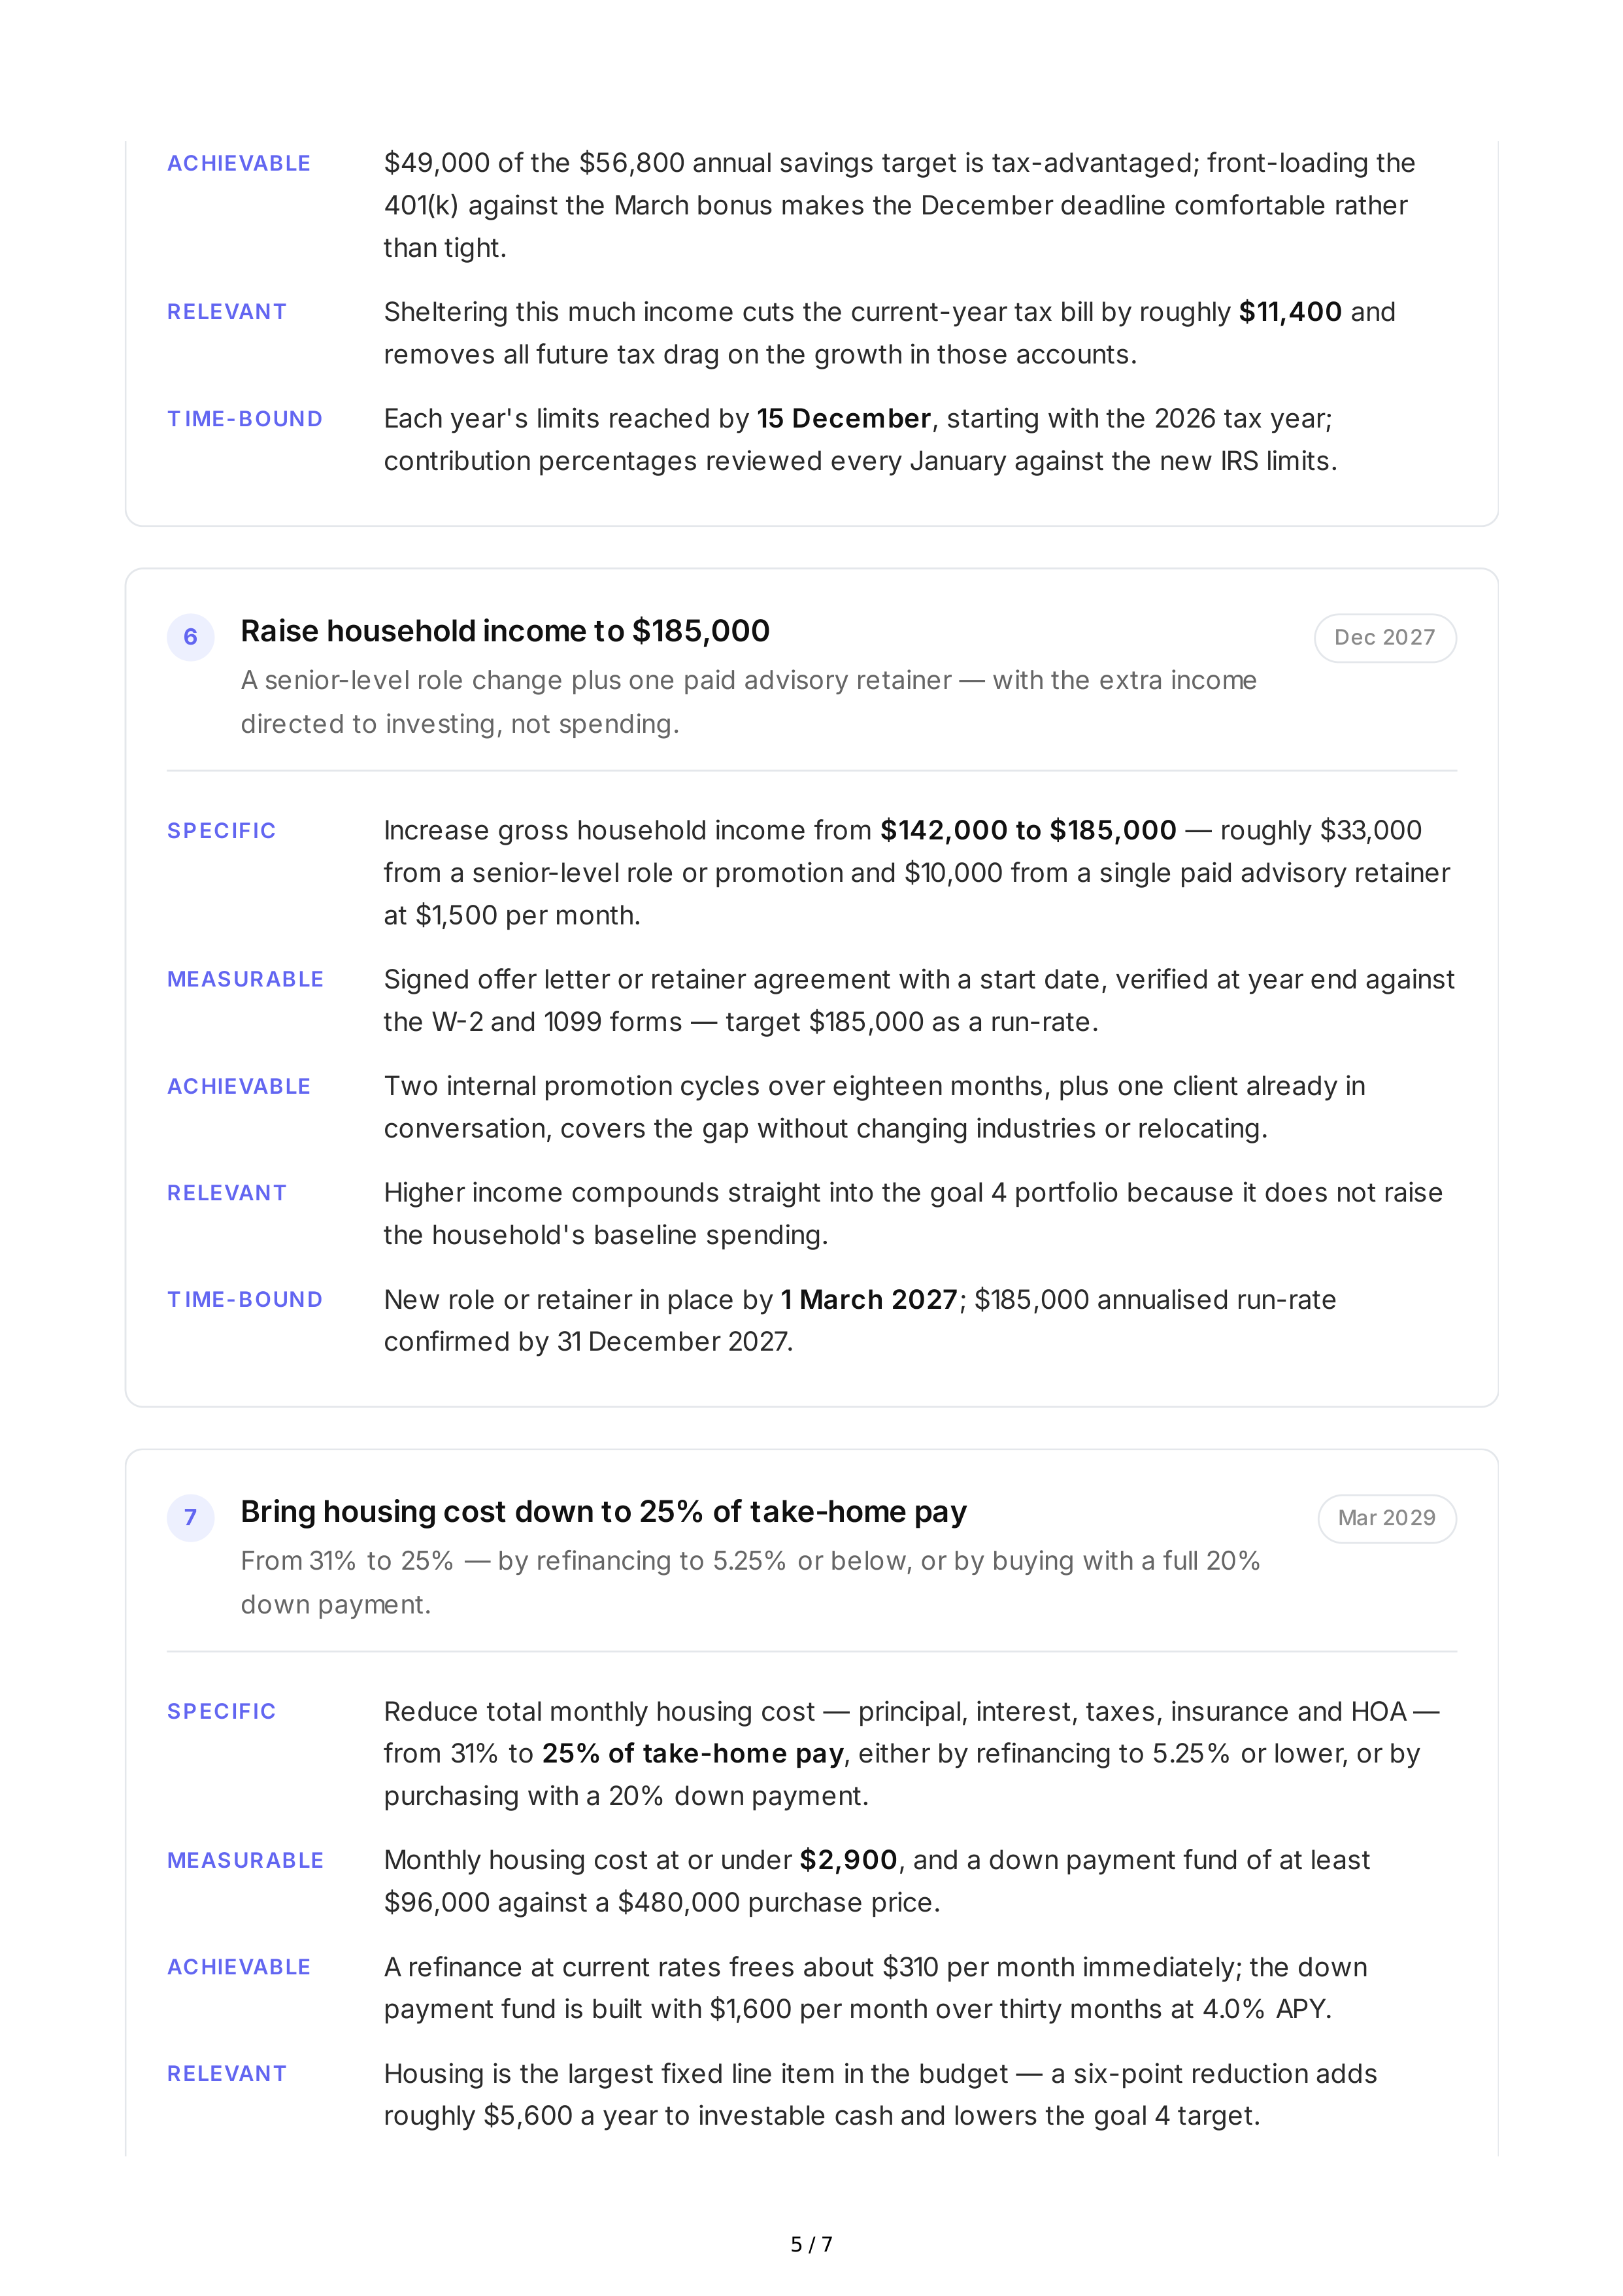
ACHIEVABLE
$
49,000
of
the
$
56,800
annual
savings
target
is
tax
-
advantaged
;
front
-
loading
the
401(
k
)
against
the
March
bonus
makes
the
December
deadline
comfortable
rather
than
tight
.
RELEVANT
Sheltering
this
much
income
cuts
the
current
-
year
tax
bill
by
roughly
$
11,400
and
removes
all
future
tax
drag
on
the
growth
in
those
accounts
.
T IME
-
BOUND
Each
year
'
s
limits
reached
by
15
December
,
starting
with
the
2026
tax
year
;
contribution
percentages
reviewed
every
January
against
the
new
IRS
limits
.
6
Raise
household
income
to
$
185,000
A
senior
-
level
role
change
plus
one
paid
advisory
retainer
—
with
the
extra
income
directed
to
investing
,
not
spending
.
Dec
2027
SPECIFIC
Increase
gross
household
income
from
$
142,000
to
$
185,000
—
roughly
$
33,000
from
a
senior
-
level
role
or
promotion
and
$
10,000
from
a
single
paid
advisory
retainer
at
$
1,500
per
month
.
MEASURABLE
Signed
offer
letter
or
retainer
agreement
with
a
start
date
,
verified
at
year
end
against
the
W
-2
and
1099
forms
—
target
$
185,000
as
a
run
-
rate
.
ACHIEVABLE
Two
internal
promotion
cycles
over
eighteen
months
,
plus
one
client
already
in
conversation
,
covers
the
gap
without
changing
industries
or
relocating
.
RELEVANT
Higher
income
compounds
straight
into
the
goal
4
portfolio
because
it
does
not
raise
the
household
'
s
baseline
spending
.
T IME
-
BOUND
New
role
or
retainer
in
place
by
1
March
2027
;
$
185,000
annualised
run
-
rate
confirmed
by
31
December
2027.
7
Bring
housing
cost
down
to
25%
of
take
-
home
pay
From
31%
to
25% —
by
refinancing
to
5.25%
or
below
,
or
by
buying
with
a
full
20%
down
payment
.
Mar
2029
SPECIFIC
Reduce
total
monthly
housing
cost
—
principal
,
interest
,
taxes
,
insurance
and
HOA
—
from
31%
to
25%
of
take
-
home
pay
,
either
by
refinancing
to
5.25%
or
lower
,
or
by
purchasing
with
a
20%
down
payment
.
MEASURABLE
Monthly
housing
cost
at
or
under
$
2,900
,
and
a
down
payment
fund
of
at
least
$
96,000
against
a
$
480,000
purchase
price
.
ACHIEVABLE
A
refinance
at
current
rates
frees
about
$
310
per
month
immediately
;
the
down
payment
fund
is
built
with
$
1,600
per
month
over
thirty
months
at
4.0%
APY
.
RELEVANT
Housing
is
the
largest
fixed
line
item
in
the
budget
—
a
six
-
point
reduction
adds
roughly
$
5,600
a
year
to
investable
cash
and
lowers
the
goal
4
target
.
5 / 7
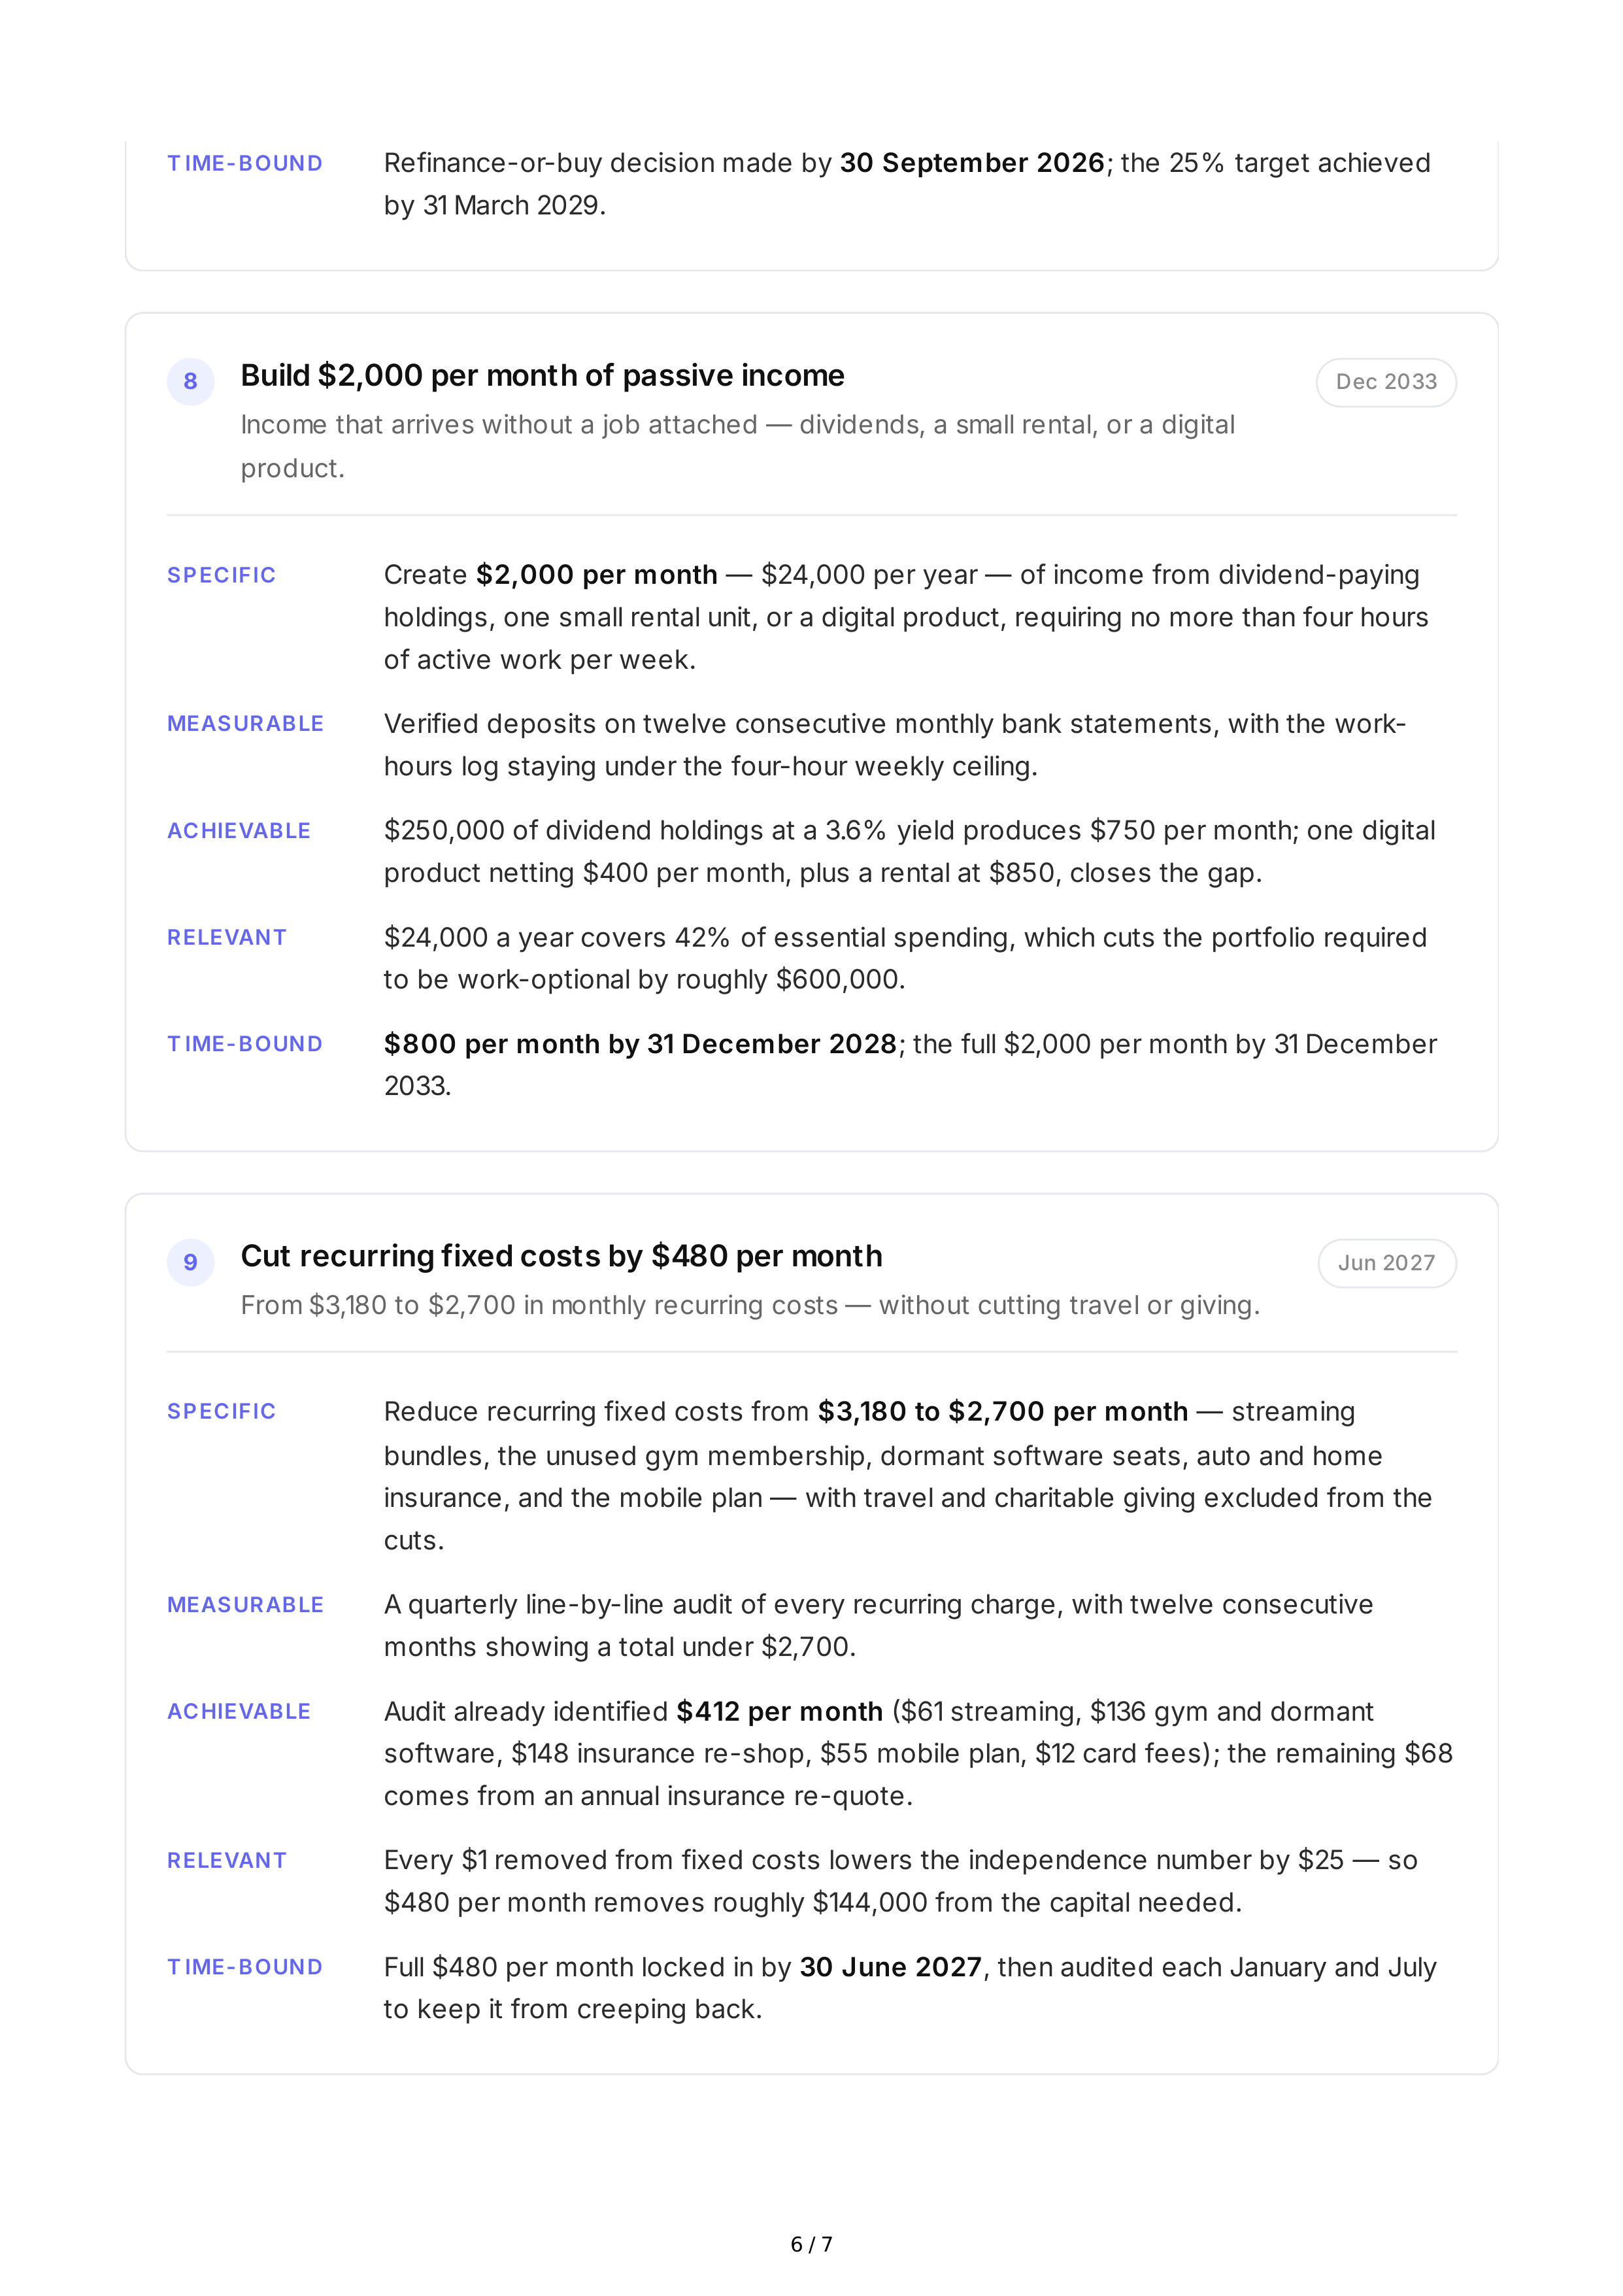
T IME
-
BOUND
Refinance
-
or
-
buy
decision
made
by
30
September
2026
;
the
25%
target
achieved
by
31
March
2029.
8
Build
$
2,000
per
month
of
passive
income
Income
that
arrives
without
a
job
attached
—
dividends
,
a
small
rental
,
or
a
digital
product
.
Dec
2033
SPECIFIC
Create
$
2,000
per
month
—
$
24,000
per
year
—
of
income
from
dividend
-
paying
holdings
,
one
small
rental
unit
,
or
a
digital
product
,
requiring
no
more
than
four
hours
of
active
work
per
week
.
MEASURABLE
Verified
deposits
on
twelve
consecutive
monthly
bank
statements
,
with
the
work
-
hours
log
staying
under
the
four
-
hour
weekly
ceiling
.
ACHIEVABLE
$
250,000
of
dividend
holdings
at
a
3.6%
yield
produces
$
750
per
month
;
one
digital
product
netting
$
400
per
month
,
plus
a
rental
at
$
850,
closes
the
gap
.
RELEVANT
$
24,000
a
year
covers
42%
of
essential
spending
,
which
cuts
the
portfolio
required
to
be
work
-
optional
by
roughly
$
600,000.
T IME
-
BOUND
$
800
per
month
by
31
December
2028
;
the
full
$
2,000
per
month
by
31
December
2033.
9
Cut
recurring
fixed
costs
by
$
480
per
month
From
$
3,180
to
$
2,700
in
monthly
recurring
costs
—
without
cutting
travel
or
giving
.
Jun
2027
SPECIFIC
Reduce
recurring
fixed
costs
from
$
3,180
to
$
2,700
per
month
—
streaming
bundles
,
the
unused
gym
membership
,
dormant
software
seats
,
auto
and
home
insurance
,
and
the
mobile
plan
—
with
travel
and
charitable
giving
excluded
from
the
cuts
.
MEASURABLE
A
quarterly
line
-
by
-
line
audit
of
every
recurring
charge
,
with
twelve
consecutive
months
showing
a
total
under
$
2,700.
ACHIEVABLE
Audit
already
identified
$
412
per
month
(
$
61
streaming
,
$
136
gym
and
dormant
software
,
$
148
insurance
re
-
shop
,
$
55
mobile
plan
,
$
12
card
fees
);
the
remaining
$
68
comes
from
an
annual
insurance
re
-
quote
.
RELEVANT
Every
$
1
removed
from
fixed
costs
lowers
the
independence
number
by
$
25 —
so
$
480
per
month
removes
roughly
$
144,000
from
the
capital
needed
.
T IME
-
BOUND
Full
$
480
per
month
locked
in
by
30
June
2027
,
then
audited
each
January
and
July
to
keep
it
from
creeping
back
.
6 / 7
10
Complete
the
protection
and
estate
foundation
Term
life
,
own
-
occupation
disability
,
umbrella
liability
,
wills
,
and
a
full
beneficiary
review
.
Dec
2026
SPECIFIC
Put
in
place
20-
year
term
life
at
12×
income
,
own
-
occupation
disability
covering
60%
of
income
,
a
$
1
M
umbrella
liability
policy
,
notarised
wills
for
both
adults
,
and
updated
beneficiaries
on
every
account
.
MEASURABLE
Five
policies
in
force
with
signed
documents
on
file
,
all
retirement
and
brokerage
beneficiary
designations
updated
,
and
a
notarised
will
held
with
the
attorney
.
ACHIEVABLE
Combined
premiums
land
near
$
172
per
month
,
which
fits
inside
the
goal
3
savings
rate
;
the
attorney
'
s
flat
fee
of
$
1,800
comes
from
the
emergency
fund
and
is
replaced
within
two
months
.
RELEVANT
A
single
uninsured
event
would
unwind
the
entire
plan
—
this
is
what
makes
the
independence
date
durable
rather
than
fragile
.
T IME
-
BOUND
All
policies
bound
by
31
October
2026
;
wills
signed
and
beneficiary
updates
confirmed
by
31
December
2026,
then
reviewed
every
three
years
.
11
Give
10%
of
gross
income
every
year
$
14,200
in
2026,
scaled
with
income
—
tracked
beside
the
savings
rate
,
not
after
it
.
Ongoing
from
2026
SPECIFIC
Donate
10%
of
gross
income
each
year
—
$
14,200
at
current
income
—
split
roughly
70%
to
four
recurring
organisations
and
30%
to
one
-
off
causes
chosen
each
December
.
MEASURABLE
Annual
giving
total
reported
next
to
the
savings
rate
on
the
same
year
-
end
summary
,
with
receipts
filed
for
every
gift
over
$
250.
ACHIEVABLE
Automated
monthly
transfers
of
$
1,183
mean
the
commitment
is
met
from
cash
flow
and
never
competes
with
the
emergency
fund
or
the
debt
payoff
.
RELEVANT
The
point
of
independence
here
is
not
just
to
stop
working
—
it
is
to
keep
giving
at
the
same
rate
whether
or
not
a
salary
arrives
,
which
means
the
10%
belongs
inside
the
plan
.
T IME
-
BOUND
Automatic
transfers
live
from
1
January
2026
;
the
amount
recalculated
every
January
against
the
previous
year
'
s
gross
income
.
7 / 7