Long
-
Term
Financial
Goals
PAR T
0 1
Retirement
&
Financial
Independence
Goals
that
ensure
you
can
stop
working
when
you
want
—
not
when
you
have
to
.
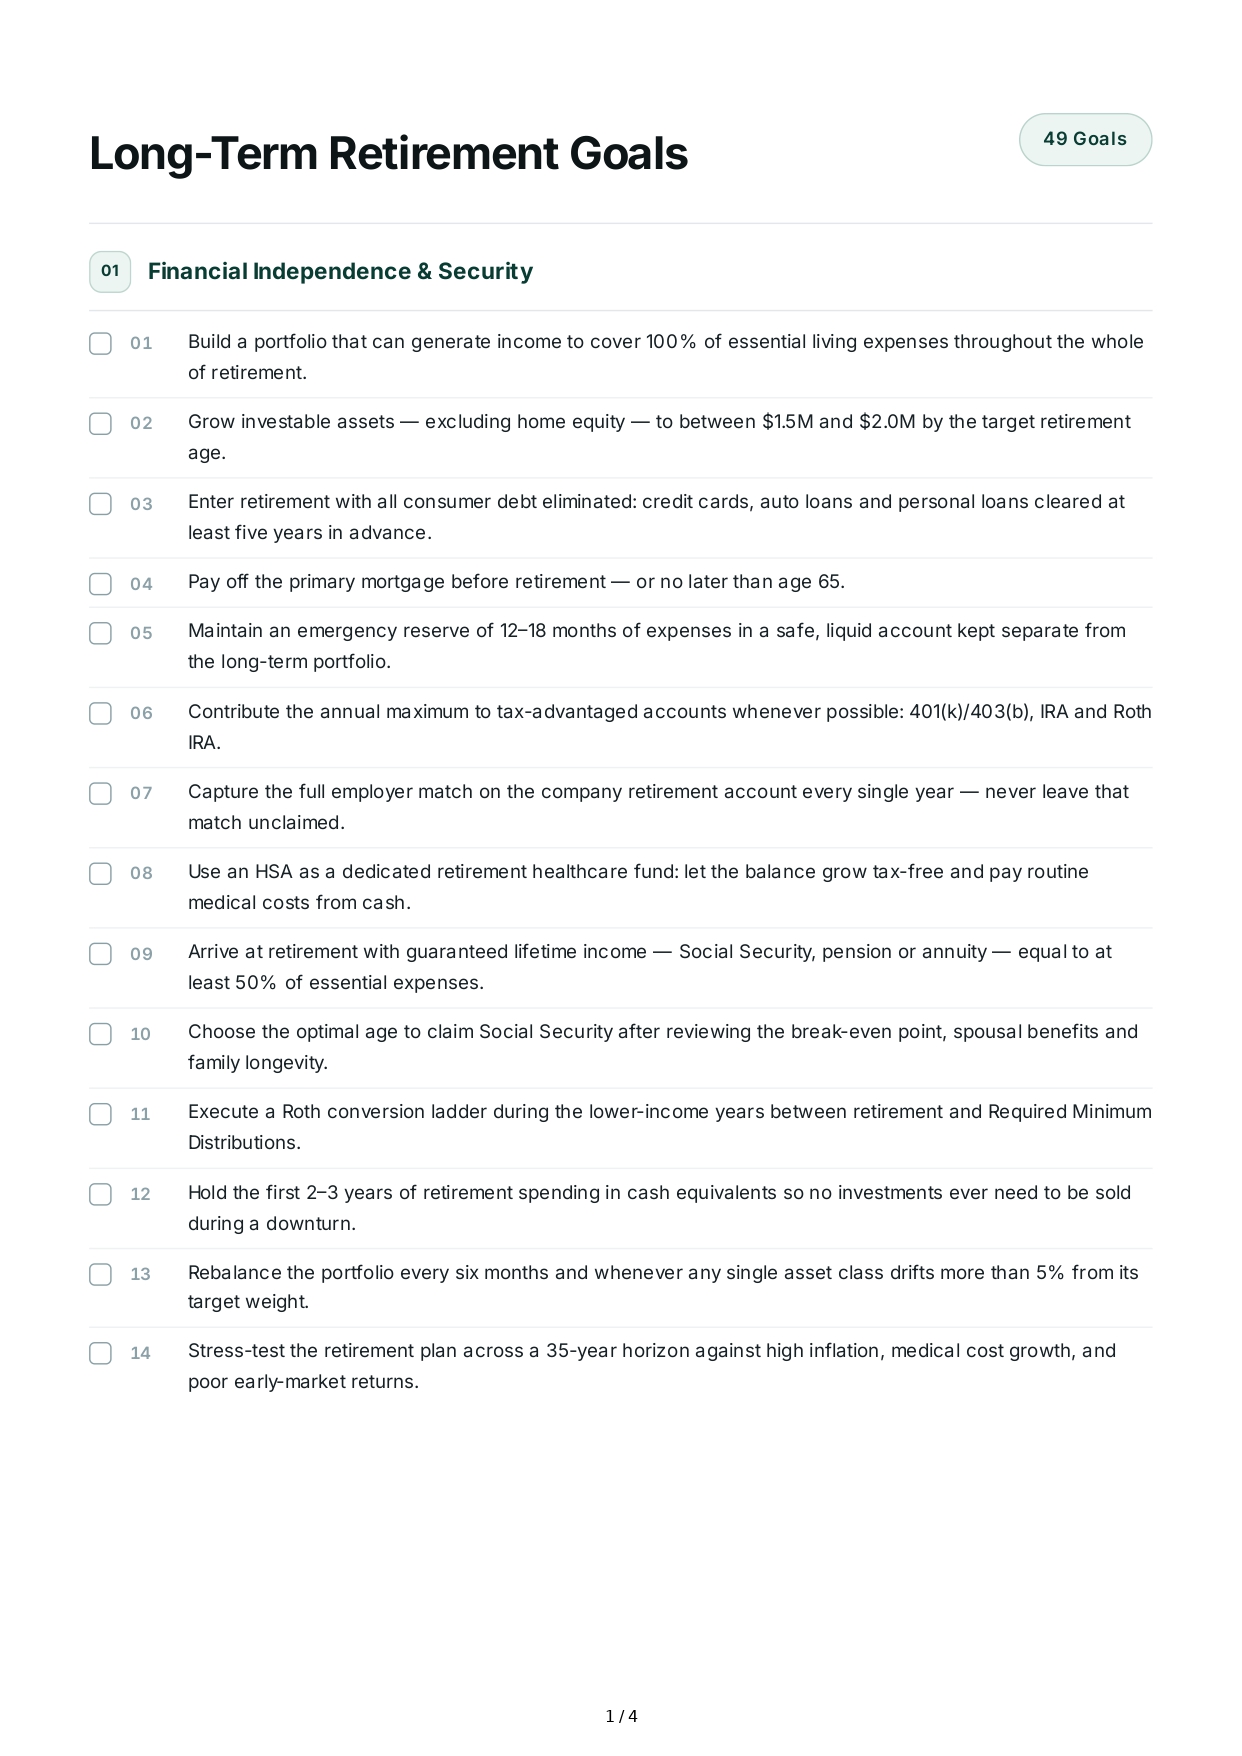
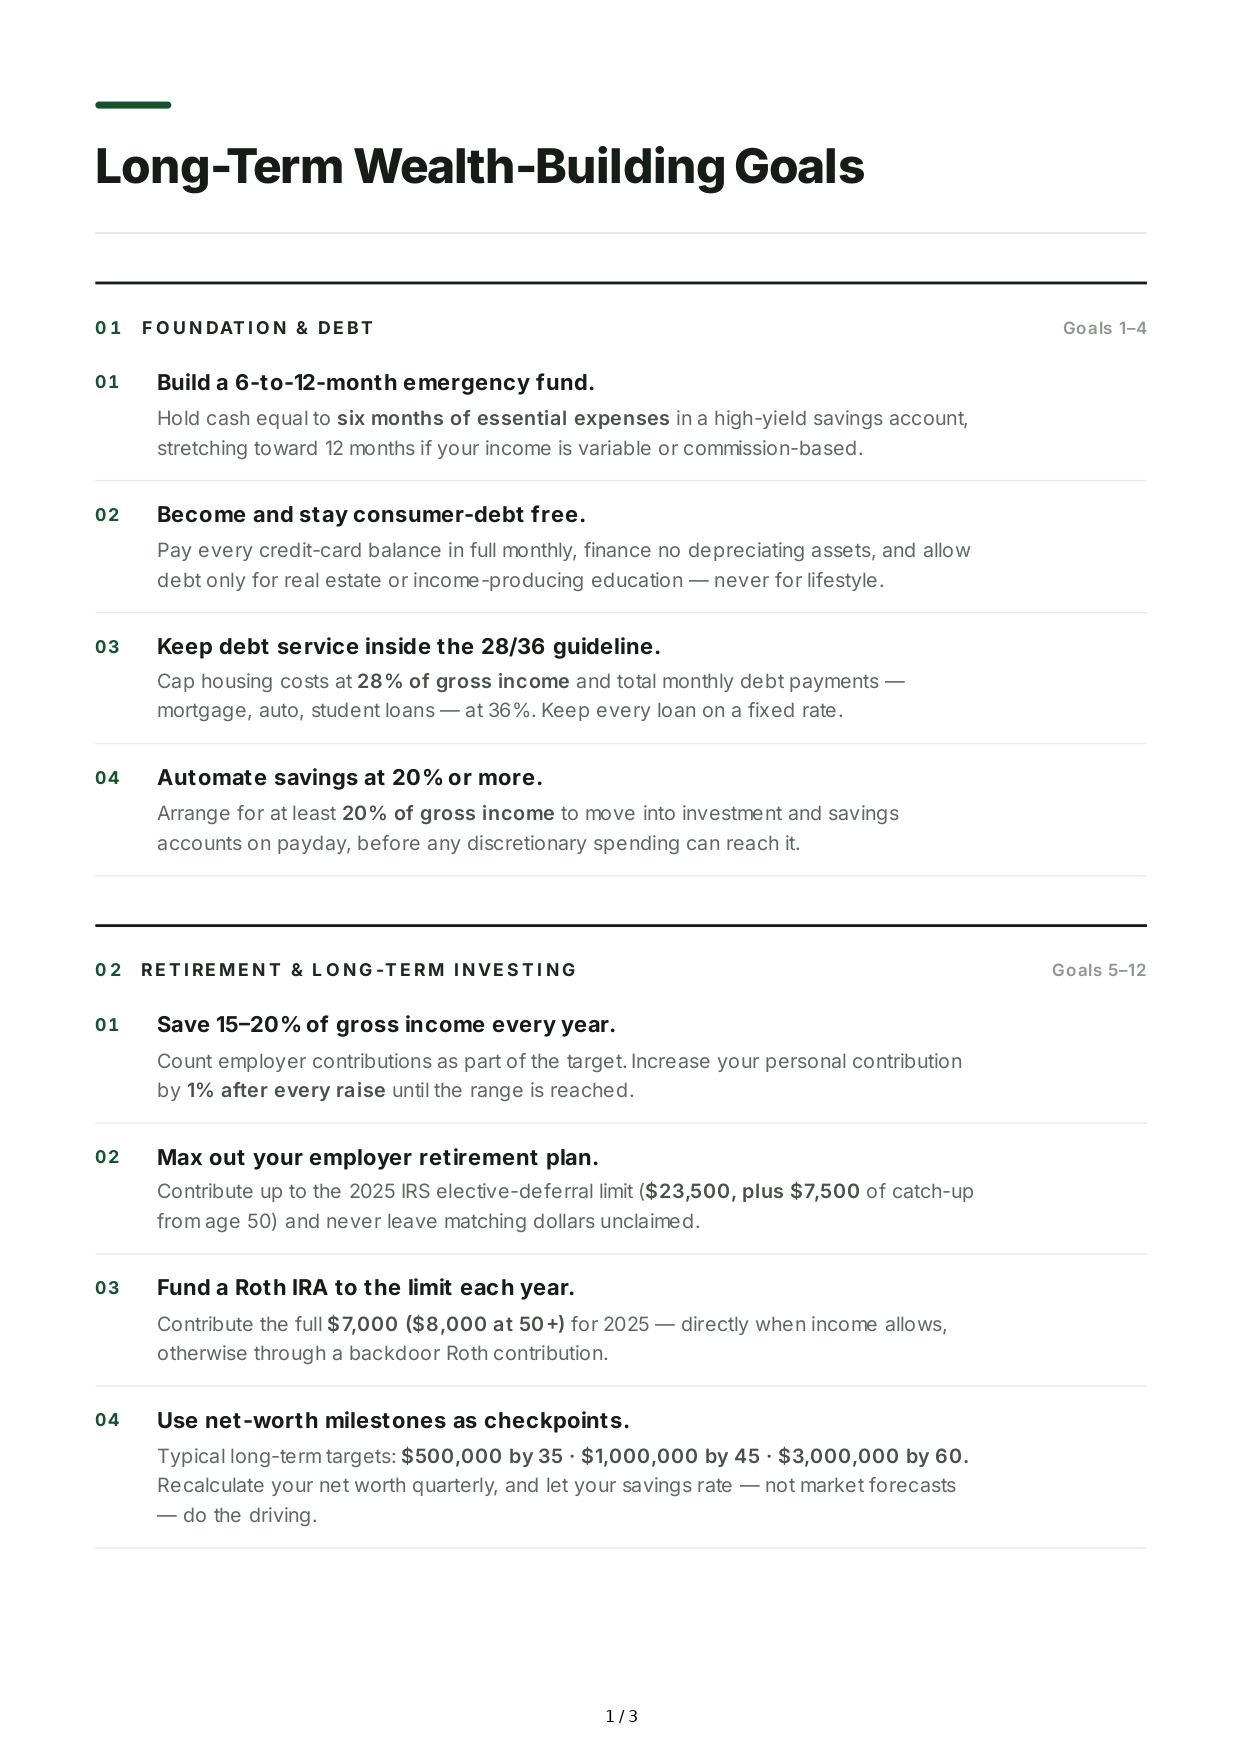
01
Max
out
retirement
accounts
every
working
year
Contribute
the
full
IRS
maximum
to
a
401(
k
) —
$
23,500
in
2025
,
plus
the
$
7,500
catch
-
up
once
you
turn
50 —
and
the
complete
$
7,000
to
a
Roth
IRA
each
year
.
Automate
both
contributions
so
the
goal
is
met
without
a
monthly
decision
.
EVERY
YEAR
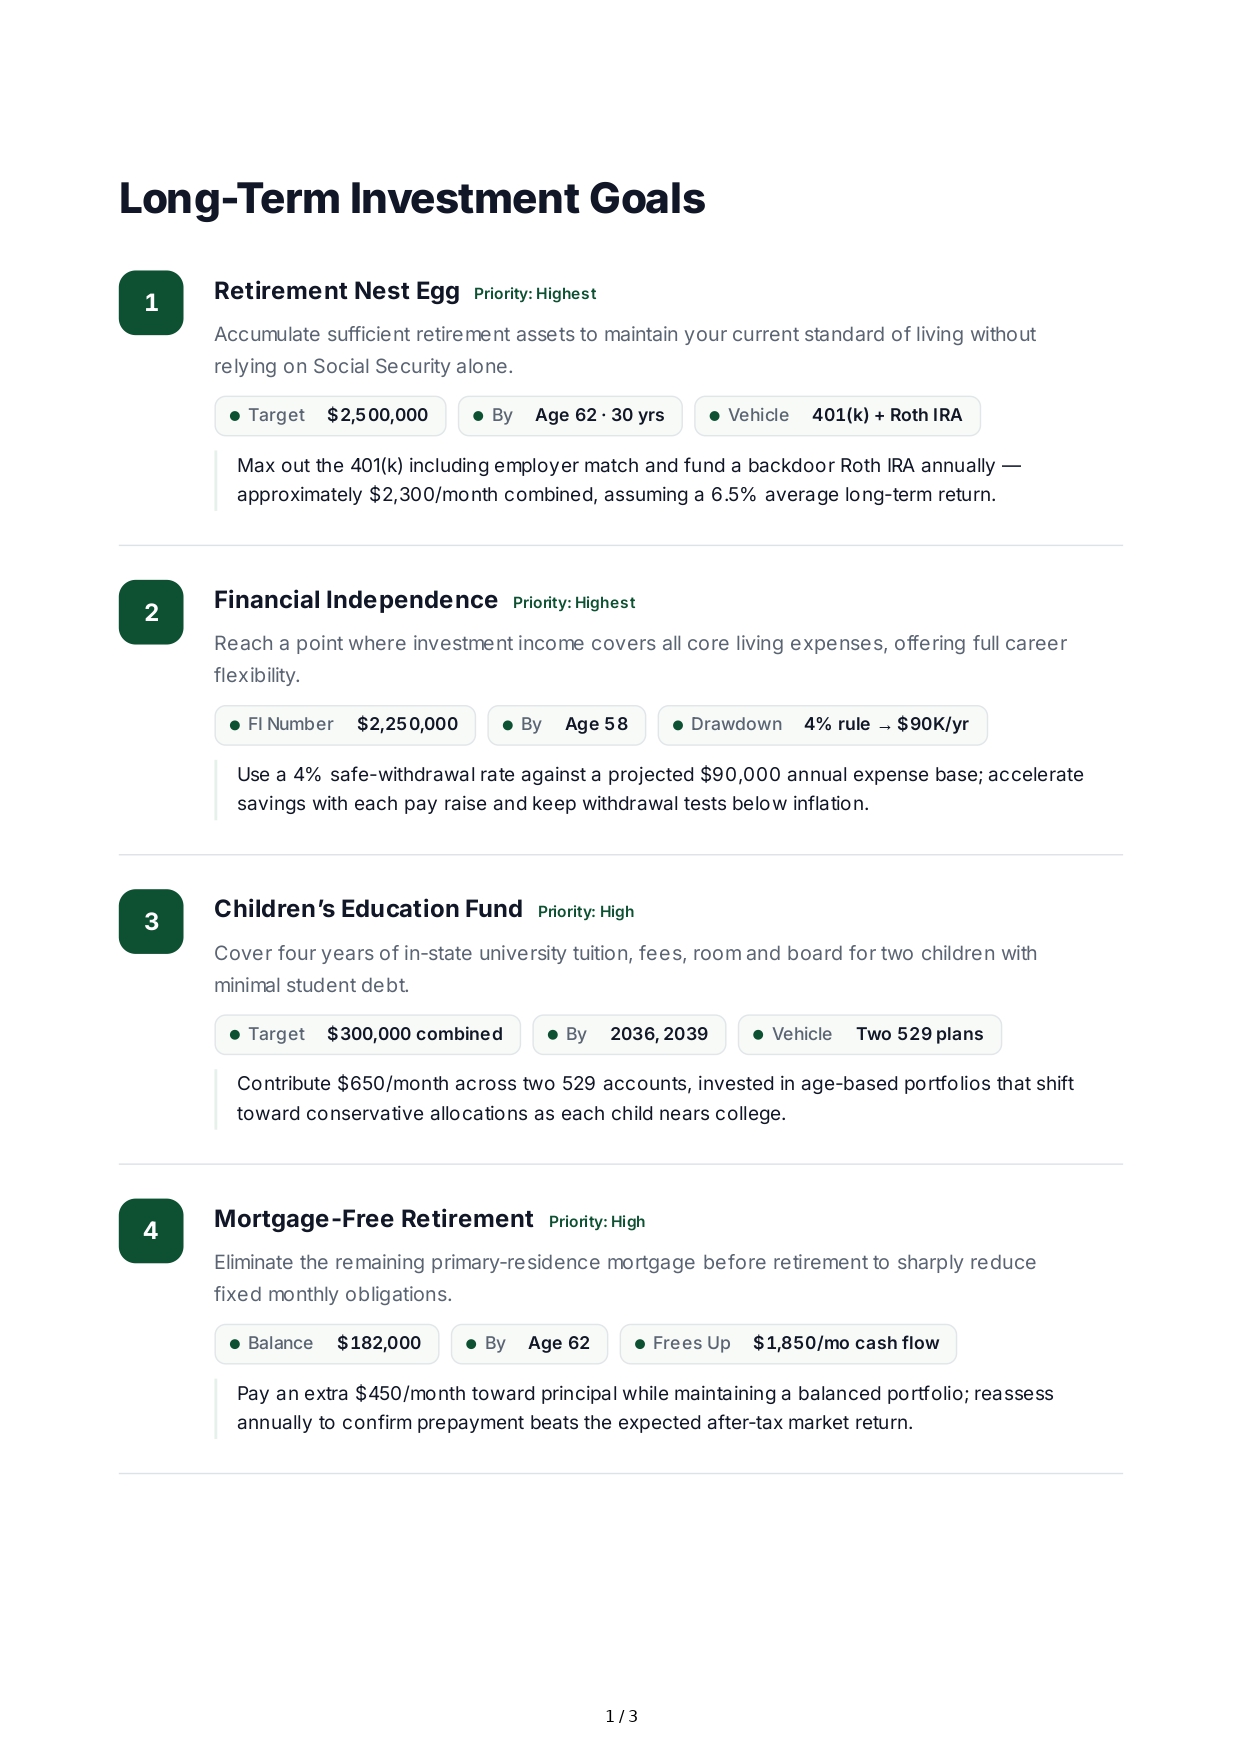
02
Build
a
retirement
portfolio
of
$
2.5
M
by
age
65
Target
a
balance
of
$
2.5
M
at
retirement
,
held
in
low
-
cost
index
funds
using
a
roughly
70/30
stock
-
to
-
bond
ratio
until
age
55
,
gradually
shifting
toward
50/50.
Following
a
4%
withdrawal
rule
,
that
supports
about
$
100,000
per
year
in
pre
-
tax
income
for
30+
years
.
Target
balance
:
$
2,500,000
B Y
AG E
6 5
03
Reach
financial
independence
— 25×
annual
expenses
Accumulate
invested
assets
equal
to
25
times
your
yearly
spending
.
If
you
live
on
$
60,000
a
year
,
that
means
a
$
1.5
M
portfolio
;
at
$
80,000,
a
$
2
M
portfolio
.
At
this
level
,
work
becomes
a
choice
rather
than
a
requirement
.
Independence
number
: 25 ×
spending
B Y
55–6 0
04
Generate
$
4,000/
month
in
passive
income
Build
dividend
,
interest
,
and
rental
income
to
roughly
$
4,000
per
month
—
enough
to
cover
housing
,
food
,
and
utilities
without
touching
the
principal
.
Use
taxable
brokerage
dividends
first
,
then
add
rental
property
or
a
small
business
only
if
it
doesn
’
t
disrupt
core
retirement
contributions
.
Monthly
target
:
$
4,000
B Y
AG E
6 0
1 / 3
PAR T
0 2
Debt
Freedom
&
Home
Eliminating
the
drag
of
interest
so
more
of
every
paycheck
works
for
building
wealth
.
01
Become
completely
free
of
consumer
debt
Pay
off
all
credit
card
balances
,
auto
loans
,
and
any
remaining
student
debt
by
age
40
—
and
stay
clear
of
them
afterward
by
keeping
credit
utilization
permanently
below
10%
and
paying
every
statement
balance
in
full
.
Deadline
:
age
40
B Y
AG E
40
02
Pay
off
the
primary
home
by
age
62
Make
one
extra
principal
payment
per
year
(
or
add
1/12
of
the
monthly
payment
each
month
).
On
a
30-
year
mortgage
taken
at
age
32,
this
shortens
the
loan
by
roughly
four
years
and
saves
tens
of
thousands
of
dollars
in
interest
.
Extra
: 1
payment
/
year
B Y
AG E
6 2
PAR T
0 3
Family
&
Education
Supporting
the
people
who
matter
—
without
derailing
your
own
retirement
.
01
Fully
fund
each
child
’
s
education
Save
toward
$
150,000
per
child
in
a
529
plan
—
roughly
$
300–
$
500
monthly
from
birth
to
age
18
,
boosted
by
birthday
and
holiday
gifts
.
Use
the
529’
s
tax
-
free
growth
for
tuition
,
room
,
board
,
and
qualified
education
costs
.
Per
child
:
$
150,000
CHILD
’
S
AG E
18
02
Create
a
sustainable
family
-
support
allowance
Define
a
clear
annual
budget
—
for
example
$
5,000–
$
10,000
per
year
—
to
help
aging
parents
or
adult
children
.
A
fixed
allowance
protects
your
core
savings
from
open
-
ended
requests
and
keeps
giving
generous
but
predictable
.
Budget
:
$
5–10
k
/
year
CONT INUOUS
2 / 3
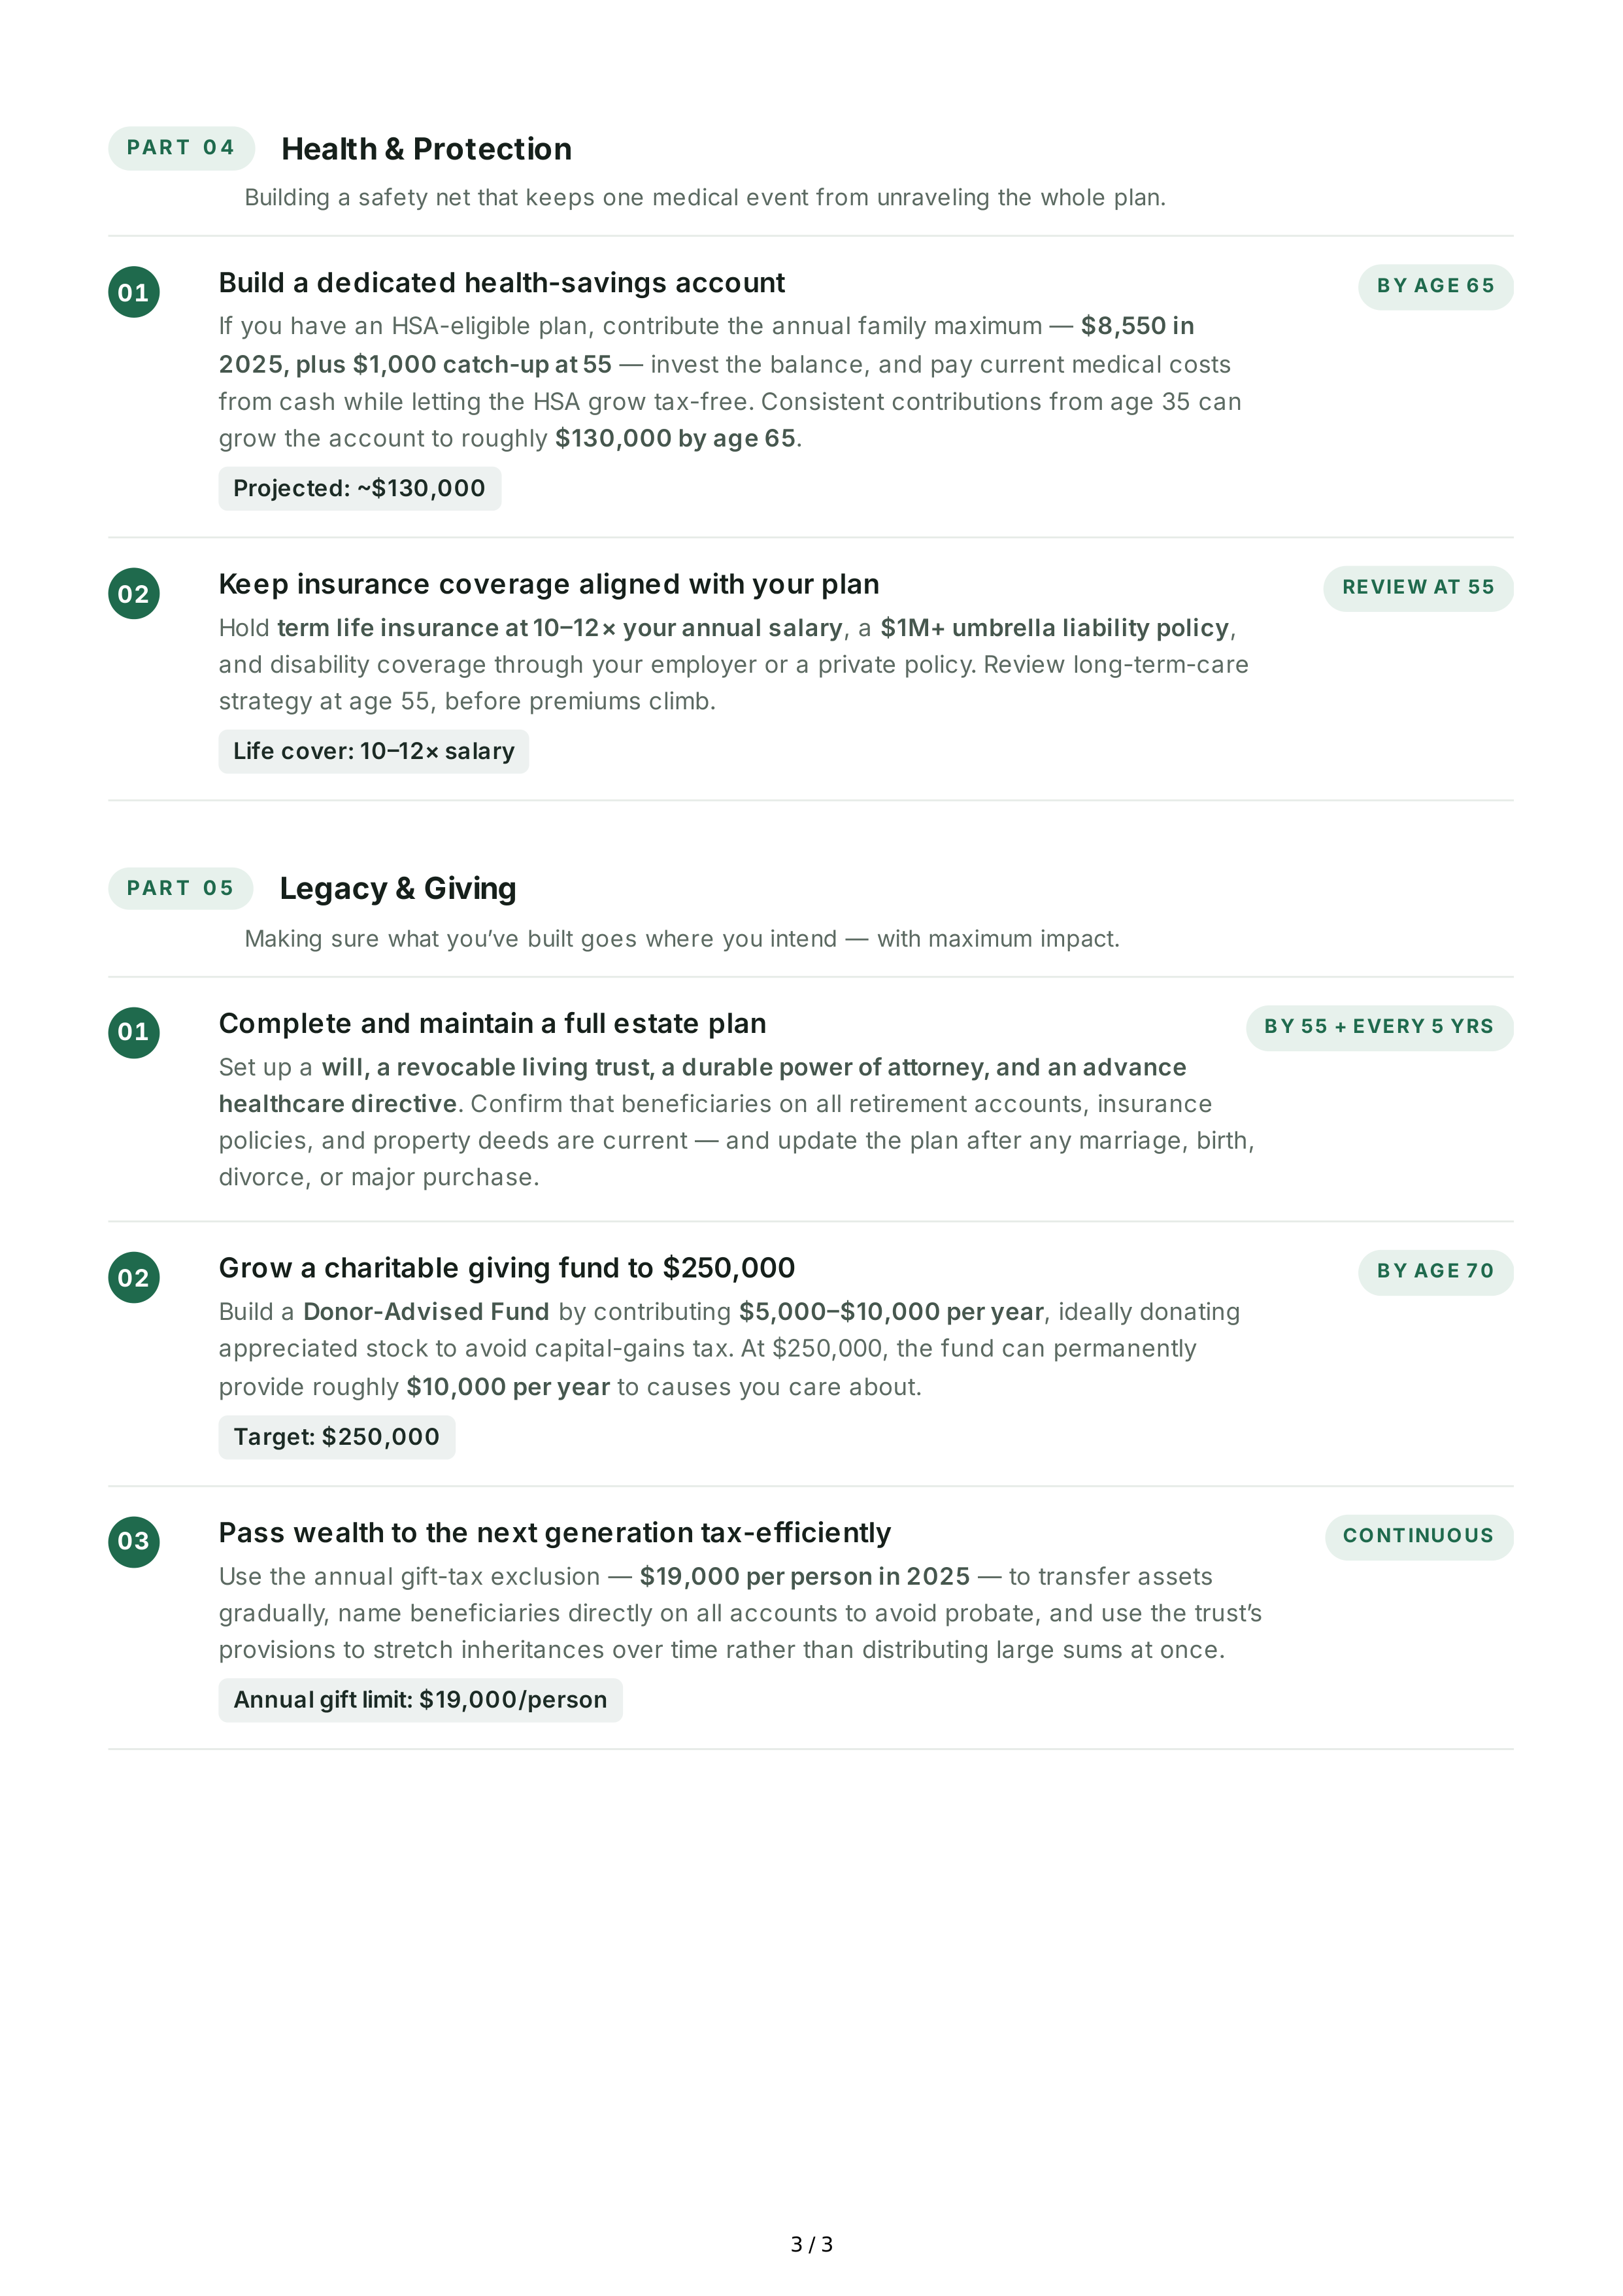
PAR T
0 4
Health
&
Protection
Building
a
safety
net
that
keeps
one
medical
event
from
unraveling
the
whole
plan
.
01
Build
a
dedicated
health
-
savings
account
If
you
have
an
HSA
-
eligible
plan
,
contribute
the
annual
family
maximum
—
$
8,550
in
2025,
plus
$
1,000
catch
-
up
at
55
—
invest
the
balance
,
and
pay
current
medical
costs
from
cash
while
letting
the
HSA
grow
tax
-
free
.
Consistent
contributions
from
age
35
can
grow
the
account
to
roughly
$
130,000
by
age
65
.
Projected
: ~
$
130,000
B Y
AG E
6 5
02
Keep
insurance
coverage
aligned
with
your
plan
Hold
term
life
insurance
at
10–12×
your
annual
salary
,
a
$
1
M
+
umbrella
liability
policy
,
and
disability
coverage
through
your
employer
or
a
private
policy
.
Review
long
-
term
-
care
strategy
at
age
55,
before
premiums
climb
.
Life
cover
: 10–12×
salary
REVIEW
AT
55
PAR T
0 5
Legacy
&
Giving
Making
sure
what
you
’
ve
built
goes
where
you
intend
—
with
maximum
impact
.
01
Complete
and
maintain
a
full
estate
plan
Set
up
a
will
,
a
revocable
living
trust
,
a
durable
power
of
attorney
,
and
an
advance
healthcare
directive
.
Confirm
that
beneficiaries
on
all
retirement
accounts
,
insurance
policies
,
and
property
deeds
are
current
—
and
update
the
plan
after
any
marriage
,
birth
,
divorce
,
or
major
purchase
.
B Y
55 +
EVERY
5
YRS
02
Grow
a
charitable
giving
fund
to
$
250,000
Build
a
Donor
-
Advised
Fund
by
contributing
$
5,000–
$
10,000
per
year
,
ideally
donating
appreciated
stock
to
avoid
capital
-
gains
tax
.
At
$
250,000,
the
fund
can
permanently
provide
roughly
$
10,000
per
year
to
causes
you
care
about
.
Target
:
$
250,000
B Y
AG E
70
03
Pass
wealth
to
the
next
generation
tax
-
efficiently
Use
the
annual
gift
-
tax
exclusion
—
$
19,000
per
person
in
2025
—
to
transfer
assets
gradually
,
name
beneficiaries
directly
on
all
accounts
to
avoid
probate
,
and
use
the
trust
’
s
provisions
to
stretch
inheritances
over
time
rather
than
distributing
large
sums
at
once
.
Annual
gift
limit
:
$
19,000/
person
CONT INUOUS
3 / 3