Short
-
Term
Debt
Reduction
Goals
P HA S E
A
—
GET
R EA DY
Goals
1–3 ·
your
first
2–4
weeks
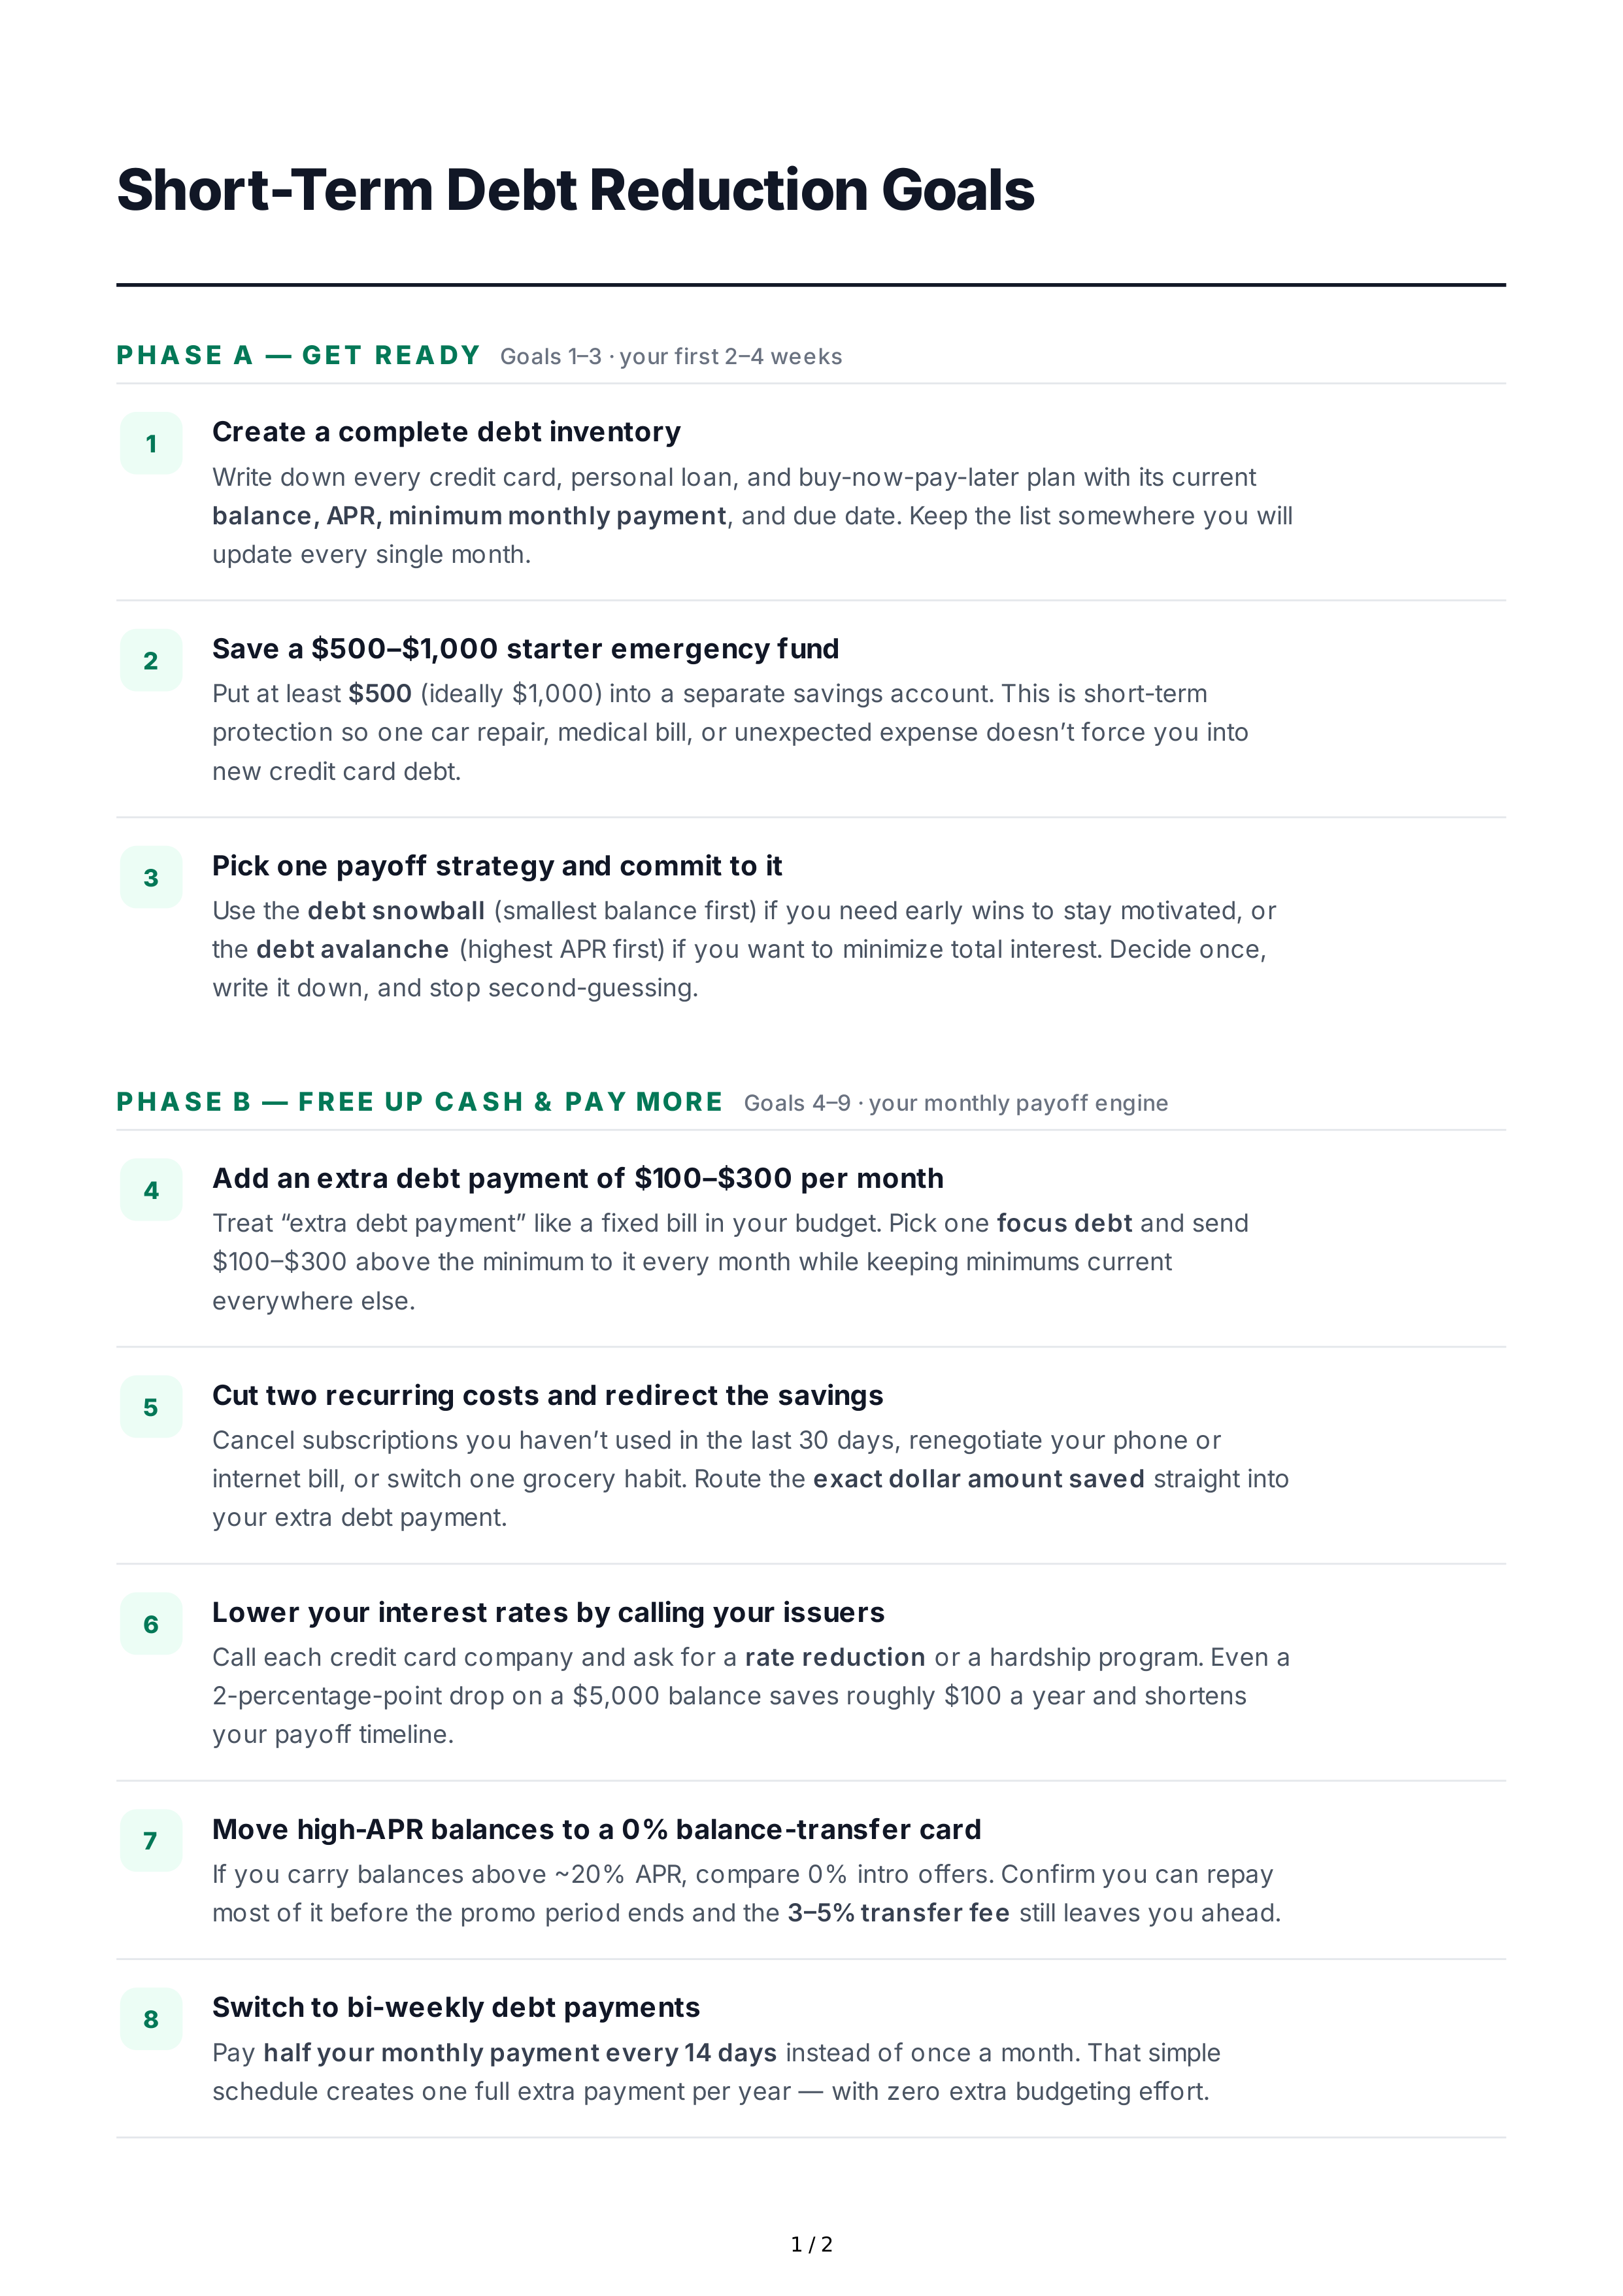
1
Create
a
complete
debt
inventory
Write
down
every
credit
card
,
personal
loan
,
and
buy
-
now
-
pay
-
later
plan
with
its
current
balance
,
APR
,
minimum
monthly
payment
,
and
due
date
.
Keep
the
list
somewhere
you
will
update
every
single
month
.
2
Save
a
$
500–
$
1,000
starter
emergency
fund
Put
at
least
$
500
(
ideally
$
1,000)
into
a
separate
savings
account
.
This
is
short
-
term
protection
so
one
car
repair
,
medical
bill
,
or
unexpected
expense
doesn
’
t
force
you
into
new
credit
card
debt
.
3
Pick
one
payoff
strategy
and
commit
to
it
Use
the
debt
snowball
(
smallest
balance
first
)
if
you
need
early
wins
to
stay
motivated
,
or
the
debt
avalanche
(
highest
APR
first
)
if
you
want
to
minimize
total
interest
.
Decide
once
,
write
it
down
,
and
stop
second
-
guessing
.
P HA S E
B
—
F R EE
UP
CA S H
&
PAY
MOR E
Goals
4–9 ·
your
monthly
payoff
engine
4
Add
an
extra
debt
payment
of
$
100–
$
300
per
month
Treat
“
extra
debt
payment
”
like
a
fixed
bill
in
your
budget
.
Pick
one
focus
debt
and
send
$
100–
$
300
above
the
minimum
to
it
every
month
while
keeping
minimums
current
everywhere
else
.
5
Cut
two
recurring
costs
and
redirect
the
savings
Cancel
subscriptions
you
haven
’
t
used
in
the
last
30
days
,
renegotiate
your
phone
or
internet
bill
,
or
switch
one
grocery
habit
.
Route
the
exact
dollar
amount
saved
straight
into
your
extra
debt
payment
.
6
Lower
your
interest
rates
by
calling
your
issuers
Call
each
credit
card
company
and
ask
for
a
rate
reduction
or
a
hardship
program
.
Even
a
2-
percentage
-
point
drop
on
a
$
5,000
balance
saves
roughly
$
100
a
year
and
shortens
your
payoff
timeline
.
7
Move
high
-
APR
balances
to
a
0%
balance
-
transfer
card
If
you
carry
balances
above
~20%
APR
,
compare
0%
intro
offers
.
Confirm
you
can
repay
most
of
it
before
the
promo
period
ends
and
the
3–5%
transfer
fee
still
leaves
you
ahead
.
8
Switch
to
bi
-
weekly
debt
payments
Pay
half
your
monthly
payment
every
14
days
instead
of
once
a
month
.
That
simple
schedule
creates
one
full
extra
payment
per
year
—
with
zero
extra
budgeting
effort
.
1 / 2
9
Send
100%
of
windfalls
to
debt
Tax
refunds
,
work
bonuses
,
cash
gifts
,
and
side
-
income
earnings
go
straight
to
your
focus
debt
before
you
give
yourself
a
chance
to
spend
them
.
Celebrate
briefly
,
then
transfer
the
full
amount
.
P HA S E
C
—
B UILD
MOMENT UM
Goals
10–12 ·
your
first
wins
&
long
-
term
traction
10
Fully
clear
your
smallest
debt
within
90
days
Identify
the
smallest
balance
on
your
list
and
make
it
your
mission
to
pay
it
off
completely
within
3
months
.
One
closed
account
changes
how
the
whole
plan
feels
—
and
frees
up
its
minimum
payment
for
the
next
target
.
11
Automate
every
payment
Enroll
in
autopay
for
the
minimum
on
every
account
to
eliminate
late
fees
,
then
set
a
separate
automatic
transfer
of
your
extra
payment
to
the
focus
debt
,
scheduled
for
the
day
after
payday
.
If
the
money
moves
before
you
see
it
,
you
can
’
t
spend
it
.
12
Review
your
balances
on
the
same
date
every
month
Pick
a
recurring
date
(
e
.
g
.
the
1
st
)
and
log
the
remaining
balance
of
every
debt
.
Seeing
the
total
drop
month
after
month
is
what
keeps
the
plan
alive
—
and
tells
you
when
it
’
s
time
to
roll
a
paid
-
off
payment
into
the
next
target
.
2 / 2