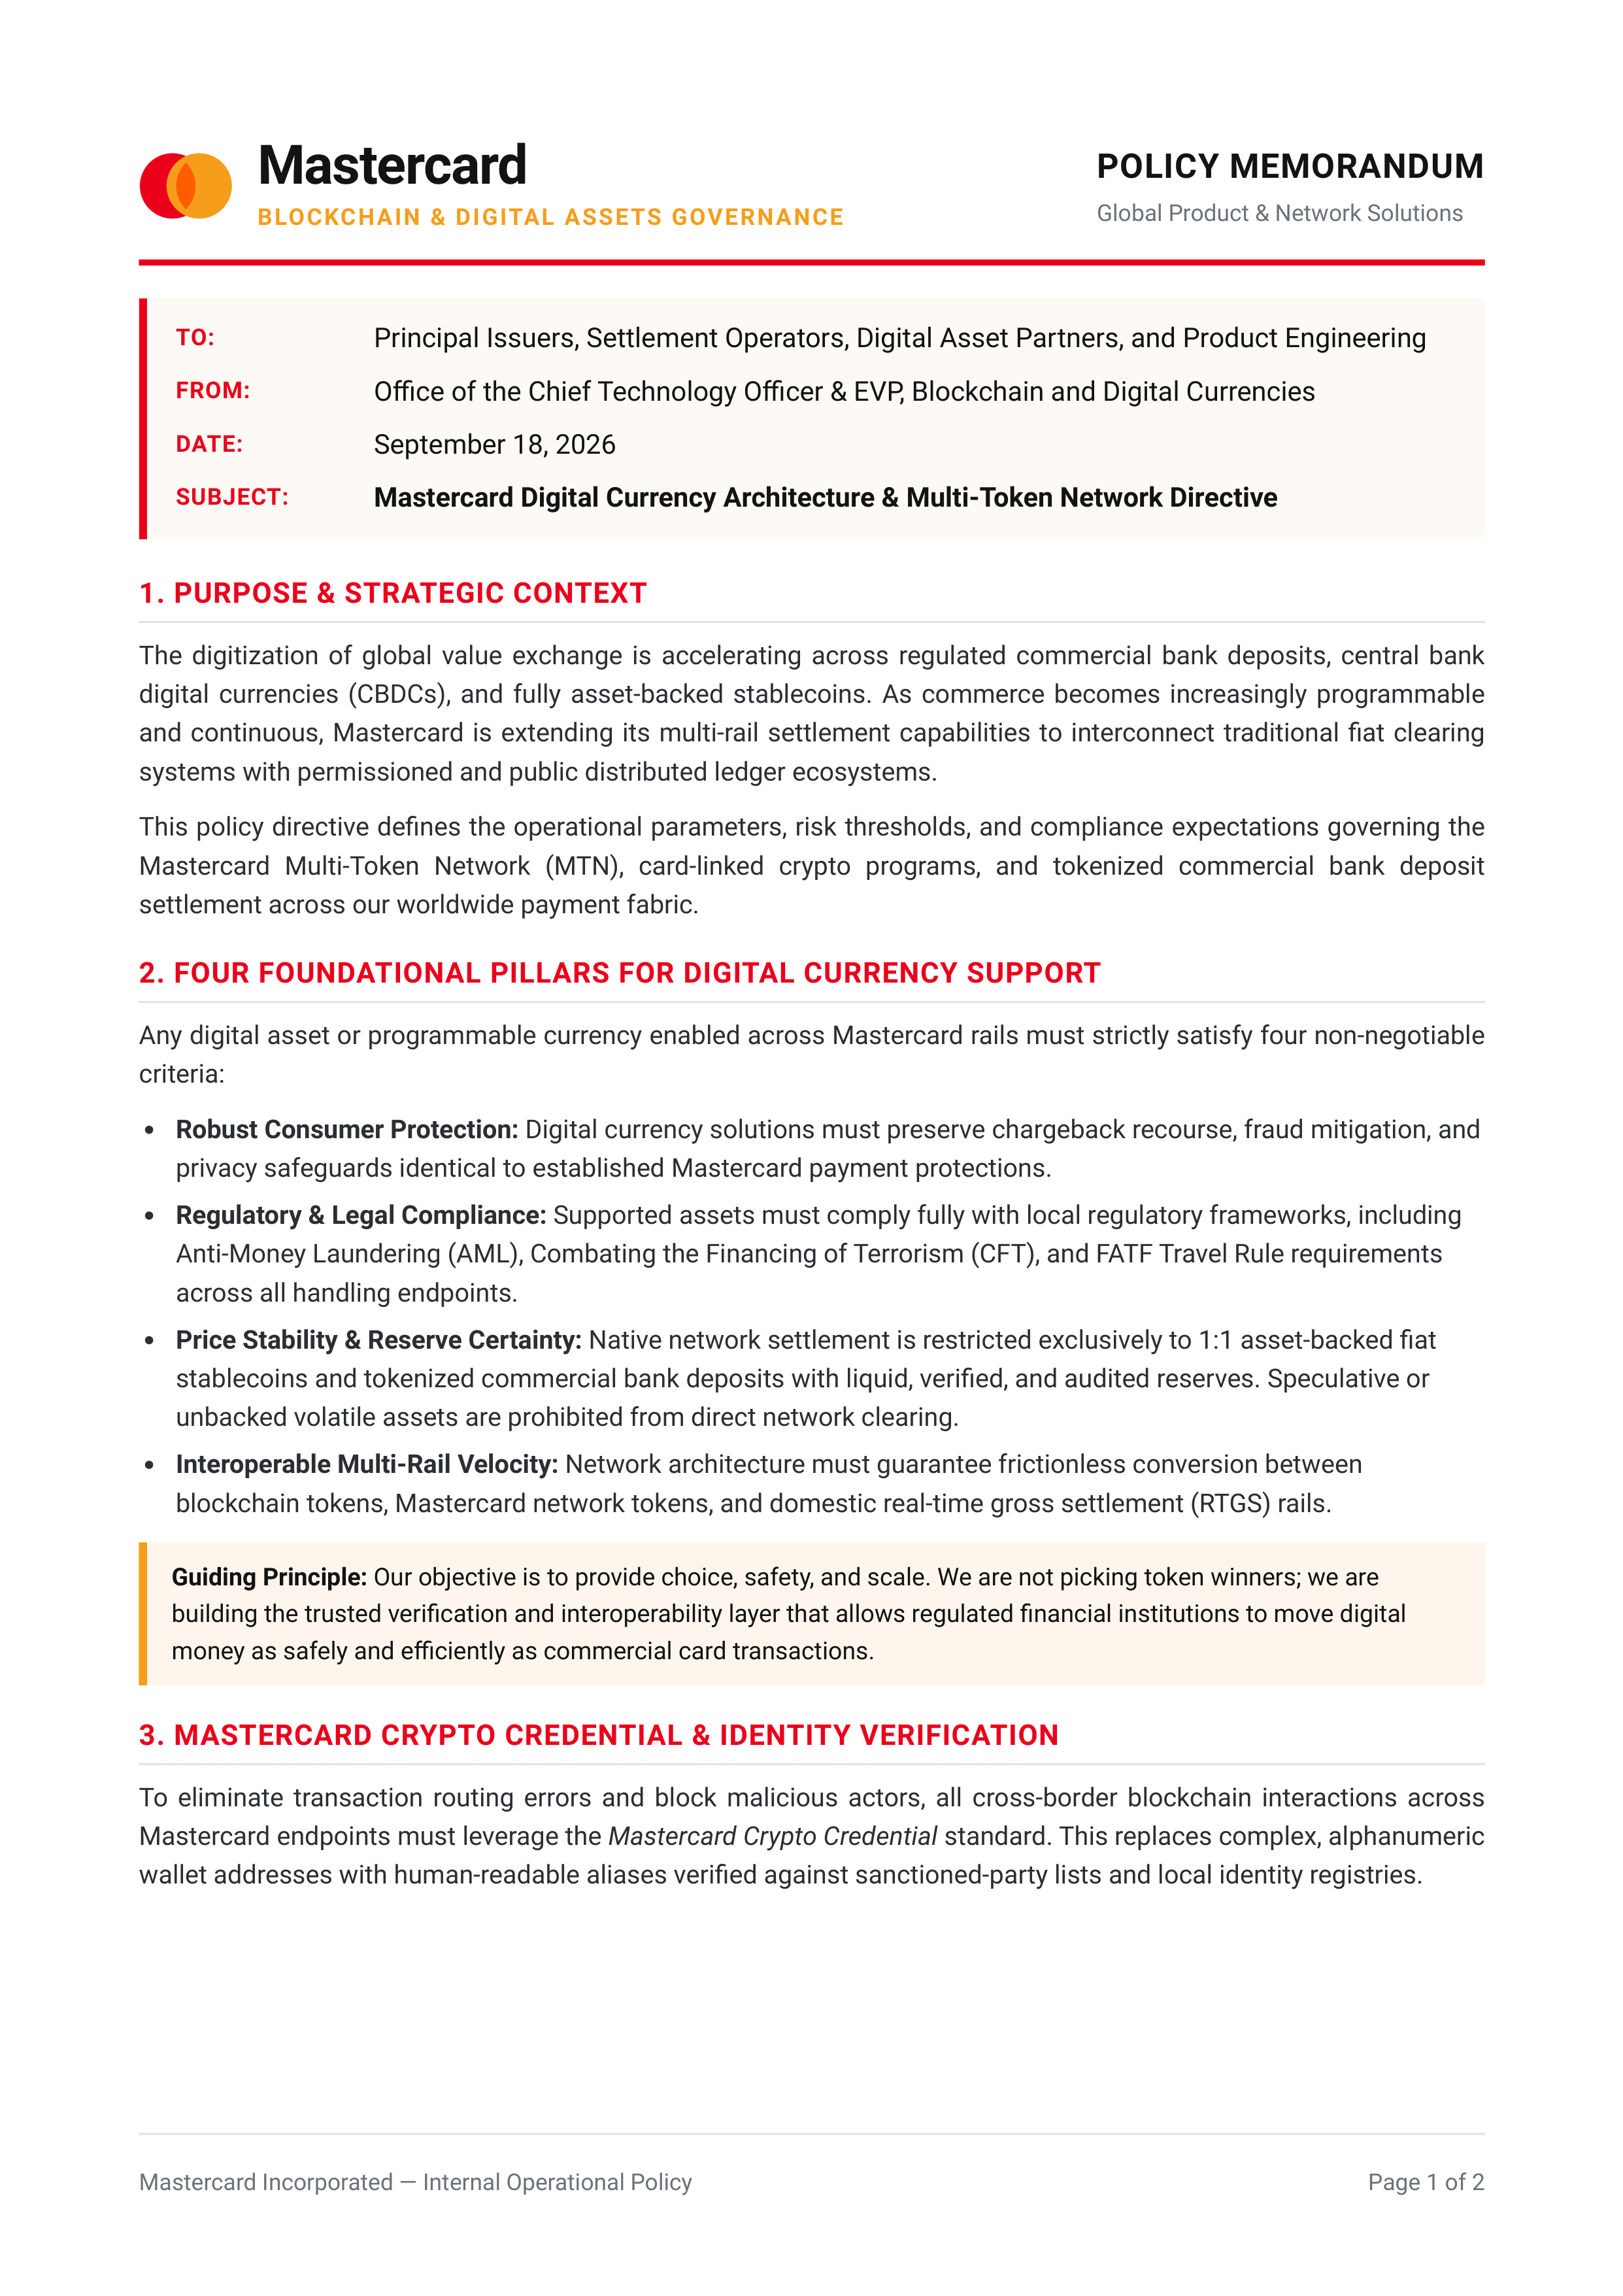
Mastercard
BLOCKCHAIN & DIGITAL ASSETS GOVERNANCE
POLICY MEMORANDUM
Global Product & Network Solutions
TO:
Principal Issuers, Settlement Operators, Digital Asset Partners, and Product Engineering
FROM:
O
ffi
ce of the Chief Technology O
ffi
cer & EVP, Blockchain and Digital Currencies
DATE:
September 18, 2026
SUBJECT:
Mastercard Digital Currency Architecture & Multi-Token Network Directive
1. PURPOSE & STRATEGIC CONTEXT
The digitization of global value exchange is accelerating across regulated commercial bank deposits, central bank
digital currencies (CBDCs), and fully asset-backed stablecoins. As commerce becomes increasingly programmable
and continuous, Mastercard is extending its multi-rail settlement capabilities to interconnect traditional
fi
at clearing
systems with permissioned and public distributed ledger ecosystems.
This policy directive de
fi
nes the operational parameters, risk thresholds, and compliance expectations governing the
Mastercard Multi-Token Network (MTN), card-linked crypto programs, and tokenized commercial bank deposit
settlement across our worldwide payment fabric.
2. FOUR FOUNDATIONAL PILLARS FOR DIGITAL CURRENCY SUPPORT
Any digital asset or programmable currency enabled across Mastercard rails must strictly satisfy four non-negotiable
criteria:
Robust Consumer Protection:
Digital currency solutions must preserve chargeback recourse, fraud mitigation, and
privacy safeguards identical to established Mastercard payment protections.
Regulatory & Legal Compliance:
Supported assets must comply fully with local regulatory frameworks, including
Anti-Money Laundering (AML), Combating the Financing of Terrorism (CFT), and FATF Travel Rule requirements
across all handling endpoints.
Price Stability & Reserve Certainty:
Native network settlement is restricted exclusively to 1:1 asset-backed
fi
at
stablecoins and tokenized commercial bank deposits with liquid, veri
fi
ed, and audited reserves. Speculative or
unbacked volatile assets are prohibited from direct network clearing.
Interoperable Multi-Rail Velocity:
Network architecture must guarantee frictionless conversion between
blockchain tokens, Mastercard network tokens, and domestic real-time gross settlement (RTGS) rails.
Guiding Principle:
Our objective is to provide choice, safety, and scale. We are not picking token winners; we are
building the trusted veri
fi
cation and interoperability layer that allows regulated
fi
nancial institutions to move digital
money as safely and e
ffi
ciently as commercial card transactions.
3. MASTERCARD CRYPTO CREDENTIAL & IDENTITY VERIFICATION
To eliminate transaction routing errors and block malicious actors, all cross-border blockchain interactions across
Mastercard endpoints must leverage the
Mastercard Crypto Credential
standard. This replaces complex, alphanumeric
wallet addresses with human-readable aliases veri
fi
ed against sanctioned-party lists and local identity registries.
Mastercard Incorporated
—
Internal Operational Policy
Page 1 of 2