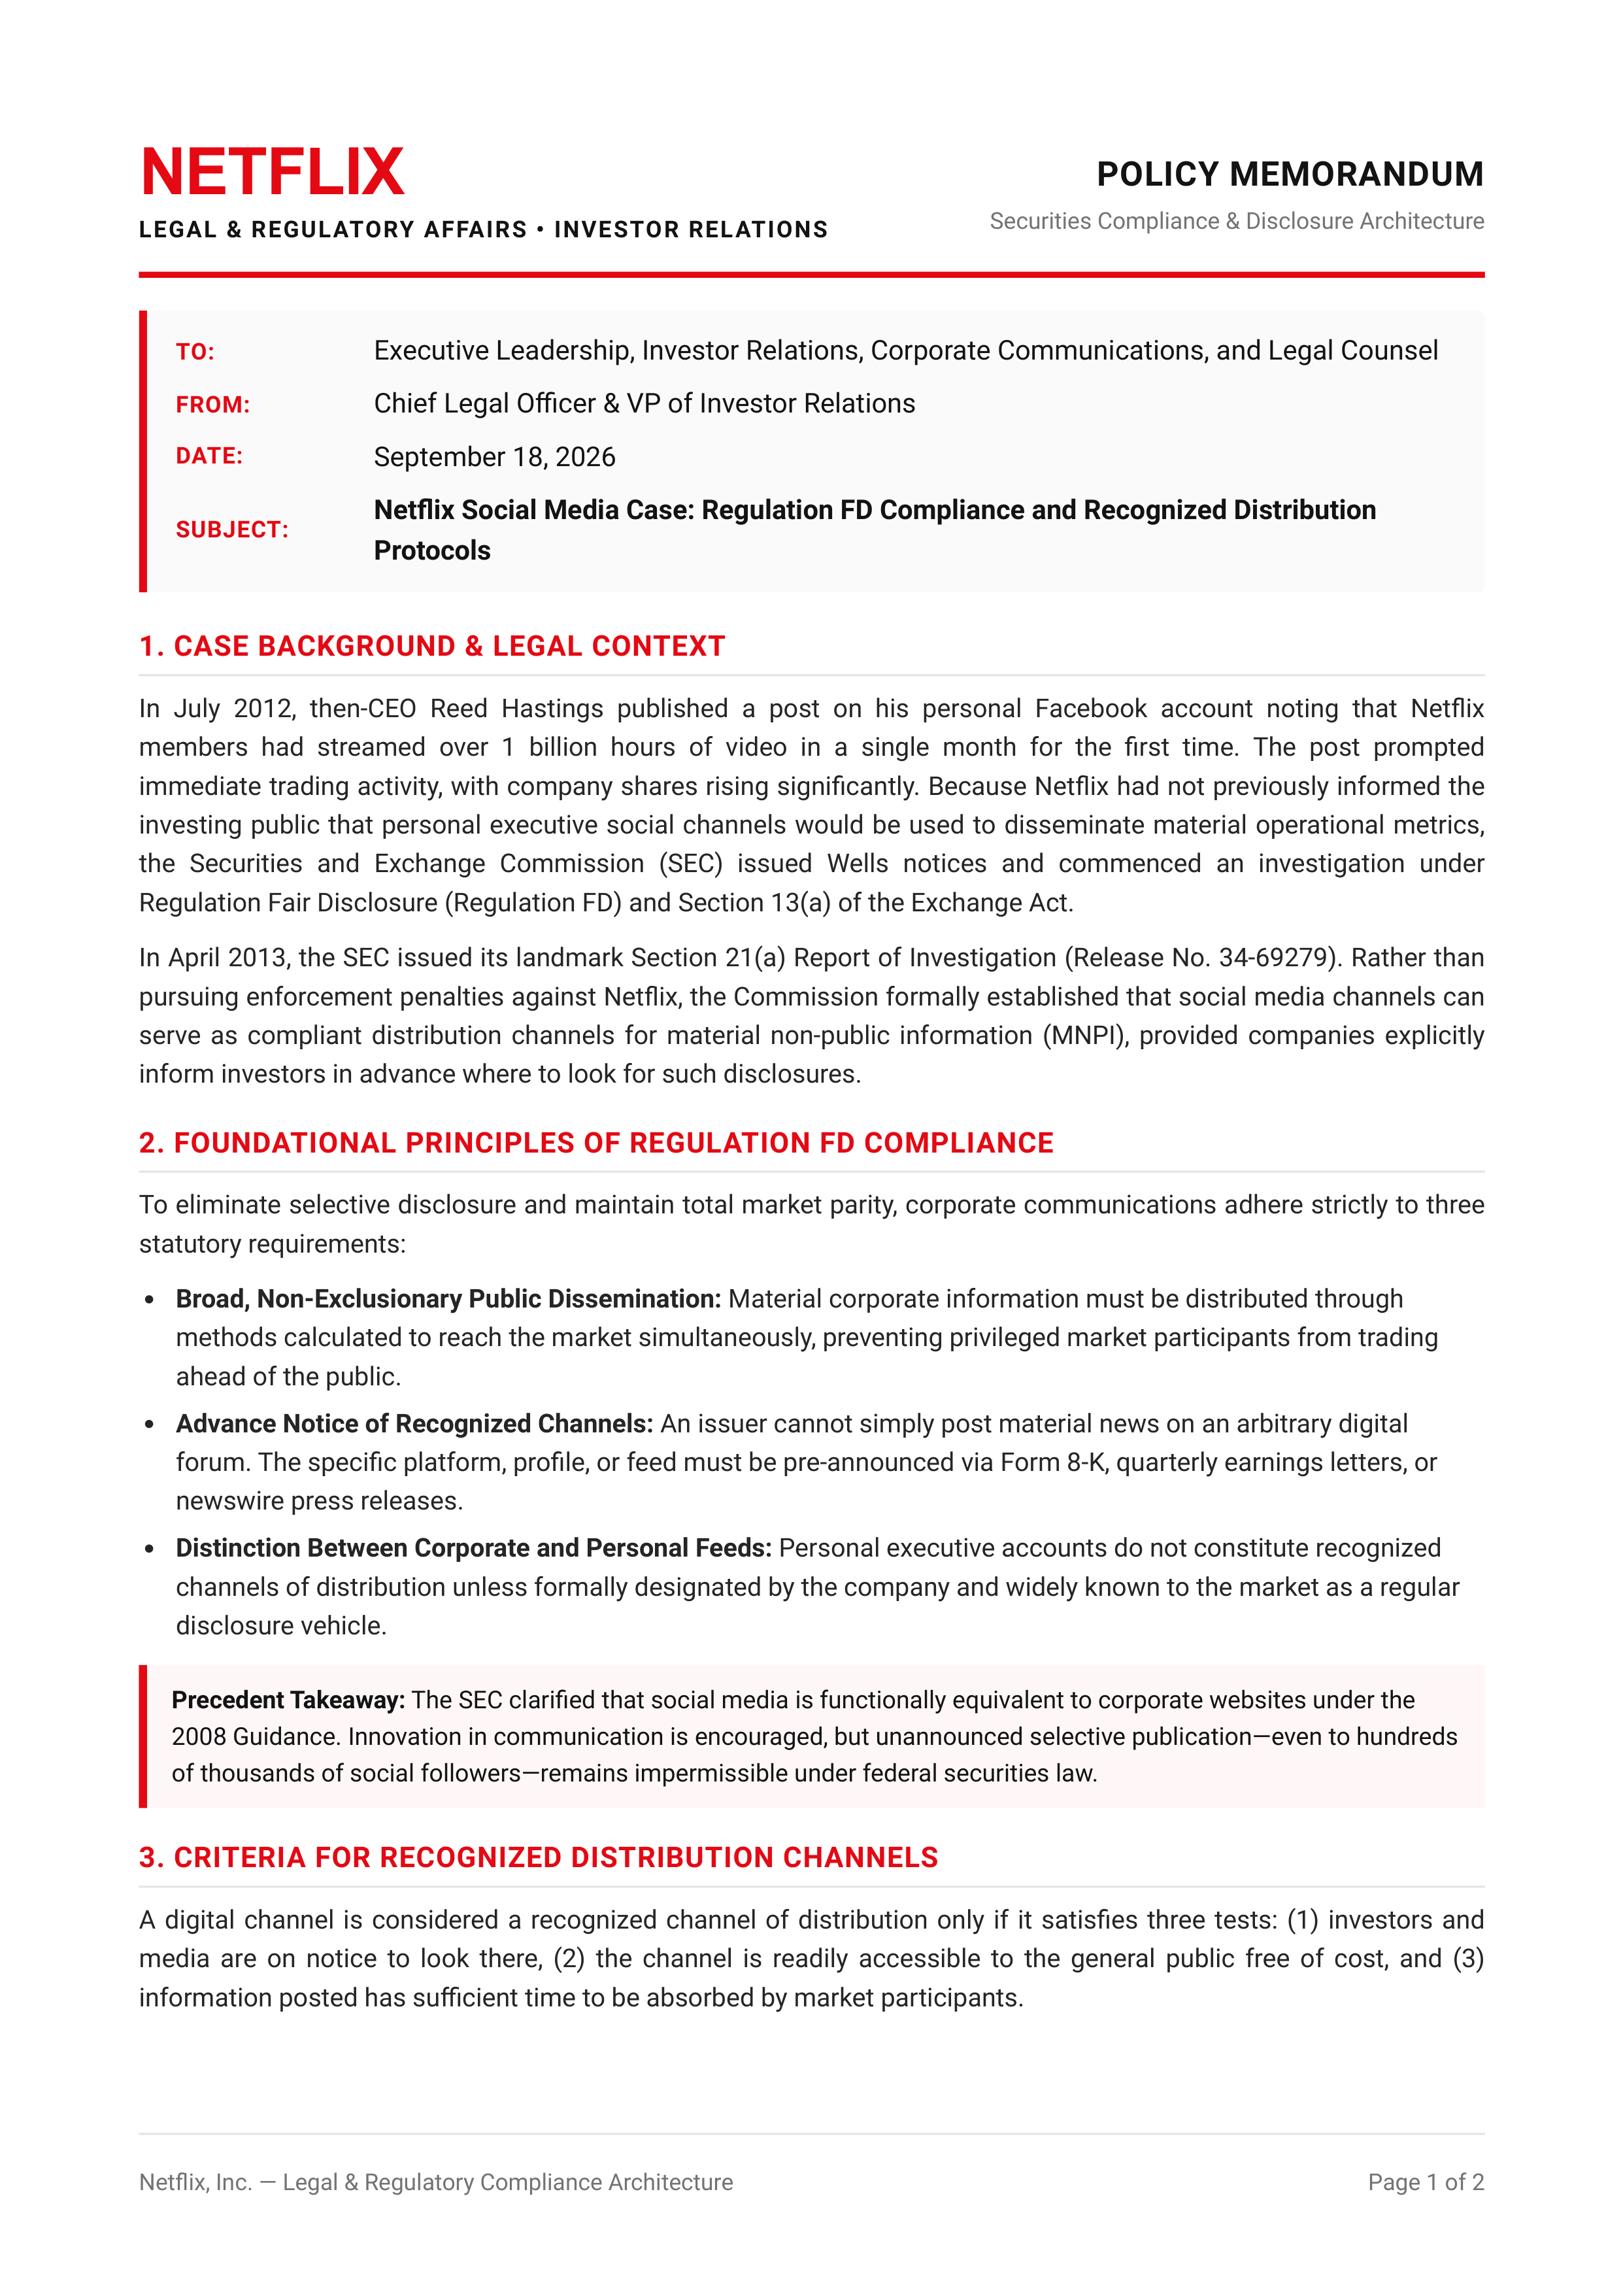
NETFLIX
LEGAL & REGULATORY AFFAIRS
•
INVESTOR RELATIONS
POLICY MEMORANDUM
Securities Compliance & Disclosure Architecture
TO:
Executive Leadership, Investor Relations, Corporate Communications, and Legal Counsel
FROM:
Chief Legal O
ffi
cer & VP of Investor Relations
DATE:
September 18, 2026
SUBJECT:
Net
fl
ix Social Media Case: Regulation FD Compliance and Recognized Distribution
Protocols
1. CASE BACKGROUND & LEGAL CONTEXT
In July 2012, then-CEO Reed Hastings published a post on his personal Facebook account noting that Net
fl
ix
members had streamed over 1 billion hours of video in a single month for the
fi
rst time. The post prompted
immediate trading activity, with company shares rising signi
fi
cantly. Because Net
fl
ix had not previously informed the
investing public that personal executive social channels would be used to disseminate material operational metrics,
the Securities and Exchange Commission (SEC) issued Wells notices and commenced an investigation under
Regulation Fair Disclosure (Regulation FD) and Section 13(a) of the Exchange Act.
In April 2013, the SEC issued its landmark Section 21(a) Report of Investigation (Release No. 34-69279). Rather than
pursuing enforcement penalties against Net
fl
ix, the Commission formally established that social media channels can
serve as compliant distribution channels for material non-public information (MNPI), provided companies explicitly
inform investors in advance where to look for such disclosures.
2. FOUNDATIONAL PRINCIPLES OF REGULATION FD COMPLIANCE
To eliminate selective disclosure and maintain total market parity, corporate communications adhere strictly to three
statutory requirements:
Broad, Non-Exclusionary Public Dissemination:
Material corporate information must be distributed through
methods calculated to reach the market simultaneously, preventing privileged market participants from trading
ahead of the public.
Advance Notice of Recognized Channels:
An issuer cannot simply post material news on an arbitrary digital
forum. The speci
fi
c platform, pro
fi
le, or feed must be pre-announced via Form 8-K, quarterly earnings letters, or
newswire press releases.
Distinction Between Corporate and Personal Feeds:
Personal executive accounts do not constitute recognized
channels of distribution unless formally designated by the company and widely known to the market as a regular
disclosure vehicle.
Precedent Takeaway:
The SEC clari
fi
ed that social media is functionally equivalent to corporate websites under the
2008 Guidance. Innovation in communication is encouraged, but unannounced selective publication
—
even to hundreds
of thousands of social followers
—
remains impermissible under federal securities law.
3. CRITERIA FOR RECOGNIZED DISTRIBUTION CHANNELS
A digital channel is considered a recognized channel of distribution only if it satis
fi
es three tests: (1) investors and
media are on notice to look there, (2) the channel is readily accessible to the general public free of cost, and (3)
information posted has su
ffi
cient time to be absorbed by market participants.
Net
fl
ix, Inc.
—
Legal & Regulatory Compliance Architecture
Page 1 of 2