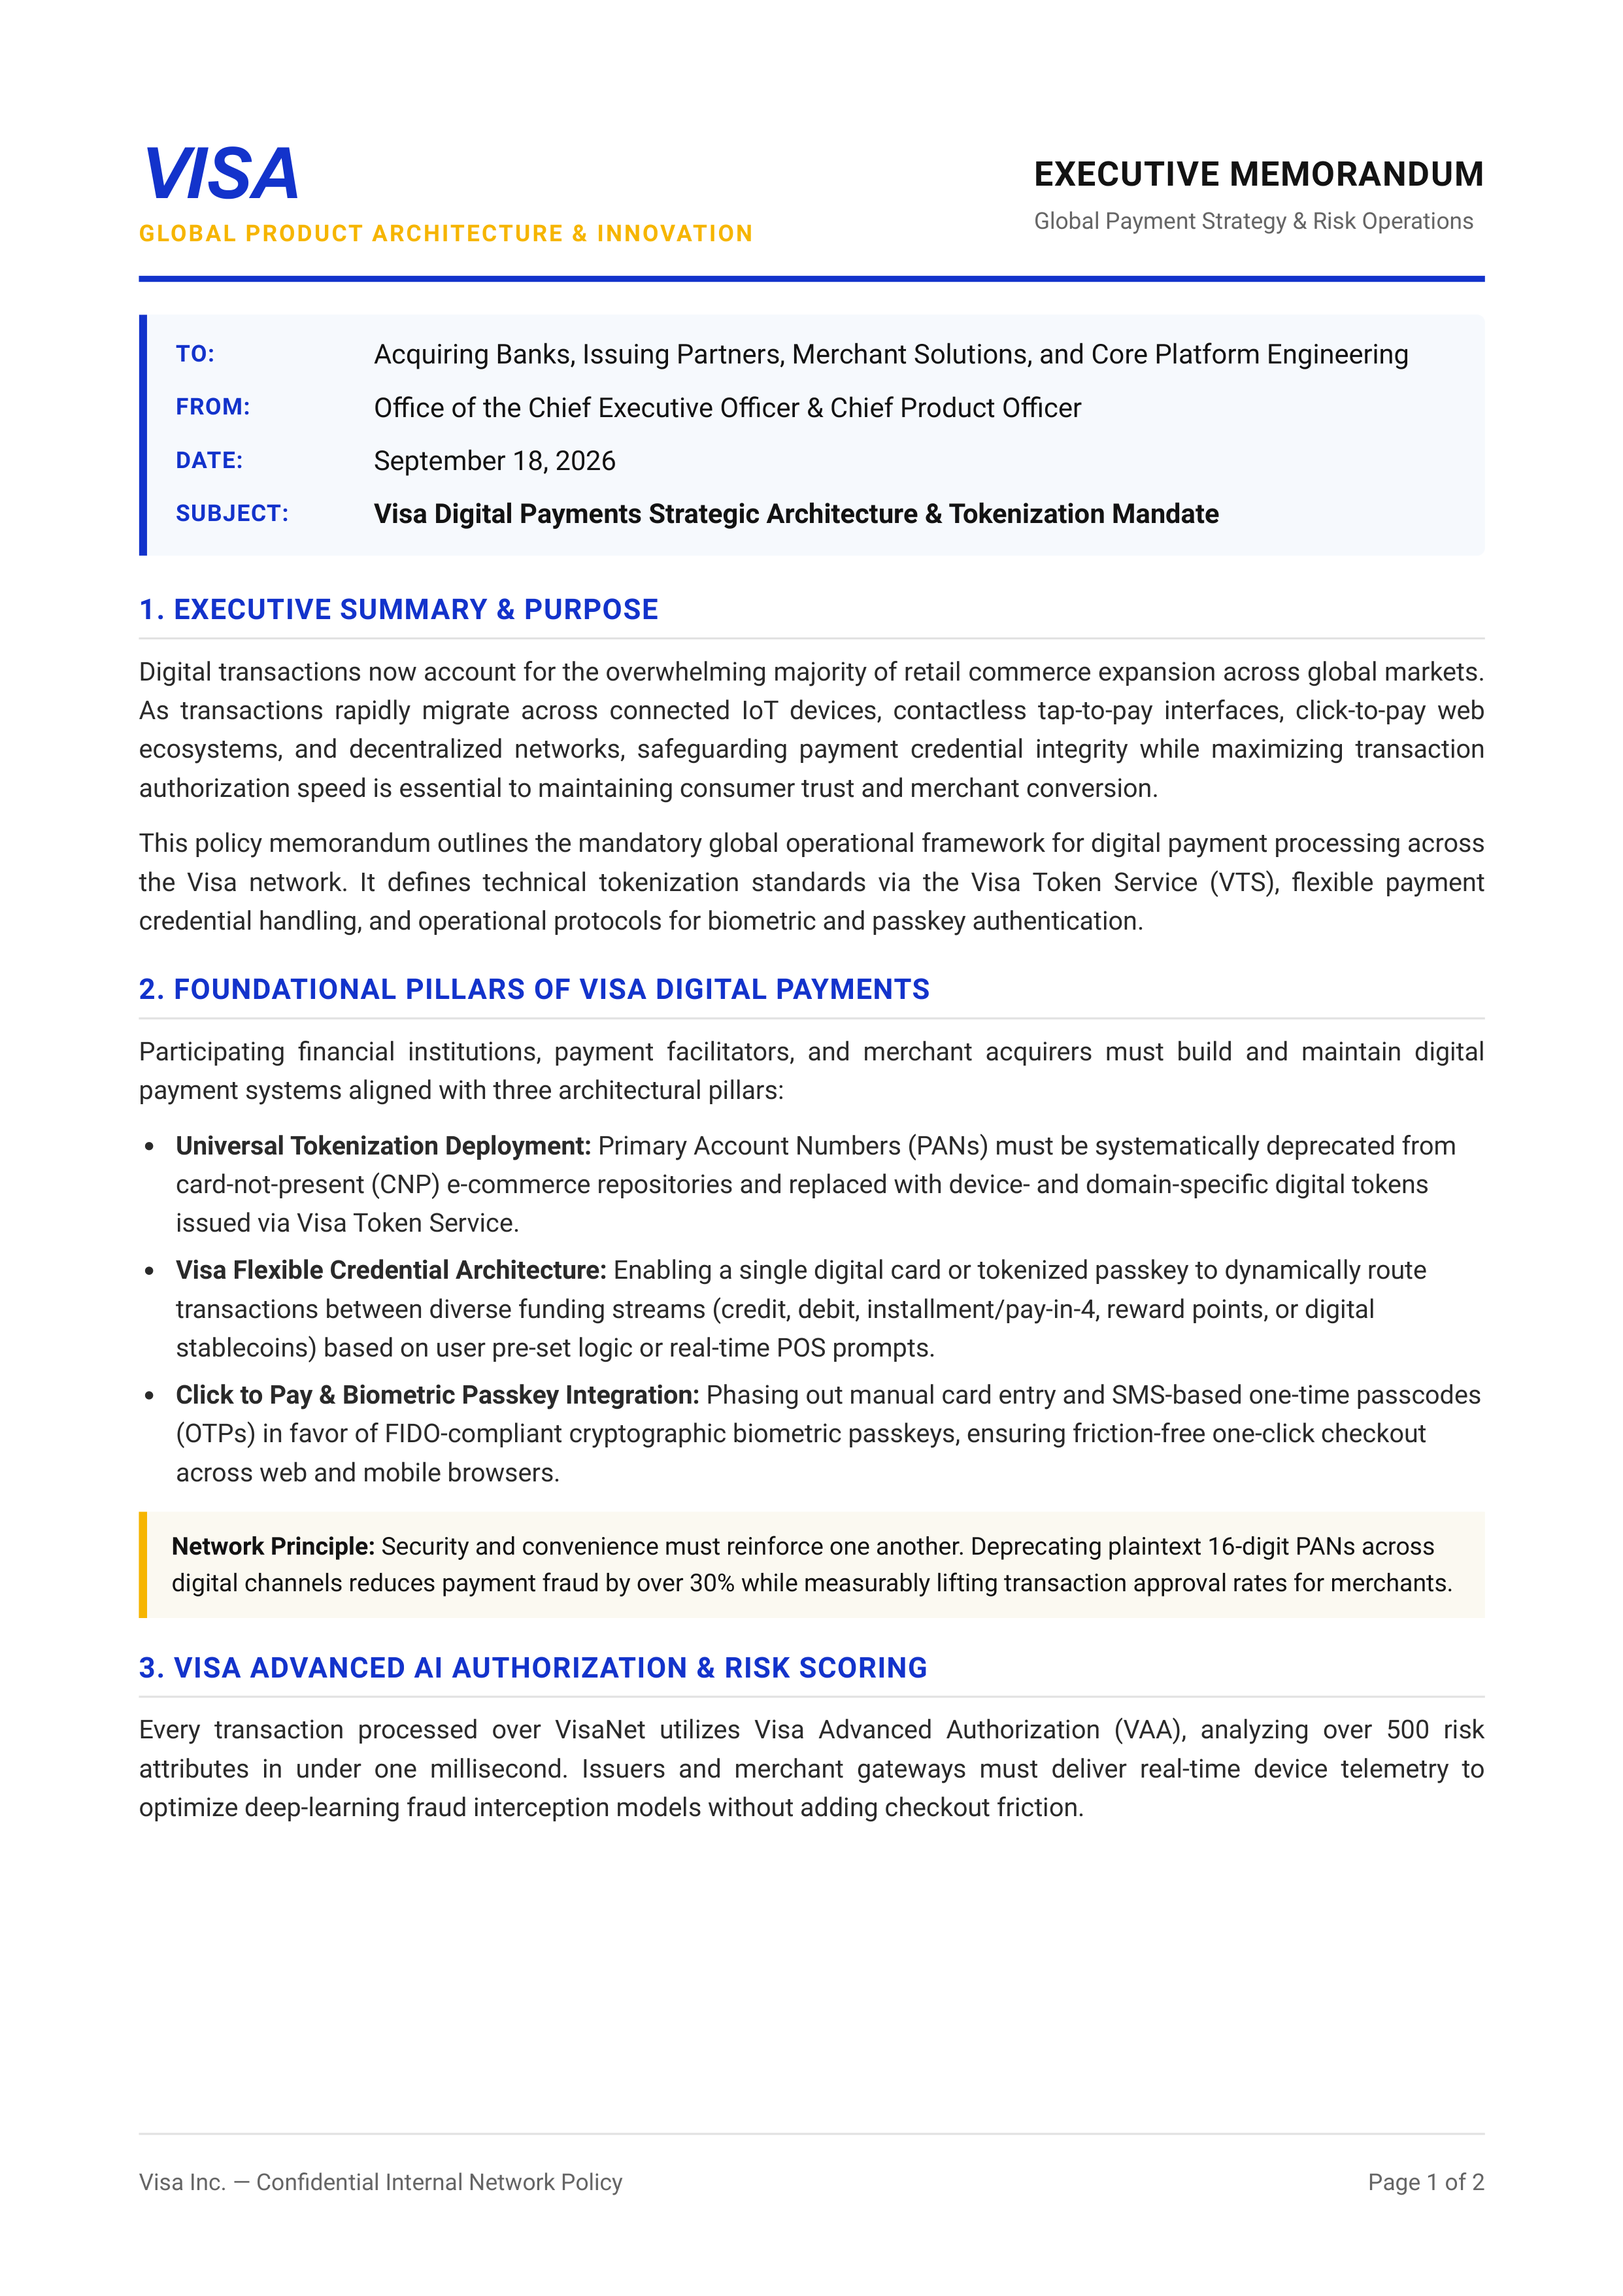
VISA
GLOBAL PRODUCT ARCHITECTURE & INNOVATION
EXECUTIVE MEMORANDUM
Global Payment Strategy & Risk Operations
TO:
Acquiring Banks, Issuing Partners, Merchant Solutions, and Core Platform Engineering
FROM:
O
ffi
ce of the Chief Executive O
ffi
cer & Chief Product O
ffi
cer
DATE:
September 18, 2026
SUBJECT:
Visa Digital Payments Strategic Architecture & Tokenization Mandate
1. EXECUTIVE SUMMARY & PURPOSE
Digital transactions now account for the overwhelming majority of retail commerce expansion across global markets.
As transactions rapidly migrate across connected IoT devices, contactless tap-to-pay interfaces, click-to-pay web
ecosystems, and decentralized networks, safeguarding payment credential integrity while maximizing transaction
authorization speed is essential to maintaining consumer trust and merchant conversion.
This policy memorandum outlines the mandatory global operational framework for digital payment processing across
the Visa network. It de
fi
nes technical tokenization standards via the Visa Token Service (VTS),
fl
exible payment
credential handling, and operational protocols for biometric and passkey authentication.
2. FOUNDATIONAL PILLARS OF VISA DIGITAL PAYMENTS
Participating
fi
nancial institutions, payment facilitators, and merchant acquirers must build and maintain digital
payment systems aligned with three architectural pillars:
Universal Tokenization Deployment:
Primary Account Numbers (PANs) must be systematically deprecated from
card-not-present (CNP) e-commerce repositories and replaced with device- and domain-speci
fi
c digital tokens
issued via Visa Token Service.
Visa Flexible Credential Architecture:
Enabling a single digital card or tokenized passkey to dynamically route
transactions between diverse funding streams (credit, debit, installment/pay-in-4, reward points, or digital
stablecoins) based on user pre-set logic or real-time POS prompts.
Click to Pay & Biometric Passkey Integration:
Phasing out manual card entry and SMS-based one-time passcodes
(OTPs) in favor of FIDO-compliant cryptographic biometric passkeys, ensuring friction-free one-click checkout
across web and mobile browsers.
Network Principle:
Security and convenience must reinforce one another. Deprecating plaintext 16-digit PANs across
digital channels reduces payment fraud by over 30% while measurably lifting transaction approval rates for merchants.
3. VISA ADVANCED AI AUTHORIZATION & RISK SCORING
Every transaction processed over VisaNet utilizes Visa Advanced Authorization (VAA), analyzing over 500 risk
attributes in under one millisecond. Issuers and merchant gateways must deliver real-time device telemetry to
optimize deep-learning fraud interception models without adding checkout friction.
Visa Inc.
—
Con
fi
dential Internal Network Policy
Page 1 of 2