WF
Wells Fargo
CONSUMER, SMALL & BUSINESS BANKING (CSBB)
STRATEGIC MEMORANDUM
Retail Network Modernization & Omnichannel Delivery
TO:
Regional Bank Presidents, Branch Operations Leads, Retail Market Executives & Digital
Banking
FROM:
Chief Executive O
ffi
cer & Senior Executive Vice President, Head of Consumer & Small
Business Banking
DATE:
September 18, 2026
SUBJECT:
Wells Fargo Branch Strategy: Network Optimization, Advisory Transformation & Digital-
Physical Integration
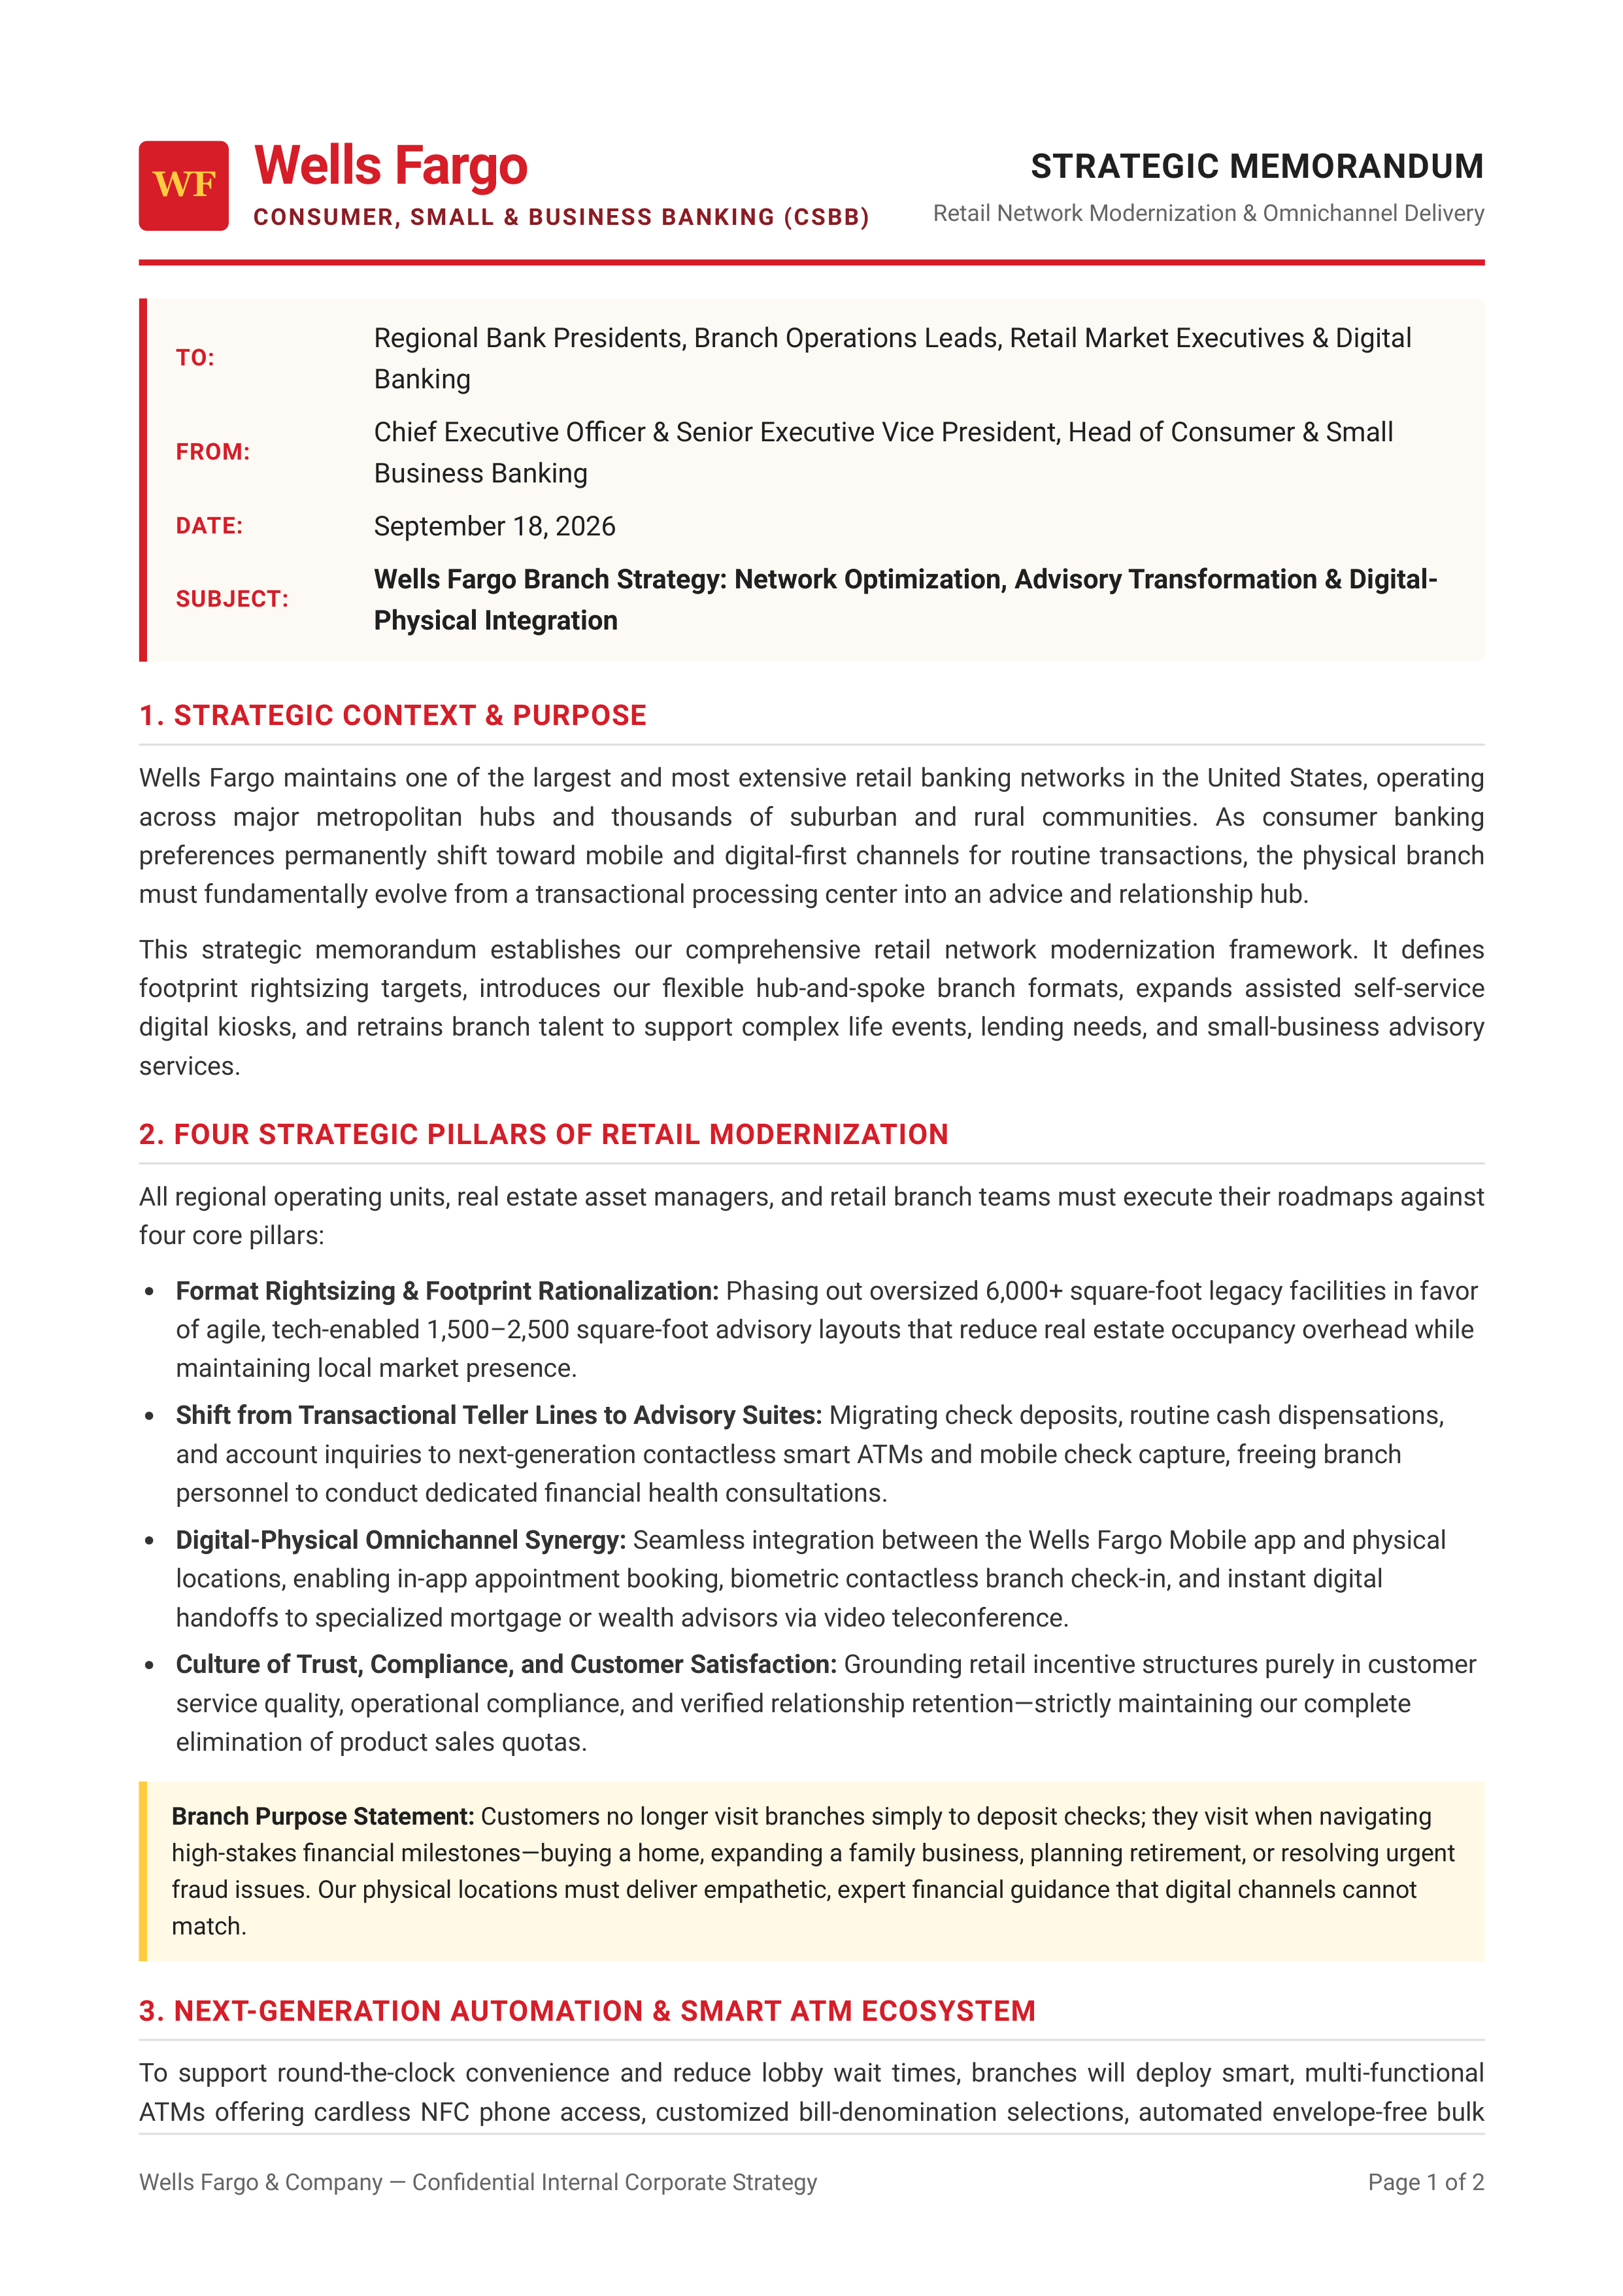
1. STRATEGIC CONTEXT & PURPOSE
Wells Fargo maintains one of the largest and most extensive retail banking networks in the United States, operating
across major metropolitan hubs and thousands of suburban and rural communities. As consumer banking
preferences permanently shift toward mobile and digital-
fi
rst channels for routine transactions, the physical branch
must fundamentally evolve from a transactional processing center into an advice and relationship hub.
This strategic memorandum establishes our comprehensive retail network modernization framework. It de
fi
nes
footprint rightsizing targets, introduces our
fl
exible hub-and-spoke branch formats, expands assisted self-service
digital kiosks, and retrains branch talent to support complex life events, lending needs, and small-business advisory
services.
2. FOUR STRATEGIC PILLARS OF RETAIL MODERNIZATION
All regional operating units, real estate asset managers, and retail branch teams must execute their roadmaps against
four core pillars:
Format Rightsizing & Footprint Rationalization:
Phasing out oversized 6,000+ square-foot legacy facilities in favor
of agile, tech-enabled 1,500
–
2,500 square-foot advisory layouts that reduce real estate occupancy overhead while
maintaining local market presence.
Shift from Transactional Teller Lines to Advisory Suites:
Migrating check deposits, routine cash dispensations,
and account inquiries to next-generation contactless smart ATMs and mobile check capture, freeing branch
personnel to conduct dedicated
fi
nancial health consultations.
Digital-Physical Omnichannel Synergy:
Seamless integration between the Wells Fargo Mobile app and physical
locations, enabling in-app appointment booking, biometric contactless branch check-in, and instant digital
handoffs to specialized mortgage or wealth advisors via video teleconference.
Culture of Trust, Compliance, and Customer Satisfaction:
Grounding retail incentive structures purely in customer
service quality, operational compliance, and veri
fi
ed relationship retention
—
strictly maintaining our complete
elimination of product sales quotas.
Branch Purpose Statement:
Customers no longer visit branches simply to deposit checks; they visit when navigating
high-stakes
fi
nancial milestones
—
buying a home, expanding a family business, planning retirement, or resolving urgent
fraud issues. Our physical locations must deliver empathetic, expert
fi
nancial guidance that digital channels cannot
match.
3. NEXT-GENERATION AUTOMATION & SMART ATM ECOSYSTEM
To support round-the-clock convenience and reduce lobby wait times, branches will deploy smart, multi-functional
ATMs offering cardless NFC phone access, customized bill-denomination selections, automated envelope-free bulk
Wells Fargo & Company
—
Con
fi
dential Internal Corporate Strategy
Page 1 of 2
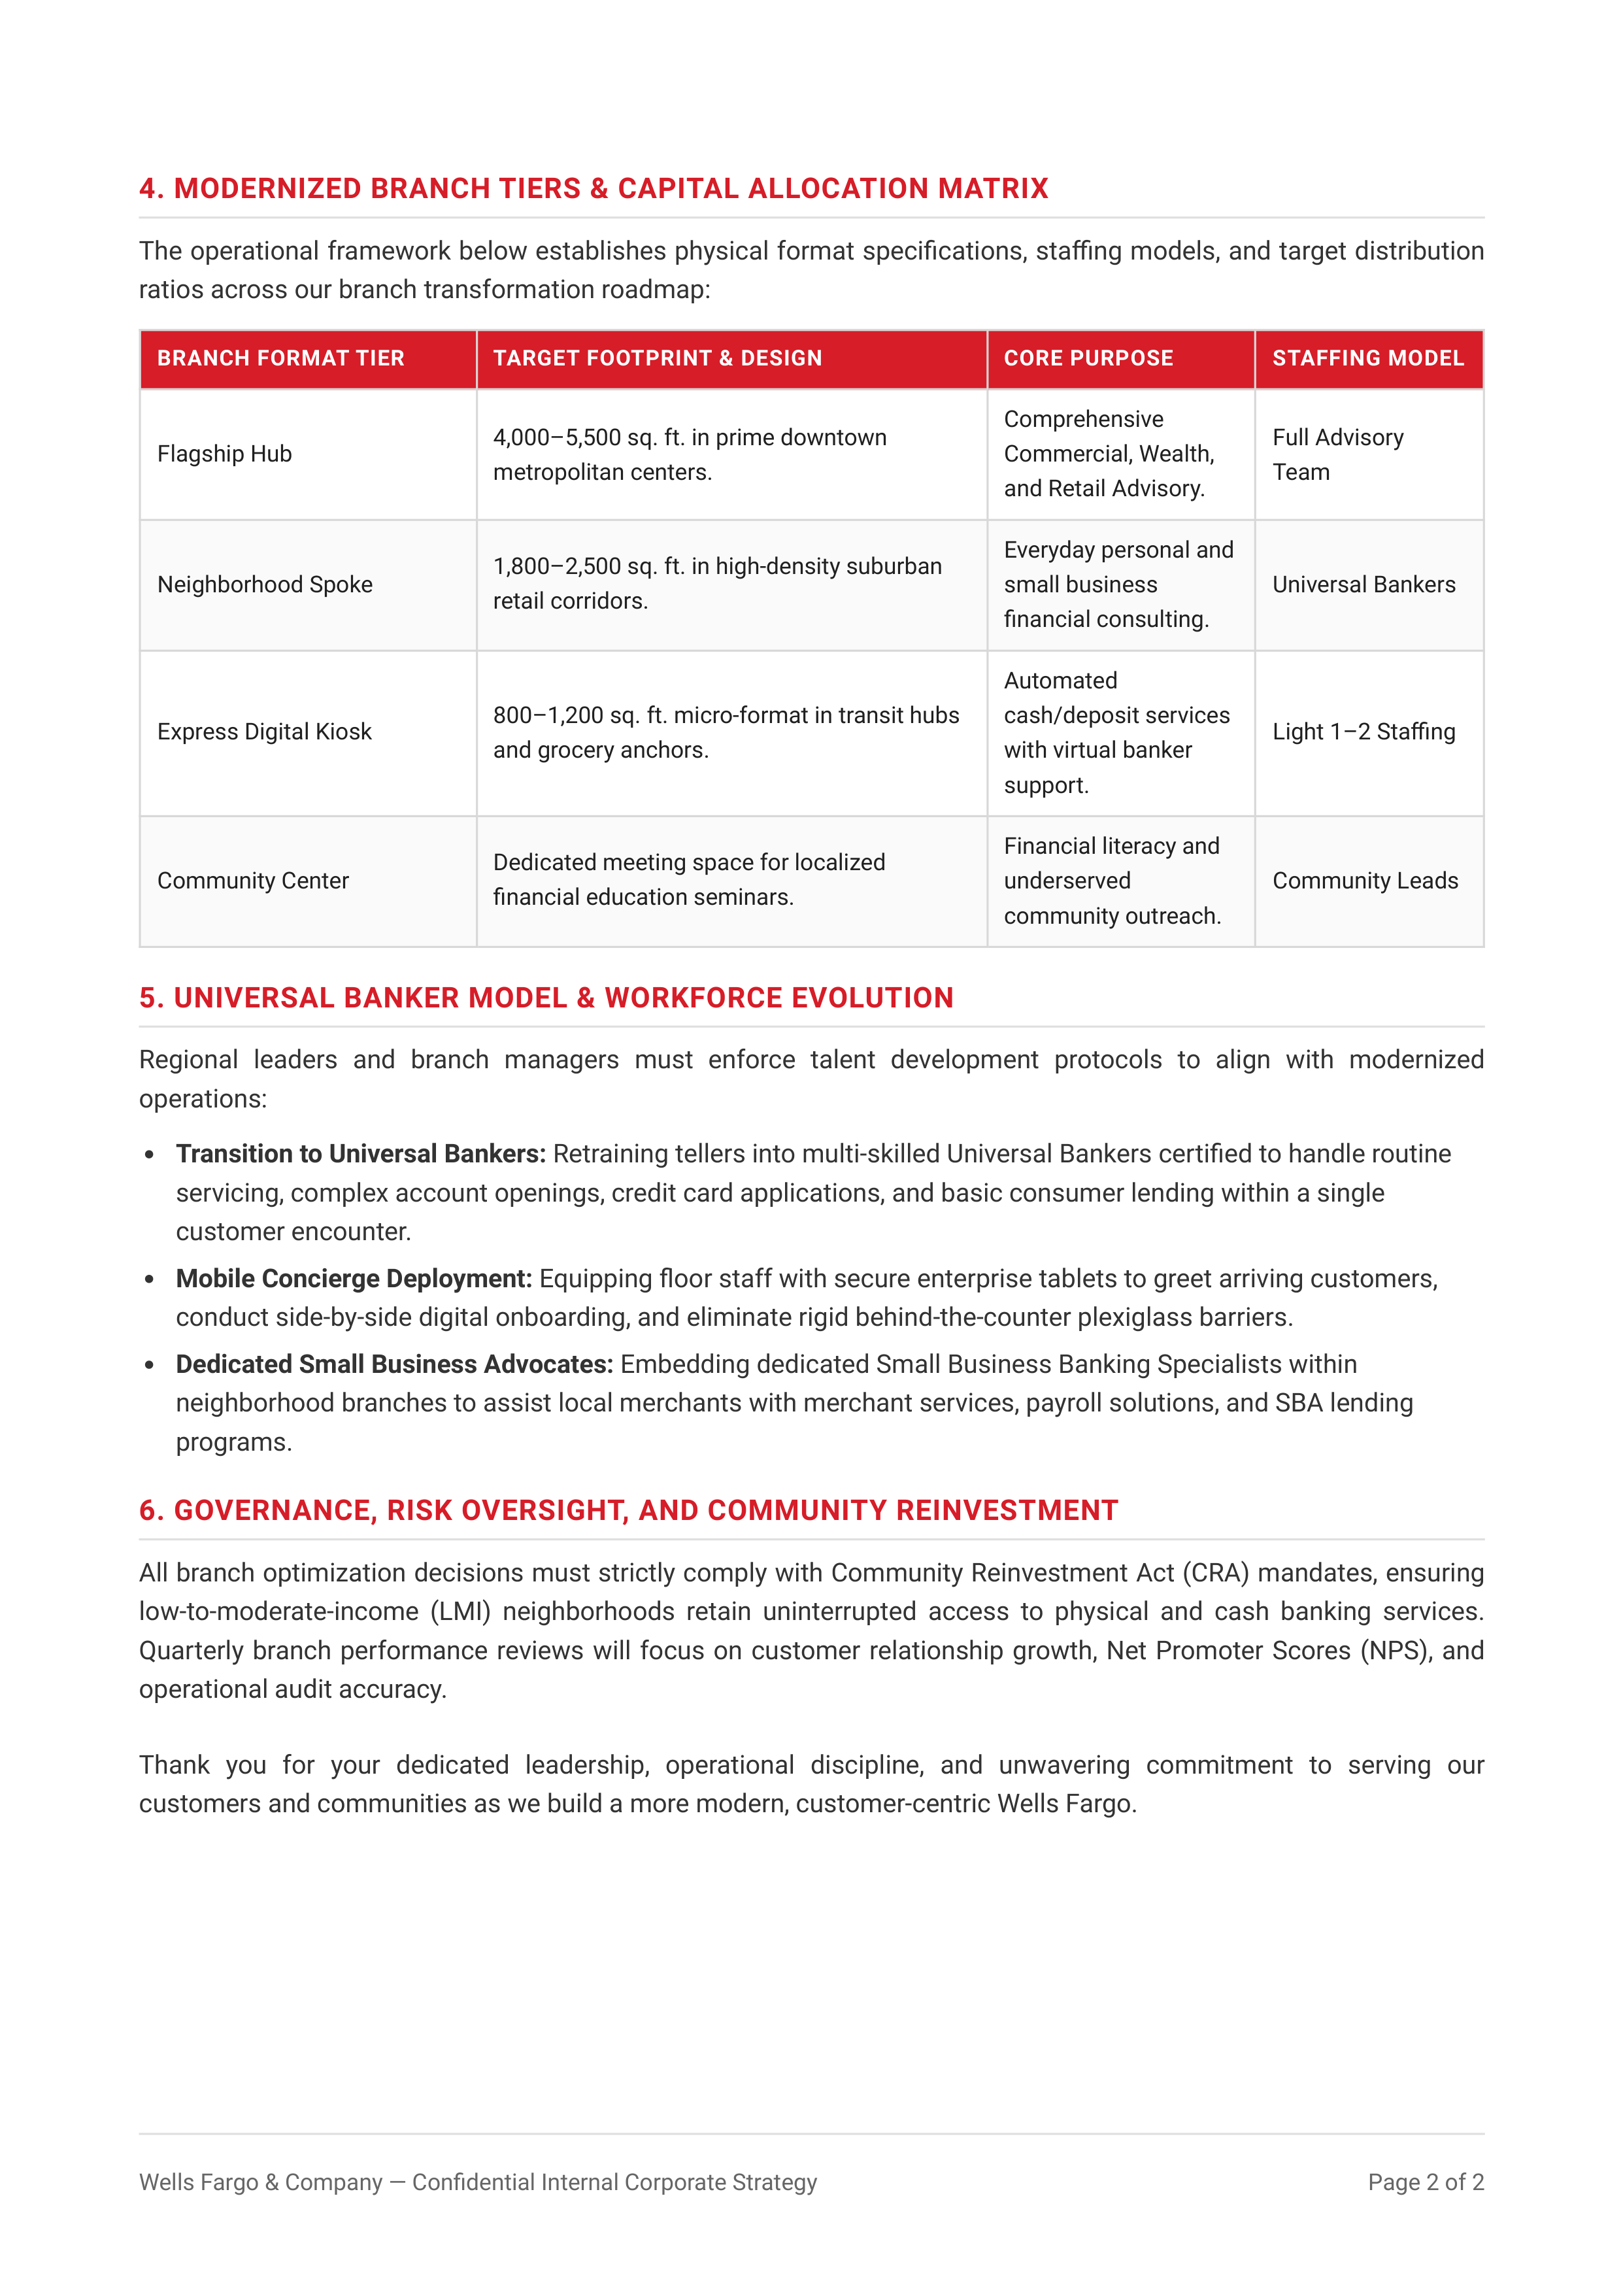
4. MODERNIZED BRANCH TIERS & CAPITAL ALLOCATION MATRIX
The operational framework below establishes physical format speci
fi
cations, sta
ffi
ng models, and target distribution
ratios across our branch transformation roadmap:
BRANCH FORMAT TIER
TARGET FOOTPRINT & DESIGN
CORE PURPOSE
STAFFING MODEL
Flagship Hub
4,000
–
5,500 sq. ft. in prime downtown
metropolitan centers.
Comprehensive
Commercial, Wealth,
and Retail Advisory.
Full Advisory
Team
Neighborhood Spoke
1,800
–
2,500 sq. ft. in high-density suburban
retail corridors.
Everyday personal and
small business
fi
nancial consulting.
Universal Bankers
Express Digital Kiosk
800
–
1,200 sq. ft. micro-format in transit hubs
and grocery anchors.
Automated
cash/deposit services
with virtual banker
support.
Light 1
–
2 Sta
ffi
ng
Community Center
Dedicated meeting space for localized
fi
nancial education seminars.
Financial literacy and
underserved
community outreach.
Community Leads
5. UNIVERSAL BANKER MODEL & WORKFORCE EVOLUTION
Regional leaders and branch managers must enforce talent development protocols to align with modernized
operations:
Transition to Universal Bankers:
Retraining tellers into multi-skilled Universal Bankers certi
fi
ed to handle routine
servicing, complex account openings, credit card applications, and basic consumer lending within a single
customer encounter.
Mobile Concierge Deployment:
Equipping
fl
oor staff with secure enterprise tablets to greet arriving customers,
conduct side-by-side digital onboarding, and eliminate rigid behind-the-counter plexiglass barriers.
Dedicated Small Business Advocates:
Embedding dedicated Small Business Banking Specialists within
neighborhood branches to assist local merchants with merchant services, payroll solutions, and SBA lending
programs.
6. GOVERNANCE, RISK OVERSIGHT, AND COMMUNITY REINVESTMENT
All branch optimization decisions must strictly comply with Community Reinvestment Act (CRA) mandates, ensuring
low-to-moderate-income (LMI) neighborhoods retain uninterrupted access to physical and cash banking services.
Quarterly branch performance reviews will focus on customer relationship growth, Net Promoter Scores (NPS), and
operational audit accuracy.
Thank you for your dedicated leadership, operational discipline, and unwavering commitment to serving our
customers and communities as we build a more modern, customer-centric Wells Fargo.
Wells Fargo & Company
—
Con
fi
dential Internal Corporate Strategy
Page 2 of 2